

Key Highlights
- Incentive Stock Options (ISOs) offer favourable tax benefits, deferring taxes until shares are sold, potentially leading to lower tax rates.
- Non-Qualified Stock Options (NSOs) provide more flexibility and can be granted to a wider range of individuals, but they incur immediate tax liabilities.
- Families must exercise ISOs within 90 days after leaving a job to maintain favourable tax treatment; missing this window can lead to lost benefits.
- ISOs require holding shares for a specific period to enjoy better tax treatment, while NSOs do not have such requirements but are less tax-friendly.
- The long-term financial implications of ISOs can include lower capital gains taxes, but they may trigger the Alternative Minimum Tax (AMT) if stock appreciates significantly.
- Consulting a financial advisor is crucial for families to understand the implications of exercising stock options and to align decisions with long-term financial goals.
- Past performance does not guarantee future results, and all investments carry risk; advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Introduction
Imagine feeling overwhelmed by the choices surrounding your family’s financial future, especially when it comes to stock options. Incentive Stock Options (ISOs) offer unique benefits, while Non-Qualified Stock Options (NSOs) come with their own challenges. Understanding these differences is key to your family’s long-term wealth.
As you navigate your options after leaving a job, it’s important to grasp the tax implications and exercise strategies that can affect your family’s financial well-being. What if you make the wrong choice? How can you ensure your family maximizes its financial potential while keeping risks at bay? We’re here for you, ready to help you make informed decisions that align with your family’s goals.
Define Incentive Stock Options and Non-Qualified Stock Options
Imagine feeling secure about your family’s financial future, even when faced with complex choices like stock options. Incentive Stock Options can be a powerful tool for employees, offering not just rewards for your hard work but also favorable tax benefits that can help your family thrive. However, when considering incentive stock options vs non-qualified stock options after leaving a company, it is important to note that these options come with specific rules and must be exercised within a certain timeframe.
On the other hand, Non-Qualified Stock Options provide more flexibility. They can be granted to a broader range of individuals, including contractors and board members, making them a versatile choice for many. While they don’t offer the same tax advantages, they can still play a significant role in your financial planning.
Navigating the world of stock options can feel overwhelming, especially when you’re trying to secure your family’s future. Without clarity on these options, you might miss out on valuable benefits that could support your family’s financial goals. Understanding these options can empower you to make informed decisions that benefit your family for years to come. Together, we can navigate this journey and ensure you’re making the best choices for your loved ones.
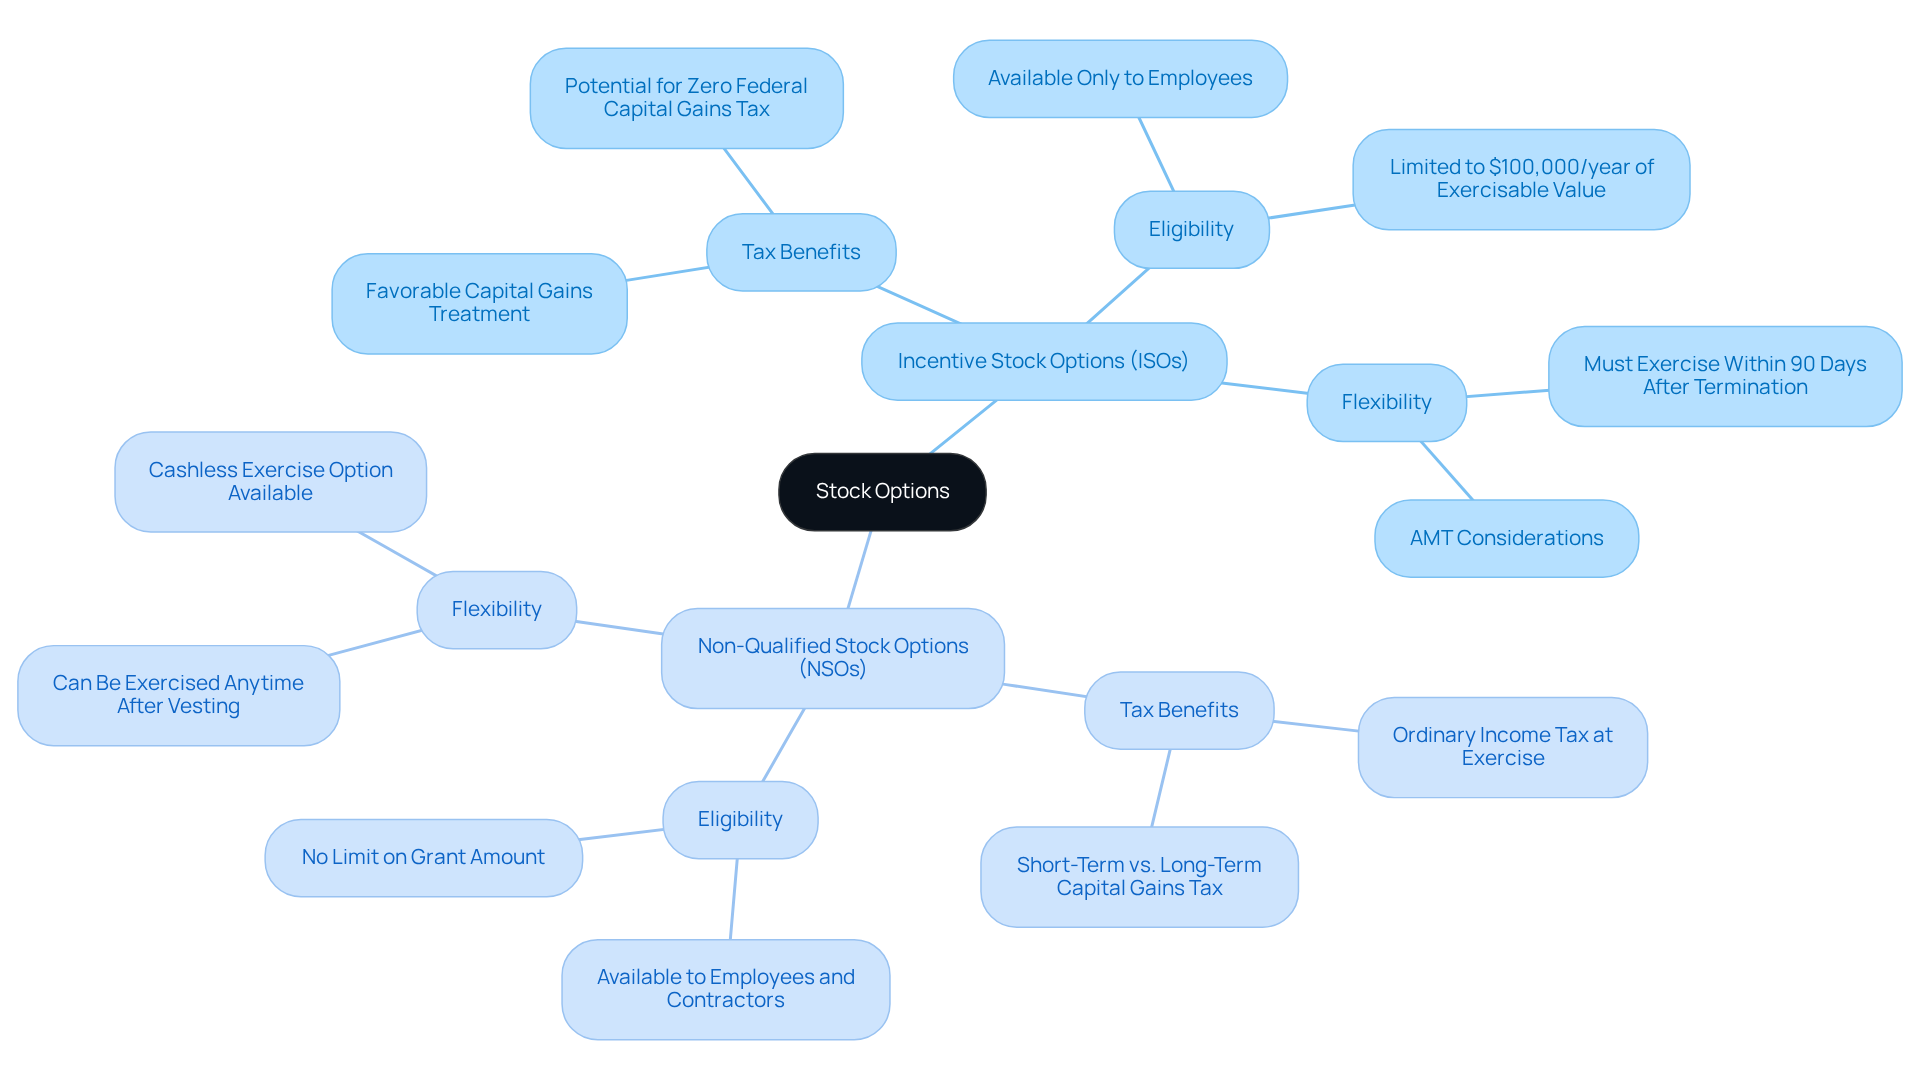
Compare Tax Treatment and Eligibility of ISOs and NSOs
Navigating the world of stock options can feel overwhelming, especially when you’re trying to secure your family’s financial future. Did you know that Incentive Stock Options can offer better tax benefits than Non-Qualified Stock Options? With ISOs, you won’t face immediate taxes; instead, they’re deferred until you sell the shares, which could mean lower rates for you later on. On the other hand, stock options hit you with taxes right away, which can feel like a heavy weight on your finances.
Imagine this: if you buy 1,000 shares at $10 each, but they’re worth $30 when you sell, that $20 difference gets taxed as regular income, which can really impact your tax return. Stock options come with rules, like needing to hold onto the shares for at least a year after you use them, and two years from when you got them, to enjoy better tax treatment. If you don’t meet these holding requirements, you might face short-term capital gains taxes, which can be a tougher hit on your wallet.
On the flip side, stock options can be given to more people, like contractors and consultants, making them easier to get but not as tax-friendly. It’s so important for families, especially those with little ones, to understand these differences as they plan their financial futures. Talking to a financial advisor can really help you see what each option means for your family and guide you in making choices that fit your goals.
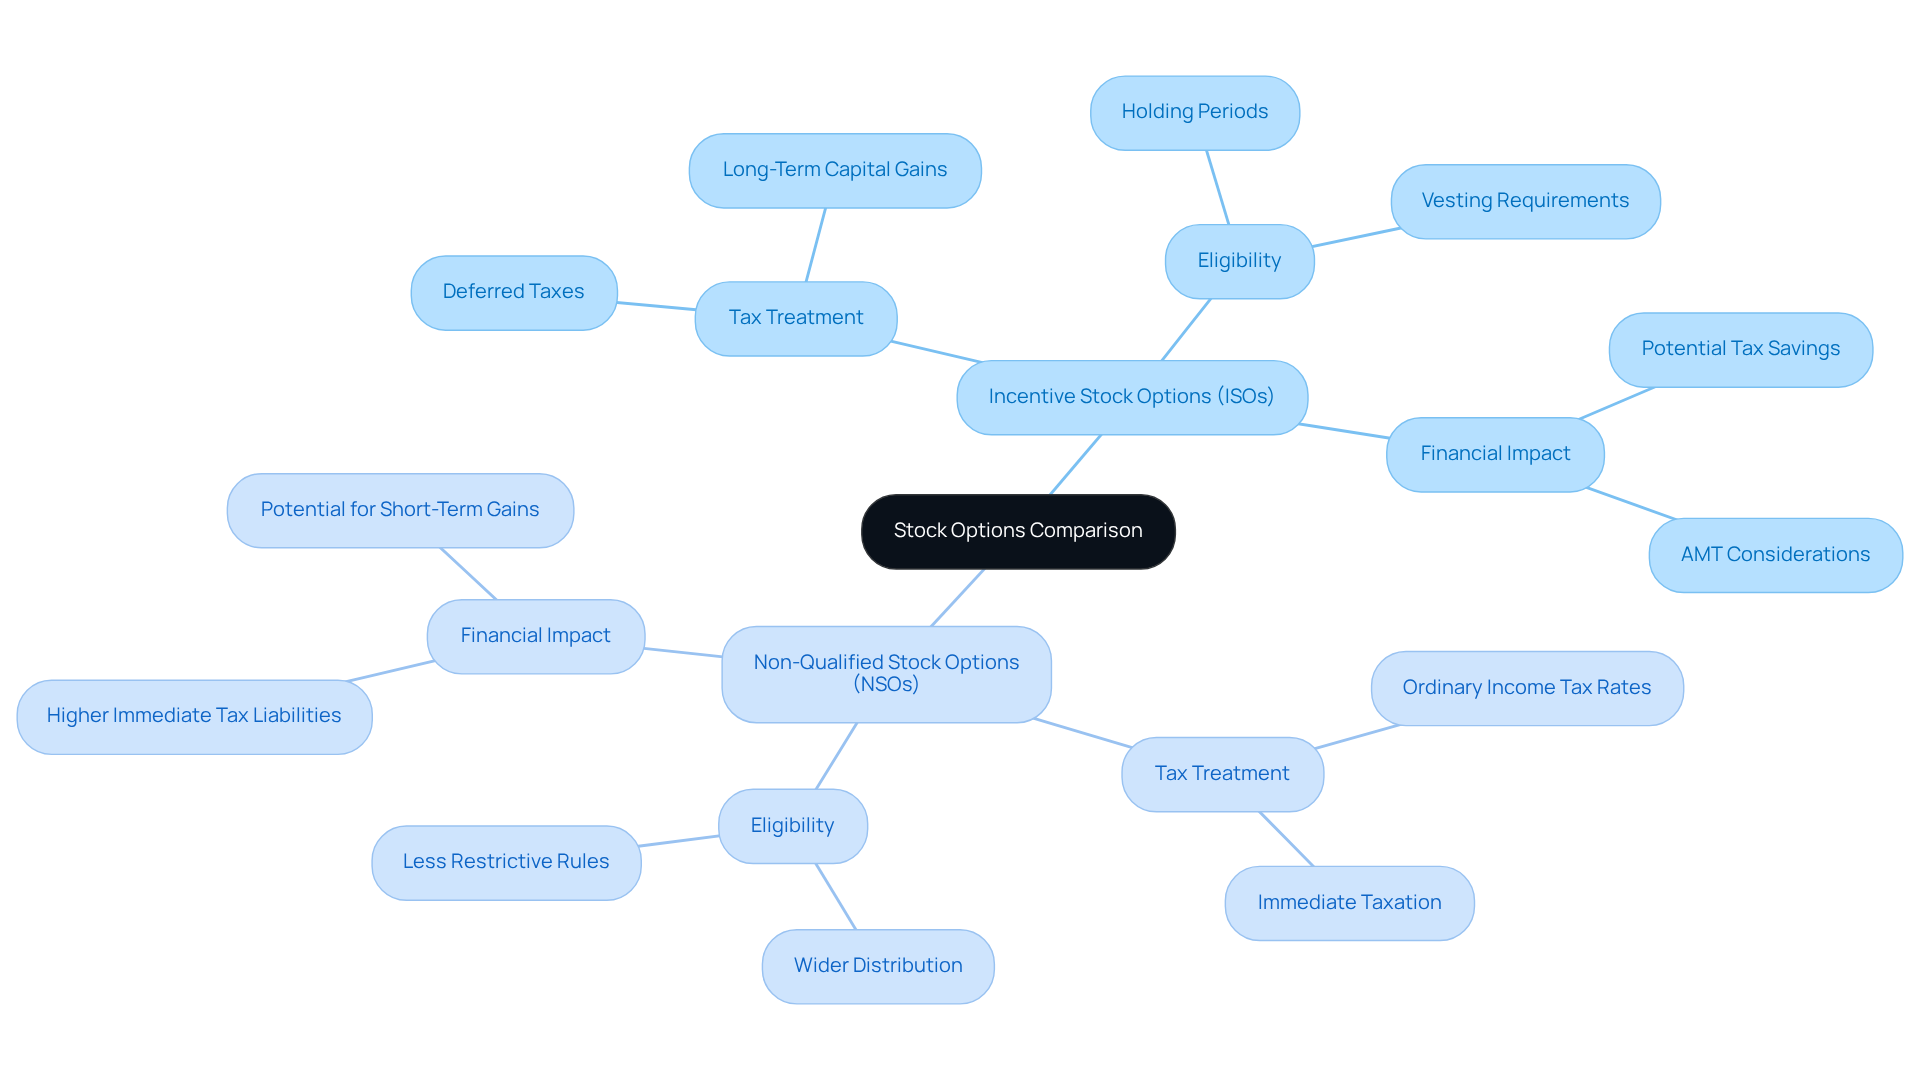
Evaluate Exercise Strategies for ISOs and NSOs After Departure
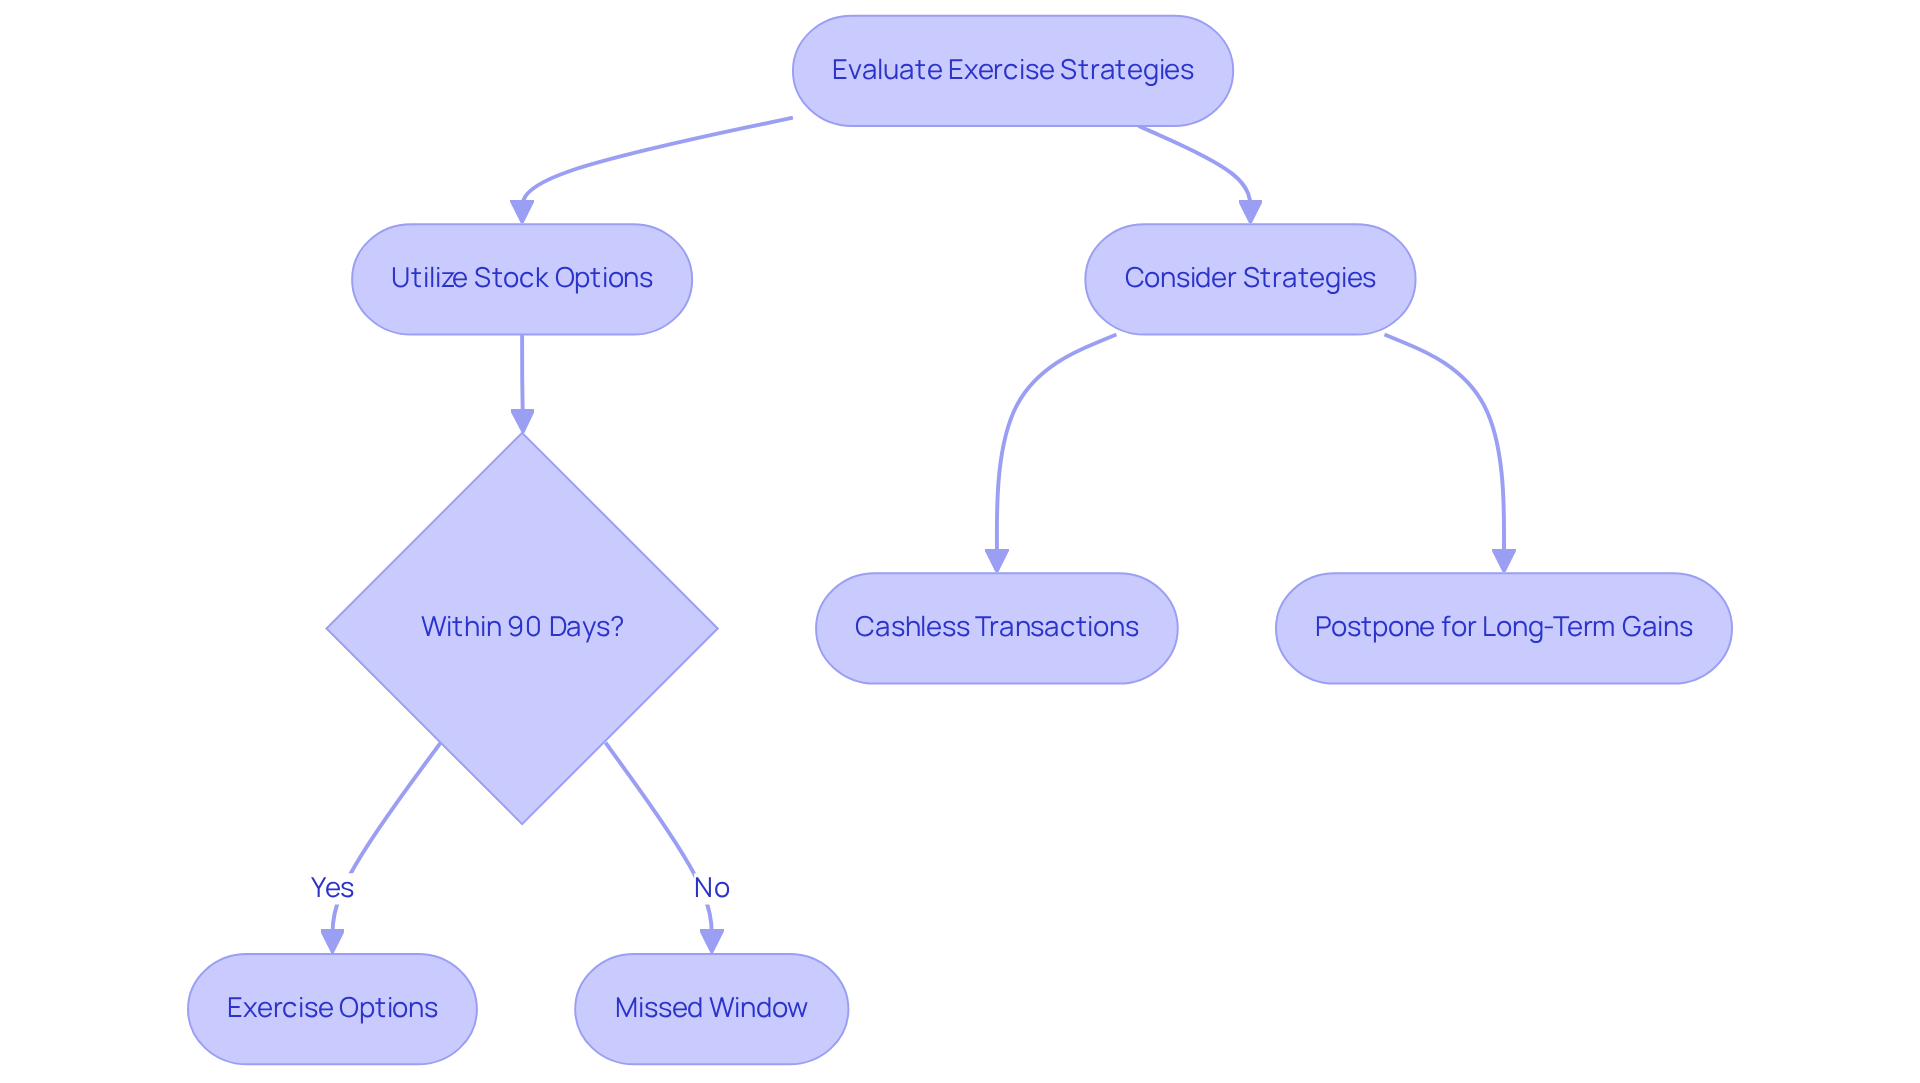
Navigating stock options after leaving a job can feel overwhelming, especially when timing is crucial for your family’s financial future. Employees generally have a 90-day period after termination to utilize their stock options while maintaining favorable tax treatment. If you miss this window, your ISOs may change, and you could lose valuable tax benefits that could help your family.
Families might consider strategies like cashless transactions, where you sell a portion of the shares to cover the transaction cost, or postponing the transaction until you qualify for long-term capital gains treatment. While stock options can be utilized at any time, it’s important to be aware of the immediate ordinary income tax consequences upon utilization. Evaluating these strategies can help families align their financial goals with their stock option decisions.
It’s concerning to know that many families miss out on valuable stock options, with billions left on the table each year. Bright Advisers is here to support families like yours in navigating these complexities, ensuring you make the most of your stock options while minimizing tax liabilities. By working with us, families like Emily and Mark, and Jay and Emma, can develop comprehensive financial plans that include investment strategies tailored to their unique situations.
It’s essential to consult with a financial advisor to understand the implications of exercising stock options and to create a plan that aligns with long-term financial goals. By understanding these strategies, you can ensure your family’s financial well-being and make choices that support your long-term goals. Please note that past performance does not guarantee future results, and all investments carry risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
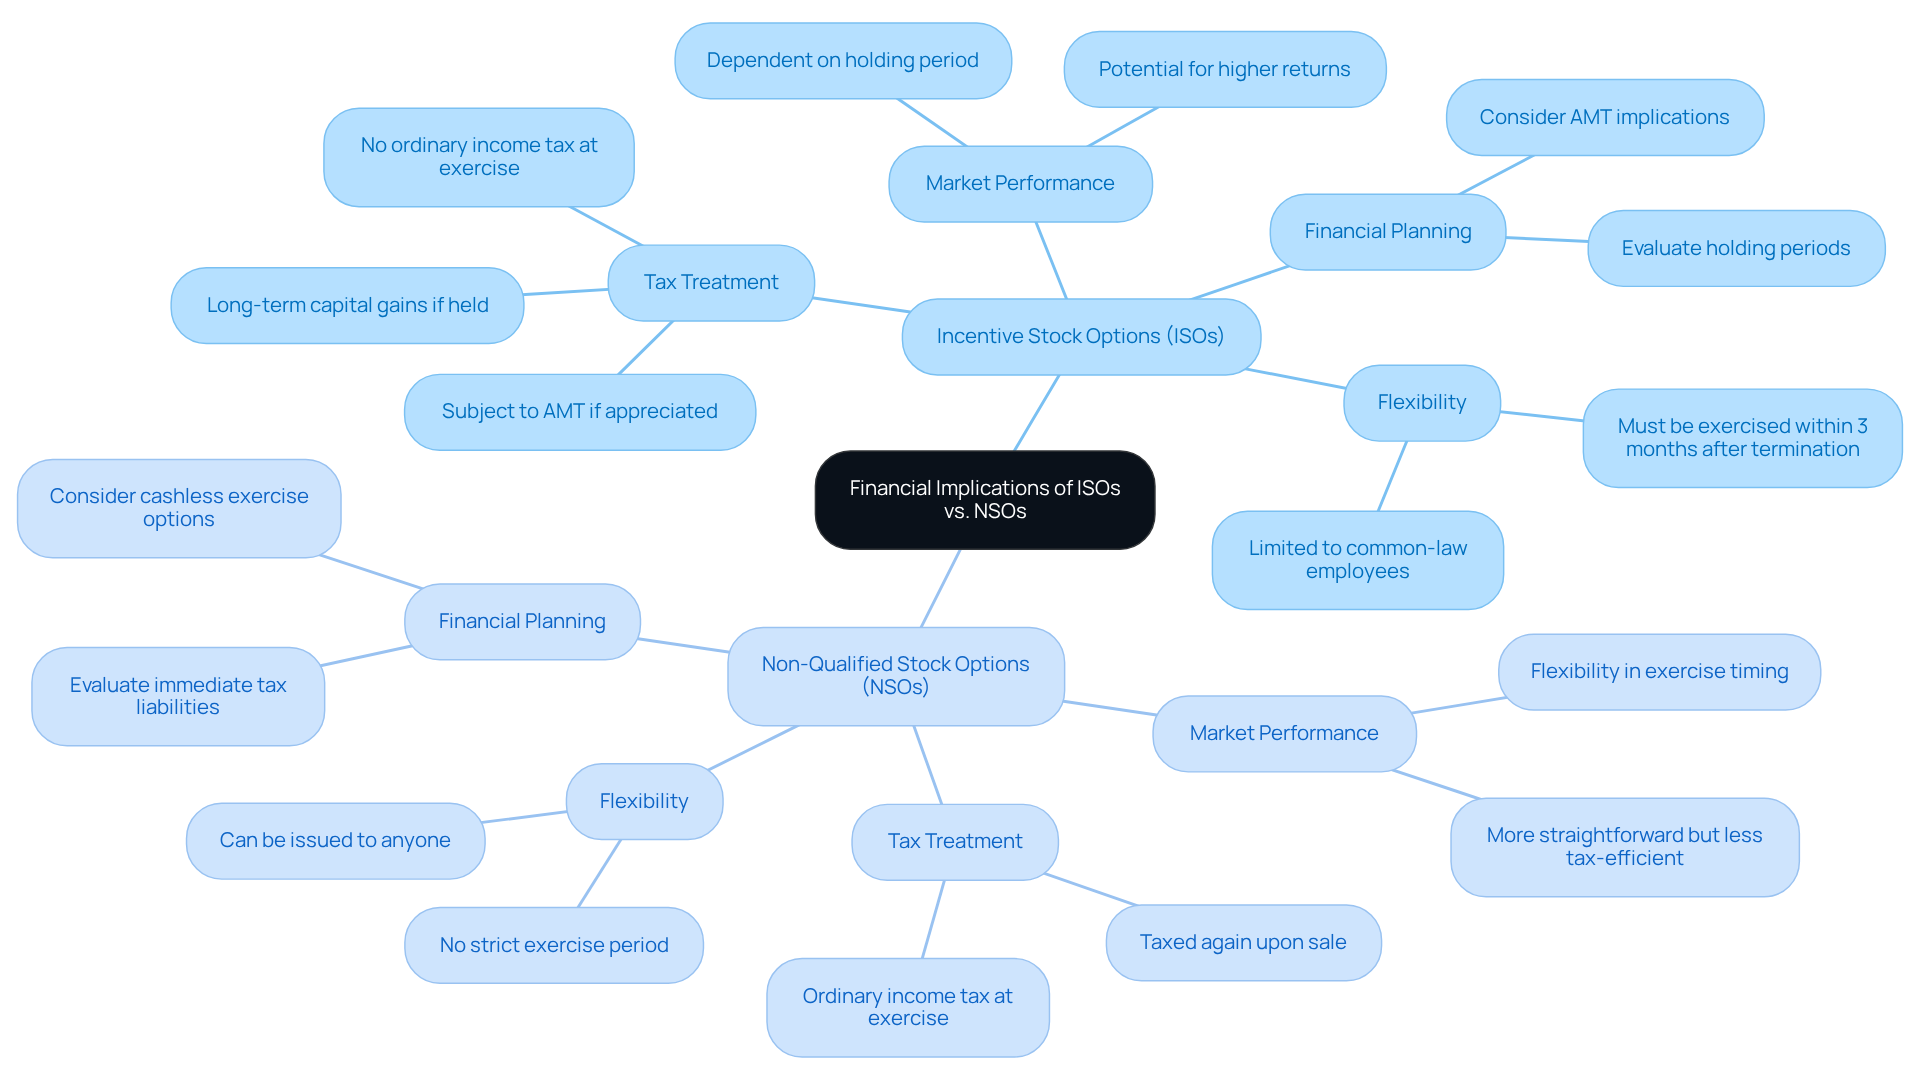
Assess Long-Term Financial Implications of ISOs vs. NSOs
Imagine navigating the complexities of stock options while trying to secure your family’s future. The long-term financial consequences of incentive stock options vs non-qualified stock options after leaving a company can feel overwhelming, particularly in terms of tax treatment and market performance. ISOs can lead to lower capital gains taxes upon sale if held for the required period, which can enhance overall returns. But there’s a catch: if the stock appreciates significantly, it could trigger the Alternative Minimum Tax (AMT), which might add stress to your financial planning.
On the other hand, Non-Qualified Stock Options (NSOs) can provide more flexibility, but they come with higher immediate tax liabilities, which can feel like a setback for families. It’s important to understand the implications of incentive stock options vs non-qualified stock options after leaving the company, as each option has its own set of consequences. Families should evaluate their financial goals, risk tolerance, and current market conditions when considering these choices.
With a thoughtful financial plan that considers these factors, you can confidently manage your stock options and work towards maximizing your family’s wealth potential. Remember, you’re not alone in this journey; together, we can navigate these complexities and build a brighter financial future for your family.
Conclusion
Imagine the worry of missing out on financial benefits just when you need them most; understanding stock options can help ease that concern. Both ISOs and NSOs come with their own set of benefits and challenges that can affect your family’s financial future. When you understand these differences, you can make choices that truly support your family’s financial goals and avoid missing out on valuable benefits.
It’s important to know how taxes and eligibility work with ISOs and NSOs, as this knowledge can make a big difference for your family. ISOs may offer tax advantages, allowing you to defer taxes until you sell your shares, while NSOs are more accessible but come with immediate tax liabilities. Missing deadlines for exercising these options can lead to lost opportunities, which can be stressful for families.
Navigating stock options can feel overwhelming, but with the right support, you can find your way through it. Consulting with a financial advisor can help you create a plan tailored to your family’s unique situation. By understanding ISOs and NSOs, you can make informed decisions that enhance your family’s financial well-being.
With the right guidance, you can turn potential confusion into clarity, ensuring your family’s financial future is bright and secure.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options are a type of employee stock option that offers favorable tax benefits, allowing employees to purchase company stock at a predetermined price. They are designed to reward employees for their hard work and can contribute to financial security for families.
What are Non-Qualified Stock Options (NSOs)?
Non-Qualified Stock Options are stock options that do not meet the requirements for favorable tax treatment like ISOs. They can be granted to a wider range of individuals, including contractors and board members, providing more flexibility in their use.
What are the key differences between Incentive Stock Options and Non-Qualified Stock Options?
The main differences include tax treatment and eligibility. ISOs offer tax advantages but are limited to employees, while NSOs can be granted to a broader range of individuals but do not provide the same tax benefits.
What should I consider when deciding between ISOs and NSOs after leaving a company?
It is important to understand the specific rules and timeframes for exercising these options. ISOs typically have stricter requirements and must be exercised within a certain period after leaving the company, while NSOs offer more flexibility.
How can understanding stock options benefit my family’s financial planning?
Gaining clarity on stock options can help you make informed decisions that align with your family’s financial goals, potentially unlocking valuable benefits that support your family’s future.
List of Sources
- Define Incentive Stock Options and Non-Qualified Stock Options
- Non-Qualified Stock Options (NSO): How NSOs Work (https://carta.com/learn/equity/stock-options/nso)
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- Incentive Stock Options vs. Non Qualified Stock Options (https://zajacgrp.com/insights/comparing-incentive-stock-options-and-non-qualified-stock-options)
- Differences Between Incentive Stock Options and Nonqualified Stock Options | Davis Wright Tremaine (https://dwt.com/blogs/startup-law-blog/2020/07/differences-between-iso-nso)
- ISOs vs. NSOs: Equity Tax Strategies | Dark Horse CPAs (https://darkhorse.cpa/blog/incentive-stock-options-vs-nonqualified-stock-options)
- Compare Tax Treatment and Eligibility of ISOs and NSOs
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- ISOs vs. NSOs: Equity Tax Strategies | Dark Horse CPAs (https://darkhorse.cpa/blog/incentive-stock-options-vs-nonqualified-stock-options)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- How Stock Options Are Taxed: ISO vs NSO | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/how-are-stock-options-taxed)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- Evaluate Exercise Strategies for ISOs and NSOs After Departure
- The Post-Termination Exercise Period (PTEP) for Options Explained (https://carta.com/learn/equity/leaving-company/post-termination-exercise-period)
- Exercising Stock Options: How & When to Exercise | Carta (https://carta.com/learn/equity/stock-options/exercising)
- Should you exercise your vested stock options after leaving your company? — Secfi (https://secfi.com/learn/what-to-do-with-stock-options-when-leaving)
- What Happens to Stock Options if You Quit? | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/what-happens-to-stock-options-if-i-leave-the-company)
- What to Do With Stock Options When You Leave a Company (https://cedarpointcap.com/financial-insights/stock-options-after-you-leave-company)
- Assess Long-Term Financial Implications of ISOs vs. NSOs
- Incentive Stock Options vs. Non Qualified Stock Options (https://zajacgrp.com/insights/comparing-incentive-stock-options-and-non-qualified-stock-options)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- Incentive Stock Options v. Non-Qualified Stock Options | Counsel for Emerging Companies and Startups (https://velawood.com/incentive-stock-options-v-non-qualified-stock-options)
- Differences Between Incentive Stock Options and Nonqualified Stock Options | Davis Wright Tremaine (https://dwt.com/blogs/startup-law-blog/2020/07/differences-between-iso-nso)
- Don’t overlook the risk that comes with your employee stock options (https://cnbc.com/2018/02/27/employee-stock-options-can-come-with-expensive-risks.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading