

Key Highlights
- Incentive Stock Options (ISOs) are exclusive to employees and offer tax benefits, allowing purchase of stock at a predetermined price without immediate income tax at exercise if certain conditions are met.
- Non-Qualified Stock Options (NSOs) can be offered to a broader group, including contractors, but are taxed as ordinary income upon exercise, leading to a higher immediate tax burden.
- ISOs may qualify for long-term capital gains tax treatment if shares are held for at least one year after exercise and two years after the grant date, potentially lowering tax rates.
- Only the first $100,000 worth of ISOs exercisable in a calendar year can benefit from special tax treatment; amounts over this limit are taxed as NSOs.
- ISOs encourage long-term commitment to the organisation, aligning interests with shareholders, while NSOs provide greater flexibility in eligibility for companies.
- Both ISOs and NSOs can trigger the Alternative Minimum Tax (AMT), complicating tax situations if not managed properly.
- Understanding the differences between ISOs and NSOs is crucial for effective financial planning and making informed decisions that support family financial goals.
Introduction
Imagine feeling overwhelmed by the complexities of executive compensation, especially when it comes to choosing between incentive stock options and non-qualified stock options. These two types of stock options can shape your financial landscape. They also come with distinct tax implications that can affect your family’s long-term wealth.
As families like yours navigate these complexities, it can be challenging to find the option that truly aligns with your financial goals and values. What if you could understand the key features and potential pitfalls of each option? How can you make informed decisions that will secure your family’s financial future? We’re here to help you through this journey.
Define Incentive Stock Options and Non-Qualified Stock Options
Imagine feeling confident about your family’s financial future, even when faced with the complexities of incentive stock options vs non-qualified stock options for executives. Have you ever wondered about Incentive Stock Options? They’re a special type of stock option just for employees, and they come with some great tax benefits! You can purchase company stock at a predetermined price, usually lower than the market value, without paying regular income tax at the time of exercise, as long as certain conditions are met.
Non-Qualified Stock Options, however, are a bit different. They can be offered to employees, contractors, and others, but they don’t come with the same tax perks as ISOs. When you exercise these options, the difference between the exercise price and the market price is taxed as ordinary income, which can be less favorable from a tax perspective.
Understanding incentive stock options vs non-qualified stock options for executives is crucial for making smart choices that can shape your family’s financial future. By grasping these definitions, you can navigate your compensation packages with confidence and ensure that your financial planning aligns with your family’s values and aspirations. We’re here for you, ready to help you make the best decisions for your loved ones.
Compare Tax Treatment and Eligibility Criteria
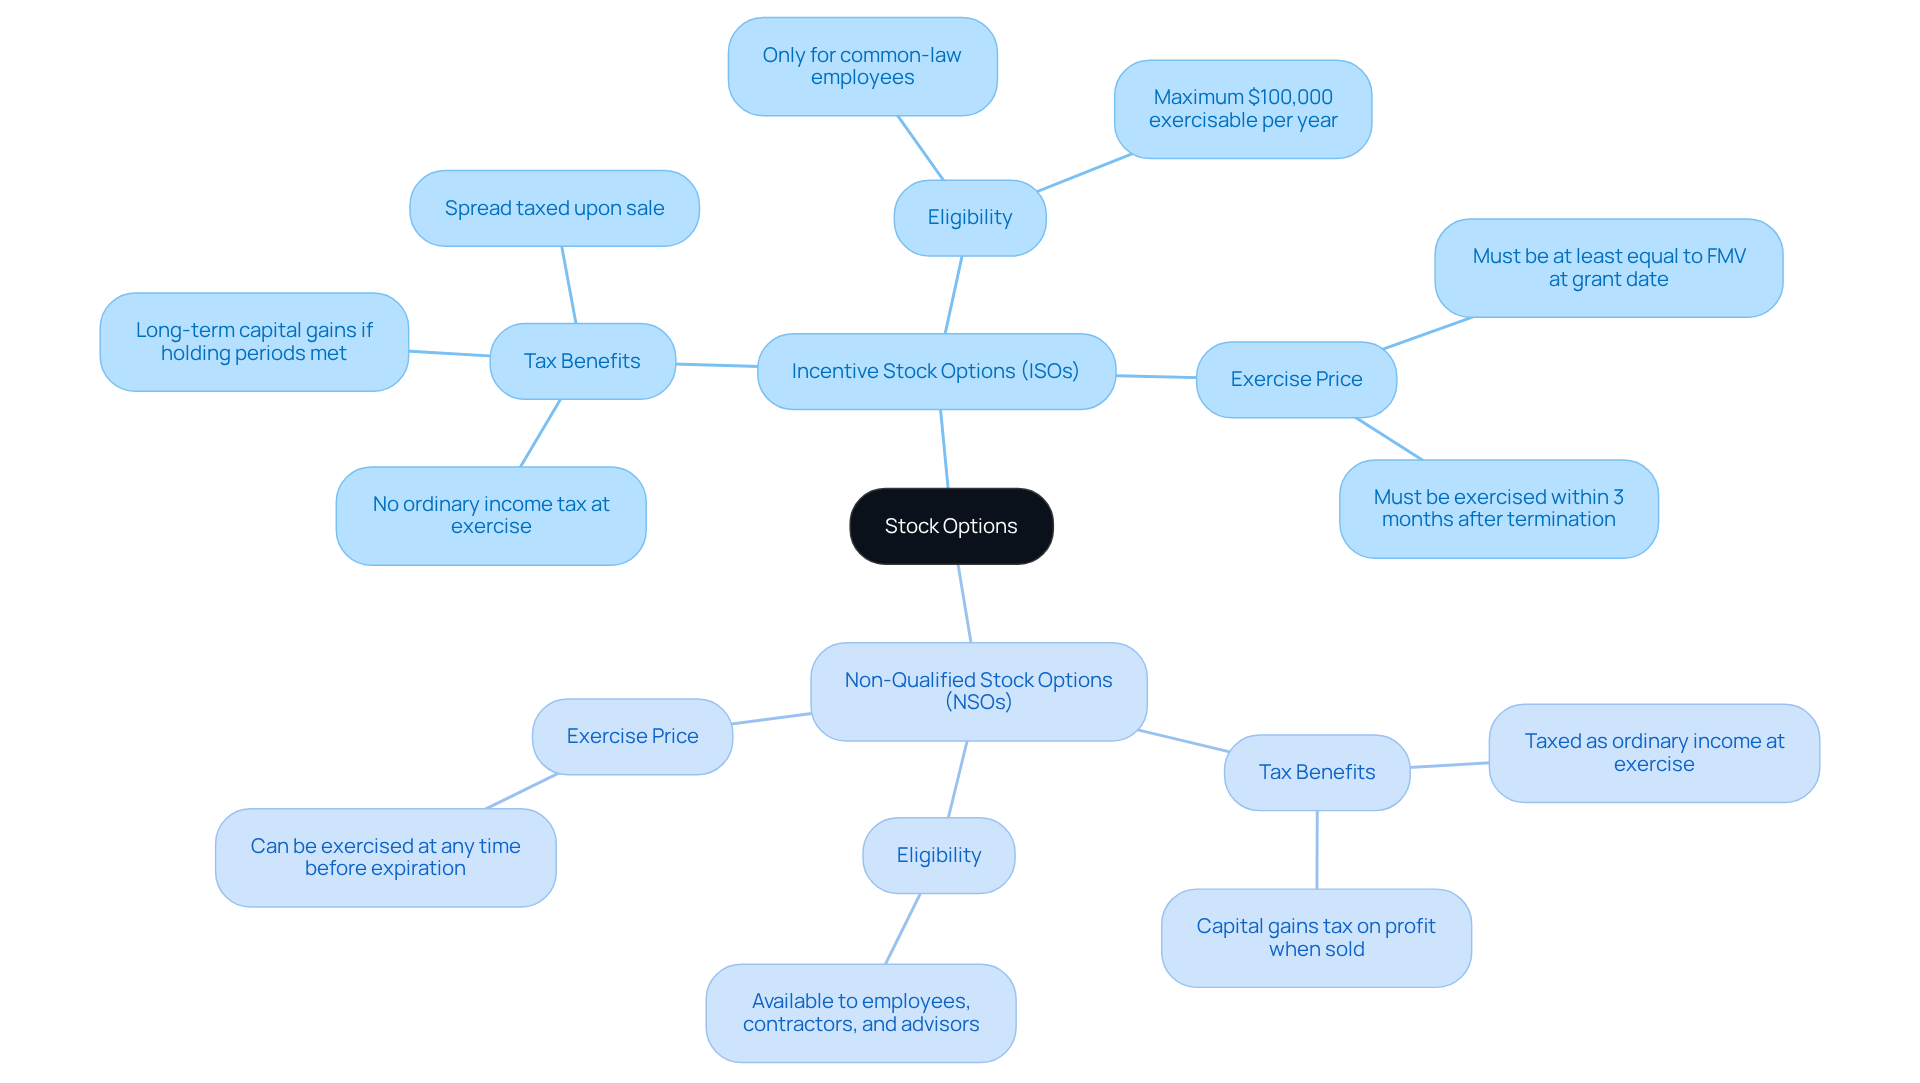
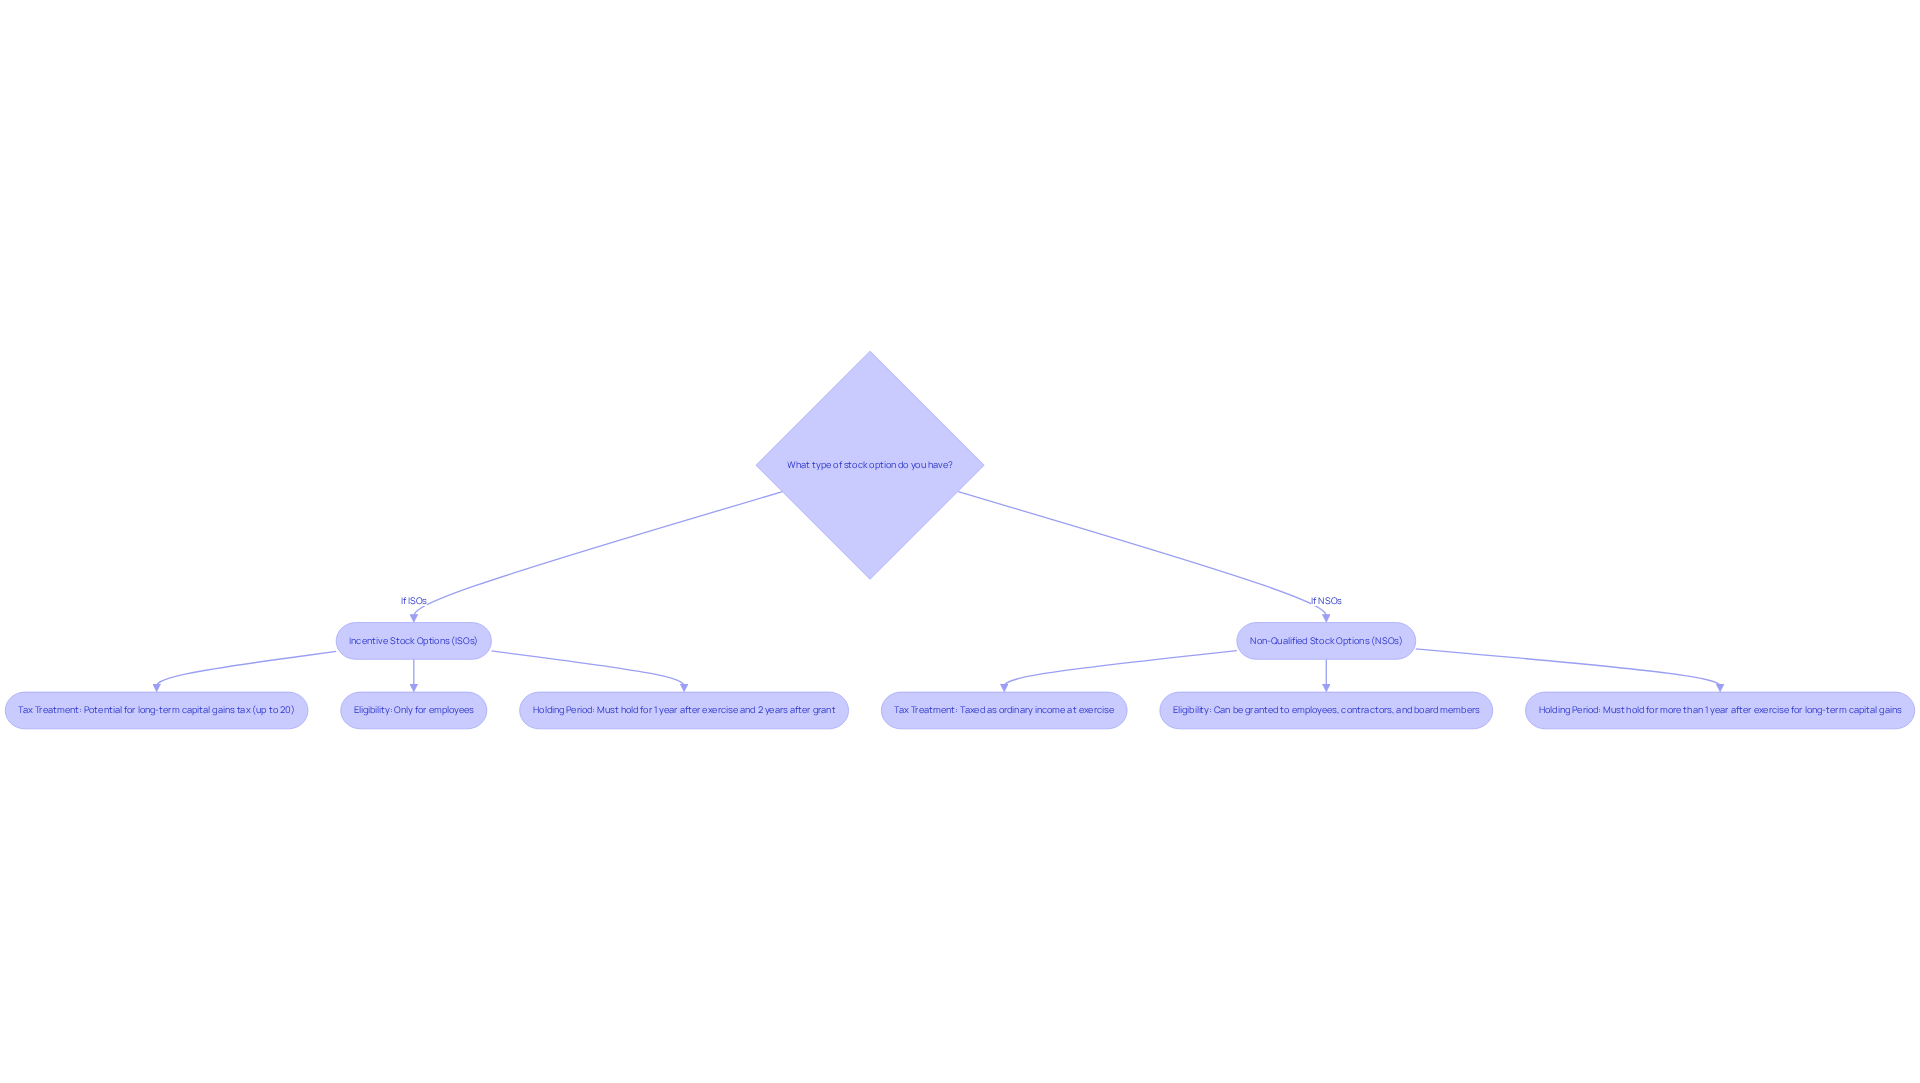
Navigating the world of stock options can feel overwhelming, especially when tax implications come into play. Imagine if you could hold onto your shares for a bit longer and benefit from lower tax rates. That’s the potential with incentive stock options! These options aren’t taxed as ordinary income at the time of exercise. Instead, if you hold the shares for at least one year after exercising and two years after the grant date, you might qualify for long-term capital gains tax treatment. This could mean a lower tax rate on any gains, potentially as low as 20%.
But here’s something to keep in mind: only the first $100,000 worth of incentive stock options that become exercisable in a single calendar year can enjoy this special tax treatment. Any amount over that limit is taxed as non-qualified stock options, which can complicate things.
On the other hand, stock options can hit your wallet harder, as they’re taxed as ordinary income right when you exercise them. This means the difference between the exercise price and the market price is taxed at your income tax rate, which can be as high as 37%. It’s important to understand that stock options trigger taxes at two points: when you exercise them and again when you sell them. This can lead to a more complex tax situation. For example, if you exercise 100 vested stock options at a grant price of $1 when the current value is $3, you’ll incur ordinary income tax on a $200 gain at exercise. Many employees have reported receiving a higher-than-expected tax bill after exercising or selling shares, which highlights the importance of understanding these tax implications.
It’s also worth noting the distinction in incentive stock options vs non-qualified stock options for executives, as incentive stock options are exclusive to employees, while non-qualified stock options can be offered to a broader group, including contractors and board members. This flexibility can be advantageous for companies looking to incentivize various contributors. However, stock options may also trigger the Alternative Minimum Tax (AMT), which can lead to unexpected tax liabilities if not properly managed. Misunderstanding these tax implications can lead to unexpected financial burdens, making it crucial to stay informed.
Understanding these differences can empower you to make informed decisions that support your family’s financial future.
Evaluate Pros and Cons for Executive Compensation
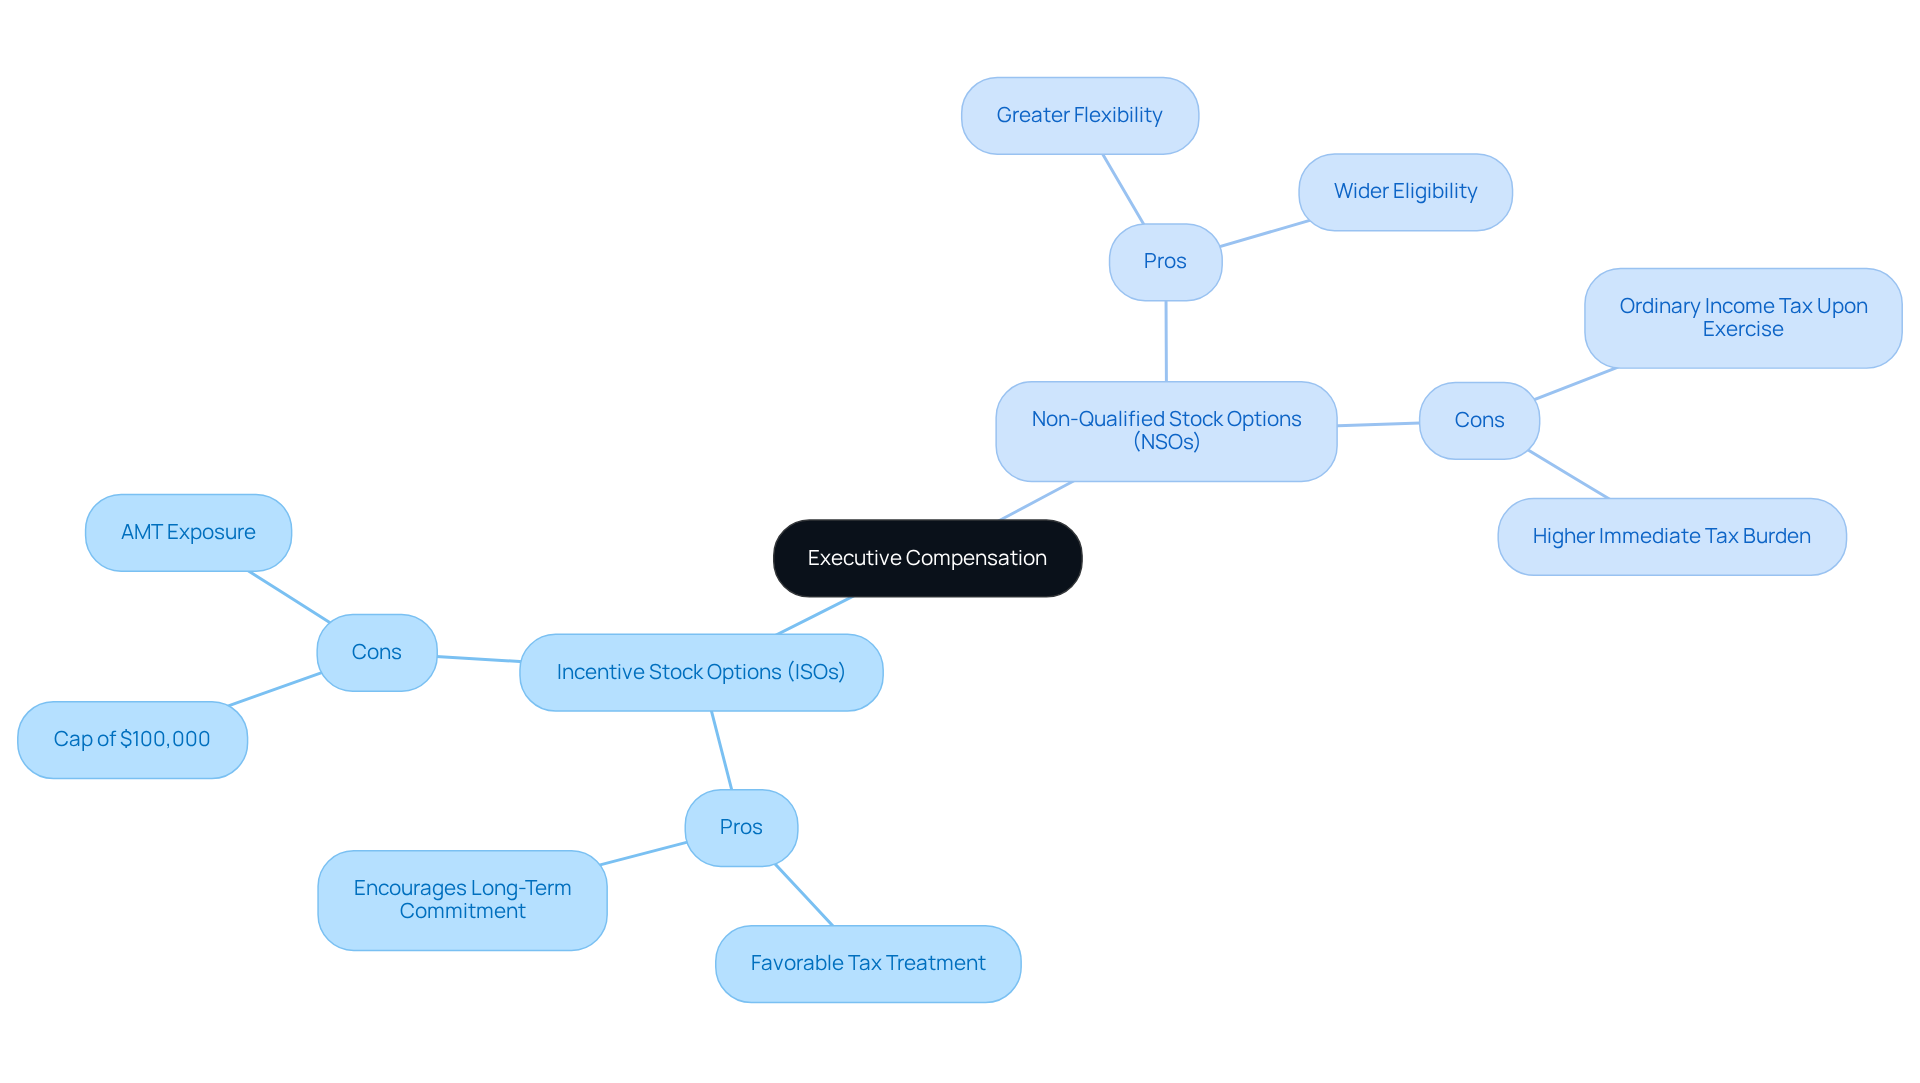
Imagine feeling confident about your financial future, knowing you’re making the best choices for your family. When considering incentive stock options vs non-qualified stock options for executives, it is clear that incentive stock options can offer significant advantages, particularly regarding favorable tax treatment. If you meet specific holding requirements, you might benefit from lower capital gains tax rates. Plus, stock options encourage long-term commitment to your organization, aligning your interests with those of shareholders. Did you know that long-term incentives account for 73% of total CEO compensation in the Russell 3000? This highlights just how important stock options are in executive pay structures.
But it’s important to know that incentive stock options do have some limits. For instance, there’s a cap of $100,000 on the total value of options that can be granted in a year, and you’ll need to exercise them within a designated timeframe. If you exercise and sell your options in the same year, the difference is treated as regular income, not alternative minimum tax income. This is a significant factor to consider for your tax planning.
On the other hand, when discussing incentive stock options vs non-qualified stock options for executives, the Non-Qualified Stock Options provide greater flexibility regarding eligibility. This means a wider range of employees can receive them without the same restrictions as incentive stock options, making them more appealing for companies looking to reward a diverse workforce. However, keep in mind that NSOs are subject to ordinary income tax upon exercise, which can lead to a higher immediate tax burden for high-level professionals. For example, CEO compensation increased by 44.7% in companies generating less than $50 million in revenue, emphasizing the competitive environment of leadership pay.
Understanding these pros and cons is essential for you as a leader, especially when planning for your family’s future. While stock options can offer considerable tax benefits, they may also expose you to the alternative minimum tax (AMT) if not managed carefully. Conversely, while stock options are easier to handle, they can result in immediate tax obligations that you’ll need to factor into your financial planning. Together, we can navigate this journey and ensure you’re making informed decisions for your loved ones.
Strategize for Long-Term Financial Goals
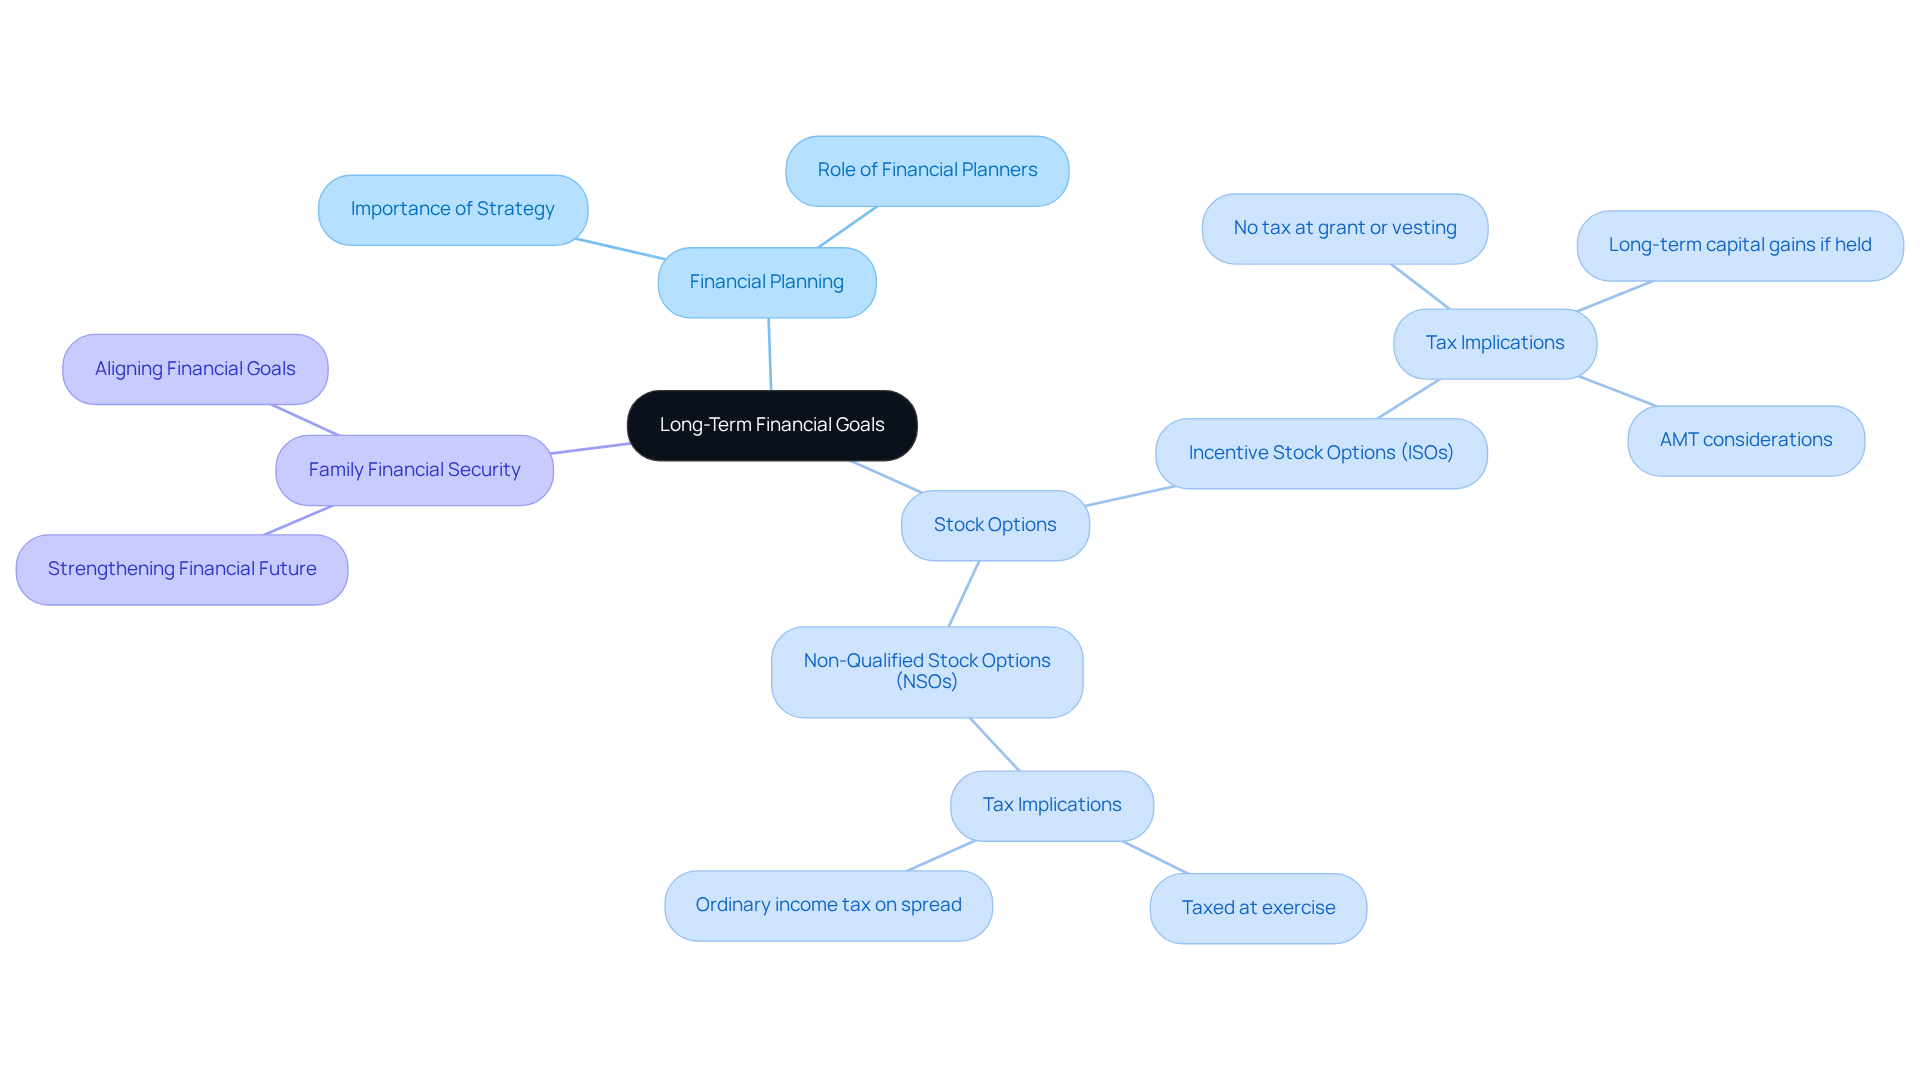
Imagine feeling overwhelmed by the choices in financial planning, especially when you want the best for your family. When planning for your family’s future, it’s important to consider the right options for your financial goals, particularly the differences between incentive stock options vs non qualified stock options for executives. Start by looking at your current tax situation and what you expect your income to be in the future. This can help you make informed decisions.
For example, if you think your income might increase, it could be wise to consider how exercising certain stock options might save you money on taxes later on. It’s also important to think about how your stock options fit into your overall financial plan for your family.
Working with a financial planner can help you create a strategy that brings together your stock options and your family’s financial goals. By taking charge of your stock options, you can strengthen your family’s financial security and pave the way for a brighter future together.
Conclusion
Imagine feeling overwhelmed by financial choices that impact your family’s future. Understanding the differences between incentive stock options and non-qualified stock options can help ease that burden. Each type of stock option has its own pros and cons that can affect your family’s finances now and in the future.
Incentive stock options can offer favorable tax treatment if certain conditions are met, which might mean more money in your pocket down the line. On the other hand, non-qualified stock options are more widely available but can lead to immediate tax implications that you need to consider.
By understanding these differences, you can make choices that truly support your family’s financial dreams. Engaging with a financial planner can provide you with a tailored strategy that weaves your stock options into a broader financial plan. Together, we can navigate this journey, ensuring that your decisions today pave the way for a secure financial tomorrow. Taking proactive steps today can ensure your family’s financial future is bright and secure, allowing you to focus on what truly matters-your loved ones.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are a special type of stock option available exclusively to employees. They allow employees to purchase company stock at a predetermined price, typically lower than the market value, without incurring regular income tax at the time of exercise, provided certain conditions are met.
How do Non-Qualified Stock Options (NSOs) differ from ISOs?
Non-Qualified Stock Options (NSOs) can be offered to employees, contractors, and others, but they do not provide the same tax benefits as ISOs. When NSOs are exercised, the difference between the exercise price and the market price is taxed as ordinary income, which can be less favorable from a tax perspective.
Why is it important to understand the differences between ISOs and NSOs?
Understanding the differences between Incentive Stock Options and Non-Qualified Stock Options is crucial for making informed decisions regarding compensation packages. This knowledge can help shape your family’s financial future and ensure that your financial planning aligns with your family’s values and aspirations.
List of Sources
- Define Incentive Stock Options and Non-Qualified Stock Options
- Differences Between Incentive Stock Options and Nonqualified Stock Options | Davis Wright Tremaine (https://dwt.com/blogs/startup-law-blog/2020/07/differences-between-iso-nso)
- Stock Options: NQSOs and ISOs (https://schwab.com/learn/story/stock-options-nqsos-and-isos-guide)
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- Incentive stock options (ISOs) and taxes: the complete guide — Secfi (https://secfi.com/learn/iso-incentive-stock-options-tax-treatment)
- ISOs vs. NSOs: Options, Taxes, and Cashless Exercise Explained (https://nasdaqprivatemarket.com/youve-got-options-what-to-know-about-isos-and-nsos)
- Compare Tax Treatment and Eligibility Criteria
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- ISO vs NSO: What’s the Difference? Tax & Eligibility (https://esofund.com/blog/difference-iso-nso)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- Range – ISO vs NSO: What’s the Difference? (https://range.com/blog/iso-vs-nso-whats-the-difference)
- Evaluate Pros and Cons for Executive Compensation
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Using Executive Compensation Data to Retain Talent | Gallagher (https://ajg.com/using-executive-compensation-data-to-retain-talent)
- San Diego Office (https://sblgllp.com/practiceareas/stockoptionplans.html)
- Compensation Committee Priorities for 2026 (https://bdo.com/insights/assurance/compensation-committee-priorities-for-2026)
- Equity Compensation: Incentive Stock Options and Non-Qualified Stock Options – Rubin Rudman (https://rubinrudman.com/article/equity-compensation-incentive-stock-options-and-non-qualified-stock-options)
- Strategize for Long-Term Financial Goals
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Industry Statistics (https://investmentadviser.org/industry-snapshots)
- ISO vs NSO options: Which are better? (https://jpmorganworkplacesolutions.com/insights/iso-vs-nso)
- 2026 Financial Planning Industry Trends Survey (https://kaplanfinancial.com/wealth-management/resources/survey-of-trends)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading