

Key Highlights
- Incentive Stock Options (ISOs) are designed for employees and offer tax benefits if certain IRS conditions are met, such as a maximum vesting amount of $100,000 per year.
- ISOs can be taxed at the lower capital gains rate if held long enough, providing potential savings for families.
- Non-Qualified Stock Options (NSOs) can be granted to a broader range of service providers and are taxed as regular income upon exercise, which can lead to immediate tax liabilities.
- Families must understand the tax implications of both ISOs and NSOs to avoid unexpected tax bills and maximise potential benefits.
- The timing of exercising stock options can significantly impact financial outcomes; early exercise of ISOs may trigger Alternative Minimum Tax (AMT), while exercising NSOs incurs immediate tax liabilities.
- Families should assess their current and anticipated income levels when choosing between ISOs and NSOs to align with their financial goals.
- Bright Advisers assists families in navigating these complexities, emphasising the importance of informed decision-making regarding stock options.
Introduction
Imagine navigating the world of stock options while trying to secure your family’s financial future. Understanding these options can shape how your family builds wealth and come with tax implications that might surprise you. As parents, you might wonder which option truly fits your family’s long-term financial dreams. How can you weigh the pros and cons of ISOs and NSOs to make choices that nurture your family’s financial health?
Define Incentive Stock Options and Non-Qualified Stock Options
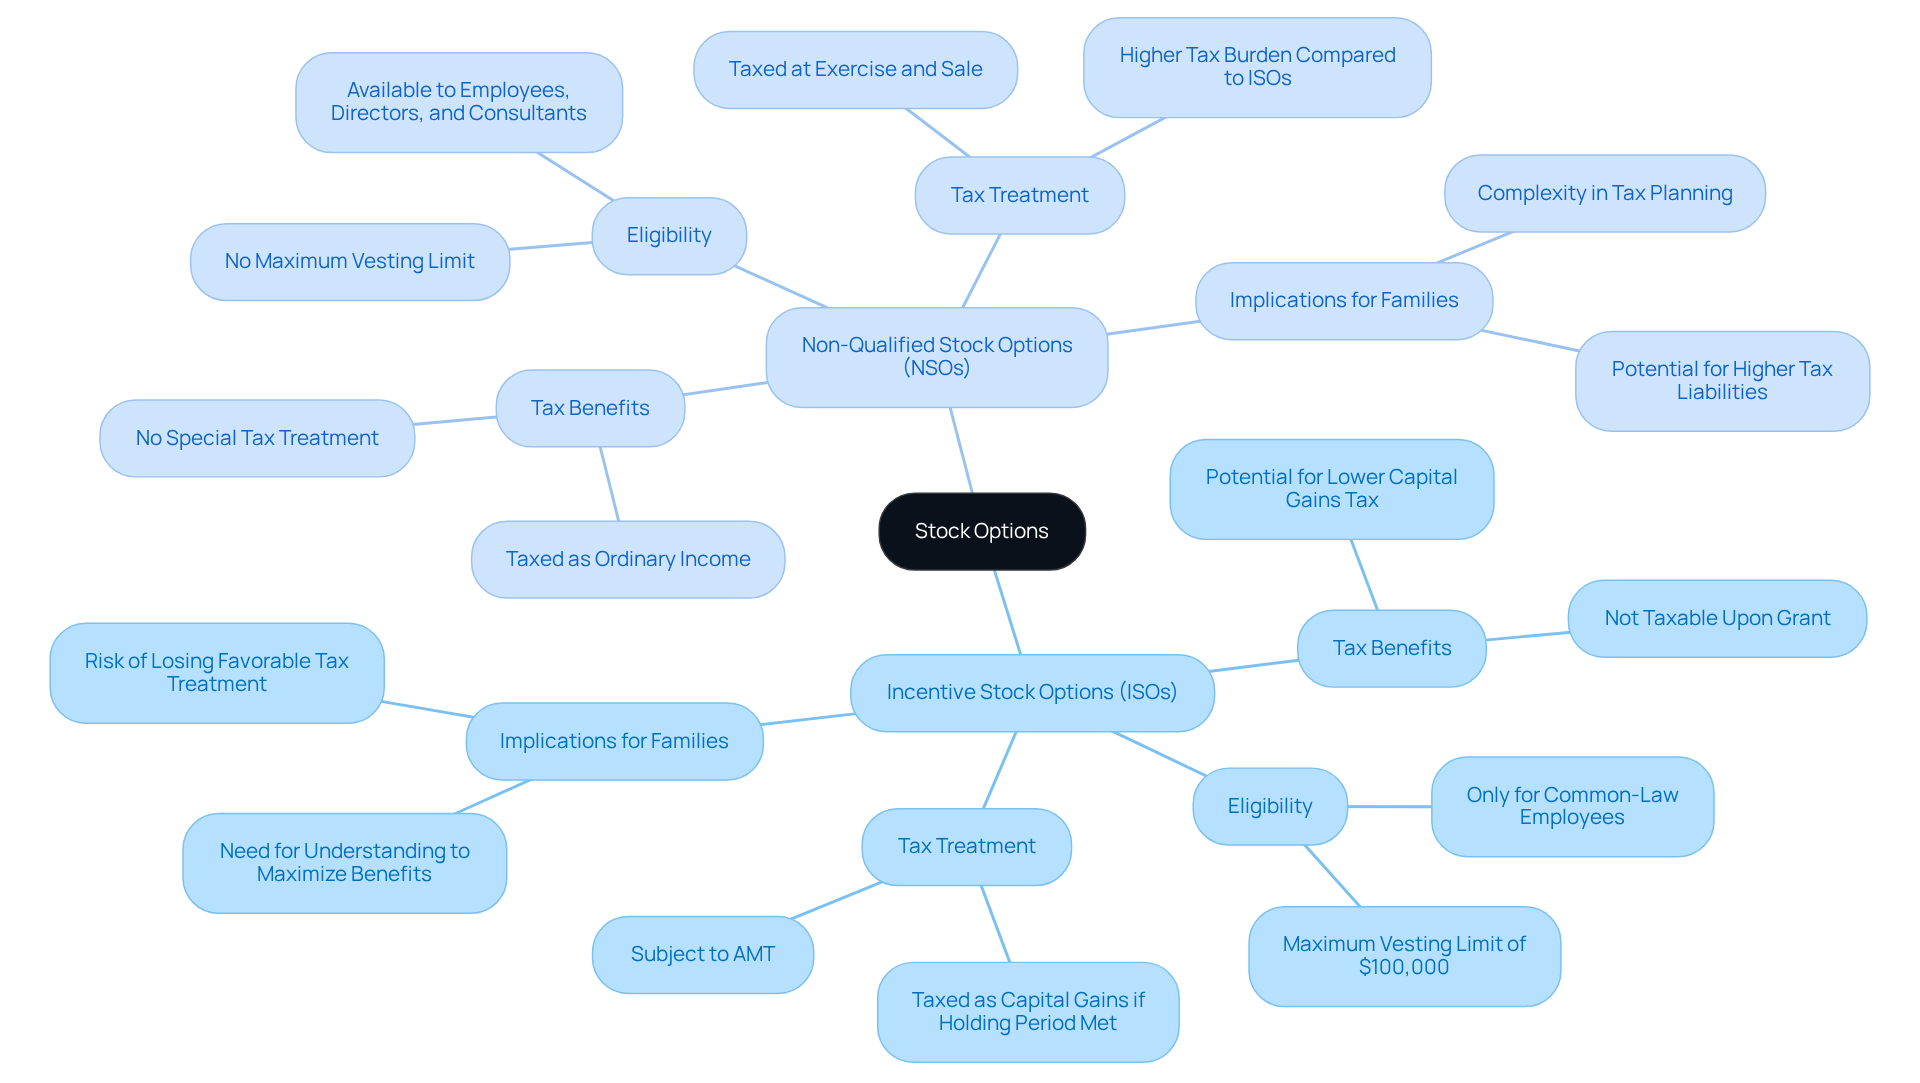
Imagine trying to secure your family’s future while navigating the complexities of incentive stock options vs non-qualified stock options after tender offer and taxes. Incentive Stock Options are special stock options just for employees, designed to offer tax benefits under certain conditions. They aim to inspire employees to help the company grow. If these options meet IRS regulations, like a maximum vesting amount of $100,000 per year and an exercise price equal to the fair market value at the time of the grant, they can provide significant tax advantages. For instance, if held long enough, they may be taxed at the lower capital gains rate.
On the other hand, when considering incentive stock options vs non-qualified stock options after tender offer, it is clear that Non-Qualified Stock Options can be granted to a wider range of service providers, including employees, directors, and consultants. Unlike their incentive counterparts, these options don’t enjoy special tax treatment. The income from exercising these options is taxed as regular income, which can be a surprise for families. This flexibility allows companies to reward various contributors, but it can leave families feeling lost in the maze of tax implications. If families don’t grasp these options, they could miss out on tax benefits that help them reach their financial goals.
Navigating the tax implications of stock options can feel overwhelming for families trying to plan for their future. Understanding these options can empower your family to make informed financial decisions that align with your values and goals.
Compare Tax Treatment and Eligibility of ISOs and NSOs
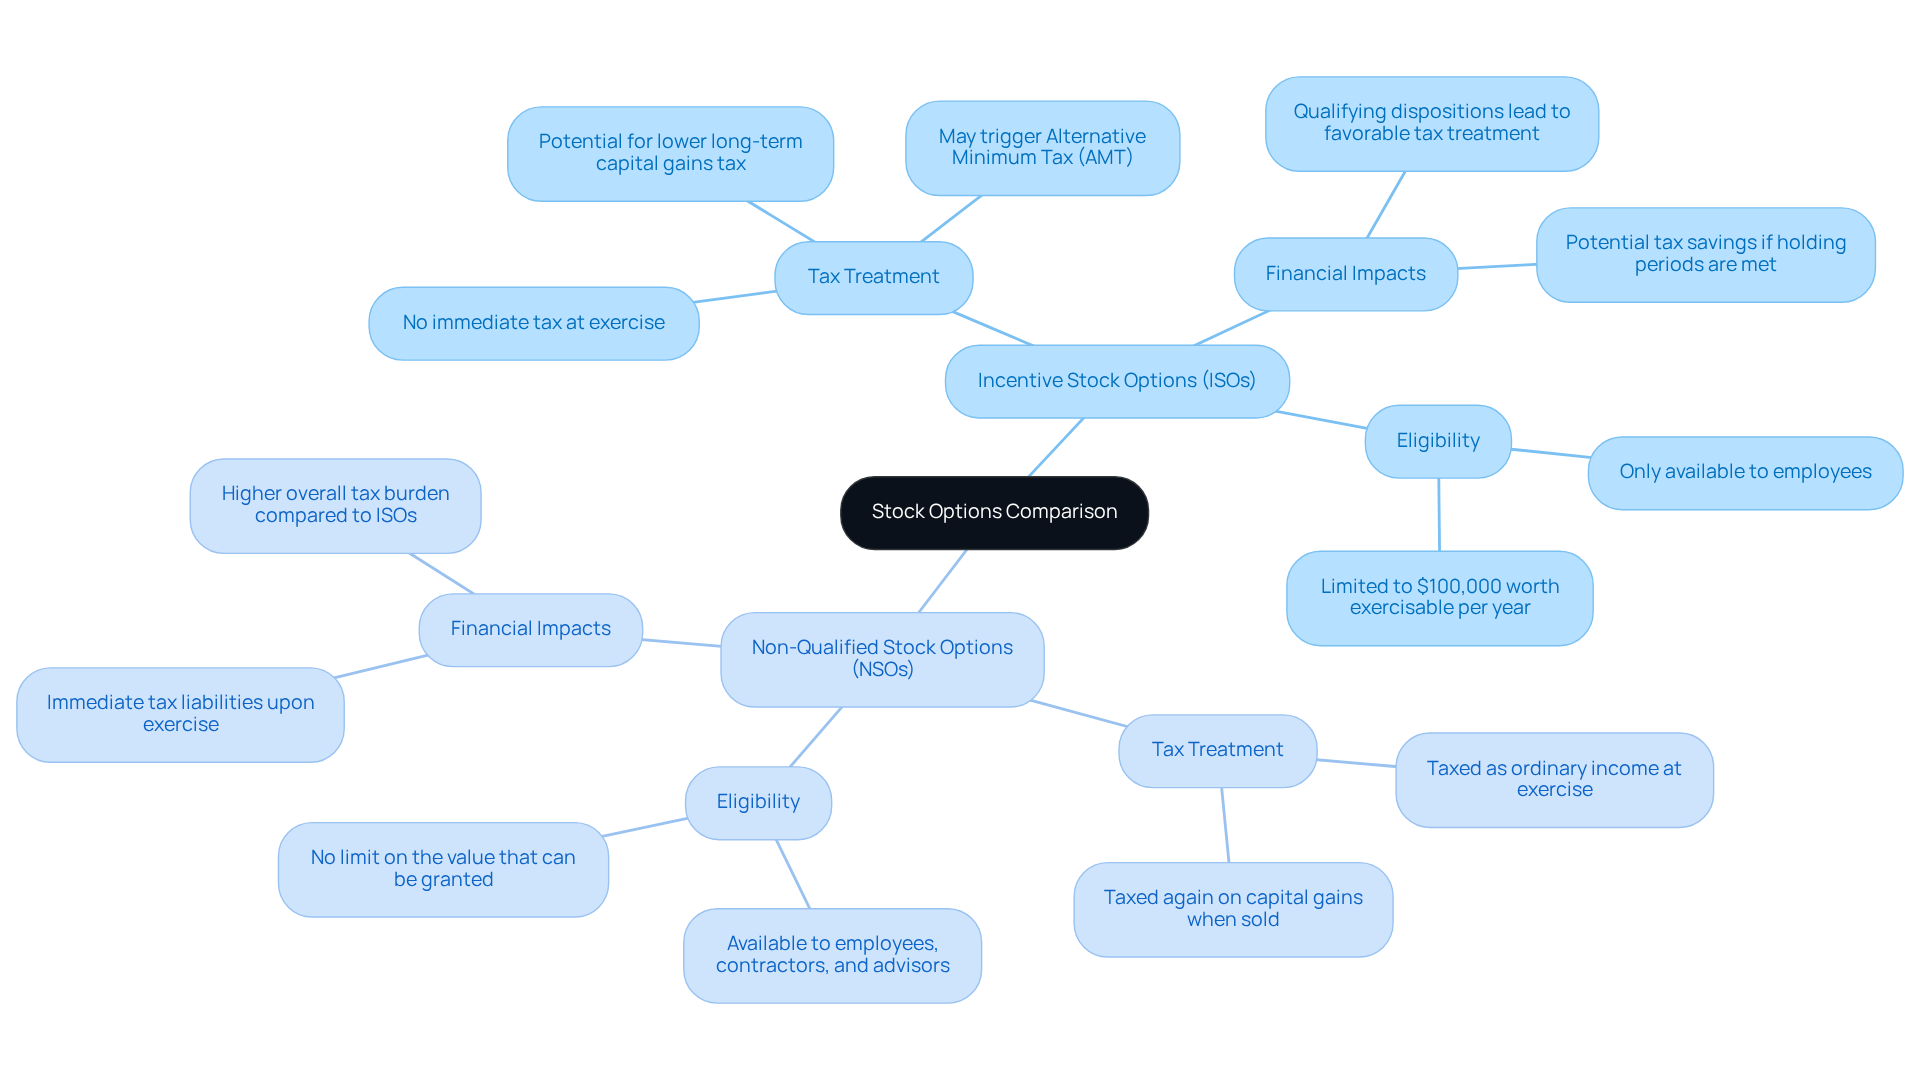
Navigating the world of stock options can feel daunting, especially when it comes to understanding how they impact your family’s financial future. With Incentive Stock Options, you won’t face immediate tax bills when you exercise them; instead, you can wait until you sell the shares to deal with taxes. By holding onto those shares for a year after you get them and two years after they’re granted, you could benefit from lower tax rates on any gains. This approach can mean real savings for your family, allowing you to invest in what truly matters to you.
On the other hand, Non-Qualified Stock Options hit you with taxes right when you use them, which can feel overwhelming. The taxable income is the difference between what you pay to exercise the option and the stock’s value at that moment. This means families using Non-Qualified Stock Options might face a bigger tax bill right away, which can be tough to manage. Plus, Non-Qualified Stock Options are available to more people, including contractors and consultants, giving families more options.
For instance, if employees exercise their options when the stock has gone up, they could face a hefty tax bill, which can be a shock for families. It’s important for families to understand the differences, including Incentive Stock Options vs Non-Qualified Stock Options after a tender offer, as they can shape your financial planning and future security. For example, families who took the time to understand and use their Incentive Stock Options wisely saved thousands in taxes, giving them peace of mind. As we look ahead, the tax landscape can feel complicated, but being informed about your stock options can help your family make the best choices for your future.
Evaluate Exercise Timing and Financial Outcomes for ISOs and NSOs
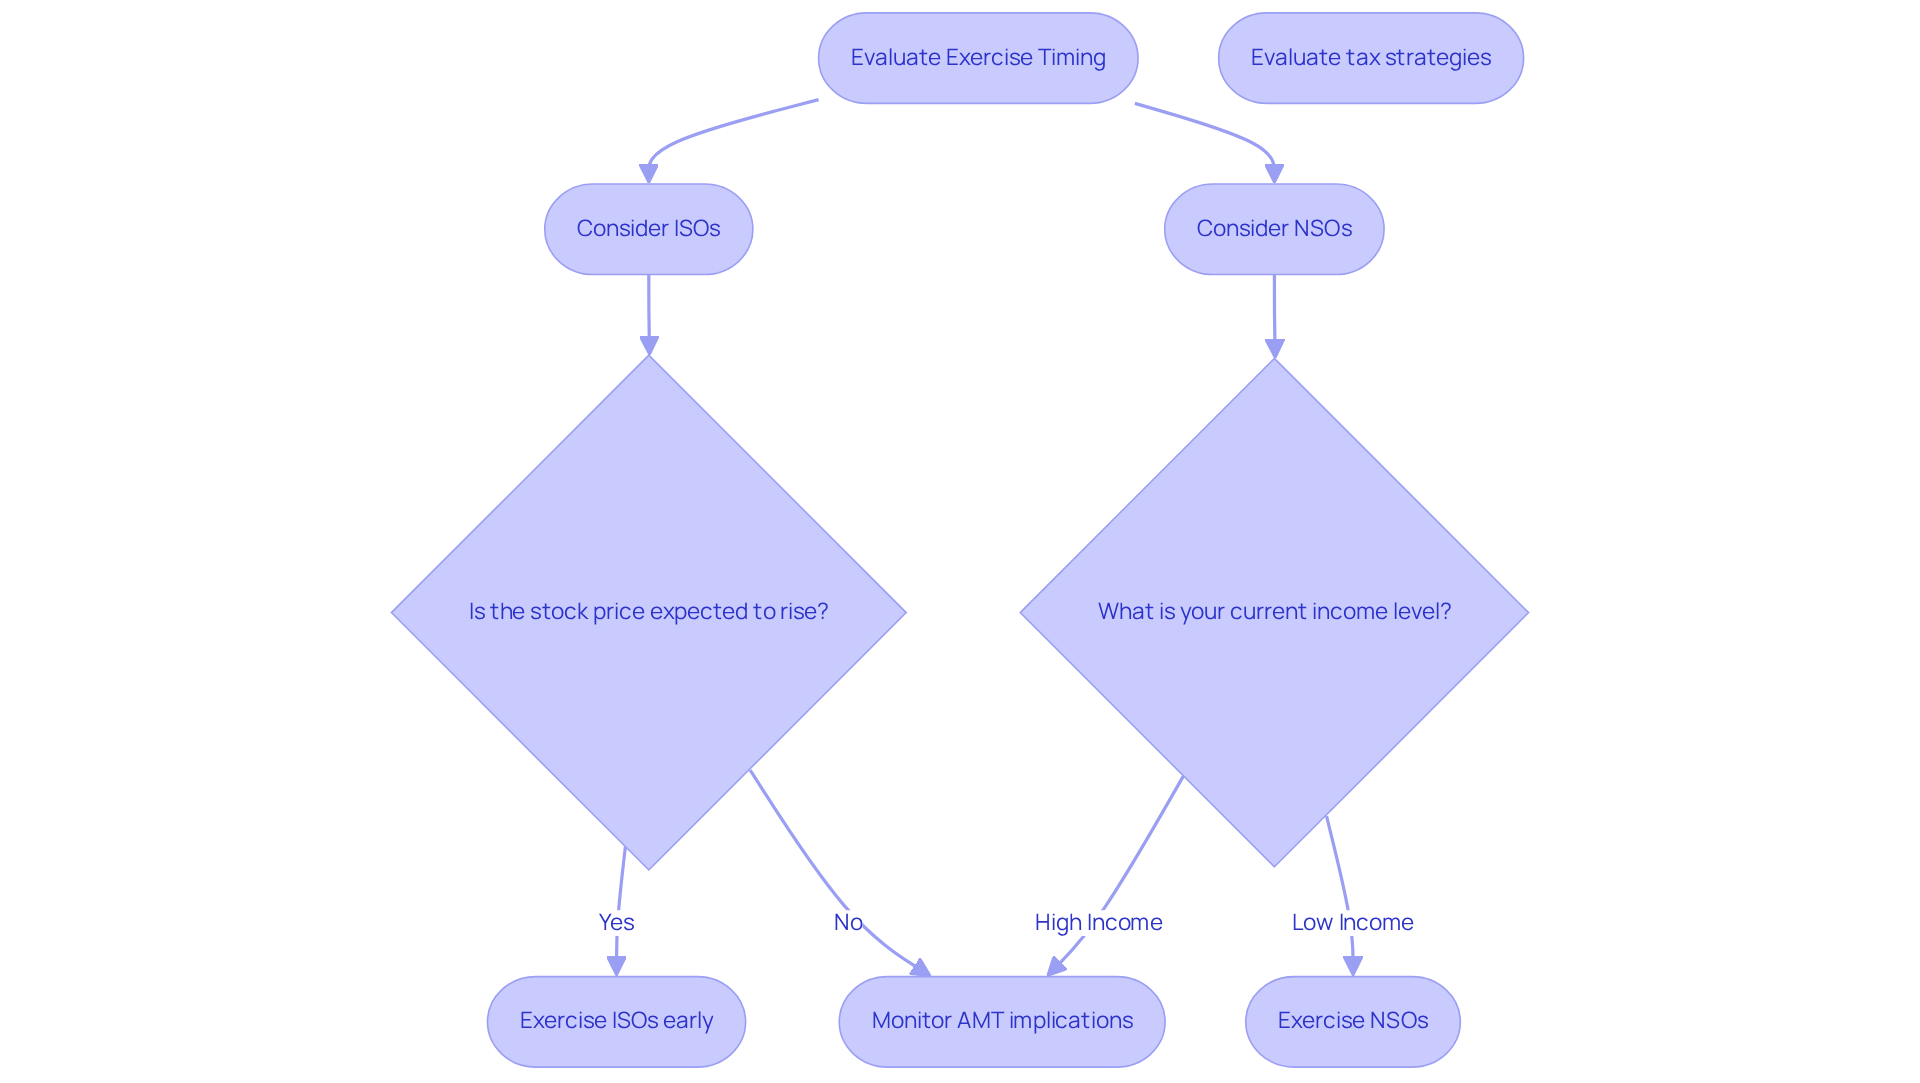
Imagine feeling uncertain about when to exercise your stock options, knowing that the timing could significantly impact your family’s financial future. The timing of exercising stock options can greatly influence financial outcomes in the context of incentive stock options vs non qualified stock options after tender offer. Acting early can be beneficial if you expect the share price to rise, as it locks in a lower purchase price and starts the holding period for long-term capital gains treatment. But be careful – this could lead to the Alternative Minimum Tax (AMT) if the difference between what you pay and the market value is significant. For example, if you exercise ISOs early in the year, you can better manage your taxes before the deadline, possibly using the sale proceeds to cover any AMT liabilities.
On the other hand, when to exercise your stock options often depends on how the stock is performing and your personal tax situation. Because stock options are taxed like regular income when you use them, it might be wise for families to act when their earnings are lower to lessen tax impacts. If the stock price is fluctuating, waiting to exercise until the price is right can help maximize your potential gains. For instance, if you have stock options with a big difference between the exercise price and market value, exercising during a low-income year can help lower your overall tax liability. It’s essential for parents to assess their finances and the market to find the best time to exercise their options, helping them make choices that support their long-term goals.
Consider the story of Emily and Mark, a couple who sought guidance from Bright Advisers to navigate their financial planning. Like many parents, they struggled to balance their busy careers with the need to manage their finances effectively. By implementing strategies to reduce debt, manage cash flow, invest wisely, and plan for retirement, they gained the flexibility to make career decisions based on their desired work-life balance. Similarly, Jay and Emma worked with Bright Advisers to create a sound financial strategy that included optimizing tax planning and evaluating education savings options, allowing them to balance their present responsibilities with long-term aspirations. By understanding the timing of your stock options, you can take control of your family’s financial journey and make choices that truly reflect your values and goals.
As always, it’s important to remember that past performance does not guarantee future results, and securities investments are subject to risk. For personalized advice, families can reach out to Bright Advisers, where services are provided through Lifeworks Advisors, a registered investment adviser.
Assess Strategic Considerations for Choosing ISOs vs. NSOs
Navigating the choice between incentive stock options vs non-qualified stock options after tender offer can be daunting for families, especially when considering the long-term impact on your financial future.
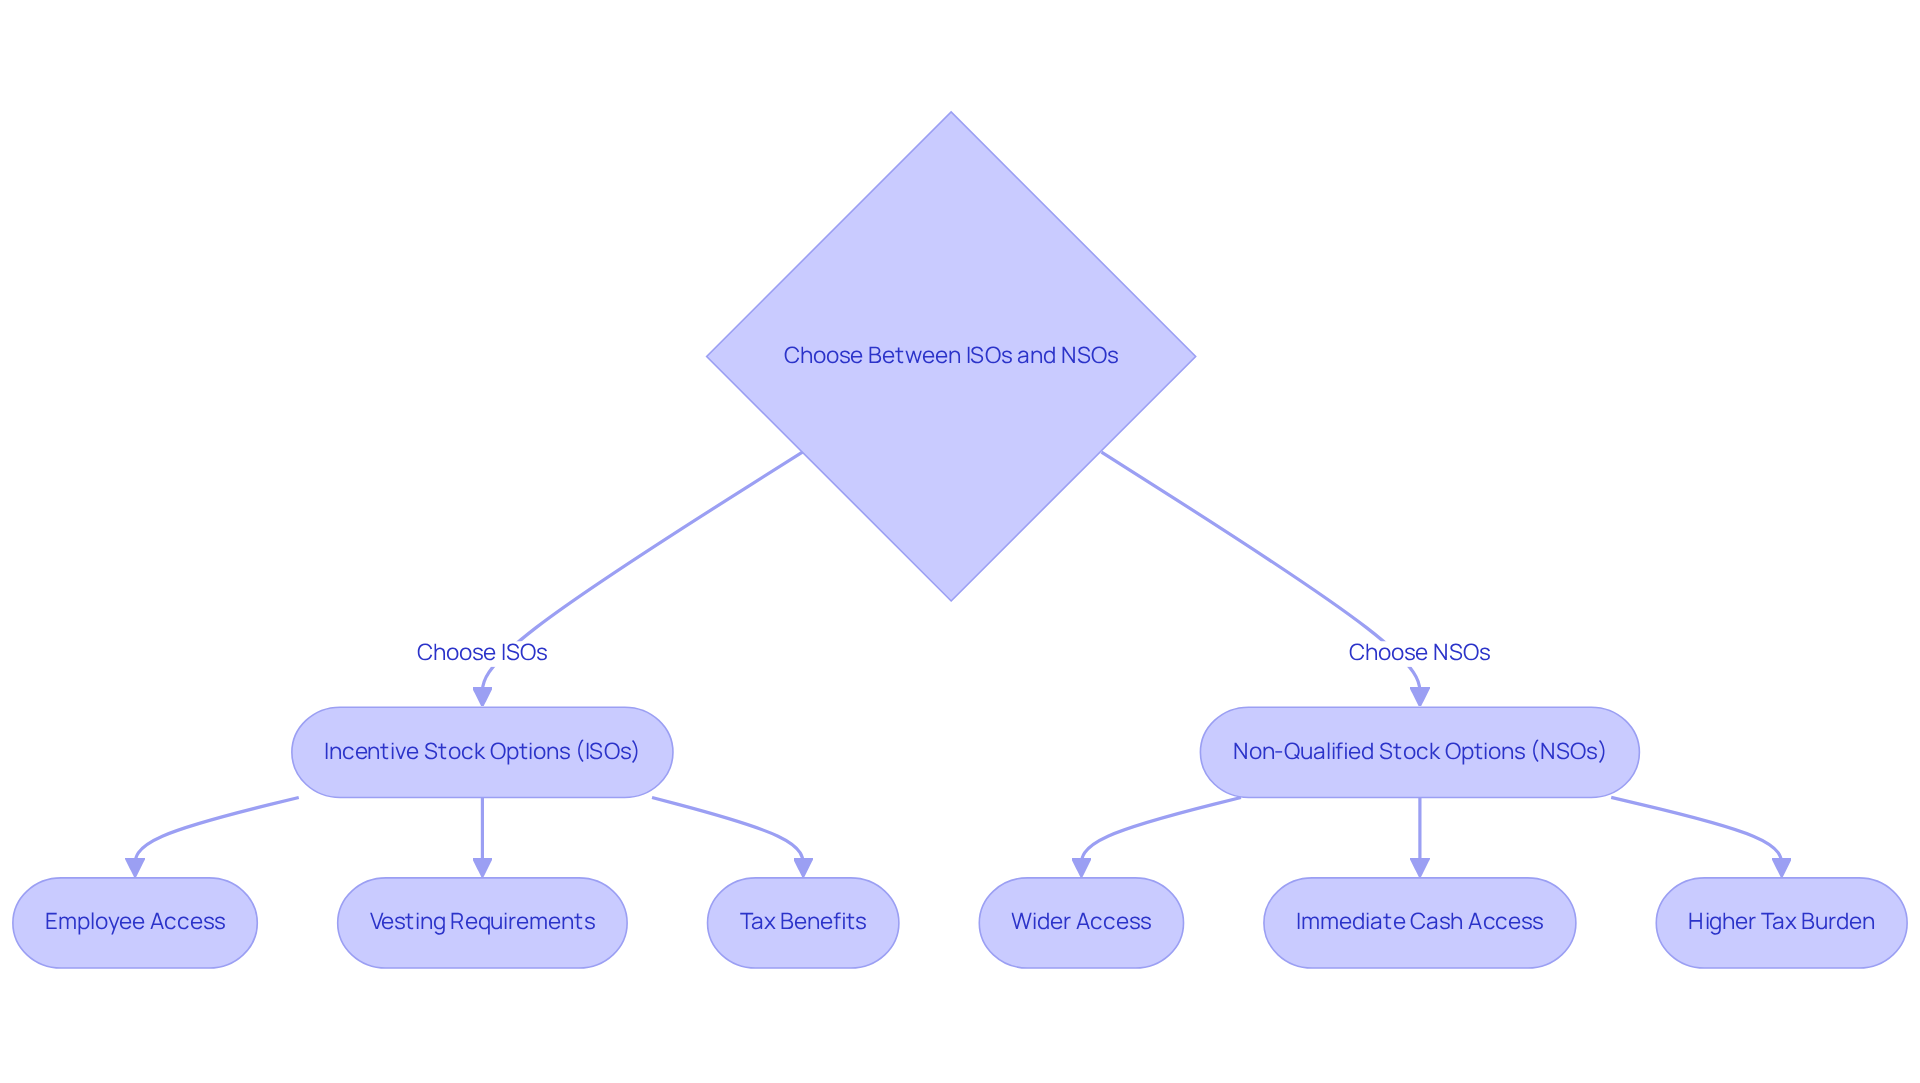
First, think about who can access these options. Incentive stock options are only available to employees and come with specific vesting and holding period requirements. In contrast, non-qualified stock options can be awarded to a wider range of service providers, including consultants and advisors.
It’s important to consider how taxes will impact your decisions on incentive stock options vs non-qualified stock options after tender offer. Families should assess their current and anticipated income levels to determine the implications of incentive stock options vs non-qualified stock options after tender offer on their overall tax burden. Stock options can provide tax benefits if the shares are held long enough to qualify for long-term capital gains treatment. This means holding the stock for at least one year after the option is granted and two years after the award date. On the flip side, NSOs offer quicker access to cash but are taxed as regular income when exercised, which can lead to a higher tax burden.
If your family is looking for long-term growth and can wait a bit, stock options might be the better choice. For example, if you exercise 100,000 ISOs at a $1 strike price when the fair market value is $5, you could face a $400,000 spread that may be subject to Alternative Minimum Tax (AMT) but not ordinary income tax at exercise. However, if immediate access to cash is a priority, NSOs may be more suitable, as they allow for quicker realization of gains, albeit at a higher tax rate.
By taking the time to consider these factors, you can make choices that truly fit your family’s needs and goals. Remember, we’re here for you as you navigate this journey.
Conclusion
Navigating the world of stock options can feel overwhelming, especially when considering how they affect your family’s financial well-being. Each option has its own set of benefits and challenges, and it’s important to consider how they can shape your family’s financial journey. Understanding these options can empower your family to make choices that truly reflect your values and aspirations.
We’ve explored important insights about how these options work, including their tax implications and who can benefit from them.
- ISOs can offer tax benefits if you hold onto them, while NSOs might be more flexible but come with immediate tax responsibilities.
- When you decide to exercise these options can greatly affect your family’s finances, so thoughtful planning is key.
Choosing between ISOs and NSOs should reflect your family’s unique financial needs and dreams. Taking the time to understand these options can help your family navigate the complexities of stock options with greater ease and confidence. If you’re looking for personalized support, we invite you to connect with Bright Advisers, where our team is ready to help you on this journey. Together, we can make choices that secure your family’s financial future for generations to come.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options are special stock options designed specifically for employees, offering potential tax benefits if certain IRS regulations are met, such as a maximum vesting amount of $100,000 per year and an exercise price equal to the fair market value at the time of the grant.
What tax advantages do Incentive Stock Options provide?
If Incentive Stock Options are held long enough and meet IRS regulations, they may be taxed at the lower capital gains rate, which can result in significant tax savings.
What are Non-Qualified Stock Options (NSOs)?
Non-Qualified Stock Options can be granted to a broader range of service providers, including employees, directors, and consultants. Unlike Incentive Stock Options, they do not receive special tax treatment.
How is income from Non-Qualified Stock Options taxed?
The income from exercising Non-Qualified Stock Options is taxed as regular income, which can lead to unexpected tax implications for families.
Why is it important for families to understand stock options?
Understanding the differences between Incentive Stock Options and Non-Qualified Stock Options can help families navigate tax implications and make informed financial decisions that align with their goals.
What challenges do families face when dealing with stock options?
Families may feel overwhelmed by the complexities of stock options and their tax implications, which can hinder their ability to plan effectively for their financial future.
List of Sources
- Define Incentive Stock Options and Non-Qualified Stock Options
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- Incentive Stock Options Tax Impacts (https://team.monetagroup.com/team/duff-torney/who-we-serve/executives/resources-for-executives/incentive-stock-options-tax-impacts)
- Non Qualified Stock Options (https://insightsoftware.com/encyclopedia/non-qualified-stock-options)
- Differences Between Incentive Stock Options and Nonqualified Stock Options | Davis Wright Tremaine (https://dwt.com/blogs/startup-law-blog/2020/07/differences-between-iso-nso)
- Compare Tax Treatment and Eligibility of ISOs and NSOs
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- ISO vs NSO: What’s the Difference? Tax & Eligibility (https://esofund.com/blog/difference-iso-nso)
- ISOs vs NSOs Tax Treatment: 2026 Complete Guide – Uncle Kam (https://unclekam.com/tax-strategy-blog/isos-vs-nsos-tax-treatment-2026-complete-guide)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- Evaluate Exercise Timing and Financial Outcomes for ISOs and NSOs
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- When Should I Exercise Stock Options? | Summitry (https://summitry.com/blog/when-to-exercise-stock-options)
- Exercising Stock Options: Taxes, Timing & Strategies (https://jpmorganworkplacesolutions.com/insights/exercise-stock-options)
- When to Exercise Stock Options at a Startup: ISO & AMT Guide (https://thestartuplawblog.com/when-to-exercise-stock-options-startup)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- Assess Strategic Considerations for Choosing ISOs vs. NSOs
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- ISOs vs. NSOs: Key Differences (2026) (https://thestartuplawblog.com/iso-vs-nso-stock-options-complete-guide)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading