

Key Highlights
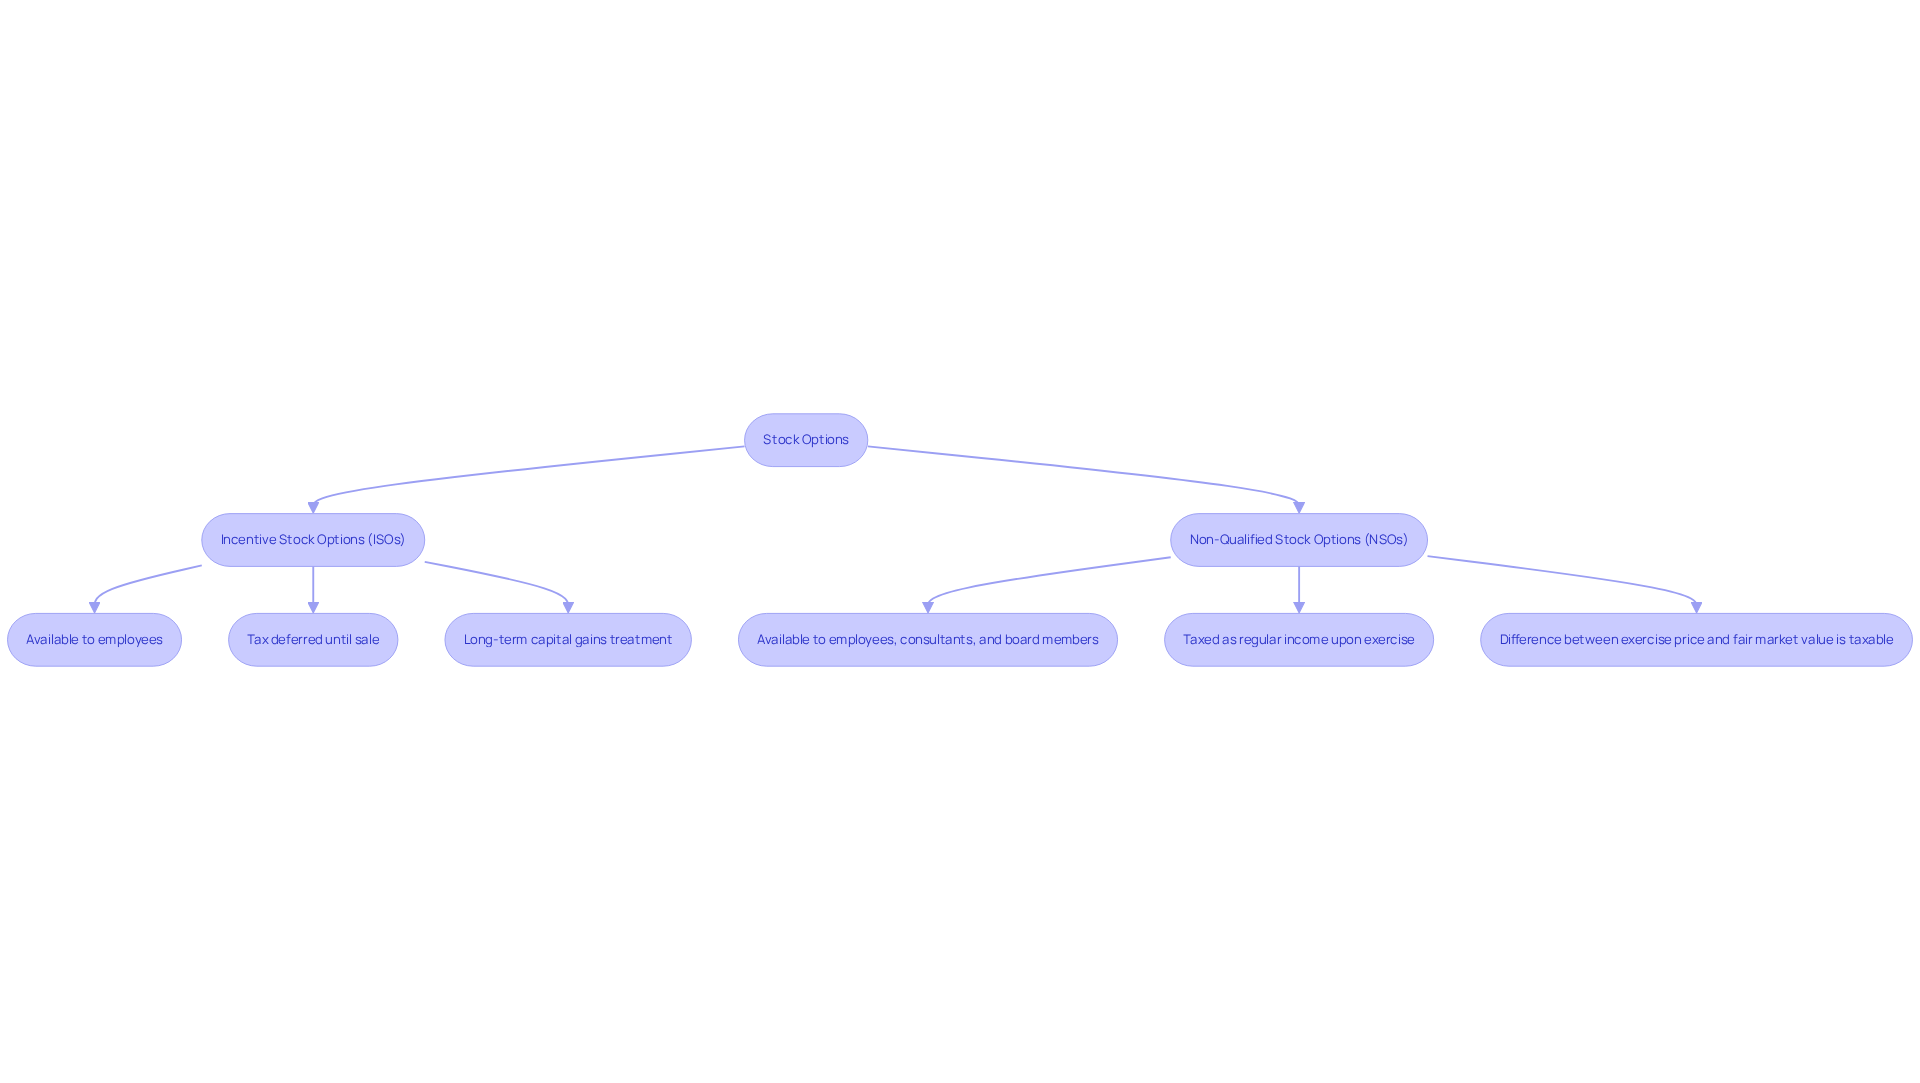
- Incentive Stock Options (ISOs) are available only to employees and allow for tax deferral until shares are sold, potentially qualifying for long-term capital gains treatment.
- Non-Qualified Stock Options (NSOs) can be granted to a wider range of individuals and are taxed as ordinary income upon exercise.
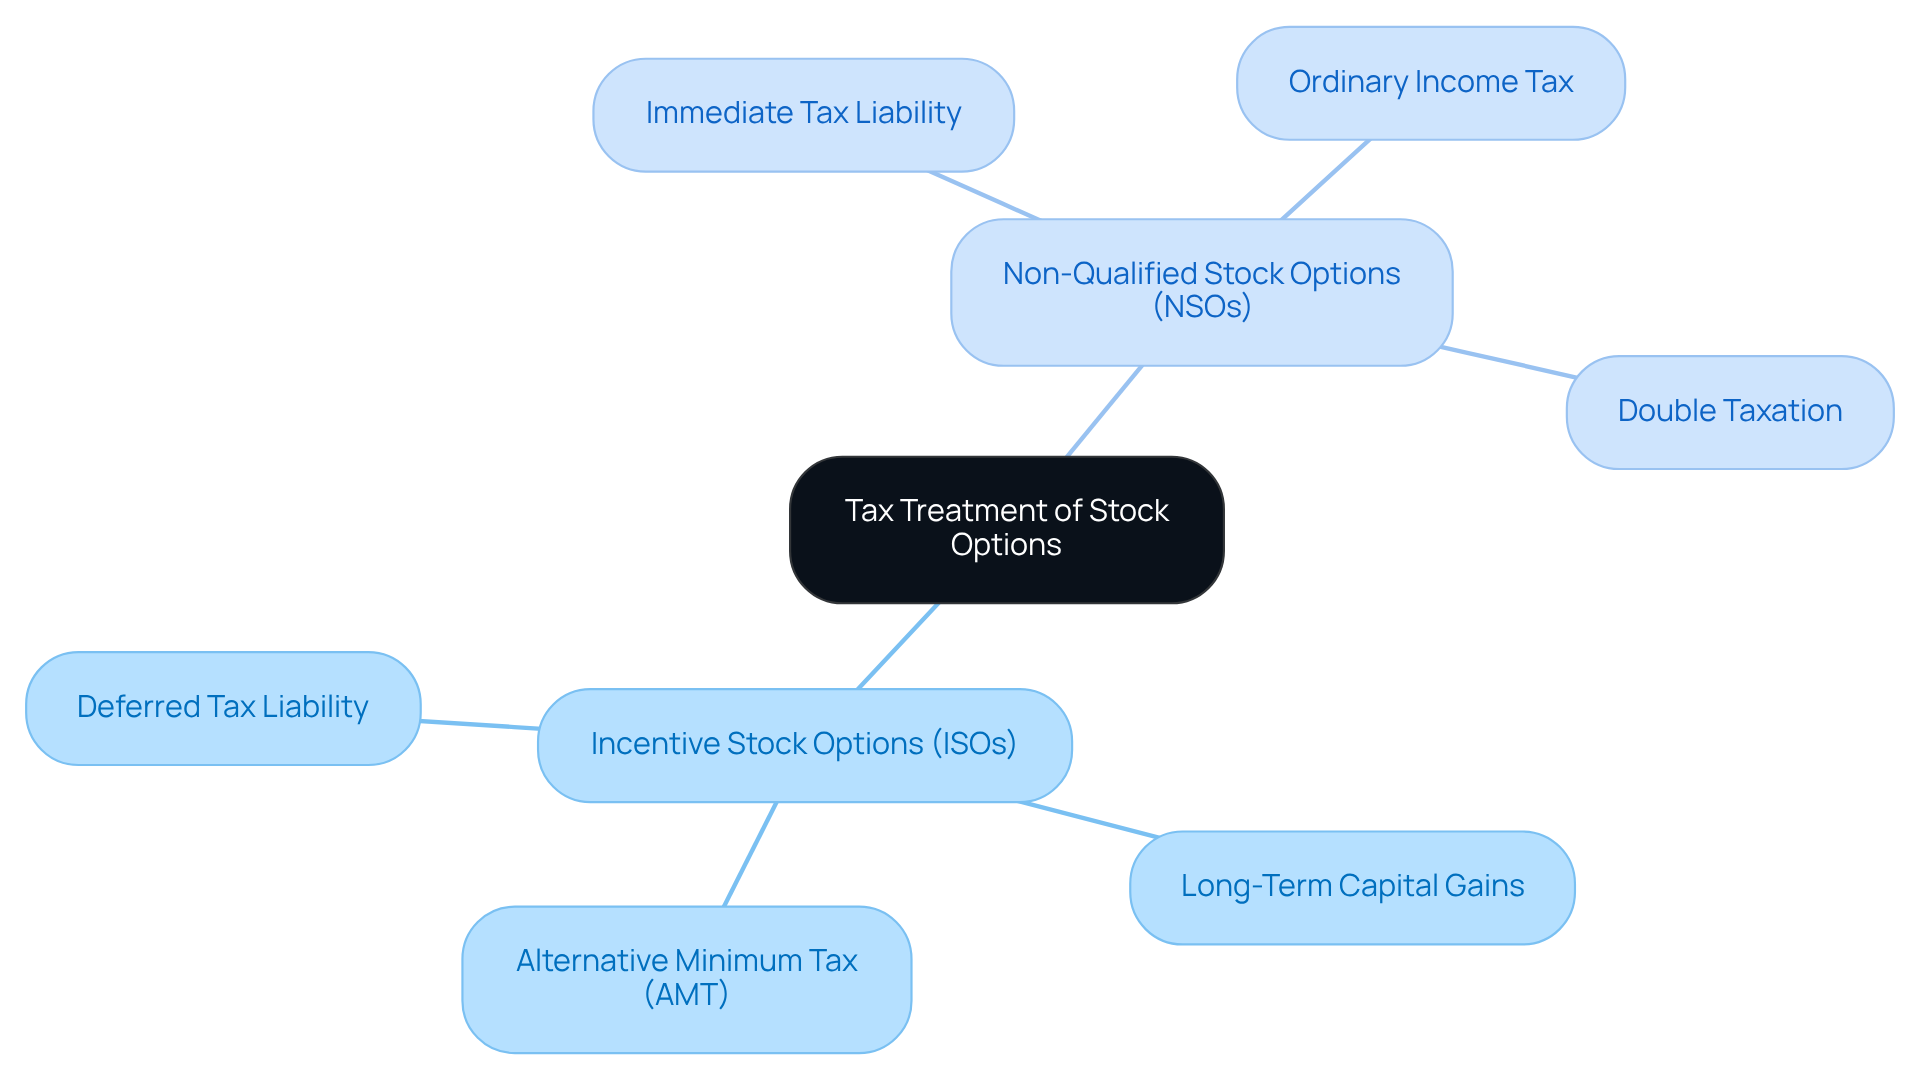
- Exercising ISOs may trigger the Alternative Minimum Tax (AMT), which families should consider in their tax planning.
- NSOs are subject to double taxation, as the difference between exercise price and fair market value is taxed as ordinary income, Social Security tax, and Medicare tax.
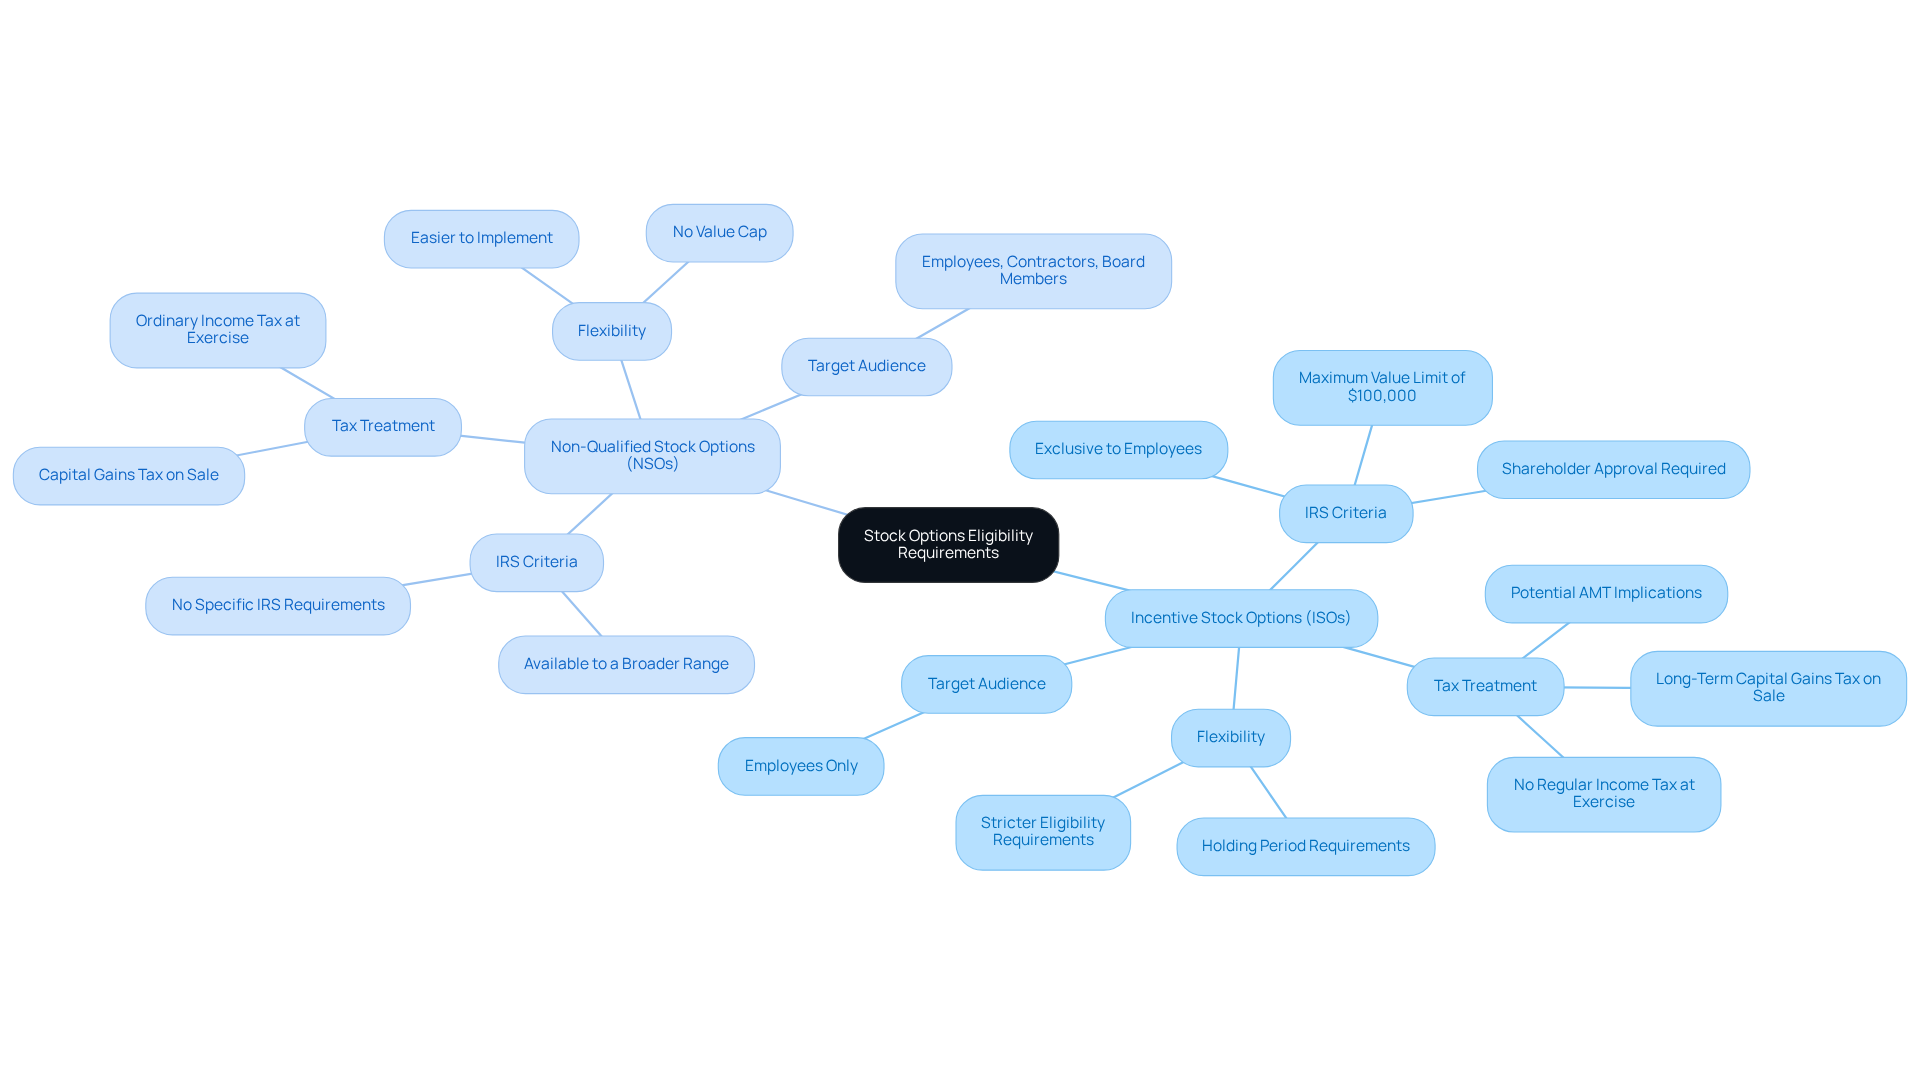
- ISOs must meet specific IRS criteria, including a $100,000 limit on exercisable stock options per year and a minimum holding period for favourable tax treatment.
- NSOs offer more flexibility for companies and can be granted without specific IRS requirements, making them easier to implement.
- Understanding the differences between ISOs and NSOs is crucial for families to make informed financial decisions and plan for potential tax liabilities.
Introduction
Imagine feeling overwhelmed by the complexities of stock options while trying to secure your family’s financial future. Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs) each present unique tax implications that can significantly impact your family’s financial planning. Understanding these differences is crucial, as the choices made today can influence long-term wealth and stability. Together, we can explore how families can leverage these options to ease tax burdens and enhance financial potential.
Define Incentive Stock Options and Non-Qualified Stock Options
Navigating the world of stock options can feel overwhelming, especially when you’re trying to secure your family’s future.
Incentive Stock Options can be a great way to help your family save on taxes, but they come with specific rules to follow. These options are only available to employees and must meet certain criteria to qualify. When you exercise these options, you won’t face immediate income tax; instead, taxes are deferred until you sell the shares. This can lead to long-term capital gains treatment if you hold onto them for the required period.
On the other hand, Non-Qualified Stock Options offer more flexibility. They can be granted to a wider range of individuals, including employees, consultants, and board members. However, unlike incentive stock options, these are taxed as regular income when exercised. This means that the difference between the exercise price and the fair market value of the stock at that time is subject to income tax.
Understanding the incentive stock options vs non-qualified stock options tax implications can truly help your family navigate financial planning with confidence and clarity. We’re here for you as you explore these options and make the best choices for your family’s future.
Compare Tax Treatment of ISOs and NSOs
Navigating the tax treatment of stock options can feel daunting for families, especially when every decision impacts your financial future.
-
Incentive Stock Options: Exercising these options doesn’t mean you’ll face immediate tax liability; instead, taxes are deferred until you sell the shares. If you hold onto those shares for more than a year after exercising and two years after the grant date, your profits could be taxed at the long-term capital gains rate, which is usually lower than ordinary income tax rates. But keep in mind, exercising stock options could lead to the Alternative Minimum Tax (AMT). It’s something families need to think about in their tax planning.
-
Non-Qualified Stock Options: On the other hand, these options are taxed right when you exercise them. The difference between the exercise price and the fair market value of the stock is treated as ordinary income, which means it’s subject to income tax, Social Security tax, and Medicare tax. This double taxation can feel like a heavy weight for families, especially if the stock appreciates significantly before exercise.
It’s important for families to understand the incentive stock options vs non-qualified stock options tax implications, as these differences can influence decisions on when to exercise options and how to plan for potential tax liabilities. Consulting with a tax advisor is essential to navigate these complexities effectively. By understanding these differences, you can make informed decisions that protect your family’s financial well-being.
Eligibility Requirements for ISOs and NSOs
Imagine feeling uncertain about your family’s financial future because of complex stock options. Understanding the incentive stock options vs non qualified stock options tax implications is crucial for families planning their financial futures.
-
Incentive Stock Options (ISOs): These options are exclusive to employees and must meet specific IRS criteria for favorable tax treatment. They need to be granted under a plan approved by shareholders, and employees must hold the shares for a minimum period to enjoy long-term capital gains tax rates. Additionally, there’s a limit of $100,000 on the value of stock options that can become exercisable in a calendar year. For families like Jay and Emma, who are focused on reducing monetary anxiety and planning for their children’s education, understanding ISOs can empower them to make informed choices about their compensation packages and long-term strategies. We’re here to help you create a financial plan that works for your family.
-
Non-Qualified Stock Options (NSOs): These options offer more flexibility and can be granted to a broader range of individuals, including employees, consultants, and board members. With no specific IRS requirements, they are easier for companies to implement. This flexibility allows businesses to tailor their compensation packages to attract and retain talent across various roles. For young families like Emily and Mark, who are balancing demanding careers with personal life, NSOs can provide additional financial opportunities that align with their goals of achieving stability and security. Together, we can navigate the complexities of your financial journey and incorporate these options into your overall strategy.
Comprehending these eligibility criteria is essential for families, as it can influence their budgeting and the potential advantages they can gain from the incentive stock options vs non qualified stock options tax implications. By understanding these options, families can unlock potential financial benefits that pave the way for a more secure future.
Conclusion
Many families feel overwhelmed by the complexities of stock options, but understanding the differences between Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs) can empower them to make informed financial decisions. Each type of stock option presents unique tax implications that can significantly impact a family’s financial planning and future wealth. By grasping these distinctions, families can better navigate their options and align them with their long-term financial goals.
The article highlights key aspects of both ISOs and NSOs, including their tax treatments and eligibility requirements. ISOs offer potential tax advantages, such as deferred taxation and the possibility of long-term capital gains, but come with specific criteria that must be met. In contrast, NSOs provide greater flexibility and can be granted to a wider range of individuals, but they are taxed as ordinary income upon exercise. Understanding these nuances allows families to strategize effectively, ensuring they maximize their benefits while minimizing tax liabilities.
Choosing the right stock option can shape your family’s financial future in ways you might not expect. Families are encouraged to consult with a tax advisor to navigate these complexities and develop a comprehensive financial plan. By taking the time to understand these options, families can pave the way for a secure financial future that aligns with their values and dreams.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options are a type of stock option available only to employees that can provide tax benefits. They allow employees to defer income tax until the shares are sold, potentially qualifying for long-term capital gains treatment if held for the required period.
What are Non-Qualified Stock Options (NSOs)?
Non-Qualified Stock Options are stock options that can be granted to a broader range of individuals, including employees, consultants, and board members. Unlike ISOs, NSOs are taxed as regular income when exercised, meaning the difference between the exercise price and the fair market value at that time is subject to income tax.
What are the tax implications of exercising Incentive Stock Options?
When you exercise Incentive Stock Options, you do not face immediate income tax. Instead, taxes are deferred until you sell the shares, which can lead to long-term capital gains treatment if the shares are held for the required period.
How are Non-Qualified Stock Options taxed?
Non-Qualified Stock Options are taxed as regular income at the time of exercise. The taxable amount is the difference between the exercise price and the fair market value of the stock at that time.
Why is it important to understand the differences between ISOs and NSOs?
Understanding the differences in tax implications between Incentive Stock Options and Non-Qualified Stock Options can help families navigate financial planning with confidence and make informed decisions regarding their stock options.
List of Sources
- Define Incentive Stock Options and Non-Qualified Stock Options
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- Incentive Stock Options vs. Non Qualified Stock Options (https://zajacgrp.com/insights/comparing-incentive-stock-options-and-non-qualified-stock-options)
- Incentive stock options (ISOs) and taxes: the complete guide — Secfi (https://secfi.com/learn/iso-incentive-stock-options-tax-treatment)
- Non-Qualified Stock Options (NSO): How NSOs Work (https://carta.com/learn/equity/stock-options/nso)
- The $115,000 ISO Tax Trap: Why Exercising Stock Options in One Year Can Backfire (https://finance.yahoo.com/markets/options/articles/115-000-iso-tax-trap-115336213.html)
- Compare Tax Treatment of ISOs and NSOs
- ISO vs NSO: The Tax Implications (https://brightonjones.com/blog/iso-vs-nso)
- How Stock Options Are Taxed: ISO vs NSO | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/how-are-stock-options-taxed)
- Incentive Stock Options vs. Non Qualified Stock Options (https://zajacgrp.com/insights/comparing-incentive-stock-options-and-non-qualified-stock-options)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- ISOs vs. NSOs: Equity Tax Strategies | Dark Horse CPAs (https://darkhorse.cpa/blog/incentive-stock-options-vs-nonqualified-stock-options)
- Eligibility Requirements for ISOs and NSOs
- Non-Qualified Stock Options (NSO): How NSOs Work (https://carta.com/learn/equity/stock-options/nso)
- Internal Revenue Bulletin: 2004-36 | Internal Revenue Service (https://irs.gov/irb/2004-36_IRB)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- Non-Qualified Stock Options Explained (Plus What They Mean for Your Company’s Taxes) | Warren Averett CPAs & Advisors (https://warrenaverett.com/insights/non-qualified-stock-options)
- Equity Compensation: Incentive Stock Options and Non-Qualified Stock Options – Rubin Rudman (https://rubinrudman.com/article/equity-compensation-incentive-stock-options-and-non-qualified-stock-options)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading