

Key Highlights:
- Independent Broker-Dealers (IBDs) operate independently from larger institutions and are registered with FINRA, earning commissions on trades and sales.
- Registered Investment Advisors (RIAs) provide investment advice and management services for a fee, regulated by the SEC or state regulators, and adhere to a fiduciary standard.
- The number of independent RIAs is projected to grow, while IBDs are expected to decline, reflecting a shift towards fee-based advisory models emphasising transparency.
- IBDs focus on transactional services and may have conflicts of interest due to commission-based compensation, while RIAs offer comprehensive planning services tailored to clients’ needs.
- RIAs typically operate on a fee-only model, aligning their success with clients’ financial goals and fostering a collaborative relationship.
- Research indicates RIAs with performance-based incentives achieve better client outcomes, enhancing long-term financial health over short-term sales tactics.
- Choosing an RIA can lead to impartial guidance, ensuring advice is tailored to unique family needs and aspirations.
Introduction
Navigating the complexities of financial advice can feel overwhelming, especially for young families eager to secure their financial futures. Imagine standing at a crossroads, faced with the choice between an Independent Broker-Dealer (IBD) and a Registered Investment Advisor (RIA). Each path offers unique advantages and approaches to wealth management, and understanding these differences is crucial for your family’s journey.
IBDs often provide a variety of investment products, many of which are tied to commissions. On the other hand, RIAs operate under a fiduciary standard, meaning they prioritize your best interests above all else. It’s important to understand how these models can impact your financial decisions and, ultimately, your family’s well-being.
As the financial landscape shifts towards transparency and personalized service, how can you determine which model aligns best with your values and long-term goals? Consider what matters most to your family. Are you looking for a partner who will put your needs first? Or do you prefer a broader range of investment options?
Together, we can navigate this journey. By exploring these options, you can find the right fit for your family’s financial aspirations. Remember, you’re not alone in this process. We’re here for you, ready to provide the support and guidance you need to make informed decisions that resonate with your family’s values.
Define Independent Broker-Dealer and RIA
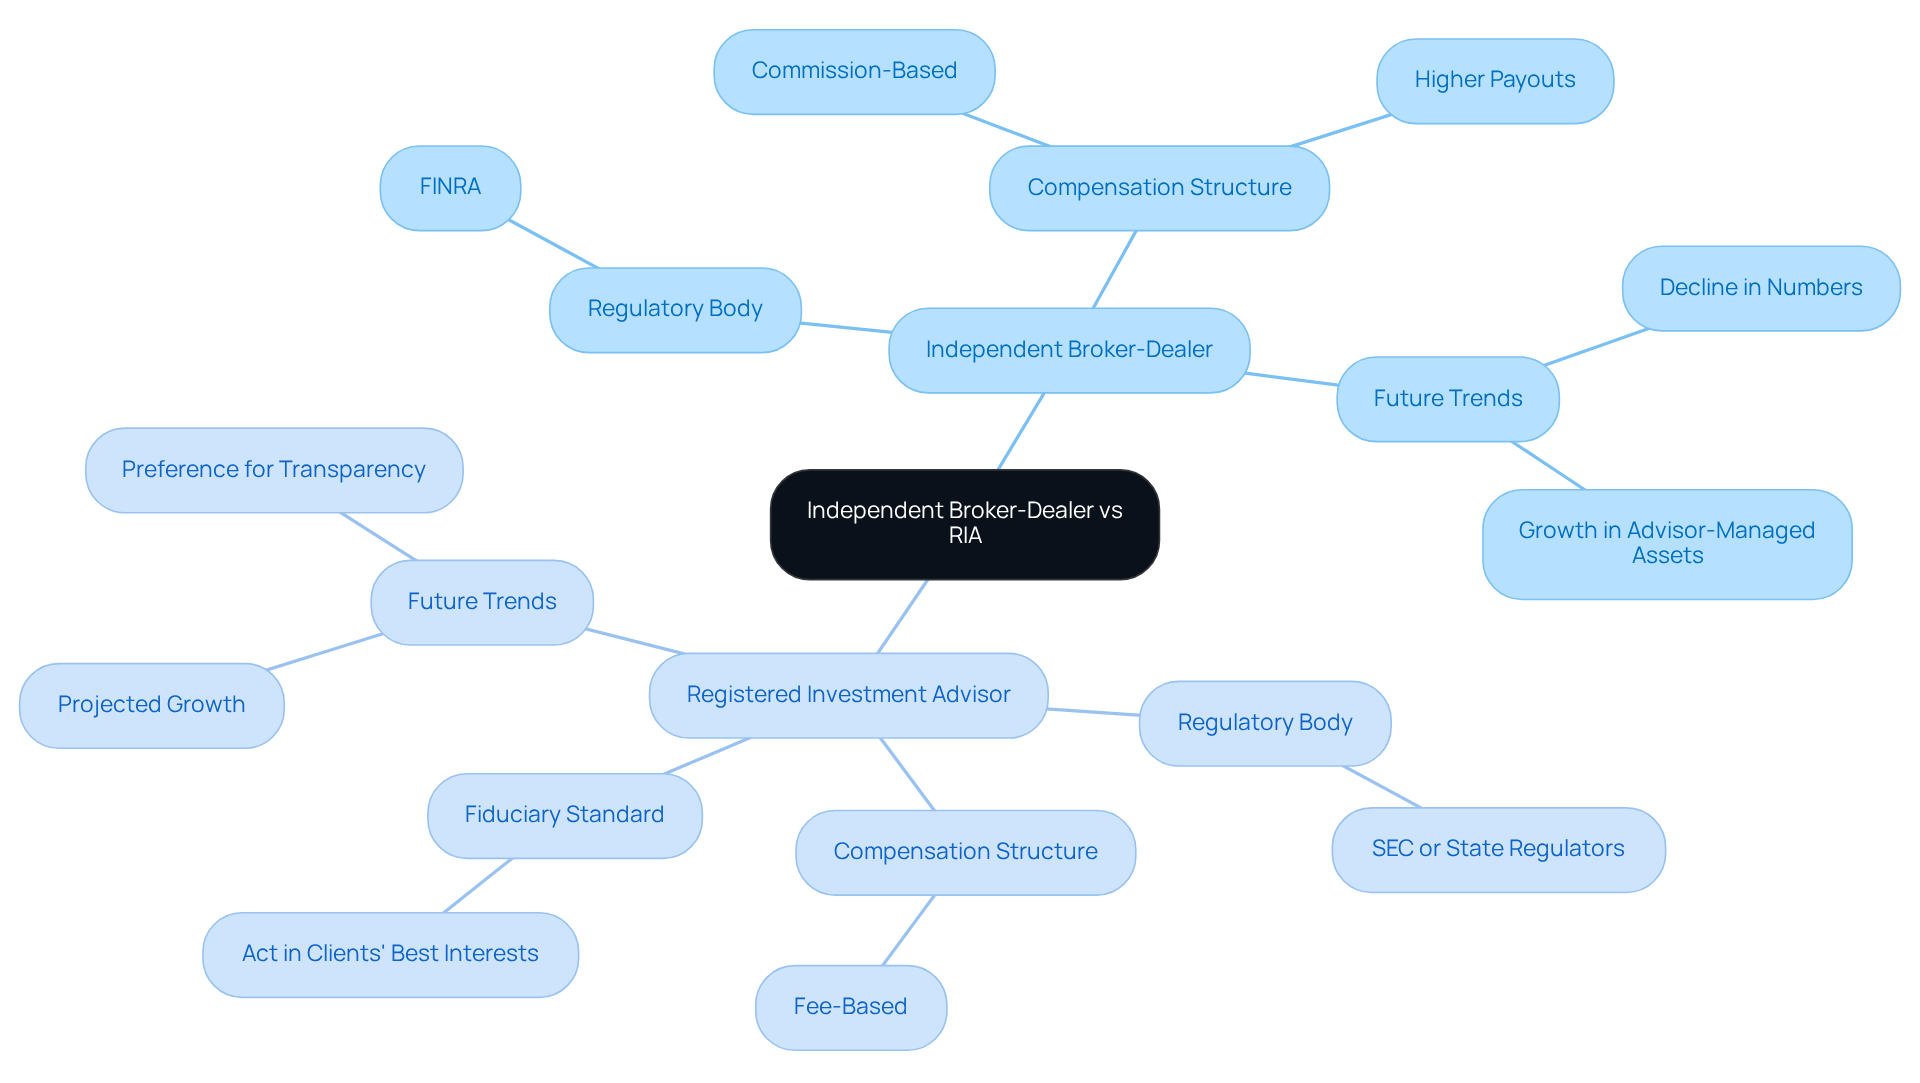
Imagine navigating the world of investments with a trusted partner by your side. An Independent Broker-Dealer (IBD) operates independently from larger institutions, which illustrates the independent broker dealer vs RIA distinction, allowing advisors to offer a wide range of investment products and services tailored to your family’s needs. Registered with the Financial Industry Regulatory Authority (FINRA), IBDs typically earn commissions on trades and sales, but it’s essential to understand how this impacts your financial journey.
On the other hand, when considering independent broker dealer vs RIA, a Registered Investment Advisor (RIA) can be a firm or an individual dedicated to providing investment advice and management services for a fee. They are regulated by the Securities and Exchange Commission (SEC) or state regulators, ensuring a level of trust and accountability. What sets RIAs apart is their , which means they are legally obligated to act in your best interests. This is crucial for families looking to secure their financial futures, as it ensures that the advice you receive prioritizes your long-term well-being over potential commissions.
As we look ahead to 2026, there’s a notable shift in the financial landscape. The comparison of independent broker dealer vs RIA indicates that independent RIAs are expected to grow at an annual rate of 4%, reaching around 56,103 advisors, while the number of IBDs is projected to decline to 79. This trend reflects a growing preference for fee-based advisory models that emphasize transparency and a client-centric approach.
At Bright Advisers, we understand the importance of empowering families through personalized financial strategies that resonate with your values and goals. We prioritize minimal fund fees to make wealth management more accessible for everyone. Together, we can navigate this journey, ensuring that your family’s financial future is secure and aligned with your dreams.
Compare Regulatory Frameworks and Compliance
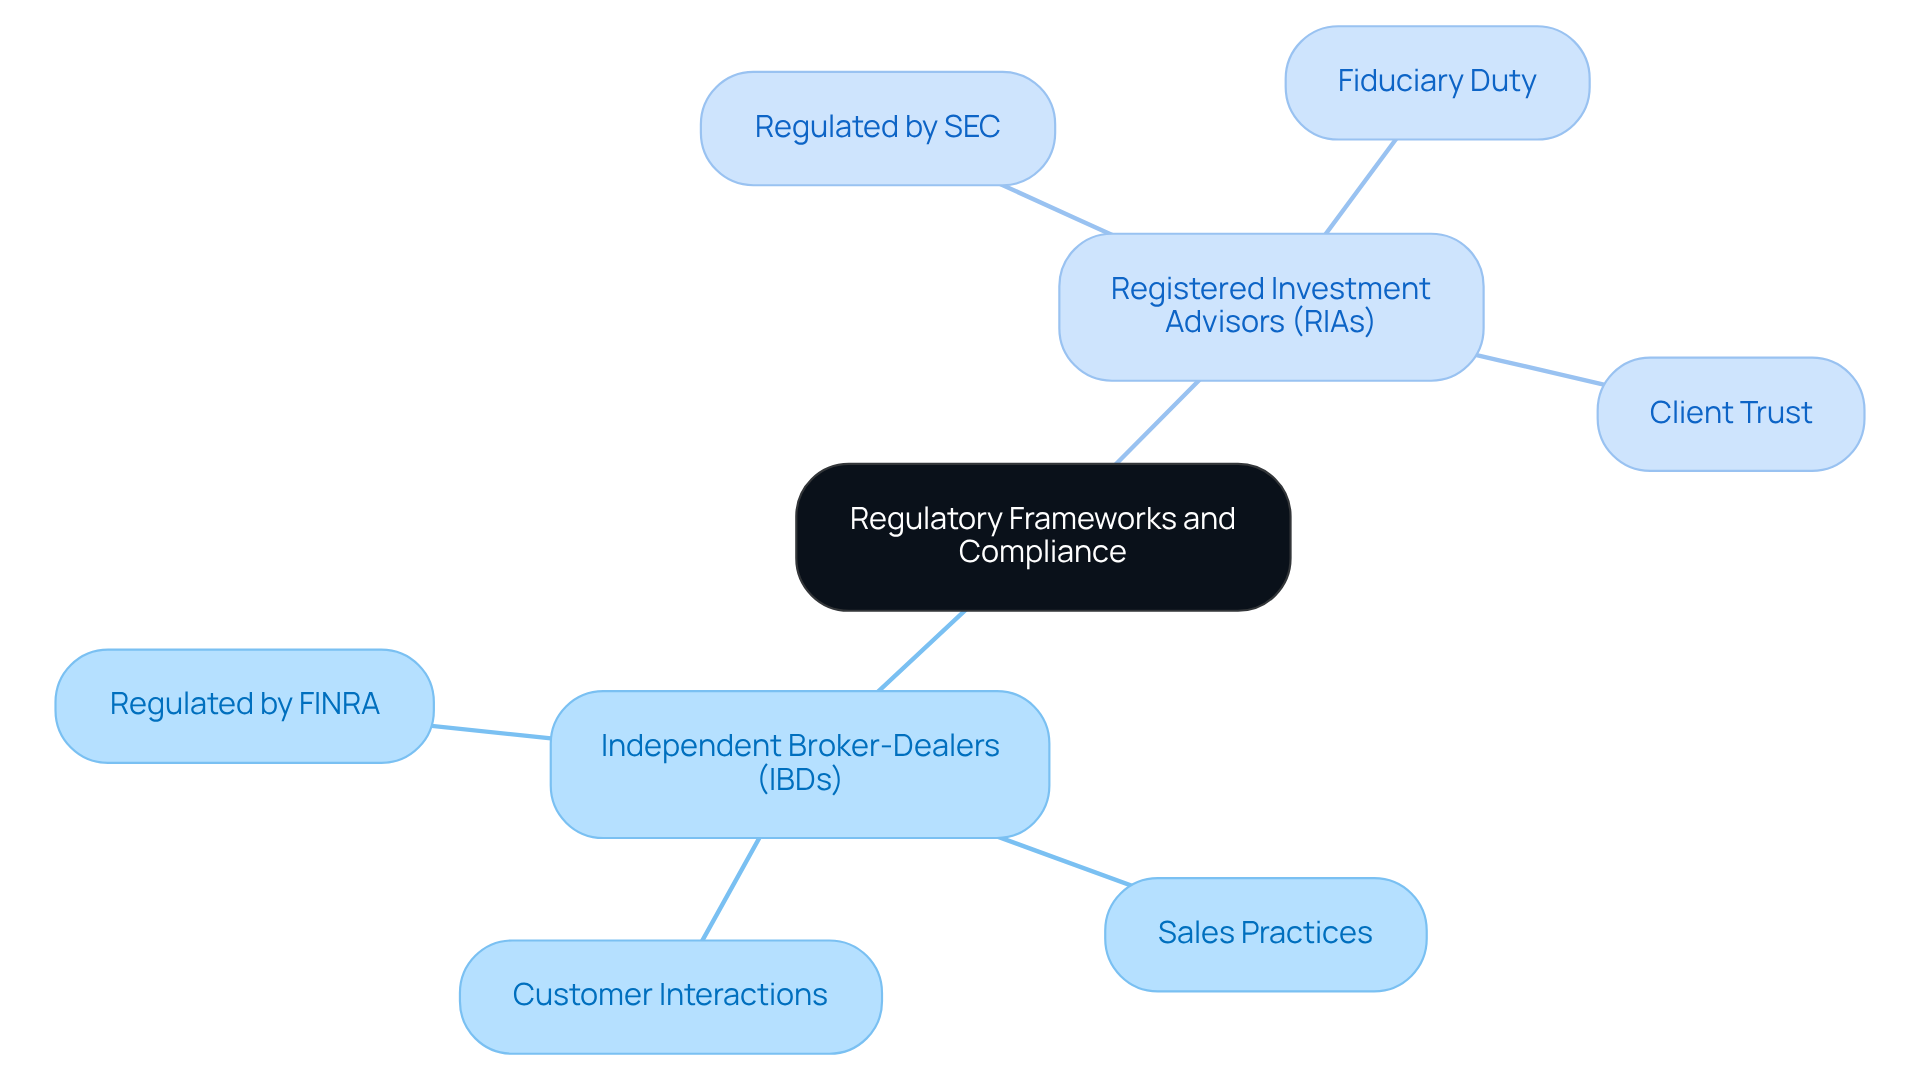
Independent Broker-Dealers (IBDs) operate under the watchful eye of FINRA, which enforces rules and standards to ensure fair practices in the securities industry. These regulations focus on sales practices and customer interactions, giving IBDs some leeway in their recommendations.
Now, imagine if you could work with someone who is legally obligated to put your family’s interests first. That’s where [Registered Investment Advisors (RIAs)](https://brightadvisers.com/what-is-the-difference-between-a-fiduciary-and-a-financial-advisor) come in. Regulated by the SEC, RIAs have a fiduciary duty that enhances accountability and builds a deeper trust between consultants and clients. For young households, choosing an RIA can bring considerable peace of mind, knowing that your consultant is dedicated to acting in your best interest.
This distinction is crucial, especially as families navigate complex economic landscapes. You want an advisor who . Together, we can navigate this journey, ensuring that your financial planning reflects what truly matters to your family. Remember, we’re here for you, ready to support you every step of the way.
Contrast Service Offerings and Financial Strategies
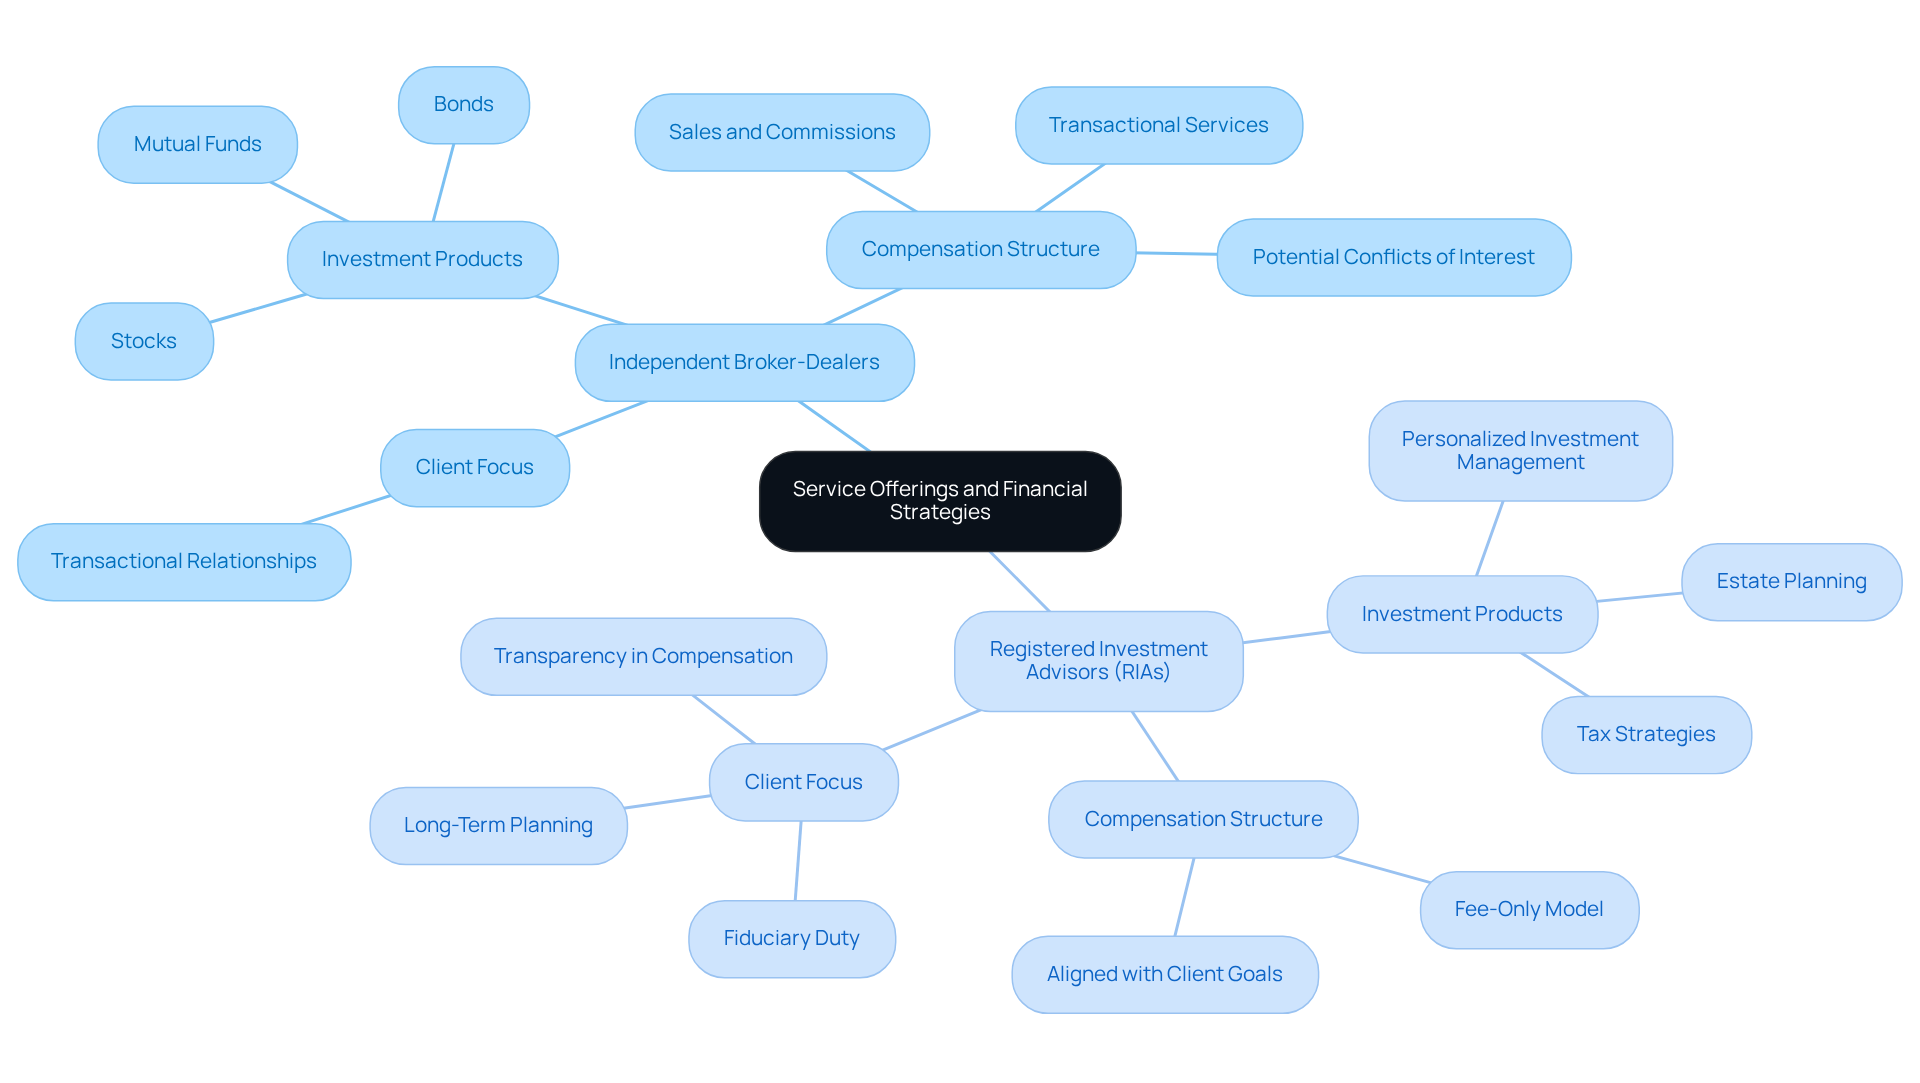
Imagine navigating the world of investments with confidence. When considering independent broker dealer vs RIA, it’s important to note that offer a variety of investment products like stocks, bonds, and mutual funds, while often focusing heavily on transactional services. This approach can sometimes lead to conflicts of interest, as sales and commissions take center stage.
Now, picture a different path. Registered Investment Advisors (RIAs) are dedicated to providing comprehensive planning services that truly cater to your family’s needs, especially when considering the differences between an independent broker dealer vs ria. They focus on personalized investment management, estate planning, and tax strategies, all while operating on a fee-only model. This means their success is tied to your financial goals, ensuring that your family’s future is always a priority.
For young households, the RIA model shines brightly. It emphasizes long-term planning and a fiduciary duty, putting your family’s economic future front and center. Recent studies reveal that nearly half of investors without advisors feel lost due to unclear compensation structures. This highlights the importance of transparency that RIAs offer, making it easier for you to understand how your money is managed.
Consider this: families working with RIAs benefit from tailored financial strategies that adapt to their evolving needs. This approach not only fosters a stable economic foundation for future generations but also builds trust. When you feel supported, you can make informed choices about your financial journey.
Together, we can navigate this journey. With the right guidance, your family’s financial future can be bright and secure.
Examine Compensation Structures and Client Impact
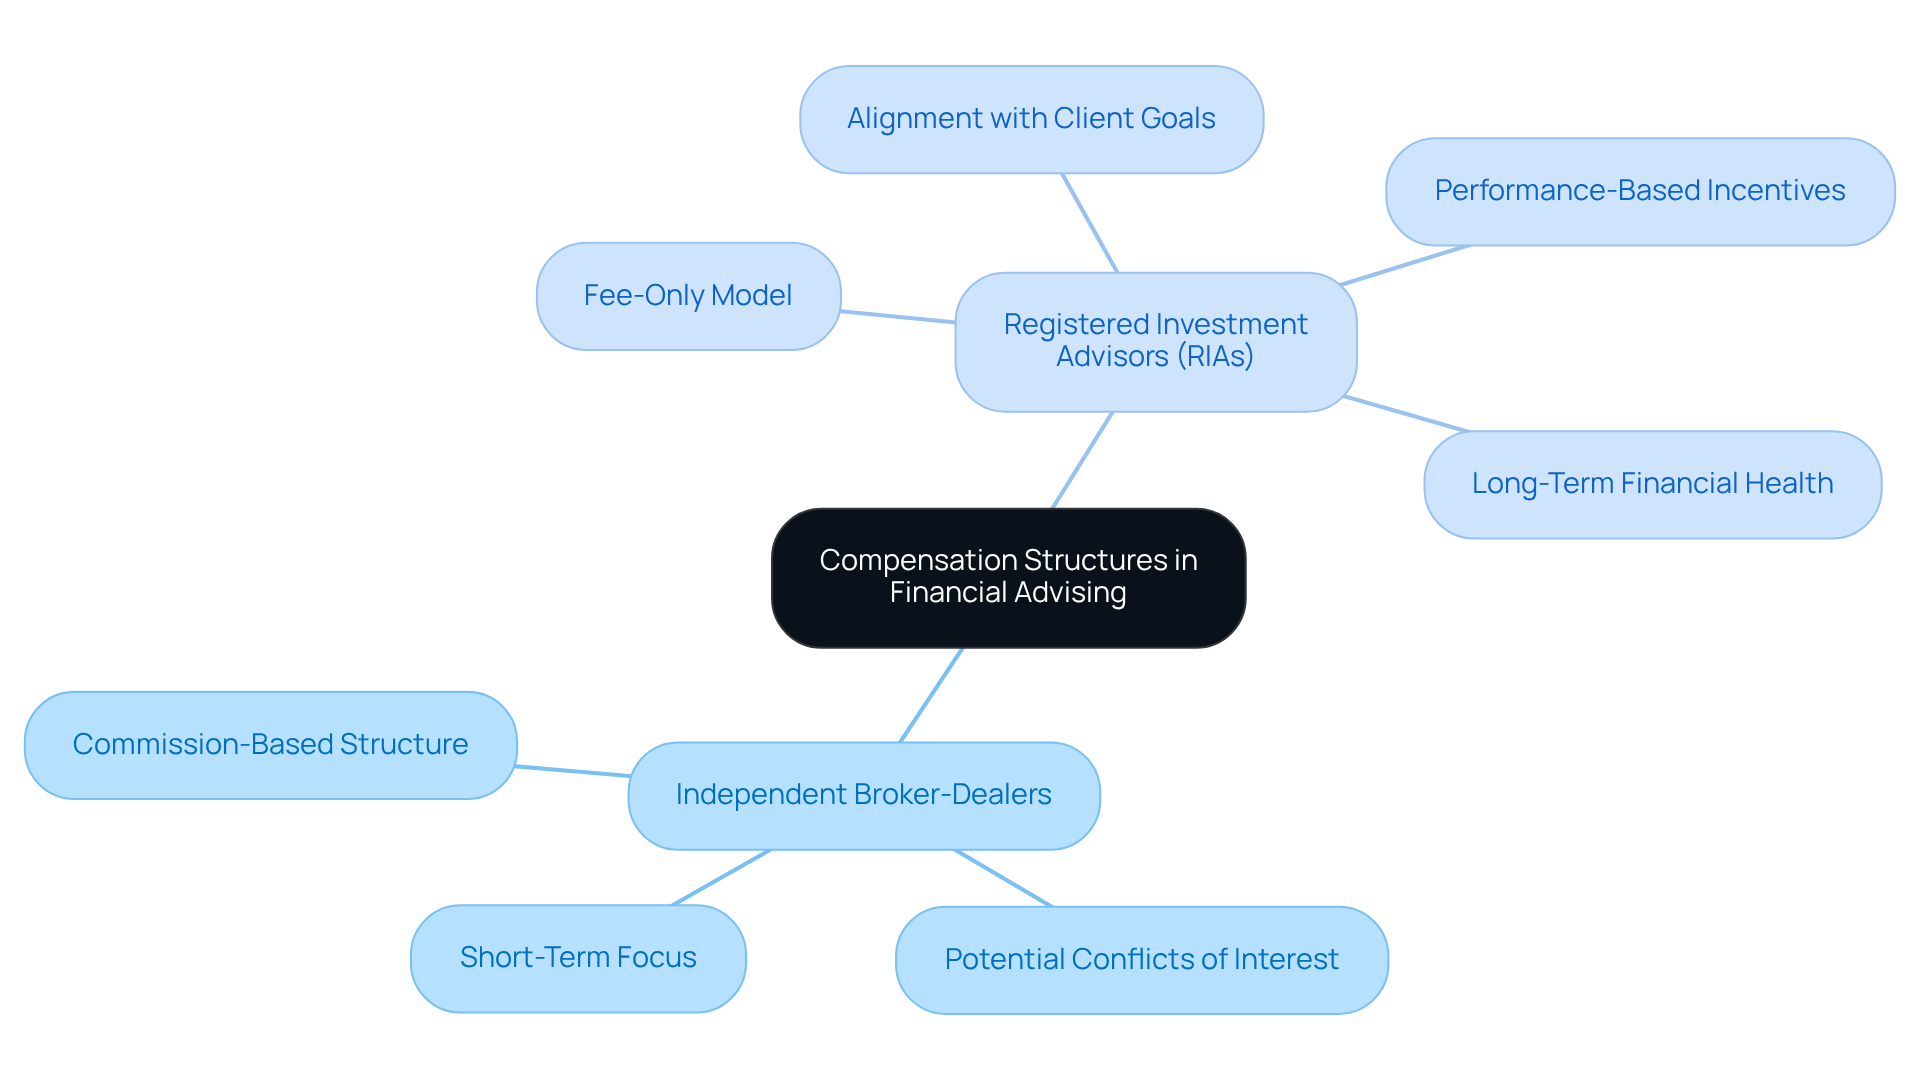
Understanding how is essential for young families. The discussion of independent broker dealer vs RIA often reveals that independent broker-dealers typically work on a commission-based structure, meaning they earn money based on the products they sell. This can lead to conflicts of interest, as some may prioritize products that pay higher commissions over those that truly serve your family’s best interests. On the other hand, in the discussion of independent broker dealer vs RIA, [Registered Investment Advisors (RIAs)](https://brightadvisers.com/?p=16459) typically operate on a fee-only model, charging clients based on assets under management or flat fees for their services. This approach aligns the advisor’s incentives with your family’s financial goals, fostering a more collaborative and transparent relationship.
Imagine if you could work with someone whose primary focus is your family’s well-being. Research shows that firms using performance-based incentives, which are more common among RIAs, often achieve better outcomes for their clients. For example, RIAs with performance-based pay have demonstrated 28% greater growth in assets under management (AUM) and 34% higher net asset flows over five years compared to those without such incentives. This alignment not only enhances the quality of guidance but also emphasizes long-term financial health over short-term sales tactics.
Choosing an RIA like Bright Advisers can lead to more impartial guidance, ensuring your family receives advice tailored to your unique needs and aspirations. For instance, when Emily and Mark partnered with Bright Advisers, they gained a clearer understanding of their financial situation and developed a comprehensive plan focused on improving their economic well-being. This plan empowered them to make career choices that prioritized their desired work-life balance, showcasing the profound impact of personalized financial strategies.
As the wealth management landscape continues to evolve, understanding the implications of compensation models, particularly in the context of independent broker dealer vs RIA, will help your family make informed decisions that secure your financial future. Remember, we’re here for you, and together, we can navigate this journey.
Conclusion
Navigating the financial landscape can feel overwhelming, especially for young families eager to secure their financial future. Understanding the difference between Independent Broker-Dealers (IBDs) and Registered Investment Advisors (RIAs) is essential. This choice impacts the level of service, accountability, and alignment with your family’s financial goals.
Imagine if you could have a partner who truly understands your family’s needs. Throughout this article, we’ve explored key differences, such as the regulatory frameworks that govern IBDs and RIAs, the compensation structures that shape their client relationships, and the types of services they offer. IBDs often work on a commission-based model, which can sometimes lead to conflicts of interest. In contrast, RIAs adhere to a fiduciary standard, prioritizing your best interests. This commitment to transparency and personalized financial strategies makes RIAs a more suitable choice for families aiming for long-term stability.
Ultimately, the choice between an IBD and an RIA can significantly influence your family’s financial journey. By opting for an RIA, you can enjoy personalized advice and a focus on long-term planning that aligns with your unique values and aspirations. As the financial advisory landscape continues to evolve, it’s important to make informed decisions that will foster a secure and prosperous future for generations to come.
Remember, we’re here for you. Together, we can navigate this journey and ensure that your family’s financial future is bright.
Frequently Asked Questions
What is an Independent Broker-Dealer (IBD)?
An Independent Broker-Dealer (IBD) operates independently from larger financial institutions, allowing advisors to offer a wide range of investment products and services tailored to clients’ needs. IBDs are registered with the Financial Industry Regulatory Authority (FINRA) and typically earn commissions on trades and sales.
What is a Registered Investment Advisor (RIA)?
A Registered Investment Advisor (RIA) can be a firm or an individual that provides investment advice and management services for a fee. RIAs are regulated by the Securities and Exchange Commission (SEC) or state regulators and are held to a fiduciary standard, meaning they are legally obligated to act in their clients’ best interests.
How do IBDs and RIAs differ in their compensation models?
IBDs generally earn commissions on trades and sales, while RIAs charge fees for their advisory services. This difference in compensation models influences the type of advice and services clients receive, with RIAs focusing more on fee-based advisory models.
What is the fiduciary standard, and why is it important?
The fiduciary standard requires RIAs to act in their clients’ best interests. This is important because it ensures that the advice provided prioritizes the clients’ long-term well-being over potential commissions, fostering a higher level of trust and accountability.
What is the projected growth for independent RIAs and IBDs by 2026?
Independent RIAs are expected to grow at an annual rate of 4%, reaching around 56,103 advisors, while the number of IBDs is projected to decline to 79. This trend indicates a growing preference for fee-based advisory models that emphasize transparency and a client-centric approach.
How does Bright Advisers approach wealth management?
Bright Advisers focuses on empowering families through personalized financial strategies that align with their values and goals. They prioritize minimal fund fees to make wealth management more accessible, ensuring that clients’ financial futures are secure and aligned with their dreams.
List of Sources
- Define Independent Broker-Dealer and RIA
- Independent broker-dealers outgrowing RIAs, captive BDs amid industry consolidation (https://investmentnews.com/independent-broker-dealers/independent-broker-dealers-outgrowing-rias-captive-bds-amid-industry-consolidation/262374)
- Cerulli Associates | Independent Broker/Dealers Lead Channel Growth (https://cerulli.com/press-releases/independent-broker-dealers-lead-channel-growth)
- 50+ Key RIA Industry Statistics to Guide Advisors in 2026 – CircleBlack (https://circleblack.com/key-ria-industry-statistics)
- RIA vs Broker Dealer: What You Need to Know (https://smartasset.com/financial-advisor/ria-vs-broker-dealer)
- Cerulli: Independent RIAs to Grow 4% Through 2028 (https://wealthmanagement.com/ria-news/cerulli-independent-rias-to-outpace-all-other-channels-by-2028)
- Compare Regulatory Frameworks and Compliance
- 10 Key Differences Between RIA vs Broker Dealer for Young Families – Bright Advisers (https://brightadvisers.com/10-key-differences-between-ria-vs-broker-dealer-for-young-families)
- IBD vs. RIA: What Are the Differences? (https://smartasset.com/advisor-resources/ibd-vs-ria)
- 70% of investors satisfied with their fiduciary advisor: Cerulli (https://citywire.com/ria/news/70-of-investors-satisfied-with-their-fiduciary-advisor-cerulli/a2462535)
- Takeaways From SEC’s Staff Bulletin On RIA Standard Of Care (https://kitces.com/blog/ria-standard-of-care-fiduciary-duty-sec-reg-bi-investment-due-diligence)
- Key Statistics (https://finra.org/media-center/statistics)
- Contrast Service Offerings and Financial Strategies
- Independent RIAs to Increase by 12% by 2028 | PLANADVISER (https://planadviser.com/independent-rias-increase-12-2028)
- Cerulli Associates | Research and Consulting for U.S. Financial… (https://cerulli.com/reports/us-advisor-metrics-2025)
- 2025 RIA Benchmarking Study | Charles Schwab (https://aboutschwab.com/ria-benchmarking-study-2025)
- More than three-quarters of advisors to embrace fee models by 2026, Cerulli says (https://investmentnews.com/practice-management/more-than-three-quarters-of-advisors-to-embrace-fee-models-by-2026-cerulli-says/259740)
- The Compelling Advisor Economics of the Independent RIA Model (https://comply.com/resource/the-compelling-advisor-economics-of-the-independent-ria-model)
- Examine Compensation Structures and Client Impact
- Compensation Structures for RIAs (https://mercercapital.com/insights/blogs/ria-valuation-insights-blog/2023/compensation-structures-for-rias)
- Three-fourths of advisors to be fee-based by 2026: Cerulli (https://citywire.com/ria/news/three-fourths-of-advisors-to-be-fee-based-by-2026-cerulli/a2462085)
- What Commissions Do Financial Advisors Earn? (https://smartasset.com/financial-advisor/financial-advisor-commissions)
- The Compelling Advisor Economics of the Independent RIA Model (https://comply.com/resource/the-compelling-advisor-economics-of-the-independent-ria-model)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading