

Overview
The Infinite Banking Concept (IBC) presents a wonderful opportunity for young families, offering benefits like tax-free growth, liquidity, and a guaranteed death benefit. These features make it an attractive financial strategy to help secure your family’s future.
However, it’s essential to consider some potential challenges. Families might face high initial costs and slow cash value accumulation. Additionally, financial discipline is crucial in this journey. Therefore, it’s important to carefully evaluate your financial situation and goals before moving forward.
Imagine if you could create a financial foundation that not only supports your family’s needs today but also ensures a secure tomorrow. By understanding both the advantages and drawbacks of IBC, you can make informed decisions that align with your family’s values.
Remember, we’re here for you. Together, we can navigate this journey and help you build a brighter financial future for your loved ones.
Key Highlights:
- The Infinite Banking Concept allows individuals to use the cash value of whole life insurance as a personal banking system.
- Overfunding whole life insurance gradually builds cash value, providing access to funds for personal expenses and investments.
- IBC offers tax-free growth, liquidity, flexible loan terms, a guaranteed death benefit, and non-correlation with market fluctuations.
- Families can reduce reliance on traditional banks, fostering economic independence through IBC.
- Challenges include high initial costs, slow cash value accumulation, complexity, opportunity costs, loan interest, and the need for financial discipline.
- Evaluating IBC suitability involves assessing financial health, setting clear goals, understanding risk tolerance, and consulting financial experts.
- Regular policy evaluations are essential to adapt to changing life circumstances and ensure alignment with financial strategies.
Introduction
In a world where financial independence is a cherished goal for many families, the Infinite Banking Concept (IBC) stands out as a transformative strategy that reimagines wealth management. Imagine being able to turn whole life insurance policies into your own personal banking system. With IBC, families can tap into cash value for a variety of needs—be it for investments or unexpected emergencies.
As more families discover the potential of IBC to foster financial stability and independence, it becomes increasingly important to understand its nuances. This includes exploring the advantages, drawbacks, and practical applications of this approach.
Together, we can navigate this journey as we delve into the core components of the Infinite Banking Concept, examining how it operates, its benefits and challenges, and the steps families can take to determine if this innovative financial strategy aligns with their goals.
Define the Infinite Banking Concept
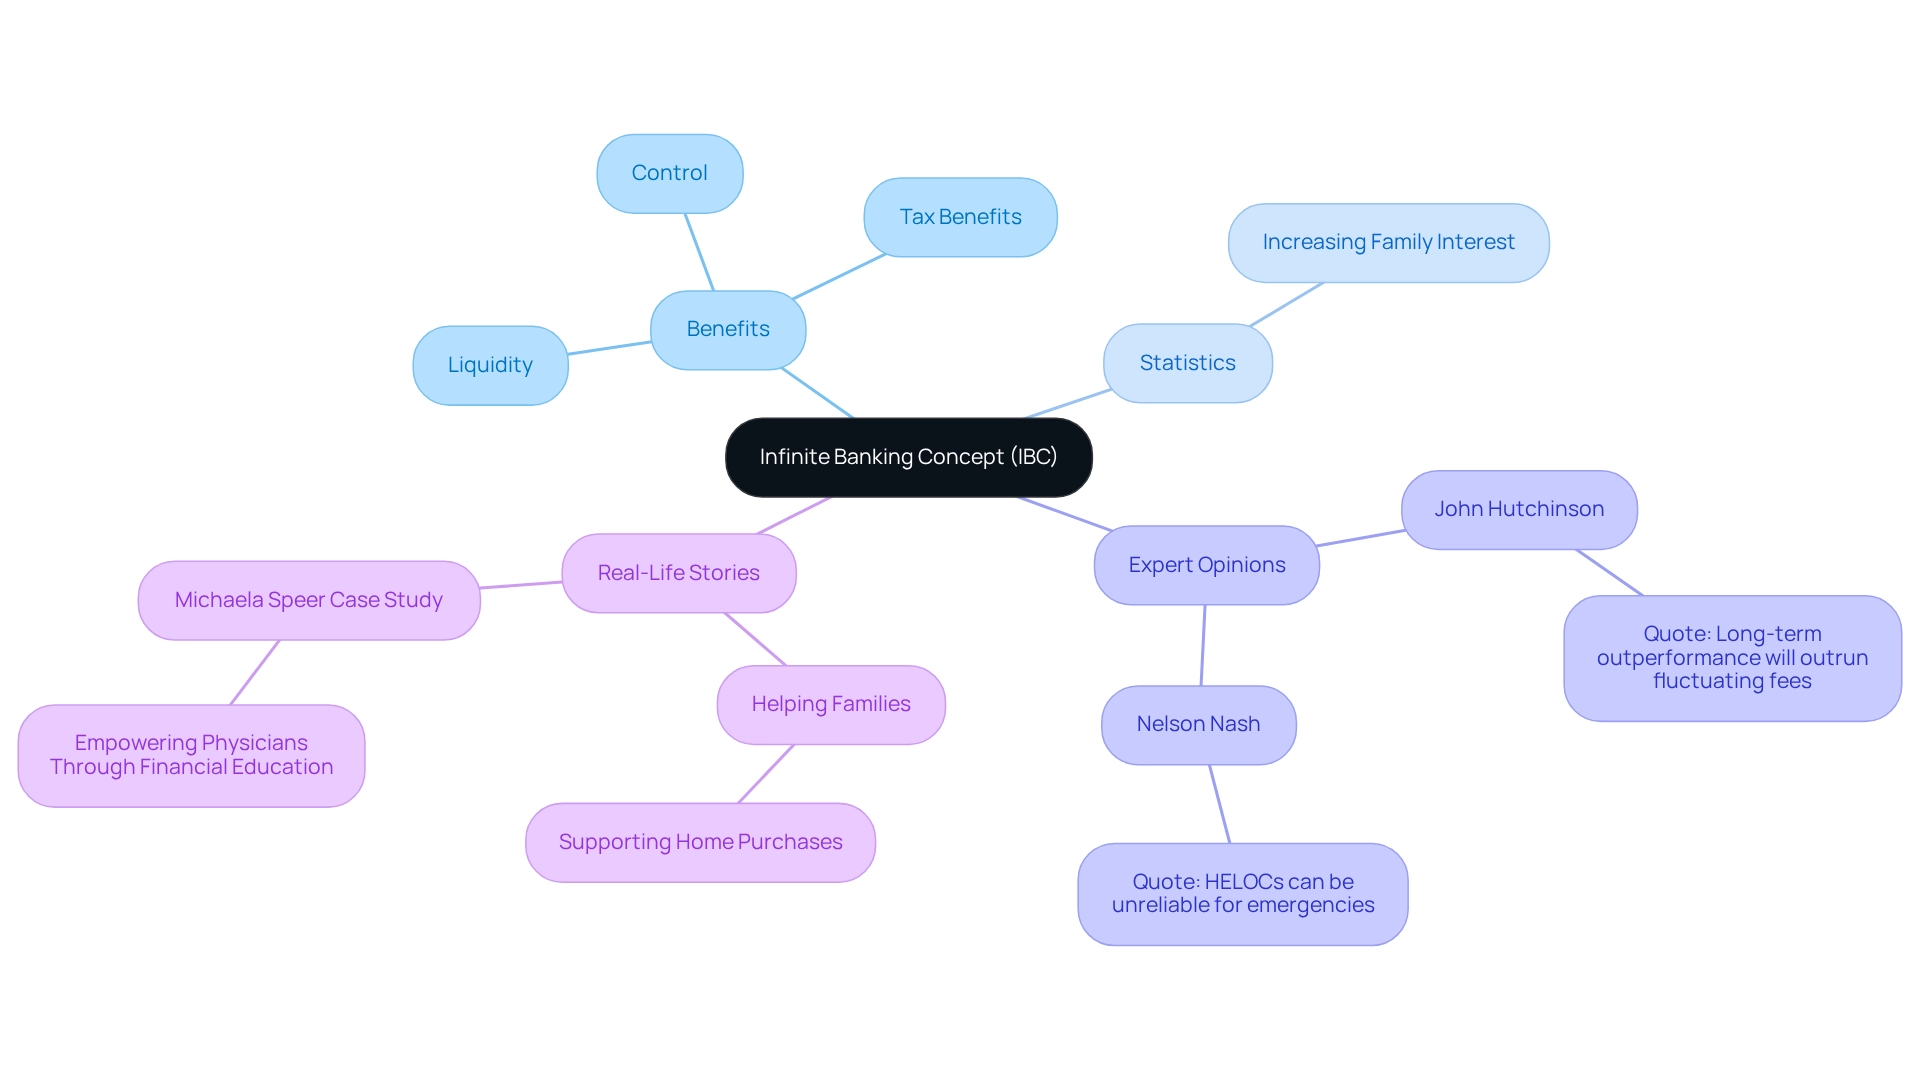
The Infinite Banking Concept (IBC) offers a nurturing approach to financial management, allowing you to utilize the cash value of a whole life insurance plan as your personal banking system. This innovative idea, rooted in the work of R. Nelson Nash, encourages policyholders to overfund their life insurance, gradually building cash value over time.
Imagine having access to funds through loans, enabling you to cover personal expenses, invest in opportunities, or manage emergencies—all without relying on traditional banks. By viewing your life insurance policy as a personal bank, you gain liquidity and control over your financial resources, all while enjoying the tax benefits that come with life insurance.
Recent statistics show that more families are considering the infinite banking concept pros and cons for wealth management, recognizing its potential to foster economic stability and independence. Experts suggest that the infinite banking concept pros and cons indicate the long-term advantages of whole life insurance, including the ability to borrow against cash value, often outweigh initial costs and liquidity challenges. For example, John “Hutch” Hutchinson, founder of BankingTruths.com, emphasizes how the long-term benefits of IBC can surpass the fluctuating fees associated with Indexed Universal Life (IUL) policies.
Real-life stories highlight the practical application of IBC in everyday situations. One inspiring case involves families using their personal banking systems to support loved ones, such as helping children purchase their first home. By borrowing from their private banks, these families not only provide financial assistance but also create favorable conditions that enhance household economic stability. This illustrates how IBC serves as a powerful tool for families looking to build and preserve wealth for generations to come. Together, we can navigate this journey towards a more secure financial future.
Explain How Infinite Banking Works
Explore the Advantages of Infinite Banking
The Infinite Banking Concept offers remarkable benefits for families looking to enhance their financial strategies, especially in light of the challenges faced by individuals like Jay and Emma.
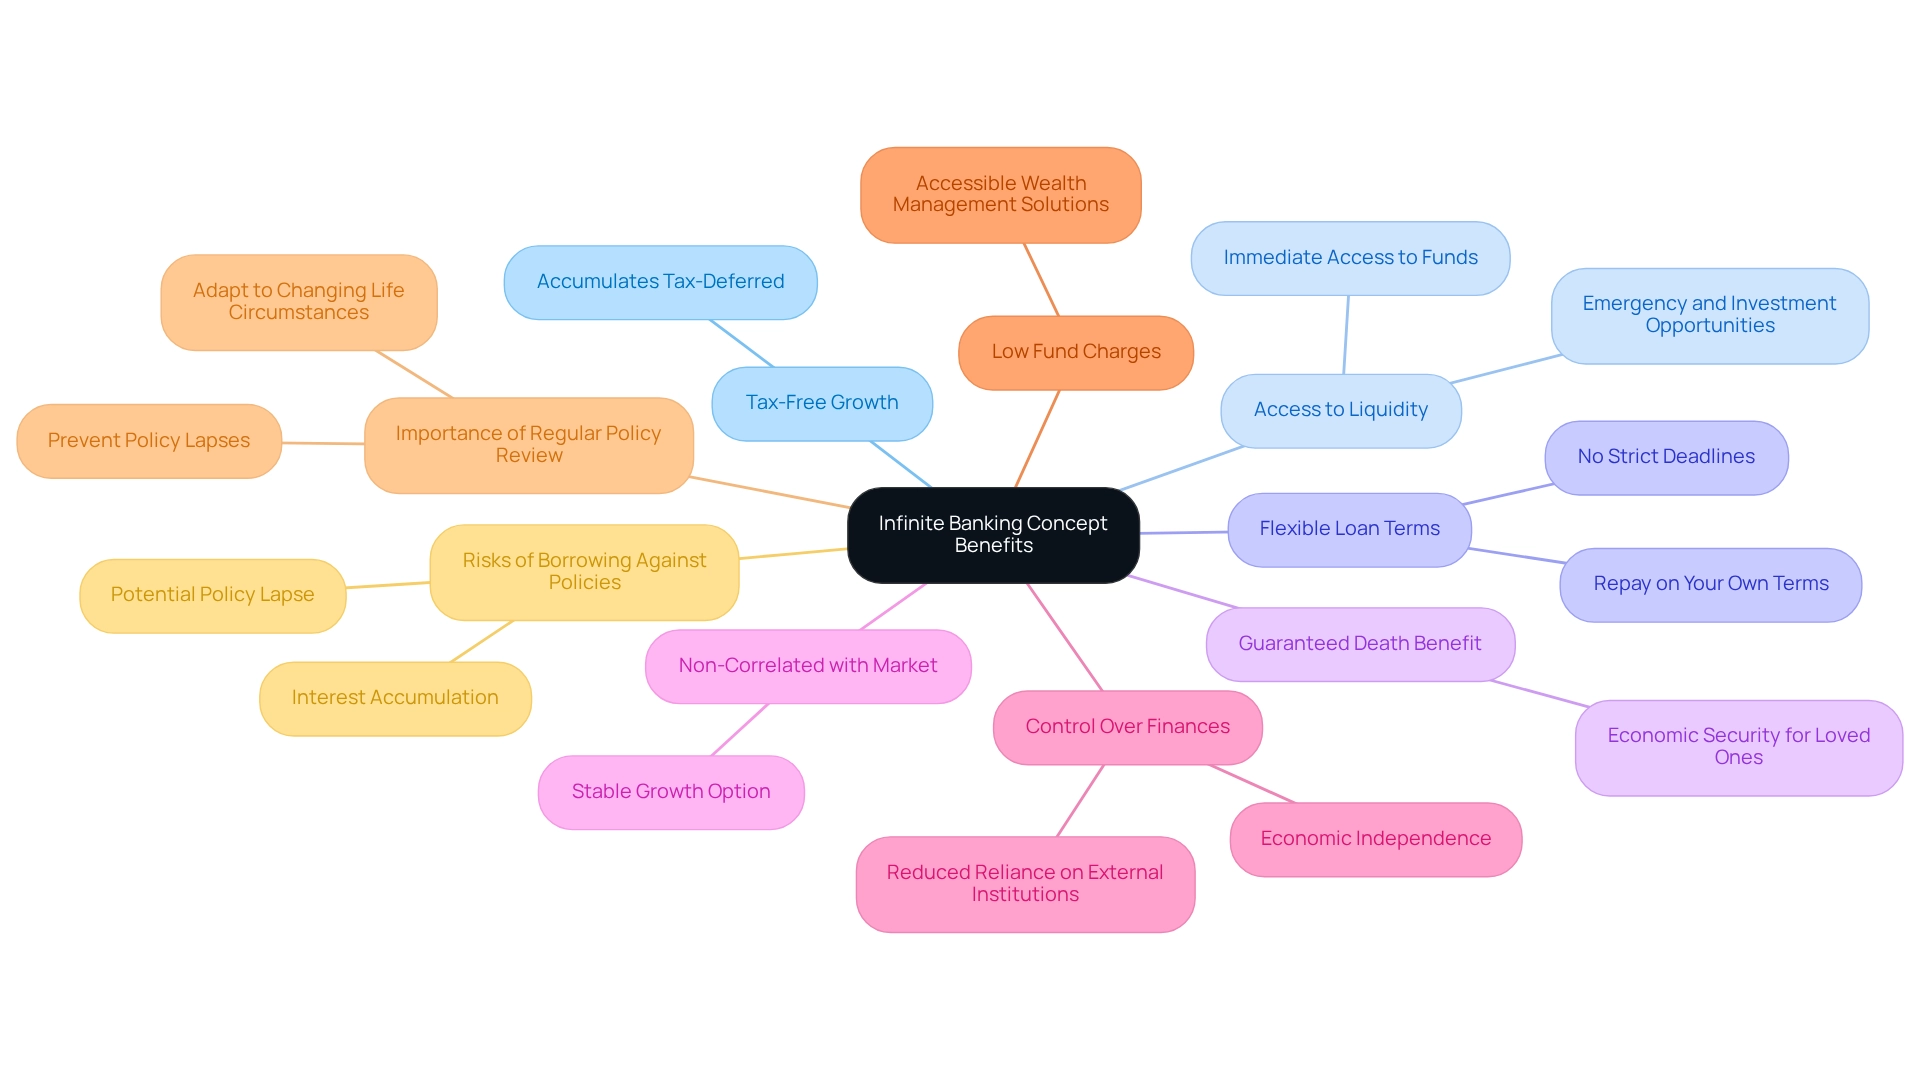
Imagine a world where your wealth grows without the burden of taxes. Tax-Free Growth allows the cash value in a whole life insurance policy to accumulate tax-deferred, giving families the opportunity to build their wealth without immediate tax implications until funds are withdrawn.
Access to Liquidity means that policyholders can borrow against their cash value at any time. This ensures immediate access to funds for emergencies or investment opportunities, which is crucial for families managing unexpected expenses.
With Flexible Loan Terms, Infinite Banking provides the freedom to repay loans on your own terms, without the pressure of strict deadlines. This flexibility is invaluable for families who want to maintain control over their financial commitments.
Additionally, the policy guarantees a Guaranteed Death Benefit, offering peace of mind and economic security for loved ones in the event of an untimely passing.
The cash value is also Non-Correlated with Market fluctuations, providing a stable growth option that can be particularly reassuring during economic downturns.
Families gain Control Over Finances, reducing reliance on external monetary institutions and fostering a sense of economic independence. Bright Advisers emphasizes Dedication to Low Fund Charges, making wealth management solutions more accessible for families. These benefits illustrate the infinite banking concept pros and cons, making it a compelling choice for families striving to build and preserve wealth while ensuring economic security for future generations. Regular policy evaluations are essential to adapt to changing life circumstances, ensuring that coverage remains adequate and aligned with evolving financial strategies.
By partnering with Bright Advisers, families like Emily and Mark have successfully integrated these principles into their planning. Through tailored wealth management strategies, they achieved financial freedom, allowing them to make career choices based on their desired work-life balance. Regular evaluations of guidelines, combined with Bright Advisers’ innovative investment approaches, ensure that families can adapt to changing situations and enhance their financial outcomes.
Together, we can navigate this journey towards a secure financial future.
Outline the Advantages of Infinite Banking
While the Infinite Banking Concept (IBC) offers several advantages, it’s essential to gently acknowledge its potential drawbacks that may concern young families:
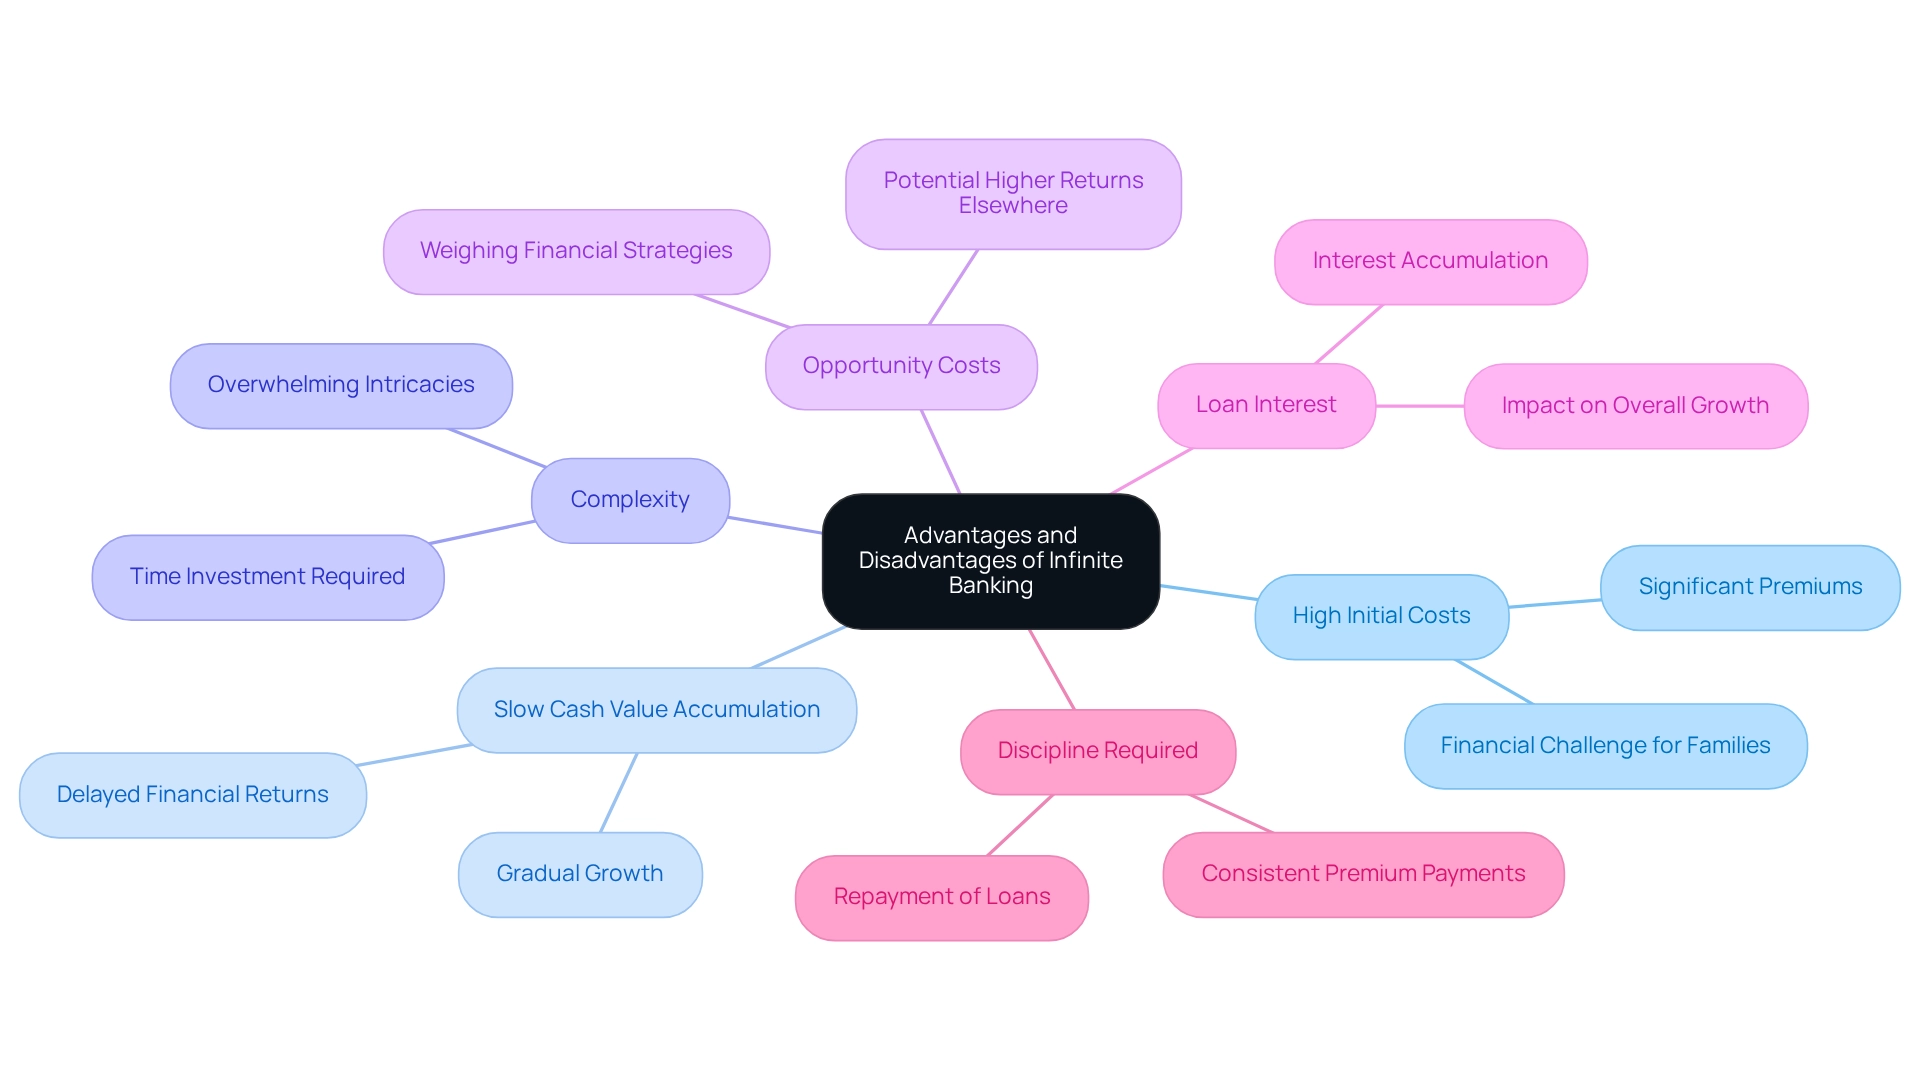
- High Initial Costs: Whole life insurance plans often require significant premiums, which can be a financial challenge for many families. As we look ahead to 2025, these starting expenses remain substantial, potentially discouraging those considering this option.
- Slow Cash Value Accumulation: The cash value of whole life insurance plans tends to grow gradually, often taking several years to reach a meaningful amount. This slower accumulation can be a drawback for those who are eager for quicker financial returns.
- Complexity: The intricacies of IBC can feel overwhelming. Families may need to invest time and effort to fully understand how to manage their plans effectively, which might not be feasible for everyone.
- Opportunity Costs: Funds set aside for premiums could potentially yield higher returns if invested elsewhere. This consideration leads to opportunity costs that families should weigh when evaluating their financial strategies.
- Loan Interest: When borrowing against the cash value, interest accumulates, which can diminish the overall growth of the plan if not managed carefully. This aspect requires attention to ensure the benefits of the policy are not undermined.
- Discipline Required: Successfully implementing IBC calls for a high level of financial discipline. Families must ensure that loans are repaid and premiums are consistently maintained to realize the full potential of their investment.
A case study titled ‘It Is Not Revolutionary’ sheds light on common misconceptions about the infinite banking concept pros and cons, clarifying that while it may offer slightly higher interest on cash, it does not present significant advantages over traditional investments. Economic specialists emphasize that life insurance should be viewed as part of a broader financial strategy rather than a standalone solution. As families navigate these complexities, understanding the pros and cons of the infinite banking concept is crucial for making informed financial choices.
Imagine if you could explore how Bright Advisers can help you manage these challenges and create a tailored strategy just for your family. We invite you to reach out for a consultation and discover how we can support you on this journey.
Discuss the Disadvantages of Infinite Banking
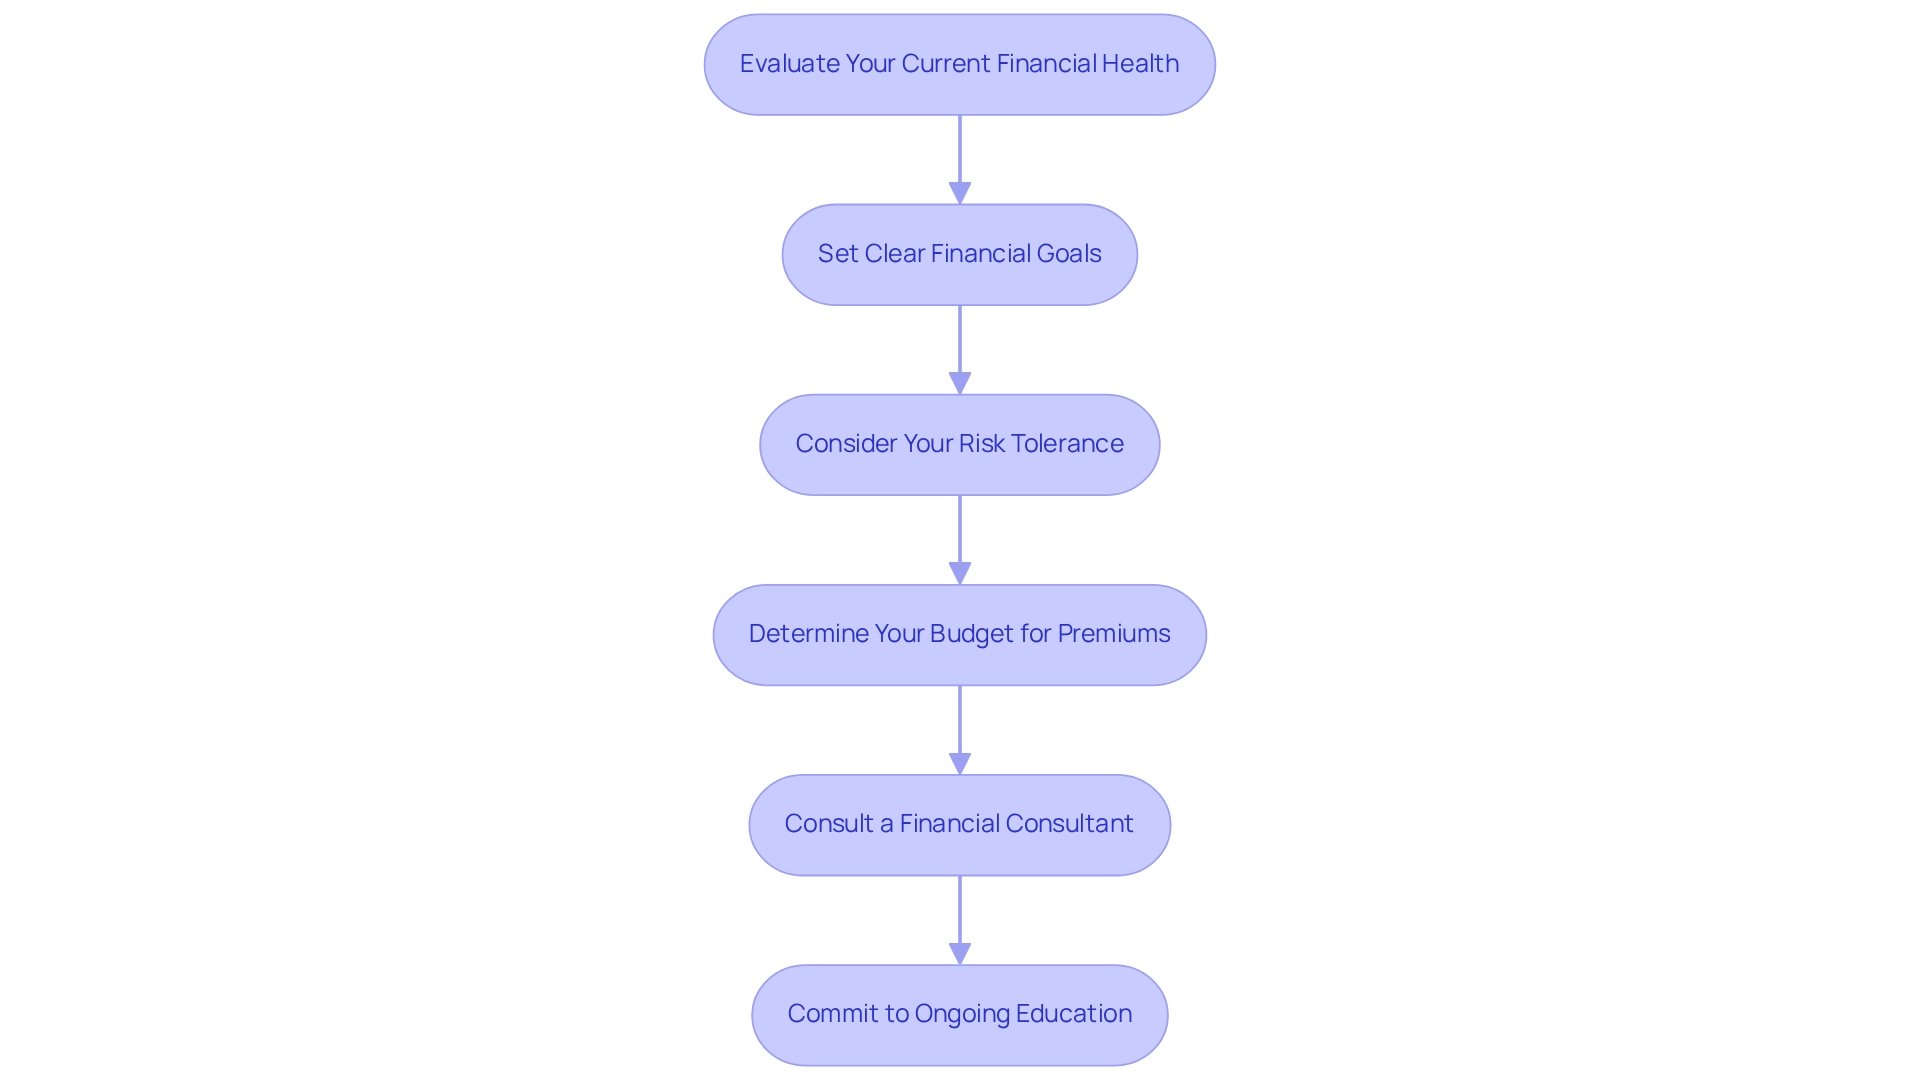
To determine if the Infinite Banking Concept (IBC) is suitable for your family, follow these essential steps:
- Evaluate Your Current Financial Health: Begin by thoroughly reviewing your income, expenses, debts, and savings. Comprehending your monetary situation is essential, particularly given that the average net worth of U.S. households is $748,000, with a median of $121,700. This context can help you assess where you stand in relation to wider economic trends. Furthermore, be mindful that around 20% of tenants encounter housing-related difficulties, which can greatly affect your economic well-being.
- Set Clear Financial Goals: Identify specific objectives you wish to achieve through IBC, such as funding education, retirement, or building an emergency fund. Establishing clear goals will guide your strategy and help you measure success.
- Consider Your Risk Tolerance: Assess your comfort level with the risks associated with whole life insurance policies, particularly regarding the potential for slow cash value growth. Understanding your risk tolerance is vital for making informed decisions.
- Determine Your Budget for Premiums: Make certain that you can easily manage the premiums related to IBC without compromising other monetary responsibilities. It’s essential to strike a balance that allows for both premium payments and other necessary expenses.
- Consult a Financial Consultant: Seek expert advice to assess whether IBC aligns with your overall monetary strategy and objectives. At Bright Advisers, our team is committed to offering customized planning and investment approaches designed for households like yours. We will help you navigate the complexities of IBC and ensure it fits your unique situation. Contact us at (714) 987-2967 or join our waitlist for more information.
- Commit to Ongoing Education: Be prepared to invest time in understanding the nuances of IBC. Ongoing education will enable you to optimize the advantages of this monetary strategy and adjust as your situation evolves.
As Paul Golden, spokesperson for NEFE, notes, “When parents return to work and take on child care expenses—where it’s estimated a quarter of their monthly budget goes—you quickly discover the math doesn’t add up.” By following these steps, families can effectively assess their financial situation and determine if the Infinite Banking Concept aligns with their long-term financial goals.
Conclusion
The Infinite Banking Concept (IBC) offers a remarkable opportunity for families yearning for greater financial independence and stability. Imagine being able to leverage the cash value of whole life insurance policies to create your own banking system. This approach provides you with liquidity and control over your finances, allowing you to feel empowered in your financial journey. The benefits of IBC—such as tax-free growth, flexible loan terms, and guaranteed death benefits—are compelling reasons to consider this strategy as part of your long-term financial planning.
However, it’s important to recognize the potential challenges that come with IBC. High initial costs, slow cash value accumulation, and the complexity of managing these policies can feel daunting. As you weigh these factors against your family’s financial goals and unique circumstances, remember that a thorough evaluation of your financial health, clear goal-setting, and consultation with trusted financial advisors can guide you through these complexities, helping you make informed decisions.
Ultimately, the Infinite Banking Concept can be a powerful tool for those who are ready to invest the time and discipline necessary for effective implementation. By understanding both the benefits and challenges of IBC, you can position your family for financial success, creating a legacy of wealth and security for future generations. We’re here for you, ready to support you on this journey toward achieving your family’s financial dreams.
Frequently Asked Questions
What is the Infinite Banking Concept (IBC)?
The Infinite Banking Concept (IBC) is a monetary strategy that allows individuals to use the cash value of a whole life insurance policy as their personal banking system. It encourages policyholders to overfund their life insurance to accumulate cash value, which can be accessed through loans for personal expenses, investments, or emergencies.
Who originated the Infinite Banking Concept?
The Infinite Banking Concept was originated by R. Nelson Nash.
What are the benefits of using IBC?
The benefits of using IBC include liquidity, greater control over financial resources, and tax advantages associated with life insurance. It allows individuals to finance needs without relying on traditional banks.
How does IBC contribute to financial stability?
IBC can foster financial stability and independence by enabling households to leverage their life insurance cash value for various financial needs, thus providing a safety net and supporting long-term wealth preservation.
What is the Total term (Tt) in relation to IBC?
The Total term (Tt) is a measure that estimates how many years a household could sustain itself if they stopped working today, calculated by dividing net worth by annual living expenses.
What are some challenges associated with IBC?
The challenges of IBC include initial costs and liquidity issues, but experts believe that the long-term advantages of whole life insurance and the ability to borrow against cash value often outweigh these challenges.
Can you provide an example of IBC in practice?
An example of IBC in practice is individuals using their personal banking systems to assist loved ones, such as helping children purchase their first home by borrowing from their cash value, which enhances their financial stability.
What must individuals consider to effectively use IBC?
Individuals must be patient and financially prepared to support their life insurance plan to fully optimize the benefits of the Infinite Banking Concept.
List of Sources
- Define the Infinite Banking Concept
- Infinite Banking: A Financial Advisor’s Review [Pros & Cons] (https://physiciansthrive.com/financial-planning/infinite-banking)
- Infinite Banking Concept Explained: How to Become Your Own Banker (https://bankingtruths.com/infinite-banking-concept-explained)
- Infinite Banking Concept updated for 2025 (https://ogletreefinancial.com/blog/the-infinite-banking-concept-becoming-your-own-banker)
- Explain How Infinite Banking Works
- Life Insurance Facts and Statistics 2025 | Bankrate (https://bankrate.com/insurance/life-insurance/life-insurance-statistics)
- The powerful tax benefits of whole life insurance | Regions Bank (https://regions.com/insights/wealth/article/the-powerful-tax-benefits-of-whole-life-insurance)
- Life Insurance Statistics, Data and Industry Trends 2025 (https://forbes.com/advisor/life-insurance/life-insurance-statistics)
- How Much Can I Borrow From Whole Life Insurance Policy? Guide (https://paradigmlife.net/how-much-can-i-borrow-from-my-whole-life-insurance)
- Get to Know Nelson Nash – Father of Infinite Banking Concept – Wealth Nation (https://wealthnation.io/blog/nelson-nash)
- Whole Life Insurance & the “Infinite Banking” Concept: Too Good to be True? (https://bandcfinancial.com/whole-life-insurance-the-infinite-banking-concept-too-good-to-be-true)
- Outline the Advantages of Infinite Banking
- Whole Life Insurance Cash Value Chart (https://forbes.com/advisor/life-insurance/whole-life-insurance-cash-value-chart)
- Bank on Yourself – Problems with Infinite Banking Concept | White Coat Investor (https://whitecoatinvestor.com/infinite-banking-bank-on-yourself)
- What Are The Downsides To The Infinite Banking Concept? | Monegenix® | (https://monegenix.com/what-are-the-downsides-to-the-infinite-banking-concept)
- The Guide to Infinite Banking: How It Works & Who It’s For (https://quotacy.com/infinite-banking)
- Top 10 Pros and Cons of Infinite Banking – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/pros-and-cons-of-the-infinite-banking-concept)
- Life Insurance Facts and Statistics 2025 | Bankrate (https://bankrate.com/insurance/life-insurance/life-insurance-statistics)
- Life Insurance Statistics & Facts – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/life-insurance-statistics)
- Discuss the Disadvantages of Infinite Banking
- Overall Financial Well-Being (https://federalreserve.gov/publications/2024-economic-well-being-of-us-households-in-2023-overall-financial-well-being.htm)
- Millennial-Age Parents Suffering Severe Financial Strain (https://nefe.org/news/2016/09/millennial-age-parents-suffering-severe-financial-strain.aspx)
- Financial Health: 7 Stats You Should Know (https://manning-napier.com/insights/financial-health-7-stats-you-should-know)
- Bank on Yourself – Problems with Infinite Banking Concept | White Coat Investor (https://whitecoatinvestor.com/infinite-banking-bank-on-yourself)
- Infinite Banking: A Financial Advisor’s Review [Pros & Cons] (https://physiciansthrive.com/financial-planning/infinite-banking)
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin