

Key Highlights
- Investment consultant fees typically range from 1% to 2% of assets under management (AUM) annually, significantly impacting long-term investment growth.
- For a $500,000 portfolio, a 1% fee could result in over $330,000 in lost returns over 20 years if not managed effectively.
- Traditional financial planning costs vary from $2,000 to $8,000, covering comprehensive services like tax strategies and estate planning.
- Families should be aware of both direct and indirect costs, with hidden fees potentially adding 0.5% to 1% to overall expenses.
- Traditional advisors charge between 0.75% and 1.5% of AUM, while actively managed mutual funds average 0.75% to 1.50% in expense ratios.
- Bright Advisers emphasises transparency, offering personalised solutions with no hidden fees, ensuring families can secure their financial future.
- Understanding fee structures and the forthcoming Total Cost Reporting (TCR) changes can help families make informed financial decisions.
- Investment consultants provide tailored strategies, while traditional planning offers a comprehensive approach to budgeting and wealth management.
- Bright Advisers focuses on innovative wealth management solutions, helping families grow wealth while keeping costs low and aligning with their values.
Introduction
Imagine feeling overwhelmed by the financial choices that shape your family’s future. Understanding the financial landscape can be a challenge for parents striving to secure their family’s well-being. Together, let’s explore how these fee structures can affect your family’s financial health over time. As you consider your options, think about which approach resonates with your family’s values and how to uncover the hidden costs that might be lurking.
Define Investment Consultant Fees and Traditional Financial Planning Costs
Have you ever wondered how much those investment fees are really costing your family? Investment consultant fees often include the costs of hiring experts to manage investments, typically structured as a percentage of assets under management (AUM), fixed rates, or hourly fees. In 2026, many investment consultant fees range from 1% to 2% of AUM annually. The impact of investment consultant fees can really add up, affecting how much your investments grow over time. For example, on a $500,000 portfolio, a 1% fee means $5,000 annually, which could lead to over $330,000 in lost returns over 20 years if not managed effectively.
In contrast, traditional monetary planning costs cover a wider range of services, including comprehensive planning, tax strategies, and estate planning. These services are often charged as fixed amounts or hourly rates, with thorough monetary plans typically ranging from $2,000 to $8,000, depending on the complexity of your financial situation. It’s important for parents to understand these differences so they can choose the right path for their family’s financial goals, especially considering the current trends in investment advisor charges and their potential long-term effects on wealth growth.
At Bright Advisers, we’re committed to keeping fees low and offering personalized solutions that truly fit your family’s needs. We ensure clarity and no hidden costs, which can greatly assist families aiming to secure their economic future. Together, we can navigate this journey toward financial security.
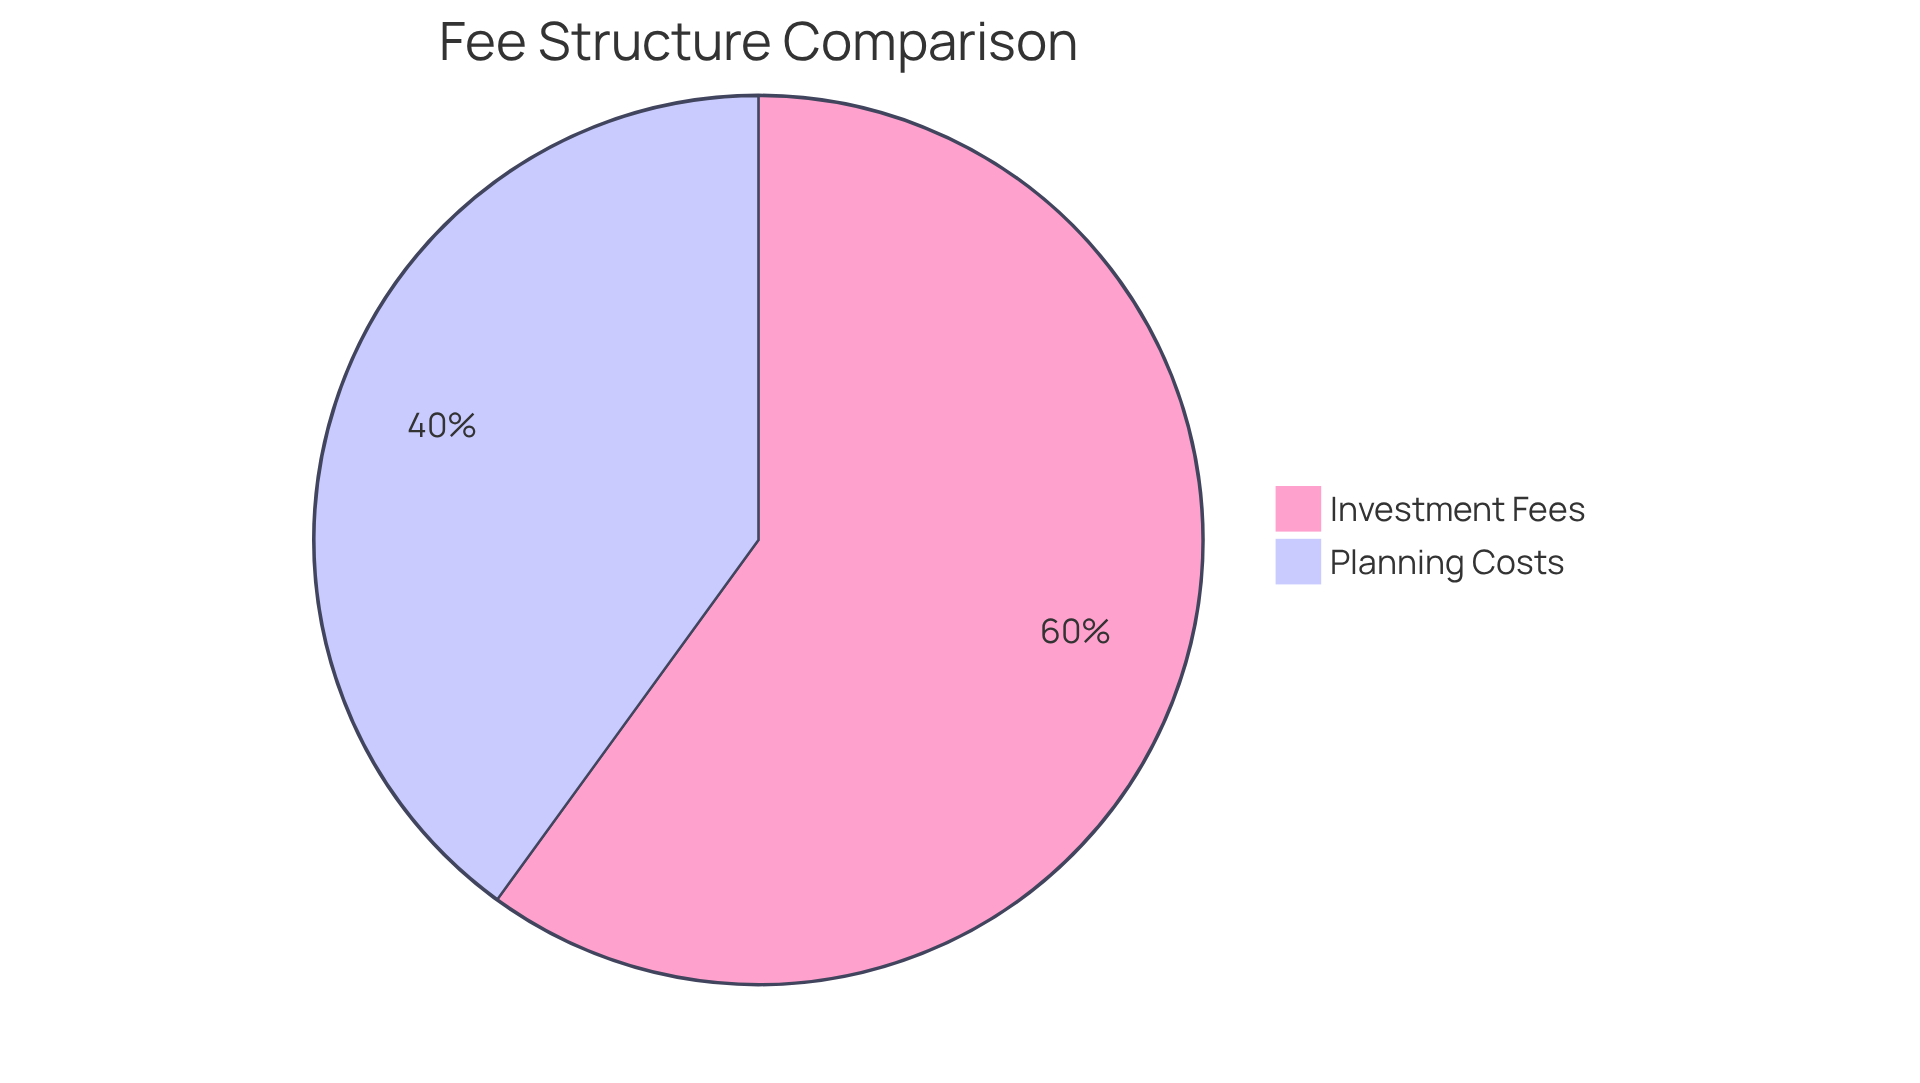
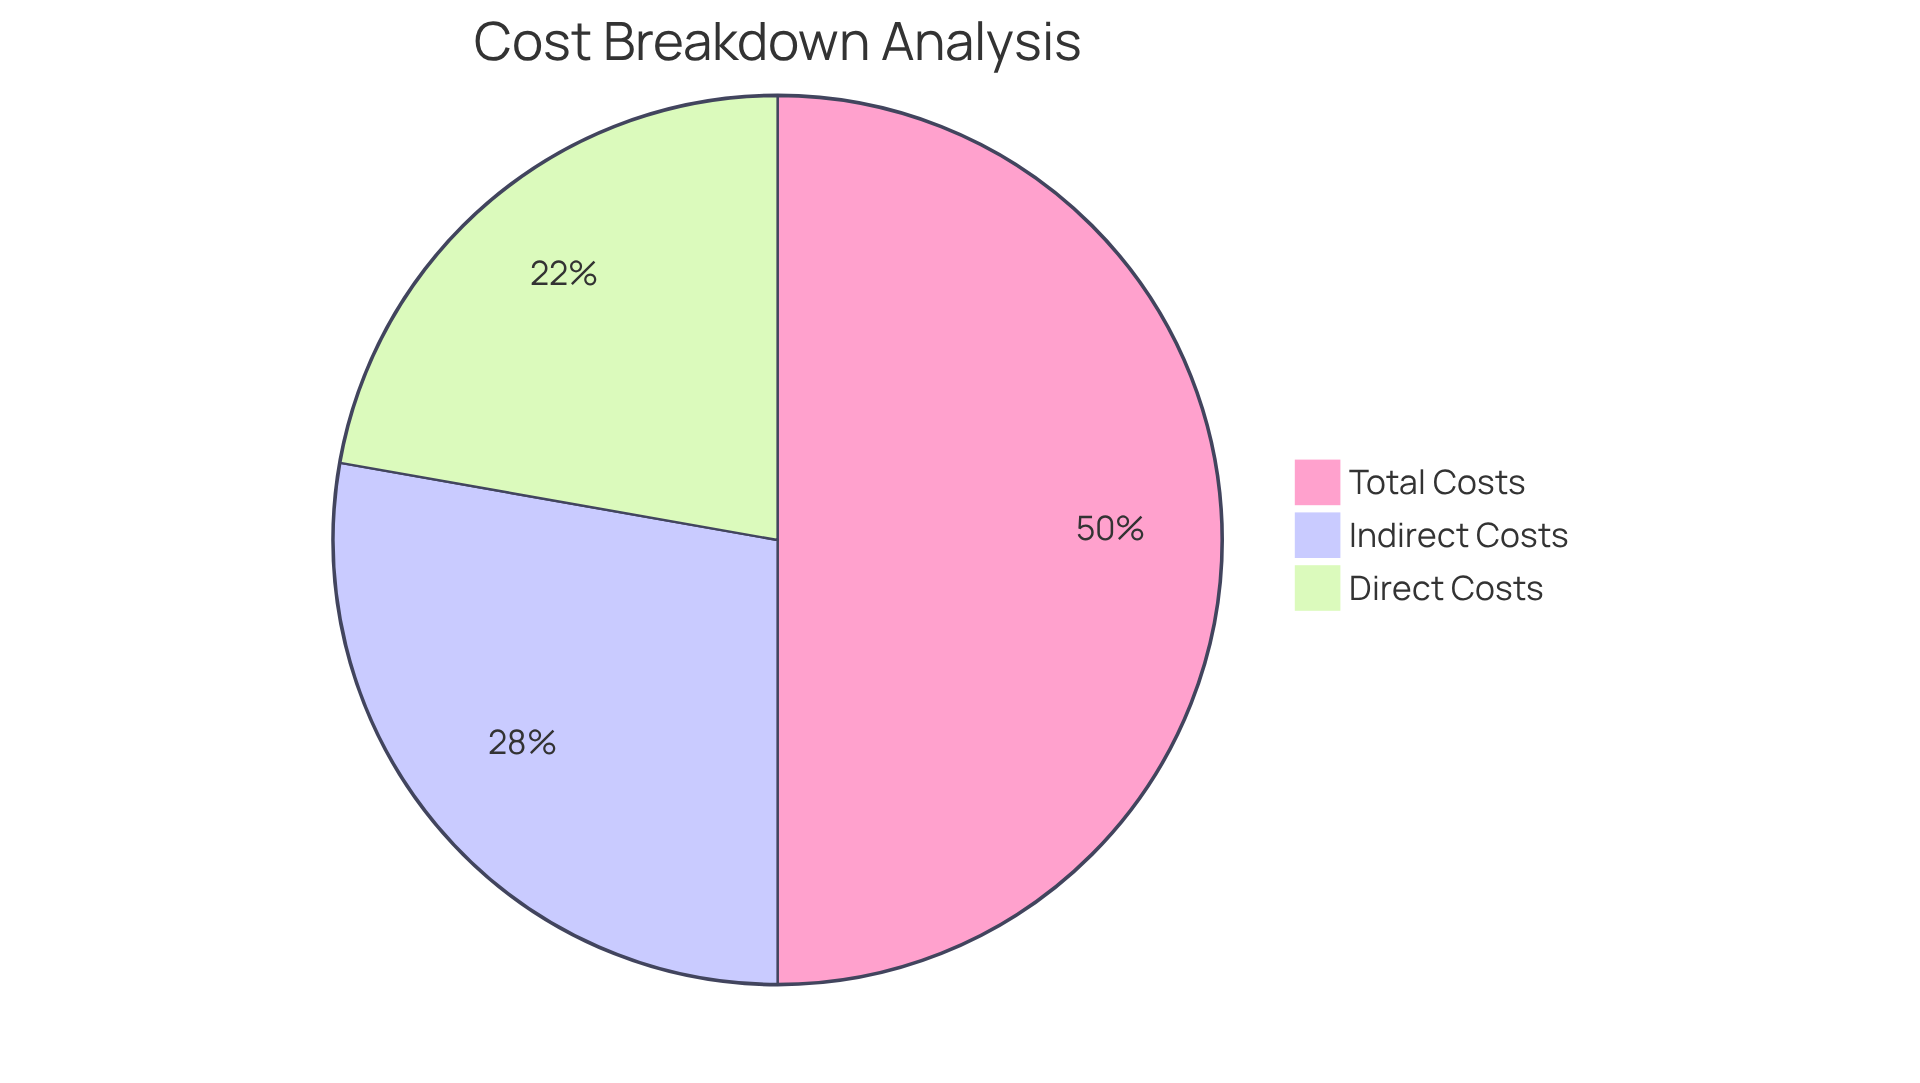
Compare Fee Structures: Direct, Indirect, and Hidden Costs
Many families struggle to understand the true costs of financial services, and it can feel overwhelming. When assessing pricing structures, it’s important to distinguish between direct expenses, like clear charges for services, and indirect expenses, which include hidden costs like fund management fees and trading commissions. You might not realize that indirect expenses can add another 0.5% to 1% due to hidden charges in mutual funds or ETFs.
For instance, traditional financial advisors typically charge between 0.75% and 1.5% of assets under management (AUM) as a direct fee. Actively managed mutual funds average expense ratios between 0.75% and 1.50%, while ETFs average just 0.14% in 2024. These concealed expenses can greatly diminish investment returns over time, and many families find it challenging to navigate the hidden costs of financial services. This lack of clarity can lead to unexpected financial strain over time, highlighting the importance of carefully scrutinizing all possible charges.
At Bright Advisers, we truly care about helping families like yours reduce fund charges, which pertains to the vast majority of our models. Imagine a family investing $100,000 only to see their returns shrink by thousands over ten years due to hidden charges. This is a reality for many, as emphasized in research on the effect of fund layering on investment expenses.
By recognizing these differences and the forthcoming Total Cost Reporting (TCR) changes effective January 1, 2026, you can make more informed choices regarding your resource management options. By staying informed and vigilant, you can protect your family’s financial future and ensure every dollar works for you.
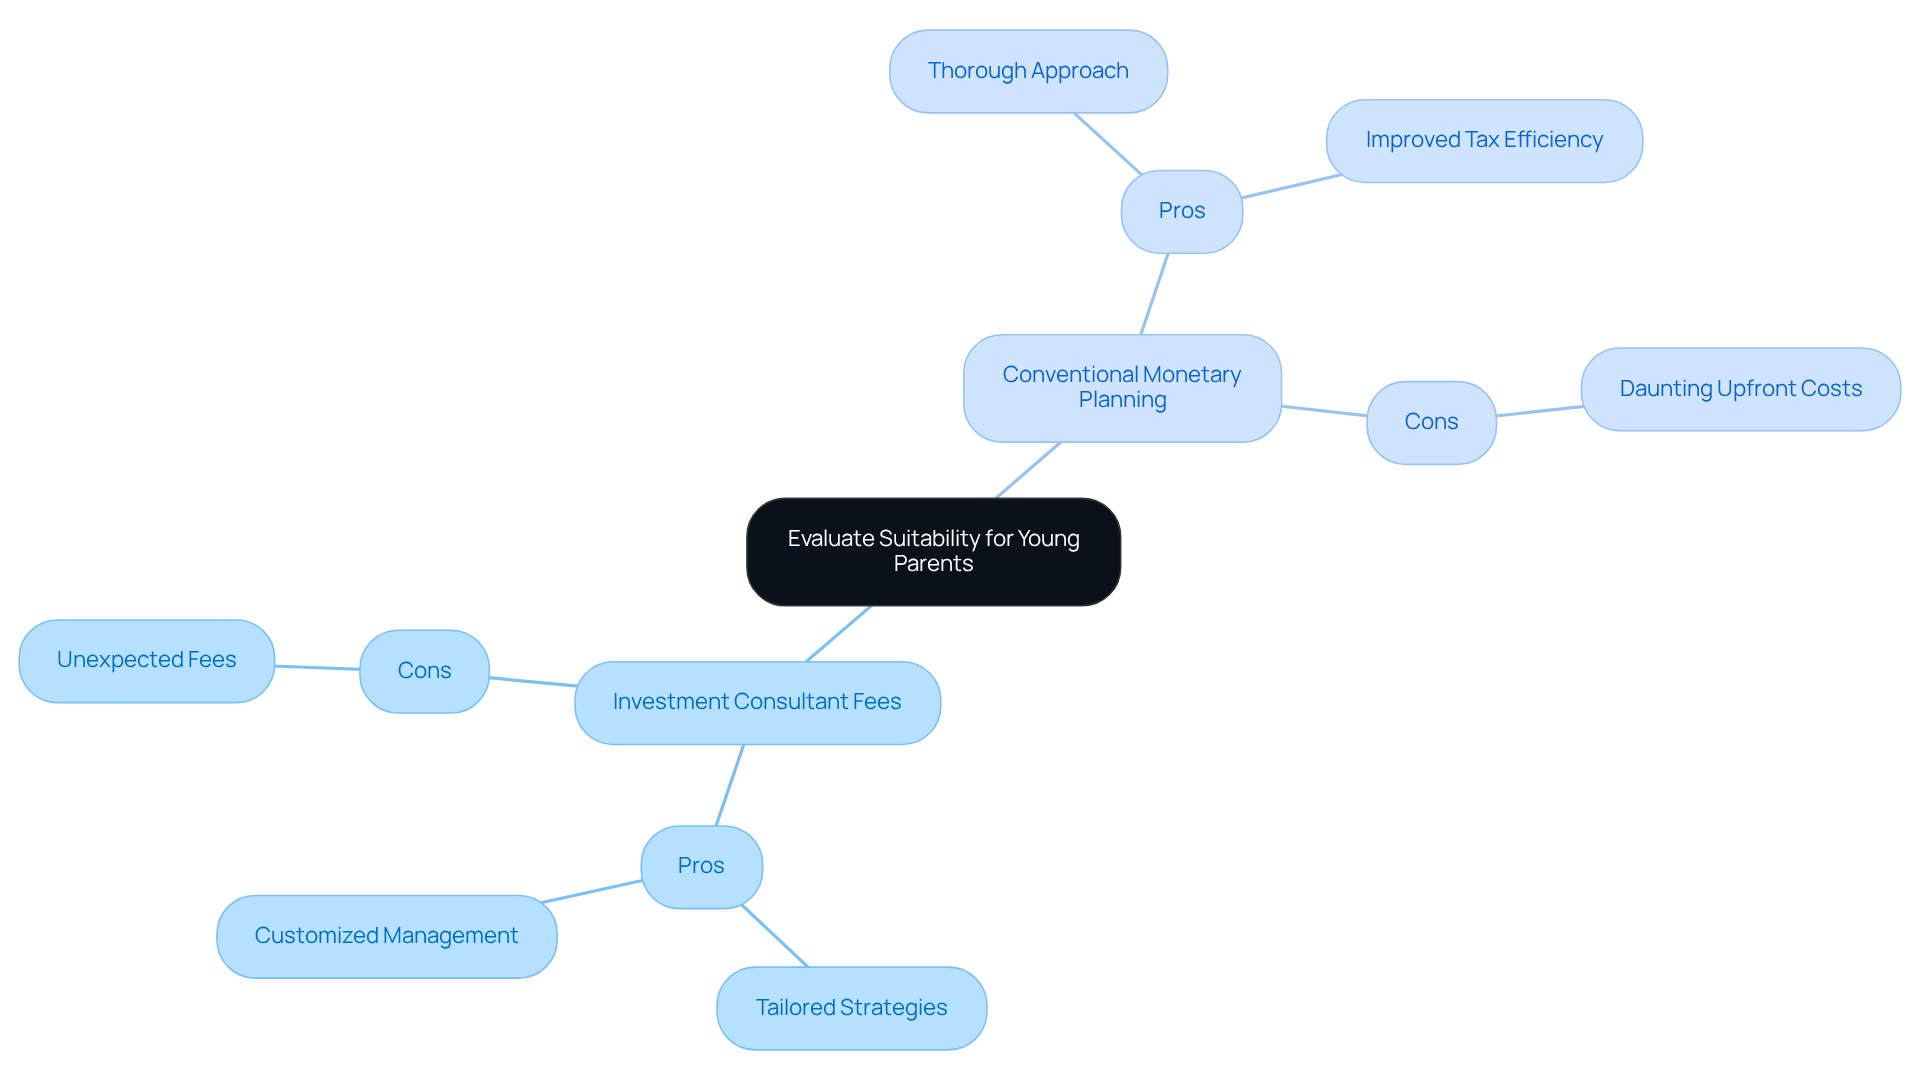
Evaluate Suitability for Young Parents: Pros and Cons of Each Approach
Navigating the world of investment consultant fees can feel overwhelming for young parents, especially when balancing family needs and financial goals. Investment advisors often provide tailored investment strategies and customized portfolio management, which can be especially beneficial for households seeking to increase their wealth. Many parents are concerned about unexpected investment consultant fees that could strain their budgets.
On the other hand, conventional monetary planning offers a more thorough method, tackling different aspects of a household’s economic landscape, including budgeting, tax strategy, and estate management. While the upfront costs might feel daunting, the thorough approach can lead to better financial health for your family in the long run. For example, households investing in a comprehensive monetary strategy often experience improved tax efficiency and effective wealth preservation methods, which can ultimately surpass the initial costs.
By understanding these factors, parents can make informed choices that truly support their family’s financial well-being, ensuring that their planning is both effective and customized to their unique needs.
Explore Innovative Wealth Management Solutions for Families
Imagine the worry of not knowing if you’re saving enough for your child’s future. At Bright Advisers, we understand that every family is unique, and we’re here to create personalized investment plans that fit your needs. We focus on keeping your costs low, so you can invest more in your family’s future without worrying about investment consultant fees. Our tax strategies are designed to help your family grow wealth while keeping more of what you earn, so you can focus on what truly matters.
With our support, you can feel confident that your family’s financial future is secure and aligned with your values. We believe that open communication is key to building trust, especially during important moments like passing on wealth to the next generation. We’re here for families of all sizes, offering clear and fair pricing, so you can focus on what matters most – your loved ones.
Conclusion
Many families feel overwhelmed by the complexity of financial fees, unsure of which path to take for their future. Understanding the differences between investment consultant fees and traditional financial planning costs can help you secure your family’s financial future. By recognizing how these fees are structured and their potential long-term impacts on wealth growth, you can make informed decisions that align with your family’s goals.
Choosing the right approach can truly shape your family’s financial well-being, especially when it aligns with your unique needs and dreams. Throughout this article, we’ve shared key insights about the direct, indirect, and hidden costs associated with both investment consulting and traditional planning. Investment consultant fees, often based on a percentage of assets under management, can accumulate over time. In contrast, traditional planning costs may seem higher upfront but often provide comprehensive services that lead to better financial outcomes.
It’s important to understand all potential charges, as this knowledge empowers families to navigate their financial journeys with confidence. By gaining clarity on these fees, families can confidently choose the best financial path for their unique journey.
When deciding between investment consultants and traditional planners, consider your family’s specific circumstances and aspirations. Embracing innovative wealth management solutions can lead to a more secure financial future, allowing you to focus on nurturing your children and building lasting legacies. Engaging with a fiduciary advisor like Bright Advisers ensures that your family receives personalized, liability-driven wealth management without hidden fees or conflicts of interest. By taking the time to understand your options, you can create a financial legacy that nurtures your family’s dreams for generations to come.
Frequently Asked Questions
What are investment consultant fees?
Investment consultant fees are costs associated with hiring experts to manage investments, typically structured as a percentage of assets under management (AUM), fixed rates, or hourly fees.
How much do investment consultant fees typically range?
In 2026, many investment consultant fees range from 1% to 2% of AUM annually.
How can investment consultant fees impact investment growth?
Investment consultant fees can significantly affect how much your investments grow over time. For example, on a $500,000 portfolio, a 1% fee means $5,000 annually, which could lead to over $330,000 in lost returns over 20 years if not managed effectively.
What do traditional financial planning costs cover?
Traditional financial planning costs cover a wider range of services, including comprehensive planning, tax strategies, and estate planning.
How are traditional financial planning costs typically charged?
Traditional financial planning costs are often charged as fixed amounts or hourly rates, with thorough monetary plans typically ranging from $2,000 to $8,000, depending on the complexity of your financial situation.
Why is it important for parents to understand the differences in fees?
It’s important for parents to understand these differences so they can choose the right path for their family’s financial goals, especially considering the current trends in investment advisor charges and their potential long-term effects on wealth growth.
What is Bright Advisers’ approach to fees?
Bright Advisers is committed to keeping fees low and offering personalized solutions that fit families’ needs, ensuring clarity and no hidden costs to assist families in securing their economic future.
List of Sources
- Define Investment Consultant Fees and Traditional Financial Planning Costs
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- Free advisor fee calculator: is your 1% really 1%? (2026) (https://truthifi.com/education/advisor-fee-fair)
- How Much Does a Financial Advisor Cost? It Depends. – NerdWallet (https://nerdwallet.com/financial-advisors/learn/how-much-does-a-financial-advisor-cost)
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- How Much Does a Financial Advisor Cost? (https://smartasset.com/financial-advisor/financial-advisor-cost)
- Compare Fee Structures: Direct, Indirect, and Hidden Costs
- What is the true impact of hidden fees on investment returns? (https://home.saxo/learn/guides/pricing/what-is-the-true-impact-of-hidden-fees-on-investment-returns)
- How to Spot Hidden Investment Fees | JCIC Asset Management Inc. (https://jcic.ca/insights/how-to-spot-hidden-investment-fees)
- Investment Management Fees Explained: What You’re Really Paying For – Towerpoint Wealth (https://towerpointwealth.com/investment-management-fees-explained-what-youre-really-paying-for)
- Mutual Fund Fees Explained: Hidden Costs & What to Avoid (https://boldin.com/retirement/fees-and-expenses-on-mutual-funds-and-etfs-a-complete-guide-to-the-often-misunderstood-and-hidden-costs-of-investments)
- Hidden Costs in ETFs and Mutual Funds That Affect Your Returns (https://mutualfundnation.com/hidden-costs-in-etfs-and-mutual-funds)
- Evaluate Suitability for Young Parents: Pros and Cons of Each Approach
- Financial Advisor Statistics in 2026: Growth and Trends in the Financial Advisory Industry in the USA (https://randallwealthgroup.com/financial-advisor-statistics)
- BofA Study Finds Fewer Gen Z Rely on Family for Financial Assistance, Even With 42% Living Paycheck to Paycheck (https://newsroom.bankofamerica.com/content/newsroom/press-releases/2026/05/bofa-study-finds-fewer-gen-z-rely-on-family-for-financial-assist.html)
- Trending (https://advisorsmagazine.com/trending/choosing-a-financial-advisor-in-2026)
- Average Savings by Age: 2026 Statistics (https://journeyadvisory.group/blog/average-savings-by-age-2026-statistics)
- Newsroom | Northwestern Mutual – Planning & Progress Study 2026 (https://news.northwesternmutual.com/planning-and-progress-study-2026)
- Explore Innovative Wealth Management Solutions for Families
- 10 Wealth Management Trends For 2026 (https://oliverwyman.com/our-expertise/insights/2025/dec/wealth-management-trends-2026.html)
- Top Wealth Management Trends in 2026: The Shift to Agentic AI and Private Markets (https://investsuite.com/insights/blogs/top-wealth-management-trends-in-2026-the-shift-to-agentic-ai-and-private-markets)
- Industry Statistics (https://investmentadviser.org/industry-snapshots)
- Wealth Trends 2026 | MSCI (https://msci.com/research-and-insights/research-reports/2026-wealth-trends)
- 7 Innovation trends reshaping wealth management in 2026 (https://linkedin.com/pulse/7-innovation-trends-reshaping-wealth-management-2026-ronald-janssen-ed7re)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading