

Overview
Is $2 million enough to retire at 40? Yes, it can be! With thoughtful planning, $2 million can provide a comfortable retirement at 40. Imagine being able to enjoy your golden years while ensuring your family’s future is secure. To make this dream a reality, it’s essential to:
- Carefully estimate your living expenses.
- Consider the impact of inflation.
- Diversify your investments.
Following the 4% withdrawal rule can be a helpful guideline.
It’s important to understand that accurately estimating your expenses is crucial. Think about your family’s needs and how they might change over time. By accounting for inflation, you can better prepare for the future. Diversifying your investments ensures that your funds will last throughout retirement, allowing you to focus on what truly matters—spending time with your loved ones.
Together, we can navigate this journey. With the right planning and support, retiring comfortably with $2 million is not just a dream but an achievable goal. Remember, you’re not alone in this; we’re here for you every step of the way.
Key Highlights:
- Accurately estimate monthly living expenses, including housing, healthcare, and leisure, to avoid future deficits.
- Consider the desired age of retirement and the number of years expected to retire to gauge total savings needs.
- Reflect on family financial responsibilities, including children’s education and support for aging parents.
- Account for inflation’s long-term impact on expenses, as many Americans fear outliving their savings.
- Use the 4% rule for annual withdrawals to balance spending and fund longevity, adjusting for inflation.
- Evaluate investment returns, aiming for a conservative estimate of 4% to 6% for retirement planning.
- Understand the tax implications of various income sources during retirement to optimise financial strategy.
- Maximise contributions to retirement accounts and take advantage of employer matching to enhance savings.
- Automate savings through regular transfers to retirement accounts to ensure consistent contributions.
- Review monthly budgets to identify areas for expense reduction and redirect savings towards retirement.
- Diversify investment portfolios to manage risk and enhance long-term returns.
Introduction
Is it possible to retire at 40 with $2 million in savings? Imagine the dream of early retirement becoming a reality, offering you the chance to spend precious moments with your family. Many are left wondering if this substantial sum can truly secure a comfortable lifestyle for decades to come. In this guide, we gently explore the essential steps for evaluating your retirement needs, understanding longevity, and implementing strategies to maximize your savings. We’ll also address the complexities of taxes and investment returns that can feel overwhelming.
It’s important to understand that the path to financial freedom can be fraught with uncertainty. With the stakes high, how can you ensure that your retirement plans are not only ambitious but also achievable? Together, we can navigate this journey, empowering you to make informed decisions for your family’s future.
Evaluate Your Retirement Needs and Goals
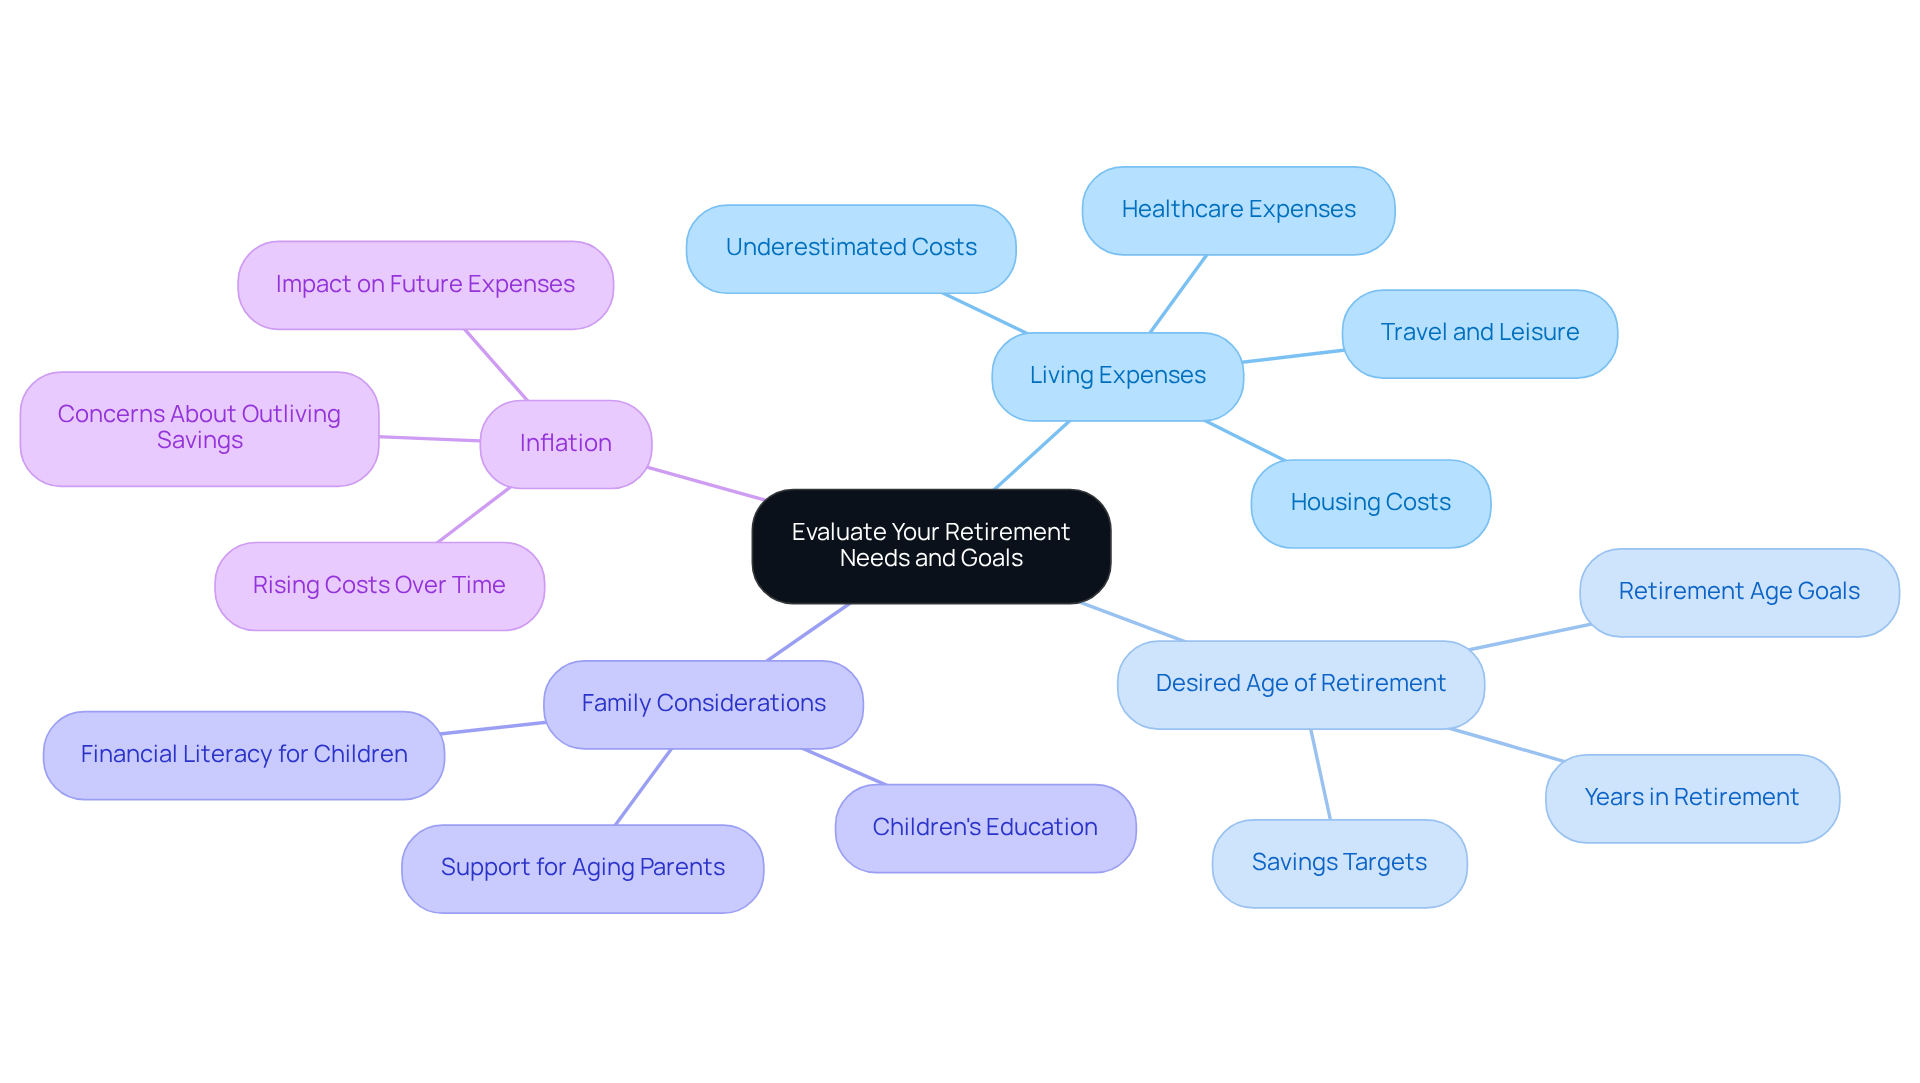
To effectively plan for the future, imagine the lifestyle you wish to embrace. Consider these key factors:
-
Living Expenses: Take a moment to accurately estimate your monthly expenses, encompassing housing, healthcare, travel, and leisure activities. Many Americans, unfortunately, undervalue these expenses, which can lead to deficits in their later years. Understanding these costs is vital, and Bright Advisers is here to help you create a personalized financial plan that aligns with your goals.
-
Desired Age of Retirement: Think about the age at which you hope to retire and how many years you expect to enjoy that time. This reflection will guide you in gauging the total savings needed. Bright Advisers can assist you in developing a strategy to meet those savings targets.
-
Family Considerations: Reflect on your children’s education, potential support for aging parents, and other family-related financial responsibilities. Teaching children financial literacy can profoundly influence your financial strategy. By modeling positive financial behaviors, you help them cultivate a healthier understanding of money. Bright Advisers offers tailored solutions to support families in navigating these important considerations.
-
Inflation: It’s essential to consider the long-term impact of inflation on your future expenses. With fluctuating inflation rates, accounting for rising costs over time is crucial. Notably, 51% of Americans believe it is somewhat or very likely they will outlast their savings, highlighting the importance of planning for inflation to secure your financial future. Bright Advisers is dedicated to reducing fund fees, ensuring that more of your investment goes toward achieving your financial objectives.
Once you have a clear understanding of your financial future needs, document your goals. As John Roberts, chief field officer at Northwestern Mutual, emphasizes, “Planning for the later years is profoundly personal.” This documentation will serve as a roadmap for your financial planning, guiding you toward a secure and fulfilling future. Remember, we’re here for you, and together, we can navigate this journey.
Calculate Longevity of $2 Million in Retirement
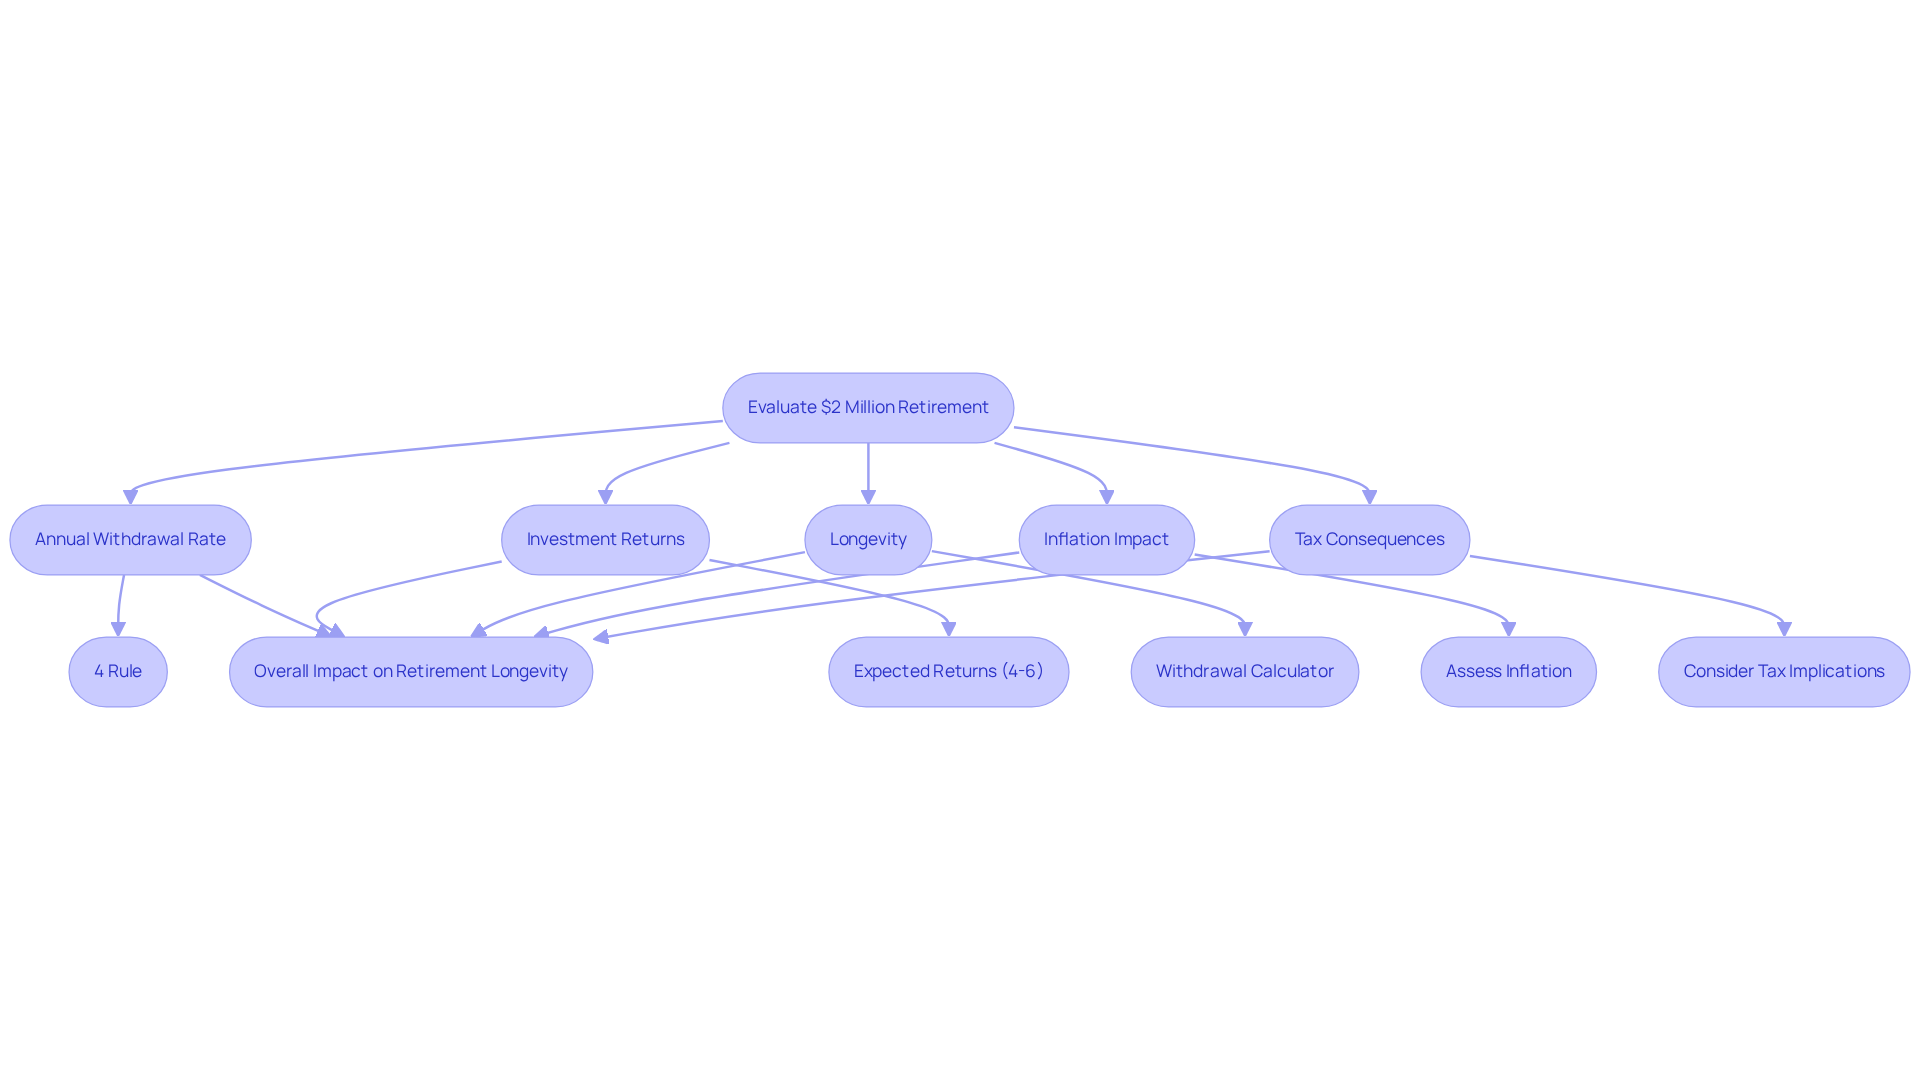
To determine how long $2 million will sustain your retirement, let’s explore some important factors together:
-
Annual Withdrawal Rate: Start by establishing your desired annual withdrawal amount. A widely recognized guideline is the 4% rule, suggesting you withdraw 4% of your initial investment portfolio each year, adjusted for inflation. This approach helps balance your spending needs with the longevity of your funds, ensuring you feel secure as you plan for the future.
-
Investment Returns: Think about the anticipated average yearly return on your investments during your later years. For 2025, a conservative estimate for retirees might range from 4% to 6%. This return will significantly influence how long your savings will last, so it’s important to stay informed.
-
Longevity: Imagine using a withdrawal calculator to enter your chosen withdrawal rate, expected returns, and life span. This tool can help you visualize how long your funds may last under various scenarios, providing peace of mind as you plan.
-
Inflation Impact: It’s crucial to remember that inflation can erode your purchasing power over time. Regularly assessing your withdrawal strategy in light of inflation is vital for preserving your economic well-being in your later years, ensuring you can maintain your lifestyle.
-
Tax Consequences: Don’t forget to consider the tax implications of your post-employment earnings. Different sources of income may be taxed at varying rates, which can affect your overall financial strategy. Understanding this can help you make informed decisions.
For instance, if you withdraw $80,000 each year (which is 4% of $2 million) and achieve an average return of 5%, it makes one wonder, is 2 million enough to retire at 40, as your funds could potentially last about 30 years. However, actual outcomes will depend on market fluctuations, inflation, and tax considerations. Regularly evaluating your investment approach and adjusting your withdrawal rate as needed can further enhance the sustainability of your funds for later years.
It’s also important to highlight that $2 million is 684% greater than the typical savings for Americans, leading to the question: is 2 million enough to retire at 40, which underscores the significance of having this amount set aside. As the average age of leaving the workforce has risen from 57 in 1991 to 61 today, planning ahead becomes essential for young families.
At Bright Advisers, we are here for you, specializing in personalized financial planning and tailored wealth management solutions. Together, we can navigate this journey, empowering families to secure their financial future through strategic planning and tax optimization.
Assess Retirement Income Taxes and Their Impact
To effectively assess the impact of taxes on your retirement income, let’s explore some thoughtful steps together:
-
Identify Revenue Sources: Begin by outlining all possible revenue sources, such as Social Security benefits, pensions, and withdrawals from savings accounts like 401(k)s and IRAs. This foundational understanding is crucial as you plan for your family’s future.
-
Understand Tax Brackets: It’s important to familiarize yourself with the current tax brackets, as these determine how your various sources of revenue are taxed. Remember, withdrawals from conventional savings accounts are typically taxed as regular earnings, which can significantly influence your total tax obligation.
-
Calculate Tax Obligation: Take a moment to estimate your total taxable earnings during your later years. This will help you understand your anticipated tax obligation and how much of your earnings will be available for your family’s needs, enabling better budgeting and planning.
-
Consider Tax-Advantaged Accounts: Explore strategies to minimize your tax burden, such as converting traditional IRAs to Roth IRAs, which can offer tax-free withdrawals in your later years. Additionally, utilizing Health Savings Accounts (HSAs) for medical expenses can further enhance your tax efficiency, allowing you to focus on what truly matters—your family’s well-being.
By incorporating these considerations into your planning, you can develop a clearer understanding of your financial landscape. Together, we can adjust your withdrawal strategies to optimize your income, ensuring a secure and nurturing environment for your loved ones.

Implement Strategies to Boost Retirement Savings
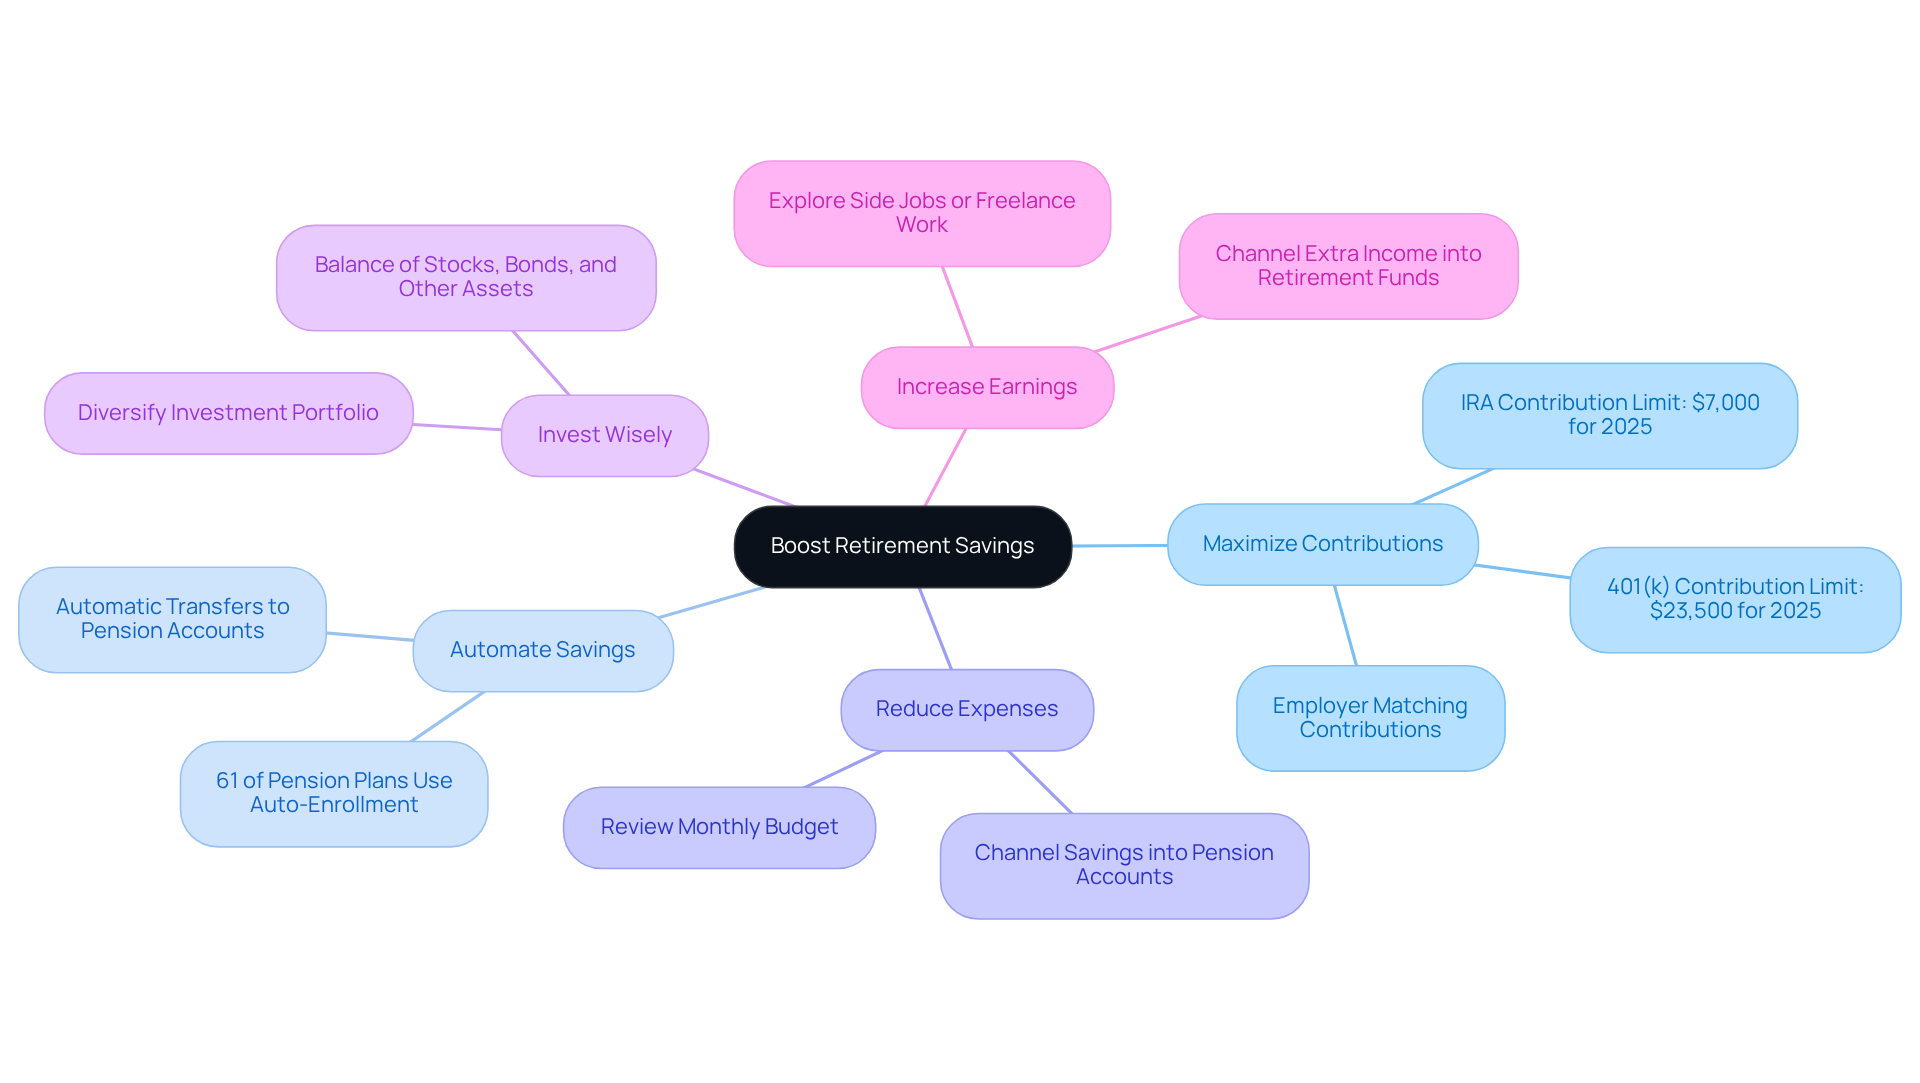
To effectively boost your retirement savings, consider implementing the following strategies:
-
Maximize Contributions: Imagine if you could contribute the maximum allowable amounts to your savings accounts, such as 401(k)s and IRAs. For 2025, the contribution limit for 401(k) plans is $23,500, while the IRA limit remains at $7,000. Additionally, take full advantage of any employer matching contributions, which can significantly enhance your savings.
-
Automate Savings: It’s important to understand the benefits of setting up automatic transfers to your pension accounts. This approach not only ensures consistent contributions but also helps you avoid the temptation to spend that money elsewhere. At present, 61% of pension plans employ auto-enrollment, facilitating saving for participants.
-
Reduce Expenses: Take a moment to conduct a thorough review of your monthly budget to identify areas where you can cut back. Channel these funds into your pension accounts. Small adjustments can lead to substantial contributions over time, reinforcing the principle that saving requires delaying gratification for larger future rewards.
-
Invest Wisely: Think about diversifying your investment portfolio to manage risk effectively. A balanced combination of stocks, bonds, and other assets customized to your risk tolerance and financial timeline can enhance returns. Remember, the stock market often rewards patience, transferring wealth from the impatient to the patient.
-
Increase Earnings: Together, we can explore opportunities to enhance your earnings through side jobs or freelance work. Channeling this extra income into your future funds can expedite your advancement towards economic stability.
By adopting these strategies, you’re not just enhancing your retirement savings; you’re taking meaningful steps towards achieving your long-term financial goals. We’re here for you on this journey, ensuring that you and your family can thrive.
Conclusion
To determine whether $2 million is sufficient for retiring at 40, it’s essential to thoughtfully evaluate your individual financial goals and needs. Imagine the peace of mind that comes from understanding your living expenses, desired retirement age, family obligations, and the impact of inflation on your future financial needs. By grasping these factors, you can create a personalized roadmap that secures your financial future.
Key insights highlight the importance of establishing a sustainable withdrawal rate, considering investment returns, and accounting for taxes on retirement income. Implementing strategies such as maximizing contributions, automating savings, and reducing expenses can significantly enhance your retirement savings. While $2 million is notably above average American savings, it requires careful planning and informed decision-making to ensure it lasts throughout your retirement.
Ultimately, the journey to a secure retirement involves proactive financial planning and strategic adjustments. By taking the necessary steps today, you can pave the way for a fulfilling and financially stable future. Embracing this proactive approach not only helps in assessing the adequacy of your retirement funds but also empowers you to make informed choices that align with your long-term family goals. Remember, together, we can navigate this journey towards a secure and happy retirement.
Frequently Asked Questions
What should I consider when evaluating my retirement needs and goals?
Key factors to consider include living expenses, desired age of retirement, family considerations, and the impact of inflation.
How can I estimate my living expenses for retirement?
Accurately estimate your monthly expenses by including housing, healthcare, travel, and leisure activities. Many people underestimate these costs, which can lead to financial deficits later in life.
Why is it important to define my desired age of retirement?
Defining your desired retirement age helps gauge the total savings needed for that period, allowing for better financial planning.
What family considerations should I keep in mind when planning for retirement?
Consider your children’s education, potential support for aging parents, and other family-related financial responsibilities. Teaching children financial literacy can also influence your financial strategy positively.
How does inflation affect my retirement planning?
Inflation can significantly impact future expenses, so it’s crucial to account for rising costs over time. Many Americans worry about outlasting their savings, highlighting the importance of planning for inflation.
What role does documentation play in retirement planning?
Documenting your financial goals serves as a roadmap for your planning, guiding you toward a secure and fulfilling future.
List of Sources
- Evaluate Your Retirement Needs and Goals
- The Best Quotes About Retirement (https://retirable.com/advice/lifestyle/best-retirement-quotes)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- 35 Retirement Quotes for a Happy, Healthy, and Wealthy Life (https://ruleoneinvesting.com/blog/personal-development/retirement-quotes)
- Americans Believe They Will Need $1.26 Million to Retire Comfortably According to Northwestern Mutual 2025 Planning & Progress Study (https://news.northwesternmutual.com/2025-04-14-Americans-Believe-They-Will-Need-1-26-Million-to-Retire-Comfortably-According-to-Northwestern-Mutual-2025-Planning-Progress-Study)
- Retirement Planning Quotes (68 quotes) (https://goodreads.com/quotes/tag/retirement-planning)
- Calculate Longevity of $2 Million in Retirement
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- How Long Will $2 Million Last in Retirement Calculator | The Annuity Expert (https://annuityexpertadvice.com/calculator/retirement/2-million)
- Can you retire with $2 million? [Updated March 2025] (https://unbiased.com/discover/retirement/can-you-retire-on-2-million)
- How Long $2 Million Will Last In Retirement (https://mywealthtrace.com/blog/how-long-will-2-million-dollars-last-in-retirement)
- The 4% Rule: How Much Can You Spend in Retirement? (https://schwab.com/learn/story/beyond-4-rule-how-much-can-you-spend-retirement)
- Assess Retirement Income Taxes and Their Impact
- 6 retirement tax planning strategies you should know (https://thrivent.com/insights/taxes/6-retirement-tax-planning-strategies-you-should-know)
- Tax Brackets And Federal Income Tax Rates For 2024-2025 | Bankrate (https://bankrate.com/taxes/tax-brackets)
- Wealth Planning for Executives & High-Net-Worth Families – Paramus, NJ (https://wealth-navigators.com/case_studies)
- Tax Laws and Tax Brackets 2025 | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/financial-planning/tax-brackets.html)
- Case Study: Retirees – Mariaca Wealth Management (https://mariacawealth.com/case_studies/retirees)
- Implement Strategies to Boost Retirement Savings
- 13 Quotes to Help Plan for Retirement | The Motley Fool (https://fool.com/retirement/2020/06/25/13-quotes-to-help-plan-for-retirement.aspx)
- 401(k) limit increases to $23,500 for 2025, IRA limit remains $7,000 | Internal Revenue Service (https://irs.gov/newsroom/401k-limit-increases-to-23500-for-2025-ira-limit-remains-7000)
- 150 Quotes on Saving, Investing, and Financial Wellness (https://deliberatedirections.com/quotes-financial-wellness)
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- 14 Must-Know Retirement Stats For 2025 – Carry (https://carry.com/learn/retirement-stats)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading