

Overview
Is $2 million enough to retire at 50? It can be sufficient, but it requires careful financial planning that considers:
- Living expenses
- Healthcare costs
- Investment returns
Imagine if you could enjoy your retirement without financial stress. By utilizing the 4% rule for sustainable withdrawals, you can set yourself up for success. It’s important to evaluate these factors and consider adjusting withdrawal rates for inflation. Together, we can navigate this journey and help you determine if your retirement savings will adequately support your desired lifestyle throughout your golden years. Remember, we’re here for you, ready to assist you in making informed decisions for your family’s future.
Key Highlights:
- Evaluate current living expenses, projected inflation, and desired retirement lifestyle to create a realistic financial plan.
- Healthcare costs can be significant; a married couple retiring in 2023 may need about $351,000 for healthcare expenses.
- Consider family financial support needs, such as children’s education, when planning retirement finances.
- Use the 4% rule to estimate annual withdrawals from retirement savings, ensuring a balance between spending and security.
- Account for investment returns to extend the longevity of retirement savings, aiming for a 75%-90% confidence level in withdrawals.
- Adjust withdrawals for inflation to maintain purchasing power over time, critical for long-term financial planning.
- Assess various income sources and their tax treatments to optimise retirement income and minimise tax burdens.
- Maximise contributions to retirement accounts, taking full advantage of employer matches to bolster savings.
- Diversify investments to balance risk and enhance growth potential for retirement funds.
- Reduce current expenses and redirect savings into retirement accounts to strengthen financial security.
- Consider delaying retirement to increase savings and reduce reliance on retirement funds.
Introduction
Considering the possibility of retiring at 50 with a $2 million nest egg invites important reflections on financial security and the sustainability of your lifestyle. As you think about this significant life change, it becomes essential to grasp the nuances of retirement planning. What strategies can help ensure that this amount not only lasts but also supports the lifestyle you envision for your family?
Imagine delving into the intricacies of budgeting, investment returns, and tax implications. These aspects reveal the complexities of achieving financial independence at a young age, prompting us to question whether $2 million is truly enough for a comfortable retirement. Together, we can navigate this journey, ensuring that your family’s future is secure and fulfilling.
Evaluate Your Retirement Needs and Goals
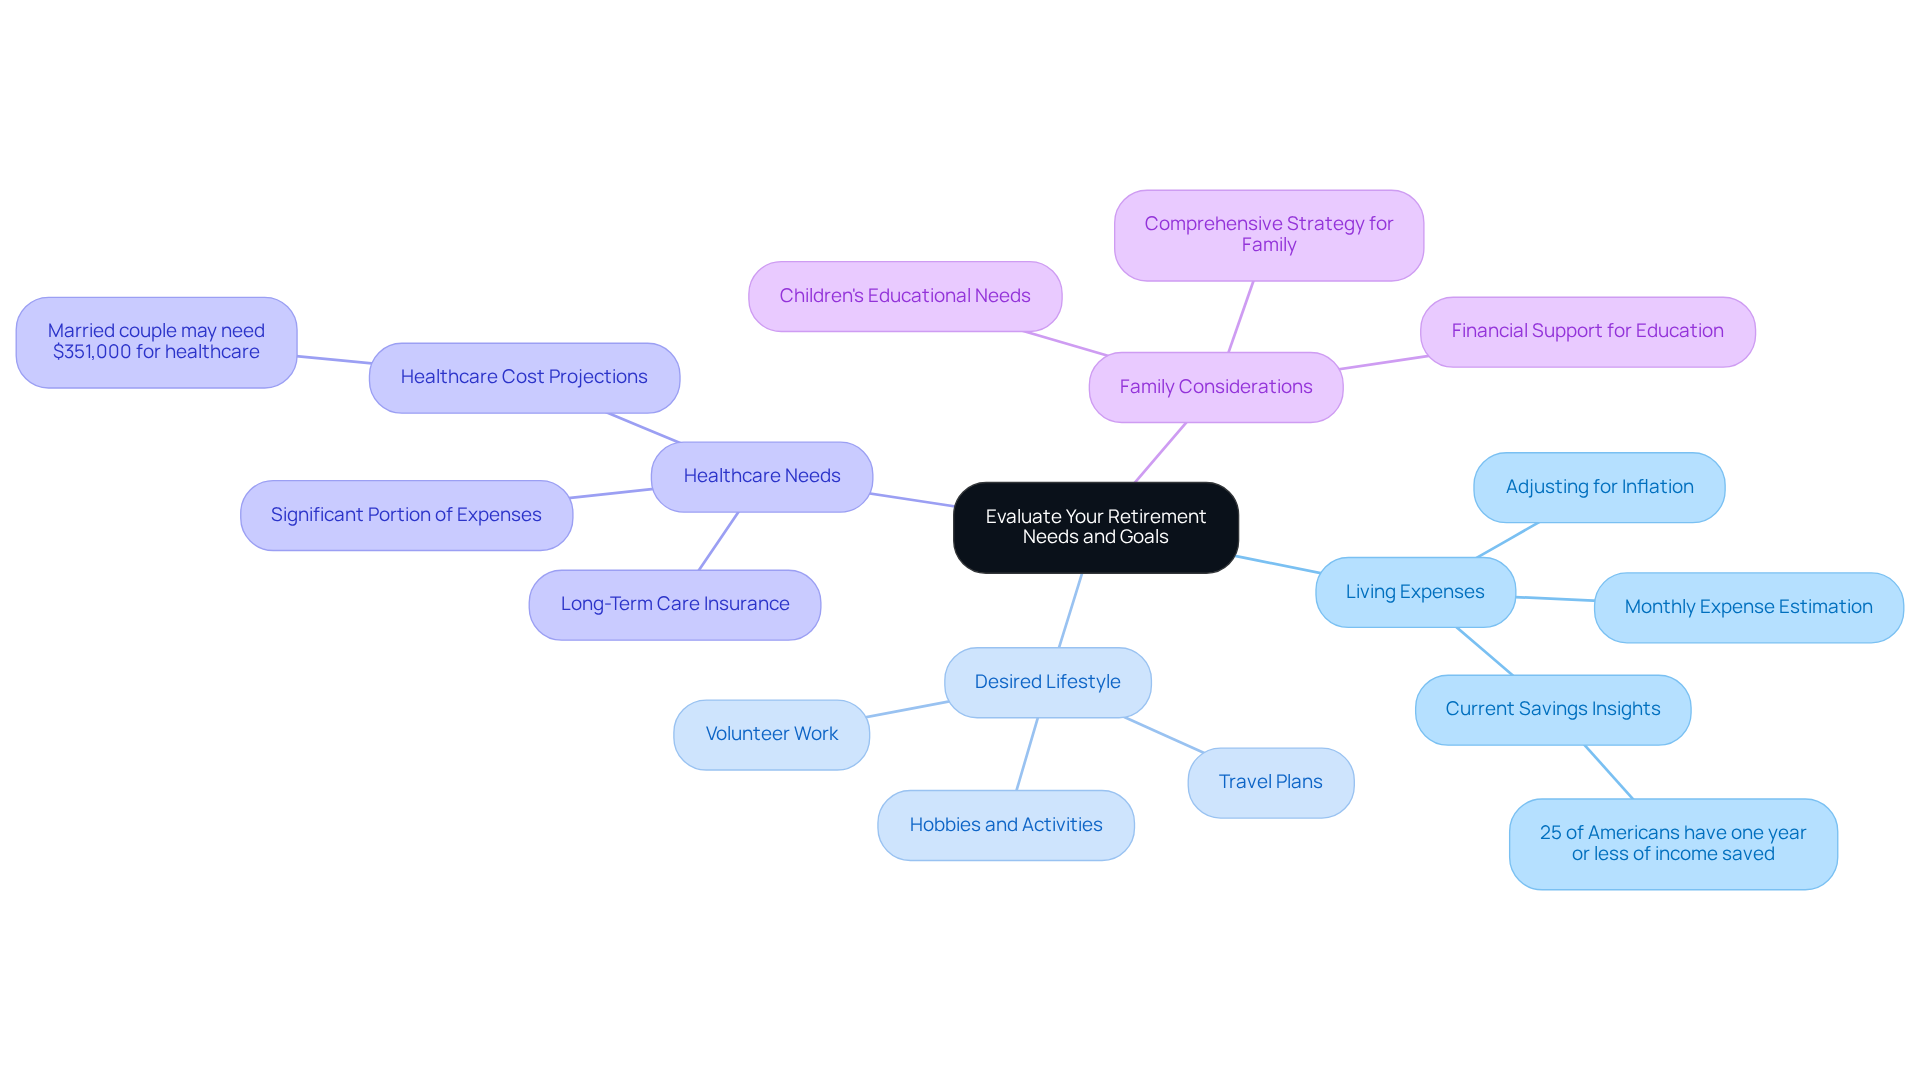
To effectively assess your future needs and objectives, begin by evaluating your current way of living and imagining your ideal post-career lifestyle. Consider the following factors:
-
Living Expenses: Start by estimating your monthly expenses, including housing, food, healthcare, and leisure activities. Use your current budget as a baseline, adjusting for inflation to ensure accuracy in your projections. In 2025, the average monthly expenses for families after their working years are expected to reflect rising costs, making this step crucial. Significantly, 25% of Americans with savings for later life have only one year or less of their current annual income set aside, highlighting the necessity of comprehensive financial planning for the future.
-
Desired Lifestyle: Imagine how you envision spending your time in retirement. Will you travel, pursue hobbies, or engage in volunteer work? Each of these activities can incur costs, so it’s essential to consider them in your budgeting. For families like Jay and Emma, who strive to balance their current responsibilities with long-term aspirations, creating a sound financial strategy is key.
-
Healthcare Needs: Recognizing that healthcare can represent a significant portion of retirement expenses is vital. Explore alternatives such as long-term care insurance or health expense accounts (HSAs) to prepare for these future requirements. Recent data indicates that a married couple retiring in 2023 may need approximately $351,000 to cover healthcare costs. Bright Advisers can assist clients in managing these expenses through customized strategies that include healthcare planning.
-
Family Considerations: If you have children, think about their future educational needs and how you might want to support them financially. This could involve saving for college or other educational costs, which can greatly affect your budget for the future. As observed with clients such as Emily and Mark, who sought advice to manage their planning while considering their children’s education, having a comprehensive strategy can enable families to attain both economic security and educational preparedness.
By clearly outlining your future objectives and comprehending the related expenses, you can develop a more precise economic plan that aligns with your dreams. Financial advisors stress that “it’s crucial to keep in mind that planning for the future is highly individual,” and beginning early can lead to a more rewarding experience in later life.
Calculate the Longevity of $2 Million in Retirement
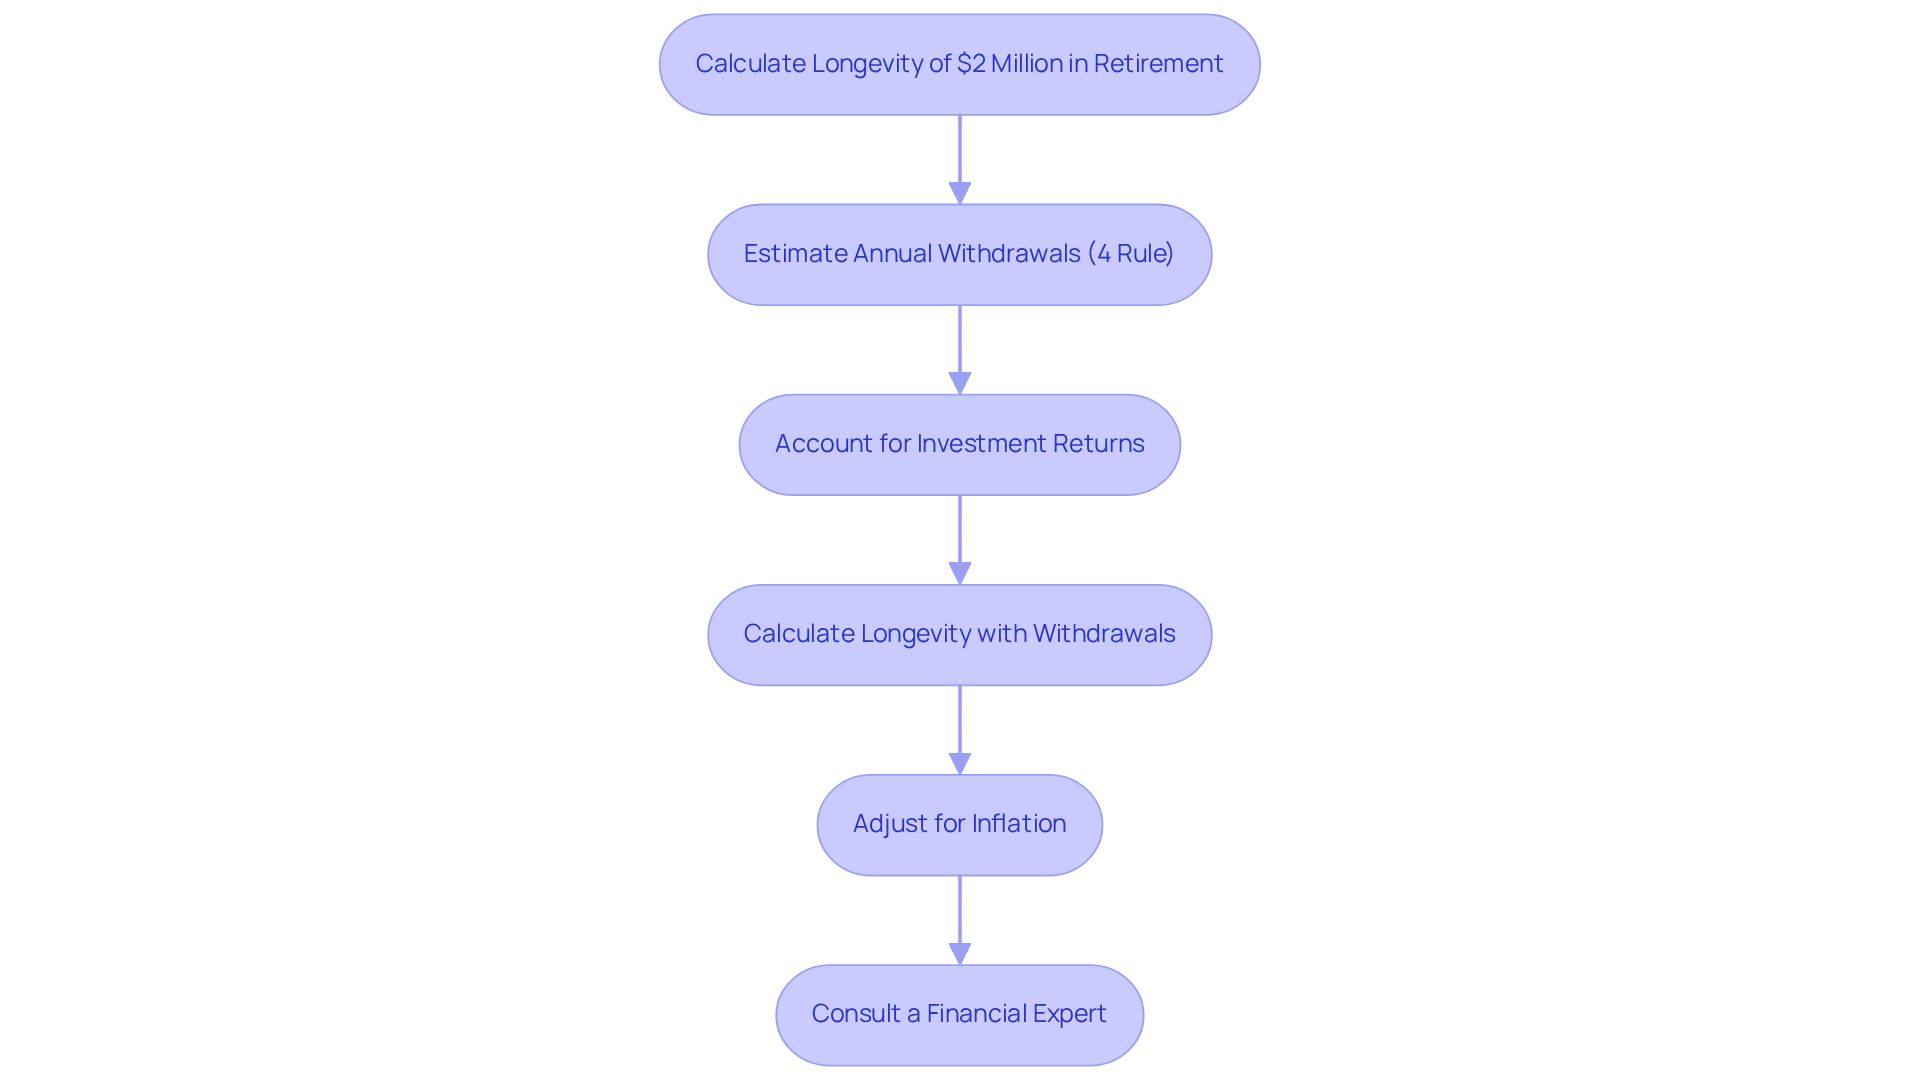
To determine how long $2 million will last in retirement—especially for young families looking to reduce financial anxiety and secure their futures—consider these steps:
-
Estimate Annual Withdrawals: A commonly accepted guideline is the 4% rule, suggesting that you withdraw 4% of your initial savings each year, adjusted for inflation. For a $2 million portfolio, determining if 2 million is enough to retire at 50 means an annual withdrawal of $80,000. Aim for a confidence level of 75% to 90% when planning your withdrawals, balancing your spending limits with the need for economic security.
-
Account for Investment Returns: Think about the expected rate of return on your investments. If your portfolio averages a 5% return, your funds can continue to grow, potentially extending their longevity and providing a cushion against unexpected expenses.
-
Calculate Longevity: Use a retirement calculator or a straightforward formula to estimate how long your funds will last based on your withdrawal rate and anticipated returns. For instance, withdrawing $80,000 each year from a $2 million portfolio with a 5% return raises the question: is 2 million enough to retire at 50, as it might allow your resources to last for about 30 years, giving you reassurance as you navigate your economic future.
-
Adjust for Inflation: Remember that inflation will erode your purchasing power over time. Adjust your withdrawals to support your desired lifestyle, ensuring your budget remains robust against rising expenses. For example, if inflation averages 2.27%, your withdrawals should increase accordingly to maintain your purchasing power—critical for young families planning for long-term needs, such as educational expenses for children.
-
Consult a Financial Expert: Seeking guidance from a financial expert is essential for personalized advice tailored to your unique situation. They can help you navigate the complexities of future planning, ensuring that your strategy aligns with your long-term goals, particularly addressing the unique challenges faced by young families.
By taking these steps and considering these factors, you can gain clearer insight into your financial future. This approach allows you to make informed adjustments to your savings plan, ultimately alleviating stress and ensuring a stable future for your family. Together, we can navigate this journey toward financial security.
Assess Retirement Income Taxes on $2 Million
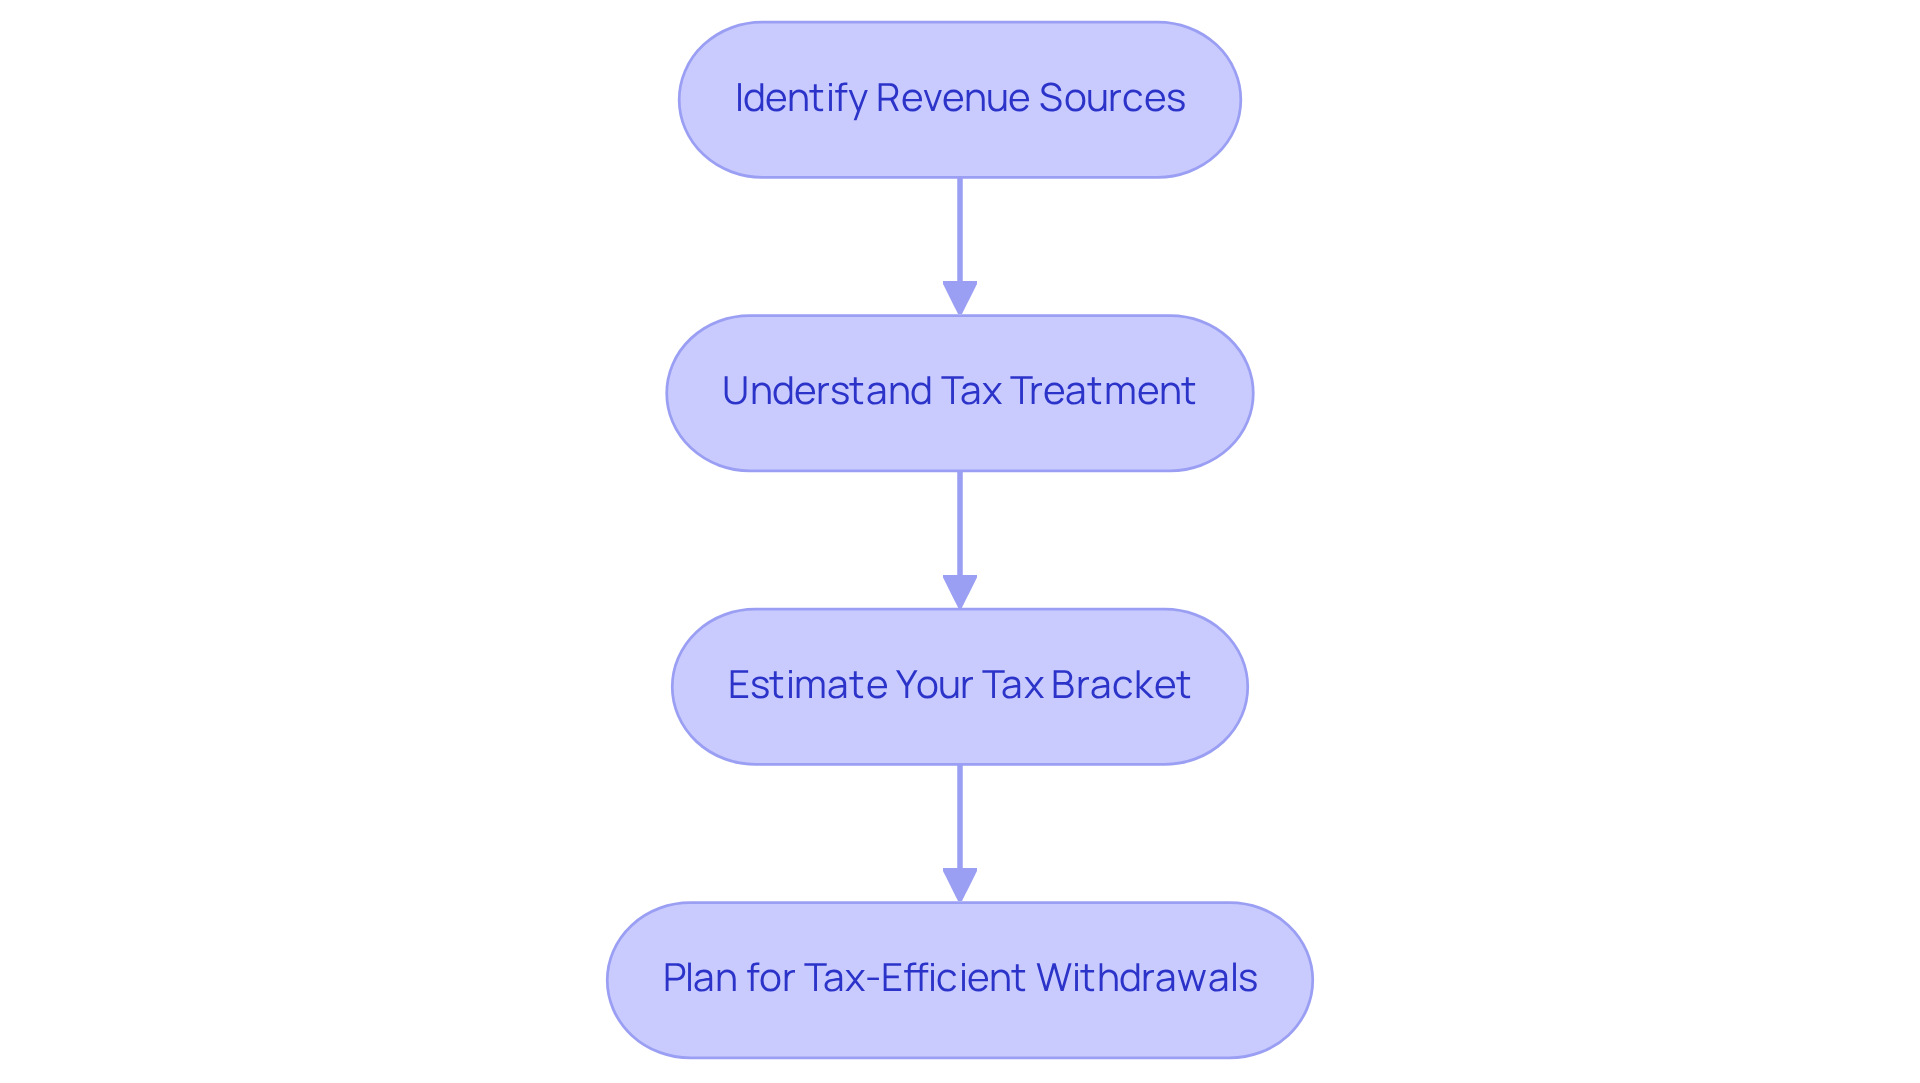
To effectively assess the tax implications of your retirement income, let’s explore some important steps together:
-
Identify Revenue Sources: Begin by determining where your post-employment funds will come from. This includes Social Security, pensions, savings accounts like 401(k) and IRA, as well as investments. Understanding these sources is crucial for your financial planning.
-
Understand Tax Treatment: It’s essential to recognize that different income sources are taxed in various ways:
- Social Security: Depending on your total income, up to 85% of your Social Security benefits may be taxable. In 2025, the average pension benefit is approximately $24,000. Fortunately, 88% of seniors receiving Social Security will pay no tax on their benefits, which could significantly impact your tax situation.
- 401(k) and Traditional IRA Withdrawals: Remember, these withdrawals are taxed as regular earnings, which can elevate your tax bracket.
- Roth IRA Withdrawals: On a positive note, qualified withdrawals from Roth IRAs are tax-free, offering a strategic advantage in your financial planning.
-
Estimate Your Tax Bracket: Imagine if you could utilize your anticipated earnings to forecast your tax bracket in retirement. This estimation will help you understand how much of your earnings will be subject to taxation. For 2025, marginal tax rates consist of 10% for earnings up to $11,925, 12% for earnings exceeding that amount, and higher rates for greater earnings.
-
Plan for Tax-Efficient Withdrawals: It’s important to implement strategies to minimize taxes. Consider prioritizing withdrawals from taxable accounts first or converting traditional IRAs to Roth IRAs. As Mariaca Wealth Management suggests, “Roth conversions can assist you in avoiding unnecessary taxes on your pension earnings.” This can help lessen future tax burdens and improve your overall economic outcome.
By thoroughly assessing your tax circumstances, you can enhance your income during your later years and keep more of your hard-earned resources. Remember, we’re here for you, ensuring a more secure financial future for you and your family.
Explore Strategies to Enhance Your Retirement Savings
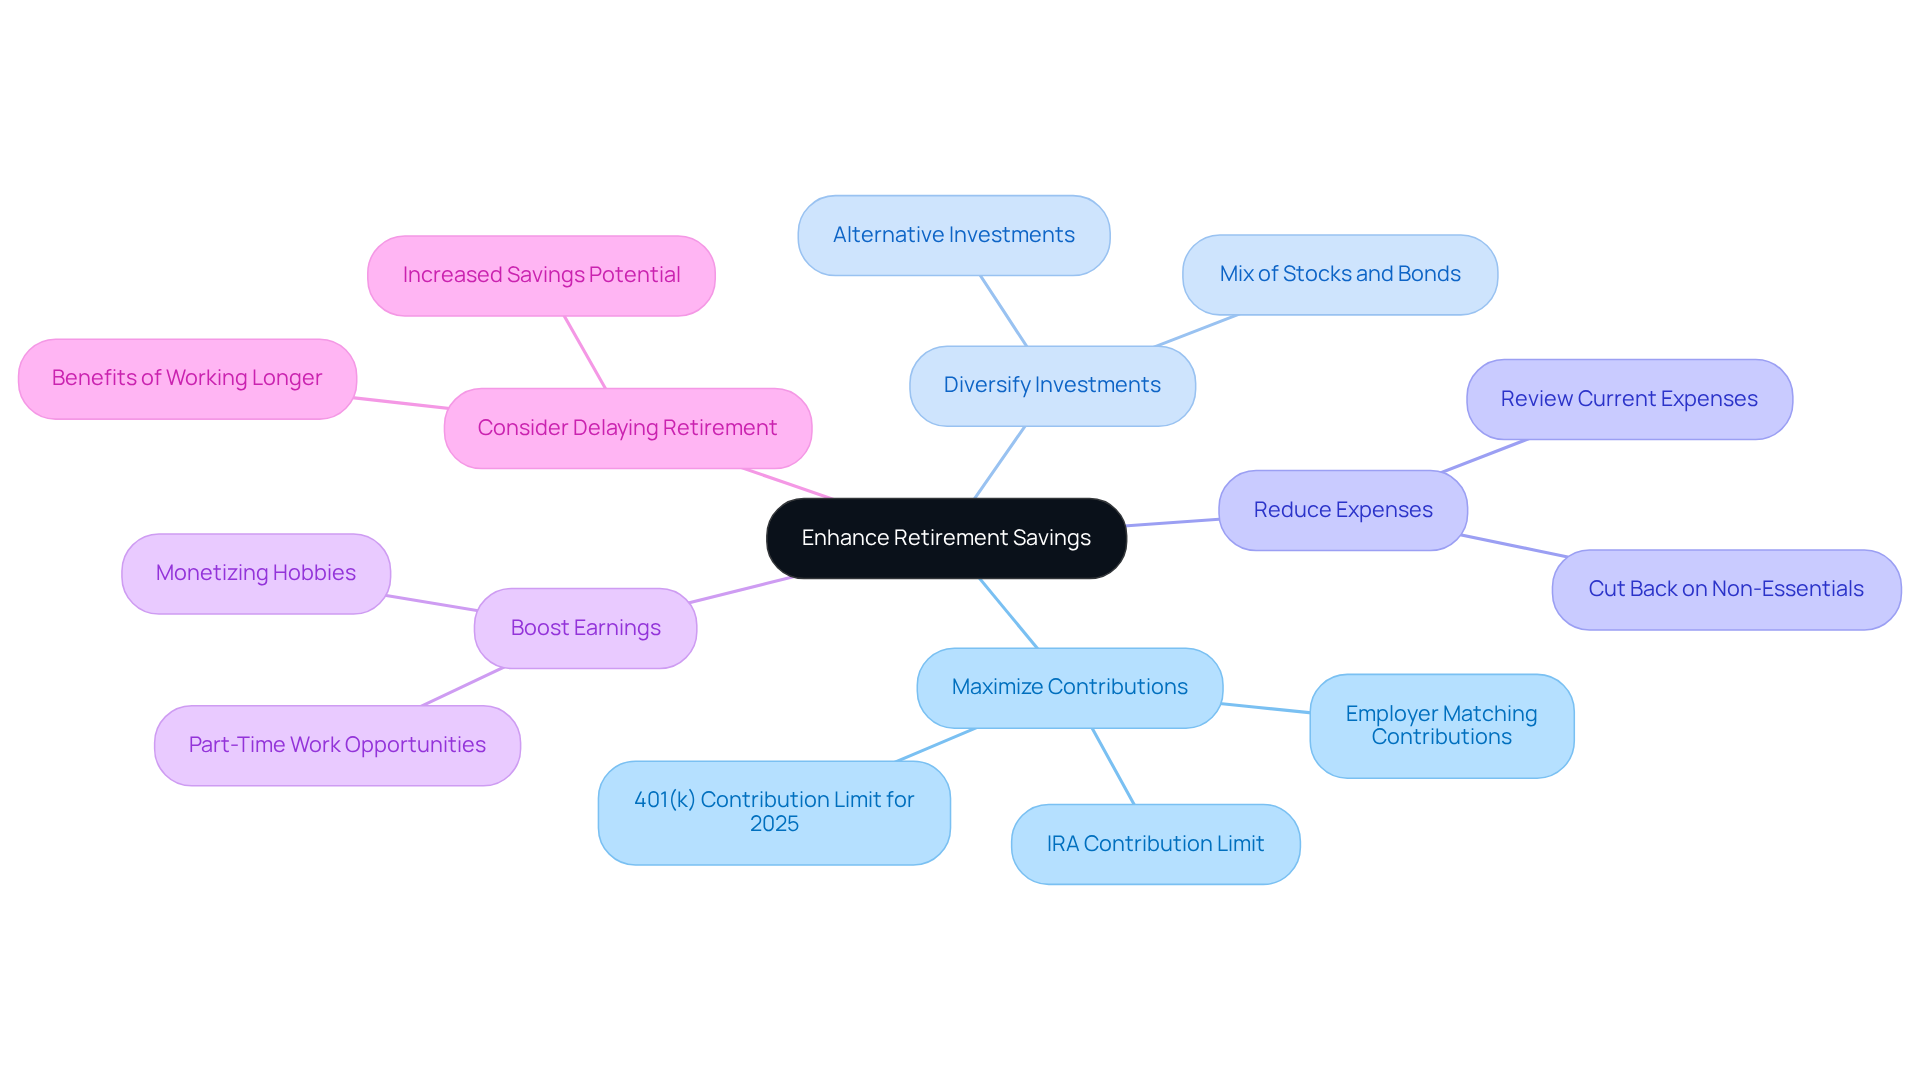
Enhancing your retirement savings is an important step towards securing your family’s future. Here are some thoughtful strategies to consider:
-
Maximize Contributions: Aim to contribute the maximum allowable amounts to your savings accounts, like 401(k)s and IRAs. For 2025, the contribution limit for 401(k)s is set at $23,500, with a combined employee and employer contribution limit of $70,000. Remember to take full advantage of employer matches, which typically range from 50 cents to $1 for each dollar contributed, often capped at 6% of your total pay.
-
Diversify Investments: Imagine if your investment portfolio was well-diversified. A mix of stocks, bonds, and alternative investments can help balance risk and return, allowing you to optimize growth potential while nurturing your family’s financial future.
-
Reduce Expenses: It’s important to understand your current expenses. Conduct a thorough review to identify areas where you can cut back. Diverting these funds into your pension accounts can strengthen your financial foundation.
-
Boost Earnings: Consider exploring opportunities for additional earnings through part-time work, freelancing, or monetizing hobbies. This extra income can significantly enhance your future funds, providing more security for your loved ones.
-
Consider Delaying Retirement: If feasible, think about working a few extra years. This approach not only boosts your reserves but also reduces the time you’ll need to rely on your savings, enhancing your overall economic stability.
By implementing these strategies, you can take meaningful steps to enhance your retirement savings and improve your family’s financial security for the future. Remember, we’re here for you on this journey, and together, we can navigate these important decisions.
Conclusion
Determining whether $2 million is enough for retirement at 50 requires a thoughtful approach that considers your personal lifestyle goals, living expenses, healthcare needs, and family dynamics. This journey involves understanding both your current and future financial needs, ensuring that your retirement plans resonate with your aspirations and the economic realities you face.
It’s crucial to assess your living expenses, estimate annual withdrawals using the 4% rule, and factor in investment returns and inflation. Additionally, being aware of tax implications on your retirement income and exploring ways to boost your savings are essential for securing a stable financial future. Each of these components plays a vital role in crafting a comprehensive retirement plan that can ease financial worries and foster peace of mind.
Ultimately, the path to financial independence at 50 is not just about achieving a monetary goal; it’s about creating a well-rounded strategy that aligns with your personal values and ensures your financial security. By actively engaging in retirement planning and seeking expert guidance, you can navigate the complexities of your financial landscape and work towards a fulfilling retirement that meets your unique needs. Remember, together, we can navigate this journey to a brighter future.
Frequently Asked Questions
How should I start evaluating my retirement needs and goals?
Begin by assessing your current lifestyle and envisioning your ideal post-career life. Consider factors such as living expenses, desired lifestyle activities, healthcare needs, and family considerations.
What factors should I consider when estimating my living expenses for retirement?
Estimate your monthly expenses, including housing, food, healthcare, and leisure activities. Use your current budget as a baseline and adjust for inflation to ensure accuracy in your projections.
Why is it important to consider my desired lifestyle in retirement?
Imagining how you want to spend your time in retirement helps you understand potential costs associated with activities like traveling, pursuing hobbies, or volunteering, which should be included in your budgeting.
How much should I plan for healthcare expenses in retirement?
Recent data suggests that a married couple retiring in 2023 may need approximately $351,000 to cover healthcare costs. It’s essential to explore options like long-term care insurance or health expense accounts (HSAs) to prepare for these expenses.
What family considerations should I keep in mind when planning for retirement?
If you have children, think about their future educational needs and how you might support them financially, such as saving for college. This can significantly impact your future budget.
How can financial advisors assist in retirement planning?
Financial advisors can help you develop a comprehensive strategy that aligns with your future objectives and related expenses, ensuring both economic security and preparedness for educational needs.
Why is it important to start planning for retirement early?
Starting early allows for a more precise economic plan that aligns with your dreams, making the transition into retirement more rewarding. Planning for the future is highly individual, and early preparation can lead to better outcomes.
List of Sources
- Evaluate Your Retirement Needs and Goals
- 35 Retirement Quotes for a Happy, Healthy, and Wealthy Life (https://ruleoneinvesting.com/blog/personal-development/retirement-quotes)
- The Best Quotes About Retirement (https://retirable.com/advice/lifestyle/best-retirement-quotes)
- Points to Consider as You Approach Retirement – Barnum Financial Group (https://barnumfinancialgroup.com/10-years-and-counting-points-to-consider-as-you-approach-retirement)
- Americans Believe They Will Need $1.26 Million to Retire Comfortably According to Northwestern Mutual 2025 Planning & Progress Study (https://news.northwesternmutual.com/2025-04-14-Americans-Believe-They-Will-Need-1-26-Million-to-Retire-Comfortably-According-to-Northwestern-Mutual-2025-Planning-Progress-Study)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- Calculate the Longevity of $2 Million in Retirement
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- The 4% Rule: How Much Can You Spend in Retirement? (https://schwab.com/learn/story/beyond-4-rule-how-much-can-you-spend-retirement)
- How Long $2 Million Will Last In Retirement (https://mywealthtrace.com/blog/how-long-will-2-million-dollars-last-in-retirement)
- How Long Will 2 Million Last in Retirement? – Gold Investing 4u (https://goldinvesting4u.com/how-long-will-2-million-last-in-retirement)
- Assess Retirement Income Taxes on $2 Million
- IRS releases tax inflation adjustments for tax year 2025 | Internal Revenue Service (https://irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2025)
- Is Social Security Income Taxable? How to Calculate Taxes (https://ml.com/articles/taxes-and-your-social-security.html)
- Case Study: Retirees – Mariaca Wealth Management (https://mariacawealth.com/case_studies/retirees)
- No Tax on Social Security is a Reality in the One Big Beautiful Bill (https://whitehouse.gov/articles/2025/07/no-tax-on-social-security-is-a-reality-in-the-one-big-beautiful-bill)
- 14 Must-Know Retirement Stats For 2025 – Carry (https://carry.com/learn/retirement-stats)
- Explore Strategies to Enhance Your Retirement Savings
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- 401(k) contribution limits 2023, 2024, and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/401k-contribution-limits)
- 401(k) limit increases to $23,500 for 2025, IRA limit remains $7,000 | Internal Revenue Service (https://irs.gov/newsroom/401k-limit-increases-to-23500-for-2025-ira-limit-remains-7000)
- 13 Quotes to Help Plan for Retirement | The Motley Fool (https://fool.com/retirement/2020/06/25/13-quotes-to-help-plan-for-retirement.aspx)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading