

Key Highlights:
- A $2 million retirement fund is often considered a benchmark for a comfortable lifestyle post-retirement.
- Retirees typically have annual expenses around $49,000, but this varies based on personal needs and location.
- Using the 4% rule, a $2 million fund allows for annual withdrawals of about $80,000, supplemented by Social Security for a total monthly income of around $8,500.
- Factors like cost of living, healthcare expenses, and inflation significantly influence the sufficiency of retirement savings.
- Diversifying investments and employing a sustainable withdrawal strategy are key to maximising a retirement portfolio.
- The risk of outliving savings is a major concern, especially as life expectancy increases.
- Unexpected healthcare costs can average $172,500 over retirement, underscoring the need for careful financial planning.
- Proactive management of finances and seeking professional financial advice can help navigate retirement challenges.
Introduction
Imagine retiring with $2 million at 65. It sounds appealing, doesn’t it? But it also raises important questions about your financial security and lifestyle choices as you age. For many young parents, this figure could be the key to a comfortable retirement. Yet, its sufficiency depends on various factors like where you live, healthcare costs, and how you manage your spending habits.
As life expectancy continues to rise and economic uncertainties linger, it’s crucial to think about how to make your savings last throughout your retirement. Picture this: you’ve worked hard, saved diligently, and now you want to ensure that your family can enjoy the fruits of your labor without worry. Exploring the intricacies of financial planning and investment strategies is essential to navigate this complex landscape.
Together, we can uncover the best paths to secure a fulfilling future for you and your loved ones. We’re here for you, ready to support you in making informed decisions that align with your family values and goals. Let’s embark on this journey together, ensuring that your retirement dreams become a reality.
Defining Retirement with $2 Million: What It Means
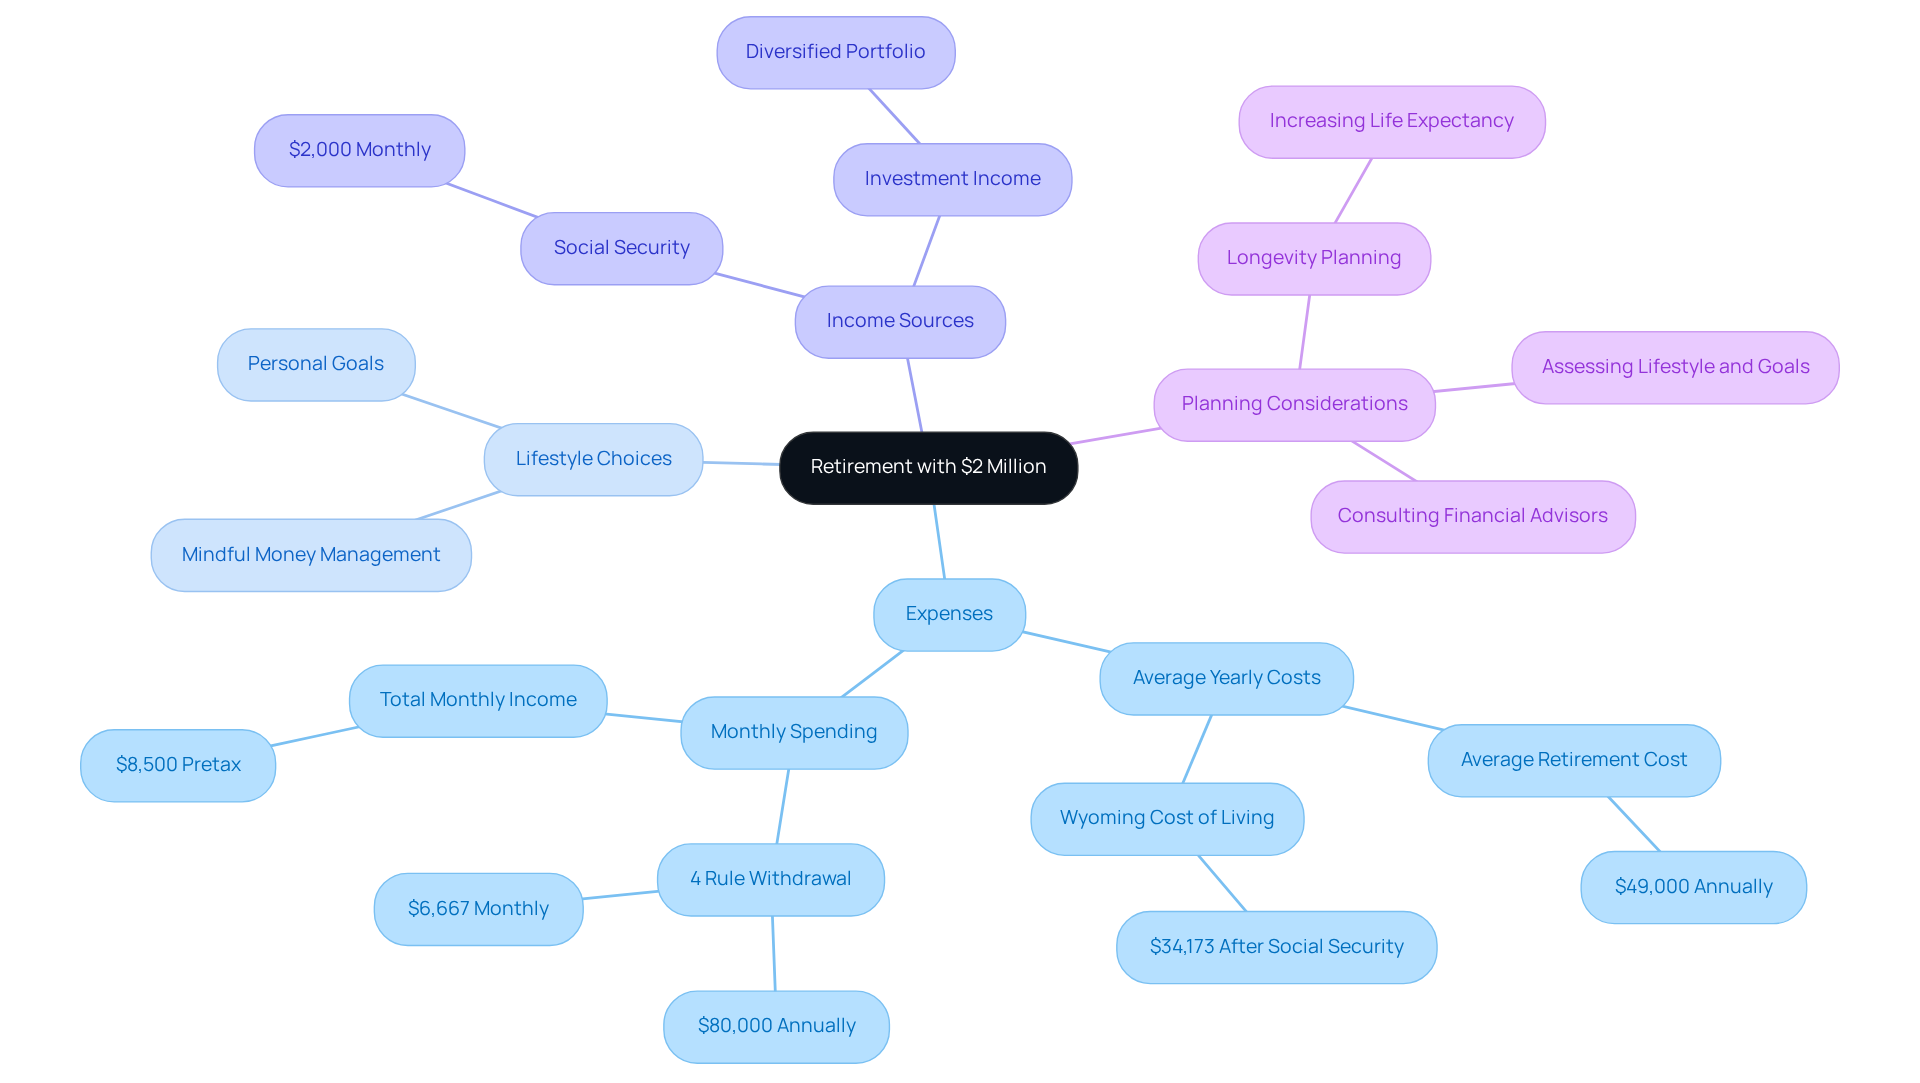
The question of whether $2 million is enough to retire at 65 highlights a significant shift from full-time work to relying on savings and investments for living expenses. This amount is often seen as a benchmark for enjoying a comfortable lifestyle after leaving the workforce, covering everything from discretionary spending to healthcare costs and even travel. But how sufficient is the amount when considering if $2 million is enough to retire at 65? It really depends on your unique situation-your lifestyle choices, where you live, and any additional income sources like Social Security all play a role.
On average, retirees find their expenses hover around $49,000 each year, but this can vary widely based on personal needs and preferences. For example, in Wyoming, the annual cost of living is about $34,173 when you factor in Social Security. If we apply the 4% rule, a $2 million savings fund allows for yearly withdrawals of around $80,000, which breaks down to about $6,667 each month. When you add in an of $2,000, retirees can expect a total monthly income of roughly $8,500 before taxes. This can comfortably cover basic living expenses and lifestyle choices.
The implications of having $2 million for your later years go beyond just numbers; they encompass lifestyle choices that can significantly impact your financial readiness. For young parents, this amount can pave the way for a secure future, especially if you practice mindful money management. Real-life stories show that while some may wonder if $2 million is enough to retire at 65, it can support a comfortable lifestyle, but your spending habits and additional income sources are crucial in shaping your overall financial security.
Ultimately, understanding the intricacies of planning for your later years with $2 million calls for a personalized approach. It’s essential to consider your goals, lifestyle expectations, and the possibility of a longer life. As life expectancy continues to rise, planning for an extended period of leisure becomes increasingly vital. Together, we can navigate this journey, ensuring that you evaluate your financial situation and prepare for a fulfilling future.
Contextual Factors Influencing Retirement Adequacy
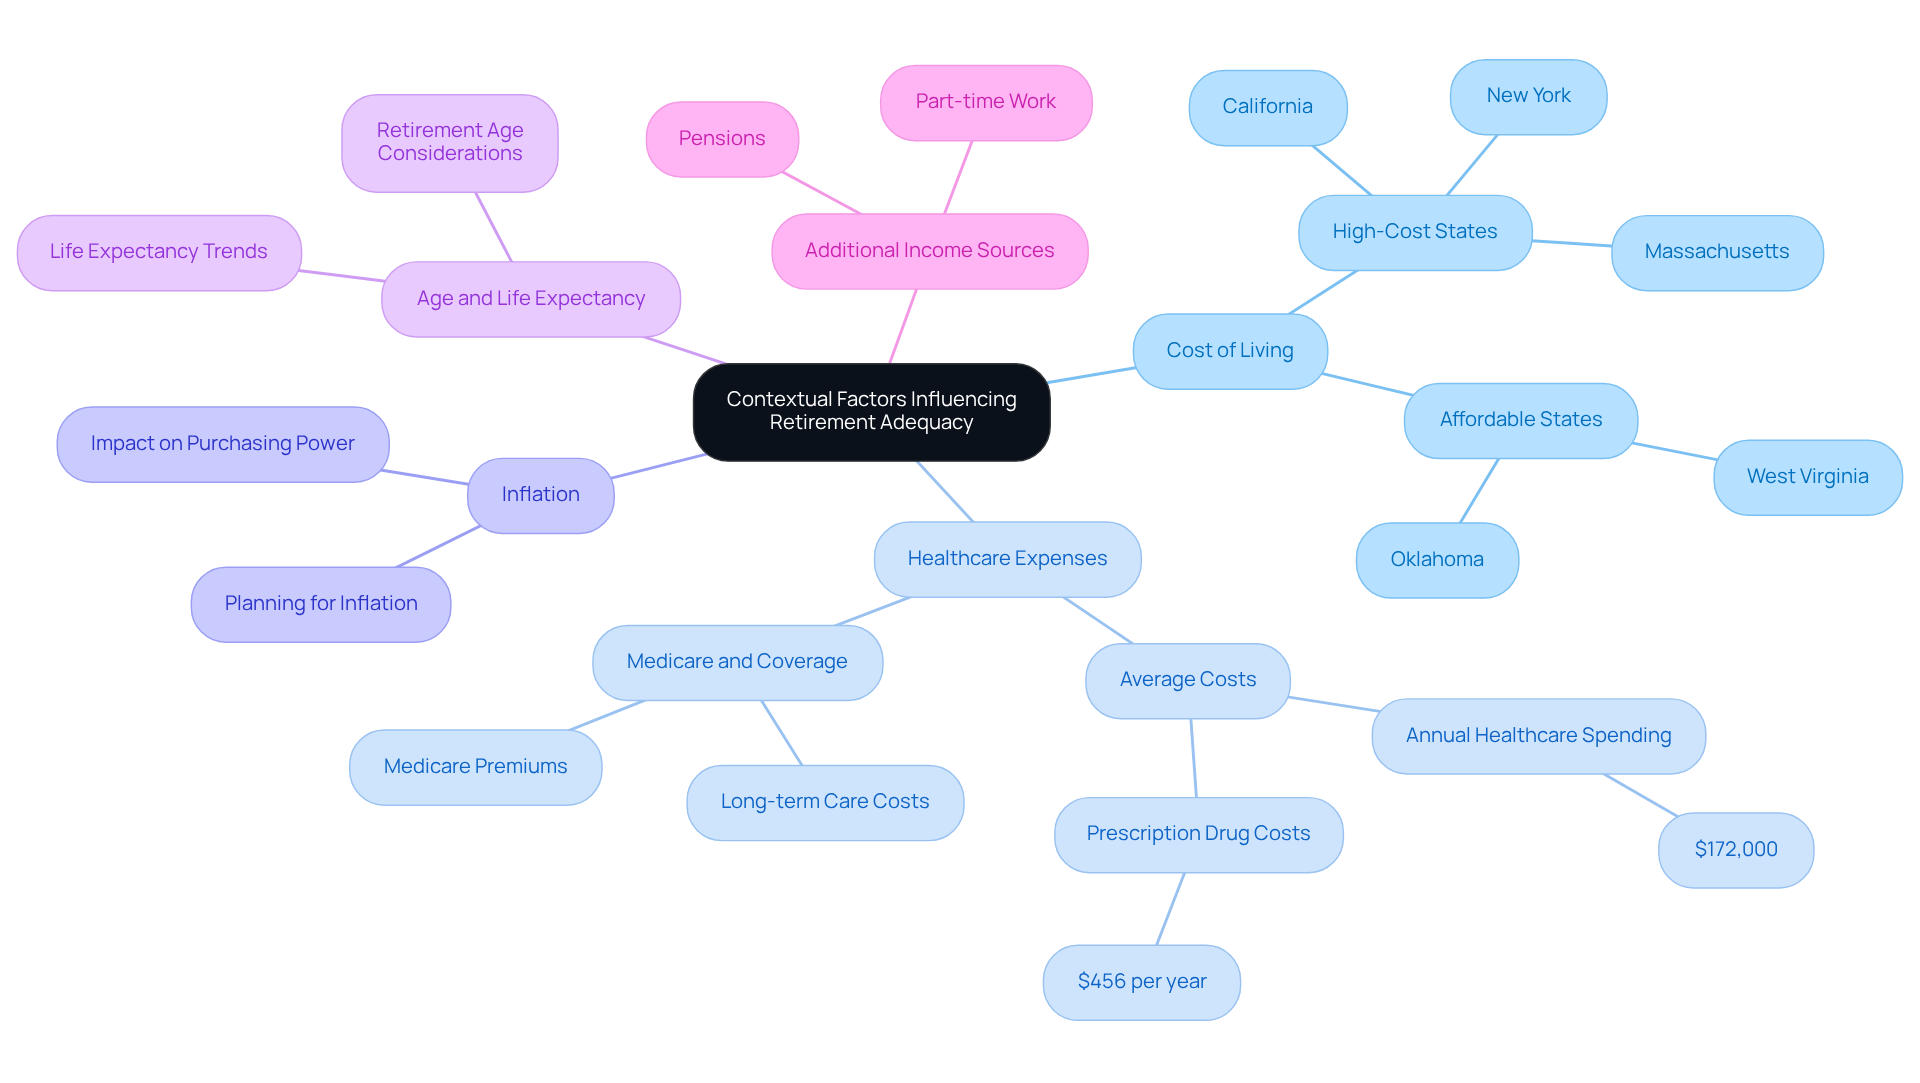
When , several important factors can help determine if 2 million is enough to retire at 65 and how far a $2 million portfolio will stretch. Imagine living in a bustling city like California or New York, where the cost of living can be quite high. You might find that your savings don’t go as far as they would in more affordable areas. It’s crucial to think about where you want to settle down and how that choice impacts your financial future.
Healthcare expenses are another key consideration. As we age, these costs can add up, so it’s wise to anticipate what you might need. Planning for these expenses can help ensure that your funds last throughout your later years, allowing you to focus on what truly matters – your family and well-being.
Inflation is also a factor that can quietly chip away at your purchasing power over time. It’s important to understand how this can affect your retirement savings. By being proactive and planning carefully, you can safeguard your financial future.
Additionally, think about your age and life expectancy. These elements play a significant role in how you should approach your retirement planning. If you have other income sources, like pensions or part-time work, these can provide a helpful boost to your savings, giving you more flexibility and peace of mind.
Remember, you’re not alone in this journey. Together, we can navigate the complexities of financial planning, ensuring that you and your family are well-prepared for the years ahead. We’re here for you, ready to support you every step of the way.
Strategies for Maximizing a $2 Million Retirement Portfolio
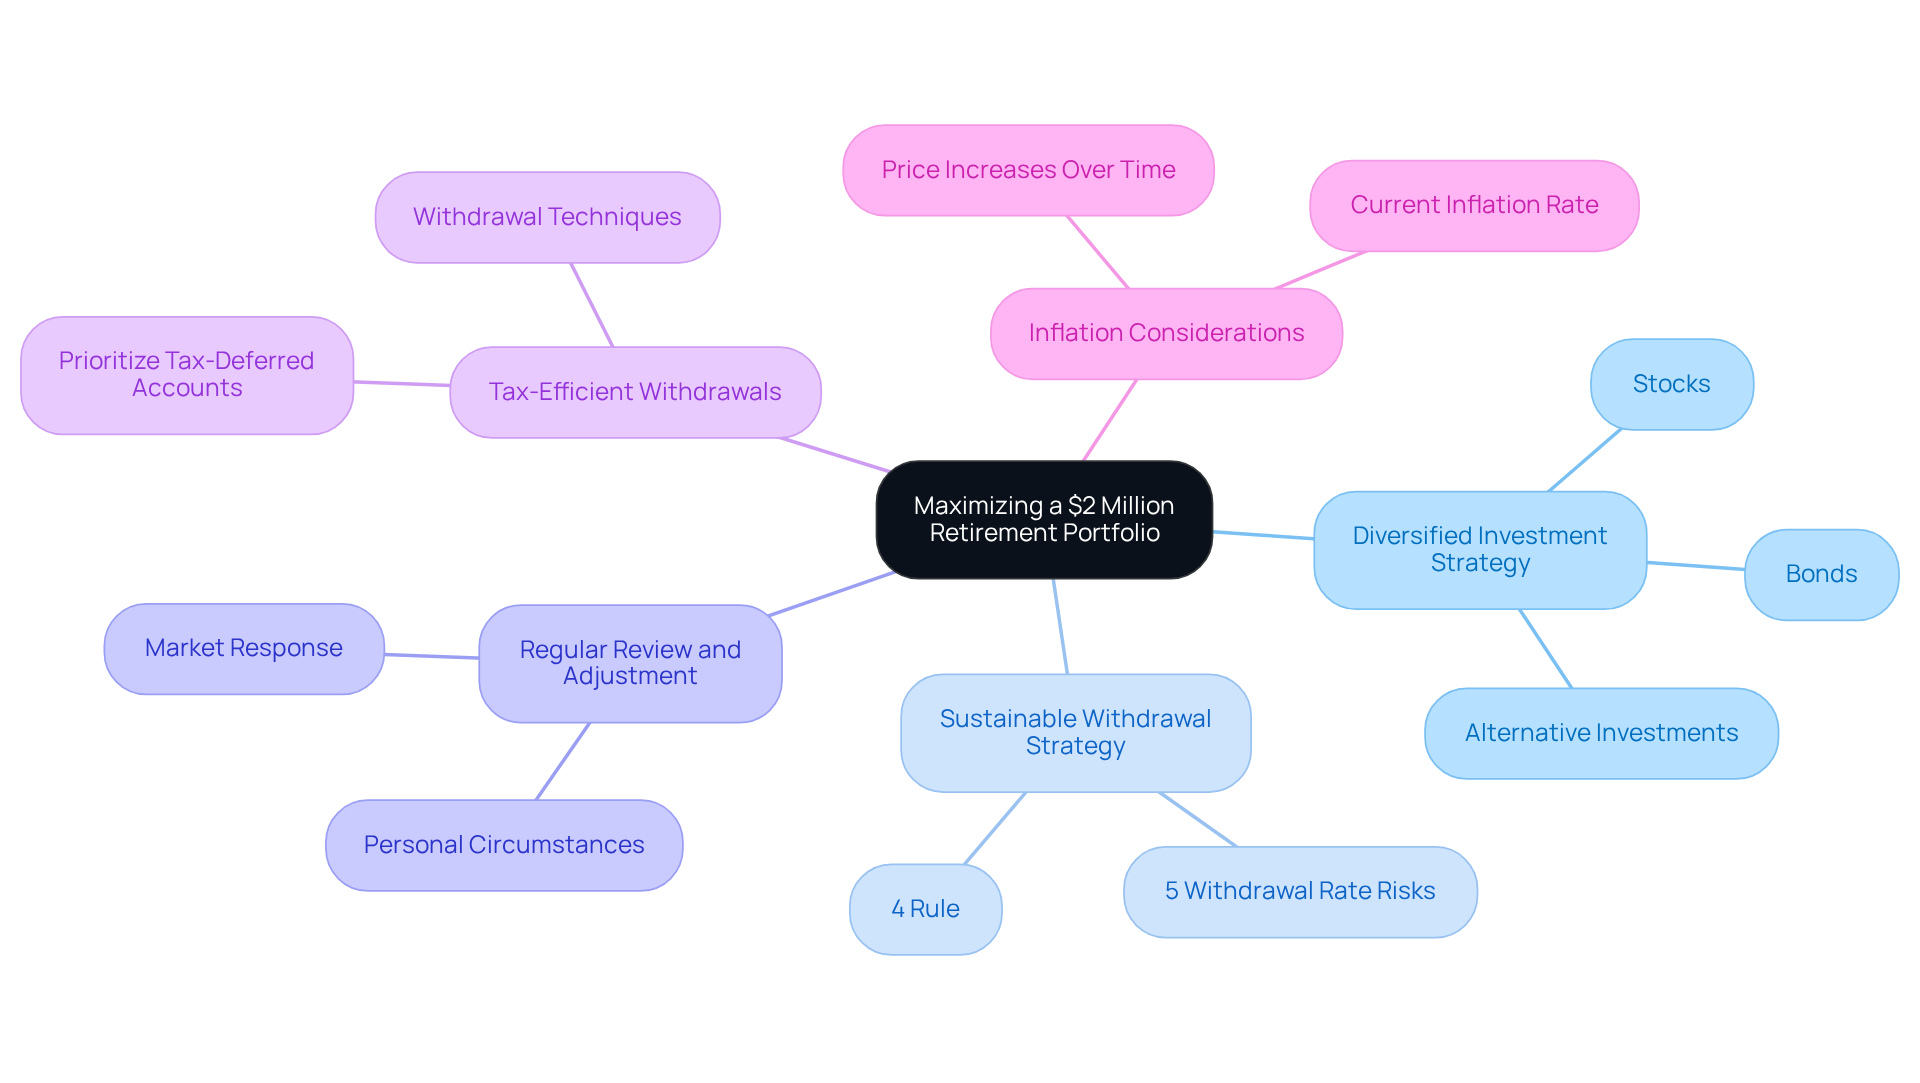
Imagine having a $2 million retirement portfolio while wondering if 2 million is 2 million enough to retire at 65 for you and your family. To make the most of it, consider adopting a diversified investment strategy that balances risk and return. At Bright Advisers, we understand how important it is to create hyper-personalized investment portfolios. By leveraging advanced technology, we can help you craft strategies that align perfectly with your unique financial goals.
Think about it: a well-rounded mix of stocks, bonds, and alternative investments can be tailored to fit your risk tolerance and income needs. This way, you can feel secure knowing your investments are working hard for you. Plus, implementing a sustainable withdrawal strategy – often guided by the 4% rule – can help ensure that your funds remain accessible throughout your later years. Just keep in mind that a 5% withdrawal rate might increase the chances of running out of money sooner.
Regularly reviewing and adjusting your investment allocations in response to market changes and personal circumstances is crucial for maintaining your financial health. And don’t forget about tax-efficient withdrawal techniques! Prioritizing withdrawals from tax-deferred accounts can significantly enhance the longevity of your savings.
With and prices today being 25% higher than they were just four years ago, it’s essential to factor these elements into your planning. Economic expert Joyce Rojas reassures us that having a solid financial plan in place can answer the question of whether is 2 million enough to retire at 65 for a comfortable retirement. Together, we can navigate this journey and ensure your family’s future is secure.
Challenges and Considerations for Retiring with $2 Million
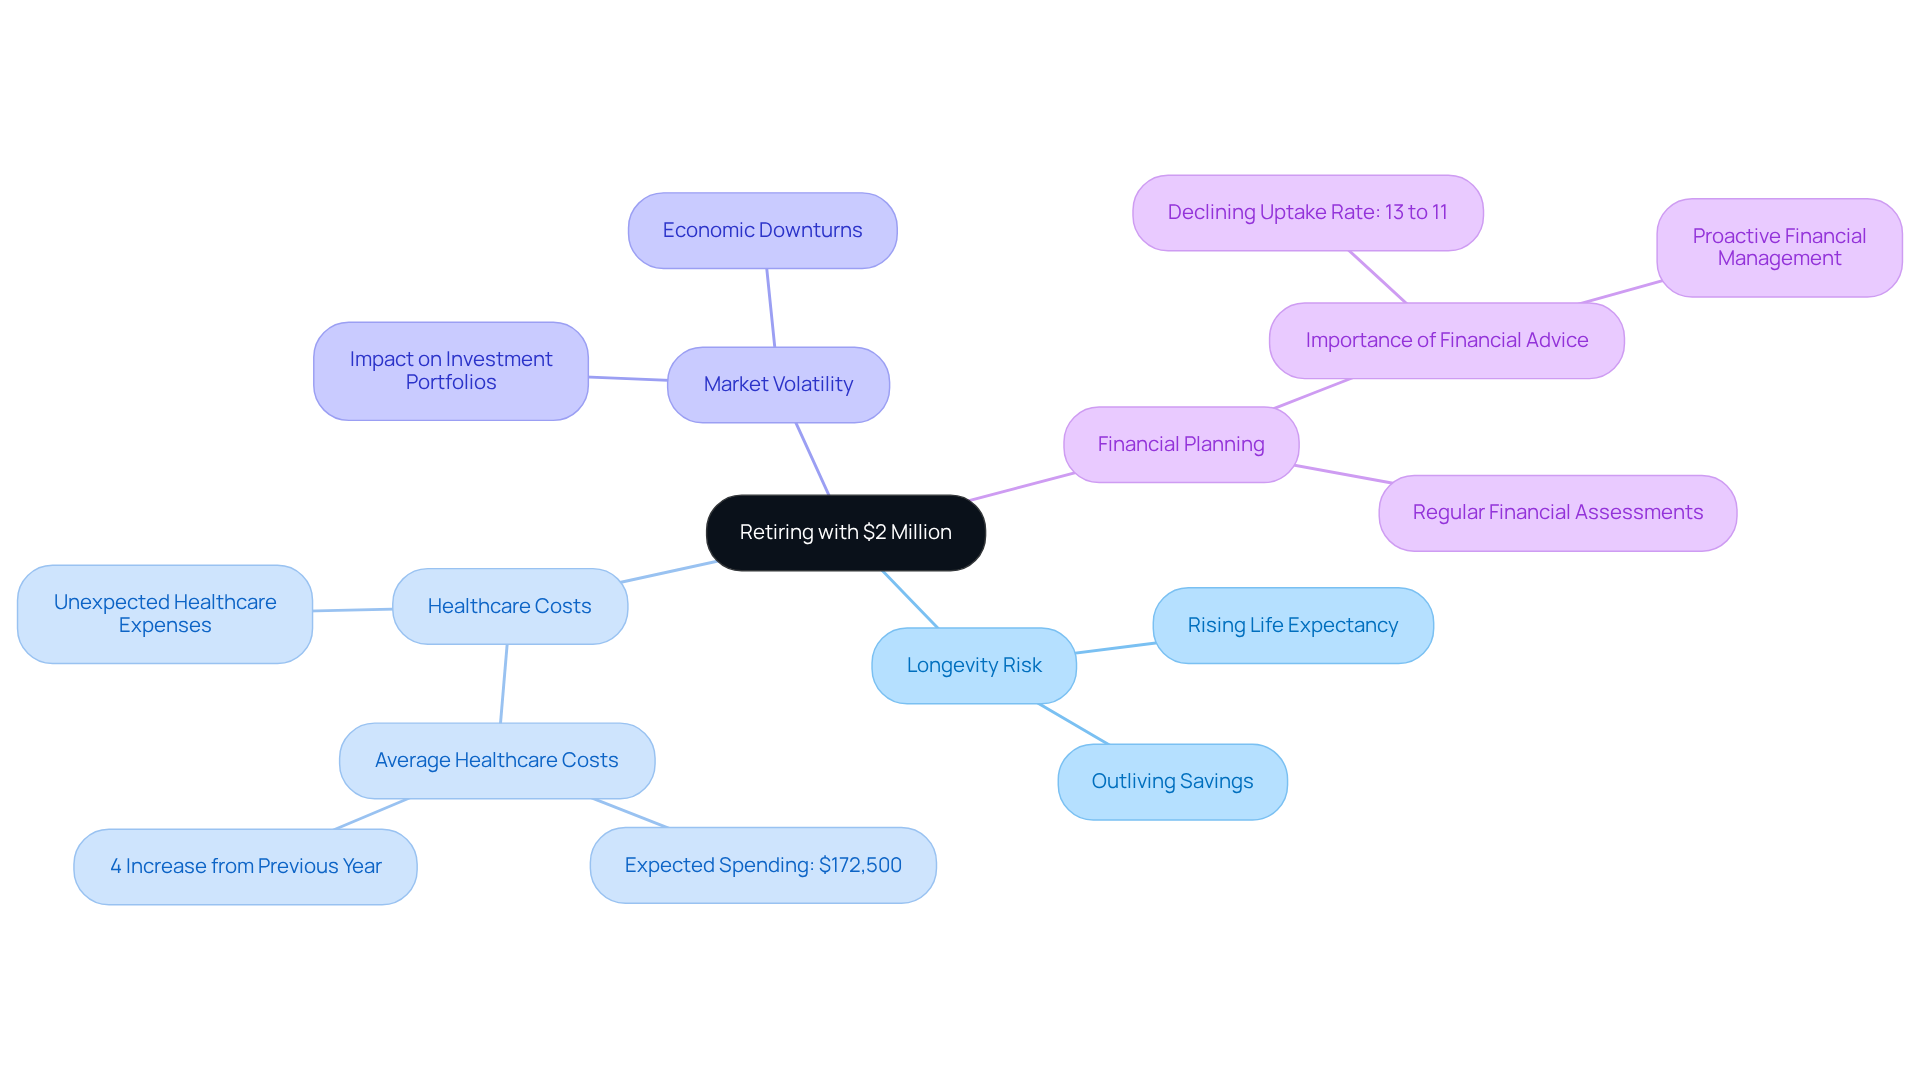
It’s completely normal to have concerns about your financial future, especially when wondering if 2 million is enough to retire at 65. One of the biggest worries is the risk of outliving your savings, especially as life expectancy keeps rising. Many retirees underestimate how long their funds will last, which raises the question of whether 2 million is enough to retire at 65, and it’s no surprise that a significant number express anxiety about their financial stability. From 2020 to 2023, the reality of exhausting resources has become all too clear for many in retirement, highlighting the importance of careful planning.
Unexpected healthcare costs can add to this stress. On average, retirees can expect to spend around $172,500 on healthcare throughout their retirement – a figure that has increased by 4% from the previous year. Market volatility is another concern; economic downturns can impact investment portfolios, leading to potential losses. Plus, if you’ve stopped working, it’s crucial to be mindful of your spending habits. Excessive withdrawals can quickly drain your savings, leaving you in a tough spot.
But don’t worry – proactive financial planning can help you navigate these challenges, including the question of whether 2 million is enough to retire at 65. Working with financial planners can provide effectively. They can help you regularly assess your financial situation and adapt to changing circumstances. It’s worth noting that the overall uptake rate for financial advice has dropped from 13% to 11% over the past four years, underscoring the importance of seeking guidance in these complex times.
Additionally, Fidelity’s Q3 2025 Retirement Analysis shows that retirement account balances are on the rise, with more young savers showing interest in Roth savings vehicles. This trend offers hope and context for those planning their financial futures. Remember, you’re not alone in this journey. Together, we can navigate these challenges and work towards a secure financial future for you and your family.
Conclusion
Retiring with $2 million at the age of 65 brings up important questions about your financial readiness and how to sustain your lifestyle. While this amount can provide a comfortable retirement, whether it’s enough really depends on your unique situation – think living expenses, healthcare needs, and other income sources. For young parents planning for the future, understanding these factors is key to ensuring your family’s financial security.
Let’s explore some key considerations that can help you determine if $2 million is sufficient for retirement:
- Personalized financial planning is crucial.
- You’ll want to consider the cost of living in your area, healthcare expenses, and how inflation might affect your savings.
- Adopting a diversified investment strategy and keeping a sustainable withdrawal rate can really help stretch your retirement savings.
- By being proactive and regularly reviewing your financial plans, you can face the uncertainties of the future with more confidence.
Ultimately, the journey toward a secure retirement is a shared effort that calls for thoughtful planning and informed decision-making. As life expectancy rises and economic conditions change, it’s vital to continually assess your financial strategies. Young parents, it’s time to take charge of your financial futures! Leverage the resources and professional guidance available to ensure your retirement dreams are not just achievable but sustainable. Embracing a proactive approach today can set the stage for a fulfilling and secure tomorrow.
Imagine if you could navigate this journey with confidence, knowing you have a solid plan in place. Together, we can make your retirement dreams a reality.
Frequently Asked Questions
Is $2 million enough to retire at 65?
Whether $2 million is enough to retire at 65 depends on individual circumstances, including lifestyle choices, location, and additional income sources like Social Security.
What are the average expenses for retirees?
On average, retirees find their expenses hover around $49,000 each year, although this can vary widely based on personal needs and preferences.
How does the cost of living affect retirement savings?
The cost of living varies by location; for example, in Wyoming, the annual cost of living is about $34,173 when factoring in Social Security.
What is the 4% rule in retirement planning?
The 4% rule suggests that retirees can withdraw about 4% of their savings each year. For a $2 million savings fund, this allows for yearly withdrawals of around $80,000.
How much total monthly income can retirees expect with $2 million and Social Security?
With a $2 million savings fund allowing for monthly withdrawals of about $6,667 and an average Social Security income of $2,000, retirees can expect a total monthly income of roughly $8,500 before taxes.
What factors impact financial readiness for retirement?
Financial readiness for retirement is influenced by lifestyle choices, spending habits, and additional income sources, which are crucial in shaping overall financial security.
Why is it important to personalize retirement planning?
Personalized retirement planning is essential to consider individual goals, lifestyle expectations, and the possibility of a longer life, especially as life expectancy continues to rise.
List of Sources
- Defining Retirement with $2 Million: What It Means
- Can a Couple Retire With $2 Million? (https://northwesternmutual.com/life-and-money/can-a-couple-retire-with-2-million)
- How long $2 million in retirement savings lasts in every U.S. state (https://cnbc.com/2025/04/19/how-long-2-million-dollars-in-retirement-savings-lasts-in-every-state.html)
- What $2 Million in Retirement Savings Looks Like in Monthly Spending (https://nasdaq.com/articles/what-2-million-retirement-savings-looks-monthly-spending)
- Is $2 Million Enough For a Comfortable Retirement? Experts Weigh In (https://investopedia.com/is-2-million-dollars-enough-for-a-comfortable-retirement-experts-weigh-in-11798968)
- What Percentage of Retirees Have $2 Million? (https://smartasset.com/retirement/what-percentage-of-retirees-have-2-million-dollars)
- Contextual Factors Influencing Retirement Adequacy
- Medicare Guidance Simplified | Chapter (https://askchapter.org/magazine/senior-health-wellness/budgeting-financial-wellness/cost-of-healthcare-in-retirement)
- Here’s How Much Retirees May Need for Healthcare Costs (https://napa-net.org/news/2024/7/heres-how-much-retirees-may-need-healthcare-costs)
- Mapped: Annual Retirement Costs by State (https://visualcapitalist.com/mapped-annual-retirement-costs-by-state)
- Fidelity Investments® Releases 2025 Retiree Health Care Cost Estimate, a Timely Reminder for All Generations to Begin Planning (https://newsroom.fidelity.com/pressreleases/fidelity-investments–releases-2025-retiree-health-care-cost-estimate–a-timely-reminder-for-all-gen/s/3c62e988-12e2-4dc8-afb4-f44b06c6d52e)
- Strategies for Maximizing a $2 Million Retirement Portfolio
- Is $2 Million Enough For a Comfortable Retirement? Experts Weigh In (https://investopedia.com/is-2-million-dollars-enough-for-a-comfortable-retirement-experts-weigh-in-11798968)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- How Many People Actually Retire with 2 Million Dollars? (https://fuchsfinancial.com/retire-with-2-million)
- What Percentage of Retirees Have $2 Million? (https://smartasset.com/retirement/what-percentage-of-retirees-have-2-million-dollars)
- Retirement: What $250K vs. $500K vs. $1M vs. $2M in Savings Looks Like in Yearly Spending (https://nasdaq.com/articles/retirement-what-250k-vs-500k-vs-1m-vs-2m-savings-looks-yearly-spending)
- Challenges and Considerations for Retiring with $2 Million
- Living longer but falling short: Retirees risk outliving savings by underestimating life expectancy (https://aviva.com/newsroom/news-releases/2025/11/living-longer-but-falling-short-retirees-risk-outliving-savings-by-underestimating-life-expectancy)
- Probability of outliving savings in the U.S. 2023| Statista (https://statista.com/statistics/945541/probability-that-retirees-will-outlive-their-savings?srsltid=AfmBOoplwfrUj9K36L735ZVCSYyDC6FA9PffgcAWOAZq-xKywnfADH1F)
- Fidelity Investments® Releases 2025 Retiree Health Care Cost Estimate, a Timely Reminder for All Generations to Begin Planning (https://newsroom.fidelity.com/pressreleases/fidelity-investments–releases-2025-retiree-health-care-cost-estimate–a-timely-reminder-for-all-gen/s/3c62e988-12e2-4dc8-afb4-f44b06c6d52e)
- Millions of Americans Are Falling Behind on Their Retirement Goals (https://pew.org/en/about/news-room/opinion/2024/10/24/millions-of-americans-are-falling-behind-on-their-retirement-goals)
- Outliving Savings: A Growing Risk (https://asppa-net.org/news/2025/5/outliving-savings-a-growing-risk)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading