

Overview
This article delves into an important question for young families: Is a High Deductible Health Plan (HDHP) combined with a Health Savings Account (HSA) a good choice? We understand that navigating healthcare options can feel overwhelming, but this combination might just be the solution you need. With lower premiums and tax advantages, it offers a practical way to manage healthcare costs while also building savings for the future.
Imagine being able to contribute to an account that not only helps cover medical expenses but also allows you to save for future healthcare needs. HSAs provide tax-deductible contributions, and the funds can even be invested, making them a strategic financial tool for your family. This means you can plan for your family’s health while also nurturing your financial well-being.
We’re here for you as you explore these options. Together, we can navigate this journey toward better health and financial security. By considering an HDHP and HSA, you’re taking a proactive step in managing your family’s healthcare costs effectively. Remember, it’s not just about saving money; it’s about ensuring a healthier future for your loved ones.
Key Highlights:
- HDHPs require a minimum deductible of $1,650 for individuals and $3,300 for families in 2025, offering lower premiums but higher out-of-pocket costs.
- HSAs provide tax-deductible contributions and tax-free withdrawals for qualifying medical expenses, enhancing financial management for families.
- Combining HDHPs with HSAs can create a strategic approach to healthcare spending, beneficial for budget-conscious families.
- HSAs can serve as a wealth-building tool through investment options, allowing families to plan for future healthcare needs.
- Employers are increasingly offering HSAs as part of benefits packages, reflecting a trend towards cost-efficient healthcare savings.
- Families must assess their healthcare needs and financial capabilities to determine if an HDHP is suitable for them.
- Common misconceptions include the belief that HDHPs are unsuitable for families due to high out-of-pocket costs, while many cover preventive services at no cost.
- HSAs are beneficial for families across various income levels, providing a way to save for medical expenses and build financial stability.
Introduction
In the ever-evolving landscape of healthcare, young families are increasingly drawn to High Deductible Health Plans (HDHPs) and Health Savings Accounts (HSAs) as strategic financial tools. Imagine if you could manage rising healthcare costs while enjoying lower monthly premiums and significant tax advantages. These options not only promise relief but also resonate with your family’s financial goals.
As you navigate the complexities of medical expenses, it’s important to understand how HDHPs and HSAs work together for effective financial planning. This article delves into the benefits, implications, and common misconceptions surrounding these plans, providing insights that empower you to make informed decisions for your healthcare needs and financial futures.
Together, we can navigate this journey and ensure your family’s well-being.
Define High Deductible Health Plans and Health Savings Accounts
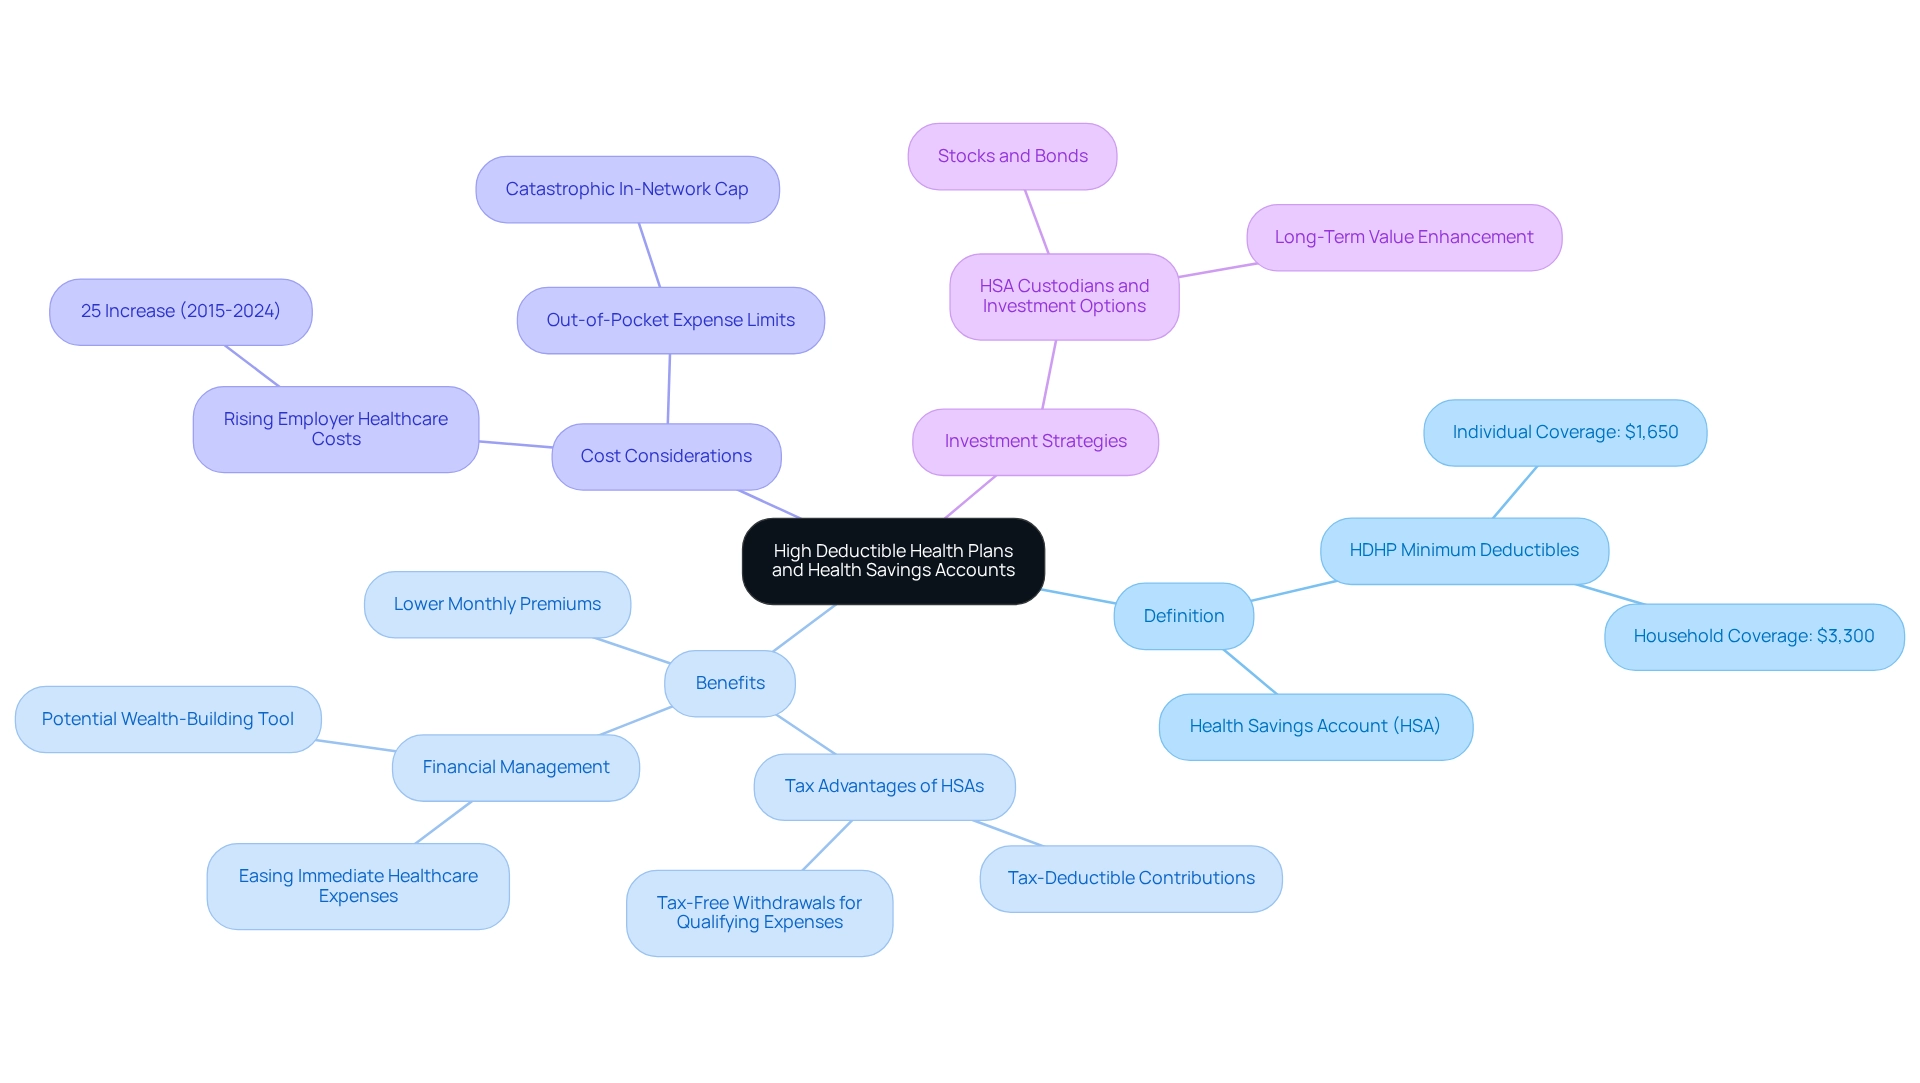
Considering whether a High Deductible Health Plan (HDHP) is a high deductible HSA plan worth it can be a smart choice for families like yours, offering a way to manage healthcare costs effectively. For 2025, an HDHP requires a minimum deductible of $1,650 for individual coverage and $3,300 for household coverage. While these plans come with higher deductibles, they often feature lower monthly premiums, raising the question of whether a high deductible HSA plan is worth it for families looking to ease immediate healthcare expenses. With employer healthcare costs rising by 25% from 2015 to 2024, exploring cost-efficient options like HDHPs becomes essential.
Imagine having a Health Savings Account (HSA) that works alongside your HDHP, providing a tax-advantaged way to save for medical expenses. Contributions to HSAs are tax-deductible, and withdrawals for qualifying expenses are tax-free. This means you can manage healthcare costs more effectively while enjoying significant financial benefits. Since their introduction in 2004, HSAs have gained popularity, with health insurance broker Louise Norris noting that “these accounts have gained traction since their debut in 2004.” This trend shows how families are increasingly using HSAs for better financial management.
When considering if a high deductible HSA plan is worth it, combining HDHPs with HSAs creates a strategic approach to healthcare spending—especially beneficial for young families on a budget. HSAs can serve not only as a savings tool but also as a potential resource for building wealth, thanks to the investment options available through various custodians. This flexibility can enhance the long-term value of your HSA, allowing you to plan for future medical expenses while optimizing your financial resources.
At Bright Advisers, we’re here to help you navigate these options, integrating planning and investment strategies through our innovative wealth management platform. This approach connects your healthcare plan to your investment strategy, ensuring you’re making the most of your resources. Additionally, your out-of-pocket costs for covered medical services are limited to the catastrophic in-network cap, providing you with extra financial protection.
This investment flexibility can transform your HSA into more than just a savings account; it can become a potential wealth-building tool. Together, we can explore how Bright Advisers can assist your family in achieving economic security and independence. For more information, please reach out to us at (714) 987-2967 or hello@brightadvisers.com. Remember, we’re here for you every step of the way.
Explore Benefits of HDHPs and HSAs for Young Families
For young households, considering if a high deductible HSA plan is worth it can provide significant economic advantages. Imagine reducing your monthly premiums with HDHPs—this scenario raises the question of whether a high deductible HSA plan is worth it, as it can enhance your cash flow and allow you to allocate funds toward essential expenses like childcare and education. Furthermore, when considering if a health savings account is a high deductible HSA plan worth it, contributing to it can help you build a financial cushion for future healthcare needs.
When considering the benefits of Health Savings Accounts, one may ask, is a high deductible HSA plan worth it, given the remarkable triple tax benefit: contributions are tax-deductible, the funds grow tax-free, and withdrawals for qualified medical expenses are also tax-free? For families anticipating increased medical costs as their children grow, understanding if this structure is a high deductible HSA plan worth it can lead to substantial savings over time. Additionally, considering whether a high deductible HSA plan is worth it, HSAs can be invested, giving families the opportunity to further increase their savings, making them an invaluable resource for long-term financial planning.
Bright Advisers has successfully supported clients like Emily and Mark, a marketing executive and a software engineer, in enhancing their financial strategies, particularly through the use of health savings accounts. By implementing personalized wealth management strategies, they gained the flexibility to make career choices based on their desired work-life balance while securing their financial future. Data from the KFF 2023 Employer Health Benefits Survey suggest that employers are increasingly recognizing the value of these plans, with many offering health savings accounts as part of their benefits packages. Major technology companies like Google, Facebook, and Apple exemplify this trend, integrating HSAs into their employee benefits and reflecting a broader movement towards valuable healthcare savings options.
As Kate Ashford, a certified senior advisor, emphasizes, “Choose the plan that allows you the best options for getting the medical care you need, when you need it.” This principle resonates deeply with Emily and Mark’s journey. By utilizing these financial resources, young households can effectively manage healthcare expenses while ensuring a secure economic future. Remember, we’re here for you—together, we can navigate this journey.
Analyze Financial Implications of Choosing an HDHP
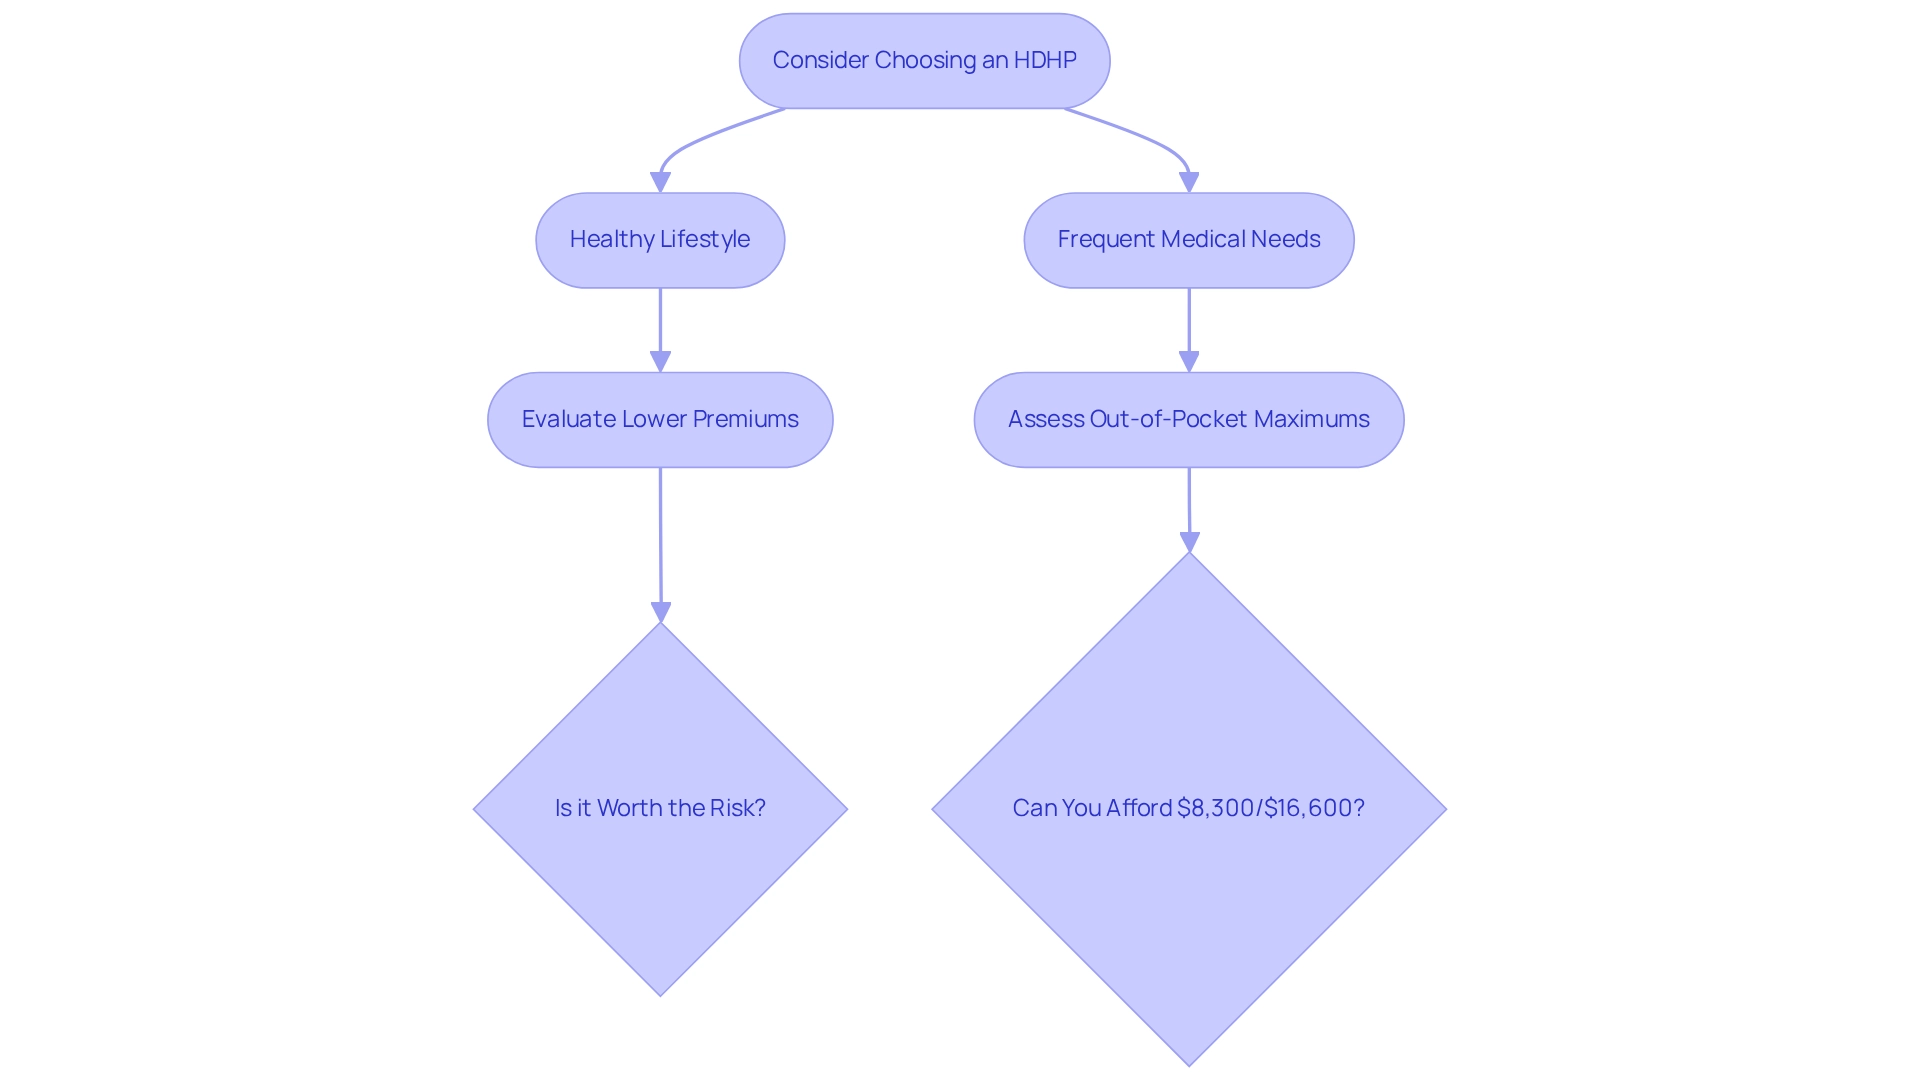
Choosing a High Deductible Health Plan (HDHP) can significantly impact the financial well-being of young households. While the allure of lower premiums is clear, it’s crucial for families to prepare for the possibility of higher out-of-pocket costs when seeking healthcare services. In 2025, the maximum out-of-pocket expenses for HDHPs are capped at $8,300 for individual plans and $16,600 for family plans. This means that households must meet these deductibles before their insurance coverage kicks in, which can pose a serious economic challenge if unexpected medical needs arise.
It’s essential for families to conduct a thorough assessment of their healthcare needs and financial capabilities to determine if they can manage these expenses effectively. For instance, families who generally lead healthy lifestyles and anticipate few medical visits may find that the savings from lower premiums outweigh the risks associated with higher deductibles. However, it’s vital to recognize that even the most favorable private plans, including employer-sponsored traditional options, often do not provide adequate protection against medical costs.
Bright Advisers can be instrumental in helping families navigate these decisions by offering personalized planning services. By evaluating individual health needs and financial situations, families can make informed choices about whether an HDHP suits them. A case study comparing traditional employer-sponsored health plans with high-deductible options reveals that while traditional plans offer better protection, both types in the private market may still leave families facing significant out-of-pocket expenses. This underscores the importance of a comprehensive evaluation of personal health needs and financial circumstances.
Understanding the economic implications of high-deductible health plans is particularly crucial for families managing the complexities of healthcare costs. Ultimately, deciding if an HDHP is a high deductible HSA plan worth it should be guided by a careful assessment of personal health needs and financial realities. Remember, Bright Advisers is here to support families in making these important decisions together.
Address Common Concerns and Misconceptions about HDHPs
Many families have concerns about high-deductible health insurance options, particularly regarding whether a high deductible HSA plan is worth it, often stemming from misunderstandings. Imagine if you believed that high-deductible health plans were unsuitable for families with children due to fears of high out-of-pocket costs. In reality, many of these plans cover preventive services at no cost, which can be a significant advantage for families with young kids who require regular check-ups and vaccinations.
It’s important to understand that Bright Advisers offers tailored financial planning strategies to help families navigate the complexities of HDHPs. By learning how to optimize the use of preventive services, families can ensure they receive essential care without incurring extra expenses.
Another common misconception is that health savings accounts are only beneficial for those with high incomes. However, HSAs can provide advantages for families across various income levels, offering a way to save for medical expenses while enjoying tax benefits. Bright Advisers encourages families to view health savings accounts as a valuable resource for financial stability. With the ability to carry over unspent HSA balances each year, families can build a reserve for future healthcare needs, which leads them to question if a high deductible HSA plan is worth it in their financial planning. Together, we can navigate this journey and ensure your family’s health and financial well-being.
Conclusion
Exploring High Deductible Health Plans (HDHPs) and Health Savings Accounts (HSAs) opens a door to a promising financial opportunity for young families. By understanding how these plans work and the benefits they offer, families can take advantage of lower premiums and significant tax advantages, effectively managing healthcare costs. The combination of HDHPs and HSAs not only provides immediate relief but also encourages long-term savings and investment potential, making them valuable tools for your financial planning.
It’s crucial to address the common misconceptions surrounding HDHPs so families can make informed choices. In reality, these plans can be especially beneficial for families with children, offering coverage for preventive services at no additional cost. Moreover, HSAs are available to families across various income levels, allowing them to build a financial cushion for medical expenses while enjoying tax benefits.
Ultimately, choosing an HDHP, complemented by an HSA, can empower families to navigate rising healthcare costs while aligning with their financial goals. Imagine having the confidence to assess your healthcare needs and determine the best course of action for your unique circumstances. By engaging with personalized financial planning services, you can embrace these options, leading to enhanced financial security and peace of mind in managing healthcare expenses. Together, we can navigate this journey and ensure a brighter financial future for your family.
Frequently Asked Questions
What is a High Deductible Health Plan (HDHP)?
A High Deductible Health Plan (HDHP) is a health insurance plan that requires a minimum deductible of $1,650 for individual coverage and $3,300 for household coverage as of 2025. These plans typically have higher deductibles but lower monthly premiums.
Why might families consider a high deductible HSA plan?
Families may consider a high deductible HSA plan to manage healthcare costs effectively, especially in light of rising employer healthcare costs. The combination of an HDHP with a Health Savings Account (HSA) can provide financial benefits and help ease immediate healthcare expenses.
What are the benefits of a Health Savings Account (HSA)?
HSAs offer tax-deductible contributions and tax-free withdrawals for qualifying medical expenses. This makes them a valuable tool for managing healthcare costs and can also serve as a potential resource for building wealth through investment options.
How can combining HDHPs and HSAs benefit families?
Combining HDHPs with HSAs creates a strategic approach to healthcare spending, especially for young families on a budget. HSAs can function as both a savings tool and an investment opportunity, enhancing long-term financial management and planning for future medical expenses.
What financial protections do HDHPs provide?
HDHPs limit out-of-pocket costs for covered medical services to a catastrophic in-network cap, providing extra financial protection for families.
How can Bright Advisers assist families with HDHPs and HSAs?
Bright Advisers offers support in navigating healthcare options, integrating planning and investment strategies through their wealth management platform. They help connect healthcare plans to investment strategies, ensuring families optimize their resources for economic security and independence.
List of Sources
- Define High Deductible Health Plans and Health Savings Accounts
- Frequently Asked Questions (https://opm.gov/healthcare-insurance/healthcare/health-savings-accounts/frequently-asked-questions)
- Top 10 reasons to use health savings accounts (https://healthinsurance.org/other-coverage/top-10-reasons-to-use-health-savings-accounts)
- High deductible health plans and health savings accounts (https://bls.gov/ebs/factsheets/high-deductible-health-plans-and-health-savings-accounts.htm)
- Explore Benefits of HDHPs and HSAs for Young Families
- Summary of Findings – 10240 | KFF (https://kff.org/report-section/ehbs-2023-summary-of-findings)
- Should You Choose a High-Deductible Health Plan? – NerdWallet (https://nerdwallet.com/article/health/high-or-low-deductible-health-insurance-plan)
- The HSA Tax-Advantage Triple Play (Health Savings Accounts) | (https://wealth45.com/the-hsa-tax-advantage-triple-play-health-savings-accounts)
- Analyze Financial Implications of Choosing an HDHP
- Should You Choose a High-Deductible Health Plan? – NerdWallet (https://nerdwallet.com/article/health/high-or-low-deductible-health-insurance-plan)
- Credible statistics on the financial barriers of high deductible health plans – PNHP (https://pnhp.org/news/credible-statistics-on-the-financial-barriers-of-high-deductible-health-plans)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin