

Overview
Getting married can be a wonderful opportunity for young families, offering not just love and commitment but also significant financial benefits. Imagine the relief of knowing that your family can enjoy lower tax rates, higher standard deductions, and access to valuable tax credits.
Consider this: married couples filing jointly can save an average of $3,062 through a marriage bonus. In 2025, they will benefit from a standard deduction of $30,000, which can make a real difference in your financial planning. Plus, credits like the Child Tax Credit and Earned Income Tax Credit can further enhance your overall tax efficiency, allowing you to focus more on what truly matters—your family.
It’s important to understand how these benefits can support your family’s goals and priorities. By planning together, you can navigate this journey with confidence, ensuring that your financial future is as bright as your family’s dreams.
We’re here for you, ready to help you explore these opportunities and make informed decisions that resonate with your family values. Together, we can create a financial strategy that supports your shared goals and nurtures your family’s well-being.
Key Highlights:
- Marriage can lead to a ‘marriage bonus,’ resulting in lower tax rates for couples with differing incomes, saving an average of $3,062.
- Married couples filing jointly can claim a higher standard deduction of $30,000 in 2025, reducing their taxable income.
- Joint filers have access to beneficial tax credits, including a maximum Child Tax Credit of $2,000 per child and an Earned Income Tax Credit (EITC) of up to $7,152 for families with two children.
- Filing jointly simplifies the tax preparation process by combining income, deductions, and credits, reducing complexity and potential errors.
- Strategies to maximise tax benefits include claiming the Child Tax Credit, Dependent Care Credit, itemising deductions, and utilising Health Savings Accounts (HSAs).
- Newlyweds should review financial goals, consult tax professionals, organise documents, and plan for future changes to optimise tax outcomes.
Introduction
Navigating the world of taxes can feel overwhelming, especially for young parents who are juggling financial responsibilities alongside family life. Yet, understanding the tax benefits of marriage can reveal significant savings and opportunities. This guide explores the compelling advantages of getting married—think marriage bonuses and enhanced tax credits—while posing an essential question: Could tying the knot be the key to optimizing tax benefits, or might it lead to unexpected financial challenges?
Imagine if you could unlock financial advantages that not only ease your burden but also support your family’s goals. By delving into the benefits of marriage, we aim to provide clarity and reassurance in this complex landscape. Together, we can navigate this journey toward financial well-being.
Understand the Tax Benefits of Marriage
Young parents should be aware that getting married is better for taxes, as it can provide several tax benefits. These include:
-
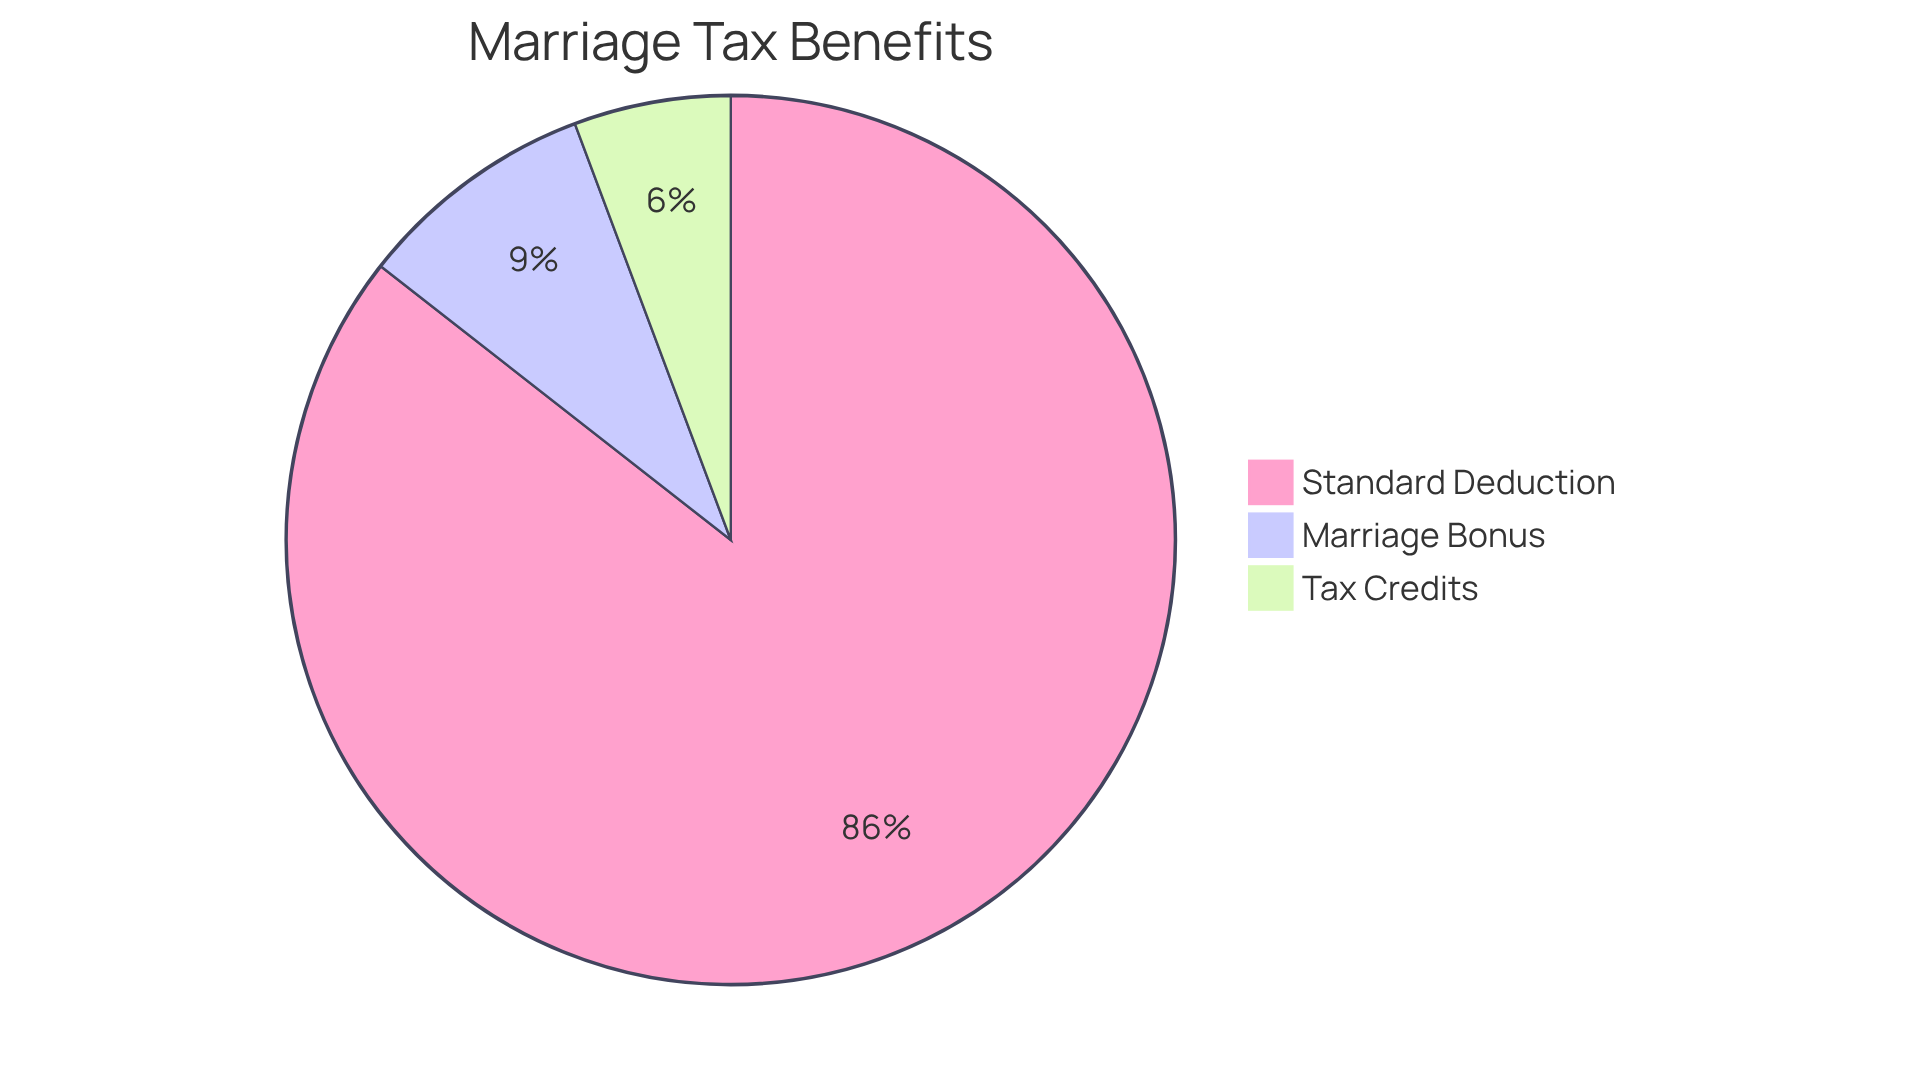
Marriage Bonus: Many couples experience a marriage bonus, where their combined income results in a lower tax rate compared to filing separately. This is particularly true for pairs with differing incomes, like Jay and Emma, who sought advice to efficiently distribute their resources and lessen financial stress. Imagine the relief of knowing that 43 percent of married partners received marriage bonuses, which illustrates why getting married is better for taxes, with average savings around $3,062.
-
Standard Deduction: Getting married is better for taxes because married partners filing jointly can claim a higher standard deduction than single filers, which for 2025 is set at $30,000. This advantage can be vital for partners like Emily and Mark, who are dedicated to establishing a robust economic base while handling challenging careers. This significantly lowers taxable income and improves overall tax efficiency, allowing them to focus on what truly matters—family.
-
Tax Credits: Certain tax credits, such as the Earned Income Tax Credit (EITC) and Child Tax Credit, may be more accessible or beneficial, raising the question of whether getting married is better for taxes when filing jointly. For partners like Allison and Brian, enhancing tax strategies has been crucial in maximizing their economic potential and ensuring their children’s future. The maximum Child Tax Credit for married individuals filing jointly is $2,000 per child, with an income cap of $400,000.
To fully utilize these advantages, it’s important for partners to evaluate their economic situation and consider if getting married is better for taxes by seeking advice from a tax expert. Just like how Bright Advisers has enabled clients to manage the intricacies of monetary planning, they can help create thorough strategies customized to your family’s needs. Together, we can navigate this journey and ensure a brighter financial future for your loved ones.
Explore Joint Filing Advantages and Tax Rates
Filing jointly presents several compelling advantages for married couples, especially for those navigating the complexities of family finances:
-
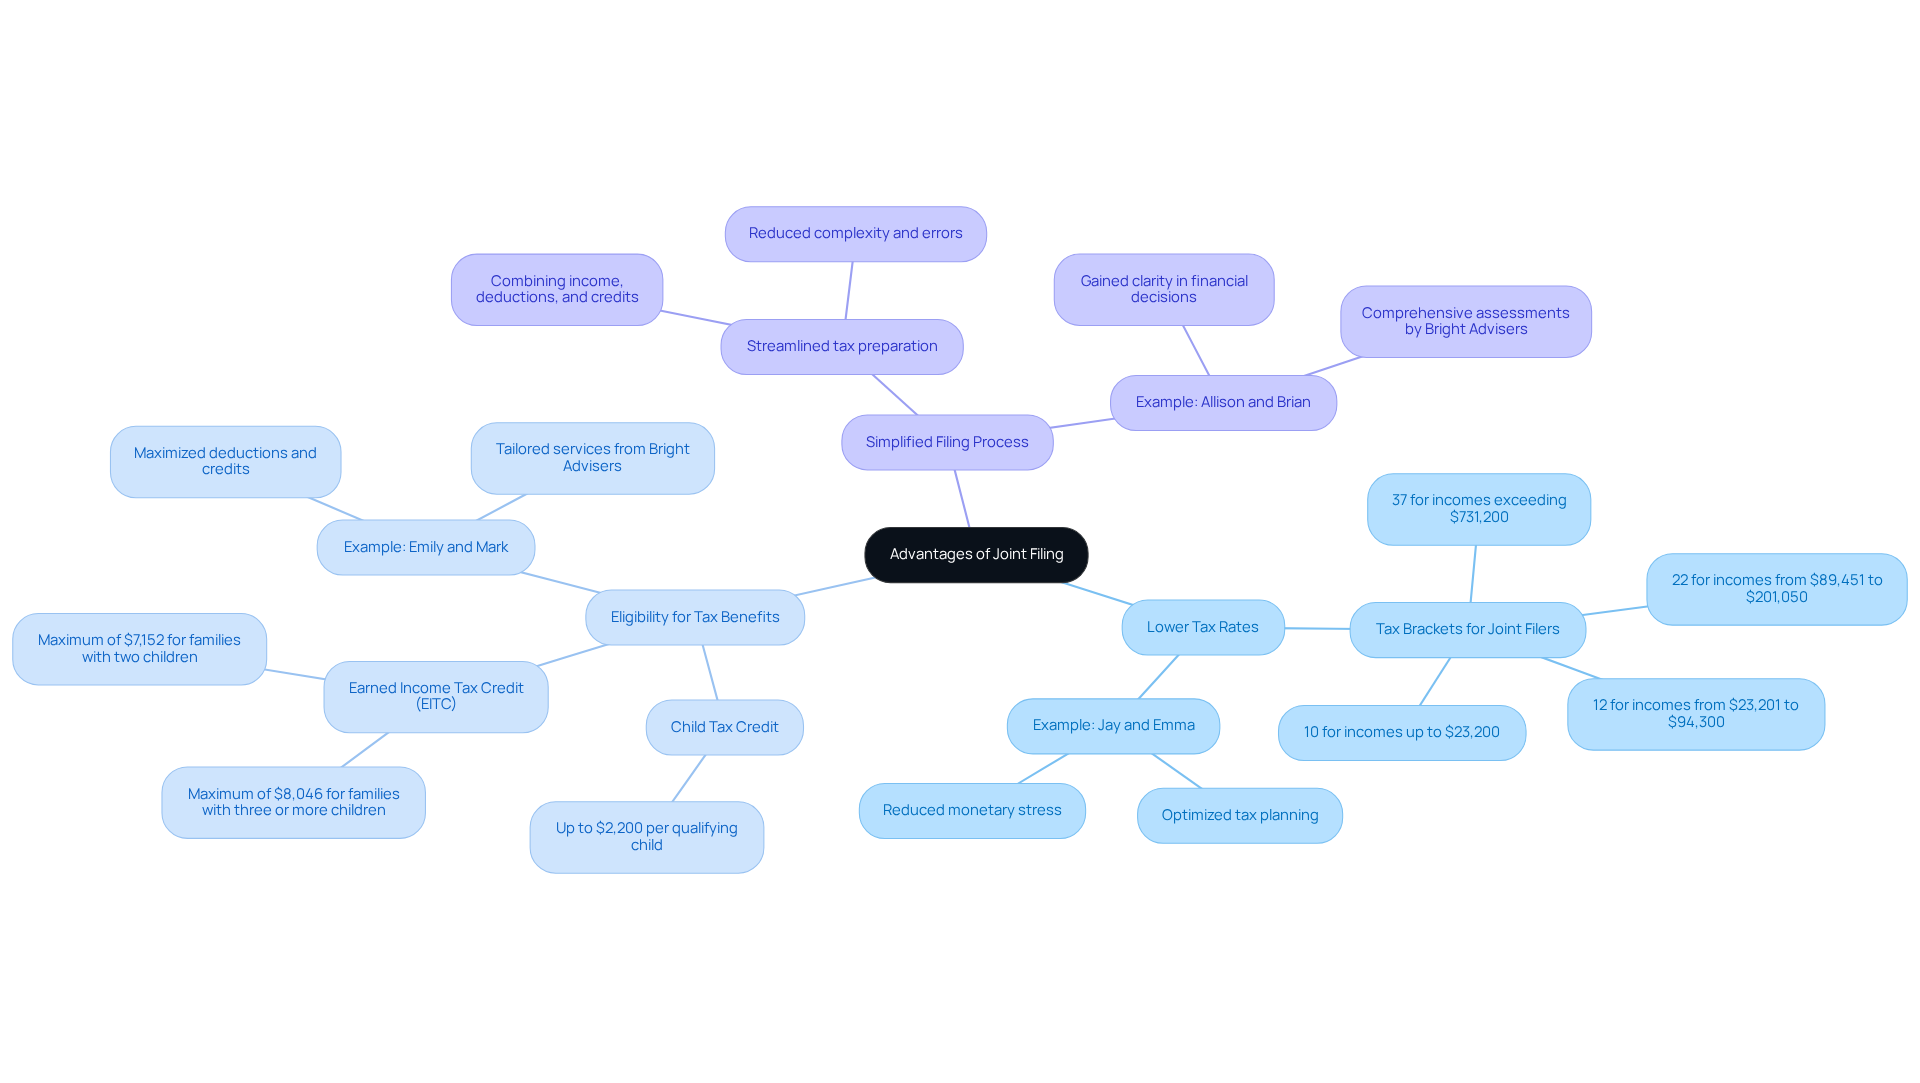
Lower Tax Rates: Imagine the relief of knowing that couples who file jointly often enjoy lower tax rates on their combined income. This is particularly beneficial when one spouse earns significantly more than the other, as the tax burden can be more evenly distributed across the income brackets. For instance, the 2025 tax brackets for joint filers start at a 10% rate for incomes up to $23,200, escalating to 37% for incomes exceeding $731,200. Couples like Jay and Emma, who aimed to lessen monetary stress, discovered that optimizing their tax planning through joint filing enabled them to allocate resources more effectively.
-
Eligibility for Tax Benefits: It’s important to understand that many tax credits and deductions are exclusively available to joint filers, significantly enhancing overall tax savings. For example, joint filers can claim the Child Tax Credit, which offers up to $2,200 per qualifying child in 2025, and the Earned Income Tax Credit (EITC), which can provide substantial credits based on combined income and number of children, with a maximum of $7,152 for families with two children. Emily and Mark, who sought economic independence, benefited from these credits as part of their comprehensive monetary strategy developed with Bright Advisers.
-
Simplified Filing Process: Consider the ease of a streamlined tax preparation process when filing jointly. This approach reduces the complexity associated with managing two separate returns, saving time and minimizing the likelihood of mistakes. Partners can combine their income, deductions, and credits into a single return. Allison and Brian, who were unaware of the financial opportunities they were missing due to inadequate tax planning, found that a simplified filing process helped them gain clarity and confidence in their financial decisions, thanks to the comprehensive assessments provided by Bright Advisers.
To fully utilize these benefits, partners should carefully examine the IRS tax brackets for married individuals filing jointly and compare their potential tax liabilities under both joint and separate filing scenarios. This analysis can reveal significant savings opportunities, particularly for couples with disparate incomes, illustrating that getting married is better for taxes as filing jointly may yield a more favorable tax outcome. Remember, together, we can navigate this journey toward financial clarity and security.
Identify Strategies to Maximize Deductions and Credits
To maximize deductions and credits, young parents can implement several effective strategies:
-
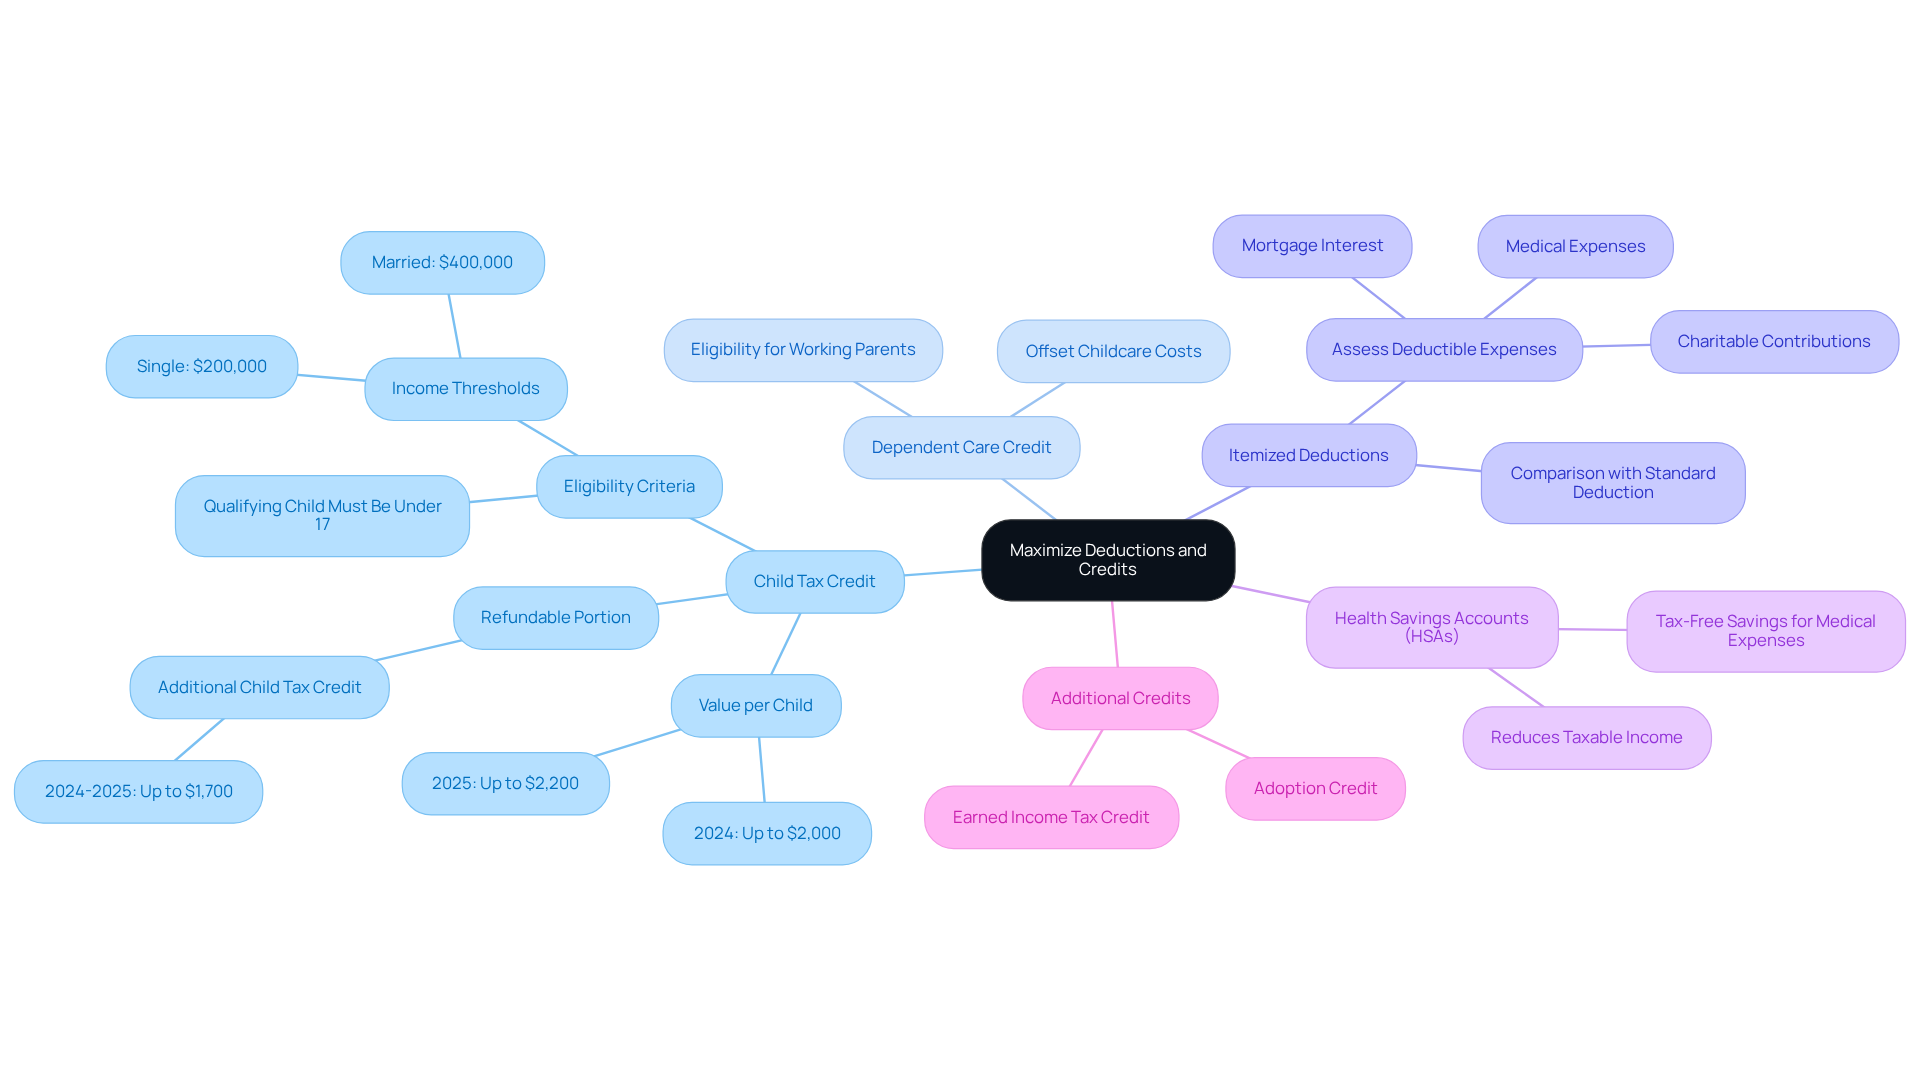
Child Tax Credit: Imagine being able to alleviate some of the financial stress that comes with raising children. To qualify for the Child Tax Credit, parents should keep accurate records of qualifying expenses and ensure their income remains below the specified thresholds. For the 2025 tax year, the credit can be valued at up to $2,200 per qualifying child, greatly alleviating the economic strain on families. Additionally, families may be eligible for the refundable portion of the Child Tax Credit, known as the Additional Child Tax Credit, which can provide up to $1,700 per qualifying child for the 2024 and 2025 tax years.
-
Dependent Care Credit: It’s important to understand that working parents may be eligible for the Dependent Care Credit, which helps offset childcare costs. This credit is especially advantageous for families with both parents working, enabling them to claim a portion of their childcare costs, thereby offering crucial monetary relief.
-
Itemized Deductions: Families should assess whether itemizing deductions—such as mortgage interest, medical expenses, and charitable contributions—exceeds the standard deduction. This evaluation can lead to greater tax savings, especially for those with significant deductible expenses.
-
Health Savings Accounts (HSAs): Contributing to an HSA offers tax-free savings for medical expenses, making it an advantageous option for families. HSAs not only reduce taxable income but also provide a safety net for healthcare costs, which can be substantial for families with young children.
-
Additional Credits: Together, we can navigate this journey by investigating eligibility for other credits, such as the Earned Income Tax Credit and Adoption Credit, which can further increase economic advantages.
By actively pursuing these strategies, families can effectively reduce their tax obligations and improve their economic well-being. Remember, the IRS may hold tax refunds until mid-February for those claiming the Additional Child Tax Credit, so planning ahead is crucial. Moreover, taking into account minimal fund fees in their investment strategies can additionally improve their economic wellbeing, enabling families to allocate more resources towards these tax-saving opportunities.
Implement Effective Tax Planning for Newlyweds
As newlyweds embark on their financial journey together, it is important to understand how getting married is better for taxes as a crucial step toward a secure future. Here are some thoughtful steps to consider:
-
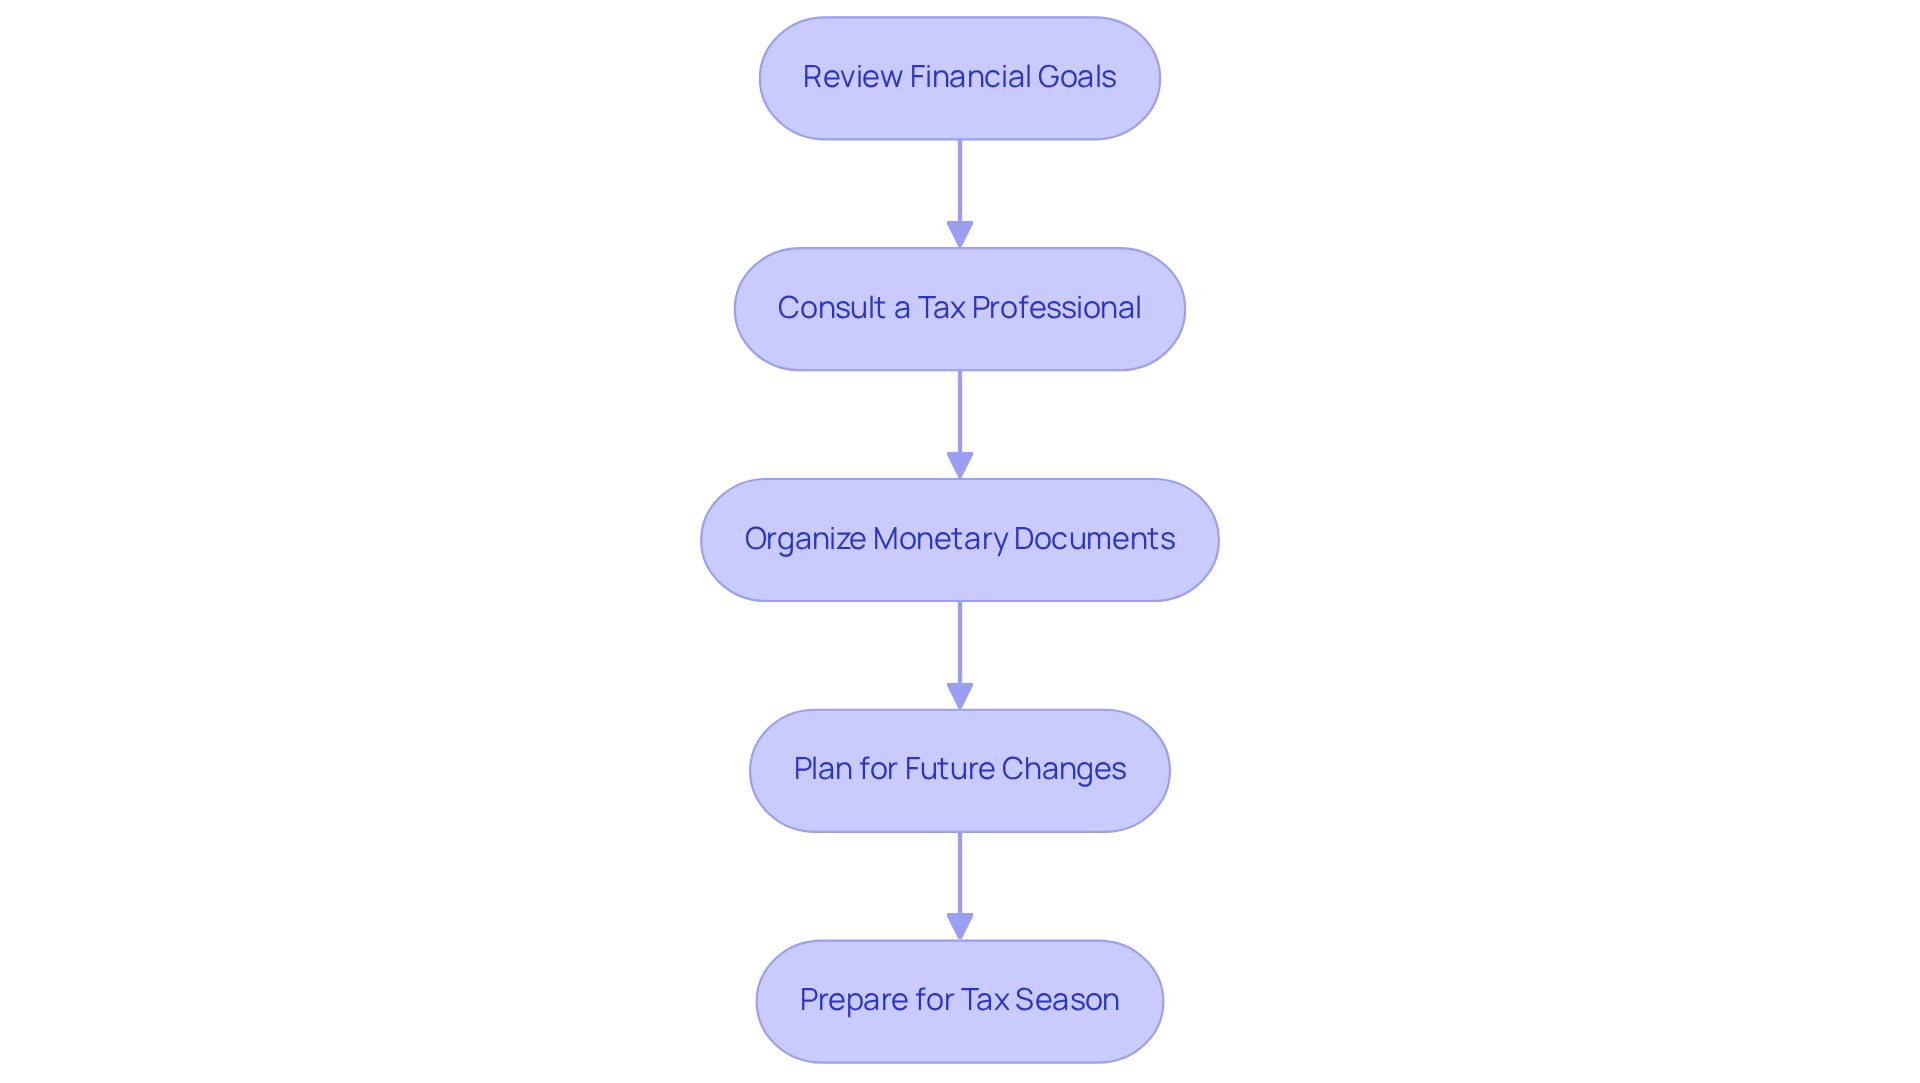
Review Financial Goals: Take a moment to engage in open discussions about your financial objectives. Marriage can shift these goals, and it’s important to recognize how. For instance, you might find yourselves prioritizing savings for a home or planning for your children’s education. This alignment is essential in crafting a family monetary strategy that truly reflects your shared values and vision.
-
Consult a Tax Professional: Imagine having a trusted expert by your side to help you navigate the complexities of tax filing as a married couple. A tax professional can illuminate potential advantages and tailor strategies to your unique financial situation, such as determining if getting married is better for taxes or understanding the marriage penalty. This comprehensive approach to wealth management, including tax planning, can significantly enhance your economic outcomes.
-
Organize Monetary Documents: Picture an organized collection of essential documents—W-2s, 1099s, and receipts for deductions—ready at your fingertips. This preparation not only simplifies tax filing but also ensures that no potential savings slip through the cracks. Remember, effective budgeting and asset tracking are key elements of a successful monetary strategy.
-
Plan for Future Changes: It’s important to anticipate how significant life events, like having children or changing jobs, may impact your tax situation. You may need to adjust your withholding or explore tax credits related to dependents. Adapting your budgeting strategies to accommodate these changes is vital for long-term success.
By following these steps, you and your partner can prepare for tax season with confidence, maximizing your monetary advantages as a married couple. Together, you can foster a stronger economic partnership. Additionally, understanding whether getting married is better for taxes can help you navigate any potential tax disadvantages that may arise from your combined income, reinforcing the importance of a comprehensive family financial strategy. Remember, we’re here for you every step of the way.
Conclusion
Getting married often brings significant financial advantages, especially when it comes to taxes. Imagine if you could unlock a world of tax benefits simply by saying “I do.” Young parents can truly thrive by understanding the various tax benefits associated with marriage, including:
- Marriage bonuses
- Increased standard deductions
- Access to valuable tax credits
This insight illustrates that marriage can be a strategic financial decision, allowing couples to optimize their tax situations and enhance their economic stability.
Consider the advantages of joint filing, which can lead to lower tax rates and eligibility for exclusive tax credits that provide substantial savings. It’s important to understand that effective tax planning can make a significant difference. Strategies such as:
- Maximizing deductions
- Utilizing Health Savings Accounts
- Consulting with tax professionals
are essential for newlyweds. Together, these insights reinforce the notion that getting married can indeed be better for taxes, opening up a range of opportunities for financial growth and security.
As you navigate your financial future, understanding the tax implications of marriage is crucial. By actively exploring the benefits and implementing effective strategies, couples can significantly reduce their tax obligations and foster a more secure economic partnership. Taking the time to plan and consult with experts can lead to a brighter financial outlook, ensuring that families not only survive but thrive together. Embracing these principles can transform the financial landscape for newlyweds, making the journey of marriage not just a personal commitment, but also a smart financial move.
Remember, we’re here for you. Together, we can navigate this journey, ensuring that you and your family can enjoy the financial benefits that marriage can bring.
Frequently Asked Questions
What are the tax benefits of marriage for young parents?
Young parents can benefit from several tax advantages when getting married, including a marriage bonus, higher standard deductions, and access to certain tax credits.
What is a marriage bonus?
A marriage bonus occurs when couples find that their combined income results in a lower tax rate compared to filing separately. About 43 percent of married partners receive this bonus, with average savings around $3,062.
How does the standard deduction change for married couples?
Married partners filing jointly can claim a higher standard deduction than single filers. For 2025, the standard deduction for married couples is set at $30,000, which significantly lowers taxable income.
What tax credits are more accessible for married couples?
Married couples may benefit more from tax credits such as the Earned Income Tax Credit (EITC) and the Child Tax Credit. The maximum Child Tax Credit for married individuals filing jointly is $2,000 per child, with an income cap of $400,000.
How can couples maximize their tax benefits after marriage?
Couples should evaluate their economic situation and consider seeking advice from a tax expert to effectively utilize the tax advantages of marriage and create customized financial strategies.
List of Sources
- Understand the Tax Benefits of Marriage
- 10 Tax Benefits of Marriage (https://turbotax.intuit.com/tax-tips/marriage/7-tax-advantages-of-getting-married/L1XlLCh0m)
- What Are the Tax Benefits of Marriage? – Nationwide (https://nationwide.com/lc/resources/personal-finance/articles/tax-benefits-of-marriage)
- What are marriage penalties and bonuses? (https://taxpolicycenter.org/briefing-book/what-are-marriage-penalties-and-bonuses)
- 6 Tax Benefits for Married Couples | Mutual of Omaha (https://mutualofomaha.com/advice/financial-planning/financial-planning-basics/6-tax-benefits-for-married-couples)
- How Marriage Affects Your Taxes (https://northwesternmutual.com/life-and-money/tax-benefits-of-marriage)
- Explore Joint Filing Advantages and Tax Rates
- Married Filing Jointly vs Separately: How Should You and Your Spouse File Taxes? (https://turbotax.intuit.com/tax-tips/marriage/should-you-and-your-spouse-file-taxes-jointly-or-separately/L7gyjnqyM)
- How Filing Jointly Affects Taxes: Key Insights for Young Families – Bright Advisers (https://brightadvisers.com/how-filing-jointly-affects-taxes-key-insights-for-young-families)
- Married filing jointly vs separately: Which to choose? | Fidelity (https://fidelity.com/learning-center/smart-money/married-filing-jointly)
- Married Filing Jointly: Pros, Cons, and Tax Tips (https://eztaxreturn.com/blog/married-filing-jointly-pros-cons-and-tax-tips)
- Federal income tax rates and brackets | Internal Revenue Service (https://irs.gov/filing/federal-income-tax-rates-and-brackets)
- Identify Strategies to Maximize Deductions and Credits
- Sweet Child of Mine: Tax Credits for Parents (https://turbotax.intuit.com/tax-tips/family/sweet-child-of-mine-tax-credits-for-parents/L1DqxZ9mh)
- Child Tax Credit | Internal Revenue Service (https://irs.gov/credits-deductions/individuals/child-tax-credit)
- Child Tax Credit for 2024 – 2025 (https://turbotax.intuit.com/tax-tips/family/child-tax-credit/L9ZIjdlZz)
- What is the child tax credit? (https://taxpolicycenter.org/briefing-book/what-child-tax-credit)
- Implement Effective Tax Planning for Newlyweds
- 17 tax tips to manage the marriage penalty (https://financial-planning.com/list/17-tax-tips-when-planning-for-the-marriage-penalty)
- Percentage of Married Couples With Separate Accounts (https://linkedin.com/pulse/percentage-married-couples-separate-accounts-nathan-mueller-mba-s66le)
- Money and Marriage Problems: What the Statistics Don’t Tell You – Pacesetter Planning (https://pacesetterplanning.com/money-and-marriage-problems)
- 10 Best Tax-Saving Tips for Couples (https://marriage.com/advice/finance/best-tax-saving-tips-for-couples)
- 112 Quotes about Marriage and Money (https://modernhusbands.com/post/112-quotes-about-marriage-and-money)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading