

Key Highlights:
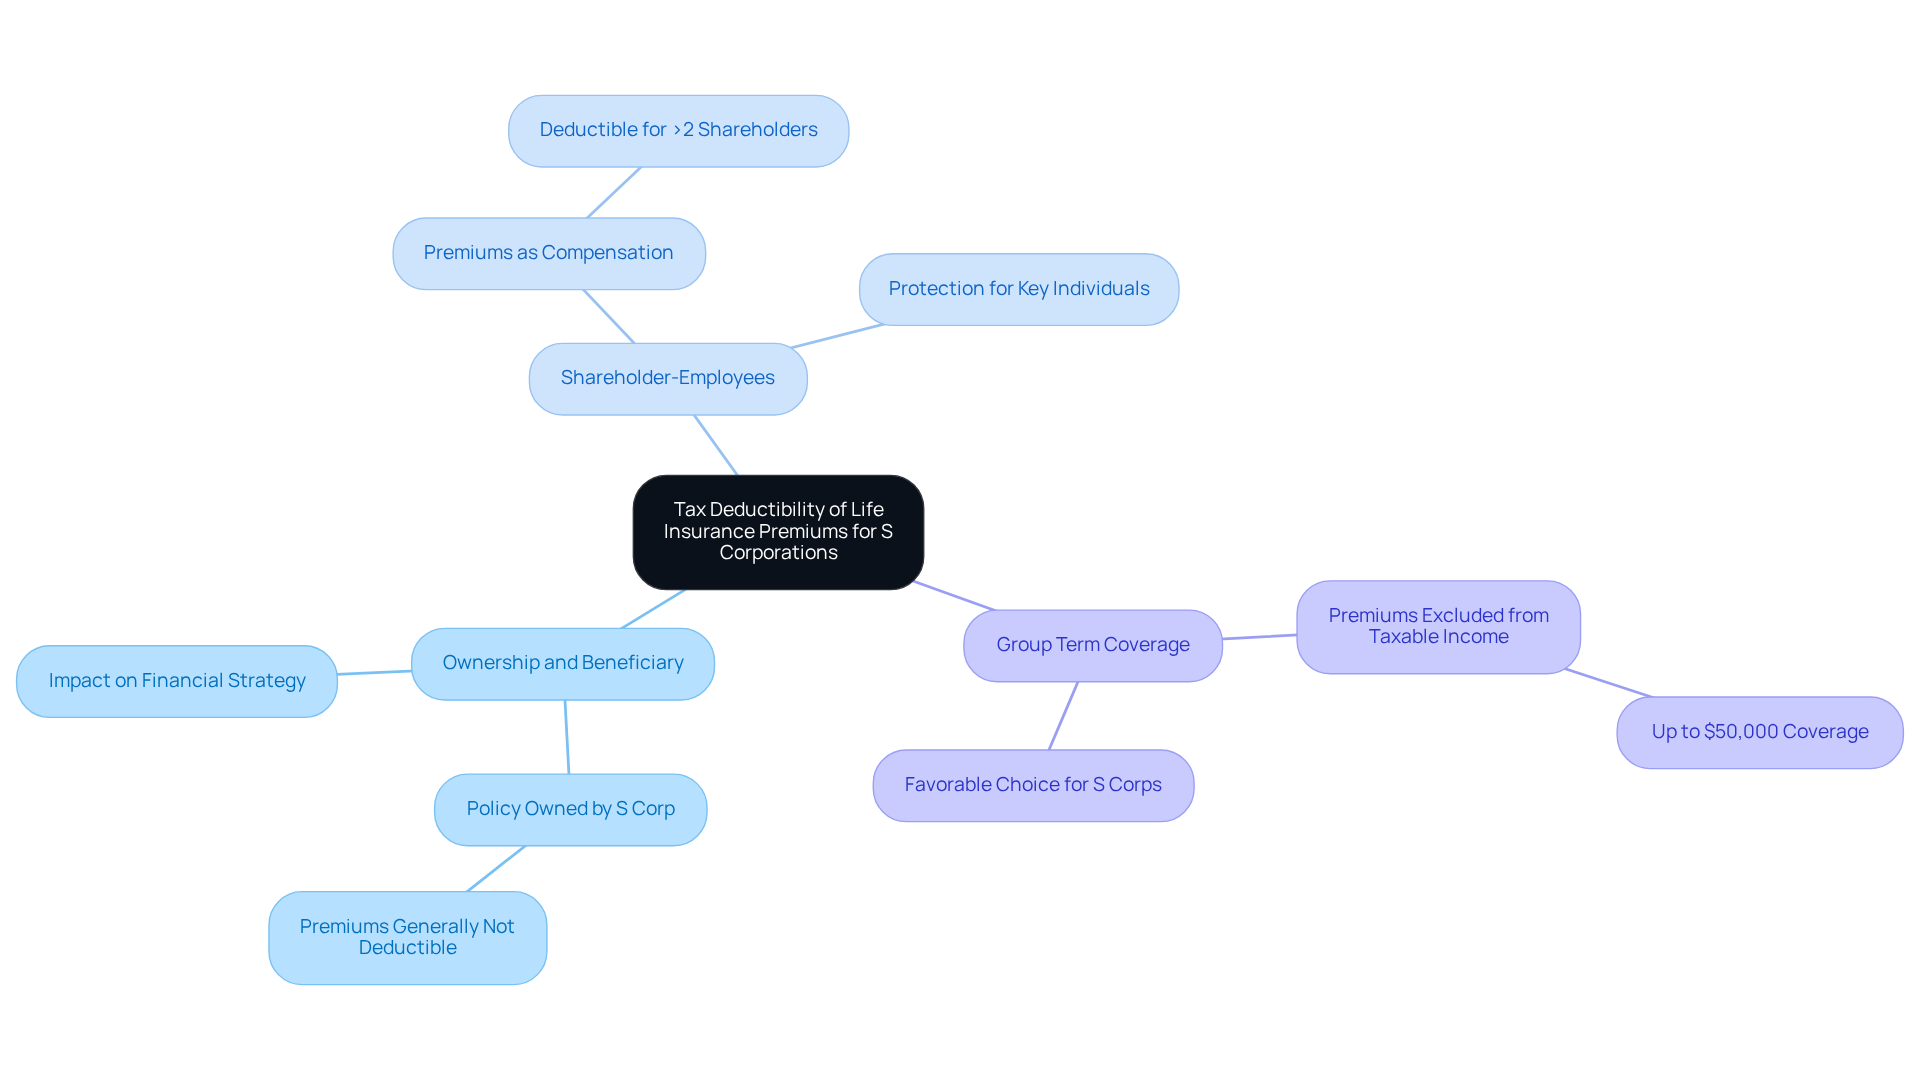
- Key Person Insurance protects businesses from financial strain due to the loss of a key employee, with death benefits typically tax-free under Section 101(a)(1).
- Group Term Life Coverage offers up to $50,000 in benefits for employees without tax implications for employers, promoting employee well-being.
- Premiums for life insurance policies owned by S Corporations are generally not deductible, impacting financial strategies.
- Shareholder-employees owning more than 2% of the S Corporation may have premiums treated as deductible compensation.
- Group term coverage premiums are excluded from taxable income for employees, making it a favourable option for S Corporations.
- Policy proceeds are usually not included in total income, providing financial relief for families during difficult times.
- Consulting a tax professional is essential for compliance and maximising tax benefits based on IRS guidelines.
- IRS publications, tax software, and online calculators are useful resources for assessing tax deductions related to life insurance.
Introduction
Navigating the world of life insurance for S Corporations can feel overwhelming, especially when you think about the potential tax implications. It’s crucial to understand the nuances of tax deductibility – not just for your business, but for the financial security of your family.
Imagine if you could protect your loved ones while also making smart financial decisions for your business. This article explores the essential aspects of life insurance policies within S Corps, looking at the types of coverage available and the specific criteria that determine tax deductibility.
As many business owners, especially young parents, grapple with questions about their financial strategies, the challenge remains: how can you effectively leverage life insurance to maximize benefits while staying compliant with IRS regulations?
We’re here for you, ready to help you navigate this journey. Together, we can explore how life insurance can be a valuable tool in your financial planning, ensuring that your family’s future is secure.
Understand Life Insurance Basics for S Corporations
Navigating whether life insurance is tax deductible for S Corp within an S Corporation can feel overwhelming, but understanding the different types of plans can make a world of difference for you and your family. Let’s explore two common options that can provide peace of mind:
- Key Person Insurance: Imagine losing a key employee-someone who drives your business forward. This policy acts as a safety net, protecting your company from the financial strain that could follow. It helps cover the costs of finding and training a replacement, while also addressing any potential loss of revenue. While the premiums for this protection aren’t deductible, the under Section 101(a)(1). This means your business can weather the storm without added financial pressure.
- Group Term Life Coverage: Often offered as a valuable employee benefit, this plan provides coverage for a group of employees, usually up to $50,000, without tax implications for you as the employer. Not only does this enhance your employee benefits, but it also fosters a supportive workplace culture. While S corporations can’t deduct premiums for group term coverage, the death benefits remain tax-free when the insured passes away, ensuring that your team feels valued and secure.
By grasping these basics, you can make informed choices about implementing these plans and understanding if life insurance is tax deductible for S Corp and its potential tax consequences. Mindy Tyson Weber, senior director at RSM US LLP, reminds us, “It is important to keep those rules in mind to help avoid unexpected results.” This highlights the need to be aware of the tax implications of coverage policies, especially with recent changes like the Pension Protection Act of 2006, which affects the tax-exempt status of proceeds from these policies.
Additionally, case studies show that while premiums may reduce stock basis, they don’t impact the accumulated adjustments account (AAA). This allows for tax-free distributions under certain conditions, making it a smart choice for your business. Group term coverage can also be a powerful tool for attracting and retaining talent, demonstrating your commitment to employee well-being.
Together, we can navigate this journey of financial planning, ensuring that you and your family are well-protected and supported.

Identify Criteria for Tax Deductibility of Life Insurance Premiums
It is essential for S Corporation owners to understand if life insurance is tax deductible for S Corp, particularly when it comes to protecting their families and businesses. Let’s explore some key criteria that can help you navigate this important aspect of financial planning:
- Ownership and Beneficiary: If your S Corporation owns the policy and is the beneficiary, premiums are generally not deductible. This is a crucial point to consider when arranging your coverage policies, as it directly impacts your financial strategy.
- Shareholder-Employees: If you have shareholders who own more than 2% of the S Corporation, the premiums paid for their coverage may be deductible as compensation. This can provide valuable tax benefits while ensuring that key individuals in your business are well-protected.
- Group Term Coverage: Premiums for group term coverage up to $50,000 are typically excluded from taxable income for employees. This makes group plans a favorable choice for S Corporations, allowing you to offer essential benefits without the added tax burden.
It’s also important to note that policy proceeds usually aren’t included in a person’s total income, meaning no income tax is required. This can offer significant financial relief for families during challenging times.
Insights from case studies reveal that while premiums are often not deductible, understanding whether life insurance is tax deductible for S Corp can provide strategic ways to arrange these plans to maximize tax advantages. For instance, consider providing coverage as an employee benefit through group plans, which may allow for deductions under specific conditions.
As Mindy Tyson Weber points out, S Corporations with prior C corporation earnings and profits (E&P) can generally make tax-free distributions only to the extent of AAA. Any additional amounts may be taxable to shareholders based on the company’s E&P. Understanding these criteria can empower S Corporation owners to , ensuring that you’re making informed decisions for your family’s future.
Together, we can navigate this journey, ensuring that your financial planning aligns with your family values and priorities.
Evaluate Your S Corp’s Life Insurance Policies for Tax Benefits
Evaluating if life insurance is tax deductible for S Corp can feel overwhelming, but we’re here to help you navigate this journey. Let’s break it down into manageable steps that prioritize your family’s financial well-being.
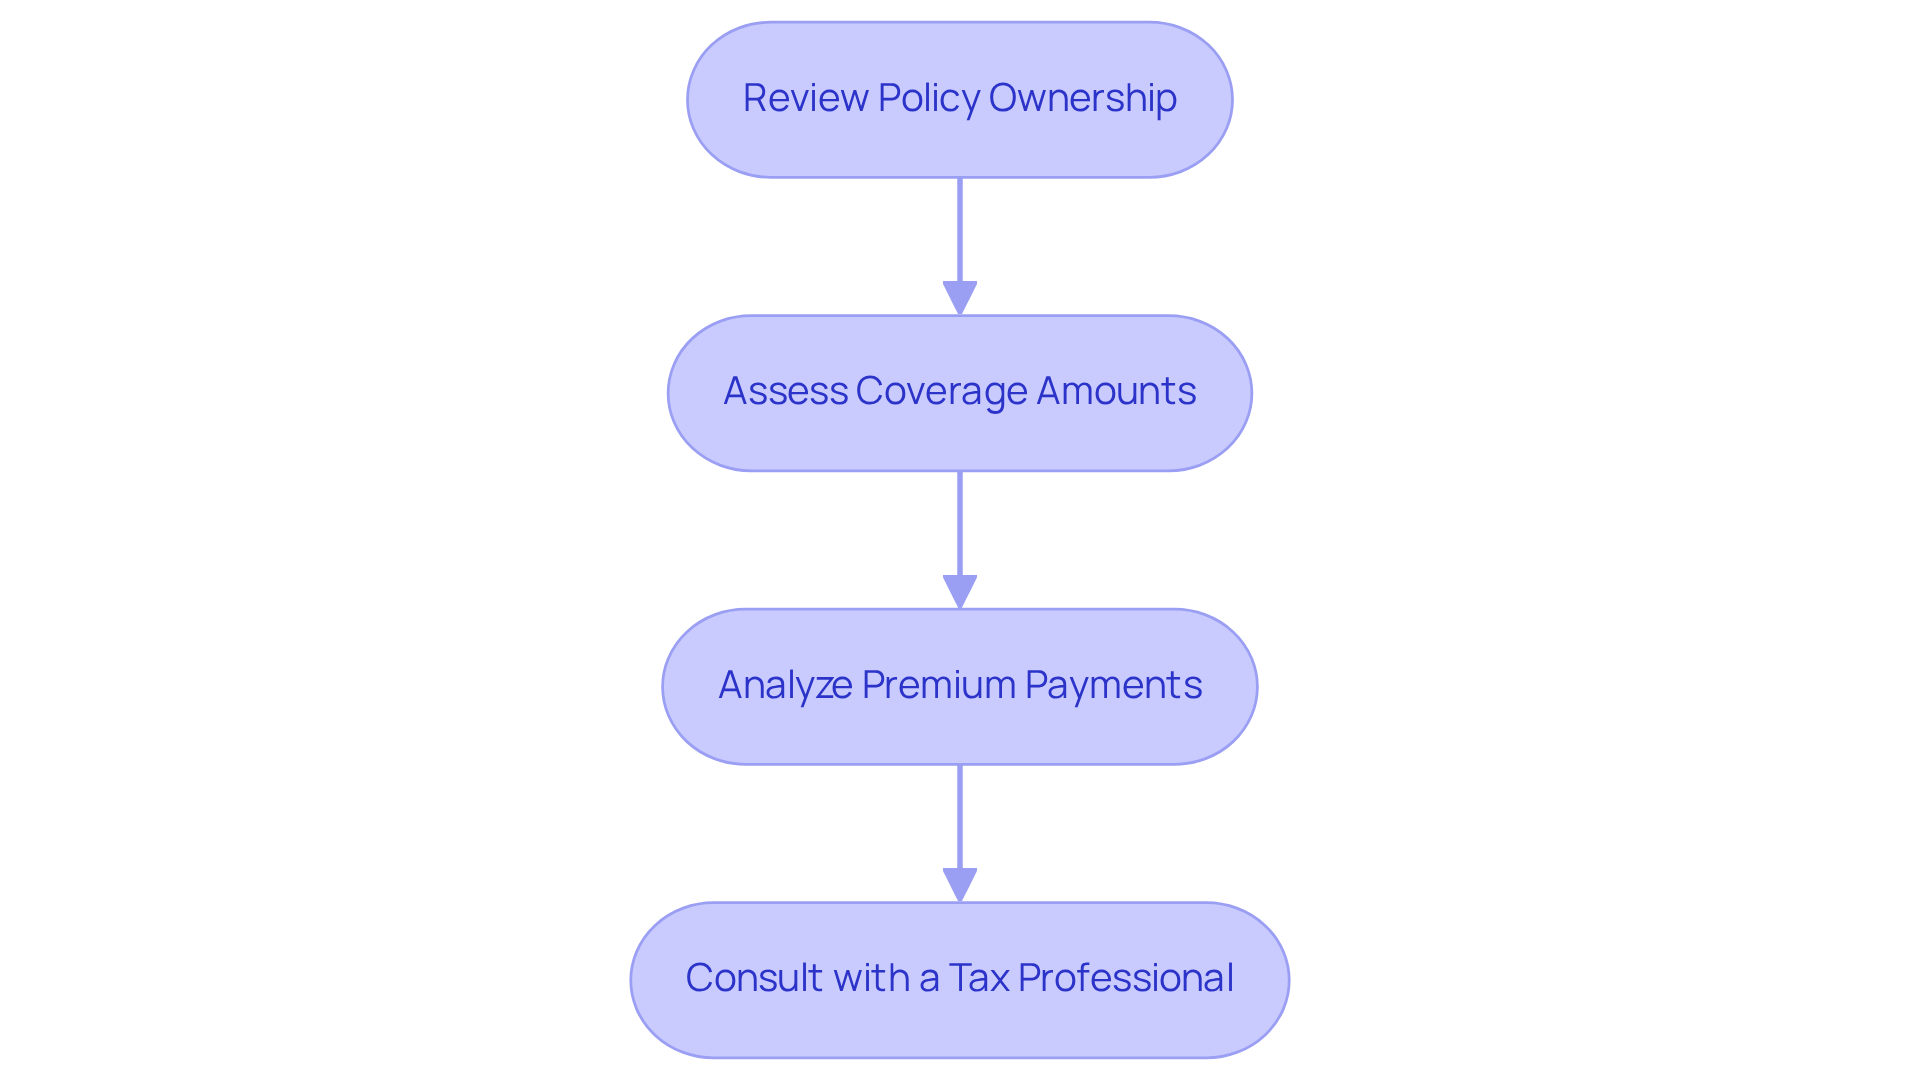
- Review Policy Ownership: Start by identifying who owns the policy and who the beneficiary is. If your S Corporation holds the insurance, keep in mind that this can increase the taxable estate value. Understanding whether is crucial for grasping deductibility and estate tax implications.
- Assess Coverage Amounts: It’s important to ensure that the coverage doesn’t exceed $50,000 for group term plans. This threshold can significantly influence whether the question of is life insurance tax deductible for S Corp applies and potential deductions. Consider the typical coverage levels for group term coverage in S Corporations to ensure compliance and peace of mind.
- Analyze Premium Payments: Take a moment to determine which premiums are being paid for shareholders. Assess whether these qualify as deductible compensation under IRS guidelines and if life insurance is tax deductible for S Corp. This step can help you maximize your benefits while staying compliant.
- Consult with a Tax Professional: Engaging a tax advisor is a vital step. They can review your plans to ensure compliance with IRS regulations while maximizing your tax benefits. This is especially important in light of the Supreme Court’s decision in Connelly v. United States, which highlights the need for proper structuring to avoid unintended tax consequences.
This assessment procedure is essential for ensuring that your S Corporation effectively utilizes its policies. By maximizing tax deductions, you can also address possible liquidity concerns for your estate. Remember, together, we can navigate this journey and secure a brighter financial future for your family.
Access Resources and Tools for Tax Deduction Assessment
Navigating whether life insurance is tax deductible for S Corp can feel overwhelming, but you’re not alone. Here are some resources and tools that can help you along the way:
- IRS Publications: Start by reviewing IRS Publication 15-B. It offers detailed insights into fringe benefits and the tax implications of life insurance, helping you understand your options better.
- Tax Software: Consider using tax preparation software that simplifies tracking and calculating deductions for premium payments. For example, TurboTax promises 100% accuracy and maximum refunds, giving you peace of mind as you manage your tax filings.
- Consultation Services: Engaging with financial advisors or tax professionals who specialize in S Corporations can provide you with personalized insights and strategies. While the average cost of working with a tax professional is around $600, think of it as a worthwhile investment in tailored advice that can make a difference for your family.
- Online Calculators: Don’t forget to use online tax calculators! They can help you estimate potential deductions based on your specific policy details and financial situation.
It’s also important to recognize that the uptake of private placement policies (PPLI) among households is expected to rise by more than 20% by 2025. This trend highlights the growing significance of tax-efficient investment options for families like yours.
With these resources at your fingertips, you can confidently of whether life insurance is tax deductible for S Corp. Remember, we’re here for you, and together, we can navigate this journey.

Conclusion
Understanding the complexities of life insurance tax deductibility for S Corporations is crucial for business owners who want to protect their families and ensure financial stability. Imagine if you could secure your loved ones’ future while navigating the intricacies of tax implications. While life insurance premiums may not always be deductible, the right policies can still offer significant benefits, such as tax-free death benefits and improved employee morale through group coverage.
It’s important to consider key factors like policy ownership and beneficiary designations. Knowing the specific criteria for tax deductibility can empower you to make informed decisions that align with your financial goals. Engaging a tax professional and utilizing resources like IRS publications and tax software can further support you in this journey.
Navigating the world of life insurance for S Corporations isn’t just about understanding tax implications; it’s about making strategic choices that safeguard both your business interests and your family’s welfare. By carefully evaluating insurance policies and leveraging available resources, you can take proactive steps toward maximizing your tax benefits and ensuring a secure financial future. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What is Key Person Insurance and how does it benefit an S Corporation?
Key Person Insurance protects an S Corporation from financial strain following the loss of a key employee. It covers costs associated with finding and training a replacement and addresses potential revenue loss. While premiums are not deductible, the death benefits are typically tax-free under Section 101(a)(1).
What is Group Term Life Coverage and what are its advantages for employees?
Group Term Life Coverage is a plan that provides life insurance for a group of employees, usually up to $50,000, and is often offered as an employee benefit. It enhances employee benefits and fosters a supportive workplace culture. Although S Corporations cannot deduct premiums, the death benefits are tax-free when the insured passes away.
Are life insurance premiums tax deductible for S Corporations?
No, S Corporations cannot deduct premiums for Key Person Insurance or Group Term Life Coverage. However, the death benefits from these policies are generally tax-free.
What are the tax implications of life insurance policies for S Corporations?
While premiums may reduce stock basis, they do not impact the accumulated adjustments account (AAA), which allows for tax-free distributions under certain conditions. It is important to be aware of these implications, especially with changes like the Pension Protection Act of 2006.
How can life insurance policies help in attracting and retaining talent?
Offering Group Term Life Coverage as an employee benefit demonstrates a commitment to employee well-being, which can be a powerful tool for attracting and retaining talent within an S Corporation.
What should S Corporations consider when implementing life insurance plans?
S Corporations should understand the tax implications of life insurance coverage policies and keep in mind the rules to avoid unexpected results, as emphasized by financial experts.
List of Sources
- Understand Life Insurance Basics for S Corporations
- Life Insurance and S Corporations: Unique Rules Present Opportunity and Peril (https://thetaxadviser.com/issues/2016/apr/life-insurance-and-s-corporation-rules-present-opportunity-and-peril)
- New Tax Treatment of Certain Employer Owned Life Insurance | Dean Mead (https://deanmead.com/new-tax-treatment-of-certain-employer-owned-life-insurance)
- Identify Criteria for Tax Deductibility of Life Insurance Premiums
- Can I Deduct Life Insurance As A Business Expense? | Ethos Life (https://ethos.com/life-insurance/life-insurance-business-expense)
- Life Insurance and S Corporations: Unique Rules Present Opportunity and Peril (https://thetaxadviser.com/issues/2016/apr/life-insurance-and-s-corporation-rules-present-opportunity-and-peril)
- Evaluate Your S Corp’s Life Insurance Policies for Tax Benefits
- Life Insurance and S Corporations: Unique Rules Present Opportunity and Peril (https://thetaxadviser.com/issues/2016/apr/life-insurance-and-s-corporation-rules-present-opportunity-and-peril)
- Reevaluating Succession Plans That Rely on Life Insurance in Closely Held Businesses – Barley Snyder (https://barley.com/reevaluating-succession-plans-that-rely-on-life-insurance-in-closely-held-businesses)
- Breaking News: Life Insurance Proceeds Now Impact Company Valuation and Estate Tax Obligations (https://bonadio.com/article/breaking-news-life-insurance-proceeds-now-impact-company-valuation-and-estate-tax-obligations)
- Tax Reduction Letter – Should Your S Corporation Buy Life Insurance? (https://bradfordtaxinstitute.com/Content/S-Corporation-Life-Insurance.aspx)
- The Tax Consequences Of Employer-provided Life Insurance (https://mjcpa.com/the-tax-consequences-of-employer-provided-life-insurance)
- Access Resources and Tools for Tax Deduction Assessment
- Best tax software for small businesses in 2025 (https://cnbc.com/select/best-tax-software-for-small-businesses)
- The best tax software of 2025 (https://cnbc.com/select/best-tax-software)
- Best Tax Software for Small Business for 2025 (https://investopedia.com/the-best-tax-software-for-small-business-8780637)
- Life Insurance and S Corporations: Unique Rules Present Opportunity and Peril (https://thetaxadviser.com/issues/2016/apr/life-insurance-and-s-corporation-rules-present-opportunity-and-peril)
- 7 Leading Private Placement Life Insurance Companies for Families – Bright Advisers (https://brightadvisers.com/7-leading-private-placement-life-insurance-companies-for-families)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin