

Overview
Understanding Modified Adjusted Gross Income (MAGI) is essential for your family’s financial well-being. MAGI, while often confused with Taxable Income, is actually derived from Adjusted Gross Income (AGI) by adding back certain deductions. In contrast, Taxable Income represents the income subject to taxation after all deductions and exemptions have been applied. It’s important to understand this distinction because MAGI plays a significant role in determining your eligibility for various tax benefits, such as the Child Tax Credit and contributions to Roth IRAs. These factors can greatly influence your family’s financial strategies and potential savings.
Imagine if knowing your MAGI could unlock opportunities for your family. By grasping how MAGI affects your tax benefits, you can make informed decisions that align with your family’s goals. This understanding not only helps in effective tax planning but also empowers you to maximize your savings.
We’re here for you as you navigate these financial waters. Together, we can explore how understanding MAGI can lead to better financial outcomes for your family. Remember, every little bit counts, and being informed is the first step toward securing your family’s future.
Key Highlights:
- Modified Adjusted Gross Income (MAGI) is calculated from Adjusted Gross Income (AGI) by adding back specific deductions such as student loan interest and foreign earned income.
- Taxable Income is the portion of income subject to taxation after deductions and exemptions are applied.
- MAGI influences eligibility for tax benefits like the Child Tax Credit and education-related credits, with thresholds set at $80,000 for single filers and $160,000 for married couples.
- Calculating MAGI involves starting with AGI and adding back certain deductions, which is crucial for effective tax planning.
- MAGI affects eligibility for healthcare incentives under the Affordable Care Act and contributions to Roth IRAs, with limits set at $236,000 for married couples and $150,000 for individuals.
- Strategies to optimise MAGI include maximising contributions to tax-deferred accounts, utilising tax credits, planning deductions strategically, and consulting financial advisors.
- Understanding the distinction between MAGI and Taxable Income can empower families to enhance their financial planning and improve overall economic well-being.
Introduction
Understanding the nuances of Modified Adjusted Gross Income (MAGI) and Taxable Income is crucial for families like yours, who aim to optimize their financial strategies. Imagine being able to unlock various tax benefits and credits through MAGI, while Taxable Income determines the actual amount you owe in taxes. This distinction is not just a technical detail; it can significantly impact your family’s tax planning.
For households striving to maximize deductions and credits, this knowledge is empowering. But how can you effectively navigate these complex definitions and ensure that you’re not leaving potential savings on the table? We’re here to help you through this journey.
Define Modified Adjusted Gross Income (MAGI) and Taxable Income
Modified Adjusted Gross Income is a vital metric that can help you understand your eligibility for various tax benefits and credits. It begins with your Adjusted Gross Income (AGI) and incorporates specific deductions, like student loan interest and foreign earned income, to provide a fuller picture of your financial situation. On the other hand, Taxable Income is the portion of your income that is subject to taxation after accounting for all applicable deductions and exemptions.
Understanding if modified adjusted gross income is the same as taxable income is essential for effective tax planning, especially for families striving to optimize their financial strategies. Many households, particularly those with higher incomes like Allison and Brian, might not fully grasp whether modified adjusted gross income is the same as taxable income, leading to missed opportunities for tax savings. For instance, Modified Adjusted Gross Income is crucial in determining eligibility for tax credits such as the Child Tax Credit and education-related credits, where thresholds are typically set at $80,000 for single filers and $160,000 for married couples filing jointly.
Recognizing the importance of these definitions can empower families to make informed decisions about their finances, ensuring they take full advantage of available tax benefits. By understanding Taxable Income, families can identify specific financial strategies, like maximizing deductions and credits, that can significantly enhance their monetary well-being. As you navigate the complexities of financial planning, this knowledge becomes invaluable for optimizing your tax obligations and securing a brighter financial future.
Imagine if you could unlock potential savings just by understanding these key concepts. Together, we can explore these financial avenues, ensuring that you and your family are well-prepared for the journey ahead. Remember, we’re here for you, guiding you through every step of this important process.

Calculate Your Modified Adjusted Gross Income (MAGI)
Calculating your Modified Adjusted Gross Income (MAGI) can feel daunting, especially when you wonder if modified adjusted gross income is the same as taxable income, but we’re here to help you through it. Follow these simple steps:
-
Start with your Adjusted Gross Income (AGI): You can find this important figure on your tax return, typically on line 11 of Form 1040. AGI represents your taxable income after subtracting above-the-line deductions from your gross income, which raises the question: is modified adjusted gross income the same as taxable income?
-
Add back specific deductions: Think of any deductions that weren’t included in your AGI, such as:
- Student loan interest deduction
- Tuition and fees deduction
- Foreign earned income exclusion
- Other tax-exempt income
-
Add these amounts together: This total will give you your Modified Adjusted Gross Income. For instance, if your AGI is $80,000 and you have $2,000 in student loan interest, your MAGI would be $82,000.
Understanding whether modified adjusted gross income is the same as taxable income is essential for families, as it influences your eligibility for various tax benefits. For example, many households rely on the student loan interest deduction. Individual taxpayers with a MAGI between $85,000 and $100,000 can deduct up to $2,500 of student loan interest. This deduction can significantly support your financial planning, especially when managing education expenses. Additionally, your MAGI plays a crucial role in determining eligibility for healthcare waivers and incentives under the Affordable Care Act, making it vital for families exploring tax benefits and healthcare options.
Consider the story of Allison and Brian, who partnered with Bright Advisers to enhance their tax situation. By understanding whether modified adjusted gross income is the same as taxable income, they were able to secure their children’s education funding and even plan for an earlier retirement. Through effective management of their MAGI, they implemented strategies that maximized their financial potential. As Ines Zemelman, an accredited enrolled agent, wisely points out, “The primary distinction between AGI and the modified version is that the latter includes some of the deductions removed when calculating AGI.”
By grasping and calculating your modified adjusted gross income, you can navigate your tax situation more effectively and improve your financial strategies. Remember, together, we can navigate this journey towards a more secure future for your family.

Compare MAGI and Taxable Income: Key Differences
Understanding whether modified adjusted gross income is the same as taxable income is essential for families as they navigate their financial strategies. Modified Adjusted Gross Income (MAGI) plays a vital role in determining eligibility for various tax benefits, such as contributions to Roth IRAs and premium tax credits under the Affordable Care Act. Imagine if you could contribute to a Roth IRA in 2025—married couples filing jointly can do so if their MAGI is below $236,000, while individual filers need to stay under $150,000 to qualify.
On the other hand, Taxable Income reflects the amount that is subject to taxation after considering deductions and exemptions. This figure directly impacts the tax owed to the IRS. For instance, a family with an adjusted gross income that qualifies for the Earned Income Tax Credit (EITC) might find that their Taxable Income is significantly reduced due to eligible deductions, such as contributions to retirement accounts or unreimbursed business expenses.
It’s important to understand whether modified adjusted gross income is the same as taxable income and how these concepts interact. This knowledge can empower families to enhance their financial planning. By grasping how these figures influence eligibility for tax advantages, families can make informed choices that improve their overall economic well-being. Take, for example, families like Emily and Mark, who worked with Bright Advisers. They gained clarity on their financial situation and crafted a comprehensive plan that included strategies for tax optimization, giving them the freedom to decide whether to continue working.
As families prepare for 2025, it’s crucial to recognize that MAGI calculations can vary depending on specific programs and situations. Seeking advice from tax experts or using reliable resources can help manage these complexities effectively. Together, we can navigate this journey, ensuring that your family’s financial future is secure and thriving.

Optimize Your MAGI for Tax Efficiency
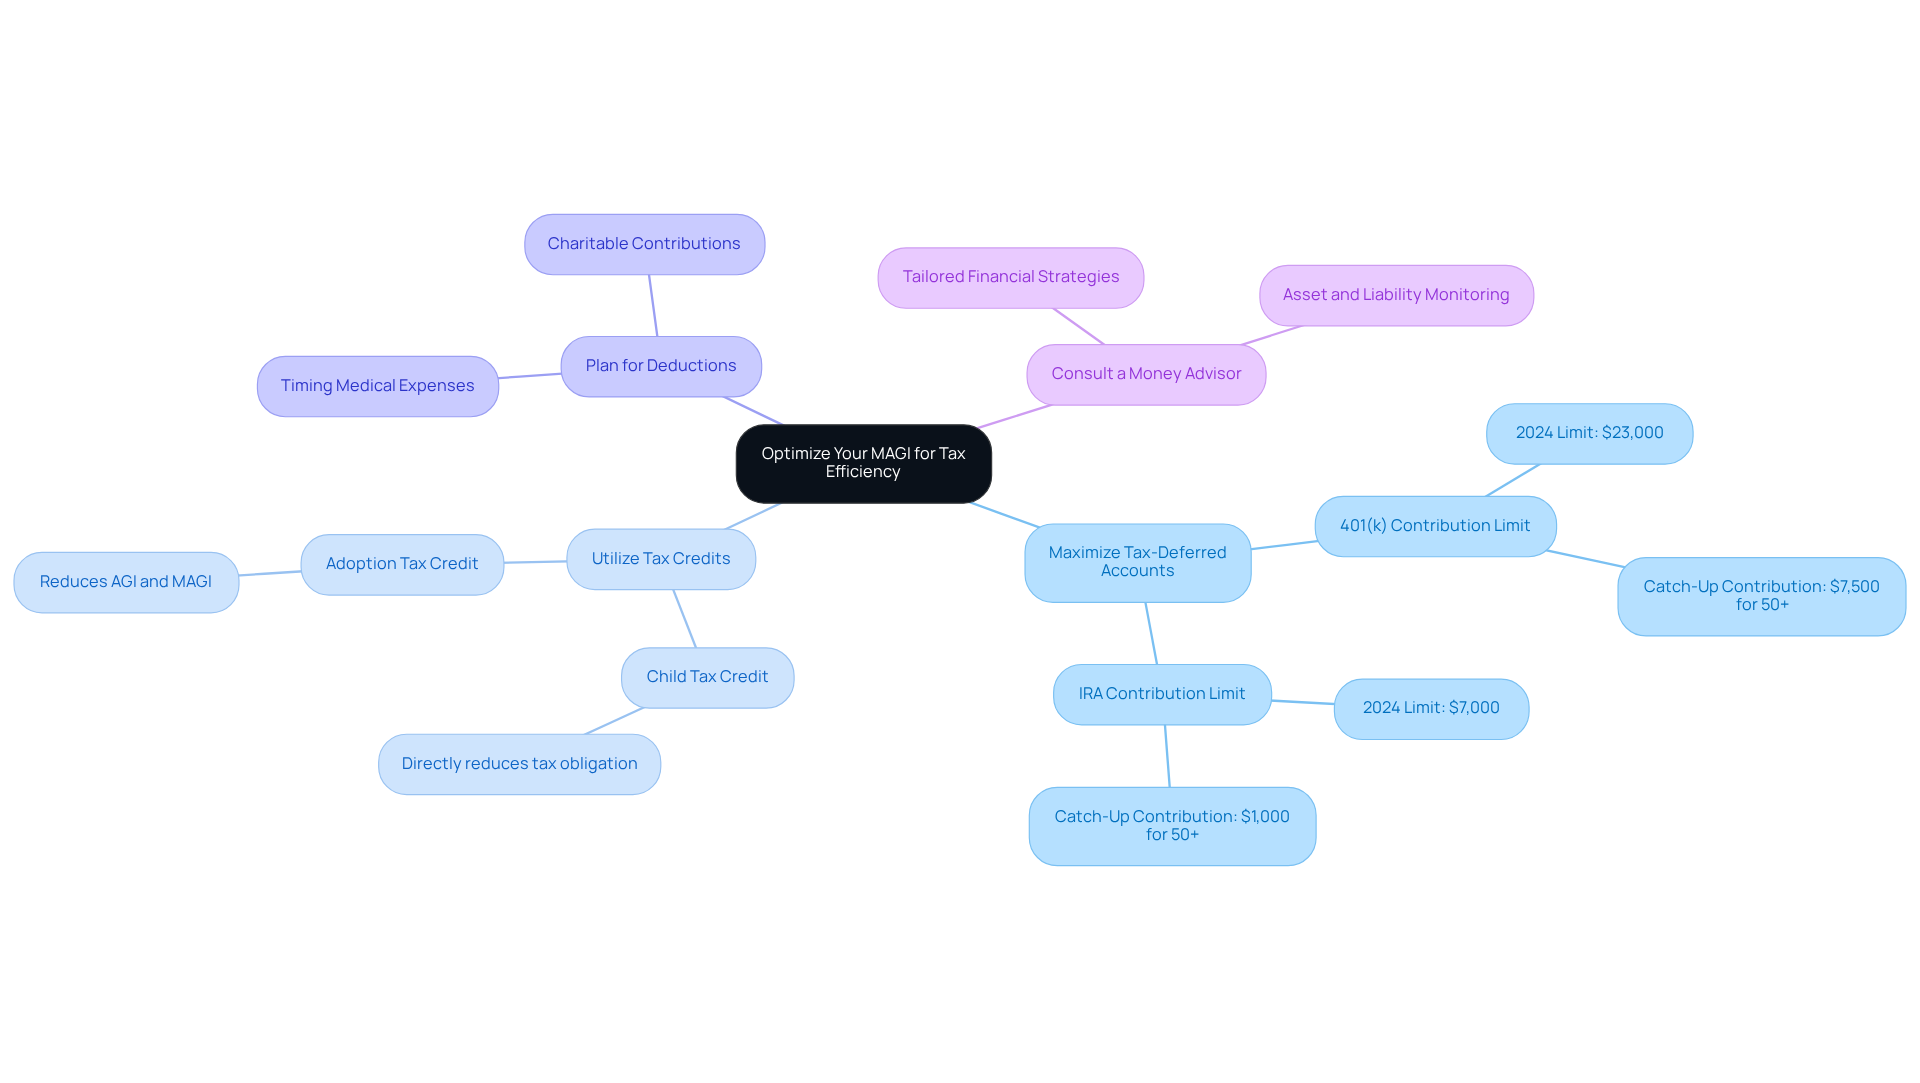
To optimize your Modified Adjusted Gross Income (MAGI) for tax efficiency, consider implementing these thoughtful strategies that can support your family’s financial well-being:
- Maximize Tax-Deferred Accounts: Imagine contributing to retirement accounts like 401(k)s or IRAs. This effective method not only decreases your Adjusted Gross Income (AGI) but also leads to the question: is modified adjusted gross income the same as taxable income? In 2024, for instance, the contribution limit for IRAs is $7,000, with an additional $1,000 catch-up contribution for those aged 50 or older. This can significantly impact your taxable income, helping you secure a brighter future for your loved ones.
- Utilize Tax Credits: It’s important to explore accessible tax credits that can directly reduce your tax obligation without affecting your MAGI. Families with young children can benefit from credits like the Child Tax Credit, which can lead to substantial savings, allowing you to invest more in your family’s needs.
- Plan for Deductions: Be strategic about your deductions. If you can control the timing of certain expenses, consider shifting them to a year when they will have a greater impact on your MAGI. For example, timing medical expenses or charitable contributions can maximize their tax benefits, ensuring your family receives the support it deserves.
- Consult a Money Advisor: Working with a financial expert can provide tailored approaches for your household’s finances. Together, you can make the most of your tax planning and utilize available resources effectively. At Bright Advisers, we offer services like asset and liability monitoring and cash flow forecasts, helping you align your financial goals with effective tax strategies.
By embracing these strategies, families can manage their modified adjusted gross income more effectively and understand if modified adjusted gross income is the same as taxable income, potentially qualifying for additional assistance and avoiding higher Medicare premiums. Understanding and optimizing MAGI is crucial for securing a stable financial future for your family. Remember, we’re here for you. For personalized assistance, contact Bright Advisers at (714) 987-2967 or email hello@brightadvisers.com.
Conclusion
Understanding the distinction between Modified Adjusted Gross Income (MAGI) and Taxable Income is essential for effective financial planning. Imagine if you could unlock valuable tax benefits simply by knowing the difference. While MAGI serves as a key determinant for eligibility in various tax credits, Taxable Income represents the amount subject to taxation after accounting for deductions and exemptions. Recognizing these differences empowers families to make informed decisions that can lead to significant tax savings and improved financial health.
Throughout this article, we’ve outlined the process of calculating MAGI, emphasizing its vital role in determining eligibility for valuable tax credits, such as those related to education and healthcare. Consider the benefits of maximizing contributions to tax-deferred accounts and planning deductions strategically. These insights illustrate how families can navigate their tax situations more effectively, leveraging available resources to secure a better financial future.
In conclusion, understanding MAGI versus Taxable Income is about more than definitions; it’s about optimizing your financial strategies and maximizing your tax benefits. We encourage families to take proactive steps in calculating their MAGI and utilizing available tax credits and deductions. By doing so, you can enhance your financial well-being and ensure a more secure future for yourselves and your loved ones. Together, we can navigate this journey toward financial stability.
Frequently Asked Questions
What is Modified Adjusted Gross Income (MAGI)?
Modified Adjusted Gross Income (MAGI) is a key metric that helps determine eligibility for various tax benefits and credits. It starts with your Adjusted Gross Income (AGI) and adds back certain deductions, such as student loan interest and foreign earned income, to give a clearer picture of your financial situation.
How does Taxable Income differ from MAGI?
Taxable Income is the portion of your income that is subject to taxation after accounting for all applicable deductions and exemptions. Unlike MAGI, which includes certain deductions, Taxable Income reflects the income that will actually be taxed.
Why is it important to understand the difference between MAGI and Taxable Income?
Understanding the difference between MAGI and Taxable Income is crucial for effective tax planning. Many families, especially those with higher incomes, may miss out on tax savings opportunities if they do not grasp how these two metrics affect their eligibility for tax credits and benefits.
What tax credits are influenced by MAGI?
MAGI is essential for determining eligibility for tax credits such as the Child Tax Credit and various education-related credits. The eligibility thresholds are typically set at $80,000 for single filers and $160,000 for married couples filing jointly.
How can understanding MAGI and Taxable Income benefit families?
By understanding MAGI and Taxable Income, families can make informed financial decisions, identify strategies to maximize deductions and credits, and ultimately enhance their monetary well-being and tax savings.
List of Sources
- Define Modified Adjusted Gross Income (MAGI) and Taxable Income
- What Is a Modified Adjusted Gross Income? The MAGI Explained (https://efile.com/what-is-modified-adjusted-gross-income)
- What is Modified Adjusted Gross Income (MAGI)? (https://totalbenefits.net/what-is-modified-adjusted-gross-income-magi)
- 130 Inspirational Quotes About Taxes (https://inc.com/geoffrey-james/130-inspirational-quotes-about-taxes.html)
- What Is Modified Adjusted Gross Income (MAGI)? – NerdWallet (https://nerdwallet.com/article/taxes/modified-adjusted-gross-income-magi)
- Modified Adjusted Gross Income (MAGI): Calculating and Using It (https://investopedia.com/terms/m/magi.asp)
- Calculate Your Modified Adjusted Gross Income (MAGI)
- What Is Modified Adjusted Gross Income (MAGI)? (https://smartasset.com/taxes/what-is-modified-adjusted-gross-income)
- What is Modified Adjusted Gross Income (MAGI) and how to calculate it? (https://taxesforexpats.com/articles/financial-planning/modified-adjusted-gross-income-magi.html)
- How to Calculate Your Modified Adjusted Gross Income | City National Bank (https://cnb.com/personal-banking/insights/calculate-magi.html)
- What Is Modified Adjusted Gross Income (MAGI)? – NerdWallet (https://nerdwallet.com/article/taxes/modified-adjusted-gross-income-magi)
- Modified Adjusted Gross Income (MAGI): Calculating and Using It (https://investopedia.com/terms/m/magi.asp)
- Compare MAGI and Taxable Income: Key Differences
- What Is Modified Adjusted Gross Income (MAGI)? – NerdWallet (https://nerdwallet.com/article/taxes/modified-adjusted-gross-income-magi)
- 10 Tax Breaks Every Middle-Class Family Should Take Advantage Of in 2025 (https://nasdaq.com/articles/10-tax-breaks-every-middle-class-family-should-take-advantage-2025)
- Modified Adjusted Gross Income (MAGI): Calculating and Using It (https://investopedia.com/terms/m/magi.asp)
- Income Definitions for Marketplace and Medicaid Coverage – Beyond the Basics (https://healthreformbeyondthebasics.org/key-facts-income-definitions-for-marketplace-and-medicaid-coverage)
- Modified Adjusted Gross Income under the Affordable Care Act – UPDATED WITH INFORMATION FOR COVID-19 POLICIES – UC Berkeley Labor Center (https://laborcenter.berkeley.edu/modified-adjusted-gross-income-under-the-affordable-care-act)
- Optimize Your MAGI for Tax Efficiency
- American Retirement and Tax-Preferred Savings Accounts, Tax Year 2018 (https://taxfoundation.org/data/all/federal/401k-ira-retirement-savings-accounts)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- Retirement and Investments (https://federalreserve.gov/publications/2024-economic-well-being-of-us-households-in-2023-retirement-investments.htm)
- Effective Strategies: How to Reduce MAGI for High Earners and Lower Premiums – IRMAA Certified Planner (https://irmaacertifiedplanner.com/how-to-reduce-magi)
- 68 Important Retirement Plan Statistics For 2024 – Carry (https://carry.com/learn/retirement-plan-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading