

Overview
Understanding the differences between tax-deferred and pre-tax contributions is crucial for your family’s financial well-being. Tax-deferred income allows your earnings to grow without immediate taxation, giving you the chance to build wealth over time. On the other hand, pre-tax contributions reduce your taxable income for the year they are made, offering immediate relief that can ease your financial burden.
Imagine if you could make the most of your earnings while also ensuring your family’s future. This understanding can significantly impact your overall financial strategy and wealth accumulation. Tax-deferred options focus on delaying tax payments, allowing you to invest in your family’s goals, while pre-tax options provide the immediate support you may need in your day-to-day life.
We’re here for you as you navigate these important decisions. By grasping these concepts, you can make informed choices that align with your family’s values and aspirations. Together, we can explore how these options fit into your financial plan, ensuring you have the support you need for a brighter future.
Key Highlights:
- Tax-deferred income allows earnings to grow without immediate taxation, benefiting long-term wealth accumulation.
- Pre-tax contributions reduce taxable income for the year they are made, leading to lower tax bills.
- 401(k) and IRA accounts are examples of tax-deferred options, with specific contribution limits and potential employer matching.
- Tax-deferred contributions focus on delaying tax payments, while pre-tax contributions emphasise immediate tax relief.
- Understanding tax implications is crucial for effective retirement planning, especially for families managing their finances.
- Factors like tax bracket considerations, investment growth, and withdrawal flexibility can influence the choice between tax-deferred and pre-tax options.
- Assessing current financial status, setting clear goals, and consulting with a financial expert are important steps for families in optimising their financial strategies.
Introduction
Understanding the intricacies of tax planning can feel overwhelming, especially for families striving to secure their financial futures. Imagine navigating a path filled with options and decisions, where tax-deferred and pre-tax contributions stand as key strategies that can profoundly influence wealth accumulation. Yet, these concepts are often misunderstood.
This article gently explores the critical differences between these strategies, revealing how each can shape a family’s financial landscape. As you consider your options, it’s important to understand how you can determine the best approach to maximize savings while minimizing tax liabilities. Together, we can navigate this journey, ensuring that your family’s financial goals are met with care and support.
Define Tax Deferred and Pre-Tax Concepts
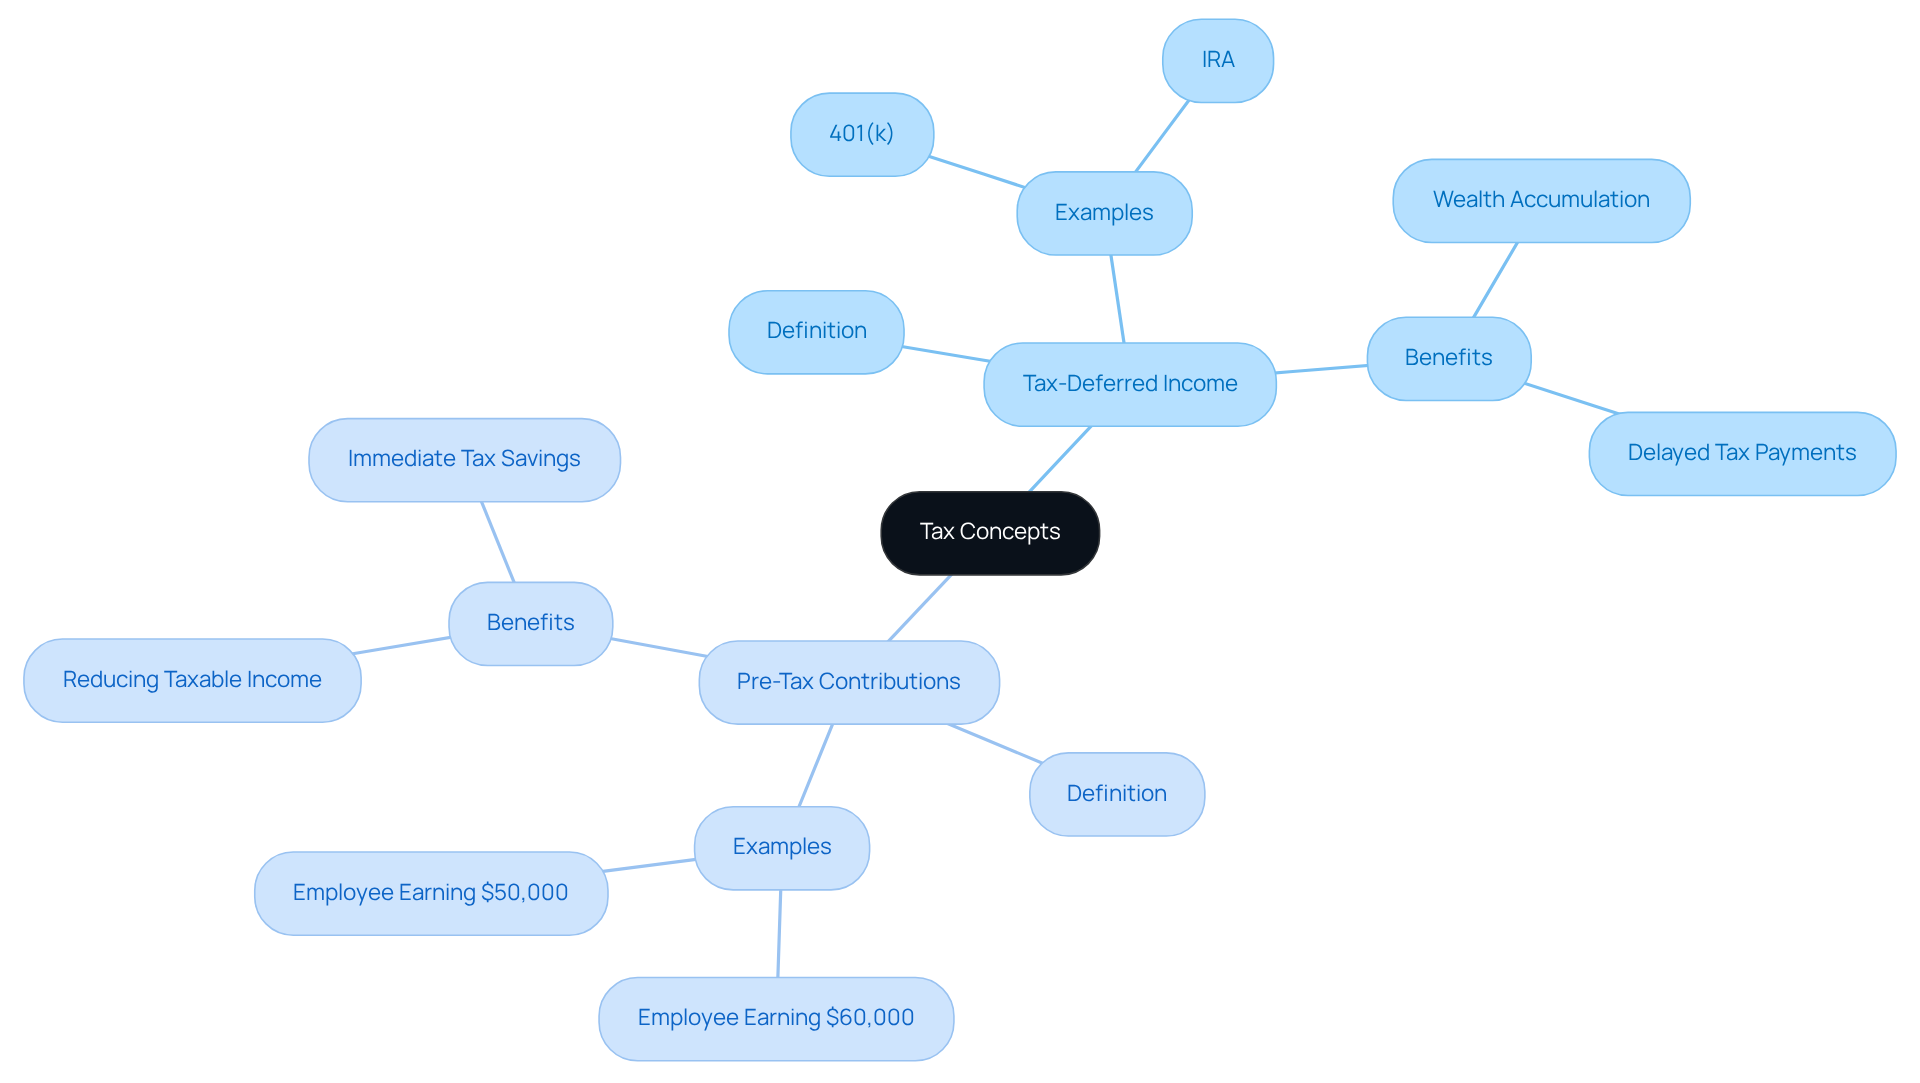
Tax-deferred income refers to earnings or investment gains that aren’t taxed until a later date. This allows your investments to grow without immediate tax implications, which can lead to greater wealth accumulation over time. For families like Allison and Brian, who worry about missing out on financial opportunities due to inadequate tax planning, understanding this concept is particularly important. Think of retirement accounts like 401(k)s and IRAs, where fees come into play upon withdrawal. In 2025, the limit for a 401(k) is $23,500, offering significant potential for tax-deferred growth.
Now, let’s talk about pre-deduction contributions. These are amounts taken from your gross earnings before calculations, effectively reducing your taxable income for the year. This can lead to a lower overall tax bill, which is essential for young families eager to maximize their resources. For instance, if an employee earning $60,000 contributes 10% pre-tax to their 401(k), they set aside $6,000 before taxes, lowering their taxable income to $54,000. Similarly, a worker making $50,000 who contributes 6% pre-tax could receive an additional $1,500 from their employer as a match, significantly boosting their future savings.
While both tax-deferred and pre-tax contributions offer advantages, the question of whether tax-deferred is the same as pre-tax highlights their differences in focus. The concept of tax-deferred income focuses on the timing of tax payments, while pre-tax contributions emphasize the immediate reduction of taxable income. Investment consultants often highlight the importance of understanding these concepts for effective retirement planning, especially for young parents managing their financial futures. As Chris Davin wisely notes, “If you have a budget that you are adhering to and if you are saving a sufficient percentage of your income, you truly don’t need to concern yourself too much with Roth vs. tax deferred.”
This choice between tax-deferred and pre-tax payments can greatly impact long-term financial outcomes, particularly for families like Allison and Brian who seek professional guidance to enhance their wealth accumulation. Remember, we’re here to support you on this journey. Together, we can navigate the complexities of financial planning and ensure a brighter future for your family.
Differentiate Between Tax Deferred and Pre-Tax Contributions
To differentiate between tax-deferred and pre-tax contributions, let’s explore these concepts together:
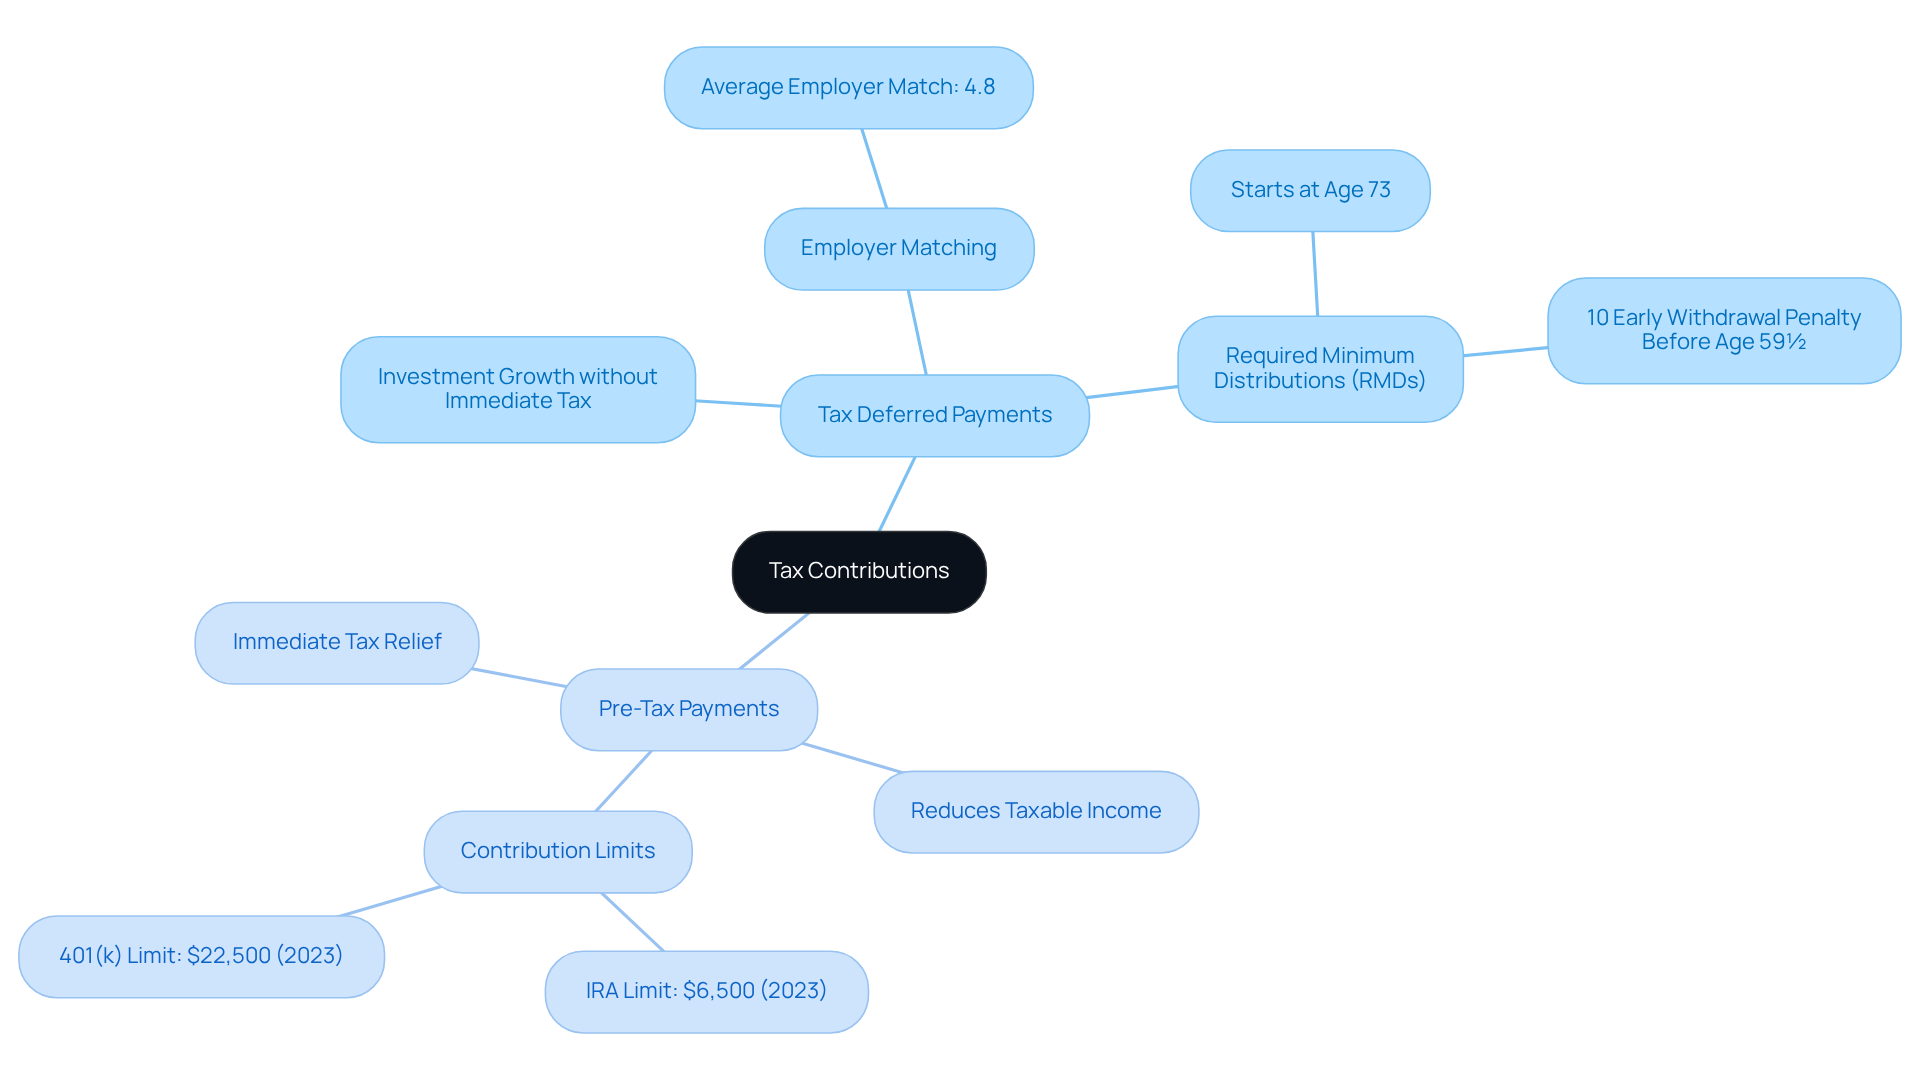
Tax Deferred Payments: Often linked to pension accounts, tax-deferred payments allow your investments to grow without immediate taxation. Imagine contributing to a 401(k); this means you won’t pay taxes on that money until you withdraw it, usually in your later years. This strategy can significantly boost your savings potential, as your investments compound without the burden of annual taxes. Plus, many employers offer matching funds, which can further enhance your retirement savings. For families like Allison and Brian, understanding these contributions is vital to maximizing their financial situation and ensuring they don’t miss out on opportunities for wealth accumulation.
Pre-Tax Payments: These contributions directly reduce your taxable income for the year they are made. For instance, when you contribute to a traditional IRA, that amount is deducted from your gross income, effectively lowering your tax liability for that year. In 2023, individuals can contribute up to $6,500 to an IRA, with those aged 50 and older allowed an additional catch-up contribution. As Marianne Hayes wisely noted, “Tax-deferred accounts enable you to save for the future while lowering your taxable income today,” highlighting the dual benefits of these strategies.
While both tax-deferred payments and pre-tax payments offer valuable tax advantages, a common question is whether tax deferred is the same as pre-tax, as they serve different purposes. Tax-deferred contributions focus on delaying tax payments until later in life, potentially allowing for greater growth. In contrast, pre-tax contributions provide immediate tax relief, which can be beneficial for managing current cash flow. It’s also important to remember that required minimum distributions (RMDs) must begin by age 73 for most tax-deferred savings accounts, and withdrawing funds from these accounts before age 59½ may incur a 10% early withdrawal penalty. Understanding these differences is crucial for planning for your future and optimizing your financial strategy, especially for young parents who want to secure their family’s economic well-being.
Together, we can navigate these financial decisions, ensuring you have the support and knowledge to make the best choices for your family.
Evaluate the Financial Implications of Each Option
When considering the financial implications of tax-deferred versus pre-tax contributions, it’s essential to reflect on several key factors that can impact your family’s future:
-
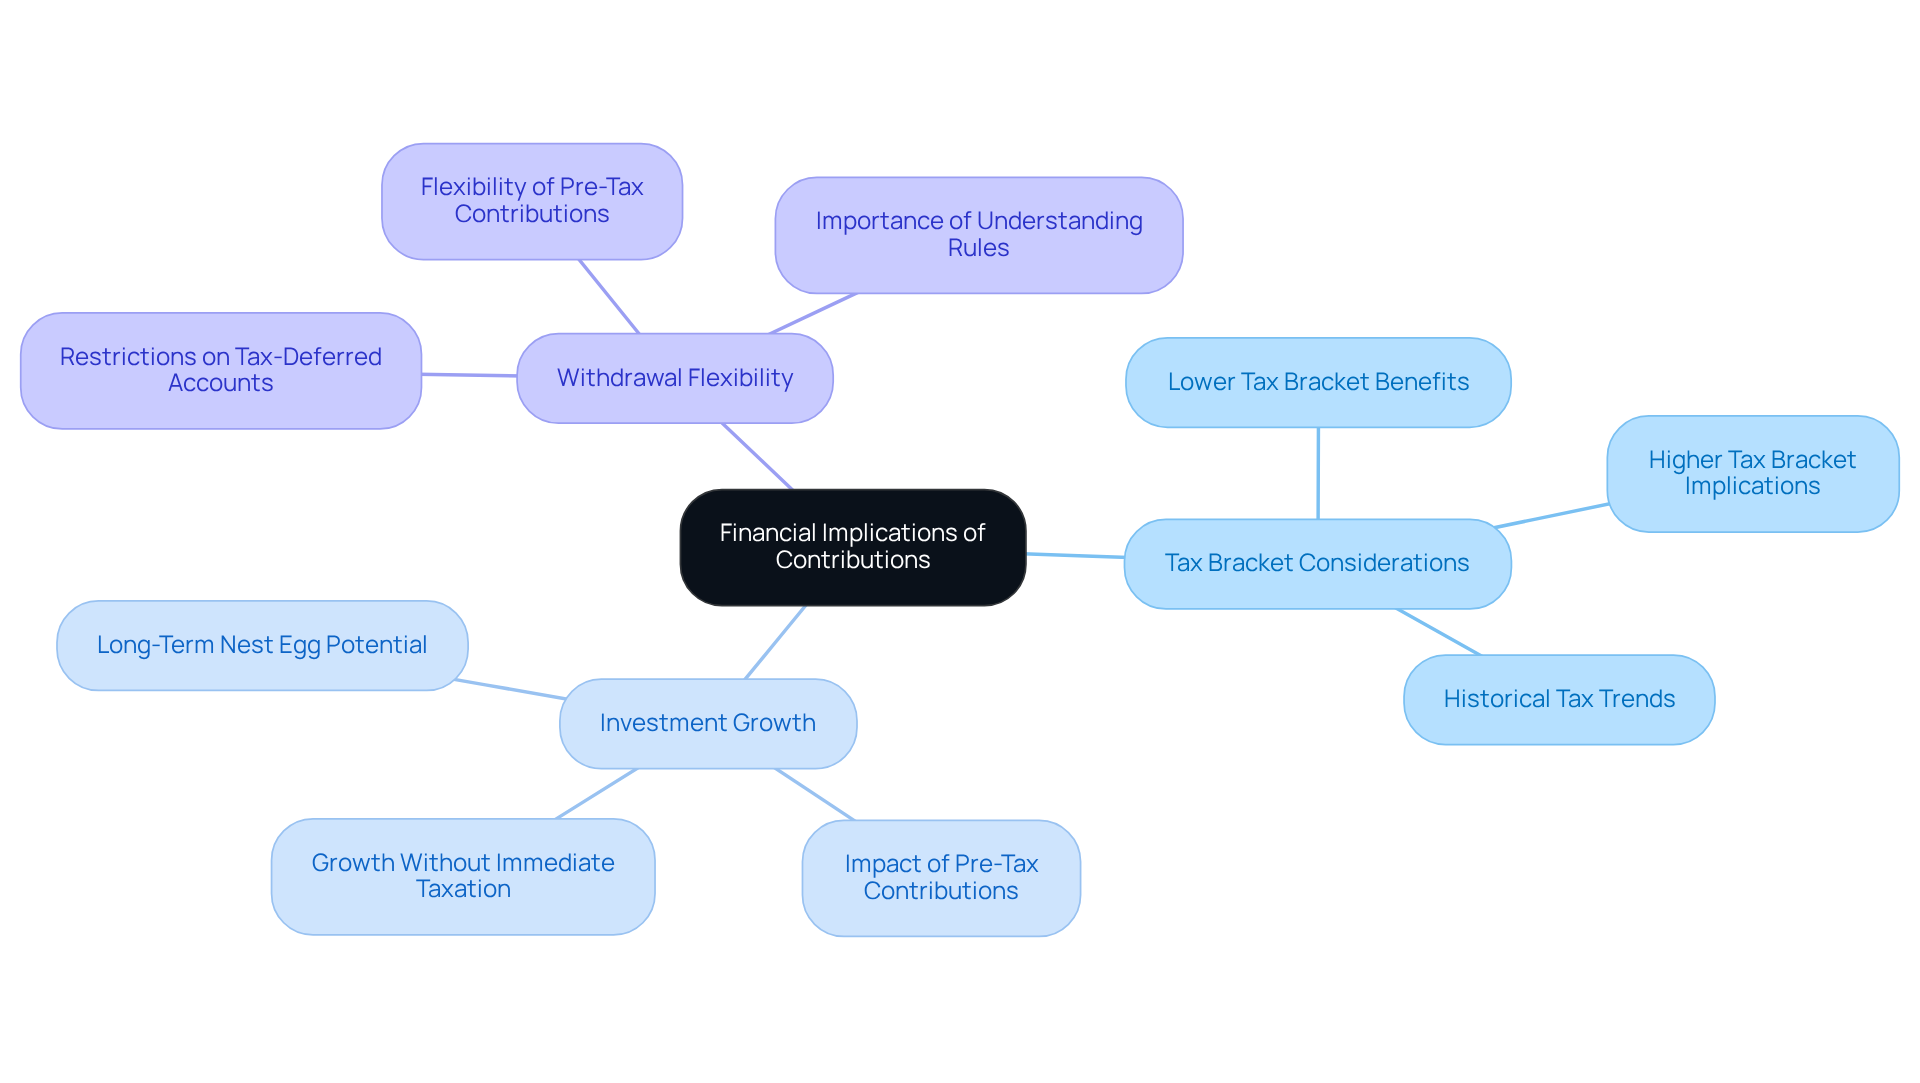
Tax Bracket Considerations: Imagine if you could plan for a more secure retirement by anticipating your tax bracket. If you foresee being in a lower income bracket during retirement, tax-advantaged accounts might be a wise choice, allowing you to withdraw funds at a reduced rate. Conversely, if you believe you’ll be in a higher tax bracket, understanding how pre-tax contributions is tax deferred the same as pre tax could offer immediate tax savings that benefit your family in the short term. It’s worth noting that historical trends show a significant decrease in the top federal marginal tax bracket, from over 90% in the 1950s to 37% today, which might influence your decision-making process.
-
Investment Growth: Picture your investments growing without the burden of immediate taxation. Tax-deferred accounts allow for this, potentially creating a larger nest egg over time. On average, these accounts can significantly enhance your savings. While pre-tax contributions allow for growth, it’s important to consider if is tax deferred the same as pre tax, since taxes due upon withdrawal could ultimately lessen your overall returns.
-
Withdrawal Flexibility: It’s important to understand that tax-deferred accounts often come with restrictions on withdrawals, which may limit your access to funds without incurring penalties. In contrast, pre-tax contributions might offer greater flexibility, depending on the specific account type. Knowing these rules is vital for effective retirement planning, ensuring you can support your family when it matters most.
By thoughtfully evaluating these factors, you can align your financial strategies with your long-term family objectives, paving the way for a more secure economic future. Remember, we’re here for you as you navigate these important decisions together.
Assess Your Financial Situation and Goals
To effectively assess your financial situation and goals, follow these steps:
-
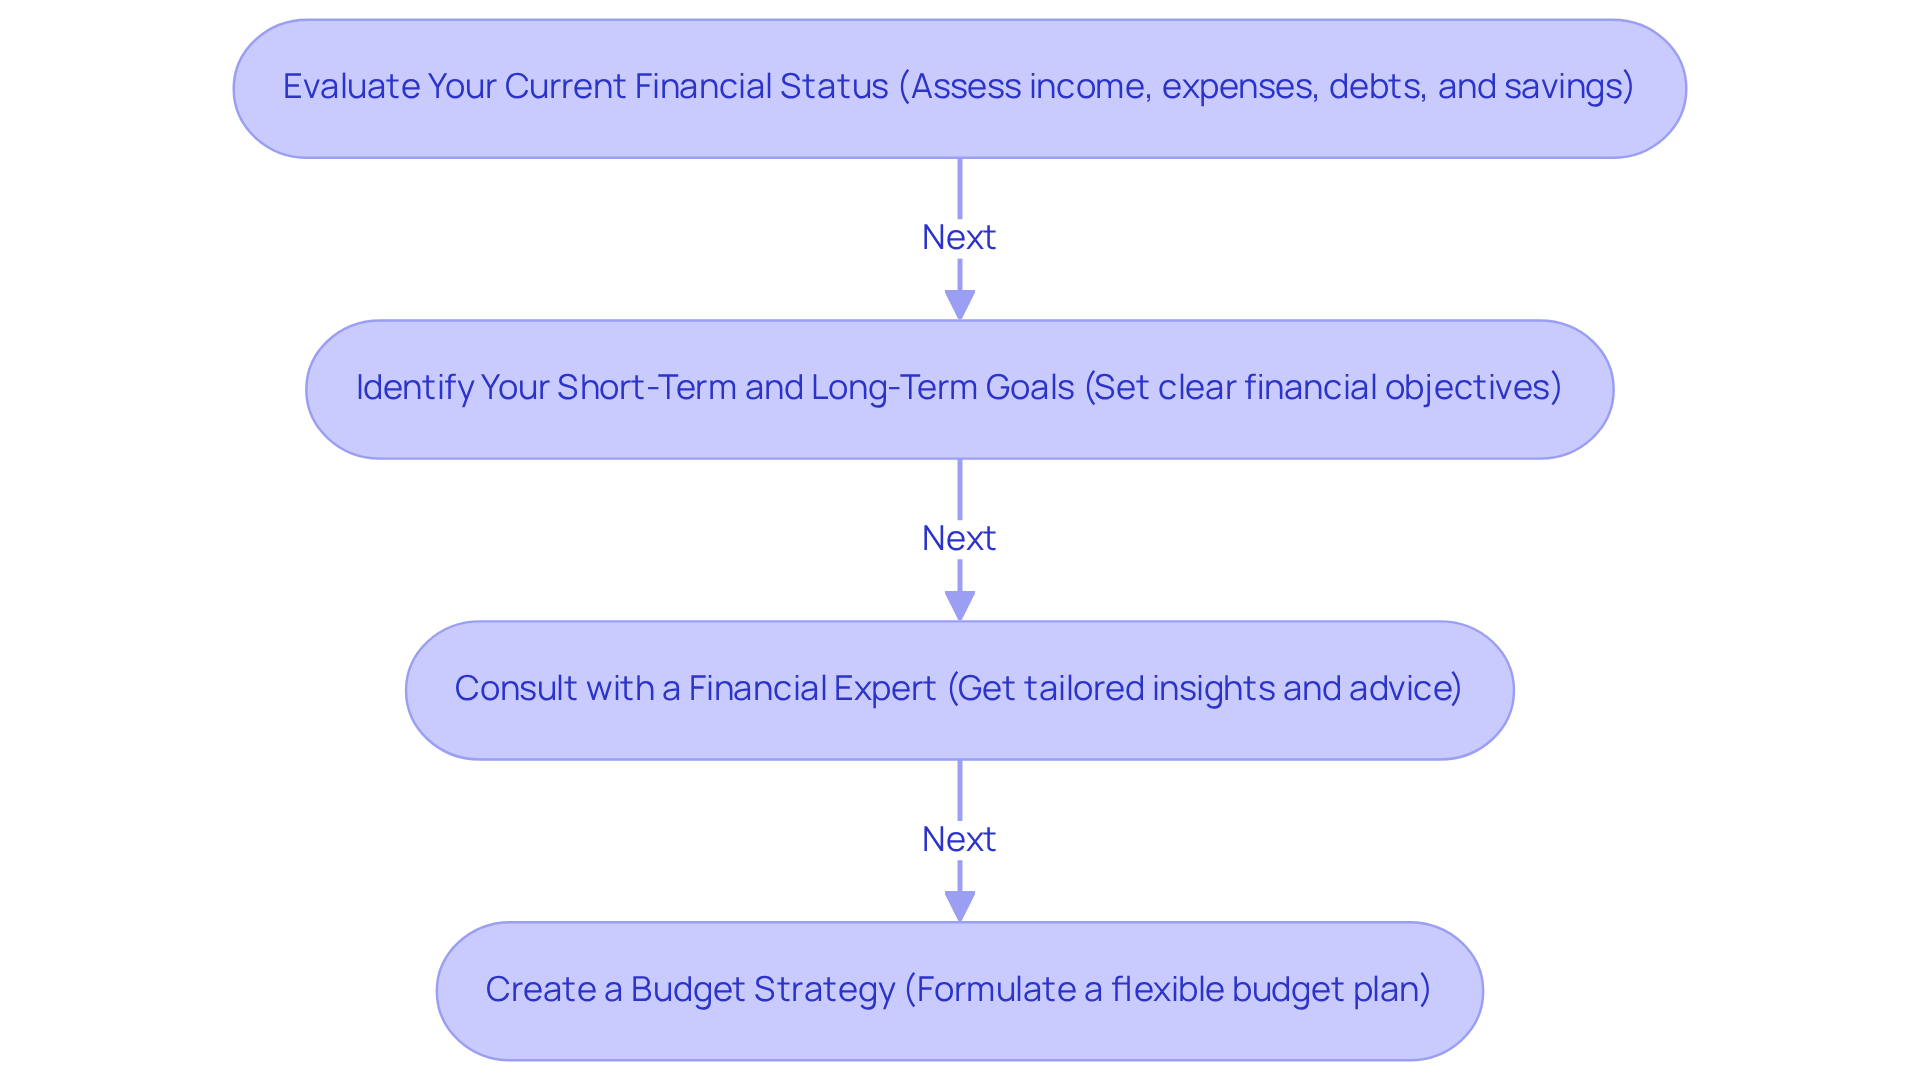
Evaluate Your Current Financial Status: Begin by taking stock of your income, expenses, debts, and savings. Understanding your present economic environment is essential for making informed choices. Imagine if you could grasp your financial landscape clearly—this is especially vital for families with young children, who often face unique economic challenges.
-
Identify Your Short-Term and Long-Term Goals: Consider what you want to achieve financially in the next few years versus in the long run. Are you saving for a home, your children’s education, or retirement? Establishing clear objectives helps prioritize your monetary efforts. As money advisors often say, “A budget directs your funds on their path instead of pondering where they disappeared.”
-
Consult with a Financial Expert: If you’re uncertain about your options, consulting with a financial expert can offer tailored insights based on your situation. They can assist you in understanding the intricacies of tax-deferred and pre-tax payments, particularly whether is tax deferred the same as pre tax, ensuring you maximize your resources. Remember, as Warren Buffett advises, “The stock market is designed to transfer money from the active to the patient.”
-
Create a Budget Strategy: Based on your evaluation, formulate a budget strategy that includes your objectives and suitable funding methods. This plan should be flexible and adaptable as your circumstances change. Effective budgeting is crucial for families, especially considering the average savings rates for households with young children, which can often fall short of ideal levels.
By taking the time to assess your financial situation and goals, you can make more informed decisions about whether is tax deferred the same as pre tax contributions. Together, we can navigate this journey towards a more secure financial future.
Conclusion
Understanding the distinctions between tax-deferred and pre-tax contributions is essential for effective financial planning. Imagine if you could secure your family’s future while managing your income and investments wisely. These two concepts, while related, serve different purposes. Tax-deferred income allows you to postpone tax payments, enabling your investments to grow without immediate taxation. On the other hand, pre-tax contributions reduce your taxable income now, providing immediate financial relief.
For families aiming to build a secure financial future, grasping these differences can lead to more informed decisions that align with your long-term goals. Throughout this guide, we’ve shared key insights regarding the implications of these financial strategies. Tax-deferred accounts, such as 401(k)s and IRAs, offer the potential for significant growth over time, while pre-tax contributions can provide immediate tax savings.
It’s important to evaluate your current financial situation, understand your goals, and consult with financial experts. These crucial steps will help you determine the best approach for your family. Ultimately, the choice between tax-deferred and pre-tax contributions can significantly influence your financial trajectory. By taking the time to assess your options and align them with your objectives, families can pave the way for a more secure economic future.
As you navigate these decisions, remember that informed planning today can lead to greater wealth accumulation tomorrow. We’re here for you, ensuring a brighter financial outlook for you and your loved ones. Together, we can navigate this journey.
Frequently Asked Questions
What is tax-deferred income?
Tax-deferred income refers to earnings or investment gains that are not taxed until a later date, allowing investments to grow without immediate tax implications.
Why is understanding tax-deferred income important for families?
Understanding tax-deferred income is crucial for families, like Allison and Brian, as it helps them avoid missing out on financial opportunities due to inadequate tax planning.
What are some examples of tax-deferred accounts?
Examples of tax-deferred accounts include retirement accounts such as 401(k)s and IRAs.
What is the contribution limit for a 401(k) in 2025?
The contribution limit for a 401(k) in 2025 is $23,500.
What are pre-deduction contributions?
Pre-deduction contributions are amounts taken from gross earnings before tax calculations, which effectively reduce taxable income for the year.
How do pre-tax contributions affect taxable income?
Pre-tax contributions lower an individual’s taxable income, potentially leading to a lower overall tax bill.
Can you provide an example of how pre-tax contributions work?
For instance, if an employee earning $60,000 contributes 10% pre-tax to their 401(k), they set aside $6,000 before taxes, reducing their taxable income to $54,000.
What is the difference between tax-deferred and pre-tax contributions?
Tax-deferred income focuses on the timing of tax payments, while pre-tax contributions emphasize the immediate reduction of taxable income.
Why is it important to understand tax-deferred and pre-tax concepts for retirement planning?
Understanding these concepts is essential for effective retirement planning, especially for young parents managing their financial futures.
What advice does Chris Davin offer regarding budgeting and saving?
Chris Davin advises that if you adhere to a budget and save a sufficient percentage of your income, you may not need to worry too much about the choice between Roth vs. tax-deferred options.
List of Sources
- Define Tax Deferred and Pre-Tax Concepts
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- Tax-Deferred vs. Roth Contributions: A Deep Dive | White Coat Investor (https://whitecoatinvestor.com/tax-deferred-vs-roth-contributions-a-deep-dive-359)
- Pre-Tax Contribution: (https://mployeradvisor.com/all-terms/pre-tax-contribution)
- Key 401(k) Statistics: Retirement Plans by the Numbers | ForUsAll Blog (https://forusall.com/401k-blog/401k-statistics)
- Average retirement savings by age | Fidelity (https://fidelity.com/learning-center/personal-finance/average-retirement-savings)
- Differentiate Between Tax Deferred and Pre-Tax Contributions
- American Retirement and Tax-Preferred Savings Accounts, Tax Year 2018 (https://taxfoundation.org/data/all/federal/401k-ira-retirement-savings-accounts)
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- Tax Deferred Pension and Retirement Savings Plans: The Short Breakdown (https://dechtmanwealth.com/insights/blog/tax-deferred-pension-and-savings-plans)
- What Is a Tax-Deferred Retirement Account? – Experian (https://experian.com/blogs/ask-experian/what-is-tax-deferred-retirement-account)
- Pretax vs. Roth 401(k) contributions: This lesser-known calculation could help you decide (https://cnbc.com/2025/10/07/pretax-vs-roth-401k-contributions.html)
- Evaluate the Financial Implications of Each Option
- Pre-tax vs. Roth 401(k): Deciding which to use for retirement is trickier than you think (https://cnbc.com/2023/02/11/how-to-decide-between-pre-tax-and-roth-401k-contributions.html)
- A new rule means some 401(k) contributions will no longer be tax-deferred. Here’s who will be affected | CNN Business (https://cnn.com/2025/10/02/business/401k-catchup-contributions-to-be-taxed)
- Why Pre-Tax Retirement Contributions Are Better Than Roth In Peak Earning Years (https://kitces.com/blog/pre-tax-retirement-contribution-roth-conversion-rmd-social-security)
- High earners could soon lose a tax break from this 401(k) change (https://cnbc.com/2025/10/10/401k-change-catch-up-contributions.html)
- Assess Your Financial Situation and Goals
- Financial Literacy Quotes (https://financialeducatorscouncil.org/financial-literacy-quotes)
- 200 Quotes About Money And Personal Finance To Inspire You (https://marriagekidsandmoney.com/20-empowering-quotes-about-money-and-personal-finance)
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- 100 Best Motivational Quotes About Finance to Boost Your Financial Goals in 2025 (https://acecloudhosting.com/blog/motivational-finance-quotes)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading