

Key Highlights
- Incentive Stock Options (ISOs) can only be granted to employees and have specific IRS criteria, including a maximum exercisable value of $100,000 per year.
- Non-Qualified Stock Options (NSOs) can be granted to a broader range of individuals, including employees, directors, and consultants, with no limits on the amount that can be granted.
- ISOs offer favourable tax treatment, allowing taxes to be deferred until shares are sold, potentially qualifying for lower long-term capital gains rates.
- Exercising ISOs may trigger the Alternative Minimum Tax (AMT), complicating tax planning for families.
- NSOs are taxed as ordinary income at the time of exercise, which can lead to immediate tax liabilities and impact budgeting strategies.
- Families should consider their long-term financial goals and the performance outlook of the company when choosing between ISOs and NSOs.
- Strategic tax planning, such as timing exercises in low-income years, can help minimise tax liabilities associated with stock options.
- Bright Advisers assists families in navigating stock options and developing financial strategies that align with their goals.
Introduction
Imagine feeling overwhelmed by the complexities of stock options while trying to secure your family’s future. Navigating the differences between Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs) can be challenging, especially for families like yours. It’s important to understand how these differences can shape your family’s financial future and tax obligations, particularly if you’re a high-income W-2 family with young children.
As you weigh your options, you might wonder: how do these stock options affect your family’s financial journey, and which choice aligns best with your long-term goals? Together, we’ll explore the key characteristics, tax implications, and strategic considerations of ISOs and NSOs, providing you with the insights needed to make informed decisions.
Define ISOs and NSOs: Key Characteristics and Eligibility
Navigating the world of stock options can feel overwhelming for families, especially when trying to make the best choices for their future. Companies may offer their employees two types of stock options, which are often compared in discussions about ISO vs NSO for executives.
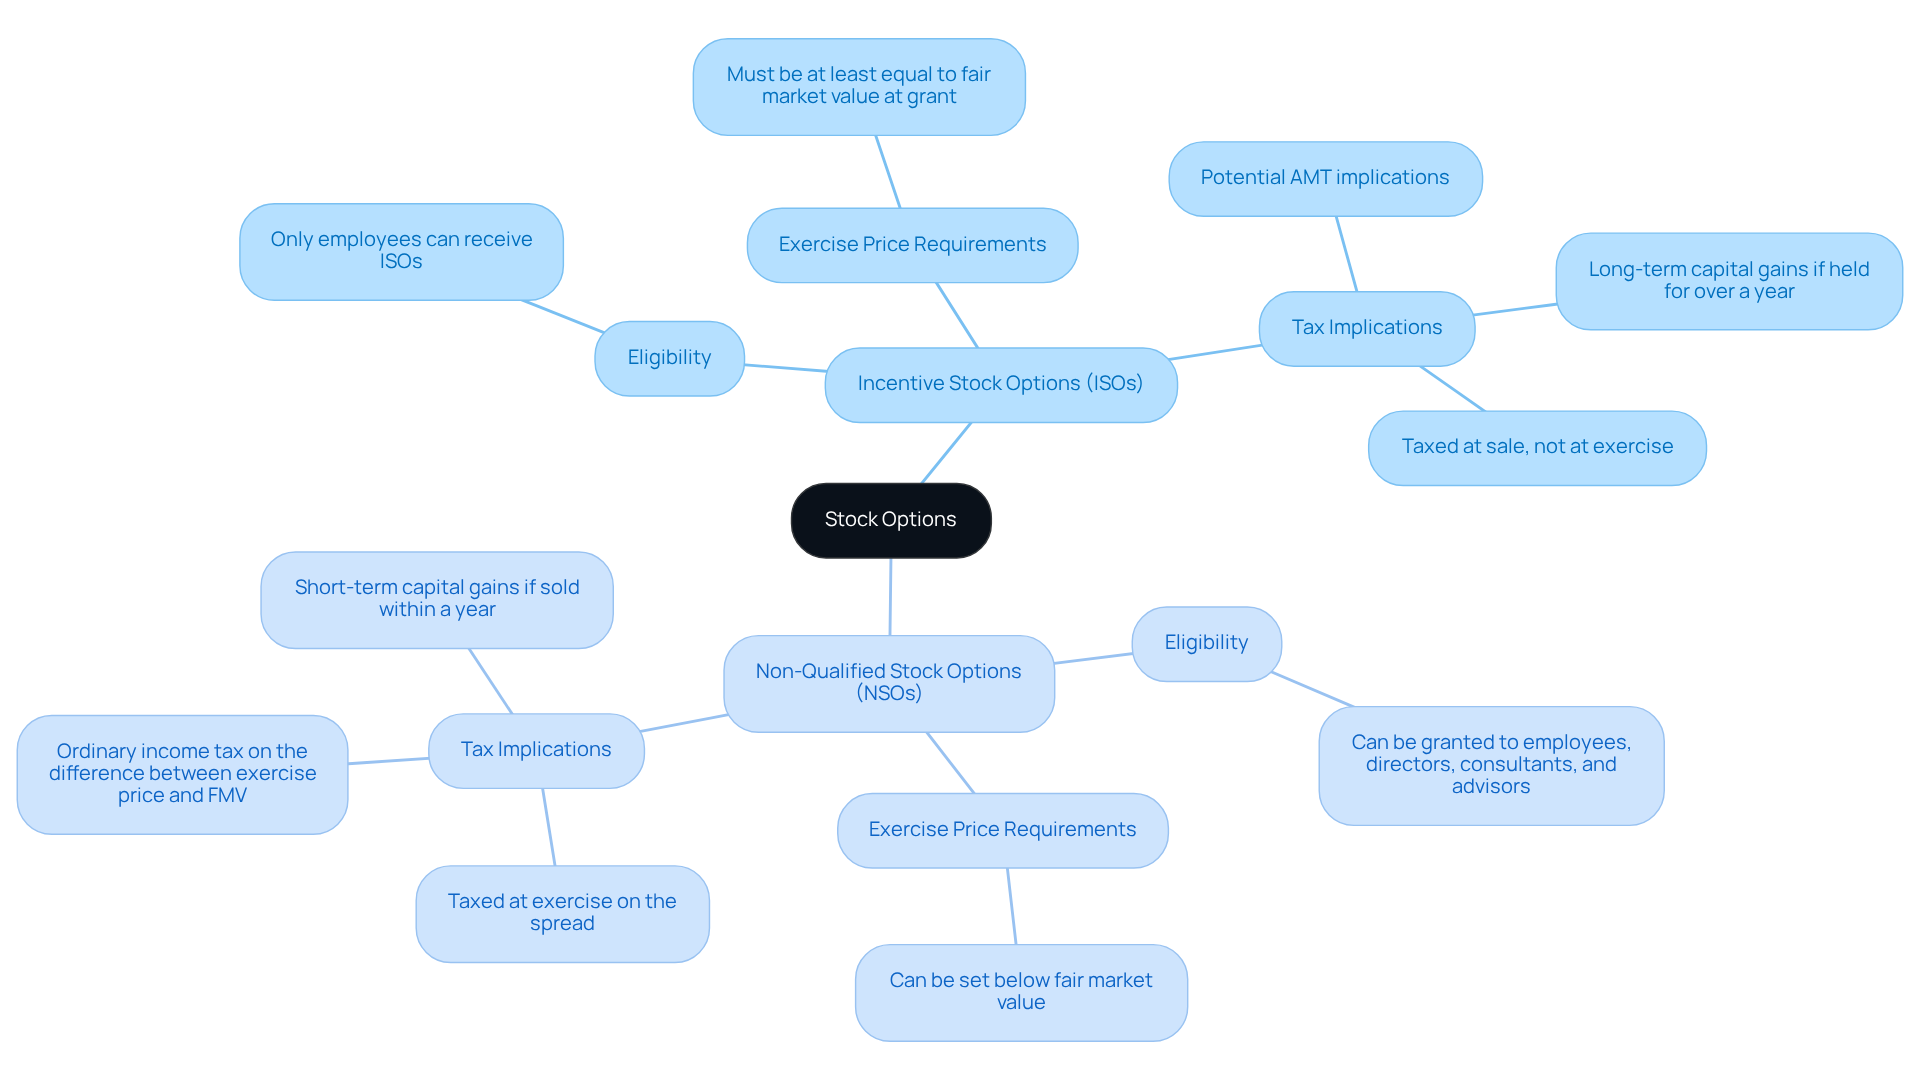
Stock options are designed with employees in mind and come with certain tax benefits. To qualify as an Incentive Stock Option (ISO), the option must meet specific criteria set by the IRS. For instance, only employees can receive ISOs, and the exercise price must be at least equal to the fair market value of the stock at the time of the grant. Additionally, stock options must be exercised within 10 years of the grant date, and there’s a limit of $100,000 on the value of ISOs that can become exercisable in any calendar year.
On the other hand, Non-Qualified Stock Options (NSOs) can be granted to a wider range of individuals, including employees, directors, consultants, and advisors. They offer more flexibility since they don’t have the same stringent requirements as ISOs. For example, NSOs can be granted to anyone, not just employees, and there are no limits on the amount that can be granted. The exercise price can also be set at any value, even below fair market value.
Understanding the differences in ISO vs NSO for executives is important for families as they consider how these options fit into their financial plans, particularly in relation to taxes and eligibility. Many families find the world of stock options confusing and overwhelming, particularly when trying to navigate the tax implications. For instance, if an employee exercises NSOs, they incur ordinary income tax on the difference between the exercise price and the current fair market value at the time of exercise. This tax responsibility can significantly impact budgeting strategies, especially for households with young kids planning their economic futures.
When families work with Bright Advisers, they can find the support they need to make sense of their financial planning. Bright Advisers emphasizes integrated tax planning strategies to assist families like Jay and Emma, who sought guidance to alleviate financial anxiety and allocate resources effectively, and Emily and Mark, who aimed for financial freedom. As you consider your options, remember that with the right guidance, you can turn confusion into clarity, ensuring your family’s financial future is bright and secure.
Analyze Tax Implications: ISOs vs NSOs
Understanding the tax implications of stock options can feel overwhelming for families, but it’s crucial for your financial peace of mind. The tax consequences of ISO vs NSO for executives can significantly impact your family’s financial planning.
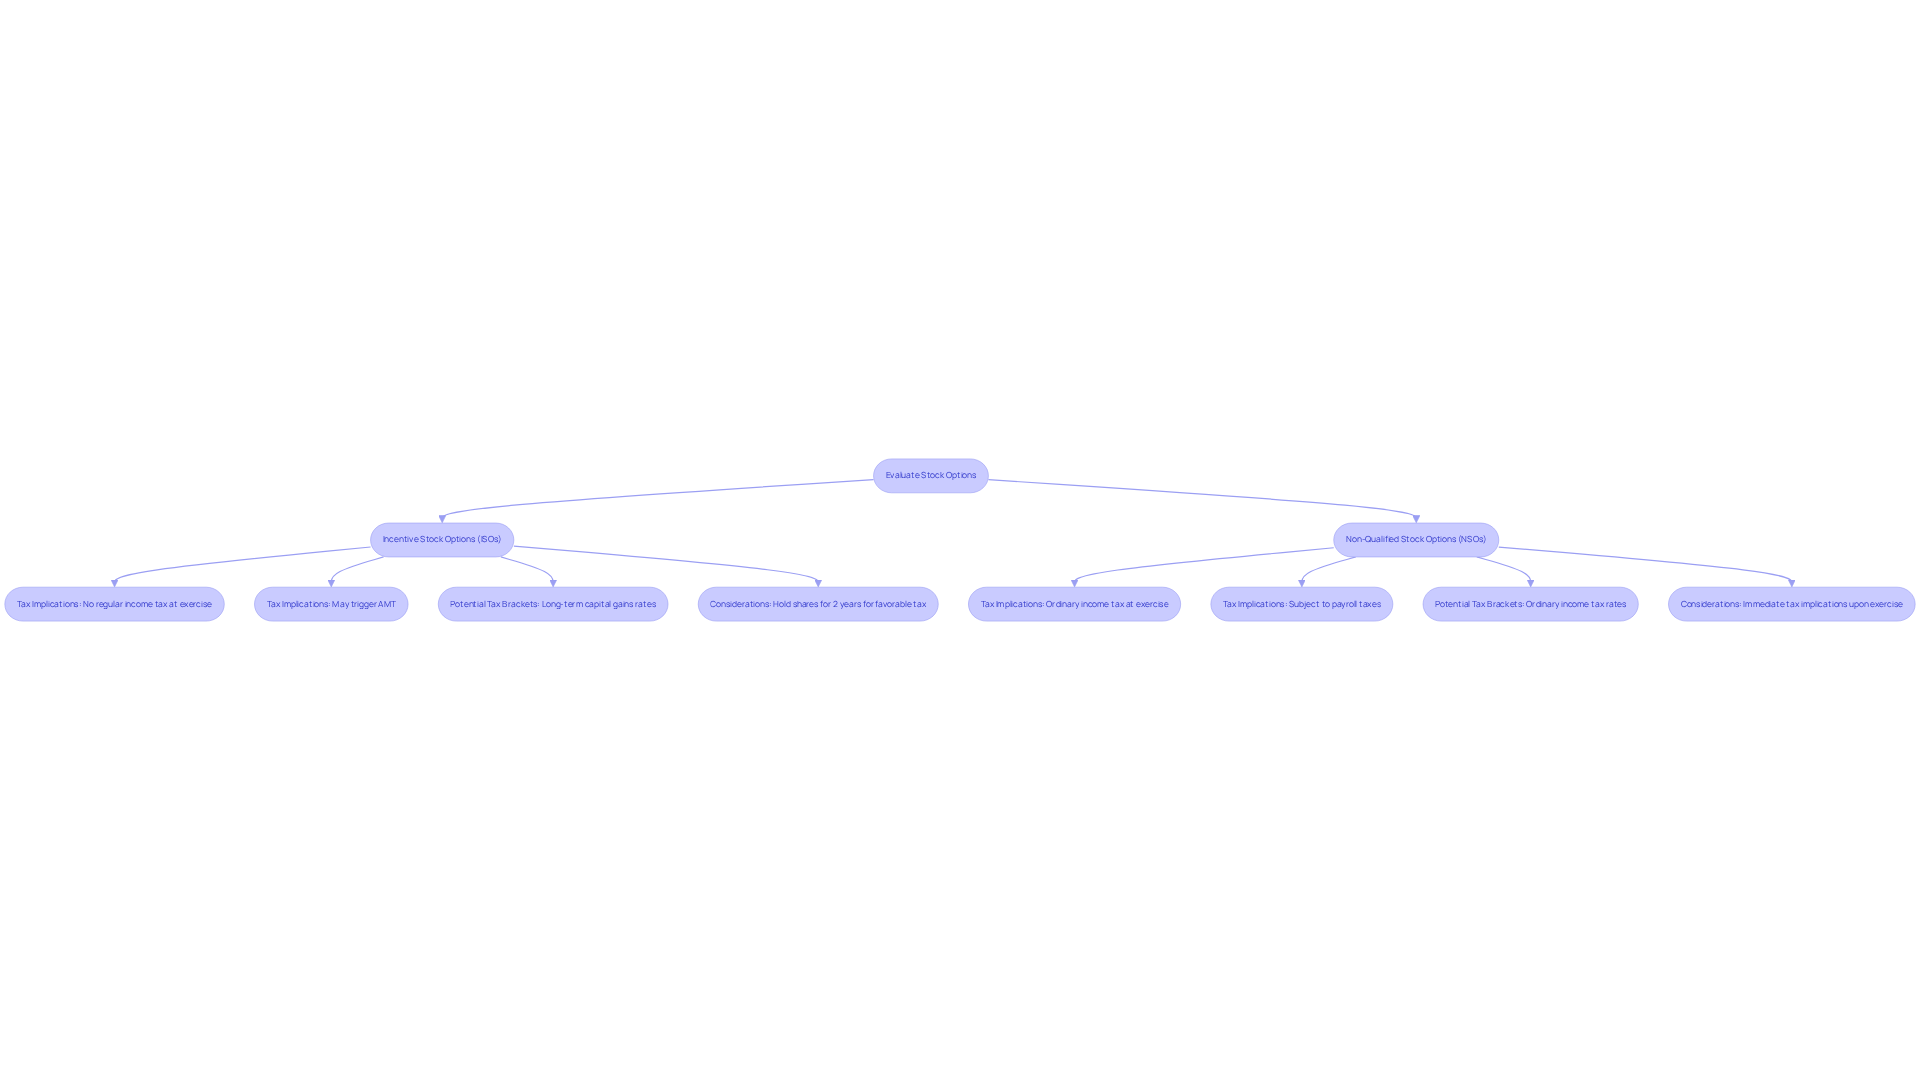
Stock options can offer advantageous tax treatment under certain conditions. When employees exercise stock options, they don’t incur regular income tax at that moment; instead, taxes are deferred until the shares are sold. If the shares are held for the required period, they may qualify for long-term capital gains rates, which are significantly lower than ordinary income tax rates. It’s important to understand that exercising ISOs might lead to the Alternative Minimum Tax (AMT), which can complicate your tax planning and create unexpected financial challenges, especially if the stock’s value has risen significantly.
In the context of ISO vs NSO for executives, NSOs are taxed as ordinary income at the time of exercise. This means that the difference between the exercise price and the fair market value of the stock is subject to income tax, Social Security tax, and Medicare tax. When the shares are later sold, any additional appreciation is taxed as capital gains. This urgent tax obligation can greatly influence a household’s budgeting, especially for high-income earners who may encounter elevated tax brackets.
As parents, grasping these tax implications is vital for ensuring your family’s financial well-being. Decisions about when to exercise options and how to manage potential tax liabilities can have lasting effects on family finances. For instance, if an employee is granted 100,000 NSOs with a strike price of $1 and exercises them when the fair market value is $5, they would recognize $400,000 as ordinary income, which could push them into a higher tax bracket. Conversely, if ISOs are exercised and held correctly, they may avoid immediate tax burdens and benefit from lower long-term capital gains rates upon sale, highlighting the differences in the ISO vs NSO for executives.
Imagine Emily and Mark, a busy couple juggling their careers while striving for financial stability for their family. By collaborating with Bright Advisers, they created a thorough strategy that included enhancing their stock options. This method not only concentrated on their urgent monetary needs but also granted them the liberty to decide whether to continue working, aligning their economic choices with their household objectives.
In conclusion, the decision regarding ISO vs NSO for executives requires thorough evaluation of their tax consequences, which can greatly affect strategies for households with young children. By seeking guidance from experts like Bright Advisers, you can ensure your family’s financial future is secure and aligned with your values.
Evaluate Strategic Considerations: Choosing Between ISOs and NSOs
Imagine navigating the complex world of stock options while trying to secure your family’s financial future. When evaluating iso vs nso for executives, several strategic factors can greatly influence your household’s economic well-being. Take the success story of Allison and Brian, who worked with Bright Advisers to enhance their financial health through thoughtful tax planning.
-
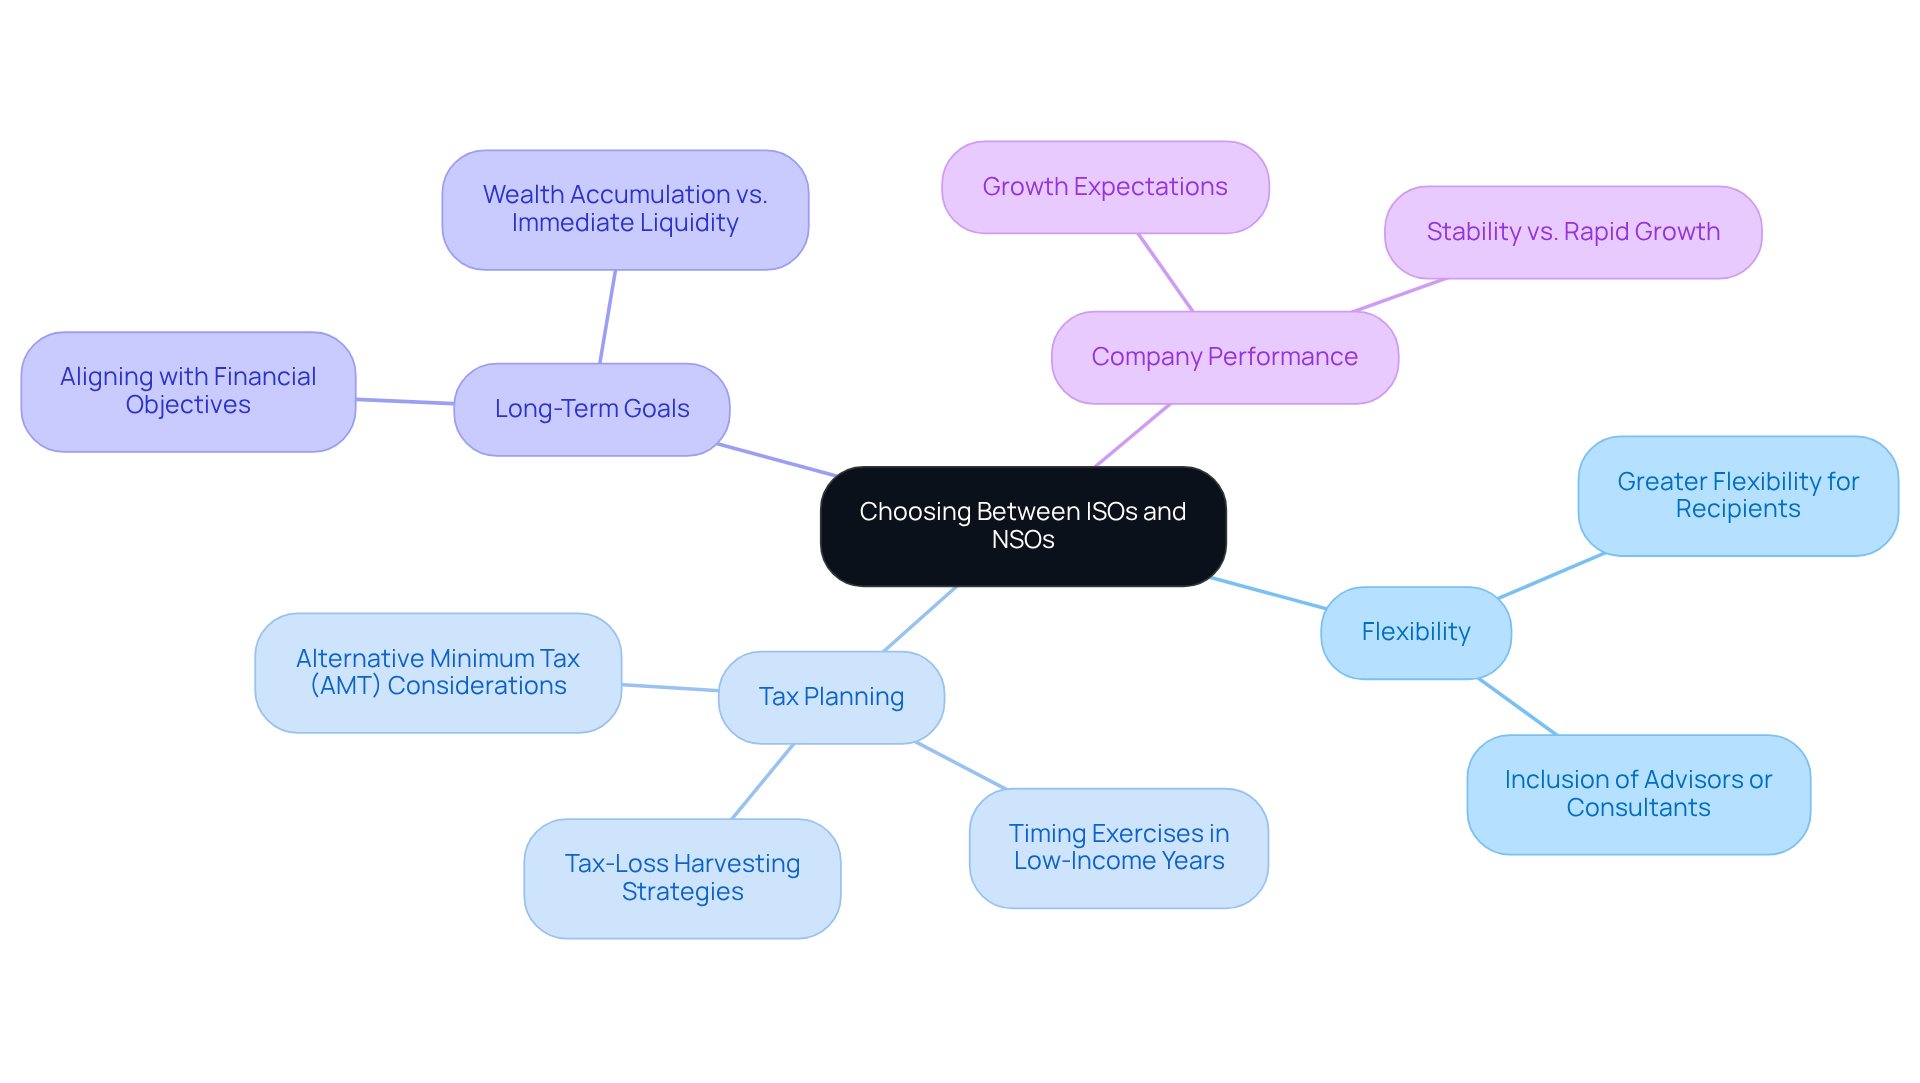
Flexibility: NSOs offer greater flexibility regarding who can receive them and the conditions for exercise. This can be beneficial for families with multiple income earners or those wishing to include advisors or consultants in their financial planning.
-
Tax Planning: The tax implications of each option can influence the timing of exercises and sales. Families may prefer stock options for their potential tax benefits, but they must also consider the implications of the Alternative Minimum Tax (AMT). For instance, only $100,000 of incentive stock options can become exercisable in any one calendar year per employee, which is an important limitation to remember. However, when considering iso vs nso for executives, NSOs can create immediate tax challenges that might strain your family’s budget. Allison and Brian discovered how strategic tax planning, including tax-loss harvesting and timing exercises in low-income years, could minimize their tax liabilities. This allowed them to secure their children’s future through education funding and gain the ability to retire sooner.
-
Long-Term Goals: It’s crucial to remember that understanding the true value of your investments can make all the difference for your family’s future. Families should align their choice with their long-term financial objectives. If the goal is to accumulate wealth over time, considering iso vs nso for executives may show that incentive stock options are more appealing due to their advantageous tax treatment upon sale. However, if immediate liquidity is necessary, NSOs might be the better option in the context of iso vs nso for executives, despite their tax disadvantages. If you believe your company is on the rise, stock options could be a great way to build your family’s future wealth.
-
Company Performance: The performance outlook of the company offering the options can also influence your decision. If substantial growth is expected, stock options may provide greater long-term advantages. Conversely, if the company is stable but not expected to grow rapidly, the discussion of iso vs nso for executives may suggest that NSOs provide more immediate benefits.
Taking the time to explore these options can help your family make choices that fit your unique financial journey. For example, a case study on disqualifying dispositions for incentive stock options illustrates that selling shares before fulfilling the required holding periods can result in unfavorable tax treatment, highlighting the significance of understanding the implications of each choice. Additionally, timing strategies, such as exercising options in a low-income year, can help minimize tax burdens associated with exercising stock options. Ultimately, these insights can assist households in navigating the complexities of stock options effectively, just as they did for Allison and Brian with the help of Bright Advisers.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Summarize Benefits and Drawbacks: A Comparative Overview
Navigating stock options can be a daunting task for families, but understanding ISO vs NSO for executives can empower your financial journey.
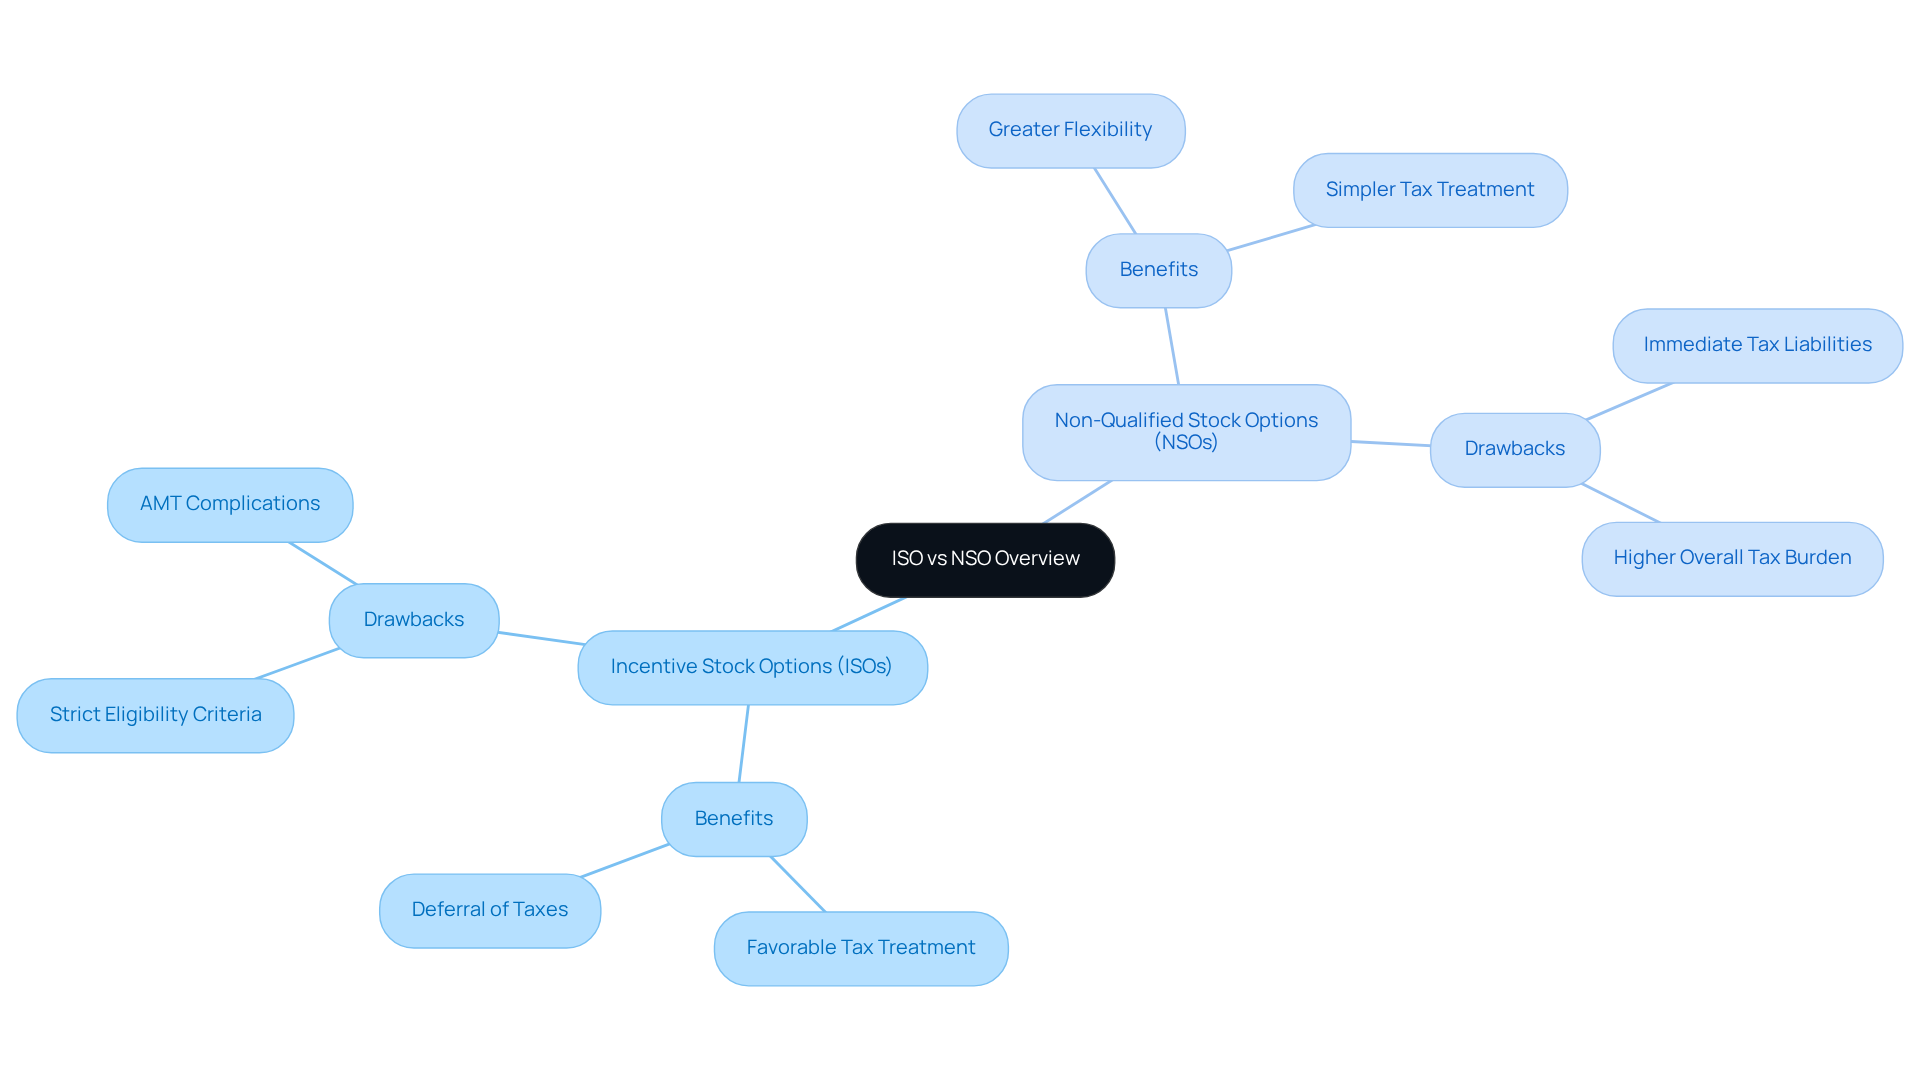
Incentive Stock Options (ISOs) offer some appealing benefits. For instance, they come with favorable tax treatment, which can lead to a lower overall tax liability. Plus, you won’t face immediate taxes when you exercise them; instead, you can defer taxes until you sell the shares. If you hold onto those shares for the required period, you might even qualify for long-term capital gains tax rates.
However, there are drawbacks to consider. ISOs have strict eligibility criteria, meaning only employees can benefit from them. Exercising ISOs may also trigger the Alternative Minimum Tax (AMT), complicating your tax planning. And remember, you must exercise them within a specific timeframe to maintain their status.
On the other hand, Non-Qualified Stock Options (NSOs) provide greater flexibility. They can be granted to employees, consultants, and others, which opens up more opportunities for compensation. There are no limits on the amount that can be granted, making them a versatile option. Plus, the tax treatment at exercise is simpler, which can ease some of the confusion.
Yet, NSOs come with their own set of challenges. They are taxed as ordinary income at exercise, which means you’ll face immediate tax liabilities. This could lead to a higher overall tax burden compared to ISOs. Additionally, any appreciation after exercise is taxed as capital gains, which may not be as favorable.
Understanding these pros and cons of ISO vs NSO for executives can help families make informed choices about their stock options. For example, Emily and Mark, a couple in their mid-30s, collaborated with Bright Advisers to evaluate their financial circumstances thoroughly. They created a strategy that not only focused on enhancing their economic well-being but also granted them the freedom to decide whether or not to keep working. With the right guidance, families can transform their financial futures, turning these options into stepping stones toward a more secure and fulfilling future for their family.
Conclusion
Many families find the world of stock options confusing and overwhelming, but understanding the distinctions between Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs) can empower them to make informed financial decisions. Each type of stock option has unique characteristics, eligibility criteria, and tax implications that can significantly impact a family’s financial strategy. By grasping these differences, families can better navigate their options and align them with their long-term financial goals.
Key insights from the article highlight that:
- ISOs offer favorable tax treatment and potential long-term capital gains benefits, but come with strict eligibility requirements and the risk of triggering the Alternative Minimum Tax (AMT).
- NSOs provide greater flexibility and can be granted to a wider range of individuals, but they incur immediate tax liabilities upon exercise, which can complicate budgeting for families.
It’s important to understand these strategic considerations, such as company performance and long-term goals, to evaluate these options carefully.
We’re here to help families navigate the complexities of stock options, ensuring they feel supported every step of the way. By seeking expert guidance, families can turn confusion into clarity, ensuring their financial choices pave the way for a secure and prosperous future. Engaging in proactive financial planning can empower families to make choices that not only enhance their current financial situation but also lay the groundwork for lasting wealth across generations.
Frequently Asked Questions
What are the two types of stock options discussed in the article?
The two types of stock options discussed are Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs).
Who is eligible to receive Incentive Stock Options (ISOs)?
Only employees are eligible to receive Incentive Stock Options (ISOs).
What are the key requirements for ISOs?
To qualify as an ISO, the exercise price must be at least equal to the fair market value of the stock at the time of the grant, the options must be exercised within 10 years of the grant date, and there is a limit of $100,000 on the value of ISOs that can become exercisable in any calendar year.
Who can receive Non-Qualified Stock Options (NSOs)?
Non-Qualified Stock Options (NSOs) can be granted to a wider range of individuals, including employees, directors, consultants, and advisors.
What are the main differences between ISOs and NSOs?
ISOs have stricter eligibility and tax benefits, while NSOs offer more flexibility, can be granted to anyone, and have no limits on the amount that can be granted. The exercise price for NSOs can also be set below fair market value.
How does exercising NSOs affect taxes?
When an employee exercises NSOs, they incur ordinary income tax on the difference between the exercise price and the current fair market value at the time of exercise.
Why is it important for families to understand stock options?
Understanding stock options is important for families as it helps them consider how these options fit into their financial plans, particularly regarding taxes and eligibility, which can significantly impact budgeting strategies.
How can Bright Advisers assist families with stock options?
Bright Advisers provides support to help families make sense of their financial planning, emphasizing integrated tax planning strategies to alleviate financial anxiety and allocate resources effectively.
List of Sources
- Define ISOs and NSOs: Key Characteristics and Eligibility
- What are nonqualified stock options (NSOs)? | Fidelity (https://fidelity.com/viewpoints/wealth-management/insights/nonqualified-stock-options)
- Non-Qualified Stock Options (NSO): How NSOs Work (https://carta.com/learn/equity/stock-options/nso)
- Non-qualified stock options (NSOs) – What’s the deal? (https://jpmorganworkplacesolutions.com/insights/non-qualified-stock-options-nsos)
- What Are Incentive Stock Options (ISOs)? (https://missionwealth.com/what-are-incentive-stock-options-isos)
- Unlocking the Power of Equity-Based Incentive Compensation: An Overview of Incentive Stock Options (ISOs) (https://foley.com/insights/publications/2024/08/equity-based-incentive-compensation-stock-options-iso)
- Analyze Tax Implications: ISOs vs NSOs
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- ISOs vs NSOs Tax Treatment: 2026 Complete Guide – Uncle Kam (https://unclekam.com/tax-strategy-blog/isos-vs-nsos-tax-treatment-2026-complete-guide)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- ISO vs NSO: What’s the Difference? Tax & Eligibility (https://esofund.com/blog/difference-iso-nso)
- How Stock Options Are Taxed: ISO vs NSO | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/how-are-stock-options-taxed)
- Evaluate Strategic Considerations: Choosing Between ISOs and NSOs
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- Summarize Benefits and Drawbacks: A Comparative Overview
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- ISOs vs. NSOs: Options, Taxes, and Cashless Exercise Explained (https://nasdaqprivatemarket.com/youve-got-options-what-to-know-about-isos-and-nsos)
- Differences Between Incentive Stock Options and Nonqualified Stock Options | Davis Wright Tremaine (https://dwt.com/blogs/startup-law-blog/2020/07/differences-between-iso-nso)
- mcdonaldjacobs.cpa (https://mcdonaldjacobs.cpa/comparing-nsos-isos-and-rsus-tax-and-planning-guide)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading