

Key Highlights
- Incentive Stock Options (ISOs) are available only to employees and offer tax benefits if held for specific periods.
- ISOs can be taxed at lower long-term capital gains rates, but may trigger Alternative Minimum Tax (AMT).
- There is a $100,000 cap on the stock value that can become exercisable in any calendar year for ISOs.
- Non-Qualified Stock Options (NSOs) can be awarded to employees and non-employees, providing more flexibility.
- NSOs are taxed as ordinary income upon exercise, potentially leading to a higher tax burden compared to ISOs.
- Families should consider timing and market conditions when exercising stock options to optimise financial outcomes.
- Strategies for ISOs include early exercise and spreading exercises over multiple years to manage AMT implications.
- For NSOs, a cashless exercise strategy can help manage immediate tax impacts, but may limit long-term gains.
- Understanding the differences between ISOs and NSOs is crucial for families to make informed financial decisions.
- Bright Advisers assists families in navigating stock options and tax strategies to enhance wealth accumulation.
Introduction
Many families feel overwhelmed by the complexities of stock options, especially when planning for a secure financial future. Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs) each come with unique characteristics and tax implications that can significantly impact your family’s wealth-building strategy.
Imagine trying to make sense of tender offers while juggling family responsibilities. How can you choose the right option that aligns with your long-term financial goals? By exploring the key differences between ISOs and NSOs, together we can help your family make informed decisions that lead to a more secure future.
Define ISOs and NSOs: Key Characteristics and Eligibility
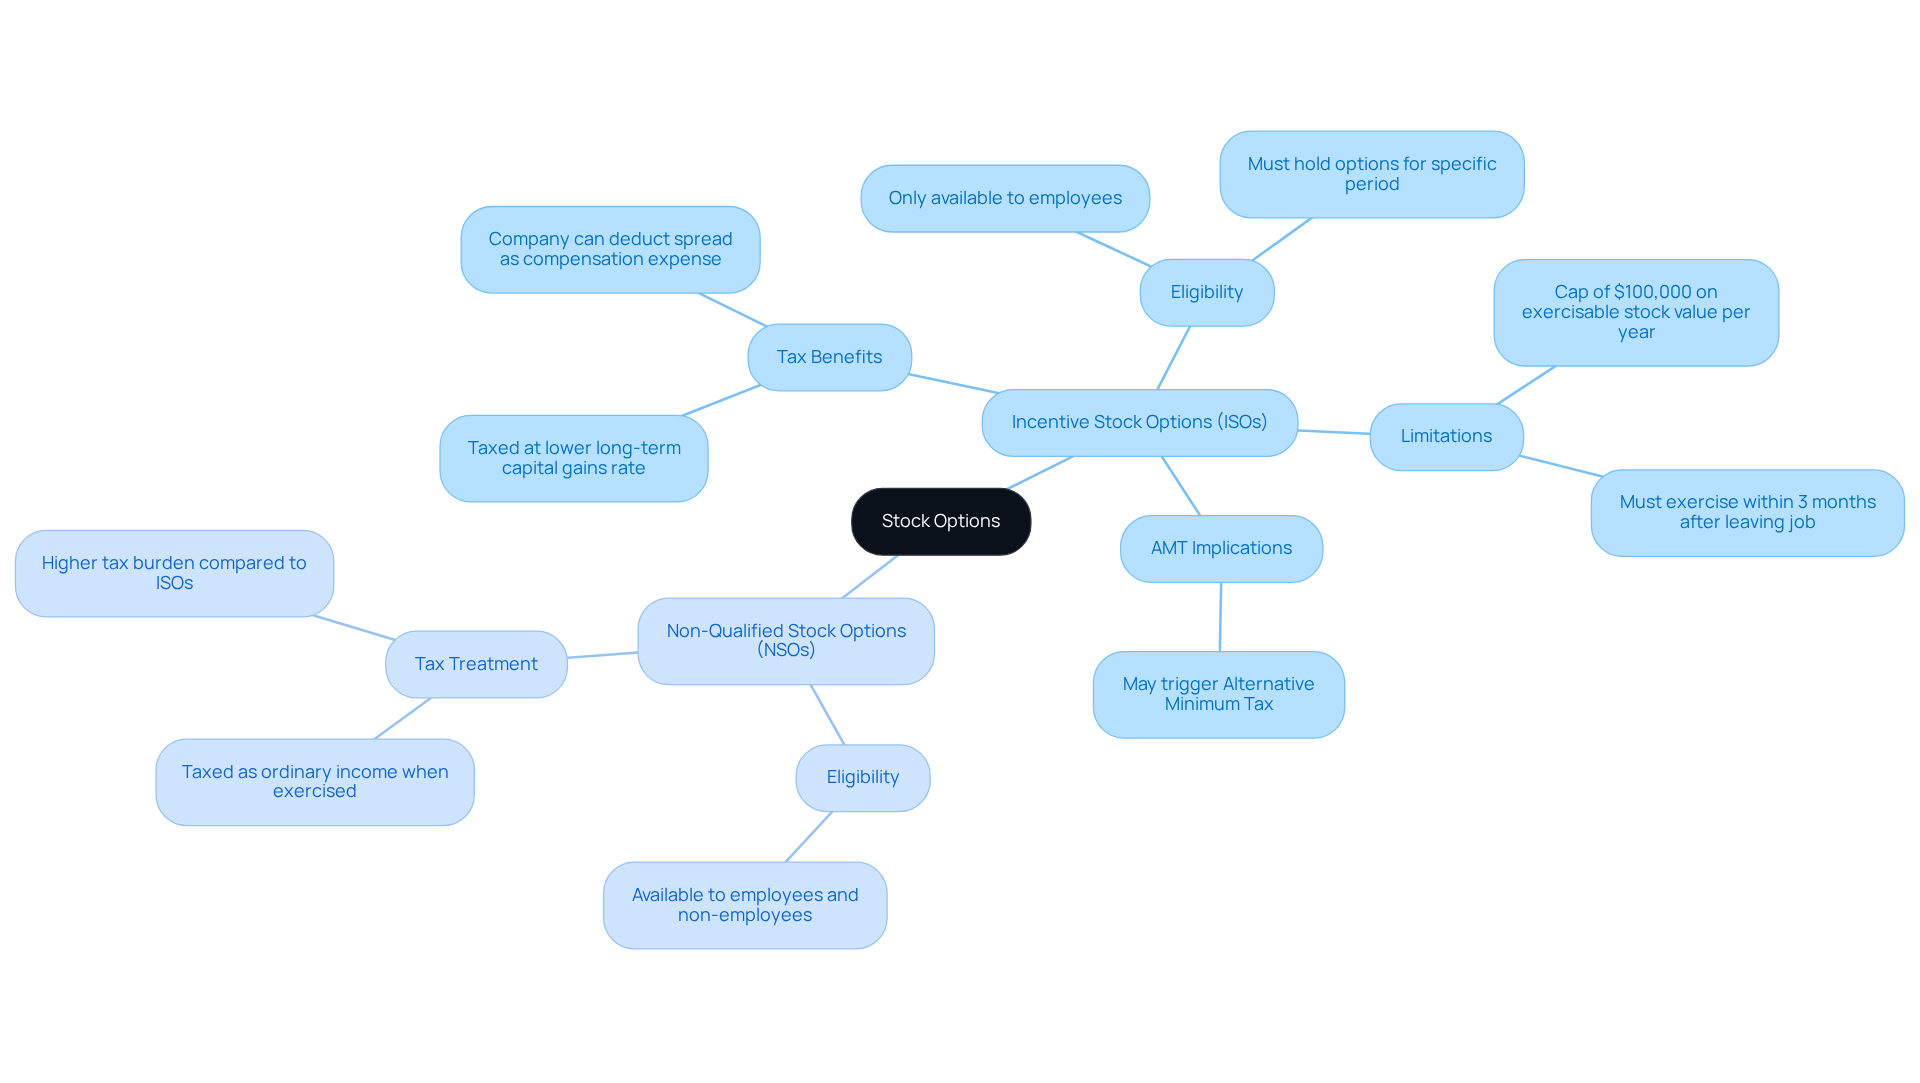
Imagine navigating the complexities of stock options while trying to secure your family’s financial future. Incentive Stock Options help employees save on taxes. These options are designed specifically for employees and come with certain requirements to qualify for tax benefits.
-
Eligibility: ISOs are only available to employees, and they must hold the options for a specific period to enjoy favorable tax treatment. If an employee leaves their job, they need to exercise their options within three months to keep those benefits.
-
Tax Benefits: If certain conditions are met, incentive stock options can be taxed at the lower long-term capital gains rate instead of ordinary income rates. This can significantly ease the tax burden. Plus, the company can deduct the spread on stock options as a compensation expense, which is beneficial for both employees and employers.
-
Limitations: There’s a cap of $100,000 on the stock value that can become exercisable in any calendar year, based on the grant date value.
-
Alternative Minimum Tax (AMT): ISOs may trigger AMT implications, which is something families need to consider when evaluating their options.
On the other hand, Non-Qualified Stock Options offer more flexibility. They can be awarded to a wider range of individuals, including employees, consultants, and board members.
-
Eligibility: NSOs can be issued to both employees and non-employees, making them more accessible.
-
Tax Treatment: Non-qualified stock options are taxed as regular income when exercised, which can lead to a higher tax burden compared to incentive stock options.
Many families find the world of stock options confusing and overwhelming. Grasping these differences is essential for families, especially when considering the long-term economic impact of ISO vs NSO after tender offer. By understanding these distinctions, families can navigate their financial futures with confidence.
At Bright Advisers, we know that families like yours face unique financial challenges, just like Jay & Emma, Emily & Mark, and Allison & Brian. By working with us, they’ve tackled the complexities of financial planning, including tax strategies that enhance their wealth accumulation potential. Together, we can help you manage your resources effectively, reduce financial anxiety, and achieve your long-term goals. Understanding these options can empower your family to make choices that align with your financial goals.
Compare Tax Treatment: ISOs vs. NSOs
Navigating the world of stock options can be daunting, especially when it comes to understanding how they impact your family’s financial future.
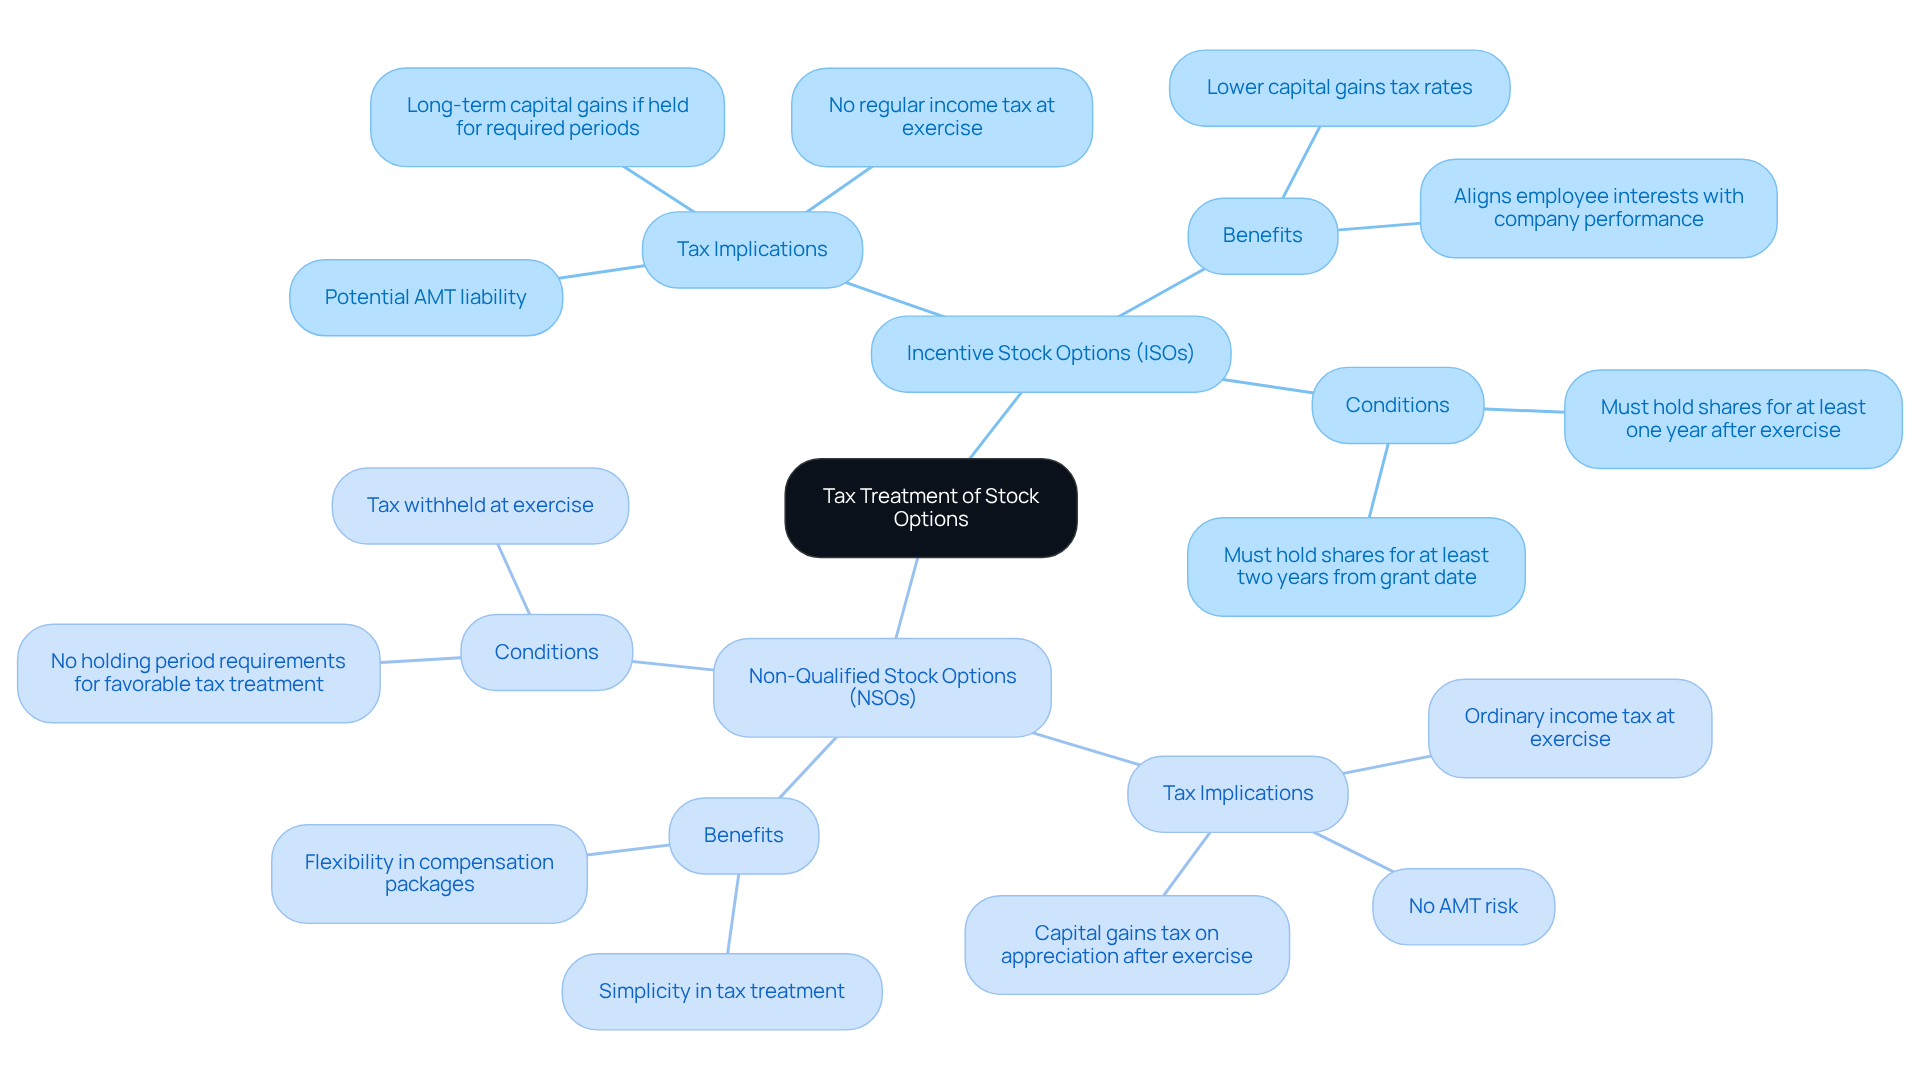
Incentive Stock Options (ISOs) offer some unique benefits that can be advantageous for families. With ISOs, you won’t face regular income tax right away when you exercise them, which can be a relief for many families. However, it’s important to understand that exercising these options might trigger the Alternative Minimum Tax (AMT), adding a layer of complexity to your tax planning. Many families find themselves feeling overwhelmed by the tax implications of stock options. If you hold onto your shares for at least one year after exercising and two years from the grant date, you could benefit from lower long-term capital gains tax rates.
On the other hand, Non-Qualified Stock Options (NSOs) are taxed differently. When you exercise NSOs, you’ll see taxes applied as ordinary income based on the difference between the exercise price and the stock’s fair market value. This could mean a hefty tax bill when you exercise, which can be a lot to manage for families. The good news is that NSOs don’t trigger AMT, making them simpler from a tax perspective. When you sell NSO shares, any increase in value beyond the exercise price is taxed as capital gains, which can vary based on how long you hold the shares.
Understanding these distinctions, particularly ISO vs NSO after tender offer, can empower families to make choices that foster financial peace of mind. By understanding ISO vs NSO after tender offer, families can make informed choices that align with their financial goals. With the right knowledge and support, you can turn these complexities into opportunities for your family’s financial growth.
Evaluate Exercise Strategies: Timing and Financial Impact
Imagine feeling overwhelmed by the complexities of stock options and wondering how to secure your family’s future. Timing can significantly influence the financial impact on families when it comes to exercising stock options. Here are some strategies to consider:
ISOs:
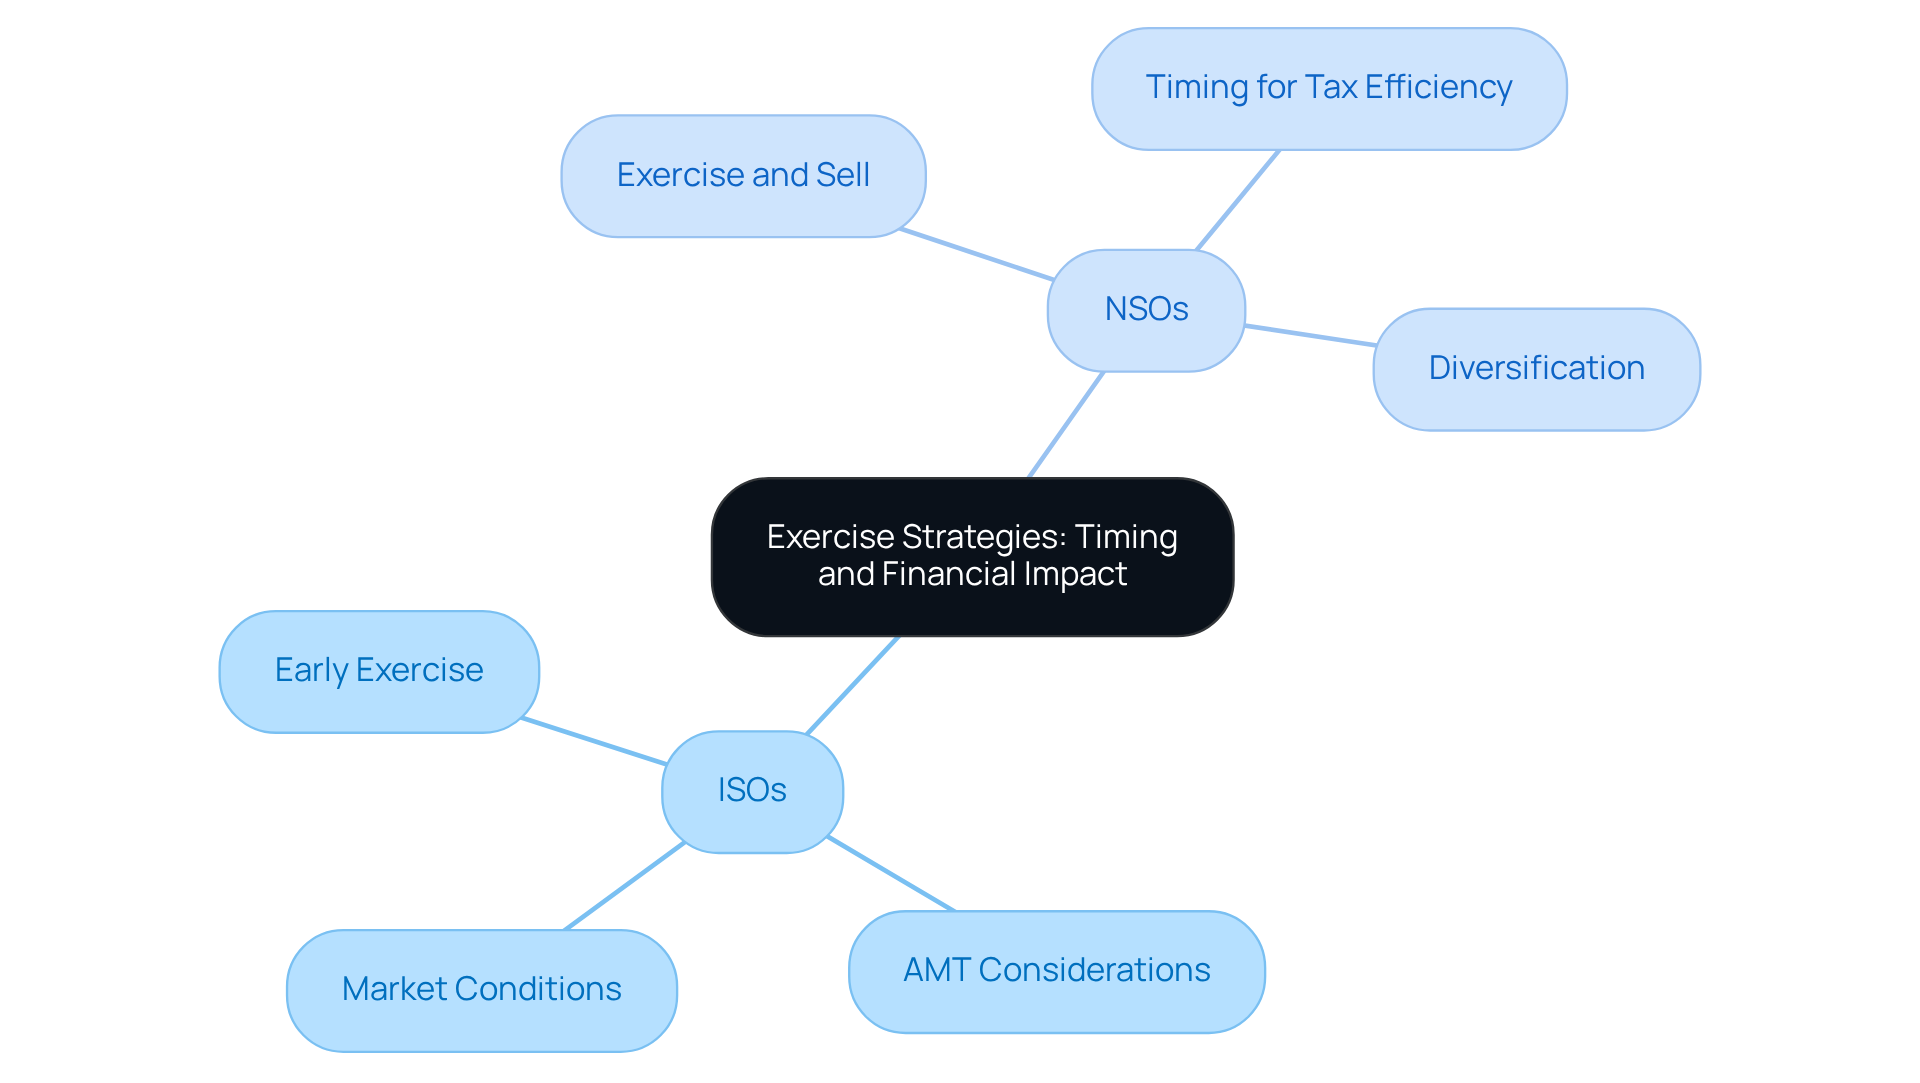
- Early Exercise: Exercising ISOs early in the year can give families the chance to hold shares long enough to qualify for long-term capital gains treatment. This can be a smart move if the stock is expected to appreciate. Plus, filing an 83(b) election within 30 days of early exercise is crucial to avoid future tax complications.
- AMT Considerations: It’s important for families to be cautious about exercising too many ISOs in a single year, as this can trigger the Alternative Minimum Tax (AMT). In California, the AMT rate is 7%, which applies on top of the federal rate of 26-28%. Spreading exercises over multiple years may help manage tax liabilities effectively.
- Market Conditions: Keeping an eye on market conditions is essential. If the stock price is expected to rise, exercising sooner may yield better long-term gains, allowing families to capitalize on favorable market trends.
NSOs:
- Exercise and Sell: Many families choose a cashless exercise strategy, where they exercise NSOs and immediately sell the shares to cover the exercise cost and taxes. This method reduces cash expenditure but may not enhance long-term profits, as the combined tax rate for non-qualified stock options can reach up to 50.3%.
- Timing for Tax Efficiency: Families should think about exercising stock options in years with lower income to minimize the tax impact. These options are taxed as ordinary income at exercise, with federal withholding rates of 22% for amounts under $1 million and 37% for amounts above.
- Diversification: After exercising NSOs, families should consider diversifying their investments to mitigate risk, especially if a significant portion of their wealth is tied to a single stock. This strategy helps manage concentration risk and aligns with long-term monetary goals.
Many families feel overwhelmed by the complexities of stock options and the potential tax implications. With a little guidance, families can navigate these strategies to find what truly fits their financial dreams and comfort levels. For instance, Allison and Brian, a couple in their late 40s, sought guidance from Bright Advisers to optimize their tax situation and secure their children’s future through education funding. Their collaboration resulted in a thorough plan that included specific strategies such as tax-loss harvesting and investment diversification, addressing their urgent needs while positioning them for a more secure retirement. With the right guidance, you can turn financial uncertainty into a brighter future for your family.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Assess Long-Term Implications: Choosing the Right Option for Your Family
Navigating the decision of iso vs nso after tender offer can feel overwhelming, especially when considering your family’s future. Here are some essential considerations to keep in mind:
ISOs:
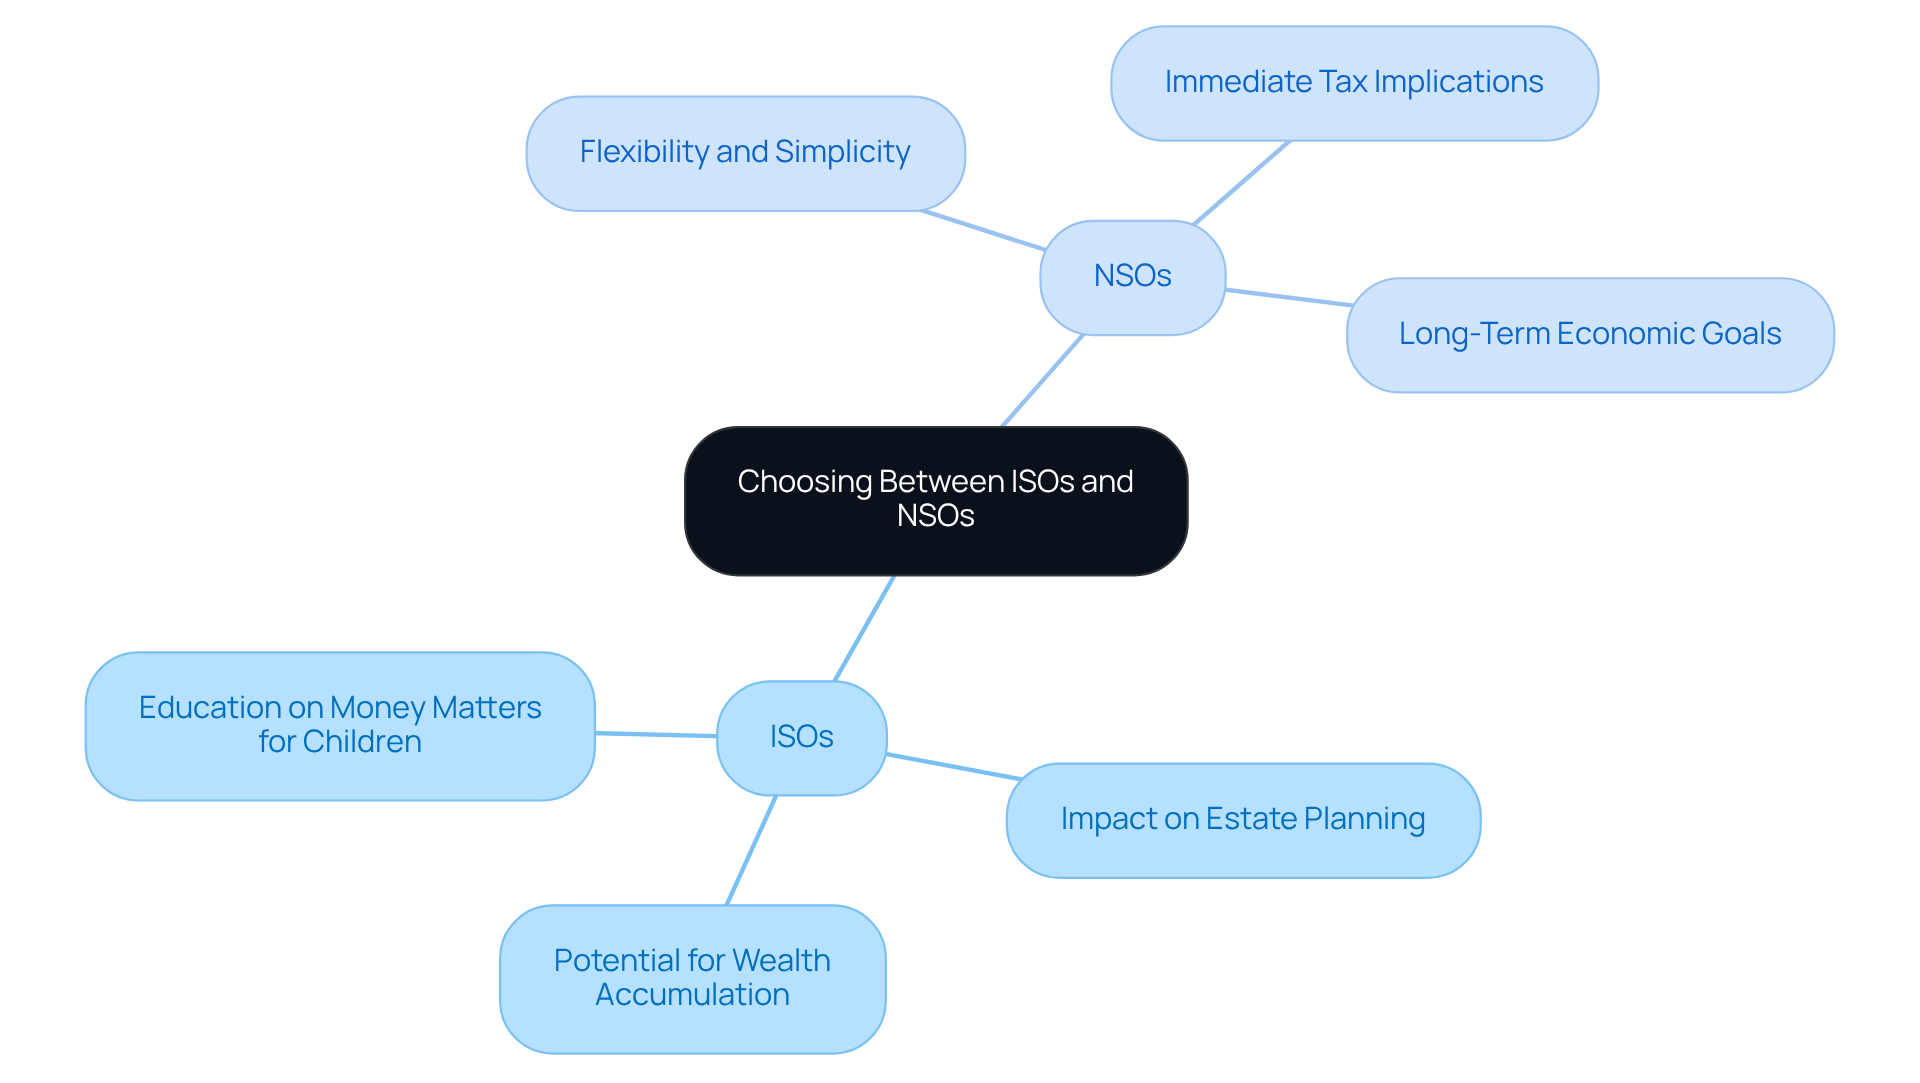
- Potential for Wealth Accumulation: When managed effectively, ISOs can help families build substantial wealth over time. Their favorable tax treatment on long-term capital gains means that profits can be taxed at lower rates if holding periods are satisfied. Think about how stock options can align with your family’s long-term investment strategies.
- Impact on Estate Planning: ISOs can play a significant role in your estate planning. The tax consequences upon the death of the option holder may affect overall estate tax liabilities. It’s important to think about how these options can help secure a bright future for your loved ones.
- Education on Money Matters for Children: ISOs also provide a wonderful opportunity to teach your children about investing and money management, nurturing a culture of financial literacy that can benefit future generations.
NSOs:
- Flexibility and Simplicity: NSOs offer greater flexibility regarding who can receive them and how they can be exercised. This can be particularly advantageous for families with diverse financial needs, helping you adjust your budgeting strategies as situations evolve.
- Immediate Tax Implications: It’s crucial to be prepared for the immediate tax consequences of exercising NSOs, which can impact your cash flow. Understanding the implications of iso vs nso after tender offer, particularly that the spread at exercise is taxed as ordinary income, is key to managing these factors effectively.
- Long-Term Economic Goals: Aligning NSO strategies with your long-term economic objectives is essential. Reflect on how these options can enhance your overall wealth management strategy, ensuring they align with your family’s monetary aspirations.
By understanding these options, you can make informed decisions that pave the way for a secure financial future for your family.
Conclusion
Imagine feeling overwhelmed by the choices in stock options and unsure of what’s best for your family’s future. Understanding the differences between Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs) can help ease that burden. Each option has its own features and tax effects that can really influence how your family builds wealth and plans for the future. By understanding these differences, families can feel more confident in choosing what’s best for their future.
ISOs can provide some tax advantages, like lower rates on long-term gains, but they also come with some tricky rules to navigate. On the other hand, NSOs can be more flexible and have immediate tax effects that might impact your family’s cash flow. It’s important for families to think about their unique situations and how these options fit into their financial plans.
Choosing between ISOs and NSOs can really influence your family’s financial future for a long time. Working with a trusted advisor like Bright Advisers can help guide your family through these choices, making sure you feel secure and supported in your financial journey. Together, we can navigate these choices and build a secure financial future for your family.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are stock options designed specifically for employees that offer potential tax benefits if certain conditions are met.
Who is eligible for ISOs?
ISOs are only available to employees, and they must hold the options for a specific period to qualify for favorable tax treatment. If an employee leaves their job, they need to exercise their options within three months to retain those benefits.
What are the tax benefits of ISOs?
If certain conditions are met, ISOs can be taxed at the lower long-term capital gains rate instead of ordinary income rates, which can significantly reduce the tax burden. Additionally, the company can deduct the spread on stock options as a compensation expense.
Are there any limitations on ISOs?
Yes, there is a cap of $100,000 on the stock value that can become exercisable in any calendar year, based on the grant date value.
What is the Alternative Minimum Tax (AMT) in relation to ISOs?
ISOs may trigger AMT implications, which families need to consider when evaluating their options.
What are Non-Qualified Stock Options (NSOs)?
Non-Qualified Stock Options (NSOs) are stock options that offer more flexibility and can be awarded to a wider range of individuals, including employees, consultants, and board members.
Who is eligible for NSOs?
NSOs can be issued to both employees and non-employees, making them more accessible than ISOs.
How are NSOs taxed?
Non-qualified stock options are taxed as regular income when exercised, which can lead to a higher tax burden compared to ISOs.
Why is it important for families to understand the differences between ISOs and NSOs?
Understanding the distinctions between ISOs and NSOs is essential for families, especially when considering the long-term economic impact of each option. This knowledge can help families navigate their financial futures with confidence.
List of Sources
- Define ISOs and NSOs: Key Characteristics and Eligibility
- Non-Qualified Stock Options (NSO): How NSOs Work (https://carta.com/learn/equity/stock-options/nso)
- Differences Between Incentive Stock Options and Nonqualified Stock Options | Davis Wright Tremaine (https://dwt.com/blogs/startup-law-blog/2020/07/differences-between-iso-nso)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- What are nonqualified stock options (NSOs)? | Fidelity (https://fidelity.com/viewpoints/wealth-management/insights/nonqualified-stock-options)
- Windham Brannon (https://windhambrannon.com/blog/incentive-stock-options-considerations-for-tech-companies)
- Compare Tax Treatment: ISOs vs. NSOs
- ISO vs. NSO Stock Options: How Each Is Taxed and Why 2026 Raises the Stakes | 409.AI (https://409.ai/articles/iso-vs-nso-how-stock-options-are-taxed)
- ISO vs NSO: The Tax Implications (https://brightonjones.com/blog/iso-vs-nso)
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- ISOs vs NSOs Tax Treatment: 2026 Complete Guide – Uncle Kam (https://unclekam.com/tax-strategy-blog/isos-vs-nsos-tax-treatment-2026-complete-guide)
- ISO vs NSO: How Stock Option Taxes Differ in 2026 | Taxstra (https://taxstra.com/iso-vs-nso)
- Evaluate Exercise Strategies: Timing and Financial Impact
- When Should I Exercise Stock Options? | Summitry (https://summitry.com/blog/when-to-exercise-stock-options)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- Exercising Stock Options: Taxes, Timing & Strategies (https://jpmorganworkplacesolutions.com/insights/exercise-stock-options)
- When to consider exercising your stock options (https://empower.com/the-currency/work/strategies-for-when-to-exercise-stock-options)
- Exercising Stock Options | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/when-to-exercise-stock-options)
- Assess Long-Term Implications: Choosing the Right Option for Your Family
- Incentive Stock Options Tax Planning Opportunities – GHJ (https://ghjadvisors.com/ghj-insights/incentive-stock-options-tax-planning-opportunities-and-pitfalls)
- ISO vs NSO: How Stock Option Taxes Differ in 2026 | Taxstra (https://taxstra.com/iso-vs-nso)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- ISO vs NSO Stock Options: Key Differences Explained (https://monumentwealthmanagement.com/resource/iso-vs-nso-stock-options)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading