

Key Highlights
- Incentive Stock Options (ISOs) are exclusive to employees and offer potential tax advantages, but may trigger the Alternative Minimum Tax (AMT).
- Non-Qualified Stock Options (NSOs) can be granted to a wider range of individuals, including contractors, and are taxed as ordinary income upon exercise.
- Families must consider the tax implications of exercising ISOs and NSOs, as ISOs may qualify for long-term capital gains while NSOs incur immediate tax liabilities.
- Strategic timing for exercising stock options can optimise tax outcomes; ISOs may be exercised early in the year to minimise AMT exposure.
- Understanding the differences between ISOs and NSOs is crucial for families in Southern California to make informed financial decisions.
- Bright Advisers emphasises fiduciary duty and transparency in helping families navigate stock options and achieve their financial goals.
Introduction
Imagine feeling overwhelmed by the complexities of stock options while trying to secure your family’s financial future. Navigating Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs) can be challenging, but understanding their unique benefits and challenges is essential for families like yours. As you consider your options, it’s crucial to grasp the differences and tax implications that come with them.
How can you use these stock options to not just grow your wealth, but also support your family’s dreams and values?
Define Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs)
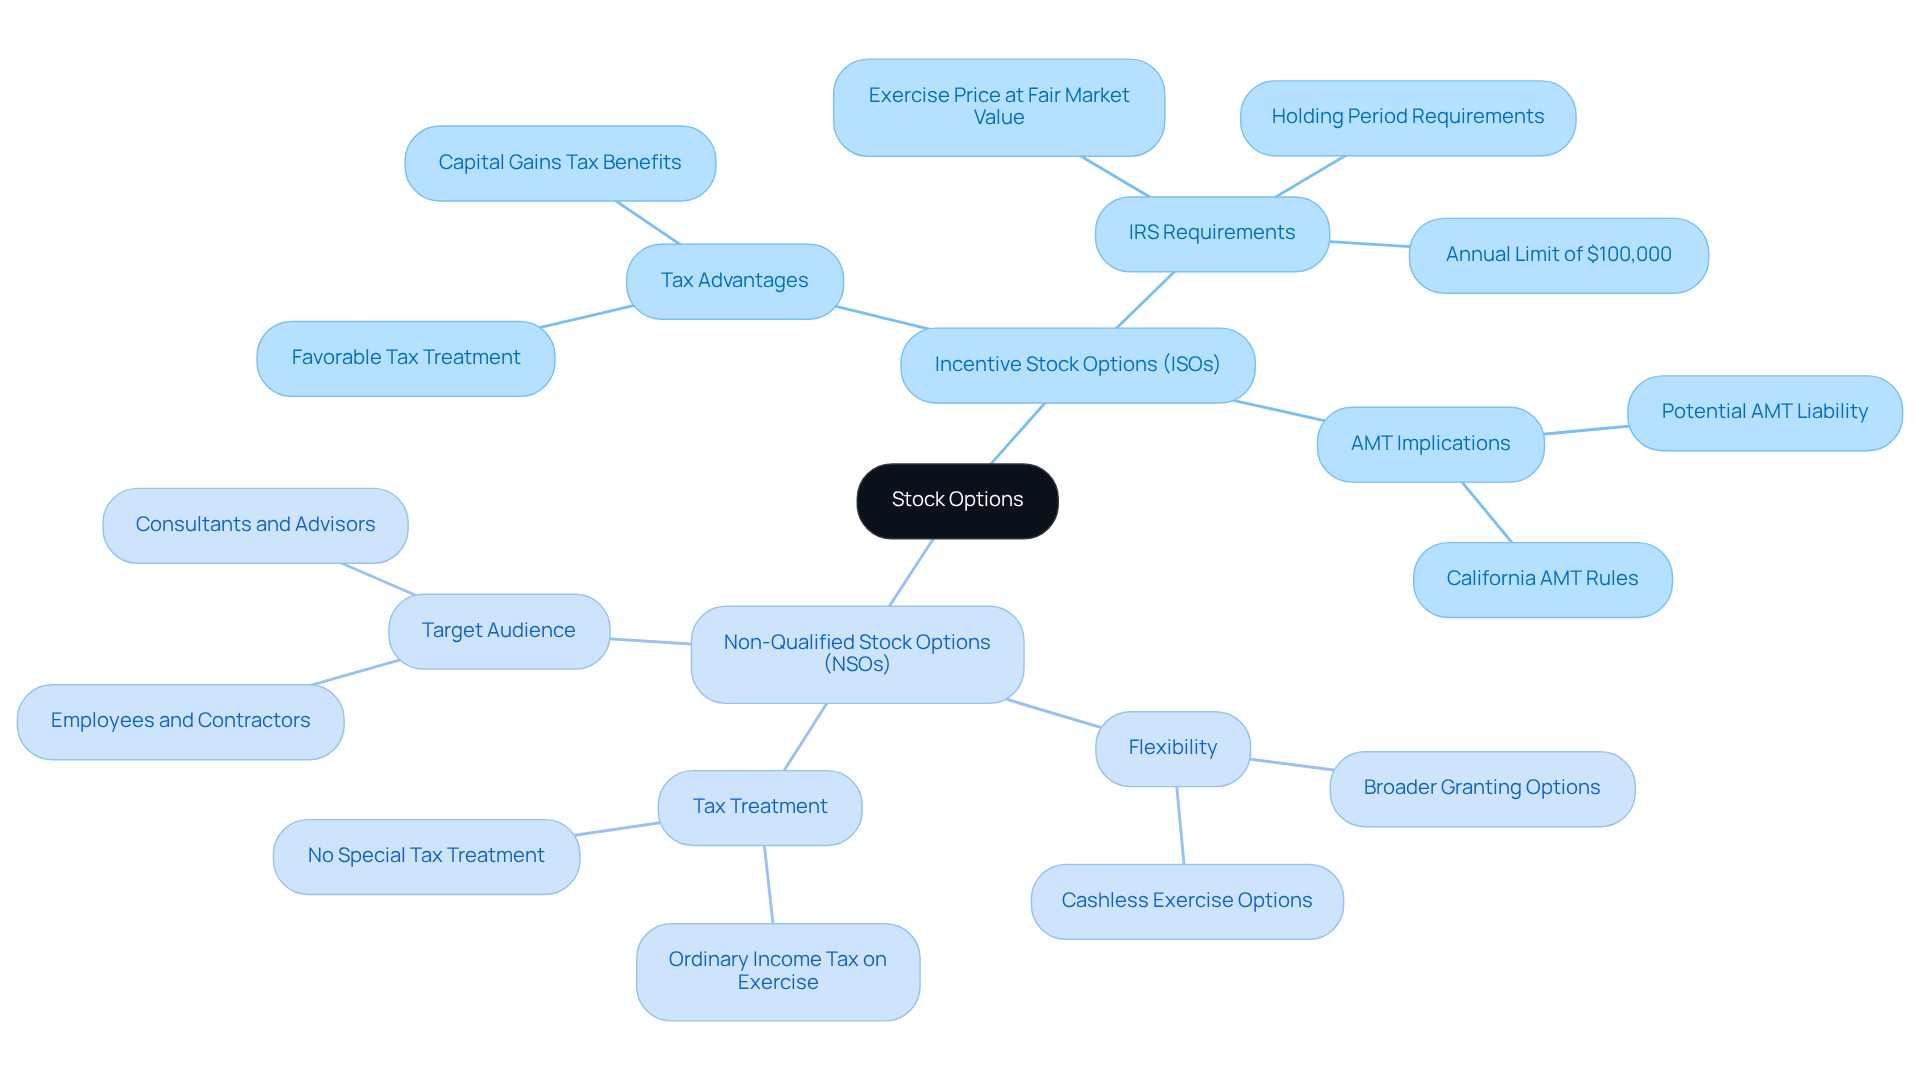
Navigating the world of stock options can feel daunting for many families, especially when it comes to making informed financial decisions. Incentive Stock Options (ISOs) are a special benefit just for employees, designed to help you grow your wealth while offering certain tax advantages, provided they meet IRS requirements. But here’s the catch: exercising those options might trigger the Alternative Minimum Tax (AMT), which could lead to some surprising tax bills, particularly in states like California where AMT rules differ from federal regulations. For families like Jay and Emma, understanding investment strategies is essential for creating a solid plan that includes retirement preparation and education financing for their children.
On the other hand, Non-Qualified Stock Options (NSOs) don’t come with the same tax perks as ISOs, but they offer flexibility. They can be granted to a wider range of individuals, including contractors and consultants. When NSOs are exercised, the difference between the exercise price and the fair market value of the stock is taxed as ordinary income. This flexibility can be especially beneficial for families like Emily and Mark, who are juggling demanding careers while striving for economic stability and the freedom to choose their work-life balance. By understanding NSOs, they can implement strategies to manage cash flow and invest wisely, aligning their financial decisions with their personal aspirations.
Understanding the differences between ISO and NSO stock options is key for families aiming to build a brighter financial future. For instance, a case study featuring Allison and Brian highlights how incorporating stock options into a comprehensive financial strategy can make a significant difference. By collaborating with Bright Advisers, families can gain valuable insights into optimizing their financial well-being and achieving their long-term goals. With the right guidance, families can turn stock options into a powerful tool for achieving their dreams and securing their children’s future.
Examine Tax Implications of ISOs vs. NSOs
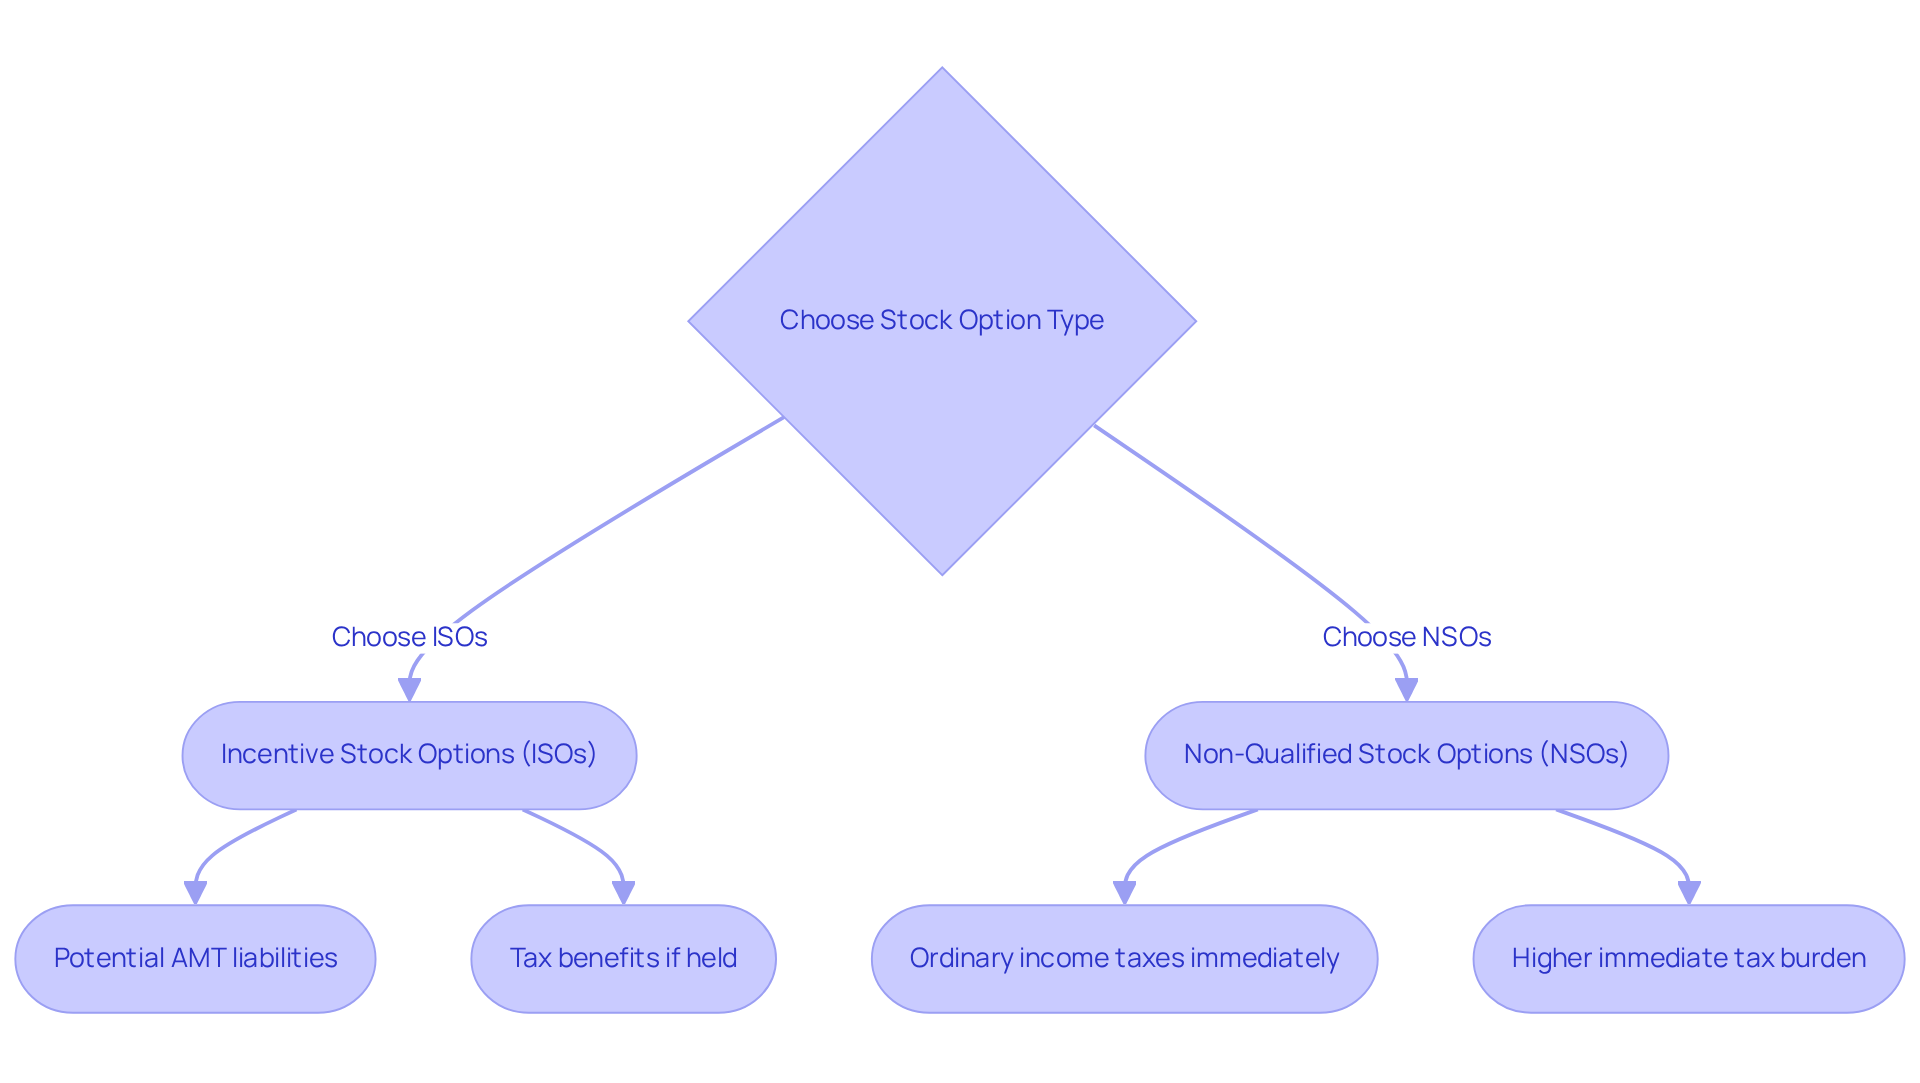
Understanding the tax implications of ISO NSO stock options is essential for your family’s financial peace of mind. Imagine the relief of knowing that Incentive Stock Options can offer you significant tax benefits, allowing you to focus on what truly matters – your family. It’s important to understand that exercising stock options might activate the Alternative Minimum Tax (AMT), which can catch families off guard during financial planning. For instance, if you exercise ISOs and hold the shares, you may face AMT liabilities based on the spread between the exercise price and the fair market value at the time of exercise. This could mean the difference between a secure financial future and unexpected burdens that weigh on your family.
On the other hand, with ISO NSO stock options, you might find yourself facing ordinary income taxes right away, which can feel overwhelming when you’re trying to plan for your family’s future. The difference between the exercise price and the fair market value of the stock is subject to income tax, Social Security tax, and Medicare tax, leading to a higher immediate tax burden for households. For example, if you exercise NSOs, you may incur substantial tax liabilities that could affect your overall monetary strategy. In California, the combined federal and state tax rates for ISO NSO stock options can reach up to 50.3%, making it crucial for families to assess their current economic situation and future tax consequences when deciding between ISO NSO stock options and ISOs.
Understanding these tax implications is vital for families like yours, as they can shape your long-term financial journey together. Case studies show that families who manage these complexities effectively can optimize their tax results and improve their economic well-being. Navigating these choices with care can lead to a brighter financial future for your family, ensuring you make the most of your hard-earned benefits.
Evaluate Timing and Strategy for Exercising ISOs and NSOs
Imagine feeling confident about your family’s financial future, even amidst the complexities of stock options. At Bright Advisers, we understand that young parents like Jay and Emma, Emily and Mark, and Allison and Brian face unique financial challenges and dreams.
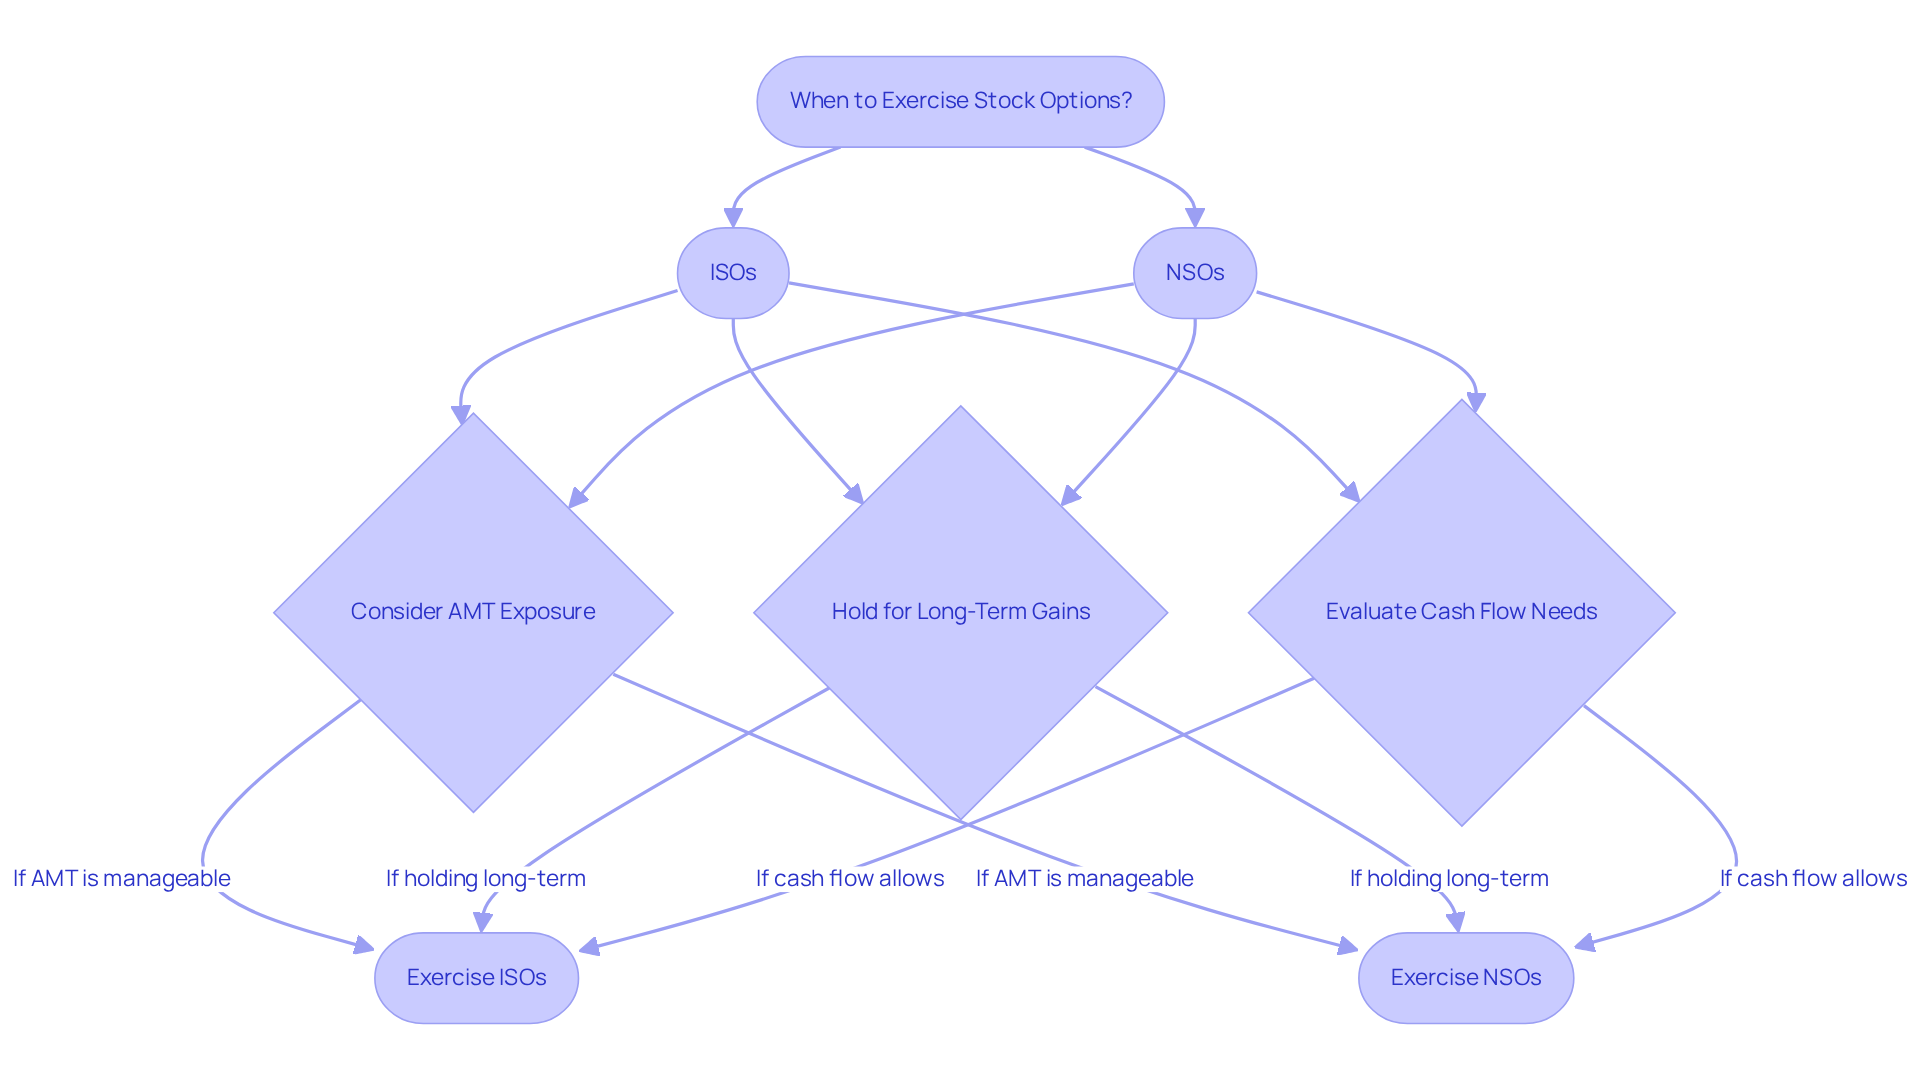
For iso nso stock options, consider exercising them early in the year to help reduce your exposure to Alternative Minimum Tax (AMT), especially if you expect a significant rise in stock value. To benefit from long-term capital gains, remember that you need to hold onto your shares for at least a year after exercising. Think about keeping an eye on how your stocks are doing and timing your exercises to fit your family’s tax situation. For instance, Jay and Emma successfully managed their financial planning by optimizing their tax strategies, which included careful consideration of their stock options.
When it comes to iso nso stock options, the strategy is generally more straightforward. Since NSOs are taxed as ordinary income when you exercise them, you might want to exercise when you expect a big jump in stock price. This way, you can enjoy the benefits of appreciation while managing your tax obligations. Just keep in mind your cash flow needs, as exercising NSOs requires upfront payment of the exercise price. Emily and Mark, for example, worked closely with Bright Advisers to create a comprehensive financial plan that included strategies for managing their iso nso stock options effectively, along with integrated tax planning and personalized portfolio management.
Navigating the world of stock options can feel overwhelming, especially when balancing family needs and financial goals. Ultimately, deciding when to exercise stock options is a key part of your family’s overall financial plan, considering your current situation, future aspirations, and tax implications. Effective timing can help you navigate the complexities of stock options while optimizing your financial outcomes, just like Allison and Brian did by incorporating tax optimization into their planning. By collaborating with Bright Advisers, you can equip yourself with the knowledge and strategies necessary to pave the way for a secure tomorrow for your family.
Summarize Key Differences and Suitability for Families
Navigating the world of iso nso stock options can feel overwhelming for families in Southern California, but understanding the differences between Incentive Stock Options and Non-Qualified Stock Options is crucial for your financial journey.
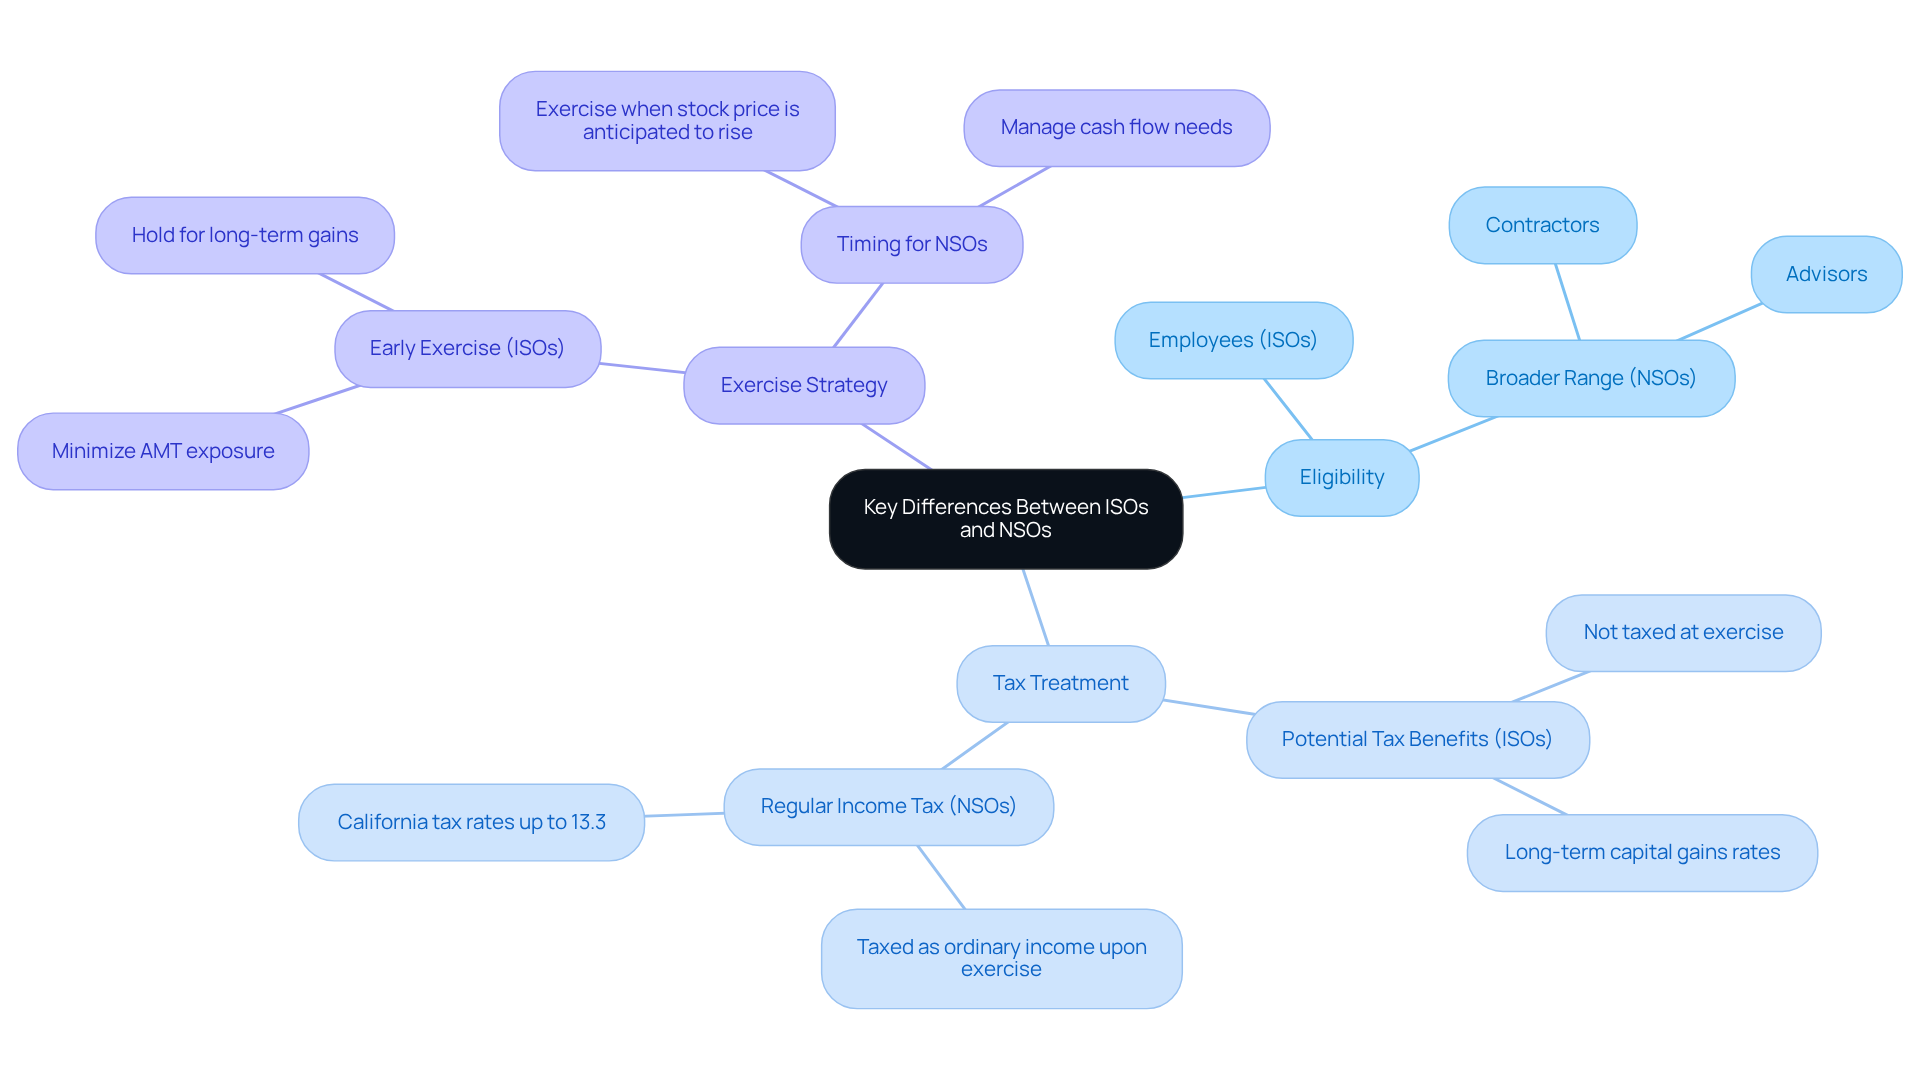
- Eligibility: Incentive Stock Options are exclusively available to employees, while NSOs can be granted to a broader range of individuals, including contractors and advisors. This means that families from different backgrounds can find value in stock options.
- Tax Treatment: Incentive Stock Options offer potential tax benefits, as they are not taxed at the time of exercise and may qualify for long-term capital gains rates if held for the required periods. On the other hand, NSOs are taxed as regular income upon exercise, which can lead to immediate tax obligations that families must consider in their planning.
- Exercise Strategy: Families may find it beneficial to exercise incentive stock options early in the year to minimize exposure to Alternative Minimum Tax (AMT) and to hold them for long-term gains. For NSOs, timing the exercise when the stock price is anticipated to rise can maximize benefits while managing cash flow needs effectively.
Many families struggle with the immediate tax obligations that come with NSOs, which can complicate financial planning. Without clarity on these differences, families may miss out on opportunities to enhance their financial futures.
Choosing between iso nso stock options should align with your family’s financial goals and tax situation. By grasping these distinctions, you can take confident steps toward securing a brighter financial future for your family.
Conclusion
Navigating the world of stock options can feel overwhelming, especially when you want the best for your family’s future. When you understand the benefits and challenges of ISOs and NSOs, you can make choices that align with your family’s dreams and secure a brighter future for your kids.
ISOs can offer tax benefits but are limited to employees, while NSOs give you more flexibility and can be offered to many people, making them a versatile choice for families. Choosing between ISOs and NSOs should be about what works best for your family’s unique needs and dreams.
By working with a fiduciary advisor like Bright Advisers, you can gain the clarity and support needed to navigate these important financial decisions. With the right guidance, you can turn these options into stepping stones for a secure and bright future for your loved ones.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are a type of stock option specifically designed for employees, offering potential tax advantages if they meet IRS requirements. They can help employees grow their wealth but may trigger the Alternative Minimum Tax (AMT) when exercised.
What are Non-Qualified Stock Options (NSOs)?
Non-Qualified Stock Options (NSOs) are stock options that do not provide the same tax benefits as ISOs. They can be granted to a broader range of individuals, including contractors and consultants, and the difference between the exercise price and the fair market value is taxed as ordinary income when exercised.
How do ISOs and NSOs differ in terms of tax treatment?
ISOs may offer tax advantages but can trigger the Alternative Minimum Tax (AMT) upon exercise, while NSOs do not have the same tax perks and are taxed as ordinary income based on the difference between the exercise price and the stock’s fair market value.
Why is it important for families to understand stock options?
Understanding stock options is crucial for families as it helps them create informed financial strategies, including retirement planning and education financing for their children, ultimately contributing to their long-term financial stability.
How can families benefit from collaborating with financial advisors regarding stock options?
By working with financial advisors like Bright Advisers, families can gain insights into optimizing their financial well-being, effectively incorporating stock options into their financial strategies, and achieving their long-term goals.
List of Sources
- Define Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs)
- Stock Option Taxes in California: ISO, NSO, and RSU Tax Planning for Tech Workers (https://ietaxattorney.com/stock-option-taxes-in-california-iso-nso-and-rsu-tax-planning-for-tech-workers)
- How are stock options taxed in California? — Secfi (https://secfi.com/learn/how-are-stock-options-taxed-in-california)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Non-Qualified Stock Options (NSO): How NSOs Work (https://carta.com/learn/equity/stock-options/nso)
- Examine Tax Implications of ISOs vs. NSOs
- How Stock Options Are Taxed: ISO vs NSO | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/how-are-stock-options-taxed)
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- US Income Tax Guide 2026 | Federal Rates, Calculators & Comparisons (https://countrytaxcalc.com/tax-guides/usa/stock-options-tax-guide-2026)
- Evaluate Timing and Strategy for Exercising ISOs and NSOs
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- Stock Option Taxes in California: ISO, NSO, and RSU Tax Planning for Tech Workers (https://ietaxattorney.com/stock-option-taxes-in-california-iso-nso-and-rsu-tax-planning-for-tech-workers)
- CPA Advisory Firm for Taxes & Business | JULIE R MERRILL CPA (https://juliemerrill.me/blog/iso-nso-tax-strategy-reduce-amt)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- Tax Planning Strategies for Incentive Stock Options (ISOs) (https://cbh.com/insights/articles/tax-planning-strategies-for-incentive-stock-options-isos)
- Summarize Key Differences and Suitability for Families
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- Stock Option Taxes in California: ISO, NSO, and RSU Tax Planning for Tech Workers (https://ietaxattorney.com/stock-option-taxes-in-california-iso-nso-and-rsu-tax-planning-for-tech-workers)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- Stock Option Tax Planning in San Francisco | SD Mayer (https://sdmayer.com/stock-option-tax-planning)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading