

Key Highlights
- Incentive Stock Options (ISOs) allow employees to purchase company stock at a predetermined price, with favourable tax treatment if specific IRS criteria are met.
- ISOs do not require tax withholding upon exercise; taxes are deferred until shares are sold, potentially qualifying for long-term capital gains tax rates.
- ISOs expire after 10 years; if an employee leaves, they typically have 90 days to exercise vested options to retain favourable tax treatment.
- Restricted Stock Units (RSUs) promise shares once vesting conditions are met, usually following a four-year vesting schedule with a one-year cliff.
- RSUs are taxed as ordinary income upon vesting, with employers required to withhold 22% for federal income taxes on amounts up to $1 million.
- Vested ISOs can convert to Non-Qualified Stock Options (NSOs) if not exercised within 90 days after leaving a company, leading to different tax implications.
- Vested RSUs remain owned after leaving a company but are taxed as ordinary income at vesting; unvested RSUs are typically forfeited.
- Tax implications differ: ISOs may trigger Alternative Minimum Tax (AMT) at exercise, while RSUs are taxed at vesting based on fair market value.
- Families should consider risk tolerance, financial goals, and tax planning when choosing between ISOs and RSUs to align with their long-term objectives.
- Bright Advisers offers personalised planning to help families navigate equity compensation complexities and optimise their financial futures.
Introduction
Many parents feel lost when trying to understand equity compensation, especially with the complexities of Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs). These financial tools can shape your family’s financial journey in ways you might not expect. Yet, many are unaware of the critical differences and implications involved.
As families navigate these choices, it’s important to consider not only the tax treatments and vesting schedules but also how these decisions align with their long-term financial goals.
Imagine if you had to leave your job – what happens to ISOs and RSUs then? How can families strategically manage these assets to secure their children’s futures?
Define ISOs and RSUs: Key Characteristics and Features
Navigating the world of equity compensation can feel overwhelming for young families, especially when it comes to understanding Incentive Stock Options and Restricted Stock Units.
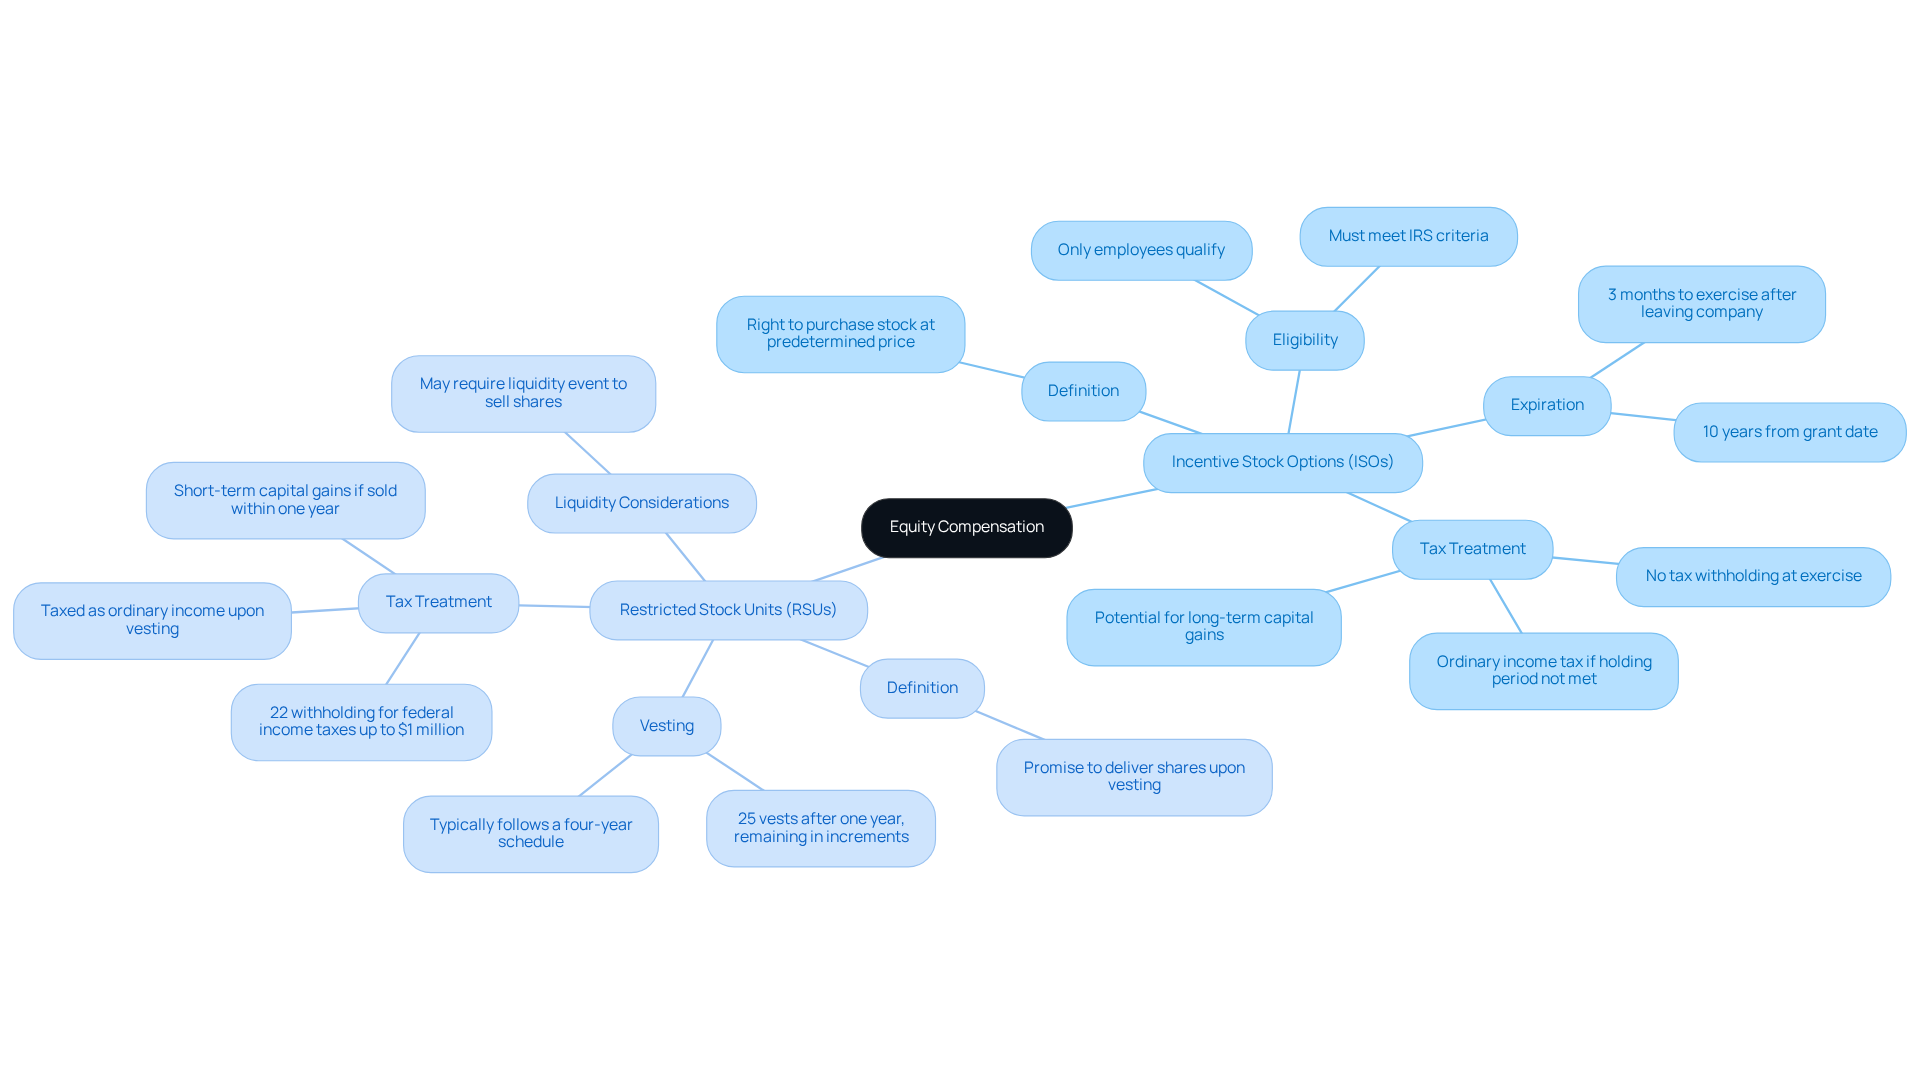
Incentive Stock Options (ISOs):
- Definition: ISOs grant employees the right to purchase company stock at a predetermined price, known as the exercise price.
- Eligibility: Only employees qualify for stock options, which must meet specific IRS criteria to receive favorable tax treatment.
- Share Treatment: You might be surprised to learn that employers don’t have to withhold taxes when you exercise your incentive stock options. Instead, obligations are postponed until you sell the shares. If you meet certain conditions, your gains may qualify for long-term capital gains tax rates, which are generally lower than ordinary income tax rates. However, this can lead to unexpected financial strain for families, particularly when tax season rolls around.
- Expiration: ISOs have a maximum expiration period of 10 years from the grant date. If you leave the company, you typically have three months to exercise your options, which is important to understand in the context of iso vs rsu after leaving company to maintain those favorable tax benefits. If you don’t meet the holding period requirements, you’ll face ordinary income tax on your gains.
Restricted Stock Units (RSUs):
- Definition: RSUs represent a promise from your employer to deliver shares of stock once specific vesting conditions are met.
- Vesting: Restricted stock units usually follow a vesting schedule, often lasting four years with a one-year cliff. This means that 25% of the grant vests after the first year, with the remaining 75% vesting in smaller increments. If you sell restricted stock units within one year of receiving them, any gain is subject to short-term capital gains tax.
- Tax Treatment: Unlike ISOs, RSUs are taxed as ordinary income upon vesting, based on the fair market value of the shares at that time. Employers must withhold 22% for federal income taxes on RSUs up to $1 million in supplemental income. This can lead to a significant tax burden, especially if a large number of shares vest in a single year.
- Liquidity Considerations: For RSUs in private companies, you may need to wait for a liquidity event, like an acquisition or IPO, before you can sell your shares.
Grasping these key traits is crucial for families as they navigate the complexities of equity compensation and plan for their economic future. For example, families like Jay & Emma, who sought guidance from Bright Advisers, successfully alleviated their monetary stress by developing a solid plan that involved enhancing tax strategies and assessing education savings options. Similarly, Emily and Mark leveraged Bright Advisers’ expertise to create a comprehensive plan that gave them the freedom to choose whether or not to continue working.
By evaluating the advantages and disadvantages of ISOs and RSUs, families can make informed choices about iso vs rsu after leaving company that align with their long-term monetary objectives. Bright Advisers provides innovative wealth management strategies, including hyper-personalized investment portfolios developed through advanced technology, factor investing, and smart beta techniques, to assist families in securing their economic futures. Remember, past performance does not guarantee future results, and all investments carry risks. By taking the time to understand these options, families can avoid surprises and make choices that truly support their financial goals. For more personalized guidance, consider reaching out to Bright Advisers, where we prioritize your family’s economic well-being.
Analyze the Impact of Leaving a Company on ISOs and RSUs
When a parent leaves a job, the fate of their Incentive Stock Options and Restricted Stock Units can feel overwhelming, especially when thinking about their children’s future.
ISOs:
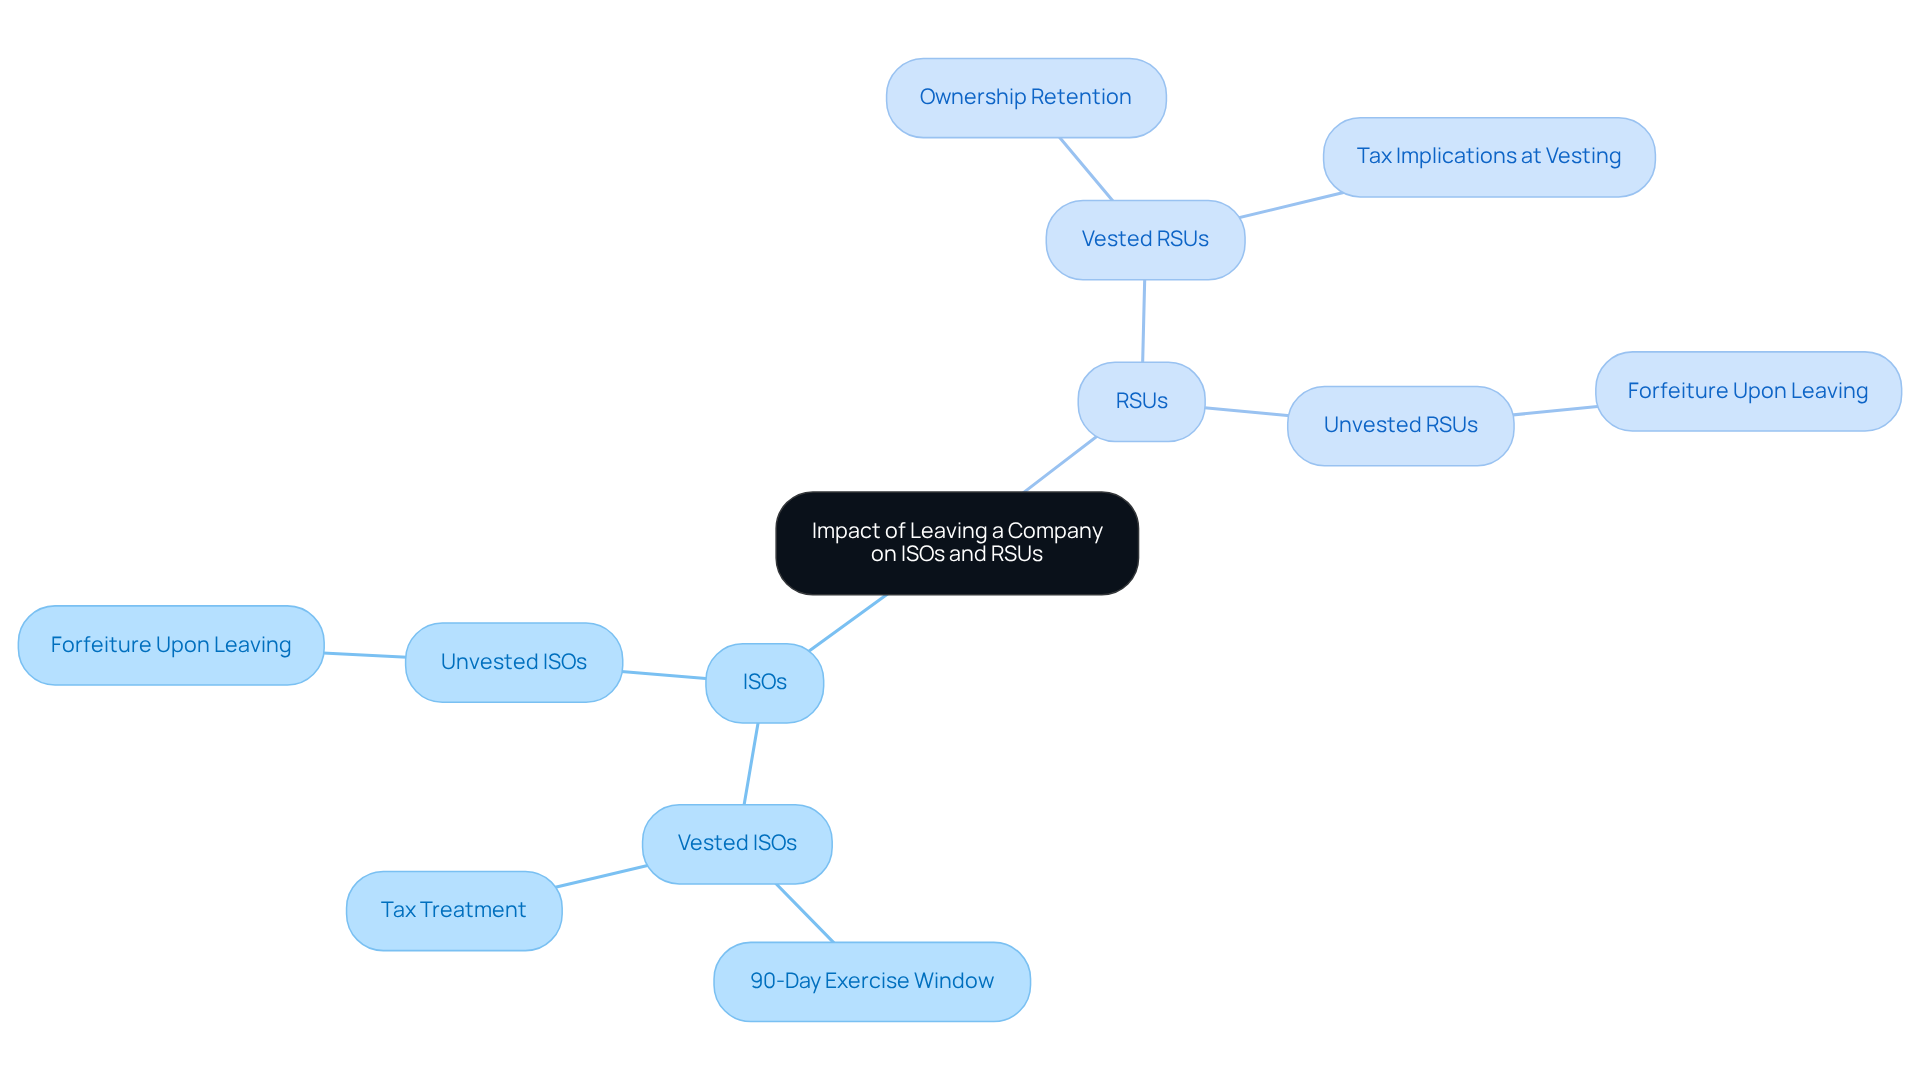
- Vested ISOs: If you have vested ISOs, you typically have a 90-day window to exercise these options to keep favorable tax treatment. If you miss this window, they convert to Non-Qualified Stock Options (NSOs), which come with different tax implications. By knowing these details, families can make informed choices that truly support their loved ones.
- Unvested ISOs: Unfortunately, unvested ISOs are usually forfeited when you leave, meaning you lose the right to purchase those shares.
RSUs:
- Vested RSUs: If you have vested RSUs, you keep ownership after leaving the company. These shares are yours, but they will be taxed as ordinary income at the time of vesting. This tax approach is something families should consider in their overall planning.
- Unvested RSUs: Unvested RSUs are typically forfeited upon departure, meaning any potential shares that haven’t yet vested are lost.
Imagine losing the chance to secure your family’s financial future because of timing. It’s important for families to understand the differences, including ISO vs RSU after leaving the company, as they can significantly impact your financial planning for your children’s futures. For instance, if a parent leaves before completing one year of service, they may lose all unvested equity, emphasizing the importance of timing and planning around vesting schedules.
At Bright Advisers, we’re here to help families navigate these complexities with personalized planning that truly understands your needs. With the right guidance, you can ensure that your family’s financial future remains bright, no matter the changes ahead.
Compare Tax Treatment of ISOs and RSUs: Implications for Employees
Navigating the tax implications of ISO vs RSU after leaving a company can feel overwhelming, especially for parents focused on their family’s future.
ISOs:
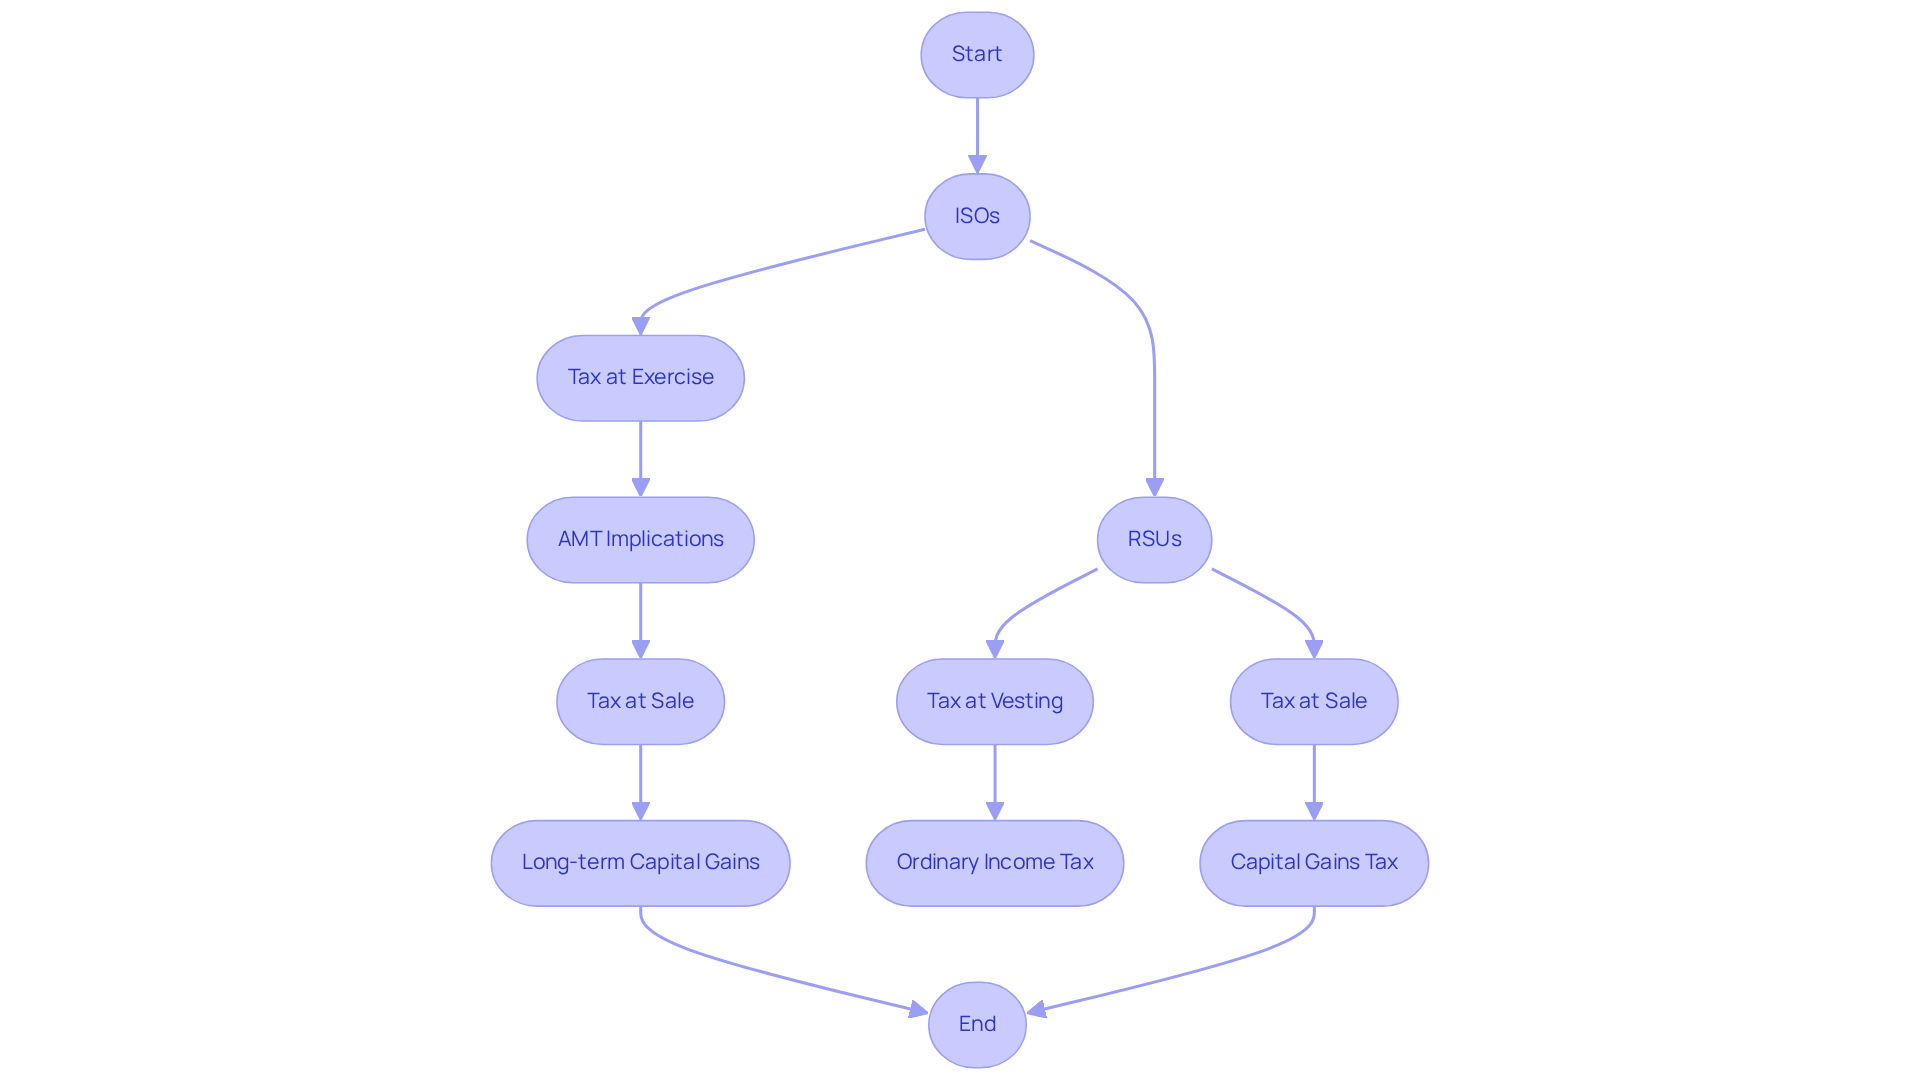
- Tax at Exercise: You won’t face regular income tax when you exercise ISOs. However, the difference between the exercise price and the fair market value at that time might trigger the Alternative Minimum Tax (AMT). You’ll want to plan carefully to avoid any surprise tax bills.
- Tax at Sale: If you hold onto your shares for at least one year after exercising and two years from the grant date, any gains will be taxed at the long-term capital gains rate, which is usually lower than ordinary income tax rates. This can significantly boost your after-tax wealth if managed well.
RSUs:
- Tax at Vesting: RSUs are taxed as ordinary income when they vest, based on the fair market value of the shares at that moment. This can lead to a hefty tax bill, especially if the shares have appreciated a lot. For example, if your RSUs vest when the stock price is high, you might find yourself in a higher tax bracket, which can increase your overall tax liability.
- Tax at Sale: After vesting, any additional gains from selling the shares are taxed as capital gains, depending on how long you hold them. If you sell within a year, these gains are taxed at ordinary income rates, while holding them longer can qualify for lower capital gains rates.
Understanding the differences in ISO vs RSU after leaving a company is key to planning your budget effectively, as they can affect your overall tax burdens and investment strategies. Imagine the stress of facing unexpected tax bills when you’re trying to provide for your family. Strategic timing of RSU vesting can help manage tax obligations, while exercising stock options at the right moments can reduce AMT exposure. Just like many families, Allison and Brian can benefit from considering these factors to secure their financial future, leading to greater economic security, funding for their children’s education, and the possibility of retiring sooner.
Evaluate Strategic Considerations: Choosing Between ISOs and RSUs
Navigating the world of stock options can feel overwhelming, especially when you’re trying to secure your family’s future. When evaluating iso vs rsu after leaving company, it’s important to consider several strategic factors that can greatly influence your financial journey.
Risk Tolerance:
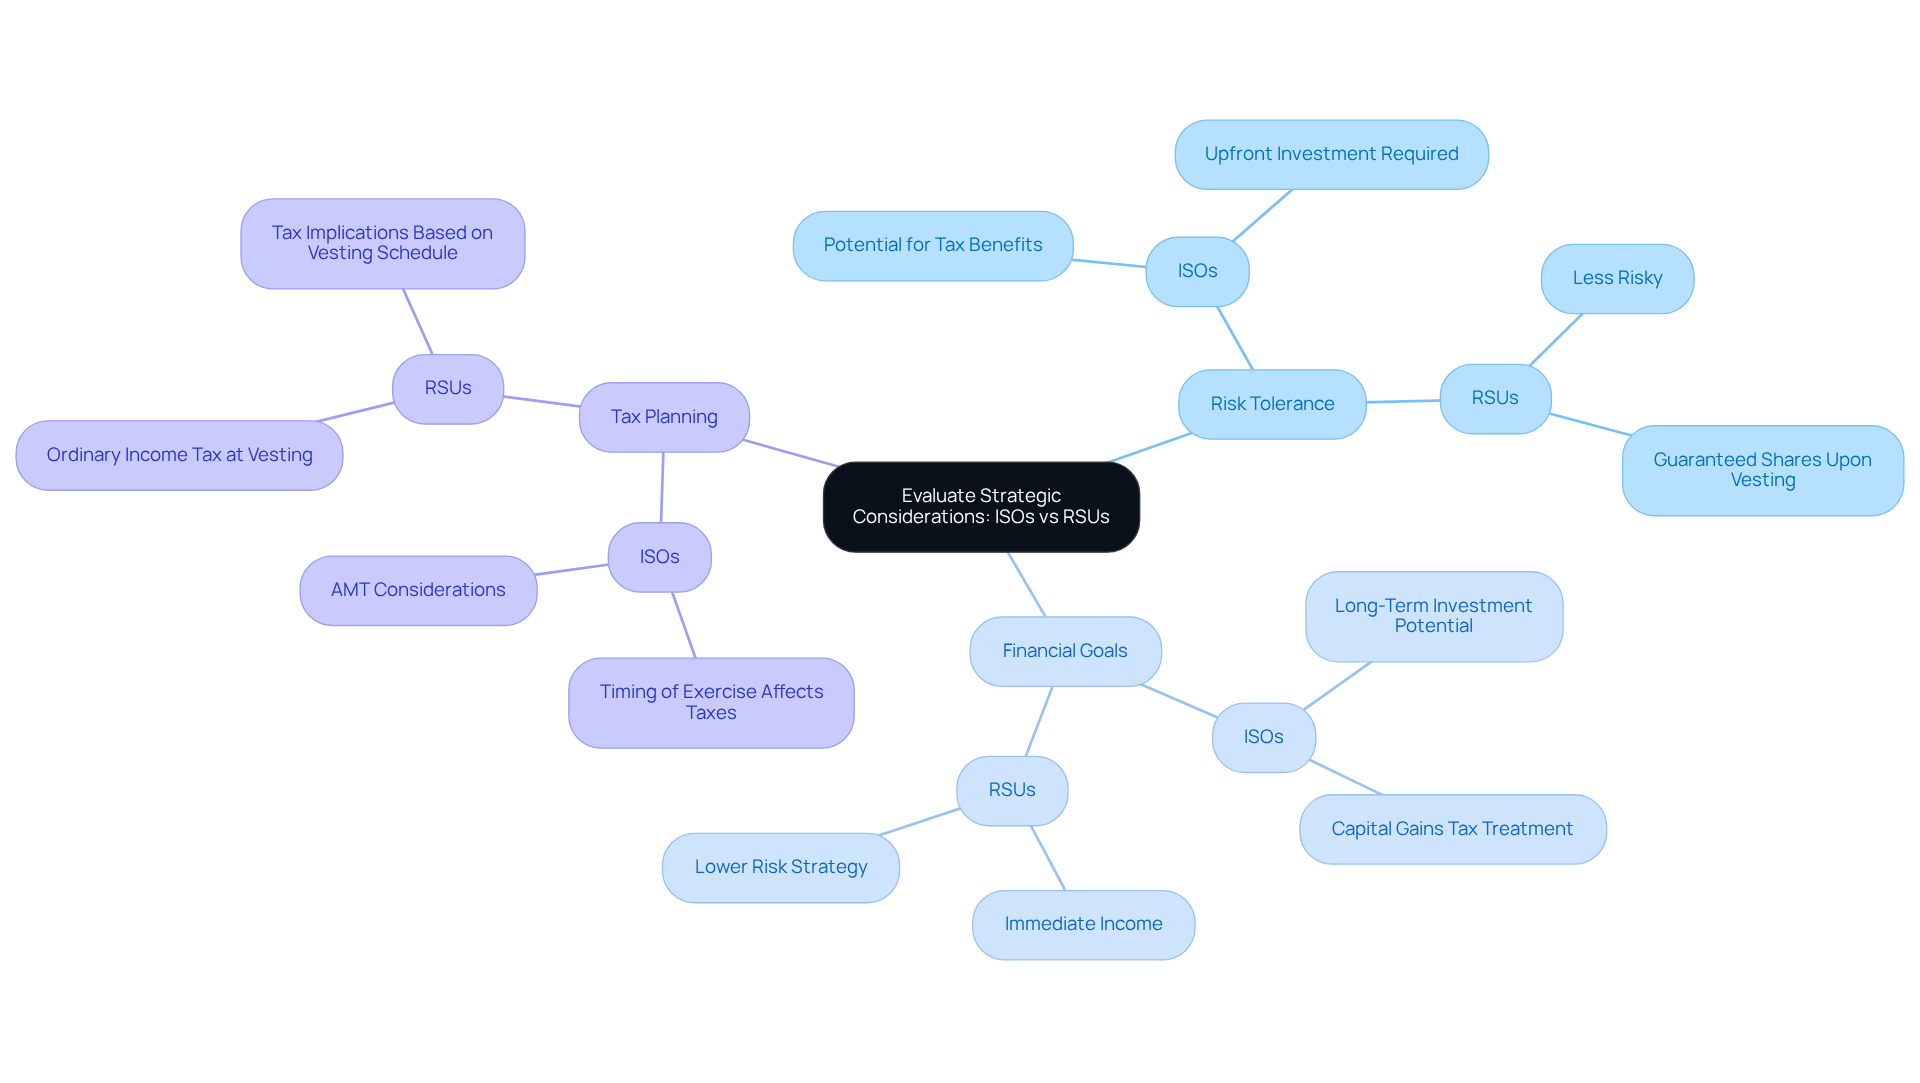
- ISOs: Imagine the worry of investing in something that could lose value; it’s a real concern for many parents. These options can be riskier since they require an upfront investment to exercise. Yet, with careful planning, they can also bring valuable tax benefits that help your family thrive.
- RSUs: On the other hand, RSUs are generally considered less risky because they represent actual shares that will be received upon vesting, regardless of stock price fluctuations.
Financial Goals:
- ISOs: If you’re looking for long-term investment opportunities and are willing to take on some risk, ISOs may be more appealing due to their potential for capital gains tax treatment. For example, Emily and Mark, a couple with ambitious career aspirations, aimed to create a budget plan that provided them the liberty to decide whether or not to keep working. By understanding their monetary situation and leveraging ISOs, they could align their investments with their long-term aspirations, particularly in the context of iso vs rsu after leaving company.
- RSUs: For those prioritizing immediate income and lower risk, restricted stock units may be the better choice, as they provide shares delivered at vesting. Jay and Emma, for instance, concentrated on alleviating monetary anxiety and efficiently distributing their resources, which involved considering RSUs as part of their strategy.
Tax Planning:
- ISOs: It’s essential to think about how your financial choices today might affect your family’s future tax situation. Exercising ISOs may trigger the Alternative Minimum Tax (AMT), so proper timing and planning can help mitigate tax liabilities. Consulting with a money advisor can provide customized strategies based on your personal circumstances. Allison and Brian, who were unaware of the financial opportunities they were missing due to inadequate tax planning, found that working with Bright Advisers helped them optimize their tax situation and secure their children’s future through education funding.
- RSUs: Since these units are taxed as ordinary income upon vesting, it’s crucial to plan for the tax implications in the year they vest to avoid unexpected burdens. Understanding the vesting schedule is key to maximizing benefits from both ISOs and RSUs, particularly in the context of iso vs rsu after leaving company.
By evaluating these strategic considerations, including the potential for future stock price volatility and the importance of consulting with financial advisors, you can make informed decisions that align with your financial goals and ensure a secure future for your family. With the right guidance, you can turn these financial choices into stepping stones for your family’s dreams. Bright Advisers is committed to helping families like yours navigate these complexities with personalized planning and tax optimization strategies.
Conclusion
Navigating the world of Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) can feel overwhelming for families, especially when planning for the future. These equity compensation types can have a big impact on your family’s financial journey, especially when it comes to planning for the future. When families understand ISOs and RSUs, they can make choices that truly reflect their hopes and dreams for the future.
ISOs can offer some tax benefits, but they also come with risks that families need to consider carefully. On the other hand, RSUs can provide more certainty since they guarantee shares once they vest, but they are taxed as regular income. Families like Emily and Mark, along with Jay and Emma, have found comfort in working with Bright Advisers to help them navigate these challenges, ensuring their financial plans reflect their dreams and values.
Choosing between ISOs and RSUs depends on your family’s unique financial situation and comfort with risk. Working with a trusted advisor like Bright Advisers can help your family make the most of your equity compensation, setting you up for a brighter future. Taking the time to understand your options today can lead to a more secure and fulfilling future for your family.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) grant employees the right to purchase company stock at a predetermined price, known as the exercise price.
Who is eligible for ISOs?
Only employees qualify for ISOs, which must meet specific IRS criteria to receive favorable tax treatment.
How are taxes handled when exercising ISOs?
Employers do not withhold taxes when you exercise ISOs; tax obligations are postponed until you sell the shares. If certain conditions are met, gains may qualify for long-term capital gains tax rates.
What is the expiration period for ISOs?
ISOs have a maximum expiration period of 10 years from the grant date. If you leave the company, you typically have three months to exercise your options to maintain favorable tax benefits.
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) represent a promise from your employer to deliver shares of stock once specific vesting conditions are met.
How does the vesting schedule for RSUs typically work?
RSUs usually follow a vesting schedule lasting four years with a one-year cliff, meaning 25% of the grant vests after the first year, with the remaining 75% vesting in smaller increments.
How are RSUs taxed?
RSUs are taxed as ordinary income upon vesting, based on the fair market value of the shares at that time. Employers must withhold 22% for federal income taxes on RSUs up to $1 million in supplemental income.
What liquidity considerations should be noted for RSUs in private companies?
For RSUs in private companies, you may need to wait for a liquidity event, such as an acquisition or IPO, before you can sell your shares.
How can families benefit from understanding ISOs and RSUs?
Understanding ISOs and RSUs helps families navigate the complexities of equity compensation and plan for their economic future, allowing them to make informed choices that align with their long-term monetary objectives.
What services does Bright Advisers provide to assist families with equity compensation?
Bright Advisers offers innovative wealth management strategies, including hyper-personalized investment portfolios and tax strategies, to help families secure their economic futures.
List of Sources
- Define ISOs and RSUs: Key Characteristics and Features
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Windham Brannon (https://windhambrannon.com/blog/incentive-stock-options-considerations-for-tech-companies)
- What is an RSU? How They Work, Benefits, & Taxes (https://carta.com/learn/equity/rsu)
- Equity Management Software with Local Expertise | Optio Incentives (https://optioincentives.com/resource-hub/what-are-rsus)
- Analyze the Impact of Leaving a Company on ISOs and RSUs
- What Happens to Stock Options if You Quit? | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/what-happens-to-stock-options-if-i-leave-the-company)
- What Happens to Vested Stock & Equity When You Leave (https://carta.com/learn/equity/leaving-company)
- What happens to my equity when I leave a company? (https://qapita.com/blog/equity-compensation-when-you-leave-a-company)
- What Happens to Your Equity When You Leave a Company? Stock Options & RSUs (https://summitry.com/blog/what-happens-to-your-equity-and-stock-options-when-leaving-a-company)
- Compare Tax Treatment of ISOs and RSUs: Implications for Employees
- RSUs vs. Options: Tax Implications of Equity Compensation (https://brightonjones.com/blog/rsus-vs-options)
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- ISOs vs RSUs: Optimize Stock Benefits | Confluence FP (https://confluencefp.com/isos-vs-rsus-strategies-to-optimize-your-employee-stock-benefits)
- Tax Insights on ISOs, RSUs, and NQSOs: A Complete Guide | RGWM (https://rgwealth.com/insights/planning-for-taxes-generated-from-equity-compensation-plans)
- Evaluate Strategic Considerations: Choosing Between ISOs and RSUs
- ISOs vs RSUs: Optimize Stock Benefits | Confluence FP (https://confluencefp.com/isos-vs-rsus-strategies-to-optimize-your-employee-stock-benefits)
- RSUs vs stock options: Differences, taxes & how they work (https://qapita.com/blog/rsu-vs-stock-options)
- Decoding ISO, NSO, RSU? A Plain English Guide to Your Startup Equity – BGM (https://bgm360.com/news-insights/iso-nso-rsu-wtf-a-plain-english-guide-to-your-startup-equity)
- RSUs vs. ISOs: Equity Compensation 101 | Wealthspire (https://wealthspire.com/blog/rsus-vs-isos-equity-compensation-101)
- The Executive’s Guide to Equity Compensation: ISOs, NSOs, RSUs, and ESPP Strategies – Carter Financial Management (https://carterwealth.com/insights/the-executives-guide-to-equity-compensation-isos-nsos-rsus-and-espp-strategies)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading