

Key Highlights
- Incentive Stock Options (ISOs) allow employees to buy company stock at a set exercise price, offering potential tax benefits if shares are held long-term.
- ISOs can trigger Alternative Minimum Tax (AMT) upon exercise, complicating tax planning for families.
- Restricted Stock Units (RSUs) automatically grant shares upon vesting, simplifying the process but taxing them as ordinary income at their fair market value.
- ISOs require an upfront cash outlay to exercise, while RSUs do not, making RSUs more accessible for families.
- The value of ISOs depends on the stock price exceeding the exercise price, while RSUs maintain value as long as the stock is above zero.
- Families must consider immediate tax liabilities from RSUs at vesting, which can impact financial planning.
- ISOs offer favourable long-term capital gains tax rates if shares are held for the required period, while RSUs are taxed at ordinary income rates upon vesting.
- Understanding the differences between ISOs and RSUs is crucial for families to make informed financial decisions that support their long-term goals.
Introduction
Imagine trying to secure your family’s financial future while navigating the complexities of equity compensation. Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) each come with their own set of benefits and challenges. As families like yours face these important choices, you might wonder:
- Which option aligns better with your financial goals?
- How do the tax implications differ?
- What risks should you consider?
Together, we can explore the key differences between ISOs and RSUs, helping you make informed decisions that lead to a more secure financial future for your family.
Define ISOs and RSUs: Key Concepts
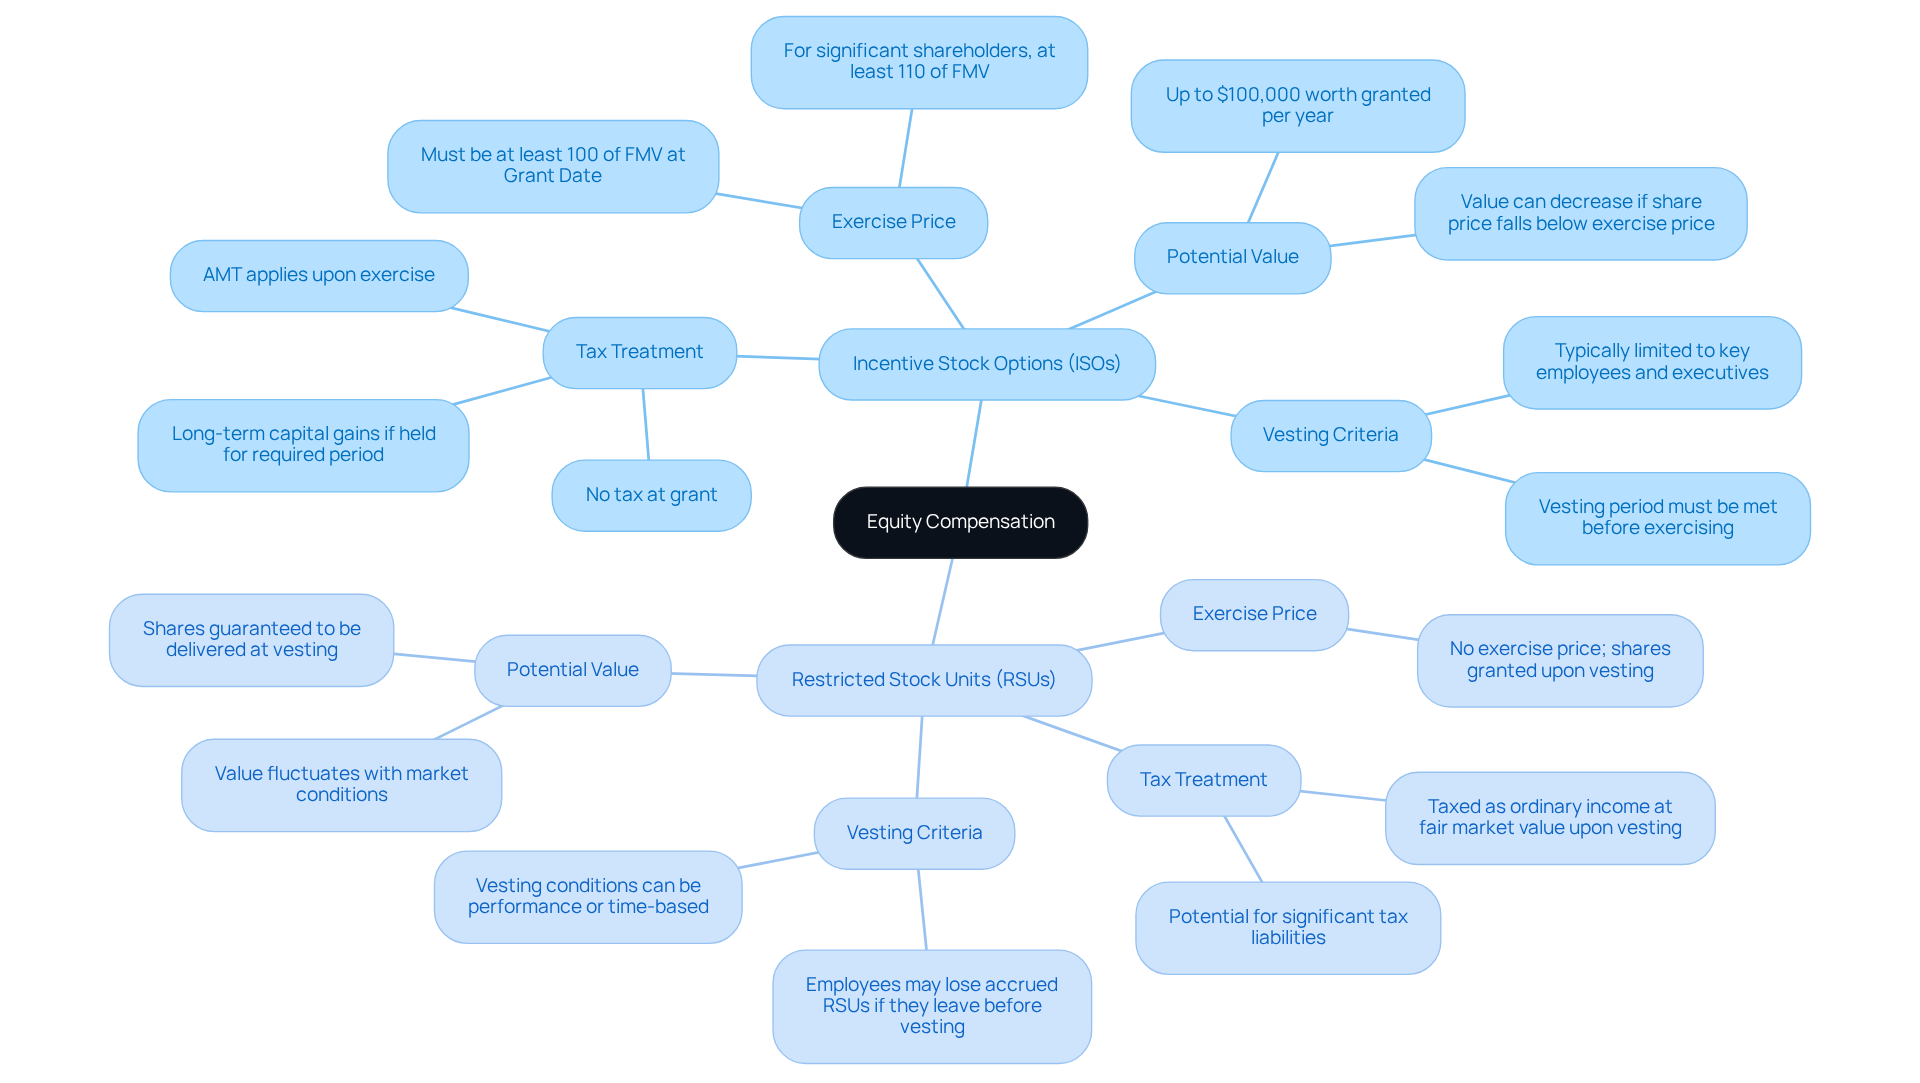
Navigating the world of equity compensation can feel overwhelming, especially when you’re focused on providing for your family. Incentive Stock Options give you the chance to buy company stock at a set price, known as the exercise price. These options are often part of your compensation package and can offer favorable tax treatment if you hold the shares for at least a year after exercising them. You might be wondering how much you can receive; typically, it’s up to $100,000 each year, depending on the stock’s value when granted. If you sell the shares after meeting the holding period, you may benefit from lower long-term capital gains tax rates. However, it’s important to remember that these options can lose value if the share price doesn’t exceed the exercise price before they expire. Imagine investing in options only to find they lose value when you need them most.
On the other hand, Restricted Stock Units automatically grant you shares once specific vesting criteria are met. This makes them a more straightforward form of equity compensation. However, keep in mind that they are taxed as ordinary income at their fair market value upon vesting, which can lead to significant tax liabilities even if you don’t sell the shares right away. This could mean unexpected financial strain when you’re trying to provide for your family.
In the tech industry, stock options are often preferred for their potential tax benefits, while restricted stock units are becoming more common as companies evolve and aim to keep talent. For instance, consider a tech professional who received 5,000 stock options at a $5 share price. When the value rose to $20 at vesting, they were able to make a significant profit upon exercising those options. Meanwhile, restricted stock units ensure you receive shares, but their worth can fluctuate with the market, impacting your overall compensation package.
Understanding the differences in ISO vs RSU for executives can help you make informed choices that support your family’s financial well-being, ensuring you’re prepared for whatever comes next.
Compare Structural Differences: ISOs vs. RSUs
Imagine feeling confident about your family’s financial future, even when faced with complex compensation options such as iso vs rsu for executives.
Ownership and Vesting:
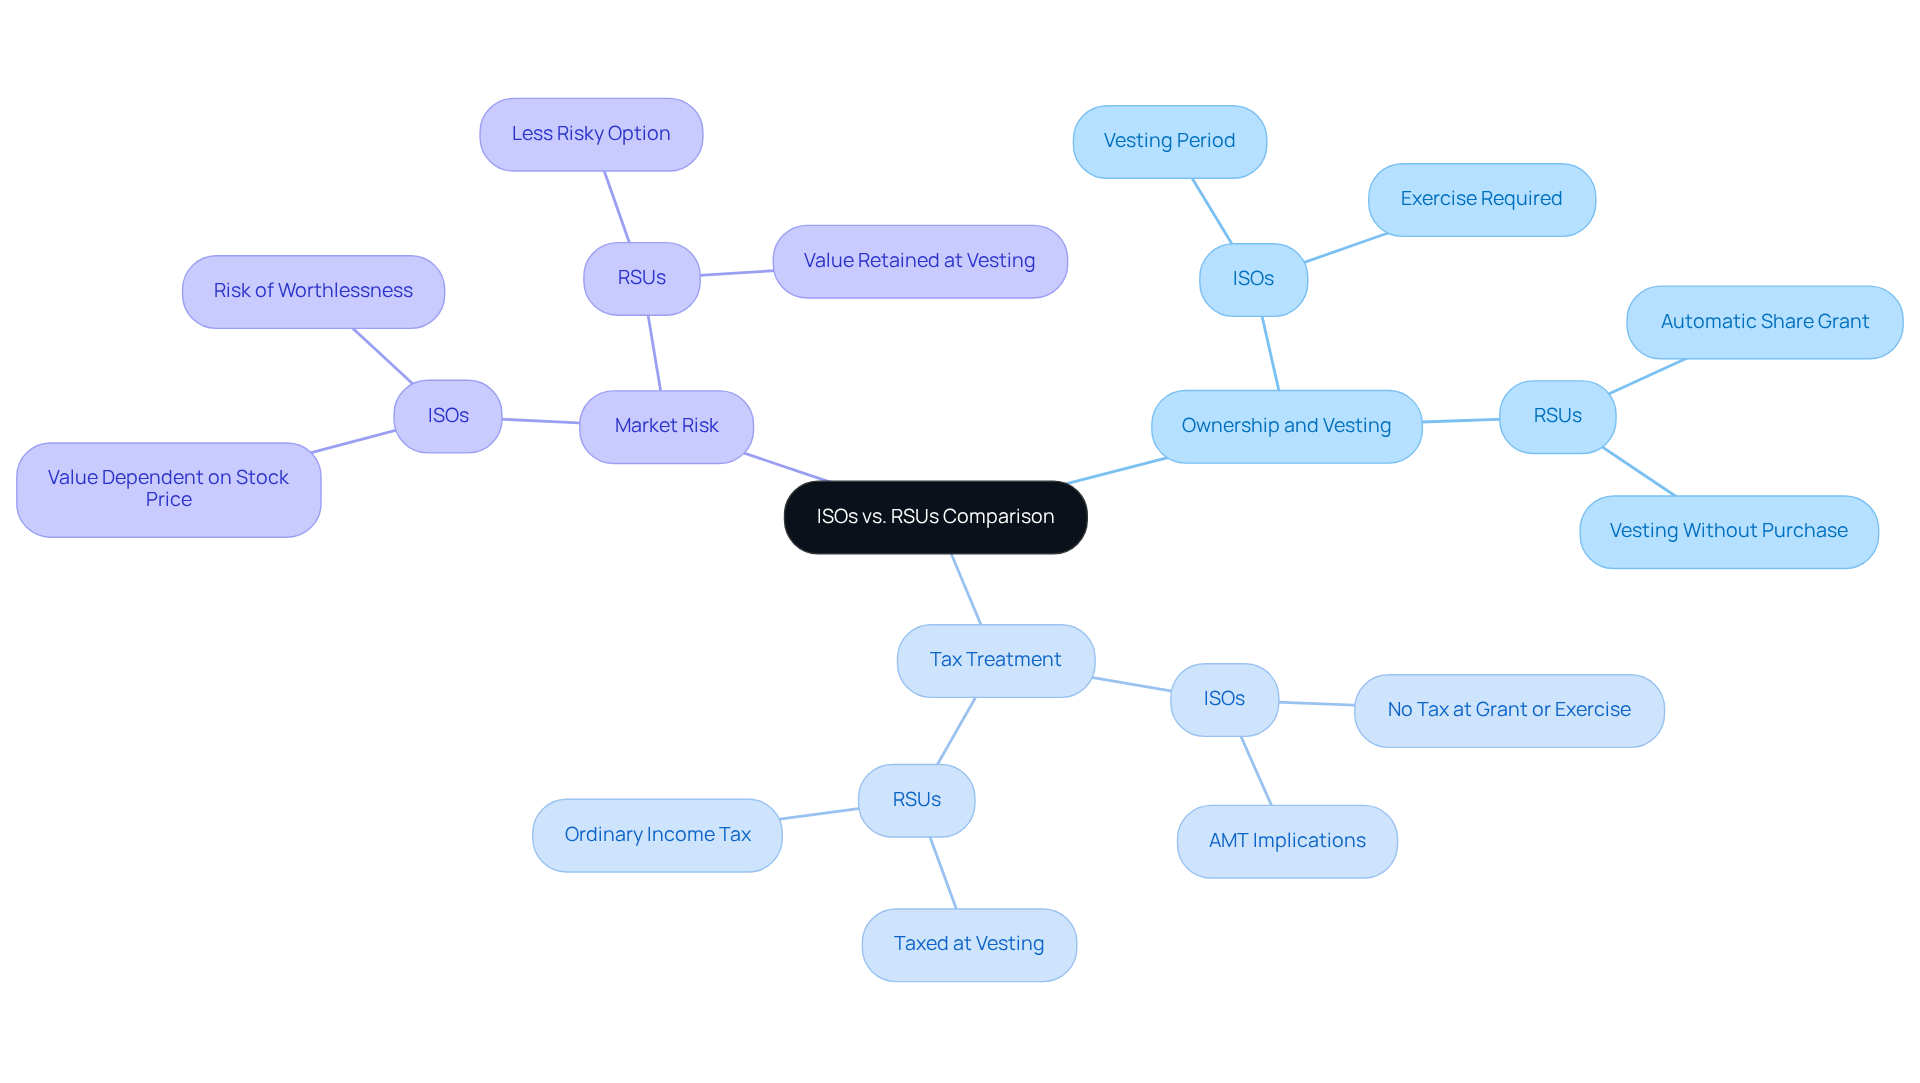
- ISOs: Employees must exercise their options to purchase shares, which requires an upfront cash outlay at the exercise price. This can feel daunting, especially when you’re trying to balance family needs. The options generally vest over a period, compelling individuals to decide when to exercise based on stock performance and personal financial strategy.
- Restricted Stock Units: Employees automatically receive shares upon vesting without any purchase requirement. This reduces the risk associated with restricted stock units, as staff do not need to use their personal funds to obtain shares, making it a more accessible option for families.
Tax Treatment:
- ISOs: Generally, there is no tax at the time of grant or exercise, but employees may face alternative minimum tax (AMT) implications when they exercise their options. Taxes are typically due only when the shares are sold, which can be a relief for families planning their finances.
- RSUs: Taxation occurs at the time of vesting, where the fair market value of the shares is treated as ordinary income. This can lead to immediate tax obligations for workers, which they must plan for accordingly, ensuring they’re prepared for any surprises.
Market Risk:
- ISOs: The value of ISOs is contingent on the stock price exceeding the exercise price. If the stock price does not rise, the options may become worthless, adding stress to your financial planning.
- Restricted Stock Units: As long as the company’s shares maintain value at the time of vesting, restricted stock units will possess worth, making them a more stable option for staff and a comforting choice for families.
Navigating the complexities of stock options can feel overwhelming, especially when considering your family’s future. Understanding iso vs rsu for executives can empower you to make informed decisions that benefit your family’s financial journey.
Analyze Tax Implications: ISOs and RSUs
Navigating the world of equity compensation can feel overwhelming, especially when tax implications come into play. Understanding the differences in ISO vs RSU for executives is crucial for making informed decisions that align with your family’s financial goals.
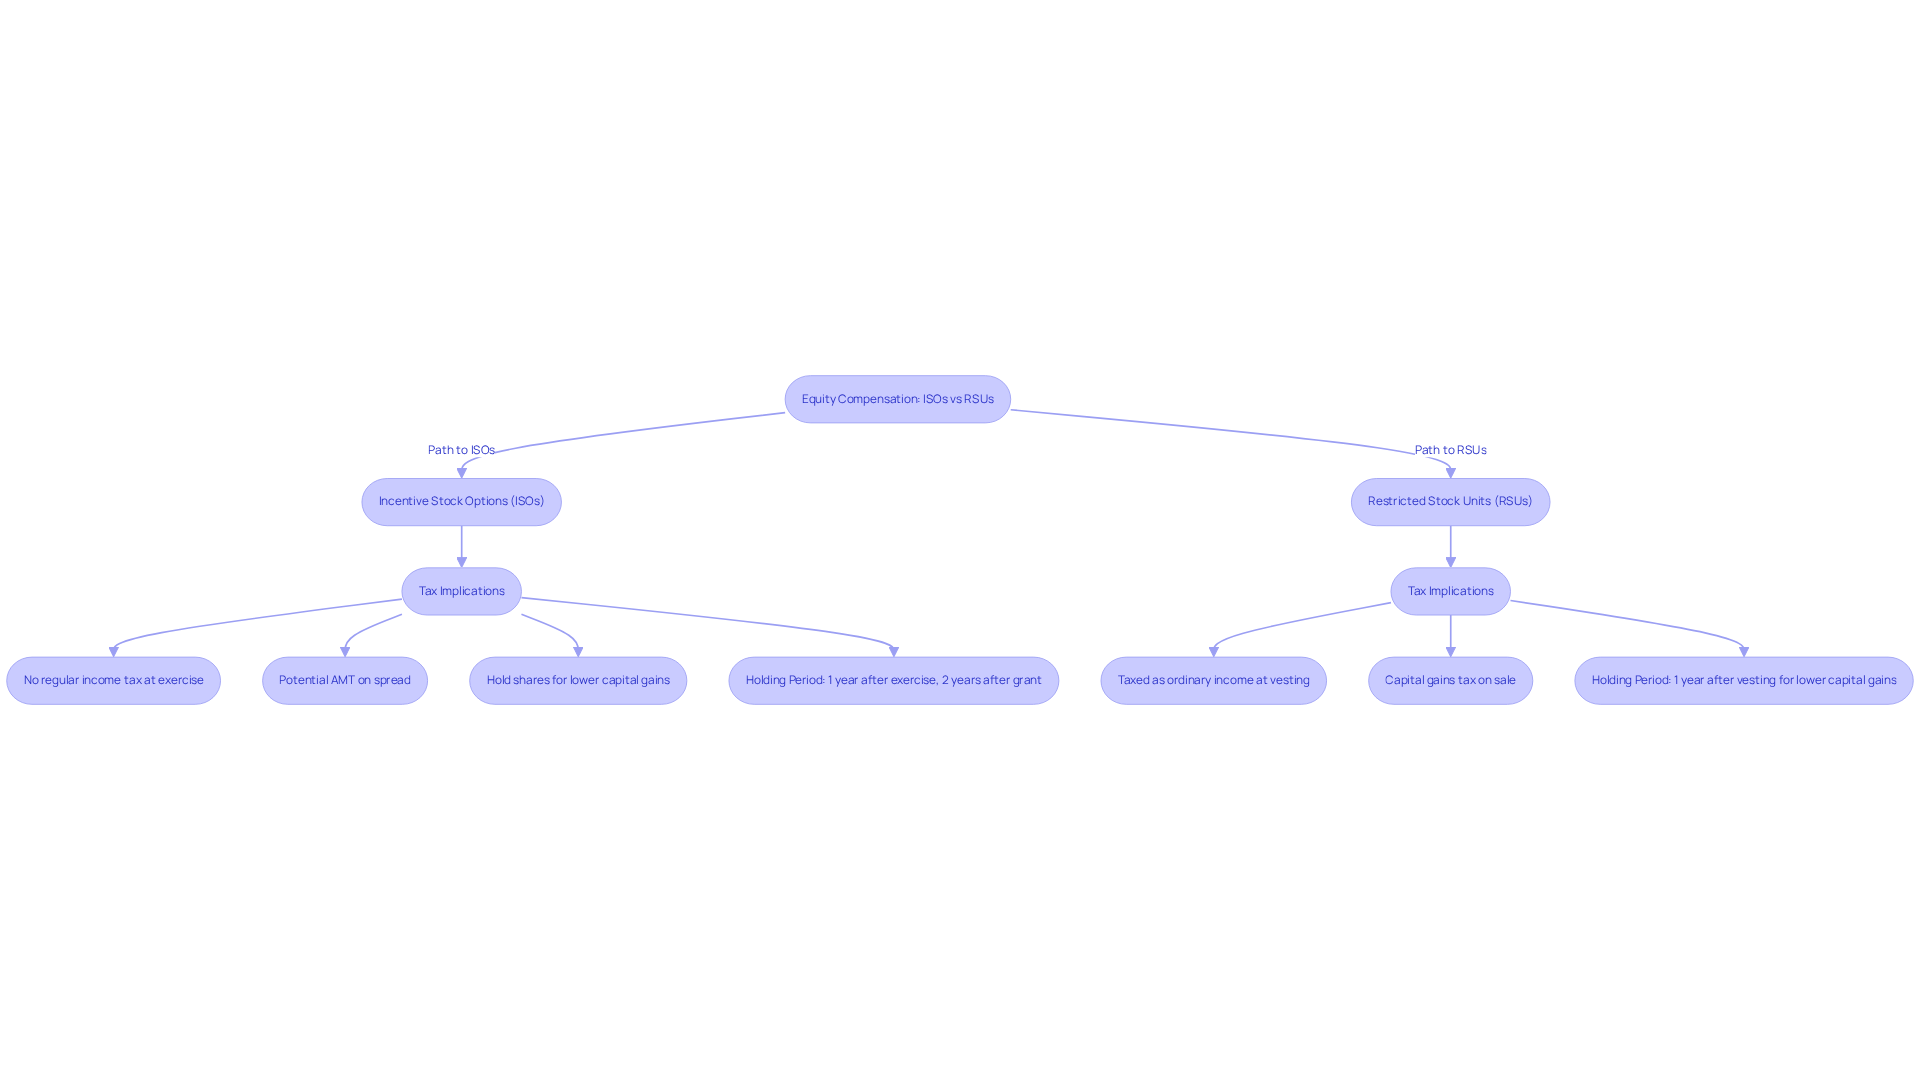
Incentive Stock Options (ISOs): A choice that can impact your family’s financial future. When it comes to exercising ISOs, you might be relieved to know that there’s generally no regular income tax due right away. However, keep in mind that the spread between the exercise price and the fair market value of the stock at exercise may trigger the Alternative Minimum Tax (AMT), which can complicate your tax planning. Imagine if you exercise options and hold shares; you could incur AMT on the difference between the exercise price and the market value.
If you hold onto those shares for a bit longer, you could benefit from lower long-term capital gains rates, which is a nice relief for your family budget. If you meet the requirements of holding the shares for at least one year after exercise and two years after the grant date, any gains are taxed at this lower rate, making it a potentially advantageous choice for maximizing your financial outcomes.
Restricted Stock Units (RSUs): Another option that comes with its own set of considerations for your family. When RSUs vest, it’s important to know that they’re taxed as ordinary income, which can feel like a surprise if the stock price is high. For instance, a single filer with a $120,000 salary and an $80,000 RSU vest could see their effective federal income tax rate approach 25% due to the added income from the RSU.
After vesting, any further gains or losses from the sale of the shares are taxed as capital gains, depending on how long you hold the shares post-vesting. If you sell within a year, the gains are taxed at ordinary income rates, while holding them for over a year qualifies for lower long-term capital gains rates.
So, what’s the main takeaway? The timing of taxation is where ISO vs RSU for executives differs significantly, and understanding this can help you better plan for your family’s needs. It’s essential to consider your individual financial situation when deciding between these options, as the right choice can lead to a more secure future for you and your loved ones. Remember, we’re here for you, ready to support you on this journey.
Evaluate Pros and Cons: ISOs vs. RSUs
Navigating the world of Incentive Stock Options and Restricted Stock Units can feel overwhelming, especially for families striving to secure their children’s future. Understanding the advantages and disadvantages of each option is crucial for aligning with your family’s financial goals.
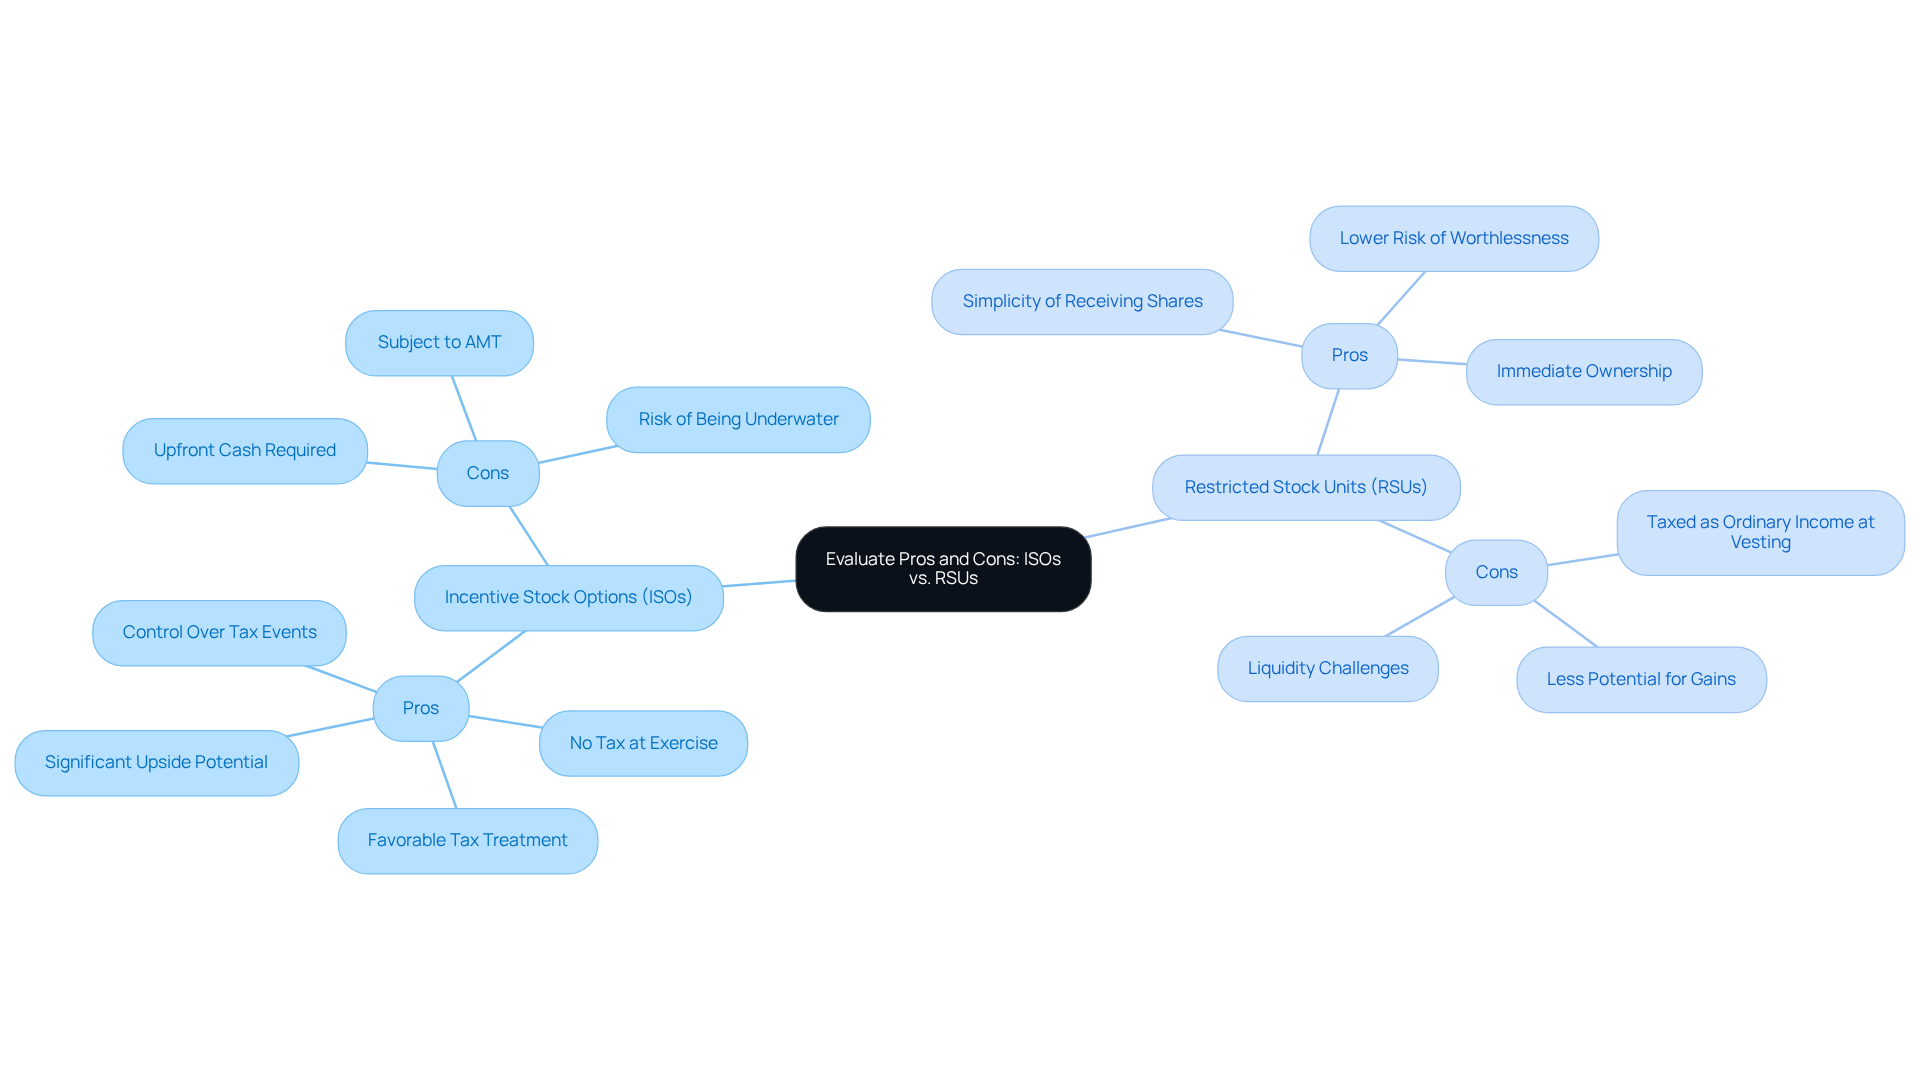
Incentive Stock Options (ISOs) can offer some appealing benefits:
- Pros:
- You might enjoy favorable tax treatment if you hold onto your shares long enough, potentially benefiting from long-term capital gains tax rates that range from 0% to 20%.
- There’s no tax incurred at the time of exercise, which can provide greater cash flow flexibility for your family.
- If the company’s stock performs well, there’s significant upside potential, allowing you to benefit from stock price appreciation.
- You have control over when to trigger tax events, helping you manage your tax liabilities effectively.
However, there are some challenges to consider:
- Cons:
- You’ll need to pay upfront cash to exercise options, which can feel like a daunting hurdle to overcome for many families.
- ISOs are subject to the Alternative Minimum Tax (AMT), which can complicate your tax planning.
- If the stock price doesn’t exceed the exercise price, the options may become worthless, leaving you with no benefit. This situation is often referred to as being ‘underwater.’
On the other hand, Restricted Stock Units (RSUs) come with their own set of advantages:
- Pros:
- Simplicity is a key advantage; you automatically receive shares upon vesting without needing to purchase them, making it easier for families to plan.
- RSUs maintain worth as long as the shares have value at vesting, lowering risk compared to stock options. They’re almost always worth something as long as the fair market value is above zero.
- Prompt ownership of shares can enhance your family’s security and align your interests with the company’s performance.
Yet, there are also some drawbacks:
- Cons:
- RSUs are taxed as ordinary income at vesting, which can create immediate tax liabilities that you’ll need to manage.
- Compared to stock options, RSUs may provide less potential for gains if the share price rises significantly after vesting.
- Liquidity challenges may arise, as RSUs require a sale or IPO for shares to be liquid.
Choosing between ISO vs RSU for executives can be a tough decision, especially when considering your family’s unique financial situation and future goals. For families like Allison and Brian, who sought guidance from Bright Advisers, incorporating tax optimization into their financial planning allowed them to secure their children’s future through education funding and gain the ability to retire sooner. By taking the time to understand these details and planning ahead, families can truly make the most of these valuable benefits together. As Gregory Weimer, a Financial Advisor, notes, “Understanding the details, planning for taxes, and integrating them into a broader financial strategy are essential steps to make the most of these benefits.
Conclusion
Imagine feeling confident in your financial decisions as a parent, knowing you’ve chosen the best path for your family’s future. Understanding the differences between Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) is essential for executives like you, aiming to make informed financial choices that benefit your loved ones. Each option has its own set of advantages and challenges, and navigating these options can feel overwhelming for families trying to secure their financial future.
ISOs offer potential tax benefits and give you control over tax events, but they require an upfront cash investment and can be subject to the Alternative Minimum Tax (AMT). On the other hand, RSUs provide a more straightforward approach to equity compensation, automatically granting shares upon vesting. However, they come with immediate tax liabilities that can catch families off guard. Choosing the right option can lead to a more secure financial future for your family, tailored to your unique circumstances and risk tolerance.
As you evaluate your options, remember that you don’t have to do this alone. We’re here to help you navigate these choices, ensuring you feel supported every step of the way. Engaging with a fiduciary advisor can provide valuable insights and guidance in making these critical decisions. With the right guidance, you can turn these choices into stepping stones for a brighter future for your family.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are a type of equity compensation that allows you to buy company stock at a predetermined price, known as the exercise price. They can offer favorable tax treatment if you hold the shares for at least a year after exercising them.
How much can I receive from ISOs each year?
Typically, you can receive up to $100,000 in ISOs each year, depending on the stock’s value when granted.
What are the tax benefits of ISOs?
If you sell the shares after meeting the holding period, you may benefit from lower long-term capital gains tax rates. However, the options can lose value if the share price does not exceed the exercise price before they expire.
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of equity compensation that automatically grants you shares once specific vesting criteria are met.
How are RSUs taxed?
RSUs are taxed as ordinary income at their fair market value upon vesting, which can lead to significant tax liabilities even if you do not sell the shares right away.
Why might companies prefer stock options over RSUs?
In the tech industry, stock options are often preferred for their potential tax benefits, while RSUs are becoming more common as companies evolve and aim to retain talent.
Can you provide an example of how stock options work?
For instance, if a tech professional receives 5,000 stock options at a $5 share price and the value rises to $20 at vesting, they can make a significant profit upon exercising those options.
How do RSUs impact overall compensation?
RSUs ensure you receive shares, but their worth can fluctuate with the market, which can impact your overall compensation package.
Why is it important to understand the differences between ISOs and RSUs?
Understanding the differences between ISOs and RSUs can help you make informed choices that support your family’s financial well-being and prepare you for future financial needs.
List of Sources
- Define ISOs and RSUs: Key Concepts
- RSUs vs. ISOs: Equity Compensation 101 | Wealthspire (https://wealthspire.com/blog/rsus-vs-isos-equity-compensation-101)
- Incentive Stock Options (ISOs) – What’s the deal? (https://jpmorganworkplacesolutions.com/insights/incentive-stock-options-isos-whats-the-deal)
- ISOs vs RSUs: Optimize Stock Benefits | Confluence FP (https://confluencefp.com/isos-vs-rsus-strategies-to-optimize-your-employee-stock-benefits)
- RSU vs Stock Options: Key Differences & Benefits (https://carta.com/learn/equity/rsu-vs-stock-options)
- Restricted Stock Units and How They Work | Wealthspire (https://wealthspire.com/blog/restricted-stock-units-rsus-how-they-work-6-common-misconceptions)
- Compare Structural Differences: ISOs vs. RSUs
- RSU vs. stock options: What’s the difference? (https://empower.com/the-currency/money/stock-options-vs-rsu)
- Stock Options vs Restricted Stock Units (RSUs): A guide (https://jpmorganworkplacesolutions.com/insights/rsus-vs-stock-options)
- RSUs vs. ISOs: Equity Compensation 101 | Wealthspire (https://wealthspire.com/blog/rsus-vs-isos-equity-compensation-101)
- NSO, ISO, RSU, ESPP, and ESOP: Making Sense of Equity Compensation Alphabet Soup – FPFoCo (https://financialplanningfortcollins.com/blog/nso-iso-rsu-espp-esop-equity-compensation)
- Analyze Tax Implications: ISOs and RSUs
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Tax Implications for Stock-Based Compensation – Bloomberg Tax (https://pro.bloombergtax.com/insights/federal-tax/tax-implications-for-stock-based-compensation)
- RSU tax for expats: how foreign RSUs are taxed | 2026 (https://taxesforexpats.com/articles/tax-saving-strategies/foreign-rsu-tax.html)
- Evaluate Pros and Cons: ISOs vs. RSUs
- RSU vs Stock Options: Key Differences & Benefits (https://carta.com/learn/equity/rsu-vs-stock-options)
- Stock Options vs Restricted Stock Units (RSUs): A guide (https://jpmorganworkplacesolutions.com/insights/rsus-vs-stock-options)
- ISOs vs RSUs: Optimize Stock Benefits | Confluence FP (https://confluencefp.com/isos-vs-rsus-strategies-to-optimize-your-employee-stock-benefits)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading