

Key Highlights
- Incentive Stock Options (ISOs) allow purchase of company stock at a set price, potentially qualifying for favourable tax treatment if conditions are met.
- California does not recognise federal tax benefits for ISOs, leading to unexpected taxes and AMT implications upon exercise.
- Restricted Stock Units (RSUs) promise shares upon vesting, taxed as ordinary income, which can create significant tax burdens in high-tax states like California.
- ISOs do not provide ownership until exercised, while RSUs grant immediate ownership and associated rights upon vesting.
- Tax treatment for ISOs generally defers taxes until shares are sold, while RSUs incur taxes at vesting, impacting cash flow.
- Families should consider monetary objectives, tax implications, risk tolerance, long-term planning, and family considerations when choosing between ISOs and RSUs.
- Professional guidance from Bright Advisers can help families navigate the complexities of equity compensation and tax strategies.
Introduction
Many families feel lost when it comes to equity compensation, especially young parents like Allison and Brian. Understanding the nuances of Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) in California can be overwhelming. These financial tools can significantly impact family finances, offering both opportunities and challenges.
As young parents strive to secure their financial futures, it’s important to understand how ISOs and RSUs differ in terms of:
- Tax implications
- Ownership rights
- Overall benefits
Let’s explore these important differences together, providing insights that can help families make informed decisions tailored to their unique financial goals.
Define ISOs and RSUs: Key Concepts in Equity Compensation
Understanding Incentive Stock Options and Restricted Stock Units is vital for families like Allison and Brian, who are navigating their financial futures with care and concern.
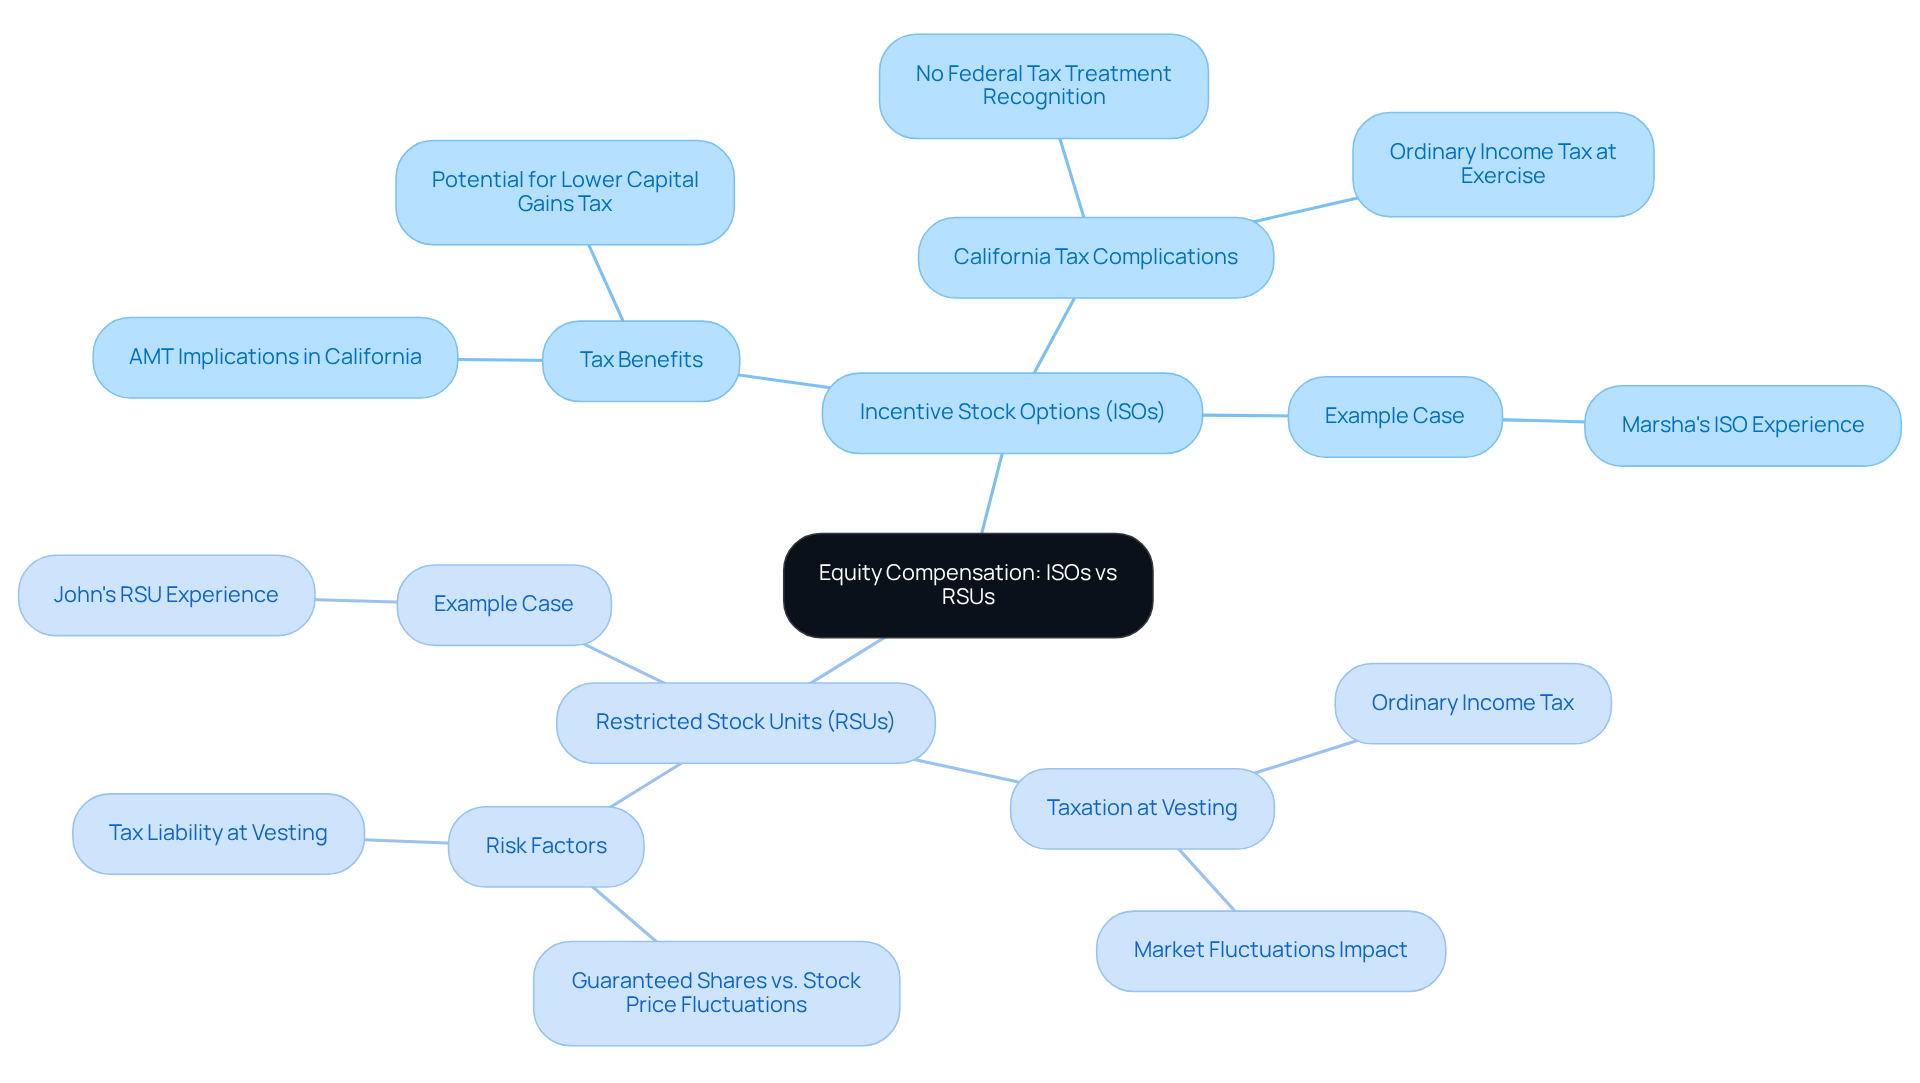
Incentive Stock Options allow you to buy company stock at a set price, which can be a great opportunity for your family. If you meet certain conditions, these options can even qualify for favorable tax treatment. This means that if the stock price goes up, you might pay lower capital gains taxes instead of ordinary income tax. However, in California, things get tricky because the state doesn’t recognize the federal tax benefits, which can lead to unexpected taxes when you exercise your options. Plus, the gain from exercising stock options is subject to the Alternative Minimum Tax (AMT) in California, adding another layer of complexity. This is why professional tax planning is so important to help you navigate these challenges effectively.
On the other hand, Restricted Stock Units (RSUs) promise to deliver shares of stock to you once certain conditions are met. When these shares vest, they are taxed as ordinary income, which can lead to a hefty tax bill, especially in high-tax states like California. Unlike stock options, RSUs guarantee shares as long as the company stays solvent, making them less risky when it comes to stock price fluctuations at the time of vesting.
Imagine Marsha, a software engineer, who was awarded 5,000 stock options at a strike price of $5. After four years, the share price rose to $20, allowing her to exercise her options and realize a profit of $75,000. However, she faced ordinary income tax on this profit due to California’s tax regulations. If the share price were to rise to $100 on May 30, 2032, Marsha could sell her shares for $500,000, making a profit of $475,000. In contrast, if Marsha had received RSUs instead, she would have been taxed on the value of the shares at vesting, which could also lead to a substantial tax liability depending on the stock’s performance at that time.
Understanding the differences in ISO vs RSU in California is essential for families to avoid costly mistakes and make the most of their benefits. By seeking guidance from professionals like Bright Advisers, families can confidently navigate their financial journey and make informed decisions that support their goals.
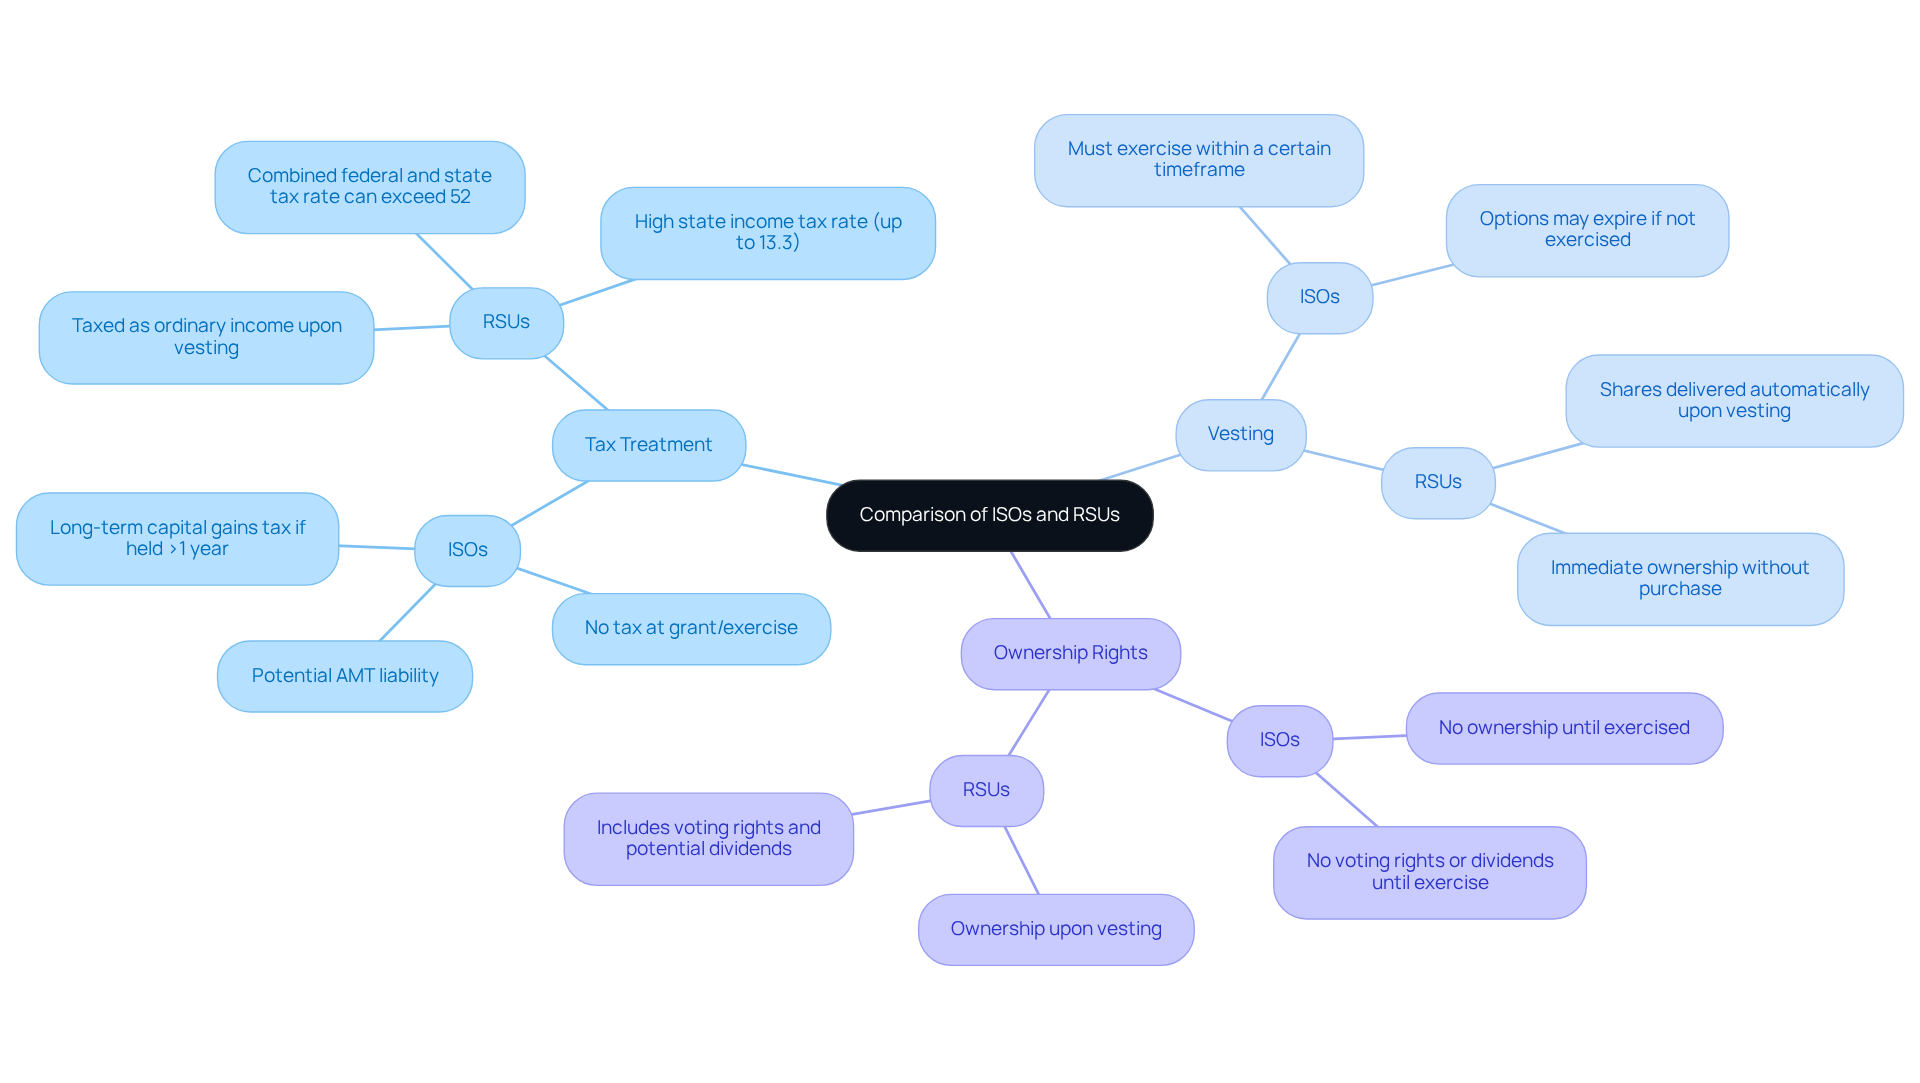
Compare Key Differences: Tax Treatment, Vesting, and Ownership Rights
Navigating the world of stock options can feel overwhelming, especially when you’re trying to secure your family’s future. When considering iso vs rsu in california, understanding the differences is crucial for making informed decisions.
Tax Treatment:
- ISOs: Generally, there’s no tax at the time of grant or exercise. However, when evaluating iso vs rsu in california, exercising stock options might trigger the Alternative Minimum Tax (AMT), which can be as high as 7%. You’ll typically owe taxes only when you sell the shares, provided you meet the holding period requirements. If you hold the shares for more than a year after exercising, you may qualify for lower long-term capital gains tax rates, which can be up to 20% federally.
- RSUs: These are taxed as ordinary income upon vesting, which can lead to a significant tax burden for families. In California, when considering iso vs rsu in california, it’s important to note that the state income tax rate can reach up to 13.3%, contributing to a combined federal and state tax rate that may exceed 52% for high earners. This immediate tax liability can feel daunting, especially when managing multiple financial responsibilities.
Vesting:
- ISOs: Vesting schedules can vary, but you must exercise your options within a certain timeframe after they vest. If you don’t exercise them, they may expire, which could mean lost value.
- RSUs: Once vested, the shares are automatically delivered to you, providing immediate ownership without needing to make a purchase. This feature makes RSUs a more straightforward option for families looking for immediate equity in the company.
Ownership Rights:
- ISOs: You don’t own the stock until you exercise your options, meaning you won’t have voting rights or dividends until that point. This can delay the benefits of ownership.
- RSUs: You gain ownership of the shares upon vesting, which includes voting rights and potential dividends. This prompt ownership can be beneficial for families wanting to participate more actively in their company’s governance and gain from dividends as part of their investment strategy.
By understanding iso vs rsu in California, you can navigate your family’s financial planning with confidence, even in a high-tax state.
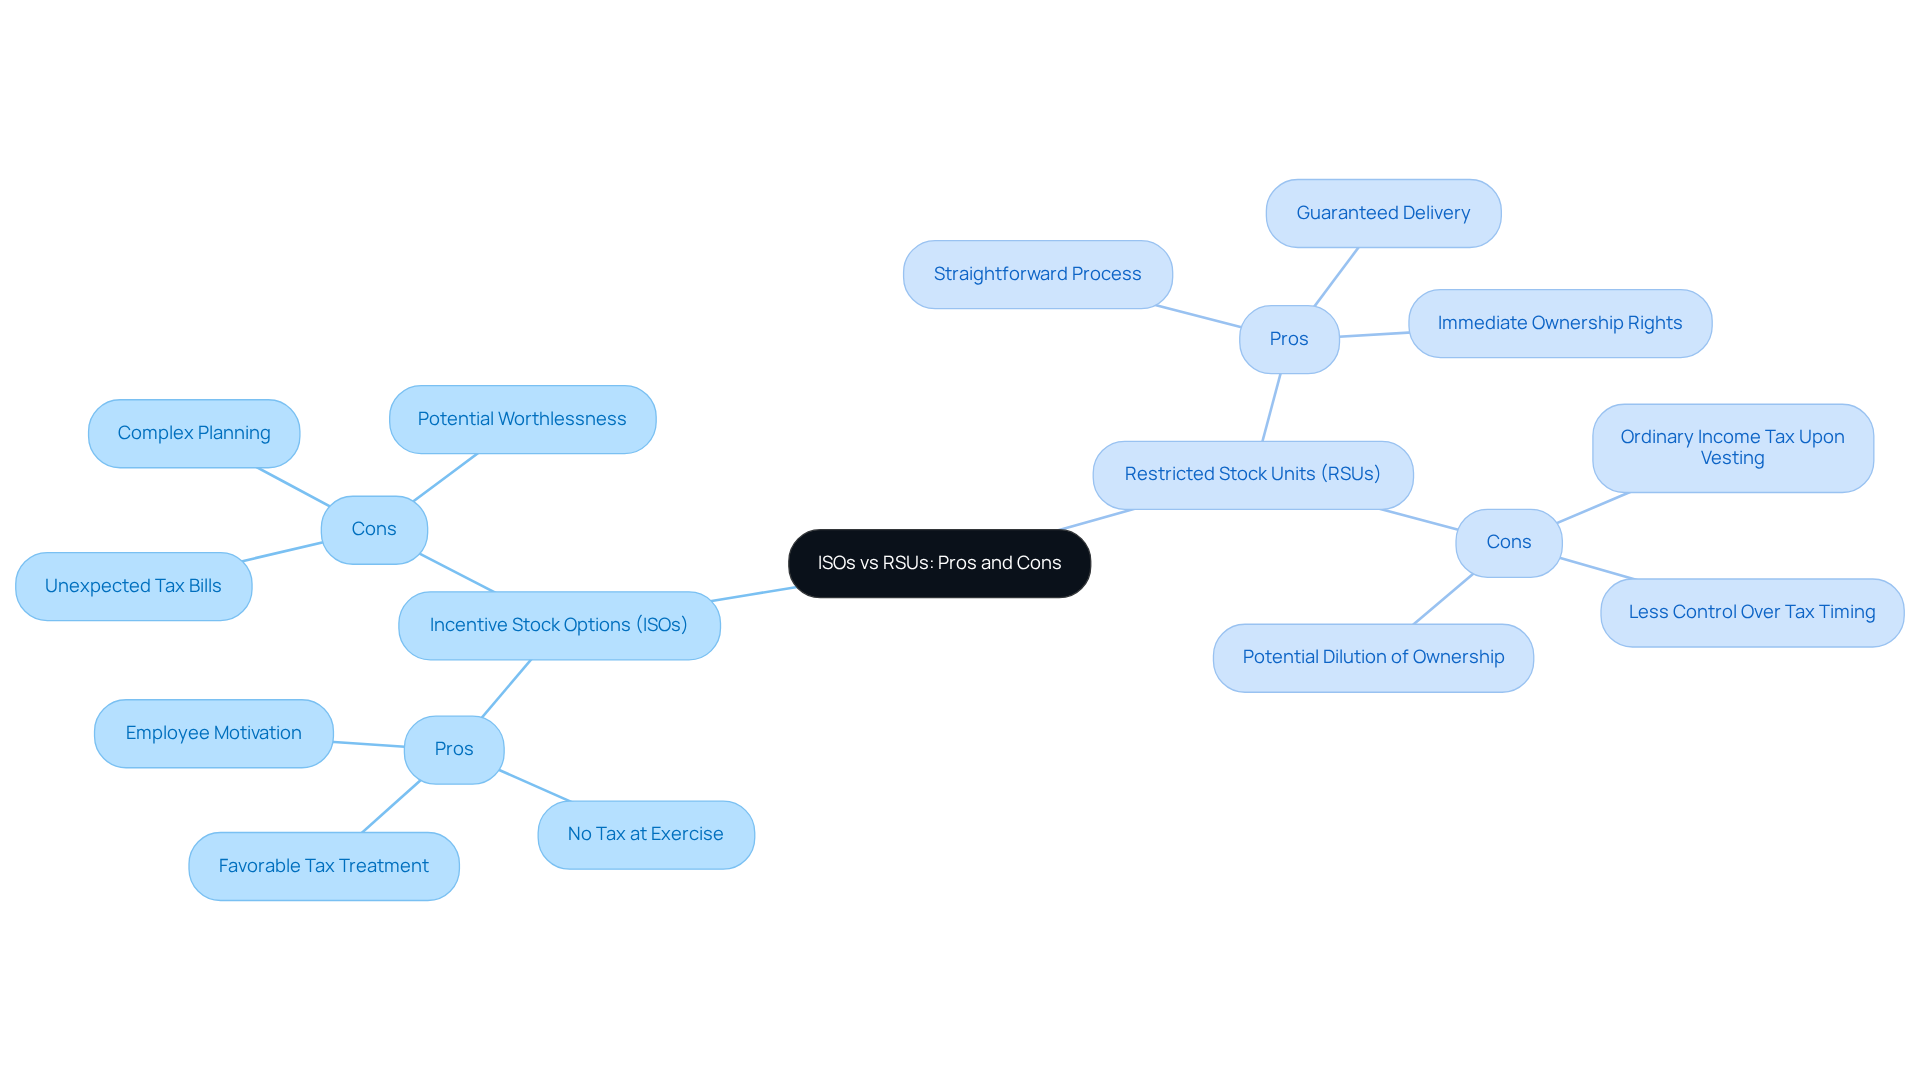
Evaluate Pros and Cons: Benefits and Drawbacks of ISOs vs. RSUs
Navigating the world of stock options can feel overwhelming, especially when it comes to making the best choices for your family’s financial future. When considering ISO vs RSU in California, both Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) offer unique advantages and disadvantages that can impact your family’s well-being through thoughtful tax planning.
Incentive Stock Options (ISOs):
-
Pros:
- If you hold onto your shares long enough, you might enjoy favorable tax treatment, allowing for capital gains tax rates instead of ordinary income tax rates, which can be as high as 37%. In 2025, long-term capital gains are taxed at a maximum rate of 23.8%.
- There’s no tax at exercise, which can really help with cash flow management for households. Just like Allison and Brian, who improved their financial situation by refining their tax strategies.
- ISOs can motivate employees by aligning their interests with the company’s performance, fostering a sense of ownership.
-
Cons:
- It’s important to understand that exercising these options can sometimes lead to unexpected tax bills, adding stress to your family’s financial planning.
- Careful planning is essential to maximize tax benefits, which can be complex for those unfamiliar with tax laws. This complexity is why individuals like Allison and Brian sought professional guidance from Bright Advisers.
- If the stock price declines, the options may become worthless, resulting in a loss of potential income.
Restricted Stock Units (RSUs):
-
Pros:
- RSUs are straightforward; employees receive shares upon vesting without needing to purchase them, making it easier for families to understand.
- You’re guaranteed delivery of shares upon vesting, reducing risk compared to ISOs, as long as the company remains solvent.
- Immediate ownership rights upon vesting, including voting rights and dividends, can enhance engagement and connection to the company.
-
Cons:
- RSUs are taxed as ordinary income upon vesting, which can create a significant tax burden, especially in high-tax states like California. This is a crucial factor for households striving to secure their economic future, as demonstrated in the situation of Allison and Brian.
- You have less control over tax timing compared to ISOs, as taxes are due at vesting regardless of whether the employee sells the shares.
- There’s a potential for dilution of ownership if the company issues more shares, impacting existing shareholders.
Understanding these advantages and disadvantages is essential for families evaluating their equity compensation choices. They can greatly influence budgeting and investment approaches. By integrating tax strategies into their plans, households can attain enhanced economic stability, much like the results achieved by Allison and Brian with Bright Advisers. This strategic approach not only helps in minimizing tax liabilities but also supports long-term goals such as education funding and early retirement. Together, we can navigate this journey toward a more secure future for your family.
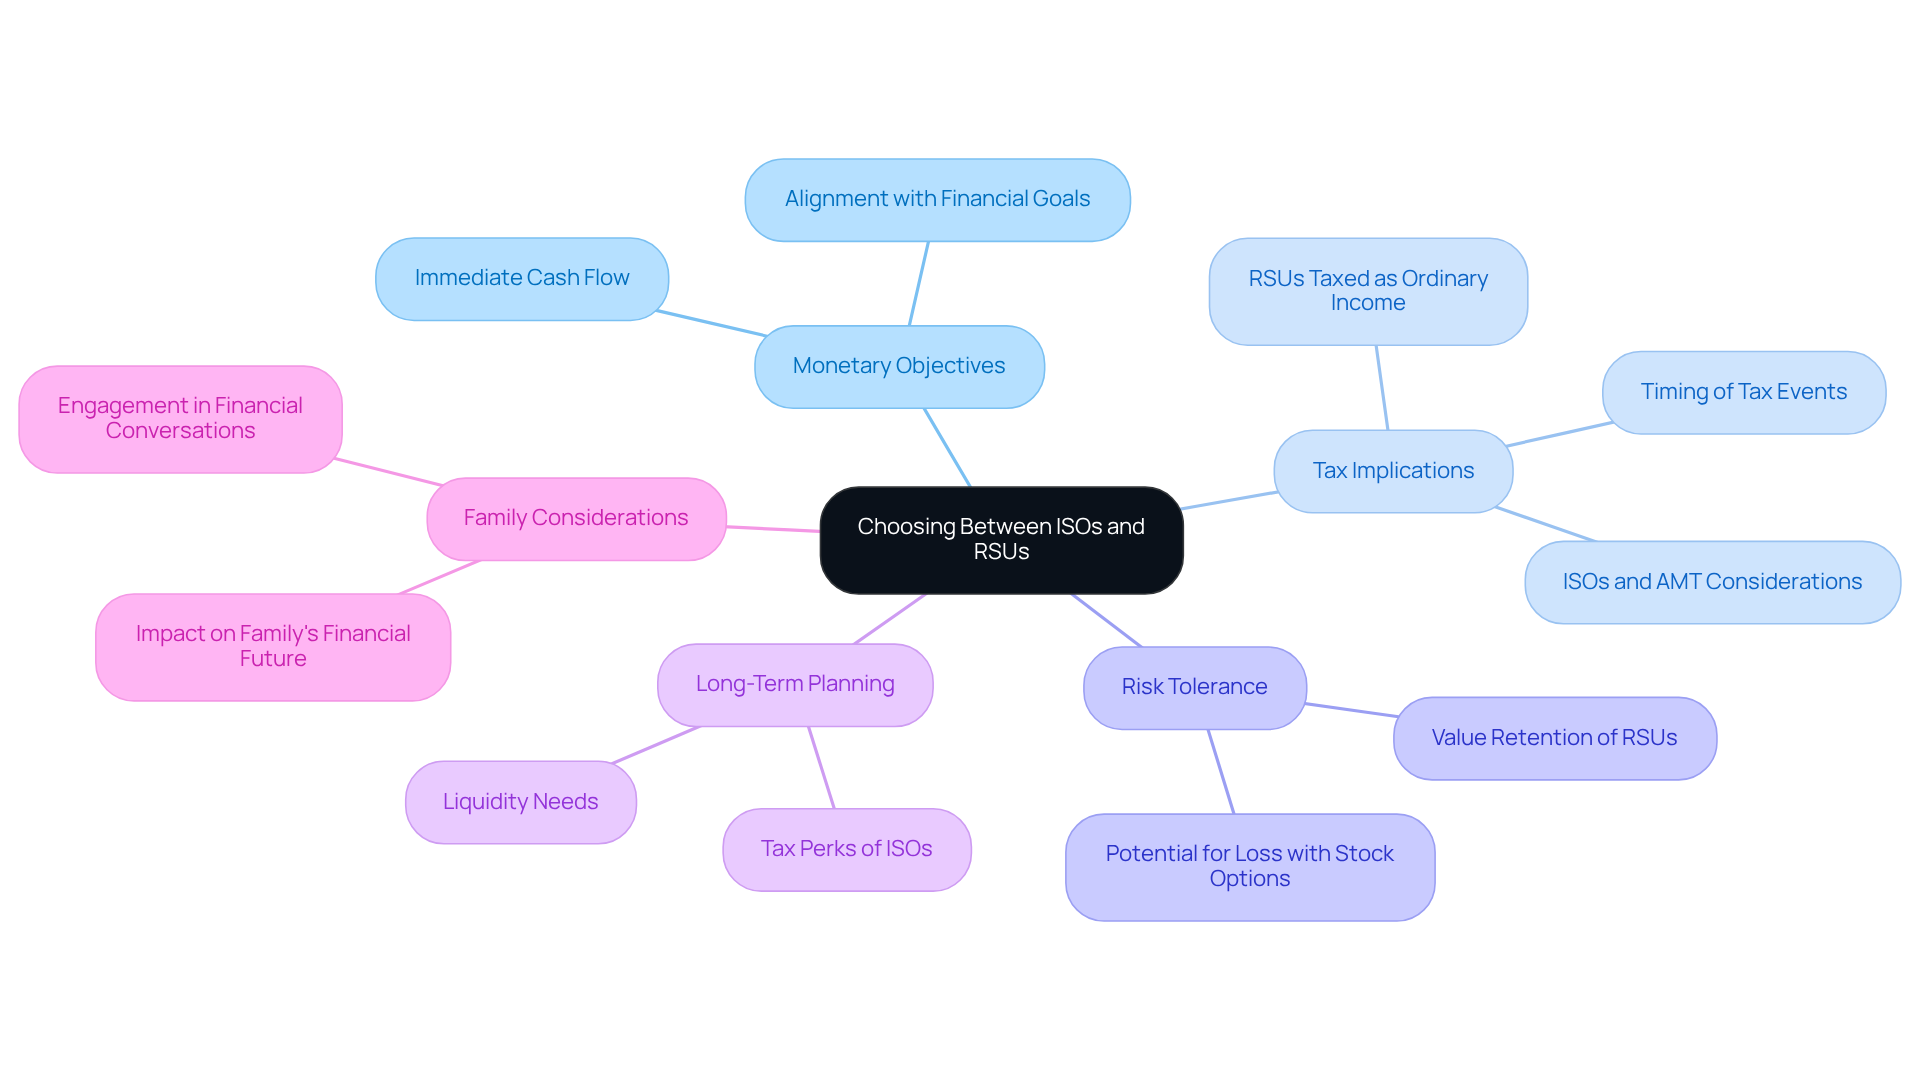
Assess Practical Considerations: Choosing Between ISOs and RSUs for Family Financial Goals
Navigating the world of stock options can feel overwhelming, especially when you’re trying to secure your family’s financial future. When deciding between Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs), young parents should consider several practical factors:
-
Monetary Objectives: Think about how each choice aligns with your household’s financial goals. If immediate cash flow is a priority, RSUs might be more beneficial since they provide shares delivered at vesting. This can be crucial for families needing liquidity. We’re here to help you create a financial plan that truly reflects what matters to your family, making sure your investments align with your dreams.
-
Tax Implications: It’s important to assess your current tax situation and how each option might affect your tax liability. Families in high-tax states like California should be particularly aware of the differences in iso vs rsu in california, as RSUs are taxed as ordinary income at their fair market value upon vesting, which can lead to a significant tax burden. At Bright Advisers, we employ innovative tax strategies, including tax-loss harvesting, to help families navigate these complexities and improve their tax situations. Plus, our clear fee structure means no hidden charges, allowing you to focus on budgeting without any surprises.
-
Risk Tolerance: Consider how comfortable you are with risk. Stock options can offer greater potential rewards but come with complexities and the risk of loss if the stock price declines. On the other hand, RSUs are generally less risky, as they typically retain value as long as the stock price is above zero. This provides more certainty, but it may lead to higher immediate tax bills. But what if the stock price drops? That’s a risk to consider.
-
Long-Term Planning: Reflect on how each option fits into your long-term financial strategy. If you’re thinking long-term, considering iso vs rsu in california might give you some tax perks. But if you need quick access to cash, RSUs could be the way to go. Bright Advisers can assist you in developing a thorough strategy framework that aligns your investment decisions with your long-term objectives.
-
Family Considerations: Discuss how your choice will affect your family’s financial future. Engaging in conversations about equity compensation with your partner can help align your financial strategies. Moreover, consulting with advisors at Bright Advisers can offer customized guidance on equity compensation and investment strategies, ensuring both parents are on the same page regarding wealth management.
With the right guidance, you can navigate these choices with confidence. If you’re interested in personalized financial planning, consider joining our waitlist to get started. Imagine making choices today that pave the way for a brighter tomorrow for your family.
Conclusion
Imagine feeling confident about your family’s financial future, knowing the best options for your unique situation. Families often feel overwhelmed by the complexities of financial options, especially when considering the impact of taxes. Understanding these differences can empower families to take control of their financial futures.
ISOs can be beneficial but come with some tax challenges, while RSUs offer guaranteed shares that are taxed differently. Having immediate ownership with RSUs can help families feel more involved in their financial journey. Every family’s financial situation is unique, and it’s important to consider what feels right for you and your loved ones.
Working with caring professionals like Bright Advisers can help you find the best path for your family’s needs. With the right guidance, your family can thrive financially, ensuring a brighter future for your children.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) allow employees to buy company stock at a predetermined price. If certain conditions are met, ISOs can qualify for favorable tax treatment, potentially resulting in lower capital gains taxes instead of ordinary income tax when the stock price increases.
What are the tax implications of exercising ISOs in California?
In California, exercising ISOs can lead to unexpected taxes because the state does not recognize the federal tax benefits. Additionally, the gain from exercising stock options is subject to the Alternative Minimum Tax (AMT), complicating the tax situation further.
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are promises to deliver shares of stock to employees once specific conditions are met. When these shares vest, they are taxed as ordinary income, which can result in a significant tax bill, especially in high-tax states like California.
How do RSUs differ from ISOs in terms of risk?
RSUs guarantee shares as long as the company remains solvent, making them less risky compared to ISOs, which depend on stock price fluctuations at the time of exercising options.
Can you provide an example of how ISOs work?
For instance, Marsha, a software engineer, was awarded 5,000 stock options at a strike price of $5. After four years, the share price rose to $20, allowing her to exercise her options and realize a profit of $75,000, but she faced ordinary income tax on this profit due to California’s tax regulations.
What happens if the share price of stock options increases significantly?
If the share price increases significantly, such as rising to $100, Marsha could sell her shares for $500,000, resulting in a profit of $475,000 after exercising her options.
How are RSUs taxed at vesting?
RSUs are taxed as ordinary income based on the value of the shares at the time they vest, which can lead to a substantial tax liability depending on the stock’s performance at that time.
Why is professional tax planning important for families dealing with ISOs and RSUs?
Professional tax planning is crucial for families to navigate the complexities of exercising ISOs and RSUs, especially in California, to avoid costly mistakes and make informed financial decisions.
List of Sources
- Define ISOs and RSUs: Key Concepts in Equity Compensation
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- RSU vs. Stock Options: Startup Equity Compensation (https://jpmorgan.com/insights/business-planning/rsu-vs-stock-options-startup-equity-compensation)
- RSUs vs. ISOs: Equity Compensation 101 | Wealthspire (https://wealthspire.com/blog/rsus-vs-isos-equity-compensation-101)
- Stock Option Taxes in California: ISO, NSO, and RSU Tax Planning for Tech Workers (https://ietaxattorney.com/stock-option-taxes-in-california-iso-nso-and-rsu-tax-planning-for-tech-workers)
- Incentive Stock Options (ISOs) – What’s the deal? (https://jpmorganworkplacesolutions.com/insights/incentive-stock-options-isos-whats-the-deal)
- Compare Key Differences: Tax Treatment, Vesting, and Ownership Rights
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- Stock Option Taxes in California: ISO, NSO, and RSU Tax Planning for Tech Workers (https://ietaxattorney.com/stock-option-taxes-in-california-iso-nso-and-rsu-tax-planning-for-tech-workers)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- RSU Tax in California: What Married Founders Need to Know in 2026 | Neptune Blog (https://meetneptune.com/blog/rsu-tax-in-california)
- How are stock options taxed in California? — Secfi (https://secfi.com/learn/how-are-stock-options-taxed-in-california)
- Evaluate Pros and Cons: Benefits and Drawbacks of ISOs vs. RSUs
- Incentive Stock Option (ISO) Taxes: A Guide (https://schwab.com/learn/story/incentive-stock-option-iso-taxes-guide)
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- The Pros and Cons of ISOs and NSOs for Employees and Employers | Eqvista (https://eqvista.com/stock-option-taxation/pros-cons-iso-nso-employees-employers)
- The Benefits and Challenges of Restricted Stock Units (RSUs) (https://unitedcapitalwealth.com/insights/investing/restricted-stock-units)
- Stock Options vs RSU: Understanding the key differences (https://cakeequity.com/guides/stock-options-vs-rsu)
- Assess Practical Considerations: Choosing Between ISOs and RSUs for Family Financial Goals
- ISOs vs RSUs: Optimize Stock Benefits | Confluence FP (https://confluencefp.com/isos-vs-rsus-strategies-to-optimize-your-employee-stock-benefits)
- Financial Planning with ISOs and RSUs in Chicago, IL (https://serenitywm.com/iso-and-rsu-planning-in-chicago-il)
- California Income Tax and Equity Compensation (https://savantwealth.com/savant-views-news/article/california-income-tax-and-equity-compensation)
- Stock Options vs Restricted Stock Units (RSUs): A guide (https://jpmorganworkplacesolutions.com/insights/rsus-vs-stock-options)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading