

Key Highlights
- Incentive Stock Options (ISOs) allow employees to buy company stock at a set exercise price, potentially benefiting from lower tax rates if held long enough.
- ISOs require exercising within three months of leaving the company to retain tax advantages.
- Restricted Stock Units (RSUs) automatically convert to shares upon vesting and are taxed as ordinary income based on their fair market value at that time.
- RSUs are generally less risky than ISOs, as they hold value as long as the stock price is above zero.
- Tax implications differ: ISOs may trigger the Alternative Minimum Tax (AMT), while RSUs are taxed immediately upon vesting.
- Families should consider the timing of exercising ISOs or selling RSUs to manage tax liabilities effectively.
- Strategic planning is essential for maximising the benefits of ISOs and RSUs, particularly for young families preparing for future expenses like education.
- Understanding the pros and cons of ISOs and RSUs can help families align their financial strategies with their long-term goals.
Introduction
Many parents feel lost when it comes to stock compensation, unsure of how to navigate the complexities. Understanding Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) can feel overwhelming, especially when you’re focused on securing your family’s financial future. Each option offers unique benefits and challenges, and knowing the best exercise strategies is crucial for maximizing your financial outcomes.
Imagine if you could effectively leverage these options to enhance your wealth while minimizing tax implications. This journey can be daunting, but with the right guidance, you can turn these challenges into stepping stones for your family’s future. Together, we can explore the key characteristics, tax consequences, and strategic considerations of ISOs and RSUs that can shape your family’s financial landscape.
We’re here for you, providing essential insights to help you make informed decisions that will benefit your family for years to come.
Define ISOs and RSUs: Key Characteristics and Mechanisms
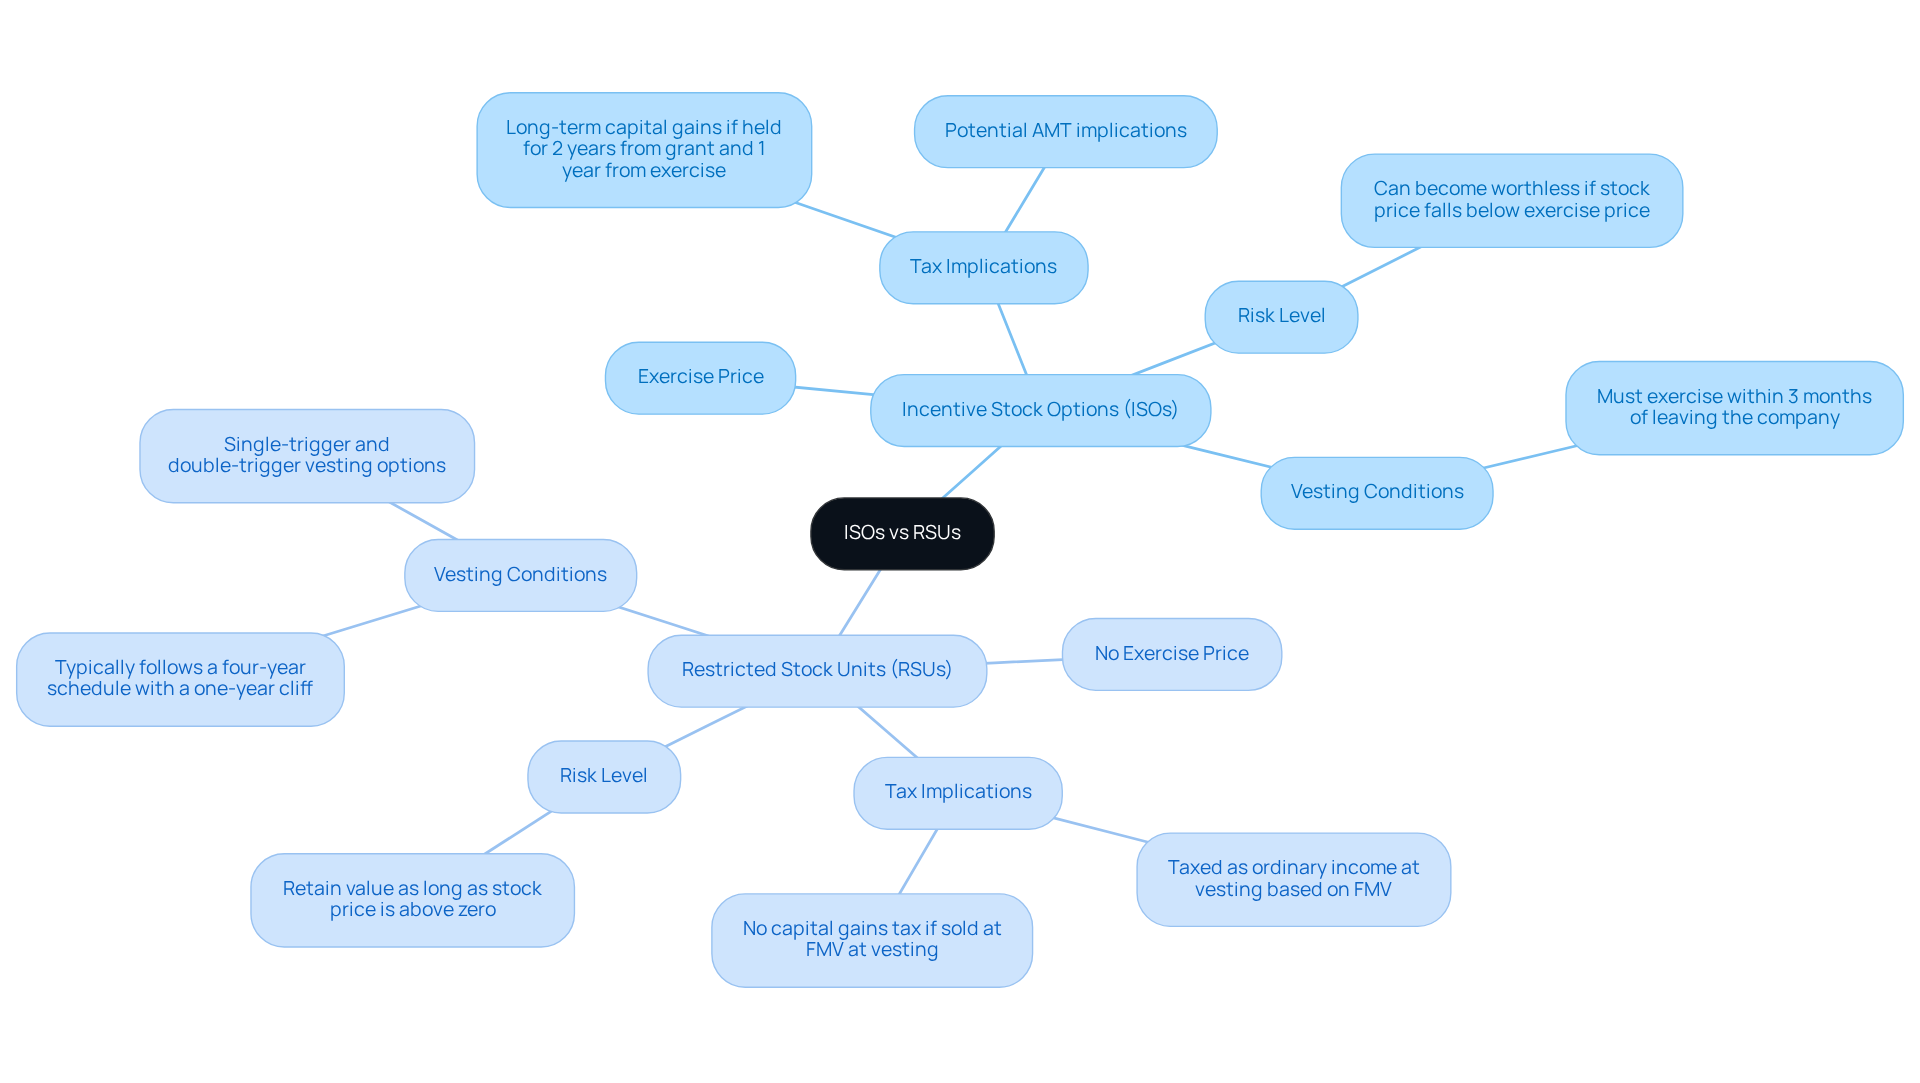
Imagine feeling confident about your family’s financial future, even when faced with the complexities of stock options and restricted stock units. Incentive Stock Options give you the chance to buy company stock at a set price, known as the exercise price. They often come as part of your pay and can be a smart way to save on taxes if you meet certain conditions. For example, if you hold the shares for at least two years from the grant date and one year from the exercise date, you might benefit from lower tax rates on your profits. However, remember that you need to exercise your stock options within three months of leaving the company to keep those tax advantages.
On the other hand, Restricted Stock Units (RSUs) promise to give you shares of stock once certain conditions are met. Unlike ISOs, you don’t have to buy RSUs; they automatically become yours when they vest. The value of these units is tied to the company’s stock price and is taxed as regular income when the shares vest. For instance, if your RSUs vest when the stock price is $50, that amount is considered ordinary income, and you’ll owe taxes based on that value.
Both stock options and restricted stock units have unique features that can significantly impact your family’s iso vs rsu exercise strategy. For instance, RSUs are generally less risky than stock options since they hold value as long as the stock price is above zero. In contrast, stock options can lose their value if the stock price falls below the exercise price. Additionally, RSUs are taxed upon vesting, meaning you owe taxes based on the fair market value at that time, while ISOs might not have immediate tax consequences at exercise but could be subject to the Alternative Minimum Tax (AMT).
Understanding these differences, particularly the iso vs rsu exercise strategy, is crucial for young parents like you, as these choices can shape your family’s financial journey. Navigating the tax implications of stock options and restricted stock units can feel overwhelming for many families. Without a clear understanding, you might miss out on maximizing your financial benefits. Together, we can navigate this journey and ensure you make informed decisions that benefit your family’s future.
Analyze Taxation and Financial Outcomes: Comparing ISOs and RSUs
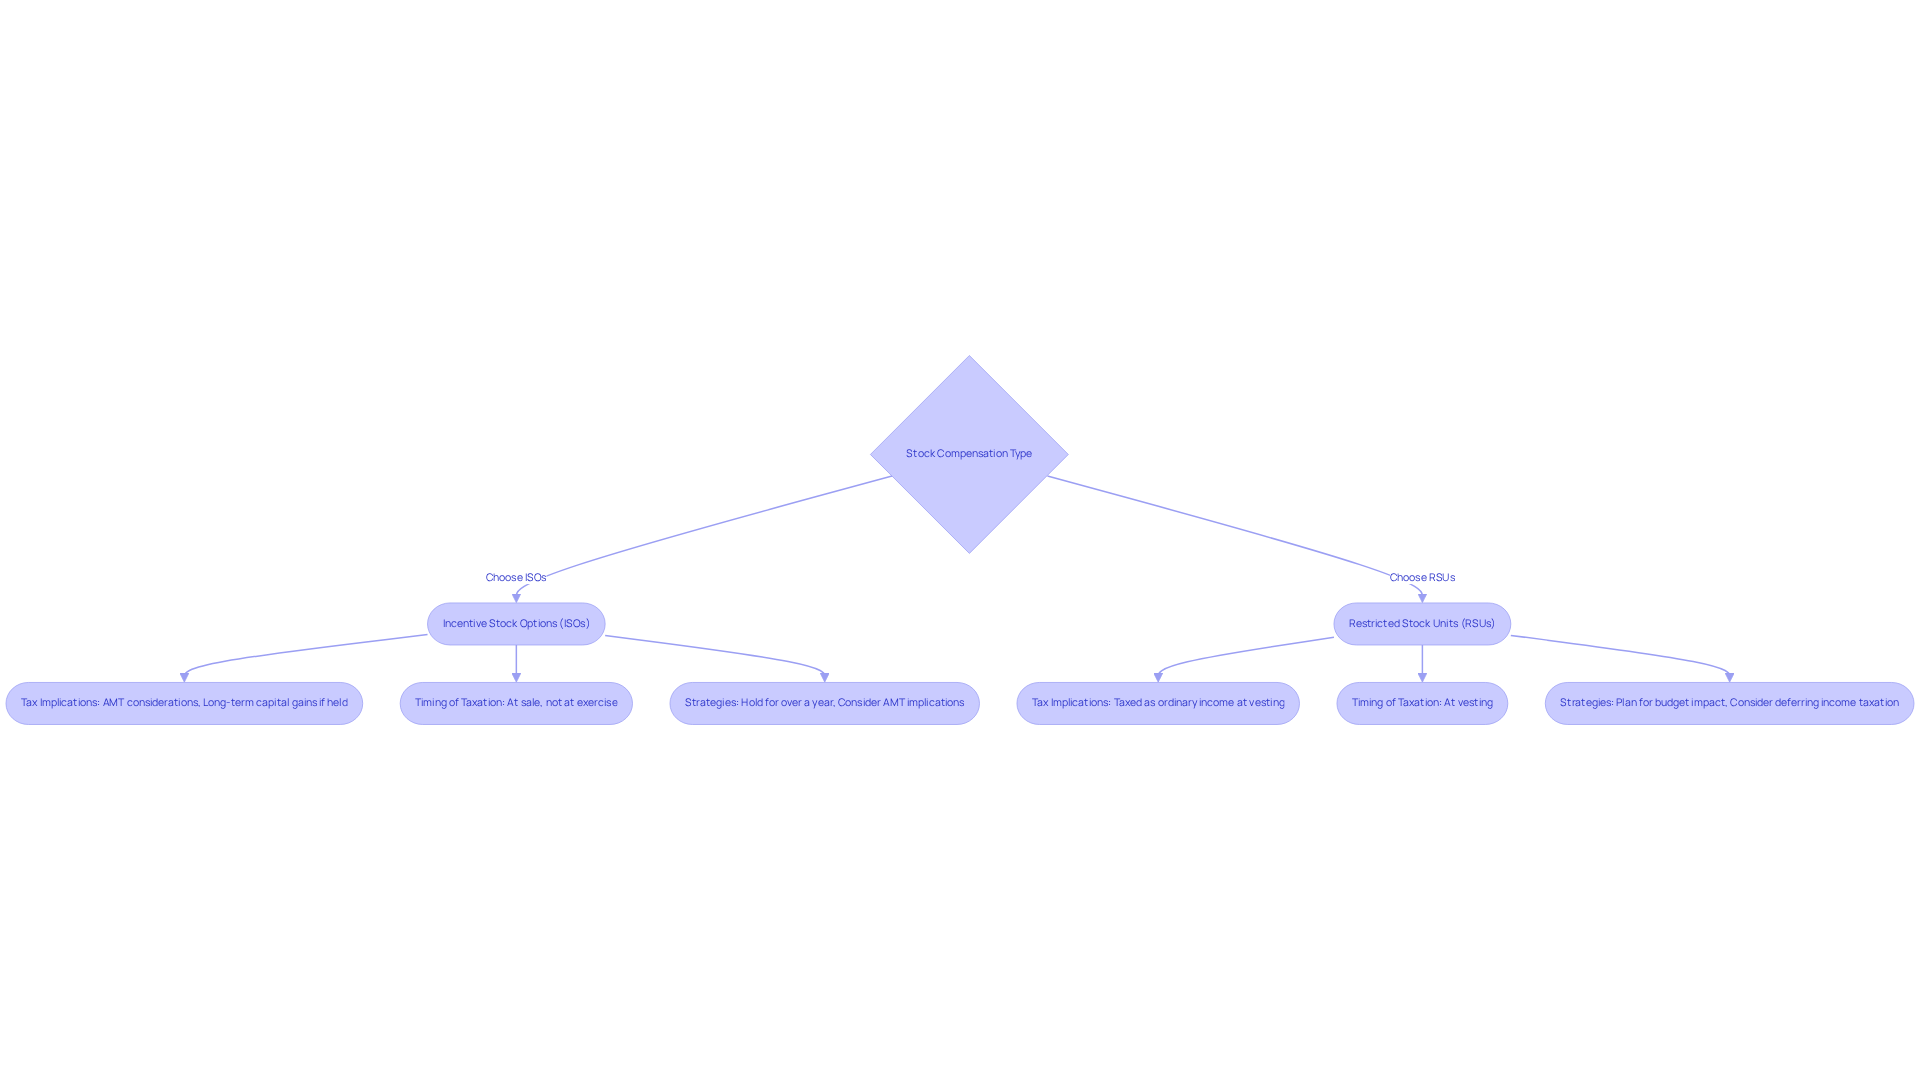
Imagine the surprise of discovering that your stock options could lead to unexpected tax bills, just when you thought you had everything under control. Exercising stock options doesn’t mean you’ll face immediate tax consequences. Instead, tax implications arise when you sell the shares. If you hold onto those shares for at least a year after exercising and two years after the grant date, any gains may qualify for the long-term capital gains tax rate, which is usually lower than ordinary income tax rates. But be aware, exercising ISOs can trigger the Alternative Minimum Tax (AMT), which means you’ll need to plan carefully to avoid any surprises.
On the other hand, when restricted stock units vest, they’re taxed as ordinary income, which can catch families off guard. This immediate taxation can really impact your budget, especially in years when several RSUs vest at once. Understanding these tax consequences is crucial for effectively implementing an ISO vs RSU exercise strategy in budget planning. The timing of your decisions about the ISO vs RSU exercise strategy or selling shares can really impact your family’s financial health. Additionally, families might consider deferring income taxation on stock options and RSUs for up to five years from the vesting date, as allowed by the Tax Cuts and Jobs Act.
Take Allison and Brian, for instance. They turned to Bright Advisers for help, hoping to unlock their financial potential through smart tax planning. Despite their high earnings, they were unaware of the monetary opportunities they were missing due to insufficient tax planning. With Bright Advisers’ support, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. This collaboration not only provided them peace of mind but also allowed them to enjoy more quality time with their loved ones. By incorporating strategies such as tax-loss harvesting and investment diversification, families can navigate the complexities of stock options and restricted stock units, particularly the ISO vs RSU exercise strategy, while ensuring their financial security and freedom. With the right strategies in place, you can transform your financial future and create lasting memories with your family, free from the worry of tax surprises.
Evaluate Strategic Considerations: Vesting and Exercise Strategies for ISOs and RSUs
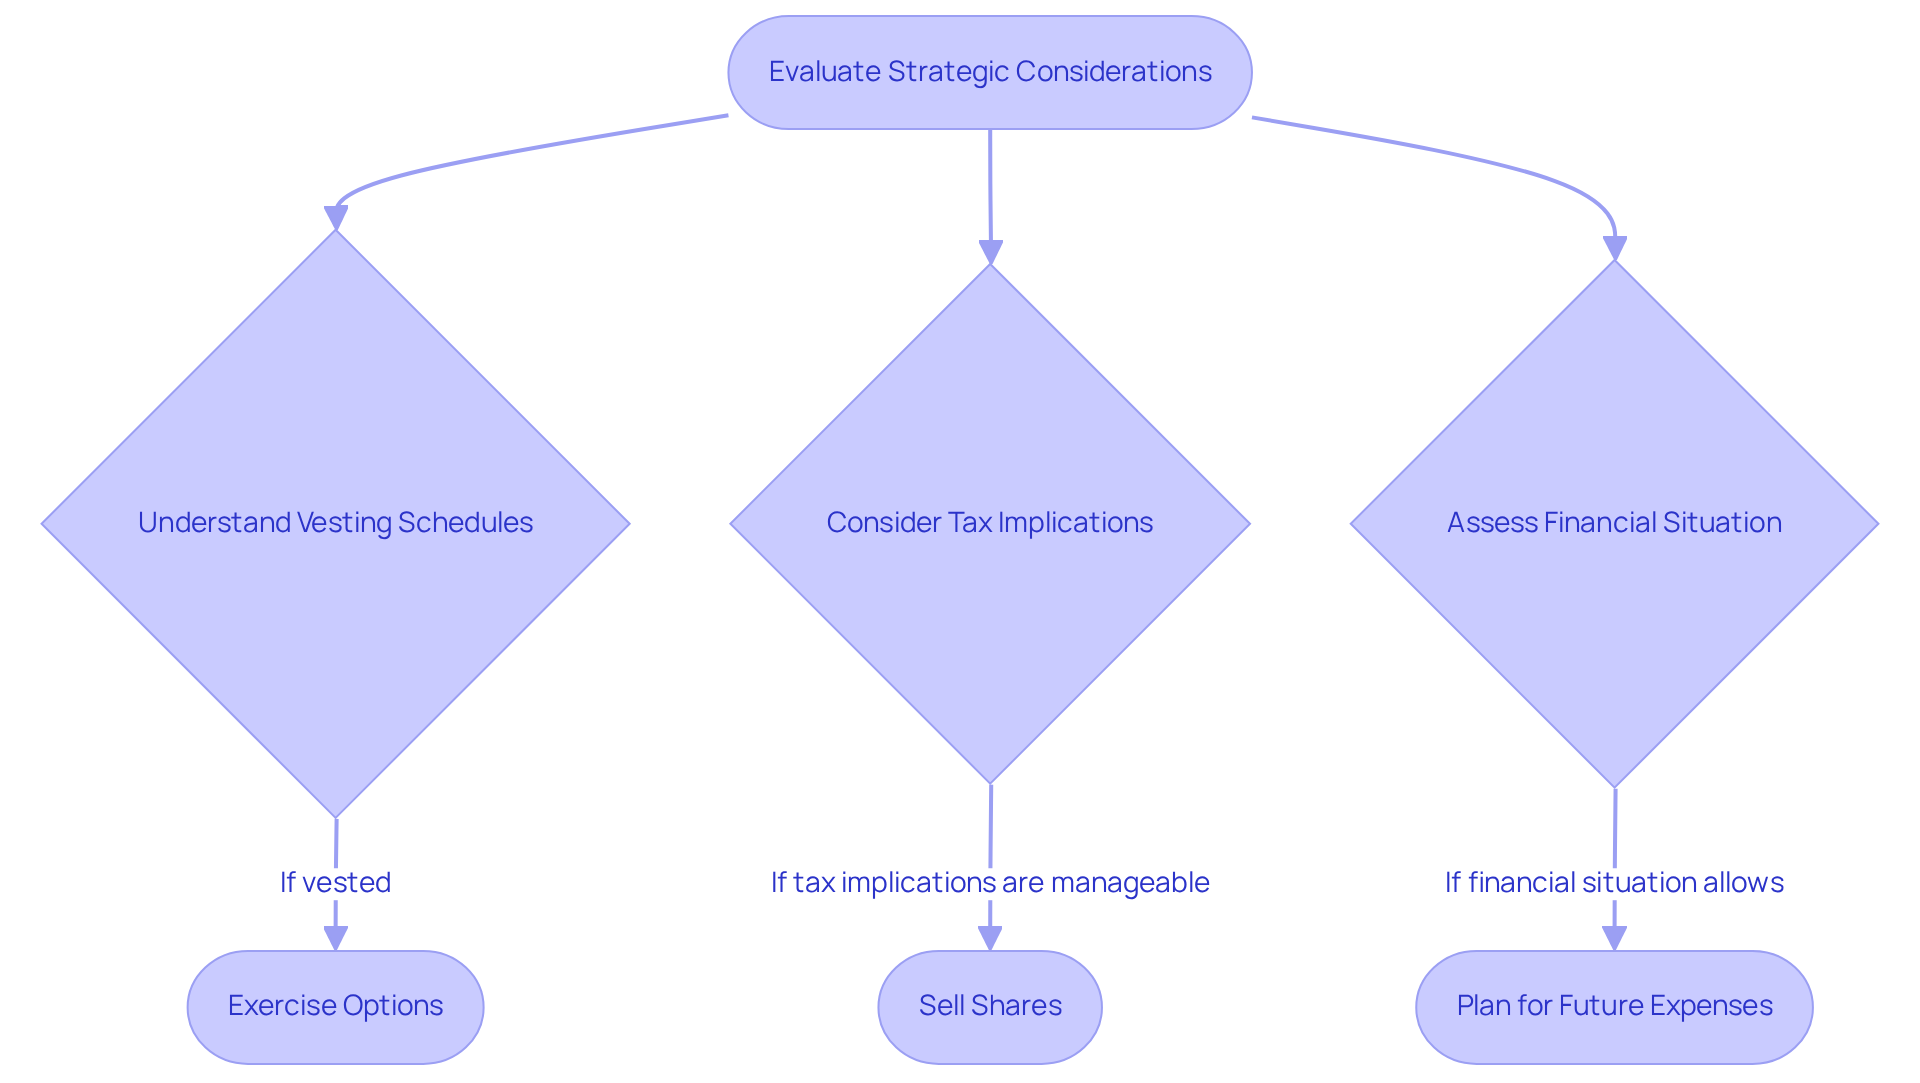
Imagine the worry of not being able to provide for your child’s future due to financial uncertainties. Understanding the iso vs rsu exercise strategy and how vesting schedules for stock options can impact your family’s future is crucial, especially for young families preparing for their children’s education and well-being.
When stock options become available, employees typically have a designated period to exercise them. But it’s important to consider how this might affect your taxes, especially with the Alternative Minimum Tax (AMT) in play. For 2025, the AMT exemption level is:
- $137,000 for joint filers
- $88,100 for single filers
Take a moment to think about your family’s financial situation and whether exercising these options feels manageable for you. Remember, exceeding the $100,000 limit on ISOs that can be exercised in a calendar year can lead to disqualification of favorable tax treatment, so careful planning is essential.
The vesting schedule for restricted stock units determines when you obtain your shares. A strategic approach involves planning for the tax implications of vesting as part of the iso vs rsu exercise strategy. You might consider selling a portion of your shares immediately upon vesting to cover the tax liability, especially if you anticipate a significant increase in stock price. When restricted stock units vest, they are taxed at their fair market value as ordinary income, which can result in a significant tax obligation even if the shares are not sold. Understanding your company’s performance and market conditions can help you decide whether to hold or sell shares after vesting. At Bright Advisers, we offer personalized strategies to help families like yours navigate these financial complexities with confidence.
For young parents, these strategic considerations are essential for ensuring that your equity compensation aligns with broader monetary goals, such as saving for your children’s education or planning for retirement. Incorporating stock options and restricted stock into a comprehensive wealth strategy can greatly aid in asset accumulation if handled effectively. Together, we can navigate these complexities and ensure a brighter future for your family. Families interested in customized planning and investment strategies are encouraged to join our waitlist to learn more about how Bright Advisers can assist them in their monetary endeavors.
Compare Pros and Cons: Weighing the Benefits and Drawbacks of ISOs vs. RSUs
Navigating the world of stock options can feel overwhelming, especially when you’re trying to secure your family’s future. Both Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) have their own advantages and disadvantages that can significantly influence your family’s financial planning, particularly in the context of the iso vs rsu exercise strategy.
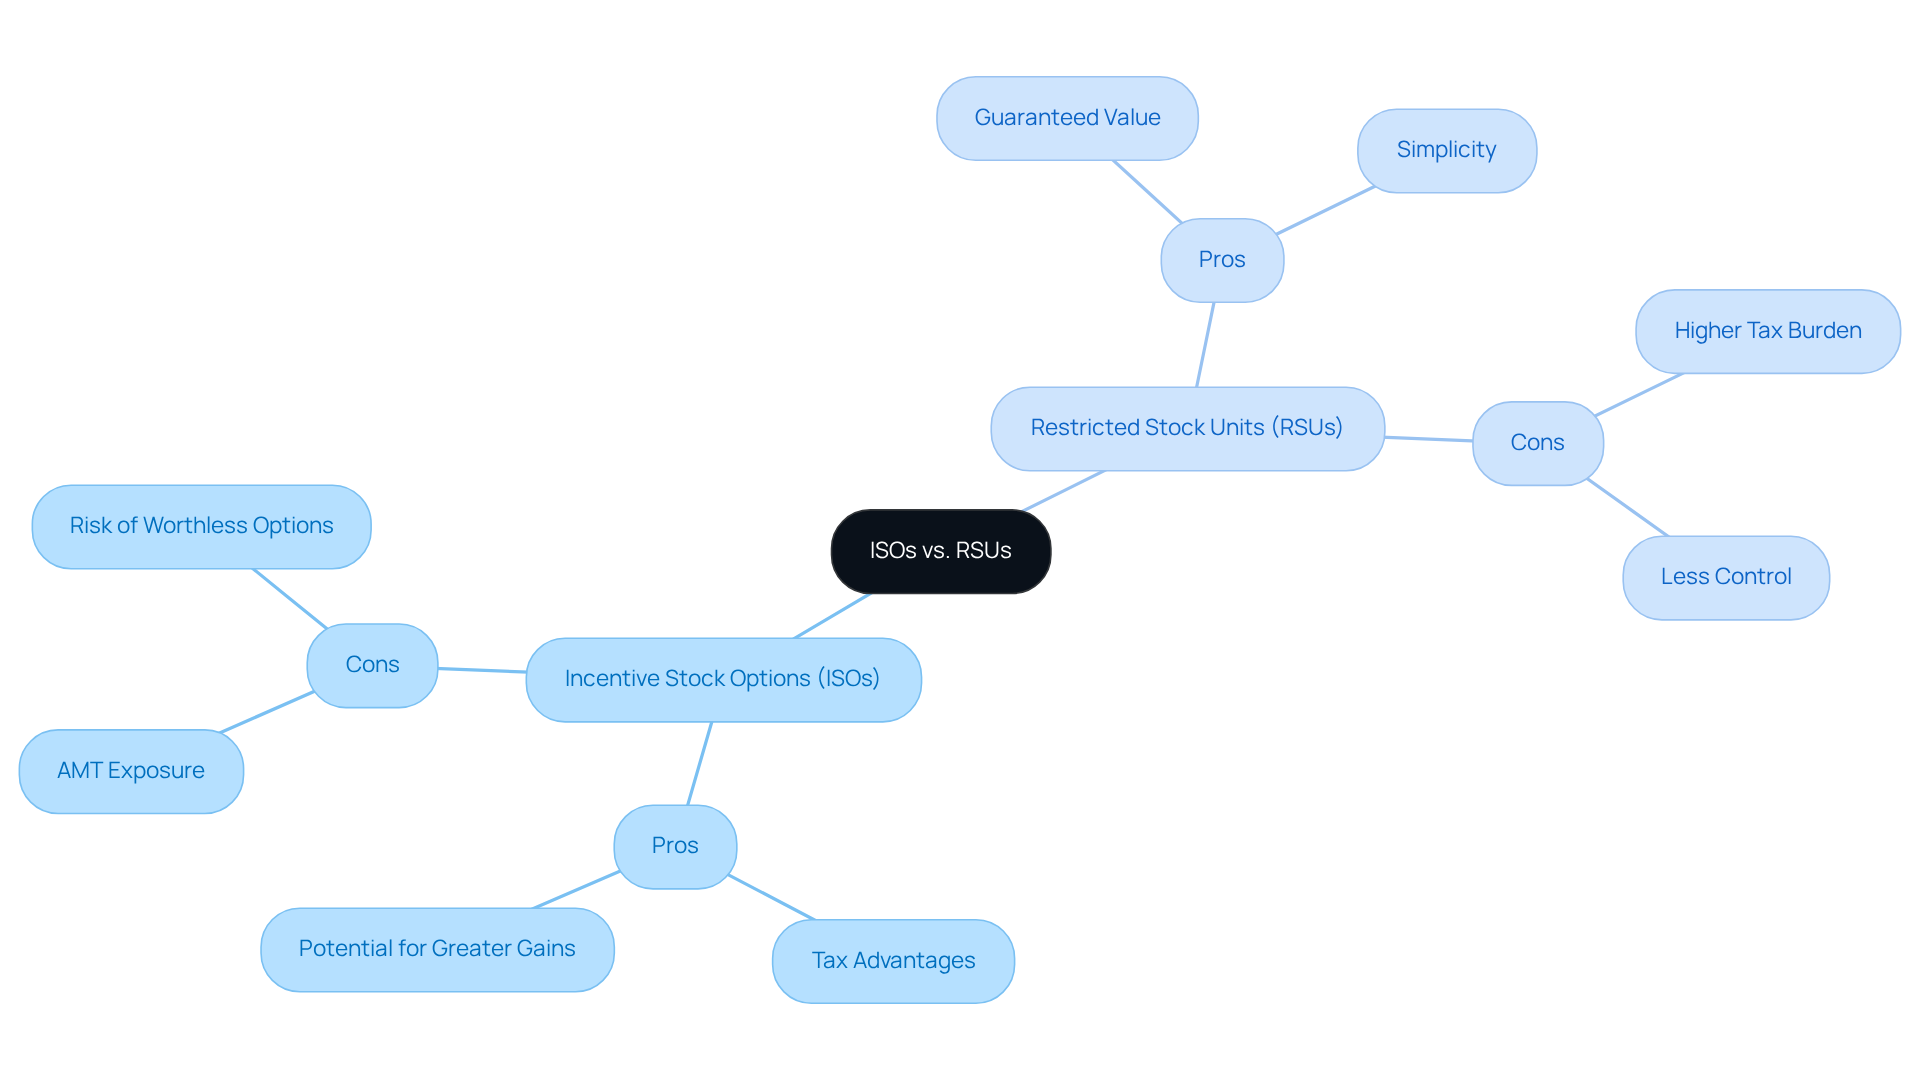
Pros of ISOs:
- Tax Advantages: If held long enough, ISOs can be taxed at the lower long-term capital gains rate, leading to substantial tax savings.
- Potential for Greater Gains: Employees can benefit from stock price appreciation without immediate tax consequences at the time of exercise, allowing for potentially larger profits.
Cons of ISOs:
- AMT Exposure: Imagine facing unexpected tax liabilities just when you thought you were making progress with your finances. The iso vs rsu exercise strategy indicates that exercising ISOs can trigger the Alternative Minimum Tax (AMT), complicating tax planning.
- Risk of Worthless Options: If the stock price falls below the exercise price, the options may become worthless, leaving you with no financial benefit.
Pros of RSUs:
- Known share count: RSUs always have value upon vesting, converting to shares without requiring an upfront purchase, providing a reliable source of income.
- Simplicity: The iso vs rsu exercise strategy indicates that Restricted Stock Units are easier to understand and manage, with straightforward tax implications that occur at vesting, making them less complex than Incentive Stock Options.
Cons of RSUs:
- Higher Tax Burden: This could mean less money for your family’s needs when you need it most, as RSUs are taxed as ordinary income upon vesting, resulting in a significant tax bill.
- Less Control: You have no influence over the timing of income recognition, as it is linked to the vesting schedule, which may not correspond with your monetary needs.
As a family, understanding these pros and cons can help you make choices that truly align with your financial goals and your loved ones’ needs. Integrating equity compensation into a long-term financial strategy can significantly impact retirement planning and overall wealth management. Together, we can navigate this journey and ensure your family’s financial future is secure.
Conclusion
Navigating the world of stock options can be daunting for young parents, especially when it comes to understanding ISOs and RSUs. Each option has its own unique characteristics that can significantly influence your family’s financial strategy. Understanding these differences helps families make choices that support their long-term goals and create a secure future for their children.
Throughout this article, we’ve highlighted key points, including the tax implications of exercising ISOs versus RSUs and the strategic considerations surrounding vesting schedules. Many families find that while ISOs can offer tax advantages if managed correctly, they also carry risks, such as exposure to the Alternative Minimum Tax (AMT). On the other hand, RSUs provide shares delivered at vesting but come with immediate tax burdens that can impact family finances. Navigating the complexities of ISOs and RSUs can feel overwhelming for many families.
Making the right choice can lead to a more secure future for your children. It’s vital for families to engage in proactive financial planning, considering how these stock options fit into their broader wealth management strategies. When you reach out to experts like Bright Advisers, you’re not just getting advice; you’re gaining a partner in navigating the complexities of stock compensation. Families are encouraged to explore personalized planning options to ensure their financial futures are not just secure, but thriving.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are a type of stock option that allows you to buy company stock at a predetermined price, known as the exercise price. They are often part of your compensation package and can provide tax benefits if certain conditions are met.
What are the tax advantages of ISOs?
If you hold ISOs for at least two years from the grant date and one year from the exercise date, you may qualify for lower tax rates on your profits. However, to retain these tax advantages, you must exercise your stock options within three months of leaving the company.
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are promises to grant you shares of stock once specific conditions are met. Unlike ISOs, you do not need to purchase RSUs; they automatically become yours when they vest.
How are RSUs taxed?
RSUs are taxed as regular income when the shares vest. For example, if your RSUs vest when the stock price is $50, that amount is considered ordinary income, and you will owe taxes based on that value.
How do ISOs and RSUs differ in terms of risk?
RSUs are generally less risky than ISOs because they retain value as long as the stock price is above zero. In contrast, ISOs can lose value if the stock price falls below the exercise price.
What are the tax implications of exercising ISOs compared to RSUs?
ISOs may not have immediate tax consequences at the time of exercise but could be subject to the Alternative Minimum Tax (AMT). In contrast, RSUs are taxed upon vesting based on their fair market value at that time.
Why is it important for families to understand ISOs and RSUs?
Understanding the differences between ISOs and RSUs is crucial for young parents, as these choices can significantly impact their family’s financial future. Navigating the tax implications can help families maximize their financial benefits.
List of Sources
- Define ISOs and RSUs: Key Characteristics and Mechanisms
- Windham Brannon (https://windhambrannon.com/blog/incentive-stock-options-considerations-for-tech-companies)
- Equity Management Software with Local Expertise | Optio Incentives (https://optioincentives.com/resource-hub/what-are-rsus)
- What is an RSU? How They Work, Benefits, & Taxes (https://carta.com/learn/equity/rsu)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Roberts & Holland LLP | Incentive Stock Options Revisited (https://robertsandholland.com/news-and-insights/incentive-stock-options-revisited)
- Analyze Taxation and Financial Outcomes: Comparing ISOs and RSUs
- Tax Implications for Stock-Based Compensation – Bloomberg Tax (https://pro.bloombergtax.com/insights/federal-tax/tax-implications-for-stock-based-compensation)
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- Stock-based compensation: Tax forms and implications (https://thetaxadviser.com/newsletters/2024/jan/stock-based-compensation-tax-forms-and-implications)
- The Alternative Minimum Tax and Incentive Stock Options (https://zajacgrp.com/insights/what-you-should-know-about-the-alternative-minimum-tax-and-incentive-stock-options)
- Evaluate Strategic Considerations: Vesting and Exercise Strategies for ISOs and RSUs
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- ISOs vs RSUs: Optimize Stock Benefits | Confluence FP (https://confluencefp.com/isos-vs-rsus-strategies-to-optimize-your-employee-stock-benefits)
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- 4 Strategies to Exercise Your Incentive Stock Options (https://zajacgrp.com/insights/4-strategies-for-exercising-your-isos-and-the-tax-impact)
- Compare Pros and Cons: Weighing the Benefits and Drawbacks of ISOs vs. RSUs
- ISOs vs RSUs: Optimize Stock Benefits | Confluence FP (https://confluencefp.com/isos-vs-rsus-strategies-to-optimize-your-employee-stock-benefits)
- RSUs vs. ISOs: Equity Compensation 101 | Wealthspire (https://wealthspire.com/blog/rsus-vs-isos-equity-compensation-101)
- ISO vs RSU | Equity Awards | Serenity Wealth Management (https://serenitywmwi.com/rsus-and-isos)
- ISO vs RSU in Equity Compensation | Zynergy Retirement (https://zynergyretirement.com/retirement-resources/iso-vs-rsu-in-equity-compensation)
- RSU vs. Stock Options: Startup Equity Compensation (https://jpmorgan.com/insights/business-planning/rsu-vs-stock-options-startup-equity-compensation)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading