

Key Highlights
- Incentive Stock Options (ISOs) allow employees to buy shares at a fixed exercise price, potentially offering tax benefits if held long enough.
- Exercising ISOs can trigger the Alternative Minimum Tax (AMT), requiring careful planning to avoid unexpected liabilities.
- Restricted Stock Units (RSUs) promise shares upon vesting without requiring upfront payment, simplifying the process for employees.
- RSUs are taxed as ordinary income at vesting, which can lead to a significant tax burden if not planned for properly.
- Understanding the timing of exercising ISOs or selling RSUs is crucial for effective tax planning and financial strategy.
- Families like Jay and Emma, and Allison and Brian, benefited from guidance by Bright Advisers to optimise their tax situations and financial planning.
- ISOs offer potential for greater gains and employee ownership but come with complex tax implications and expiration risks.
- RSUs provide guaranteed delivery of shares but are subject to ordinary income tax and market risks.
Introduction
Imagine feeling overwhelmed by the complexities of equity compensation while trying to secure your family’s future. For young families, understanding the nuances of Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs) can feel like a daunting task. These financial tools hold the potential to shape your family’s financial future, presenting both opportunities and challenges.
In this article, we’ll explore how understanding the timing of ISOs and RSUs can help you make choices that benefit your family’s future. We’ll provide insights on how to strategically approach these options, maximizing benefits while minimizing tax implications.
How can you, as a young parent, navigate these choices to align with your family’s dreams and goals? Together, we can find a way to make informed decisions that support your long-term financial aspirations.
Define ISOs and RSUs: Key Characteristics and Features
Navigating the world of equity compensation can feel overwhelming for young families, especially when it comes to understanding Incentive Stock Options and Restricted Stock Units.
Incentive Stock Options let employees buy company shares at a fixed price, known as the exercise price, which is usually set at the fair market value when granted. These options can be appealing because they may offer tax benefits. If employees hold onto the shares for at least a year after buying them and for two years after the grant date, they might qualify for lower capital gains tax rates when selling. However, it’s important to note that exercising stock options can trigger the alternative minimum tax (AMT), which requires careful planning to avoid unexpected tax liabilities. Additionally, there’s a limit of $100,000 on the amount that can trigger tax implications, and these options expire 10 years from the grant date.
On the other hand, Restricted Stock Units (RSUs) promise shares of stock to employees once certain conditions, like a vesting period, are met. Unlike stock options, RSUs don’t require employees to buy shares; they automatically convert into shares upon vesting. This makes it easier for employees since there are no upfront costs. However, RSUs are taxed as ordinary income based on their fair market value at the time of vesting, which can lead to a significant tax burden if not planned for properly.
While both ISOs and RSUs help companies attract and keep great talent, understanding the iso vs rsu exercise timing is crucial for families, as these options affect employees differently regarding taxes and ownership. For instance, families like Jay and Emma, who sought guidance from Bright Advisers, were able to create a solid strategy that included enhancing tax planning and assessing education savings options. This method not only alleviated their monetary anxiety but also assisted them in balancing their current responsibilities with long-term goals. Similarly, Emily and Mark benefited from a thorough evaluation of their economic circumstances, enabling them to create a strategy that offered the freedom to decide whether or not to keep working. By taking the time to understand these options, families can build a brighter financial future together, ensuring their dreams are within reach.
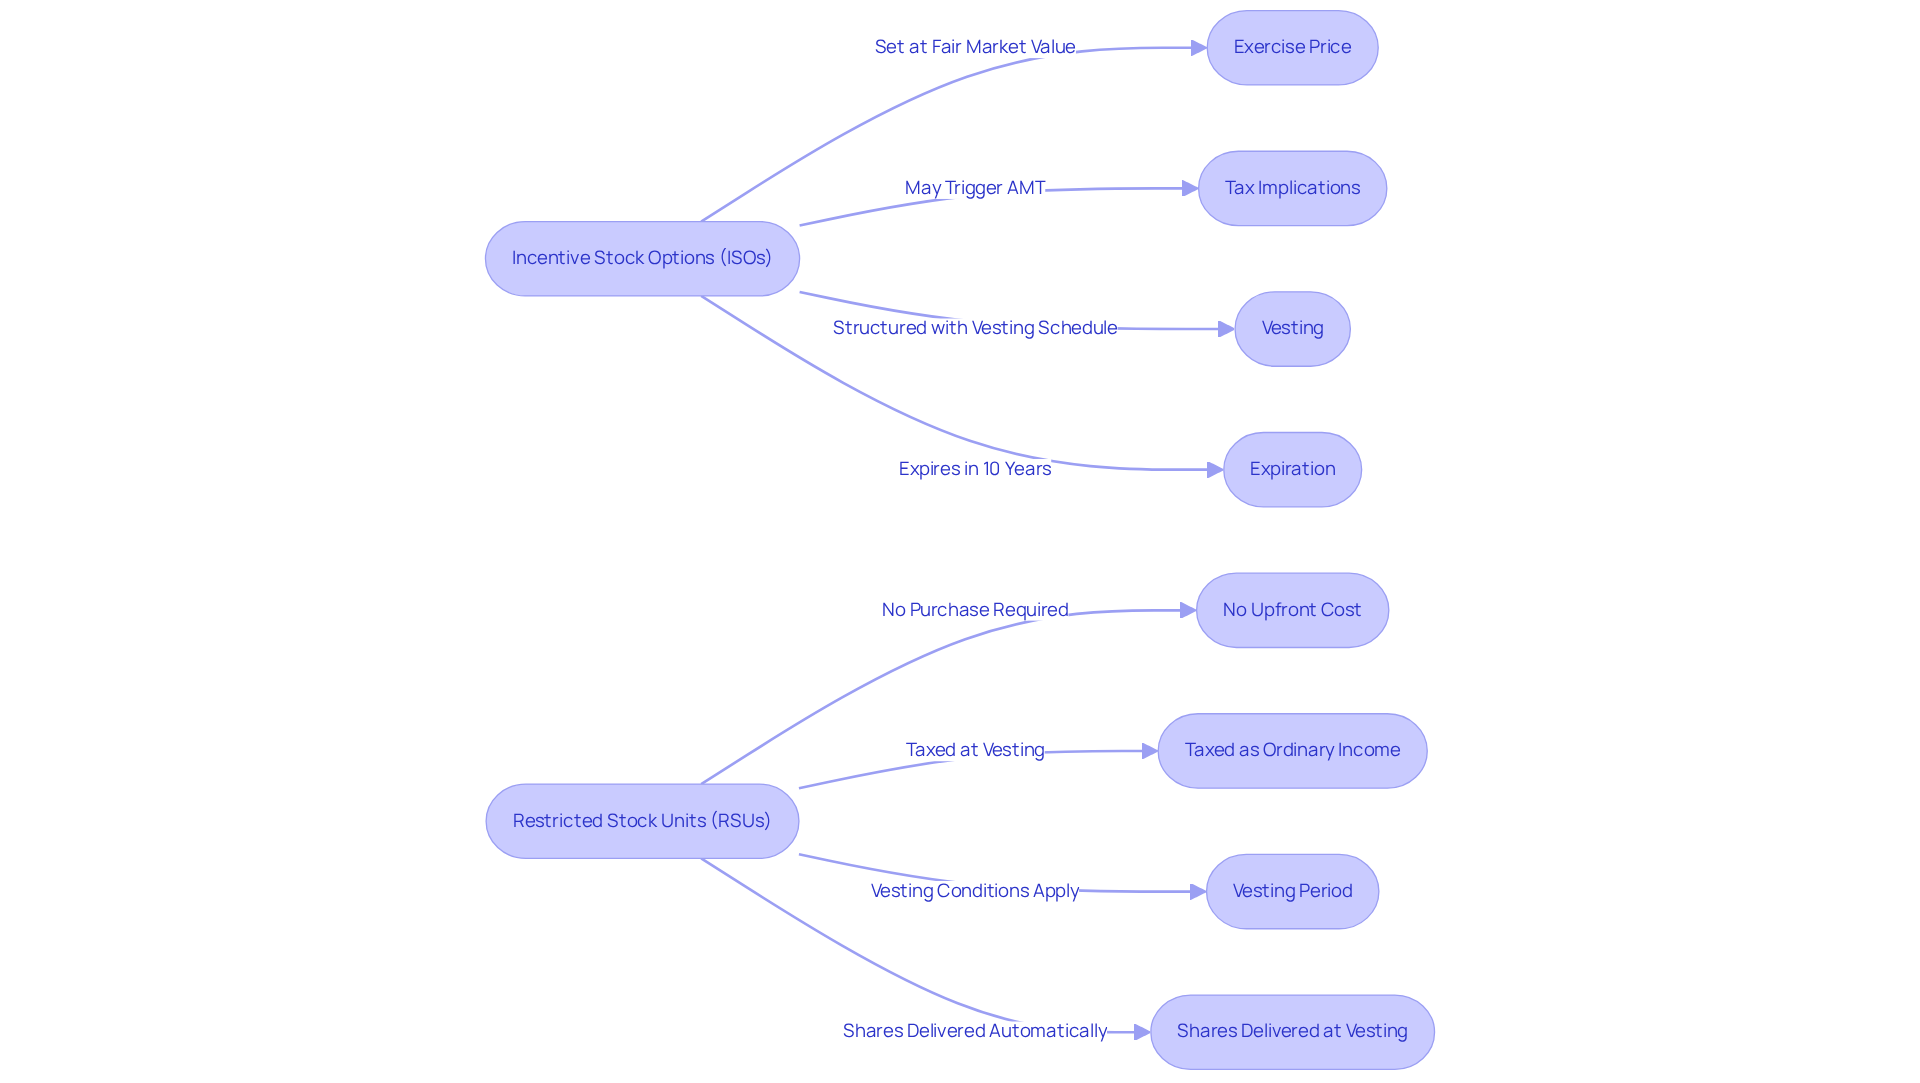
Analyze Exercise Timing: Strategic Considerations for ISOs and RSUs
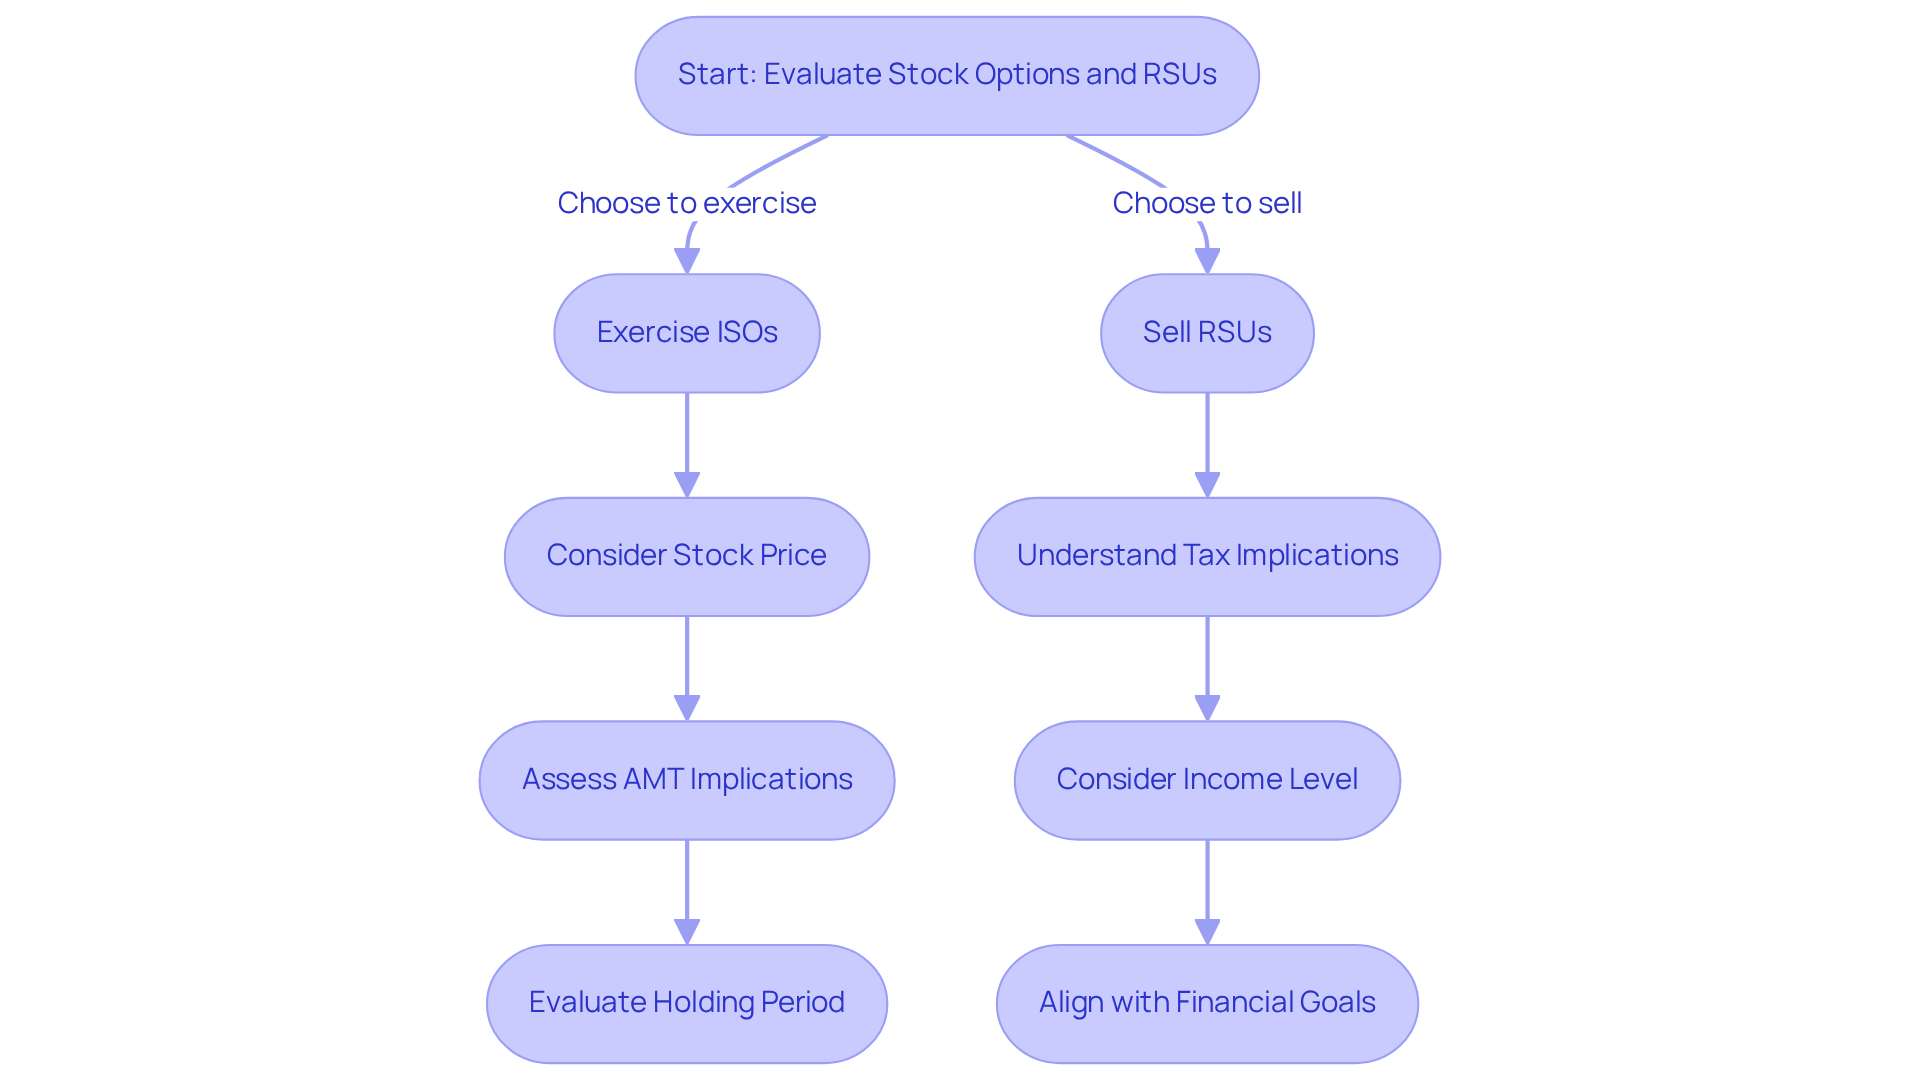
Imagine the weight of making the right choice about your stock options and restricted stock units, knowing it could impact your family’s financial future. When it comes to iso vs rsu exercise timing, exercising your stock options or selling restricted stock units is a big decision that can really affect your family’s finances. You might be able to exercise your options once they become available, but factors like stock price changes and your personal situation can influence the iso vs rsu exercise timing. If you decide to exercise early in the year, you could have a longer window to meet the holding period requirements for favorable tax treatment. But if you exercise early, you might run into the Alternative Minimum Tax (AMT), which can catch you off guard if you’re not prepared. If you exercise ISOs and hold the shares, you may face AMT based on the difference between the exercise price and the market value at exercise, which can complicate your financial situation. In 2025, the AMT exemption levels are $88,100 for single filers and $137,000 for joint filers, so it’s important to keep these thresholds in mind when planning your exercises.
On the other hand, when your restricted stock units vest, they’re taxed as ordinary income, so understanding iso vs rsu exercise timing is essential for your family’s budget. You’ll want to consider your overall income for the year, as vesting can push you into a higher tax bracket. For example, if your stock options become available when the share price is high, selling right away can help reduce tax liabilities, but it might limit your potential profits if the stock continues to rise. If you have vested stock units, aligning your investments with your company’s long-term success can be a smart move, but it also increases your exposure to company-specific risks.
Allison and Brian, a couple in their late 40s, faced similar challenges. As a medical device sales representative and a restaurant owner, they were earning substantial incomes but were unaware of the monetary opportunities they were missing due to inadequate tax planning. By collaborating with Bright Advisers, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. Their experience emphasizes the significance of strategic tax planning in navigating the complexities of stock options and restricted stock units, ensuring that families can make informed choices that align with their long-term monetary objectives.
Ultimately, determining the iso vs rsu exercise timing for when to exercise your stock options or sell those units should align with your broader financial picture, including your tax strategy and cash needs. Consulting with a trusted advisor can be the key to transforming your financial journey into one of confidence and security for your family. Remember, past performance does not guarantee future results, and all investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
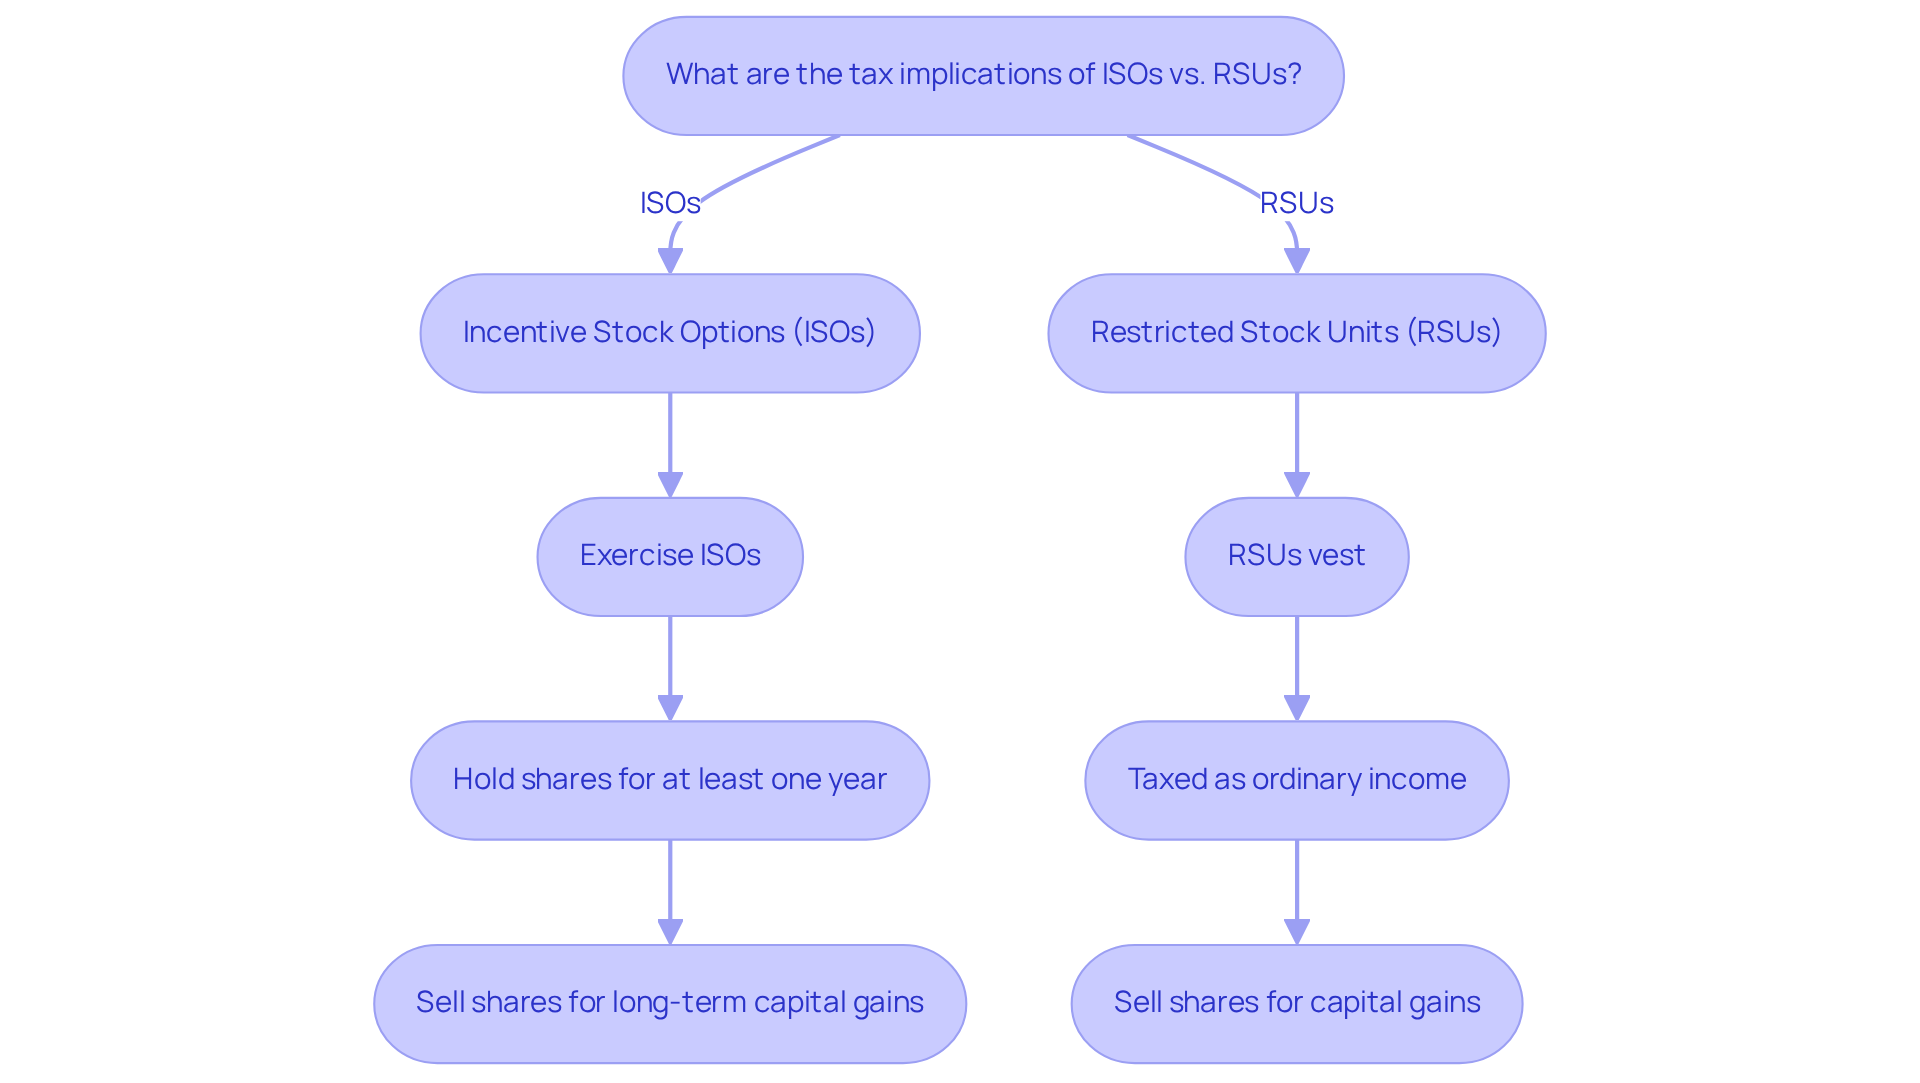
Compare Tax Implications: Understanding the Financial Impact of ISOs and RSUs
Navigating the world of stock options and restricted stock units can feel overwhelming, especially when it comes to understanding the tax implications that come with them.
With Incentive Stock Options (ISOs), you typically won’t face taxes right when you exercise them, but holding onto those shares too long could lead to some unexpected tax consequences. If you sell the shares after meeting the holding period requirements – at least one year after exercise and two years after the grant date – you’ll benefit from lower long-term capital gains tax rates.
On the other hand, Restricted Stock Units (RSUs) are taxed as ordinary income when they vest, which means you’ll see that value added to your taxable income for the year. Any gains from selling the shares after vesting will also be subject to capital gains tax, depending on how long you hold onto them.
As young parents, it’s important to understand these tax implications, as they can shape your overall tax liability and investment strategy. For instance, families like Jay & Emma, who sought guidance from Bright Advisers, were able to create a solid strategy that included enhancing tax planning and developing a personalized retirement plan. Likewise, Emily and Mark gained from a thorough evaluation of their monetary situation, enabling them to navigate the intricacies of planning effectively. By understanding these tax implications, families can pave the way for a more secure financial future for their children.
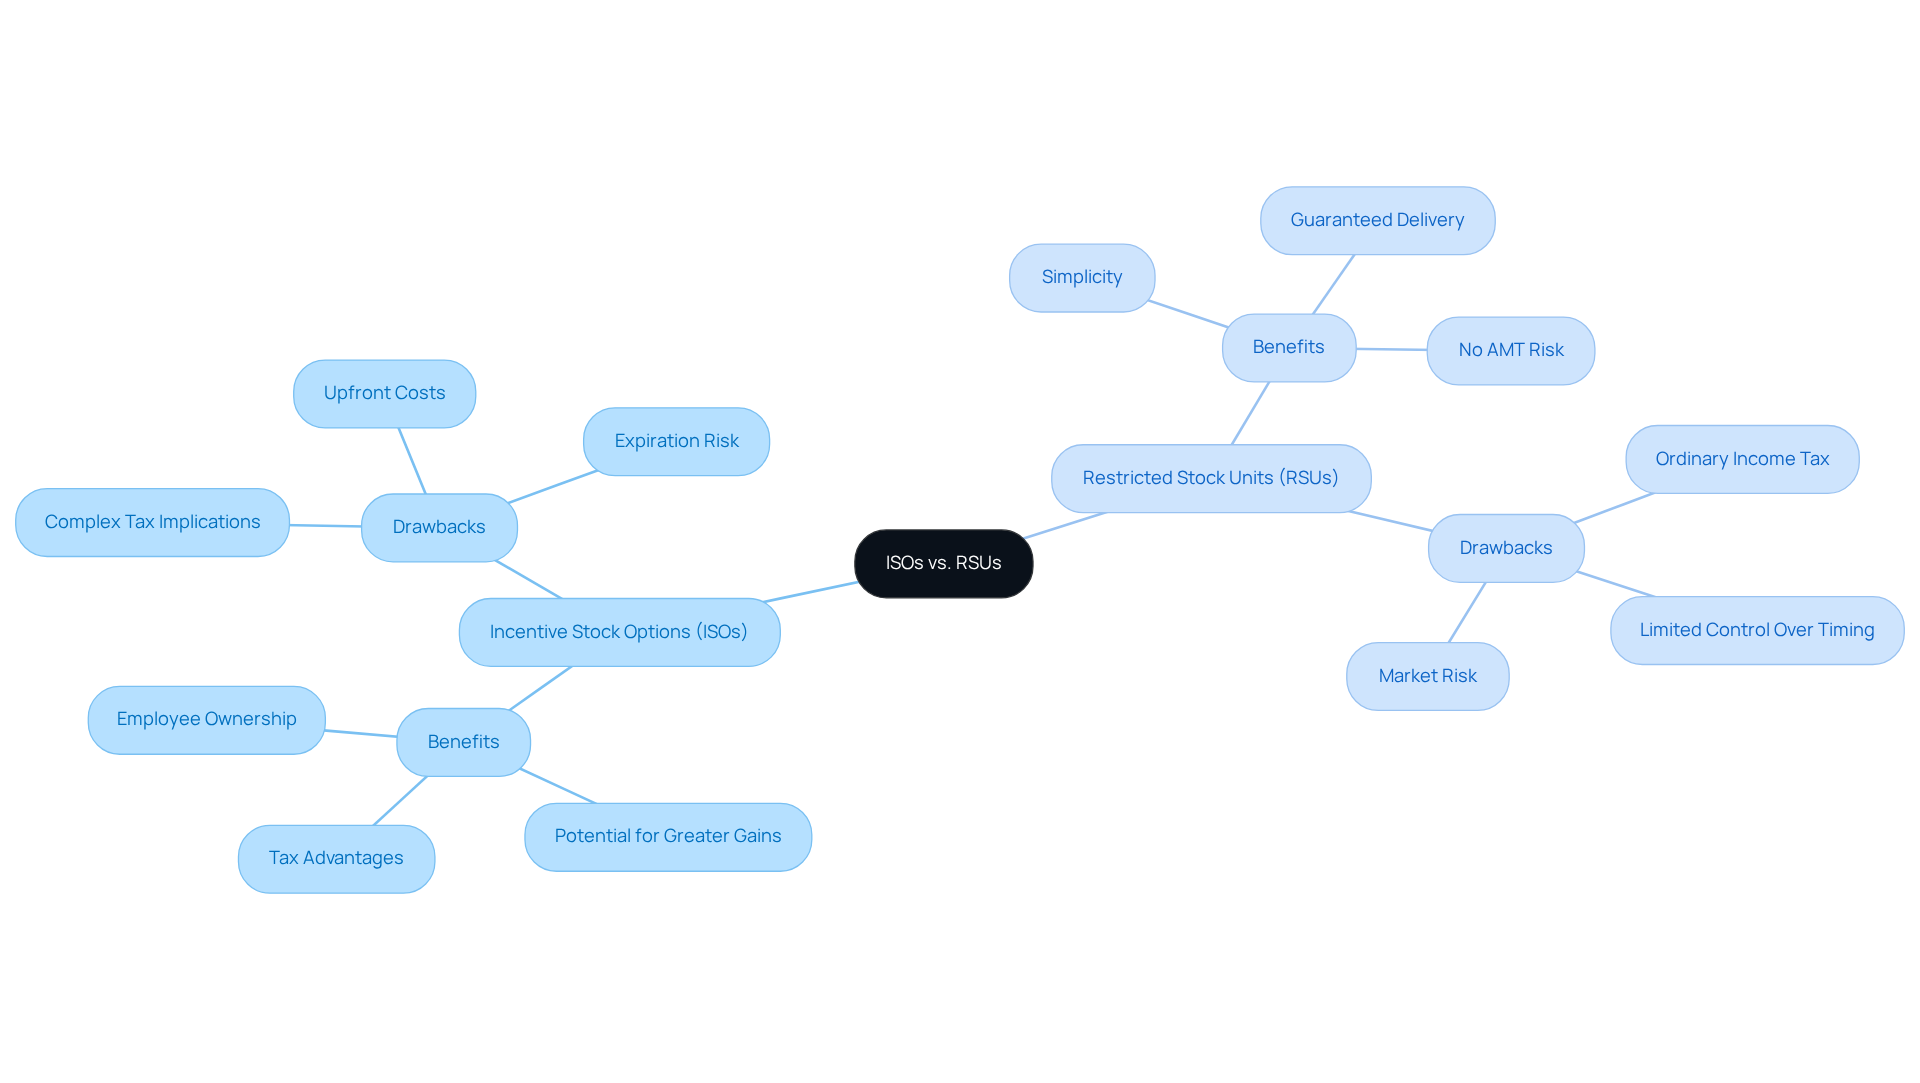
Evaluate Benefits and Drawbacks: A Comparative Summary of ISOs and RSUs
Navigating the world of Incentive Stock Options and Restricted Stock Units can feel daunting, especially for families looking to secure their financial future.
Benefits of ISOs:
- Tax Advantages: If held for at least one year after purchase and two years after grant, gains can be taxed at lower capital gains rates, significantly reducing tax liabilities. This can be particularly beneficial for families like Allison and Brian, who have leveraged tax planning to enhance their financial situation.
- Potential for Greater Gains: If the stock price increases, the potential profit can be substantial, aligning employee interests with company performance.
- Employee Ownership: ISOs can help employees feel more connected to their company, inspiring them to work towards shared success.
Drawbacks of ISOs:
- Complex Tax Implications: The risk of Alternative Minimum Tax (AMT) can complicate tax planning, requiring careful consideration.
- Upfront Costs: Employees must pay the exercise price to acquire shares, which can be a financial burden.
- Expiration Risk: ISOs typically have a limited exercise period of 10 years, necessitating timely decisions.
Benefits of RSUs:
- Simplicity: RSUs are straightforward, converting to shares without requiring an upfront payment, making them easier to manage.
- Guaranteed Delivery: As long as the company holds value, restricted stock units will provide shares upon vesting, ensuring employees receive compensation.
- No AMT Risk: Restricted stock units do not trigger AMT, simplifying tax planning and reducing potential liabilities.
Drawbacks of RSUs:
- Ordinary Income Tax: RSUs are taxed as ordinary income upon vesting, which can lead to a higher tax bill compared to capital gains rates.
- Limited Control Over Timing: Employees have less control over when they receive shares, complicating tax planning strategies.
- Market Risk: If the company’s stock price declines after vesting, the value of the shares may decrease, impacting overall compensation.
Ultimately, understanding both ISOs and RSUs, particularly regarding iso vs rsu exercise timing, can empower families to make choices that align with their financial dreams. By working with Bright Advisers, families can develop a comprehensive financial strategy that incorporates these elements, ensuring they make informed decisions that support their long-term financial security. With the right support, families can confidently choose the path that best nurtures their financial well-being.
Conclusion
Imagine feeling confident about your family’s financial future, knowing the ins and outs of Incentive Stock Options (ISOs) and Restricted Stock Units (RSUs). Timing your decisions about these options can make a big difference in your family’s financial journey. When you understand how ISOs and RSUs work, you can make choices that truly support your family’s dreams and aspirations.
Throughout this article, we’ve explored the differences between ISOs and RSUs, highlighting their respective benefits and drawbacks.
- ISOs offer potential tax advantages and greater profit opportunities, but they come with complexities like the risk of Alternative Minimum Tax (AMT) and upfront costs.
- On the other hand, RSUs provide simplicity and guaranteed delivery of shares, but they are taxed as ordinary income upon vesting, which can lead to a higher tax burden.
Real-life examples of families who have successfully navigated these options with the help of Bright Advisers illustrate the importance of strategic planning in maximizing the benefits of equity compensation.
With the right guidance, you can navigate these choices with confidence, ensuring they fit your family’s unique situation. Taking these steps today can pave the way for a brighter tomorrow for you and your loved ones.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) allow employees to purchase company shares at a fixed price, known as the exercise price, which is typically set at the fair market value when granted. They may offer tax benefits if certain holding periods are met.
What are the tax benefits associated with ISOs?
If employees hold onto the shares for at least one year after purchasing them and for two years after the grant date, they may qualify for lower capital gains tax rates when selling the shares. However, exercising ISOs can trigger the alternative minimum tax (AMT).
Are there any limits on ISOs?
Yes, there is a limit of $100,000 on the amount of ISOs that can trigger tax implications in a given year, and these options expire 10 years from the grant date.
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are promises of shares of stock to employees that are granted once certain conditions, such as a vesting period, are met. Unlike stock options, RSUs do not require employees to buy shares; they automatically convert into shares upon vesting.
How are RSUs taxed?
RSUs are taxed as ordinary income based on their fair market value at the time of vesting, which can lead to a significant tax burden if not planned for properly.
How do ISOs and RSUs differ in terms of employee costs?
ISOs require employees to buy shares at the exercise price, while RSUs do not require any upfront costs as they automatically convert into shares upon vesting.
Why is understanding the differences between ISOs and RSUs important for families?
Understanding the differences is crucial because they affect employees differently regarding taxes and ownership. Proper planning can help families manage their financial responsibilities and long-term goals effectively.
How can families benefit from guidance on ISOs and RSUs?
Families can benefit from guidance by creating solid strategies that enhance tax planning and assess education savings options, alleviating monetary anxiety and helping balance current responsibilities with long-term goals.
List of Sources
- Define ISOs and RSUs: Key Characteristics and Features
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Equity Management Software with Local Expertise | Optio Incentives (https://optioincentives.com/resource-hub/what-are-rsus)
- What is an RSU? How They Work, Benefits, & Taxes (https://carta.com/learn/equity/rsu)
- Stock Options vs Restricted Stock Units (RSUs): A guide (https://jpmorganworkplacesolutions.com/insights/rsus-vs-stock-options)
- Analyze Exercise Timing: Strategic Considerations for ISOs and RSUs
- RSUs vs. ISOs: Equity Compensation 101 | Wealthspire (https://wealthspire.com/blog/rsus-vs-isos-equity-compensation-101)
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- Tax Planning Strategies for Incentive Stock Options (ISOs) (https://cbh.com/insights/articles/tax-planning-strategies-for-incentive-stock-options-isos)
- ISOs vs RSUs: Optimize Stock Benefits | Confluence FP (https://confluencefp.com/isos-vs-rsus-strategies-to-optimize-your-employee-stock-benefits)
- mcdonaldjacobs.cpa (https://mcdonaldjacobs.cpa/comparing-nsos-isos-and-rsus-tax-and-planning-guide)
- Compare Tax Implications: Understanding the Financial Impact of ISOs and RSUs
- What is an RSU? How They Work, Benefits, & Taxes (https://carta.com/learn/equity/rsu)
- Restricted Stock and Performance Stock Taxes: A Guide (https://schwab.com/learn/story/rsu-taxes-and-psu-taxes)
- Incentive Stock Option (ISO) Taxes: A Guide (https://schwab.com/learn/story/incentive-stock-option-iso-taxes-guide)
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- Restricted Stock Unit (RSU) Tax Guide: Vesting, Selling & Reporting (https://summitry.com/blog/how-are-rsus-taxed)
- Evaluate Benefits and Drawbacks: A Comparative Summary of ISOs and RSUs
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Incentive Stock Options: How ISOs Work vs NSOs – NerdWallet (https://nerdwallet.com/investing/learn/isos)
- 8 Advantages of Incentive Stock Options You May Want to Know (https://zajacgrp.com/insights/8-advantages-of-incentive-stock-options-you-should-know)
- Windham Brannon (https://windhambrannon.com/blog/incentive-stock-options-considerations-for-tech-companies)
- Incentive Stock Options (ISOs) in Private Companies (https://instrumentalwealth.com/blog/incentive-stock-options-private-companies)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading