

Overview
Navigating the world of investment can feel overwhelming, especially for young parents who want the best for their families. The choice between lump sum investing and dollar cost averaging (DCA) is a significant one, and it’s essential to understand how each strategy aligns with your unique financial situation and family goals.
Imagine if you could reduce the stress of market fluctuations. DCA allows you to invest gradually, which can help mitigate risks during uncertain times. This approach not only eases the burden of market volatility but can also lead to better returns when the market is unpredictable. It’s a comforting thought, knowing you can invest steadily while focusing on what truly matters—your family.
On the other hand, lump sum investing might be appealing if you’re in a consistently rising market. This strategy has the potential for higher returns, which could significantly benefit your family’s future. However, it’s crucial to assess your personal risk tolerance and financial objectives before diving in.
Ultimately, the right choice depends on your family’s needs and aspirations. Remember, we’re here for you on this journey. Together, we can explore these strategies and find the best path forward for your financial well-being.
Key Highlights:
- Lump sum investing involves committing a significant amount of money into an asset all at once, while dollar cost averaging (DCA) spreads investments over time at regular intervals.
- DCA can help mitigate the stress of market fluctuations and potentially lower the average cost per share, especially in volatile markets.
- During 2020, investors using DCA with $10,000 monthly in the S&P 500 outperformed a single lump sum investment of $120,000 at the year’s start.
- Lump sum investing may incur fewer transaction fees, but risks include investing at market peaks, leading to immediate losses.
- DCA allows for purchasing more shares when prices are low, but may result in lower returns in a consistently rising market.
- Families should evaluate their financial situation, goals, and risk tolerance before choosing between lump sum and DCA strategies.
- Setting specific financial targets, like saving for education or a home, is crucial for effective financial planning.
- Consulting a financial advisor can provide personalised guidance to align investment strategies with family goals.
Introduction
Navigating the world of investments can feel overwhelming, especially when you’re trying to decide between lump sum investing and dollar cost averaging. Each strategy has its own unique advantages and challenges, particularly in a fluctuating market where timing can greatly influence your returns. As families like yours strive to align financial choices with long-term goals, understanding these investment methods becomes essential.
Imagine if you could find the right balance between potential gains and risk management. How can you, as a concerned parent, make informed decisions that truly support your family’s financial future? It’s important to understand the implications of each approach, as they can significantly impact your journey towards financial security. Together, we can navigate this journey, ensuring that your family’s values and aspirations are at the forefront of your investment strategy.
Understand Lump Sum Investing and Dollar Cost Averaging
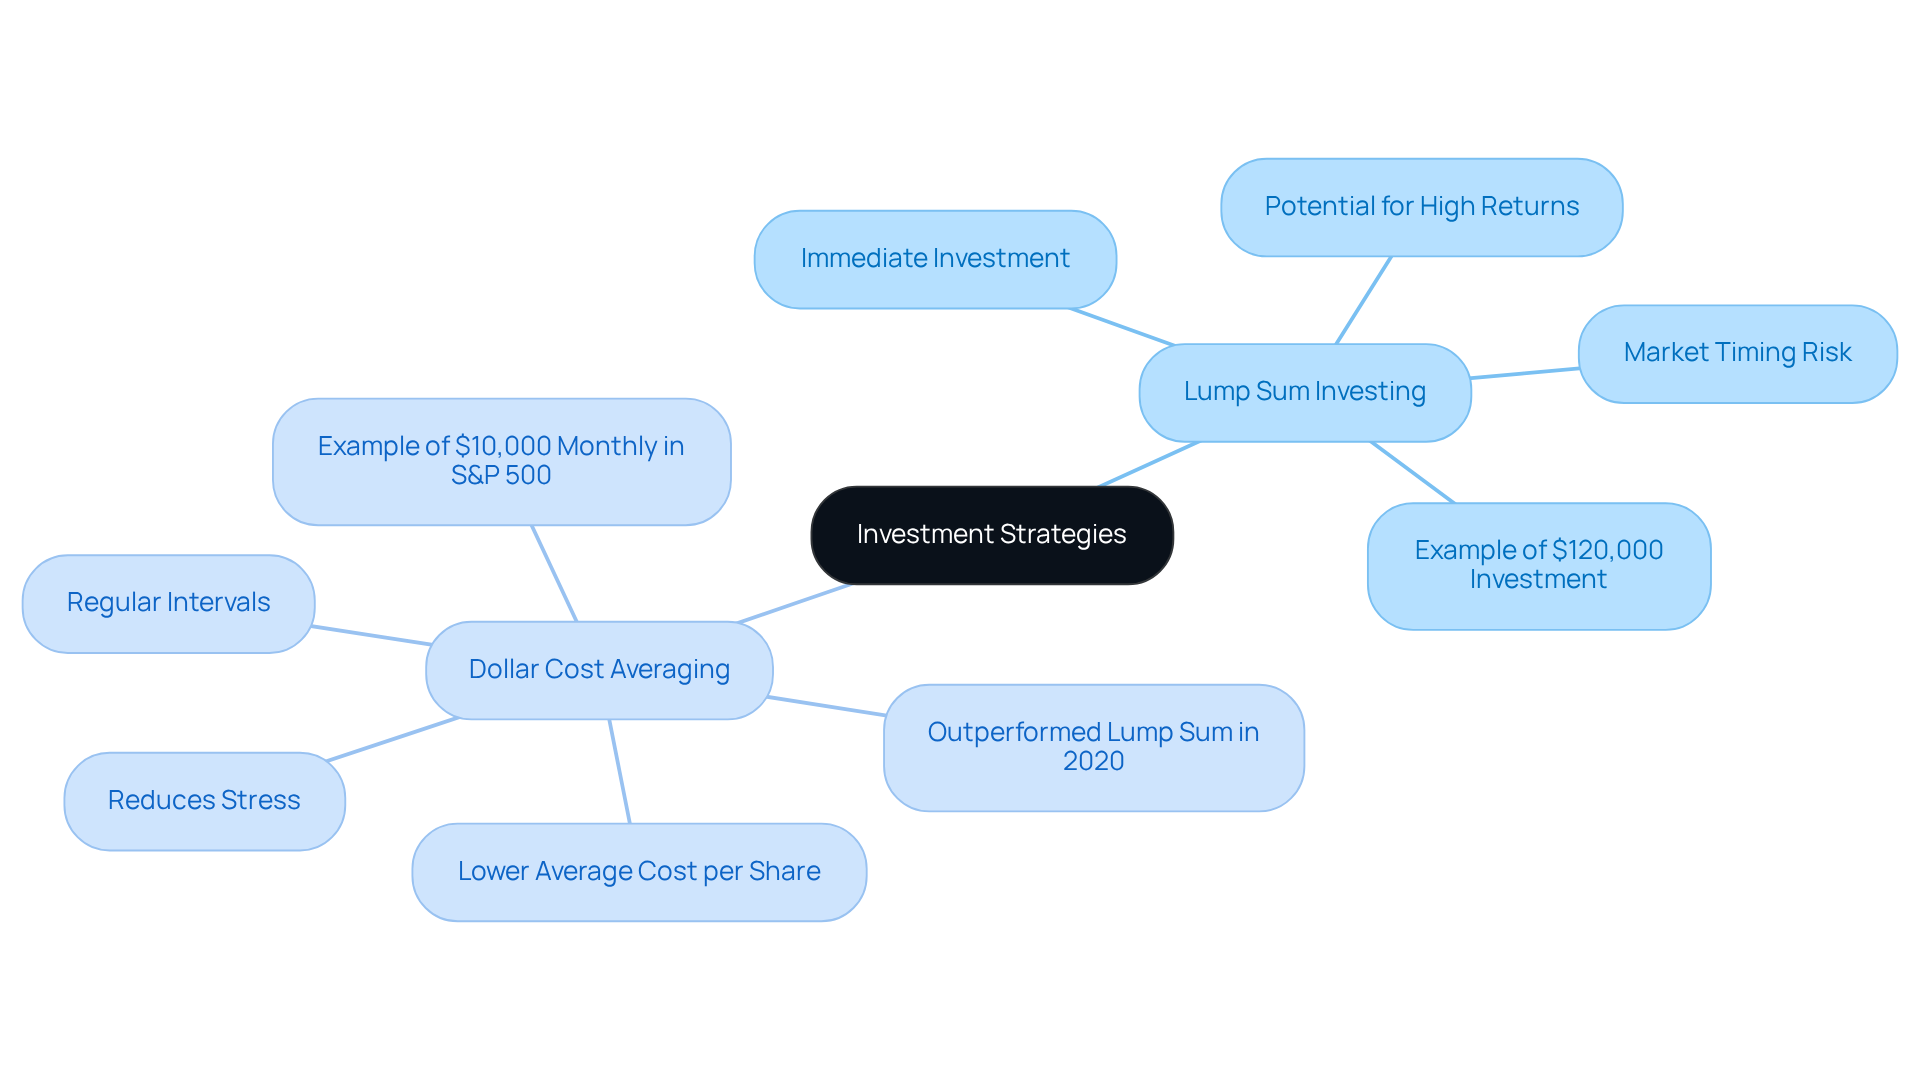
Committing a substantial amount of money into a financial asset all at once can feel like a big leap, whether you choose a lump sum or dollar cost average allocation. This strategy might seem appealing during prosperous times, allowing investors to seize immediate profits. However, imagine if you could take a more gradual approach—this is where dollar cost averaging (DCA) comes into play. By allocating a fixed amount at regular intervals, regardless of market conditions, you can ease the stress of price fluctuations. This method helps diversify your investments over time, potentially lowering the average cost per share.
Consider the tumultuous financial landscape of 2020. Those who adopted a dollar cost averaging strategy, investing $10,000 each month in the S&P 500, found that they outperformed a single investment of $120,000 made at the year’s start. This example illustrates how DCA can be a lifeline in unpredictable markets, offering a sense of security.
As we look ahead to 2025, it’s clear that the lump sum or dollar cost average approach continues to attract attention, especially among individuals who have experienced sudden wealth or liquidity events. Yet, many financial advisors caution against placing large sums all at once. The stress of fluctuating markets can weigh heavily on your mind. Instead, they recommend a more thoughtful approach to investing by using a lump sum or dollar cost average to relieve that pressure.
Understanding these strategies is crucial for families striving to align their financial choices with their goals and risk tolerance. By thoughtfully weighing the pros and cons of each method, you can make informed decisions that nurture your family’s long-term financial well-being. Remember, we’re here for you—together, we can navigate this journey toward financial security.
Evaluate the Pros and Cons of Each Strategy
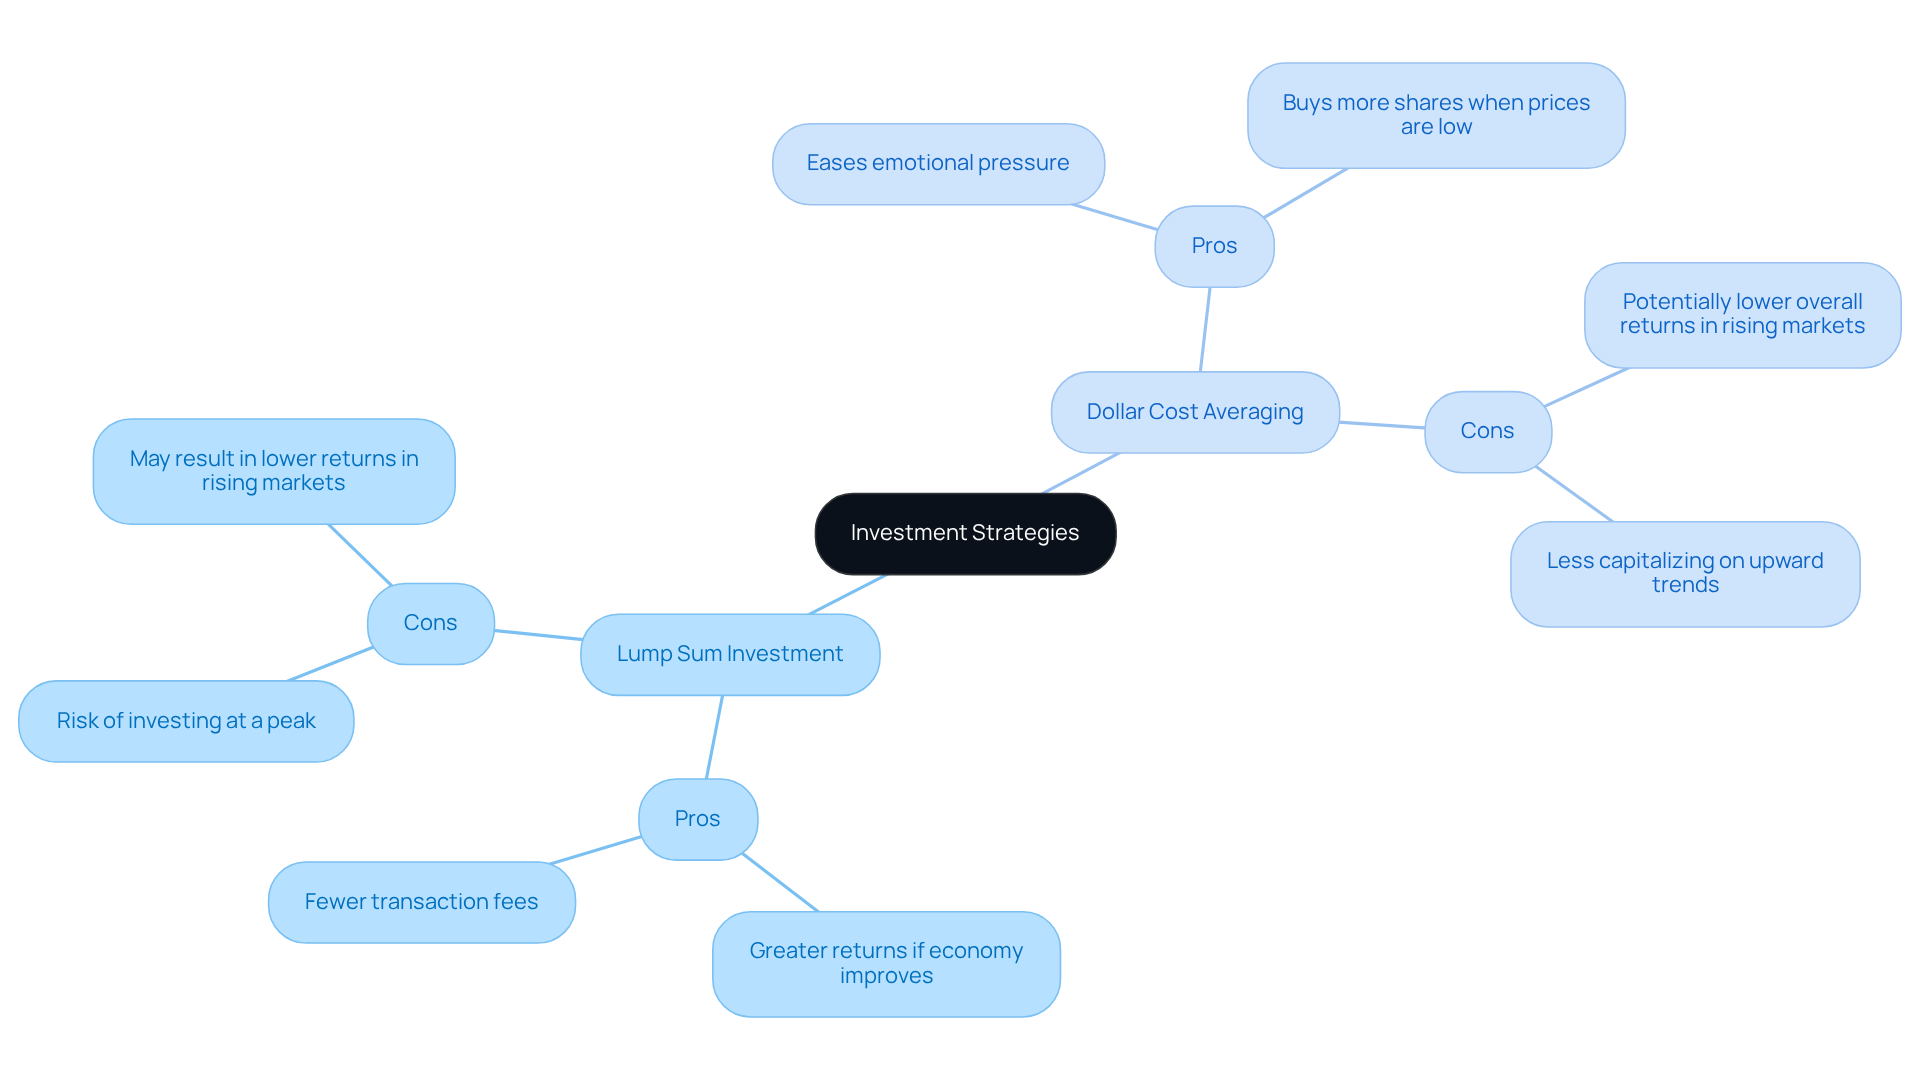
Allocating funds as a lump sum or dollar cost average offers several benefits that can resonate with your family’s financial goals. Imagine the possibility of greater returns if the economy improves after your investment. Plus, it incurs fewer transaction fees compared to making multiple smaller investments. However, it’s important to consider the risk of investing at a peak, which could lead to immediate losses if the value decreases.
On the other hand, the strategy of using a lump sum or dollar cost average can help ease the emotional pressure many parents feel when timing their investments. It allows you to buy more shares when prices are low and fewer when prices are high, potentially lowering your average cost per share. Yet, it’s worth noting that the strategy of a lump sum or dollar cost average may result in lower overall returns in a consistently rising market, as you might not fully capitalize on the upward trend.
At Bright Advisers, we understand the unique challenges young families face in their financial planning journey. Our innovative wealth management strategies, including hyper-personalized asset portfolios, are designed to help you navigate these decisions with confidence. By leveraging advanced technology, we aim to alleviate your anxiety and safeguard your family’s economic future, ensuring that your strategy aligns with your long-term objectives.
Together, we can explore our scientific investment strategies, such as the Diversified Premia, Opportunity Strategy, and Quality Strategy. These customized approaches are here to maximize your outcomes while supporting your family’s financial plan. Remember, we’re here for you every step of the way.
Assess Your Financial Situation and Goals
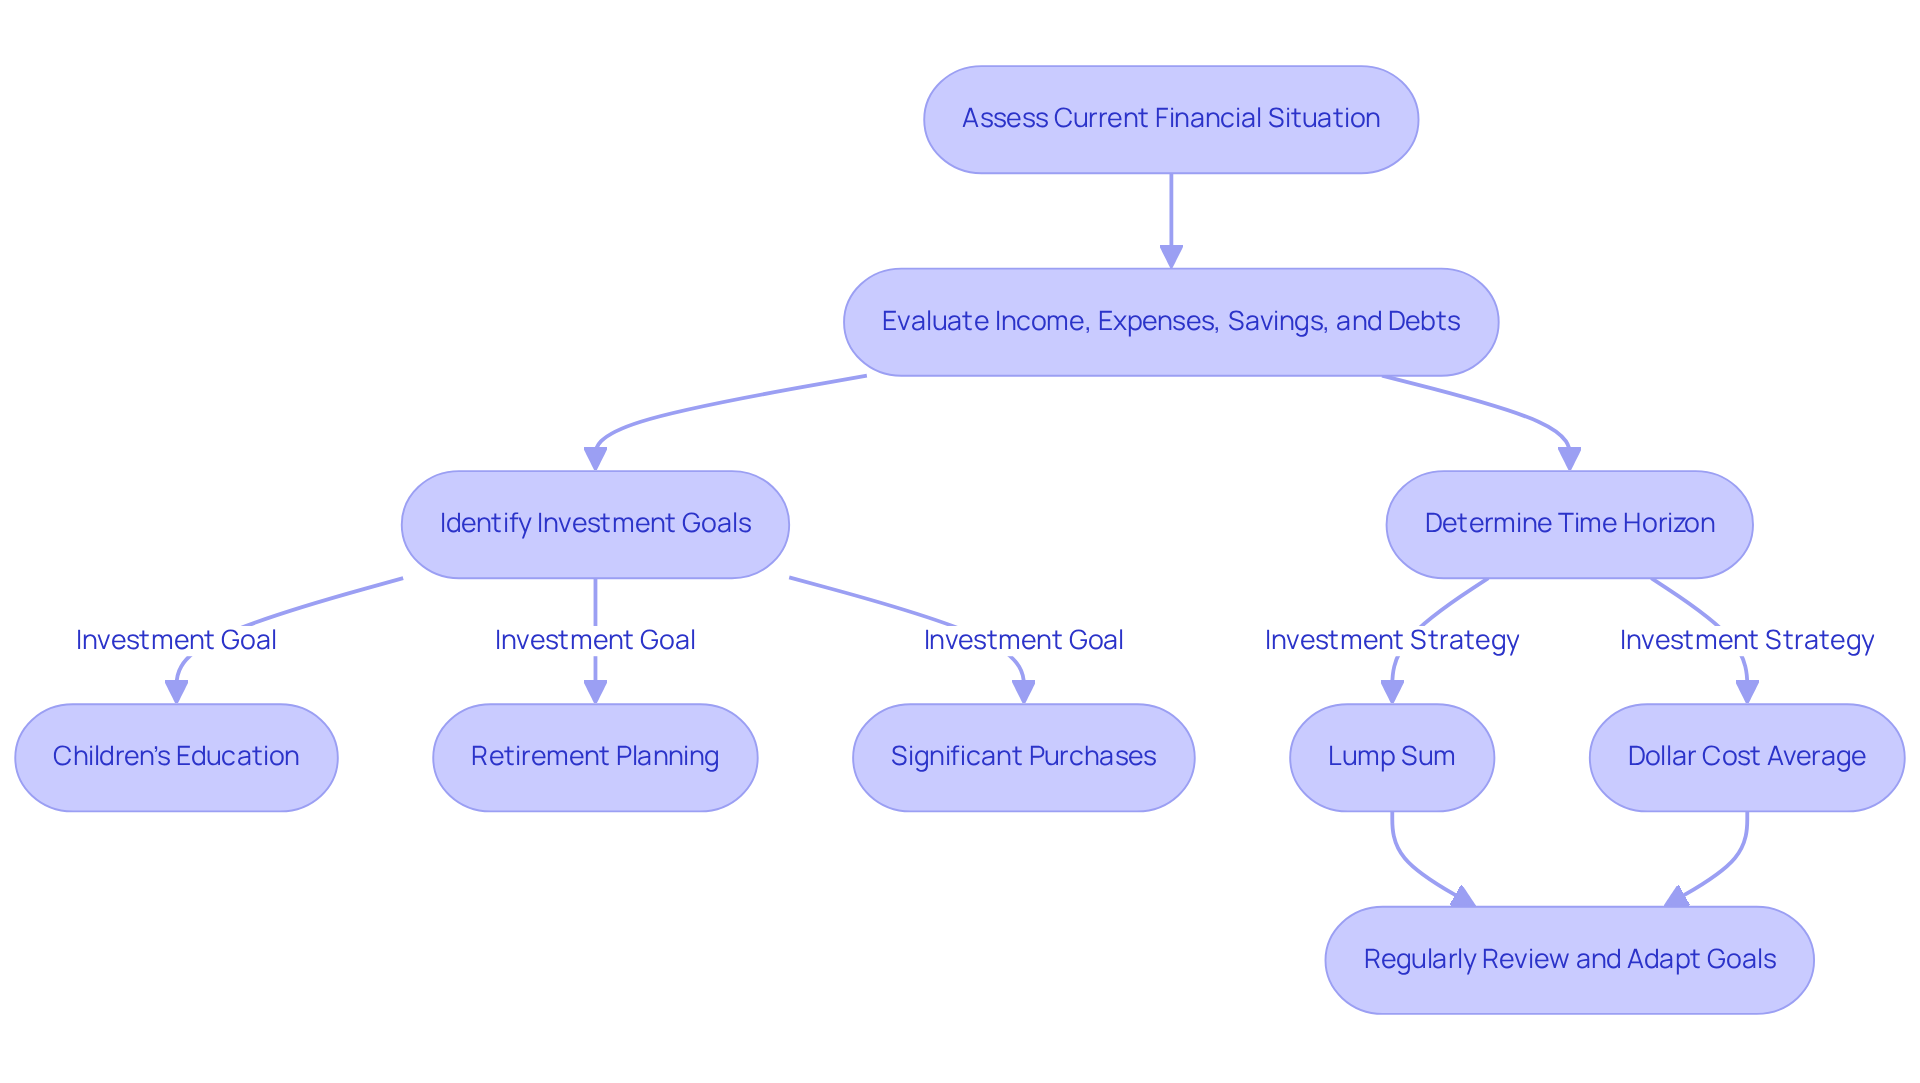
Begin by taking a moment to evaluate your current financial situation. Consider your income, expenses, existing savings, and any debts. This foundational understanding is essential for effective financial planning. Next, think about your investment goals. Are you saving for your children’s education, planning for retirement, or preparing for a significant purchase? Research shows that young parents often save an average of $30,000 for their children’s education. This highlights the importance of setting specific targets that reflect your family’s vision for the future.
It’s also critical to understand your time horizon. If you’re looking to invest for the long term, using a lump sum or dollar cost average strategy can be beneficial, allowing you to take advantage of growth over time. However, if you’re feeling risk-averse or uncertain about market conditions, using a lump sum or dollar cost average strategy might be more suitable. This approach enables you to invest gradually, helping to mitigate the impact of market volatility.
Real-life examples can illustrate how families have successfully defined their investment goals. Imagine a family saving for a home down payment, setting a goal of $50,000 within five years. This would require monthly contributions of approximately $833. This organized method not only clarifies objectives but also promotes accountability, aligning with the comprehensive management strategies provided by Bright Advisers, including budgeting and tax planning.
Experts emphasize that setting financial goals is an ongoing journey that requires planning, discipline, and flexibility. It’s essential to consistently assess and modify your objectives as life evolves, ensuring you stay in sync with your monetary priorities. Consulting with a financial advisor can also maximize your tax-efficient savings and investments, providing additional support along your economic journey. By creating a clear picture of your financial landscape, you can make informed choices that support your family’s long-term well-being. Remember, at Bright Advisers, we believe in the philosophy to ‘Plan purposefully. Live richly.
Make an Informed Decision Based on Your Analysis
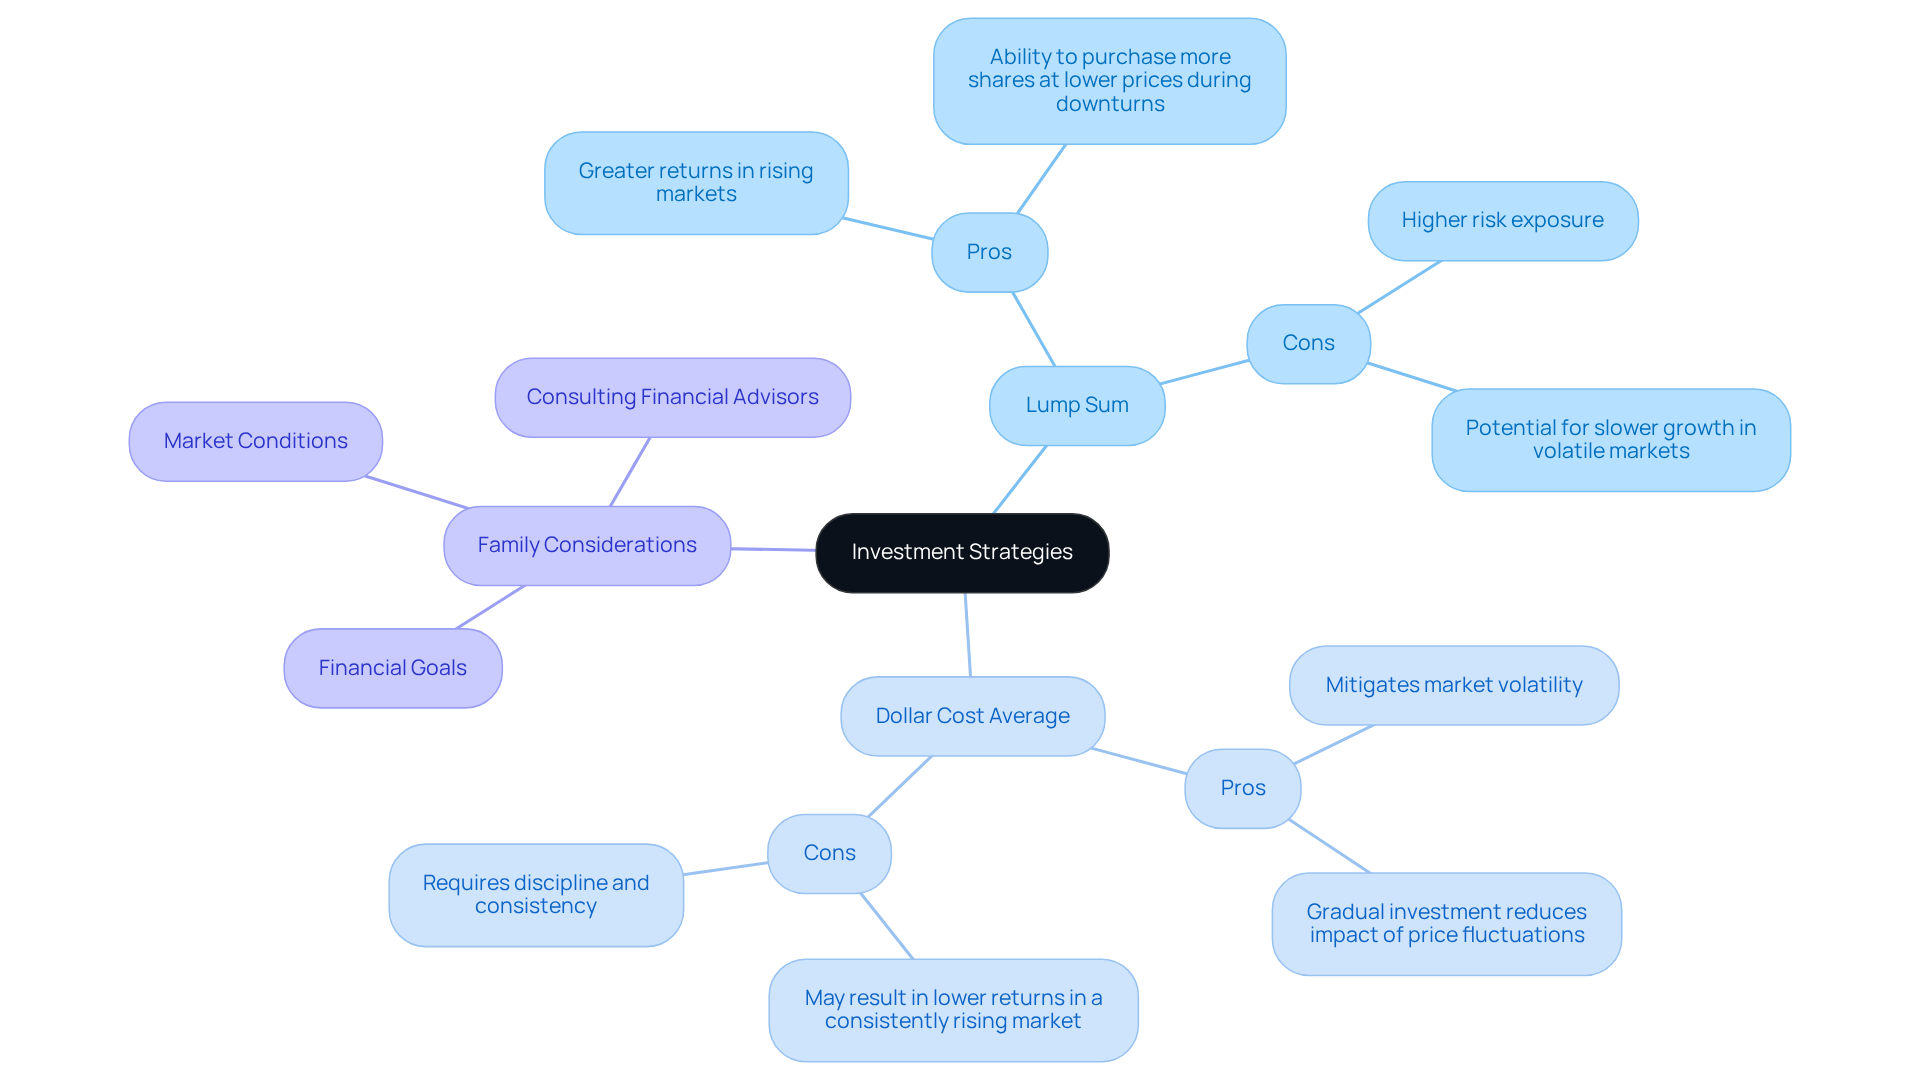
When weighing the pros and cons of contributions, it’s essential to consider whether to choose a lump sum or dollar cost average based on your family’s financial situation and long-term goals. If you have a lump sum available and feel comfortable with the associated risks, you may find that lump sum or dollar cost average investing could offer greater returns, especially in a rising market. Conversely, if you prefer a cautious approach that mitigates exposure to market volatility, opting for a lump sum or dollar cost average allows for gradual investment over time, helping to soften the impact of price fluctuations.
Consider how you feel about economic changes and how each strategy fits into your overall financial plan. For instance, families who opted for a lump sum or dollar cost average during market downturns often found it beneficial, as it enabled them to purchase more shares at lower prices, ultimately enhancing their long-term financial prospects. In 2025, data revealed that 41% of young parents prioritize a company’s ESG (Environmental, Social, and Governance) track record when making investment choices, showcasing a growing commitment to sustainable investing.
Ultimately, whichever strategy you choose, ensure it aligns with your family’s financial aspirations and supports your journey toward a secure future. Remember, consulting with a financial advisor can provide personalized insights tailored to your unique situation, guiding you through these significant decisions with care.
Conclusion
Choosing between lump sum investing and dollar cost averaging is a crucial decision that can significantly shape your family’s long-term financial success. Each strategy has its unique advantages and disadvantages, making it essential for you to carefully evaluate your financial situation and goals before committing to one approach. Understanding these investment methods empowers families to align their financial choices with their aspirations, whether you’re saving for education, retirement, or other significant milestones.
Throughout this guide, we’ve explored the benefits of both lump sum investing and dollar cost averaging. Lump sum investing can lead to greater returns in a rising market, while dollar cost averaging provides a comforting buffer against market volatility, allowing you to purchase more shares at lower prices. Additionally, personal financial assessments and goal-setting are vital in determining which strategy best suits your individual circumstances. As highlighted, young families, in particular, must navigate these choices with a focus on their long-term objectives and risk tolerance.
Ultimately, the journey toward financial security requires thoughtful planning and informed decision-making. We encourage you to consult with financial advisors to tailor your strategies to your unique needs and circumstances. By doing so, you can confidently embark on your investment journey, ensuring that your choices today pave the way for a prosperous tomorrow. Together, we can navigate this journey, supporting each other along the way.
Frequently Asked Questions
What is lump sum investing?
Lump sum investing involves committing a substantial amount of money into a financial asset all at once.
What is dollar cost averaging (DCA)?
Dollar cost averaging (DCA) is an investment strategy where a fixed amount of money is allocated at regular intervals, regardless of market conditions, which helps ease the stress of price fluctuations.
What are the benefits of dollar cost averaging?
DCA helps diversify investments over time, potentially lowering the average cost per share and providing a sense of security in unpredictable markets.
How did dollar cost averaging perform during the financial landscape of 2020?
Investors who adopted a dollar cost averaging strategy, investing $10,000 each month in the S&P 500, outperformed those who made a single investment of $120,000 at the year’s start.
Why do financial advisors caution against lump sum investing?
Many financial advisors caution against placing large sums all at once due to the stress of fluctuating markets, recommending a more thoughtful approach to investing.
How can families align their financial choices with their goals?
Families can align their financial choices with their goals and risk tolerance by understanding the pros and cons of lump sum investing and dollar cost averaging, allowing them to make informed decisions for long-term financial well-being.
List of Sources
- Understand Lump Sum Investing and Dollar Cost Averaging
- Retirement Planning Case Study – Cedarwood WM (https://cedarwoodwm.co.uk/case_studies/case-study-title-3)
- Dollar-Cost Averaging Versus Lump Sum Investing (https://forbes.com/sites/kristinmckenna/2025/04/15/dollar-cost-averaging-versus-lump-sum-investing)
- Case Study: Retirees – Mariaca Wealth Management (https://mariacawealth.com/case_studies/retirees)
- Getting a client mortgage-free with a secure retirement – Hobbs Financial Practice Limited (https://hobbsfinancial.ie/case_studies/mortgage-free-secure-retirement)
- Assess Your Financial Situation and Goals
- How to Set Financial Goals for Your Future (https://investopedia.com/articles/personal-finance/100516/setting-financial-goals)
- Five Financial Goals To Boost Your Wealth In 2025 (https://investors.com/etfs-and-funds/personal-finance/financial-goals-to-boost-your-wealth-in-2025)
- Make an Informed Decision Based on Your Analysis
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- What is Risk Tolerance? A Guide for Parents & Teens | Mydoh (https://mydoh.ca/learn/money-101/investing/what-is-risk-tolerance-a-guide-for-parents-teens)
- How Will the Great Wealth Transfer Impact the Markets? (https://ml.com/articles/great-wealth-transfer-impact.html)
- The 200 best investing quotes of all time – Equito (https://equito.co/the-best-investing-quotes)
- How to Determine Your Risk Tolerance Level (https://schwab.com/learn/story/how-to-determine-your-risk-tolerance-level)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading