

Overview
For young families, choosing between lump sum investing and dollar cost averaging (DCA) can feel overwhelming. It’s essential to consider your unique financial situation and risk tolerance. While lump sum investing might promise higher returns in a thriving market, many families find comfort in DCA. This strategy not only eases the stress of market fluctuations but also helps in managing emotional responses to financial decisions.
Imagine if you could invest without the constant worry of timing the market poorly. DCA allows you to invest steadily over time, reducing anxiety and fostering a sense of security for your family. This approach can be especially beneficial for those navigating the ups and downs of financial planning while juggling family priorities.
Ultimately, the best strategy is one that aligns with your family’s values and goals. Remember, we’re here for you, ready to support you through this journey. Together, we can navigate these important decisions with confidence and care.
Key Highlights:
- Lump sum investing involves a one-time investment of a large sum, potentially leading to higher returns in favourable markets.
- A Vanguard study shows lump sum investing outperforms dollar cost averaging 64% of the time over six months and 92% over 36 months.
- Dollar cost averaging (DCA) spreads investments over time, reducing volatility effects and allowing for consistent purchasing regardless of market conditions.
- DCA can provide psychological comfort by mitigating the fear of poor timing and market fluctuations.
- Lump sum investing has risks, including market timing risk and emotional stress from committing a large amount at once.
- DCA encourages disciplined investing habits but may yield lower returns compared to lump sum investing over long periods.
- The choice between lump sum and DCA should consider a family’s risk tolerance, financial situation, and market conditions.
- Consulting with a financial planner can help families make informed decisions tailored to their unique circumstances.
Introduction
Imagine a sudden financial windfall—perhaps an unexpected bonus or an inheritance. For young families, this moment presents a pivotal choice between two investment strategies: lump sum investing and dollar cost averaging. Each approach offers distinct advantages and potential pitfalls, making it essential for families to weigh their options carefully.
With the stakes high and market volatility a constant concern, it’s important to understand how families can determine which strategy best aligns with their financial goals and risk tolerance. Together, we can navigate this journey.
Define Lump Sum Investing and Dollar Cost Averaging
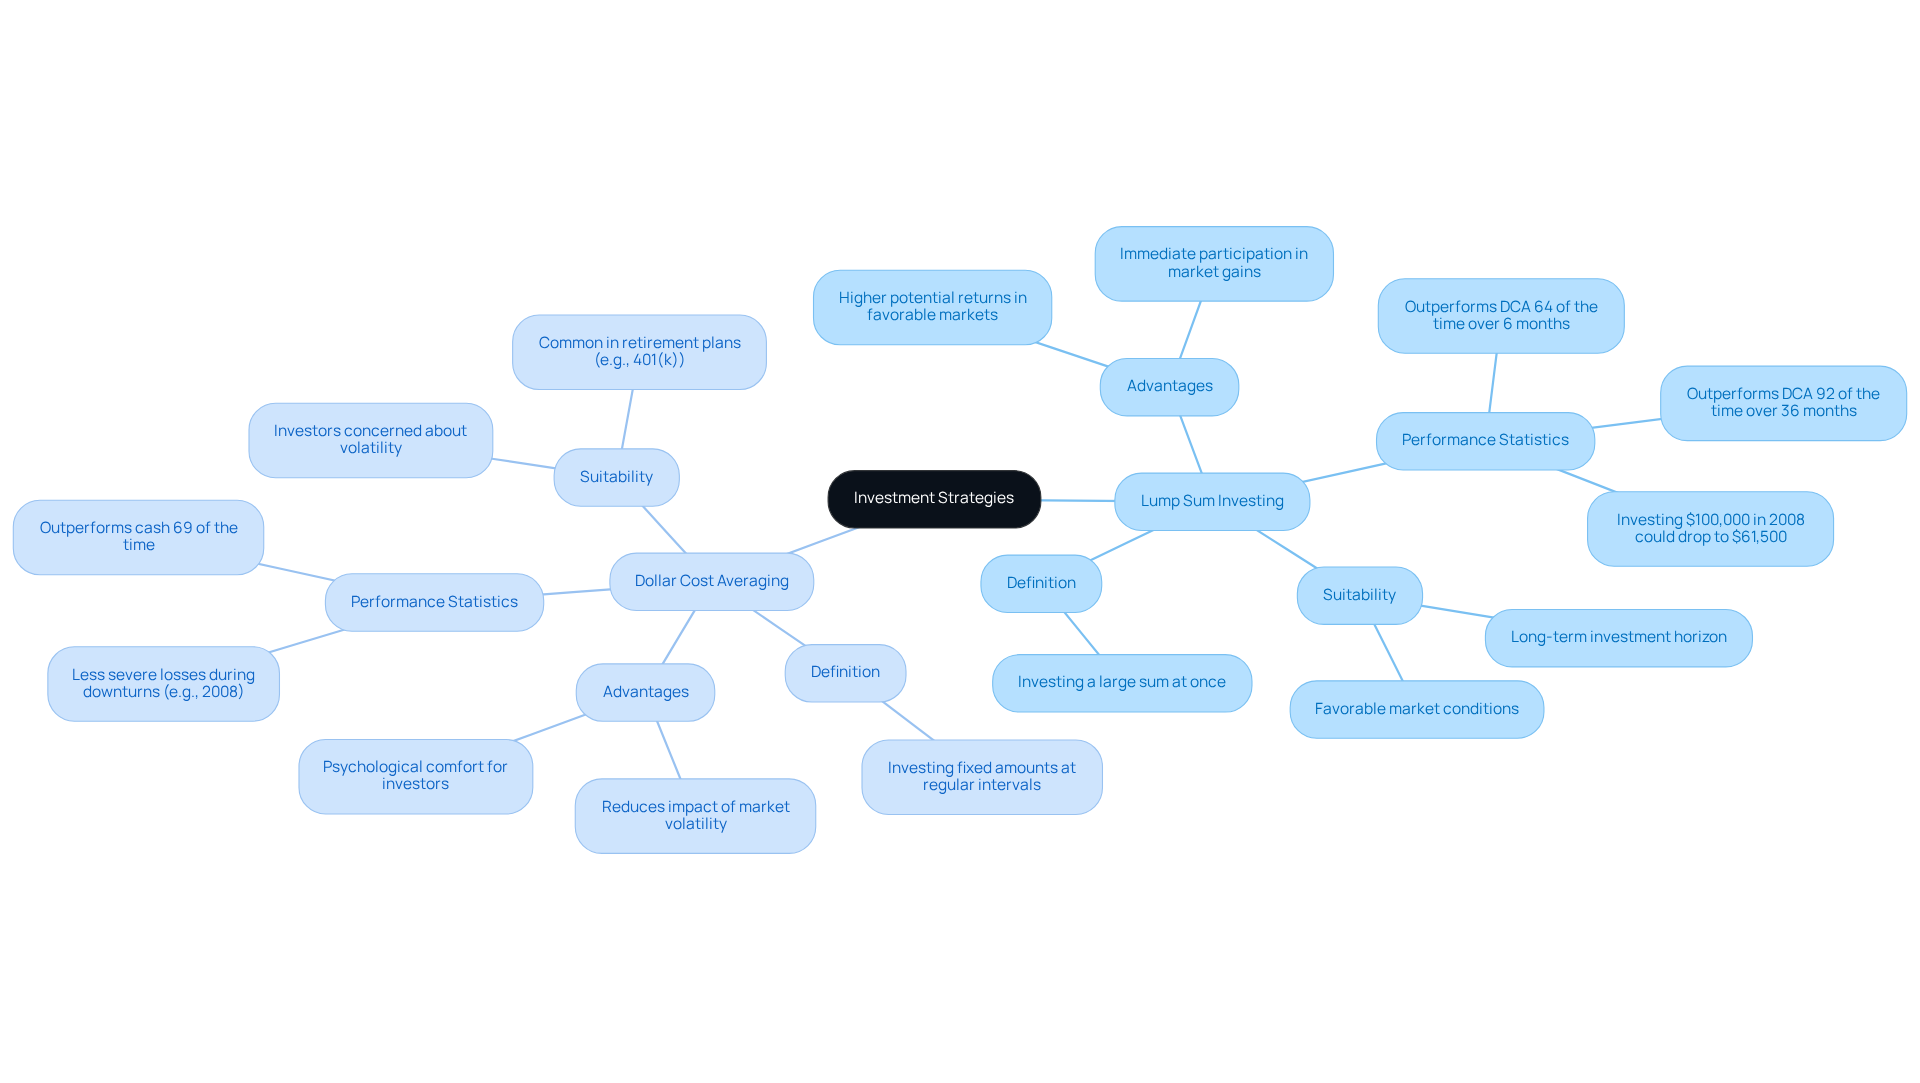
Imagine receiving a significant windfall, like an inheritance or a bonus. When considering lump sum vs dollar cost averaging, it’s important to note that lump sum allocation allows you to invest a substantial amount of money into financial assets, such as stocks or mutual funds, all at once. This strategy can be particularly beneficial, enabling you to seize potential gains right away. A Vanguard study reveals that when comparing lump sum vs dollar cost averaging (DCA), lump sum investing outperforms DCA 64% of the time over six months and an impressive 92% of the time over 36 months, showcasing its efficiency in favorable market conditions.
On the flip side, the strategy of dollar cost averaging involves breaking down a total sum into smaller, fixed contributions made at regular intervals, which contrasts with a lump sum vs dollar cost averaging approach. This approach helps reduce the effects of volatility by spreading investments over time. It allows you to buy more shares when prices are low and fewer when they are high. For example, during the economic downturn of 2008, investors using DCA experienced a milder decline; a $100,000 investment fell to about $74,000, compared to a lump sum that might have dropped to $61,500.
Both strategies, namely lump sum vs dollar cost averaging, have their unique advantages. DCA provides a psychological comfort, easing concerns about the timing of investments. However, when considering lump sum vs dollar cost averaging, lump sum investing may be more suitable for those with a long-term investment horizon or when market conditions are favorable, as it allows for immediate participation in potential financial growth. Understanding these differences can empower families to make informed decisions that align with their financial aspirations. Remember, we’re here for you, and together, we can navigate this journey toward financial security.
Evaluate Pros and Cons of Each Strategy
Lump Sum Investing
Pros:
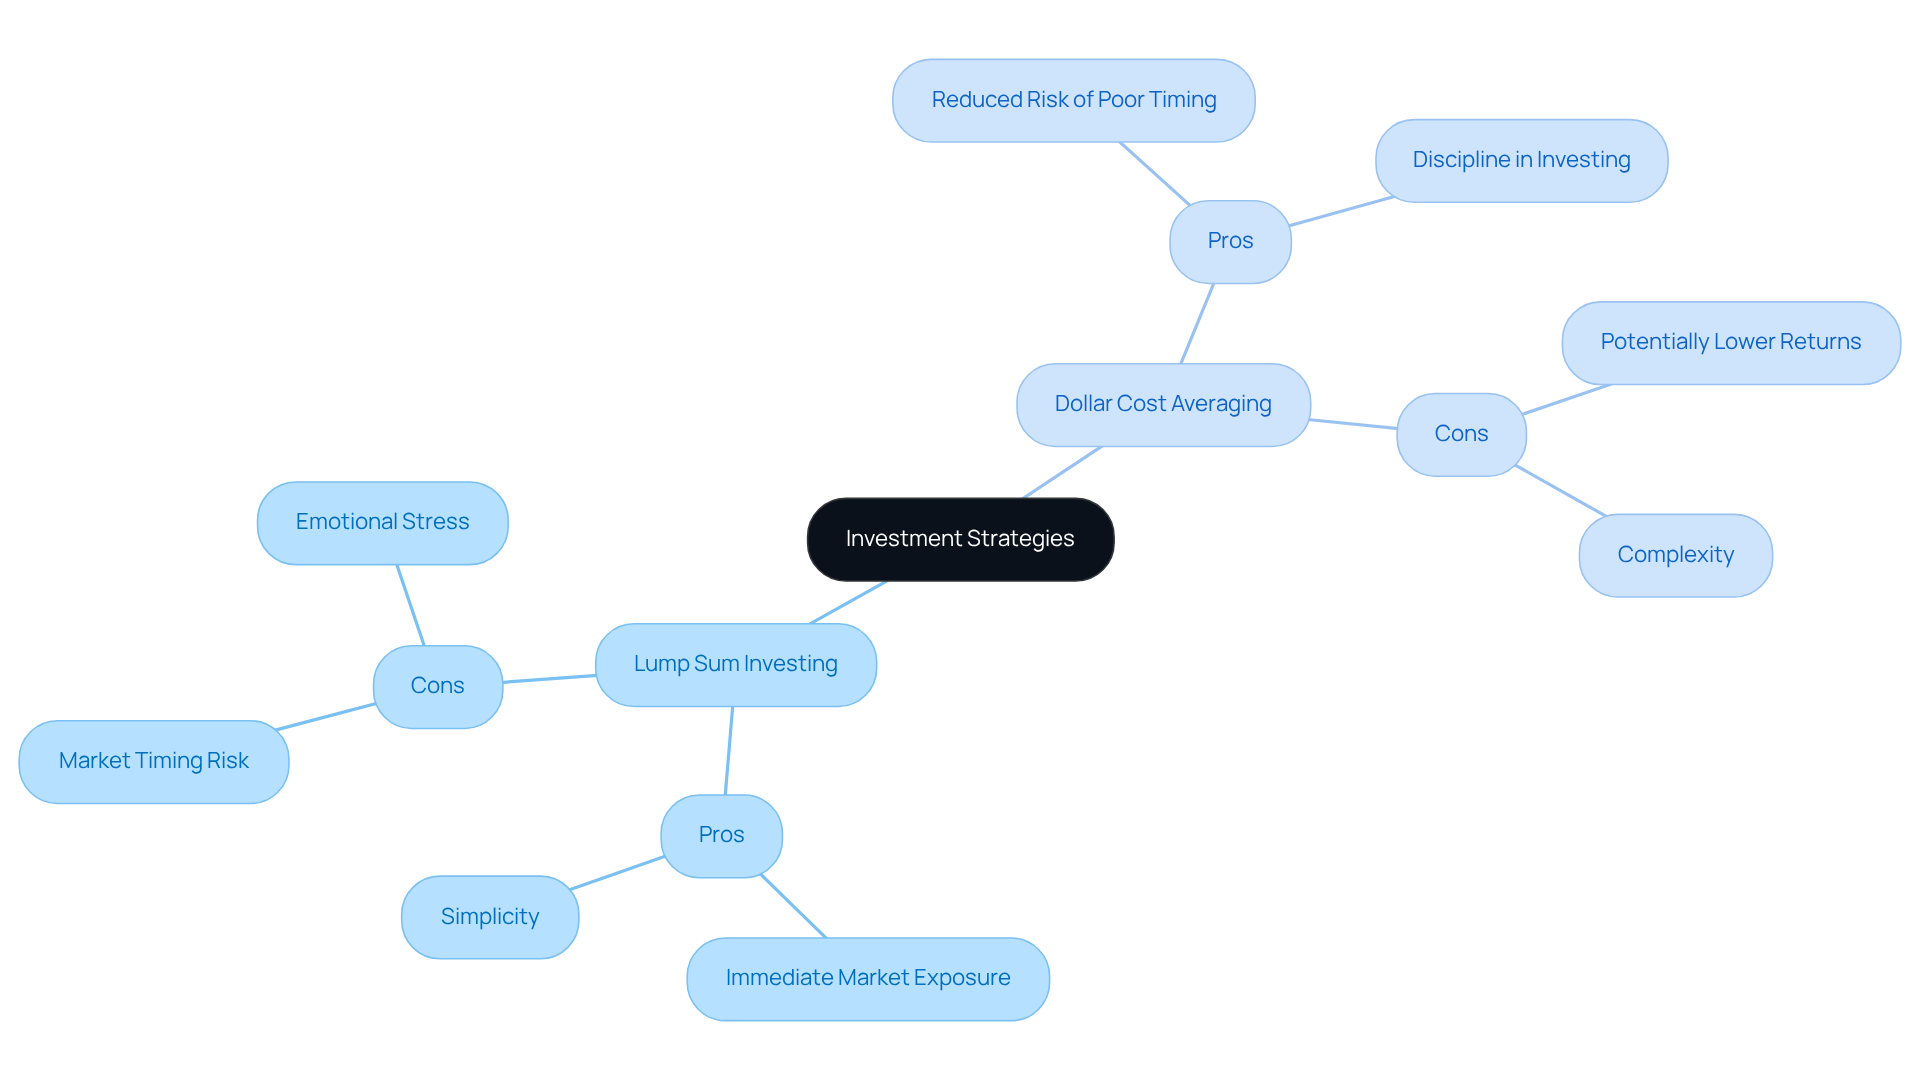
- Immediate Market Exposure: Imagine being able to invest your entire amount right away, allowing it to benefit from market growth immediately. This can lead to higher returns over time, especially in rising environments where seizing prompt profits is key for your family’s future.
- Simplicity: This approach is straightforward and requires less ongoing management compared to the strategy of lump sum vs dollar cost averaging. It can be a simpler choice for families looking to invest without the hassle.
Cons:
- Market Timing Risk: However, it’s important to understand that if the market declines shortly after your investment, the entire amount could face significant losses. For instance, investing a large sum at the beginning of 2008 could have resulted in nearly a 40% loss, highlighting the risks tied to timing your investments.
- Emotional Stress: The pressure of committing a substantial amount at once can lead to anxiety, especially during unpredictable financial times. This emotional burden might discourage some families from choosing this strategy.
Dollar Cost Averaging
Pros:
- Reduced Risk of Poor Timing: Now, consider dollar cost averaging (DCA). By spreading your investments over time, you reduce the risk of investing all your funds at a market peak. This strategy can help ease the emotional stress that comes with market fluctuations, making investing more manageable for your family.
- Discipline in Investing: DCA encourages consistent funding practices, which can be beneficial for long-term wealth accumulation. It allows you to buy more shares when prices are low and fewer when they are high, fostering a steady investment habit.
Cons:
- Potentially Lower Returns: It’s worth noting that historically, lump sum investing has outperformed DCA in many scenarios, particularly in rising markets. Over a 20-year period, lump-sum allocation typically concluded slightly ahead of DCA, with only negligible differences in returns.
- Complexity: Managing multiple smaller investments can be more complex and time-consuming than a single lump sum investment. This may require more attention and organization from your family.
In summary, while both strategies, namely lump sum vs dollar cost averaging, have their merits, it’s crucial for families to consider their unique financial situations and emotional comfort levels. Remember, we’re here for you—together, we can navigate this journey toward financial well-being.
Assess Suitability for Young Families
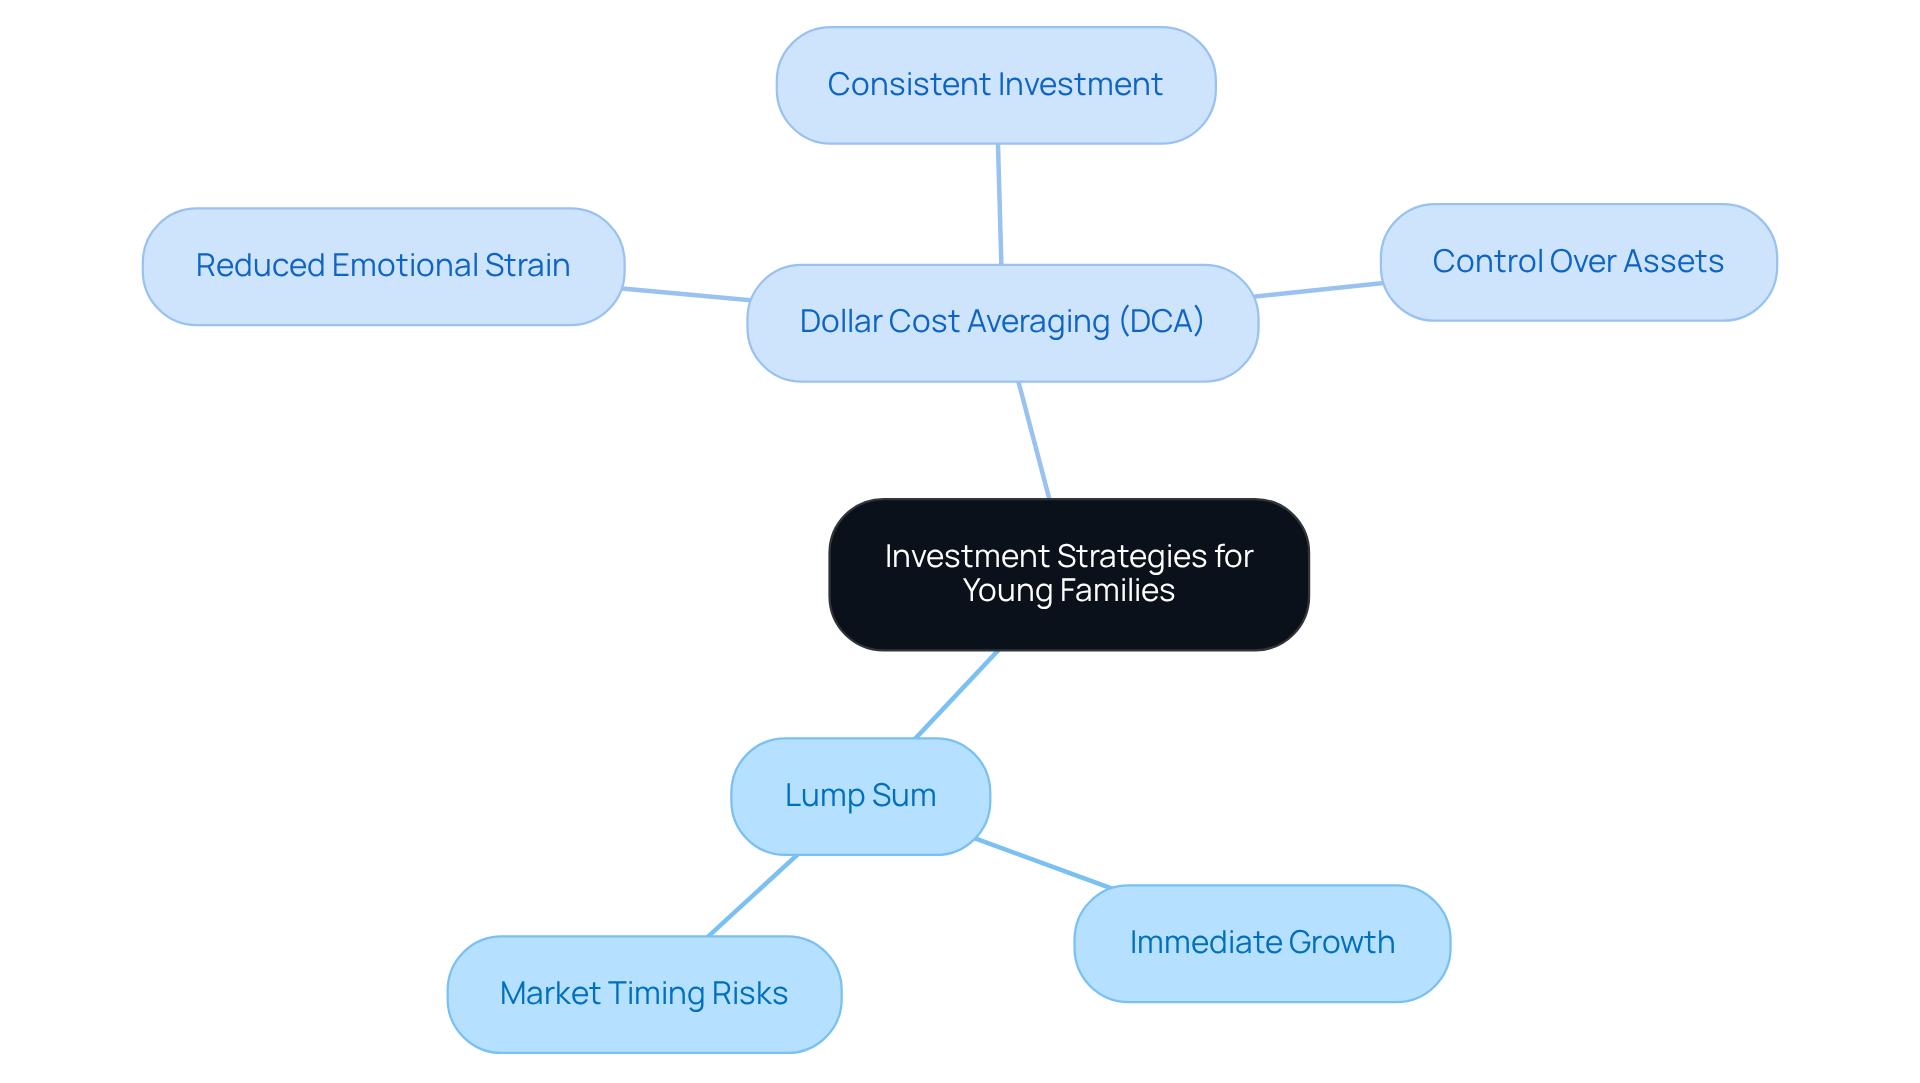
Imagine a moment when your family receives a sudden influx of cash—perhaps from a bonus or an inheritance. For young families, this can be an exciting opportunity to consider the advantages of lump sum vs dollar cost averaging in investing, which has the potential for immediate growth. However, it’s essential to pause and reflect on your family’s risk tolerance and the current market conditions. The volatility of the market can lead to significant short-term losses, and understanding this is crucial.
If you find yourself leaning towards a more cautious approach, dollar cost averaging (DCA) might be the right fit for your family. This strategy allows you to invest smaller amounts gradually, easing the emotional strain that market fluctuations can bring. It offers a sense of control over your assets, making it particularly beneficial for families with limited disposable income. With DCA, you can invest consistently without the pressure of a large upfront commitment.
At Bright Advisers, we believe that personalized financial planning should be accessible to everyone. Our in-house technology helps eliminate unnecessary fund fees and captures tax-loss harvesting opportunities, ensuring your family’s financial journey is as smooth as possible.
Ultimately, the choice between lump sum vs dollar cost averaging depends on your family’s unique financial situation, investment goals, and comfort level with risk. Consulting with a financial planner at Bright Advisers can provide you with tailored guidance that empowers you to make informed decisions. Together, we can navigate this journey, enhancing your wealth management experience and aligning it with your family’s values and vision.
Conclusion
Navigating the decision between lump sum investing and dollar cost averaging is a pivotal moment for young families eager to foster their financial growth. Each strategy offers unique advantages and challenges, making it vital to choose an approach that resonates with your family’s financial goals and comfort with risk. Imagine the immediate market exposure and potential higher returns that lump sum investing can provide. On the other hand, dollar cost averaging can offer a more gradual and reassuring way to handle market ups and downs.
Key insights reveal that:
- Lump sum investing often shines in favorable market conditions, yet it carries the risk of notable losses if market timing doesn’t align.
- Conversely, dollar cost averaging helps cushion the impact of market fluctuations and encourages disciplined investing, though it may result in lower overall returns during a consistently rising market.
It’s essential for families to thoughtfully weigh these factors to discover which strategy aligns best with their unique circumstances.
Ultimately, embarking on the journey toward financial security means understanding these investment strategies and their implications. By seeking guidance from financial experts and reflecting on personal comfort levels with risk, young families can make informed decisions that pave the way for a more secure financial future. Embracing a personalized approach to investing not only enhances wealth management but also aligns with your family’s values and aspirations, ensuring a brighter tomorrow for everyone involved. Together, we can navigate this journey, and we’re here to support you every step of the way.
Frequently Asked Questions
What is lump sum investing?
Lump sum investing involves allocating a significant amount of money into financial assets, such as stocks or mutual funds, all at once. This strategy can help investors seize potential gains immediately.
How does lump sum investing compare to dollar cost averaging (DCA)?
A study by Vanguard shows that lump sum investing outperforms dollar cost averaging 64% of the time over six months and 92% of the time over 36 months, particularly in favorable market conditions.
What is dollar cost averaging (DCA)?
Dollar cost averaging is a strategy where a total sum is broken down into smaller, fixed contributions made at regular intervals. This approach helps reduce the effects of market volatility by spreading investments over time.
What are the benefits of dollar cost averaging?
DCA allows investors to buy more shares when prices are low and fewer when prices are high, providing a psychological comfort and easing concerns about the timing of investments.
How did dollar cost averaging perform during the economic downturn of 2008?
During the 2008 downturn, investors using DCA saw a $100,000 investment decline to about $74,000, while those who invested a lump sum might have seen their investment drop to $61,500.
Which strategy is more suitable for long-term investors?
Lump sum investing may be more suitable for long-term investors or when market conditions are favorable, as it allows for immediate participation in potential financial growth.
Why is it important to understand the differences between lump sum investing and dollar cost averaging?
Understanding these differences empowers families to make informed decisions that align with their financial aspirations and helps them navigate their journey toward financial security.
List of Sources
- Define Lump Sum Investing and Dollar Cost Averaging
- Does lump sum investing beat dollar cost averaging? (https://wiserinvestor.com/does-lump-sum-investing-beat-dollar-cost-averaging)
- How Dollar-Cost Averaging Stacks Up Against Lump-Sum Investing (https://forbes.com/sites/wesmoss/2025/07/28/how-dollar-cost-averaging-stacks-up-against-lump-sum-investing)
- Investing a Large Cash Inflow: All at Once or “Spread It Out”? – Strategic Wealth Partners (https://stratwealth.com/blog-investing-a-large-cash-inflow-all-at-once-or-spread-it-out)
- Evaluate Pros and Cons of Each Strategy
- How Dollar-Cost Averaging Stacks Up Against Lump-Sum Investing (https://forbes.com/sites/wesmoss/2025/07/28/how-dollar-cost-averaging-stacks-up-against-lump-sum-investing)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading