

Key Highlights
- Client concentration risk arises when a significant portion of wealth depends on a few sources, leading to potential financial instability.
- Nearly 75% of private wealth offices prioritise reducing client concentration risk to safeguard revenue growth.
- Strategies to diversify client bases include expanding networking efforts, utilising referrals, targeting diverse markets, and creating continuous income sources.
- Monitoring metrics such as revenue contributions and customer segmentation helps families assess their exposure to client concentration risk.
- Setting alerts for changes in customer contributions and conducting regular reviews can enhance financial stability.
- Technology, such as budgeting apps, provides real-time insights into finances, aiding families in making informed decisions.
- Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, emphasises fiduciary duty and transparency in wealth management.
- Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Introduction
Imagine feeling secure about your family’s financial future, even in uncertain times. Understanding client concentration risk is essential for families like yours. This risk happens when a big part of your wealth depends on just a few clients or investments, which can make things shaky during tough economic times.
By looking into smart ways to diversify, families can not only reduce these risks but also strengthen their financial stability. How can young families find their way through the challenges of managing wealth to create a secure and balanced financial future? Together, we can explore ways to build a more resilient financial future for your family.
Define Client Concentration Risk in Wealth Management
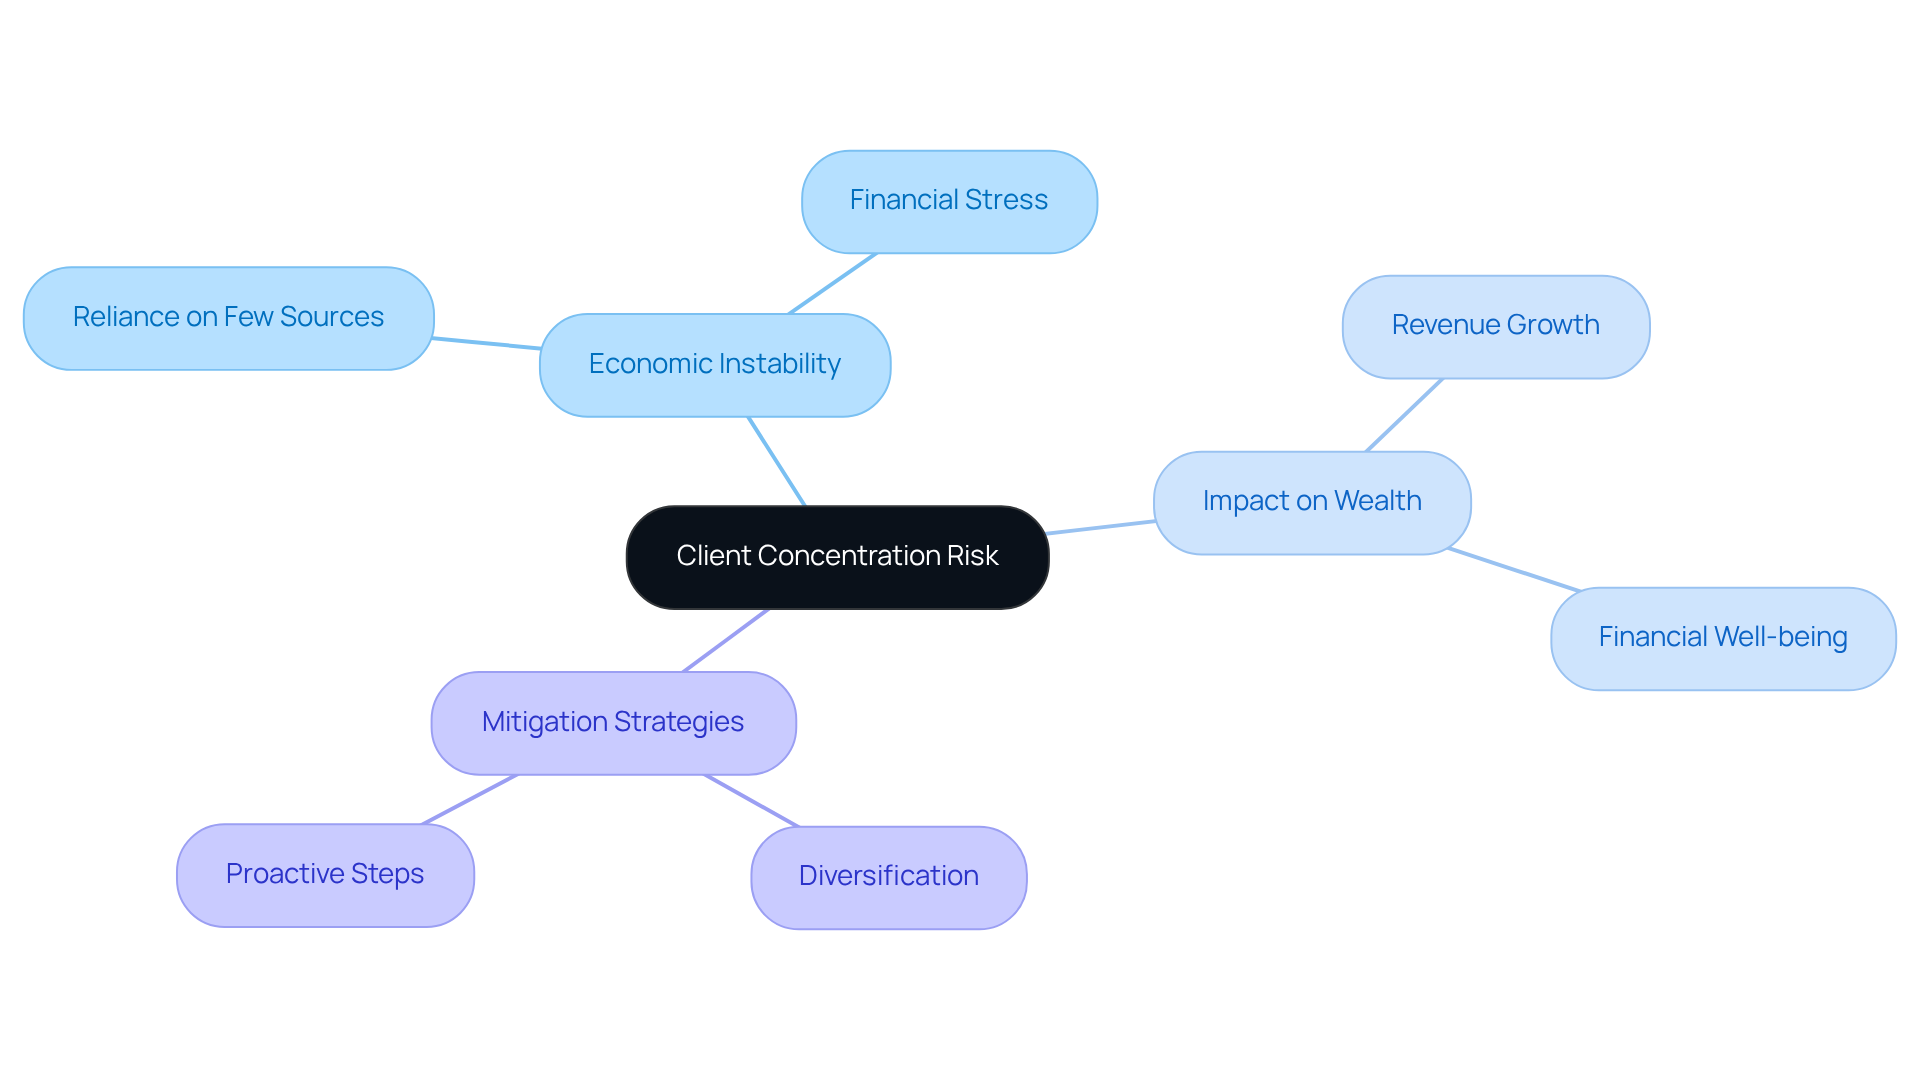
Imagine the worry that comes when your family’s financial stability hinges on just a few sources of income. Client concentration risk refers to the economic instability that can arise when a significant part of your household’s wealth relies on a small number of customers or investments. This can lead to significant financial stress if one of those sources falters.
Many families, just like yours, are taking steps to protect their wealth by diversifying their investments. Present data shows that almost three-quarters of private wealth offices focus on reducing client concentration risk, as losing a key patron can significantly affect revenue growth and overall financial well-being.
By recognizing this risk, you can take proactive steps to safeguard your family’s future. Understanding these risks empowers you to build a resilient financial future for your family.
Implement Strategies to Diversify Client Base
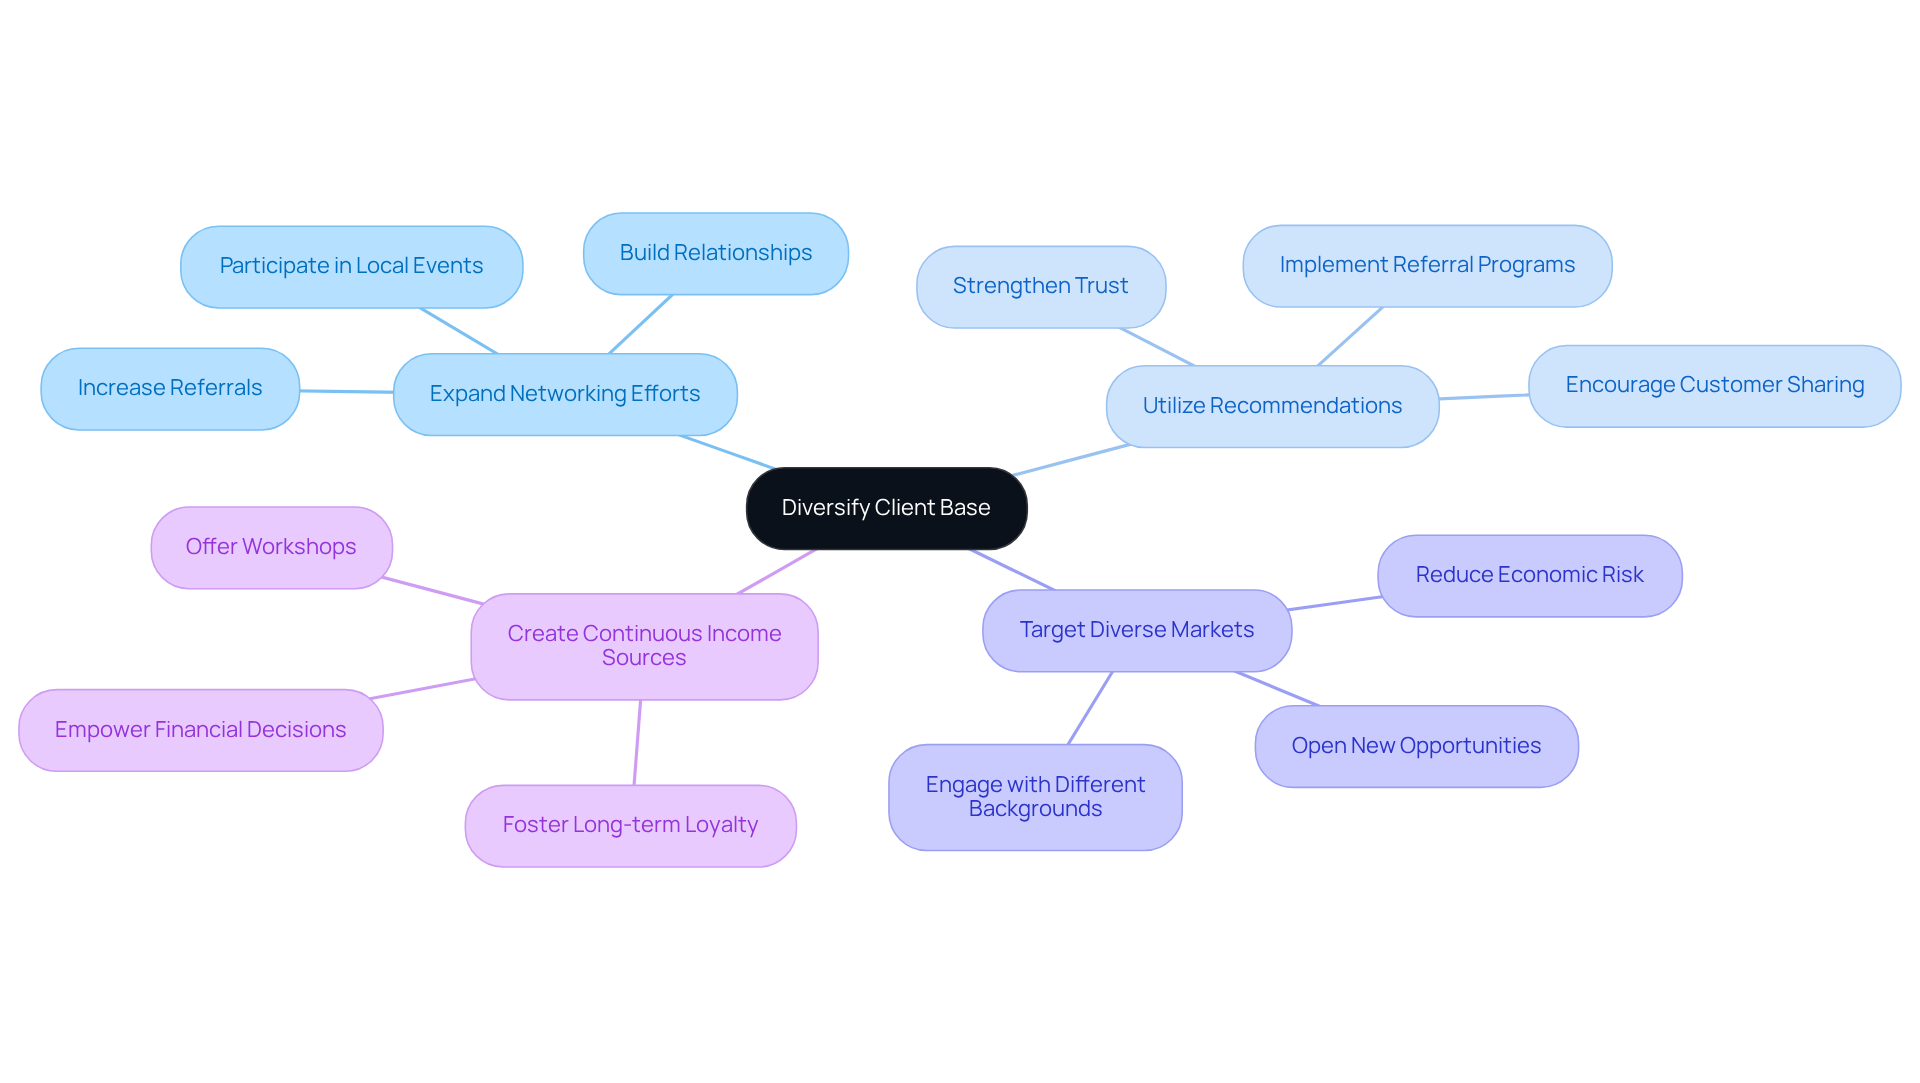
Imagine the worry of relying too heavily on a few clients for your family’s financial stability. To effectively manage client concentration risk, families should consider some nurturing strategies to diversify their client base:
- Expand Networking Efforts: Think about how wonderful it would be to connect with new families at local events, sharing experiences and building relationships that can lead to new opportunities. Participating in community-focused events in Southern California can foster connections and increase the likelihood of referrals.
- Utilize Recommendations: Encourage your happy customers to share their positive experiences with friends and family, creating a community of trust and support. A structured referral program can motivate current customers to bring in new ones, strengthening bonds through personal recommendations.
- Target Diverse Markets: Consider reaching out to families from different backgrounds, as this can open doors to new opportunities and strengthen your financial foundation. Interacting with customers from various sectors can help reduce client concentration risk associated with economic downturns, ensuring a more stable portfolio.
- Create Continuous Income Sources: Imagine offering services that not only help families but also create lasting bonds, like workshops that empower them to make informed financial decisions together. This method nurtures long-term customer loyalty and establishes a more robust economic foundation.
By embracing these strategies, you can build a resilient financial future for your family, ensuring peace of mind in uncertain times.
Monitor and Manage Client Concentration Metrics
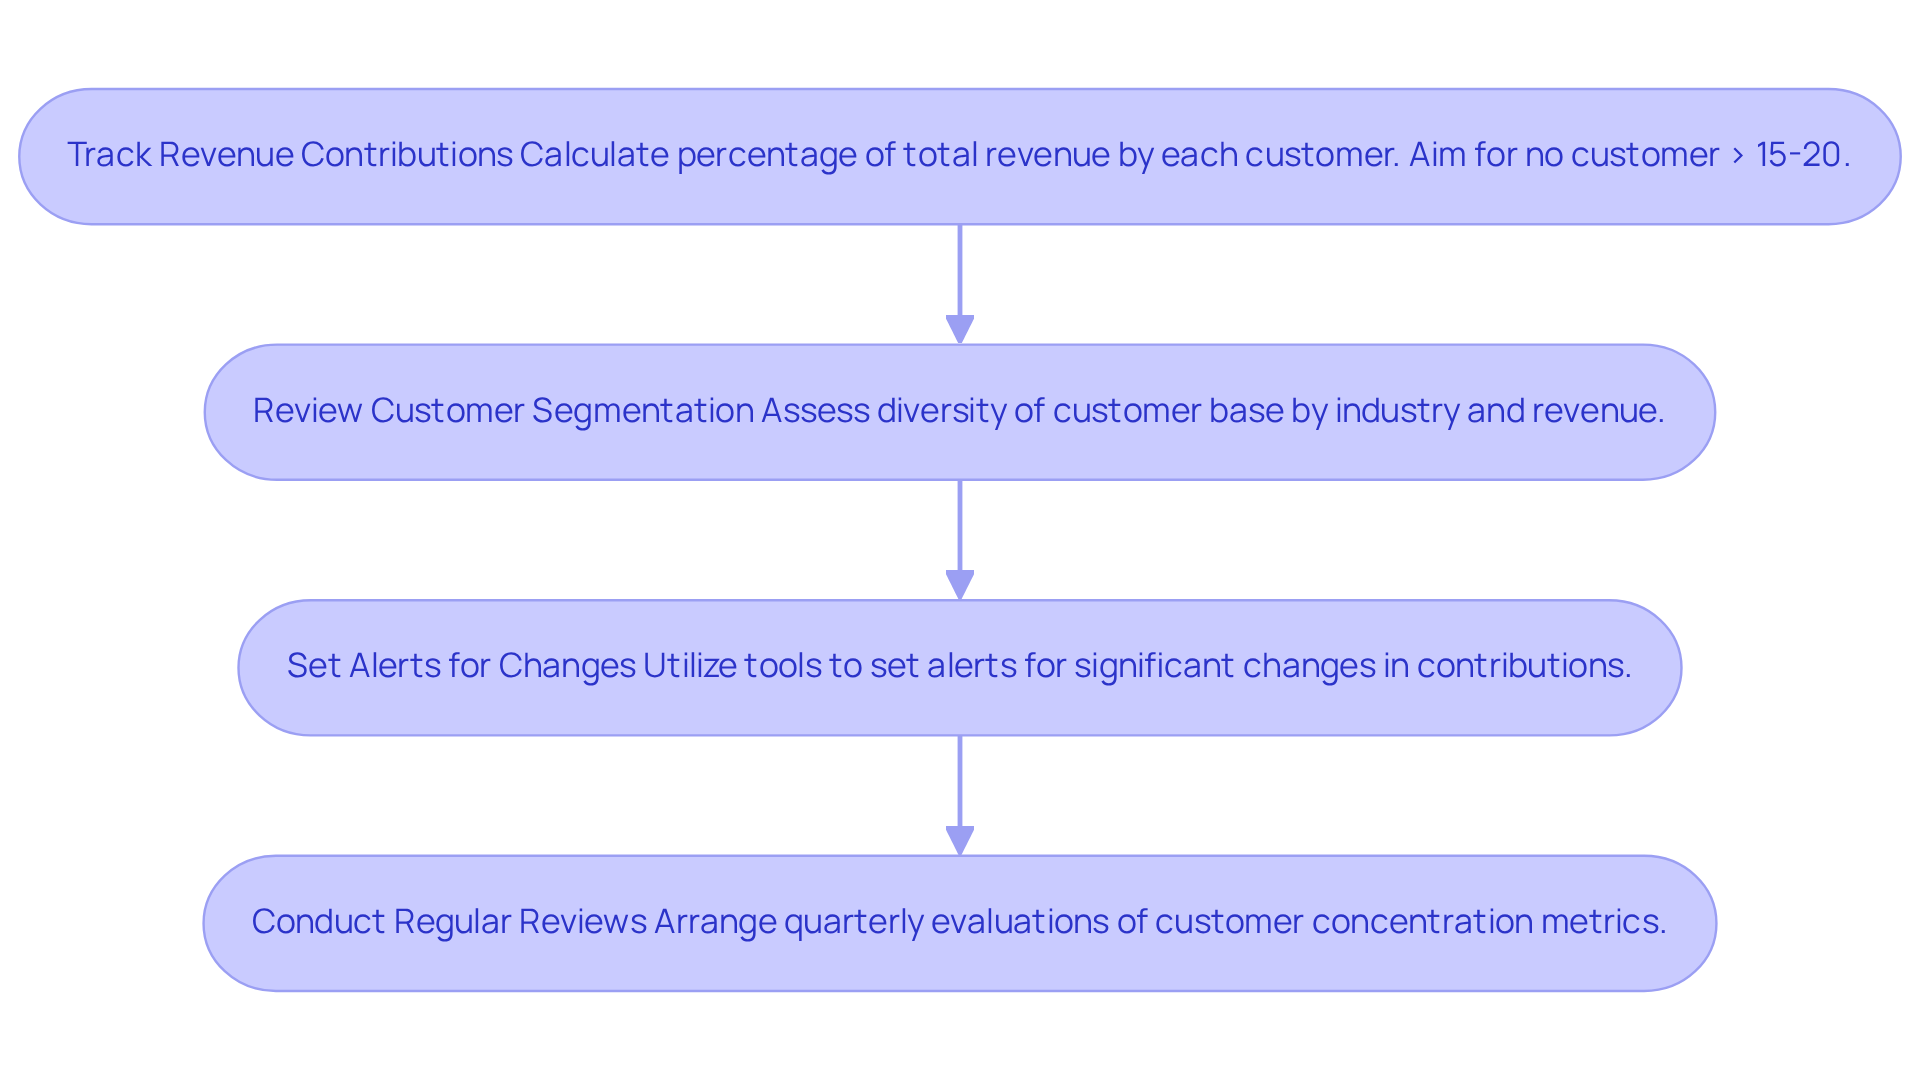
Imagine the worry that comes with relying too heavily on just a few customers for your family’s financial stability. To effectively manage client concentration risk, families should regularly monitor key metrics that indicate their exposure. Here are some actionable steps:
- Track Revenue Contributions: Calculate the percentage of total revenue generated by each customer. Ideally, no individual customer should represent more than 15-20% of total revenue. This can be done using simple spreadsheets or financial management software.
- Review Customer Segmentation: Regularly assess the diversity of your customer base. Segment customers by industry, revenue contribution, and engagement level to identify any over-reliance on specific accounts. For instance, in wealth management, it’s common for leading customers to contribute significantly to revenue, with the top five customers often accounting for 25-40% of total revenue.
- Set Alerts for Changes: Utilize management tools that enable households to set alerts for significant changes in contributions. This proactive approach helps families react quickly to shifts in their financial landscape, especially since losing a major customer can lead to a worrying drop in revenue.
- Conduct Regular Reviews: Arrange quarterly or bi-annual evaluations of customer concentration metrics with a monetary advisor. This ensures that families stay informed about their financial health and can make educated choices regarding diversification strategies. Frequent evaluations can uncover trends that suggest possible issues, such as increased churn rates among mid-market customers.
By actively monitoring these metrics, families can maintain a balanced approach to wealth management, thereby reducing the risks associated with client concentration risk. At Bright Advisers, we’re here to help families like Emily and Mark navigate these complexities through tailored wealth management solutions. Founded by Kevin Luu and Kathleen Chou in 2010, Bright Advisers emphasizes fiduciary duty and transparency, ensuring no hidden fees or conflicts of interest. This tailored planning not only addresses urgent financial issues but also enhances tax strategies, ensuring families can achieve their long-term financial objectives with confidence.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to uncertainty. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Leverage Technology for Effective Risk Management
Imagine the sleepless nights worrying about your family’s financial future. How can you ensure you’re making the right choices? Integrating technology can make it easier to manage those challenges.
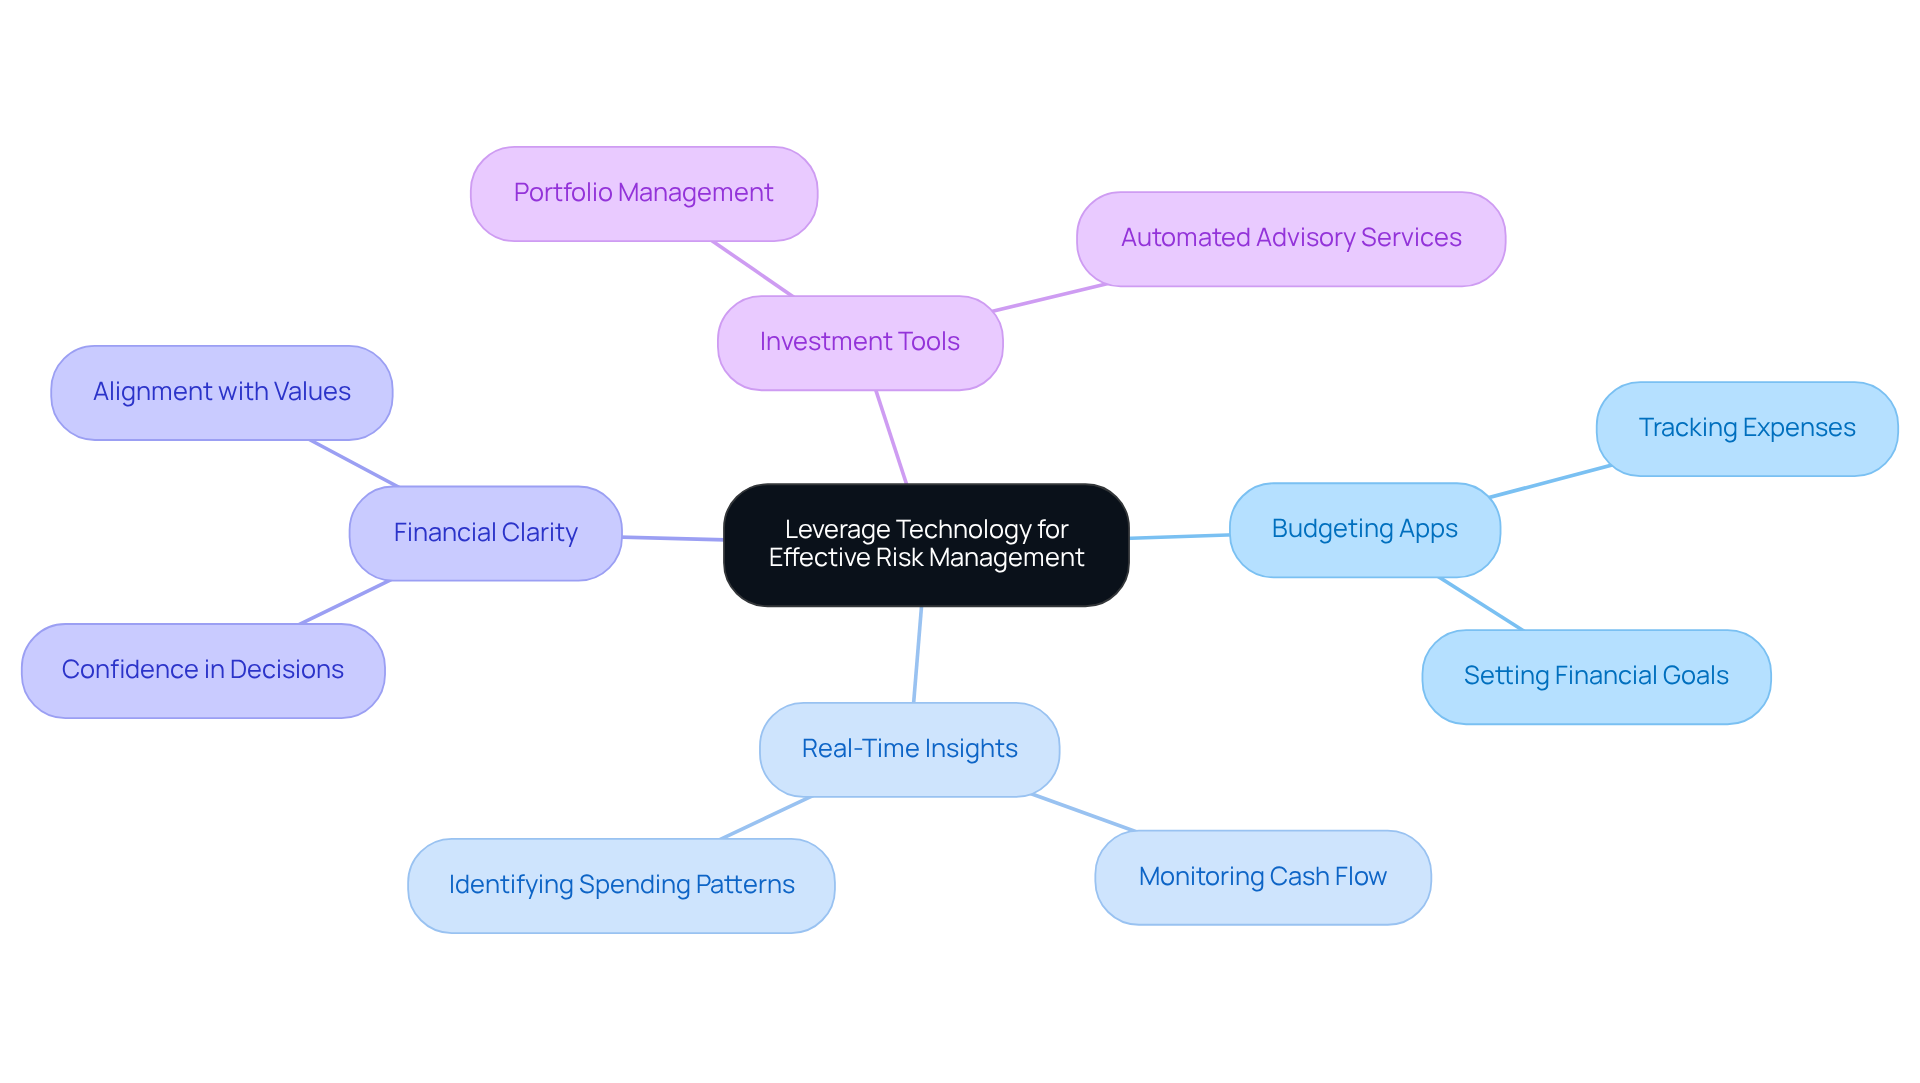
Think about using budgeting apps that give you real-time insights into your family’s finances. They can help you see where you stand and where you might need to focus your efforts. With a clear picture of your family’s finances, you can make informed decisions that align with your values and goals.
Many families are turning to technology to help them understand their finances better, and it’s becoming a vital part of wealth management. For instance, Emily and Mark found clarity in their financial situation through a comprehensive assessment, allowing them to develop a plan that truly reflects their aspirations.
Investing in tools that help you manage your family’s finances can be a game-changer, making it easier to stay on track with your goals. Imagine how much more confident you could feel knowing you have the right resources at your fingertips.
By embracing these technological advancements, you can take control of your family’s financial journey and secure a brighter future together. Bright Advisers is here to support families like yours in making wise wealth decisions and preserving your legacy for generations to come.
Conclusion
Imagine feeling secure about your family’s financial future, knowing you’re not relying on just a few sources of income. When you understand this risk, you can create a more stable and resilient financial future for your family. Taking proactive steps can help your family diversify investments, so you’re not relying on just a few sources of income.
Think about expanding your network, asking for referrals, and exploring new markets to create steady income for your family. Keeping an eye on your investments and using technology can help you manage risks more effectively. These practices can ease financial stress and build a supportive community around your family.
Diversification is key to feeling secure about your family’s financial future. When you take these steps, you create a strong financial foundation that helps your family thrive, no matter what happens. By embracing these practices, you can protect your wealth and focus on what truly matters – creating lasting memories with your loved ones.
If you need personalized guidance, we’re here for you. Reach out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967 to explore tailored solutions together.
Frequently Asked Questions
What is client concentration risk in wealth management?
Client concentration risk refers to the economic instability that can occur when a significant portion of a household’s wealth relies on a small number of customers or investments, potentially leading to financial stress if one of those sources falters.
Why is client concentration risk a concern for families?
It is a concern because if a key source of income or investment fails, it can significantly impact a family’s financial stability and overall well-being.
What steps can families take to mitigate client concentration risk?
Families can protect their wealth by diversifying their investments, which helps reduce reliance on a limited number of income sources.
How prevalent is the focus on reducing client concentration risk among wealth management offices?
Present data indicates that almost three-quarters of private wealth offices prioritize reducing client concentration risk to enhance revenue growth and financial stability.
What is the benefit of recognizing client concentration risk?
Recognizing this risk empowers families to take proactive measures to safeguard their financial future and build a more resilient financial plan.
List of Sources
- Define Client Concentration Risk in Wealth Management
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Family Office Study 2025: Statistics, Research, and Insights (https://pbig.ml.com/articles/family-office-report.html)
- (PDF) The Concentration Risk Indicator: Raising the Bar for Financial Stability and Portfolio Performance Measurement (https://researchgate.net/publication/368744006_The_Concentration_Risk_Indicator_Raising_the_Bar_for_Financial_Stability_and_Portfolio_Performance_Measurement)
- Customer Concentration Risk | Formula + Calculator (https://wallstreetprep.com/knowledge/customer-concentration)
- Famous Quotes on Financial Stability and Well-Being – Center for the Advancement of Well-Being (https://wellbeing.gmu.edu/famous-quotes-on-financial-stability-and-well-being)
- Implement Strategies to Diversify Client Base
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- Referral Marketing Statistics 2025: Key Trends & Insights (https://impact.com/referral/top-10-referral-marketing-statistics)
- Referral strategies for financial advisors: How to build a business that grows itself (https://advisorengine.com/action-magazine/articles/referral-strategies-for-financial-advisors)
- The Power Of Networking With Purpose (https://forbes.com/sites/matthewmeade/2025/12/16/the-power-of-networking-with-purpose)
- How Financial Advisors Can Generate More Client Referrals (https://lpl.com/join-lpl/why-choose-lpl/news-and-insights/8-tips-for-quality-referrals.html)
- Monitor and Manage Client Concentration Metrics
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Customer Concentration Risk | Formula + Calculator (https://wallstreetprep.com/knowledge/customer-concentration)
- Customer Concentration (https://metrichq.org/saas/customer-concentration)
- Revenue Concentration: Risk Analysis & Fixes | Count (https://count.co/metric/revenue-concentration-analysis)
- What is Customer Concentration Ratio? Definition, Process & Key Metrics (https://hyperbots.com/glossary/customer-concentration-ratio)
- Leverage Technology for Effective Risk Management
- Insights (https://bny.com/corporate/global/en/insights.html)
- Wealth Tech Trends Shaping the Next Decade (https://fusioniq.io/thought-leadership/wealth-management-tech-trends)
- Wealth Managers Plan Major Tech Investments for 2026 (https://wealthmanagement.com/financial-technology/advisors-are-unsatisfied-with-tech-stacks-they-plan-to-prioritize-upgrades-in-2026-)
- 50 Risk Management Quotes: Wisdom for Smart Decision-making | ITD World (https://itdworld.com/blog/leadership/risk-management-quotes)
- Risk Management Quotes from Warren Buffett, Keynes, and More | Seno Teguh Kuncoro posted on the topic | LinkedIn (https://linkedin.com/posts/seno-kuncoro_riskmanagement-quotes-activity-7380884593018802176-fcML)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading