

Key Highlights
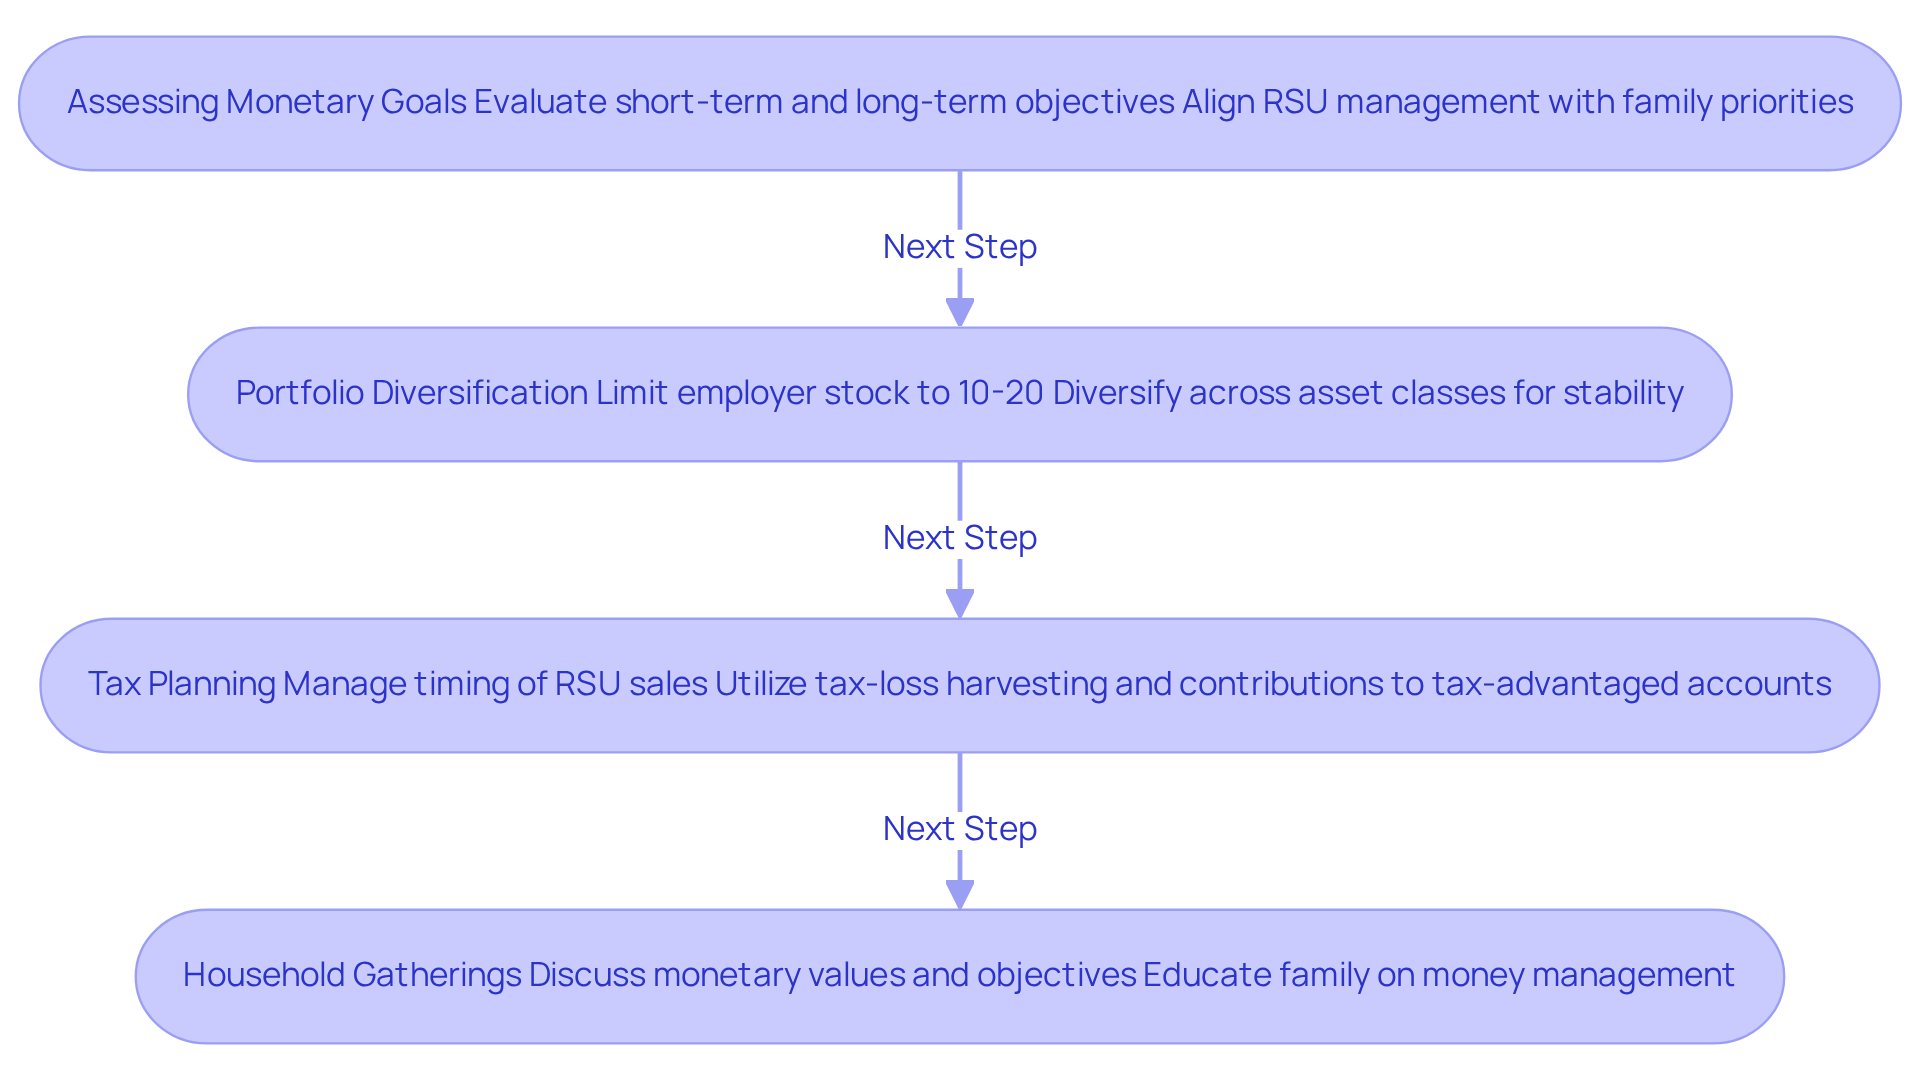
- Restricted Stock Units (RSUs) are often part of compensation packages, especially in tech and startups, and are taxed as regular income upon vesting in California.
- Families need to understand RSU tax implications to effectively manage their financial planning and avoid unexpected tax bills.
- Selling RSUs upon vesting can help cover tax obligations and reduce financial risk.
- California imposes a mandatory withholding of 10.23% on RSU income, which can significantly impact family budgets.
- Profits from selling RSUs are subject to capital gains tax, with short-term gains taxed at ordinary income rates if sold within a year of vesting.
- Strategies to minimise RSU tax burden include adjusting withholding, tax-loss harvesting, making charitable contributions, and timing sales.
- Integrating RSUs into a comprehensive financial plan involves assessing monetary goals, diversifying portfolios, and engaging in household discussions about financial values.
- Bright Advisers, founded in 2010 by Kevin Luu and Kathleen Chou, focuses on helping families navigate RSU complexities and make informed wealth decisions.
Introduction
Imagine feeling overwhelmed by the complexities of Restricted Stock Units (RSUs) while trying to secure your family’s financial future in California. It’s important to understand how RSUs fit into California’s tax framework, especially when you’re focused on securing your family’s financial future and managing those immediate tax burdens.
What if there were simple strategies that could help your family minimize RSU tax liabilities and weave these units into a solid financial plan? In this article, we’ll explore essential tactics that can empower your family to make informed decisions, helping you preserve your wealth and achieve your financial goals together.
Define Restricted Stock Units (RSUs) and Their Importance in California Taxation
Imagine the stress of receiving a large sum from your employer, only to realize the tax implications could impact your family’s financial future. Restricted Stock Units (RSUs) are often part of the compensation package, especially in the tech and startup world. When your RSUs vest, they’re taxed as regular income under California RSU tax, which can feel overwhelming, especially for families trying to plan ahead. This means that if you’re a high earner, you could face a hefty tax bill, which can be daunting when you’re trying to provide for your family.
It’s important for families to understand these implications so they can navigate their tax responsibilities with confidence. One way to ease the burden is by considering selling your RSUs right when they vest, which can help you avoid putting all your eggs in one basket. Working with a knowledgeable advisor can make a world of difference in optimizing your California RSU tax and securing your family’s financial future.
We understand that young parents like you face unique financial challenges, particularly when navigating the complexities of California RSU tax. Our tailored wealth management solutions are designed to help families like yours navigate these complexities with ease and confidence. Together with our consultants, you can develop a financial strategy that addresses your immediate tax needs while also planning for your children’s future.
We’re here to help you build a legacy of wealth that reflects your family’s values and aspirations. Since 2010, our mission at Bright Advisers has been to support families in making smart financial decisions that last for generations.
Explore Taxation Mechanisms for RSUs: Vesting, Selling, and State-Specific Considerations
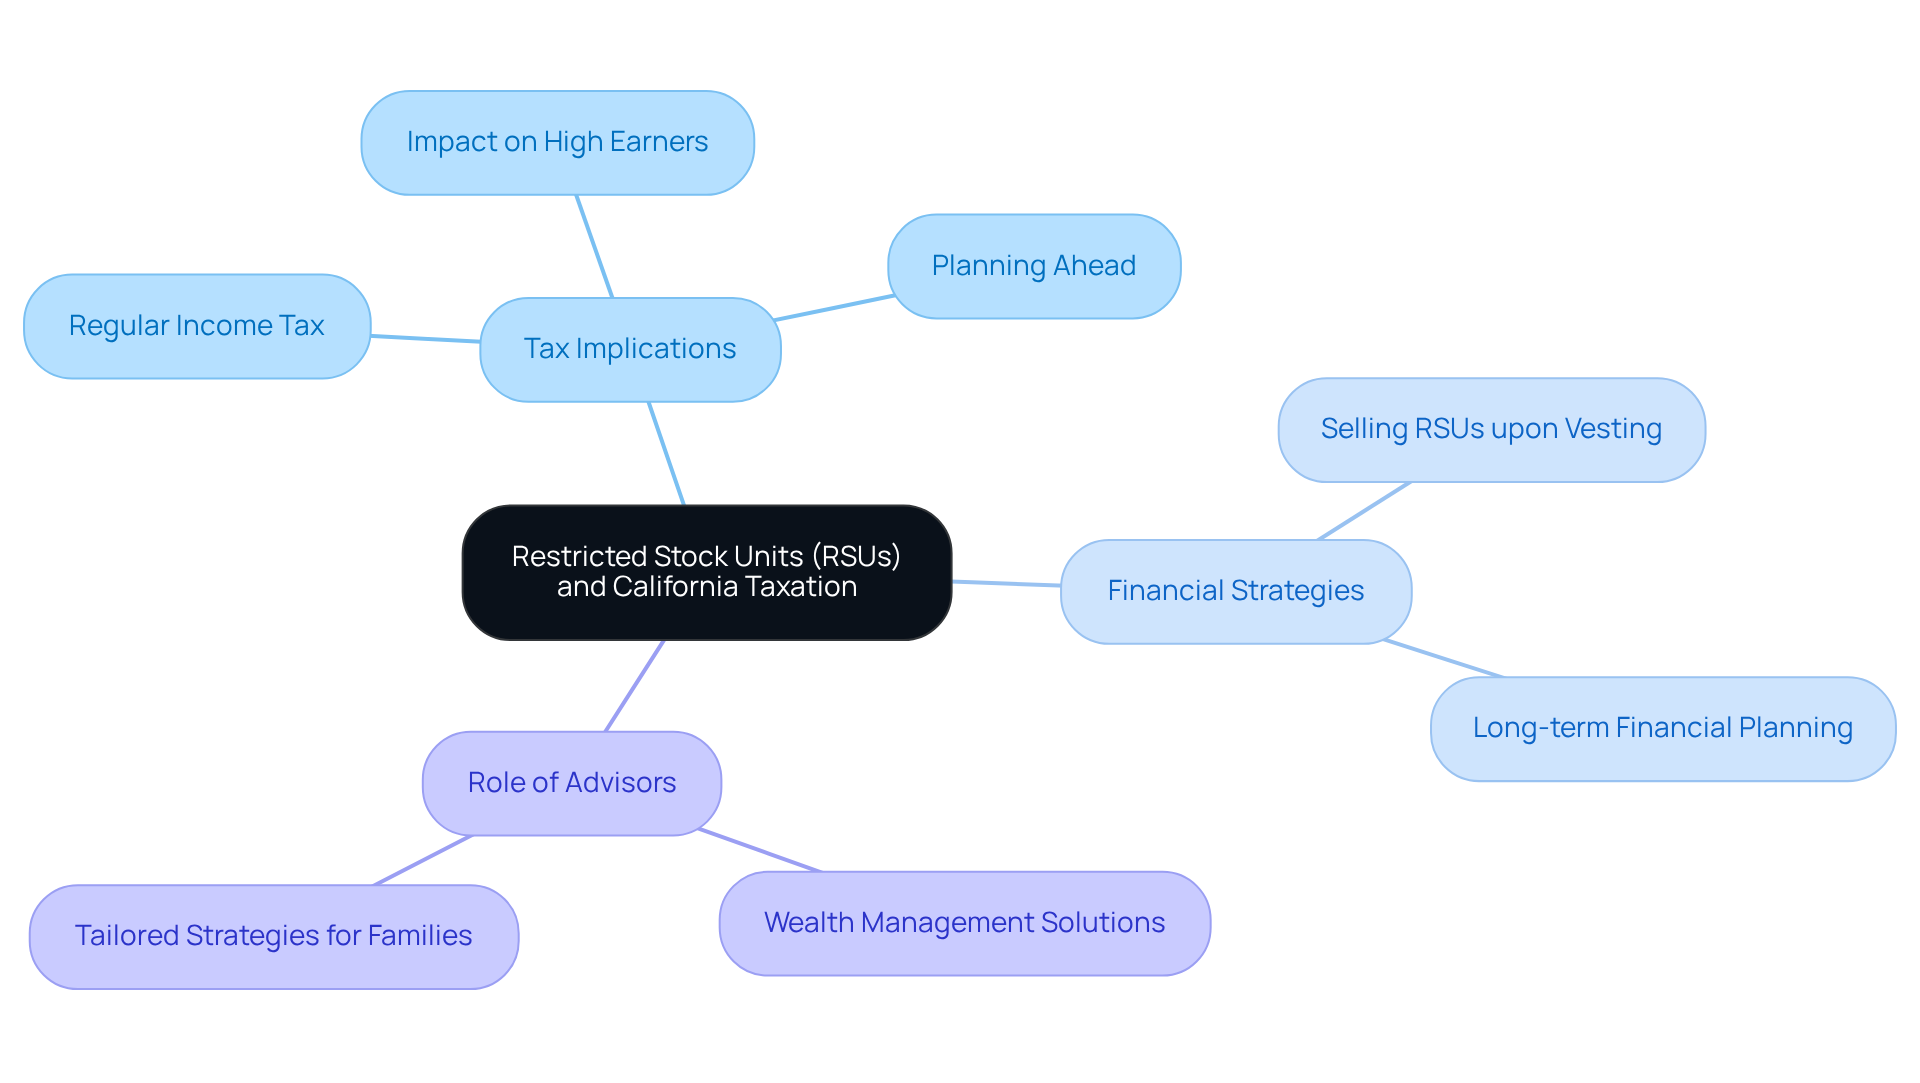
Imagine the surprise of receiving a hefty tax bill just when you thought you were making progress with your finances. In California, when your restricted stock units vest, the value of those shares is considered ordinary income, which means you’ll be subject to California RSU tax along with federal taxes. For instance, if you have 100 restricted stock units vesting at a value of $100 per share, that’s $100,000 in taxable income. This could push you into a higher tax bracket, which can be quite stressful for families trying to manage their budgets. You’ll also see a mandatory withholding of 10.23% on your RSU income, which can feel like a big hit when you’re trying to manage your family’s budget.
When you sell those shares, any profit you make is subject to capital gains tax. If you sell within a year of vesting, those gains are taxed as short-term capital gains at ordinary income rates. But if you hold onto them for over a year, you could benefit from lower long-term capital gains rates. It’s common for families to feel overwhelmed by the tax obligations that come with restricted stock units. Understanding these implications is crucial, as they can significantly influence your overall financial planning and the California RSU tax liability.
Consider this: one family decided to sell enough restricted stock units at vesting to cover their tax obligations while keeping others for potential growth. This strategy helped them balance immediate tax responsibilities with their long-term investment goals. If you don’t plan ahead, you might find yourself facing unexpected tax bills that could put a strain on your family’s finances. Consulting with a knowledgeable tax advisor can be a game-changer, helping you optimize your RSU strategies and avoid surprises down the road. Together, we can navigate this journey and ensure your family’s financial stability.
Implement Strategies to Minimize RSU Tax Burden for Families in California
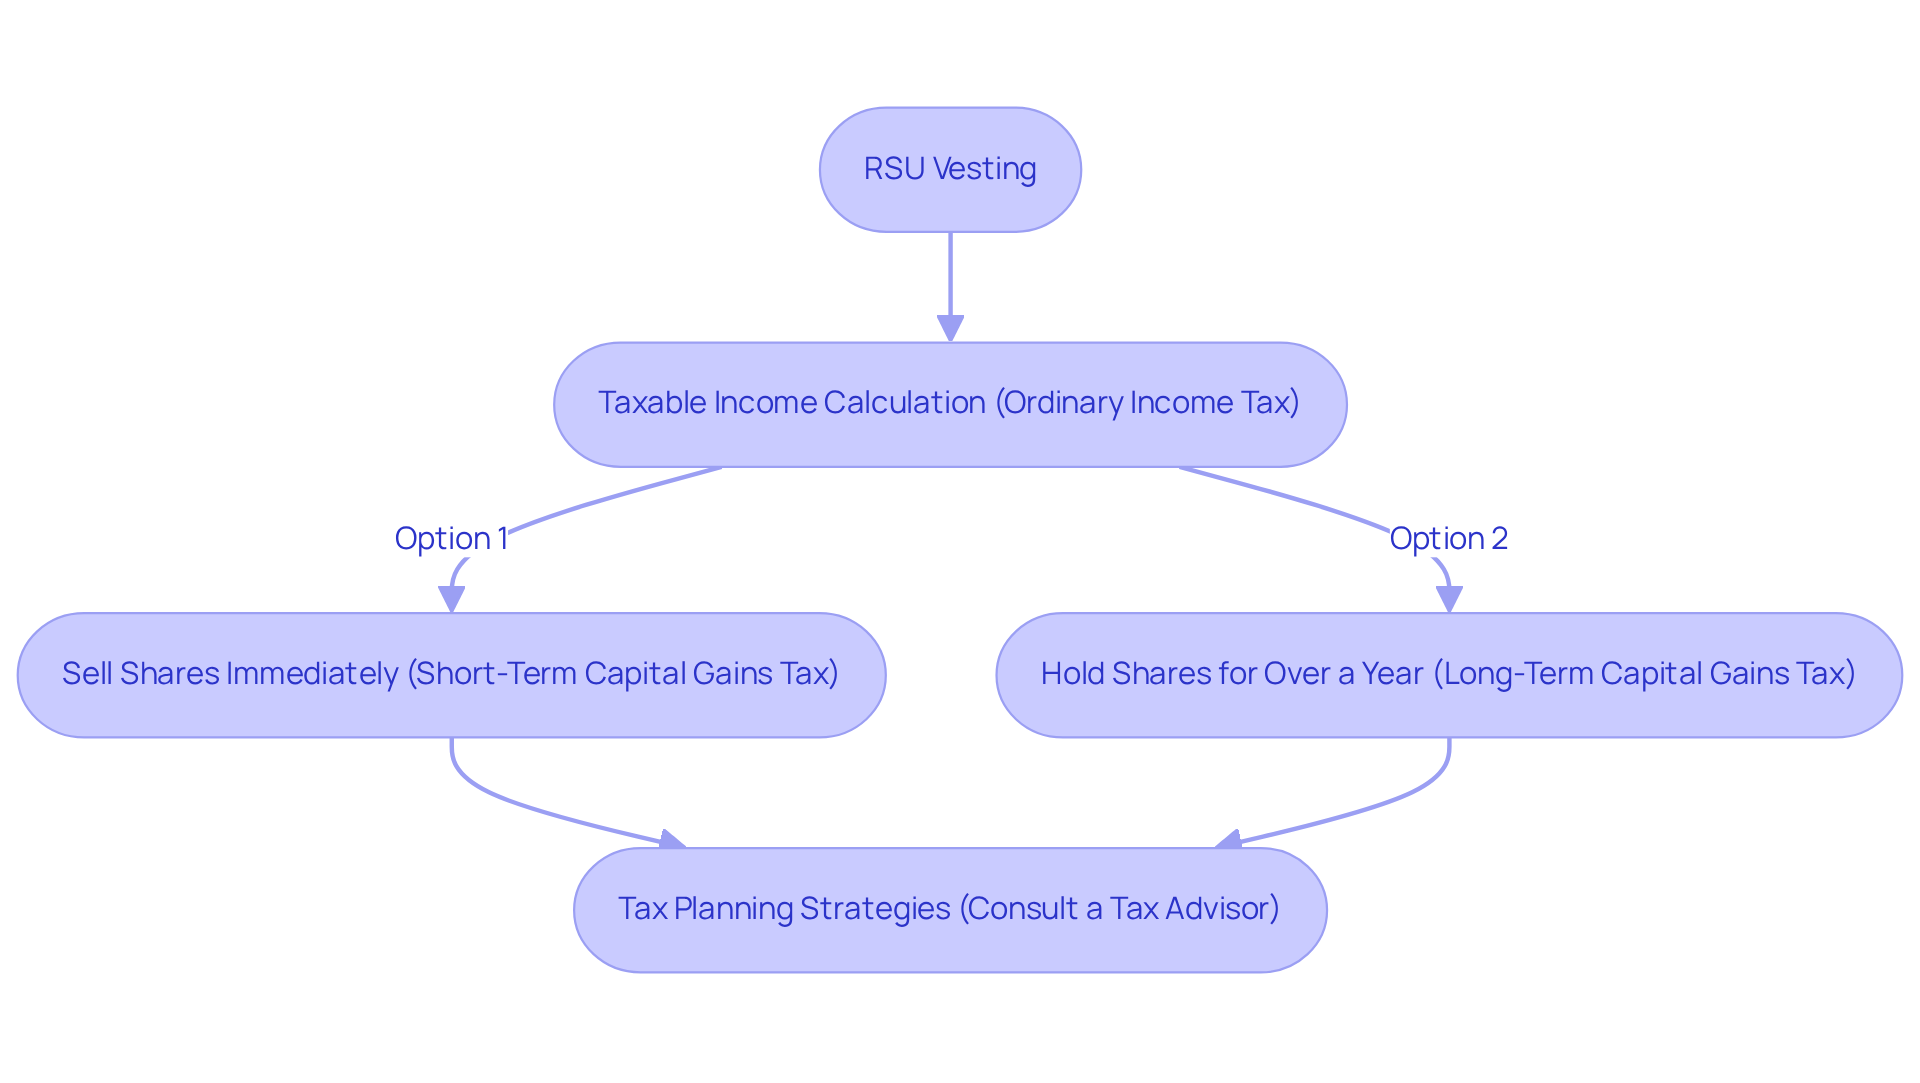
Imagine the relief of knowing you can minimize your tax burden while securing your family’s financial future. To effectively manage the tax implications of RSUs, families in California can implement several strategic approaches:
- Adjust Withholding: By adjusting your withholding, you can ease the worry of unexpected tax bills at year-end, giving you peace of mind. Take a moment to review your W-4 forms and ensure that your withholding amounts align with your expected tax liabilities.
- Tax-Loss Harvesting: Think of tax-loss harvesting as a way to balance your family’s financial scales, allowing you to offset gains from RSUs with losses from other investments. This strategy can effectively lower your taxable income, providing a valuable tax shield from California RSU tax.
- Charitable Contributions: When you donate appreciated RSUs to charity, you not only support a cause close to your heart but also enjoy tax benefits that can lighten your financial load. You can claim a charitable deduction while avoiding capital gains tax on the appreciated value.
- Timing Sales: By carefully planning when to sell your RSUs, you can make choices that align with your family’s financial goals and reduce your tax burden. Consider market conditions and your overall income for the year to optimize your transactions.
With these strategies, you can confidently navigate your tax obligations and focus on what truly matters-your family’s well-being. Together, we can ensure a more secure monetary future for you and your loved ones.
Integrate RSUs into Comprehensive Financial Planning for Families
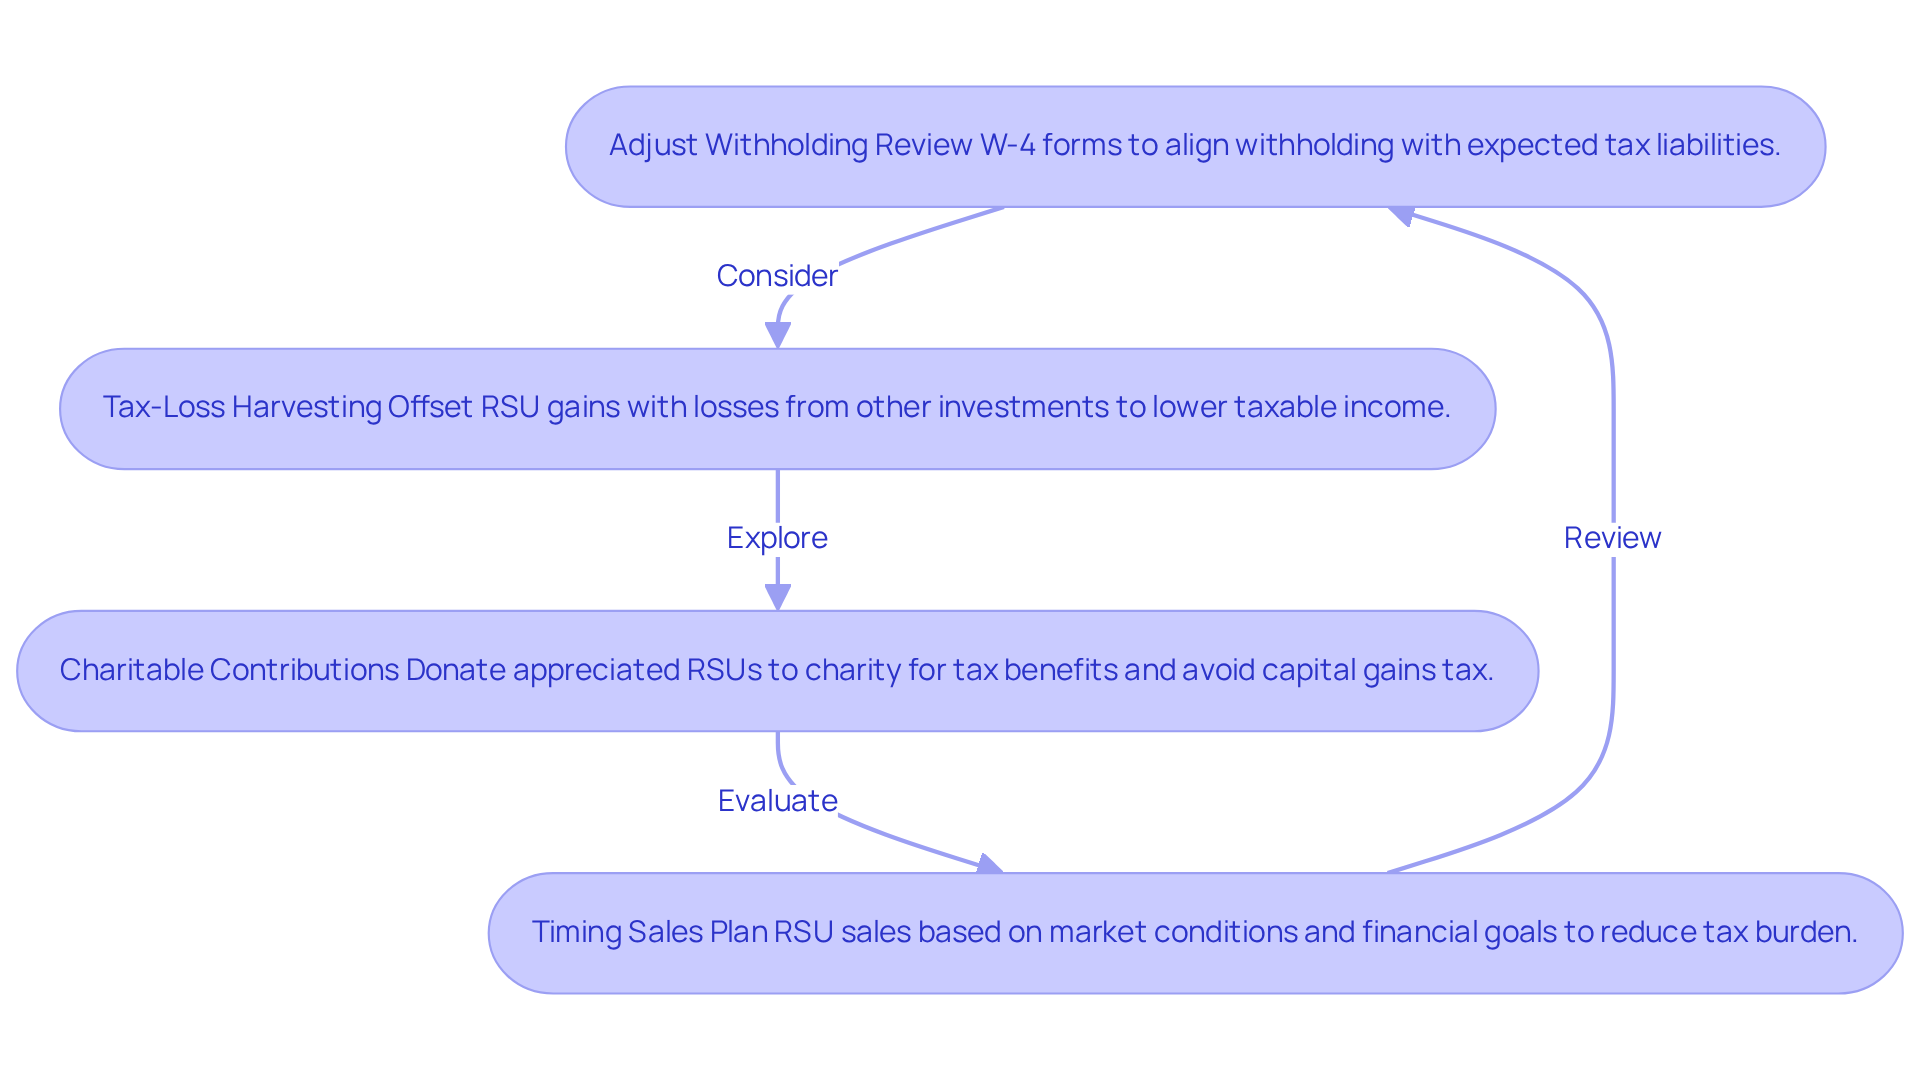
Imagine navigating the complexities of financial planning while ensuring your family’s future is secure and bright. Integrating RSUs into your family’s financial plan involves several essential steps:
- Assessing Monetary Goals: Families should evaluate both short-term and long-term monetary objectives, such as saving for children’s education, planning for retirement, and preparing for major purchases. This helps you align your RSU management with what truly matters for your family’s future. For example, Jay and Emma, a couple backed by Bright Advisers, successfully created a solid monetary strategy that involved optimizing their tax planning and developing a tailored retirement plan.
- Portfolio Diversification: Holding too much of your wealth in one stock can feel like walking a tightrope, where one misstep could lead to significant losses. A wise approach is to remember that keeping no more than 10-20% of your portfolio in your employer’s stock can help mitigate this risk. Households should consider diversifying their investments across various asset classes, such as bonds, real estate, and international stocks, to enhance stability and reduce exposure to market volatility. Jay and Emma balanced growth potential and risk management by selecting investment strategies focused on diversification, including factor investing and smart beta approaches.
- Tax Planning: Understanding how to manage california rsu tax effectively can make a world of difference when integrating RSUs into your family’s finances. Families can optimize their tax situation by strategically managing the timing of RSU sales and understanding the implications of california rsu tax at vesting. This includes utilizing tax-loss harvesting and maximizing contributions to tax-advantaged accounts to minimize overall tax liability. For example, retaining restricted stock units for more than a year can qualify for long-term capital gains rates, which can save substantial taxes for high-income individuals. Bright Advisers helped Jay and Emma navigate these complexities, allowing them to fund their children’s education while planning for retirement through integrated tax planning strategies.
- Household Gatherings: Participating in open conversations about monetary values and objectives within the household can promote a collective comprehension of how to handle RSUs and other assets. These gatherings can also be wonderful chances to teach your kids about money management and the importance of planning for the future together.
By following these steps, households can create a unified monetary plan that not only supports their current goals but also ensures their children’s economic futures. With the right guidance, you can transform your financial landscape and create a legacy of security for your children. Bright Advisers is dedicated to helping families like Jay and Emma make wise wealth decisions and preserve wealth across generations.
Conclusion
Imagine feeling overwhelmed by the complexities of Restricted Stock Units (RSUs) and their tax implications – you’re not alone. Navigating these challenges is crucial for families in California. When families understand how RSUs fit into California’s tax system, they can make choices that truly affect their financial health. By grasping the nuances of RSU taxation, families can prepare for the financial responsibilities that come with these valuable assets.
Let’s explore some practical strategies that can help families ease the burden of RSU taxes:
- Adjusting withholding
- Engaging in tax-loss harvesting
- Making charitable contributions
- Timing sales
These approaches provide families with the tools they need to manage their tax obligations effectively. Additionally, integrating RSUs into a comprehensive financial plan ensures that families can align their immediate financial needs with long-term goals, fostering a secure future for their children.
Managing RSUs isn’t just about crunching numbers; it’s about building a future filled with financial stability and purpose for your family. By taking proactive steps and seeking guidance from trusted advisors like Bright Advisers, families can navigate these challenges with confidence. Embracing these strategies not only enhances financial literacy but also empowers families to make wise wealth decisions that will benefit generations to come. With the right support, families can turn these challenges into opportunities for lasting financial security.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of compensation often provided by employers, particularly in the tech and startup sectors. They represent a promise to deliver shares of stock to employees once certain conditions, such as vesting, are met.
How are RSUs taxed in California?
In California, when RSUs vest, they are taxed as regular income. This can lead to significant tax implications, especially for high earners, which may impact their family’s financial future.
Why is it important for families to understand RSU taxation?
Understanding RSU taxation is crucial for families to navigate their tax responsibilities effectively and to plan their finances with confidence, especially when facing potentially hefty tax bills.
What strategy can help manage the tax burden from RSUs?
One strategy to manage the tax burden is to consider selling RSUs immediately upon vesting. This approach can help mitigate risks associated with holding onto the stock.
How can a financial advisor assist with RSU tax planning?
A knowledgeable financial advisor can help optimize California RSU tax strategies and provide tailored wealth management solutions to address immediate tax needs while planning for the family’s future.
What is the mission of Bright Advisers?
Bright Advisers aims to support families in making wise financial decisions that preserve wealth across generations, reflecting their values and aspirations.
When was Bright Advisers founded?
Bright Advisers was founded in 2010 by Kevin Luu and Kathleen Chou.
List of Sources
- Define Restricted Stock Units (RSUs) and Their Importance in California Taxation
- How Restricted Stock Units (RSUs) are Taxed in California – Summitry (https://summitry.com/blog/rsu-taxes-in-california)
- How Are RSUs Taxed in California? – Fischer Investment Strategies (https://fischerinvestmentstrategies.com/how-are-rsus-taxed-in-california)
- Restricted Stock Units – Jane Financial (https://janefinancial.com/restricted-stock-units)
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- RSU Tax in California: What Married Founders Need to Know in 2026 | Neptune Blog (https://meetneptune.com/blog/rsu-tax-in-california)
- Explore Taxation Mechanisms for RSUs: Vesting, Selling, and State-Specific Considerations
- How Restricted Stock Units (RSUs) are Taxed in California – Summitry (https://summitry.com/blog/rsu-taxes-in-california)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- RSU tax in California: What you need to know (https://wise.com/gb/blog/rsu-california-tax)
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- RSU Tax in California: What Married Founders Need to Know in 2026 | Neptune Blog (https://meetneptune.com/blog/rsu-tax-in-california)
- Implement Strategies to Minimize RSU Tax Burden for Families in California
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- RSU Tax Planning: Tips and Strategies | Citrine Capital (https://citrinecapitaladvisors.com/blog/rsu-tax-planning-guide)
- RSU Tax in California: What Married Founders Need to Know in 2026 | Neptune Blog (https://meetneptune.com/blog/rsu-tax-in-california)
- Integrate RSUs into Comprehensive Financial Planning for Families
- RSU Concentration Explained: Risks, Scenarios, and Smarter Diversification Strategies (https://candor.co/articles/equity-compensation-basics/rsu-concentration-explained-risks-scenarios-and-smarter-diversification-strategies)
- Restricted Stock Units and Building a Diversified Portfolio (https://brightonjones.com/blog/restricted-stock-units)
- How To Diversify Your RSUs In A Tax-Efficient Way? – True Root Financial (https://truerootfinancial.com/how-to-diversify-your-rsus-in-a-tax-efficient-way)
- RSU Tax Planning: 5 Proven Strategies For 2026 (https://tdwealth.net/rsu-tax-planning-strategies-tech-executives)
- Eight Great Investing Quotes (https://southstatebank.com/retirement-plan-services/retirement-insights/eight-great-investing-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading