

Key Highlights
- Community property laws in California dictate that assets acquired during marriage are jointly owned by both spouses, impacting estate planning and asset distribution.
- Understanding community property can help families manage financial outcomes during divorce, with costs ranging from $12,000 to $26,000 in California.
- The community property step up allows surviving spouses to benefit from tax advantages, potentially saving significant amounts on capital gains taxes.
- Effective financial planning involves inventorying assets, consulting a fiduciary advisor like Bright Advisers, and creating wills or trusts to protect shared assets.
- Families should regularly review tax implications of shared assets and educate children about financial management to prepare them for future responsibilities.
- Challenges in community property management include distinguishing between shared and distinct assets, navigating divorce proceedings, and understanding state-specific laws.
Introduction
Imagine feeling overwhelmed by the complexities of community property laws, especially when your family’s future is at stake. In California, where shared assets play a crucial role in financial planning, understanding the benefits of community property step up is essential for families looking to secure their financial future and preserve wealth across generations.
Many families feel overwhelmed by the thought of dividing assets, especially during tough times like divorce or loss. But with the right guidance, families can find clarity and confidence in their financial choices.
This article delves into the significance of community property, offering strategies and insights to help families manage their wealth effectively while addressing the challenges that may arise.
Define Community Property: Key Concepts and Importance
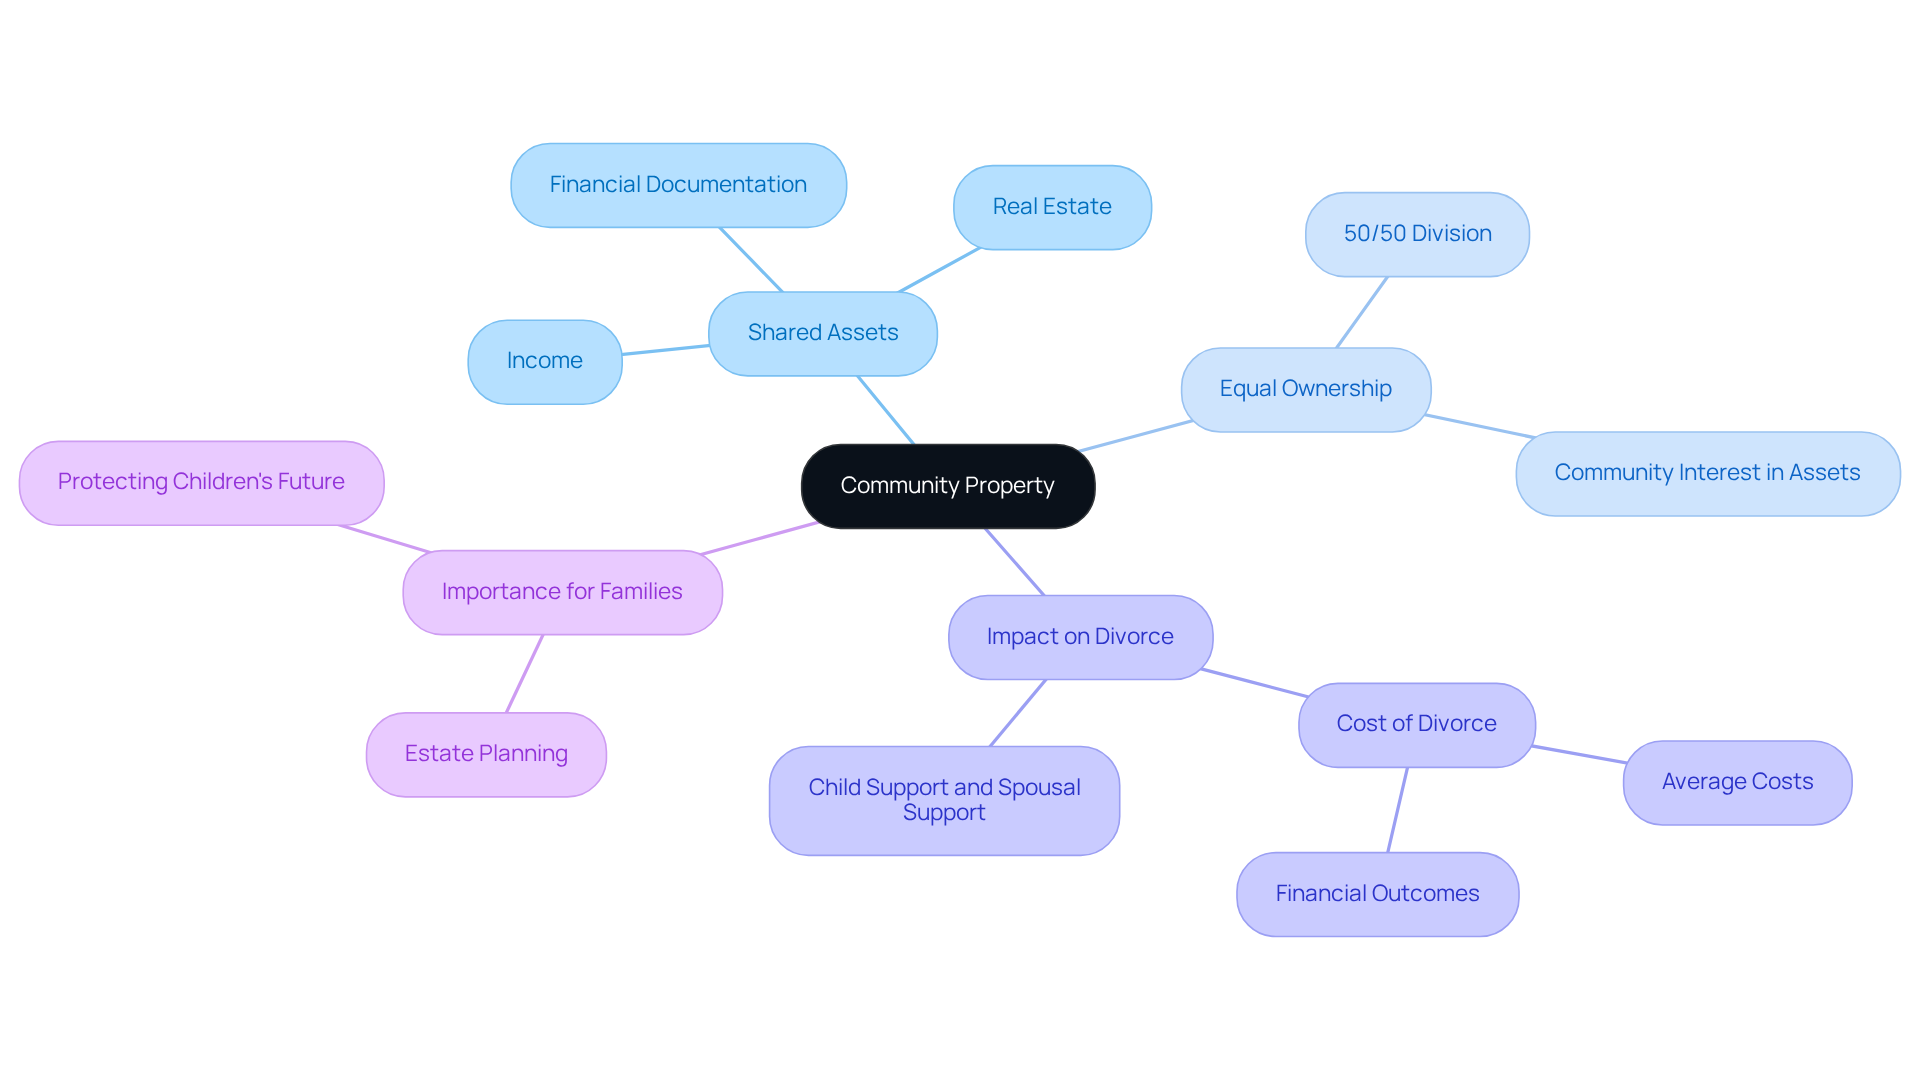
Imagine navigating the complexities of shared assets while trying to secure your family’s future. In California and several other U.S. states, the concept of community property step up establishes that any resources acquired during a marriage are jointly owned by both spouses. This includes income, real estate, and various other assets. Understanding shared assets is crucial for families, especially those with young children. When both partners recognize their equal ownership of shared assets, it helps families manage estate planning, tax consequences, and asset distribution during divorce or death more effectively.
For instance, the community property step up in California requires a 50/50 division of shared assets, which can significantly impact financial outcomes in divorce cases. Did you know that divorce can cost families between $12,000 and $26,000 in California? That’s a significant amount that could impact your children’s future. By grasping these concepts, you can make informed choices that truly benefit your family’s future, ensuring that your children’s needs are prioritized.
Case studies show how community asset laws work in real-life situations, like the division of a household or retirement accounts. These examples highlight the importance of clear financial documentation and legal advice. By understanding these concepts, you can take proactive steps to protect your family’s financial well-being and ensure a stable future for your children.
Explore Implications of Community Property Laws for Families
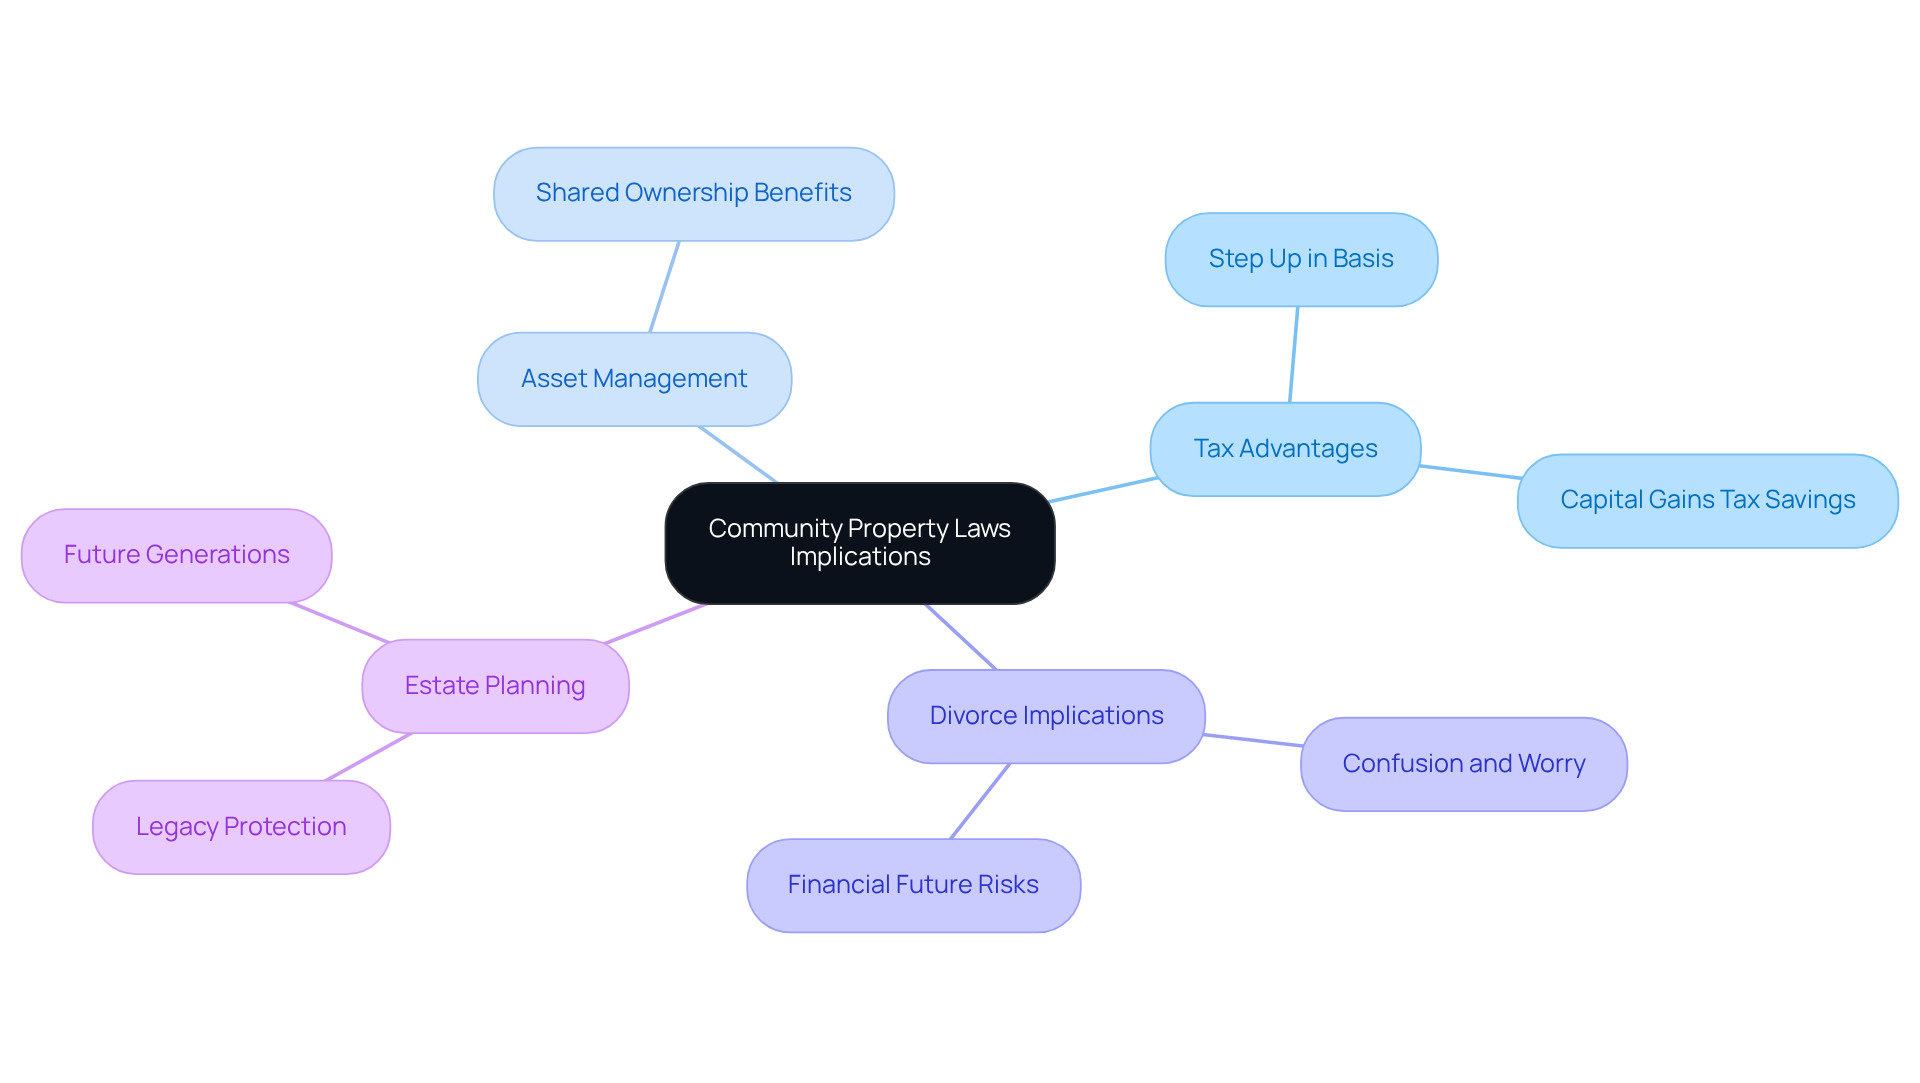
Imagine facing the loss of a loved one while also worrying about your family’s financial future. Community asset laws in California offer substantial tax advantages for families, especially regarding asset management and wealth preservation. When one partner passes away, the surviving partner receives a full community property step up in basis for shared assets. This change in value can help families save on capital gains taxes when they sell the property. For example, if a couple purchased their home for $400,000 and it appreciates to $1,200,000 at the time of death, the community property step up allows the surviving spouse’s tax basis to increase to $1,200,000, which permits a sale without incurring capital gains tax. This tax benefit can be a lifeline for families wanting to keep their wealth intact for future generations.
However, when families face divorce, the division of assets can lead to confusion and worry about their financial future. Families such as Allison and Brian might be losing out on monetary opportunities because of insufficient tax planning, making it essential to comprehend the effects of shared ownership laws. Understanding these laws is essential; otherwise, families might miss out on opportunities that could protect their financial well-being. For example, a case study illustrates how a couple’s shared assets status enabled them to save significant sums in taxes compared to individual assets, highlighting the significance of effective estate planning.
By utilizing the advantages of shared ownership regulations, families can ensure that their monetary legacies are maintained, ultimately safeguarding a brighter future for their offspring. By understanding and leveraging these laws, you can ensure your family’s financial legacy is protected for generations to come.
Implement Community Property Strategies in Family Financial Planning
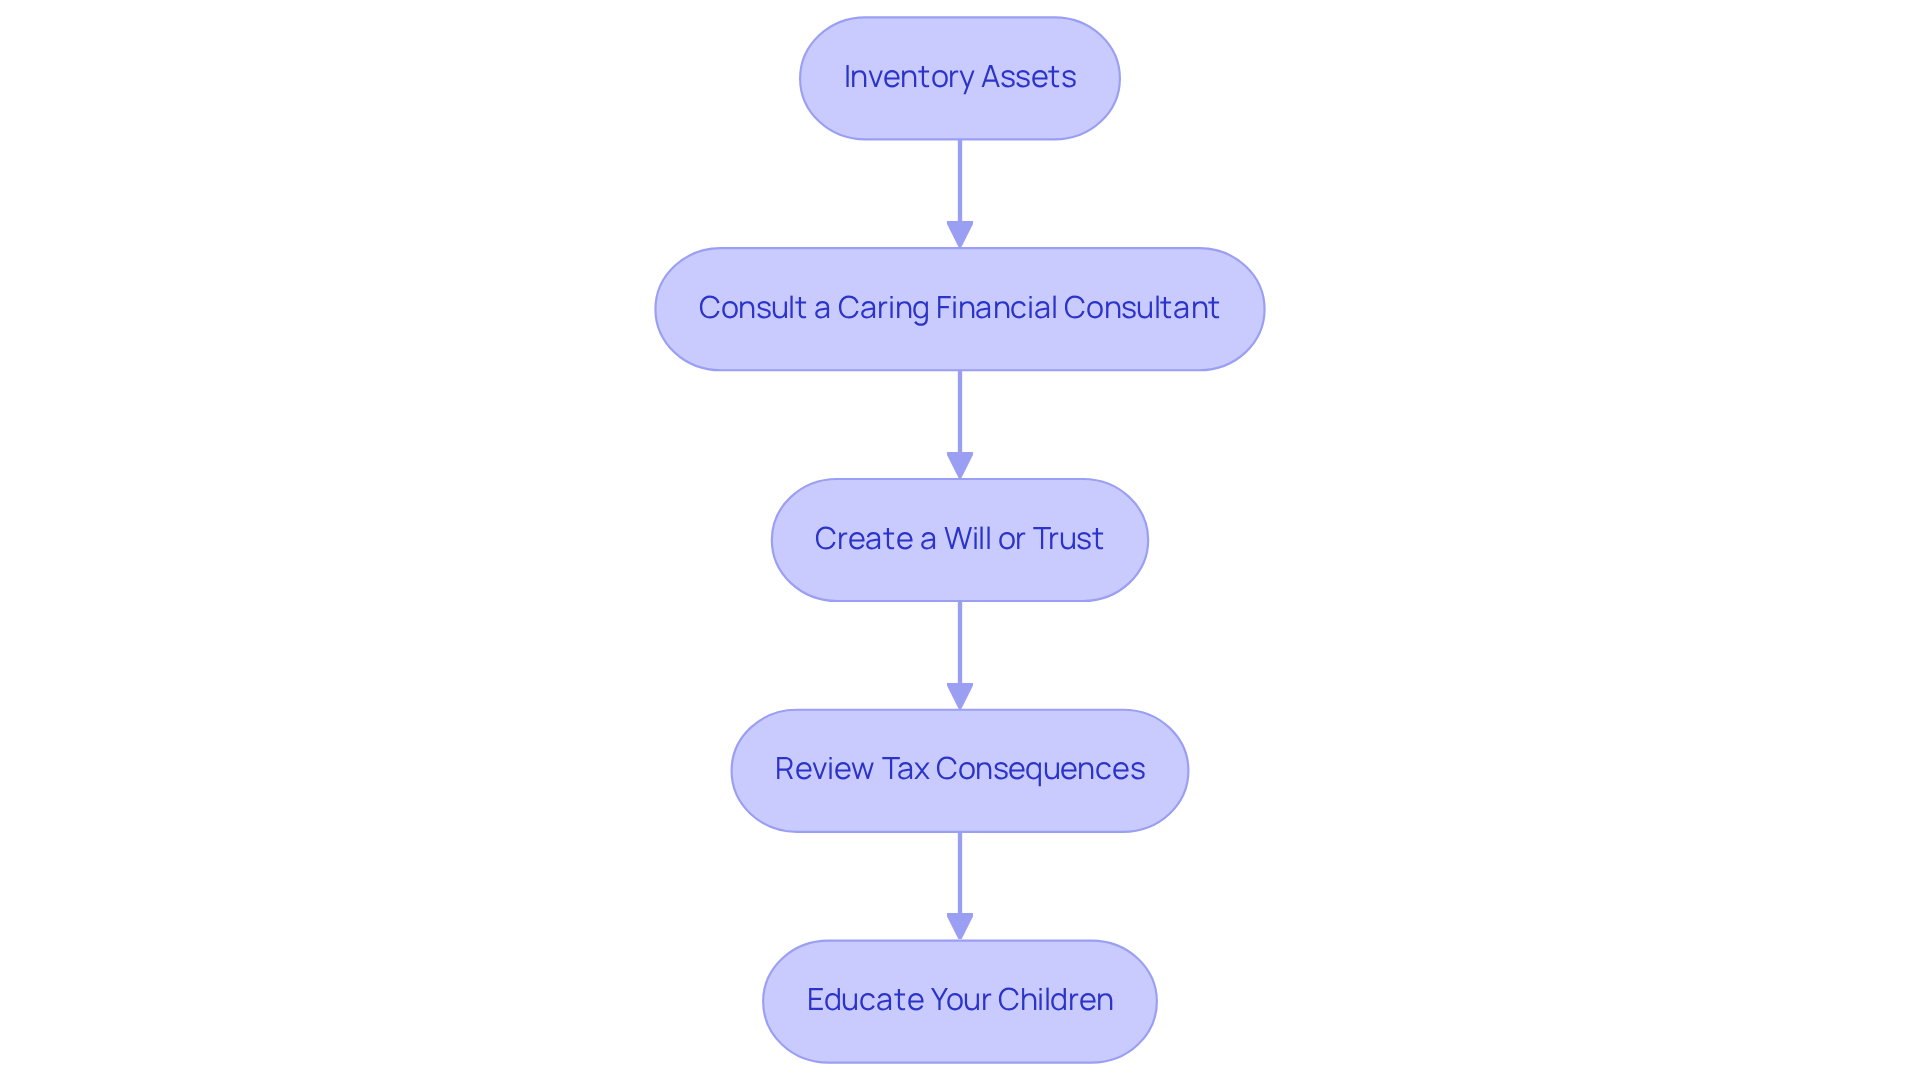
Navigating financial planning can feel daunting, especially when balancing family needs and future goals. To help you along this journey, here are some gentle steps to consider for effective household monetary planning:
- Inventory Assets: Start by cataloging all assets acquired during your marriage, including income, real estate, and investments. This inventory helps clarify what makes up your shared assets.
- Consult a Caring Financial Consultant: Consider reaching out to a caring fiduciary advisor, like Bright Advisers, who understands your unique family values and can help you create a personalized financial plan tailored to your household’s needs.
- Create a Will or Trust: Establishing a will or trust ensures that your shared assets are allocated according to your wishes, especially in the case of one spouse’s passing. This step provides peace of mind for you and your loved ones.
- Review Tax Consequences: It’s important to regularly evaluate the tax implications of your shared assets, particularly regarding capital gains and estate taxes. Bright Advisers can assist you in navigating these complexities effectively, enhancing your household’s economic strategy.
- Educate Your Children: Incorporate money management lessons into family discussions. Teaching your children about the significance of community property step up and wealth management prepares them for future financial responsibilities.
Interacting with a fiduciary advisor can also lessen anxiety regarding money. In fact, 49% of clients report feeling less worried about their finances through their advisor relationship.
With the right support, you can build a secure financial future for your family, ensuring peace of mind for years to come.
Address Challenges and Exceptions in Community Property Management
Navigating community asset laws can feel overwhelming for families, especially when unexpected challenges arise. Families often face various hurdles that can complicate their financial management.
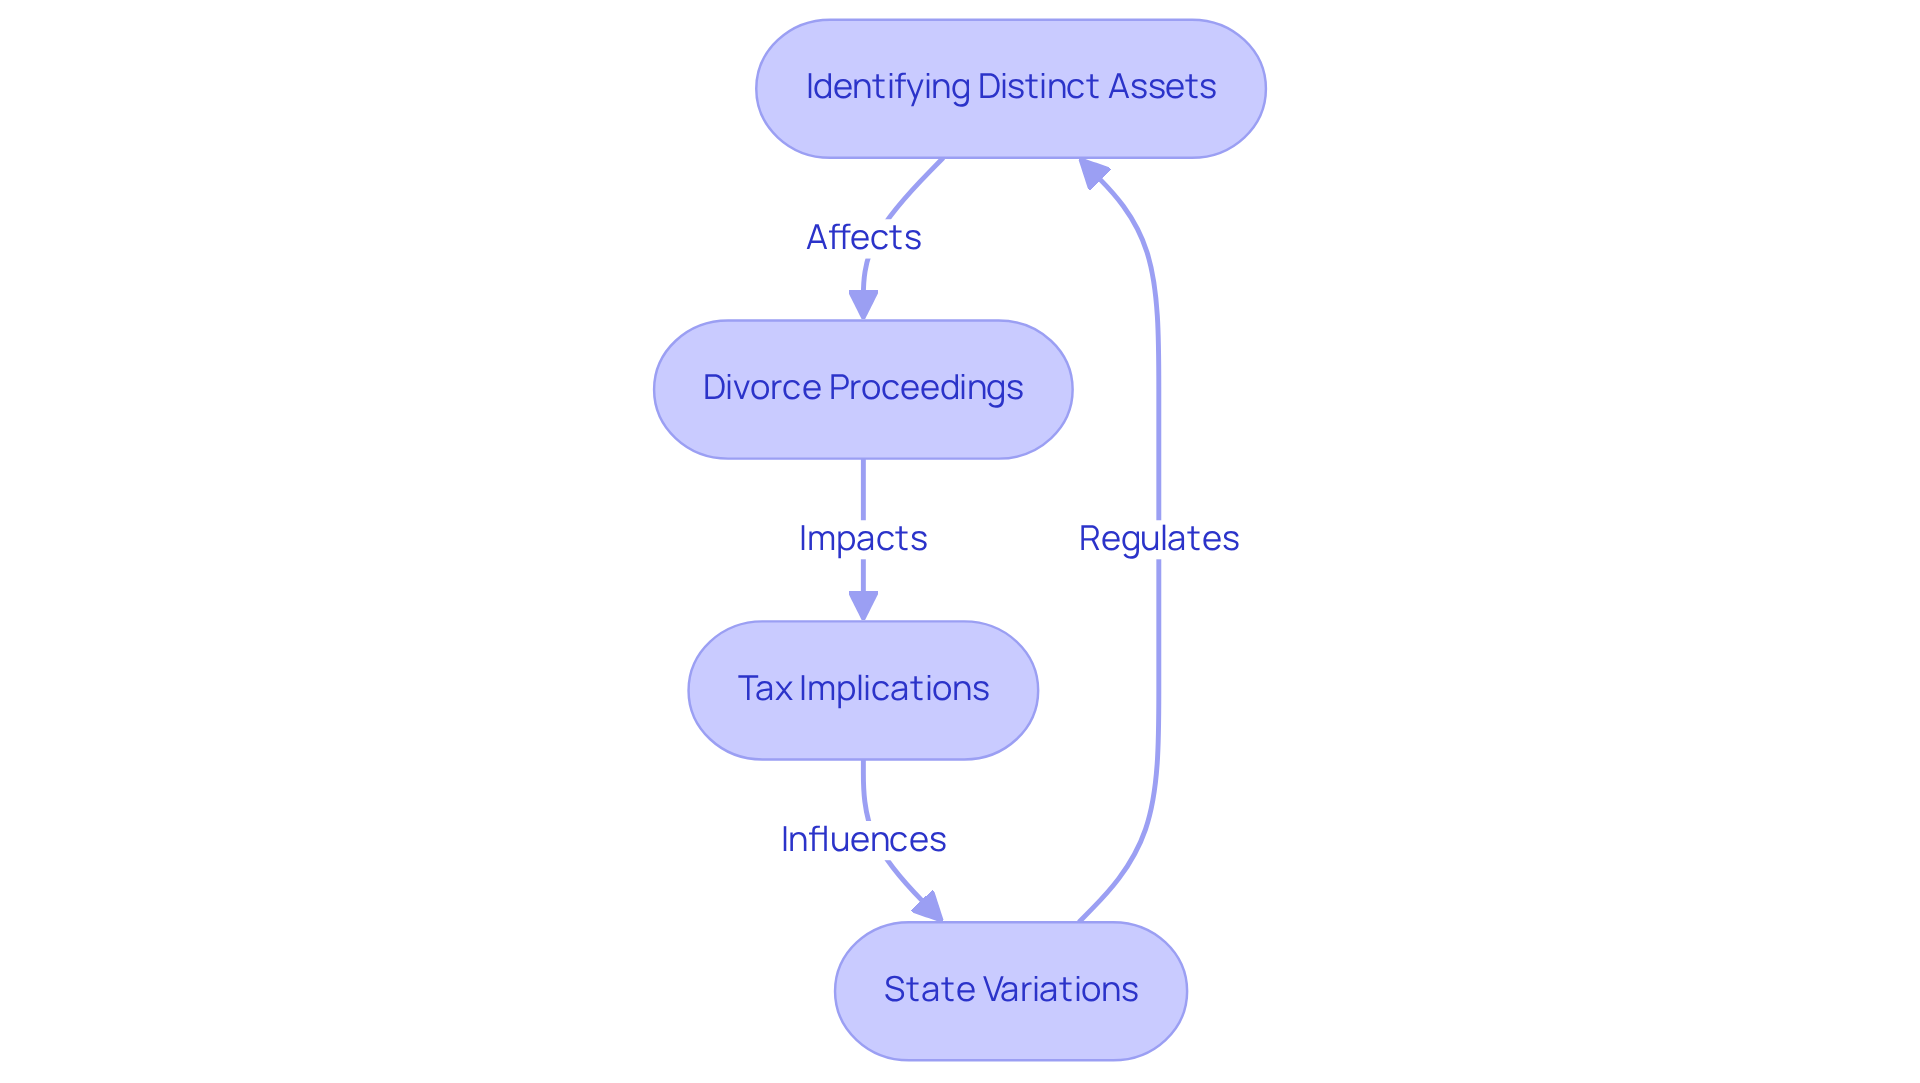
- Identifying Distinct Assets: Imagine the stress of distinguishing between what belongs to you and what’s shared. Resources obtained before marriage or received as gifts or inheritances are typically categorized as distinct assets, exempt from shared asset regulations. Keeping detailed records can help clarify these distinctions and prevent conflicts.
- Divorce Proceedings: Picture the emotional turmoil of dividing your family’s hard-earned assets during a divorce. During this time, shared assets must be divided equally, which can lead to significant conflicts. Open communication and the guidance of legal professionals can help ease these disputes, ensuring a smoother transition for everyone involved.
- Tax Implications: It’s important to grasp how communal assets can affect your taxes, because missteps here can lead to surprises down the road. Consulting with tax professionals can assist households in navigating these complexities effectively, ensuring you’re prepared for any financial implications.
- State Variations: Community property laws vary considerably among states, making it essential for families to understand the specific regulations that apply to their situation. This knowledge is vital for effective asset management and planning, particularly in the context of community property step up.
By proactively addressing these challenges and exceptions, families can create a robust financial strategy that protects their assets. Taking these steps today can pave the way for a secure tomorrow for your family.
Conclusion
Imagine navigating the complexities of financial planning without knowing how community property laws impact your family. Understanding these laws is crucial for families who want to secure their financial future. When you recognize that assets acquired during marriage are jointly owned, it becomes easier to manage estate planning, tax implications, and asset distribution. Many families struggle to grasp how community property laws affect their financial decisions. But when you understand these laws, you can confidently secure your children’s future.
Throughout this article, we’ve shared key insights about community property laws, especially in California. The community property step-up provides significant tax advantages, allowing surviving spouses to benefit from increased asset value without incurring capital gains taxes. Additionally, practical strategies for managing shared assets include:
- Creating a will or trust
- Consulting with a fiduciary advisor like Bright Advisers
These are vital steps in effective financial planning.
By embracing these insights, you can create a lasting legacy that nurtures your family’s future. Engaging with knowledgeable advisors and educating your children about financial management will further enhance your family’s ability to navigate these complexities, fostering a secure and intentional financial future.
Frequently Asked Questions
What is community property?
Community property refers to the legal concept that any resources acquired during a marriage are jointly owned by both spouses. This includes income, real estate, and various other assets.
Why is understanding community property important for families?
Understanding community property is crucial for families, especially those with young children, as it helps manage estate planning, tax consequences, and asset distribution during divorce or death more effectively.
How does community property affect asset division in divorce cases in California?
In California, community property requires a 50/50 division of shared assets, which can significantly impact financial outcomes in divorce cases.
What are the potential costs of divorce in California?
Divorce can cost families between $12,000 and $26,000 in California, which can significantly affect children’s futures.
How can families protect their financial well-being regarding community property?
Families can protect their financial well-being by understanding community property laws, maintaining clear financial documentation, and seeking legal advice to navigate asset division effectively.
Are there real-life examples of community property laws in action?
Yes, case studies illustrate how community asset laws work in real-life situations, such as the division of a household or retirement accounts, emphasizing the importance of understanding these concepts.
List of Sources
- Define Community Property: Key Concepts and Importance
- California Community Property Law Explained | Wilkinson & Finkbeiner (https://wf-lawyers.com/orange-county/california-community-property-law-explained)
- How California’s Community Property Laws Impact Divorce Settlements (https://marmolejolaw.com/blog/2025/october/how-california-s-community-property-laws-impact-)
- Is California a Community Property State? 50/50 Splits. (https://affamlaw.com/blog/california-community-property)
- California Community Property Laws – FindLaw (https://findlaw.com/state/california-law/california-marital-property-laws.html)
- Explaining California’s Community Property System (https://mysocallawyer.com/blog/2024/september/explaining-california-s-community-property-syste)
- Explore Implications of Community Property Laws for Families
- Avoid Capital Gains Tax with Smart Estate Planning (https://shrr.com/news_events/why-tax-and-estate-planning-matters-the-step-up-in-basis-explained)
- Community Property and California Estate Planning: What CA Couples Need to Know (https://clarkallison.com/blog/community-property-and-california-estate-planning-what-ca-couples-need-to-know)
- Community Property vs. Separate Property: How It Affects Your California Estate Plan (https://livingtrust-attorneys.com/blog/community-property-separate-property-california-estate-planning-2026)
- How Community Property Affects Estate and Tax Planning (https://sowardslawfirm.com/blog/how-community-property-affects-estate-and-tax-planning)
- Estate Planning for California Community Property (https://modernwealthlaw.com/estate-planning-california-community-property)
- Implement Community Property Strategies in Family Financial Planning
- Study: Americans Working With CFP® Professionals Enjoy Greater Financial Well-Being (https://cfp.net/news/2025/02/news-releases/americans-working-with-cfp-professionals-enjoy-greater-financial-well-being)
- Safeguard Your Assets Before Marriage: Legal and Financial Strategies to Protect Yourself (https://criadv.com/insight/safeguard-assets-divorce)
- Financial Advisors Report Clients Have Greater Family Engagement and Fresh Conversations Around Generational Wealth Transfer (https://prnewswire.com/news-releases/financial-advisors-report-clients-have-greater-family-engagement-and-fresh-conversations-around-generational-wealth-transfer-302093742.html)
- How putting families first can help advisors retain next-gen clients (https://investmentnews.com/practice-management/how-putting-families-first-can-help-advisors-retain-next-gen-clients/259204)
- Address Challenges and Exceptions in Community Property Management
- Divorce Statistics in the U.S. and Orange County, California (https://sullivan-law.com/divorce-statistics-in-the-us-and-orange-county)
- Divorce Rate in California | Hopper Hopper & Strebe (https://westcoastdivorce.com/blog/divorce-rate-in-california)
- California Divorce Statistics | Fernandez Law Group (https://cfli.com/california-divorce-statistics)
- California Divorce Rate [2026 Updated] – Latest Statistics (https://ocfamilylawanddivorce.com/blog/california-divorce-rate)
- California Divorce Rate 2026 – Latest Statistics (https://campuzanolaw.com/blog/california-divorce-rate)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading