

Key Highlights
- Capital gains are profits made from selling shares for more than their purchase price, with tax rates varying based on income and holding period.
- Cost basis is the original value of shares, including commissions, crucial for calculating capital gains accurately.
- Holding period affects tax rates; shares held over a year are taxed at lower long-term capital gains rates, while those held less than a year are taxed as ordinary income.
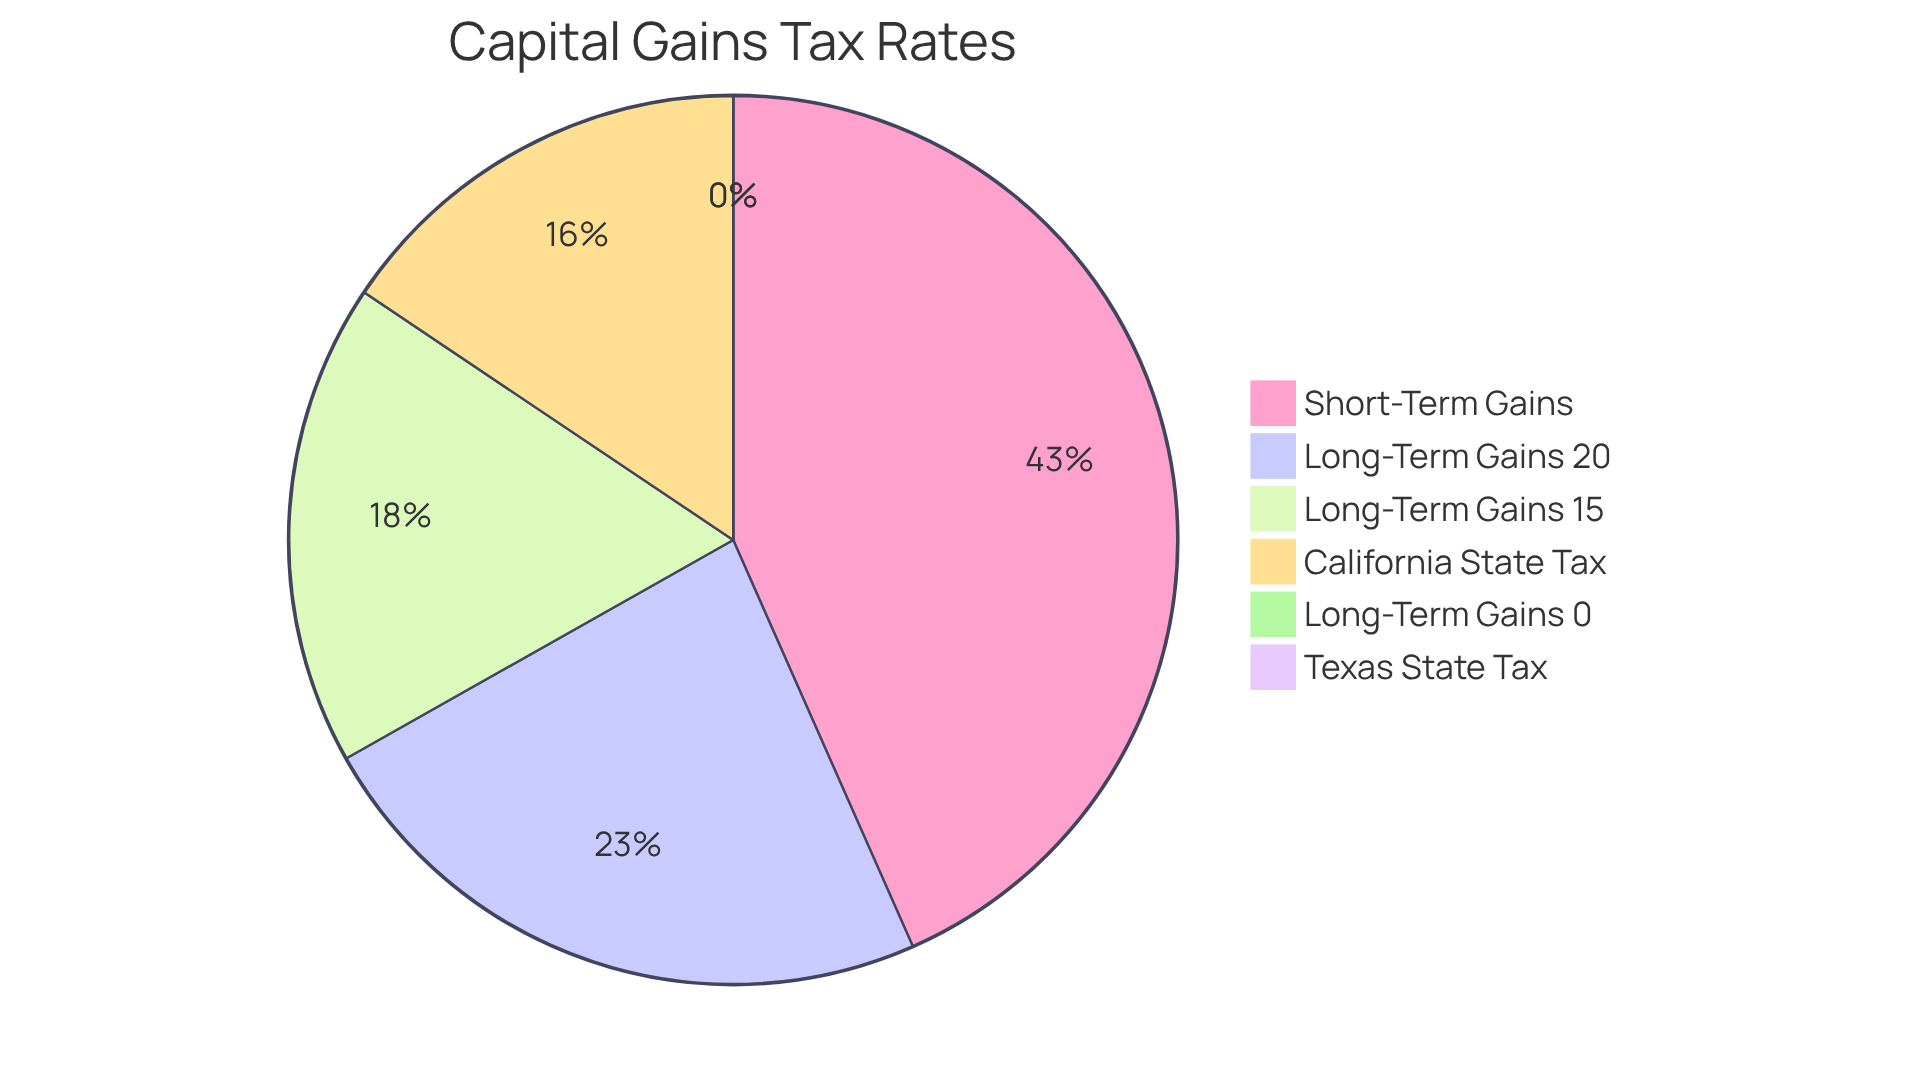
- Short-term capital gains can be taxed up to 37%, while long-term gains are taxed at 0%, 15%, or 20% based on income levels.
- State taxes on capital gains vary significantly, with California imposing a 13.3% rate and states like Texas having no income tax.
- Families can use strategies like tax-loss harvesting, timing sales, gifting shares, and utilising retirement accounts to minimise tax liabilities.
- Effective planning and timing for stock sales can enhance financial outcomes, aligning sales with personal financial objectives and market conditions.
- Bright Advisers offers personalised financial planning services to help families navigate stock sales and tax implications.
Introduction
Many families feel overwhelmed by the thought of managing stock sales and the associated tax implications. It’s important for families to grasp key ideas like capital gains and cost basis to make informed choices about their investments. With the right strategies, families can ease their tax burdens and improve their financial health. Imagine if families could plan their stock sales in a way that maximizes benefits while easing tax worries. In this article, we’ll explore helpful strategies for navigating stock sales and their tax implications together.
Define Stock Sale: Key Concepts for Families
Navigating the world of share sales can feel overwhelming for many families. Understanding key concepts like capital gains, cost basis, and holding period is essential for households looking to secure their financial futures.
-
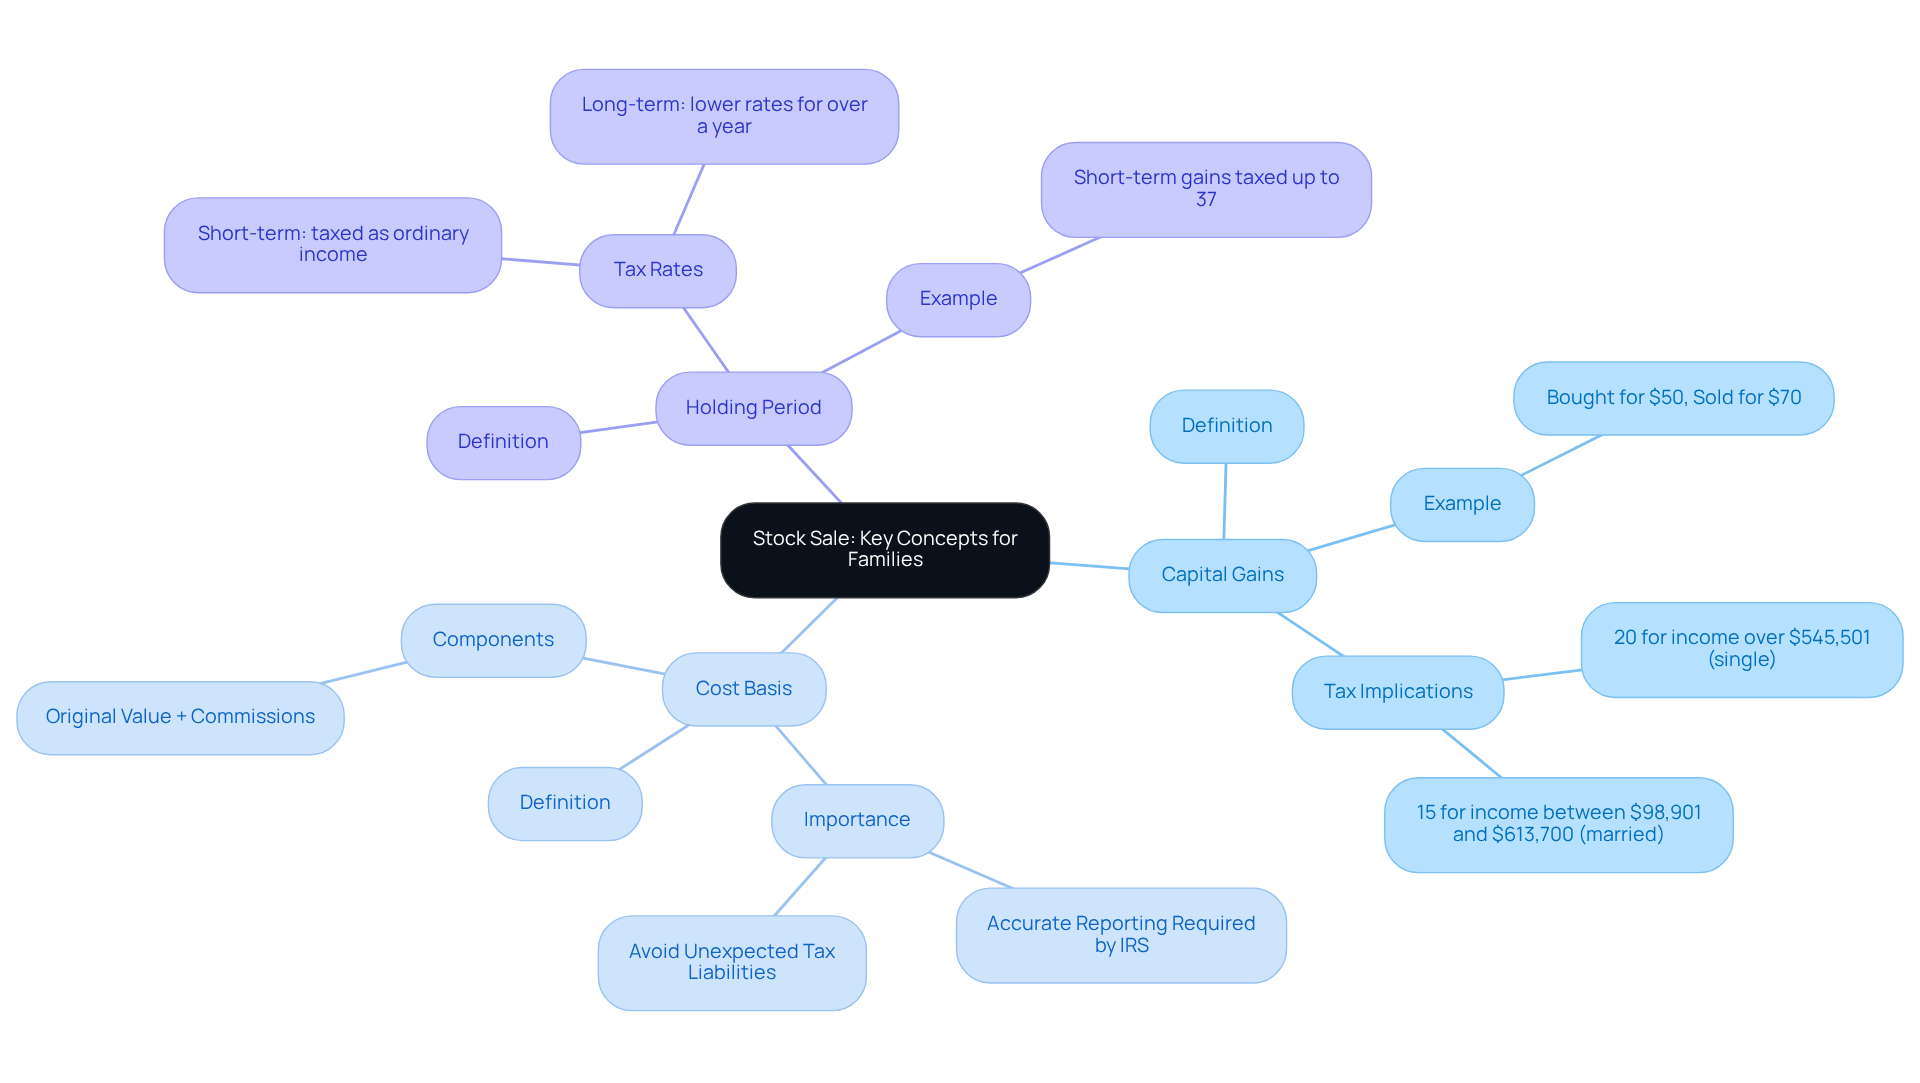
Capital Gains: This is the profit you make when you sell a share for more than you paid for it. For example, if you bought shares for $50 and sold them for $70, your capital gain is $20 per share. For instance, in 2026, if you’re a single filer earning over $545,501, you’ll face a 20% long-term capital gains tax. Married couples filing jointly will see the same rate for income exceeding $613,701. If your income falls between $98,901 and $613,700 as a married couple, you’ll be taxed at a 15% long-term capital gains rate. This is important to keep in mind as you plan your finances.
-
Cost Basis: This refers to the original value of your shares, including any commissions or fees you paid when you bought them. Knowing your cost basis is crucial for accurately calculating your capital gains. The IRS requires precise reporting of your cost basis for investments sold that were acquired after certain dates. If you don’t report it correctly, you might face unexpected tax liabilities.
-
Holding Period: The length of time you hold onto your shares before selling them affects the tax rate on your capital gains. Stocks held for more than a year are usually taxed at lower long-term capital gains rates, while those held for less than a year are taxed as ordinary income. For example, short-term capital gains can be taxed at rates up to 37% for high-income earners, which can significantly affect your overall tax burden.
Understanding these concepts helps families navigate stock sales and their financial implications more easily. Consider Jay and Emma, who turned to Bright Advisers to ease their financial worries and allocate their resources wisely. They crafted a comprehensive strategy that included improving their tax planning and exploring education savings options. Similarly, Emily and Mark, both busy professionals, worked with Bright Advisers to create a plan that gave them the freedom to choose whether to continue working. These success stories show how personalized budgeting can help families achieve their goals and secure their financial futures.
When you’re thinking about selling your assets, remember that we’re here to help you make smart financial choices for your family’s future. If you’re interested in learning more about how we can assist you, please join our current client waitlist.
Understand Tax Implications of Stock Sales
Imagine the worry of not knowing how much of your hard-earned money will go to taxes when you sell your stocks. When you trade shares, it’s important to understand how taxes can impact your family’s financial future.
Let’s break down the difference between short-term and long-term capital gains, so you can see how it affects your family’s finances. Short-term capital gains apply to stocks held for one year or less and are taxed at ordinary income tax rates, which can reach as high as 37%. On the other hand, long-term capital gains, for stocks held for over a year, benefit from reduced tax rates of 0%, 15%, or 20%, depending on your household’s income level. For instance, in 2026, single filers with taxable income up to $49,450 will face a 15% long-term capital gains tax rate, while those exceeding $545,500 will be taxed at 20%.
Families should also consider state taxes, which can vary significantly. For example, California imposes a capital gains tax rate of 13.3%, while states like Texas have no state income tax. This difference can affect the timing and approach of asset sales, as households in high-tax regions may aim to reduce their tax obligations by employing a company stock sale tax strategy, adjusting their sale timing, or contemplating a move to areas with more advantageous tax circumstances.
High-income households may also be subject to an additional 3.8% tax on net investment income, which includes capital gains. This tax applies if modified adjusted gross income exceeds $250,000 for married couples filing jointly.
Understanding these tax implications can empower families to make smarter financial decisions and secure their future. For example, families can utilize tax-loss harvesting strategies to offset gains with losses, potentially reducing their overall tax liability.
Consider the situation of Jay and Emma, who sought guidance from Bright Advisers to alleviate their monetary anxiety and allocate their resources effectively. They developed a comprehensive monetary strategy that included enhancing their tax planning and assessing education savings options. Likewise, Emily and Mark, who desired the liberty to decide whether to keep working, gained from a customized monetary plan that catered to their specific needs. Allison and Brian, despite their high incomes, realized they were missing out on monetary opportunities due to insufficient tax planning. Through their collaboration with Bright Advisers, they optimized their tax situation and secured their children’s future through education funding.
With the right guidance, you can turn tax complexities into opportunities for your family’s future.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Implement Strategies to Minimize Tax Liabilities
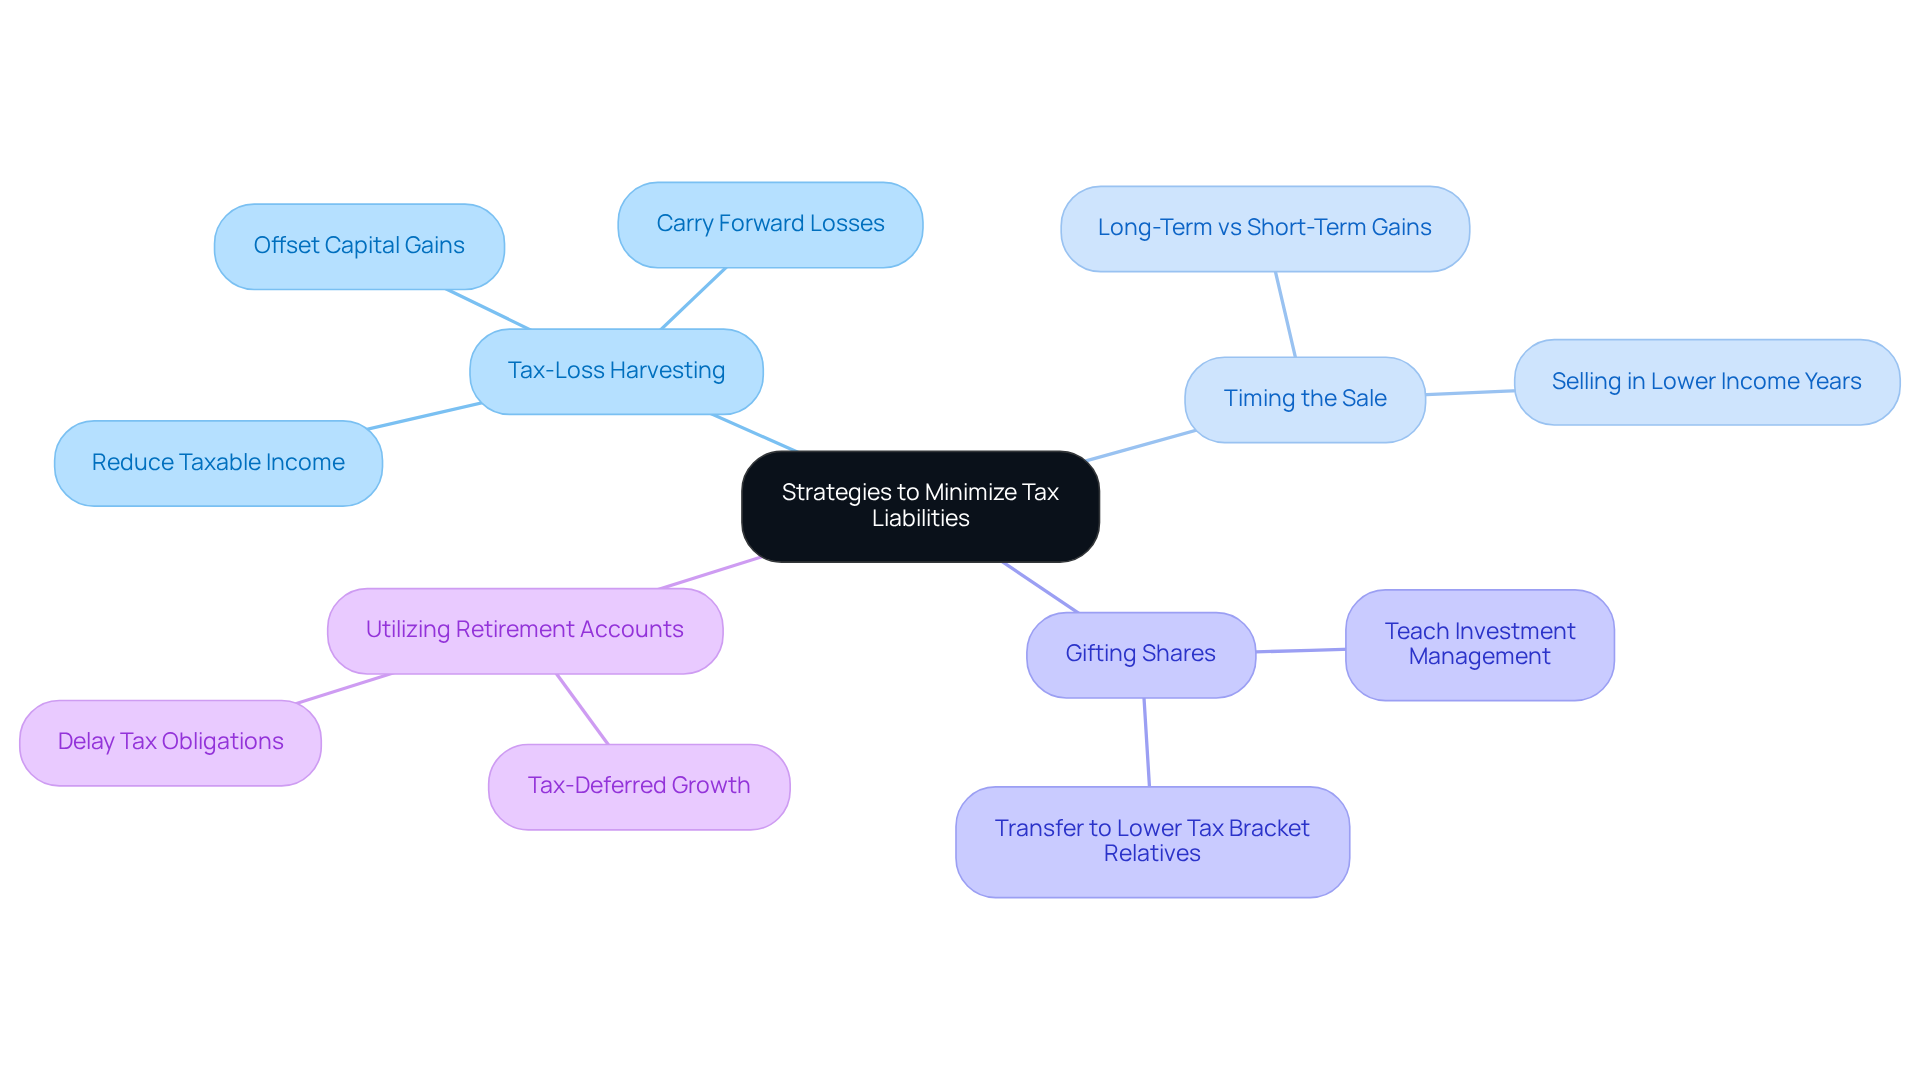
Imagine feeling less stressed about your family’s financial future while navigating the complexities of stock sales and taxes. To minimize tax liabilities associated with stock sales, families can adopt several effective strategies:
-
Tax-Loss Harvesting: This approach can be a helpful way to ease the burden of taxes on your family’s investments, allowing you to keep more of what you’ve worked hard for. For instance, if you sell an asset for a profit of $10,000 but also sell another for a loss of $5,000, you can offset the profit, lowering your taxable income. In 2026, tax-loss harvesting opportunities were realized multiple times for a representative account, demonstrating its effectiveness in managing tax liabilities. Bright Advisers offers integrated tax planning services that can help families implement this strategy effectively.
-
Timing the Sale: It’s important to consider when to sell your assets. Holding shares for over a year can significantly lower tax rates, as long-term capital gains are taxed at reduced rates compared to short-term gains. Additionally, selling in a year when your income is lower can place you in a lower tax bracket, further reducing tax liabilities.
-
Gifting Shares: Households can transfer appreciated shares to children or relatives in lower tax brackets. This approach can assist in lowering the overall tax obligation for the household, as the recipient may incur a reduced capital gains tax rate when they eventually sell the shares. This not only benefits the household financially but also teaches younger generations about investment management.
-
Utilizing Retirement Accounts: Selling stocks within accounts that provide tax benefits, such as IRAs or 401(k)s, can delay obligations until withdrawal, allowing for potential growth without immediate financial consequences. This company stock sale tax strategy is particularly beneficial for households looking to grow their investments over time while minimizing current tax obligations.
It’s common for families to feel overwhelmed by the complexities of tax obligations, especially when it comes to selling stocks. By using these strategies, families like Jay & Emma can find relief from financial stress and feel more in control of their resources. Likewise, Emily & Mark, who sought economic independence, and Allison & Brian, who aimed to enhance their monetary potential through effective tax planning, demonstrate how customized planning can lead to a more secure economic future.
With the right strategies in place, you can transform your family’s financial landscape and pave the way for a brighter future together. For individuals interested in exploring these strategies further, consider joining our current waitlist for personalized financial planning services through Lifeworks Advisors, a registered investment adviser.
Plan and Time Your Stock Sale Effectively
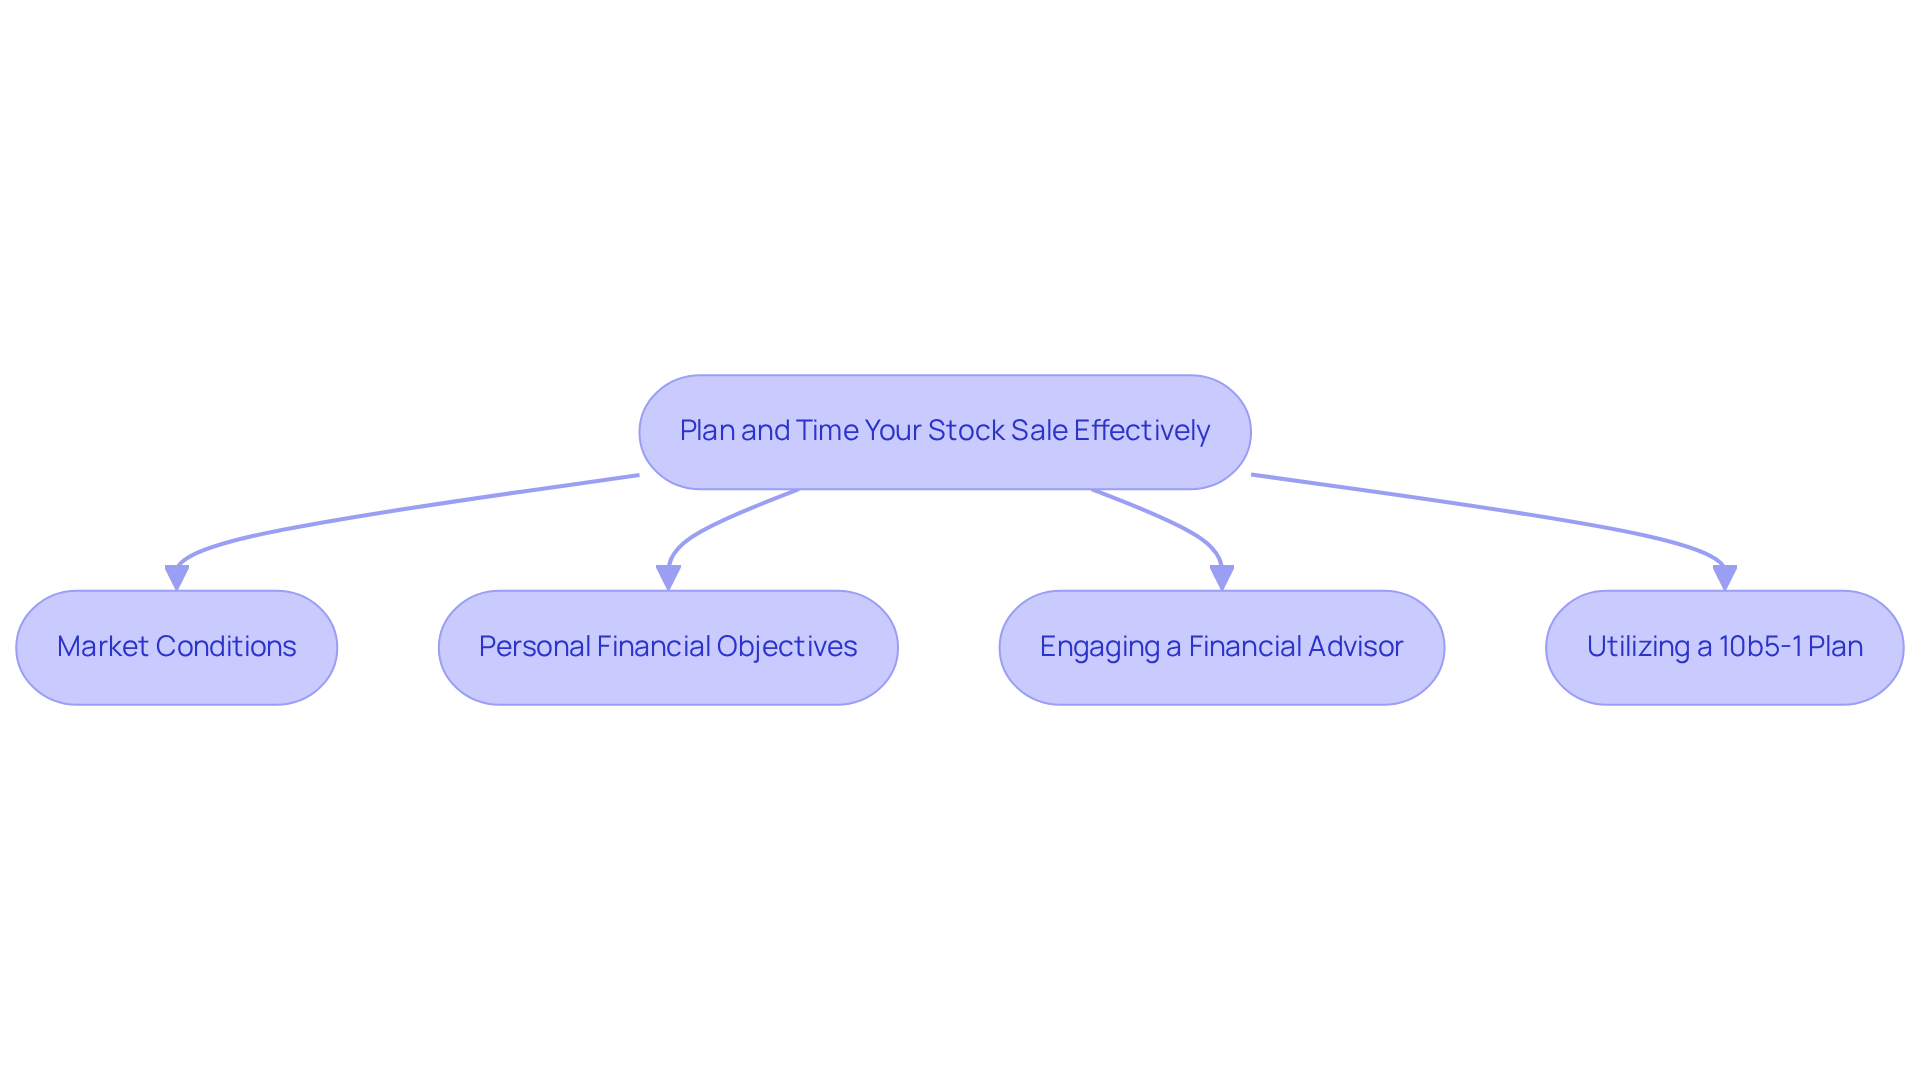
Imagine feeling secure about your family’s financial future while navigating the complexities of a company stock sale tax strategy. Effective planning and timing are crucial for implementing a successful company stock sale tax strategy. Here are some gentle strategies to consider:
-
Market Conditions: Staying informed about market trends can help you identify the best times to sell. For instance, selling during market peaks can enhance profits, while selling in downturns might lead to losses. Just think about how the S&P 500 increased by 2.7% in Q4 2025 – this suggests a positive environment for equity sales.
-
Personal Financial Objectives: Aligning your asset sales with specific goals, like funding your child’s education or purchasing a family home, can guide your decisions. Clear objectives help ensure that your sales contribute to your family’s long-term needs.
-
Reaching Out to a Caring Financial Advisor: Engaging a financial advisor, like those at Bright Advisers, can provide you with personalized advice tailored to your unique situation. They can help you navigate complex tax implications and develop a company stock sale tax strategy that aligns with your family’s goals. With innovative approaches like smart beta and factor investing, they can enhance your portfolio performance. Bright Advisers’ technology even supports the creation of hyper-personalized portfolios, making traditional investment products feel outdated.
-
Utilizing a 10b5-1 Plan: If your family holds significant company stock, a 10b5-1 plan allows for pre-scheduled sales, reducing the risk of insider trading violations. This systematic approach helps you manage your investments effectively while ensuring compliance.
By taking these steps, you can create a brighter financial future for your family, ensuring peace of mind as you navigate this journey together. Remember, all advisory services are provided through Lifeworks Advisors, a registered investment adviser. Past performance does not guarantee future results, and securities investments are subject to risk.
Conclusion
Imagine feeling confident about your family’s financial future, even when navigating the complexities of stock sales. Understanding these sales can feel daunting, but grasping their impact on your family’s financial health can ease worries about taxes and future planning.
We’ve shared practical strategies to help your family navigate tax burdens from stock sales with confidence. From tax-loss harvesting to timing your sales wisely, these approaches empower you to make informed decisions that align with your family’s values and goals.
Taking proactive steps today can lead to a more secure financial future for your family tomorrow. We’re here for you, encouraging you to reach out to fiduciary advisors like Bright Advisers. Together, we can develop tailored strategies that not only address immediate tax concerns but also pave the way for a prosperous financial future. By taking these steps, families can turn financial challenges into stepping stones for a brighter future together.
Frequently Asked Questions
What is a capital gain?
A capital gain is the profit made when you sell a share for more than you paid for it. For example, if you bought shares for $50 and sold them for $70, your capital gain would be $20 per share.
How does income affect long-term capital gains tax rates?
For single filers earning over $545,501, the long-term capital gains tax rate is 20%. Married couples filing jointly face the same rate for income exceeding $613,701. If a married couple’s income falls between $98,901 and $613,700, they will be taxed at a 15% long-term capital gains rate.
What is cost basis and why is it important?
Cost basis refers to the original value of your shares, including any commissions or fees paid when purchased. It is crucial for accurately calculating capital gains, as the IRS requires precise reporting of cost basis for investments sold that were acquired after certain dates.
What is the holding period and how does it affect taxes?
The holding period is the length of time you hold onto your shares before selling them. Stocks held for more than a year are usually taxed at lower long-term capital gains rates, while those held for less than a year are taxed as ordinary income, which can be as high as 37% for high-income earners.
How can families benefit from understanding stock sales?
Understanding key concepts like capital gains, cost basis, and holding period helps families navigate stock sales and their financial implications more easily, allowing them to make informed decisions about their investments and tax planning.
How can Bright Advisers assist families with financial planning?
Bright Advisers helps families craft comprehensive strategies that include improving tax planning and exploring education savings options, ultimately supporting them in achieving their financial goals and securing their futures.
List of Sources
- Define Stock Sale: Key Concepts for Families
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- What Tax-Savvy Investors Need to Know About Cost Basis (https://americancentury.com/plan/tax-center/cost-basis)
- Save on Taxes: Know Your Cost Basis (https://schwab.com/learn/story/save-on-taxes-know-your-cost-basis)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- What is cost basis for taxes? | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/cost-basis)
- Understand Tax Implications of Stock Sales
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- State Capital Gains Tax Rates for 2026: How Much Investors Pay This Year (https://kiplinger.com/taxes/state-capital-gains-tax-rates)
- A Guide to the Capital Gains Tax Rates: Short-term vs. Long-term Capital Gains Taxes (https://turbotax.intuit.com/tax-tips/investments-and-taxes/guide-to-short-term-vs-long-term-capital-gains-taxes-brokerage-accounts-etc/L7KCu9etn)
- State-by-State Capital Gains Tax Rates for 2026 (https://theentrustgroup.com/blog/state-capital-gains-tax)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- Implement Strategies to Minimize Tax Liabilities
- Harnessing tax-loss harvesting in volatile markets (https://am.jpmorgan.com/us/en/asset-management/adv/insights/portfolio-insights/taxes/harnessing-tax-loss-harvesting-in-volatile-markets)
- Tax loss harvesting after April 15, strategies to use in 2026 (https://instead.com/resources/blog/tax-loss-harvesting-after-april-15-strategies-to-use-in-2026)
- Tax-Loss Harvesting Strategies: How They Work (https://am.gs.com/en-us/advisors/campaign/tax-loss-harvesting-strategies-how-they-work)
- Tax-Loss Harvesting: The Smart Investor’s Guide 2026 (https://tsginvest.com/tax-loss-harvesting)
- What is Tax-Loss Harvesting? Rules & Examples | New York Life (https://newyorklife.com/articles/what-is-tax-loss-harvesting)
- Plan and Time Your Stock Sale Effectively
- 2026 Market Outlook | J.P. Morgan Global Research (https://jpmorgan.com/insights/global-research/outlook/market-outlook)
- Americans Set Ambitious Financial Goals for 2026 But Rising Cost of Living Could Disrupt Those Plans (https://aicpa-cima.com/news/article/americans-set-ambitious-financial-goals-for-2026-but-rising-cost-of-living)
- What is the Outlook for the Stock Market in 2026? | Hoffman Financial Group (https://hoffmancorporation.com/stock-market-outlook-what-is-the-outlook-for-the-stock-market-in-2026)
- Quotes on Market Timing • Novel Investor (https://novelinvestor.com/quote-category/market-timing)
- 2026 Mid-Year Outlook: U.S. Stocks and Economy (https://schwab.com/learn/story/us-stock-market-outlook)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading