

Overview
Imagine achieving the dream of early retirement at age 55. This goal is within reach through thoughtful financial planning that considers your long-term living expenses, healthcare costs, and Social Security options. It’s important to understand that a comprehensive financial plan is essential. By budgeting wisely, grasping retirement account rules, and committing to ongoing financial education, you can pave the way for a secure and fulfilling retirement lifestyle for you and your family.
Together, we can navigate this journey. Picture a future where you can spend more quality time with your loved ones, free from financial worries. Building a solid financial foundation not only supports your dreams but also nurtures your family’s well-being.
Remember, we’re here for you. Embrace the steps toward financial security with confidence, knowing that the right strategies can help you achieve your retirement goals. Let’s take this journey together, ensuring a brighter future for your family.
Key Highlights:
- Early retirement at age 55 offers opportunities for freedom but requires careful financial planning for potentially 30-40 years of living expenses.
- Average life expectancy in the U.S. is projected to reach 79.5 years by 2050, necessitating long-term financial strategies.
- Healthcare costs are expected to rise, with projections indicating that 60% of U.S. adults could face heart disease and stroke by 2050, impacting retirement budgets.
- Social Security benefits decrease if claimed before full retirement age, which can significantly affect financial plans.
- A comprehensive financial plan should include assessing current financial situations, establishing clear future objectives, and creating a detailed budget.
- The Rule of 55 allows penalty-free withdrawals from a 401(k) for those who leave their job in the year they turn 55, offering flexibility in budgeting.
- Understanding IRA withdrawal rules and tax implications is essential to avoid unexpected financial pressures.
- Continuous financial education through online courses, literature, and community workshops is crucial for long-term financial success.
- Regular consultations with financial advisors can help adapt financial plans to changing circumstances and improve overall monetary literacy.
Introduction
The dream of retiring at 55 is one that many young parents hold dear, offering a chance to savor life beyond the traditional work schedule. However, this wonderful opportunity comes with important considerations that require thoughtful planning and foresight. Imagine if you could enjoy more time with your family, but first, it’s crucial to understand the intricacies of financial longevity and the rules surrounding retirement accounts. By equipping yourself with the right knowledge and resources, you can navigate these complexities with confidence.
In this article, we will explore the essential factors that contribute to a successful early retirement. We’ll highlight the importance of comprehensive financial planning, lifestyle adjustments, and continuous education. Together, we can navigate this journey toward a fulfilling and financially secure retirement. By embracing these strategies, you can pave the way for a future where you spend quality time with your loved ones, creating cherished memories that last a lifetime.
We’re here for you as you take these important steps. Remember, with the right support and planning, early retirement can become a reality, allowing you to focus on what truly matters—your family.
Understand Early Retirement at Age 55
Embracing life beyond employment at the early retirement age 55 can be a wonderful opportunity to enjoy good health and newfound freedom. However, this transition requires thoughtful consideration of several key factors.
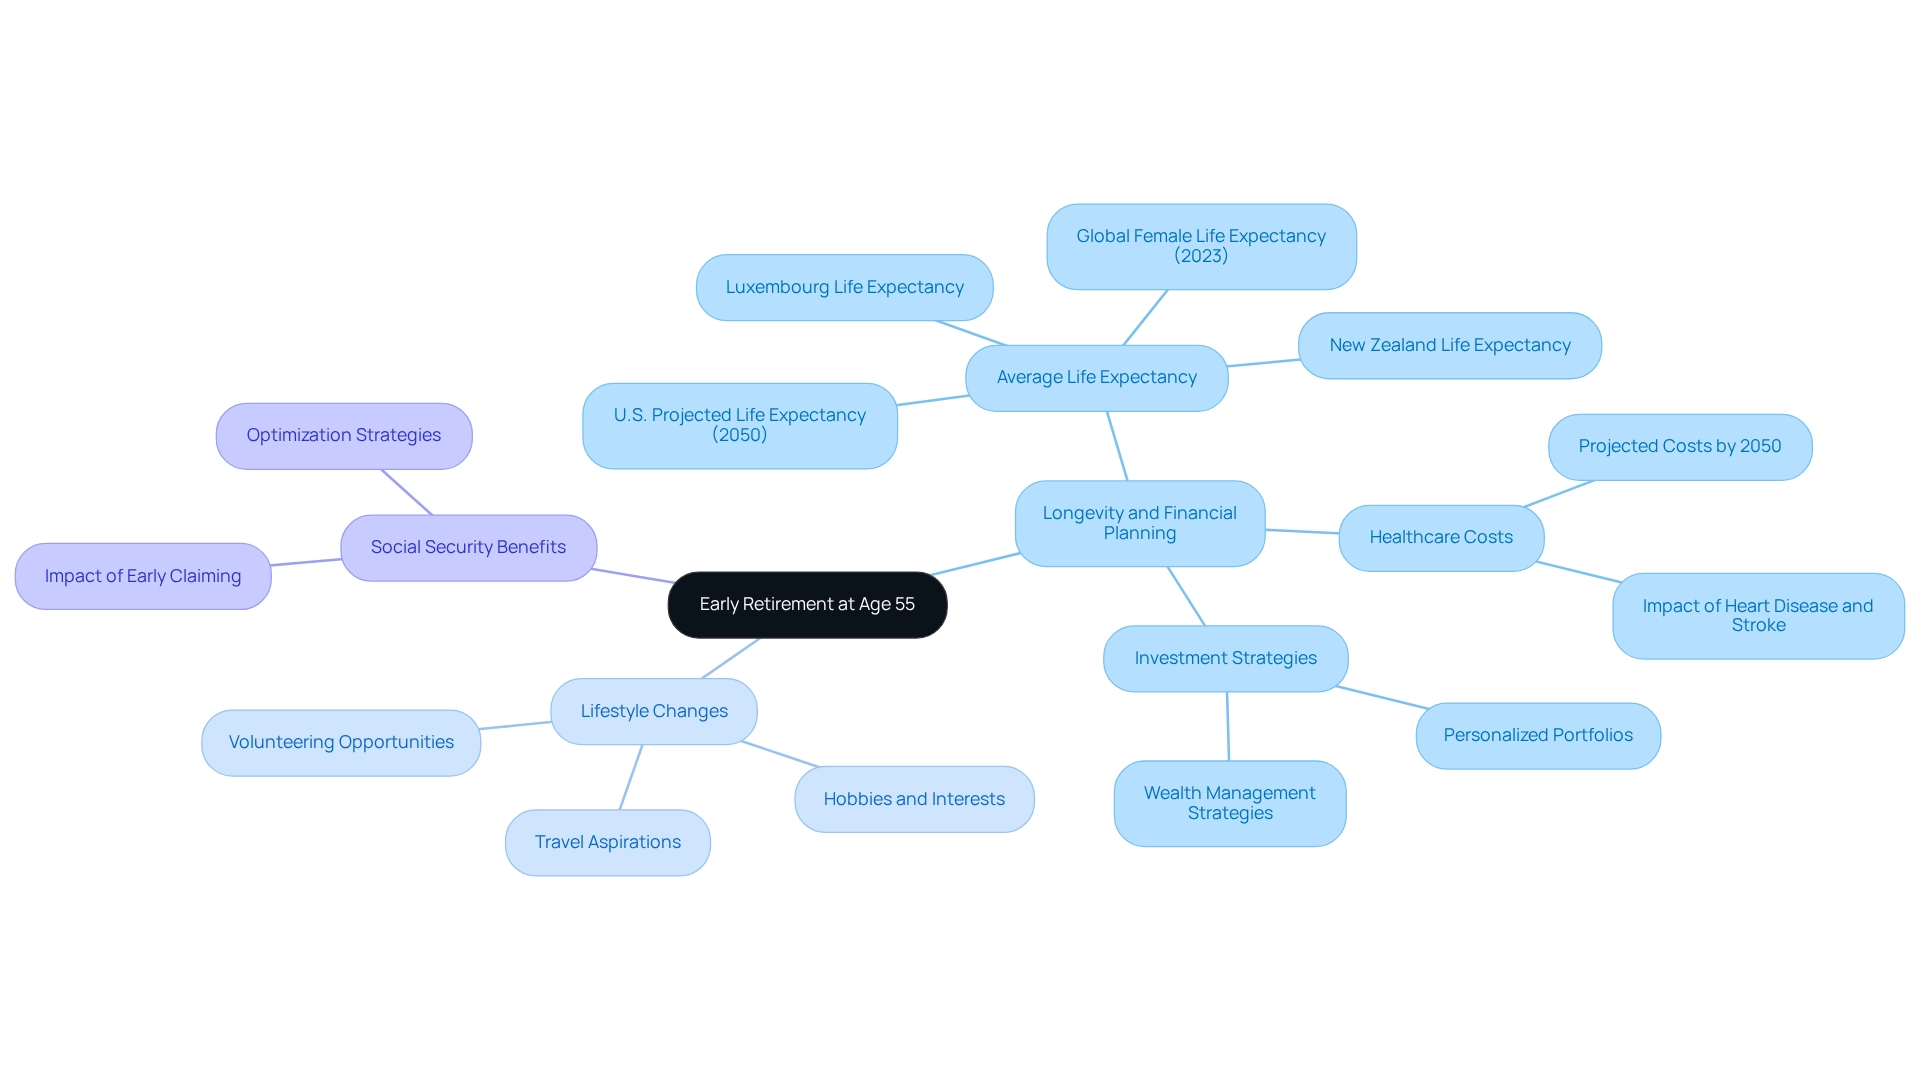
Longevity and Financial Planning: Imagine planning for 30 to 40 years of living expenses. With the average life expectancy in the U.S. projected to reach around 79.5 years by 2050, and global female life expectancy at birth averaging 75.9 years in 2023, it’s crucial to think about your longevity and prepare your finances accordingly. Bright Advisers offers personalized investment portfolios tailored to your unique financial situation, helping ensure your retirement plan is both strong and adaptable.
Lifestyle Changes: It’s essential to reflect on how your daily life will change after retirement. Will you travel more, pursue hobbies, or volunteer? Clearly defining your lifestyle aspirations will help shape your financial needs. With Bright Advisers’ innovative wealth management strategies, you can align your investment approach with your family goals, optimizing your wealth accumulation while considering that early retirement age 55 often results in higher healthcare expenses before you become eligible for Medicare at age 65. As Robert McAllister highlights, projections suggest that by 2050, at least 60% of U.S. adults could be impacted by heart disease and stroke, potentially tripling related healthcare costs to $1.8 trillion. It’s vital to include these potential expenses in your budget to avoid financial strain later. Bright Advisers’ advanced technology can help you manage these costs effectively, ensuring your budget remains resilient against unexpected healthcare challenges.
Social Security Benefits: If you plan to rely on Social Security, be mindful that benefits will decrease if claimed before reaching your full retirement age. This reduction can significantly impact your overall financial plan. Partnering with Bright Advisers allows you to create a comprehensive strategy that addresses all aspects of your future, including optimizing your Social Security benefits. By understanding these vital considerations and leveraging the innovative solutions offered by Bright Advisers, you can prepare for a successful transition into early retirement age 55, ensuring your strategy aligns with your family’s long-term goals. Together, we can navigate this journey, supporting you every step of the way.
Develop a Comprehensive Financial Plan
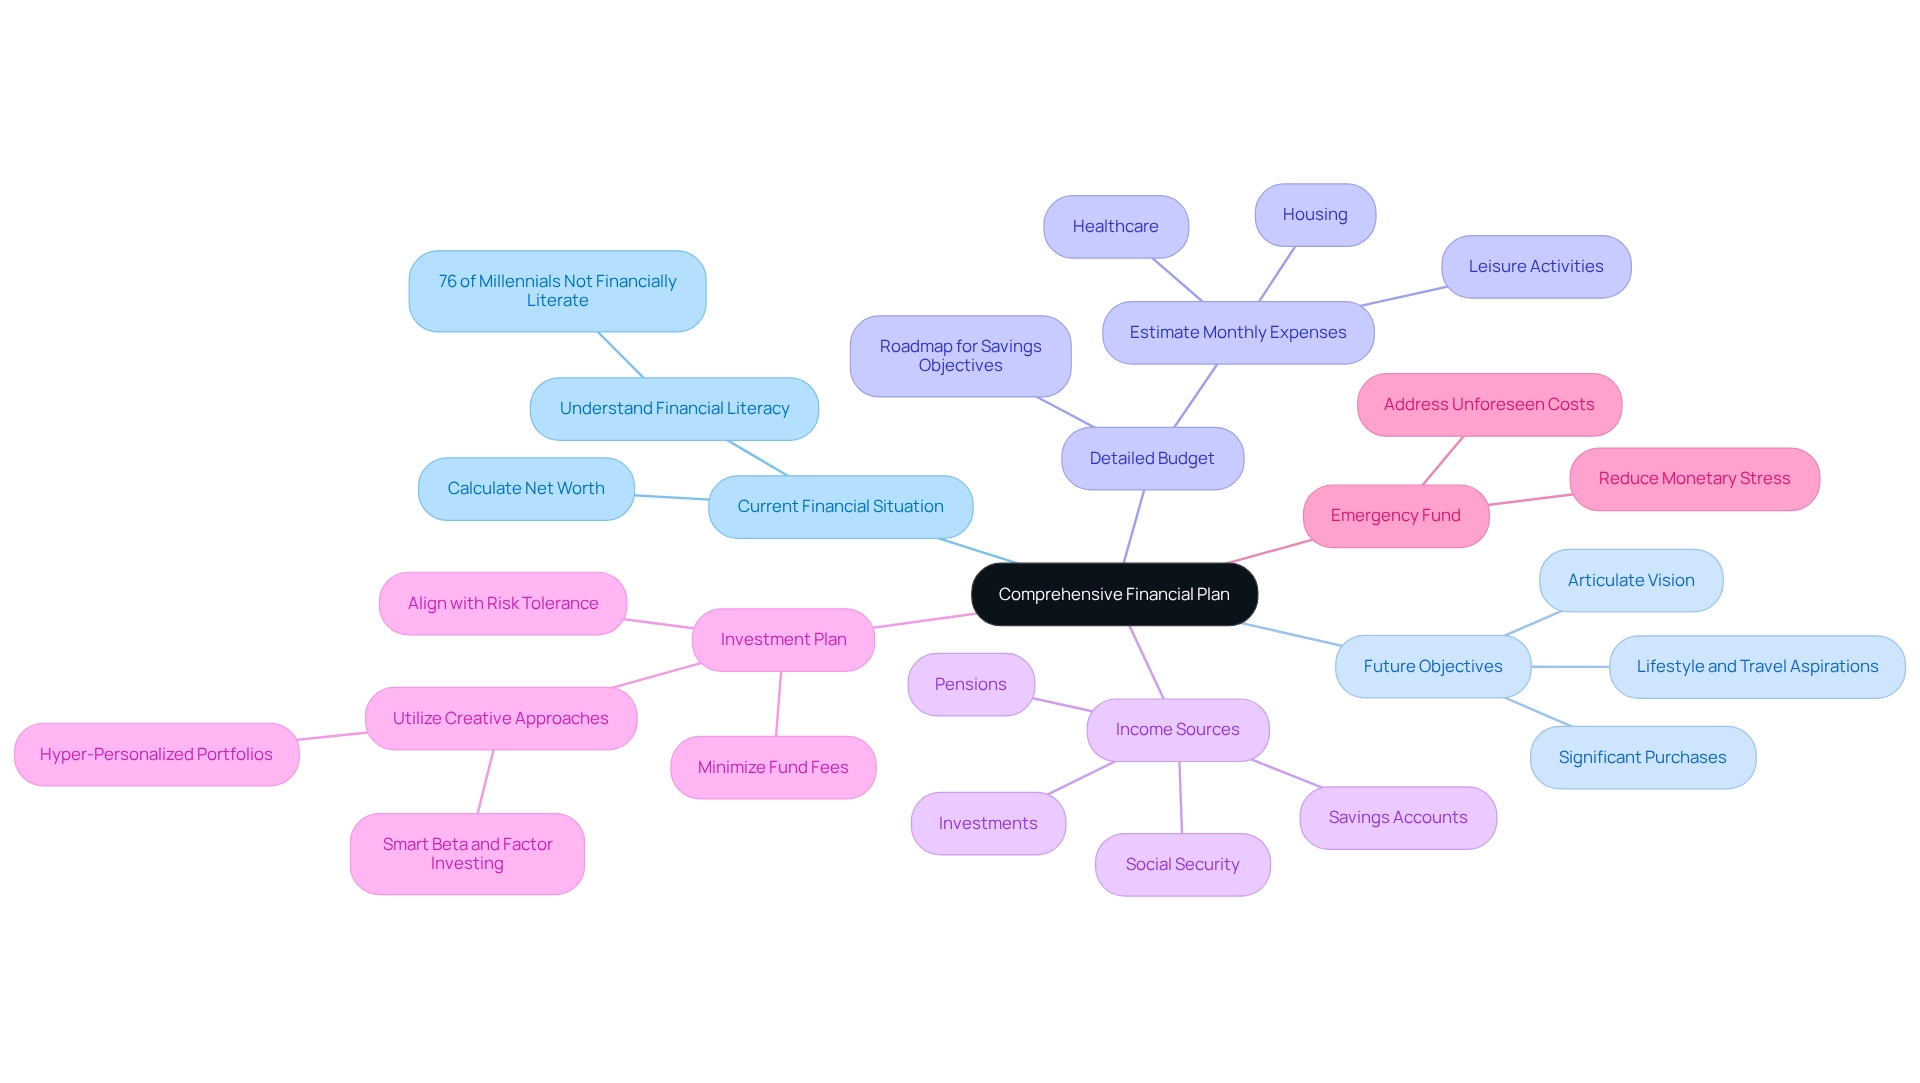
To retire at the early retirement age 55, a robust financial plan is essential, encompassing income, expenses, and investment strategies.
-
Assess Your Current Financial Situation: Begin by calculating your net worth, which includes both assets and liabilities. This evaluation offers a clear insight into your financial well-being and preparedness for the future. It’s important to remember that 76% of millennials are not financially literate, highlighting the significance of understanding your finances.
-
Establish Clear Objectives for Your Future: Articulate your vision for this phase of life. Consider your desired lifestyle, travel aspirations, and any significant purchases you plan to make. Imagine if you could create the life you’ve always dreamed of. As Jen Kirkman humorously states, “Instead of saving for someone else’s college education, I’m currently saving for an upscale living community filled with golf carts and attractive young male nurses who enjoy butterscotch.”
-
Create a Detailed Budget: Estimate your monthly expenses during your later years, factoring in housing, healthcare, and leisure activities. This budget will serve as a roadmap for your savings objectives, helping you visualize your financial journey.
-
Identify Income Sources: Determine the various income streams you will depend on in your later years, such as pensions, Social Security, savings accounts, and investments. Knowing where your income will come from can alleviate worries and help you plan effectively.
-
Investment Plan: Develop an investment plan that aligns with your risk tolerance and retirement timeline. Bright Advisers utilizes creative approaches, including smart beta and factor investing, to develop hyper-personalized portfolios that improve your economic results. Their commitment to minimal fund fees ensures that you can access these strategies without excessive costs. Additionally, their innovative technology renders traditional investment products obsolete, leading to more efficient investment portfolios.
-
Emergency Fund: Create an emergency fund to address unforeseen costs, which can reduce monetary stress during retirement. Having this safety net can provide peace of mind, knowing you are prepared for unexpected challenges.
The economic pressure numerous households encounter, as emphasized in the case study ‘Living Paycheck-to-Paycheck,’ highlights the importance of a thorough budget to prevent such circumstances. For example, via their partnership with Bright Advisers, clients such as Allison and Brian enhanced their tax circumstances and ensured their children’s future, showcasing the transformative power of effective planning. By diligently following these steps, you can create a thorough budget plan that supports your goals for early retirement age 55, ensuring a secure and fulfilling future. Remember, the interconnectedness of monetary literacy, planning, and overall economic health is crucial in this process. Together, we can navigate this journey towards financial security.
Navigate Retirement Account Rules and Penalties
Navigating account regulations is essential for early leavers from the workforce, especially for those reaching early retirement age 55. Here are some key considerations that can help you feel more secure in your financial journey:
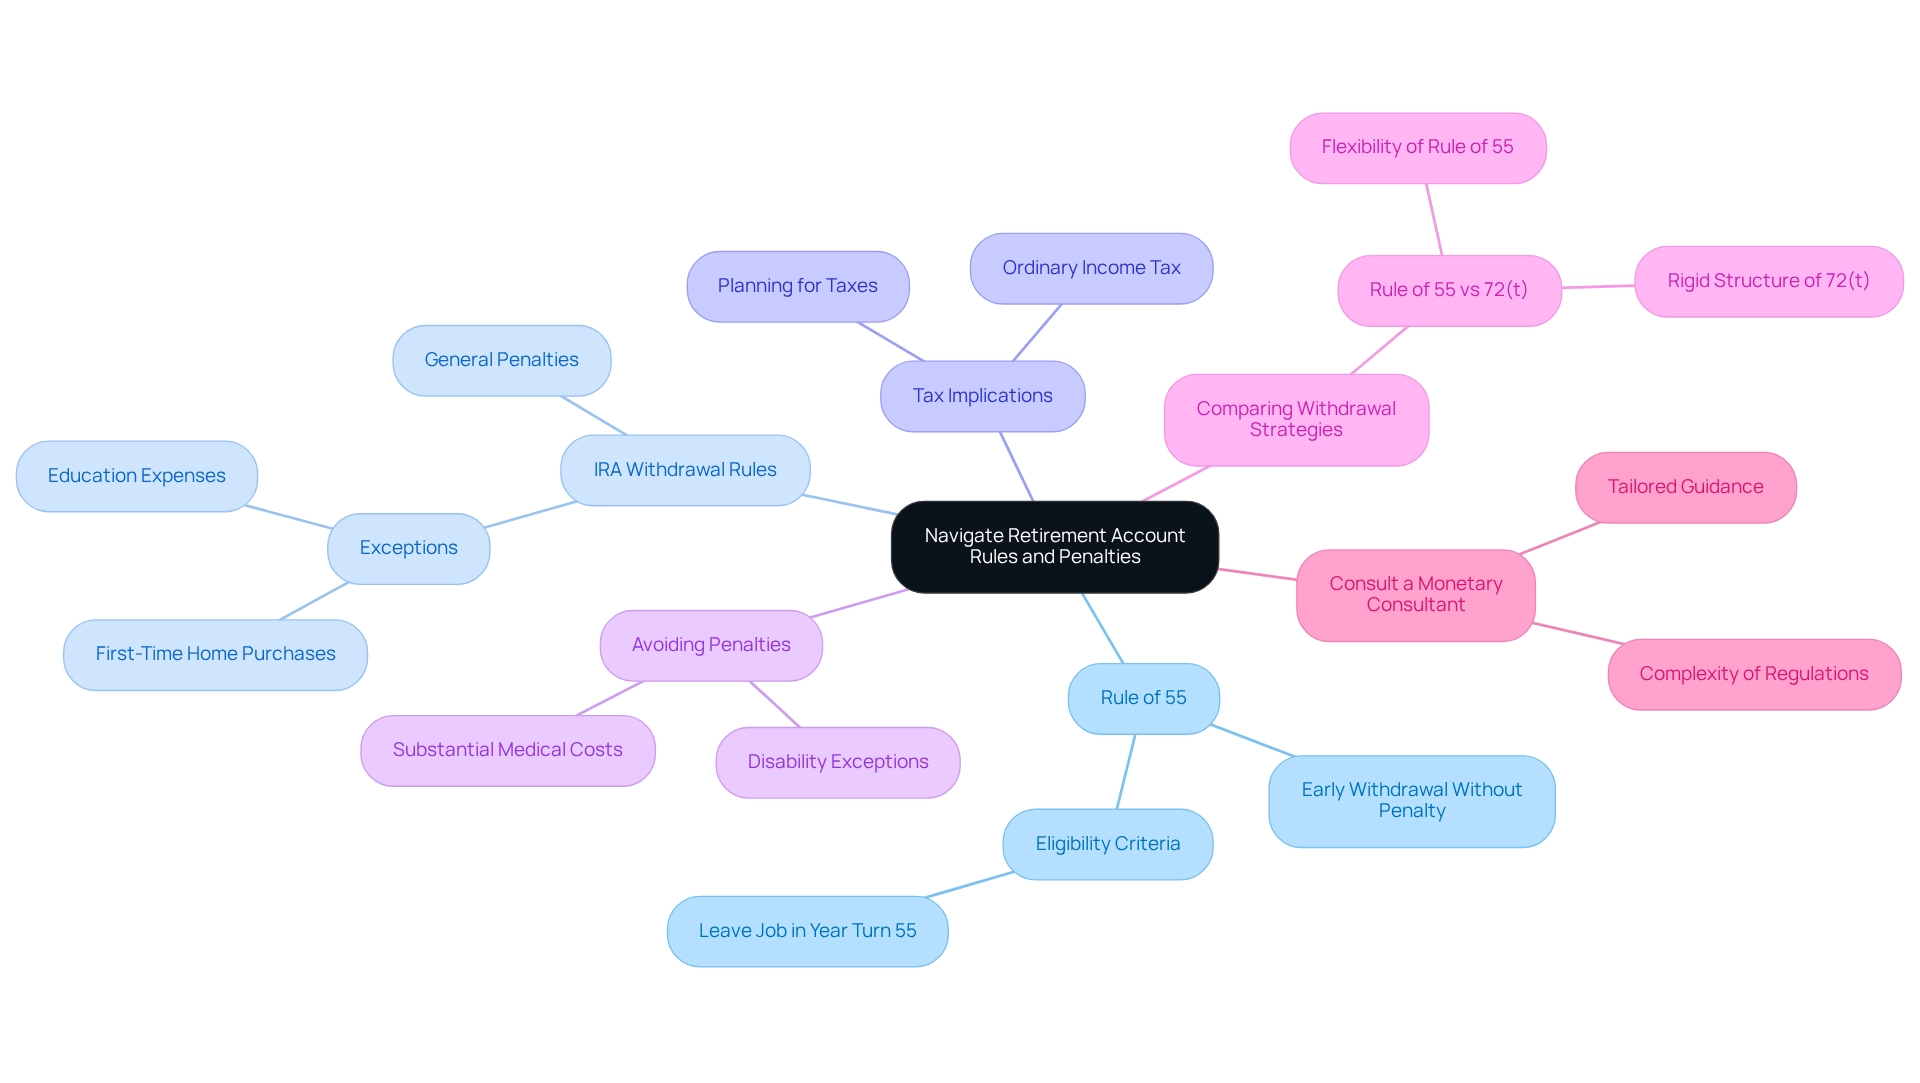
- The Rule of 55: Imagine being able to withdraw from your 401(k) without the worry of a 10% early withdrawal penalty. This rule allows individuals who leave their job in the calendar year they reach the early retirement age 55 or later to do just that. This provision can be a crucial resource for obtaining funds during initial withdrawal, providing adaptability in your budget planning. Remember, this rule applies specifically if you leave your job in the year you turn 55 or later, aligning with the early retirement age 55.
- IRA Withdrawal Rules: It’s important to understand that generally, withdrawals from an IRA before age 59½ incur penalties. However, there are exceptions that could benefit you, such as qualified first-time home purchases or education expenses, allowing you to access necessary liquidity without penalties.
- Tax Implications: When considering withdrawals from savings accounts, keep in mind that they are taxed as ordinary income. Preparing for these taxes can help you avoid unexpected monetary pressures later in life, ensuring your family’s financial stability.
- Avoiding Penalties: Understanding exceptions to early withdrawal penalties is key. If you encounter disability or substantial medical costs, you may be eligible for penalty-free withdrawals. This knowledge can provide you with greater economic flexibility in challenging times.
- Comparing Withdrawal Strategies: The Rule of 55, which relates to an early retirement age 55, offers more flexibility in withdrawal amounts and timing compared to the rigid structure of the 72(t) rule, which requires individuals to commit to substantially equal periodic payments for at least five years. This comparison highlights the benefits of the Rule of 55 in your financial planning, allowing you to make choices that align with your family’s needs.
- Consult a Monetary Consultant: Given the complexities surrounding savings account regulations, seeking guidance from a monetary consultant can help ensure that you make informed decisions tailored to your unique situation. We’re here for you in this journey.
As Rebecca Lake, an expert in investing and estate planning, points out, “Grasping the intricacies of account regulations is essential for efficient monetary planning.” By understanding these guidelines, you can handle your savings accounts with confidence, reducing possible penalties and creating a path for a financially secure early withdrawal.
Moreover, recent market insights suggest a resurgence in economic markets, which may affect your planning strategies for the future. Staying updated on market conditions can assist you in making improved choices concerning your financial assets, ensuring that your family’s future remains bright.
Utilize Resources for Continuous Financial Education
To ensure long-term financial success in retirement, engaging in continuous financial education is crucial.
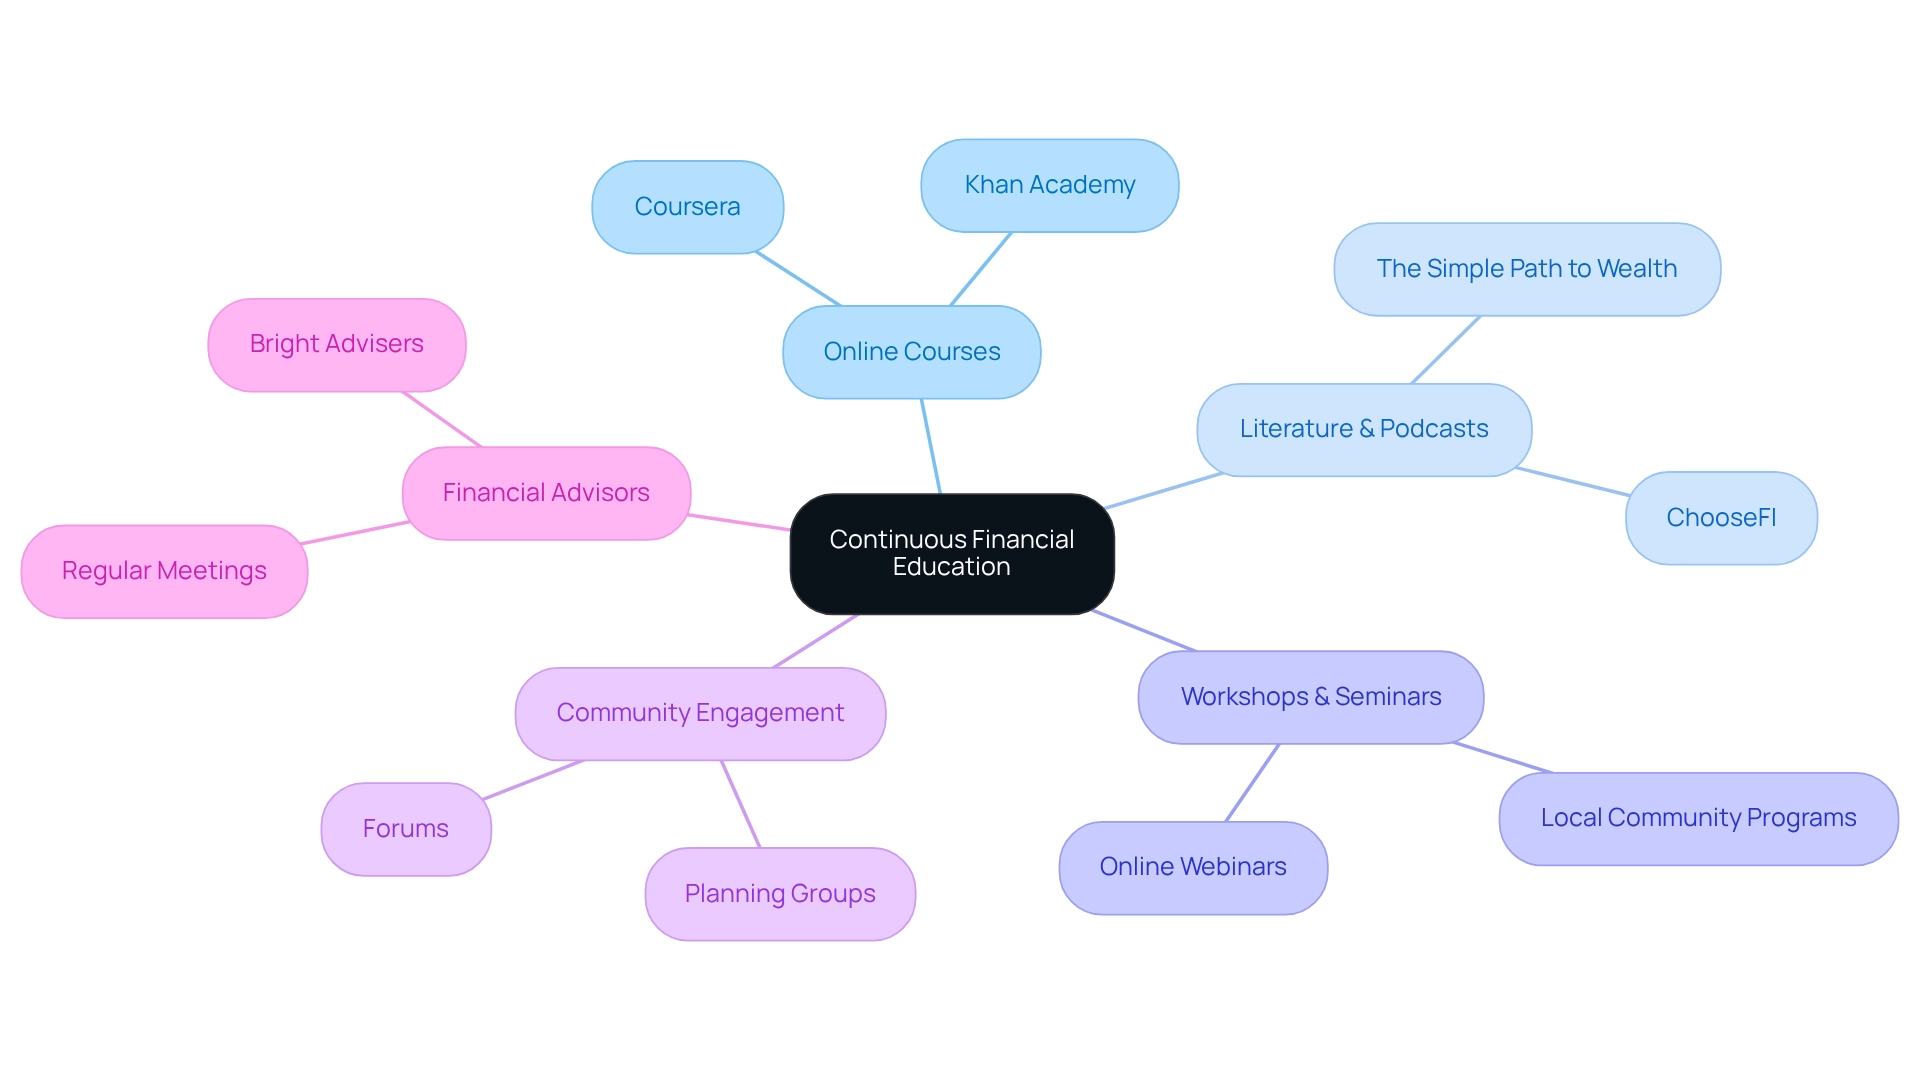
Imagine if you could confidently manage your finances and secure your family’s future. Online courses from platforms like Coursera and Khan Academy offer free resources on personal finance and planning for later life. These courses can enhance your understanding of key economic concepts. In fact, recent statistics reveal that 65% of individuals who completed online money management courses reported greater confidence in handling their savings for the future.
Consider exploring insightful literature and podcasts focused on retirement planning. Titles like ‘The Simple Path to Wealth’ and podcasts such as ‘ChooseFI’ provide valuable perspectives and strategies that can significantly improve your economic literacy.
It’s important to understand that numerous organizations conduct workshops and seminars aimed at enhancing monetary literacy. Seek out local community programs or online webinars that can provide practical knowledge and skills. Abdullah Al Bahrani highlights the significance of locating reliable sources of information to deepen your comprehension of economic concepts.
Together, we can navigate this journey by joining planning groups or forums. This enables you to exchange experiences and gain insights from others. Participating in a community can provide assistance and fresh perspectives on effective monetary approaches.
Remember, regular meetings with financial advisors are crucial to remain updated on best practices tailored to your changing economic circumstances. For example, Emily and Mark, a couple who collaborated with Bright Advisers, executed strategies like debt reduction, cash flow management, and retirement planning, which enabled them to attain economic freedom. Experts suggest that individuals assess their economic plans at least once a year to adjust to evolving situations.
A practical tip for improving your economic well-being is to curb impulse spending. This can lead to a healthier bank account and improved readiness for the future.
As money expert Suze Orman states, “A significant aspect of monetary freedom is having your heart and mind unburdened by concerns about the what-ifs of life.” By leveraging these resources, you can significantly enhance your financial knowledge, empowering you to make informed decisions that align with your early retirement age 55 goals and understanding the Rule of 55.
We’re here for you as you embark on this important journey towards financial security.
Conclusion
Achieving the dream of retiring at 55 is a journey that requires a thoughtful and nurturing approach. It involves understanding financial longevity, planning with care, and making informed lifestyle choices. By assessing your current financial situation, setting clear retirement goals, and creating detailed budgets, you can lay a strong foundation for your early retirement aspirations.
Imagine navigating the intricacies of retirement account rules—it’s crucial for avoiding penalties and ensuring that your funds are accessible when you need them. Utilizing provisions like the Rule of 55 can provide you with beneficial flexibility. Moreover, continuous financial education through online courses, books, and professional consultations empowers you to adapt your strategies as your circumstances change.
Ultimately, with strategic planning and the right resources, early retirement can transition from a dream to a beautiful reality. This allows you to cherish moments with your family and pursue your passions freely. By prioritizing financial literacy and leveraging the tools available to you, the path to a secure and fulfilling retirement becomes much clearer. Together, we can navigate this journey, offering you the opportunity to savor life’s precious moments.
Frequently Asked Questions
What are the key factors to consider when transitioning to early retirement at age 55?
Key factors include longevity and financial planning, lifestyle changes, and Social Security benefits. It’s important to plan for living expenses over 30 to 40 years, reflect on how daily life will change, and understand the impact of claiming Social Security benefits early.
How does longevity affect financial planning for early retirement?
With an average life expectancy projected to reach around 79.5 years by 2050, planning for 30 to 40 years of living expenses is crucial. This requires thoughtful financial strategies to ensure sustainability throughout retirement.
What lifestyle changes should one consider when planning for retirement?
Individuals should reflect on their aspirations for retirement, such as traveling, pursuing hobbies, or volunteering. Clearly defining these goals will help shape financial needs and investment strategies.
Why is it important to consider healthcare expenses in retirement planning?
Early retirement at age 55 may lead to higher healthcare costs before Medicare eligibility at age 65. Projections suggest that healthcare costs related to heart disease and stroke could significantly increase, making it essential to include these potential expenses in your budget.
How can Bright Advisers assist in retirement planning?
Bright Advisers offers personalized investment portfolios and innovative wealth management strategies to help align financial planning with lifestyle goals, manage healthcare costs, and optimize Social Security benefits.
What happens to Social Security benefits if claimed before full retirement age?
Benefits will decrease if claimed before reaching full retirement age, which can significantly impact your overall financial plan. It’s important to consider this when developing a retirement strategy.
How can one ensure a successful transition into early retirement?
By understanding key considerations such as longevity, lifestyle changes, and Social Security, and by leveraging the solutions offered by Bright Advisers, individuals can prepare effectively for early retirement and align their strategy with long-term family goals.
List of Sources
- Understand Early Retirement at Age 55
- US Life Expectancy 1950-2025 – Trends and Influences Over the Decades – North American Community Hub (https://nchstats.com/us-life-expectancy-trends)
- Life Expectancy Statistics and Facts (2025) (https://media.market.us/life-expectancy-statistics)
- Develop a Comprehensive Financial Plan
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- The Best Quotes About Retirement (https://retirable.com/advice/lifestyle/best-retirement-quotes)
- Navigate Retirement Account Rules and Penalties
- When Can You Withdraw? 401(k)s and the Rule of 55 (https://schwab.com/learn/story/retiring-early-5-key-points-about-rule-55)
- Early Retirement Distributions: 72t and Rule of 55 | RGWM Insights (https://rgwealth.com/insights/early-retirement-72t-rule-of-55)
- Using the Rule of 55 to Take Early 401(k) Withdrawals (https://smartasset.com/retirement/401k-55-rule)
- Utilize Resources for Continuous Financial Education
- Financial Literacy Statistics: How Financially Literate Are Americans? (https://marketwatch.com/financial-guides/banking/financial-literacy-statistics)
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- Money Talk: 10 Great Quotes About Personal Finance (https://3riversfcu.org/blog/post/money-talk-10-great-quotes-about-personal-finance)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading