

Key Highlights
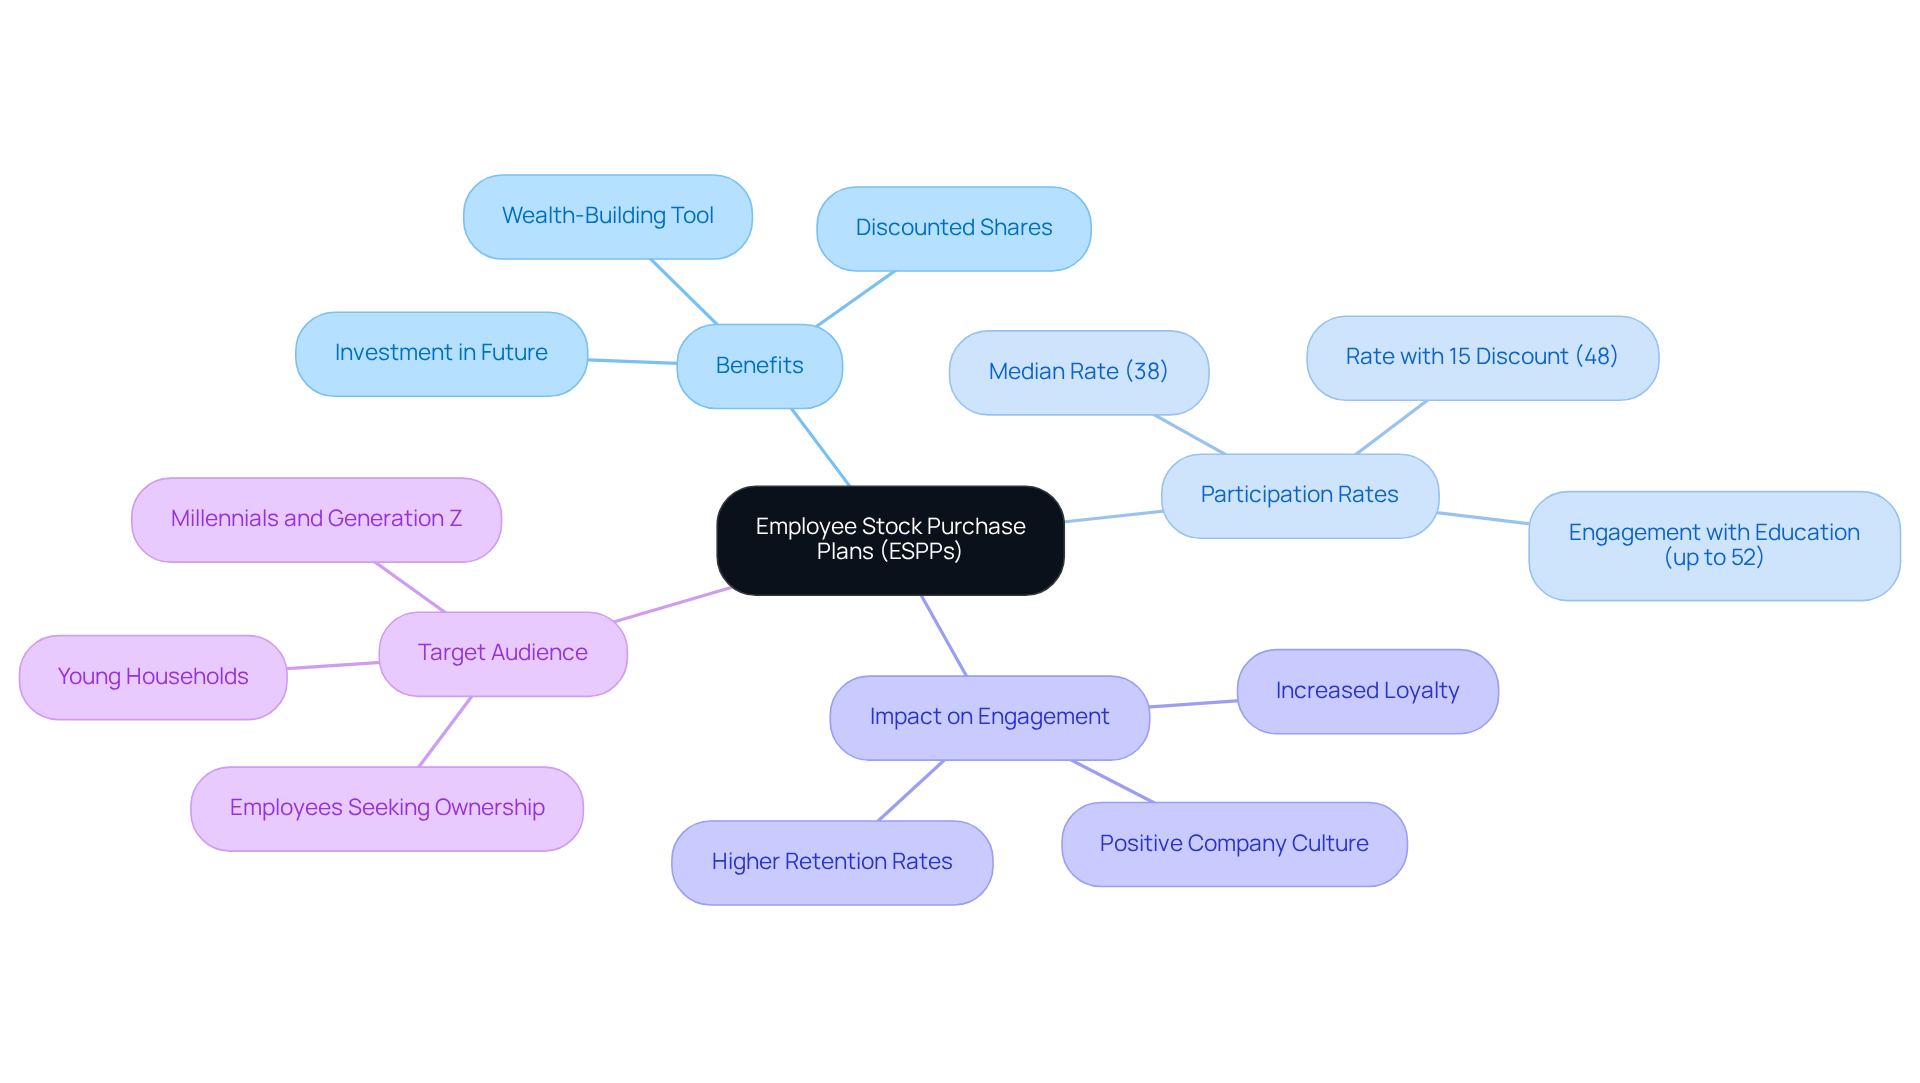
- Employee Stock Purchase Plans (ESPPs) allow employees to buy company stock at a discount, typically between 5% and 15%, through payroll deductions.
- Participation in ESPPs can be a strategic wealth-building tool for young families, with median participation rates at 38%, rising to 48% for a 15% discount.
- Companies that effectively communicate the value of ESPPs see higher employee engagement and loyalty, contributing to overall growth.
- Form 3922 is crucial for reporting ESPP transactions, capturing details like purchase date and fair market value, which are essential for accurate tax reporting.
- Improper handling of Form 3922 can lead to penalties, emphasising the need for meticulous record-keeping to avoid tax-related issues.
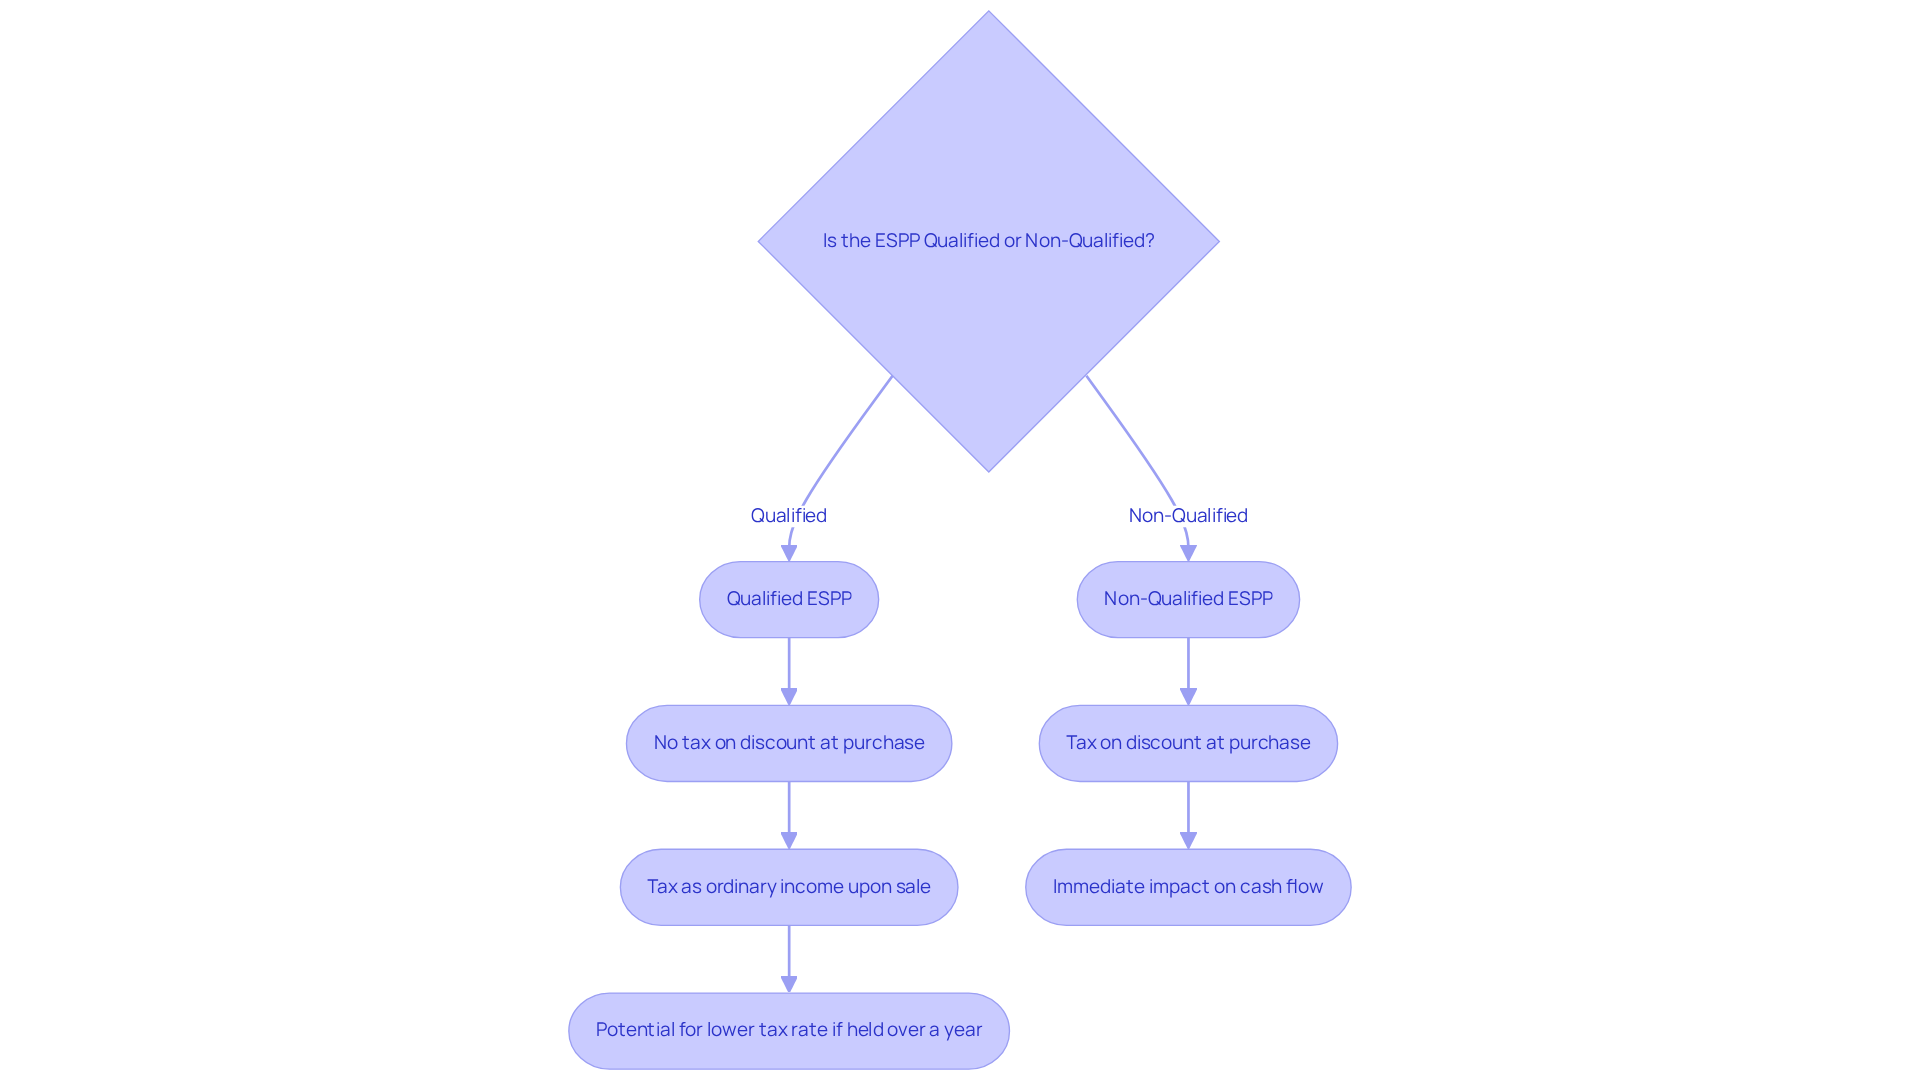
- Understanding the tax implications of ESPP transactions is vital; qualified plans treat discounts as ordinary income upon sale, while non-qualified plans tax discounts at purchase.
- Families can benefit from lower tax rates on gains if shares are held for over a year, highlighting the importance of strategic timing in share sales.
- Staying organised with ESPP documentation simplifies tax filing and reduces anxiety, allowing families to focus on their financial goals.
- Partnering with Bright Advisers can enhance financial well-being through integrated tax planning strategies, turning tax season into an opportunity for growth.
Introduction
Imagine feeling overwhelmed by the complexities of Employee Stock Purchase Plans (ESPPs) while trying to secure your family’s financial future. These plans can be a great way to invest in your company and enjoy potential tax benefits. But understanding the tax documents, especially Form 3922, is key to managing your finances effectively.
How can you and your family make the most of your ESPP benefits and avoid costly tax mistakes? Together, we’ll explore how to manage your ESPP tax documents, helping you make informed decisions that support your family’s financial goals.
Define Employee Stock Purchase Plans (ESPPs)
Imagine a way to invest in your family’s future while supporting the company you believe in. Employee Stock Purchase Plans (ESPPs) are a wonderful opportunity for you to buy shares of your company at a discount, often through easy payroll deductions. These plans let you buy company stock at a discount, usually between 5% and 15%. It’s a great way to invest in your future while supporting your company.
For young households, participating in an ESPP can act as a strategic wealth-building tool. You might wonder if investing in your company’s stock is the right choice for your family. By investing in your employer’s stock at a discount, you can accumulate assets that may increase in value over time, complementing other investment strategies. The median participation rate in ESPPs is currently 38%, but this figure rises to 48% for companies offering a 15% discount, highlighting the attractiveness of these plans. Moreover, companies that effectively communicate the value of ESPPs see higher engagement rates, with participation rates reaching up to 52% when multiple educational methods are employed.
Think about how reassuring it would be to know your investments reflect your commitment and hard work. Case studies illustrate the positive impact of ESPPs on employee engagement and retention. For instance, companies that prioritize educating their employees about ESPPs report increased participation and loyalty, ultimately contributing to overall company growth. Additionally, expert insights emphasize that ESPPs can be particularly beneficial for younger employees, who often prioritize ownership and investment opportunities in their employment decisions. By leveraging these plans, young families can not only secure their financial future but also foster a sense of belonging and investment in their workplace.
By embracing ESPPs, you’re not just investing in stocks; you’re investing in your family’s dreams and future stability.
Explore Form 3922: Purpose and Importance
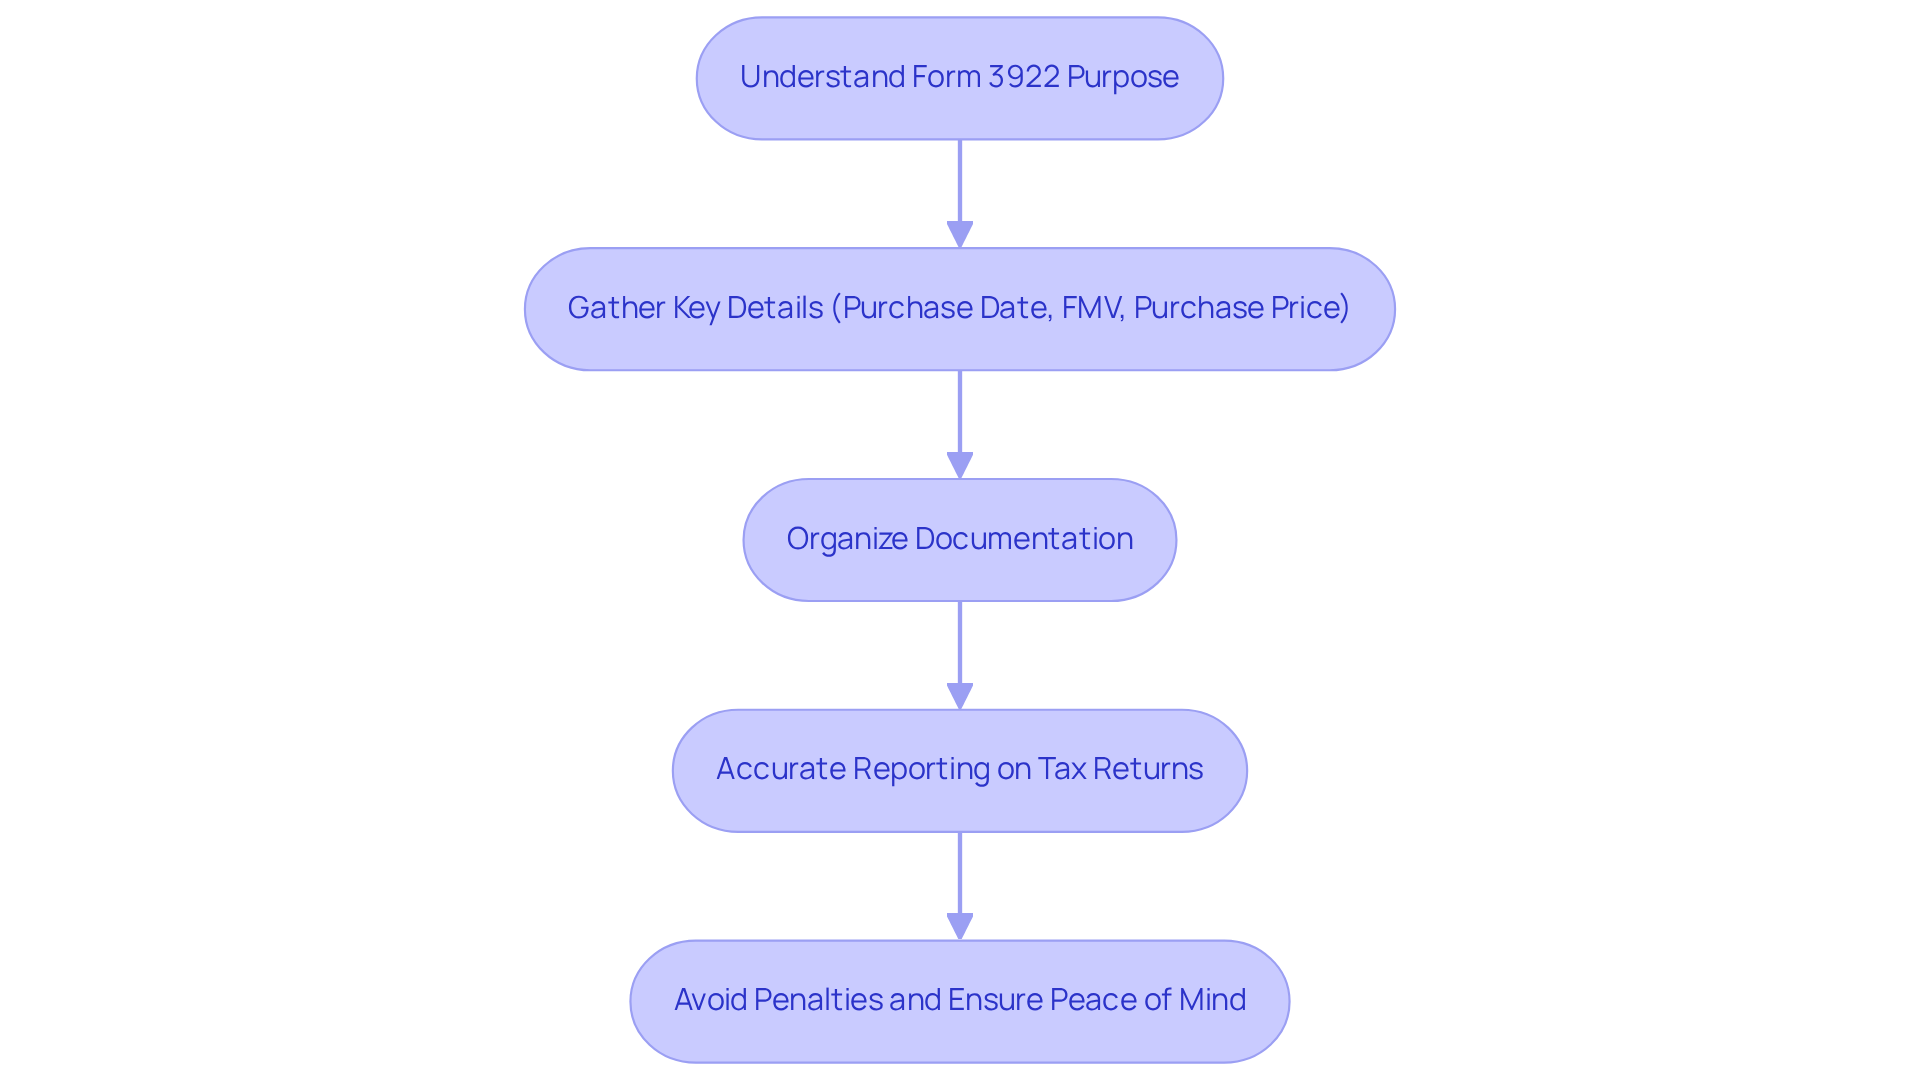
Navigating the world of employee stock purchase plans can feel overwhelming, especially when it comes to understanding important documents like the espp tax document. This form, known as the ‘Transfer of Stock Acquired Through an Employee Stock Purchase Plan,’ is provided by employers to employees who buy stock through an ESPP. It captures key details such as the purchase date, fair market value (FMV) on the grant date, and the purchase price. For young parents, grasping and organizing the espp tax document is essential for accurate income reporting from ESPP transactions on tax returns. Imagine the stress of facing unexpected tax penalties due to paperwork mistakes. Keeping track of your documents is crucial for peace of mind.
Improper handling of Document 3922 can lead to significant penalties, emphasizing the need for meticulous record-keeping. For instance, errors in reporting can incur fines of up to $630 per statement, which can escalate if not addressed promptly. By prioritizing the accurate completion and storage of the espp tax document, young parents can confidently navigate the complexities of tax reporting, safeguarding their financial future.
Case studies show that households who keep organized documentation of their ESPP transactions, including the espp tax document and Form 3922, encounter fewer tax-related problems and enhanced peace of mind during tax season. Taking the time to manage Form 3922 can be your first step toward a more secure financial future for your family.
Understand Tax Implications of ESPP Transactions
Imagine feeling uncertain about how your Employee Stock Purchase Plan could impact your family’s finances. The ESPP tax document outlines the tax implications of Employee Stock Purchase Plan (ESPP) transactions, which can vary significantly between qualified and non-qualified plans. In a qualified ESPP, the discount on stock purchases isn’t taxed when you buy the shares; instead, it’s treated as ordinary income when you sell them. When you hold onto shares for over a year, you might benefit from a lower tax rate on any gains, which can be a great advantage for families looking to maximize their investment returns.
On the other hand, non-qualified ESPPs require you to pay taxes on the discount right when you purchase the shares, as outlined in the ESPP tax document. This can affect your cash flow and tax obligations, which is something many young households worry about. Understanding these differences is key to planning your family’s finances effectively. It’s important to know how these decisions can impact your financial future, especially when you’re trying to secure your family’s well-being.
Think about how keeping your shares longer could lead to better tax benefits for your family. There are case studies where families have strategically timed their share sales, resulting in significant tax savings. Without this knowledge, families might miss out on significant savings that could benefit their financial stability. By understanding the ESPP tax document and its implications, you can make informed decisions that align with your family’s financial goals. Understanding these tax implications can empower your family to make choices that truly support your financial dreams.
Guide to Reporting ESPP Transactions on Tax Returns
Imagine the anxiety of navigating tax forms while juggling family responsibilities; it can feel overwhelming, but we’re here to help you through it. When it comes to reporting ESPP transactions on your tax returns, having the correct espp tax document and taking a structured approach can make all the difference.
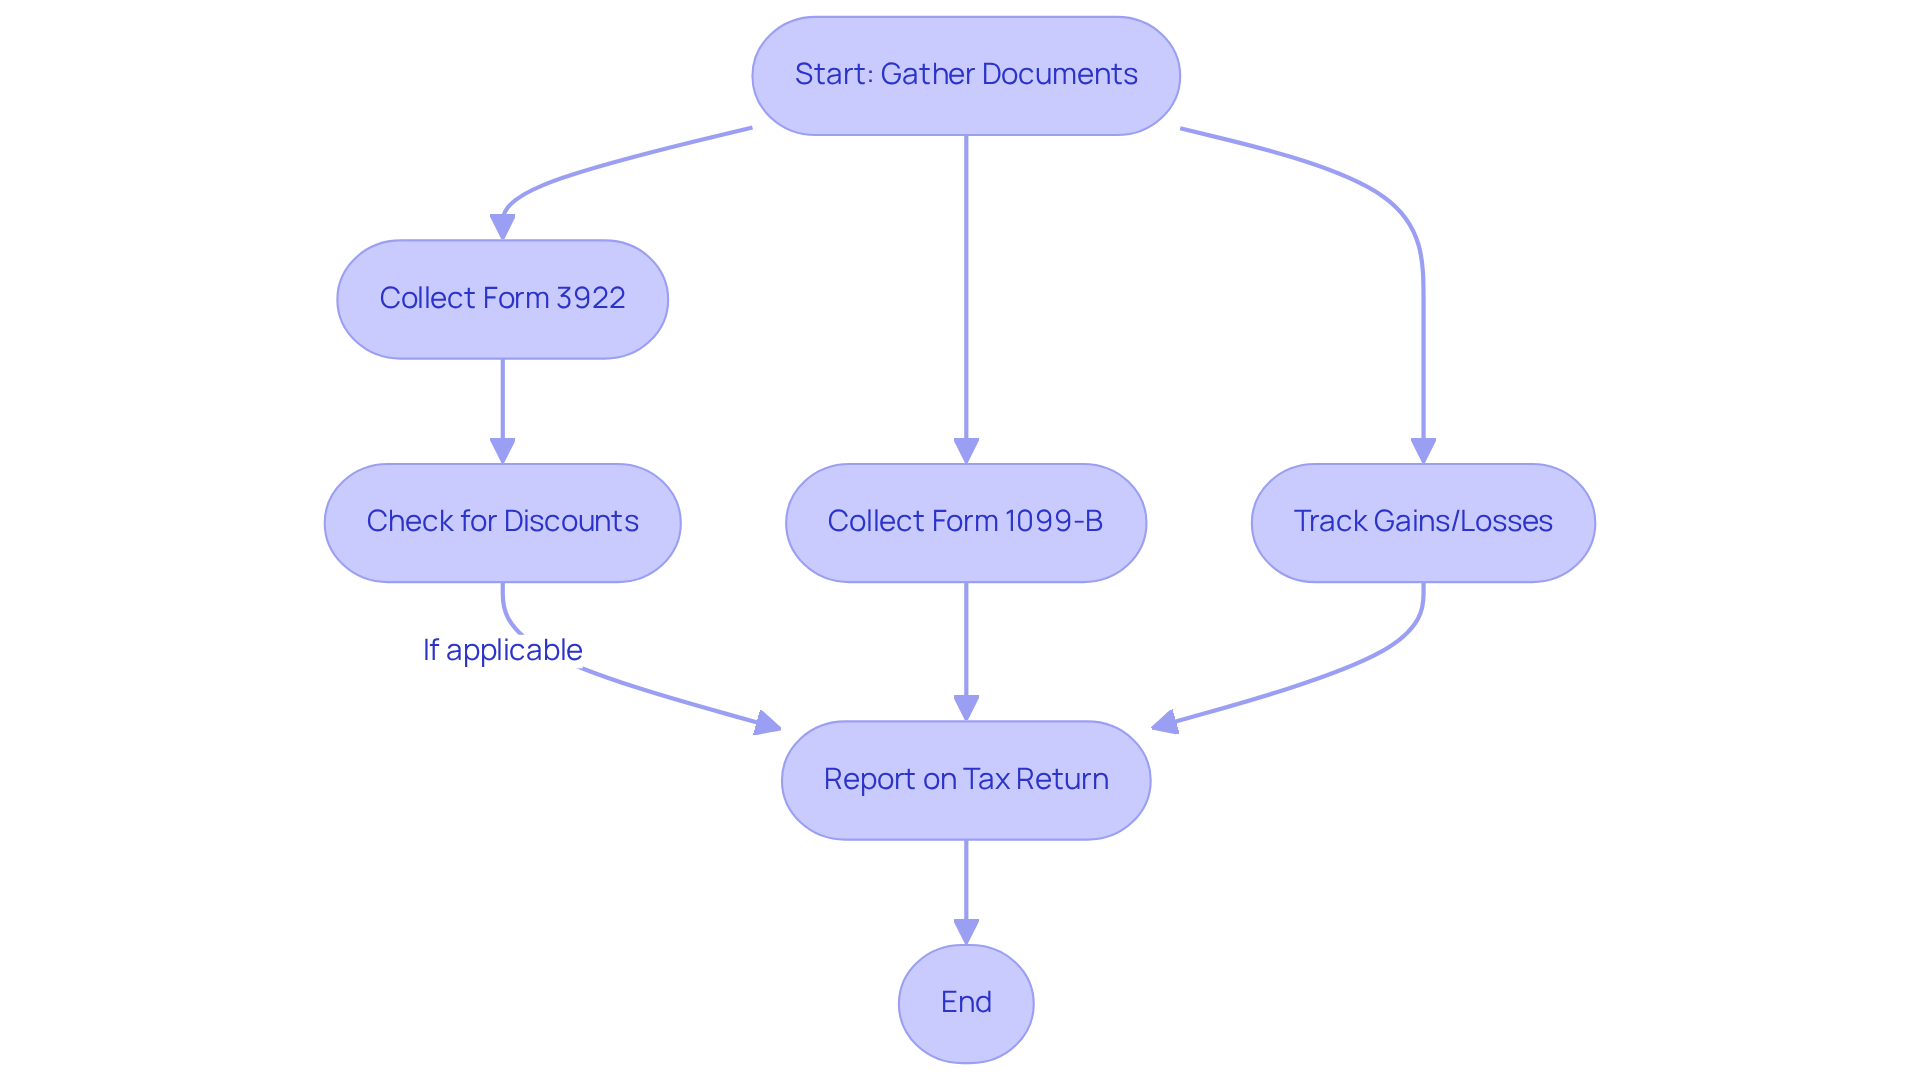
First, gather your 3922 and any important documents, including the espp tax document and the 1099-B, which shows the sale of your stock. This means you get to enjoy the benefits of a discount on your stock purchase, which can feel like a little win in your financial journey.
Next, you’ll want to keep track of any gains or losses from selling your stock, which can be reported on specific forms to help you stay organized. If you’ve held onto those shares for over a year, you can benefit from lower tax rates on those gains, which is a relief for many families.
For young parents like Jay and Emma, who are focused on reducing monetary anxiety and optimizing their resources, keeping meticulous records and understanding these steps can simplify tax filing and help avoid costly mistakes. By staying organized and informed, families like Jay and Emma can feel more secure about their finances, paving the way for a brighter future for their children.
By partnering with Bright Advisers, families can benefit from integrated tax planning strategies that enhance their overall financial well-being, ensuring they make the most of their financial resources. With the right support, you can turn tax season into an opportunity for financial growth and peace of mind for your family.
Conclusion
Imagine feeling confident about your family’s financial future, even when tax season rolls around. Mastering the intricacies of Employee Stock Purchase Plans (ESPPs) is essential for young families like yours. By understanding how to effectively manage ESPP tax documents, such as Form 3922, you can navigate the complexities of tax reporting with ease. Many parents feel overwhelmed by tax reporting, especially when it comes to ESPPs. But this knowledge empowers you to make informed investment decisions, fostering a sense of ownership and stability in your financial journey.
Throughout this guide, we’ve shared key insights on the benefits of participating in ESPPs, the importance of accurate documentation, and the tax implications associated with these plans. From the advantages of discounted stock purchases to the necessity of meticulous record-keeping, each element plays a crucial role in ensuring that your family can maximize its financial potential while minimizing stress during tax season. The case studies and practical strategies outlined serve as a roadmap for you to follow, reinforcing the importance of being proactive in your financial planning.
When you understand how to manage your ESPP tax documents, you’re not just checking a box; you’re laying down a strong foundation for your family’s future. By taking the time to educate yourself and seek guidance from trusted advisors like Bright Advisers, you can transform tax season from a source of anxiety into an opportunity for growth. By embracing this journey, you’re not just preparing for tax season; you’re building a legacy for your family.
Frequently Asked Questions
What are Employee Stock Purchase Plans (ESPPs)?
Employee Stock Purchase Plans (ESPPs) are programs that allow employees to buy shares of their company at a discount, typically between 5% and 15%, often through payroll deductions.
How can ESPPs benefit young households?
ESPPs can serve as a strategic wealth-building tool for young households by allowing them to invest in their employer’s stock at a discount, potentially increasing their assets over time and complementing other investment strategies.
What is the median participation rate in ESPPs?
The median participation rate in ESPPs is currently 38%, which increases to 48% for companies offering a 15% discount.
How does effective communication impact ESPP participation rates?
Companies that effectively communicate the value of ESPPs can see participation rates rise to 52% when multiple educational methods are employed.
What impact do ESPPs have on employee engagement and retention?
Case studies show that companies prioritizing education about ESPPs report increased employee participation and loyalty, contributing to overall company growth.
Why are ESPPs particularly beneficial for younger employees?
ESPPs are beneficial for younger employees as they often prioritize ownership and investment opportunities in their employment decisions, helping them secure their financial future and fostering a sense of belonging in their workplace.
What is the overall message regarding ESPPs?
By participating in ESPPs, employees are not only investing in stocks but also in their family’s dreams and future stability.
List of Sources
- Define Employee Stock Purchase Plans (ESPPs)
- Maximizing ESPP Impact: Boost Growth & Engage Talent | Equiniti (https://equiniti.com/us/insights/eq-views/employee-stock-purchase-plans-espp-is-your-espp-positively-impacting-your-company-growth)
- 7 ways to boost ESPP enrollment (https://jpmorganworkplacesolutions.com/insights/how-to-boost-participation-in-your-espp)
- NASPP | Why Your Qualified ESPP Should Offer a 15% Discount (https://naspp.com/blog/why-15-percent-for-espp)
- Employee Stock Purchase Programs: 2026 Guide to ESPP Risks & Benefits (https://advisorfinder.com/blog-posts/employee-stock-purchase-programs-risks-benefits-2025)
- Explore Form 3922: Purpose and Importance
- Understanding Form 3922: Transfer of Stock Obtained Under an ESOP Plan (https://qapita.com/blog/form-3922)
- Form 3922: ESPP Reporting & Stock Basis Explained (https://usehaven.com/blog-posts/form-3922-espp-reporting-stock-basis-explained)
- What is Form 3922: Everything You Need to Know | Qapita (https://linkedin.com/posts/qapita_what-is-form-3922-everything-you-need-to-activity-7277933658840162304-hDsf)
- About Form 3922, Transfer of Stock Acquired Through An Employee Stock Purchase Plan Under Section 423(c) | Internal Revenue Service (https://irs.gov/forms-pubs/about-form-3922)
- Understand Tax Implications of ESPP Transactions
- ESPP Taxation: Qualified vs. Non-Qualified Plans & Dispositions | Equity Comp Academy (https://3040wealth.com/academy/espp-taxation)
- Employee Stock Purchase Plans (https://turbotax.intuit.com/tax-tips/investments-and-taxes/employee-stock-purchase-plans/L8NgMFpFX)
- ESPP Tax Rules: What You Need to Know (https://wealthenhancement.com/blog/espp-tax-rules-what-you-need-to-know)
- NASPP | Trends in ESPPs: Five Facts and a Myth (https://naspp.com/blog/five-trends-in-espps)
- Employee Stock Purchase Plan (ESPP) Taxes: A Guide (https://schwab.com/learn/story/espp-taxes)
- Guide to Reporting ESPP Transactions on Tax Returns
- Employee Stock Purchase Plans (https://turbotax.intuit.com/tax-tips/investments-and-taxes/employee-stock-purchase-plans/amp/L8NgMFpFX)
- Employee Stock Purchase Plans (https://turbotax.intuit.com/tax-tips/investments-and-taxes/employee-stock-purchase-plans/L8NgMFpFX)
- ESPP double tax: How to avoid getting taxed twice on shares (https://taxesforexpats.com/articles/investments/how-to-avoid-getting-double-taxed-on-espp-employee-stock-purchase-plan.html)
- Form 3922: ESPP Reporting & Stock Basis Explained (https://usehaven.com/blog-posts/form-3922-espp-reporting-stock-basis-explained)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading