

Key Highlights:
- A 401(k) is an employer-sponsored savings plan that allows pre-tax contributions, lowering taxable income and often includes employer matching.
- In 2026, 92% of employers with 401(k) plans offer matching contributions, making them a popular choice for families.
- Roth IRAs involve after-tax contributions, allowing for tax-free withdrawals during retirement, beneficial for those expecting higher future tax brackets.
- Families should evaluate their current and future financial situations to choose between a 401(k) and a Roth IRA for optimal savings.
- Maximising employer matching in a 401(k) while contributing to a Roth IRA can create a diversified tax strategy for long-term financial security.
- In 2026, the 401(k) contribution limit will increase to $24,500, while the IRA limit will rise to $7,500, with additional catch-up contributions for those 50 and older.
- Automatic deposits into retirement accounts encourage consistent saving and help families stay focused on long-term financial goals.
- Regularly reviewing retirement plans is essential, especially during significant life changes, to adjust contributions and stay informed about tax regulations.
Introduction
Understanding the ins and outs of 401(k) plans and Roth IRAs is crucial for families looking to build a secure financial future. These valuable savings tools not only come with tax benefits but also offer strategies for long-term growth that can truly make a difference in your family’s wealth.
Imagine if you could navigate these options with confidence – how do you balance contributions and maximize benefits? This article explores best practices for funding 401(k)s and Roth IRAs, providing you with the knowledge to make informed decisions that align with your family’s financial goals.
We’re here for you, ready to help you on this journey. Together, we can ensure that your family’s financial future is bright and prosperous.
Understand 401(k) and Roth IRA Basics
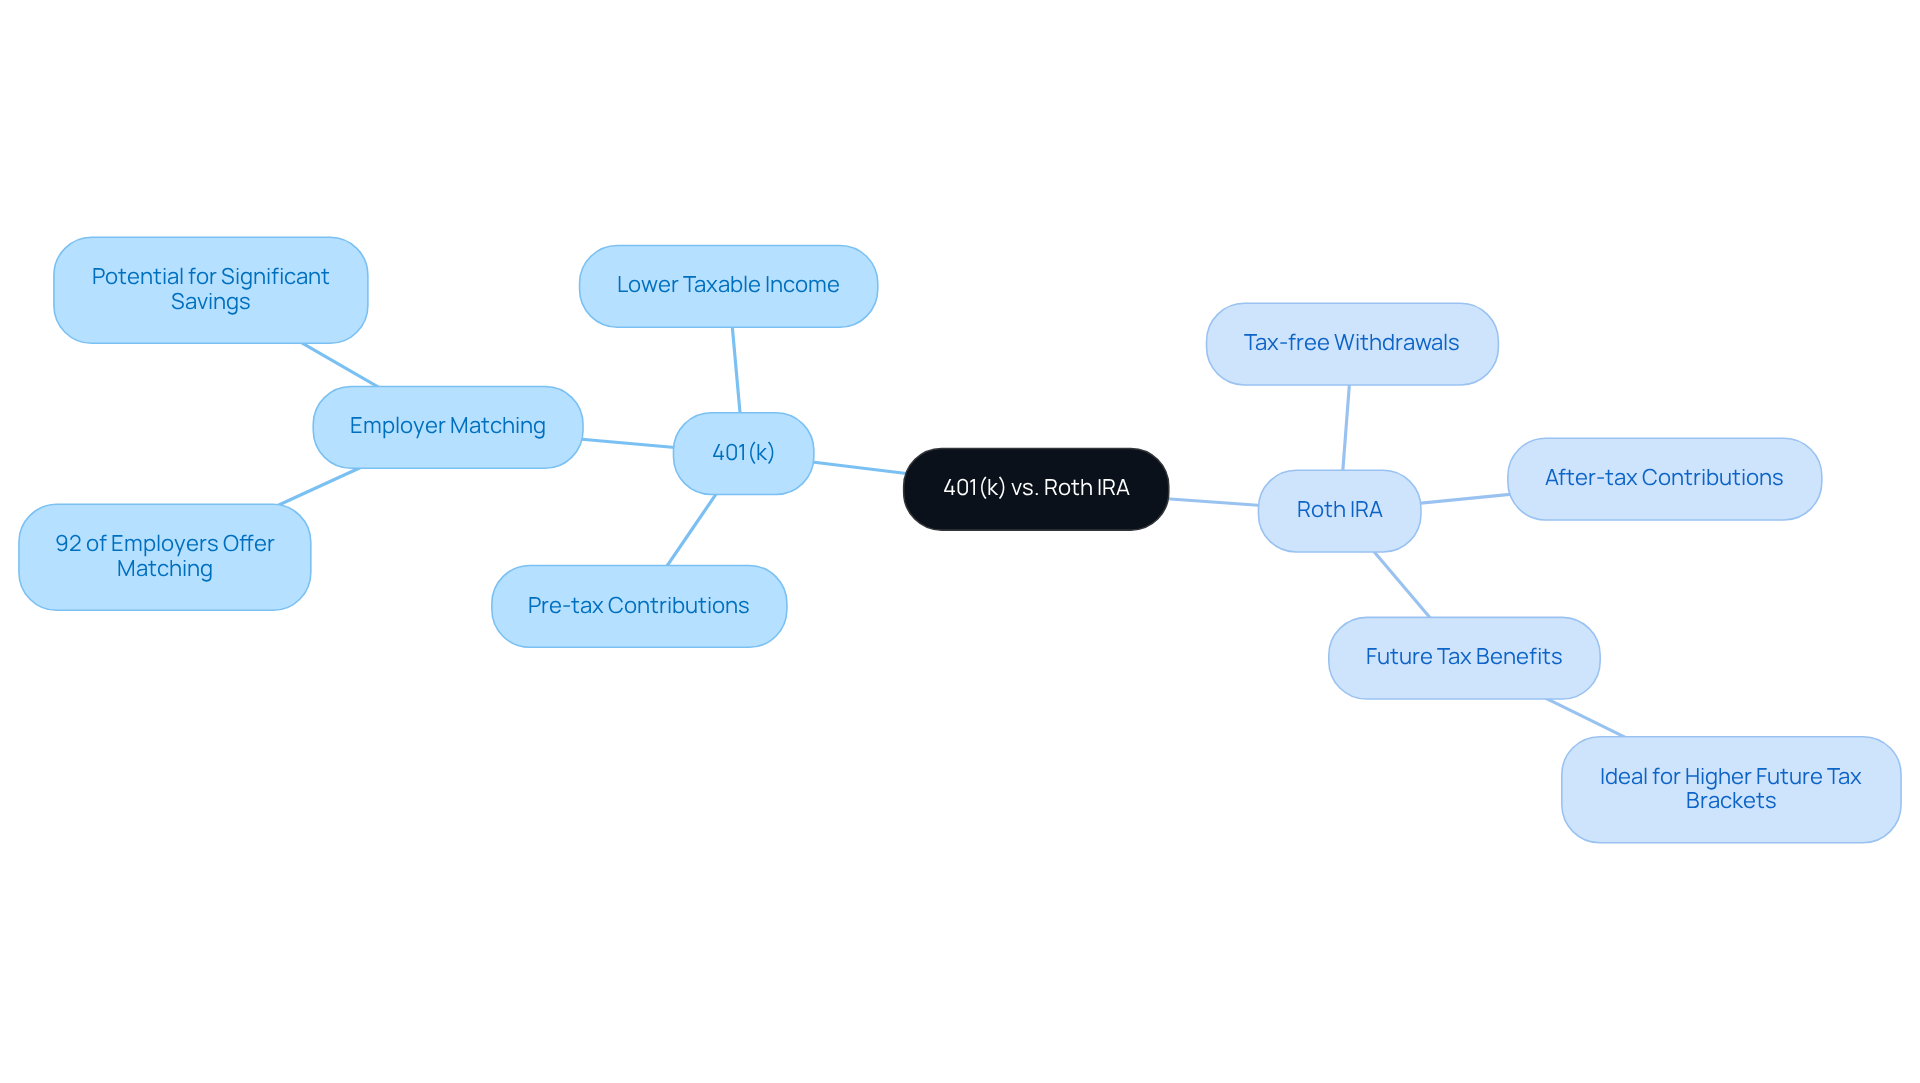
Imagine planning for your family’s future with confidence. A 401(k) is an employer-sponsored savings plan that facilitates funding 401(k)s and Roth IRAs by allowing you to set aside a portion of your paycheck before taxes are taken out. This pre-tax contribution not only lowers your taxable income for the year but often comes with employer matching funds, which can significantly boost your savings for what lies ahead. In 2026, about 92% of employers with 401(k) plans offer matching contributions, making this a popular choice for many families.
On the other hand, funding 401(k)s and Roth IRAs involves contributing after-tax dollars to a Roth IRA, which permits tax-free withdrawals during retirement. This feature can be especially beneficial for families who expect to be in a higher tax bracket later in life, offering flexibility and potential tax savings. Understanding these differences is crucial for families to choose the plan that aligns best with their financial goals, especially when it comes to funding 401(k)s and Roth IRAs.
For example, families anticipating a lower tax category after leaving the workforce might find a 401(k) more advantageous. In contrast, those expecting higher future income may prefer the tax-exempt growth of a Roth IRA. By evaluating their current and future financial situations, families can make informed decisions that support their long-term financial well-being.
At Bright Advisers, we empower young families like Jay and Emma, Emily and Mark, and Allison and Brian by providing personalized wealth management solutions. We focus on , ensuring you can navigate these options effectively. Together, we can embark on this journey toward a secure financial future.
Leverage Tax Advantages for Long-Term Growth
Are you feeling overwhelmed by the thought of saving for your family’s future? You’re not alone. The unique tax benefits of funding 401(k)s and Roth IRAs can significantly impact your savings journey.
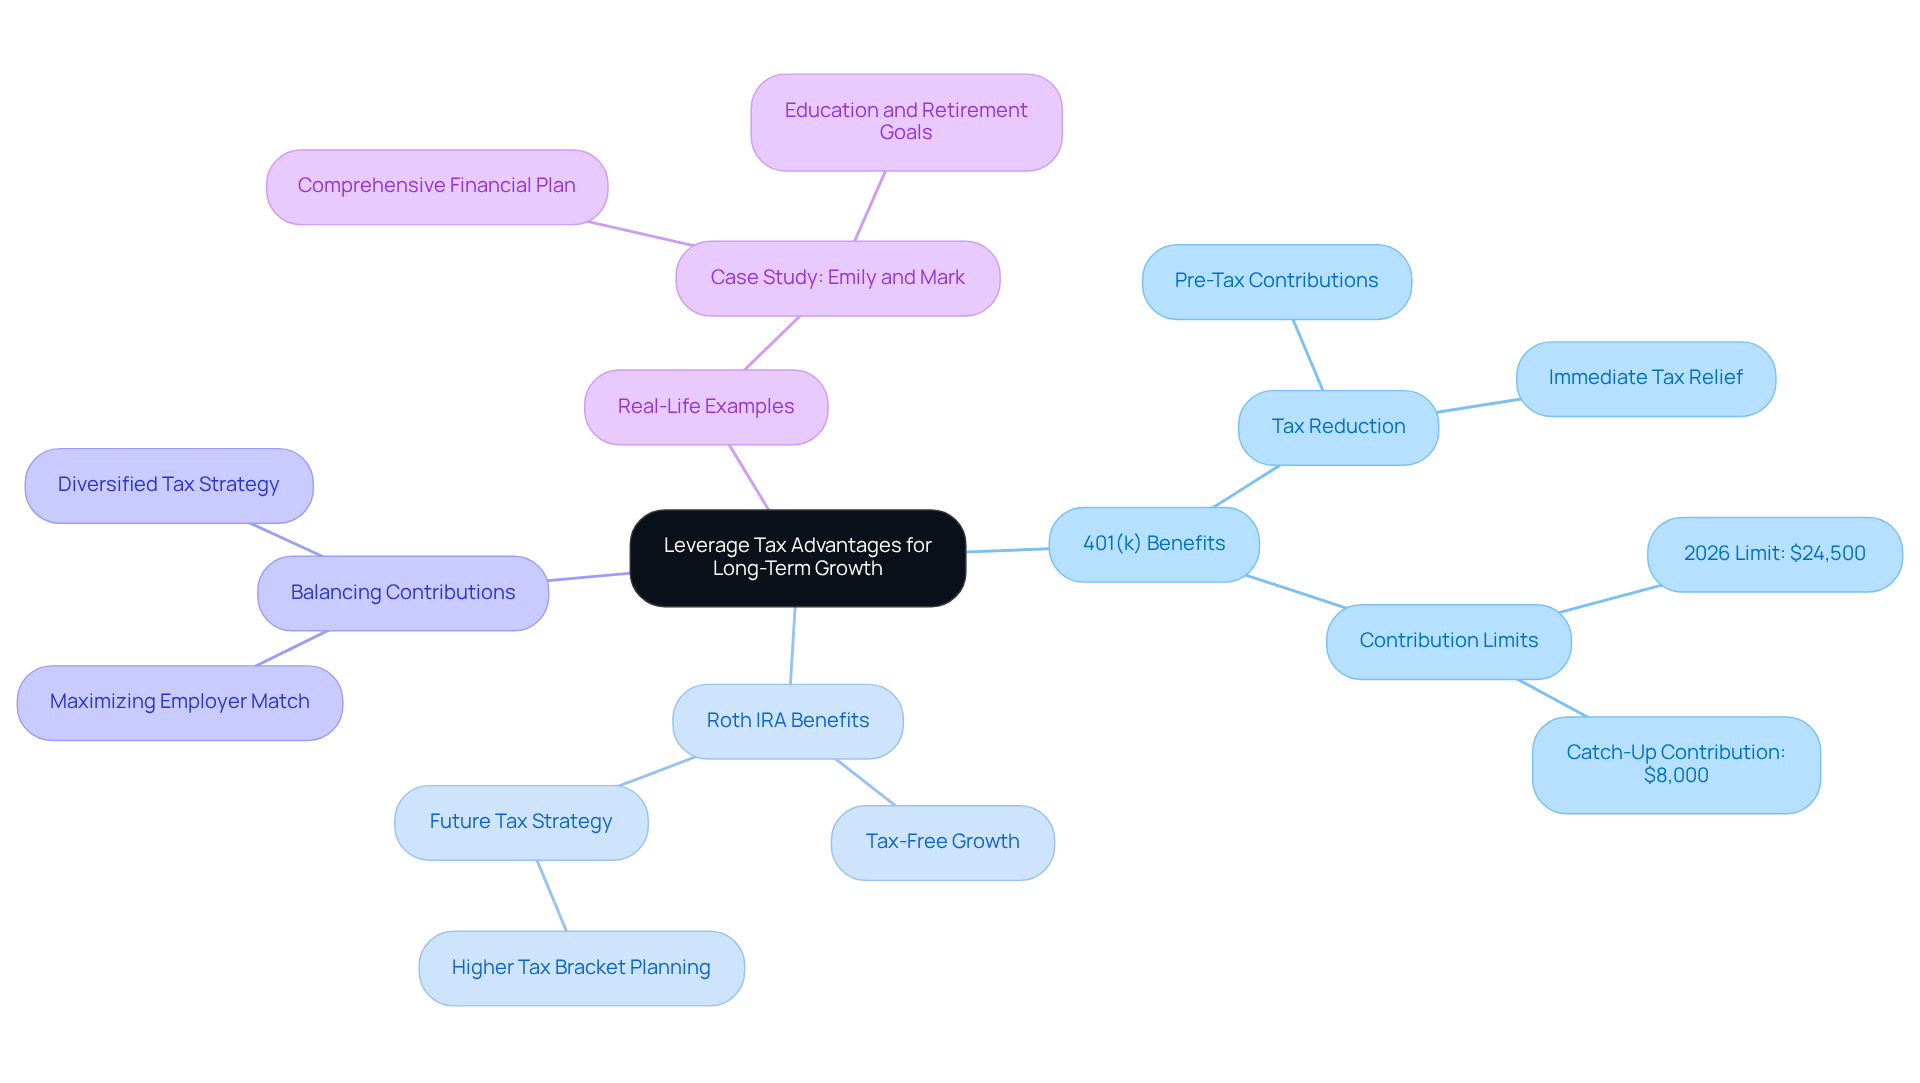
Imagine this: contributions to a 401(k) plan can reduce your taxable income, which means a lower tax bill for you this year. For 2026, the contribution limit has increased to $24,500, allowing for substantial pre-tax savings. On the other hand, families can benefit from funding 401(k)s and Roth IRAs, as they provide tax-free growth and withdrawals, especially for those expecting to be in a higher tax bracket later on.
By thoughtfully balancing contributions through funding 401(k)s and Roth IRAs, you can optimize your tax situation and enhance your overall savings. For instance, maximizing employer matching in a 401(k) while funding 401(k)s and Roth IRAs creates a diversified tax strategy that strengthens your long-term financial security. This approach allows you to benefit from immediate tax assistance while preparing for tax-exempt income in the future, aligning perfectly with your family’s financial goals.
At Bright Advisers, we understand the challenges families face. We’ve successfully guided families like Emily and Mark, who wanted to ease their financial worries and . By partnering with us, they developed a comprehensive financial plan that empowered them to achieve their dreams and gain the freedom to choose whether or not to continue working.
Remember, we’re here for you. Together, we can navigate this journey toward a secure and fulfilling future for your family.
Implement Effective Funding Strategies
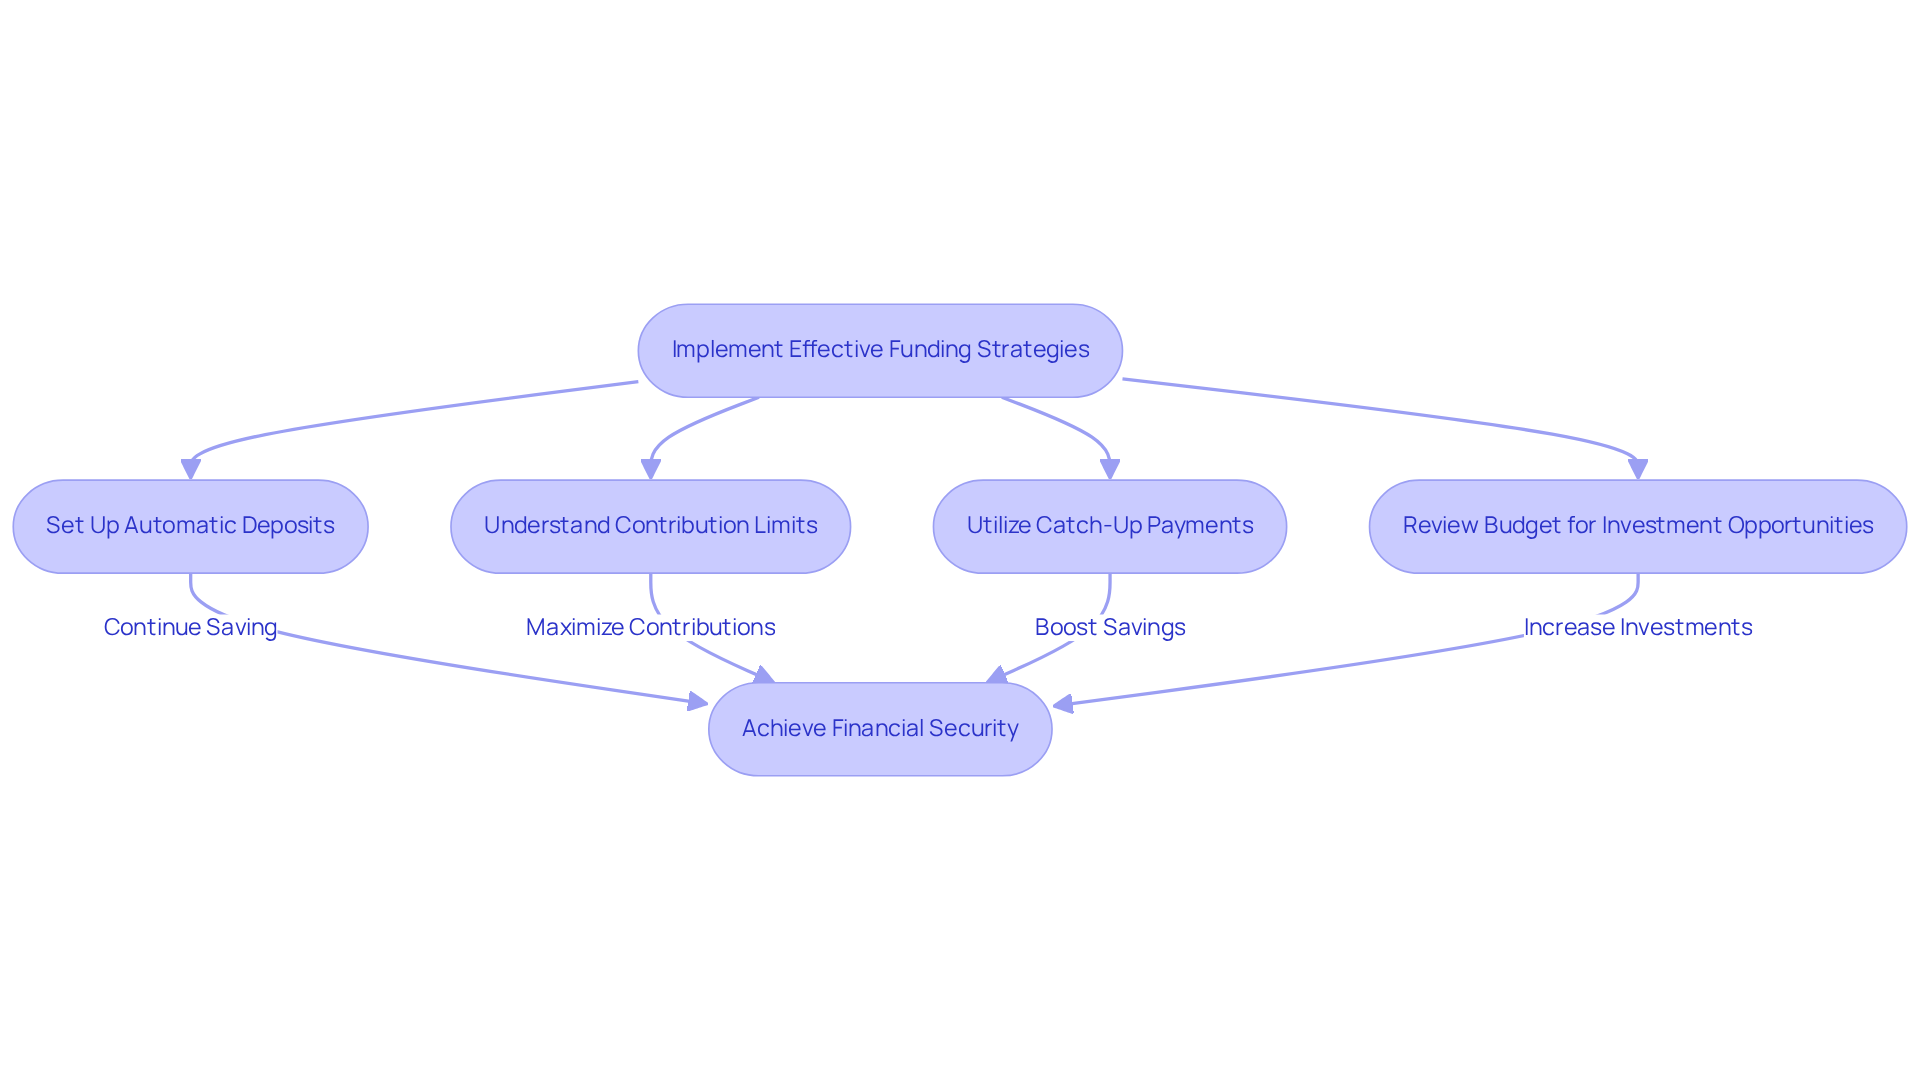
Imagine if you could effortlessly secure your family’s financial future. Setting up automatic deposits from your paycheck into funding 401(k)s and Roth IRAs can help make that dream a reality. This simple strategy not only encourages consistent saving but also helps you resist the urge to spend elsewhere.
Starting in 2026, the maximum contribution limit for a 401(k) will increase to $24,500, while the IRA limit will rise to $7,500. If you’re 50 or older, you can contribute up to $8,600, which includes a catch-up amount of $1,100. These limits are there for you to take advantage of, especially if you qualify for Roth IRA contributions. Think about it: by utilizing catch-up payments, you can significantly boost your savings for the years ahead.
Regularly reviewing your budget can reveal opportunities for greater investments, further enhancing your future savings. Financial advisors emphasize that automatic deposits are crucial for funding 401(k)s and Roth IRAs, as they not only simplify the saving process but also help families stay focused on their long-term financial goals.
Consider the success story of Jay and Emma. They managed to finance their future through personalized strategies with Bright Advisers. By establishing automatic payments, they optimized their tax situation and secured funding for their children’s education, striking a balance between current responsibilities and future aspirations.
Together, we can navigate this journey toward financial security. We’re here for you, ready to support you in making the most of your family’s .
Review and Adjust Retirement Plans Regularly
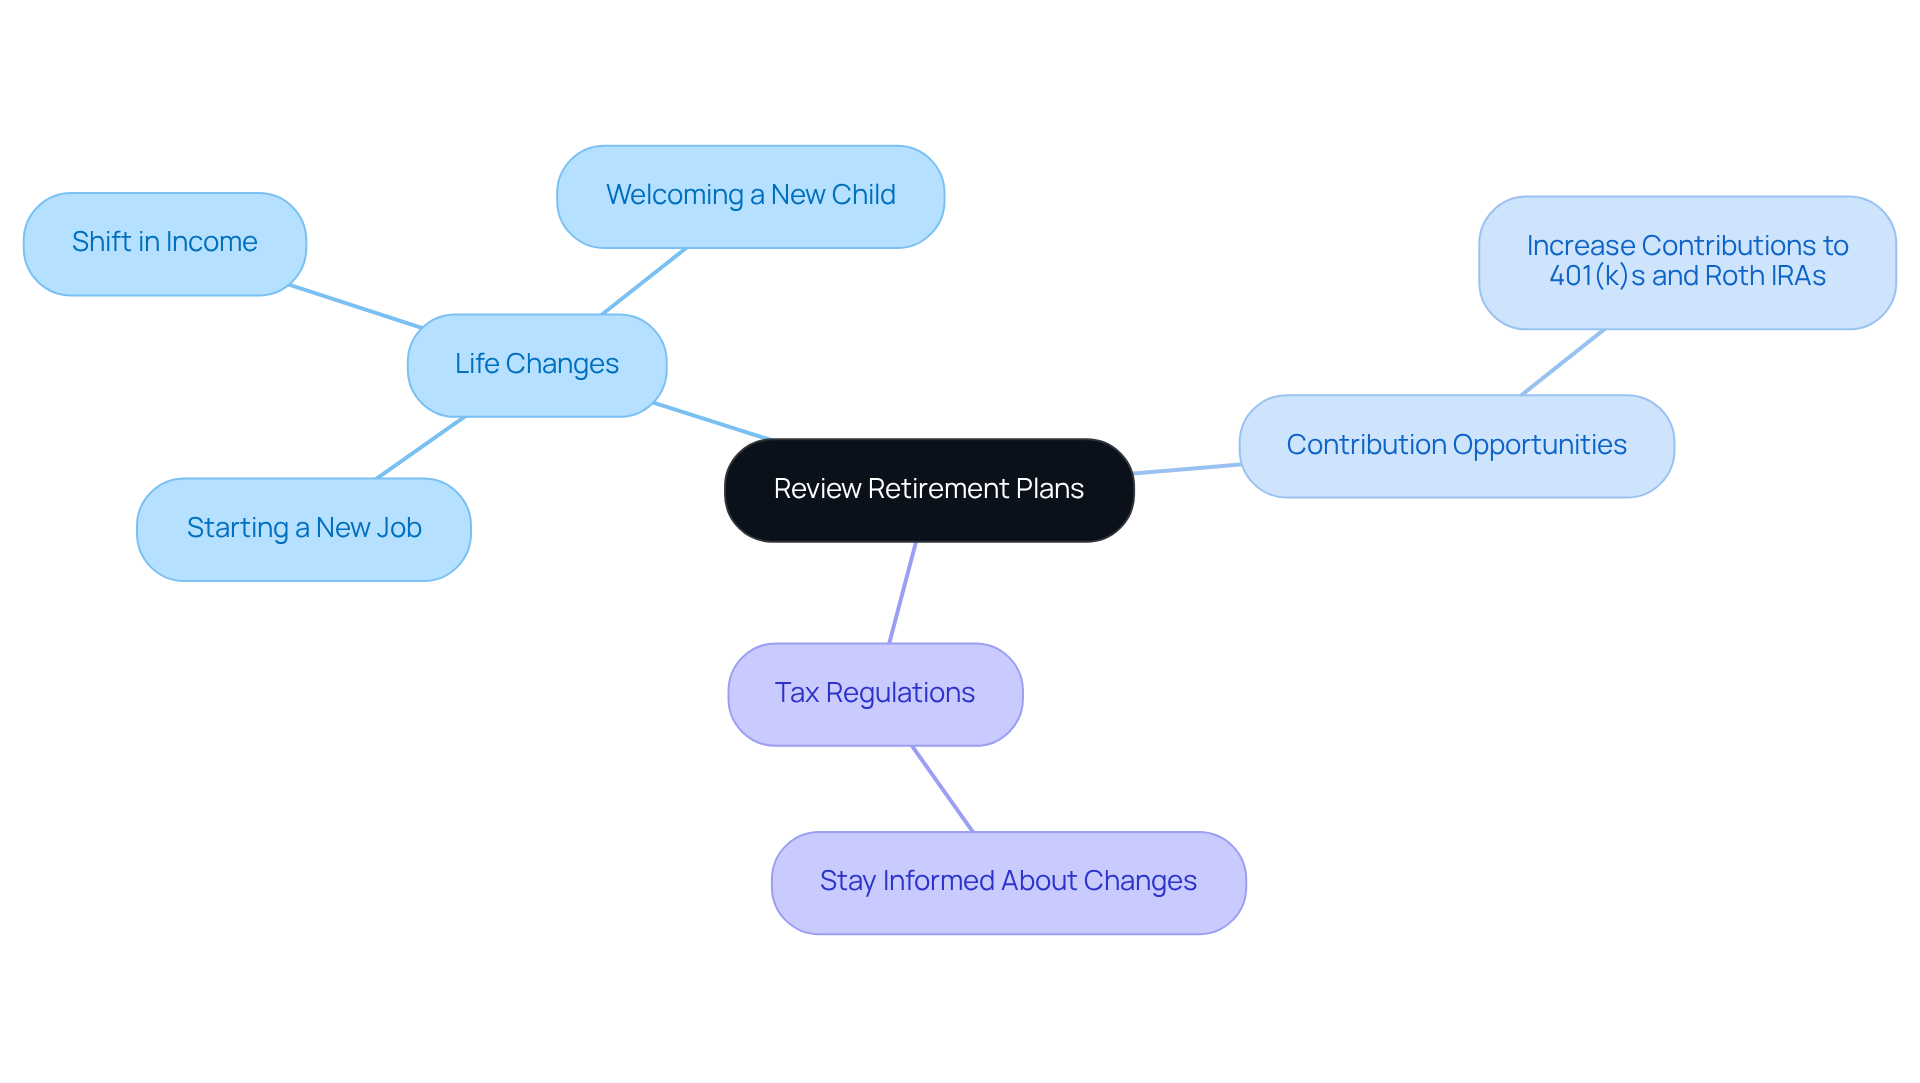
As a family, it’s essential to take a moment each year to review your retirement plans, especially during significant life changes like:
- Starting a new job
- Experiencing a shift in income
- Welcoming a new child
These evaluations are not just numbers on a page; they’re about understanding your family’s needs and aspirations.
Imagine if your earnings increase – this could be a wonderful opportunity for funding 401(k)s and Roth IRAs by boosting your contributions. In fact, recent data shows that in 2020, 92.1% of 401(k)-style account holders actively contributed to their accounts. This highlights just how vital regular involvement in savings is for securing your family’s future.
It’s also important to stay informed about changes in tax regulations that could impact your savings accounts, including contribution limits and tax benefits. Flexibility and awareness can empower you to navigate the complexities of retirement planning. Remember, we’re here for you, helping you stay on track to achieve your long-term financial goals. Together, we can navigate this journey and is bright.
Conclusion
Mastering the details of 401(k)s and Roth IRAs is crucial for families looking to secure their financial future. By understanding what makes each retirement plan unique, families can make informed choices that align with their long-term goals. The decision between a 401(k) and a Roth IRA depends on personal circumstances, like current income and future tax expectations, so it’s important to evaluate these factors thoughtfully.
Throughout this article, we’ve highlighted key strategies for funding these retirement accounts. The advantages of employer matching contributions, the significance of tax benefits, and the importance of consistent contributions have all been emphasized. Plus, setting up automatic deposits and regularly reviewing retirement plans are essential practices that can lead to greater financial security. These strategies not only boost savings but also help families navigate the complexities of retirement planning with confidence.
Ultimately, taking proactive steps toward funding 401(k)s and Roth IRAs can pave the way for a more secure and fulfilling future. We encourage families to assess their financial situations, take advantage of available tax benefits, and seek personalized guidance to optimize their retirement strategies. By committing to these practices, families can build a strong financial foundation that supports their dreams and ensures a brighter tomorrow. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What is a 401(k)?
A 401(k) is an employer-sponsored savings plan that allows employees to set aside a portion of their paycheck before taxes are taken out, which lowers their taxable income for the year.
What are the benefits of a 401(k)?
The benefits of a 401(k) include tax-deferred growth on savings, potential employer matching contributions, and a reduction in taxable income for the year.
What is a Roth IRA?
A Roth IRA is an individual retirement account that allows individuals to contribute after-tax dollars, enabling tax-free withdrawals during retirement.
How does a Roth IRA benefit families?
A Roth IRA can be particularly beneficial for families who expect to be in a higher tax bracket in the future, as it offers tax-exempt growth and flexibility for withdrawals during retirement.
How can families decide between a 401(k) and a Roth IRA?
Families can decide between a 401(k) and a Roth IRA by evaluating their current and future financial situations, including their expected tax brackets after retirement.
What percentage of employers offer matching contributions for 401(k) plans?
In 2026, about 92% of employers with 401(k) plans offer matching contributions.
What is the focus of Bright Advisers in terms of financial planning?
Bright Advisers focuses on empowering young families by providing personalized wealth management solutions, ensuring financial security and educational preparedness.
List of Sources
- Understand 401(k) and Roth IRA Basics
- Key 401(k) Statistics: Retirement Plans by the Numbers | ForUsAll Blog (https://forusall.com/401k-blog/401k-statistics)
- The Average 401(k) Balance by Age (https://tha.org/blog/the-average-401k-balance-by-age)
- One in Four Workers Miss Out on Full 401(k) Match (https://shrm.org/topics-tools/news/benefits-compensation/one-four-workers-miss-full-401k-match)
- Average retirement savings by age | Fidelity (https://fidelity.com/learning-center/personal-finance/average-retirement-savings)
- Is Roth Better Than 401(k)? Key Insights for Young Families – Bright Advisers (https://brightadvisers.com/is-roth-better-than-401-k-key-insights-for-young-families)
- Leverage Tax Advantages for Long-Term Growth
- 401(k) contribution limits 2025 and 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/401k-contribution-limits)
- 401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500 | Internal Revenue Service (https://irs.gov/newsroom/401k-limit-increases-to-24500-for-2026-ira-limit-increases-to-7500)
- How 401(k) Contributions Reduce Your Taxable Income for Families – Bright Advisers (https://brightadvisers.com/how-401-k-contributions-reduce-your-taxable-income-for-families)
- 56 Important Retirement Plan Statistics For 2026 – Carry (https://carry.com/learn/retirement-plan-statistics)
- Implement Effective Funding Strategies
- 13 Quotes to Help Plan for Retirement | The Motley Fool (https://fool.com/retirement/2020/06/25/13-quotes-to-help-plan-for-retirement.aspx)
- The Average IRA Balance by Age and Generation (https://kiplinger.com/retirement/iras/the-average-ira-balance-by-age)
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/retirement/learn/retirement-statistics)
- Report on the Economic Well-Being of U.S. Households in 2024 – May 2025 – Savings and Investments (https://federalreserve.gov/publications/2025-economic-well-being-of-us-households-in-2024-savings-and-investments.htm)
- Average Retirement Savings in 2026: How Do You Compare? | The Motley Fool (https://fool.com/research/average-retirement-savings)
- Review and Adjust Retirement Plans Regularly
- 35 Retirement Quotes for a Happy, Healthy, and Wealthy Life (https://ruleoneinvesting.com/blog/personal-development/retirement-quotes)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- New Data Reveal Inequality in Retirement Account Ownership (https://census.gov/library/stories/2022/08/who-has-retirement-accounts.html)
- More Than Half of U.S. Households Have Retirement Accounts, CRS Says (https://asppa-net.org/news/2025/3/more-than-half-of-u.s.-households-have-retirement-accounts-crs-says)
- What Percentage of Americans Have a Retirement Savings Account? (https://news.gallup.com/poll/691202/percentage-americans-retirement-savings-account.aspx)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading