

Key Highlights
- An Irrevocable Life Insurance Trust (ILIT) secures life insurance benefits for families, protecting them from taxes and ensuring financial stability.
- Starting in 2026, families can pass on up to $15 million without tax implications, making it essential to plan ahead for ILITs.
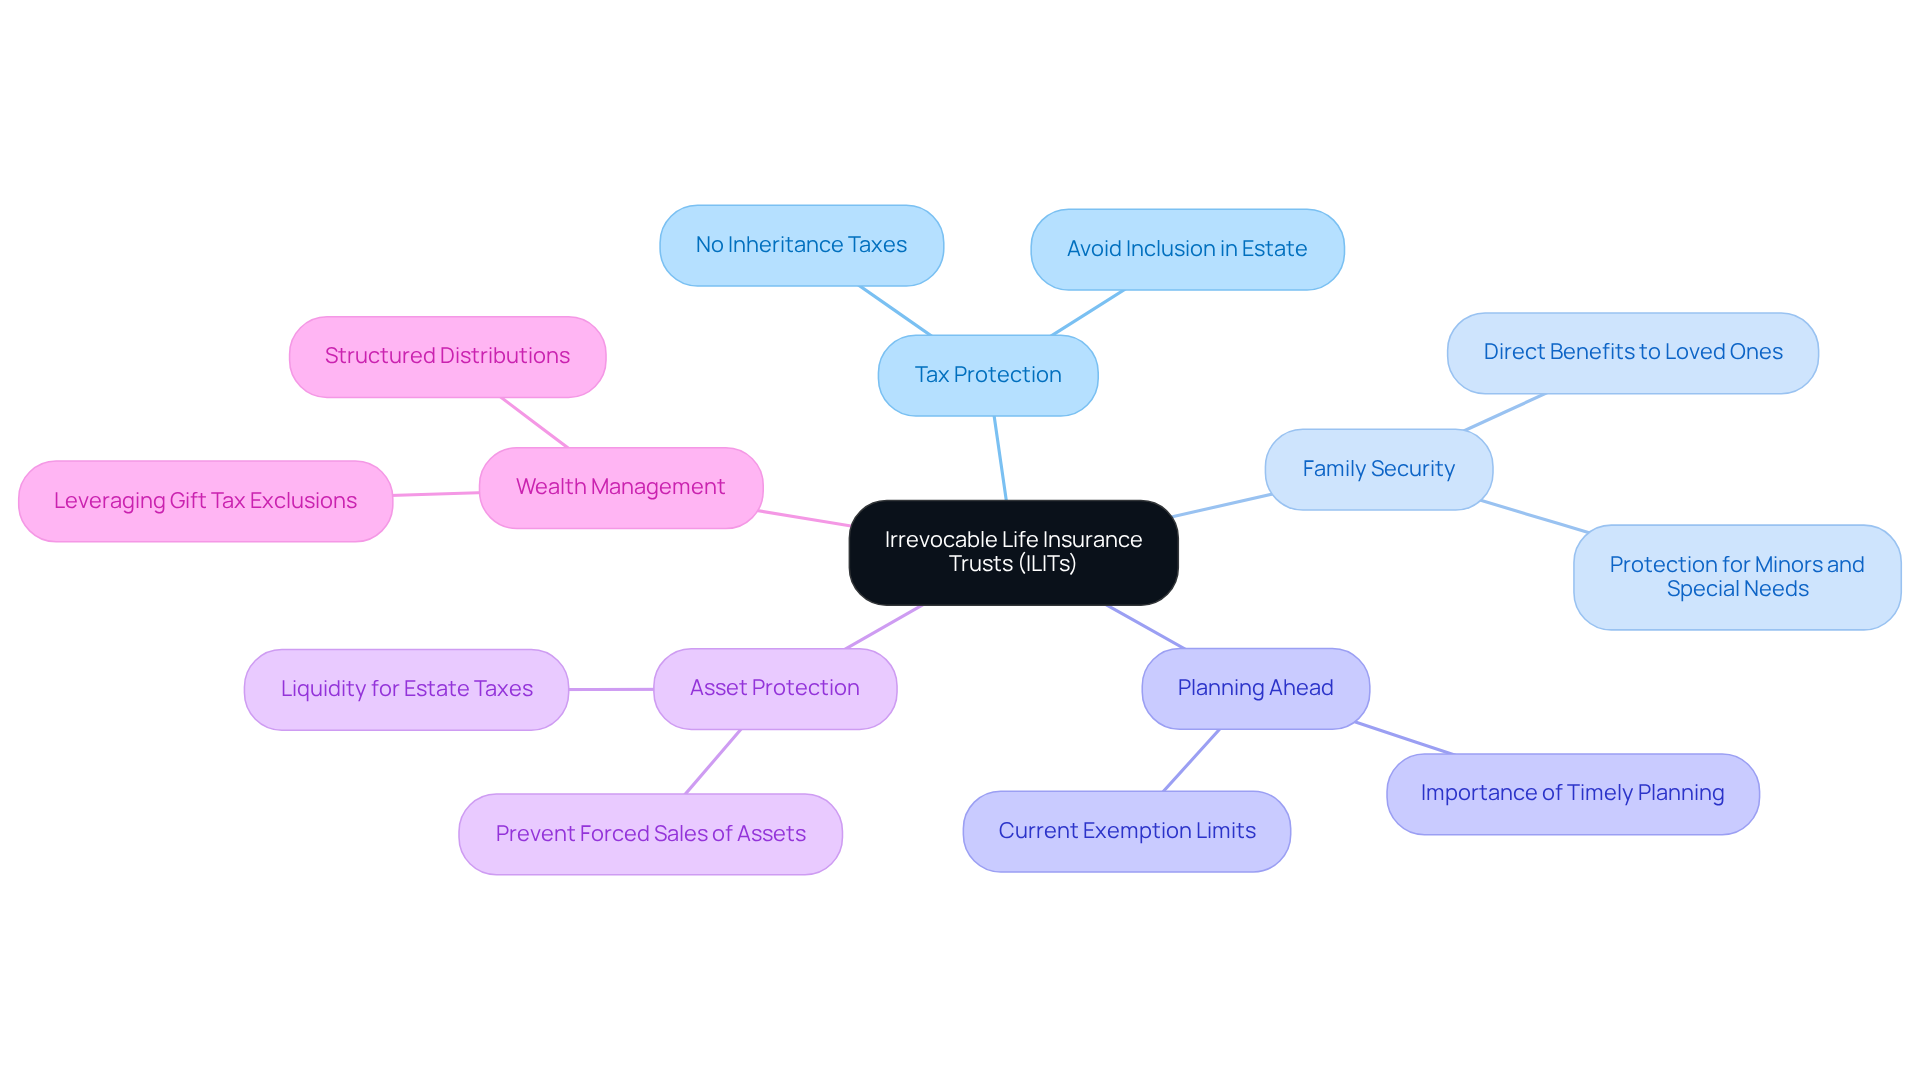
- ILITs provide liquidity for inheritance taxes, preventing the need to sell valuable assets like homes.
- Benefits of ILITs include asset protection from creditors, control over distribution to beneficiaries, and support for special needs children.
- ILITs help avoid probate, allowing beneficiaries quick access to funds without delays or costs.
- Once established, ILITs cannot be changed or revoked, which may limit flexibility for families as circumstances evolve.
- Setting up an ILIT can cost between $2,000 to $5,000, requiring careful planning and legal assistance.
- Families should appoint a responsible trustee to manage the ILIT and ensure compliance with IRS regulations.
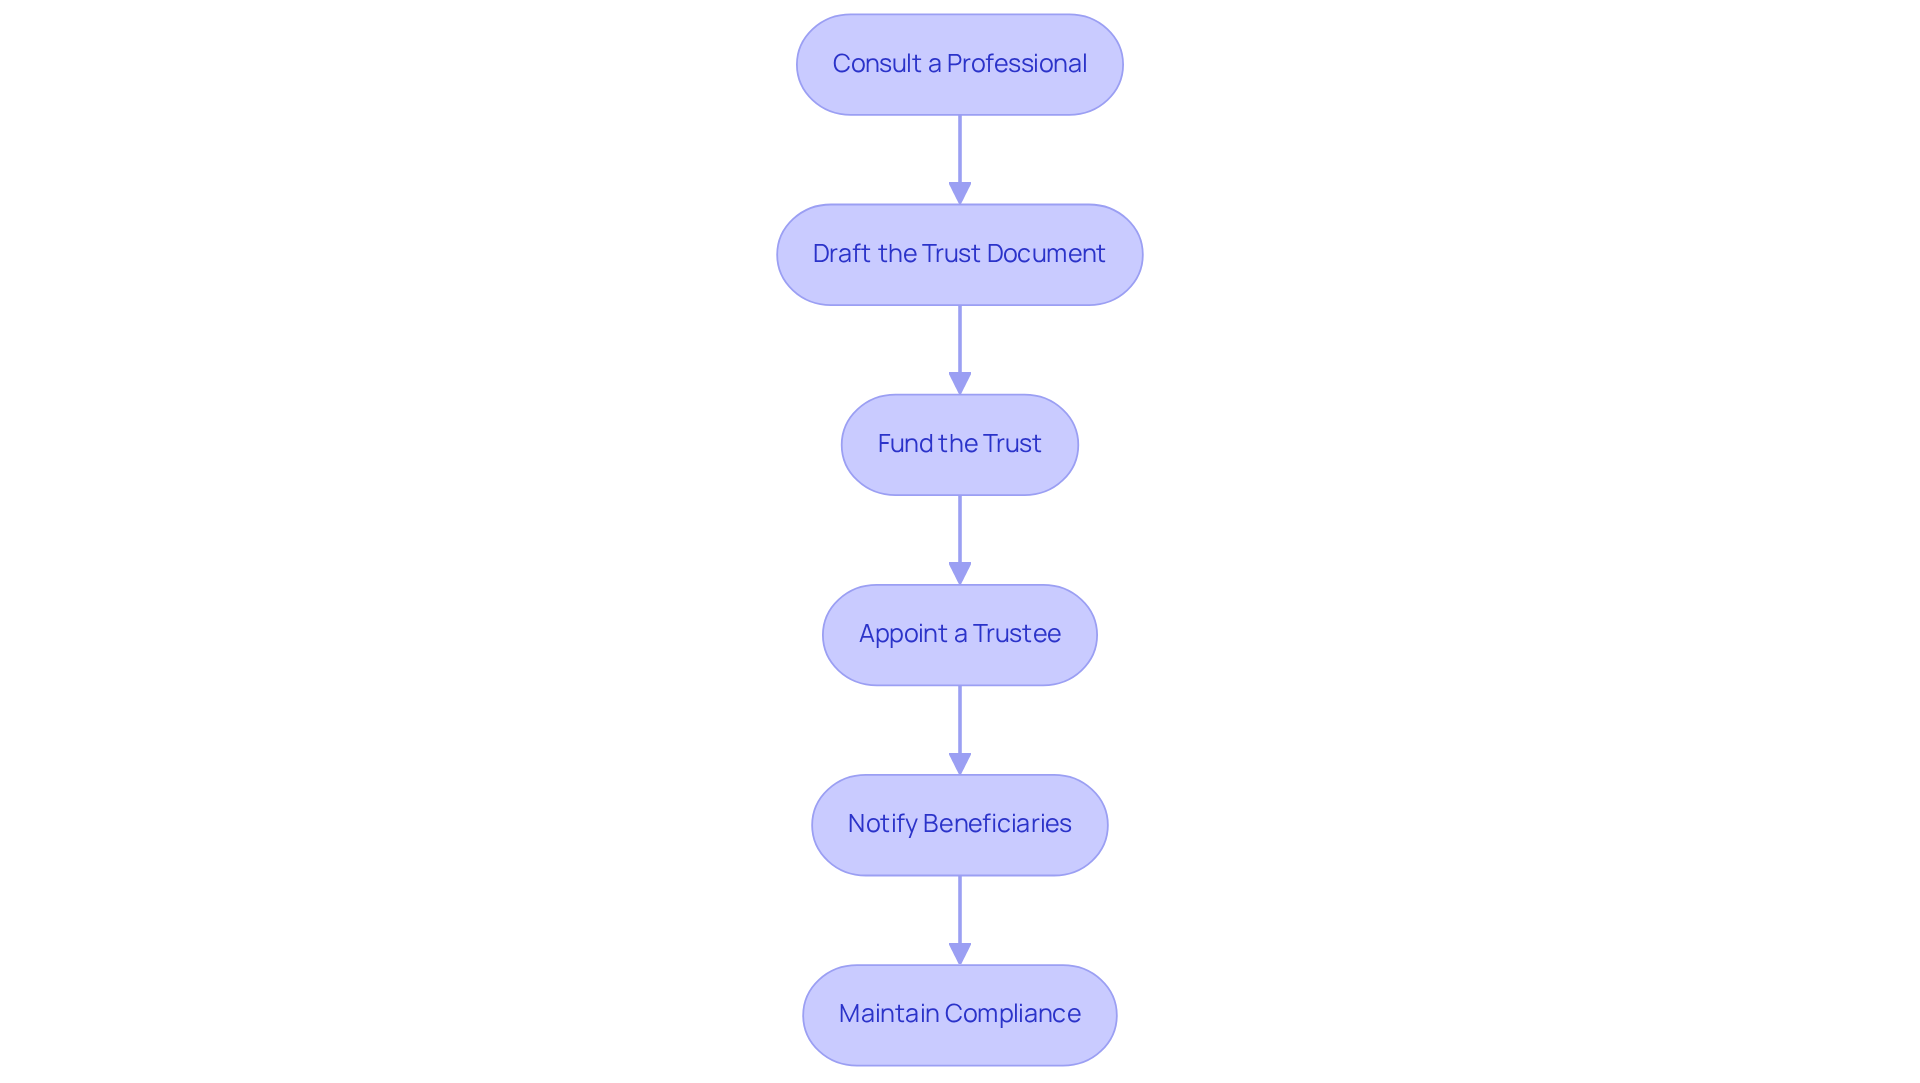
- Steps to establish an ILIT include consulting a professional, drafting the trust document, funding the trust, and maintaining compliance.
Introduction
Many families worry about what will happen to their loved ones if financial challenges arise. Irrevocable Life Insurance Trusts (ILITs) offer a powerful solution for families seeking to protect their wealth while navigating the complexities of estate planning. As tax laws evolve and the stakes rise, it’s important to understand how families can effectively leverage ILITs to shield their loved ones from financial burdens. Together, we can explore how ILITs can protect your family’s financial future, highlighting their benefits and what to watch out for.
Define Irrevocable Life Insurance Trusts (ILITs)
Imagine the peace of mind that comes from knowing your family’s future is secure, even in uncertain times. An Irrevocable Life Insurance Trust (ILIT) helps keep life insurance policies safe from taxes, ensuring your family’s future is secure. Once you set it up, you can rest easy knowing that the benefits from your life insurance go directly to your loved ones, free from taxes and worries. This structure is especially beneficial for families who want to protect their children’s financial future without facing hefty tax implications.
Starting in 2026, families can pass on up to $15 million without tax worries, but it’s crucial to plan ahead. The current property tax exemption is expected to be cut in half by the end of 2025, making now the perfect time to consider establishing or adding to an ILIT grantor trust. If you have appreciating assets or a growing business, this could be a vital step in securing your family’s legacy.
Imagine a family who used an ILIT to cover inheritance taxes without selling their cherished home – this is the power of planning. ILITs not only provide liquidity for inheritance duties but also protect your loved ones from having to sell valuable assets. They ensure that distributions are organized and that inheritances are safeguarded, especially for minors or individuals with special needs.
As wealth management evolves, the importance of the ILIT grantor trust remains strong. By taking these steps now, you can ensure your loved ones are protected, allowing you to focus on what truly matters – your family’s happiness.
Explore Benefits of ILITs for Young Families
Imagine a future where your family is financially secure, even in the face of changing tax laws.
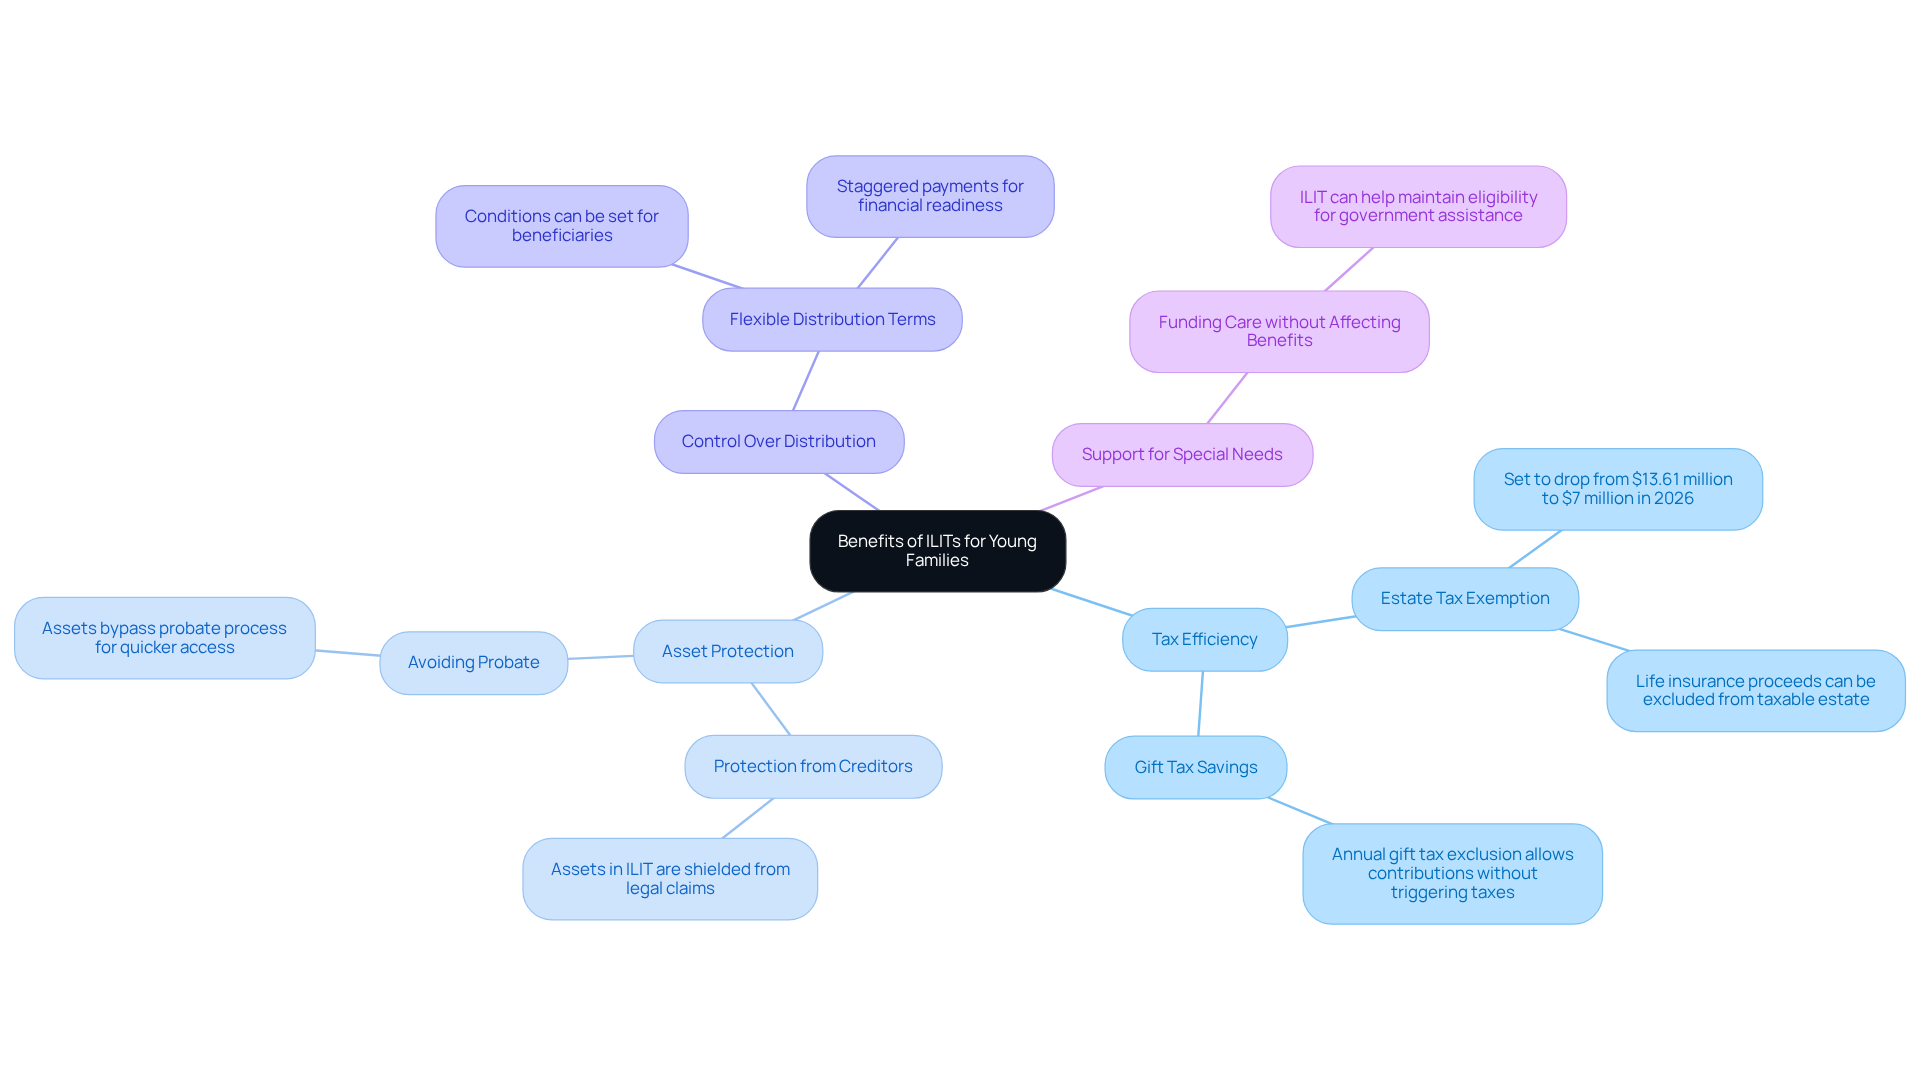
Tax efficiency can be enhanced with an ILIT grantor trust, enabling you to pass on more to your loved ones without the concern of heavy taxes, especially as the estate tax exemption is set to drop significantly in 2026. This means you can ensure that your family receives the support they need without the burden of taxation.
- Asset Protection: The assets in an ILIT grantor trust are protected from creditors and legal claims, ensuring your family’s financial legacy remains safe. This is especially important if you’re concerned about potential financial conflicts that could affect your heirs.
- Control Over Distribution: With an ILIT grantor trust, you can decide how and when your loved ones receive their life insurance benefits, providing you with peace of mind. This flexibility is particularly beneficial for families with young children or beneficiaries who may not yet be financially responsible. You can set conditions or stagger distributions to ensure they’re ready.
- Support for Special Needs: If you have children with special needs, an ILIT grantor trust can help fund their care without risking their eligibility for government assistance. This thoughtful planning secures their future while ensuring they have access to necessary support services.
- Avoiding Probate: Avoiding probate is achievable since assets in an ILIT grantor trust bypass the probate process, enabling your beneficiaries to access funds quickly and without the associated costs and delays. This efficiency is crucial for families needing immediate liquidity to manage expenses, ensuring your loved ones aren’t left in financial uncertainty.
By considering an ILIT grantor trust, you’re taking a significant step toward safeguarding your family’s financial future.
Assess Risks and Considerations of ILITs
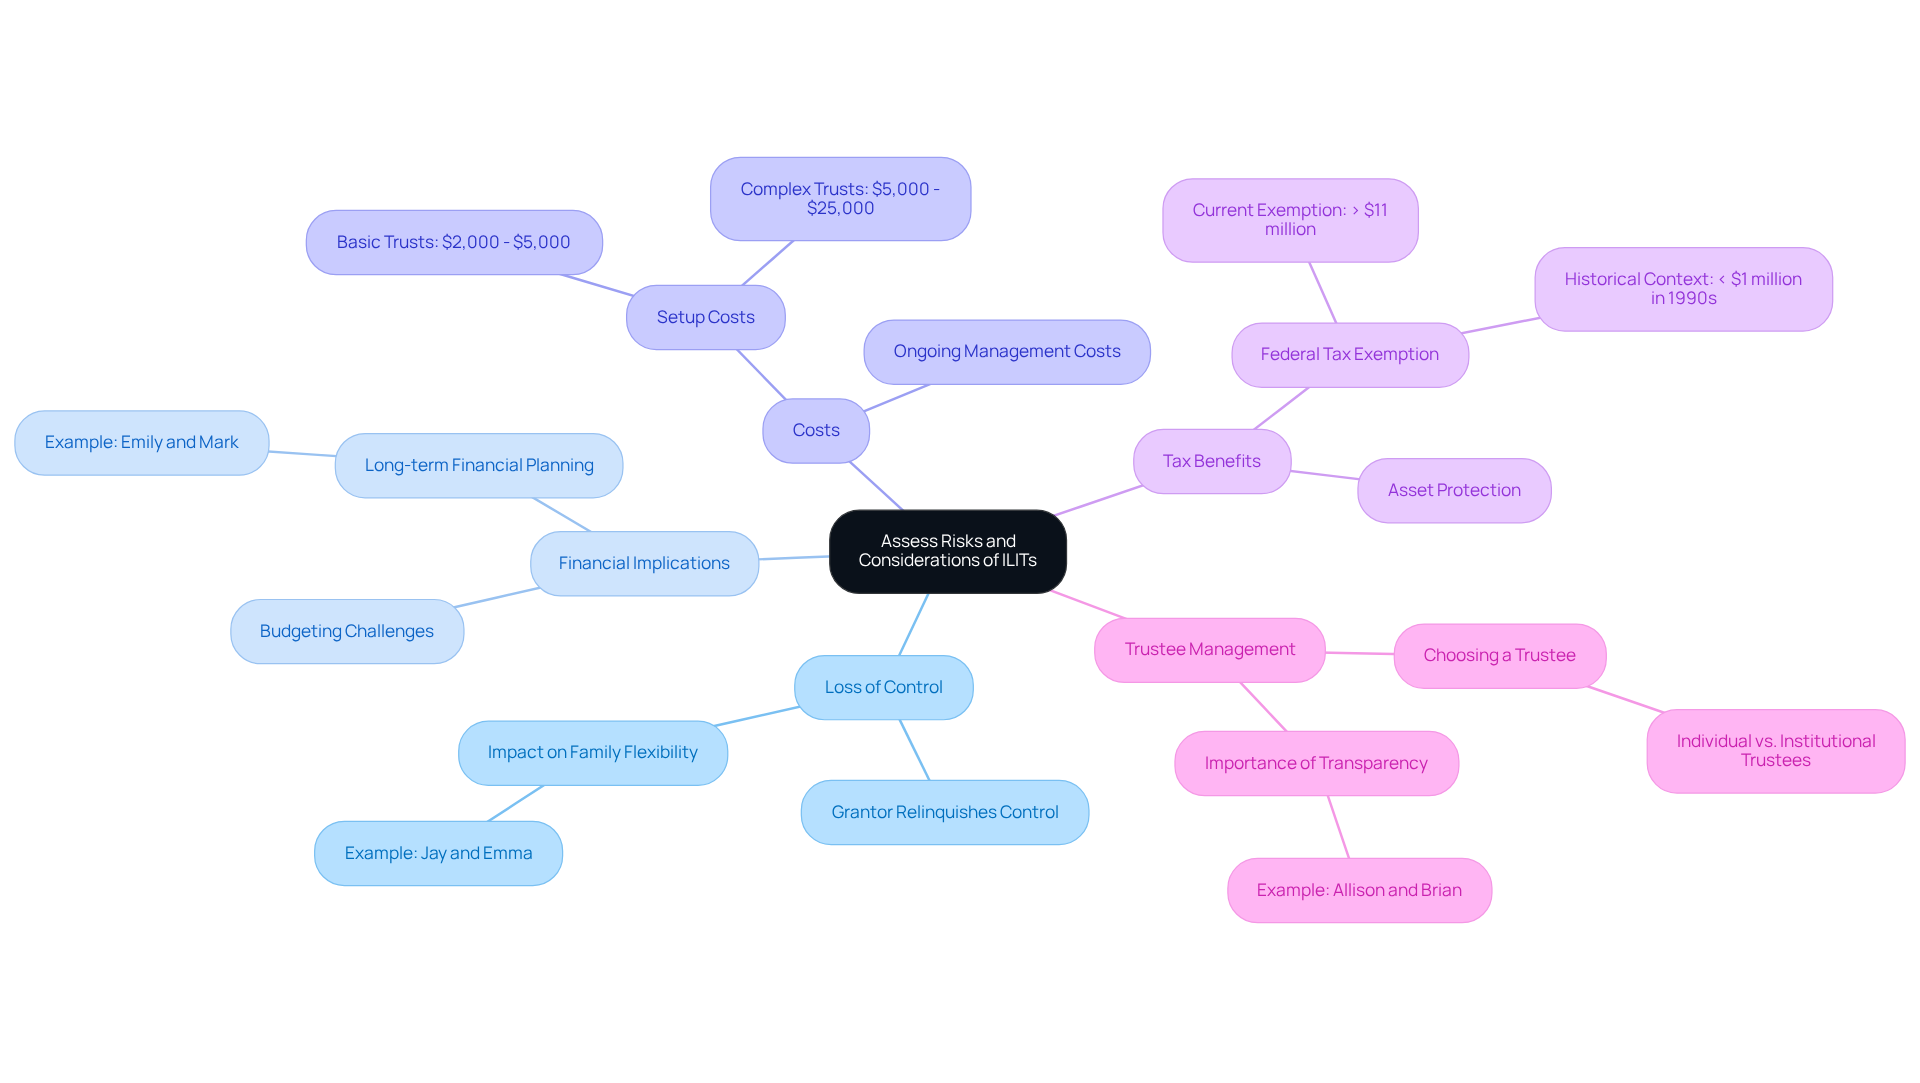
Imagine feeling locked into a decision that might not fit your family’s needs down the road. Once an ILIT grantor trust is established, the grantor cannot change or revoke it. This can leave families feeling uncertain about their financial future, especially when life changes are inevitable, like for households such as Jay and Emma, who are balancing monetary obligations while preparing for their children’s education and their retirement.
When you set up an ILIT grantor trust, you give up control over the assets, which can be tough for parents wanting to stay flexible with their finances. It’s a worry for many young parents who want to keep their budgeting in sync with their growing family’s needs.
Getting an ILIT set up can feel overwhelming and might need some legal help, which can add to the costs. You might find that setting one up can cost anywhere from $2,000 to $5,000, and more complex setups can go even higher. Families need to be prepared for the extra work that comes with managing a trust, just like Emily and Mark did with Bright Advisers to improve their financial situation.
ILIT grantor trusts can offer some tax perks, but they also require careful planning to remain compliant with IRS rules. It’s worth noting that the federal tax exemption is over $11 million, which is something to keep in mind for estate planning. Bright Advisers helps families like Allison and Brian make the most of their financial potential with smart tax strategies.
If the trustee isn’t careful, it could mean that the assets aren’t managed well, putting your family’s goals at risk. Sometimes, individual trustees can charge less than big banks, which is something families might want to consider when looking at costs. Bright Advisers emphasizes the importance of being responsible and transparent, so families get the support they need to manage their trusts and reach their financial goals.
Implement Steps to Establish an ILIT
Imagine the peace of mind that comes from knowing your family’s future is secure, even when you’re not there to protect them.
- Consult a Professional: Begin by engaging an estate planning attorney who specializes in trusts. Their expertise will ensure that your ilit grantor trust is established correctly and adheres to all legal requirements, safeguarding your family’s financial future.
- Draft the Trust Document: Work with your attorney to create a trust document that clearly states your wishes, names beneficiaries, and appoints a trustee. This way, your intentions are accurately reflected.
- Fund the Trust: You can either purchase a new life insurance policy or transfer an existing one into the ILIT. It’s crucial that the trust is named as both the owner and beneficiary of the policy to maximize tax benefits and ensure compliance with IRS regulations.
- Appoint a Trustee: Think about who in your life you trust to manage this important responsibility. This person will be responsible for managing the trust according to its terms and acting in the best interest of the beneficiaries, which is vital for the trust’s success.
- Notify Beneficiaries: Inform the beneficiaries about the ILIT and its purpose. Clear communication will help them understand how the ilit grantor trust will benefit them in the future, fostering transparency and trust.
- Maintain Compliance: Stay on top of necessary administrative tasks, such as filing gift tax returns and sending Crummey notices to beneficiaries. These actions are essential to ensure that the trust remains compliant with IRS regulations and retains its tax advantages.
Taking these steps today can safeguard your family’s tomorrow, ensuring they thrive even in your absence.
Conclusion
Imagine a future where your family’s financial security is assured, free from the worries of tax burdens and complications. Establishing an Irrevocable Life Insurance Trust (ILIT) is a proactive step toward that goal. This powerful estate planning tool can protect your assets from taxes, ensuring your loved ones receive the intended benefits without the burden of financial complications.
It’s crucial to plan ahead, especially with upcoming tax law changes that might affect how your wealth is passed on. Throughout this article, we’ve highlighted key benefits of ILITs, including:
- Tax efficiency
- Asset protection
- Control over distributions
- The ability to support special needs beneficiaries
These advantages can alleviate financial stress during challenging times.
Navigating the complexities of an irrevocable trust can feel daunting, but understanding these aspects is crucial for your family’s peace of mind. Remember, the avoidance of probate and the provision of liquidity for inheritance taxes are essential benefits that can ease your family’s journey.
Ultimately, the decision to create an ILIT grantor trust is significant and can profoundly impact your family’s legacy. Reaching out to a caring estate planning professional can help you feel supported as you navigate this important journey. When you take these steps, you’re not just planning for the future; you’re creating a legacy of love and support for generations to come.
Frequently Asked Questions
What is an Irrevocable Life Insurance Trust (ILIT)?
An Irrevocable Life Insurance Trust (ILIT) is a legal structure that helps keep life insurance policies safe from taxes, ensuring that the benefits from the policies go directly to your loved ones without tax implications.
How does an ILIT benefit families?
ILITs protect families from hefty tax implications on life insurance benefits, providing peace of mind that their financial future is secure. They also ensure liquidity for inheritance duties and protect valuable assets from being sold to cover taxes.
What changes are expected regarding property tax exemptions starting in 2026?
Starting in 2026, families will be able to pass on up to $15 million without tax worries, but the current property tax exemption is expected to be cut in half by the end of 2025. This makes it crucial to plan ahead.
Why is it important to establish or add to an ILIT grantor trust now?
Establishing or adding to an ILIT grantor trust now is important due to the anticipated reduction in property tax exemptions, which could impact families’ ability to pass on wealth without tax implications.
How can an ILIT help with inheritance taxes?
An ILIT can cover inheritance taxes, allowing families to avoid selling cherished assets, such as homes, to meet tax obligations. This ensures that inheritances are safeguarded and organized, especially for minors or individuals with special needs.
What is the overall mission of using an ILIT in wealth management?
The mission of using an ILIT in wealth management is to help families make wise wealth decisions and preserve their wealth across generations, ensuring that loved ones are protected and can focus on family happiness.
List of Sources
- Define Irrevocable Life Insurance Trusts (ILITs)
- The Ultimate Guide to Life Insurance for Estate Planning Using an Irrevocable Life Insurance Trust (https://mericleco.com/irrevocable-life-insurance-trust)
- What Is an Irrevocable Life Insurance Trust (ILIT)? (https://northwesternmutual.com/life-and-money/what-is-an-irrevocable-life-insurance-trust)
- Irrevocable Life Insurance Trusts: A Powerful Tool for Estate Planning and Liquidity | Trident Trust (https://tridenttrust.com/knowledge/insights/irrevocable-life-insurance-trusts-a-powerful-tool-for-estate-planning-and-liquidity)
- irrevocable life insurance trust (ILIT) (https://law.cornell.edu/wex/irrevocable_life_insurance_trust_(ilit))
- Explore Benefits of ILITs for Young Families
- The Ultimate Guide to Life Insurance for Estate Planning Using an Irrevocable Life Insurance Trust (https://mericleco.com/irrevocable-life-insurance-trust)
- How Young Parents Can Use Life Insurance to Cover Inheritance Tax – Bright Advisers (https://brightadvisers.com/how-young-parents-can-use-life-insurance-to-cover-inheritance-tax)
- Maximizing Your Estate Plan: Leveraging Irrevocable Life Insurance Trusts (ILITs) | Lawless, Edwards & Warren (https://lawlessedwardswarren.com/blog/maximizing-your-estate-plan-leveraging-irrevocable-life-insurance-trusts-ilits)
- How High-Net-Worth Families Strategically Use Life Insurance for Tax-Efficient Wealth Transfer (https://trcfinancial.com/post/how-high-net-worth-families-strategically-use-life-insurance-for-tax-efficient-wealth-transfer)
- Maximizing the Tax Benefits of Irrevocable Life Insurance Trusts (ILITs) (https://horizonlawca.com/maximizing-the-tax-benefits-of-irrevocable-life-insurance-trusts-ilits)
- Assess Risks and Considerations of ILITs
- Advantages and Disadvantages of an ILIT – Paramus, New Jersey Estate Litigation Attorneys and Estate Planning Lawyers (https://kneelaw.com/advantages-and-disadvantages-of-an-ilit)
- How Much Does It Cost to Set up an Irrevocable Trust? (https://offshore-protection.com/offshore-blog/how-much-does-it-cost-to-set-up-an-irrevocable-trust)
- Implement Steps to Establish an ILIT
- Irrevocable Life Insurance Trusts for Estate Planning (https://glenmede.com/insights-private-wealth/irrevocable-life-insurance-trusts-for-estate-planning)
- What Is an ILIT and Do You Need One in California? – Lawvex (https://lawvex.com/irrevocable-life-insurance-trust-ilit-guide)
- Five Things to Know Before You Create an ILIT – Pennington Law, PLLC (https://penningtonestateplanning.com/estate-planning/trusts/five-things-to-know-before-you-create-an-ilit)
- Irrevocable Life Insurance Trusts for High-Net-Worth Estate Planning (https://beckelderlaw.com/irrevocable-life-insurance-trusts-for-high-net-worth-estate-planning)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading