

Key Highlights
- Incentive Stock Options (ISOs) allow employees to purchase company shares at a predetermined exercise price, offering potential financial benefits.
- Key concepts include grant date, exercise price, expiration, and vesting period, which are crucial for understanding ISOs.
- 41% of employees do not utilise their options due to concerns about affordability and risks, highlighting the need for financial education.
- Strategies for managing ISOs include creating a calendar for important dates, setting alerts, conducting regular reviews, and educating family members.
- Only 30% of families have a long-term financial plan, emphasising the importance of proactive financial management.
- Tax implications of ISOs can be complex, with considerations for alternative minimum tax (AMT) and holding periods for favourable capital gains treatment.
- Families in high-tax states like California must understand specific state tax implications related to ISOs.
- Engaging a financial advisor with expertise in equity compensation can help families navigate the complexities of ISOs and develop tailored strategies.
- Bright Advisers focuses on fiduciary duty and transparency, providing personalised financial guidance to help families manage their stock options effectively.
Introduction
Imagine the relief of understanding how Incentive Stock Options (ISOs) can secure your family’s financial future. These options offer a unique chance to acquire company shares at a predetermined price, along with significant tax advantages when managed wisely.
However, many families feel overwhelmed by the ticking clock of their ISOs, unsure of how to make the most of this opportunity.
How can you ensure your family is maximizing the benefits of your ISOs while avoiding costly pitfalls? Together, we’ll explore essential strategies that can help your family take control of your financial decisions regarding stock options, paving the way for a secure and prosperous future.
Understand Incentive Stock Options: Key Concepts and Definitions
Imagine feeling uncertain about your financial future while juggling the needs of your family – this is where understanding Incentive Stock Options can make a difference. These options allow employees to buy company shares at a set price, known as the exercise price, and they can be a valuable part of your compensation package. When managed correctly, they offer significant tax advantages that can benefit your family.
Let’s break down some key concepts:
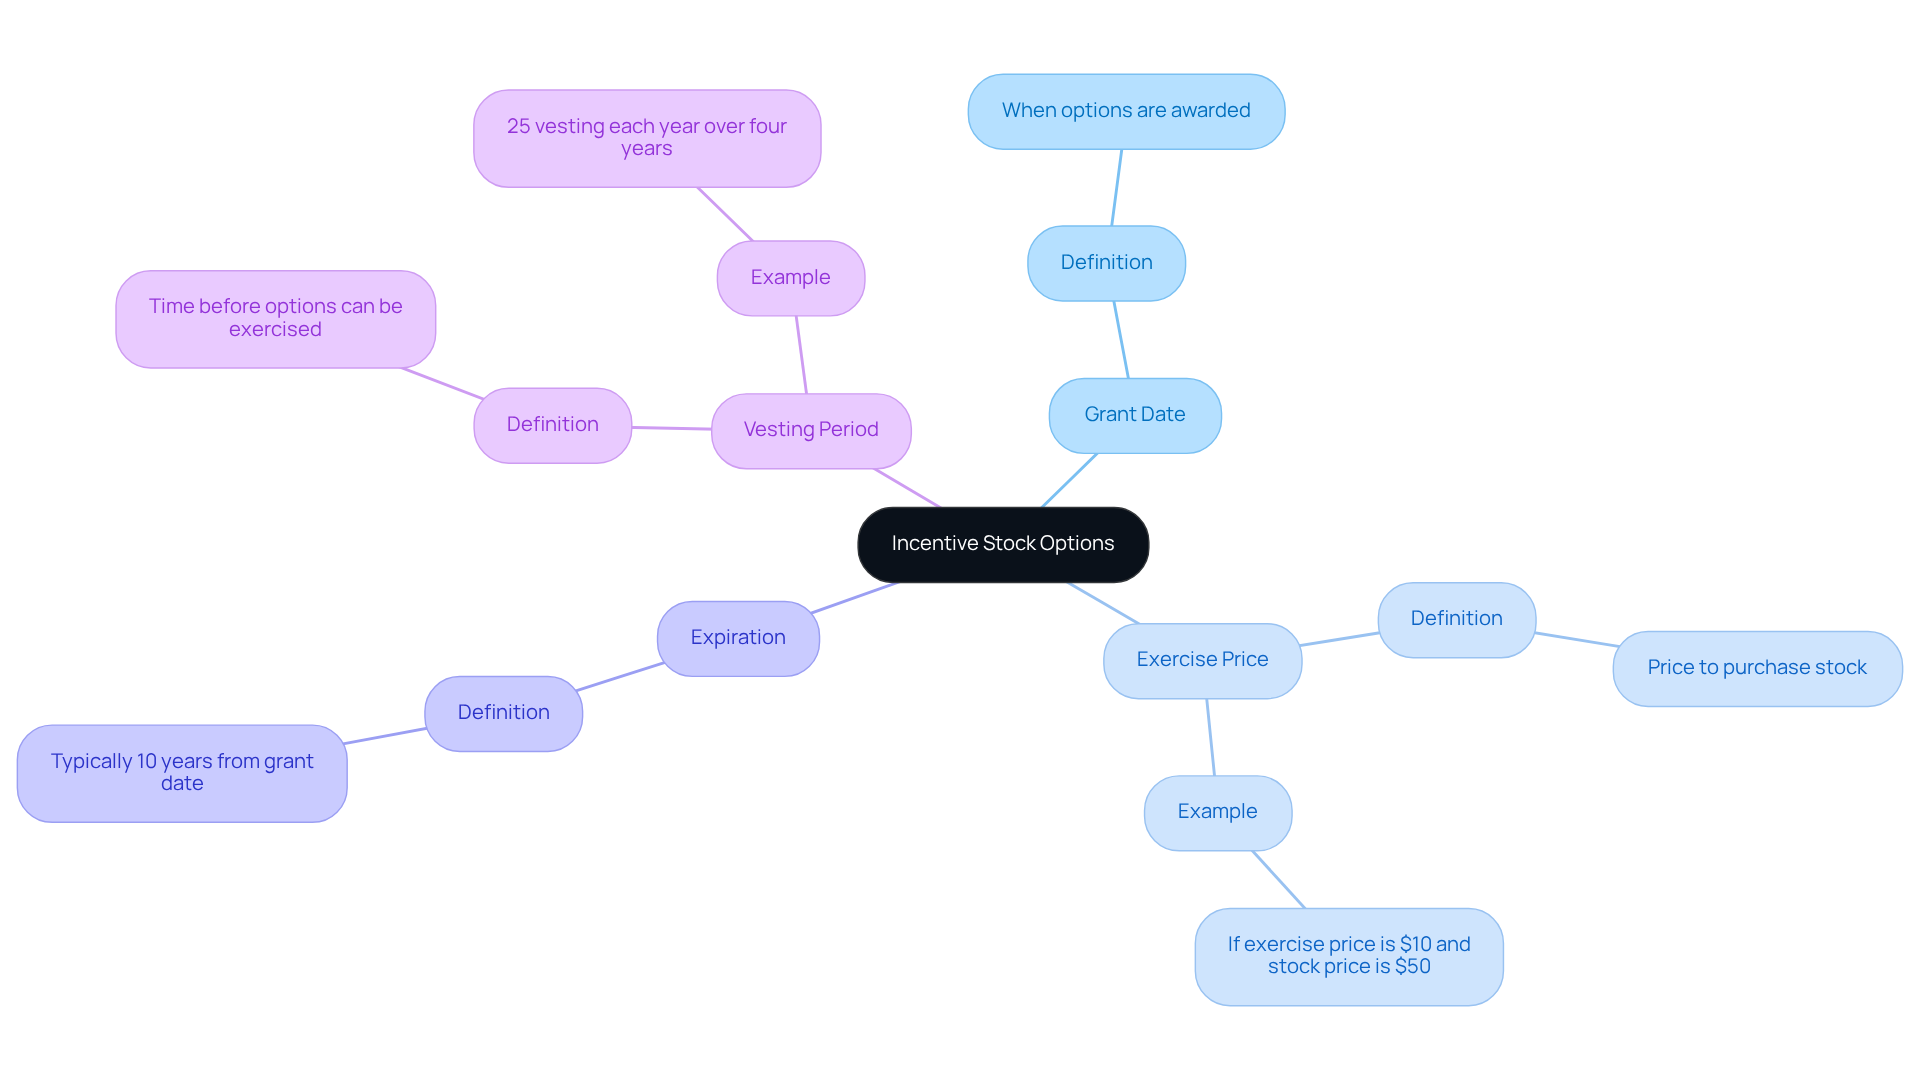
- Grant Date: This is when the options are awarded, marking the start of their lifecycle.
- Exercise Price: This is the price at which you can purchase the stock, usually set at the market price on the grant date. For instance, if the exercise price is $10 and the stock price rises to $50, the potential gain is substantial.
- Expiration: The incentive stock options expiration typically occurs 10 years from the grant date, but this can change based on your employment status. It’s important to keep track of this timeline to avoid losing your options before the incentive stock options expiration.
- Vesting Period: This is the time you must wait before exercising your options, often tied to your continued employment. Usually, 25% of stock options vest each year over four years, allowing you to gradually access your options.
Understanding these concepts can really help families navigate their financial futures with confidence. However, many employees – 41% – don’t utilize their options due to worries about affordability and perceived risks. This highlights the need for clear monetary guidance and education to help families manage the complexities of exercising stock options, especially when considering their children’s financial literacy and legacy planning.
At Bright Advisers, we focus on innovative wealth management strategies, including integrated tax planning and personalized financial guidance, to help families manage their stock options effectively. If you’re ready to take control of your financial journey, consider joining our waitlist for personalized guidance – we’re here for you. Remember, all advisory services are provided through Lifeworks Advisors, a registered investment adviser. Past performance does not guarantee future results, and securities investments are subject to risk.
Monitor Expiration Dates: Strategies for Timely Action
Imagine the peace of mind that comes from knowing your family’s financial future is secure, especially when considering the incentive stock options expiration. Let’s explore some gentle strategies to help your family manage Incentive Stock Options (ISOs) with confidence:
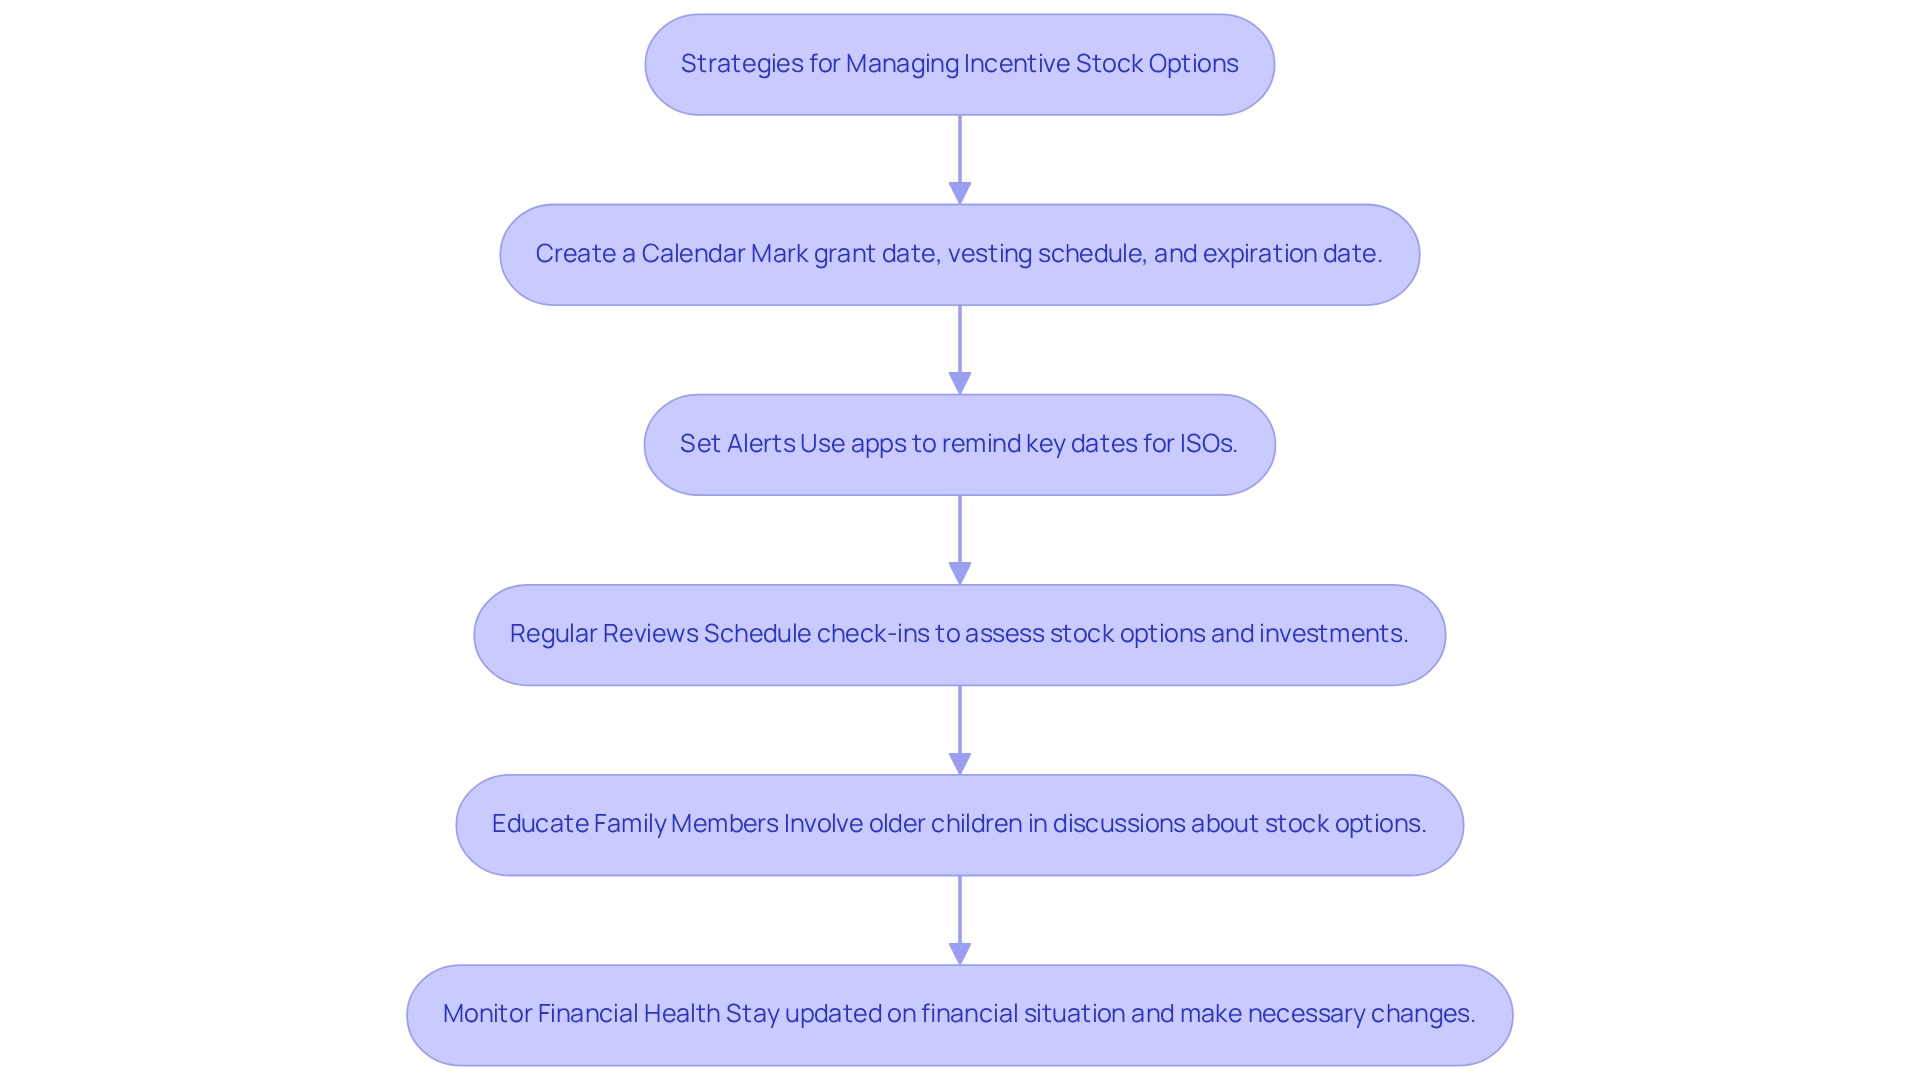
- Create a Calendar: Mark the grant date, vesting schedule, and expiration date on a family calendar. This visual reminder can help ensure that no important dates are overlooked.
- Set Alerts: Use digital tools or apps to set reminders for key dates related to your ISOs. Alerts can prompt timely action, such as exercising options or consulting with a money advisor.
- Regular Reviews: Schedule consistent check-ins to assess your stock options alongside other investments. This approach can assist households in staying updated about their monetary situation and making necessary changes.
- Educate Family Members: Involve older children in discussions about stock options and their implications. This not only readies them for future monetary responsibilities but also nurtures a culture of money understanding within the household.
Did you know that only 30% of families have a long-term financial plan? This highlights the importance of taking proactive steps to secure your family’s future. By actively tracking incentive stock options expiration dates and utilizing these strategies, households can enhance their money management skills and benefit from their ISOs while avoiding unnecessary losses. Comprehending the timing of ISO exercises can greatly affect tax exposure and liquidity, making it crucial for households to remain informed and involved in their planning. Moreover, Bright Advisers’ dedication to low fund fees and a clear fee structure helps ensure that households can access affordable investment choices, further aiding their economic objectives. As Kris Borghesan notes, “The lack of financial literacy leads to poor financial habits and decisions,” underscoring the importance of these strategies in fostering a financially secure future. With the right strategies in place, you can turn your ISOs into a stepping stone for your family’s financial success.
Navigate Tax Implications: Maximize Benefits and Minimize Liabilities
Navigating the world of incentive stock options expiration can feel daunting for families, particularly when tax implications come into play.
-
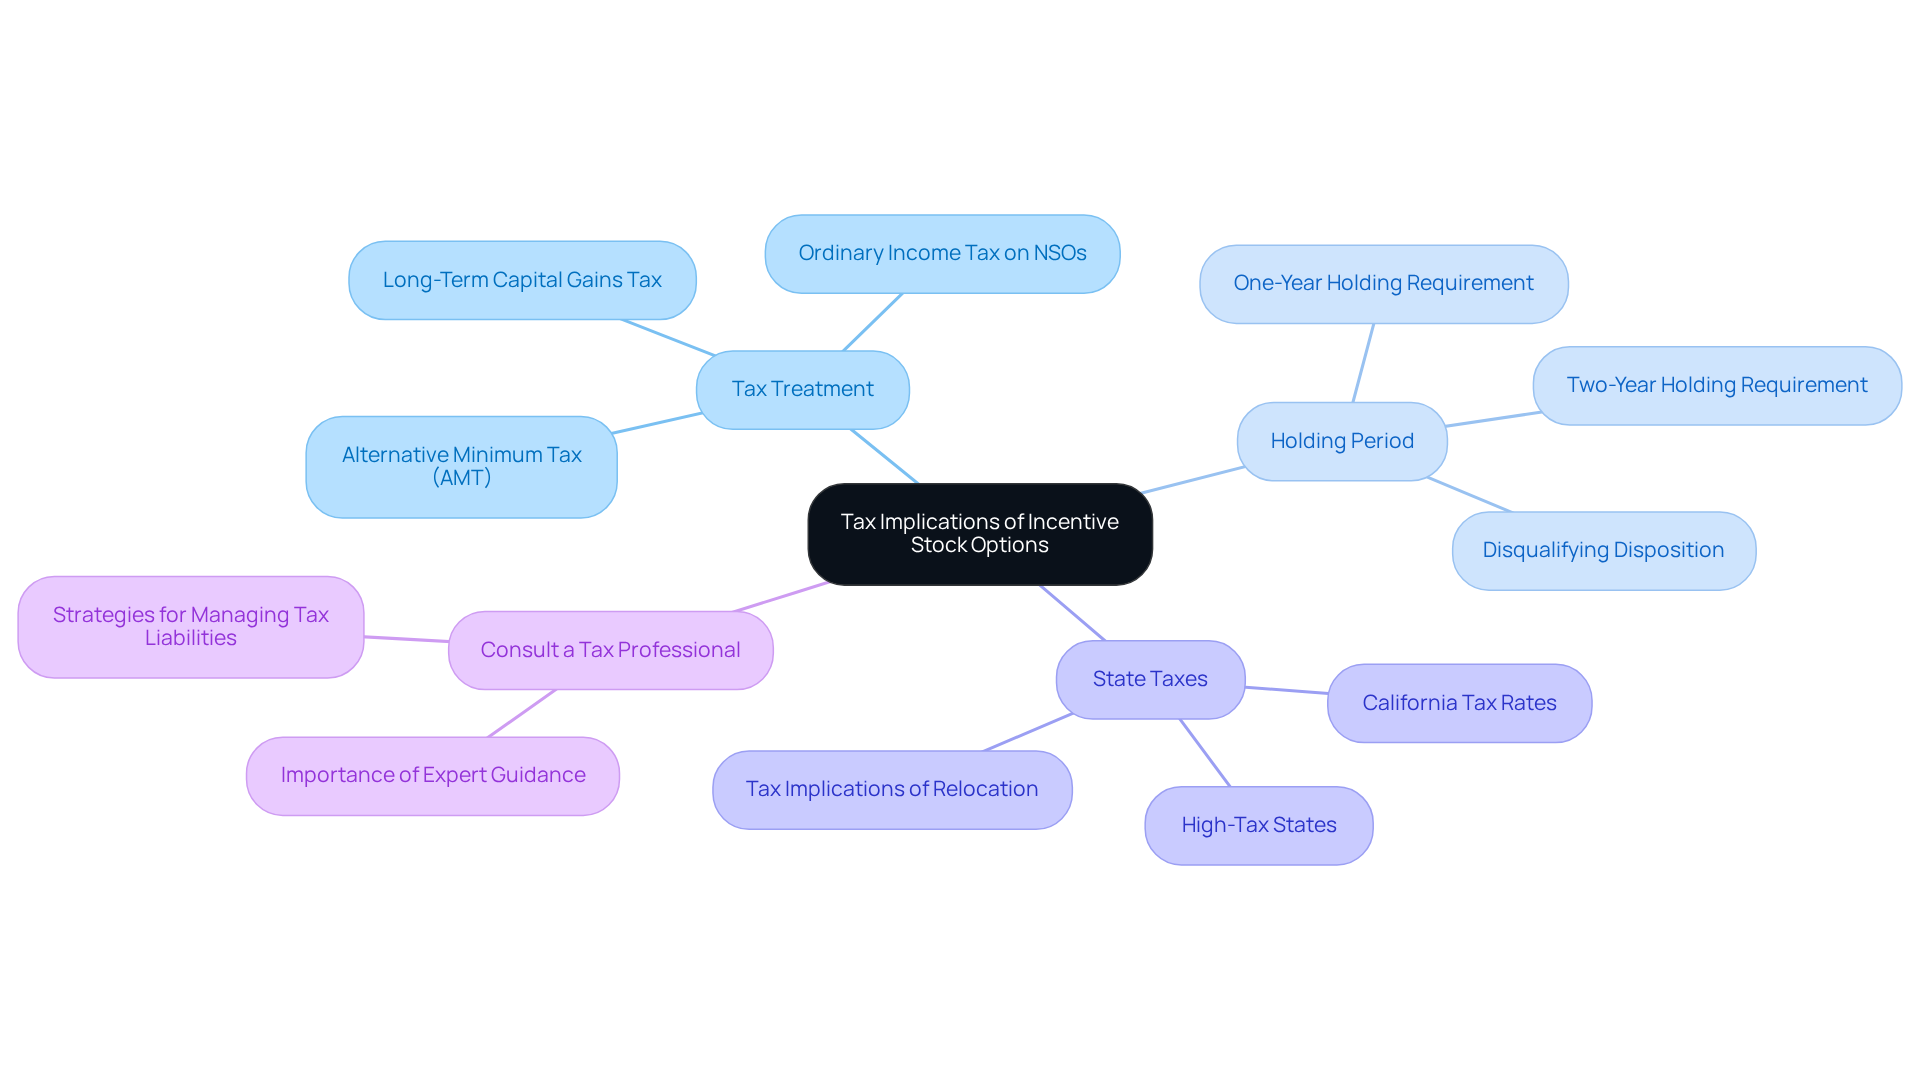
Tax Treatment: Many families feel overwhelmed by the complexities of tax regulations, especially when it comes to ISOs. It’s important to grasp how AMT can lead to unexpected tax bills that might strain your budget. For instance, Jay and Emma collaborated with Bright Advisers to navigate their monetary landscape, ensuring they understood AMT implications while planning for their children’s education and retirement.
-
Holding Period: To qualify for favorable long-term capital gains tax treatment, shares must be held for at least one year after exercise and two years after the grant date. This strategy can significantly lessen the tax load, enabling households to benefit from reduced tax rates on gains. Emily and Mark sought advice from Bright Advisers to develop a plan that involved strategically holding their stock options to enhance tax advantages.
-
State Taxes: Families should also consider state-specific tax implications, particularly in high-tax states like California, where rates can reach up to 13.3%. California levies taxes on stock options only if the alternative minimum tax is activated, making it crucial for households to comprehend how incentive stock options expiration affects their circumstances. Allison and Brian learned how to leverage state tax laws through their collaboration with Bright Advisers, ensuring they planned effectively and avoided surprises during tax season.
-
Consult a Tax Professional: Given the complexities of tax regulations surrounding stock options, engaging a tax advisor familiar with these issues can provide households with specific strategies that align with their overall monetary plan. By collaborating with Bright Advisers, households like Jay and Emma, Emily and Mark, and Allison and Brian developed the confidence to make informed choices that aligned with their long-term objectives.
With a clear understanding of these tax implications, families can confidently navigate their financial journey, ensuring a brighter future for their loved ones.
Engage Financial Advisors: Tailor Strategies for Your Family’s Needs
Many families feel overwhelmed by the complexities of managing their Incentive Stock Options, especially regarding the incentive stock options expiration, unsure of where to start. To effectively manage ISOs, here are some gentle steps to consider when engaging financial advisors:
-
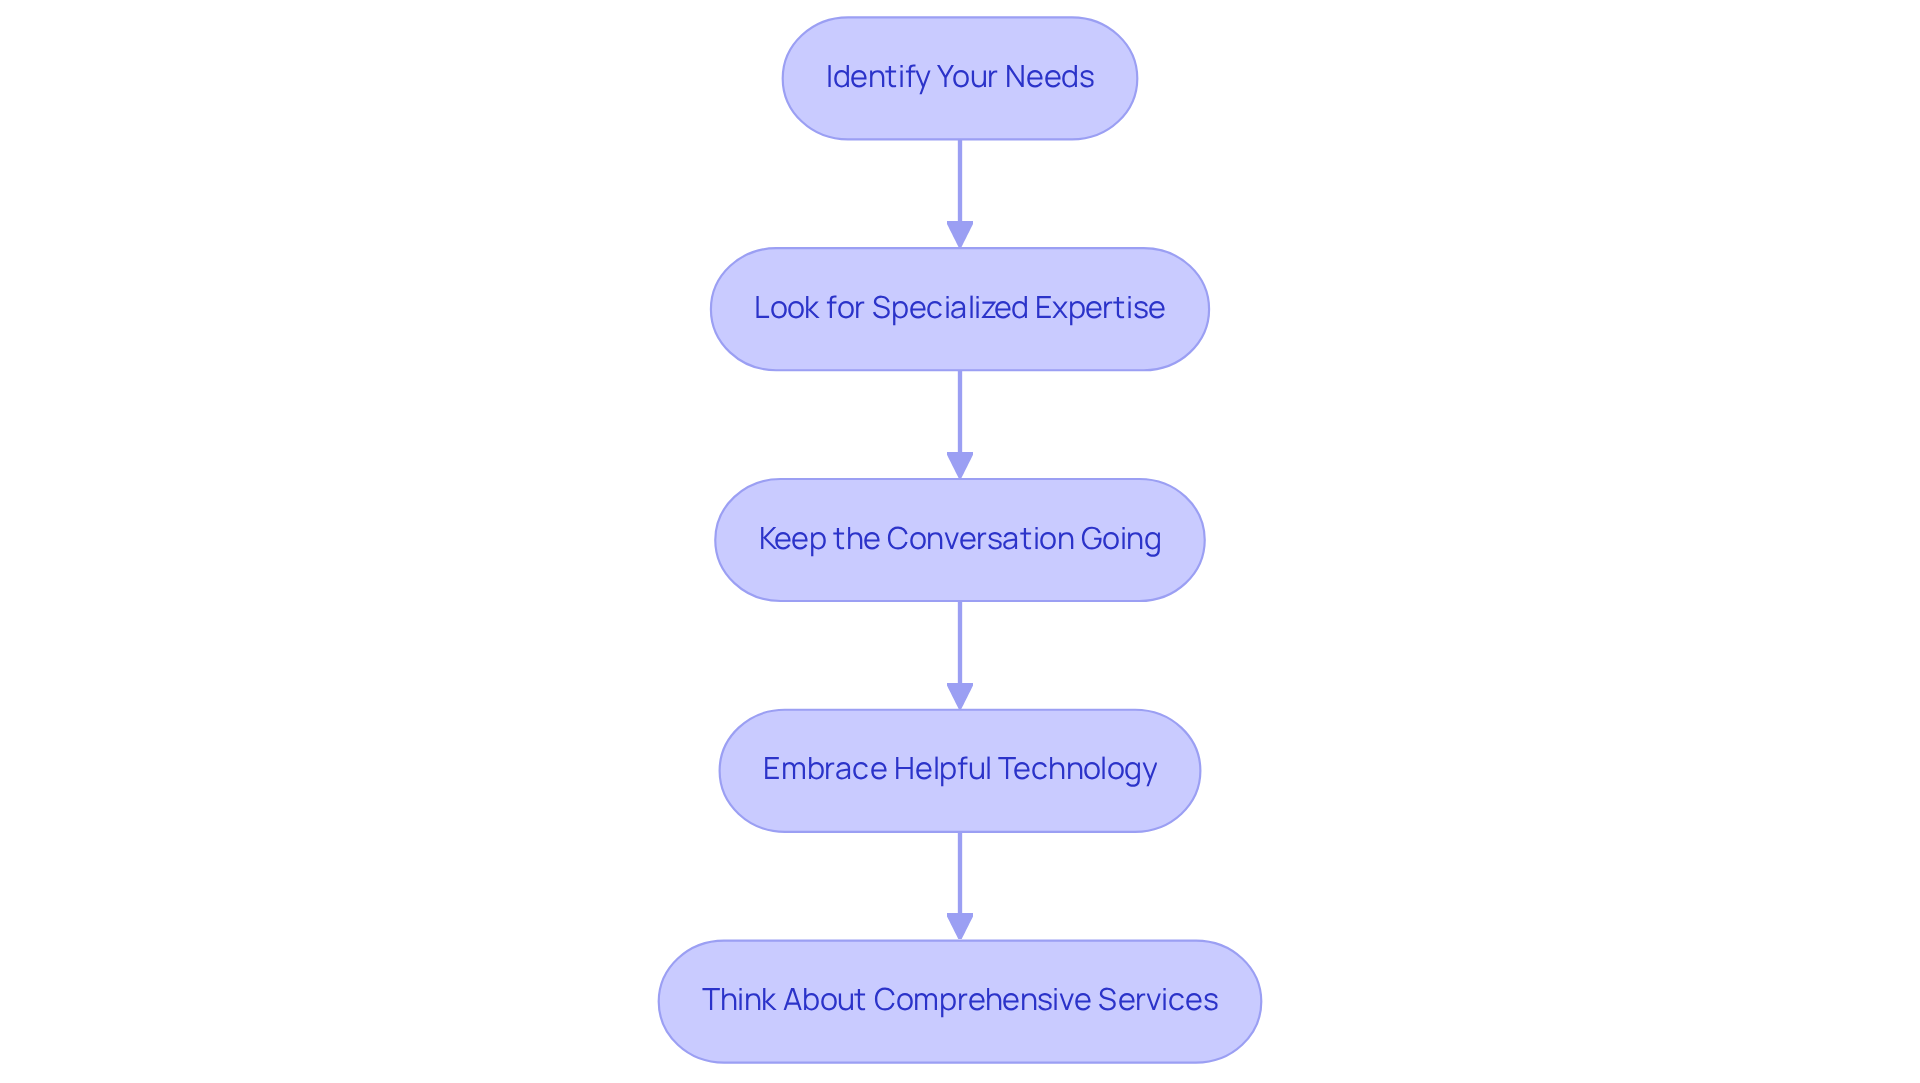
Identify Your Needs: Take a moment to think about your monetary goals and the specific areas where you could use a helping hand, like tax planning or investment strategies. Understanding your unique financial situation is key to effective planning.
-
Look for Specialized Expertise: Seek out advisors who truly understand equity compensation and have experience with ISOs. Their insights can provide valuable perspectives and strategies tailored to your family’s financial landscape, helping you make informed choices.
-
Keep the Conversation Going: It’s important to maintain regular communication with your advisor. This way, your financial plan can adapt as your family’s needs and goals evolve. Ongoing dialogue is essential for adjusting strategies when life changes.
-
Embrace Helpful Technology: Utilize the tools your advisor offers to keep track of your investments and stock options easily. For instance, Bright Advisers uses in-house technology to create personalized portfolios that adjust to changing economic conditions, steering clear of costly mutual funds and ETFs.
-
Think About Comprehensive Services: Consider working with advisors who can help you with all aspects of your financial plan, ensuring everything works together smoothly. Bright Advisers operates on a client-first model with no hidden fees or conflicts of interest, charging a simple, transparent monthly fee.
Imagine feeling confident in your financial decisions, knowing you have expert guidance tailored to your family’s unique needs. Statistics show that families who actively engage with financial advisors are better positioned to navigate the complexities of equity compensation, leading to improved financial outcomes. With the right support, you can navigate these challenges and secure a brighter financial future for your family.
Conclusion
Imagine feeling confident about your family’s financial future, knowing you have a solid grasp on Incentive Stock Options (ISOs). Understanding and managing ISOs is essential for families who want to secure their financial well-being. By grasping the key concepts, keeping an eye on expiration dates, and navigating tax implications, you can effectively leverage your ISOs to enhance your family’s wealth.
Many families feel overwhelmed by the complexities of Incentive Stock Options, unsure of how to navigate them effectively. But it doesn’t have to be that way. Engaging with knowledgeable financial advisors can make a world of difference. The insights shared in this article highlight the importance of proactive planning and education in making informed decisions regarding stock options.
Key strategies discussed include:
- Creating a calendar to track important dates
- Setting alerts for timely actions
- Involving family members in financial discussions
Understanding the tax implications and seeking specialized advice can significantly impact your family’s financial landscape. By implementing these best practices, you can avoid common pitfalls and maximize the benefits of your stock options.
Ultimately, managing your Incentive Stock Options is about more than just financial gain; it’s about building a culture of financial understanding and responsibility together as a family. Engaging with a fiduciary advisor like Bright Advisers can provide the necessary support and guidance to navigate these complexities. By taking these steps, you’re not just investing in your future; you’re nurturing a legacy of financial wisdom for your family.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options are options that allow employees to buy company shares at a set price, known as the exercise price, which can be a valuable part of their compensation package.
What is the grant date in relation to ISOs?
The grant date is when the options are awarded to the employee, marking the start of their lifecycle.
What is the exercise price?
The exercise price is the price at which you can purchase the stock, usually set at the market price on the grant date. For example, if the exercise price is $10 and the stock price rises to $50, the potential gain is substantial.
How long do Incentive Stock Options typically last?
Incentive Stock Options typically expire 10 years from the grant date, but this can change based on your employment status.
What is a vesting period?
The vesting period is the time you must wait before exercising your options, often tied to your continued employment. Typically, 25% of stock options vest each year over four years.
Why do many employees not utilize their stock options?
Many employees, about 41%, do not utilize their options due to concerns about affordability and perceived risks, highlighting the need for clear monetary guidance and education.
How can Bright Advisers assist families with ISOs?
Bright Advisers focuses on innovative wealth management strategies, including integrated tax planning and personalized financial guidance, to help families manage their stock options effectively.
What should I know about the advisory services provided by Bright Advisers?
All advisory services are provided through Lifeworks Advisors, a registered investment adviser. Past performance does not guarantee future results, and securities investments are subject to risk.
List of Sources
- Understand Incentive Stock Options: Key Concepts and Definitions
- Stock Options 101: The Essentials | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/stock-options-101)
- What are Stock Option? Types of Options & How They Work (https://carta.com/learn/equity/stock-options)
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- 2022 Employee Stock Options Report | Carta (https://carta.com/data/2022-employee-stock-options-report)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Monitor Expiration Dates: Strategies for Timely Action
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- 40 Financial Literacy Statistics in the United States – Intuit Blog (https://intuit.com/blog/innovative-thinking/financial-tips/financial-literacy-statistics)
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- Navigate Tax Implications: Maximize Benefits and Minimize Liabilities
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- How are stock options taxed in California? — Secfi (https://secfi.com/learn/how-are-stock-options-taxed-in-california)
- Incentive Stock Options Tax Planning Opportunities – GHJ (https://ghjadvisors.com/ghj-insights/incentive-stock-options-tax-planning-opportunities-and-pitfalls)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- How Stock Options Are Taxed: ISO vs NSO | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/how-are-stock-options-taxed)
- Engage Financial Advisors: Tailor Strategies for Your Family’s Needs
- Adapt or Die: Serving the Next Generation of Clients (https://financialplanningassociation.org/learning/publications/journal/APR24-adapt-or-die-serving-next-generation-clients-OPEN)
- 2024 Schwab Modern Wealth Survey Shows Increasing Financial Confidence From Generation to Generation and Younger Americans Investing at an Earlier Age (https://pressroom.aboutschwab.com/press-releases/press-release/2024/2024-Schwab-Modern-Wealth-Survey-Shows-Increasing-Financial-Confidence-From-Generation-to-Generation-and-Younger-Americans-Investing-at-an-Earlier-Age/default.aspx)
- Financial Advisor Statistics in 2026: Growth and Trends in the Financial Advisory Industry in the USA (https://randallwealthgroup.com/financial-advisor-statistics)
- 27% of Americans use financial advisors, with 60% prioritizing trust as the top factor (https://yougov.com/en-us/articles/50180-27-americans-use-financial-advisors-60-prioritizing-trust-as-the-top-factor)
- How to choose a financial advisor | Vanguard (https://investor.vanguard.com/investor-resources-education/article/how-to-choose-a-financial-advisor)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading