

Key Highlights
- Incentive Stock Options (ISOs) allow families to buy company shares at a set strike price, offering potential tax benefits if held for specified durations.
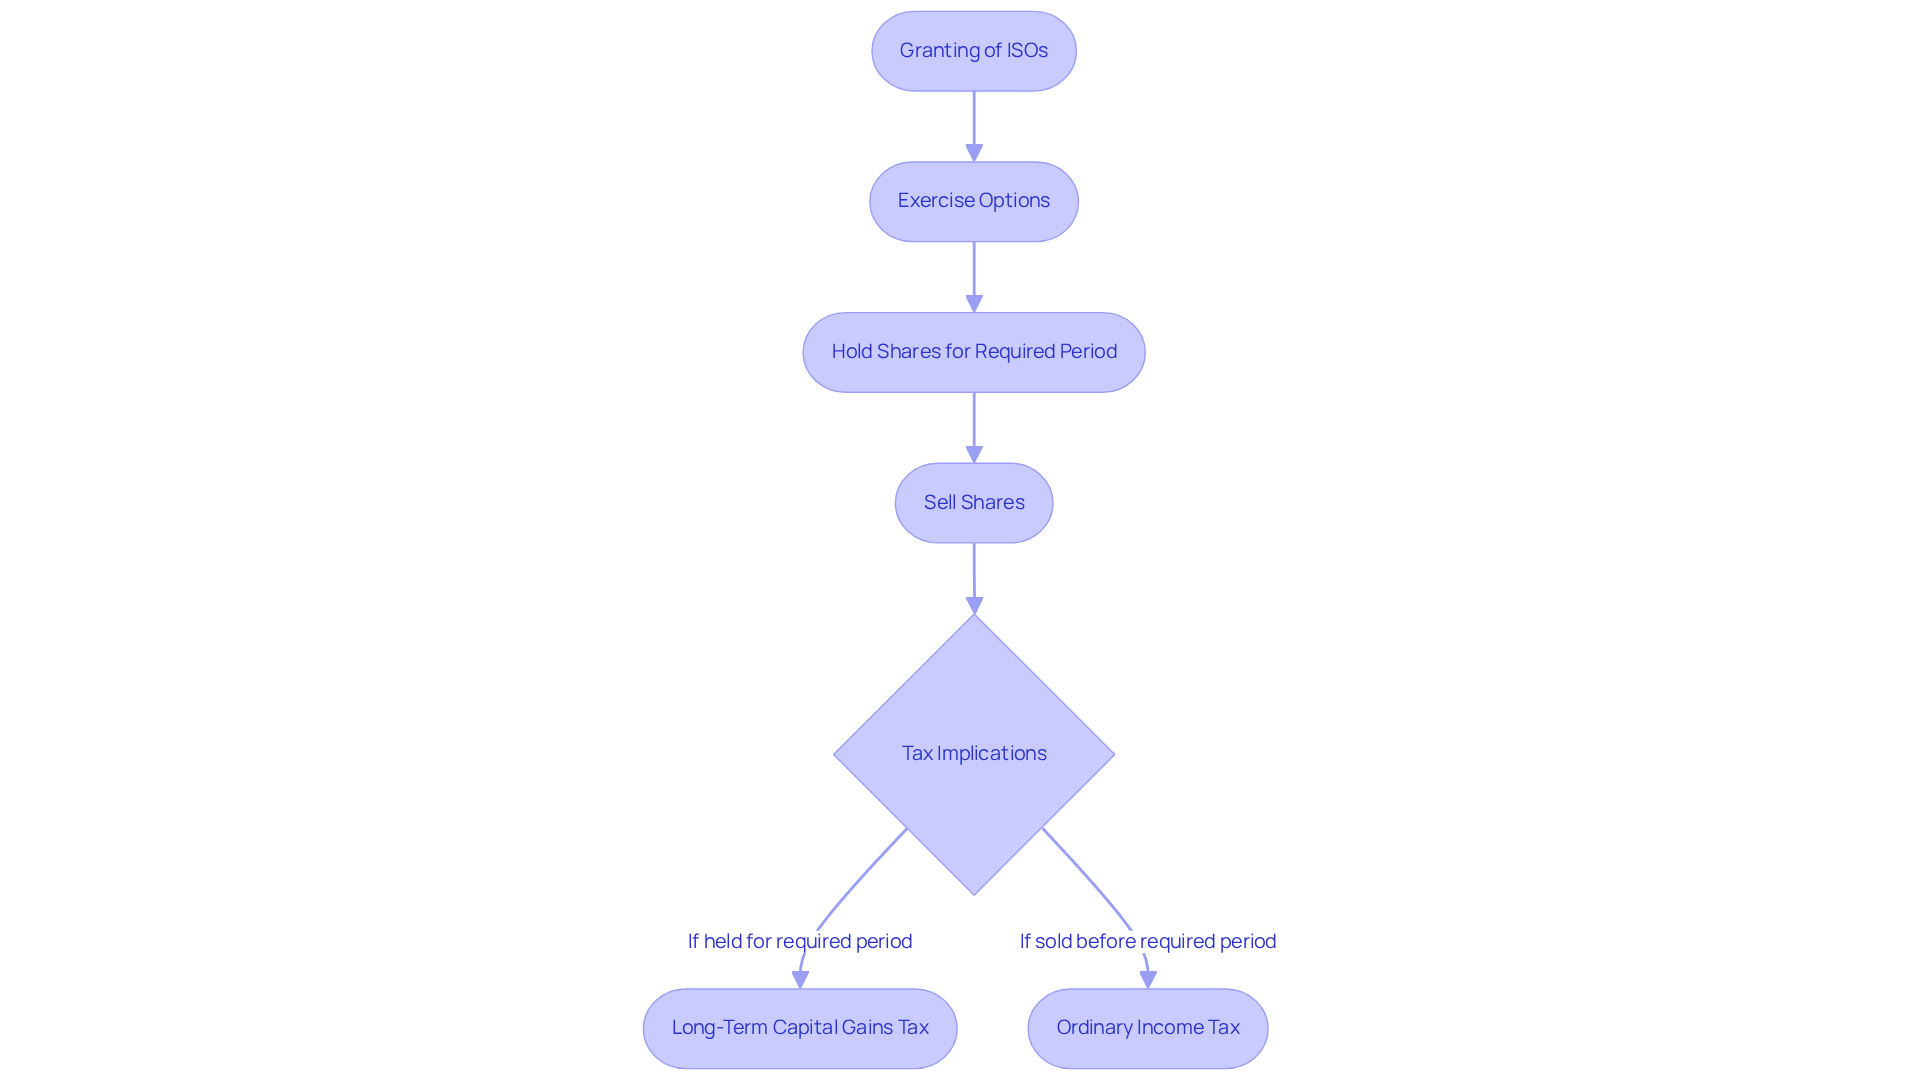
- Profits from ISOs can be taxed at lower long-term capital gains rates if shares are held for at least one year after exercising and two years after the grant date.
- Families in California should be aware that the state does not recognise federal tax treatment of ISOs, which may lead to unexpected tax obligations.
- Exercising ISOs can trigger the Alternative Minimum Tax (AMT), which counts the ‘bargain element’ as earnings, potentially leading to a hefty tax bill.
- Strategies to minimise tax exposure include staggering exercises, exercising early in the year, selling shares to cover taxes, monitoring earnings levels, and tax-loss harvesting.
- Timing is crucial when exercising and selling ISOs; families should consider market conditions and personal financial situations to optimise their strategies.
- Utilising resources such as tax software, financial advisors, educational materials, and tax planning tools can enhance families’ understanding and management of ISOs.
Introduction
Imagine feeling overwhelmed by the complexities of Incentive Stock Options (ISOs) while trying to secure your family’s financial future. Understanding how to plan for these options can unlock opportunities for financial growth while protecting your family from unexpected tax surprises.
In California’s complex tax landscape, it’s natural to wonder: how can your family make the most of your ISOs while keeping tax worries at bay?
This guide will share essential strategies and insights to help your family navigate ISO tax planning with confidence, paving the way for a more secure financial future.
Understand Incentive Stock Options (ISOs)
Imagine feeling secure about your family’s financial future while navigating the complexities of stock options. Incentive Stock Options let you buy company shares at a set price, known as the strike price. This can be a great opportunity for your family. Unlike Non-Qualified Stock Options, Incentive Stock Options offer favorable tax treatment under certain conditions. You won’t owe taxes on earnings when the options are granted or exercised, as long as you hold the shares for a specified duration. If you exercise your ISOs and keep the shares for at least one year after exercising and two years after the grant date, any profit from selling them may be taxed at the long-term capital gains rate, which is usually lower than standard tax rates. This tax benefit is especially important for families in California, where high state tax rates can impact your overall financial situation.
For example, if an executive is granted 5,000 shares at a strike price of $10, and the fair market value rises to $30, the potential profit from selling those shares after meeting the holding requirements could be substantial. If sold after the required period, the profit would be taxed at the long-term capital gains rate, leading to significant tax savings compared to ordinary income tax rates.
Navigating the complexities of stock options can feel overwhelming, especially when balancing family priorities. Talking to a financial advisor can really help your family make the most of your ISOs. They can guide you through various tax scenarios to maximize the benefits of ISO sales. It’s also crucial to understand California’s tax regulations, as the state doesn’t recognize the federal tax treatment of incentive stock options, which could lead to unexpected tax obligations.
Families should keep meticulous records, like IRS Form 3921, which details the exercise of incentive stock options and is essential for accurate tax reporting. To maximize your incentive stock options tax planning in the Bay Area, it’s crucial to understand their tax benefits, especially in California’s complicated tax landscape. By seeking expert advice, families can turn potential tax challenges into opportunities for growth and security.
Explore Tax Implications and AMT Considerations
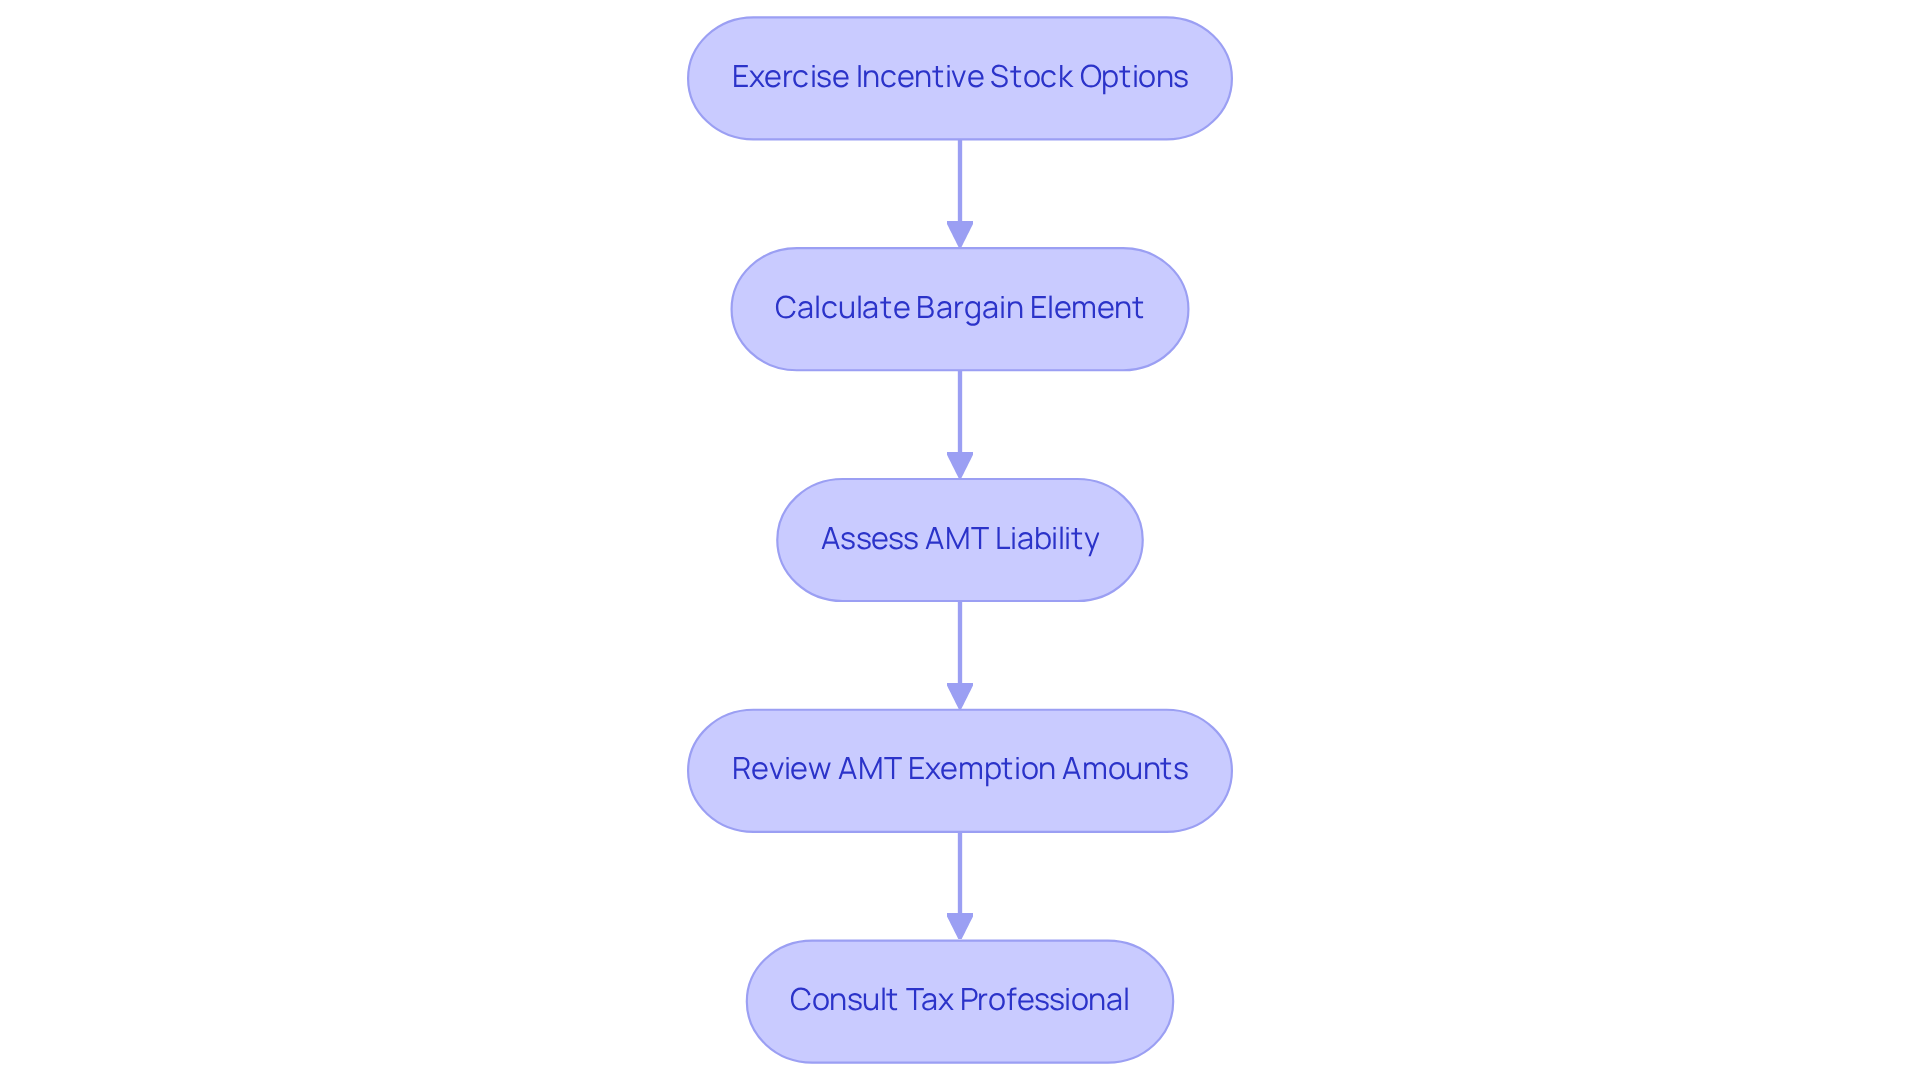
Imagine the surprise of receiving a hefty tax bill just when you thought you were making progress with your family’s financial goals. When you exercise Incentive Stock Options, it’s crucial to think about incentive stock options tax planning in the Bay Area and how it might affect your taxes. Unlike standard earnings tax, exercising stock options can trigger the Alternative Minimum Tax (AMT), which is designed to ensure everyone pays a minimum amount of tax, regardless of deductions and credits.
Picture this: if you exercise your stock options when the share price has significantly risen, the ‘bargain element’ – the difference between the strike price and the fair market value at exercise – will be counted as earnings for AMT purposes. This could lead to a surprising tax bill, even if you haven’t sold any shares yet.
In 2026, the AMT exemption amounts will be $90,100 for single filers and $140,200 for married couples filing jointly, with phase-out thresholds set at $500,000 and $1,000,000, respectively. It’s important to understand your earnings levels and potential AMT thresholds to avoid unexpected tax liabilities. For instance, a single filer with a W-2 earnings of $150,000 who exercises 10,000 ISOs at a $1 strike price when the company’s fair market value is $10 per share could face an AMT liability of approximately $12,974, despite not having sold any shares. Understanding how AMT works is essential for incentive stock options tax planning in the Bay Area, as it can help you avoid surprises and keep your family’s finances on track.
Reaching out to a tax professional can be a comforting step in navigating the complexities of incentive stock options tax planning in the Bay Area together. They can assist you in developing a strategy for incentive stock options tax planning in the Bay Area to minimize AMT exposure, including timing ISO exercises and effectively managing your adjusted gross income. By addressing these financial challenges through professional tax planning, you can better optimize your family’s wealth accumulation potential. By taking proactive steps now, you can protect your family’s financial future and enjoy peace of mind.
Implement Strategies to Minimize Tax Exposure
Imagine facing a hefty tax bill just when you thought you were on solid financial ground. To minimize tax exposure related to Incentive Stock Options (ISOs), families can adopt several effective strategies:
-
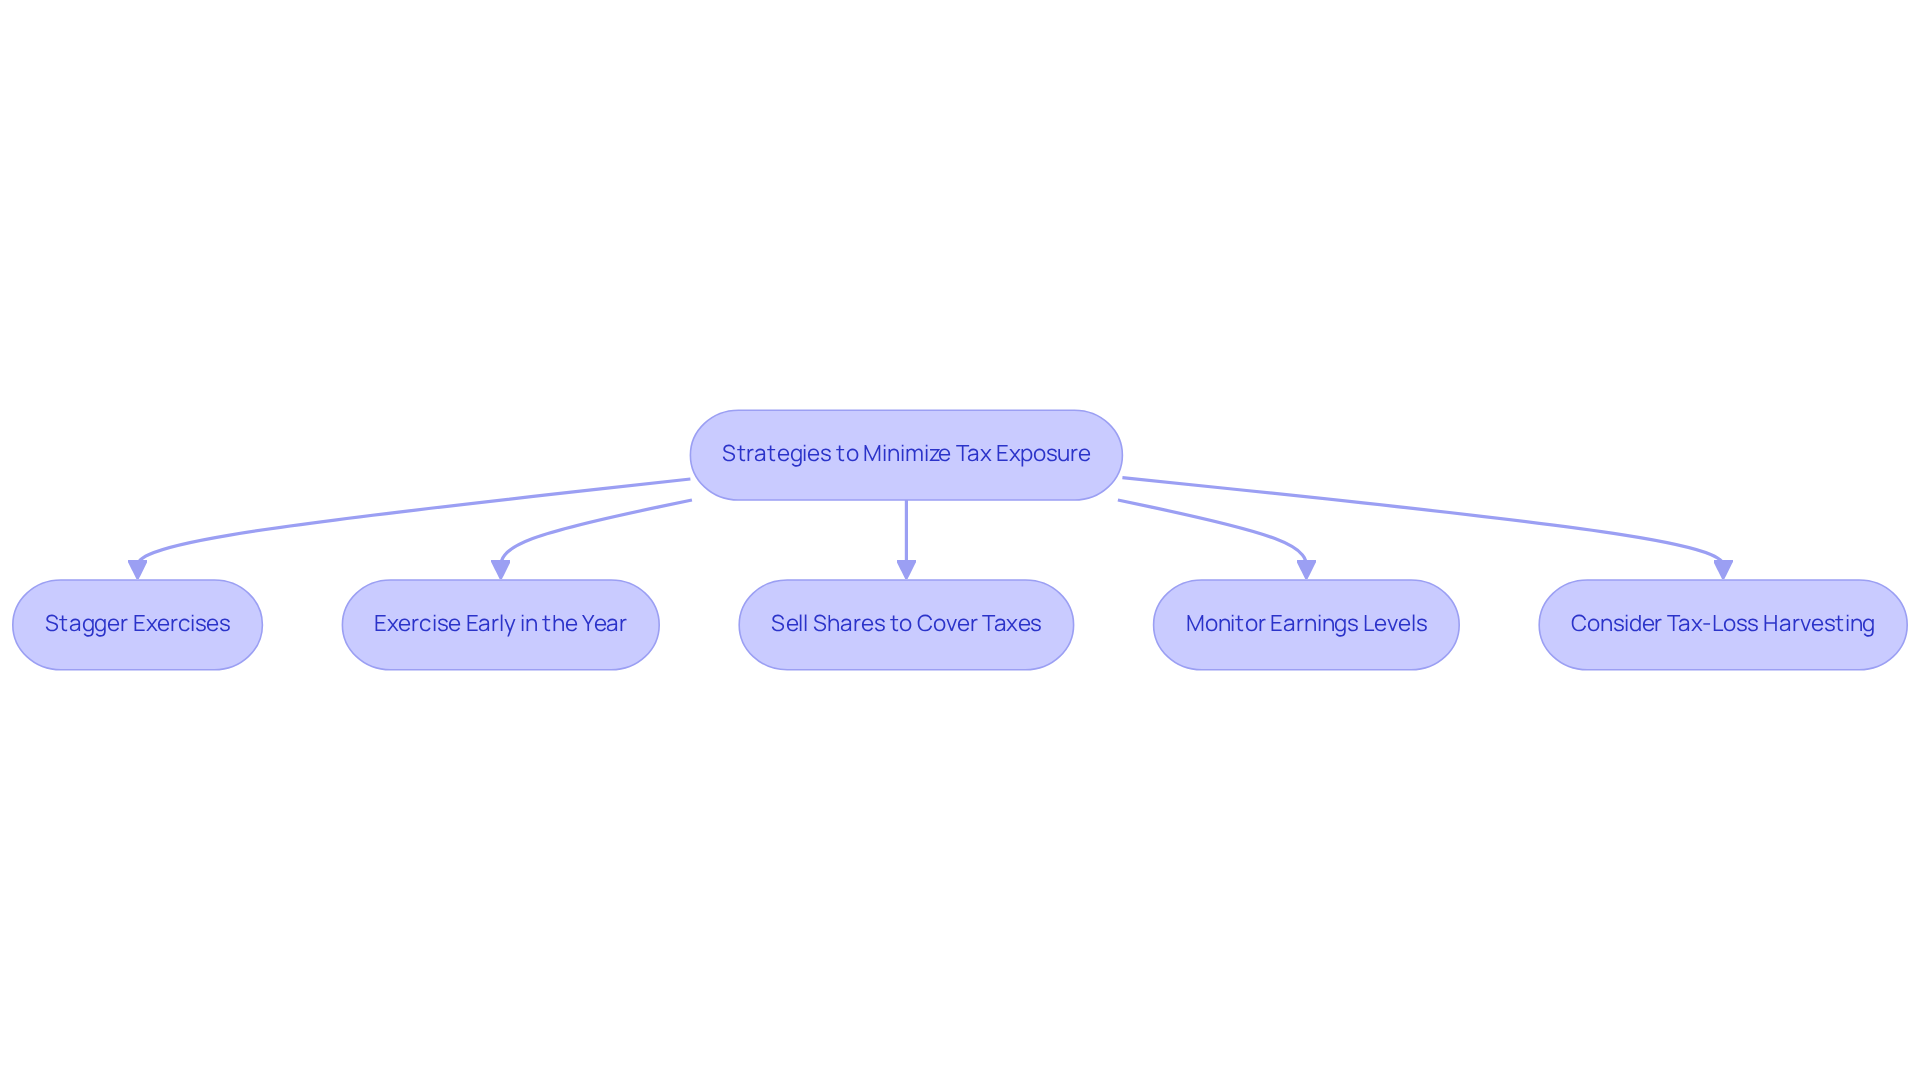
Stagger Exercises: Instead of exercising all your options in one year, consider staggering them over multiple years. This way, you can keep your income below the AMT threshold, which helps reduce your tax impact. For instance, staggering exercises can prevent exceeding the AMT exemption levels, which for 2026 are set at $90,100 for single filers and $140,200 for married couples filing jointly.
-
Exercise Early in the Year: Engaging in your stock options early in the calendar year allows more time to hold the shares, potentially qualifying for long-term capital gains treatment. This strategy can be particularly beneficial as it provides flexibility to adjust your position based on stock performance throughout the year.
-
Sell Shares to Cover Taxes: If you anticipate a significant tax bill from exercising your ISOs, consider selling a portion of the shares to cover the tax liability. This can prevent cash flow issues and ensure you can meet your tax obligations without financial strain. For example, if you exercise 1,000 options at a profit of $240 per share, selling a portion can help manage the tax bill effectively.
-
Monitor Earnings Levels: Keep track of your overall earnings and adjust your exercise strategy accordingly. If you anticipate a lower income year, it may be an ideal time to exercise stock options to minimize tax exposure. This proactive approach can help families navigate the complexities of incentive stock options tax planning in the Bay Area more effectively.
-
Consider Tax-Loss Harvesting: If you have investments that have lost value, think about selling them to offset gains from your stock options. This approach can assist in lowering your overall tax obligation and enhancing your economic situation.
Many families worry about unexpected tax bills that can throw their financial plans off course. With these strategies, you and your family can navigate the tax obligations of ISOs more smoothly, ensuring a more stable economic future. Additionally, understanding the potential for AMT credit recovery can further aid in managing tax liabilities, as it allows families to recoup some taxes paid during ISO exercises in future years when regular tax exceeds tentative minimum tax. For families seeking customized support in navigating these complexities, Bright Advisers offers specialized wealth management solutions that enhance economic security and freedom through incentive stock options tax planning in the Bay Area.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Determine Optimal Timing for Exercise and Sale
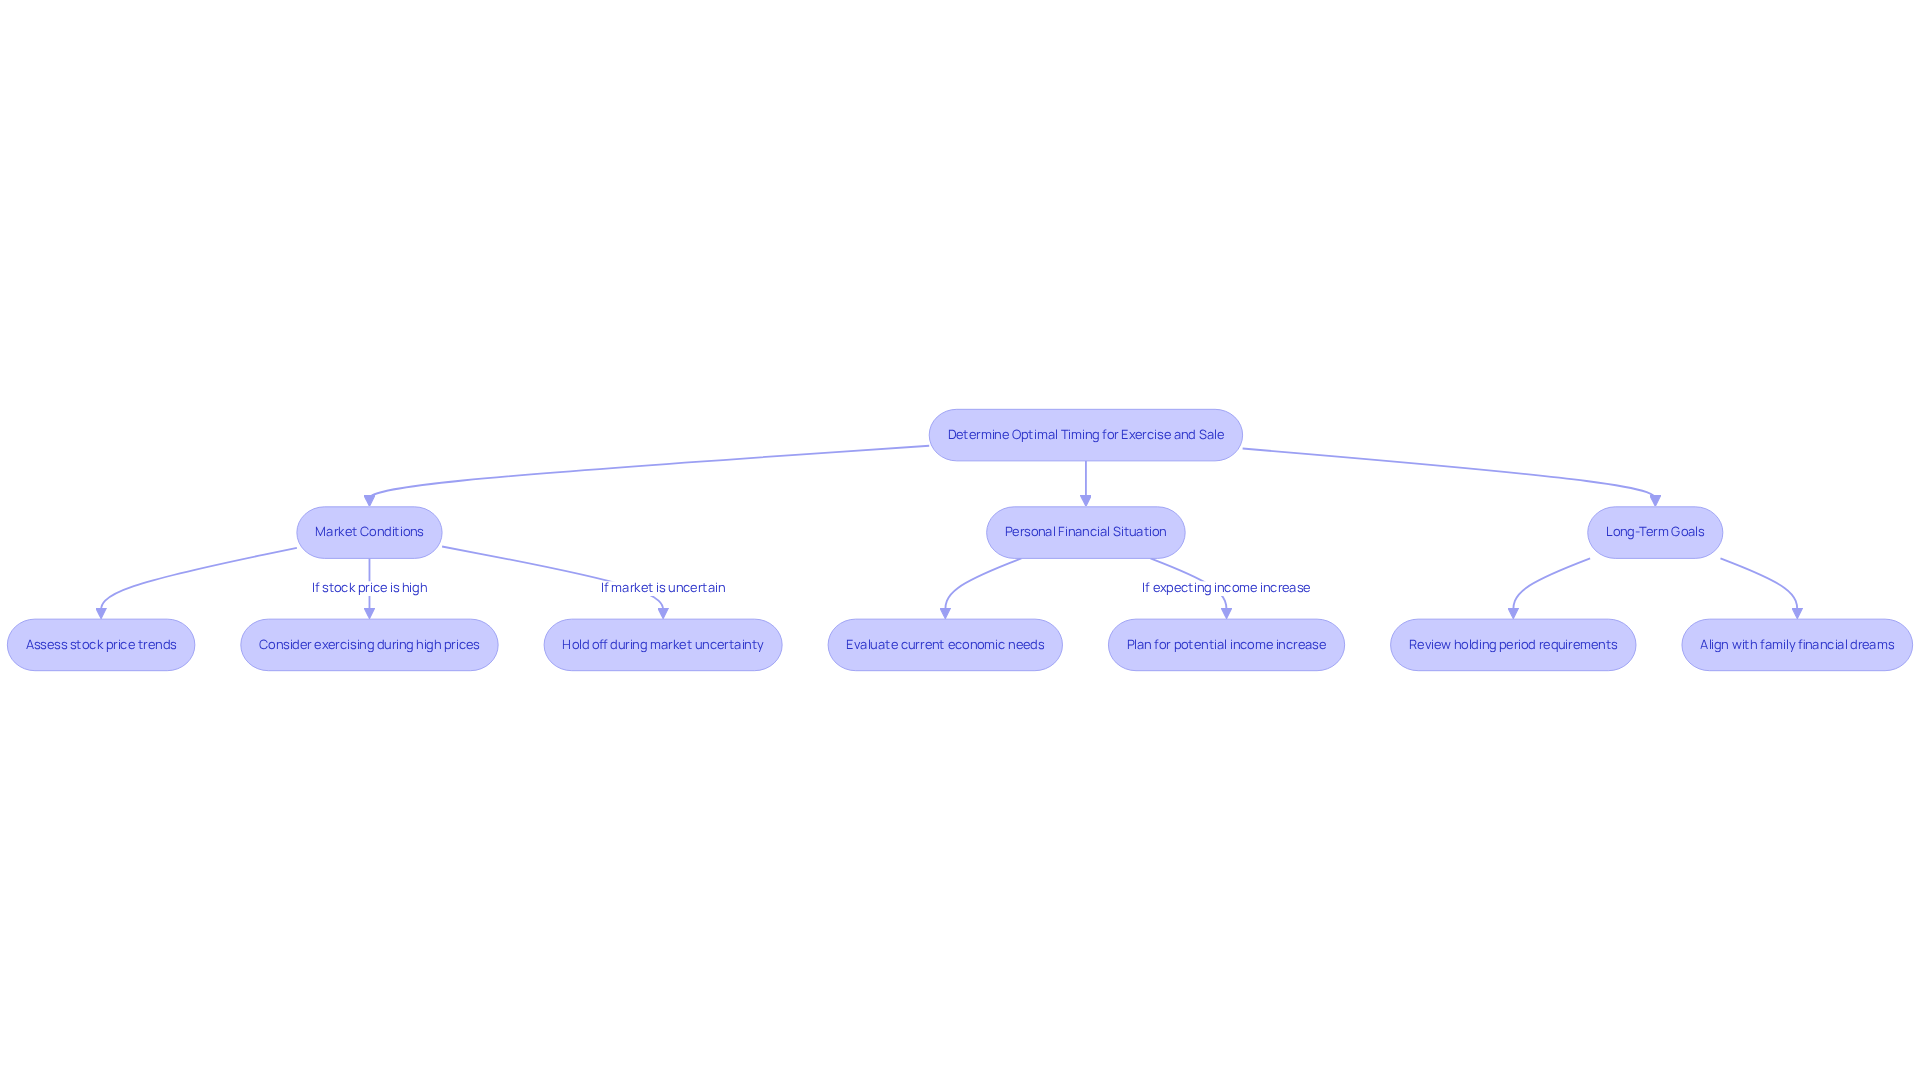
Imagine feeling overwhelmed by the timing of your incentive stock options tax planning in the Bay Area while trying to secure your family’s financial future. Timing is essential when exercising and selling these options, and there are key considerations for incentive stock options tax planning in the Bay Area that can help guide your decisions.
It’s important to understand how market conditions can impact your choices. Picture this: if your company’s stock price is soaring, exercising and selling might feel like a safe bet to lock in profits. But during those unpredictable times, it might be wise to hold off until things settle down.
Next, think about your personal monetary situation. Assess your current economic needs and tax implications. If you expect a significant income increase in the upcoming year, you should consider incentive stock options tax planning in the Bay Area by exercising ISOs now to help avoid higher tax brackets later.
Now, let’s reflect on your long-term goals. If you plan to hold the shares for an extended period, ensure you meet the holding period requirements to benefit from favorable tax treatment. When you take a moment to think about these factors, you can better align your ISO strategies with your family’s financial dreams.
Families who create a budget are not just planning; they’re setting themselves up for success, making them 2.5 times more likely to save enough for a comfortable retirement. With thoughtful planning, you can turn uncertainty into opportunity for your family’s financial journey.
Utilize Resources and Tools for Effective Planning
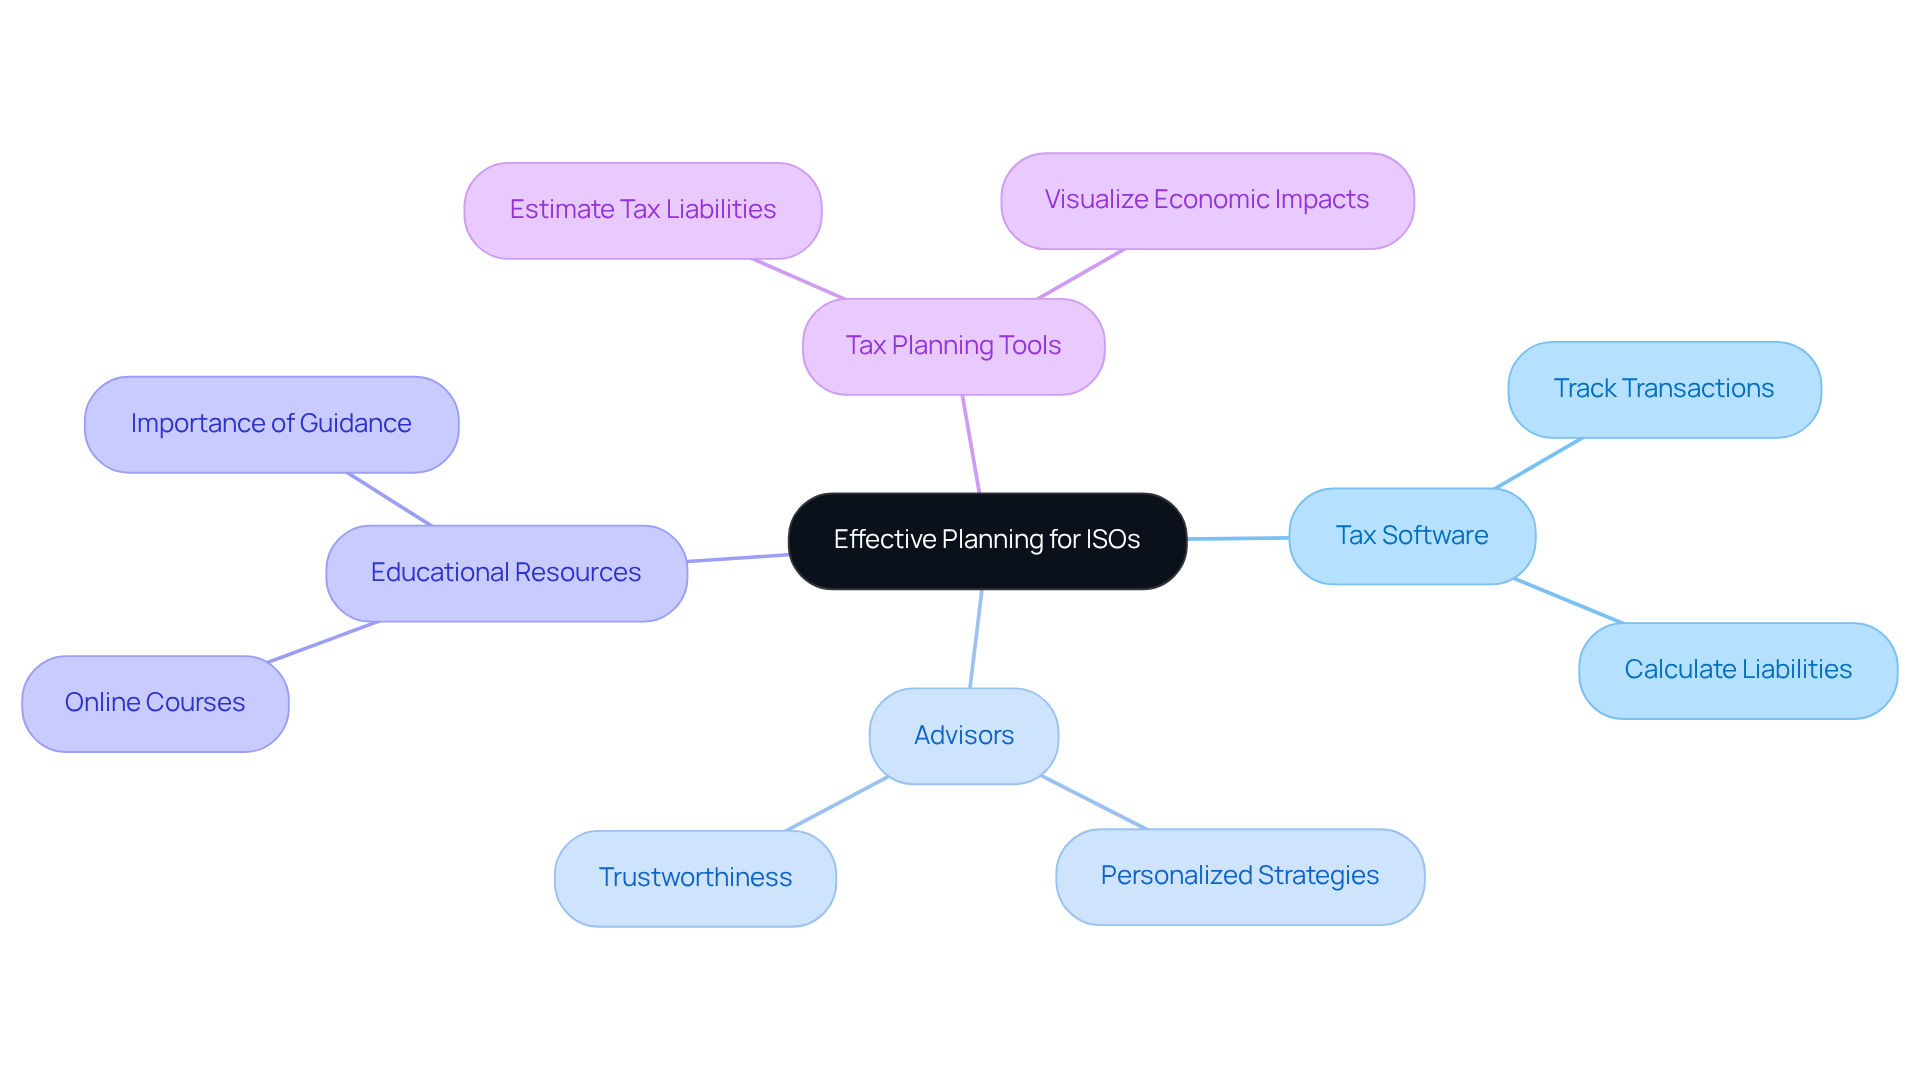
Imagine feeling confident about your family’s financial future, even when faced with the complexities of Incentive Stock Options. To effectively manage your ISOs and navigate the associated tax implications, consider utilizing the following resources that can support your family’s financial strategy:
-
Tax Software: Investing in reliable tax software can help you track ISO transactions and calculate potential tax liabilities. Many programs are designed specifically for stock options, making it easier to manage your financial responsibilities.
-
Advisors: Consulting with an advisor from Bright Advisers who specializes in incentive stock options tax planning in the Bay Area can provide personalized strategies. They can assist you with tax-loss harvesting and investment approaches tailored to your family’s economic circumstances. Remember, trustworthiness and cost are key factors when selecting an advisor, so finding someone who meets these criteria is essential.
-
Educational Resources: Exploring online courses or webinars focused on incentive stock options tax planning in the Bay Area can be incredibly beneficial. Many reputable platforms offer valuable content that can enhance your understanding of ISOs and their implications, empowering you to make better financial choices. In fact, 41% of Americans turn to advisors and planners for monetary information, highlighting the importance of seeking guidance.
-
Tax Planning Tools: Utilizing tax planning calculators can help you estimate potential tax liabilities based on various exercise and sale scenarios, particularly in the context of incentive stock options tax planning in the Bay Area. These tools allow you to visualize the economic impact of your decisions, enabling more strategic planning.
It can be tough to navigate the complexities of Incentive Stock Options, especially with the tax implications involved. By using these resources, your family can make informed decisions regarding your ISOs, ultimately supporting your long-term financial well-being. With the right support, you can turn the challenges of managing ISOs into opportunities for your family’s financial growth. We’re here to help your family align your values and goals with smart budgeting and tax planning strategies.
Conclusion
We understand that navigating the world of Incentive Stock Options (ISOs) can feel overwhelming, especially when you’re focused on securing your family’s future. It’s important to know that the way ISOs are taxed in California can really shape your family’s financial journey. By understanding how to make the most of ISOs and being aware of the tax implications, you can make choices that truly support your family’s dreams.
Key strategies to consider include:
- Staggering exercises to manage tax exposure
- Exercising early in the year to qualify for long-term capital gains
- Utilizing tax-loss harvesting to offset gains
It’s also crucial to grasp the implications of the Alternative Minimum Tax (AMT) to avoid unexpected tax liabilities. With a little proactive planning and the right support, you can turn the challenges of ISOs into stepping stones for your family’s financial growth.
We encourage you to take charge of your family’s financial future by exploring tax planning tools, reaching out to trusted advisors, and learning more about ISOs together. Embracing these strategies not only enhances your family’s economic security but also empowers you to make wise wealth decisions that can be cherished across generations. Remember, we’re here for you every step of the way.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) allow employees to purchase company shares at a predetermined price, known as the strike price. They offer favorable tax treatment under certain conditions, making them a beneficial opportunity for families.
How do ISOs differ from Non-Qualified Stock Options?
Unlike Non-Qualified Stock Options, ISOs provide favorable tax treatment, meaning you won’t owe taxes on earnings when the options are granted or exercised, provided you meet specific holding requirements.
What are the tax benefits of exercising ISOs?
If you exercise your ISOs and hold the shares for at least one year after exercising and two years after the grant date, any profit from selling them may be taxed at the long-term capital gains rate, which is typically lower than ordinary income tax rates.
Why is understanding California’s tax regulations important for ISOs?
California does not recognize the federal tax treatment of ISOs, which can lead to unexpected tax obligations. Understanding these regulations is crucial for effective tax planning.
What records should families keep regarding ISOs?
Families should maintain meticulous records, including IRS Form 3921, which details the exercise of incentive stock options and is essential for accurate tax reporting.
What is the Alternative Minimum Tax (AMT) and how does it relate to ISOs?
The AMT is designed to ensure that individuals pay a minimum amount of tax, regardless of deductions and credits. Exercising ISOs can trigger AMT, as the ‘bargain element’ (the difference between the strike price and fair market value at exercise) is counted as earnings for AMT purposes.
What are the AMT exemption amounts for 2026?
In 2026, the AMT exemption amounts will be $90,100 for single filers and $140,200 for married couples filing jointly, with phase-out thresholds set at $500,000 and $1,000,000, respectively.
How can families minimize AMT exposure when exercising ISOs?
Families can minimize AMT exposure by developing a strategy with a tax professional, which may include timing ISO exercises and effectively managing adjusted gross income.
Why is it beneficial to consult a financial advisor regarding ISOs?
A financial advisor can help families navigate the complexities of ISOs, guide them through various tax scenarios, and maximize the benefits of ISO sales, ensuring better financial outcomes.
List of Sources
- Understand Incentive Stock Options (ISOs)
- Incentive Stock Options Tax Impacts (https://team.monetagroup.com/team/duff-torney/who-we-serve/executives/resources-for-executives/incentive-stock-options-tax-impacts)
- How are stock options taxed and reported? (https://jacksonhewitt.com/tax-help/tax-tips-topics/personal-finance-savings/how-are-stock-options-taxed-and-reported)
- Incentive Stock Option (ISO) Taxes: A Guide (https://schwab.com/learn/story/incentive-stock-option-iso-taxes-guide)
- Stock Option Taxes in California: ISO, NSO, and RSU Tax Planning for Tech Workers (https://ietaxattorney.com/stock-option-taxes-in-california-iso-nso-and-rsu-tax-planning-for-tech-workers)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- Explore Tax Implications and AMT Considerations
- What is the Alternative Minimum Tax? How AMT Works & Calculation (https://carta.com/learn/equity/stock-options/taxes/amt)
- Strategies to Reduce AMT on Stock Options – Phoenix Strategy Group (https://phoenixstrategy.group/blog/strategies-reduce-amt-stock-options)
- Alternative Minimum Tax (AMT): How It Works for Stock Options in 2026 (https://esofund.com/blog/alternative-minimum-tax-amt)
- Who pays the AMT? (https://taxpolicycenter.org/briefing-book/who-pays-amt)
- Alternative Minimum Tax (AMT): Who Pays It and How It Works (https://reedcorp.tax/helpful-guides/alternative-minimum-tax-explained)
- Implement Strategies to Minimize Tax Exposure
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- 4 Strategies to Exercise Your Incentive Stock Options (https://zajacgrp.com/insights/4-strategies-for-exercising-your-isos-and-the-tax-impact)
- Tax Planning Strategies for Incentive Stock Options (ISOs) (https://cbh.com/insights/articles/tax-planning-strategies-for-incentive-stock-options-isos)
- The AMT That Blindsides Founders Who Exercise ISOs And How to Model Your Way Out (https://linkedin.com/pulse/amt-blindsides-founders-who-exercise-isos-how-model-your-ryan-wang-fsu8c)
- ISO Tax Strategies: Maximize Your Stock Options (https://instrumentalwealth.com/blog/iso-tax-strategies-maximize-your-stock-options)
- Determine Optimal Timing for Exercise and Sale
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- 40 Financial Literacy Statistics in the United States – Intuit Blog (https://intuit.com/blog/innovative-thinking/financial-tips/financial-literacy-statistics)
- Growing share of U.S. adults say their personal finances will be worse a year from now (https://pewresearch.org/short-reads/2025/05/07/growing-share-of-us-adults-say-their-personal-finances-will-be-worse-a-year-from-now)
- 1 in 3 Americans say their financial situation has deteriorated in the past year, new survey finds (https://finance.yahoo.com/personal-finance/banking/article/my-money-survey-100020297.html)
- Personal Financial Situation (https://news.gallup.com/poll/1621/personal-financial-situation-index.aspx)
- Utilize Resources and Tools for Effective Planning
- Only 41% of Americans Use a Financial Advisor—And Most Younger Adults Shun the Professionals (https://investopedia.com/americans-using-a-financial-advisor-11812935)
- CFP Study Shows Its Advisers Linked to Stronger Financial Outcomes | PLANADVISER (https://planadviser.com/cfp-study-shows-its-advisers-linked-to-stronger-financial-outcomes)
- Research Finds CFP® Professional-Advised Americans Experience Greater Financial Preparedness, Confidence and Trust (https://cfp.net/news/2026/01/cfp-professional-advised-americans-experience-greater-financial-preparedness)
- Cerulli Associates | 53% of Households Believe in the Importance of a… (https://cerulli.com/press-releases/53-of-households-believe-in-the-importance-of-a-financial-plan)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading