

Key Highlights
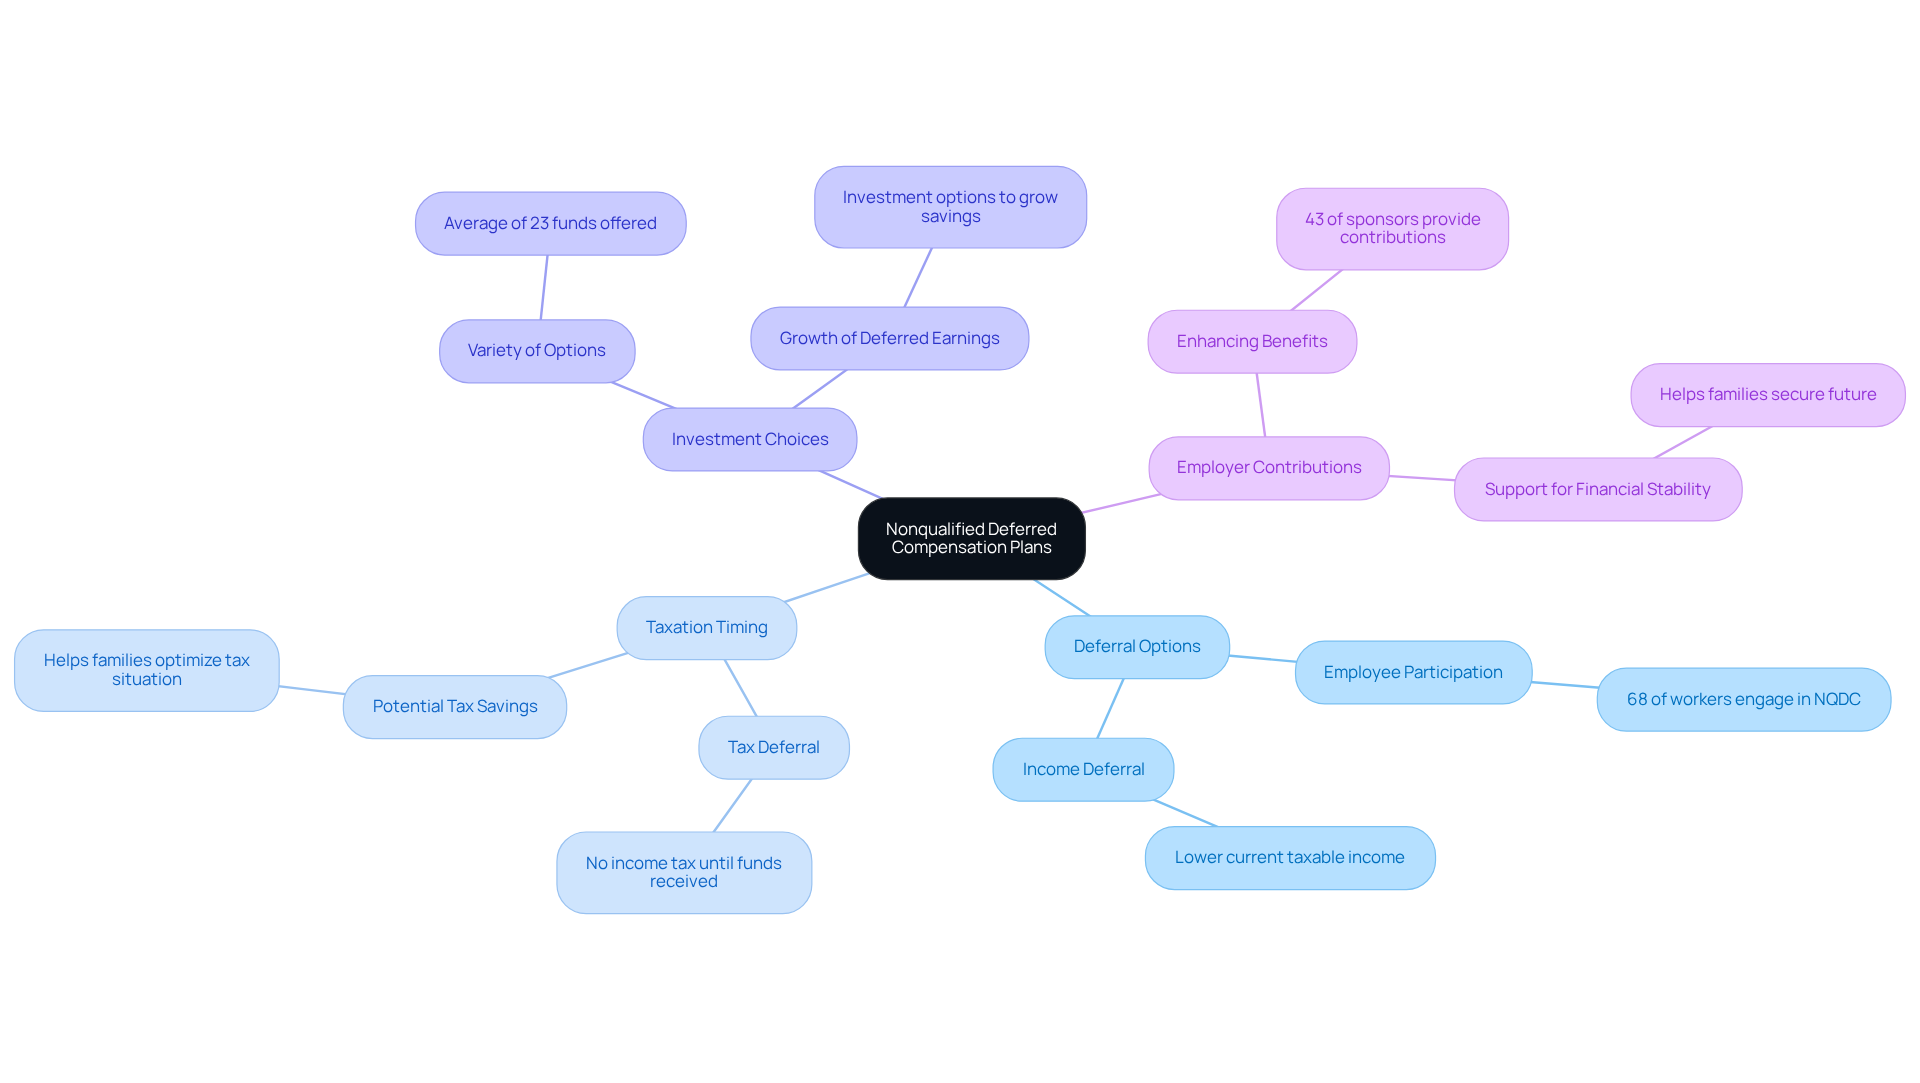
- NQDC plans allow employees to defer income tax withholding until retirement, benefiting families by managing current taxable income.
- Approximately 68% of workers participate in NQDC arrangements primarily for retirement savings.
- Taxation on deferred compensation occurs only upon receipt of funds, potentially leading to tax savings for families.
- NQDC programmes typically offer around 23 investment options, allowing families to grow deferred earnings over time.
- Employer contributions enhance NQDC benefits, with about 43% of sponsors providing these contributions.
- Compliance with IRS regulations, particularly Section 409A, is crucial to avoid penalties associated with NQDC plans.
- Deferred compensation assets are not protected from creditors, posing a risk for participants with significant financial obligations.
- Understanding income tax withholding methods, such as the Percentage Method and Aggregate Method, is essential for effective financial planning.
- Families should stay informed about tax regulations, seek professional guidance, and keep organised records to ensure compliance.
- Utilising resources like IRS publications, monetary calculators, and professional advisors can help families manage their NQDC plans effectively.
Introduction
Many families feel overwhelmed by the complexities of income tax withholding on Nonqualified Deferred Compensation (NQDC). These plans can be a great way to defer income tax until retirement, helping to ease the tax burden during those high-earning years. But it’s important to understand the different withholding mechanisms and compliance requirements to avoid surprises down the road.
How can families navigate these complexities to make the most of their NQDC plans and protect their financial well-being?
Understand Nonqualified Deferred Compensation Plans
Imagine a future where your family’s financial worries are eased, thanks to smart planning today. Nonqualified Deferred Compensation (NQDC) plans help employees, especially those earning more, to delay part of their income tax withholding on nonqualified deferred compensation until retirement. This can be a smart move for families looking to manage their finances effectively.
Key Features of NQDC Plans:
- Deferral Options: You can choose how much of your income to defer, which can lower your current taxable income. About 68% of workers engage in non-qualified deferred compensation arrangements mainly to save for retirement.
- Taxation Timing: You won’t owe income tax withholding on nonqualified deferred compensation until you receive the funds, which can lead to potential tax savings. This is especially helpful for families wanting to optimize their tax situation, just like how we assist families like Jay & Emma in creating sound financial strategies.
- Investment Choices: Many NQDC programs offer a variety of investment options, allowing you to grow your deferred earnings over time. On average, organizations provide around 23 funds in their NQDC offerings. At Bright Advisers, we focus on strategies that truly fit your family’s financial goals, helping you feel confident in your choices, as shown by Emily & Mark’s customized approach.
- Employer Contributions: Some plans may include contributions from your employer, which can enhance the overall benefit. Approximately 43% of sponsors provide these contributions, further supporting families like Allison & Brian in securing their future stability.
Considerations:
- Risk of Noncompliance: NQDC plans must follow IRS regulations, especially Section 409A, to avoid penalties. It’s wise for employers to seek guidance from financial experts to ensure compliance and improve program effectiveness.
- Absence of Safeguards: Resources in deferred compensation arrangements aren’t protected from creditors, which is an important consideration for participants, especially those with significant financial obligations.
Grasping these components is crucial for families aiming to utilize NQDC arrangements as part of their broader financial approach. With 90% of plan participants considering these plans essential for achieving retirement objectives, they present a significant opportunity for families to improve their planning and investment strategies. With the right guidance, you can turn these opportunities into a secure future for your family.
Explore Income Tax Withholding Mechanisms
Imagine feeling secure about your family’s financial future, even when faced with the complexities of income tax withholding on nonqualified deferred compensation. Understanding how income tax withholding on nonqualified deferred compensation works can help you navigate this intricate landscape with confidence.
Let’s explore some common methods of withholding that can impact your family’s finances:
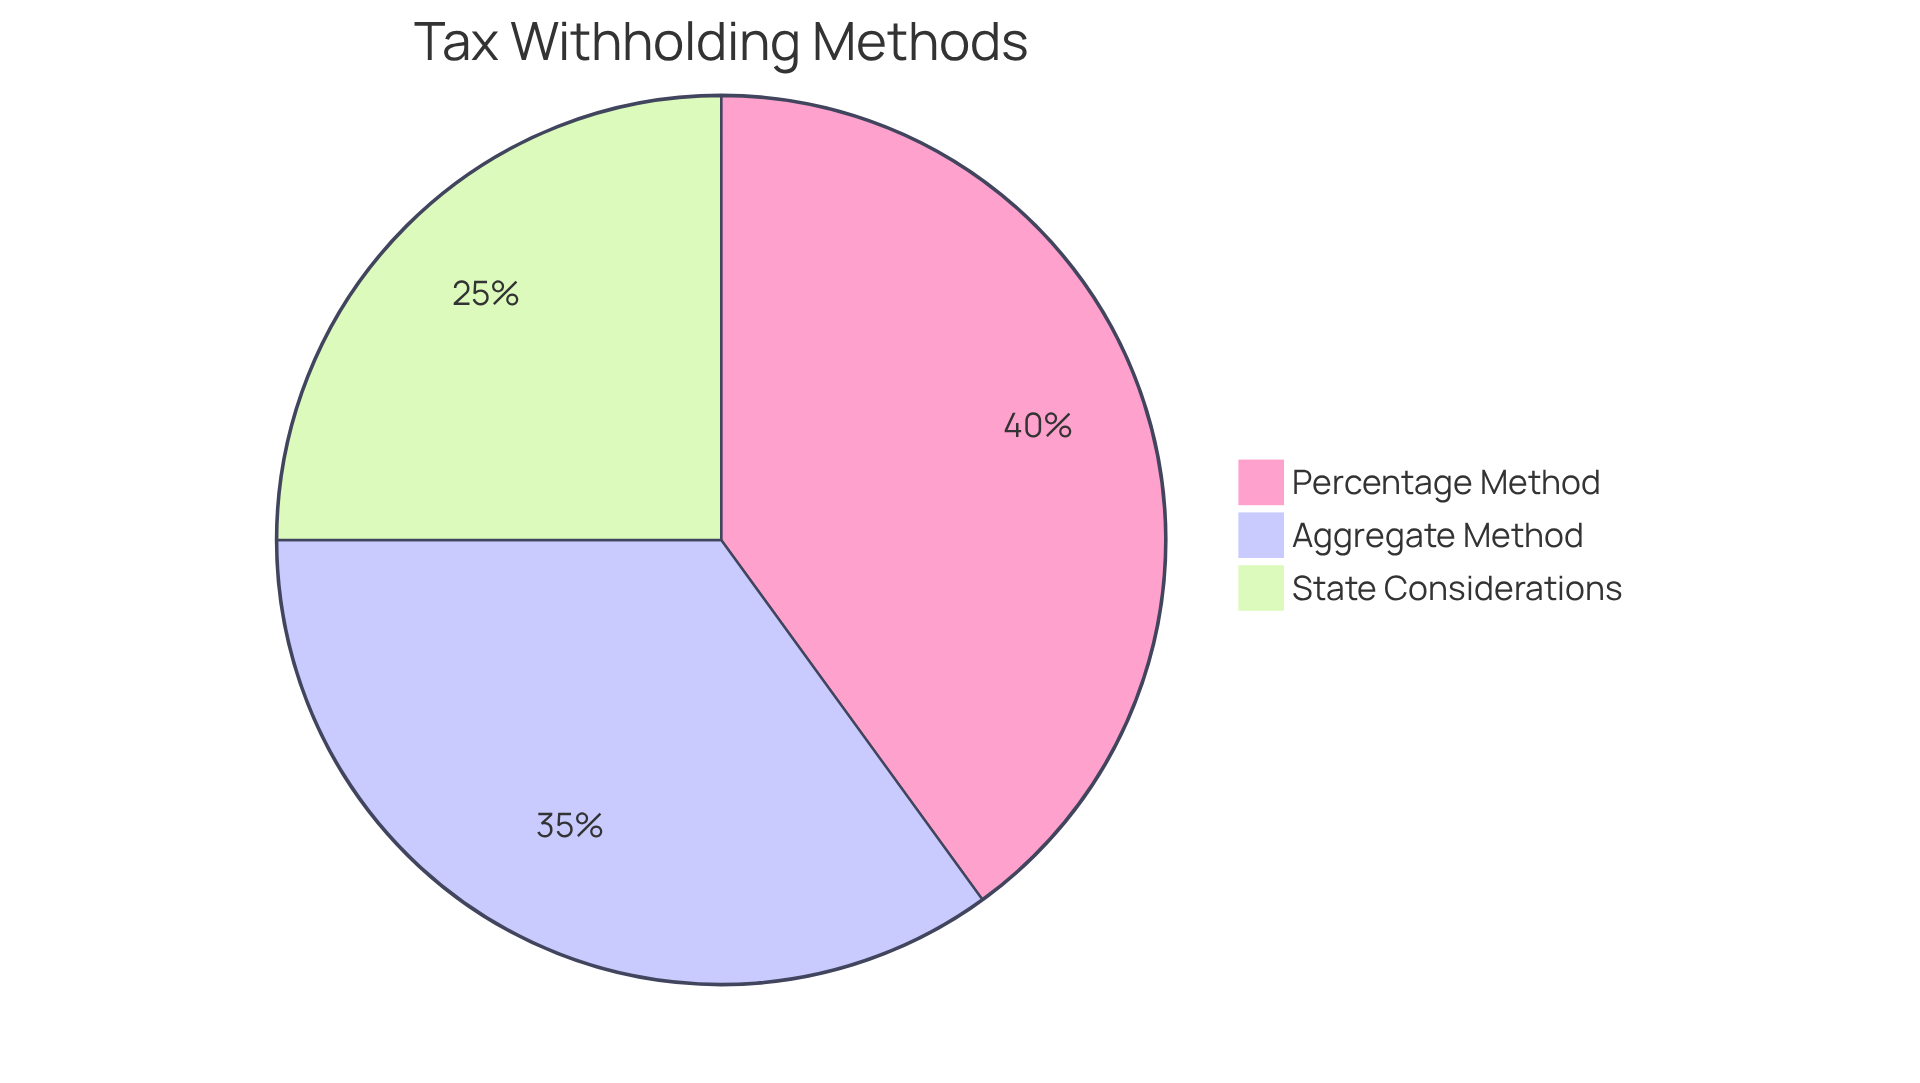
- Percentage Method: Employers may withhold a flat percentage of the distribution, typically around 22% for federal income tax, unless specified otherwise. This straightforward approach can help you anticipate your tax obligations.
- Aggregate Method: This method combines the deferred compensation distribution with your standard wages, which might lead to a higher withholding rate based on your total income. It’s important to be aware of how this could affect your take-home pay.
- State Revenue Considerations: Depending on where you live, additional state income taxes may apply. States like California and New York have higher tax rates, while others, like Texas or Florida, have none. Knowing your state’s tax landscape can help you plan better.
Navigating tax withholding can feel overwhelming, especially when you’re trying to secure your family’s future. Under certain conditions, NQDC may be subject to FICA taxation before federal income taxation, complicating the timing of tax liabilities. It’s important to grasp these rules about income tax withholding on nonqualified deferred compensation so you can steer clear of any surprise tax bills that could catch you off guard.
Compliance is key. Amounts that fail to comply with Section 409A are reported in Box 12 using Code Z. This is essential for preserving the tax-deferred status of non-qualified deferred compensation arrangements. Remember, Non-Qualified Deferred Compensation payouts are taxed as ordinary income, not capital gains, which is an important consideration for families planning their finances.
Take a moment to review your NQDC plan’s withholding options and reach out to a tax advisor. Together, you can ensure everything is in order and make the most of your tax strategy for your family’s benefit.
Consider the story of Avery, who, after being promoted to senior vice president, qualified to enroll in an NQDC plan during the open enrollment period. This opportunity allowed Avery to secure a more stable financial future for their family. Continuous education for both participants and HR teams is essential for the effective functioning of these initiatives. Effective communication fosters trust and clarity, reducing the risk of confusion and dissatisfaction among employees regarding their deferred compensation.
By understanding these tax implications, you can take proactive steps to safeguard your family’s financial well-being.
Implement Best Practices for Tax Compliance
Imagine feeling secure about your family’s financial future while navigating the complexities of tax regulations together. To ensure compliance with tax regulations regarding Nonqualified Deferred Compensation (NQDC) plans, families should adopt the following best practices:
-
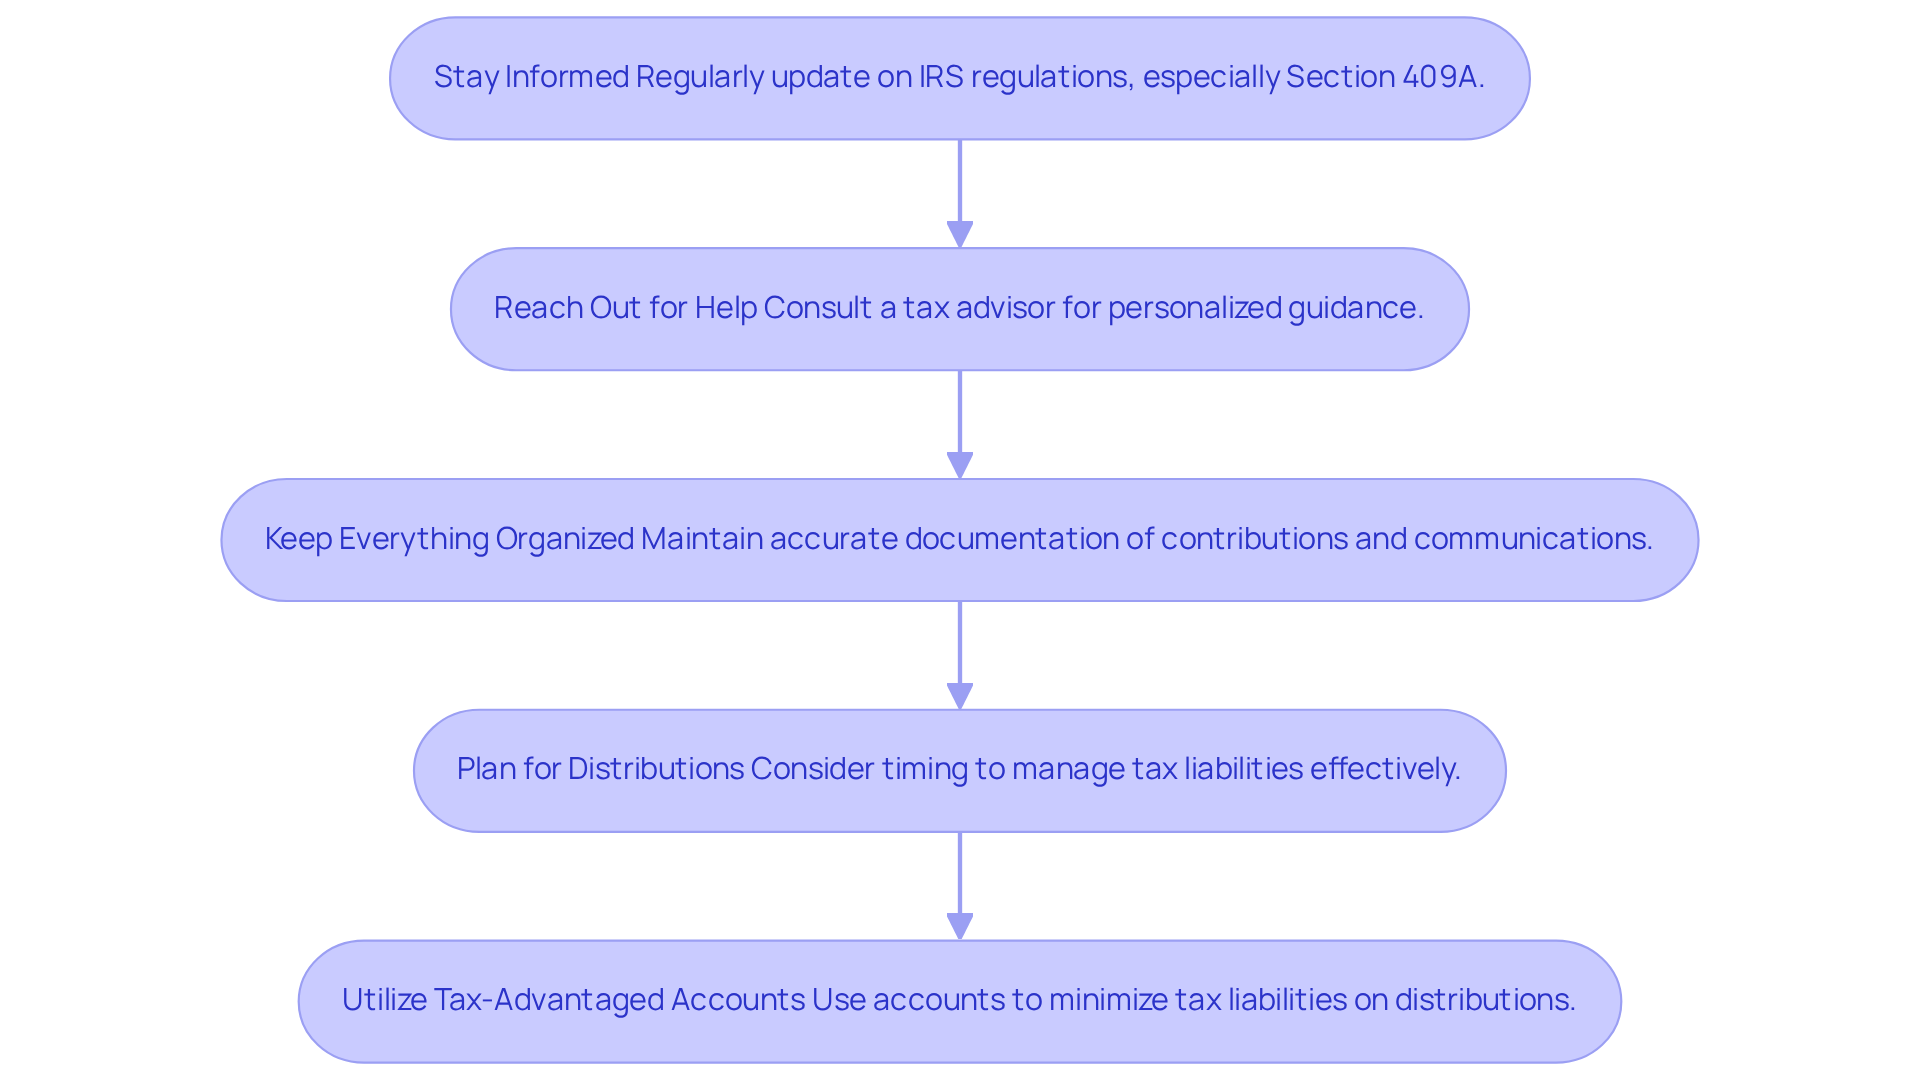
Stay Informed: Regularly update yourself on IRS regulations, particularly Section 409A. Understanding these rules helps ensure your non-qualified deferred compensation arrangement remains compliant with income tax withholding on nonqualified deferred compensation. It’s important to grasp the consequences of any changes in the law that could influence your strategy.
-
Reach Out for Help: It’s a good idea to reach out to a tax advisor who understands your family’s unique needs. They can help you navigate the complex tax implications and develop an effective strategy. Their expertise can help you avoid costly mistakes. As Corey F. Schechter notes, “Nonqualified Deferred Compensation arrangements are invaluable tools for executives and key employees by offering customized compensation packages and aligning their financial interests with the company’s long-term goals.”
-
Keep Everything Organized: Keep a close eye on all your contributions and communications; it helps ensure everything is in order for your family’s future. Accurate documentation is essential for ensuring compliance with income tax withholding on nonqualified deferred compensation and precise tax reporting. The IRS highlights that written terms must align with actual operations, and any divergence can lead to penalties.
-
Plan for Distributions: Think carefully about when to take distributions to manage tax liabilities effectively. Receiving large distributions in a single year can push you into a higher tax bracket. Consider spreading distributions over multiple years if possible. For instance, a research manager received a payment of $50,000 in a year earlier than elected, highlighting the importance of timing.
-
Utilize Tax-Advantaged Accounts: Consider using tax-advantaged accounts for any distributions to further minimize tax liabilities. This can enhance your overall monetary strategy and help preserve wealth for future generations. Remember, the yearly compensation cap under section 401(a)(17) was $265,000 for 2016, which is essential for families to consider when planning their non-qualified deferred compensation distributions.
By following these best practices, you can protect your family’s financial future and ensure peace of mind as you navigate this journey together.
Utilize Resources and Tools for Effective Management
Imagine navigating the complexities of financial planning while juggling the needs of your family – it’s no small feat, is it? Effectively managing strategies for income tax withholding on nonqualified deferred compensation can feel overwhelming, but with the right resources, you can make informed decisions that benefit your loved ones.
Here are some valuable options to consider:
-
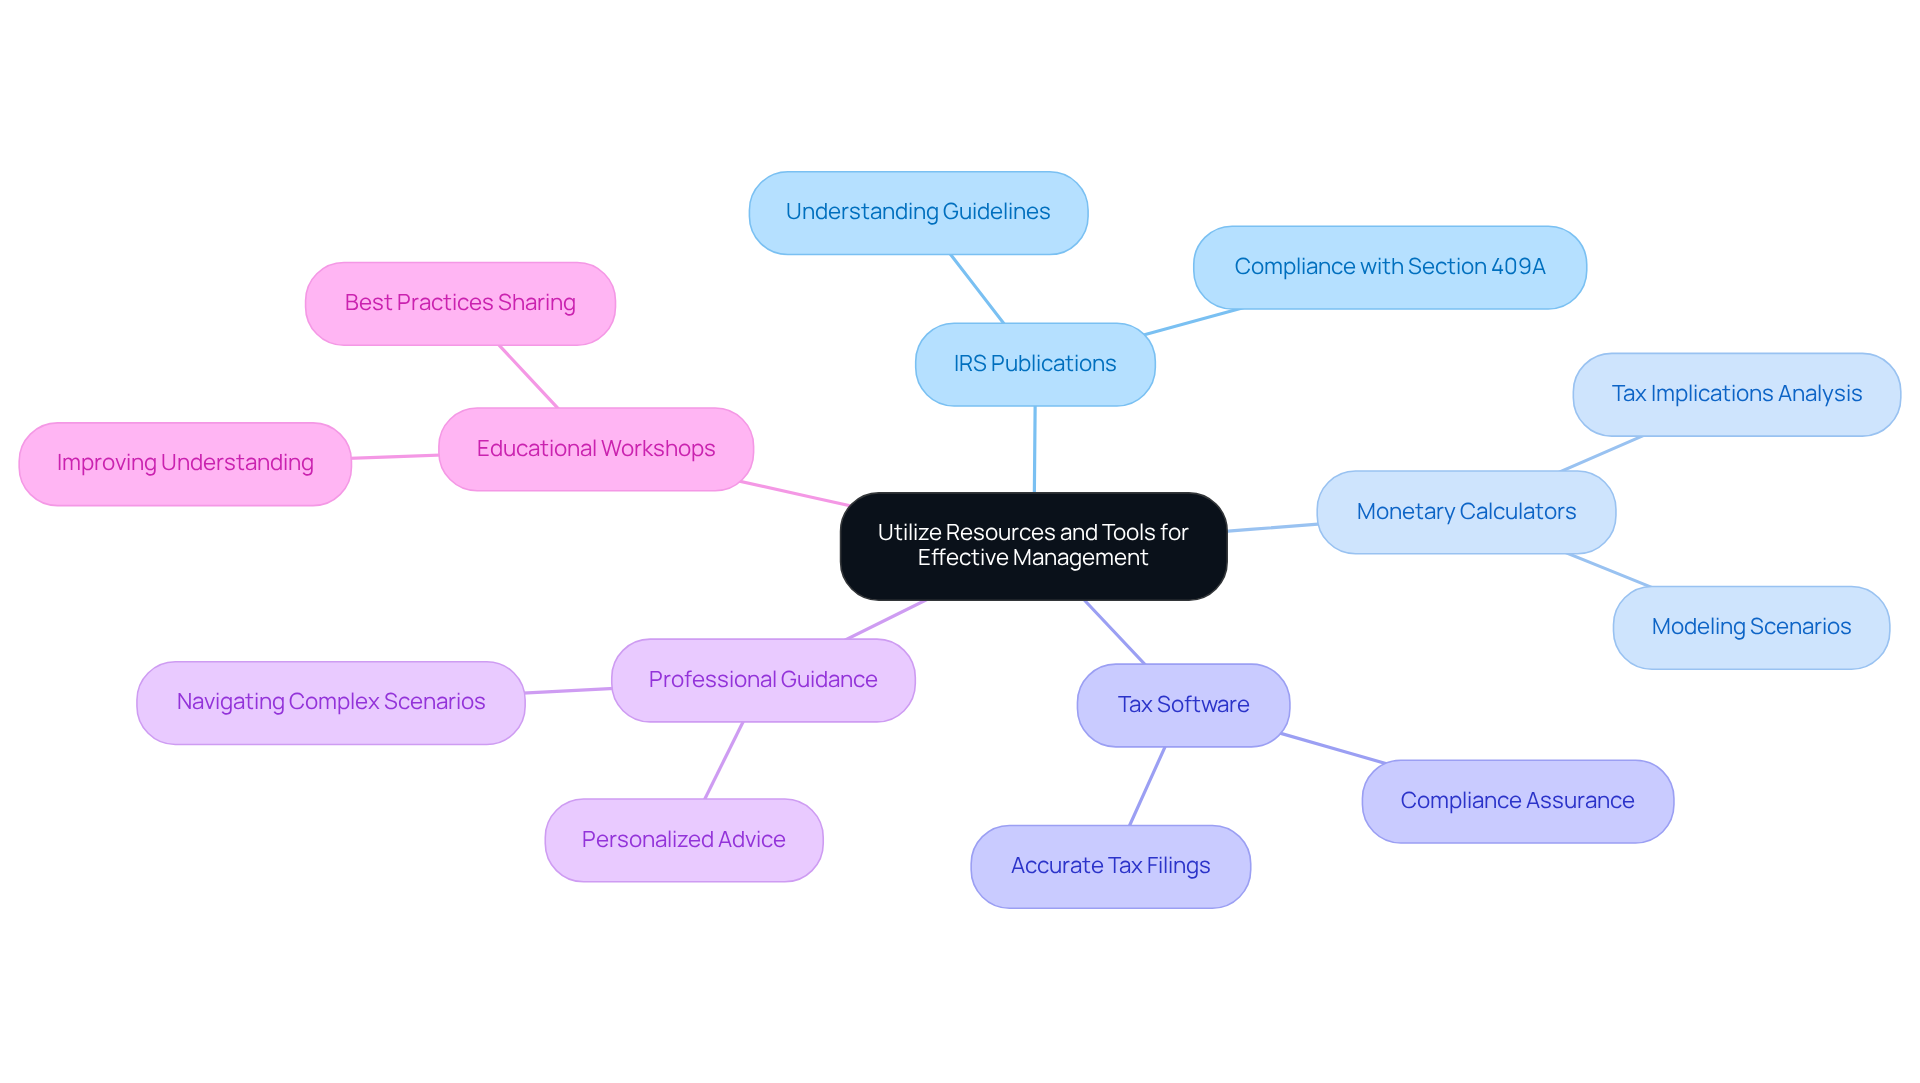
IRS Publications: Dive into IRS publications related to non-qualified deferred compensation arrangements and Section 409A. Understanding these guidelines is crucial for compliance and for optimizing your family’s income tax withholding on nonqualified deferred compensation benefits.
-
Monetary Calculators: Utilize online monetary calculators to model different scenarios regarding distributions and tax implications. These tools can help you make informed choices about your non-qualified deferred compensation options, especially since 95% of Fortune 1000 companies support such arrangements.
-
Tax software that includes features for reporting income tax withholding on nonqualified deferred compensation distributions should be considered. This ensures accurate tax filings and compliance with federal and state guidelines, which is essential for avoiding penalties.
-
Professional Guidance: Reach out to friendly advisors or tax specialists who can help you understand NQDC arrangements better. Their expertise can provide personalized advice tailored to your family’s financial situation, guiding you through complex tax scenarios.
-
Educational Workshops: Attend workshops or webinars focused on NQDC initiatives and tax strategies. These sessions can improve your understanding and keep your family informed about best practices, enabling you to manage your strategies effectively.
With these resources at your fingertips, you can confidently manage your NQDC plans, ensuring your family’s financial well-being is prioritized. By taking these steps, you can ensure your family’s financial future is secure, allowing you to focus on what truly matters – your loved ones.
Conclusion
Imagine navigating the complexities of income tax withholding on nonqualified deferred compensation without the right support. Mastering this area is essential for families aiming to secure their financial future. When families understand NQDC plans, they can manage their tax obligations better and make smarter financial choices. This knowledge empowers them to make informed decisions that align with their long-term goals.
Think about the key insights we’ve explored together about NQDC plans – like how deferral options and timing can shape your family’s financial future. We’ve also highlighted the importance of compliance with IRS regulations, especially Section 409A, to avoid penalties. Staying informed, seeking professional guidance, and utilizing available resources are best practices that can help families navigate these complexities.
With these strategies, families can feel more confident as they navigate the complexities of income tax withholding together. Families are encouraged to take proactive steps, such as consulting with tax advisors and utilizing educational resources, to ensure they are well-prepared for the financial implications of their decisions. Taking these steps today can pave the way for a secure financial future for your family, ensuring peace of mind for generations to come.
Frequently Asked Questions
What is a Nonqualified Deferred Compensation (NQDC) plan?
An NQDC plan allows employees, particularly those earning more, to delay part of their income tax withholding on nonqualified deferred compensation until retirement, helping families manage their finances effectively.
What are the key features of NQDC plans?
Key features include deferral options that lower current taxable income, taxation timing that delays income tax until funds are received, a variety of investment choices to grow deferred earnings, and potential employer contributions that enhance benefits.
How do deferral options work in NQDC plans?
Employees can choose how much of their income to defer, which can lower their current taxable income. About 68% of workers engage in NQDC arrangements mainly to save for retirement.
When do you owe taxes on NQDC funds?
You won’t owe income tax withholding on nonqualified deferred compensation until you receive the funds, which can lead to potential tax savings.
What investment choices are typically available in NQDC plans?
Many NQDC programs offer a variety of investment options, with organizations providing an average of around 23 funds in their offerings.
Do employers contribute to NQDC plans?
Yes, some NQDC plans may include contributions from employers, with approximately 43% of sponsors providing these contributions to enhance the overall benefit.
What are the risks associated with NQDC plans?
Risks include the potential for noncompliance with IRS regulations, particularly Section 409A, which can lead to penalties, and the absence of safeguards, as resources in deferred compensation arrangements are not protected from creditors.
Why are NQDC plans considered essential for retirement planning?
About 90% of plan participants consider NQDC plans essential for achieving retirement objectives, making them a significant opportunity for families to improve their planning and investment strategies.
List of Sources
- Understand Nonqualified Deferred Compensation Plans
- Trends in nonqualified deferred compensation plans (https://principal.com/businesses/trends-insights/trends-nonqualified-deferred-compensation-plans)
- Nonqualified Deferred Compensation Plans (NQDCs) | Fidelity Investments (https://fidelity.com/viewpoints/retirement/nqdc)
- Here’s Why Companies Offer Nonqualified Deferred Compensation Plans (https://napa-net.org/news/2025/2/heres-why-companies-offer-nonqualified-deferred-compensation-plans)
- Survey Finds NQDC Plans Effective, but Still Underused | PLANADVISER (https://planadviser.com/survey-finds-nqdc-plans-effective-but-still-underused)
- Explore Income Tax Withholding Mechanisms
- Non-Qualified Deferred Compensation Plans: Employer Guide (https://rippling.com/blog/non-qualified-deferred-compensation-plan)
- State income tax implications with deferred compensation (https://wipfli.com/insights/articles/tax-state-income-tax-implications-with-deferred-compensation)
- Nonqualified deferred compensation and state taxes | Fidelity (https://fidelity.com/learning-center/personal-finance/nqdc-state-taxes)
- Tax reporting for NQDC plans: A guide for deferred compensation arrangements | Voya.com (https://voya.com/voya-insights/tax-reporting-nqdc-plans-guide-deferred-compensation-arrangements)
- Implement Best Practices for Tax Compliance
- Application of Section 409A to Nonqualified Deferred Compensation Plans (https://federalregister.gov/documents/2016/06/22/2016-14331/application-of-section-409a-to-nonqualified-deferred-compensation-plans)
- Section 409A compliance: Errors, penalties, & corrections | Our Insights | Plante Moran (https://plantemoran.com/explore-our-thinking/insight/2019/01/409a-compliance-errors-penalties-and-corrections)
- Frequently Asked Questions on IRC § 409A Nonqualified Deferred Compensation Plans and The Risks on Noncompliance (https://sblgllp.com/frequently-asked-questions-on-irc-409a-nonqualified-deferred-compensation-plans-and-the-risks-on-noncompliance)
- 26 U.S. Code § 409A – Inclusion in gross income of deferred compensation under nonqualified deferred compensation plans (https://law.cornell.edu/uscode/text/26/409A)
- Utilize Resources and Tools for Effective Management
- Survey Finds NQDC Plans Effective, but Still Underused | PLANADVISER (https://planadviser.com/survey-finds-nqdc-plans-effective-but-still-underused)
- Advisors – Practical Applications of Non-Qualified Deferred Compensation Grand Junction Colorado Lawyer Attorney Law Firm (https://thplaw.net/index.aspx?TypeContent=ARTICLES&Art_Title=Advisors—Practical-Applications-of-Non-Qualified-Deferred-Compensation&art_id=304)
- 2025 NQDC Survey (https://psca.org/industry-content/surveys/nqdc-survey)
- Tax reporting for NQDC plans: A guide for deferred compensation arrangements | Voya.com (https://voya.com/voya-insights/tax-reporting-nqdc-plans-guide-deferred-compensation-arrangements)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading