

Key Highlights
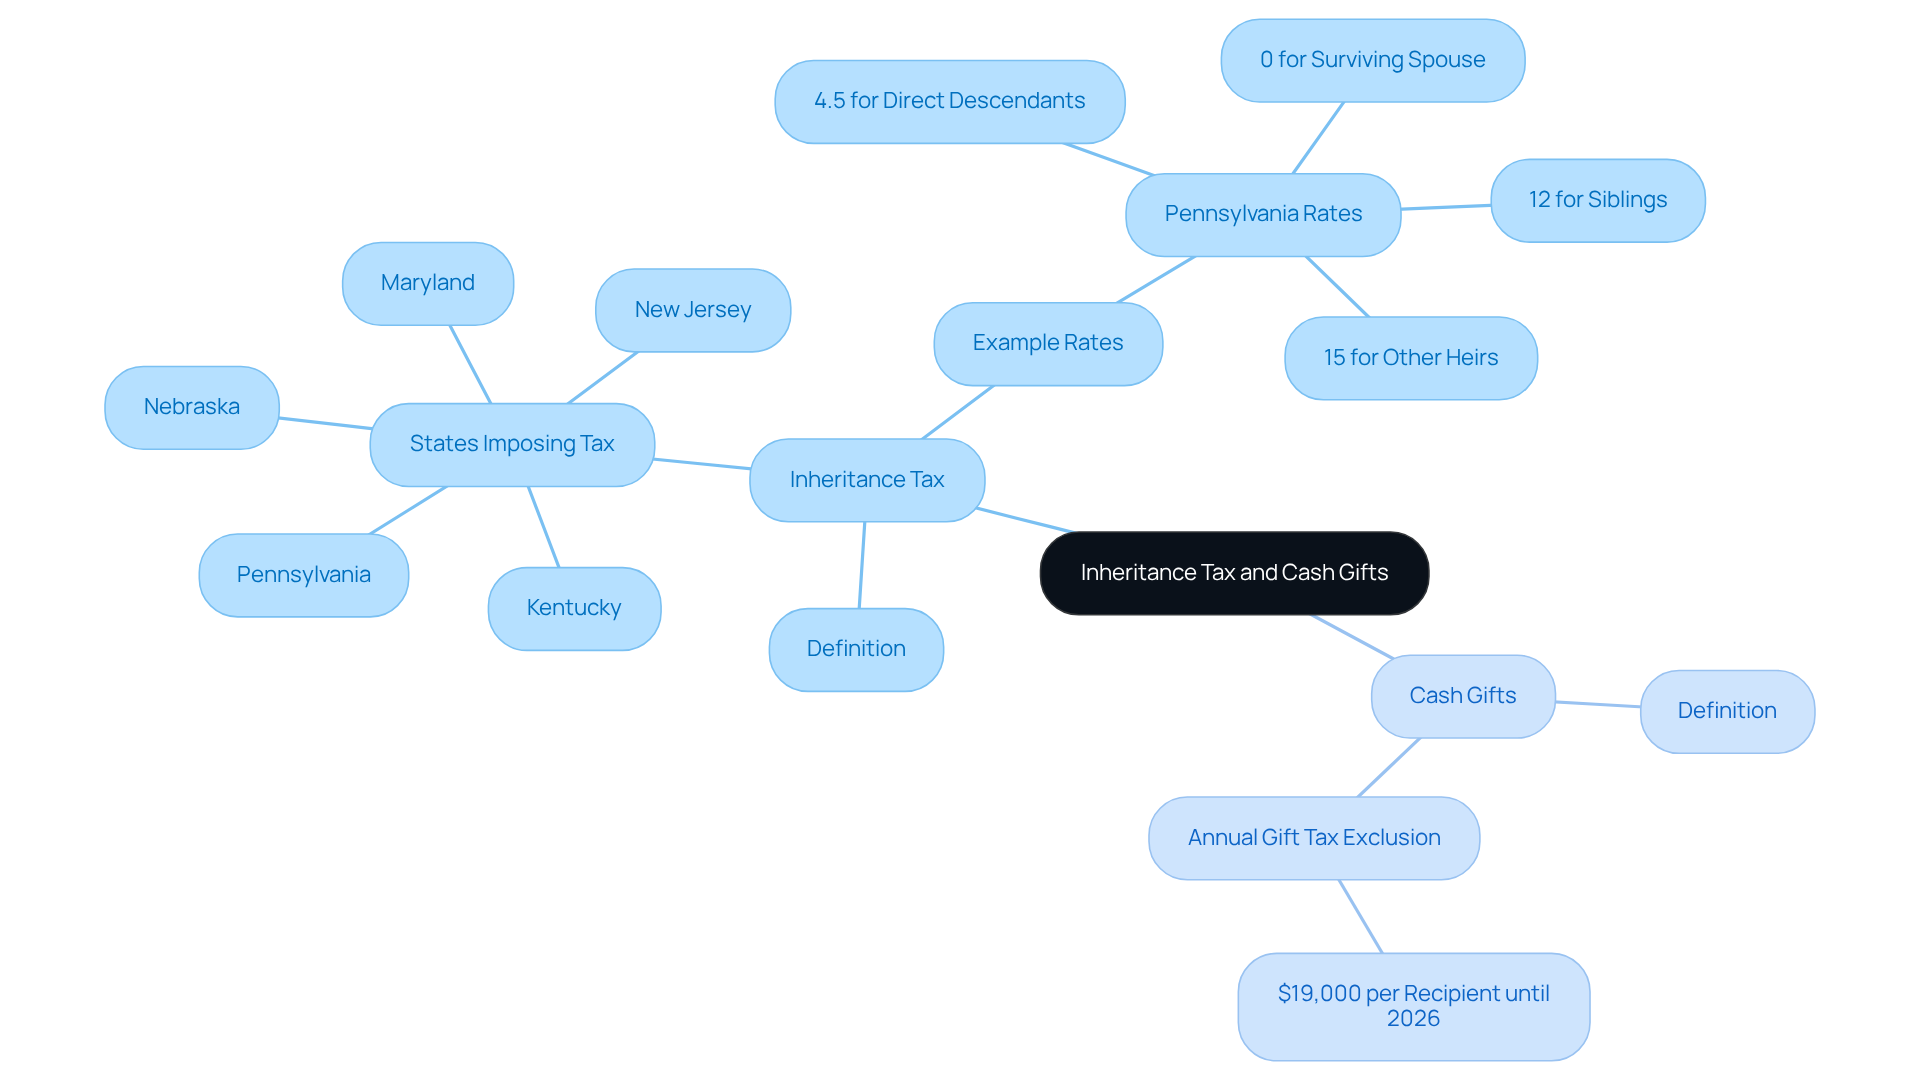
- Inheritance tax is a state-level tax on assets inherited from a deceased individual, paid by beneficiaries, with only five states imposing it: Kentucky, Nebraska, New Jersey, Pennsylvania, and Maryland.
- Pennsylvania’s inheritance tax rates vary, with 0% for transfers to a surviving spouse or a parent from a child aged 21 or younger, and up to 15% for other heirs.
- Cash gifts are monetary transfers made without expecting anything in return, which can help reduce the taxable estate of the donor.
- The annual gift tax exclusion allows individuals to gift up to $19,000 per recipient without incurring gift tax until 2026, doubling to $38,000 for married couples.
- Direct payments for educational or medical expenses are exempt from taxation, allowing families to support loved ones without tax implications.
- Gifts over $19,000 can affect the lifetime tax exemption, currently set at $15 million, and gifts made within three years of passing may count against the taxable estate.
- Effective cash gifting strategies include planning ahead, utilising annual exclusions, making direct payments for expenses, documenting contributions, and consulting a professional.
- Bright Advisers emphasises fiduciary duty and transparency in wealth management, helping families navigate tax implications and secure their financial legacy.
Introduction
Imagine feeling lost in a maze of inheritance tax and cash gifts while trying to secure your family’s financial future. It’s important to understand how these elements work together, as your choices today can shape your loved ones’ futures.
So, what can you do to manage cash gifts wisely and ease the burden of inheritance tax? Together, we’ll explore practical strategies that help you make informed choices, ensuring your family’s wealth is not just preserved but passed on with love.
Define Inheritance Tax and Cash Gifts
Imagine facing the complexities of inheritance tax cash gifts while trying to secure your family’s future. Inheritance tax is a state-level tax imposed on the value of assets inherited from a deceased individual. Unlike estate tax, which is levied on the estate before distribution, inheritance tax is paid by the beneficiaries receiving the assets. This tax varies by state, with only five states currently imposing it:
- Kentucky
- Nebraska
- New Jersey
- Pennsylvania
- Maryland
For instance, Pennsylvania has an inheritance tax rate of 0% for transfers to a surviving spouse or to a parent from a child aged 21 or younger, while rates can go up to 15% for other heirs.
Monetary transfers are simply gifts given from one person to another, without expecting anything back. These contributions can be made during a person’s lifetime and are often utilized as a method to decrease the taxable estate of the donor. The annual gift tax exclusion allows individuals to gift up to $19,000 per recipient without incurring gift tax until 2026. Understanding these definitions is crucial for households aiming to navigate the complexities of wealth transfer and tax implications effectively.
We understand that managing wealth intentionally is crucial for families like yours. As you contemplate the implications of inheritance tax cash gifts and monetary presents, remember that these choices can significantly influence your family’s financial legacy. With the right support, you can ensure your family’s financial legacy is protected for generations to come.
Explore Cash Gift Limits and Exemptions
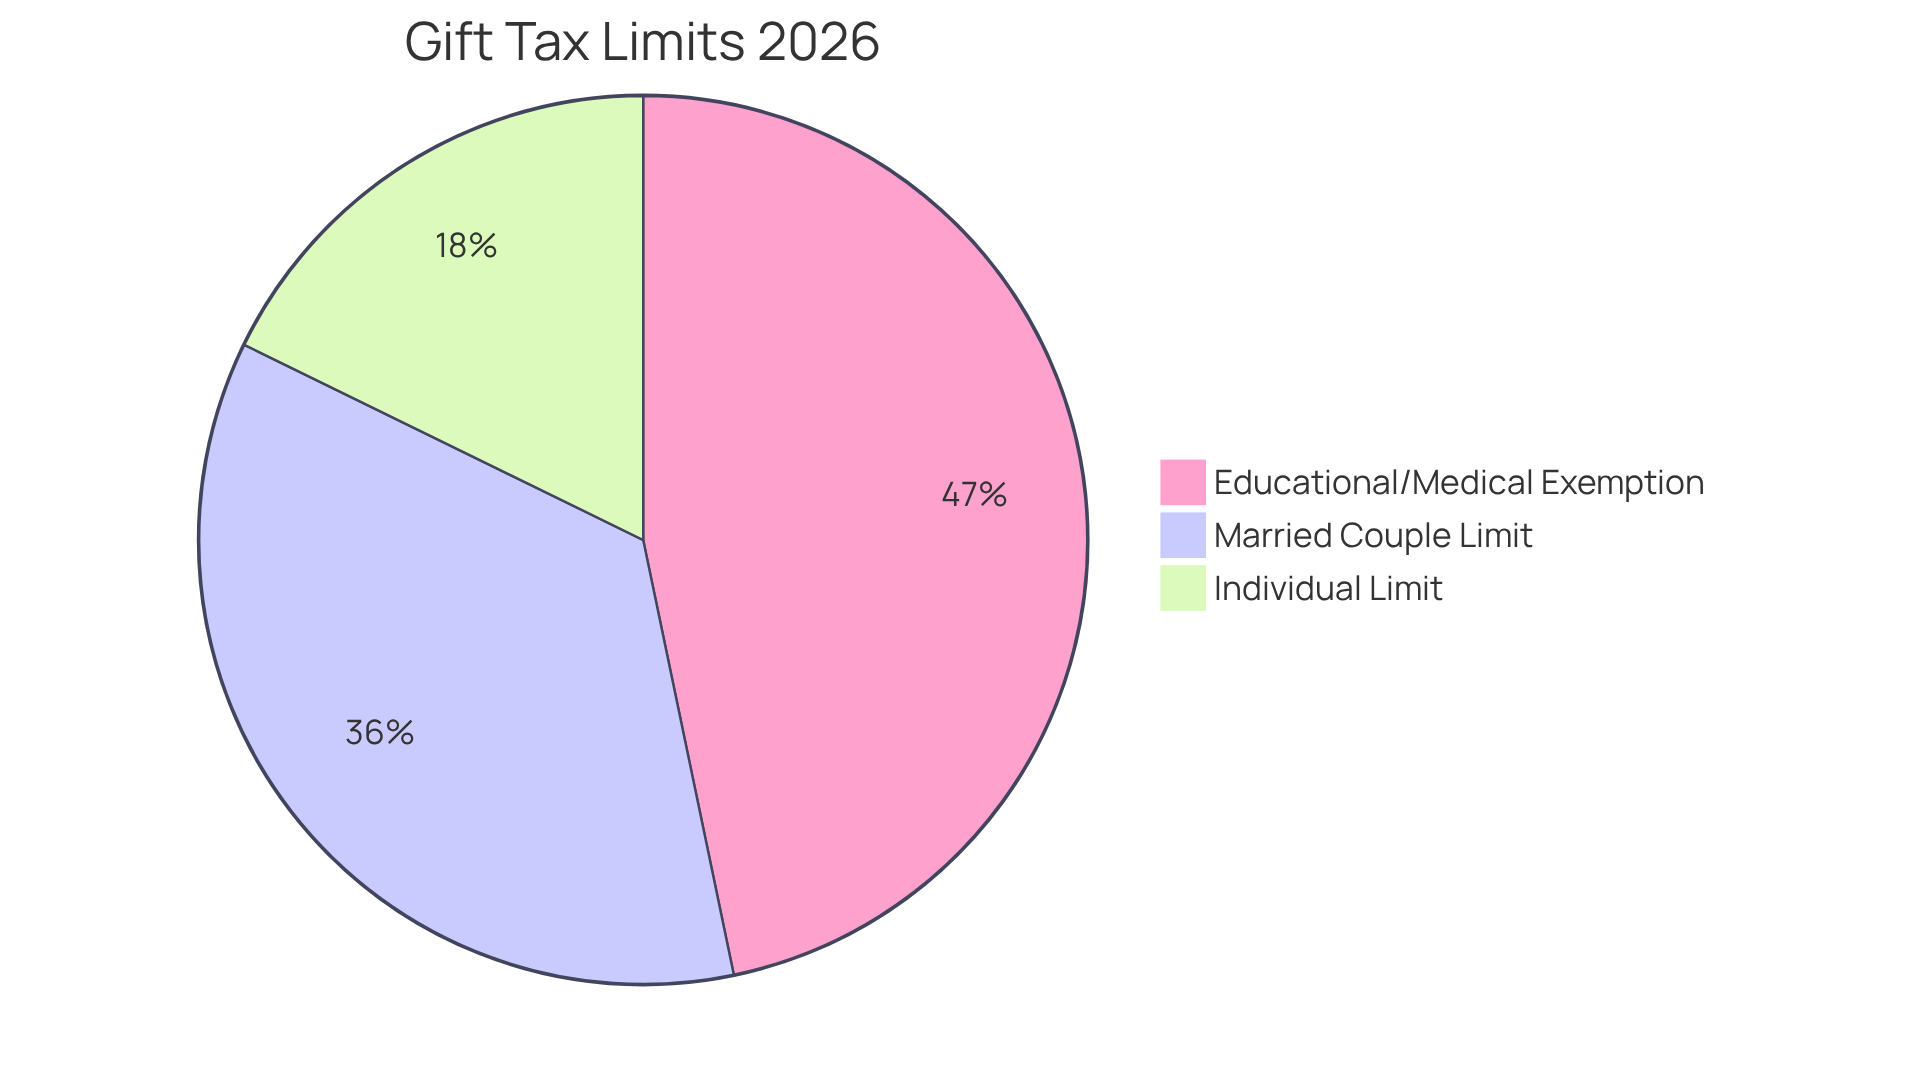
Imagine being able to gift your loved ones as inheritance tax cash gifts without the worry of tax penalties. In 2026, you can gift up to $19,000 to each person without worrying about federal gift tax. If you’re married, that limit doubles to $38,000 when both partners agree to share the contribution.
What’s even better? Contributions for educational or medical expenses are exempt from taxation if paid directly to the institution or provider. For instance, a grandparent could pay $50,000 of a grandchild’s college tuition directly to the college and still give another $19,000 tax-free.
Understanding these limits can help your family transfer wealth smoothly and avoid unnecessary tax worries related to inheritance tax cash gifts. Consistent annual gifting can significantly reduce the size of a taxable estate and minimize future exposure to inheritance tax cash gifts.
We encourage families to chat with their tax professionals before making big contributions to ensure your strategies align with your long-term financial goals. Together, we can navigate this journey toward a secure future for your family.
Understand the Impact of Cash Gifts on Inheritance Tax
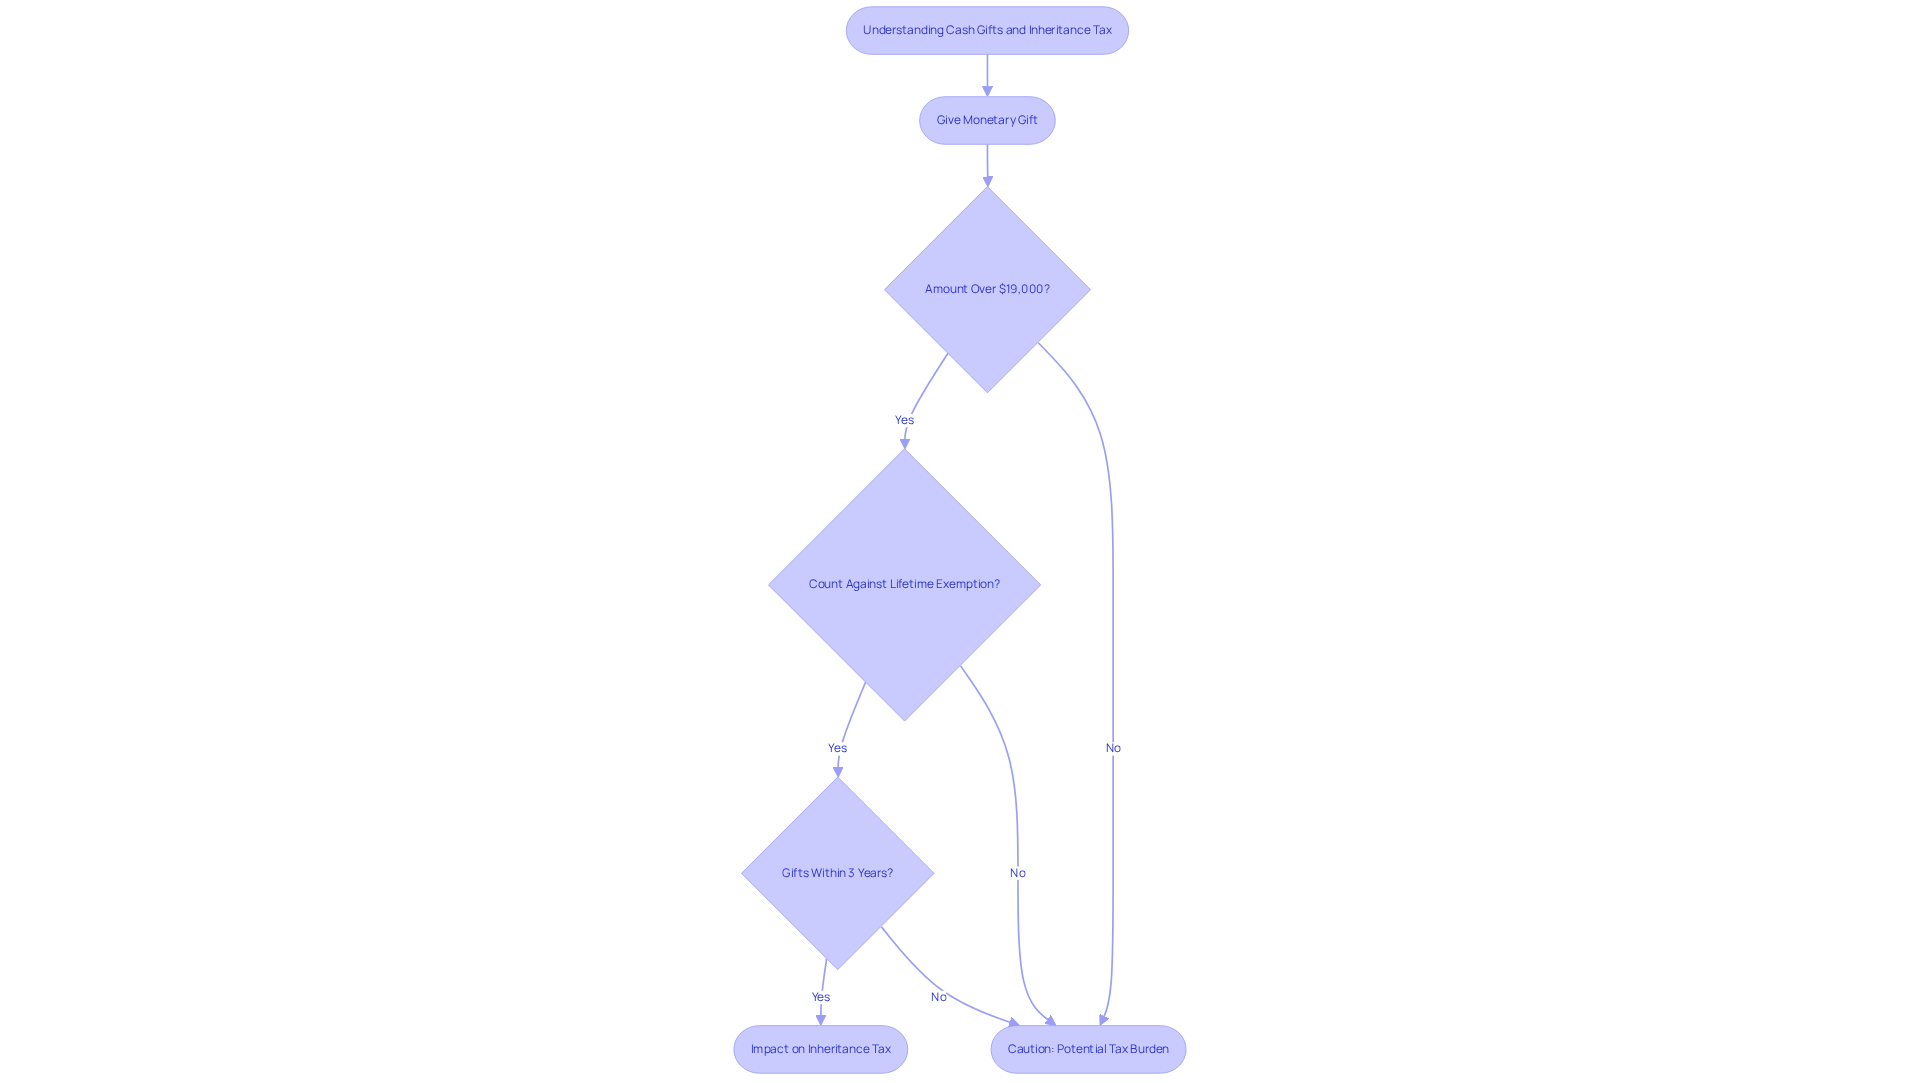
Imagine feeling secure about your family’s financial future while navigating the complexities of inheritance tax assessments. Monetary gifts can significantly affect the amount of inheritance tax cash gifts that your loved ones may owe. When you give a monetary gift over $19,000, it can affect your lifetime tax exemption, which is currently $15 million and adjusted for inflation. It’s also important to know that gifts given within three years of passing can be counted in the taxable estate, which might increase the burden of inheritance tax cash gifts on your loved ones.
For instance, if you give $50,000 to your child, $31,000 will count against your lifetime exemption, leaving you with $14,969,000 for future gifts without tax implications. By timing your gifts wisely and staying within the limits, you can help lessen the burden of inheritance tax cash gifts on your loved ones and protect your family’s future. This is especially important as fewer families are facing estate taxes today, thanks to higher exemptions and deductions. By grasping these concepts, you can make informed choices about passing on your wealth and planning for your family’s future.
Consider the situation of Allison and Brian, who sought guidance from Bright Advisers to enhance their economic potential through proper tax planning. They learned specific strategies, such as leveraging annual gift exclusions and timing their gifts effectively, which allowed them to secure their children’s future through education funding while also gaining the ability to retire sooner. By integrating tax strategies into their comprehensive plan, they experienced peace of mind and economic stability, enabling them to enjoy more quality time with their loved ones. This success story demonstrates how households can gain from strategic tax planning and personalized financial solutions, ensuring a brighter future for their children.
Implement Strategies for Effective Cash Gifting
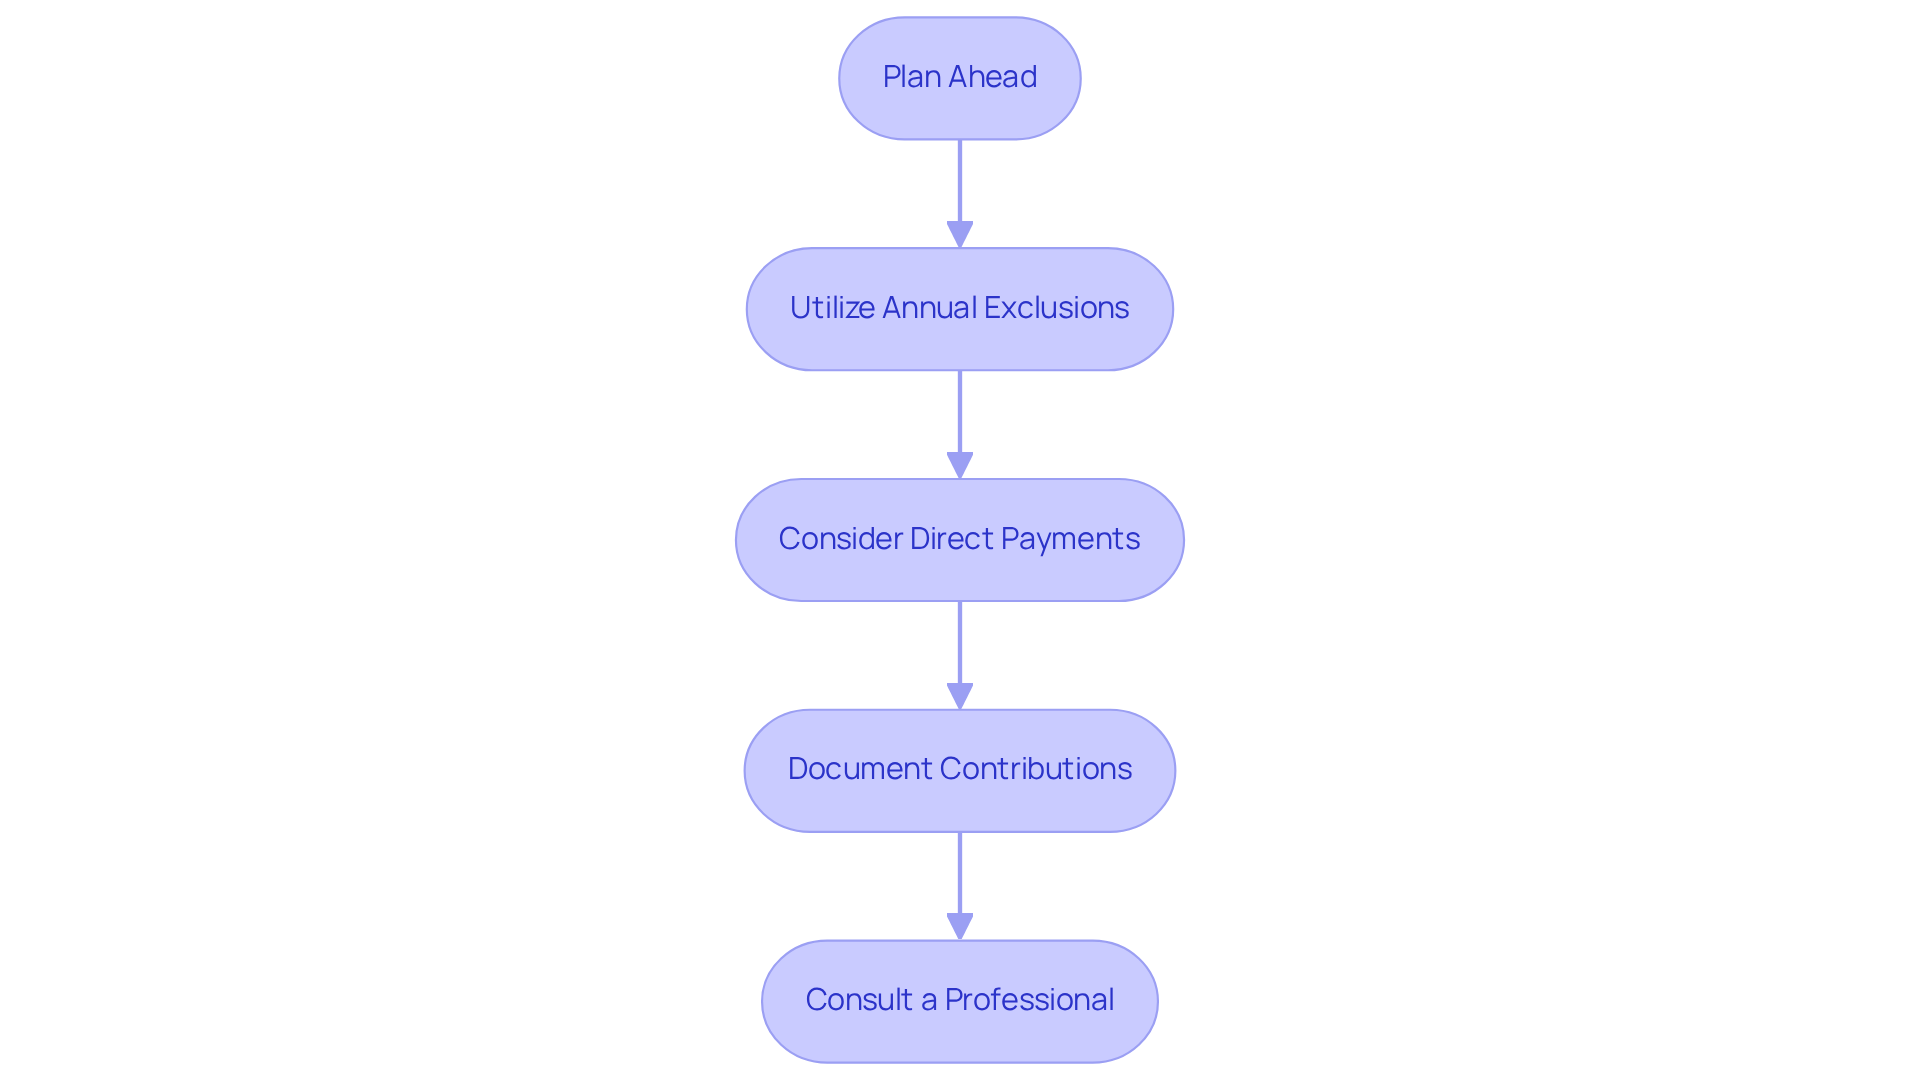
Imagine feeling confident about your family’s financial future while navigating the complexities of inheritance tax cash gifts. To implement effective cash gifting strategies, families should consider a few important steps:
- Plan Ahead: Think about the total amount you want to give and who will receive it. This foresight helps maximize the benefits of inheritance tax cash gifts.
- Utilize Annual Exclusions: In 2026, the annual tax exclusion for gifts is set at $19,000 per recipient. Families can give this amount as inheritance tax cash gifts to multiple recipients without triggering taxes or reducing their lifetime exemption. Plus, married couples can combine exclusions for a total of $38,000 per recipient when splitting contributions, thereby reducing their potential inheritance tax cash gifts.
- Consider Direct Payments: For educational or medical expenses, paying institutions directly allows families to support loved ones without tax implications. For instance, a grandparent can pay $60,000 in tuition directly to a university without it being considered a taxable transfer. Remember, direct payments for educational or medical expenses do not count toward the annual exclusion limit for inheritance tax cash gifts.
- Document Contributions: Keep thorough records of all donations, including dates and amounts. This documentation is essential for following IRS regulations and helps track cumulative contributions over time, including inheritance tax cash gifts. Don’t forget that IRS Form 709 is necessary when any individual contribution exceeds the $19,000 annual exclusion.
- Consult a Professional: Talking to a financial planner or tax advisor can really help you tailor your gifting strategy to fit your family’s unique needs and dreams. As emphasized, “Coordination matters,” and professionals can provide insights on how to structure gifts effectively, especially with changing tax laws. Bright Advisers offers integrated in-house tax planning services to help families navigate these complexities.
By using these strategies, families like Jay & Emma can ease financial stress and prepare for their children’s education while managing wealth transfer and minimizing taxes. Bright Advisers’ dedication to customized wealth management solutions ensures that families receive the support they need to make informed choices about their legacy. Plus, our transparent, all-inclusive fee structure means there are no hidden fees, commissions, or conflicts of interest, allowing families to focus on what truly matters: their financial future.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. All advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Conclusion
Imagine feeling confident about your family’s financial legacy, even amidst the complexities of inheritance tax and cash gifts. Understanding these distinctions can empower you to make informed decisions that significantly impact your family’s wealth transfer strategies. Many families feel overwhelmed by the intricacies of these topics, unsure of how to navigate these important financial decisions. But with the right knowledge, you can feel empowered to make choices that truly benefit your loved ones.
Key insights include:
- The importance of annual gift tax exclusions
- The benefits of direct payments for educational and medical expenses
- The necessity of thorough documentation
These strategies not only help in reducing the taxable estate but also ensure that you can gift your loved ones without incurring unnecessary tax penalties. Engaging with professionals like Bright Advisers can further enhance these efforts, providing tailored guidance that aligns with your family’s unique financial goals.
By taking these proactive steps, you can ensure your family’s financial legacy is not just preserved, but cherished for generations to come. Together, we can navigate this journey, ensuring that your financial legacies are protected and valued for years to come.
Frequently Asked Questions
What is inheritance tax?
Inheritance tax is a state-level tax imposed on the value of assets inherited from a deceased individual. It is paid by the beneficiaries receiving the assets, unlike estate tax, which is levied on the estate before distribution.
Which states impose inheritance tax?
Currently, only five states impose inheritance tax: Kentucky, Nebraska, New Jersey, Pennsylvania, and Maryland.
How does Pennsylvania’s inheritance tax rate work?
In Pennsylvania, the inheritance tax rate is 0% for transfers to a surviving spouse or to a parent from a child aged 21 or younger. For other heirs, the rates can go up to 15%.
What are cash gifts?
Cash gifts are monetary transfers given from one person to another without expecting anything in return. These gifts can be made during a person’s lifetime and are often used to decrease the taxable estate of the donor.
What is the annual gift tax exclusion?
The annual gift tax exclusion allows individuals to gift up to $19,000 per recipient without incurring gift tax until 2026.
Why is understanding inheritance tax and cash gifts important for families?
Understanding these concepts is crucial for households aiming to navigate the complexities of wealth transfer and tax implications effectively, which can significantly influence a family’s financial legacy.
List of Sources
- Define Inheritance Tax and Cash Gifts
- Estate tax vs. inheritance tax: Who pays & in which states? (https://thrivent.com/insights/estate-planning/estate-tax-vs-inheritance-tax-who-pays-and-in-which-states)
- Estate and Inheritance Taxes by State (https://taxfoundation.org/data/all/state/estate-inheritance-taxes)
- End of Tax Season Messages, Inspirational & Funny Quotes for Accountants & CPAs (https://swagmagic.com/blog/end-of-tax-season-quotes)
- Inheritance Tax (https://pa.gov/agencies/revenue/resources/tax-types-and-information/inheritance-tax)
- What Is Inheritance Tax? | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/trust-and-estate-planning/what-is-inheritance-tax.html)
- Explore Cash Gift Limits and Exemptions
- 2026 Gift Tax Exclusions (https://farmoffice.osu.edu/blog/tue-02172026-710pm/2026-gift-tax-exclusions)
- What is the Annual Gift Tax Exclusion Limit for 2026? (https://adamsbrowncpa.com/blog/what-is-the-annual-gift-tax-exclusion-limit-for-2026)
- Tax-Free Gifting in 2026: What Financial Givers Should Know (https://merceradvisors.com/family-finance/tax-free-gifting-in-2026-what-financial-givers-should-know)
- New Federal Law Affects 2026 Estate Planning Exemptions | Estate Gift Tax Exemption and Gift Tax Exclusion (https://federatedinsurance.com/posts/its-your-life/estate-planning-exemptions)
- Annual Gift Tax and Estate Tax Exemptions for 2026 (https://elderlawanswers.com/annual-gift-tax-and-estate-tax-exemptions-for-2026-21282)
- Understand the Impact of Cash Gifts on Inheritance Tax
- The Estate and Gift Tax: An Overview (https://congress.gov/crs-product/R48183)
- New Federal Law Affects 2026 Estate Planning Exemptions | Estate Gift Tax Exemption and Gift Tax Exclusion (https://federatedinsurance.com/posts/its-your-life/estate-planning-exemptions)
- IRS Announces Increased Gift and Estate Tax Exemption Amounts for 2026 (https://morganlewis.com/pubs/2025/10/irs-announces-increased-gift-and-estate-tax-exemption-amounts-for-2026)
- Implement Strategies for Effective Cash Gifting
- What is the Annual Gift Tax Exclusion Limit for 2026? (https://adamsbrowncpa.com/blog/what-is-the-annual-gift-tax-exclusion-limit-for-2026)
- SOI tax stats – Gift tax statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-gift-tax-statistics)
- Gifting Money to Children: Tax Rules, Limits, and What Families Should Know in 2026 – New England Private Wealth Advisors (https://nepwealth.com/insights/gifting-money-to-children)
- 9 Rules for Gifting Money to Family | Western Union US (https://westernunion.com/blog/en/us/gifting-money-to-family)
- Understanding the Tax Impact of Gifting in 2026 – Babb Financial Group LLC | Flagstaff AZ Retirement Income Planning (https://babbgroup.com/gifting)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading