

Key Highlights
- Wisconsin has no inheritance tax for individuals who pass away on or after January 1, 1992, allowing families to inherit assets without state tax burdens.
- As of 2026, the federal estate exemption is set at $15 million for individuals, meaning estates below this threshold won’t incur federal estate charges.
- Families should determine the total value of their assets, identify deductions, and calculate the taxable value to understand potential federal tax obligations.
- Consulting a tax professional is recommended to navigate complexities surrounding estate taxes and ensure compliance with regulations.
- Resources for managing inheritance tax include the Wisconsin Department of Revenue, planning lawyers, financial planning tools, and educational materials from Bright Advisers.
- Common inheritance tax issues include misunderstanding tax obligations, flawed property valuation, failure to document deductions, and delays in settlement among heirs.
- Proactive planning with qualified professionals can help families limit potential tax liabilities and ensure efficient asset transfer.
Introduction
Many families feel overwhelmed by the intricacies of financial planning, especially when it comes to understanding inheritance tax. In Wisconsin, the absence of an inheritance tax since 1992 offers a unique opportunity for families to manage their legacies without the burden of state taxes. But it’s important to understand that as federal regulations come into play, families need to be aware of potential tax implications that could affect their legacies.
How can you ensure your family is prepared for these challenges while securing a bright financial future? Together, we can explore essential steps and resources to help you navigate inheritance tax management in Wisconsin, paving the way for a smoother transition of wealth across generations.
Understand Inheritance Tax Basics in Wisconsin
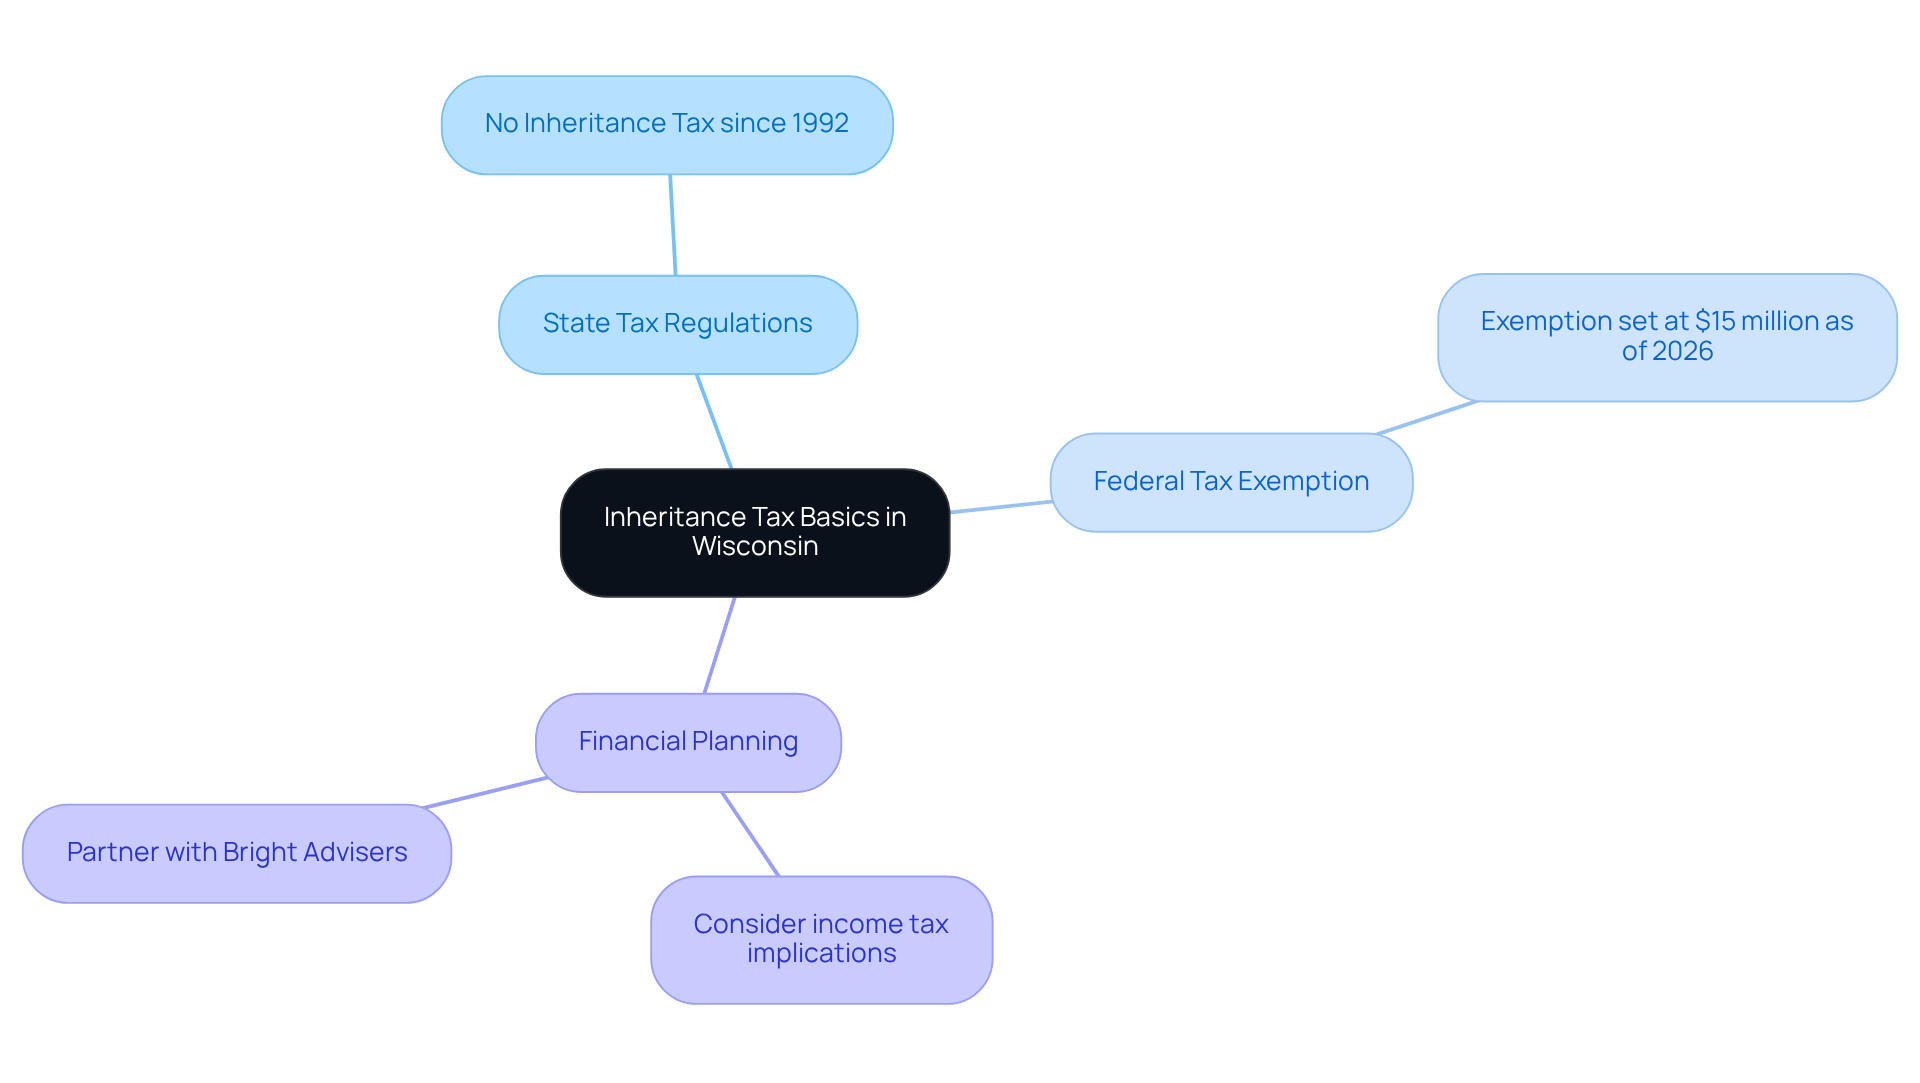
Imagine the relief of knowing your family’s inheritance won’t come with unexpected tax burdens. In Wisconsin, there is no inheritance tax for individuals who pass away on or after January 1, 1992. This means that when you receive assets, you won’t owe state taxes, allowing families to plan their inheritance without the worry of extra tax obligations.
It’s important for families, especially young parents like Jay and Emma, to feel less anxious about their finances and secure their children’s future. While Wisconsin doesn’t impose an inheritance tax, it’s crucial to understand the federal tax regulations that may apply to larger estates regarding inheritance tax. As of 2026, the federal estate exemption is set at $15 million, meaning estates valued below this threshold won’t incur federal estate charges.
Many families worry about unexpected tax burdens when planning their inheritance. It’s also essential to consider how inherited assets might affect your income taxes, especially if those assets generate income. By partnering with Bright Advisers, you can create a plan that not only tackles inheritance tax concerns but also helps you invest wisely for your family’s future. With the right guidance, you can ensure your family’s future is secure and free from financial worries.
Calculate Your Inheritance Tax Obligations
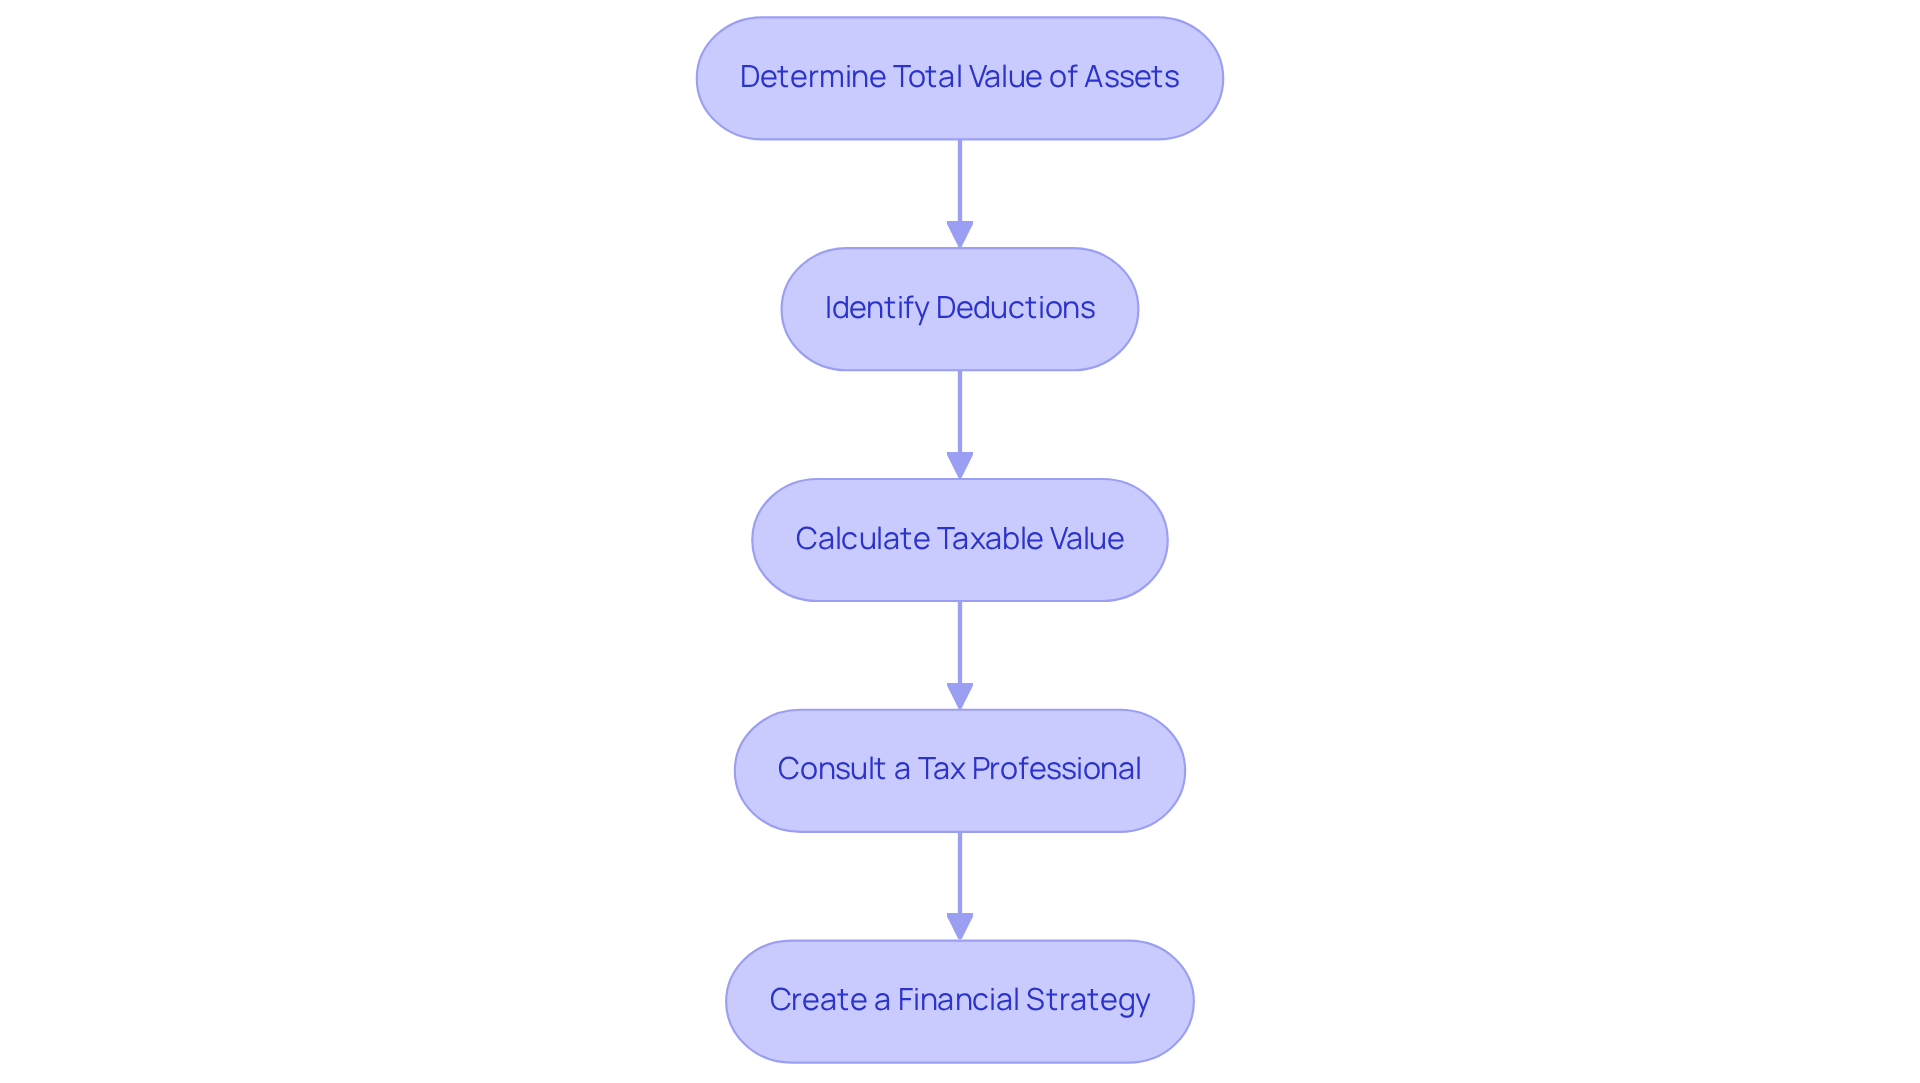
Imagine the worry of leaving your loved ones with unexpected financial burdens, especially when it comes to taxes. While Wisconsin doesn’t impose an inheritance tax, it’s still important for families to be proactive about understanding their potential inheritance tax Wisconsin obligations related to their assets. Let’s gently walk through some steps that can help you feel more secure:
- Determine the Total Value of the Assets: Start by adding up all your holdings, including real property, bank accounts, investments, and personal belongings. This total will help you see if your assets exceed the federal exemption threshold of $15 million for individuals and $30 million for married couples in 2026.
- Identify Deductions: Certain expenses can be deducted from the total property value, such as funeral costs, debts, and administrative expenses. Keeping accurate documentation of these deductions is crucial for a precise calculation.
- Calculate the Taxable Value: Subtract the identified deductions from the total value to find the taxable amount. If this amount exceeds the exemption threshold, federal inheritance fees may apply, which can feel overwhelming. For example, a property appraised at $16 million would only be liable for fees on $1 million, leading to an effective rate of less than 3 percent.
- Consult a Tax Professional: Given the complexities surrounding estate taxes, it’s wise to seek guidance from a tax professional. They can provide personalized advice based on your specific situation and help navigate any state-specific tax implications.
We understand the unique challenges families like Jay & Emma face as they aim to alleviate financial stress while preparing for their children’s education and their retirement. By creating a comprehensive financial strategy that includes tax considerations and education funding, they found a balance between their current responsibilities and long-term goals. Similarly, Emily & Mark were able to create a financial plan that gave them the freedom to choose whether or not to continue working, thanks to our tailored wealth management solutions.
If you connect with these narratives and wish to ensure your household’s financial stability, consider reaching out to Bright Advisers for customized financial strategies and tax enhancement methods. We currently have a client waitlist, and we invite you to join us to explore how we can assist you. Taking these steps can bring peace of mind, knowing your family’s future is secure and well-planned. Remember, past performance does not guarantee future results, and all advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Utilize Resources for Effective Tax Management
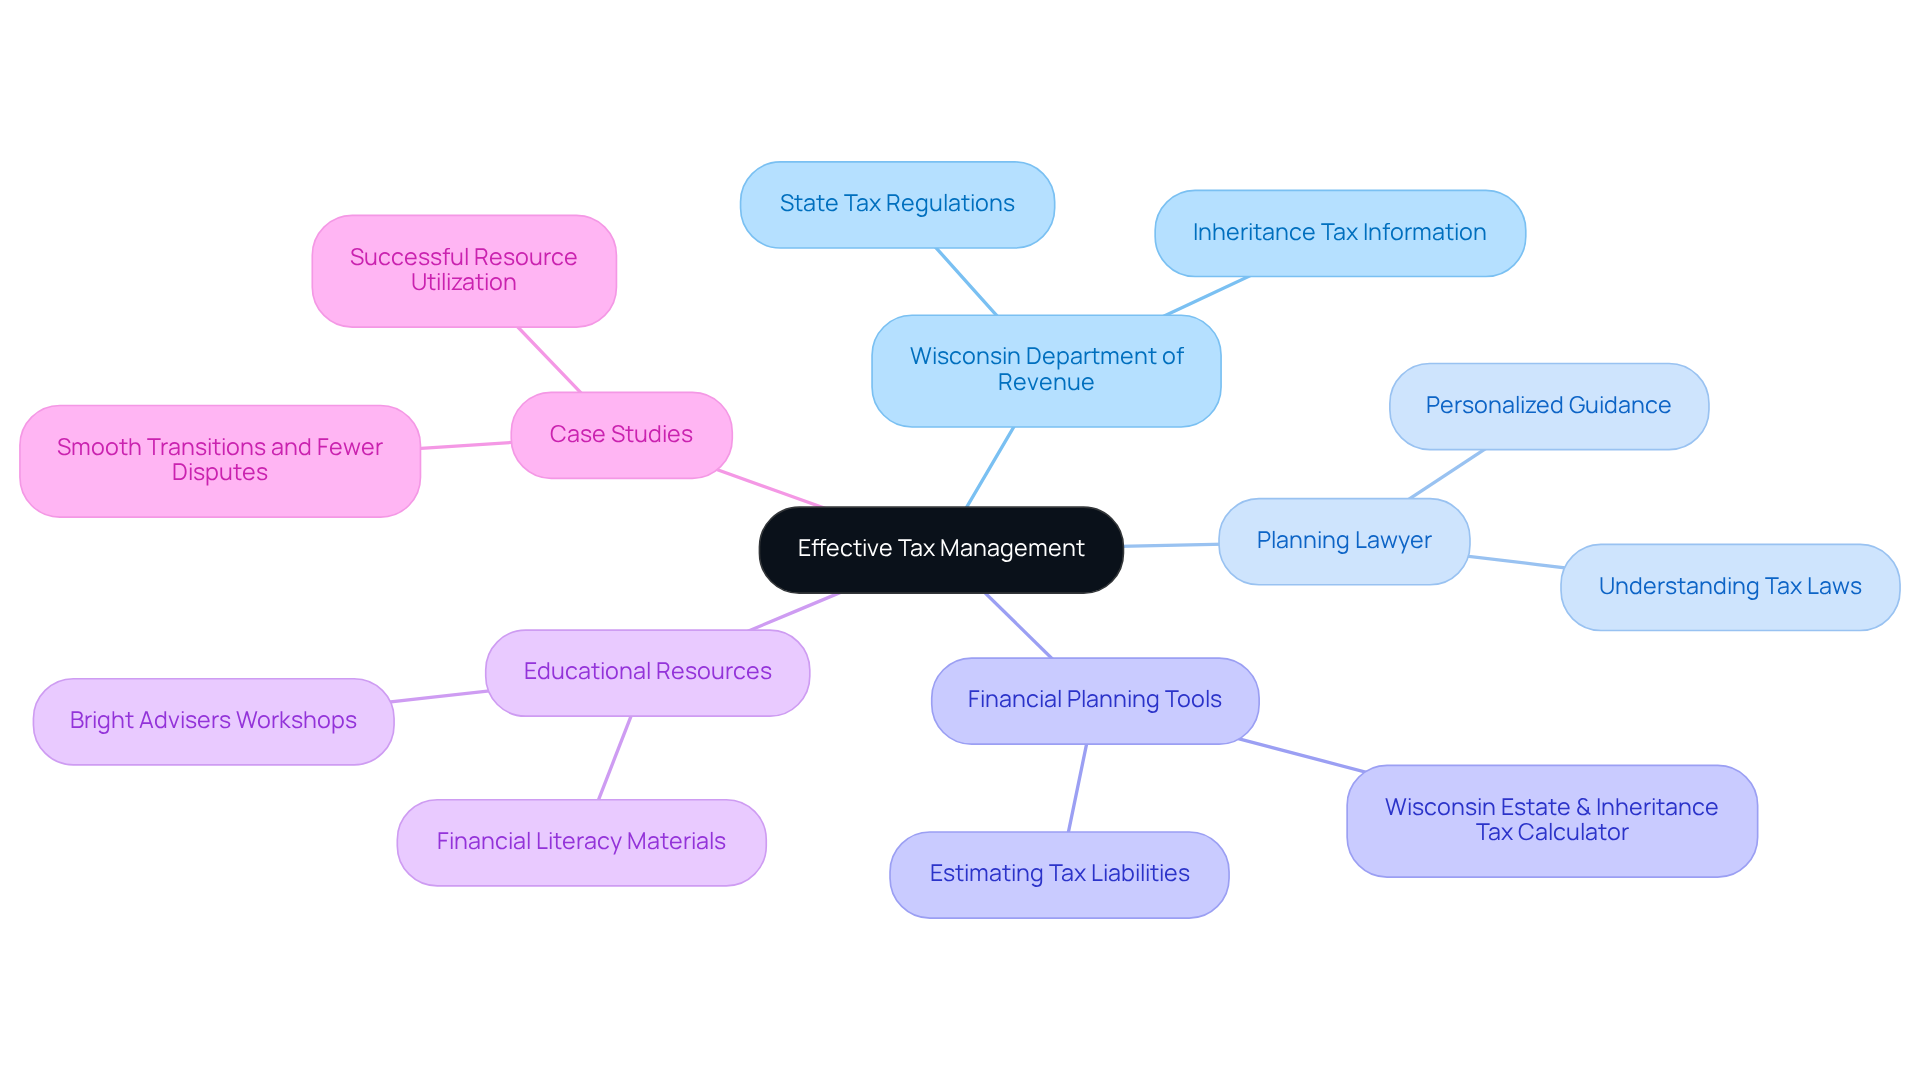
Imagine the peace of mind that comes from knowing your family’s financial future is secure. To effectively manage inheritance tax considerations and estate planning, families can utilize the following resources:
- Wisconsin Department of Revenue: You can find helpful information on state tax regulations, including inheritance tax, on the Wisconsin Department of Revenue’s website. This is an essential first step for understanding the legal structure that governs wealth management in Wisconsin.
- Consulting with a planning lawyer can offer personalized guidance suited to your household’s needs. They can help you understand tax laws and make sure your estate plan follows state regulations, keeping your family’s financial future safe.
- Financial Planning Tools: Online calculators, like the Wisconsin Estate & Inheritance Tax Calculator, can assist households in estimating potential tax liabilities. These tools are crucial for proactive strategy, enabling families to prepare for upcoming financial responsibilities effectively.
- Educational Resources: Bright Advisers offers educational materials and workshops focused on financial literacy for households. These resources help families understand the implications of inheritance and property management, ensuring they are well-informed when making choices about their financial legacy.
- Case Studies: Insights from families who have effectively utilized Wisconsin Department of Revenue resources emphasize the significance of informed preparation. For example, families that used local resource services for distribution reported smoother transitions and fewer disputes during the distribution process.
Navigating tax laws can feel daunting, especially when you’re trying to protect your family’s future. With these resources, you can confidently navigate inheritance tax Wisconsin and property management, ensuring your family’s wishes are honored and your loved ones are protected. By taking these steps, you can ensure your family’s legacy is protected and your loved ones are cared for.
Troubleshoot Common Inheritance Tax Issues
Imagine the uncertainty that comes with planning for your family’s future amidst complex tax responsibilities. While Wisconsin does not impose an inheritance tax, many families still face challenges in managing their assets and understanding their federal tax obligations.
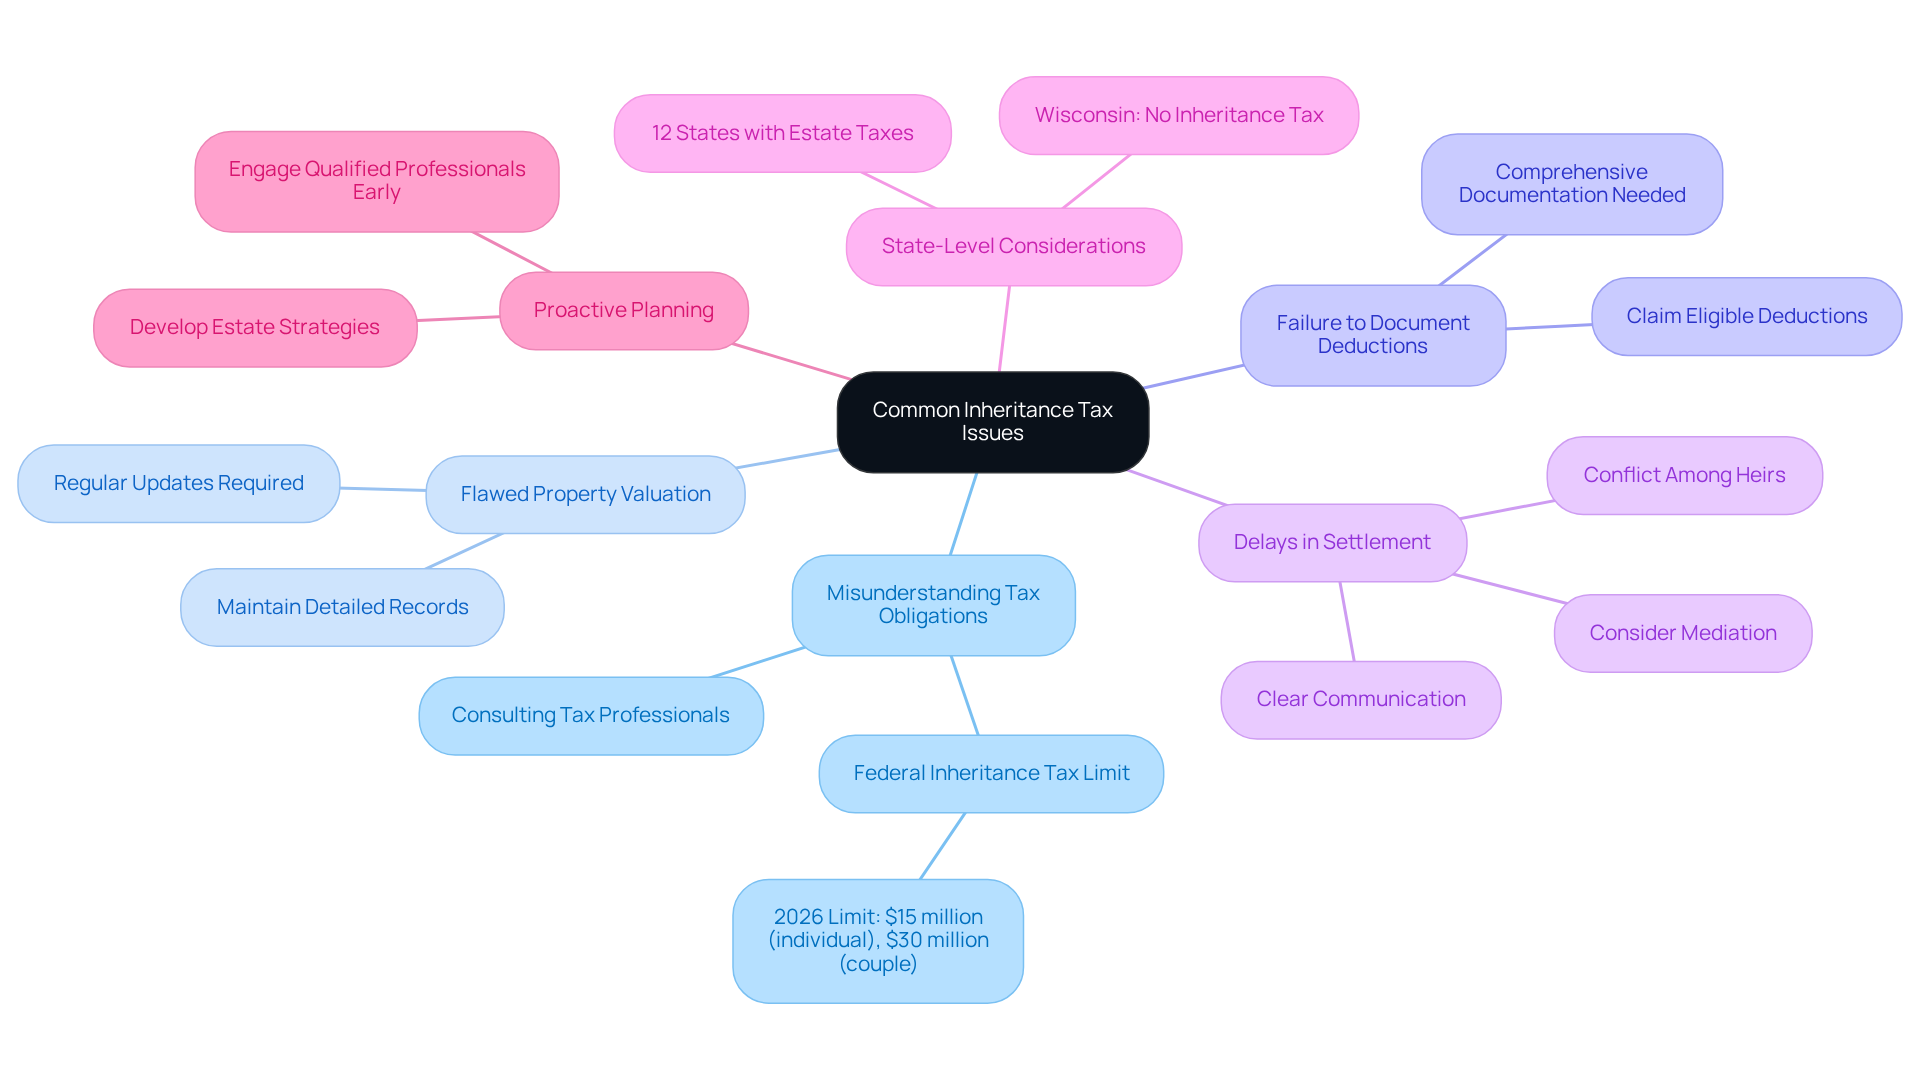
- Misunderstanding Tax Obligations: Imagine the stress of navigating tax responsibilities without clear guidance. Many families are unaware of their federal inheritance tax responsibilities. For 2026, the federal inheritance tax limit rises to $15 million for an individual and $30 million for a couple, as mentioned in the One Big Beautiful Bill Act. To avoid confusion, it’s crucial to understand these limits and consult a tax professional if needed.
- Flawed Property Valuation: A property’s value can vary, leading to potential tax complications. Regularly updating your property valuation and maintaining detailed records of all assets and liabilities is essential to ensure compliance and accurate reporting.
- Failure to Document Deductions: Families often overlook eligible deductions, which can increase tax liabilities. Comprehensive documentation of all expenses associated with the property is essential to ensure that all deductions are claimed, potentially lowering the overall tax burden.
- Delays in Settlement: Conflicts among heirs or incomplete documentation can lead to delays in resolving the property. This can lead to a more harmonious family dynamic during a challenging time. Establishing clear communication among household members and considering mediation for disputes can help facilitate a smoother settlement process.
- State-Level Considerations: Although Wisconsin does not impose an inheritance tax, households should be aware that 12 states and Washington, D.C., levy taxes on property transfers, each with varying exemption amounts and tax rates. Grasping these state-specific regulations is essential for effective property management.
- Proactive Planning: We’re here to help you connect with the right professionals who can guide you through this journey. Engaging with qualified attorneys and tax professionals early in the planning process can assist households in developing strategies to limit potential tax liabilities. As Paul Goeringer notes, working early on to develop an estate plan with qualified attorneys and tax professionals can help you create strategies to limit the inheritance tax Wisconsin burden on your heirs as well. This proactive approach is essential to ensure that family assets are preserved and passed on efficiently. By taking proactive steps now, you can ensure your family’s legacy is protected and cherished for generations to come.
Conclusion
Imagine the peace of mind that comes from understanding how to navigate inheritance tax in Wisconsin for your family’s future. With no state inheritance tax imposed since 1992, families can focus on planning their legacies without the burden of additional tax obligations. It’s important to understand that while Wisconsin has no state inheritance tax, being aware of federal estate tax regulations can help prevent unexpected financial stress for your family.
Throughout this guide, we’ve shared key steps to help families navigate the complexities of inheritance tax management. From calculating potential tax obligations to utilizing available resources, families can take control of their financial planning. Engaging with professionals, understanding asset valuations, and documenting deductions are vital strategies that can significantly ease the inheritance process. By taking these steps, families can not only minimize tax liabilities but also feel confident in creating a secure financial future for their children, just like Jay and Emma did.
Ultimately, taking these steps today can mean a brighter tomorrow for your loved ones, ensuring they are cared for and supported in every way possible. Families are encouraged to leverage resources such as the Wisconsin Department of Revenue and financial planning tools to stay informed and prepared. By taking these actions, families can ensure their legacies are preserved and their loved ones are protected. For those seeking personalized guidance, Bright Advisers stands ready to assist in crafting a comprehensive financial strategy that aligns with your family’s unique needs. Embrace the opportunity to secure your family’s future today, and remember that past performance does not guarantee future results. All advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Frequently Asked Questions
Is there an inheritance tax in Wisconsin?
No, Wisconsin does not impose an inheritance tax for individuals who pass away on or after January 1, 1992.
What does the absence of inheritance tax mean for families in Wisconsin?
Families in Wisconsin can receive assets without owing state taxes, allowing them to plan their inheritance without the worry of extra tax obligations.
Are there any federal tax regulations that families should be aware of regarding inheritance?
Yes, while Wisconsin has no inheritance tax, families should understand federal tax regulations that may apply to larger estates. As of 2026, the federal estate exemption is set at $15 million, meaning estates valued below this threshold won’t incur federal estate charges.
How might inherited assets affect income taxes?
Inherited assets may generate income, which could affect your income taxes. It’s important to consider this when planning your inheritance.
How can families plan for inheritance tax concerns?
Families can partner with Bright Advisers to create a plan that addresses inheritance tax concerns and helps them invest wisely for their family’s future.
List of Sources
- Understand Inheritance Tax Basics in Wisconsin
- What is the estate tax exemption? | Fidelity (https://fidelity.com/learning-center/personal-finance/what-is-the-estate-tax-exemption)
- The Estate Tax Exemption Amount for 2026 (https://kiplinger.com/taxes/new-estate-tax-exemption-amount)
- Estate Tax Exemption Sunsets in 2026 (https://citizensbank.com/private-banking/insights/estate-tax-exemption.aspx)
- Wisconsin Estate Tax: Everything You Need to Know (https://smartasset.com/estate-planning/wisconsin-estate-tax)
- Calculate Your Inheritance Tax Obligations
- Estate Taxes: Who Pays, How Much and When | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/trust-and-estate-planning/estate-taxes.html)
- 2026 State Estate and Inheritance Taxes: What You Need to Know (https://creativeplanning.com/insights/taxes/state-estate-inheritance-taxes)
- The Federal Estate Tax (https://cbpp.org/research/federal-tax/the-federal-estate-tax)
- Utilize Resources for Effective Tax Management
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- Estate Planning Statistics to Read Before Writing Your Will (https://legalzoom.com/articles/estate-planning-statistics)
- Alarming Estate Planning Statistics (https://financialsense.com/blog/21022/alarming-estate-planning-statistics)
- Estate Planning Statistics (https://stoufferlegal.com/blog/estate-planning-statistics)
- Estate Planning Statistics | LifeGen Law Group (https://lifegenlawgroup.com/estate-planning-statistics)
- Troubleshoot Common Inheritance Tax Issues
- 2026 State Estate and Inheritance Taxes: What You Need to Know (https://creativeplanning.com/insights/taxes/state-estate-inheritance-taxes)
- Federal estate tax and gift tax limits announced for 2026 (https://agproud.com/articles/62714-federal-estate-tax-and-gift-tax-limits-announced-for-2026)
- Ten Facts You Should Know About the Federal Estate Tax (https://cbpp.org/research/federal-tax/ten-facts-you-should-know-about-the-federal-estate-tax)
- What the Scheduled 2026 Estate Tax Changes Mean for High Net Worth Families (https://nyestateplan.com/2026-estate-tax-changes-high-net-worth-families)
- Exploding Common Estate Tax Myths (https://vrakascpas.com/blog/exploding-common-estate-tax-myths)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading