

Key Highlights:
- Understanding recipient designations is crucial for ensuring assets are distributed according to the holder’s wishes after death.
- The recipient designation form takes precedence over a will, making it vital to review and update regularly.
- Primary recipients inherit first, with secondary recipients stepping in if primary ones are unavailable; nearly 40% of holders have outdated designations.
- Life changes, such as marriage or divorce, necessitate updates to beneficiary designations to avoid complications.
- Consulting a financial advisor can help align beneficiary choices with overall estate plans and clarify tax implications.
- Eligible Designated Beneficiaries (EDBs) like spouses and minor children have flexible distribution options under inherited 403(b) rules.
- Designated Recipients must follow specific distribution guidelines, often requiring full withdrawal within 10 years due to the SECURE Act.
- Non-Designated Recipients may face probate complications if no beneficiaries are named, underscoring the need for regular updates.
- Trusts can be named as recipients for greater control over asset distribution according to specific wishes.
- Withdrawals from inherited 403(b) accounts are taxed as ordinary income, impacting overall tax liability.
- The SECURE Act mandates that most non-spouse recipients withdraw the entire balance within 10 years, affecting tax strategy.
- Inherited 403(b) distributions are exempt from the 10% early withdrawal penalty, providing more flexibility for beneficiaries.
- Common mistakes include neglecting to update designations, lack of knowledge about distribution regulations, ignoring tax implications, and not seeking professional guidance.
Introduction
Managing inherited 403b accounts can feel overwhelming for many families. When it comes to securing a loved one’s financial legacy, the stakes are high. This guide is here to offer a compassionate roadmap for parents, outlining essential steps to ensure that beneficiary designations are current and truly reflect your family’s needs.
Imagine if you could navigate the complexities of tax implications and distribution rules with confidence. It’s important to understand how to avoid common pitfalls and make informed decisions that genuinely benefit your heirs. Together, we can explore these challenges and find the best path forward for your family.
Understand Beneficiary Designations
Managing inherited 403b rules can feel overwhelming, but understanding recipient designations is a crucial step in ensuring your loved ones are taken care of. These designations determine who receives the assets of the fund when the holder passes away. Let’s explore how to navigate this important process together:
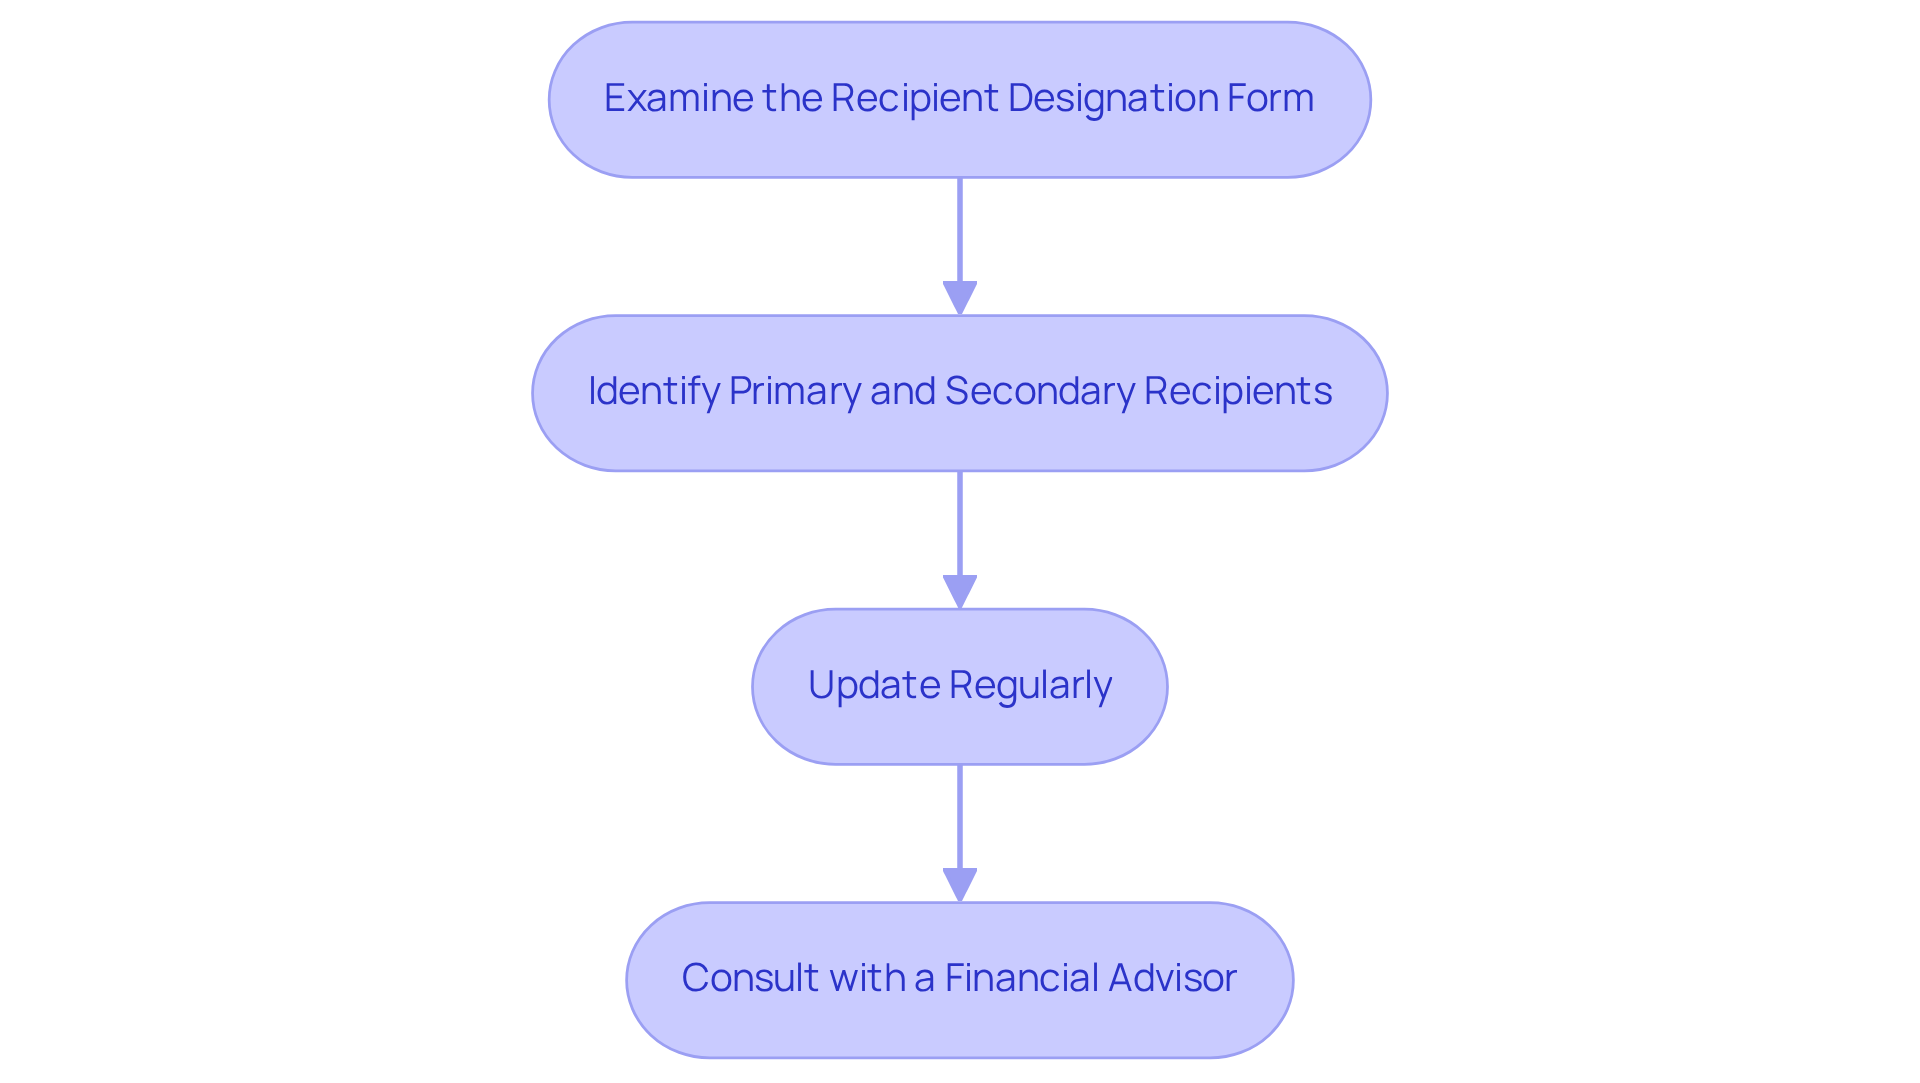
- Examine the Recipient Designation Form: Start by locating the document that specifies your recipients. This form is vital, as it takes precedence over any instructions in a will, ensuring your wishes are honored.
- Identify Primary and Secondary Recipients: Think of primary recipients as the first in line to inherit the assets, while secondary recipients step in if the primary ones are unavailable. It’s essential to review these titles regularly; nearly 40% of holders have outdated designations, according to Fidelity. This oversight can lead to unintended distributions, which can be distressing for families.
- Update Regularly: Life changes – like marriage, divorce, or welcoming a new child – call for . Financial advisors often highlight that neglecting these updates can create complications, such as an ex-spouse receiving the funds, which can add stress during already challenging times. As one expert reminds us, “Americans often overlook these forms, despite major life events like marriage, divorce, or the birth of a child.”
- Consult with a Financial Advisor: If you’re feeling uncertain about your designations, reaching out to a financial planner can be incredibly helpful. They can guide you in aligning your choices with your overall estate plan and clarify the tax implications of your decisions. For instance, spousal recipients can treat inherited funds according to inherited 403b rules as their own, offering more flexibility in managing withdrawals and contributions. Plus, understanding the SECURE Act’s impact on non-spouse recipients is crucial, as it requires them to withdraw the total funds within 10 years after the account holder’s passing.
By actively managing your recipient designations, you can safeguard your family’s financial legacy and avoid potential issues that arise from outdated information. Remember, we’re here for you, and together, we can navigate this journey.
Identify Types of Beneficiaries
When it comes to managing an inherited 403b, it is essential for young families like Jay and Emma to understand the . They’re looking to ease financial worries and allocate their resources wisely.
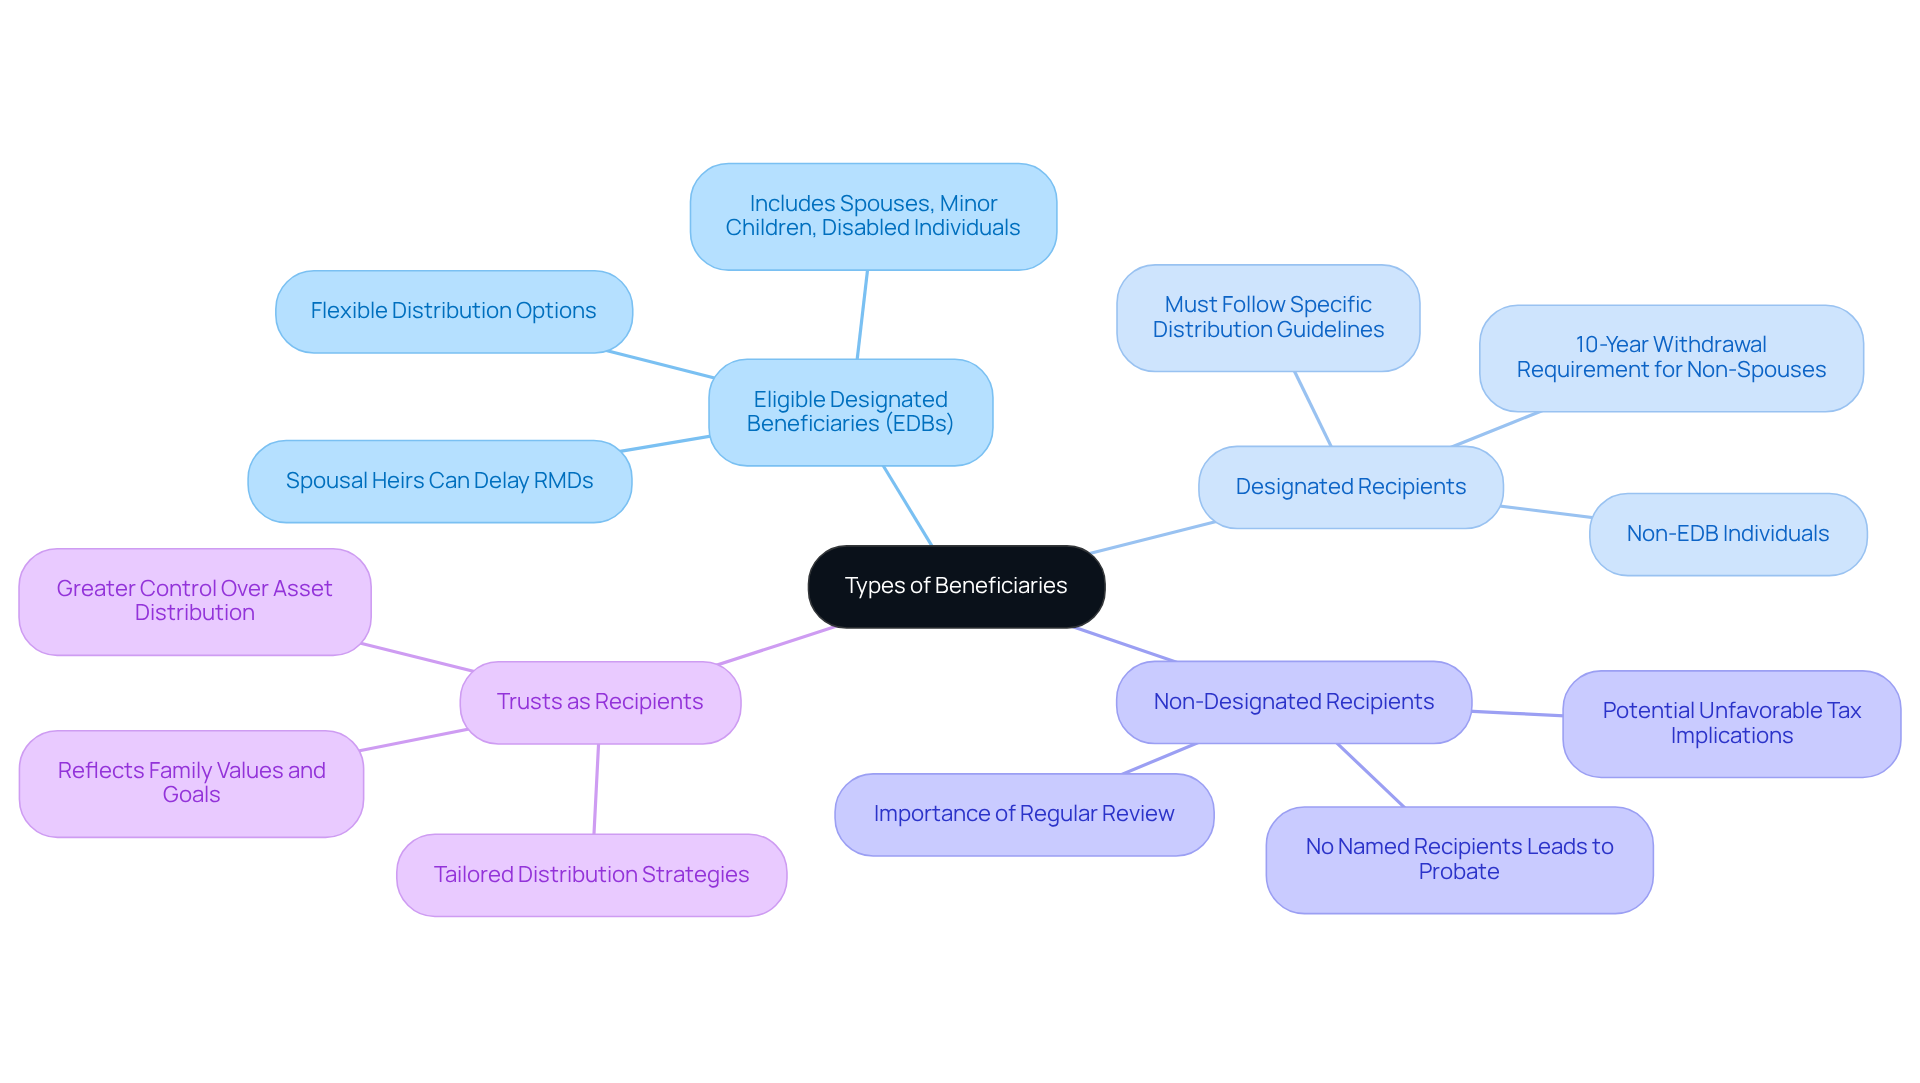
- Eligible Designated Beneficiaries (EDBs) are a key group to know. This includes spouses, minor children, and individuals who are disabled or chronically ill. EDBs have flexible distribution options, which can help them manage their inherited assets effectively. For example, spousal heirs can transfer the inherited 403b rules into their own retirement fund, delaying required minimum distributions until their personal required beginning date.
- Next, we have Designated Recipients. This category covers anyone listed on the recipient form who doesn’t qualify as an EDB. These recipients must adhere to specific distribution guidelines, which can vary based on the holder’s situation. As per SECURE Act guidelines, most non-spouse recipients are required to withdraw the entire fund from inherited 403b rules within 10 years. This could lead to unexpected tax consequences, so it’s crucial to be aware.
- Then there are Non-Designated Recipients. If no recipients are named, the asset might go through probate, complicating the distribution process and possibly resulting in unfavorable tax implications. Keeping recipient designations up to date is vital-ideally, review them every 3-5 years or after major life events. As one financial advisor wisely noted, ‘Many clients mistakenly believe they finished this paperwork years ago and never need to review it.’
- Lastly, consider Trusts as Recipients. Parents might opt to name a trust as a recipient, which allows for greater control over how assets are distributed to heirs. This approach can be particularly beneficial in ensuring that funds are managed according to specific wishes and timelines, enabling tailored distribution strategies that reflect the family’s values and goals.
Navigating these options can feel overwhelming, but remember, you’re not alone. Together, we can explore these pathways to secure your family’s financial future.
Explore Tax Implications of Inheritance
Inheriting a 403(b) can feel overwhelming, especially when trying to understand the inherited 403b rules and their tax implications. Let’s break it down together, so you can navigate this journey with confidence.
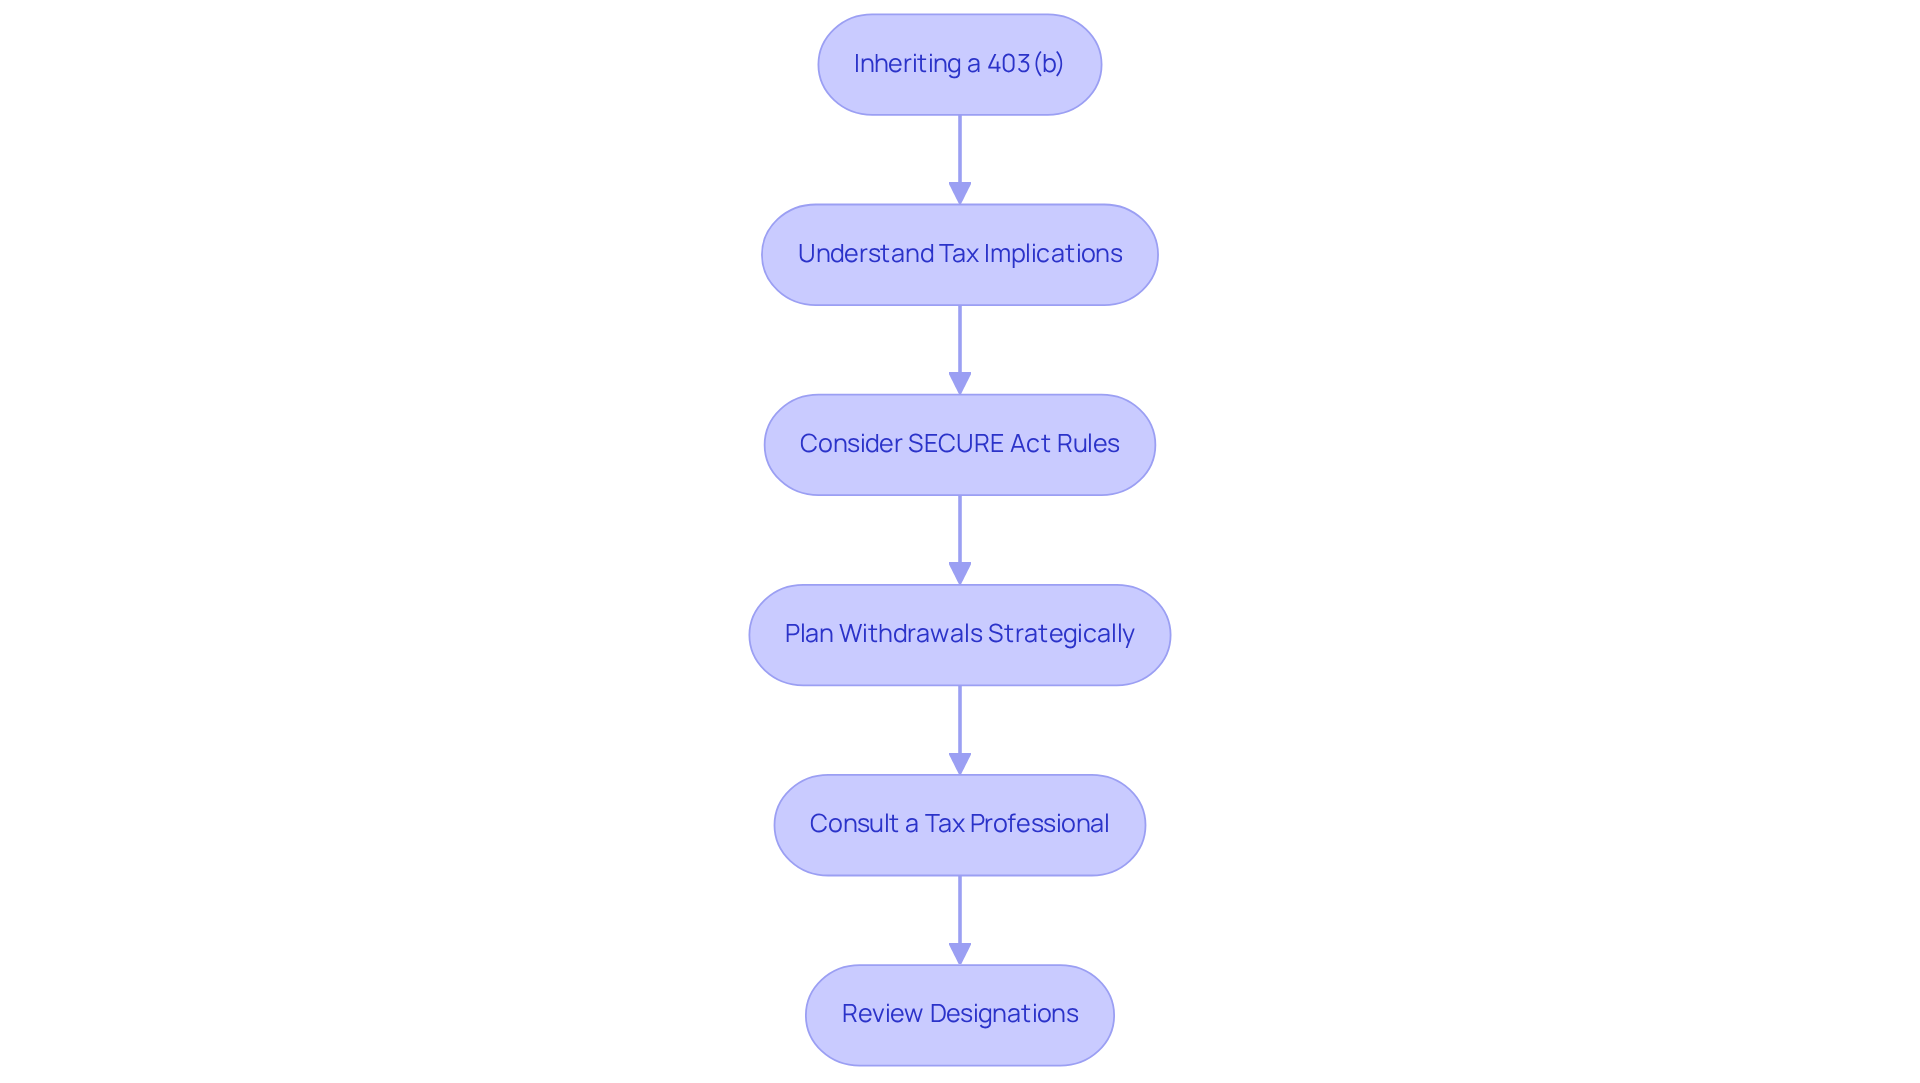
- When you withdraw from an inherited 403b, those distributions are generally tax. This means the amount you take out will be added to your taxable income for the year, which could significantly affect your overall tax liability. It’s important to keep this in mind as you plan your finances.
- The SECURE Act introduces inherited 403b rules, which include a 10-year rule that requires most recipients to withdraw the entire balance within ten years of the account holder’s passing. This can impact your tax bracket, so planning your withdrawals strategically is crucial. Imagine if you could minimize your tax implications just by timing your withdrawals wisely. Financial experts emphasize that overlooking this can lead to higher tax bills.
- One silver lining is that, under inherited 403b rules, inherited 403(b) distributions aren’t subject to the 10% early withdrawal penalty, regardless of your age. This flexibility allows you to manage your withdrawals without incurring extra costs, giving you peace of mind.
- Consult a Tax Professional: Given the complexities of tax laws, it’s wise to consult with a tax professional. They can help you strategize the best approach for your withdrawals and minimize tax liabilities. Dr. Barbara O’Neill highlights the importance of reviewing designations periodically to ensure they align with your current preferences. If the inherited account is a Roth 403(b), you might benefit from tax-free distributions if certain conditions are met.
Remember, you’re not alone in this. We’re here for you, ready to support you as you navigate these financial waters. Together, we can ensure your family’s future is secure.
Avoid Common Inheritance Mistakes
To ensure a smooth inheritance process, it’s essential for parents to avoid these common pitfalls:
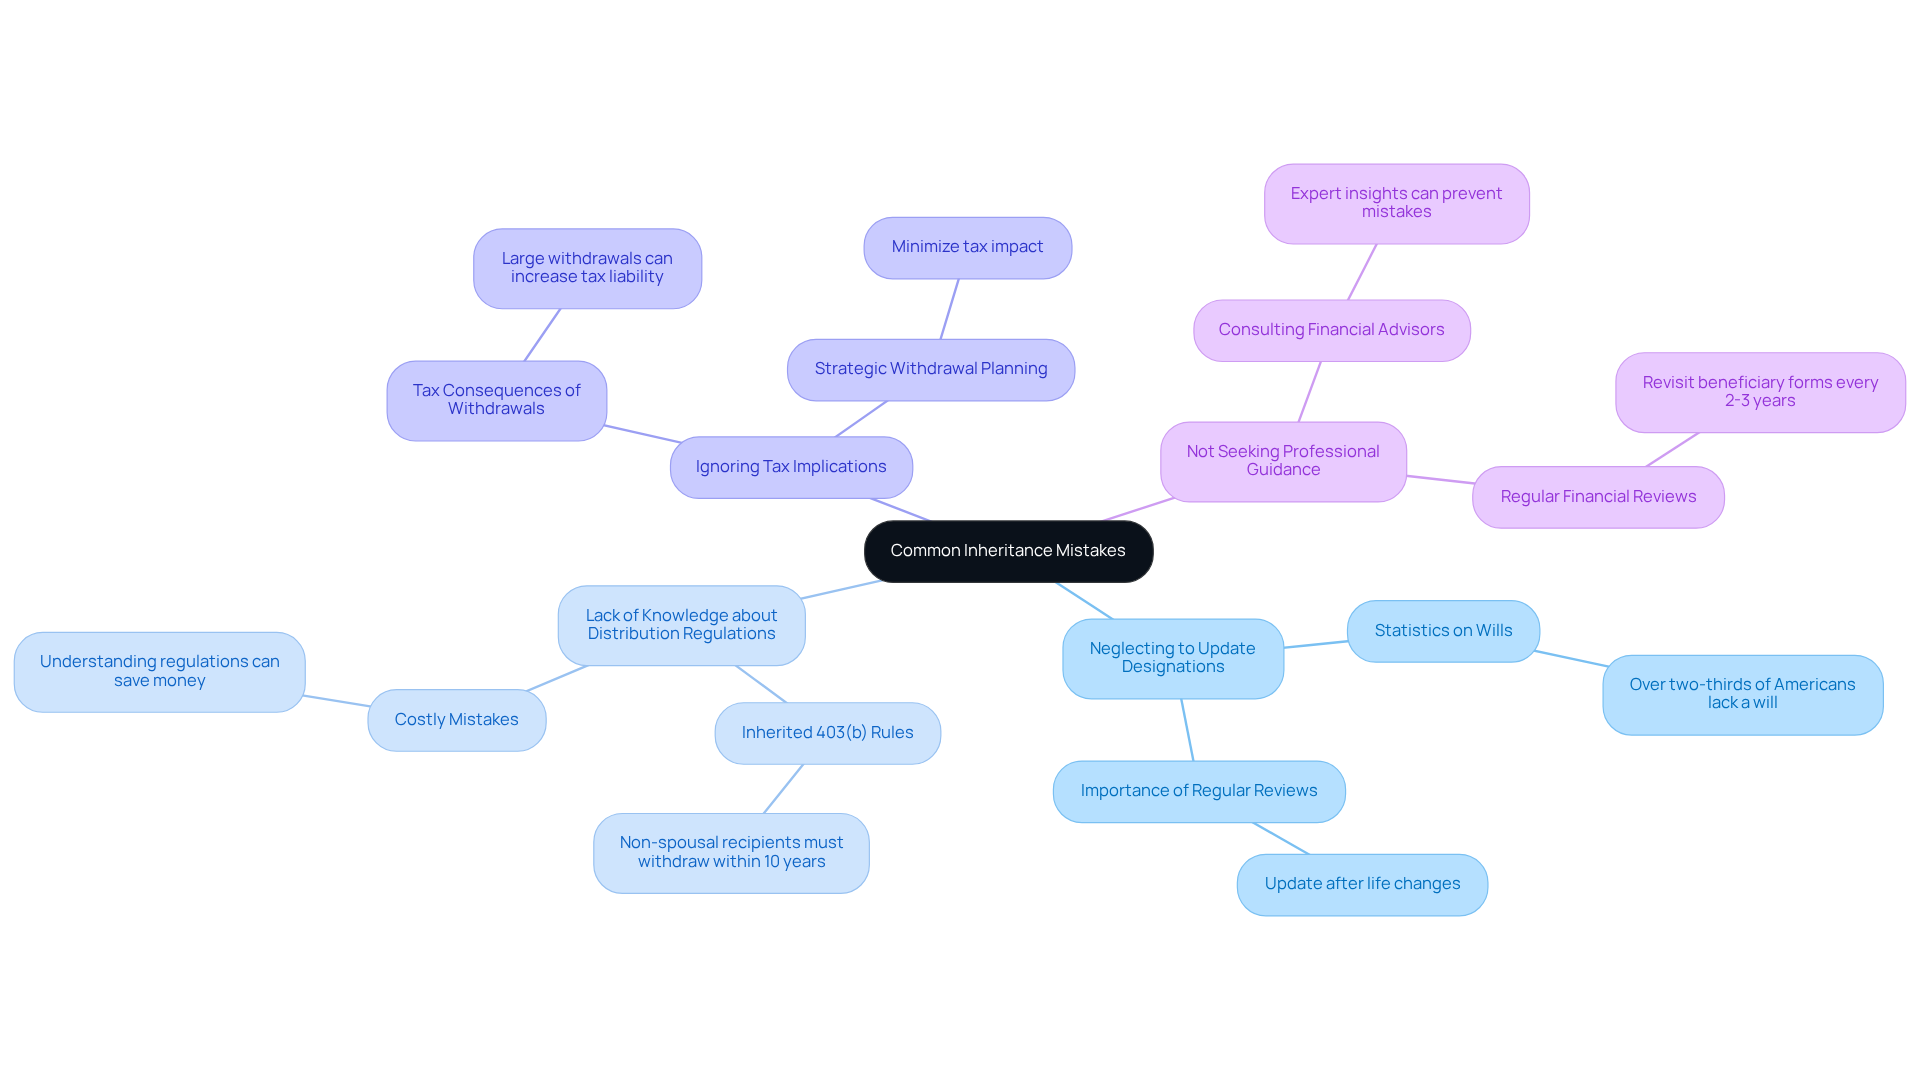
- Neglecting to Update Designations: Imagine the heartache of having unintended individuals receive your hard-earned assets. Sadly, statistics reveal that over two-thirds of Americans don’t have a will, and many forget to update their recipient forms after significant life changes. Regularly reviewing and updating these designations is vital to ensure your wishes are honored. Families like Jay and Emma, who worked with Bright Advisers, recognized the importance of keeping their recipient information current as part of their overall financial strategy.
- Lack of Knowledge about Distribution Regulations: It’s important to understand the specific rules governing distributions from inherited funds. For example, non-spousal recipients must withdraw total funds from inherited 403b rules plans within ten years of the account holder’s passing to avoid hefty penalties. Familiarizing yourself with these regulations can save you from costly mistakes. Emily and Mark, another couple who partnered with Bright Advisers, benefited from understanding these rules, empowering them to make informed choices about their financial future.
- Ignoring Tax Implications: Have you considered the tax consequences of withdrawals? Overlooking this can lead to unexpected tax bills. Large withdrawals might push beneficiaries into a higher tax bracket, increasing their overall tax liability. Thoughtful planning of withdrawals can help and align with your family’s financial goals. Allison and Brian’s experience with Bright Advisers highlights how effective tax planning can enhance financial outcomes and secure a family’s future.
- Not Seeking Professional Guidance: Navigating the complexities of inherited accounts can feel overwhelming. Consulting with a financial advisor or estate planner can provide valuable insights and ensure you’re making informed decisions. Experts recommend revisiting beneficiary forms every two to three years, especially before major life events, to avoid complications later on. Bright Advisers is here to empower families to navigate these complexities, ensuring you’re well-prepared for the future. Regular financial reviews are also crucial to adapt to changing circumstances and stay aligned with your financial goals.
Conclusion
Understanding the nuances of inherited 403b rules is crucial for parents who want to secure their family’s financial future. Imagine being able to provide for your loved ones, even in the face of unforeseen loss. By mastering the processes surrounding beneficiary designations, types of beneficiaries, tax implications, and common pitfalls, you can ensure that your family is well taken care of. This proactive approach not only protects your assets but also brings peace of mind during challenging times.
Key insights from this guide highlight the importance of:
- Regularly updating beneficiary designations
- Understanding the different types of beneficiaries
- Being aware of the tax implications associated with inherited 403b accounts
Seeking professional guidance can significantly enhance your decision-making and help you avoid costly mistakes that might arise from overlooking these crucial aspects.
Ultimately, navigating inherited 403b rules is about more than just compliance; it’s about taking control of your family’s financial legacy. By staying informed and proactive, you can create a secure future for your beneficiaries, ensuring that your hard-earned assets are distributed according to your wishes. Remember, engaging with financial professionals and regularly reviewing designations empowers you to make informed choices, leading to a more stable and secure financial landscape. We’re here for you, ready to support you on this journey.
Frequently Asked Questions
What is the importance of understanding beneficiary designations for a 403b?
Beneficiary designations determine who receives the assets of the fund when the holder passes away, ensuring that your loved ones are taken care of.
How do I find out who my beneficiaries are?
You can locate your beneficiaries by examining the Recipient Designation Form, which specifies your recipients and takes precedence over any instructions in a will.
What is the difference between primary and secondary recipients?
Primary recipients are the first in line to inherit the assets, while secondary recipients step in if the primary ones are unavailable.
Why is it important to regularly review beneficiary designations?
Nearly 40% of holders have outdated designations, which can lead to unintended distributions and distress for families. Regular reviews ensure that your wishes are honored.
When should I update my beneficiary designations?
You should update your designations after significant life changes, such as marriage, divorce, or the birth of a child, to avoid complications like an ex-spouse receiving the funds.
How can a financial advisor assist with beneficiary designations?
A financial advisor can help align your choices with your overall estate plan, clarify tax implications, and provide guidance on the impact of laws like the SECURE Act on non-spouse recipients.
What is the SECURE Act and how does it affect non-spouse beneficiaries?
The SECURE Act requires non-spouse recipients to withdraw the total funds from an inherited 403b account within 10 years after the account holder’s passing.
List of Sources
- Understand Beneficiary Designations
- What Happens to Your 403(b) When You Die: A Complete Guide (https://westernsouthern.com/retirement/what-happens-to-my-403b-when-i-die)
- 10 Essential 403b Inheritance Rules Every Young Parent Should Know – Bright Advisers (https://brightadvisers.com/10-essential-403-b-inheritance-rules-every-young-parent-should-know)
- Out-of-date beneficiary designations are a common and costly mistake (https://cnbc.com/2018/04/16/out-of-date-beneficiary-designations-are-a-common-and-costly-mistake.html)
- The Importance of Keeping Beneficiary Designations Up to Date — Ascensus (https://thelink.ascensus.com/articles/2024/7/17/the-importance-of-keeping-beneficiary-designations-up-to-date)
- Many Americans make this costly 401(k) and IRA mistake — don’t leave a mess for your family (https://m.economictimes.com/news/international/us/many-americans-make-this-costly-401k-and-ira-mistake-dont-leave-a-mess-for-your-family/articleshow/126239542.cms)
- Identify Types of Beneficiaries
- What Happens to Your 403(b) When You Die: A Complete Guide (https://westernsouthern.com/retirement/what-happens-to-my-403b-when-i-die)
- New Rule on Inherited IRAs Beneficiaries Taking Effect in 2025 (https://trustetc.com/blog/new-ira-beneficiaries-and-inherited-ira-rule)
- Explore Tax Implications of Inheritance
- What Happens to Your 403(b) When You Die: A Complete Guide (https://westernsouthern.com/retirement/what-happens-to-my-403b-when-i-die)
- The SECURE Act: The Good, The Bad and The Ugly | Baker Institute (https://bakerinstitute.org/research/secure-act-good-bad-and-ugly)
- Death and Your 403(b) :: Dan’s Blog :: 403bwise (https://403bwise.org/blog/entry/guest-blog-403b-and-death-11.30.21)
- Avoid Common Inheritance Mistakes
- 10 Essential 403b Inheritance Rules Every Young Parent Should Know – Bright Advisers (https://brightadvisers.com/10-essential-403-b-inheritance-rules-every-young-parent-should-know)
- 10 Common Estate Planning Mistakes to Avoid (https://merceradvisors.com/insights/trust-estate/10-common-estate-planning-mistakes-to-avoid)
- Out-of-date beneficiary designations are a common and costly mistake (https://cnbc.com/2018/04/16/out-of-date-beneficiary-designations-are-a-common-and-costly-mistake.html)
- Many Americans make this costly 401(k) and IRA mistake — don’t leave a mess for your family (https://m.economictimes.com/news/international/us/many-americans-make-this-costly-401k-and-ira-mistake-dont-leave-a-mess-for-your-family/articleshow/126239542.cms)
- Inherited an IRA? Don’t Fall Into the 10-Year Tax Trap (https://kiplinger.com/retirement/inheritance/inherited-ira-how-to-avoid-a-tax-trap)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading