

Key Highlights
- Intentionally Defective Grantor Trusts (IDGTs) allow families to manage wealth while minimising tax liabilities, as assets are not counted for income tax but are subject to inheritance tax.
- As of 2024, the inheritance tax threshold is $13.61 million per person, with gifts above this threshold incurring a 40% gift tax.
- IDGTs enable families to transfer appreciating properties while maintaining control, allowing for financial assistance to heirs or charitable initiatives.
- The trust can grow without incurring additional tax obligations, benefiting heirs by allowing them to inherit gains tax-free.
- IDGTs are irrevocable, meaning assets cannot be reclaimed once transferred, which can be a concern for families.
- Ongoing income tax obligations on the trust’s earnings can create financial burdens, necessitating careful financial planning.
- Establishing an IDGT involves consulting a professional, drafting an agreement, funding the trust, paying income taxes, and regularly reviewing its performance.
- IDGTs can effectively secure a family’s financial legacy, especially with recent tax legislation changes increasing the inheritance tax exemption.
Introduction
Imagine feeling overwhelmed by the thought of securing your family’s financial future, wondering if it’s even possible. Intentionally defective ILITs can help high-income parents manage their wealth and enjoy tax benefits, but they can be confusing.
Let’s explore how these trusts work and how they can help you protect your family’s future. But with these benefits come challenges. How can you navigate these complexities to secure your family’s financial legacy?
Define Intentionally Defective Grantor Trusts (IDGTs)
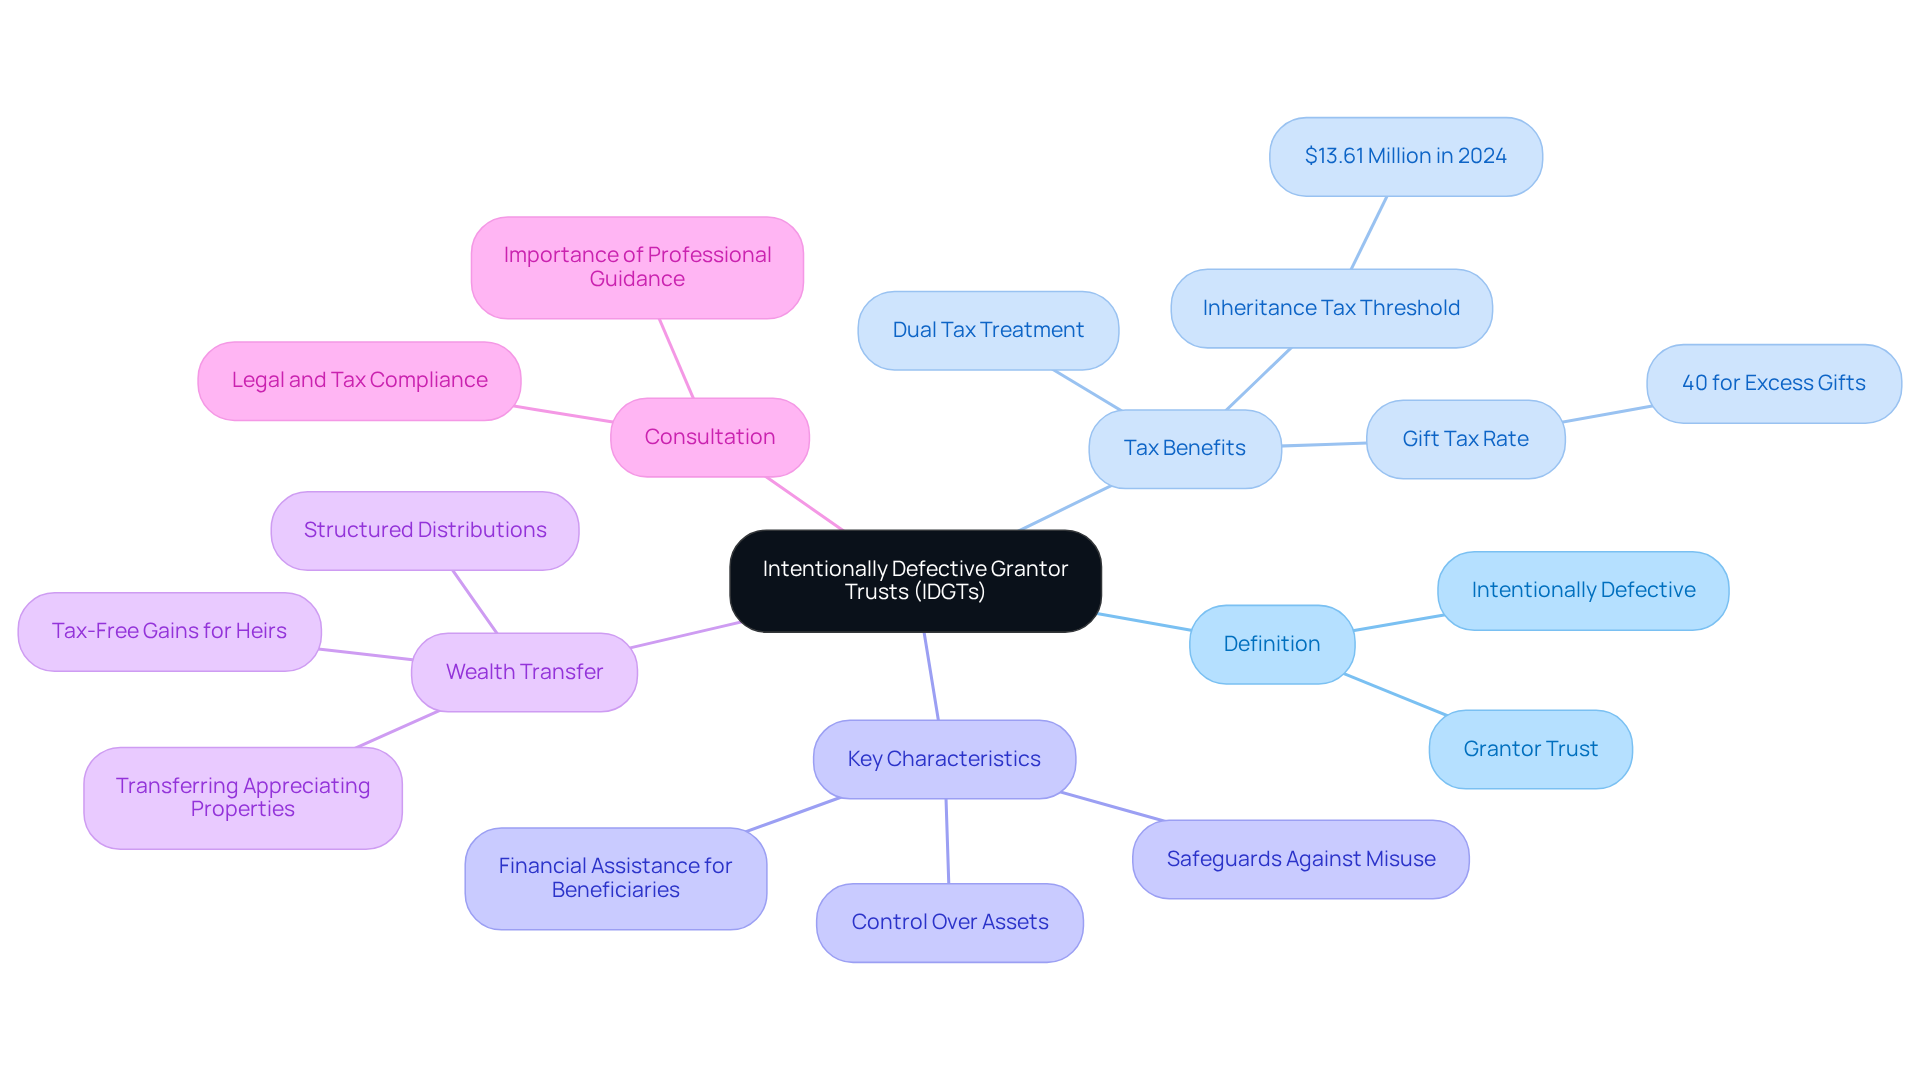
Imagine the peace of mind that comes from knowing your family’s financial future is secure, even amidst the complexities of tax laws. An intentionally defective ILIT helps families manage their wealth while offering unique tax benefits, allowing you to keep some control over your assets. The term ‘intentionally defective’ means that while the trust isn’t counted for income tax purposes, it still holds value for inheritance tax. This means that although the assets in the trust aren’t part of your taxable holdings, you still need to pay income taxes on the trust’s earnings. This dual treatment allows families to transfer wealth efficiently while minimizing tax liabilities, making intentionally defective ILIT a powerful tool for high-income families aiming to secure their children’s financial futures.
As of 2024, the inheritance tax threshold stands at $13.61 million per person, allowing individuals to transfer substantial wealth without incurring transfer taxes. However, gifts exceeding this threshold are subject to a 40% gift tax rate. IDGTs can effectively secure the current value of appreciating properties for estate tax purposes, allowing families to benefit from future appreciation without increasing their intentionally defective ILIT.
Key characteristics of IDGTs include the ability to transfer appreciating properties while maintaining control over the intentionally defective ILIT arrangement. This can be designed to offer financial assistance for children, grandchildren, or charitable initiatives. You can also set specific guidelines for how the funds are distributed, ensuring that your family’s wealth is preserved and used wisely.
For families with significant assets, using intentionally defective ILIT can be a game-changer, making it easier to pass on wealth without the heavy tax burden that often comes with it. For example, if a family puts $5 million of business stock into an IDGT and it increases to $10 million, the heirs can receive the $5 million gain without incurring any charges, while the grantor pays the income obligations of the arrangement, effectively lowering their taxable holdings.
By taking proactive steps today, you can ensure your family’s legacy is protected for generations to come, allowing you to focus on what truly matters-your loved ones. It’s important to consult with a qualified professional, such as Bright Advisers, to explore integrated tax planning strategies tailored to your family’s needs. Please remember that past performance does not guarantee future results, and all investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Explain How IDGTs Work
Imagine a future where your family’s financial legacy is secure, free from the burden of hefty taxes. Intentionally defective ILIT can be a valuable tool for families like yours, allowing you to protect your wealth while keeping it intact for generations to come.
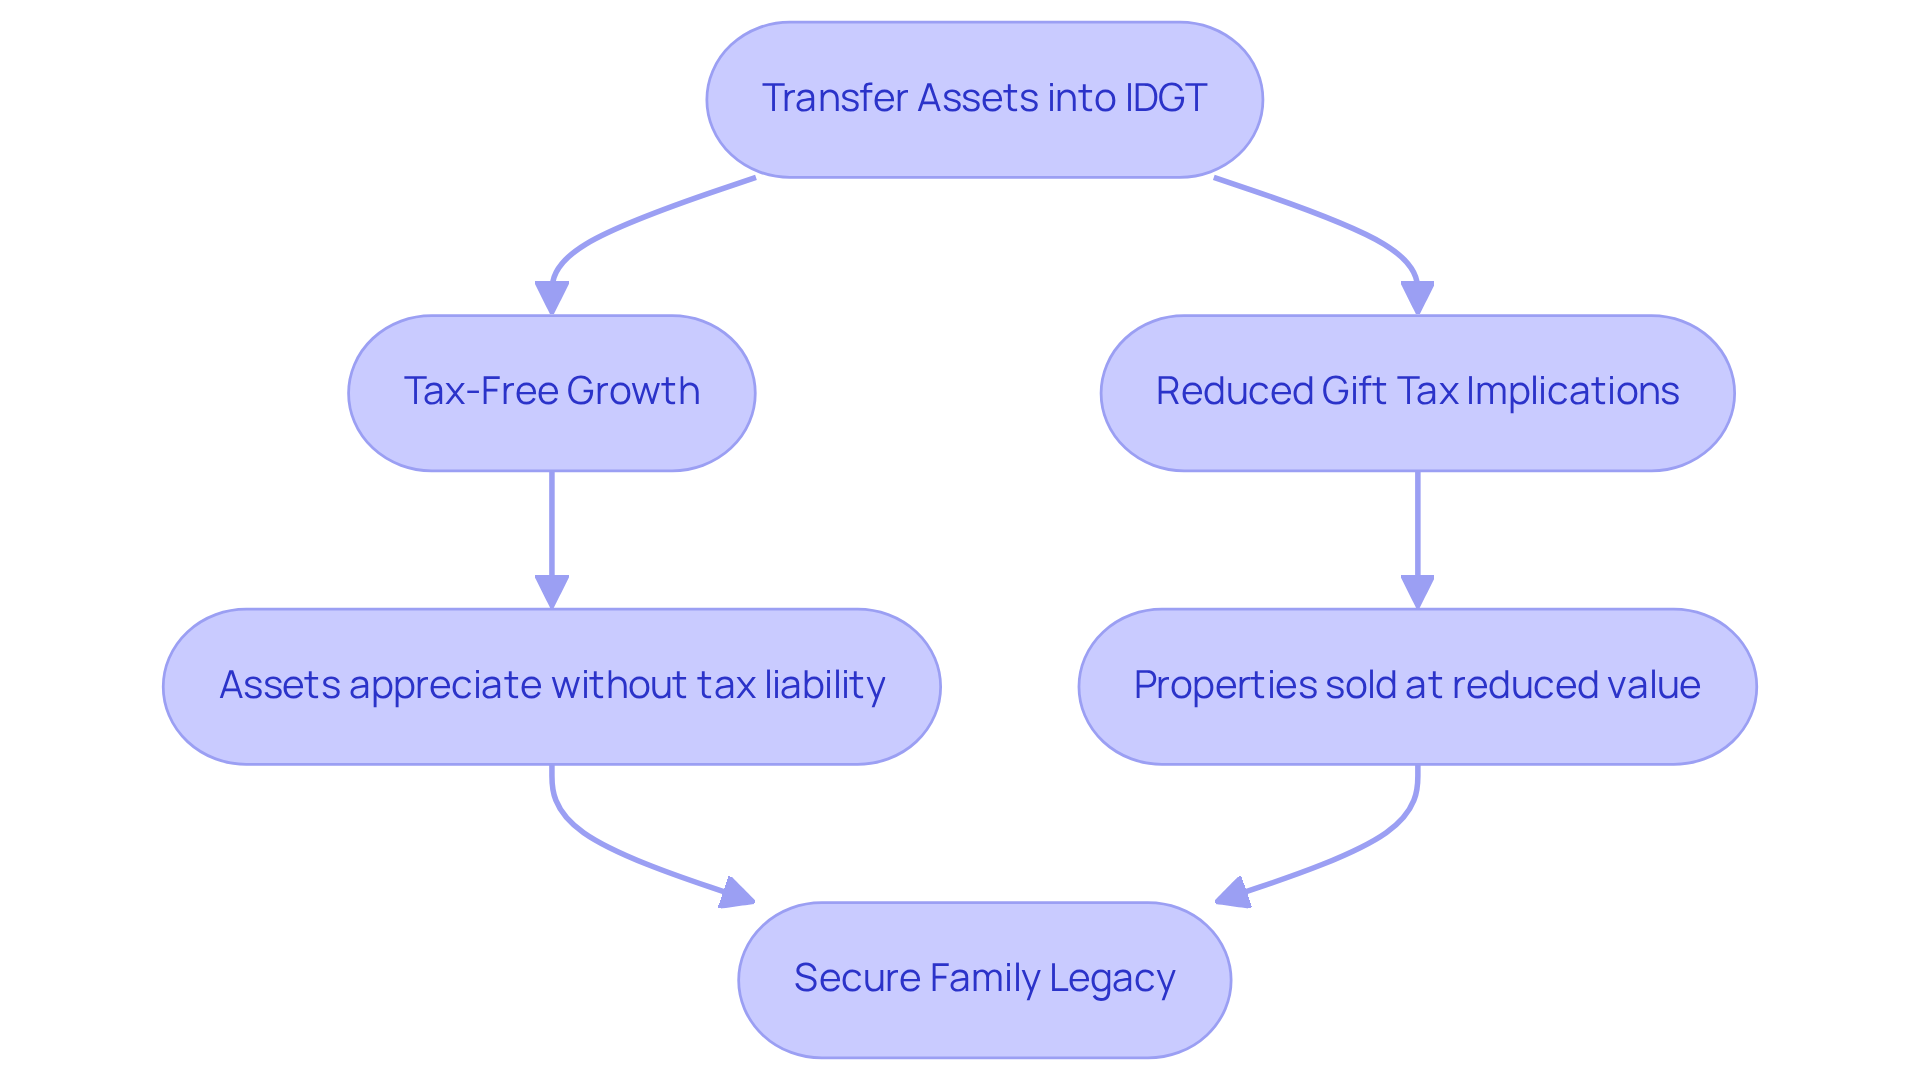
Picture this: you transfer resources into an IDGT, and while you still have certain rights, like paying the income taxes on the trust’s earnings, the trust itself can grow without incurring additional tax obligations. For instance, if you place $5 million of business stock into an IDGT and it appreciates to $10 million, your heirs can inherit that gain without facing a tax hit. This means less financial stress for your family when it comes time to pass on your legacy.
When properties are sold to the IDGT, they can be transferred at a reduced value, which helps minimize potential gift tax implications. The trust can hold various assets, including real estate and investments, which can appreciate over time, benefiting your loved ones without increasing your tax liability. This approach is perfect for families who want to pass on their legacy while still being in control of their assets.
With recent changes in tax legislation, like the One Big Beautiful Bill Act (OBBBA) raising the inheritance tax exemption to $15 million per individual in 2026, IDGTs have become even more appealing. Families can use these arrangements to maintain wealth across generations, ensuring that their financial legacy is effectively managed and passed down.
But don’t worry, with the right support, you can navigate this journey together and make sure your family’s goals are met. For families like Allison and Brian, who are concerned about their financial well-being and are seeking professional assistance to navigate tax planning complexities, IDGTs can be a valuable tool in optimizing their financial situation. With the right guidance, you can ensure your family’s dreams are protected for generations to come.
Evaluate Benefits and Drawbacks of IDGTs
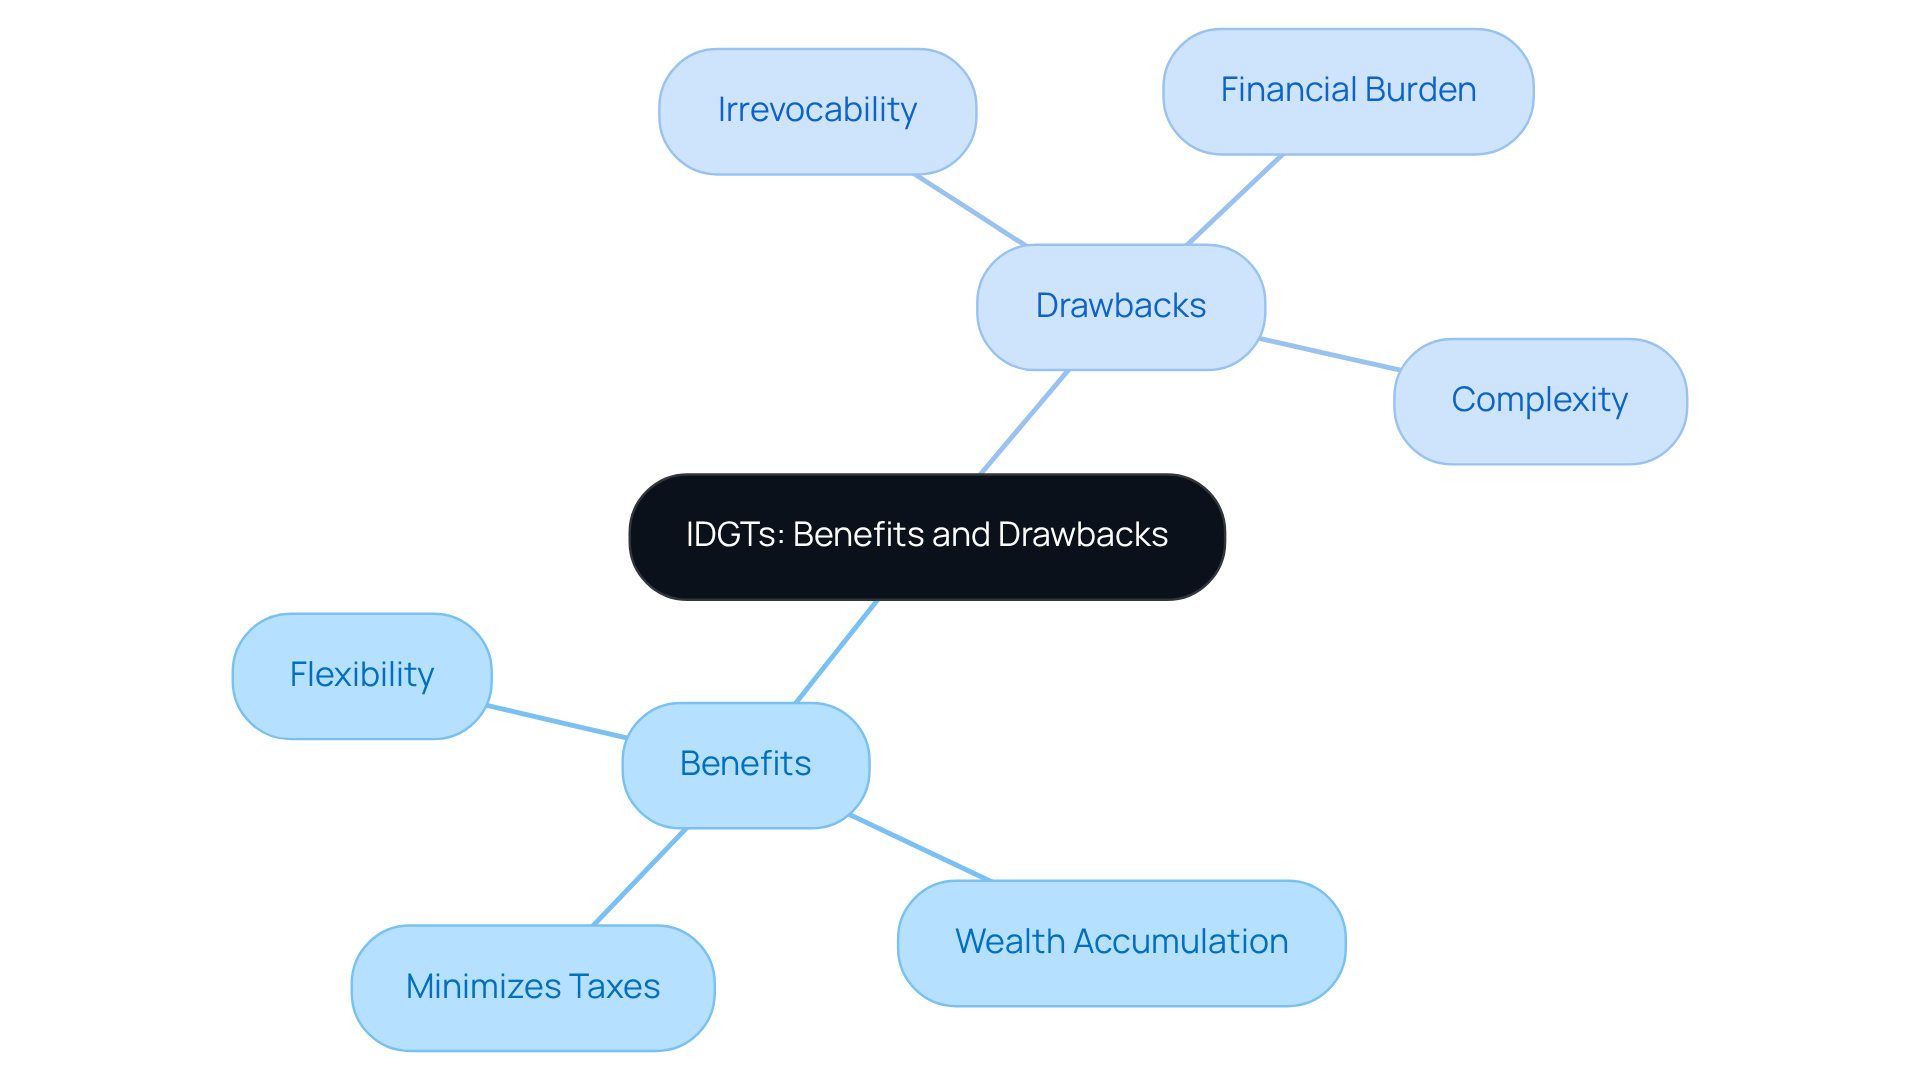
Imagine being able to pass on your hard-earned wealth to your children while minimizing the taxes they might face in the future. Intentionally defective grantor trusts (IDGTs) can help you achieve this goal. They allow you to pass on wealth to your heirs while reducing estate levies, as the assets are excluded from your taxable estate. By paying the income taxes on the trust’s earnings, you enable the trust to grow without tax drag, which can significantly enhance wealth accumulation over time. Plus, IDGTs offer flexibility in managing resources, allowing you to customize the trust to meet your family’s specific needs, including provisions for intentionally defective grantor trusts.
But it’s important to think about some challenges that come with this option. IDGTs are irrevocable, meaning that once you transfer assets, you can’t reclaim them. This loss of control can be a significant concern for families. Additionally, the ongoing obligation of paying income taxes on the trust’s earnings can create a financial burden, especially if it generates substantial income. Setting up and maintaining an IDGT can also be complex, often requiring professional legal and tax advice.
Did you know that many families are turning to grantor trusts as a way to secure their legacy? Statistics show that out of the 2.8 million irrevocable trusts, around 600,000 are categorized as grantor trusts. The federal inheritance tax threshold for 2023 is set at $12.92 million for individuals, with forecasts indicating a reduction to between $6 and $7 million by 2026. This highlights the importance of strategic planning for families with considerable wealth. IDGTs can effectively lock in the value of your holdings at the time of transfer, which decreases potential taxes on the inheritance of intentionally defective grantor trusts.
Case studies demonstrate how intentionally defective grantor trusts can reduce the income tax burden of asset holdings, especially for grantors who can cover the income tax liabilities. However, the ongoing responsibility of paying income taxes can strain personal finances. That’s why careful financial planning is essential to manage these obligations without affecting your overall financial stability. Engaging with experienced financial planners and tax professionals is crucial to ensure that an IDGT aligns with your individual financial objectives and circumstances.
With the right guidance, you can navigate the complexities of intentionally defective grantor trusts and confidently secure your family’s financial future.
Outline Steps to Establish an IDGT
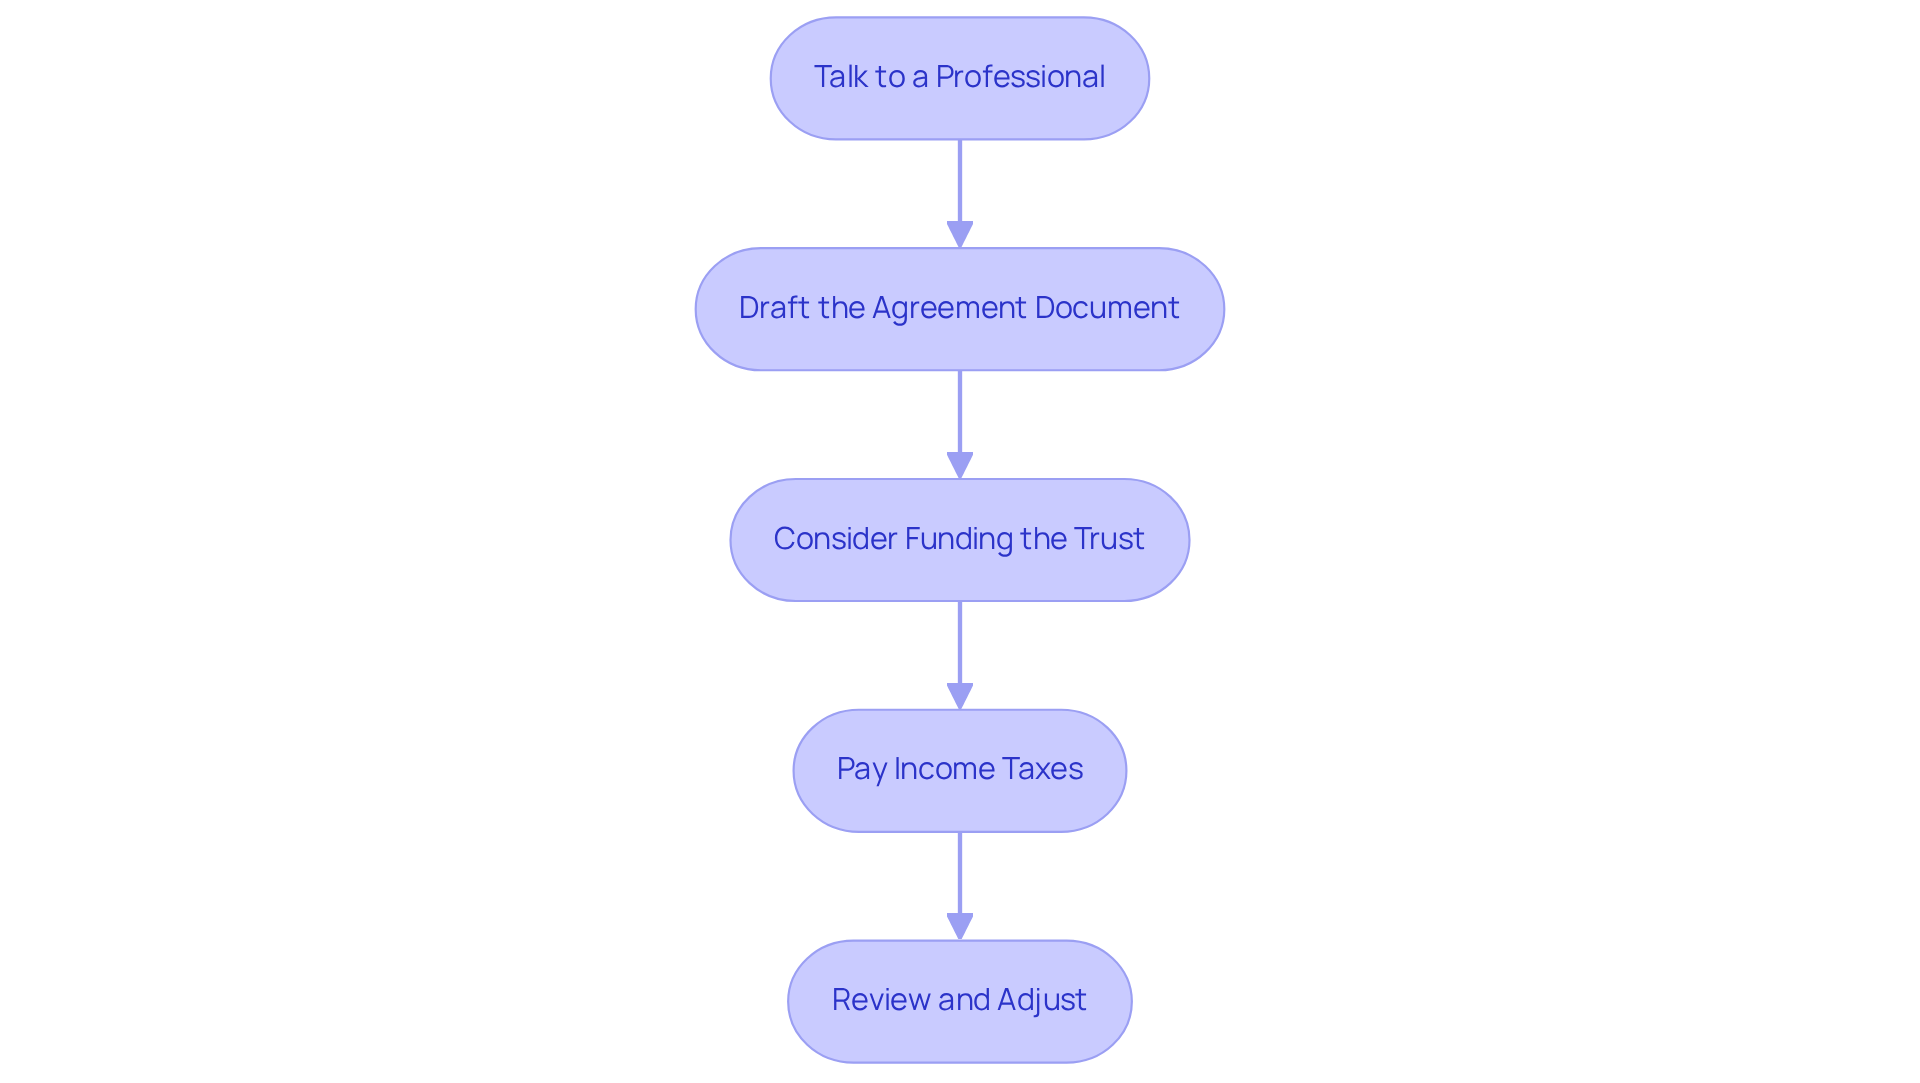
Imagine securing your family’s future while navigating the complexities of estate planning. To establish an Intentionally Defective Grantor Trust (IDGT), follow these essential steps:
-
Talk to a Professional: It’s important to talk to a professional who understands your family’s needs. An estate planning attorney can help ensure the intentionally defective ILIT is structured correctly and meets all legal requirements.
-
Draft the Agreement Document: Collaborate with your attorney to create a document that outlines the terms of the IDGT. This includes the powers you retain as the grantor and the rights of the beneficiaries.
-
Consider funding the trust by thinking about moving your assets into the intentionally defective ILIT through gifting or selling items. This step is crucial for protecting your family’s wealth, so make sure to assess the value of these assets accurately to avoid triggering gift tax implications.
-
Pay Income Taxes: As the grantor, you’ll be responsible for paying income taxes on the earnings of the entity. Incorporating this obligation into your overall financial planning can help maintain the value of the fund for future growth.
-
Review and Adjust: Regularly check in on the trust’s performance and make necessary adjustments to align with your family’s financial goals and changing circumstances.
By taking these steps, you can create a secure future for your family, ensuring that your hard-earned wealth is preserved for generations to come. For instance, placing $5 million of family business stock in an IDGT that appreciates to $10 million allows heirs to receive the $5 million gain tax-free, demonstrating the potential benefits of this strategy.
Conclusion
Imagine securing your family’s financial future while navigating the complexities of tax implications with ease. Establishing an intentionally defective grantor trust (IDGT) can be a wonderful way for families to protect their legacy. This special trust can help your family pass on wealth smoothly, reducing tax worries and allowing your assets to grow without extra costs. When you grasp how IDGTs work, you can keep control of your wealth and ensure a bright future for your loved ones.
We’ve explored the ups and downs of IDGTs together, helping you understand what’s best for your family. You can pass on growing assets without adding tax burdens, but it’s important to think through your choices carefully. Working with caring professionals like Bright Advisers can help you navigate estate planning and make sure your trust fits your family’s needs.
Deciding to set up an IDGT isn’t just about tax benefits; it’s about building a legacy that your family will cherish forever. Taking these steps today can empower your family to thrive for generations to come, ensuring that your legacy is cherished and protected. If you’re ready to explore this valuable option, talking to a trusted advisor can help you make choices that safeguard your family’s wealth.
Frequently Asked Questions
What is an intentionally defective grantor trust (IDGT)?
An IDGT is a type of trust that allows families to manage their wealth while offering unique tax benefits. It is considered “intentionally defective” because, for income tax purposes, the trust is not counted as part of the grantor’s taxable holdings, but it still holds value for inheritance tax.
How does an IDGT benefit families in terms of taxes?
An IDGT allows families to transfer wealth efficiently while minimizing tax liabilities. Although the assets in the trust are not part of the grantor’s taxable holdings, the grantor must pay income taxes on the trust’s earnings. This dual treatment helps families secure their financial future while managing tax implications.
What is the inheritance tax threshold for 2024?
As of 2024, the inheritance tax threshold is $13.61 million per person. Individuals can transfer substantial wealth without incurring transfer taxes, but gifts exceeding this threshold are subject to a 40% gift tax rate.
What are the key characteristics of IDGTs?
Key characteristics of IDGTs include the ability to transfer appreciating properties while maintaining control over the trust arrangement. They can be designed to provide financial assistance for children, grandchildren, or charitable initiatives, with specific guidelines for fund distribution.
How can IDGTs help families with significant assets?
IDGTs can be a game-changer for families with significant assets, allowing them to pass on wealth without incurring heavy tax burdens. For example, if a family places $5 million of business stock into an IDGT that appreciates to $10 million, the heirs can receive the $5 million gain without incurring charges, while the grantor pays the income obligations.
Why is it important to consult a professional when considering an IDGT?
Consulting a qualified professional, such as Bright Advisers, is important to explore integrated tax planning strategies tailored to your family’s needs. They can help ensure that your family’s legacy is protected for generations to come.
What disclaimers should be noted regarding IDGTs and investments?
It is important to remember that past performance does not guarantee future results, and all investments are subject to risk. Advisory services related to IDGTs are provided through Lifeworks Advisors, a registered investment adviser.
List of Sources
- Define Intentionally Defective Grantor Trusts (IDGTs)
- Intentionally Defective Grantor Trusts (IDGTs) – Wealthspire (https://wealthspire.com/blog/intentionally-defective-grantor-trusts-idgt)
- Intentionally Defective Grantor Trusts (https://marinerwealthadvisors.com/insights/intentionally-defective-grantor-trusts)
- Intentionally Defective Grantor Trusts | National Advisors Trust (https://nationaladvisors.com/a-guide-to-intentionally-defective-grantor-trusts-idgts)
- Explain How IDGTs Work
- IDGTs: A Versatile Estate Planning Tool (https://marinerwealthadvisors.com/insights/idgts-a-versatile-estate-planning-tool)
- Intentionally Defective Grantor Trusts | National Advisors Trust (https://nationaladvisors.com/a-guide-to-intentionally-defective-grantor-trusts-idgts)
- What is an intentionally defective grantor trust (IDGT)? | Fidelity (https://fidelity.com/viewpoints/wealth-management/insights/intentionally-defective-grantor-trusts)
- Grantor Trusts & IDGTs: Estate Planning & Tax Considerations (https://commercetrustcompany.com/research-and-insights/articles/understanding-intentionally-defective-grantor-trusts)
- Asset Transfers and Intentionally Defective Grantor Trusts | Pierro Law (https://pierrolaw.com/tax-planning/asset-transfers-and-intentionally-defective-grantor-trusts)
- Evaluate Benefits and Drawbacks of IDGTs
- Intentionally Defective Grantor Trusts (https://marinerwealthadvisors.com/insights/intentionally-defective-grantor-trusts)
- Intentionally Defective Grantor Trusts: Understanding the Hidden Drawbacks – Falcon Wealth Planning (https://falconwealthplanning.com/falcon-articles/intentionally-defective-grantor-trusts-understanding-the-hidden-drawbacks)
- Trusts: Income and Estate and Gift Tax Issues (https://congress.gov/crs-product/R48879)
- Understanding the Uses, Benefits, and Drawbacks of an Intentionally Defective Grantor Trust (IDGT) – GSRM (https://gsrm.com/understanding-the-uses-benefits-and-drawbacks-of-an-intentionally-defective-grantor-trust-idgt)
- What is an intentionally defective grantor trust (IDGT)? | Fidelity (https://fidelity.com/viewpoints/wealth-management/insights/intentionally-defective-grantor-trusts)
- Outline Steps to Establish an IDGT
- Grantor Trusts & IDGTs: Estate Planning & Tax Considerations (https://commercetrustcompany.com/research-and-insights/articles/understanding-intentionally-defective-grantor-trusts)
- Intentionally Defective Grantor Trusts | National Advisors Trust (https://nationaladvisors.com/a-guide-to-intentionally-defective-grantor-trusts-idgts)
- IDGTs: A Versatile Estate Planning Tool (https://marinerwealthadvisors.com/insights/idgts-a-versatile-estate-planning-tool)
- An Overview of Intentionally Defective Grantor Trusts – Smith and Howard (https://smith-howard.com/an-overview-of-intentionally-defective-grantor-trusts)
- Understanding the Uses, Benefits, and Drawbacks of an Intentionally Defective Grantor Trust (IDGT) – GSRM (https://gsrm.com/understanding-the-uses-benefits-and-drawbacks-of-an-intentionally-defective-grantor-trust-idgt)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading