

Overview
Navigating the path to homeownership can be overwhelming, especially for first-time buyers. This article outlines the rules for withdrawing funds from an IRA specifically for your first home purchase. Did you know you can withdraw up to $10,000 penalty-free if you meet certain conditions?
Understanding the eligibility criteria is crucial. Imagine if you could access your savings without the worry of penalties. It’s also important to remember that these funds need to be utilized within 120 days. Consulting with tax experts can provide peace of mind, ensuring you comply with IRS regulations.
We know that financial decisions can feel daunting, but you’re not alone. By taking these steps, you can navigate the financial landscape more effectively, making informed choices for your family’s future. Together, we can navigate this journey, ensuring you have the support you need to achieve your homeownership dreams.
Key Highlights:
- First-time homebuyers can withdraw up to $10,000 from their IRA without penalties under specific conditions.
- To qualify, a first-time homebuyer must not have owned a principal residence in the past two years.
- Both spouses can withdraw $10,000 each, totaling $20,000 for home purchases.
- Withdrawn funds must be used within 120 days for purchasing, constructing, or renovating a primary residence.
- If a home purchase is canceled, funds can be returned to the IRA within 120 days to avoid penalties.
- Consulting tax experts is crucial for understanding implications and ensuring compliance with IRS regulations.
- Other exceptions to early withdrawal penalties include disability, certain medical expenses, and qualified education costs.
- The article emphasizes the importance of maintaining thorough documentation of withdrawals and home purchases for IRS compliance.
Introduction
As the dream of homeownership becomes increasingly elusive for many families, first-time buyers are exploring innovative ways to finance their new beginnings. Imagine if there was a way to tap into your retirement savings to help secure that dream. One such avenue lies within the often-overlooked Individual Retirement Account (IRA). This tool not only serves as a retirement savings vehicle but also offers unique provisions for accessing funds without penalties.
It’s important to understand that the IRS permits penalty-free withdrawals of up to $10,000 for first-time home purchases. However, understanding the eligibility criteria, rules, and potential pitfalls is crucial for aspiring homeowners. This article delves into the intricacies of IRA withdrawals, providing insights into how families can leverage their retirement savings to achieve their homeownership goals while maintaining their financial stability. Together, we can navigate this journey toward a brighter future.
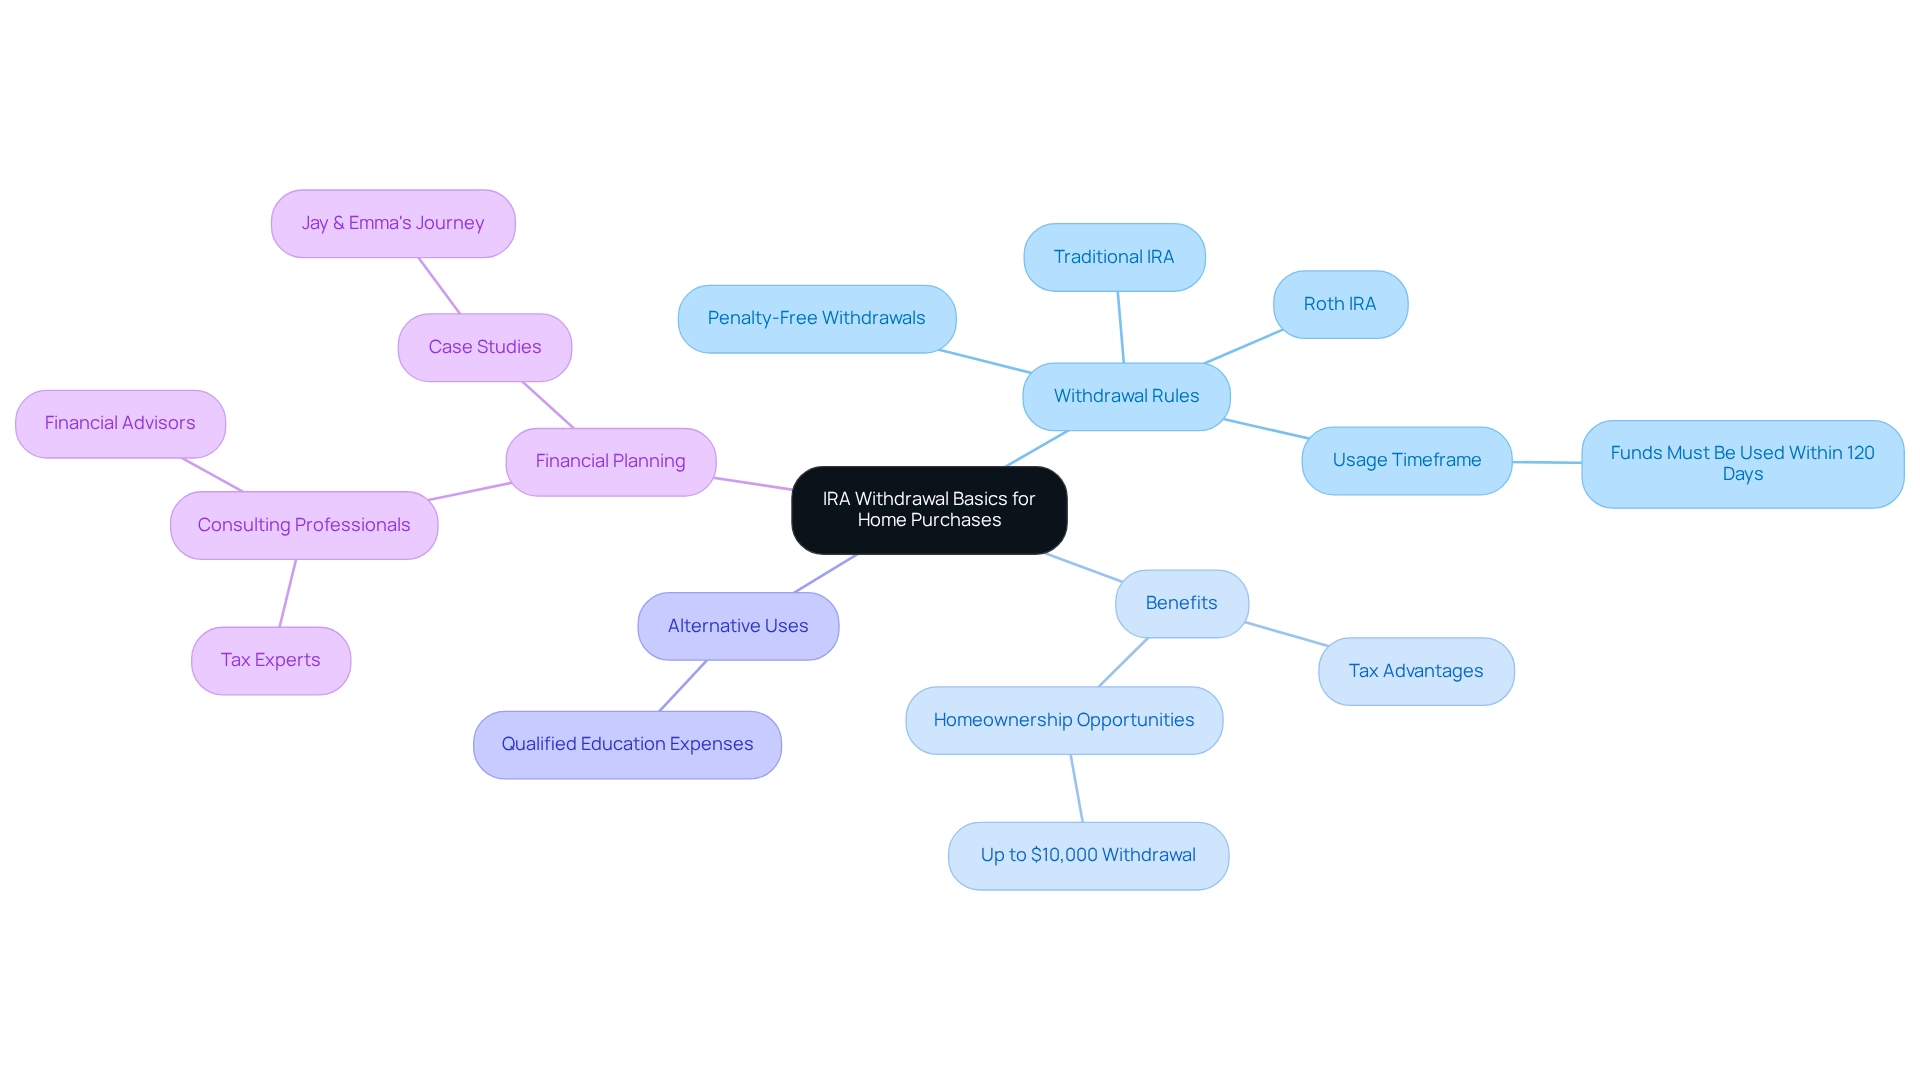
Clarify IRA Withdrawal Basics for Home Purchases
An Individual Retirement Account (IRA) is more than just a savings vehicle; it’s a tax-advantaged way to secure your family’s future. If you’re a first-time homebuyer, you’ll be pleased to know that the IRA withdrawal rules for home purchase allow both Traditional and Roth IRAs to offer special provisions for penalty-free withdrawals under certain conditions. Imagine being able to take out up to $10,000 from your IRA by following the IRA withdrawal rules for home purchase to buy your first home! This opportunity is available to you at any age, as long as you use the funds within 120 days of withdrawal. It’s a wonderful advantage that allows you to retain the tax benefits of your account while stepping into homeownership.
Recent statistics reveal that many first-time homebuyers are tapping into their IRA resources for down payments, highlighting the importance of understanding these regulations. But that’s not all—IRA funds can also be used for qualified education expenses, showcasing their flexibility beyond just home purchases. It’s important to discuss these options with tax experts who can clarify the implications of such withdrawals, helping your family align its financial strategies with long-term goals. As Meilahn wisely points out, ‘This also retains the tax benefits and keeps your retirement plan on track.’ By understanding the IRA withdrawal rules for home purchase, you can make informed decisions that enhance your family’s stability and future aspirations for homeownership.
Additionally, consider the maximum amount for a 401(k) loan, which is $50,000 or 50% of the account’s vested value. This context can be invaluable for families exploring their financial possibilities. Take, for example, Jay & Emma’s journey; with the guidance of Bright Advisers, they navigated the complexities of financial planning, creating a comprehensive plan that aligned with their dreams of homeownership and economic independence. Remember, consulting experts for IRA distributions not only clarifies the regulations but also empowers families to achieve their financial objectives. Together, we can navigate this journey toward a secure and fulfilling future.
Explore Eligibility and Rules for IRA Withdrawals
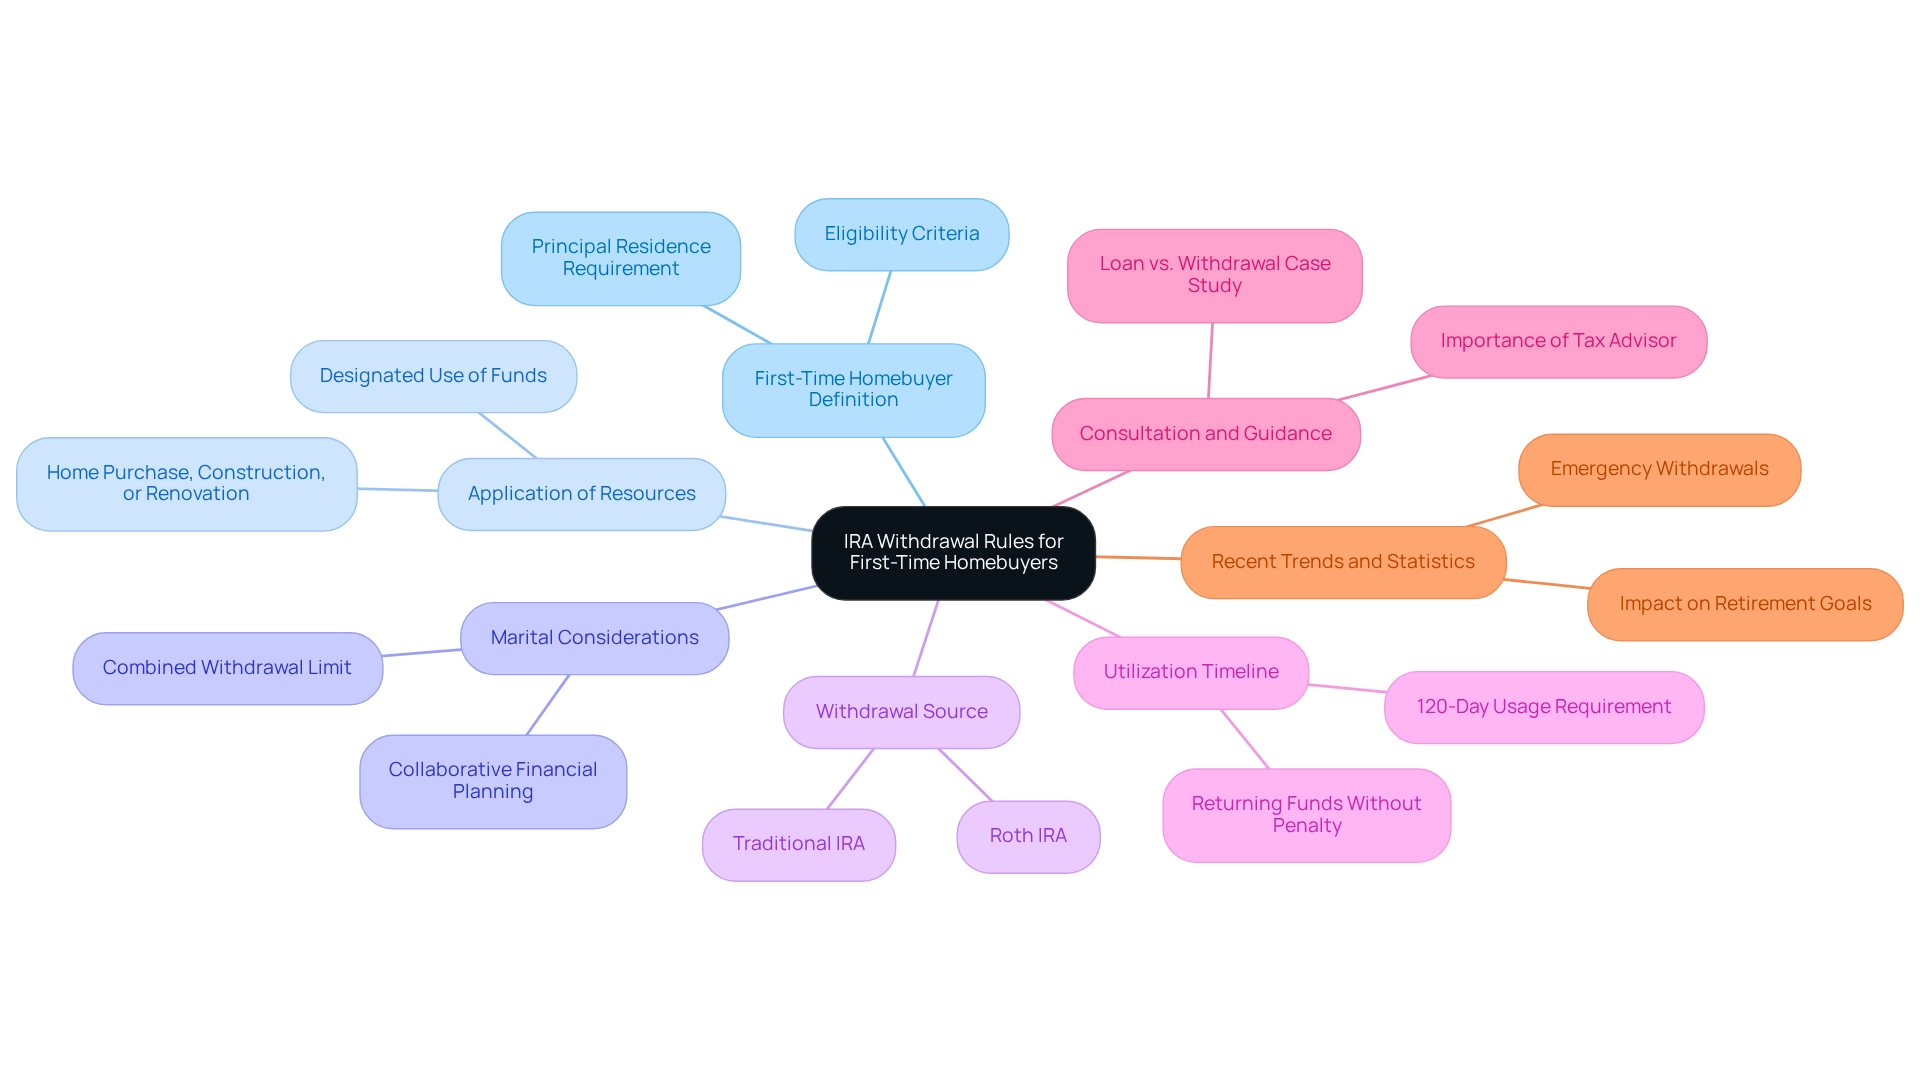
Navigating the journey of homeownership can be overwhelming, especially for first-time homebuyers. To ease some of that burden, let’s explore the IRA withdrawal rules for home purchase that enable you to qualify for a $10,000 penalty-free withdrawal from your IRA when buying your first home.
-
First-Time Homebuyer Definition: To qualify, you must be considered a first-time homebuyer, meaning you haven’t owned a principal residence in the past two years. This definition opens the door to new opportunities for you and your family.
-
Application of Resources: The funds you withdraw must be specifically designated for purchasing, constructing, or renovating your primary residence. This ensures that your hard-earned savings are used to create a home for your loved ones.
-
Marital Considerations: If you’re married, there’s good news! Both you and your spouse can each withdraw up to $10,000, allowing for a combined total of $20,000 for your home purchase. This collaborative approach can significantly ease the financial strain.
-
Withdrawal Source: Remember, these resources need to come from either a Traditional or Roth IRA. It’s essential to know where your funds are coming from to make informed decisions.
-
Utilization Timeline: To avoid penalties, be sure to use the funds within 120 days of withdrawal. If your home purchase is canceled or delayed, you can return the funds to your IRA within this timeframe without incurring tax penalties. This flexibility is crucial for first-time homebuyers like you, who may face unexpected changes.
As we look ahead to 2025, many first-time homebuyers are expected to tap into IRA distributions, reflecting a growing trend of leveraging retirement savings for home purchases. Financial experts stress the importance of understanding the IRA withdrawal rules for home purchase. They advise prospective homebuyers to consult with a tax advisor to navigate their unique circumstances effectively. As Kevin O’Neil, Managing Director at Merrill, wisely notes, “You should consult your personal tax advisor regarding your specific situation before making any decisions.”
Moreover, recent statistics suggest that plans may allow employees to withdraw up to $1,000 for unforeseen expenses. This adaptability of retirement accounts can be a lifeline for first-time homebuyers facing unexpected costs.
Real-life stories illustrate how first-time homebuyers have successfully accessed IRA funds, highlighting the importance of being informed about the IRA withdrawal rules for home purchase and eligibility criteria. Additionally, a case study comparing loans to withdrawing from retirement accounts emphasizes expert guidance against early access due to penalties and taxes, suggesting that viewing a 401(k) loan as a more favorable option might be wise.
Understanding these guidelines empowers families like yours to make strategic financial decisions on the path to homeownership. Remember, we’re here for you, and together, we can navigate this journey.
Understand Penalties and Exceptions for Early Withdrawals
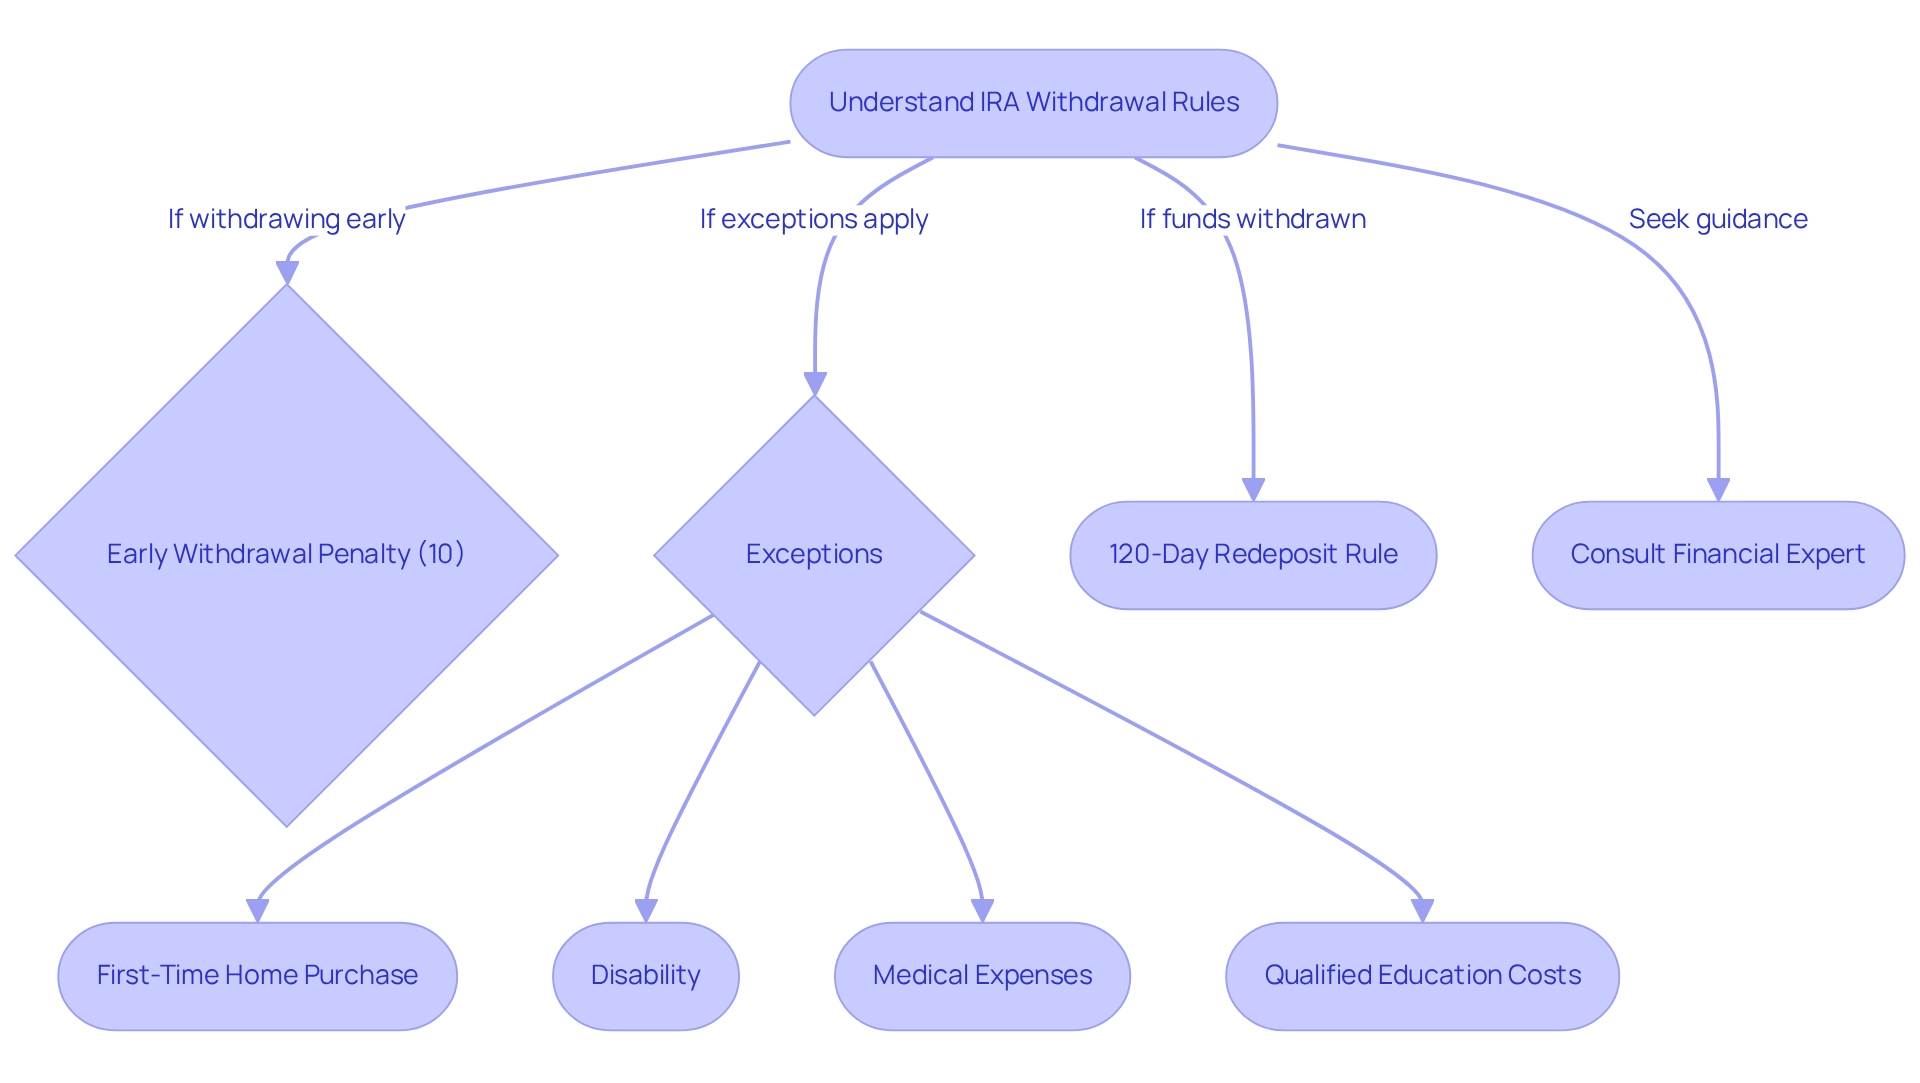
Withdrawing money from your IRA before reaching 59½ often incurs a 10% early exit fee, in addition to standard income taxes on the amount taken out. However, there are several exceptions that can help ease this financial burden. For instance, under the IRA withdrawal rules for home purchase, first-time homebuyers can withdraw up to $10,000 without facing this penalty, making it a valuable option for those embarking on the journey of purchasing their first home. Other exceptions include withdrawals due to disability—defined by the IRS as the inability to engage in any substantial gainful activity due to physical or mental conditions—as well as certain medical expenses and qualified education costs.
Imagine if you were among the many individuals unaware of these exceptions in 2025. This lack of knowledge can lead to unnecessary penalties. If funds are withdrawn and not utilized within 120 days, they must be redeposited into the IRA to avoid penalties, underscoring the importance of understanding the rules governing IRA withdrawals.
It’s crucial to consult IRS guidelines or seek advice from a financial expert to effectively navigate the IRA withdrawal rules for home purchase. At Bright Advisers, we are committed to minimizing fund fees, which apply to most of our models, ensuring that families can access wealth management solutions without incurring excessive costs. A case study illustrates the importance of professional guidance: individuals like Allison and Brian, who consulted tax experts before making withdrawals, were better equipped to align their financial objectives with their home purchasing decisions. This emphasizes the value of tailored financial guidance.
As Susan S. Lewis, a Certified Public Accountant, wisely advises, “Seek professional guidance to create a strategy that aligns with your financial objectives.” This proactive approach can help ensure that you make informed decisions regarding your IRA distributions, ultimately empowering young parents to safeguard their financial future. Together, we can navigate this journey with confidence.
Implement Steps for Executing an IRA Withdrawal
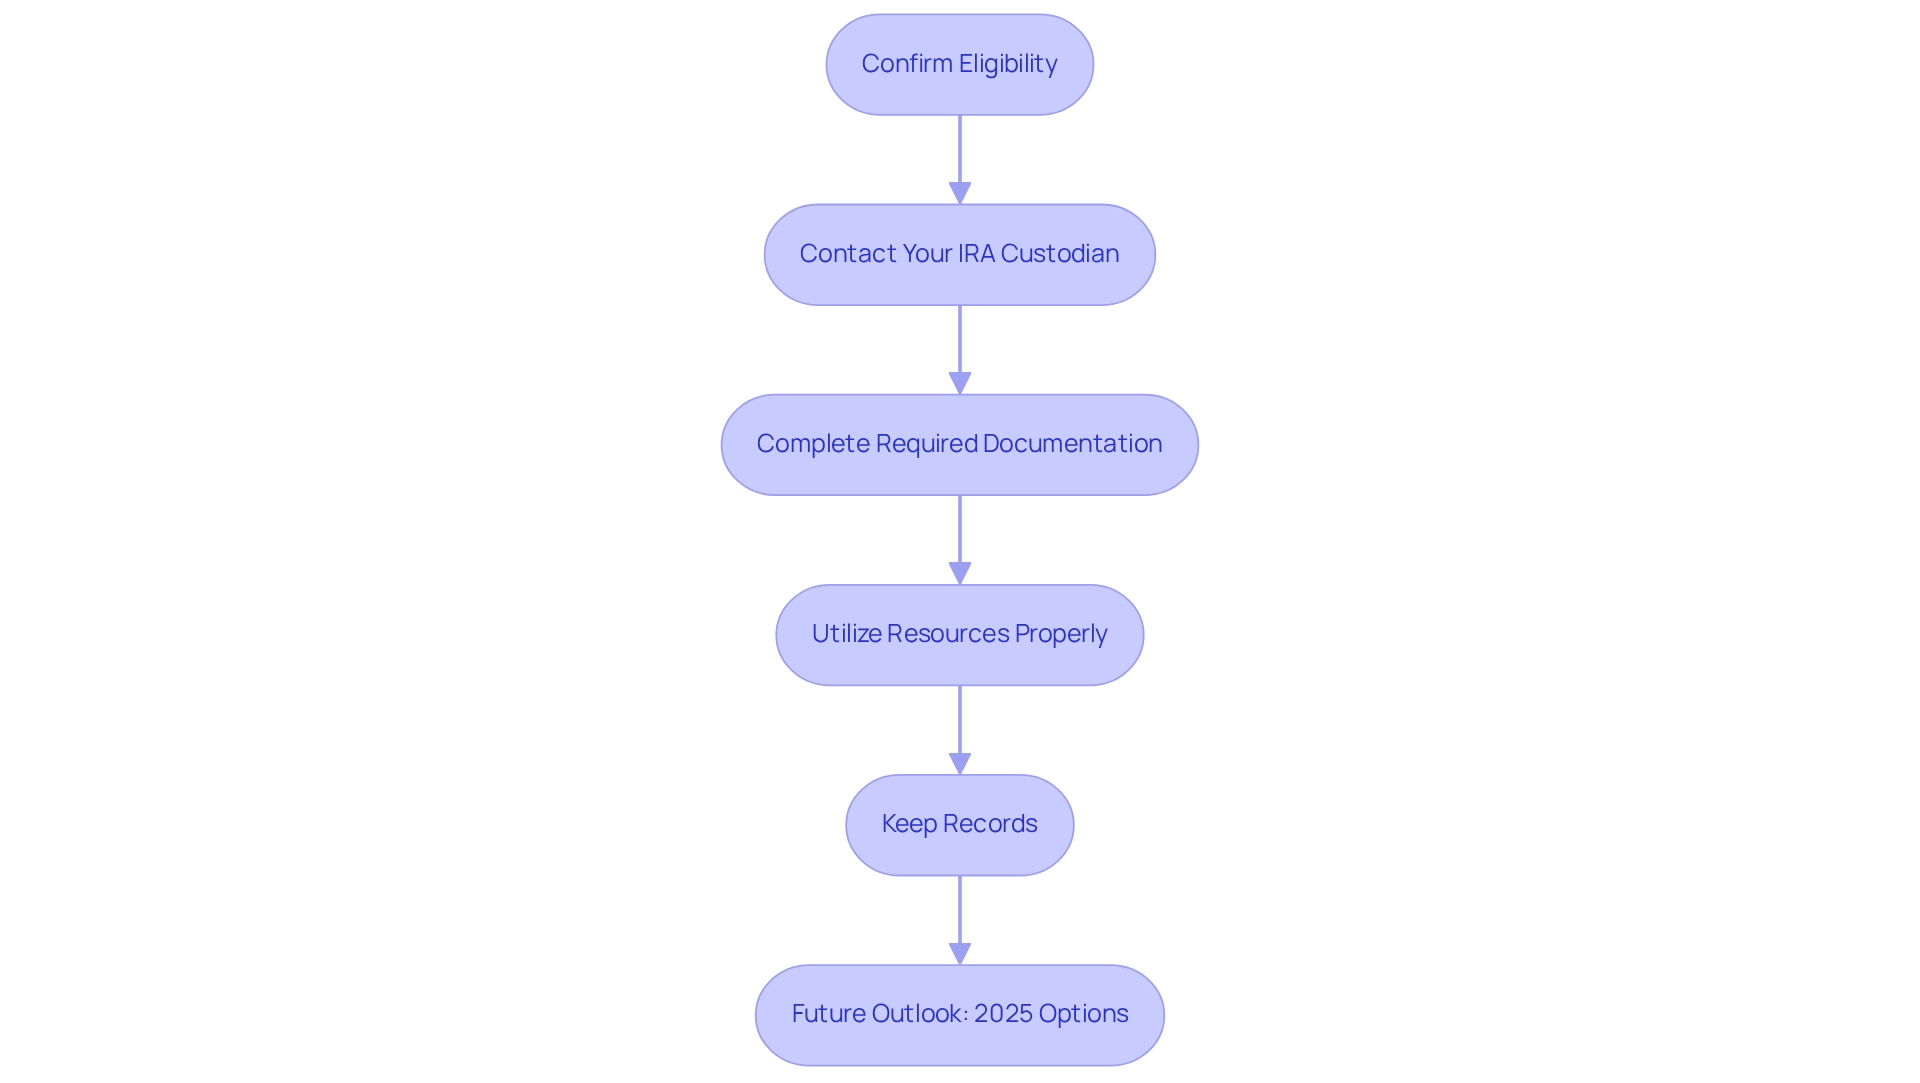
Are you considering using your IRA to buy your first home? It’s a big step, and we’re here to help you navigate this journey with confidence. To successfully execute an IRA distribution for a home purchase, it’s important to understand the IRA withdrawal rules for home purchase and follow these essential steps:
-
Confirm Eligibility: First, verify that you qualify as a first-time homebuyer. Familiarizing yourself with the IRA withdrawal rules for home purchase is crucial, as they allow you to withdraw up to $10,000 without penalties.
-
Contact Your IRA Custodian: Reach out to your IRA custodian or financial institution to inform them of your intention to withdraw funds for your home purchase. They will guide you through the necessary forms and procedures, making the process smoother for you.
-
Complete Required Documentation: Take your time to accurately fill out the request form, indicating the specific amount you wish to withdraw. This step is important to ensure everything is in order.
-
Utilize Resources Properly: After withdrawing the money, remember to use those funds within 120 days for the acquisition of your primary residence. Following the IRA withdrawal rules for home purchase helps you avoid any potential penalties, allowing you to focus on your new home.
-
Keep Records: Maintaining thorough documentation of both the withdrawal and the home purchase is essential for compliance with IRS regulations. Understanding the IRA withdrawal rules for home purchase will give you peace of mind as you move forward.
Looking ahead to 2025, individuals can explore options such as rolling over 401(k) assets into an IRA. This allows for tax-free access to up to $10,000 for first-time home purchases, which aligns with the IRA withdrawal rules for home purchase, providing additional pathways for families seeking to leverage their retirement savings while enjoying tax advantages. Imagine being able to roll over up to $10,000 tax-free into an IRA and using those funds for your first home.
Testimonials from families who have successfully navigated this process highlight the importance of understanding these rules and the potential for significant financial benefits. Remember, together, we can navigate this journey, ensuring you make informed decisions that align with your family’s values and priorities.
Conclusion
Leveraging an Individual Retirement Account (IRA) for first-time home purchases opens a door to fulfilling the dream of homeownership for aspiring families. Imagine being able to access up to $10,000 penalty-free, simply by understanding the basics of IRA withdrawals. This opportunity is available for both Traditional and Roth IRAs, allowing you to retain the tax advantages of your retirement accounts while making a strategic investment in your primary residence.
It’s important to note that eligibility criteria play a crucial role in this journey. First-time homebuyers must meet specific conditions, such as:
- Not having owned a principal residence in the past two years
- Ensuring that the withdrawn funds are utilized within 120 days
Consulting with tax professionals can help potential buyers navigate these complexities, empowering you to make informed decisions that align with your family’s financial goals. Real-life examples illustrate the effectiveness of this approach, showcasing how families like yours have successfully utilized their IRA funds to achieve homeownership.
Being aware of the penalties associated with early withdrawals, as well as the exceptions that exist for first-time homebuyers, is essential. By understanding these regulations and executing the necessary steps for a withdrawal, families can minimize financial risks and maximize their chances of securing a home. Ultimately, the thoughtful use of IRA funds not only supports your aspirations for homeownership but also fosters long-term financial stability, paving the way for a brighter future. Remember, together, we can navigate this journey toward a secure and nurturing home for your family.
Frequently Asked Questions
What is an Individual Retirement Account (IRA)?
An Individual Retirement Account (IRA) is a tax-advantaged savings vehicle designed to help secure your family’s financial future.
Can first-time homebuyers withdraw from their IRA for home purchases?
Yes, first-time homebuyers can withdraw up to $10,000 from their IRA for home purchases without penalty, provided they follow the IRA withdrawal rules for home purchase.
Are there age restrictions for withdrawing from an IRA for home purchase?
No, there are no age restrictions for withdrawing from an IRA for home purchase, as long as the funds are used within 120 days of withdrawal.
Besides home purchases, can IRA funds be used for other purposes?
Yes, IRA funds can also be used for qualified education expenses, demonstrating their flexibility beyond just home purchases.
Why is it important to consult tax experts regarding IRA withdrawals?
Consulting tax experts is important because they can clarify the implications of IRA withdrawals and help families align their financial strategies with long-term goals.
What is the maximum amount that can be borrowed from a 401(k) loan?
The maximum amount for a 401(k) loan is $50,000 or 50% of the account’s vested value.
How can families benefit from expert guidance in financial planning?
Expert guidance in financial planning can help families navigate complexities, create comprehensive plans, and align their financial objectives with their dreams of homeownership and economic independence.
List of Sources
- Clarify IRA Withdrawal Basics for Home Purchases
- IRA Withdrawals: Laws, Penalties, and Life Event Exceptions | The Motley Fool (https://fool.com/retirement/plans/ira/withdrawal)
- IRA and 401(k) Withdrawal Rules | U.S. Bank (https://usbank.com/retirement-planning/financial-perspectives/ira-and-401k-withdrawal-rules.html)
- IRA Withdrawal for Home Purchase: Find Out How | Lewis CPA (https://lewis.cpa/blog/using-ira-for-home-purchase)
- Explore Eligibility and Rules for IRA Withdrawals
- Using an IRA to Make a House Down Payment as First-Time Buyer (https://nolo.com/legal-encyclopedia/using-ira-make-house-down-payment.html)
- Guide to Retirement Account Withdrawals: IRAs and 401(k) (https://merrilledge.com/article/retirement-account-withdrawal)
- IRA and 401(k) Withdrawal Rules | U.S. Bank (https://usbank.com/retirement-planning/financial-perspectives/ira-and-401k-withdrawal-rules.html)
- Understand Penalties and Exceptions for Early Withdrawals
- What Are the Exceptions to the IRA Early Withdrawal Penalty? (https://smartasset.com/retirement/ira-early-distribution-exceptions)
- Early Distributions and Penalty Tax Exceptions — Ascensus (https://thelink.ascensus.com/articles/2025/4/16/early-distributions-and-penalty-tax-exceptions)
- IRA Withdrawal for Home Purchase: Find Out How | Lewis CPA (https://lewis.cpa/blog/using-ira-for-home-purchase)
- Implement Steps for Executing an IRA Withdrawal
- Publication 590-B (2024), Distributions from Individual Retirement Arrangements (IRAs) | Internal Revenue Service (https://irs.gov/publications/p590b)
- Yes, You Can Use Your IRA to Purchase a Home | Lord Abbett (https://lordabbett.com/en-us/financial-advisor/insights/retirement-planning/yes–you-can-use-your-ira-to-purchase-a-home-.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading