

Key Highlights
- A life estate allows individuals to live in their home for life while ensuring it passes to their children after their death.
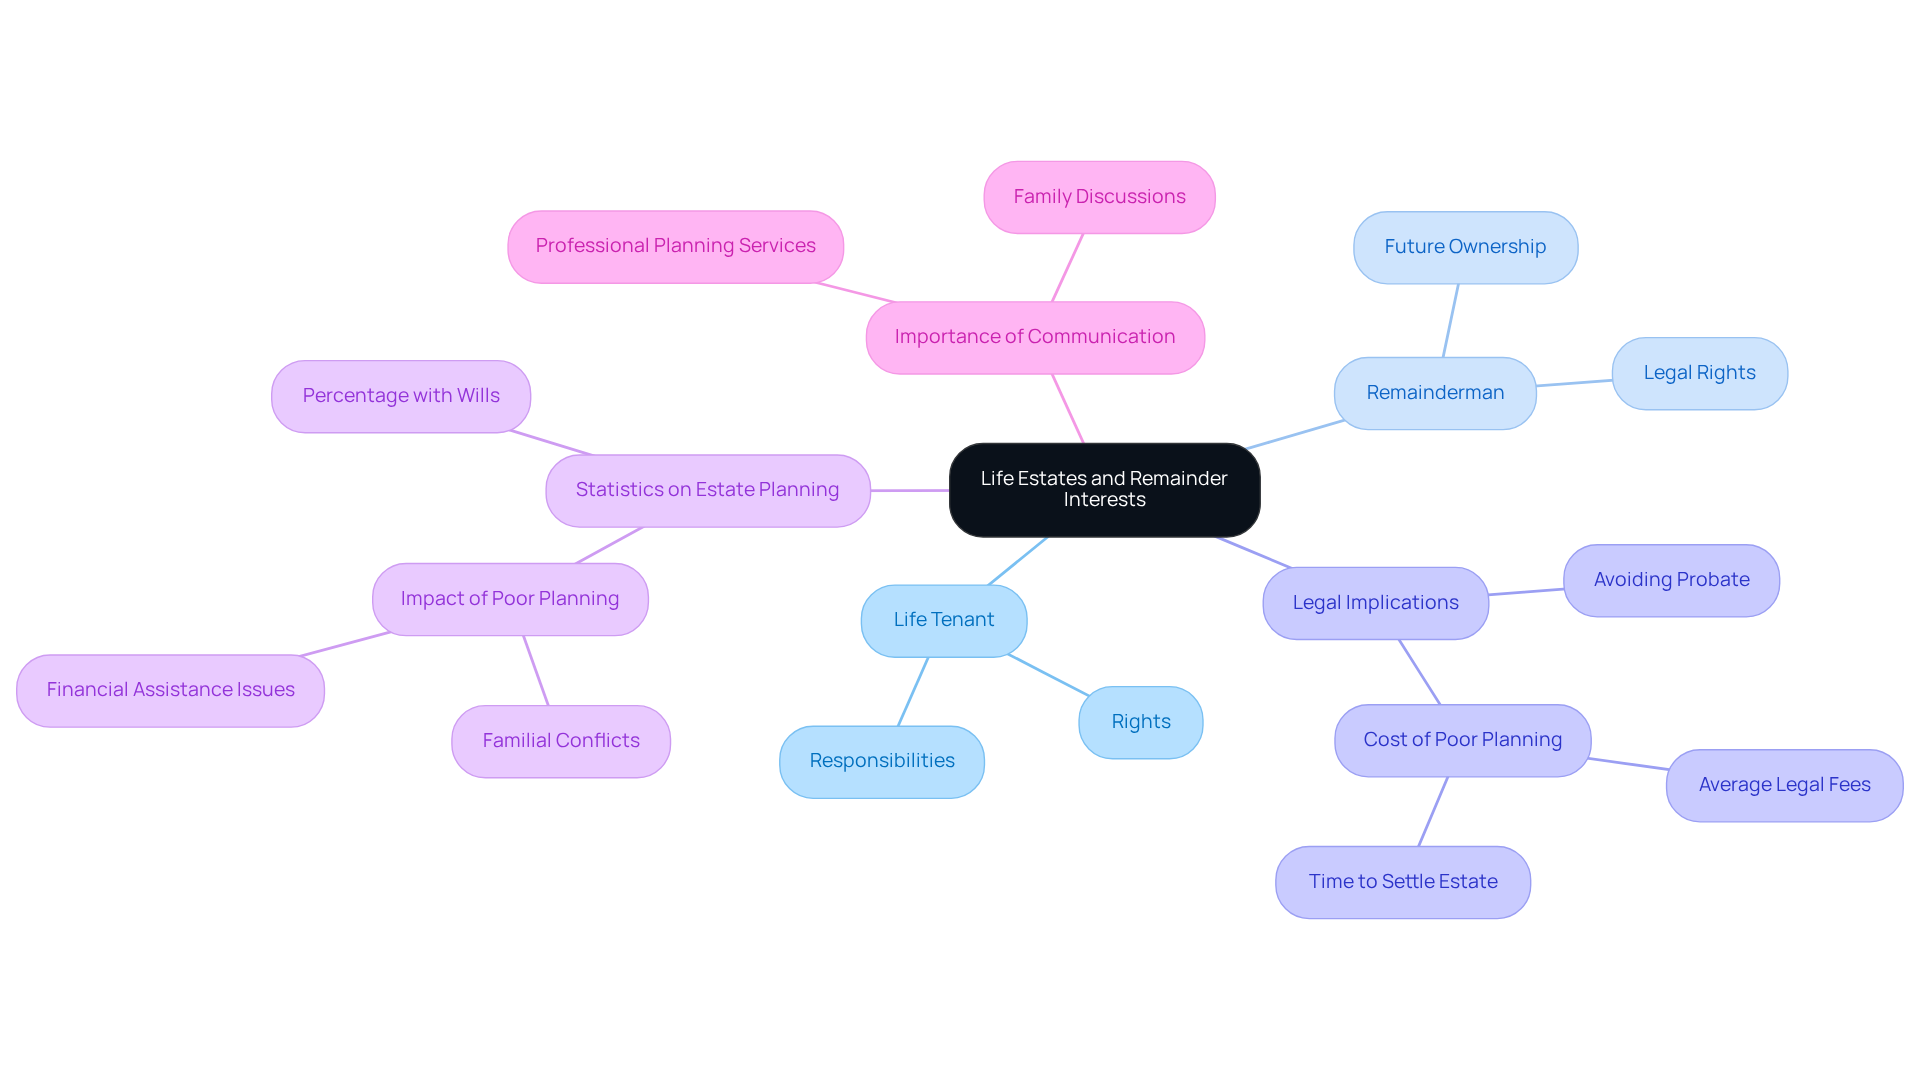
- Key terms include ‘Life Tenant’ (the person using the property) and ‘Remainderman’ (the future owner after the life tenant’s death).
- Life estates can help avoid probate, facilitating smoother property transitions.
- Only 32% of Americans have a will or living trust, indicating a gap in asset planning.
- Effective communication about asset planning can prevent disputes among heirs.
- IRS life estates have specific rules regarding gift tax implications and require accurate valuation using actuarial tables.
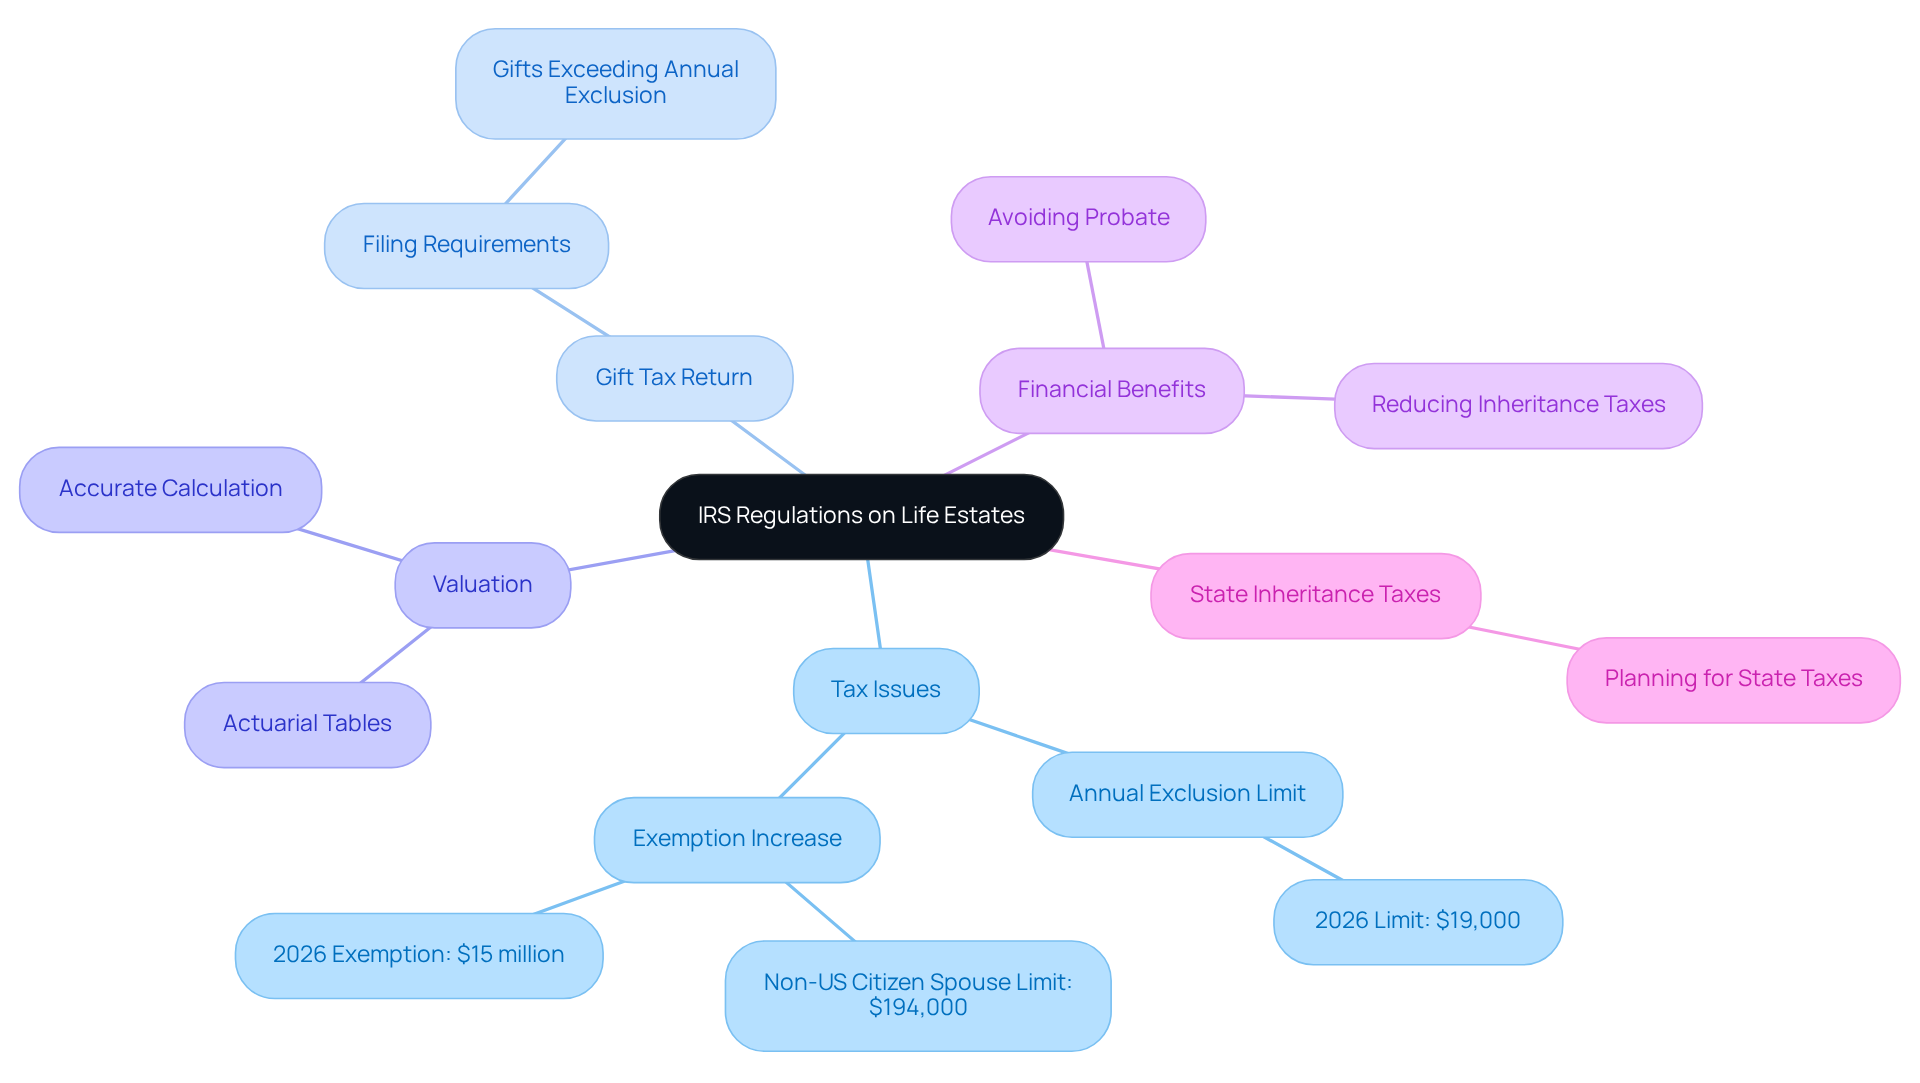
- In 2026, the gift tax exclusion will be $19,000 per recipient, with an inheritance exemption of $15 million per person.
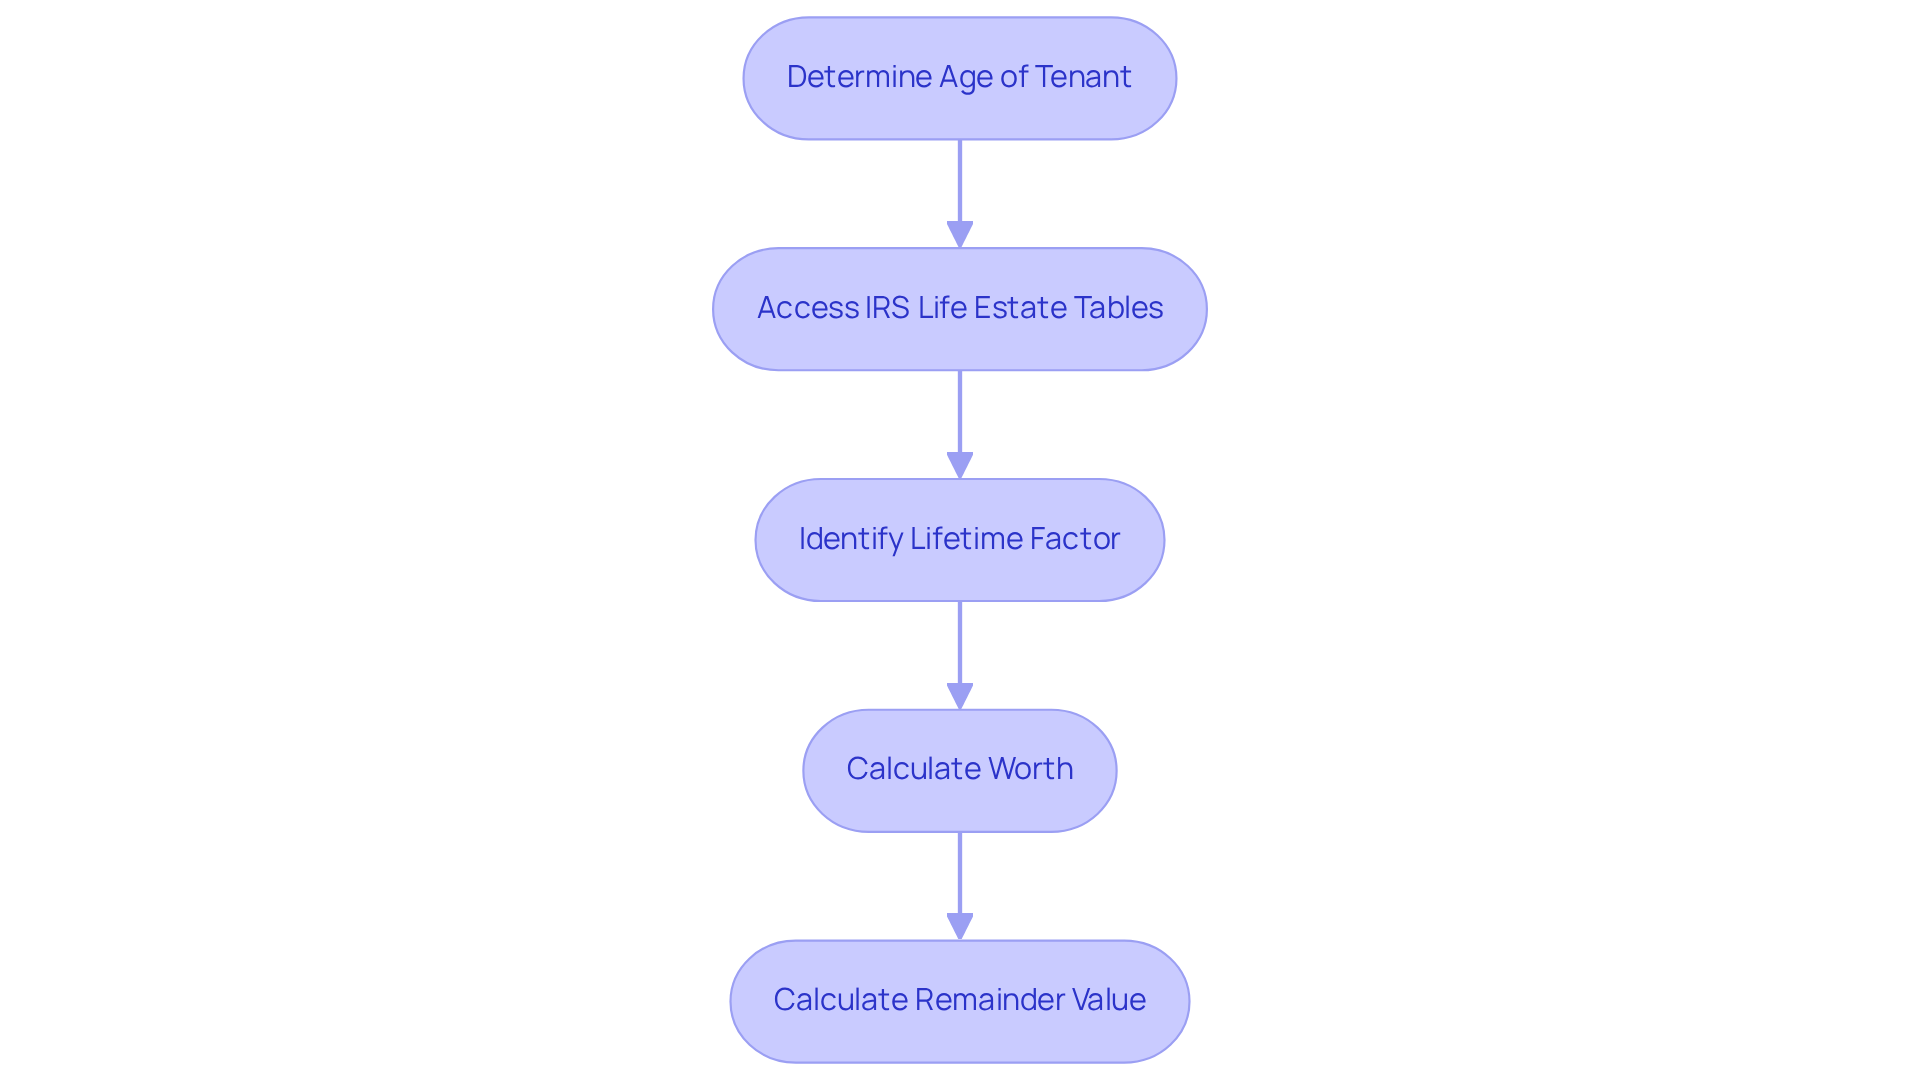
- Calculating values involves determining the tenant’s age, using IRS tables, and understanding the lifetime factor for accurate property valuation.
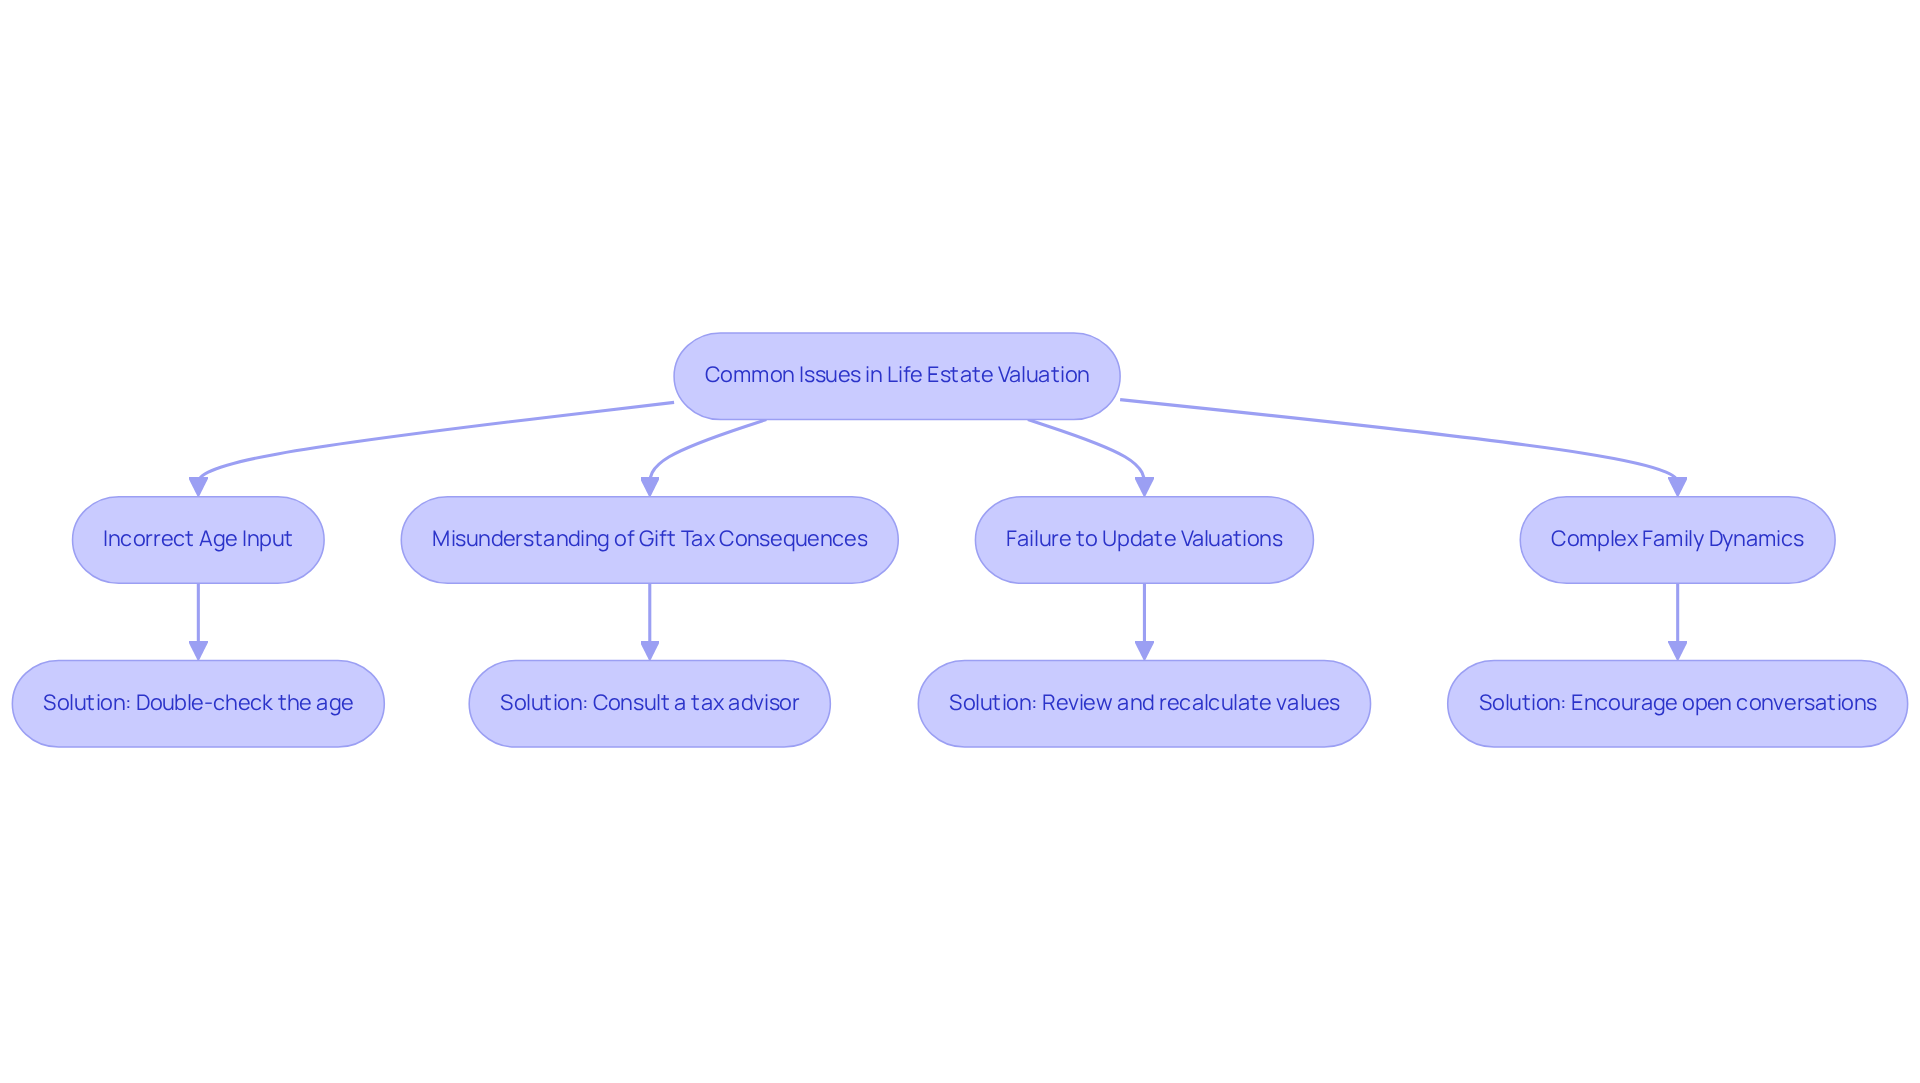
- Common issues in life estate valuation include incorrect age input, misunderstanding gift tax consequences, and failure to update valuations.
- Proactive management of life estates can safeguard family legacies and ensure financial security.
Introduction
Imagine securing your family’s future with confidence, even amidst the complexities of IRS life estate regulations. This guide gently walks you through the steps of navigating life estates, showing how they can bring peace of mind while ensuring a smooth transition of property to your heirs.
Navigating these complexities can feel overwhelming for many families. But with the right knowledge and support, families can confidently navigate these challenges. Together, we can safeguard your legacy.
Understand Life Estates and Remainder Interests
Imagine the peace of mind that comes from knowing your home is secure for your family, even after you’re gone. An irs life estate allows you to stay in your home for life while ensuring that your children inherit it when you’re no longer there. This setup can be a wonderful way for parents to pass on their home to their kids, all while enjoying the comfort of living there themselves.
Here are some key concepts to understand:
- Life Tenant: The individual who has the right to use the property for their lifetime.
- Remainderman: The person or organization that will take full ownership of the property after the life tenant passes away.
- Legal Implications: Life estates can help avoid probate, making the transition of property ownership smoother.
Understanding these concepts can help you create a solid plan that supports your family and preserves your irs life estate, ensuring your home remains safe for years to come. Recent statistics show that only 32% of Americans have established a will or living trust, highlighting a significant gap in planning for assets. Moreover, 31% of individuals indicate that leaving loved ones without adequate financial assistance is the most harmful result of insufficient inheritance planning.
Many families face challenges due to a lack of communication about asset planning, leading to confusion and disputes among heirs. For instance, individuals whose parents had a financial plan are 2.5 times more likely to seek professional planning services themselves, underscoring the importance of proactive preparation.
As we live longer, with the chance of surviving from age 60 to 90 increasing significantly, the importance of property interests and remainder claims in succession planning becomes even clearer. By understanding the irs life estate, you can take a significant step toward safeguarding your family’s future and ensuring your wishes are honored. Together, we can navigate this journey.
Review IRS Regulations on Life Estates
Imagine facing unexpected tax issues while trying to secure your family’s future – it’s a worry no parent should have to bear. The IRS life estate has specific rules regarding property interests that you need to understand to avoid potential tax pitfalls.
When you transfer a life estate, it’s considered a gift. If its value exceeds the annual exclusion limit, you’ll need to file a gift tax return. In 2026, this limit will remain at $19,000 per recipient. Plus, the inheritance and gift exemption will increase to $15 million per person, allowing for significant wealth transfer without federal charges.
It’s important to know that the IRS life estate requires the use of actuarial tables to determine the value of life interests and remainder interests. Accurate valuation is crucial for tax purposes, so take the time to calculate it carefully.
An IRS life estate can offer considerable financial benefits, such as avoiding probate and potentially reducing inheritance taxes. And if you have a non-US citizen spouse, you’ll be glad to know that the annual gift amount will rise to $194,000 in 2026.
If you live in a state with inheritance taxes, it’s essential to factor these into your death planning. For more guidance, refer to IRS Publication 1457, which outlines the actuarial tables and provides advice on assessing property interests. Understanding these regulations empowers you to make informed choices for your family’s financial future. Together, we can navigate this journey with confidence.
Calculate Values Using IRS Actuarial Tables
Imagine feeling confident about your family’s financial future, even amidst the complexities of property valuations. Understanding the worth of a personal interest or remainder share can feel daunting, but using the IRS life estate tables can help guide you through it.
- Determine the Age of the Tenant: Start by identifying the tenant’s age when the tenancy is established.
- Access the IRS life estate by visiting the IRS website to find the appropriate actuarial tables, such as IRS Publication 1457.
- Identify the Lifetime Factor: Discover the lifetime factor that corresponds to the tenant’s age in the tables. For instance, if the tenant is 70 years old, the factor might be around 0.5.
- Calculate the Worth: Multiply the total asset value by the duration factor to find the current value of the duration. For example, with a real asset valued at $300,000 and a life interest factor of 0.5, the value of the interest would be $150,000.
- Calculate the Remainder Value: Subtract the value of the duration interest from the total property value to find the remainder interest value. In this case, the remainder interest would be $300,000 – $150,000 = $150,000.
Getting these calculations right is important for your peace of mind and can help you navigate tax reporting with confidence, especially when it comes to your IRS life estate. Remember, reaching out to a financial planner or tax consultant can provide you with the support you need to navigate these complexities with ease.
Troubleshoot Common Issues in Life Estate Valuation
Navigating property interests can feel overwhelming for parents, especially when every detail matters for your family’s future. Here’s how to troubleshoot some common challenges you might face:
Common Issues and Solutions:
-
Incorrect Age Input: Imagine how crucial it is to get the tenant’s age right when it comes to those important actuarial tables. Even a small mistake can lead to significant valuation discrepancies.
- Solution: Take a moment to double-check the age; it can make a world of difference in ensuring accuracy.
-
Misunderstanding of Gift Tax Consequences: Many parents may not realize that transferring a property interest can trigger gift tax responsibilities, complicating your financial planning.
- Solution: It’s a good idea to chat with a tax advisor who can help you navigate these implications and keep everything in line with IRS regulations, especially regarding the §7520 rate used for valuations.
-
Failure to Update Valuations: As real estate values change, it’s easy to overlook updating your estate valuations. This oversight could mean missing out on opportunities to secure your family’s future.
- Solution: Make it a habit to review and recalculate values, especially after big changes in your life or asset values; it’s a simple way to stay on top of things for your family.
-
Complex Family Dynamics: Disagreements among family members about property valuation or distribution can complicate matters.
- Solution: Encourage open conversations and think about mediation to help everyone feel heard and understood during conflicts, ensuring that all parties grasp the valuation process and its implications.
By proactively addressing these issues, you’re not just managing property; you’re safeguarding your family’s legacy and peace of mind.
Conclusion
Imagine the worry of leaving your family with complicated legal matters after you’re gone; understanding IRS life estate regulations can help ease that burden. With a life estate, you can pass your home to your children without the hassle of probate, all while still enjoying your home for the rest of your life. This arrangement brings peace of mind and helps your family transition smoothly, showing how important it is to plan ahead.
Throughout this guide, we’ve explored key concepts like life tenants, remaindermen, and the legal implications of life estates. We also delved into the IRS regulations surrounding life estates, emphasizing the need for accurate valuations using IRS actuarial tables to avoid potential tax pitfalls. Common challenges in life estate valuation were addressed, providing practical solutions to ensure families can navigate these complexities with confidence.
Ultimately, the significance of understanding life estates cannot be overstated. By taking the time to educate yourself on these regulations and planning accordingly, you can preserve your family’s wealth across generations. Engaging with a fiduciary advisor, like Bright Advisers, can further enhance this process, ensuring transparency and personalized guidance tailored to your family’s unique needs. Now is the time to take action and explore how life estates can bring peace of mind to your family’s future.
Frequently Asked Questions
What is a life estate?
A life estate is a legal arrangement that allows an individual (the life tenant) to live in and use a property for their lifetime, while ensuring that the property will pass to another person (the remainderman) after the life tenant’s death.
Who is a life tenant?
A life tenant is the individual who has the right to use and occupy the property for their lifetime under a life estate arrangement.
Who is a remainderman?
A remainderman is the person or organization that will gain full ownership of the property once the life tenant passes away.
What are the legal implications of a life estate?
Life estates can help avoid probate, which simplifies the transition of property ownership after the life tenant’s death.
Why is it important to understand life estates and remainder interests?
Understanding these concepts is crucial for creating a solid estate plan that supports family members and preserves the life estate, ensuring the home remains secure for future generations.
What statistics highlight the importance of estate planning?
Recent statistics show that only 32% of Americans have established a will or living trust, and 31% believe that leaving loved ones without adequate financial assistance is the most harmful result of insufficient inheritance planning.
How does communication about asset planning affect families?
A lack of communication about asset planning can lead to confusion and disputes among heirs, emphasizing the need for proactive preparation.
What is the significance of planning for property interests as we age?
As life expectancy increases, understanding property interests and remainder claims becomes increasingly important in succession planning to safeguard family assets and ensure wishes are honored.
List of Sources
- Understand Life Estates and Remainder Interests
- Actuarial Tables – Greenleaf Trust (https://greenleaftrust.com/missives/actuarial-tables)
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- 5 Eye-Opening Statistics About Estate Planning – Nickerson Law: A Professional Corporation (https://jeffreycnickersonlaw.com/blog/5-eye-opening-statistics-about-estate-planning)
- Life Estate and Remainder Interest Table (https://public-dhhs.ne.gov/nfocus/Manuals/APX469/apx469/life_estate_and_remainder_interest_table.htm)
- Review IRS Regulations on Life Estates
- IRS Announces Increased Gift and Estate Tax Exemption Amounts for 2026 (https://morganlewis.com/pubs/2025/10/irs-announces-increased-gift-and-estate-tax-exemption-amounts-for-2026)
- Estate and Gift Tax FAQs | Internal Revenue Service (https://irs.gov/newsroom/estate-and-gift-tax-faqs)
- Estate Tax Exemption Sunsets in 2026 (https://citizensbank.com/private-banking/insights/estate-tax-exemption.aspx)
- Unintended Consequences: How Using a Life Estate Results in Gift Tax Liability – AlerStallings (https://alerstallings.com/blog/estate-planning/unintended-consequences-how-using-a-life-estate-results-in-gift-tax-liability)
- Calculate Values Using IRS Actuarial Tables
- IRS Life Estate and Remainder Interest Calculator – Scheuerman Law LLC (https://scheuermanlaw.com/irs-life-estate-and-remainder-interest-calculator)
- What process is used to calculate life estate and remainder values using IRS tables and age factors? NC (https://piercelaw.com/news/real-estate-qa-series/what-process-is-used-to-calculate-life-estate-and-remainder-values-using-irs-tables-and-age-factors-nc)
- Actuarial tables | Internal Revenue Service (https://irs.gov/retirement-plans/actuarial-tables)
- Troubleshoot Common Issues in Life Estate Valuation
- SSA – POMS: SI 01140.120 – Life Estate and Remainder Interest Tables (https://secure.ssa.gov/poms.nsf/lnx/0501140120)
- Actuarial tables | Internal Revenue Service (https://irs.gov/retirement-plans/actuarial-tables)
- Life Estate – 5 Problems to Know About – Elville and Associates (https://elvilleassociates.com/blogs/6168/life-estates)
- IRS Life Estate and Remainder Interest Calculator – Scheuerman Law LLC (https://scheuermanlaw.com/irs-life-estate-and-remainder-interest-calculator)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading