

Key Highlights
- Incentive Stock Options (ISOs) can create tax implications when exercised, as the difference between purchase price and market value counts as income for tax purposes.
- The Alternative Minimum Tax (AMT) ensures high-income earners pay a minimum tax, with exemption amounts set at $90,100 for single filers and $140,200 for married couples in 2026.
- Families can use the ISO exercise AMT calculator strategy to time ISO exercises and manage tax liabilities effectively.
- Strategies to minimise AMT exposure include exercising ISOs early in the year, spreading exercises over multiple years, monitoring stock prices, and consulting with a tax advisor.
- Utilising unused AMT credits from previous years can help offset future tax liabilities.
- Regularly reviewing and adjusting financial strategies is crucial for long-term success and adapting to changes in income or personal circumstances.
- Bright Advisers assists families in making informed wealth decisions and preserving assets across generations.
Introduction
Imagine feeling overwhelmed by the complexities of Incentive Stock Options and the Alternative Minimum Tax while trying to secure your family’s financial future. It’s important to understand how these elements interact, as the choices you make today can shape your family’s financial future in profound ways.
In this article, we’ll explore how families can use the ISO exercise AMT calculator to make informed choices, helping to reduce tax liabilities and support long-term financial success. Together, let’s discover how families can leverage these tools to avoid being caught off guard by unexpected tax bills.
Understand ISOs and AMT Basics for Family Financial Planning
Have you ever felt overwhelmed by the complexities of stock options and their tax implications? Incentive Stock Options (ISOs) can be a great opportunity, but they come with some important considerations, especially when it comes to taxes. When you exercise ISOs, the difference between what you pay for the stock and its current market value counts as income for tax purposes, even if you haven’t sold the stock yet. This distinction is crucial for families, particularly those with higher incomes, as it can significantly impact your tax obligations.
It’s important to understand that the Alternative Minimum Tax (AMT) is a parallel tax system designed to ensure that high-income earners pay a minimum amount of tax. Imagine the surprise of receiving a tax bill that you weren’t prepared for, just when you thought you were managing your finances well. For instance, in 2026, the AMT exemption amount for single filers is set at $90,100, while for married couples filing jointly, it is $140,200. However, these exemptions begin to phase out once your income exceeds certain thresholds, which can lead to unexpected financial stress.
Understanding the connection between ISOs and AMT is essential for an effective household budgeting strategy that incorporates the ISO exercise AMT calculator strategy. Families can benefit from the ISO exercise AMT calculator strategy by strategically timing ISO exercises, potentially spreading them across multiple years to stay below AMT thresholds. Talking to a tax advisor can really help you navigate these tricky waters and find the best strategies for your family’s needs. By understanding these concepts, you can take control of your financial future and ensure your family’s stability.
Utilize the AMT Calculator for Accurate Tax Planning
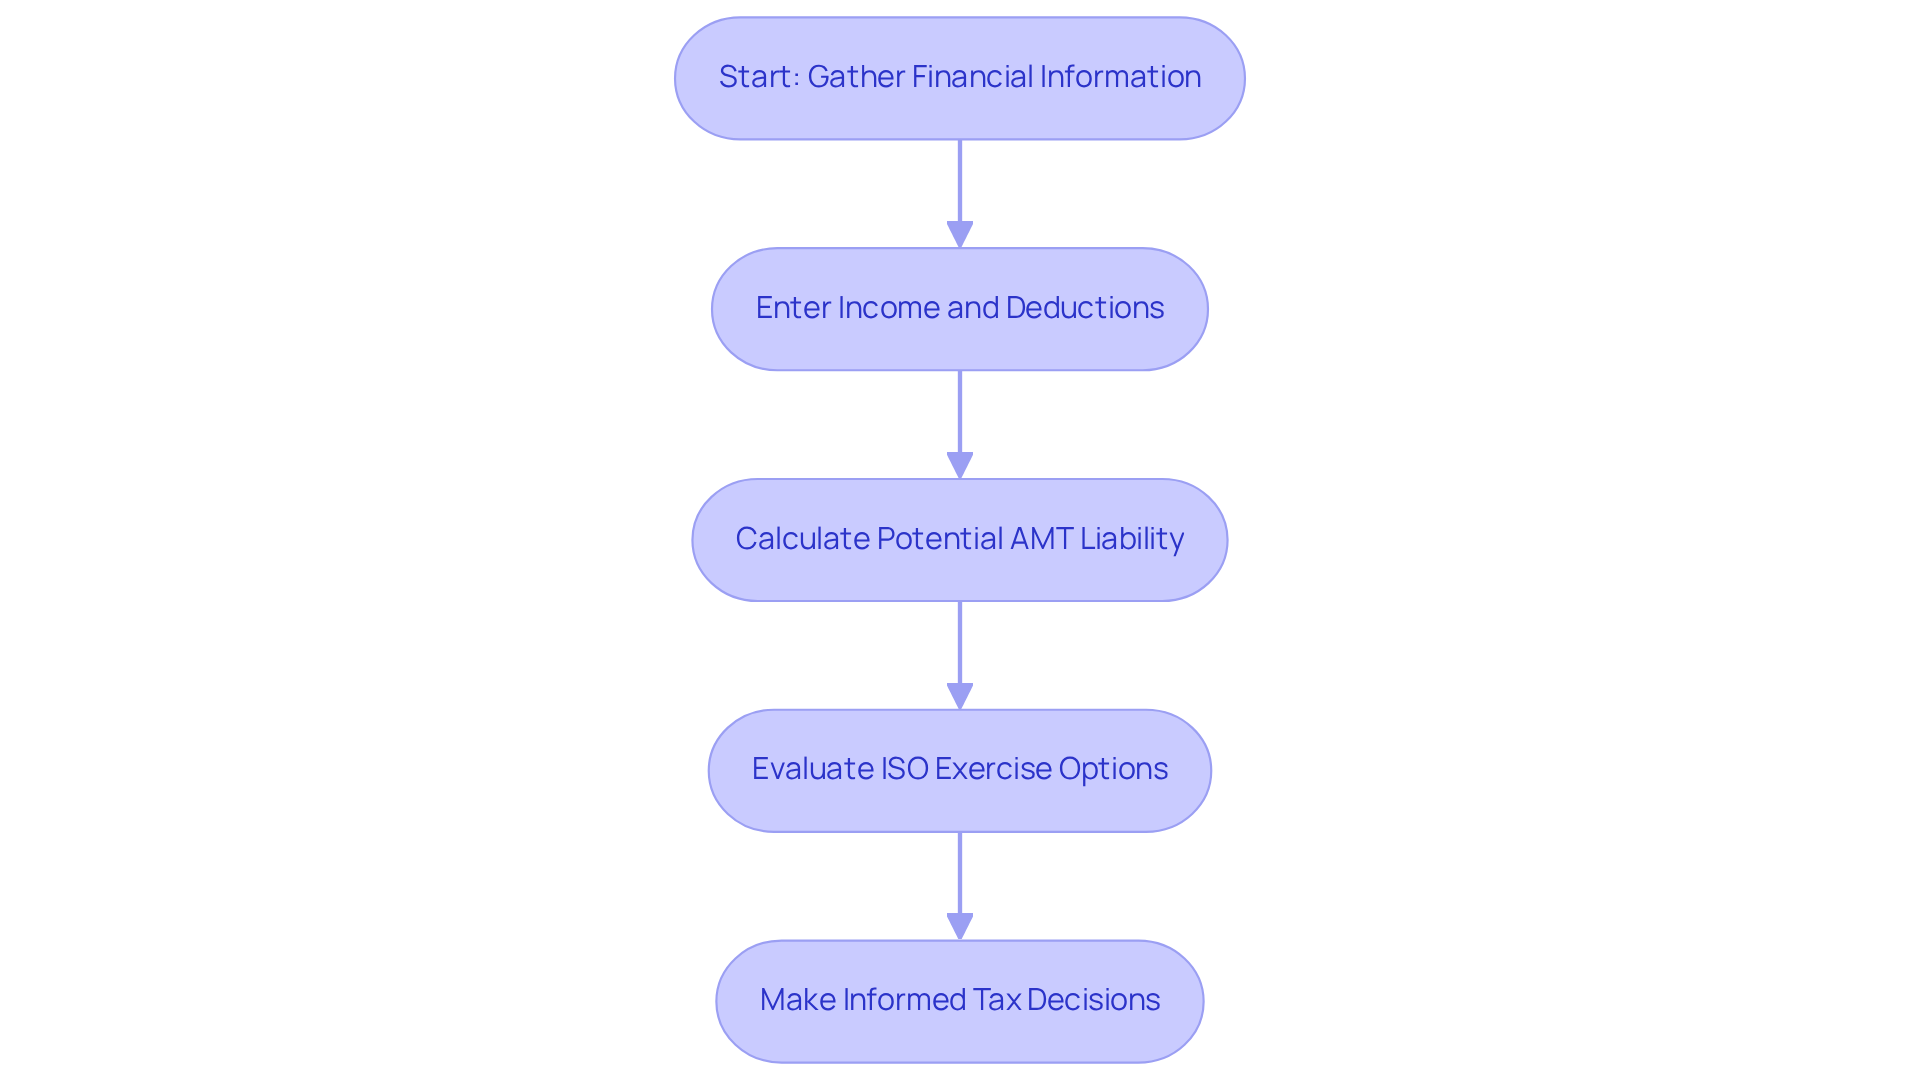
Imagine feeling confident about your family’s financial future, even when faced with the complexities of tax planning for incentive stock options. An ISO exercise AMT calculator strategy is an invaluable tool for households navigating these challenges. By simply entering details like income and deductions, families can get a clearer picture of their potential AMT liability. This proactive step helps families see how exercising their options can impact their taxes, making it easier to make informed choices that benefit their future.
For instance, if a household expects a substantial income rise in a particular year, they can apply the ISO exercise AMT calculator strategy to evaluate how many ISOs they can exercise without activating AMT. Many families feel overwhelmed by the complexities of tax planning, especially when it comes to incentive stock options. This foresight assists them in evading unforeseen tax liabilities and facilitates more efficient budget planning. It’s important to check these calculations regularly, especially as your family’s financial situation evolves, so you can stay on track with your tax strategies.
More and more families are turning to the ISO exercise AMT calculator strategy to help them navigate the ever-changing tax landscape, finding peace of mind in their planning. Case studies show that households who strategically utilize the ISO exercise AMT calculator strategy can better manage their tax obligations, particularly when exercising ISOs, which can lead to significant tax consequences even without immediate cash income. By understanding the nuances of AMT calculations, households can navigate their financial futures with greater confidence. With the right tools and support, you can navigate these challenges and secure a brighter financial future for your family.
Implement Strategies to Minimize AMT Exposure from ISO Exercises
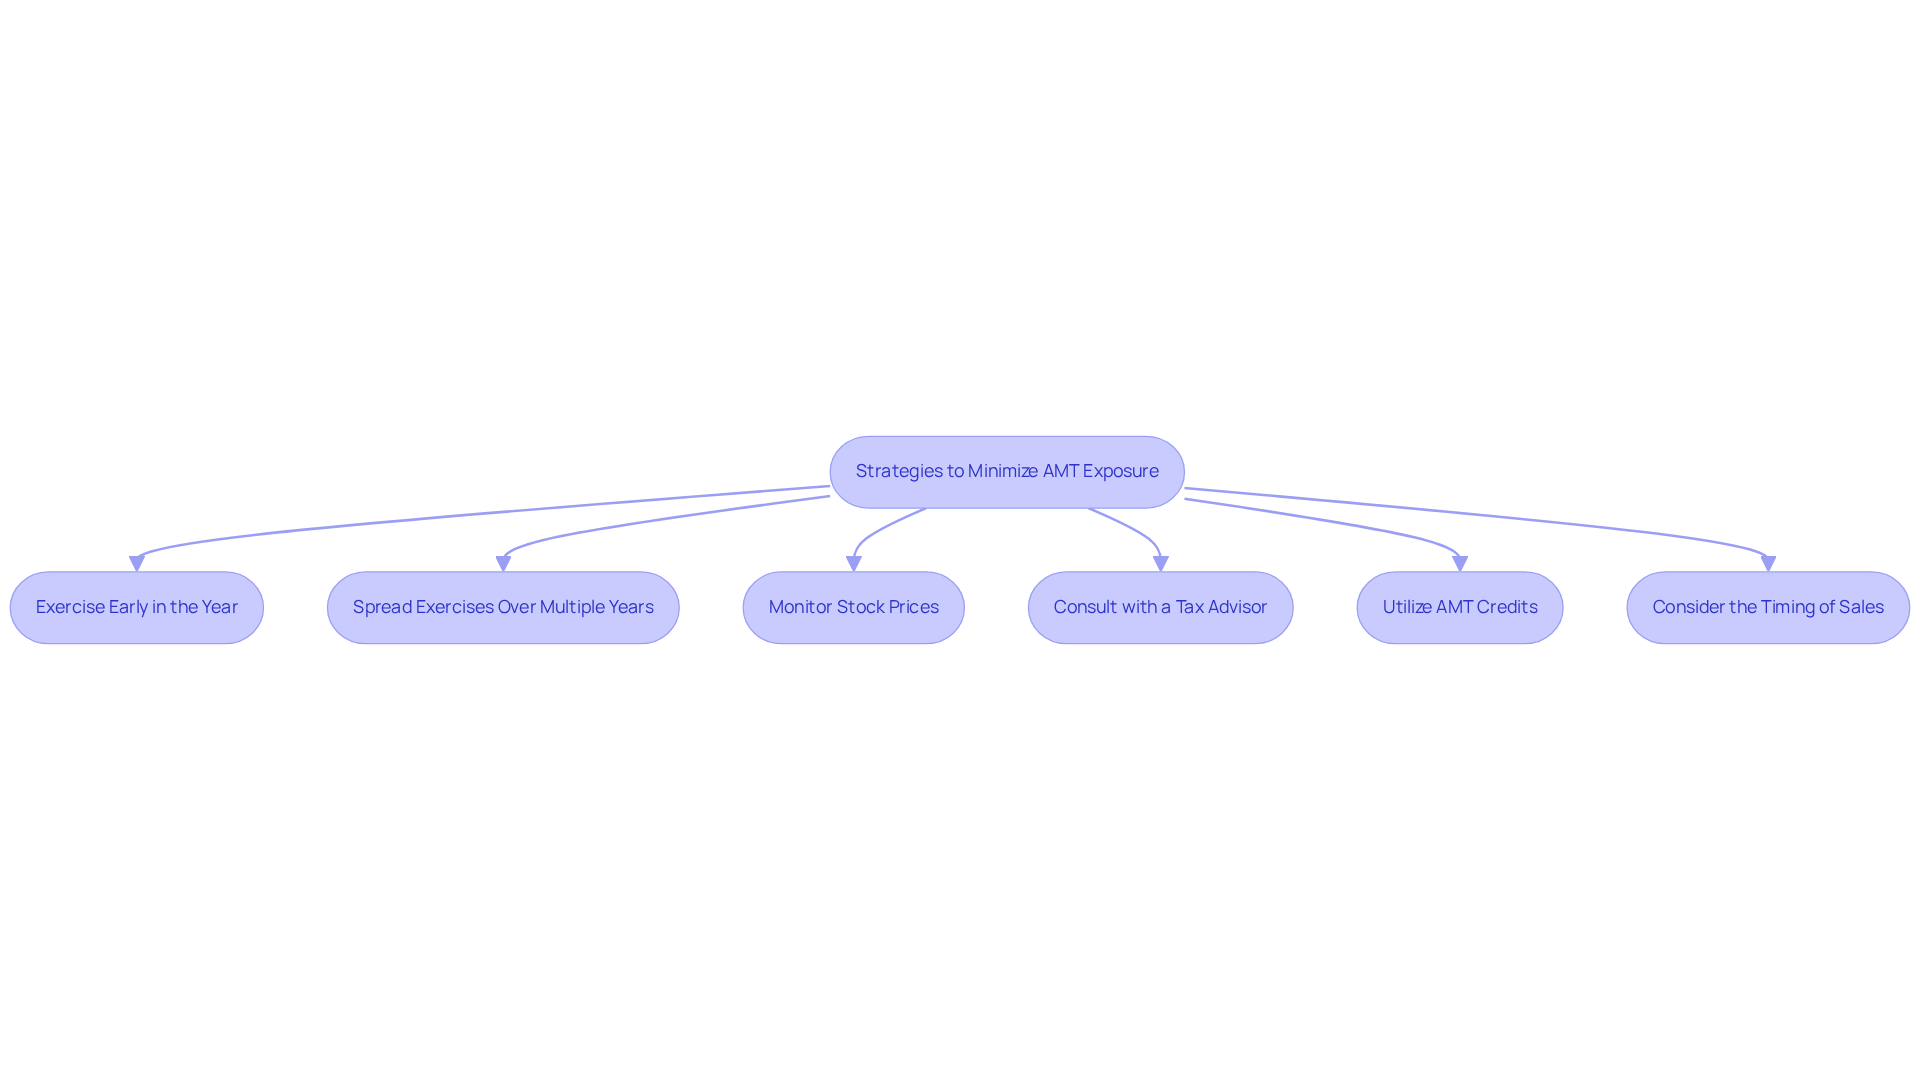
Imagine the stress of navigating tax liabilities while trying to secure your family’s financial future. To minimize AMT exposure from ISO exercises, families can adopt several effective strategies:
- Exercise Early in the Year: Exercising ISOs early in the calendar year can help you manage your tax liabilities more effectively. This timing might allow for potential stock price appreciation without immediately triggering AMT, as your income may fall into a lower tax bracket. Families like Allison and Brian could miss out on significant financial opportunities if they delay exercising their options.
- Spread Exercises Over Multiple Years: You might consider spreading out your ISO exercises over several years. This approach is part of the iso exercise amt calculator strategy, helping to keep your income levels below the AMT threshold and reducing the likelihood of triggering AMT. For instance, the AMT exemption for single filers is $90,100, and for joint filers, it is $140,200, which can assist you in planning your activities.
- Monitor Stock Prices: Keep an eye on stock market trends and think about exercising ISOs when stock prices are lower. This strategy can reduce the income recognized for AMT purposes, allowing you to exercise your options without incurring significant tax liabilities. As highlighted in various case studies, utilizing the iso exercise amt calculator strategy based on market conditions can lead to improved economic outcomes.
- Consult with a Tax Advisor: Talking to a tax consultant who knows ISOs and AMT can really help your family find the best strategies that align with your unique monetary situation. As seen with families like Allison and Brian, who are worried about their economic well-being, seeking guidance from a qualified tax advisor is highly advisable. Expert advice is crucial in navigating AMT complexities and applying the iso exercise amt calculator strategy to ensure you make the most of your resources.
- Utilize AMT Credits: You can leverage unused AMT credits from previous years to offset future tax bills. Understanding how to carry forward these credits can significantly reduce your tax liabilities in subsequent years. The IRS allows taxpayers to carry forward excess or unused AMT credits indefinitely, which can be advantageous for families managing their finances over time.
- Consider the Timing of Sales: Selling shares from exercised ISOs strategically can help cover AMT liabilities. Assess the timing of these sales to ensure they align with your overall monetary strategy and cash flow requirements. For example, selling shares in a year when your income is lower can help mitigate the impact of AMT.
By taking these steps, you can feel more in control of your AMT exposure and create a brighter financial future for your family, allowing you to focus on what truly matters. Remember, past performance does not guarantee future results, and all investments carry risks. For personalized guidance, consider reaching out to Bright Advisers, where we assist families in making wise wealth decisions and preserving assets across generations.
Monitor and Adjust Financial Strategies for Long-Term Success
Imagine feeling secure in your family’s financial future, even when life throws unexpected challenges your way. For households to attain long-term economic success, it’s essential to regularly review and adjust your financial strategies. But with so many financial responsibilities, it can feel overwhelming to keep track of everything. That’s why it’s important to regularly review your financial strategies, including investment performance and tax situations, making necessary adjustments based on changes in income or personal circumstances.
At Bright Advisers, we understand that every family is unique. That’s why we focus on creating a personalized financial strategy that reflects your values and goals, making budgeting and planning feel more manageable. We recommend setting aside time for regular budget check-ins-maybe every few months-to see how you’re doing and adjust as needed. These check-ins are a great opportunity to look at your financial situation and make sure everything is still on track for your family’s needs.
Keeping up with tax changes can feel daunting, but it’s essential for making sure your family’s financial plan stays relevant and effective. Did you know that many families struggle to save enough for emergencies? It’s a common challenge, but taking proactive steps can make a big difference in your peace of mind. Families who regularly review their budgets often feel more confident about their financial futures. Imagine how reassuring it would be to know you’re prepared for unexpected expenses!
When families take an active role in their finances, they often find they understand their money better and can make smarter decisions. Take Emily and Mark, for instance. By working with us, they discovered a clearer picture of their finances and created a plan that truly reflected their family’s dreams. With our help, they learned how to manage their debt and cash flow, allowing them to make career choices that fit their family’s lifestyle.
When families stay engaged in their financial planning, they can tackle challenges together, ensuring a secure future for their loved ones. Taking charge of your financial journey today can pave the way for a brighter tomorrow for your family.
Conclusion
Imagine feeling confident about your family’s financial future, even amidst the complexities of taxes and investments. Understanding the intricacies of Incentive Stock Options (ISOs) and the Alternative Minimum Tax (AMT) can be tough, but it’s essential for families like yours who want to secure a brighter tomorrow. When you understand how to use the ISO exercise AMT calculator, you can simplify tax implications and make choices that support your family’s financial goals.
Throughout this journey, we’ve explored key strategies that can make a difference. Think about the importance of:
- Timing your ISO exercises
- Spreading them over multiple years
- Consulting with tax advisors for invaluable insights
Utilizing the AMT calculator gives you a clearer picture of potential tax liabilities, allowing for better planning and budgeting. Regularly checking in on your financial strategies ensures you stay on track, adapting to changes in income and personal circumstances.
Taking charge of your financial planning means you can build a secure future for your loved ones. By implementing these strategies and leveraging tools like the ISO exercise AMT calculator, you can minimize your AMT exposure and pave the way for long-term financial success. Engaging with a fiduciary advisor like Bright Advisers can further enhance this journey, ensuring that you make wise wealth decisions and preserve your assets across generations. With the right strategies and support, you can transform financial uncertainty into lasting security for your family.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are a type of stock option that can provide tax benefits to employees. When exercised, the difference between the purchase price and the current market value is considered income for tax purposes, even if the stock has not been sold.
How do ISOs affect tax obligations?
When you exercise ISOs, the income generated from the difference between the purchase price and the market value is subject to tax. This can significantly impact tax obligations, especially for families with higher incomes.
What is the Alternative Minimum Tax (AMT)?
The Alternative Minimum Tax (AMT) is a parallel tax system designed to ensure that high-income earners pay a minimum amount of tax. It can lead to unexpected tax bills if not properly planned for.
What are the AMT exemption amounts for 2026?
In 2026, the AMT exemption amount is set at $90,100 for single filers and $140,200 for married couples filing jointly. However, these exemptions begin to phase out at certain income thresholds.
How can families manage the impact of ISOs and AMT on their finances?
Families can manage the impact by using the ISO exercise AMT calculator strategy, which involves strategically timing ISO exercises and potentially spreading them across multiple years to stay below AMT thresholds.
Why is it important to consult a tax advisor regarding ISOs and AMT?
Consulting a tax advisor can help families navigate the complexities of ISOs and AMT, allowing them to find the best strategies tailored to their financial needs and avoid unexpected tax liabilities.
List of Sources
- Understand ISOs and AMT Basics for Family Financial Planning
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- What is the Alternative Minimum Tax? How AMT Works & Calculation (https://carta.com/learn/equity/stock-options/taxes/amt)
- Alternative Minimum Tax (AMT): How It Works for Stock Options in 2026 (https://esofund.com/blog/alternative-minimum-tax-amt)
- Summary of the Tax Consequences of Incentive Stock Options (ISOs) (https://heltzelkallozfinancial.com/tax-consequences-of-isos.htm)
- Utilize the AMT Calculator for Accurate Tax Planning
- Understanding the Alternative Minimum Tax | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/alternative-minimum-tax)
- What Is the Alternative Minimum Tax (AMT)? (https://schwab.com/learn/story/beware-these-amt-triggers)
- Alternative Minimum Tax (AMT): Who Pays It and How It Works (https://reedcorp.tax/helpful-guides/alternative-minimum-tax-explained)
- Planning for the AMT (https://thetaxadviser.com/issues/2025/mar/planning-for-the-amt)
- What is the AMT? (https://taxpolicycenter.org/briefing-book/what-amt)
- Implement Strategies to Minimize AMT Exposure from ISO Exercises
- ISO Taxes: How AMT and AMT Credits Work + Avoiding AMT on ISO Exercises | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/tax-isos-amt-credits)
- AMT and ISOs: 6 Steps to Minimize Alternative Minimum Taxes… (https://archerim.com/six-strategies-to-minimize-alternative-minimum-tax-from-incentive-stock-options)
- Strategies to Reduce AMT on Stock Options – Phoenix Strategy Group (https://phoenixstrategy.group/blog/strategies-reduce-amt-stock-options)
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- Monitor and Adjust Financial Strategies for Long-Term Success
- Financial Literacy Statistics (https://financialeducatorscouncil.org/financial-literacy-statistics)
- 40 Financial Literacy Statistics in the United States – Intuit Blog (https://intuit.com/blog/innovative-thinking/financial-tips/financial-literacy-statistics)
- Report on the Economic Well-Being of U.S. Households in 2024 – May 2025 – Savings and Investments (https://federalreserve.gov/publications/2025-economic-well-being-of-us-households-in-2024-savings-and-investments.htm)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Why Financial Literacy is Crucial for Long-Term Success (https://firstcomcu.org/post/why_financial_literacy_is_crucial_for_longterm_success.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading