

Key Highlights
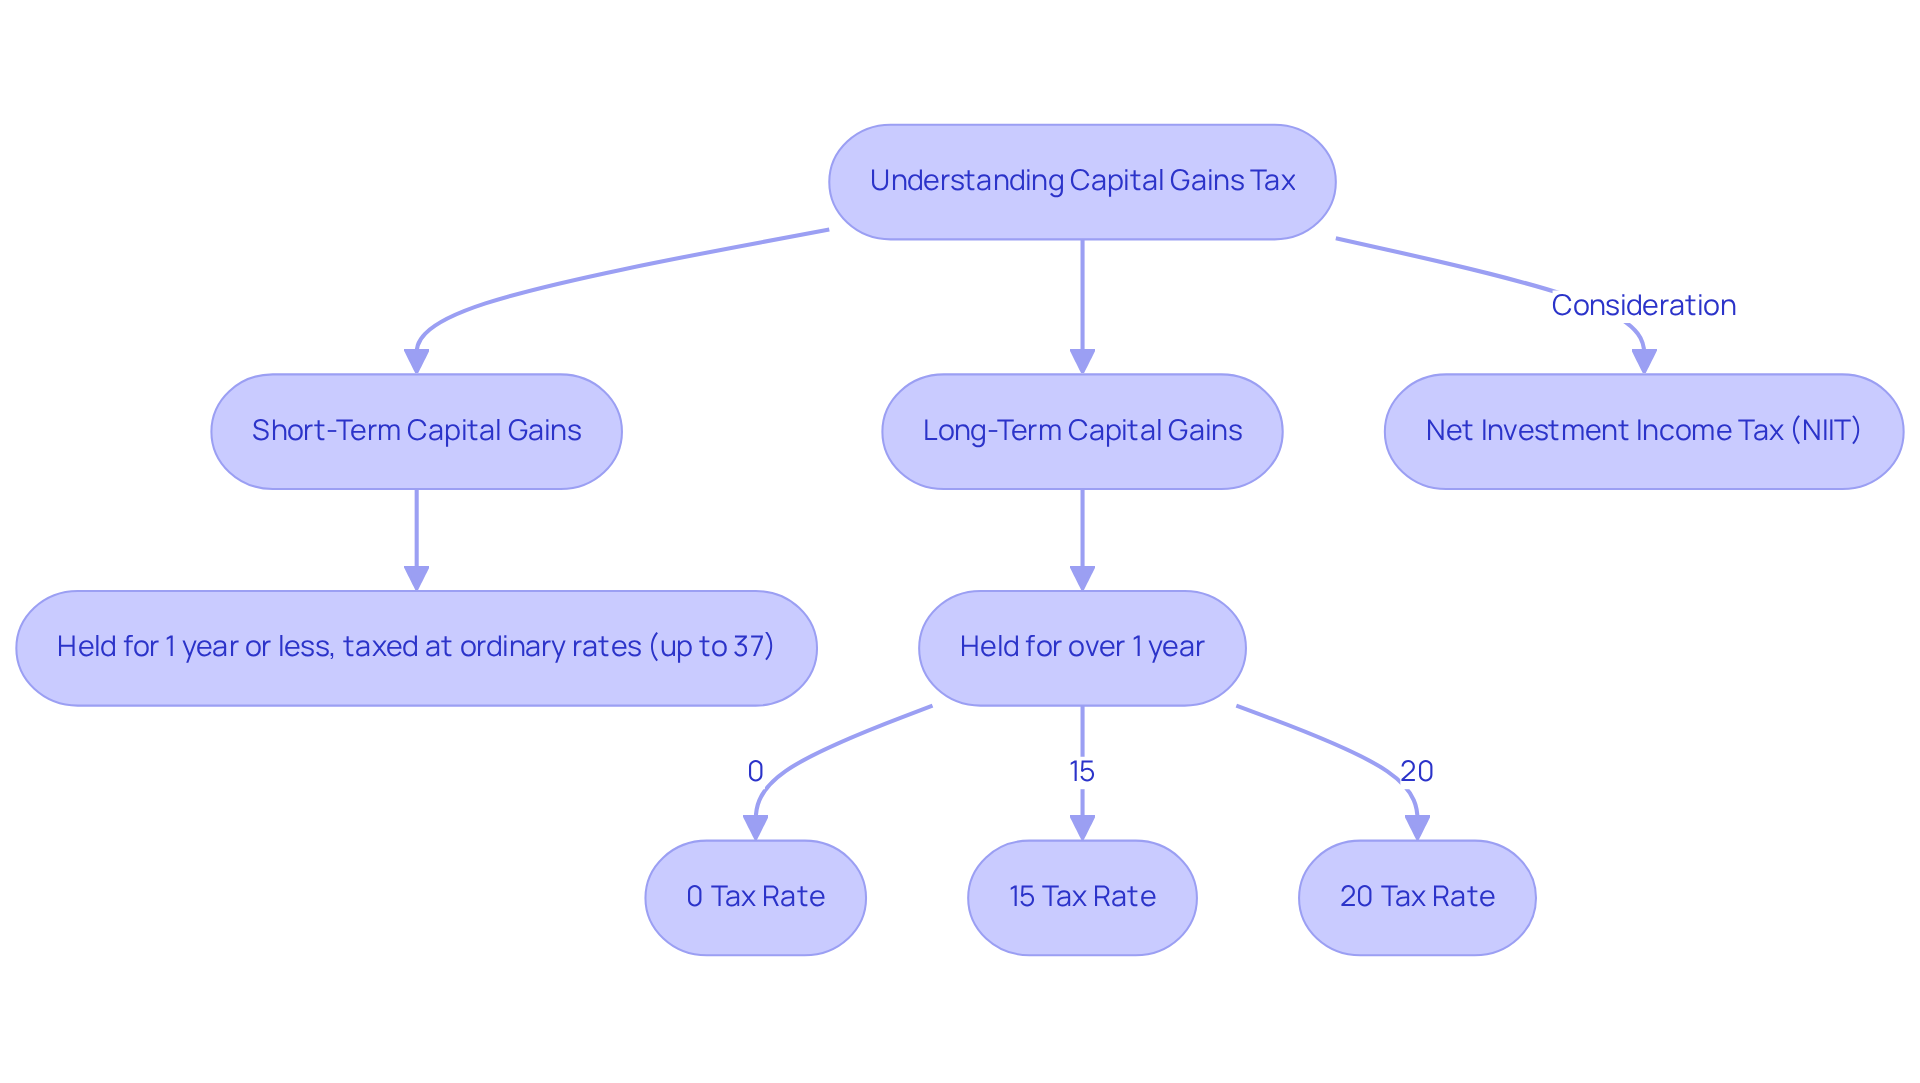
- Capital gains tax is imposed on profits from selling assets, with short-term gains taxed at ordinary income rates (up to 37%) and long-term gains at lower rates (0%, 15%, or 20%).
- By 2026, long-term capital gains tax rates will be 15% for single filers earning up to $49,450 and 20% for those exceeding $545,500.
- High-income earners may incur an additional 3.8% Net Investment Income Tax (NIIT) on certain investment revenues.
- Tax-loss harvesting allows families to offset realised profits by selling underperforming investments, potentially saving on taxes.
- Strategies to minimise capital gains taxes include holding investments long-term, utilising tax-advantaged accounts, and planning sales strategically based on income fluctuations.
- Donating appreciated stocks can provide tax deductions while avoiding capital gains taxes, benefiting both the donor and the charity.
- Consulting with financial advisors can help families develop personalised tax strategies, stay informed on tax law changes, and integrate tax planning with overall financial goals.
Introduction
Imagine facing the complexities of capital gains tax while trying to secure your family’s future – it’s a challenge many high-income families encounter. It’s important to understand the differences between short-term and long-term capital gains, as these nuances can significantly affect your family’s financial future.
In this article, we’ll explore some caring strategies to help families minimize tax liabilities from stock sales, giving you a chance to strengthen your financial security. Together, we can discover how these strategies can lighten your tax burden and create a brighter future for your children.
Understand Capital Gains Tax Basics
Imagine navigating the complexities of capital gains tax while trying to secure your family’s future. Capital gains tax is levied on the profit from selling an asset, such as stocks. For high-income families, grasping the distinctions between short-term and long-term capital gains is crucial:
- Short-term capital gains apply to assets held for one year or less and are taxed at ordinary income tax rates, which can reach up to 37%.
- Long-term profits apply to assets held for over one year and are taxed at lower rates, typically 0%, 15%, or 20%, based on your taxable income.
By 2026, families will find that long-term profit tax rates are set at 15% for single filers earning up to $49,450, and 20% for those exceeding $545,500, making it essential to plan ahead. Furthermore, high-income earners may face the Net Investment Income Tax (NIIT), which imposes an additional 3.8% on certain investment revenue, including profits from asset sales.
Many families feel overwhelmed by the complexities of capital gains tax and how it affects their financial future. Grasping these distinctions enables households to foresee their tax obligations and plan efficiently. For example, tax-loss harvesting can be a strategic method, allowing households to sell underperforming investments to offset realized profits, with any leftover losses applicable against ordinary income up to $3,000. With this understanding, families can confidently navigate their investment choices and tax strategies.
Consider the story of Jay and Emma, a couple seeking to reduce their financial anxiety while planning for their children’s education and their retirement. With Bright Advisers’ guidance, they developed a comprehensive financial strategy that included optimizing their tax situation. Similarly, Emily and Mark, both busy professionals, leveraged Bright Advisers’ expertise to create a financial plan that allowed them the freedom to choose whether to continue working. They recognized the significance of tax planning on profits in reaching their financial objectives.
Allison and Brian, another couple, realized they were missing out on financial opportunities due to inadequate tax planning. By collaborating with Bright Advisers, they utilized large stock sale tax planning for high income earners to optimize their tax situation and secure their children’s future through education funding. These stories show how understanding taxes and using smart strategies can help families find financial peace and independence.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Implement Tax Minimization Strategies
Imagine facing the daunting task of selling stocks while worrying about large stock sale tax planning for high income earners and its implications for your family’s future. To minimize capital gains taxes, there are several effective strategies that can help you navigate this complex landscape.
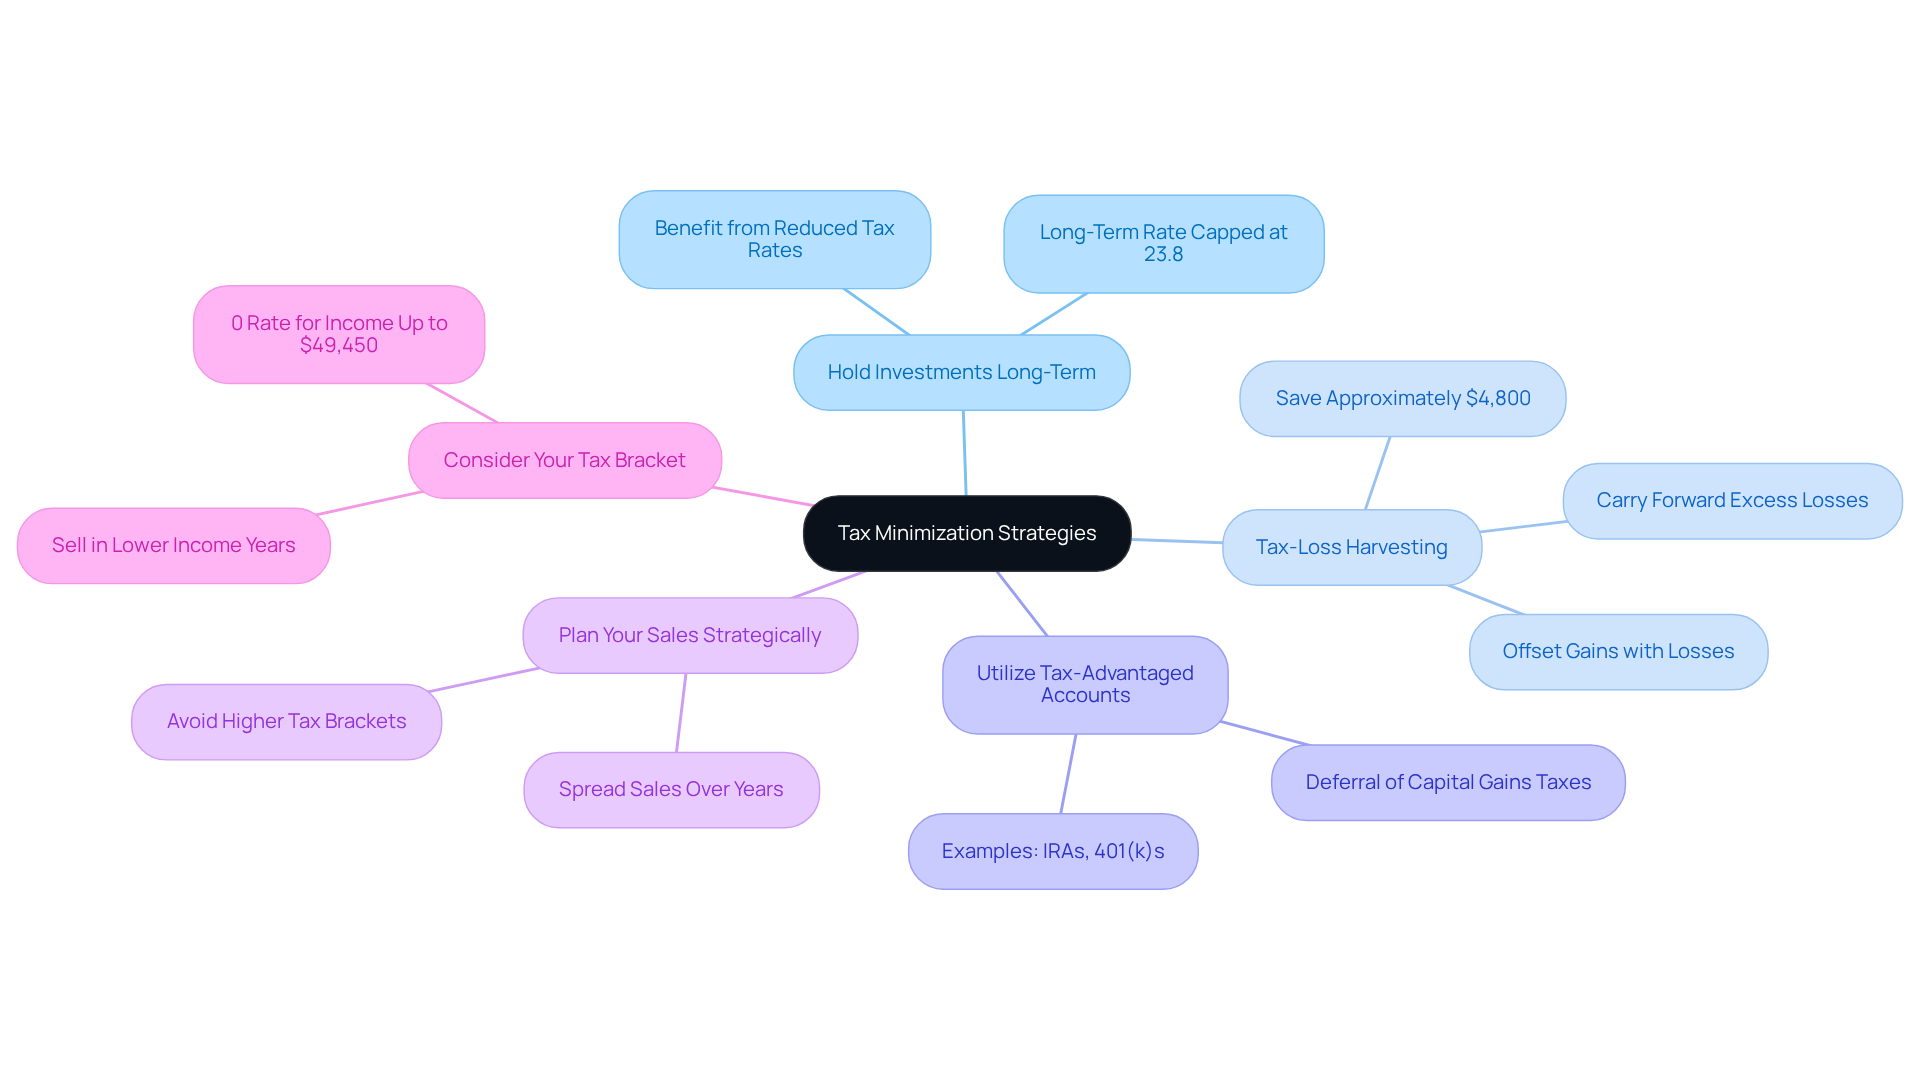
- Hold Investments Long-Term: Imagine holding onto your investments for a little longer, knowing that it could save your family money on taxes. By keeping stocks for over a year, you can benefit from reduced long-term tax rates on profits, capped at 23.8% for 2026, compared to short-term rates that can soar as high as 37%.
- Tax-Loss Harvesting: Think about selling an investment that didn’t perform well, allowing you to offset gains from another investment. For instance, if you sell Investment A at a loss of $30,000 and realize a profit of $25,000 from Investment B, you can completely offset that profit, leading to no tax liabilities. This method can save your family approximately $4,800, merging benefits from investment earnings and reductions in regular income.
- Utilize Tax-Advantaged Accounts: Consider using tax-advantaged accounts like IRAs or 401(k)s, which can be a great way to protect your family’s investments from taxes until you need them. Selling stocks within these accounts allows you to defer capital gains taxes, providing a strategic advantage in your financial planning.
- Plan Your Sales Strategically: Imagine spreading out your stock sales over the years, helping your family avoid higher tax brackets and keeping more money in your pocket. This is especially crucial for high-income households, as large stock sale tax planning for high income earners can lead to significantly different tax consequences depending on income levels.
- Consider Your Tax Bracket: If you know a lower income year is coming, think about selling stocks then to take advantage of lower tax rates. For example, households with taxable income up to $49,450 for individual filers fall into the 0% investment earnings tax category, making it a favorable moment to realize profits.
By utilizing these approaches, you can efficiently handle your investment earnings and improve your family’s overall financial situation. Consulting with a tax advisor can further refine these strategies to align with your individual financial goals. Remember, we’re here for you, and together, we can navigate this journey.
Plan the Timing of Your Stock Sale
Imagine feeling confident about your family’s financial future, even when the stock market feels unpredictable.
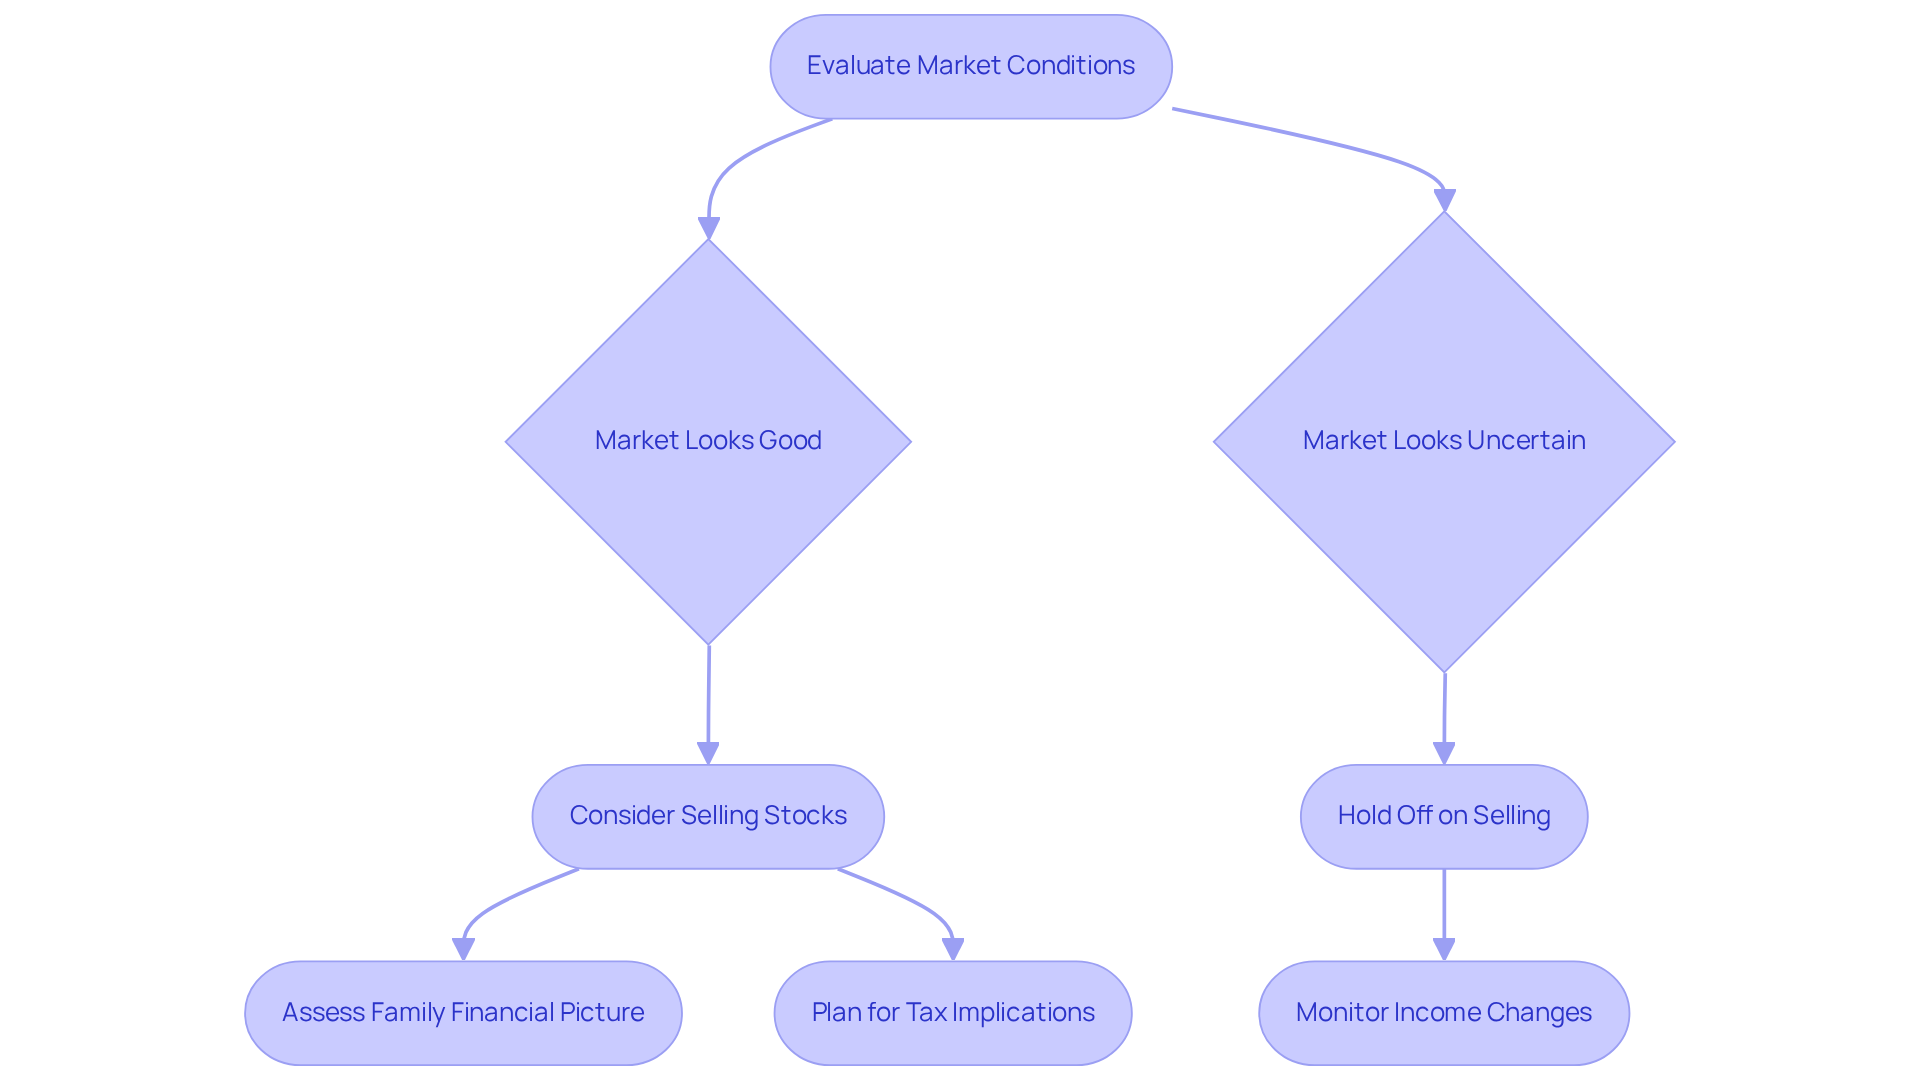
When the market’s looking good, it might be a great time to think about selling some stocks. Just remember, it’s important to consider how this fits into your family’s financial picture and the large stock sale tax planning for high income earners that might come into play.
If you’ve made some profits earlier in the year, it could be wise to hold off on selling more stocks until the next tax year. This way, you can spread out your tax burden, which might help ease the financial strain on your family.
Keep an eye on any significant changes in your income, like a new job or a bonus. Engaging in large stock sale tax planning for high income earners by timing your stock sales around these changes can help minimize the tax impact, especially if you expect to fall into a lower tax bracket.
Knowing where you stand with your tax brackets can really help you make smarter choices for your family. Engaging in large stock sale tax planning for high income earners can help you pay less in taxes on your long-term profits if you sell shares in a year when your earnings are lower.
Looking ahead to 2026, it’s good to know that if you’re a single filer, you won’t pay taxes on long-term gains if your income is below $49,450. This could be a great opportunity for your family to maximize your investments! For married couples filing jointly, the thresholds are even higher, which facilitates large stock sale tax planning for high income earners to strategically plan their sales.
By understanding these factors, you can navigate the complexities of stock sales with confidence. With the right strategies, you can turn market challenges into opportunities for your family’s growth and security.
Leverage Charitable Contributions for Tax Benefits
Imagine feeling the weight of tax obligations while wanting to support the causes that matter most to your family. Philanthropic donations can be a gentle way to ease that burden. Here’s how families can leverage this approach:
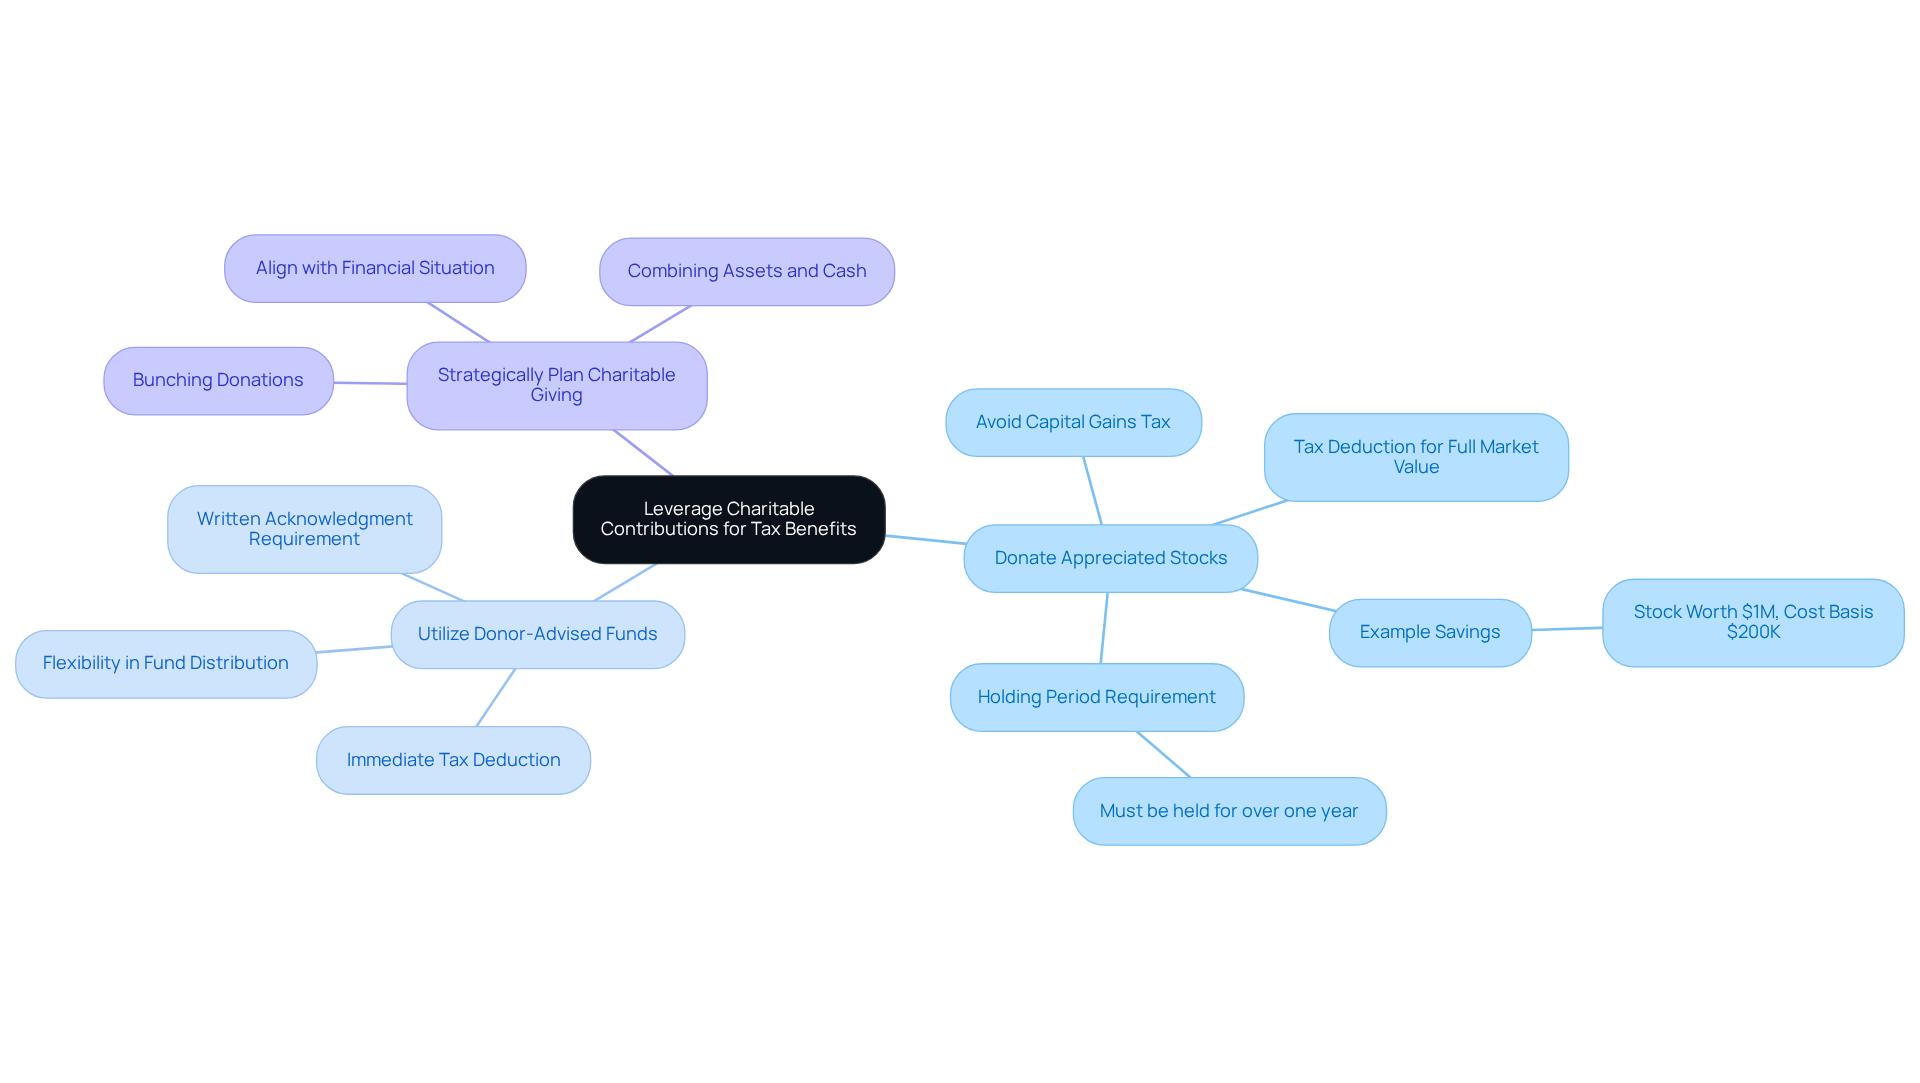
- Donate Appreciated Stocks: Instead of selling stocks and facing capital gains tax, consider donating them directly to a charity. This way, families can avoid paying taxes on profits while enjoying a tax deduction for the full market value of the stock. For example, if a family donates stock worth $1 million that they bought for $200,000, they could save around $370,000 in income tax and avoid $190,400 in capital gains tax. Plus, for stocks held for more than a year, the deduction is limited to 30% of adjusted gross income (AGI), with any excess contributions carried forward for up to five additional tax years.
- Utilize Donor-Advised Funds (DAFs): Contributing to a donor-advised fund allows families to make a charitable contribution and receive an immediate tax deduction. This approach offers flexibility in deciding how to distribute the funds over time, maximizing tax benefits through large stock sale tax planning for high income earners, particularly in high-income years. Remember, donations valued over $250 require a written acknowledgment from the charity for tax purposes.
- Strategically Plan Charitable Giving: Families should plan their charitable contributions to align with their financial situation. Bunching multiple years’ worth of donations into a single year can help surpass the standard deduction threshold, enhancing tax benefits. For instance, by combining contributions of appreciated assets and cash, families can boost their tax deductions while supporting their chosen charities.
By taking control of their charitable giving, families can utilize large stock sale tax planning for high income earners to not only reduce their tax burden but also feel empowered in their financial journey. Families like Allison and Brian have found that by using these strategies, they can lighten their tax burden while supporting the causes they care about. Together, we can navigate this journey, ensuring a brighter future for your loved ones. Please note that past performance does not guarantee future results, and all investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Consult Financial Advisors for Expert Guidance
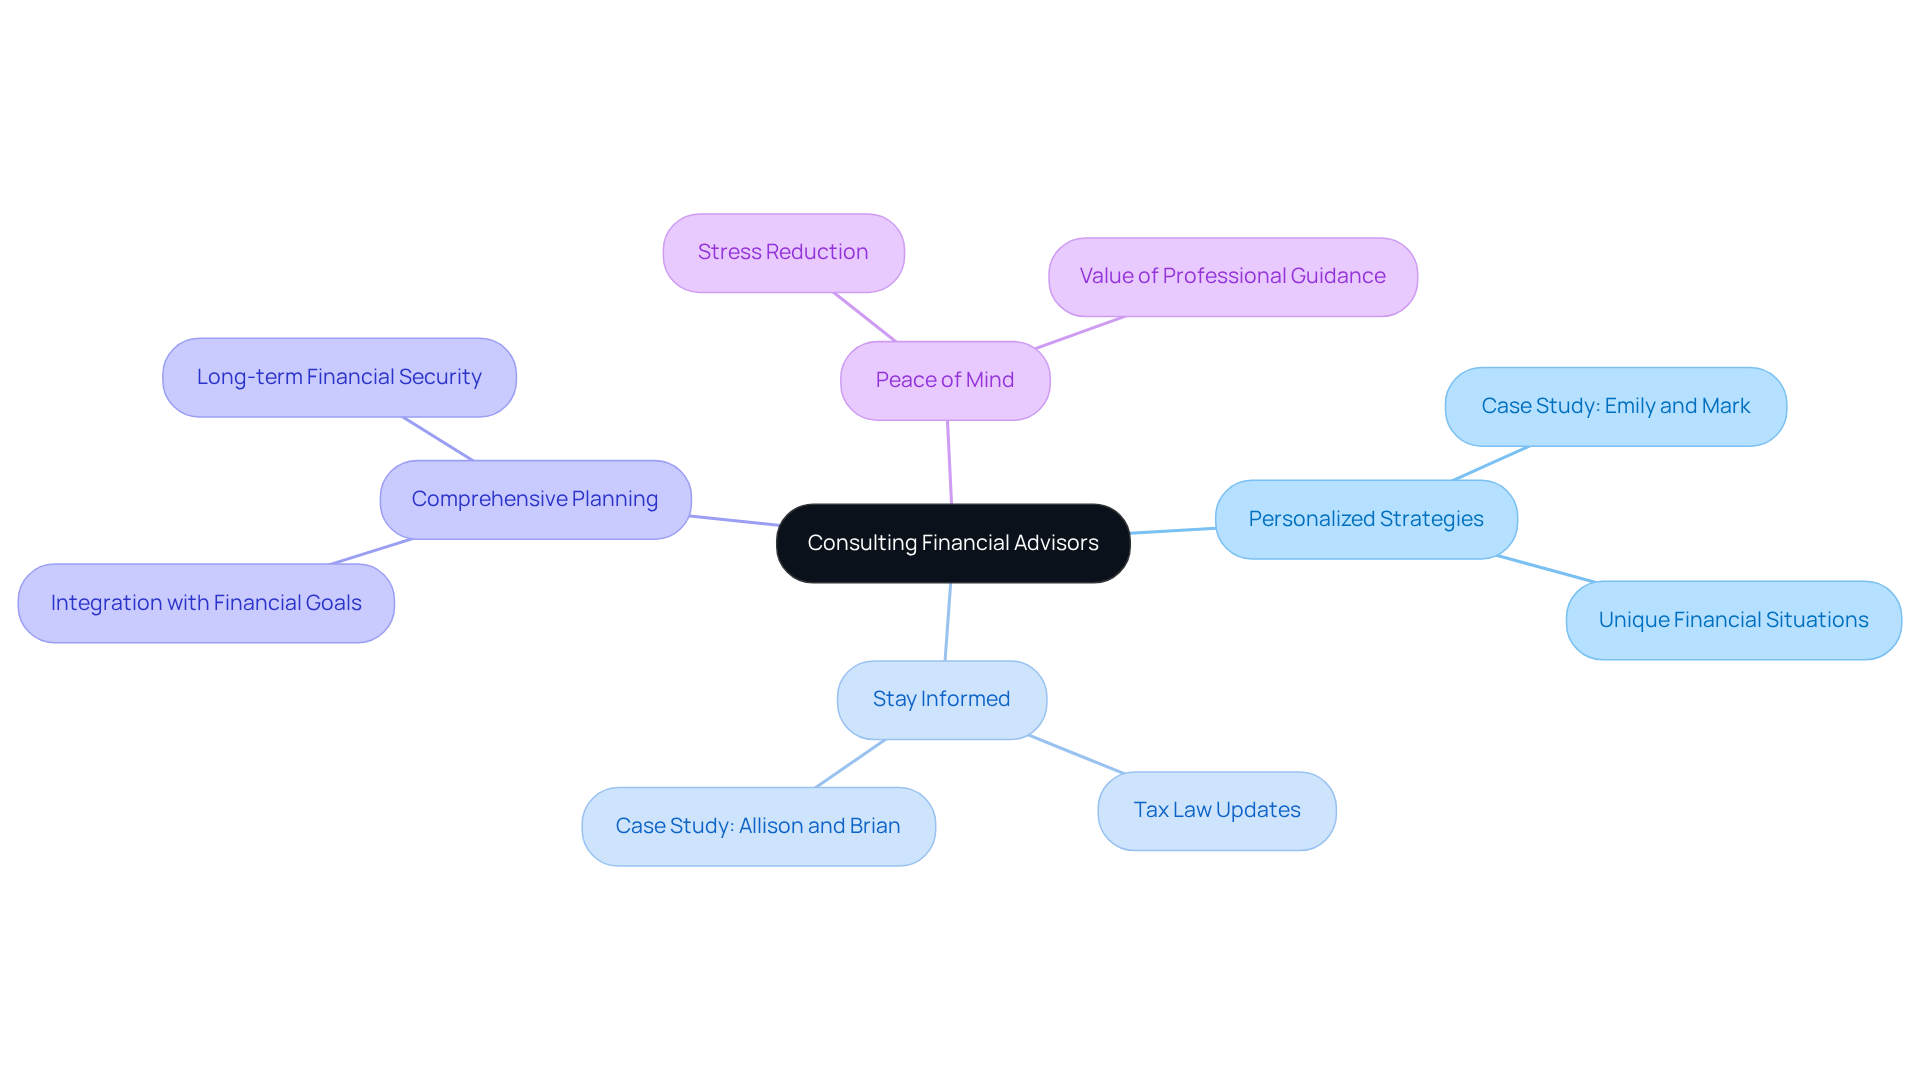
Imagine feeling overwhelmed by tax laws while trying to secure your family’s future. You’re not alone in this journey. Collaborating with a financial advisor can offer invaluable perspectives on tax planning related to investment profits. Here’s why:
- Personalized Strategies: Think of a financial advisor as your personal guide, helping you create strategies that fit your unique situation. For example, Emily and Mark, a couple in their mid-thirties, collaborated with Bright Advisers to achieve a clearer understanding of their financial situation. They developed a comprehensive plan that not only focused on optimizing their financial well-being but also provided them with the freedom to choose whether or not to continue working.
- Stay Informed: Tax laws are constantly changing, and it’s easy to feel lost in the maze of regulations. Advisors can keep you updated on new strategies that may impact your large stock sale tax planning for high income earners. Allison and Brian, another couple seeking guidance, discovered that proper tax planning could significantly enhance their financial potential, allowing them to secure their children’s future through education funding and gain the ability to retire sooner.
- Comprehensive Planning: Advisors can integrate tax planning with your overall financial strategy, ensuring that your investment decisions align with your long-term goals. This thorough approach is essential for households aiming to secure their financial future. Bright Advisers helped both Emily and Mark and Allison and Brian incorporate tax optimization into their financial plans, leading to peace of mind and improved financial security.
- Peace of Mind: Collaborating with a professional can reduce the stress of tax planning, enabling you to concentrate on your loved ones and other priorities. As Jim DeCarlo emphasizes, “advice pays!” which highlights the value of professional guidance in achieving better financial outcomes.
With the right support, you can transform your financial future and focus on what truly matters-your family. More and more families are realizing how crucial it is to have professional financial guidance, with 35% of Americans seeking advice from financial advisors. This trend highlights the significance of expert guidance in navigating complex tax scenarios, particularly for high-income households, with a focus on large stock sale tax planning for high income earners. Case studies, such as those of Emily and Mark and Allison and Brian, show that families who work with professionals often experience improved capital gains tax outcomes, reinforcing the idea that professional advice can lead to better financial decisions and enhanced peace of mind.
Conclusion
Imagine feeling confident about your family’s financial future, even amidst the complexities of tax planning. Navigating the intricacies of large stock sale tax planning can feel overwhelming, especially for high-income families. Understanding capital gains tax and implementing effective strategies can significantly impact your family’s overall financial health. By timing stock sales wisely and leveraging charitable contributions, you can optimize your tax situation and enhance your wealth preservation efforts.
It’s important to recognize how proactive tax planning can truly make a difference for your family. Key insights from this guide highlight the importance of:
- Distinguishing between short-term and long-term capital gains
- Utilizing tax-loss harvesting
- Strategically planning stock sales to minimize tax liabilities
Real-life examples, like those of Jay and Emma, Emily and Mark, and Allison and Brian, show how effective tax planning can lead to greater financial peace and independence.
Without proactive measures, families risk losing out on significant savings that could benefit their future. High-income families should consider consulting with a financial advisor to tailor strategies that align with their unique circumstances. By taking these steps, you can pave the way for a secure financial future, ensuring your family’s dreams are within reach. Embrace the opportunity to optimize your financial strategy today and explore how Bright Advisers can assist in navigating these complexities for your family’s benefit.
Frequently Asked Questions
What is capital gains tax?
Capital gains tax is a tax levied on the profit from selling an asset, such as stocks.
What are the differences between short-term and long-term capital gains?
Short-term capital gains apply to assets held for one year or less and are taxed at ordinary income tax rates, which can reach up to 37%. Long-term capital gains apply to assets held for over one year and are taxed at lower rates, typically 0%, 15%, or 20%, based on taxable income.
What are the long-term capital gains tax rates for 2026?
For 2026, long-term capital gains tax rates are set at 15% for single filers earning up to $49,450 and 20% for those exceeding $545,500.
What is the Net Investment Income Tax (NIIT)?
The Net Investment Income Tax (NIIT) imposes an additional 3.8% on certain investment revenue, including profits from asset sales, affecting high-income earners.
How can families effectively manage their capital gains tax?
Families can manage capital gains tax by understanding the distinctions between short-term and long-term gains, planning ahead, and utilizing strategies like tax-loss harvesting.
What is tax-loss harvesting?
Tax-loss harvesting is a strategy that allows households to sell underperforming investments to offset realized profits, with any leftover losses applicable against ordinary income up to $3,000.
What strategies can families use to minimize capital gains taxes?
Families can minimize capital gains taxes by holding investments long-term, utilizing tax-loss harvesting, using tax-advantaged accounts, planning sales strategically, and considering their tax bracket.
How does holding investments long-term benefit families?
Holding investments for over a year allows families to benefit from reduced long-term tax rates on profits, which are capped at 23.8% for 2026, compared to higher short-term rates.
What are tax-advantaged accounts, and how do they help?
Tax-advantaged accounts, such as IRAs or 401(k)s, allow families to protect their investments from taxes until needed, deferring capital gains taxes and providing a strategic advantage.
Why is it important to plan stock sales strategically?
Planning stock sales strategically helps families avoid higher tax brackets and retain more money, especially crucial for high-income households.
What should families consider regarding their tax bracket when selling stocks?
Families should consider selling stocks in a lower income year to take advantage of lower tax rates, such as realizing profits when taxable income is up to $49,450 for individual filers, which falls into the 0% investment earnings tax category.
Who provides advisory services related to capital gains tax planning?
Advisory services related to capital gains tax planning are provided through Lifeworks Advisors, a registered investment adviser.
List of Sources
- Understand Capital Gains Tax Basics
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- What Is Capital Gains Tax? 2026 Rates Explained (https://nw.bank/blog-detail/blog/2026/05/05/what-is-capital-gains-tax–2026-rates-explained)
- Implement Tax Minimization Strategies
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- Tax-Loss Harvesting: A Practical Guide for Financial Advisors (https://icfs.com/specialists-desk/tax-loss-harvesting)
- Managing accounts to lower taxes | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/tax-advantaged-accounts)
- Tax Loss Harvesting Tips: Smart Strategies to Cut Taxes & Boost Returns (https://wealthenhancement.com/blog/essential-tax-loss-harvesting-tips)
- Plan the Timing of Your Stock Sale
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- A Guide to the Capital Gains Tax Rates: Short-term vs. Long-term Capital Gains Taxes (https://turbotax.intuit.com/tax-tips/investments-and-taxes/guide-to-short-term-vs-long-term-capital-gains-taxes-brokerage-accounts-etc/L7KCu9etn)
- What is capital gains tax? | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/realized-capital-gains)
- Tax-Smart Strategies for Selling Securities | Morgan Stanley (https://morganstanley.com/articles/selling-stocks-taxes)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- Leverage Charitable Contributions for Tax Benefits
- Charitable contributions: tax strategies (https://fidelitycharitable.org/guidance/charitable-tax-strategies/charitable-contributions.html)
- Why Donating Appreciated Stock Makes Financial Sense (https://ghcf.org/articles/why-donating-appreciated-stock-makes-financial-sense)
- SOI Tax Stats – Individual noncash charitable contributions | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-individual-noncash-charitable-contributions)
- Tax Advantages for Donor-Advised Funds | NPTrust (https://nptrust.org/what-is-a-donor-advised-fund/daf-tax-consideration)
- Tax Strategies for Charitable Giving: Methods to Maximize Benefits | Parametric Portfolio Associates (https://parametricportfolio.com/blog/charitable-giving-tax-benefit-strategies)
- Consult Financial Advisors for Expert Guidance
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Only 41% of Americans Use a Financial Advisor—And Most Younger Adults Shun the Professionals (https://investopedia.com/americans-using-a-financial-advisor-11812935)
- A new study finds that clients working with an advisor would see a 2.39%–2.78% annual return premium (based on investment and tax planning services) over those without an advisor, after accounting… | Michael Kitces (https://linkedin.com/posts/michaelkitces_weekend-reading-for-financial-planners-february-activity-7299473143427985409-W4D7)
- How Many Financial Advisors Are in the U.S.? | Finance Strategists (https://financestrategists.com/financial-advisor/advisor-types/how-many-financial-advisors-are-in-the-us)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading