

Key Highlights
- Capital gains tax can significantly impact families’ financial planning, especially when selling stocks.
- A 20% tax rate applies to higher incomes, with an additional 3.8% tax on gains for those in higher brackets.
- Holding investments for over a year can lead to lower long-term capital gains tax rates, potentially as low as 0%.
- Tax-loss harvesting allows families to offset profits with losses, reducing taxable income.
- Utilising tax-advantaged accounts like IRAs and 401(k)s can defer taxes on profits until withdrawal.
- Gifting appreciated stocks to family members in lower tax brackets can help avoid capital gains taxes.
- Year-end planning and instalment sales can help families manage tax liabilities by timing stock sales strategically.
- State capital gains tax rates vary, with states like California and New York having higher rates compared to no-income-tax states like Texas.
- Advanced techniques such as Charitable Remainder Trusts (CRTs) and Qualified Small Business Stock (QSBS) can provide significant tax benefits.
- Income splitting strategies can help reduce overall tax burdens for high-income households.
Introduction
Imagine facing a significant stock sale and feeling overwhelmed by the complexities of capital gains tax. Many families feel lost when faced with capital gains tax, especially during significant stock sales. When families understand how long they’ve held their assets and the tax rates involved, they can make better financial decisions. Together, we’ll uncover strategies that can help families like Jay and Emma secure their financial futures while managing investments wisely.
How can families use these strategies to reduce their tax burden and improve their financial well-being?
Understand Capital Gains Tax Basics
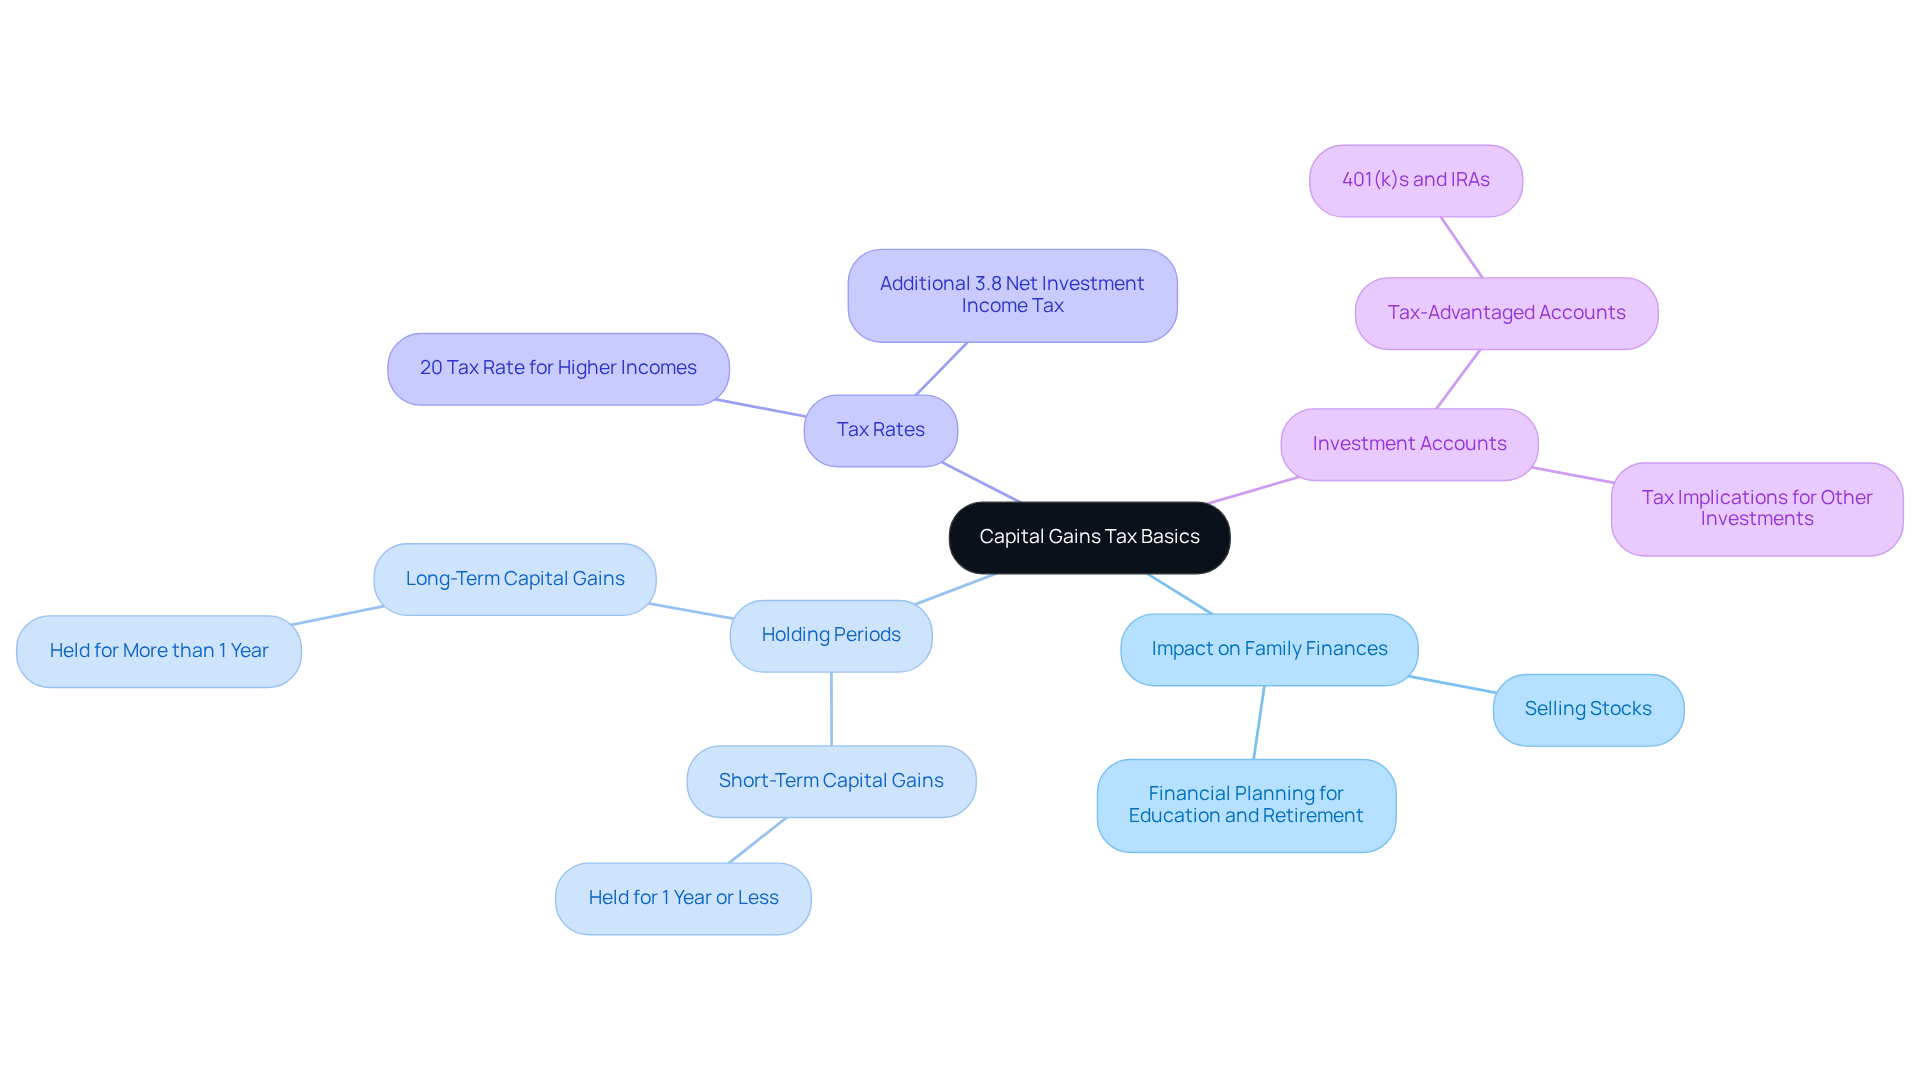
Imagine facing a hefty tax bill just when you’re trying to secure your family’s future – this is the reality of capital gains tax for many parents today. Have you ever wondered how selling your stocks could impact your family’s finances? It’s important to understand that how long you hold onto an asset can change the tax you owe.
For families planning ahead, knowing that a 20% tax rate kicks in for higher incomes can help you strategize better. And if you’re in a higher income bracket, there’s an extra 3.8% tax to consider on your gains. Understanding these differences is crucial for families, as they can impact large stock sale tax planning, influencing when you decide to sell your stocks and how much tax you’ll owe.
This is particularly relevant for families like Jay and Emma, who want to ease their financial worries while planning for their kids’ education and their own retirement. At Bright Advisers, we’re here to help families navigate these complexities, so you can make informed choices about your investments with confidence.
Remember, if you have investments in tax-advantaged accounts like 401(k)s and IRAs, those profits aren’t taxed the same way. By understanding these tax implications, you can align your financial planning with your family’s long-term dreams and goals.
Implement Effective Tax Minimization Strategies
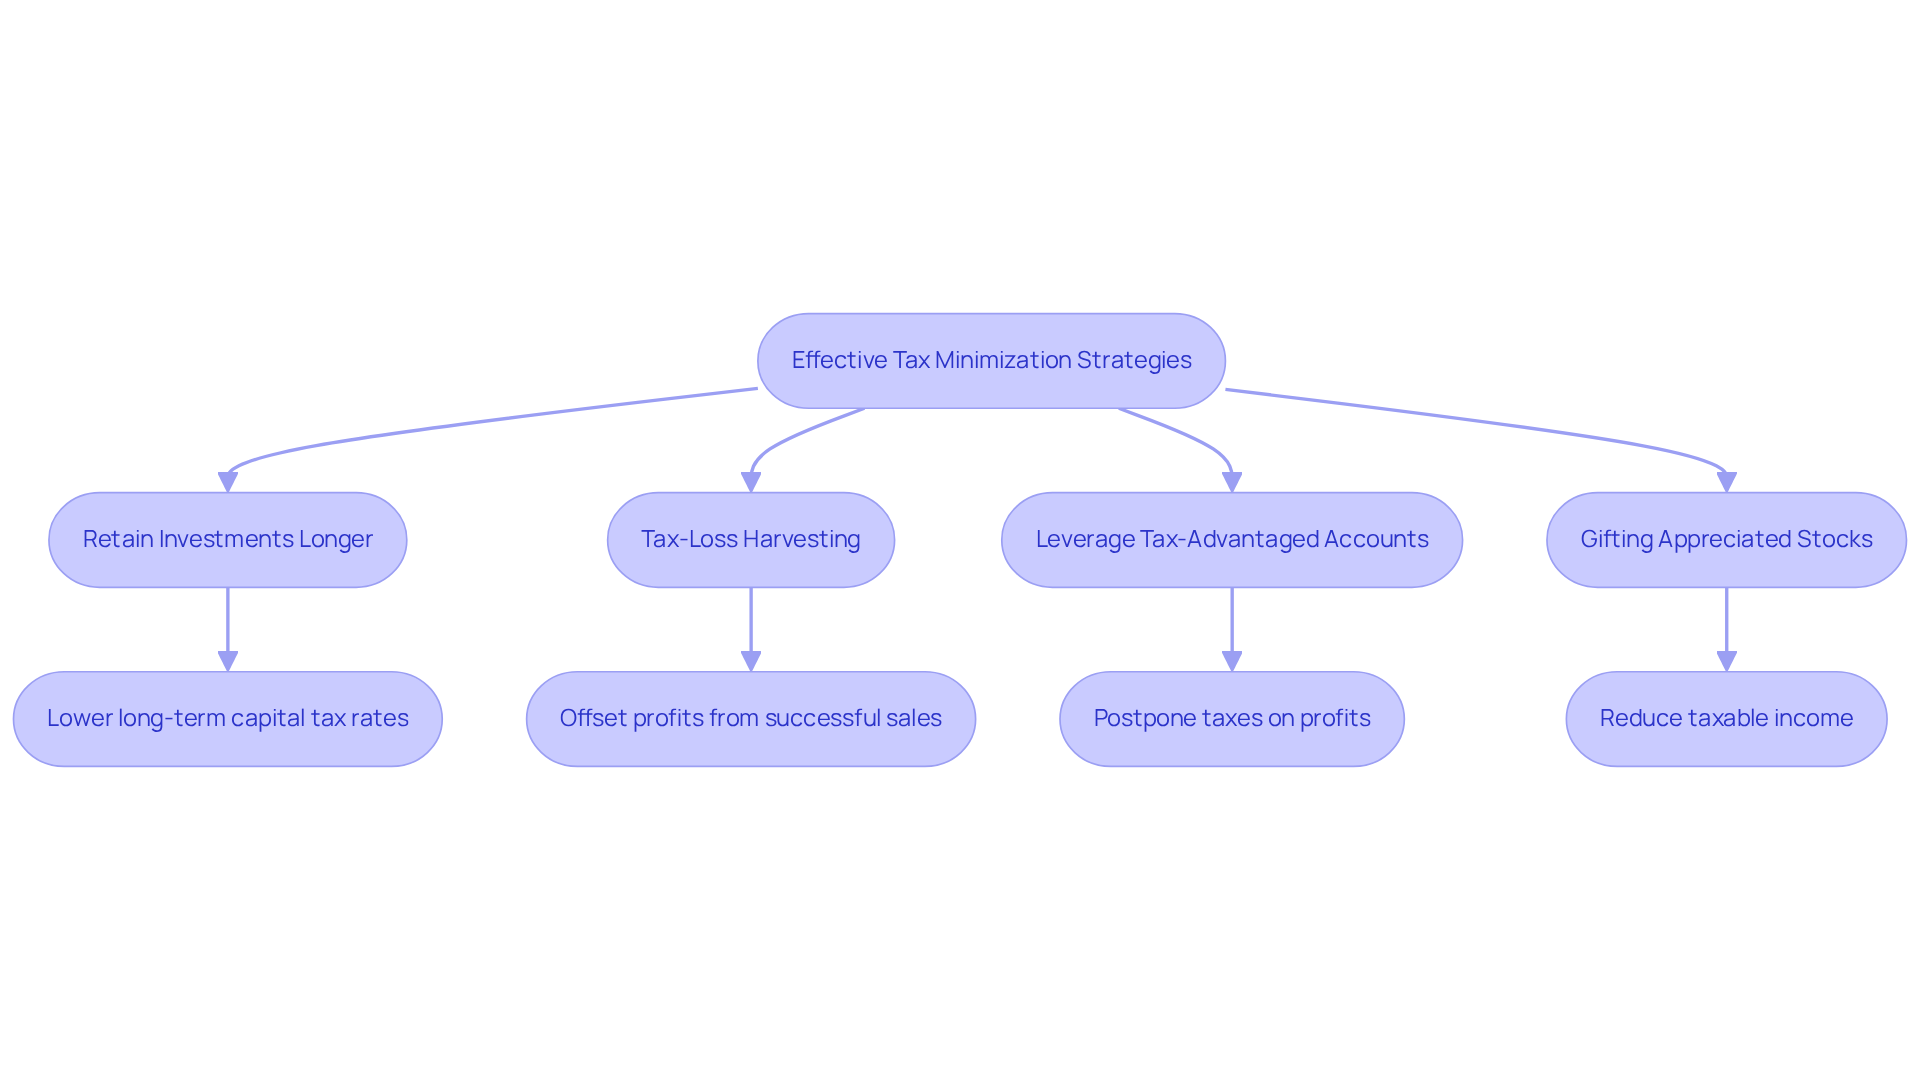
Imagine feeling confident about your family’s financial future, even when faced with the complexities of capital gains taxes. Here are some gentle strategies to help you navigate this journey:
- Retain Investments Longer: When you hold onto your stocks for over a year, you can enjoy the comfort of lower long-term capital tax rates, which can be as low as 0% for certain income brackets. This means more of your hard-earned money stays with you and your family.
- Tax-Loss Harvesting: This strategy involves selling underperforming stocks to offset profits from successful sales. For instance, if you realize a profit of $10,000 from one stock but experience a loss of $4,000 from another, you can lower your taxable profit to $6,000. This can greatly reduce your tax obligation. Emily and Mark effectively utilized this strategy with guidance from Bright Advisers, allowing them to manage their investments wisely while balancing their demanding careers.
- Leverage Tax-Advantaged Accounts: Investing through vehicles such as IRAs or 401(k)s enables you to postpone taxes on profits until withdrawal. This allows your investments to grow without the burden of immediate taxation, giving you more time to build your family’s future.
- Gifting Appreciated Stocks: You can gift appreciated stocks to your children or other family members in lower tax brackets, potentially avoiding capital gains taxes altogether. This not only decreases your taxable income but also teaches younger generations about financial management. Jay and Emma successfully navigated funding their children’s education while planning for retirement, achieving a balance between their present responsibilities and long-term aspirations.
By embracing these strategies, you can lighten your tax burden and feel more secure in your family’s financial journey. For example, tax-loss harvesting can yield estimated savings of $4,800 based on current tax rates, demonstrating its effectiveness in managing capital gains taxes. By understanding and applying these strategies, you can navigate the complexities of tax planning more effectively. Bright Advisers is dedicated to assisting families like Allison and Brian, who sought guidance to enhance their financial potential through effective tax planning, ensuring they utilize their financial resources to the fullest.
Note: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Plan Sales Timing and Structure for Tax Efficiency
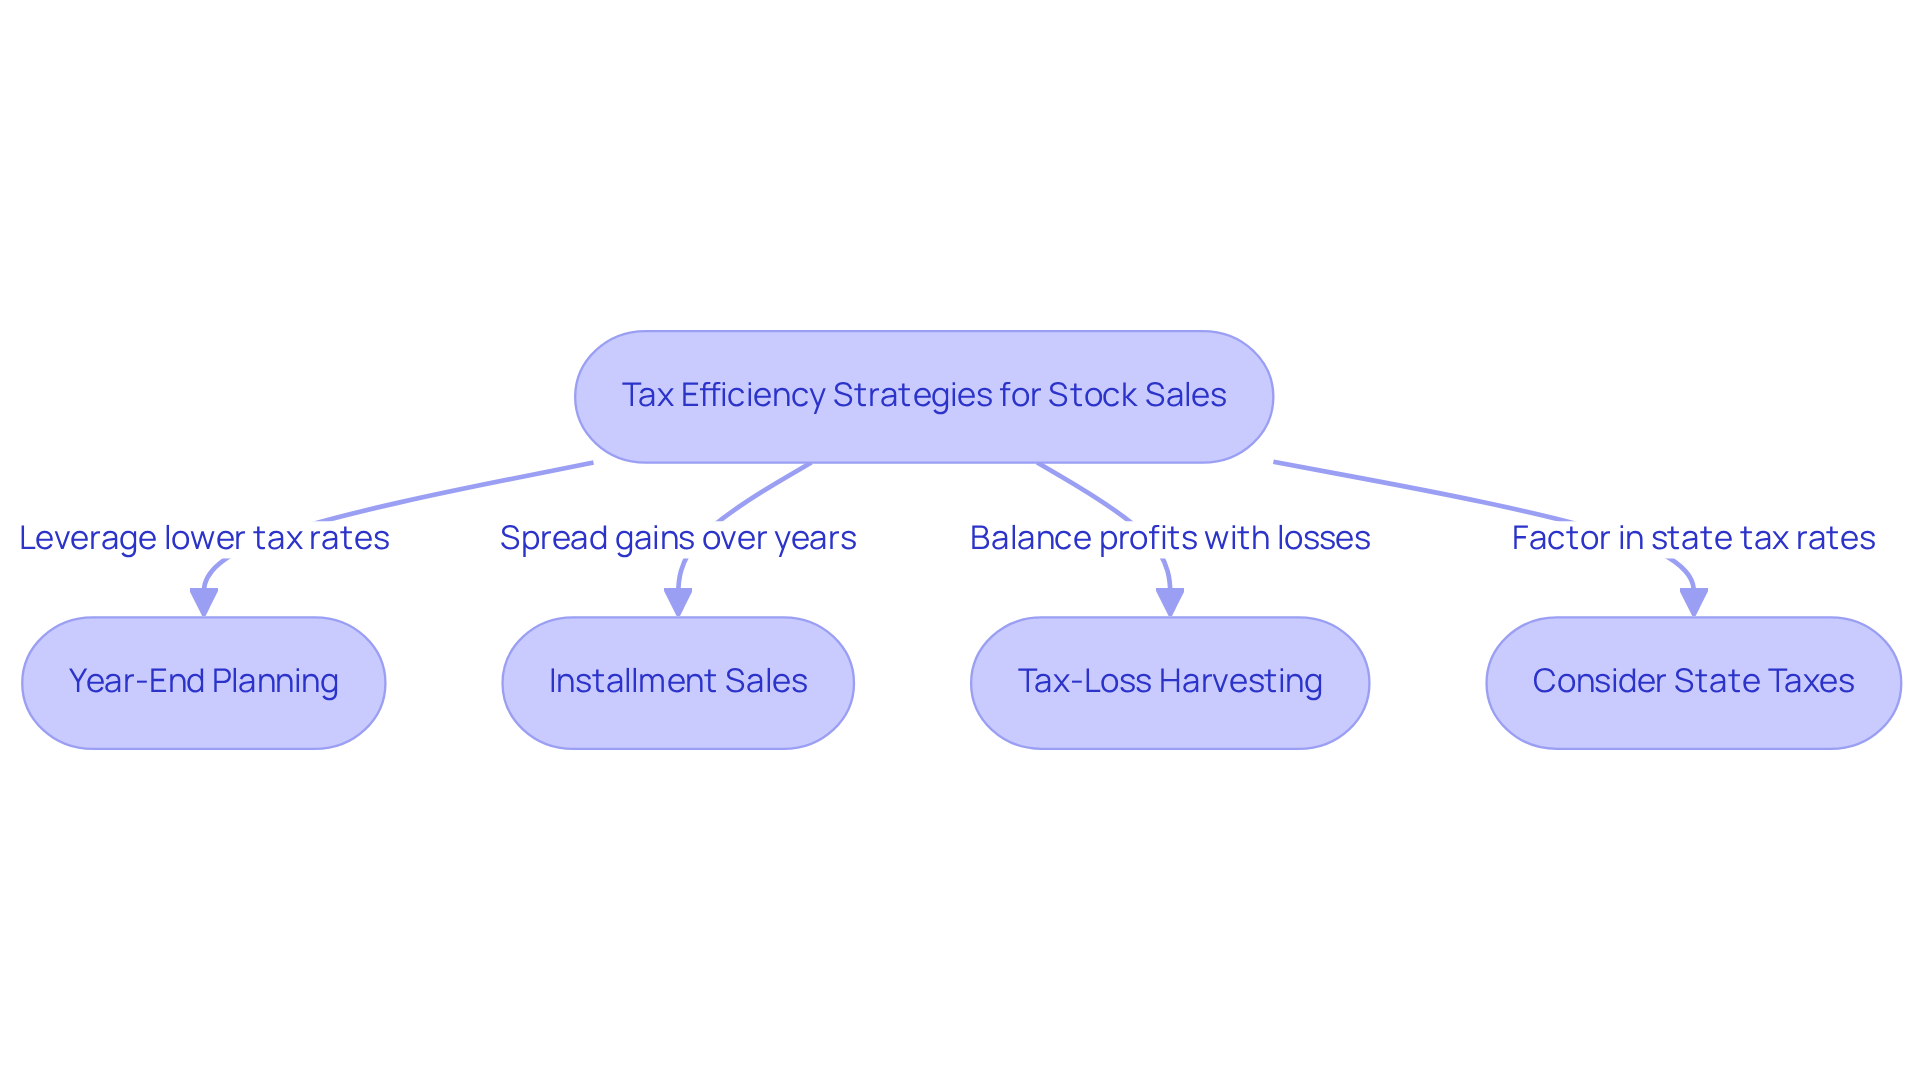
Many families feel overwhelmed by the complexities of large stock sale tax planning, particularly when it comes to stock sales. Here are some key strategies to consider that can help ease your worries:
- Year-End Planning: If your family anticipates a lower income year, selling stocks during that time might be a smart move. Imagine if you could leverage lower tax rates by selling appreciated stocks. This can really lighten your tax burden, especially if you’re moving into a lower tax bracket. Remember, interest income from installment payments can be taxed at rates as high as 37%, which is considerably more than long-term profit rates.
- Installment Sales: Instead of selling everything at once, consider structuring your sales over multiple years. This approach can help distribute your investment returns, keeping your family within a lower tax category and reducing overall tax obligations. For instance, if you spread a $400,000 profit over four years, you could significantly lower your effective tax rate. This strategy was a game-changer for Allison and Brian, who learned to manage their capital effectively with our help, securing their children’s future through education funding.
- Tax-Loss Harvesting: It’s also wise to think about selling other investments at a loss to balance out your realized profits. This strategy can effectively minimize your overall tax impact. For example, if you realize a $100,000 profit from stock sales, selling another investment at a $50,000 loss can lower your taxable income. Allison and Brian successfully implemented this strategy, enhancing their financial situation.
- Consider State Taxes: Don’t forget about state capital gains tax rates, which can vary widely. States like California and New York have higher rates compared to states with no income tax, like Texas or Florida. It’s important to factor in these differences when planning your sales.
By utilizing large stock sale tax planning, your family can strategically plan the timing and structure of stock sales to significantly reduce tax liabilities, ensuring more resources are available for your children’s future. We’re here to help families like Allison and Brian navigate these complexities together, offering comprehensive tax planning strategies that contribute to financial stability and peace of mind.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk.
Explore Advanced Tax Management Techniques
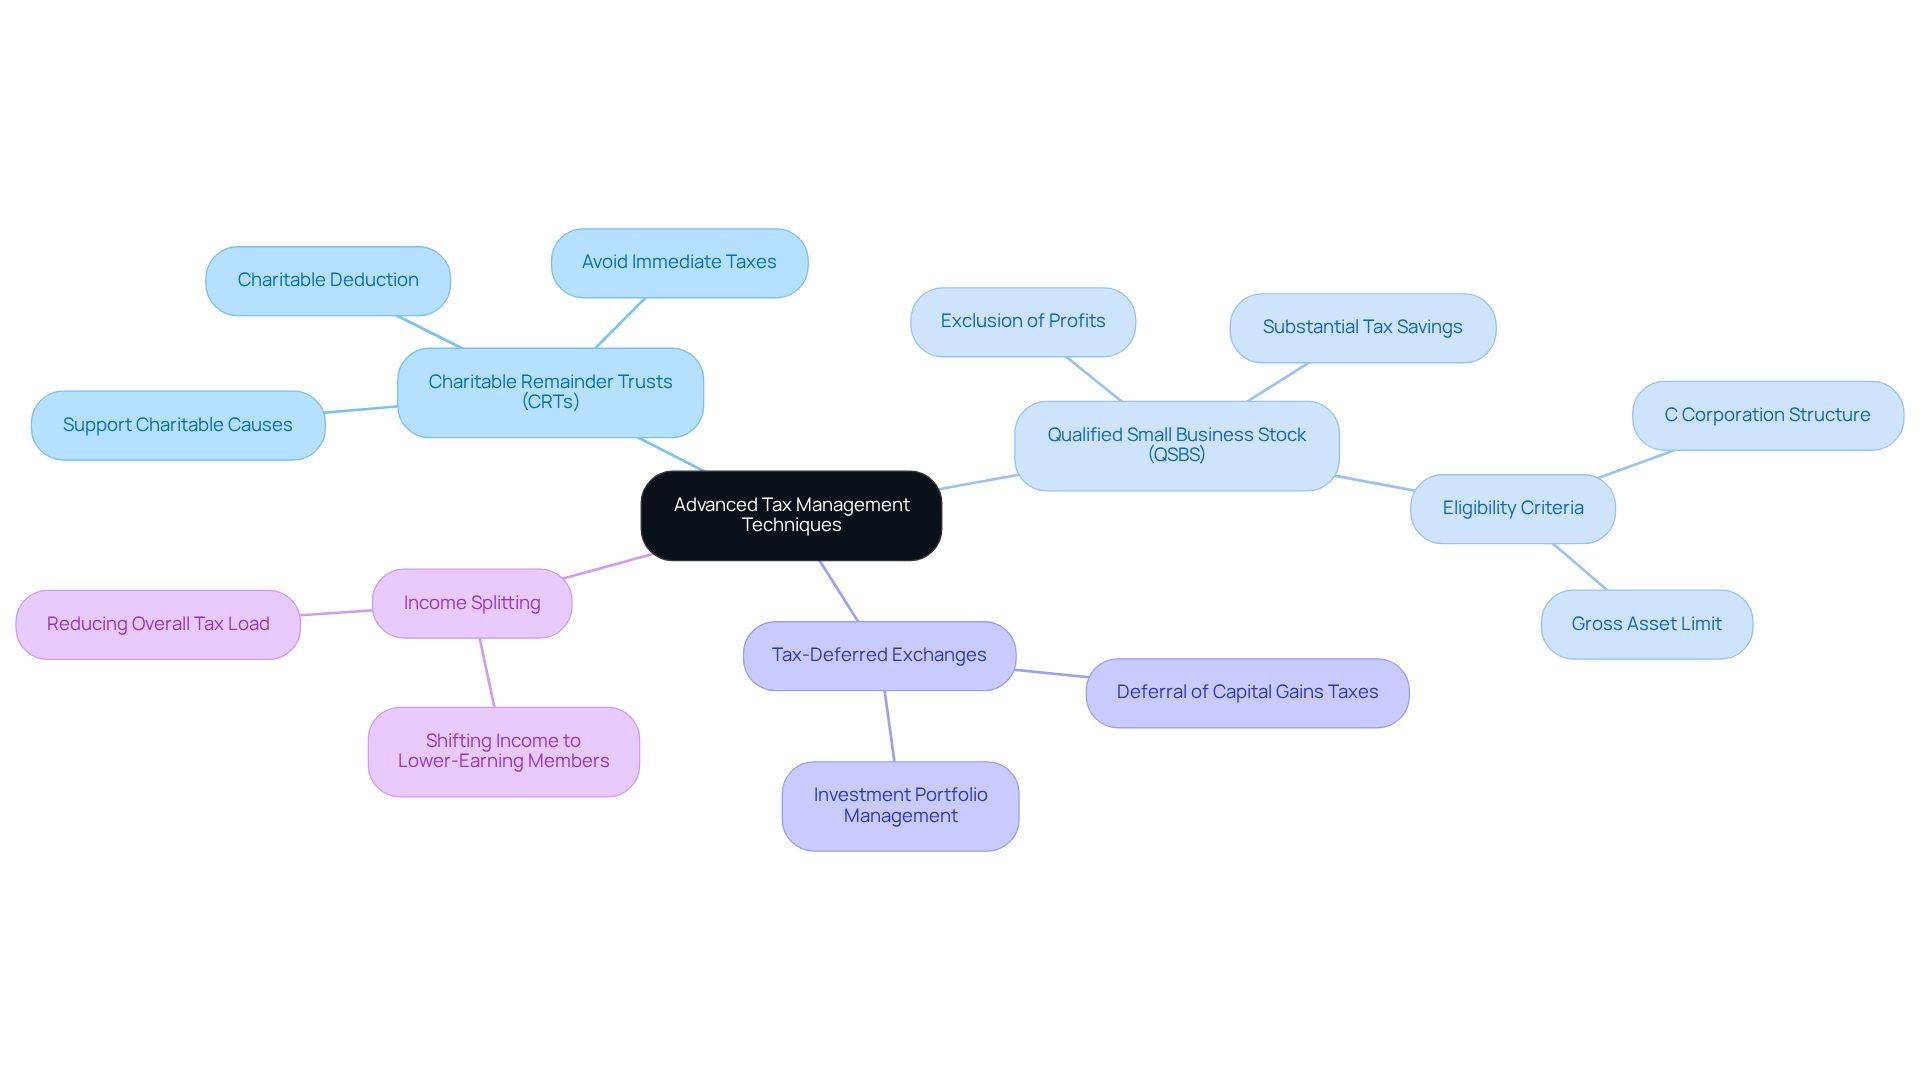
Navigating the world of taxes can feel overwhelming, especially for families striving to secure their financial future. For families with substantial stock holdings, large stock sale tax planning techniques can significantly enhance financial efficiency, as demonstrated by Jay and Emma’s experience with Bright Advisers.
- Charitable Remainder Trusts (CRTs): If you place appreciated stocks into a CRT, you can avoid immediate taxes on profits and even get a charitable deduction. This strategy not only supports charitable causes but also helps manage tax liabilities effectively. Jay and Emma utilized this approach, successfully reducing their tax burdens while contributing to meaningful charitable initiatives.
- Qualified Small Business Stock (QSBS): Families may benefit from QSBS provisions, which allow for the exclusion of profits from the sale of qualified small business stock if held for more than five years. This can lead to substantial tax savings, especially for those involved in startups or small businesses. Significantly, QSBS enables employees to exclude up to $15 million in federal profits, making it a powerful resource for high-income households like Jay and Emma.
- Tax-Deferred Exchanges: You might consider using 1031 exchanges for your real estate or stocks, which can help you defer those pesky capital gains taxes. This strategy can be especially advantageous for households aiming to effectively manage their investment portfolios through large stock sale tax planning.
- Income Splitting: Households can explore strategies that involve shifting income to lower-earning members. This method can lessen the overall tax load, making it a valuable strategy for high-income households.
Imagine the peace of mind that comes with knowing your family’s financial future is secure. By exploring these advanced techniques, you can enhance your tax efficiency and better secure your financial future. The use of CRTs, in particular, has been shown to provide significant benefits, as evidenced by Jay and Emma’s success in managing their tax liabilities while supporting charitable initiatives. Additionally, their comprehensive budget establishment and investment strategies focused on diversification have allowed them to balance growth potential and risk management, further securing their financial future. Incorporating expert opinions, such as those from tax professionals, can further validate these strategies and provide families with the guidance needed to navigate complex tax regulations. With the right strategies in place, you can transform your financial landscape and ensure a brighter future for your family.
Conclusion
Many families feel overwhelmed by the complexities of tax planning, unsure of how to secure their financial future. Understanding the intricacies of large stock sale tax planning is crucial for families looking to protect their financial well-being. By grasping the nuances of capital gains tax and implementing effective strategies, families can navigate the complexities of stock sales with confidence.
Key strategies such as:
- Retaining investments longer
- Utilizing tax-loss harvesting
- Leveraging tax-advantaged accounts
can greatly reduce tax liabilities. Additionally, considering the timing and structure of stock sales, along with advanced techniques like Charitable Remainder Trusts and Qualified Small Business Stock provisions, can further enhance financial efficiency. Families like Jay and Emma have successfully applied these strategies, demonstrating the tangible benefits of proactive tax planning.
It’s important to recognize how effective tax management can truly make a difference for families. By taking the time to understand and implement these strategies, families can not only minimize their tax burdens but also ensure that more resources are available for their children’s future. Working with a caring fiduciary advisor can help families find their way through these complexities, empowering them to make informed financial decisions that align with their long-term goals.
Frequently Asked Questions
What is capital gains tax?
Capital gains tax is a tax on the profit made from selling an asset, such as stocks. The amount of tax owed can vary based on how long the asset was held and the taxpayer’s income level.
How does the holding period of an asset affect capital gains tax?
The length of time you hold onto an asset can change the tax rate you owe. Generally, assets held for more than one year are subject to lower long-term capital gains tax rates, while assets held for less than a year are taxed at higher short-term rates.
What are the capital gains tax rates for higher-income families?
Higher-income families may face a capital gains tax rate of 20%. Additionally, there is an extra 3.8% tax on gains for those in higher income brackets.
Why is understanding capital gains tax important for families?
Understanding capital gains tax is crucial for families as it can significantly impact financial planning, especially regarding large stock sales, education funding, and retirement planning.
How can families strategize around capital gains tax?
Families can strategize by considering the timing of stock sales and understanding the tax implications of their investments, which can help them minimize tax liabilities and align their financial planning with long-term goals.
Are profits from tax-advantaged accounts taxed the same way as regular investments?
No, profits from tax-advantaged accounts like 401(k)s and IRAs are not taxed in the same way as regular investments, which can provide families with additional tax benefits.
How can Bright Advisers assist families with capital gains tax planning?
Bright Advisers helps families navigate the complexities of capital gains tax and investment decisions, enabling them to make informed choices that support their financial goals and secure their family’s future.
List of Sources
- Understand Capital Gains Tax Basics
- What is capital gains tax? | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/realized-capital-gains)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- A Guide to the Capital Gains Tax Rates: Short-term vs. Long-term Capital Gains Taxes (https://turbotax.intuit.com/tax-tips/investments-and-taxes/guide-to-short-term-vs-long-term-capital-gains-taxes-brokerage-accounts-etc/L7KCu9etn)
- What Is Capital Gains Tax? 2026 Rates Explained (https://nw.bank/blog-detail/blog/2026/05/05/what-is-capital-gains-tax–2026-rates-explained)
- Implement Effective Tax Minimization Strategies
- What is capital gains tax? | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/realized-capital-gains)
- Wealthfront Tax-Loss Harvesting | Wealthfront Whitepapers (https://research.wealthfront.com/whitepapers/tax-loss-harvesting)
- Here’s how to make your tax-loss harvesting strategy do more for you | J.P. Morgan Private Bank U.S. (https://privatebank.jpmorgan.com/nam/en/insights/markets-and-investing/ideas-and-insights/heres-how-to-make-your-tax-loss-harvesting-strategy-do-more-for-you)
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- Plan Sales Timing and Structure for Tax Efficiency
- Installment Sales: How to Spread a Large Capital Gain Across Multiple Tax Years – True Wealth Design (https://truewealthdesign.com/installment-sales-spreading-capital-gains)
- Year-End Planning Tips (https://eisneramper.com/insights/tax/tax-planning-chapter-1125)
- Installment sales spread capital gains over years (https://instead.com/resources/blog/installment-sales-spread-capital-gains-over-years)
- Installment Sales Can Be a Win-Win for Buyers and Sellers – GRF CPAs & Advisors (https://grfcpa.com/resource/installment-sales-can-be-a-win-win-for-buyers-and-sellers)
- 5 year-end tax-planning actions to take before 2026 | J.P. Morgan Private Bank U.S. (https://privatebank.jpmorgan.com/nam/en/insights/markets-and-investing/ideas-and-insights/5-year-end-tax-planning-actions-to-take-before-2026)
- Explore Advanced Tax Management Techniques
- Qualified Small Business Stock (QSBS) Explained (https://carta.com/learn/startups/tax-planning/qsbs)
- Quite Some BS: Expanded ‘QSBS’ Giveaway in Trump Tax Law Threatens State Revenues and Enriches the Wealthy (https://itep.org/qsbs-trump-tax-law-threatens-state-revenues-enriches-wealthy)
- Quite the Skewed Business Subsidy: QSBS Exclusion Is a Poor Way to Encourage Investment (https://taxfoundation.org/blog/qualified-small-business-stock-qsbs-exclusion)
- SOI Tax Stats – Split-interest trust statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-split-interest-trust-statistics)
- The qualified small business stock exclusion overwhelmingly benefits the wealthy and should be reformed in 2025 (https://equitablegrowth.org/the-qualified-small-business-stock-exclusion-overwhelmingly-benefits-the-wealthy-and-should-be-reformed-in-2025)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading