

Key Highlights
- Liquidity events, such as stock option vesting or business sales, can create significant financial opportunities but also challenges, including tax implications.
- Families should start planning years in advance of a liquidity event to manage their newfound wealth effectively.
- Engaging children in financial discussions helps instil values and prepares them for future financial responsibilities.
- Diversification strategies, including asset allocation and geographic diversification, are essential for protecting wealth after a liquidity event.
- Regular portfolio rebalancing ensures that families maintain their desired investment strategy and risk levels.
- Continuous financial education through programmes, workshops, and expert consultations is crucial for families to navigate wealth management.
- Personalised financial planning should reflect each family’s unique goals and values, incorporating regular reviews to adapt to changing circumstances.
- Statistics show that structured financial planning significantly increases the likelihood of achieving retirement savings goals.
Introduction
Imagine receiving a financial windfall, but feeling overwhelmed by the responsibility that comes with it. Liquidity events, like stock option vesting or business sales, can significantly change your family’s financial landscape. But with great opportunity comes great responsibility. These moments present both exciting possibilities and daunting challenges.
Let’s dive into some essential diversification strategies that can help your family enhance financial stability after these events. It’s important to ensure that your financial decisions align with your core values. How can families navigate the complexities of these transitions while securing their financial future? Together, we can explore how to turn these challenges into stepping stones for a secure financial future.
Understand Liquidity Events and Their Impact on Wealth Management
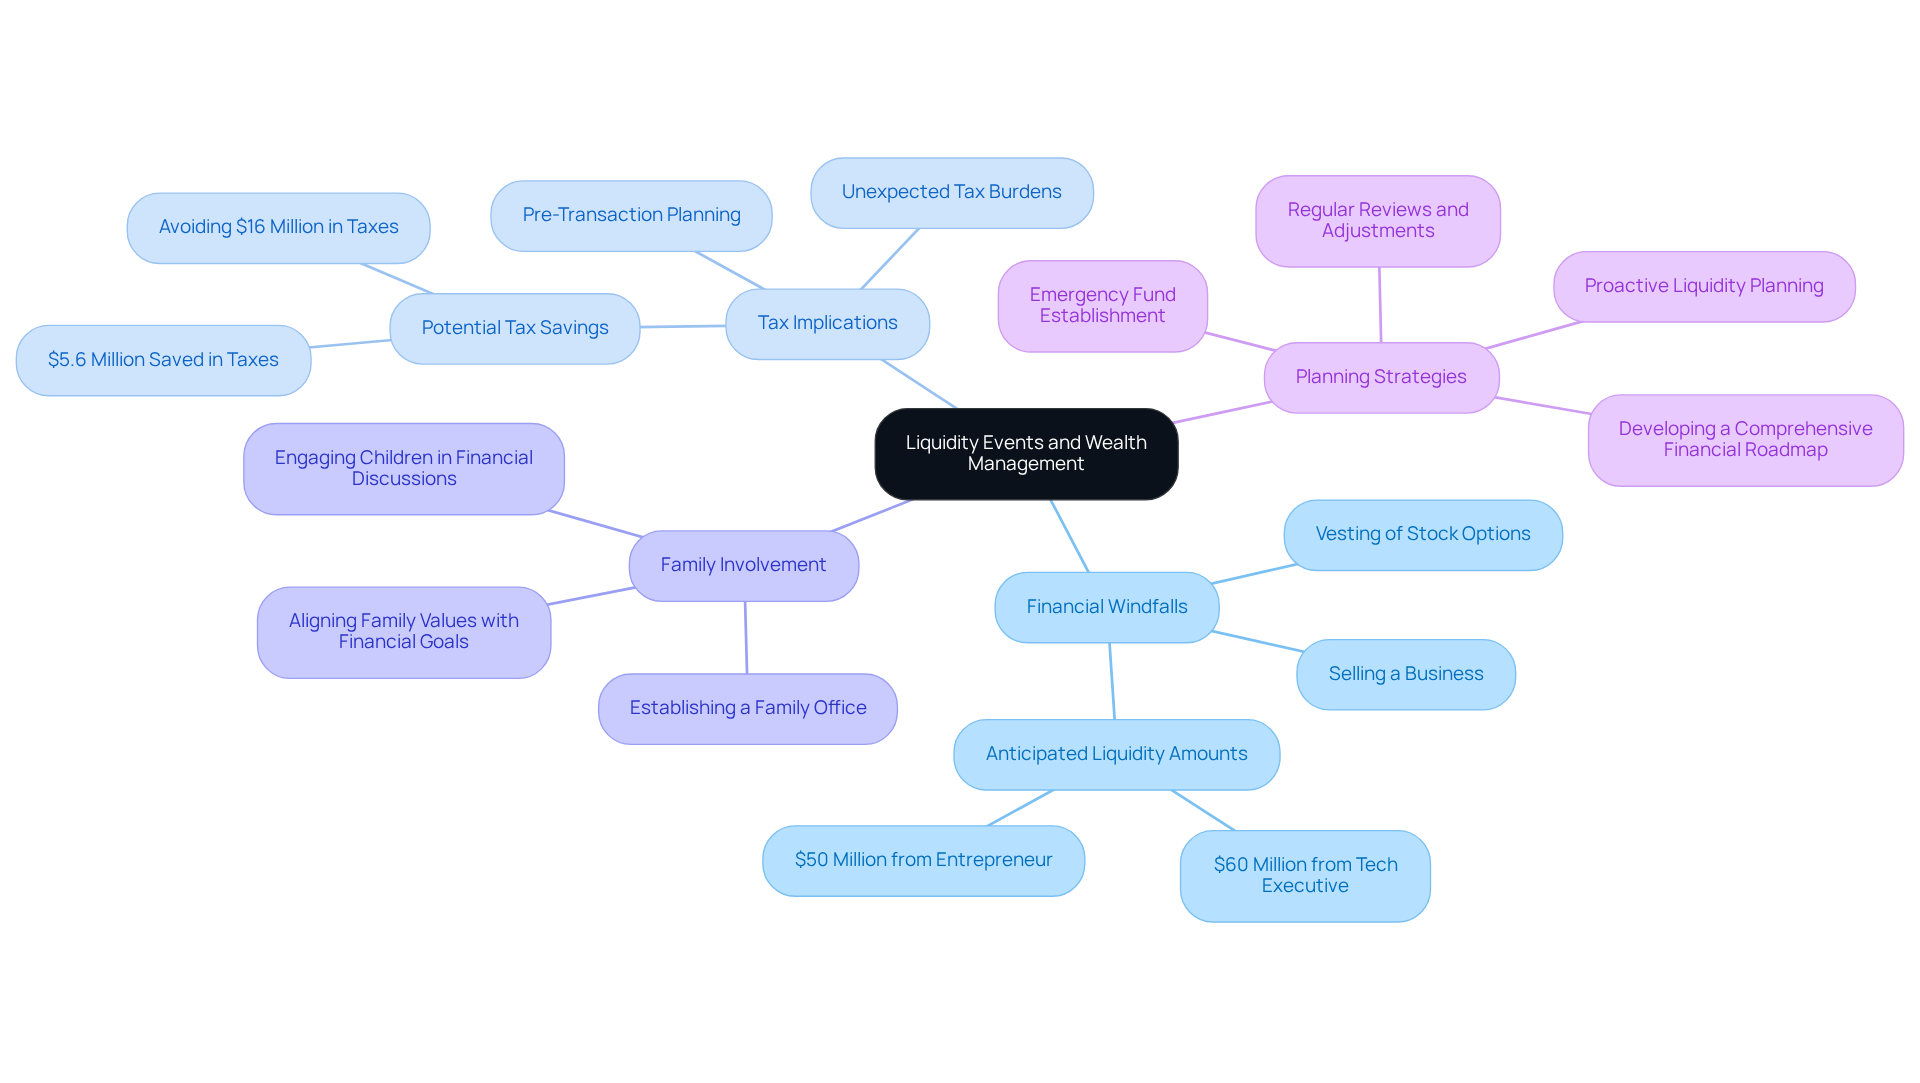
Imagine receiving a life-changing financial windfall, only to feel overwhelmed by the decisions that come with it. Liquidity events, such as the vesting of stock options or selling a business, can generate significant funds, but they also come with challenges, including understanding taxes and developing a liquidity after vesting diversification strategy for future planning. It can be overwhelming to navigate the complexities of liquidity events, especially when they involve significant financial decisions.
Think about a family that suddenly finds themselves with a large sum of money from a liquidity event. Without proper guidance, families might find themselves facing unexpected tax burdens that could impact their financial future. Getting organized ahead of time is so important. It’s wise for families to start planning a few years before a liquidity event to make the most of their new wealth.
Bringing kids into the conversation helps them learn about money and keeps family values at the forefront. This way, everyone can work together to ensure that the family’s financial goals align with their values. Setting up a personal office can really help manage the new challenges that come with a big financial change. With the right support and planning, you can turn these challenges into opportunities for your family’s future.
Implement Diversification Strategies to Enhance Financial Stability
Imagine facing a sudden financial windfall and wondering how to protect your family’s future. After a liquidity event, many families feel uncertain about how to secure their financial stability. Here are some gentle strategies to consider that can help you navigate this journey with confidence.
-
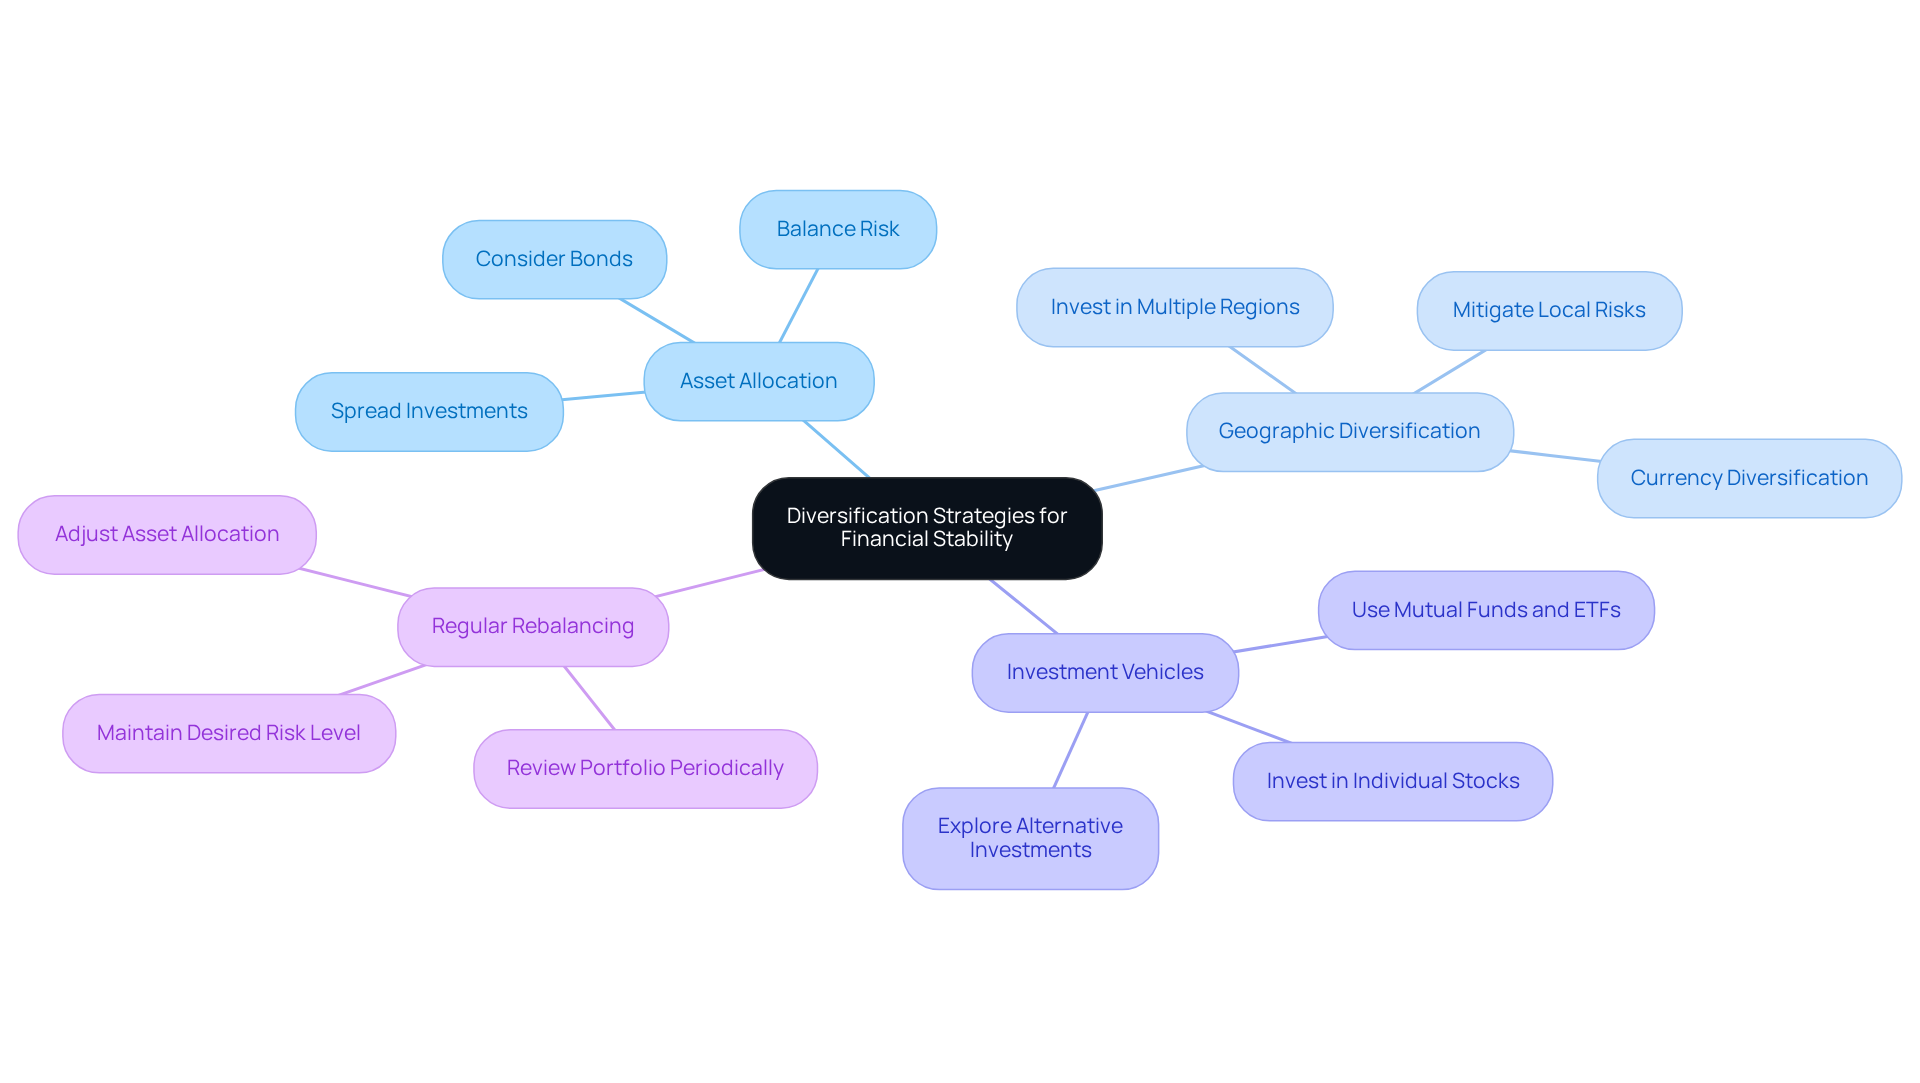
Asset Allocation: It’s important for families to think about spreading their investments across different areas, like stocks, bonds, real estate, and alternative investments. This balanced approach helps reduce risks associated with market ups and downs, ensuring your family’s wealth is managed wisely.
-
Geographic Diversification: Investing in various regions can shield your family from local economic downturns. By exploring opportunities both at home and abroad, you can lessen the risks tied to any single economy, giving you peace of mind.
-
Investment Vehicles: Utilizing a mix of investment options, such as mutual funds, ETFs, and individual stocks, allows families to tap into different sectors and industries. This not only spreads risk but also enhances the potential for returns, no matter the market conditions.
-
Regular Rebalancing: It’s essential for families to routinely review and adjust their portfolios to keep their desired asset allocation. This practice ensures that you’re not overly concentrated in any one investment or sector, which is crucial for long-term financial health.
By embracing these strategies, families can feel empowered to take control of their financial future, knowing they’re not alone in this journey. Together, we can navigate these important decisions and work towards a more secure tomorrow.
Engage in Continuous Financial Education and Strategic Planning
Many families feel lost when it comes to managing newfound wealth, especially after a liquidity event. Participating in ongoing monetary education is essential for households. Here are some strategies to consider:
-
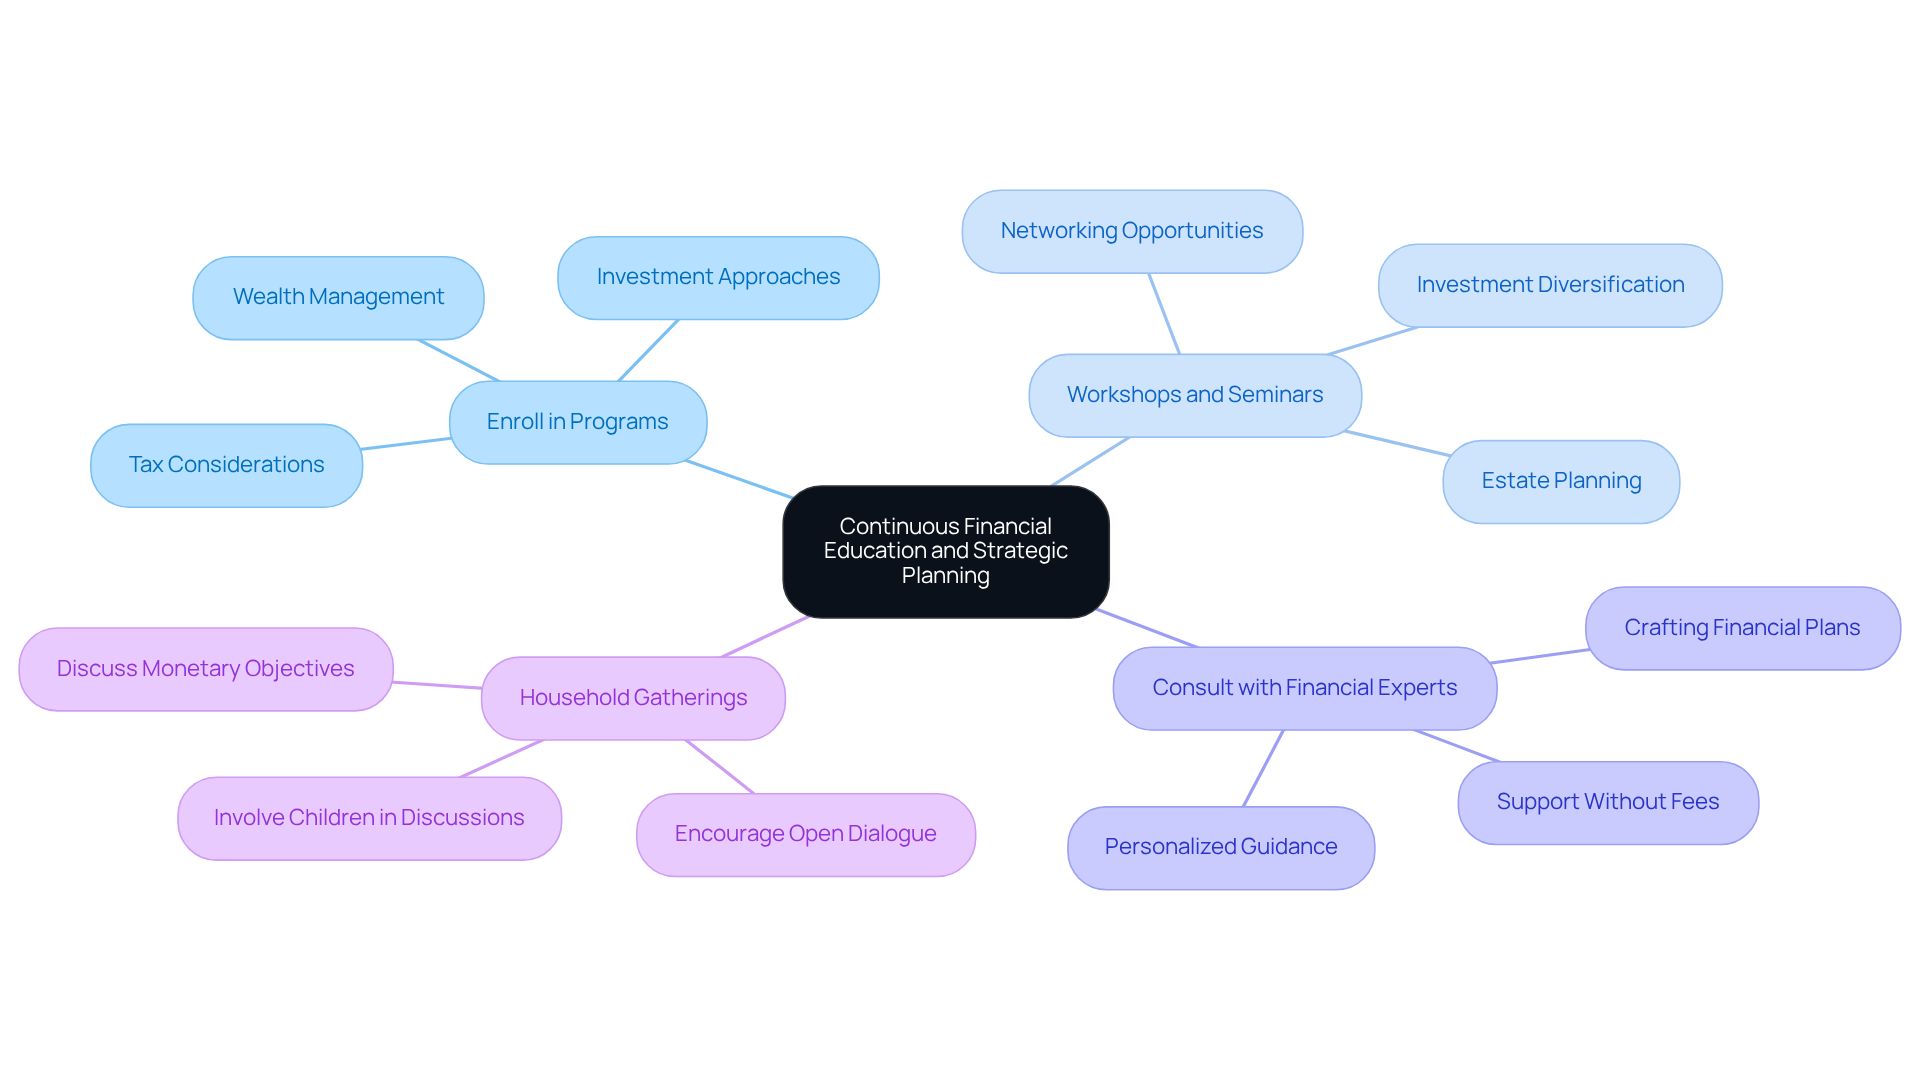
Enroll in Programs: Look for programs that emphasize wealth management, investment approaches, and tax considerations. These can provide the knowledge needed to make informed decisions. Research shows that states requiring personal finance education have higher savings rates among graduates, proving the effectiveness of such programs.
-
Workshops and Seminars: Imagine connecting with others who share your financial goals and learning from experts who understand your journey. Attending workshops and seminars on topics like estate planning and investment diversification can offer valuable insights and networking opportunities. For instance, individuals participating in employer-sponsored retirement seminars saw a nearly 27% rise in net worth, highlighting the significance of focused economic education.
-
Consult with Financial Experts: Regularly seek advice from financial experts who can offer personalized guidance based on your household’s unique economic situation. We work hand-in-hand with families to craft financial plans that reflect their values. Our personalized approach ensures you get the support you need without unnecessary fees.
-
Household Gatherings: Conduct regular household gatherings to discuss monetary objectives, principles, and tactics. This practice encourages open dialogue and ensures that all household members are united in their monetary strategies. Involving children in these discussions can also improve their understanding of money management. Research indicates that teenagers who learn about handling accounts are more likely to open them and save.
By emphasizing ongoing monetary education and implementing a liquidity after vesting diversification strategy, households can navigate the intricacies of asset management more effectively. Without the right guidance, financial stress can overshadow the joy of newfound opportunities. For instance, Jay and Emma, a household supported by Bright Advisers, successfully developed a robust strategy that included enhanced tax management and a personalized retirement approach. This method not only reduced their monetary stress but also enabled them to distribute their resources efficiently, ensuring they are well-prepared for upcoming economic obstacles. With the right support and education, you can turn financial uncertainty into a path toward a secure future for your family.
Adopt Personalized Financial Planning for Tailored Wealth Management
Imagine facing a sudden change in your financial situation and feeling overwhelmed by the choices ahead. Customized wealth management is essential for households to efficiently oversee their assets, especially when applying a liquidity after vesting diversification strategy after a liquidity event. Families should consider the following steps:
-
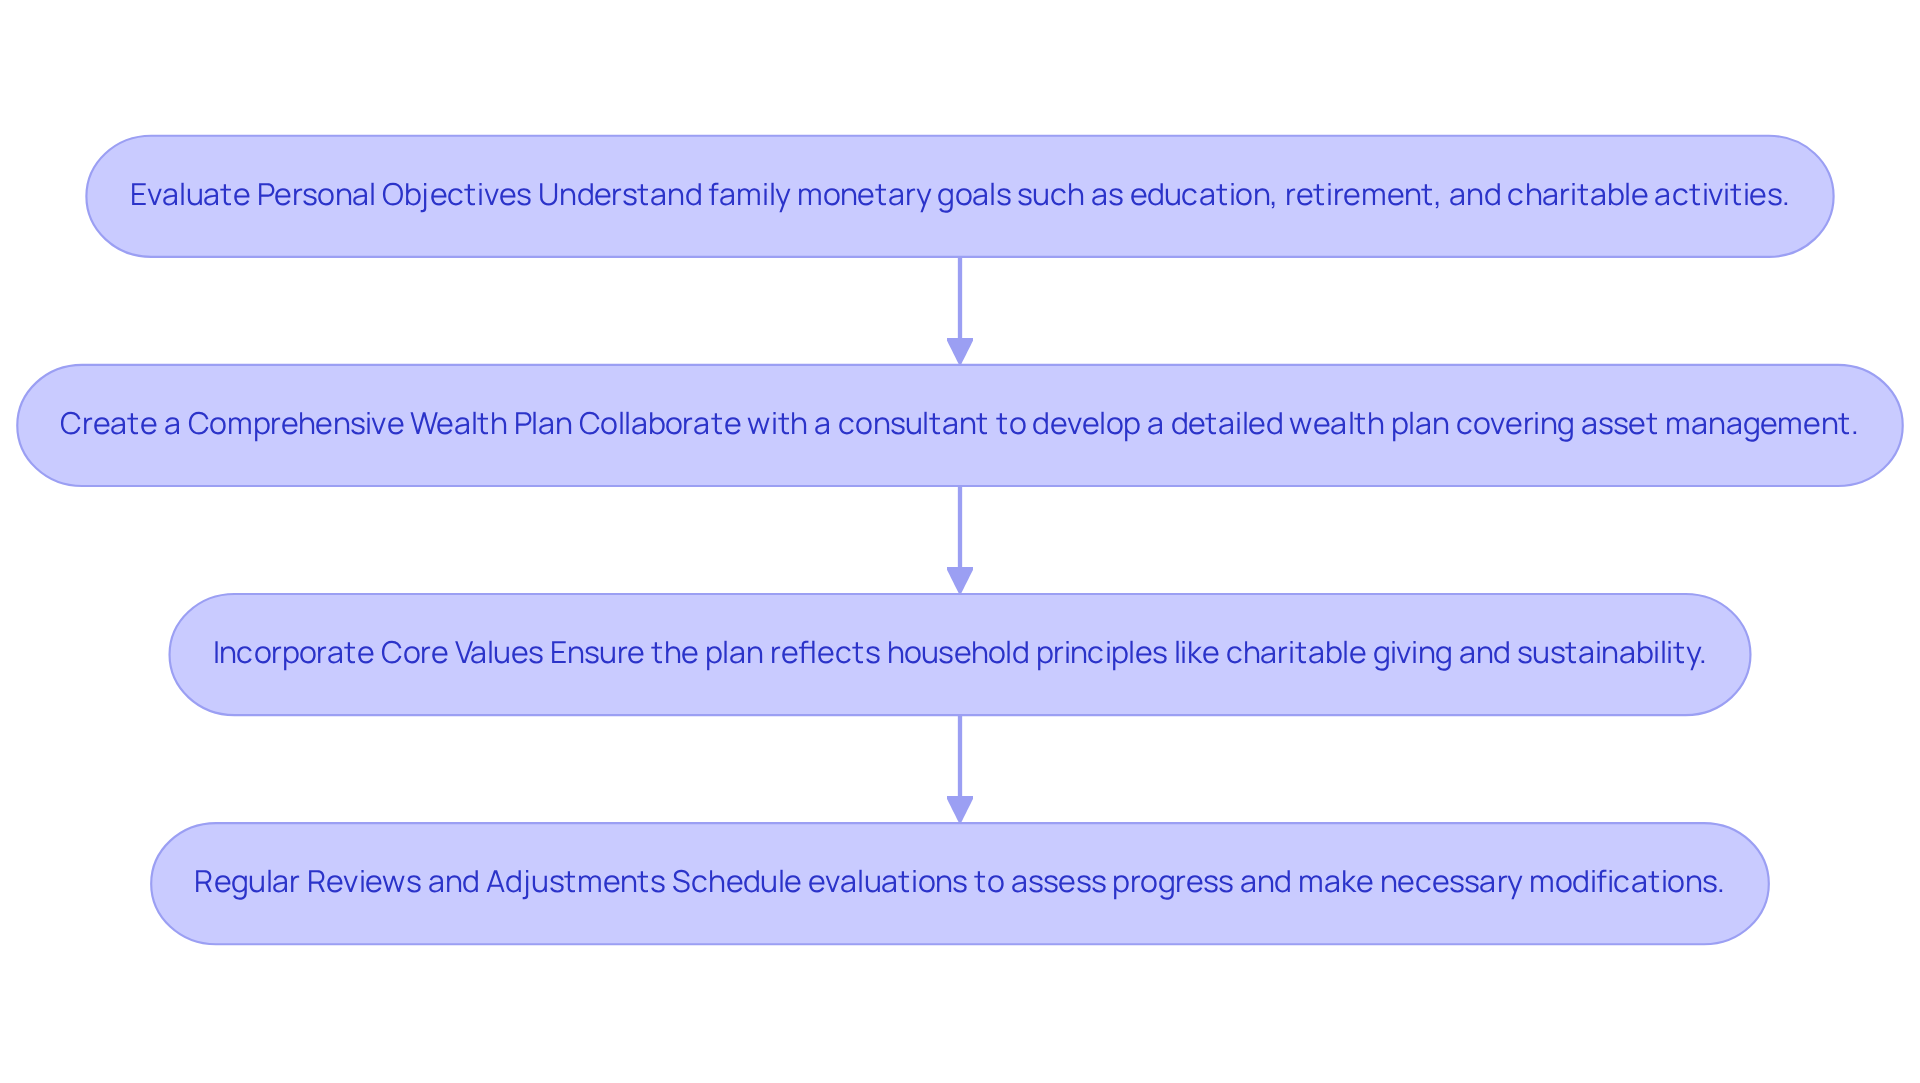
Evaluate Personal Objectives: It’s important for each family member to express their monetary goals. Whether it’s saving for children’s education, preparing for retirement, or engaging in charitable activities, understanding what matters most to your family is the first step in creating a money plan that truly fits your needs.
-
Create a Comprehensive Wealth Plan: Collaborate with a consultant to develop a detailed wealth plan that covers all aspects of asset management, including investment strategies, tax preparation, and estate organization. Bright Advisers emphasizes innovative strategies like factor investing and smart beta techniques to build personalized portfolios. This plan needs to be flexible, so you can adjust it as your life changes.
-
Incorporate Core Values: Ensure that your monetary plan reflects your household’s essential principles and priorities. This might include considerations for charitable giving, sustainability, or supporting local businesses. Aligning your financial choices with your family values can enhance satisfaction and commitment to the plan.
-
Regular Reviews and Adjustments: Schedule consistent evaluations of your plan to assess progress and make necessary modifications. This approach helps ensure that your strategy remains relevant and effective in achieving your family’s financial objectives.
By embracing tailored wealth management, families can gain clarity and confidence in their financial decisions. Statistics show that households with a budget plan are 2.5 times more likely to save sufficiently for retirement, highlighting the significance of a structured approach to money management. Moreover, families that engage in consistent financial planning express greater confidence about their financial futures. In fact, 83% of individuals who set financial goals feel more positive about their finances within a year.
For instance, through their collaboration with Bright Advisers, families like Allison and Brian have successfully optimized their tax situation and secured their children’s future through education funding. Similarly, Emily and Mark gained the freedom to choose whether to continue working by implementing strategies to manage cash flow and plan for retirement. This research highlights how financial planning can empower families to take control of their futures, emphasizing the value of receiving assistance from a financial professional who prioritizes clients’ best interests.
Conclusion
Imagine feeling overwhelmed by financial decisions after a liquidity event, unsure of how to secure your family’s future. But with the right strategies, you can find stability and peace of mind. By spreading your investments across different areas and types, you can reduce risks and build a stronger financial future for your family. Regularly checking in on your investments helps ensure they align with your goals, giving you confidence during uncertain times.
It’s so important to keep learning about finances, especially as your family grows and changes. Engaging in workshops and discussions with financial experts can empower you to make informed choices. Talking openly about your financial goals with your family creates a supportive environment where everyone is on the same page. This proactive approach not only eases stress but also helps you embrace your financial future with confidence.
Personalized financial planning is key to helping your family find their way after a liquidity event. By assessing your unique goals and values, you can create a plan that truly reflects your family’s needs. Regularly reviewing and adjusting your plan ensures it stays relevant and effective. With the right support, you can turn financial uncertainty into a journey of empowerment for your family. Embracing these practices will not only enhance your financial literacy but also create a legacy of informed decision-making for generations to come.
Frequently Asked Questions
What is a liquidity event?
A liquidity event refers to a significant financial occurrence, such as the vesting of stock options or the sale of a business, that generates a substantial amount of money.
What challenges do liquidity events present?
Liquidity events can lead to challenges such as understanding tax implications and developing a diversification strategy for future financial planning.
Why is it important to plan ahead for a liquidity event?
Planning ahead is crucial because it helps families manage potential tax burdens and make informed decisions about their newfound wealth, ensuring they maximize the benefits of the liquidity event.
How can families prepare for a liquidity event?
Families should start planning a few years before a liquidity event, which includes organizing their finances and discussing their financial goals and values together.
What role do children play in discussions about liquidity events?
Involving children in conversations about money helps them learn financial literacy and ensures that family values are considered in financial decision-making.
What is the benefit of setting up a personal office after a liquidity event?
Establishing a personal office can help families manage the complexities and challenges that arise from a significant financial change, providing support and guidance for future planning.
List of Sources
- Understand Liquidity Events and Their Impact on Wealth Management
- Liquidity Event Wealth Management FAQ (https://caprock.com/liquidity-event-wealth-management-faq)
- Financial Planning Following a Liquidity Event | William Blair (https://williamblair.com/Insights/Financial-Planning-Following-a-Liquidity-Event)
- Financial Planning After a Liquidity Event – Evercore Wealth Management (https://evercorewealthandtrust.com/liquidity-event-financial-planning)
- The advantages of proactive planning for liquidity events (https://crainscleveland.com/crains-content-studio/wealth-management-guide/2026/ccl-clearstead-wealth-management-planning-liquidity)
- A Guide to Preparing for Wealth Transfer – Merrill (https://ml.com/articles/prepare-for-wealth-transfer.html)
- Implement Diversification Strategies to Enhance Financial Stability
- Eight Great Investing Quotes Worth Remembering | Stone Oak Wealth (https://stoneoakwealth.com/eight-great-investing-quotes)
- Investment portfolios: Asset allocation models | Vanguard (https://investor.vanguard.com/investor-resources-education/education/model-portfolio-allocation)
- Benefits of Geographic Diversification for Financial Stability – Oceanside Advisors (https://oceansideadvisors.com/benefits-of-geographic-diversification-for-financial-stability-2)
- Global Household Asset Allocation Trends (https://linkedin.com/top-content/workplace-trends/trends-in-financial-markets/global-household-asset-allocation-trends)
- Quotes and Advises from world’s best investors and wealthy (https://millswealthadvisors.com/all-quotes)
- Engage in Continuous Financial Education and Strategic Planning
- Financial Literacy Statistics (https://financialeducatorscouncil.org/financial-literacy-statistics)
- Financial Literacy Statistics (2026) (https://wallethub.com/edu/b/financial-literacy-statistics/25534)
- 40 Financial Literacy Statistics in the United States – Intuit Blog (https://intuit.com/blog/innovative-thinking/financial-tips/financial-literacy-statistics)
- Financial Literacy Data Insights (https://ifdm.stanford.edu/data-financial-literacy)
- Can you answer these 3 questions about your finances? The majority of US adults cannot (https://weforum.org/stories/2024/04/financial-literacy-money-education)
- Adopt Personalized Financial Planning for Tailored Wealth Management
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- Family Savings Goals: By the Numbers (https://bankwithunited.com/thrive-home/family-saving-goals-by-the-numbers.html)
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- Article – New Research Shows Most American Households Do Financial Planning, But the Extent of This Planning Varies Greatly | Consumer Federation of America (https://consumerfed.org/news/press-releases/new-research-shows-most-american-households-do-financial-planning-but-the-extent-of-this-planning-varies-greatly)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading