

Key Highlights
- Restricted Stock Units (RSUs) are valuable assets that can significantly impact a family’s financial future once they vest.
- Families must understand the tax implications of RSUs, as they can lead to unexpected tax burdens, especially in high-tax states like California and New York.
- Implementing a liquidity after vesting tax strategy, such as selling a portion of vested RSUs, can help families manage tax obligations and improve cash flow.
- Using tax-advantaged accounts like 401(k)s or HSAs can mitigate the tax impact of RSUs.
- Establishing a consistent plan for selling RSUs can reduce financial stress and ensure liquidity when needed.
- Aligning RSU management with long-term financial goals, such as retirement and education funding, is crucial for families.
- Diversifying investments by reallocating a portion of RSUs into a balanced portfolio can enhance financial stability and reduce risk.
- Engaging with a fiduciary advisor, like Bright Advisers, can provide families with the guidance needed to make informed financial decisions.
Introduction
Imagine the moment when your Restricted Stock Units (RSUs) vest, bringing both excitement and uncertainty for your family’s financial future. Understanding how these units work is essential for families like yours, as they can significantly impact your income and tax obligations. Picture this: you’re excited about the potential boost to your finances, but then you realize it could lead to unexpected challenges.
In this article, we’ll explore some key strategies to help your family navigate the liquidity and tax implications of RSUs, ensuring you’re on the right path to achieving your financial dreams. It’s important to understand how to manage these assets effectively, so you can align them with your long-term goals.
Together, we can navigate these challenges and ensure your family is not just prepared for tax consequences but also ready to thrive financially after these vesting events.
Define Restricted Stock Units (RSUs) and Their Importance for Families
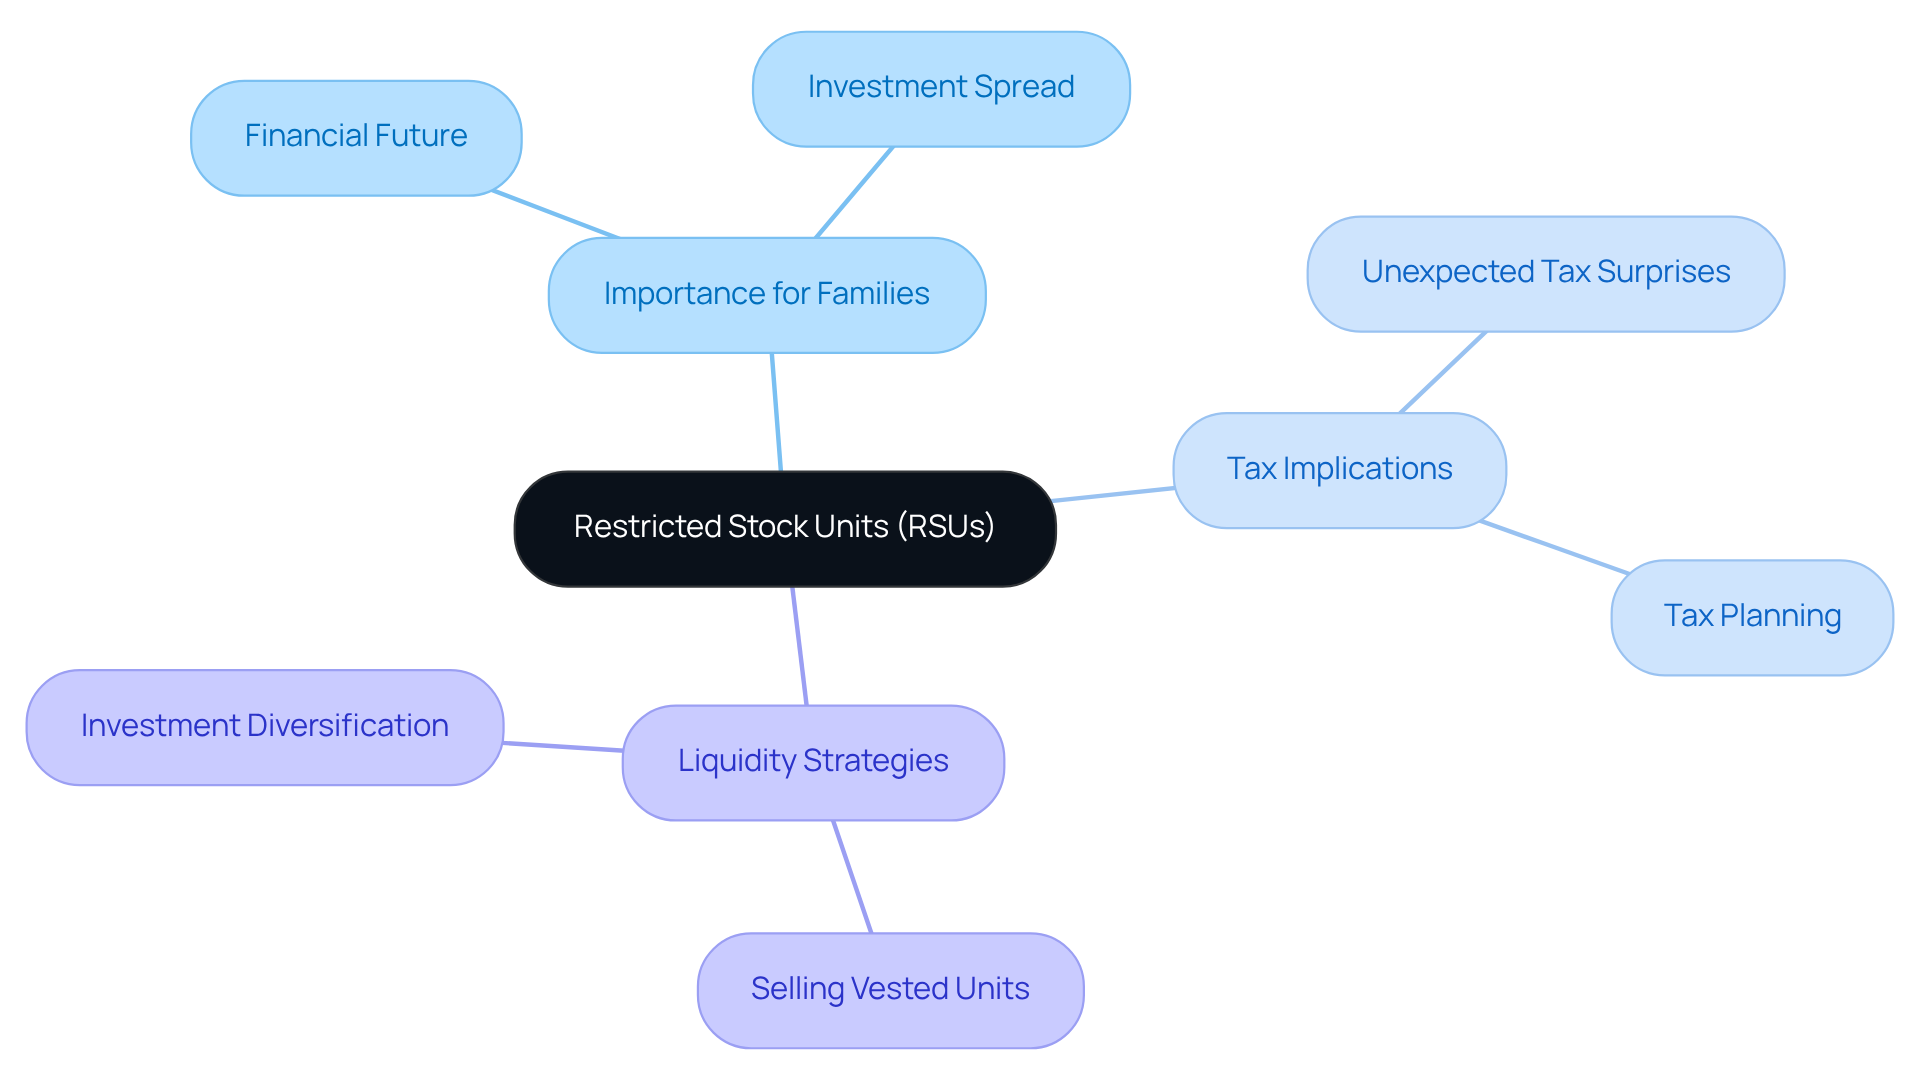
Imagine receiving a valuable gift from your employer, but not fully understanding how it impacts your family’s financial future. Restricted Stock Units (RSUs) can feel like a treasure, promising to reward you with shares, but only after meeting certain milestones. It’s essential for families to grasp these units, as they can significantly influence your financial journey together.
When these units vest, they become part of your income, which can bring unexpected tax surprises for your family, making a liquidity after vesting tax strategy essential. Navigating the tax implications of restricted stock units can feel overwhelming, especially when you’re trying to implement a liquidity after vesting tax strategy to secure your family’s future. It’s vital for families to weave these units into their financial plans, preparing for any tax surprises and maximizing their liquidity after vesting tax strategy.
Many families find that selling a part of their vested units helps them spread their investments, reducing risks and securing their future. Understanding these units not only aids in tax planning but empowers families to make informed choices for a brighter financial future. Together, we can navigate this journey and ensure your family’s financial well-being.
Explore RSU Tax Implications and Strategies for Families
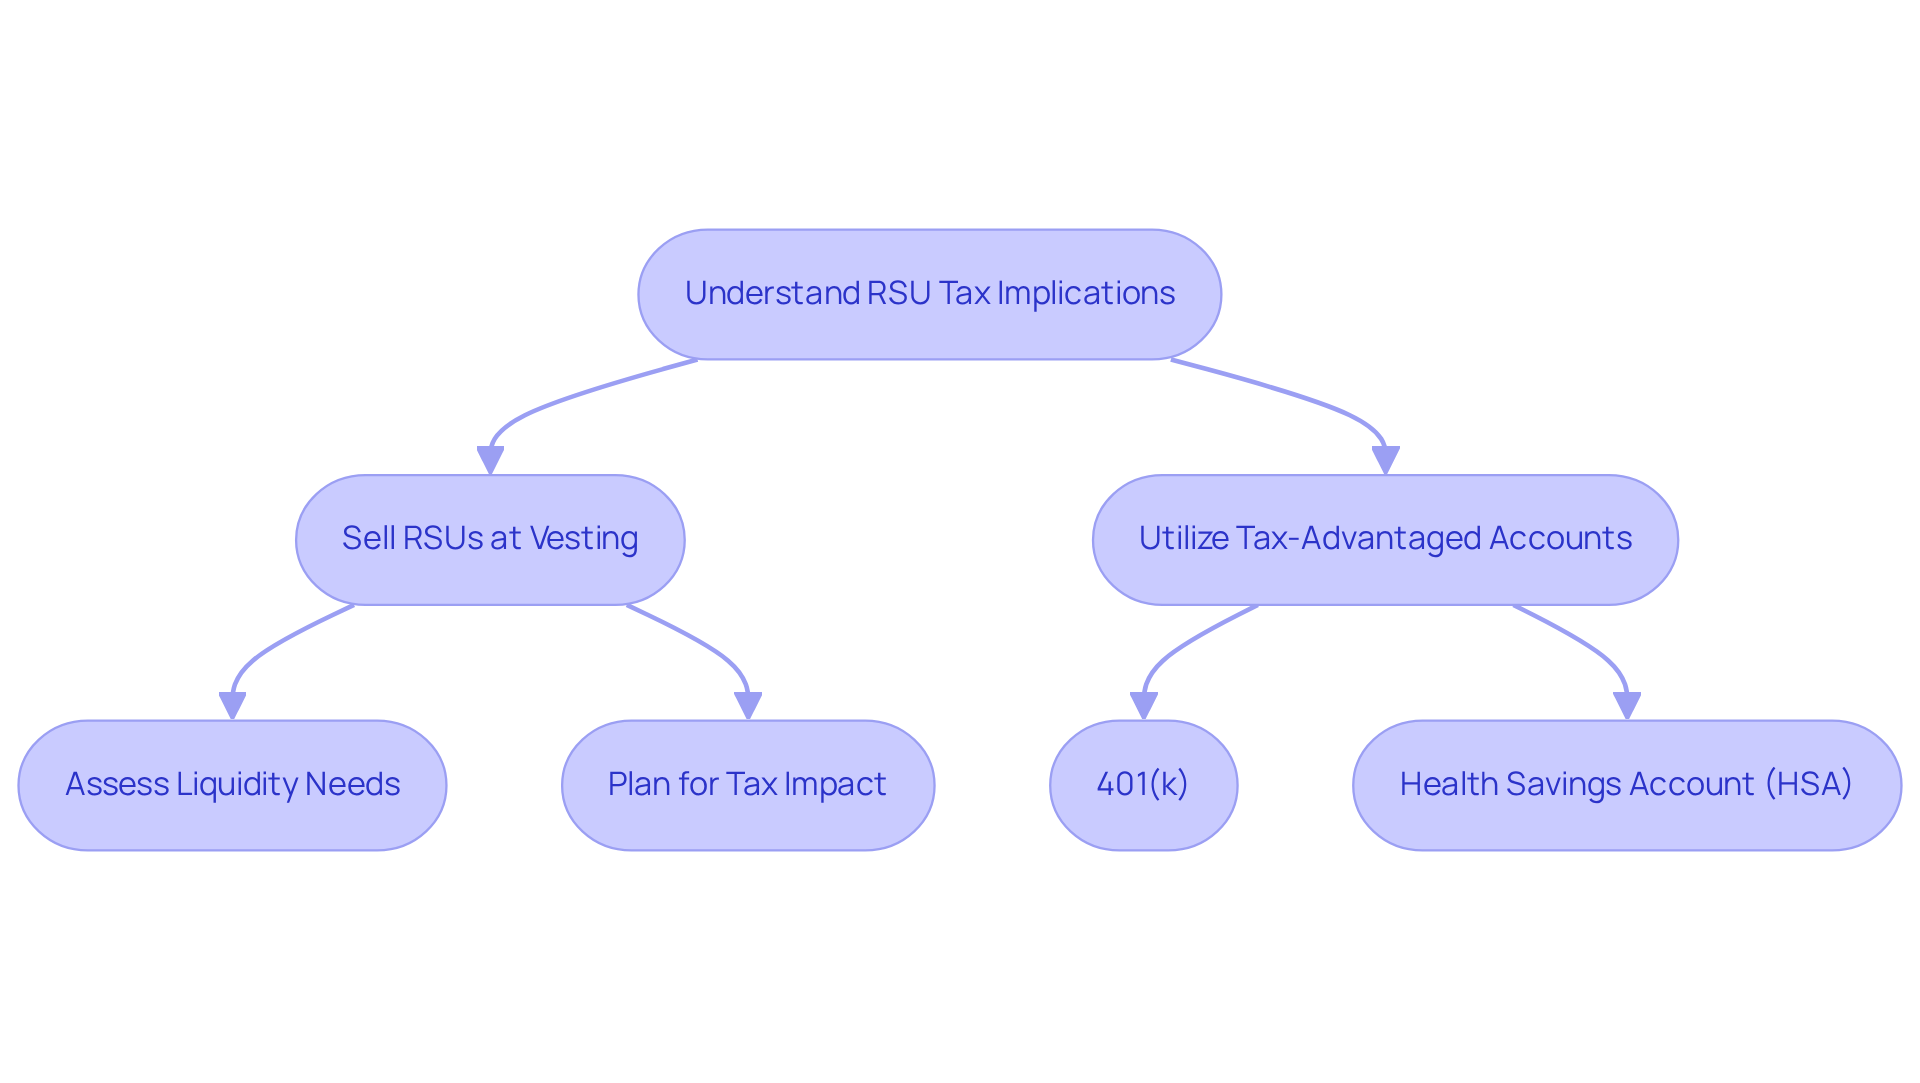
Imagine facing a hefty tax bill just when you thought you were making progress with your finances. In high-tax states like California and New York, this can feel especially overwhelming for families. It’s important to understand that this tax burden can be a lot to handle, and planning ahead can make a big difference.
One option families might explore is selling a part of their restricted stock units right when they vest as a liquidity after vesting tax strategy to help cover those tax bills. You might also consider tax-advantaged accounts like 401(k)s or Health Savings Accounts (HSAs) to help ease some of the tax impact. These accounts can provide valuable benefits for your family.
Thinking ahead about when to sell your restricted stock units can help you manage your taxes better, especially when considering your liquidity after vesting tax strategy during years when your income might be lower. Families who work together to align their RSU strategies with their overall financial plans often discover that a liquidity after vesting tax strategy can help lighten their tax load and improve their cash flow.
By taking proactive steps today, you can ease the financial burden tomorrow and focus on what truly matters-your family.
Implement Effective Liquidity Strategies After RSU Vesting
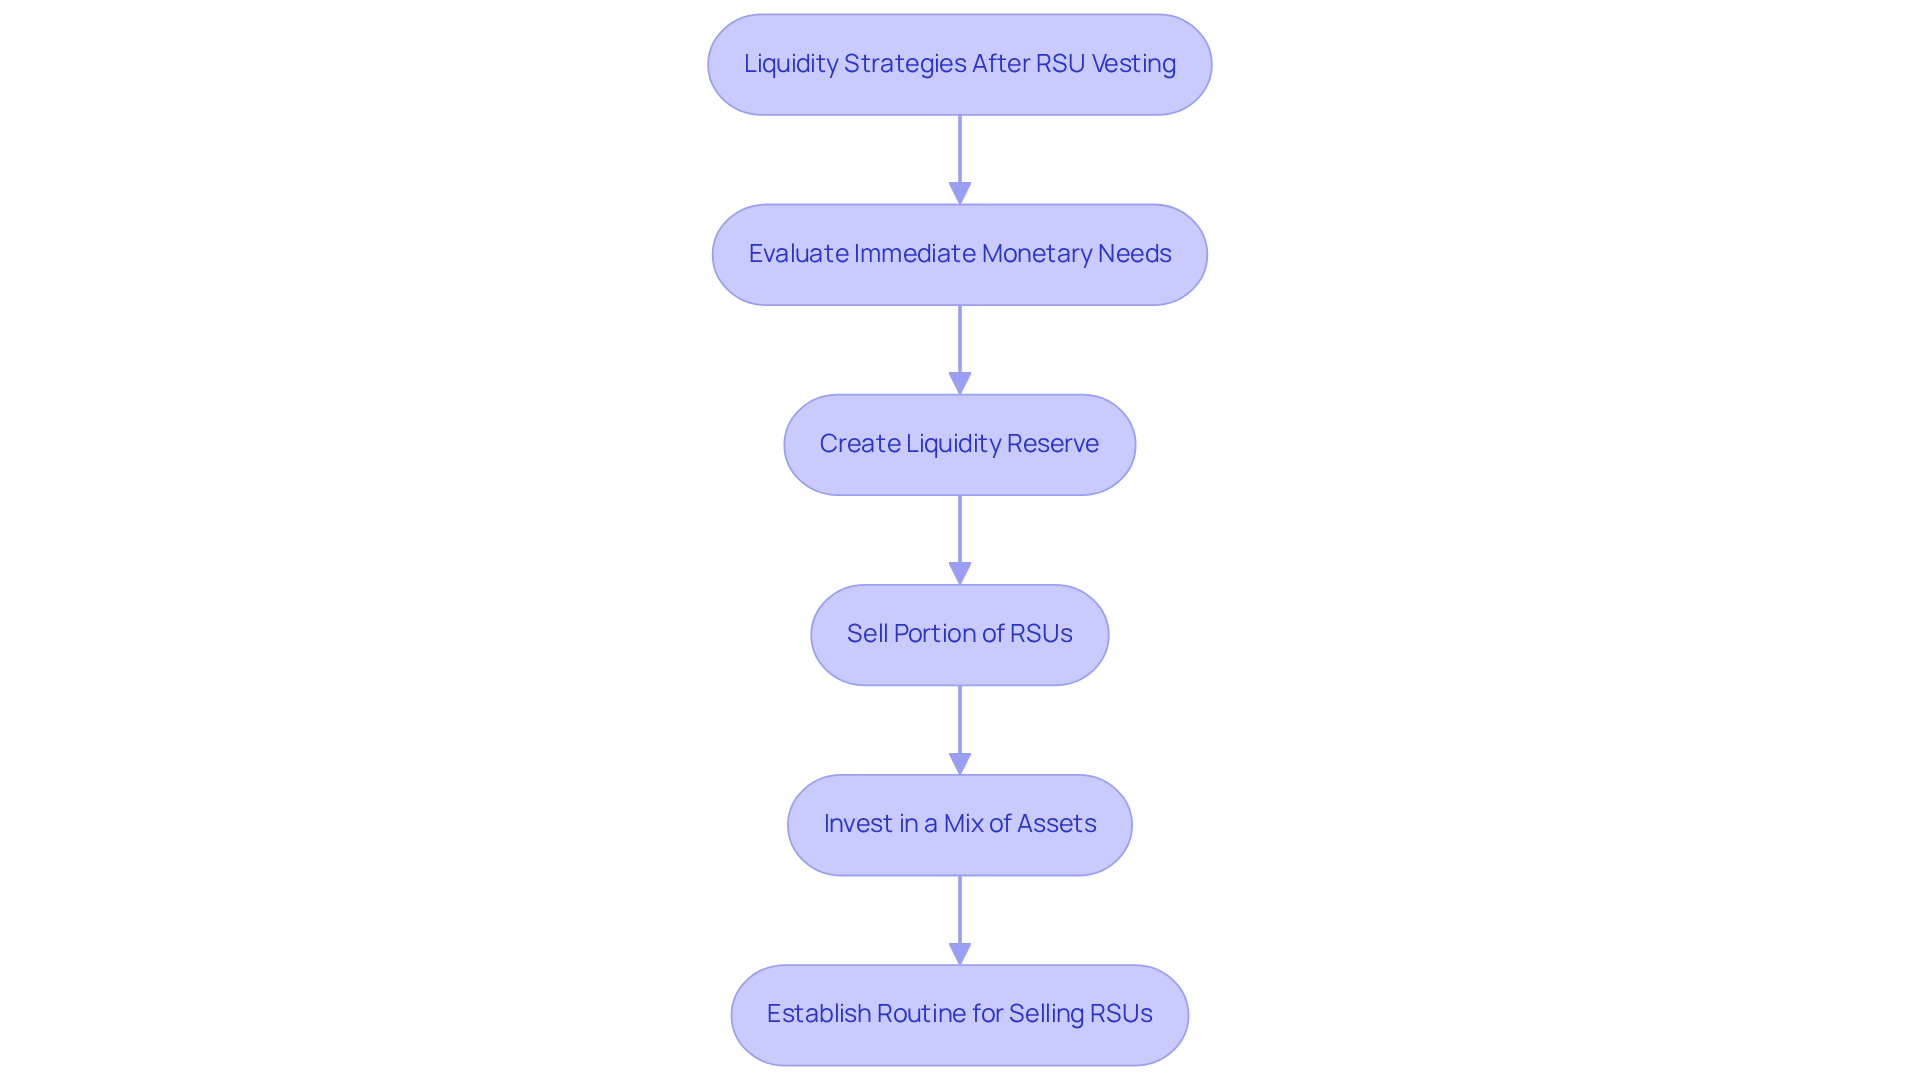
Imagine the relief of knowing you’re prepared for the tax obligations that come with your restricted stock units vesting. After your restricted stock units vest, it’s important to think about a liquidity after vesting tax strategy to manage those tax obligations. One gentle approach is to create a liquidity reserve before your RSUs vest, which can be funded through savings or by selling a portion of the RSUs as they vest. Consider evaluating your immediate monetary needs, like funding your children’s education or paying down debt, when deciding how much to sell.
Using some of the proceeds from RSU sales to invest in a mix of assets can support your family’s long-term stability while addressing short-term liquidity needs. Having a consistent plan for selling your equity awards can help reduce stress and create a steady flow of funds. For instance, establishing a routine for selling a portion of your restricted stock units each time they vest can simplify your financial planning and ensure that liquidity is available when you need it.
It’s also wise to think about how you might allocate your restricted stock units in the future, as this can offer further benefits and influence your current selling choices. It’s important to grasp the tax implications of selling your RSUs, as the standard withholding rate might not cover everything for high earners, potentially leading to unexpected tax burdens. By proactively assessing your monetary situation and establishing a clear liquidity after vesting tax strategy, you can effectively manage your liquidity needs following RSU vesting. By taking these steps, you can ensure your family’s financial future is secure and stress-free.
Align RSU Management with Long-Term Financial Goals
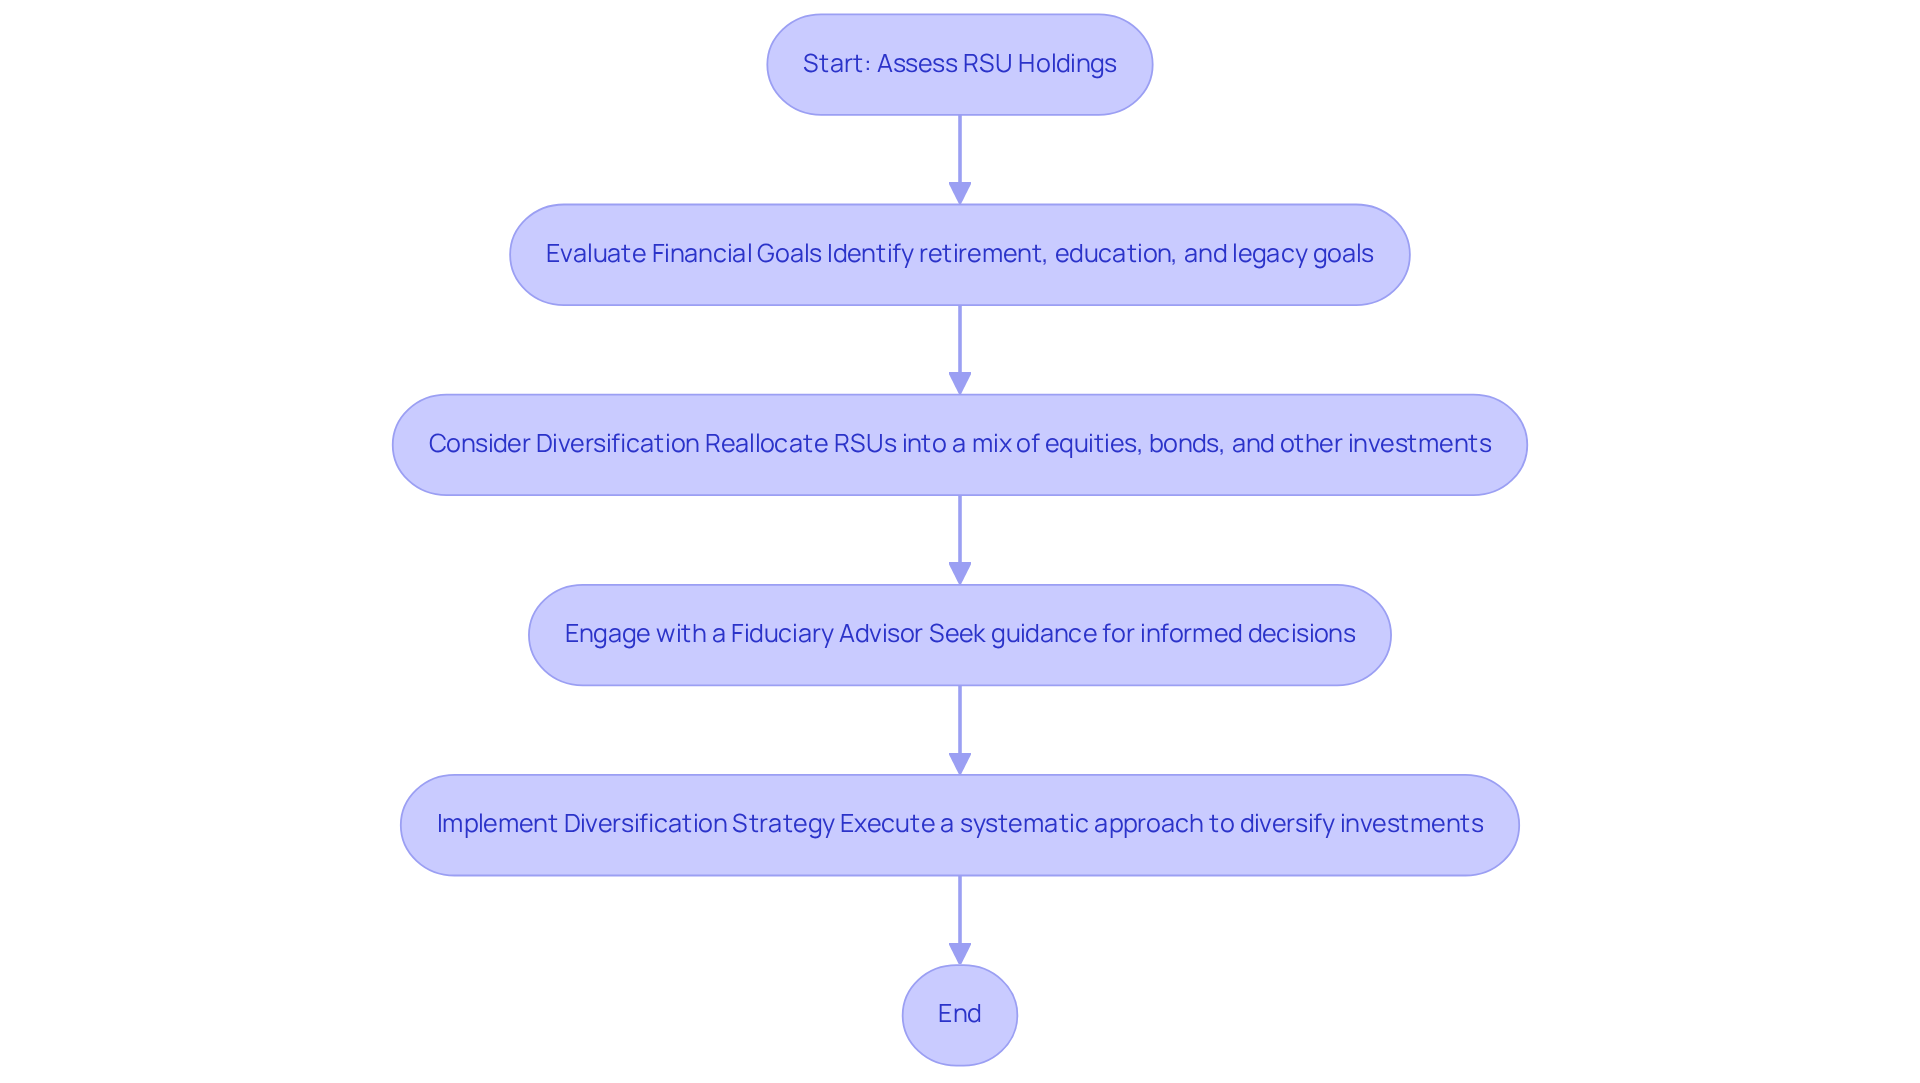
Navigating the world of Restricted Stock Units can feel daunting, especially when balancing family priorities and financial goals. To effectively manage RSUs, it’s important to think about how your restricted stock units fit into your overall investment picture. Aligning your strategy with long-term objectives, like retirement planning, funding education, or creating a legacy, can make a significant difference. Diversifying your investments is crucial to mitigate the risks associated with holding a concentrated position in company stock. Consider reallocating a portion of your RSUs into a mix of equities, bonds, and other investments to enhance your family’s financial stability.
Taking the time to review and adjust your financial plan can help ensure your RSUs are working for you as your life changes. It’s important to understand that engaging with a caring fiduciary advisor, like Bright Advisers, can help you feel more confident as you navigate these important decisions. They can provide the guidance you need to make informed choices that align with your family’s values.
Let’s look at a story that shows how this approach can really make a difference. A household with substantial RSU holdings successfully executed a systematic diversification strategy, selling a portion of their shares at each vesting event and reinvesting the proceeds into a balanced portfolio, all while managing their liquidity after vesting tax strategy. This approach not only diminished their exposure to market fluctuations but also aligned their investments with their long-term monetary goals.
When you take charge of your RSUs and weave them into a thoughtful financial plan, you can feel empowered to build a future that reflects your family’s values and dreams. Together, we can ensure that your financial decisions support your family’s dreams and pave the way for a brighter future.
Conclusion
Imagine the relief of understanding how Restricted Stock Units (RSUs) can work for your family’s financial future. When your RSUs vest, they can affect your family’s income and taxes. It’s important to have a plan in place to manage this. Planning ahead for taxes and aligning your RSU management with your family’s goals can help you feel more confident in navigating these complexities.
It’s wise to consider selling some of your vested RSUs to cover taxes and improve your cash flow. Think about using tax-friendly accounts and spreading out your investments to reduce risks with concentrated stocks. Working with a trusted advisor, like Bright Advisers, can help you create a financial plan that truly reflects your family’s values and dreams.
When you take charge of your RSUs, you’re not just easing today’s worries; you’re paving the way for your family’s dreams tomorrow. By planning carefully and including your RSUs in your overall financial strategy, you can make sure your choices support your family’s long-term dreams. Taking these steps means you’re not just managing finances; you’re nurturing your family’s future together.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of compensation offered by employers that promise to reward employees with shares of stock after certain milestones are met.
Why are RSUs important for families?
RSUs can significantly influence a family’s financial future, as they become part of the family’s income once they vest, potentially leading to unexpected tax implications.
What happens when RSUs vest?
When RSUs vest, they convert into shares of stock, which then become part of the employee’s income and may trigger tax liabilities.
What is a liquidity after vesting tax strategy?
A liquidity after vesting tax strategy is a financial plan that helps families manage the tax implications of RSUs after they vest, ensuring they have sufficient liquidity to cover any tax surprises.
How can families manage the risks associated with RSUs?
Many families choose to sell a portion of their vested RSUs to diversify their investments, which can help reduce risks and secure their financial future.
How can understanding RSUs aid in tax planning?
Understanding RSUs allows families to prepare for potential tax liabilities and make informed financial decisions, ultimately contributing to a brighter financial future.
List of Sources
- Define Restricted Stock Units (RSUs) and Their Importance for Families
- Financial Planning With Restricted Stock Units: 3 Key Questions | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/restricted-stock-units-and-financial-planning)
- RSUs: Balancing Opportunity and Risk in Modern Compensation (https://resilientplanning.com/blog/rsus-balancing-opportunity-and-risk-in-modern-compensation)
- RSUs Are Income, Not Magic: How to Think About Your Restricted Stock Units (https://savantwealth.com/savant-views-news/article/rsus-are-income-not-magic-how-to-think-about-your-restricted-stock-units)
- Restricted Stock Units: 6 Tax And Financial-Planning Strategies (https://forbes.com/sites/brucebrumberg/2025/07/01/restricted-stock-units-6-tax-and-financial-planning-strategies)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- Explore RSU Tax Implications and Strategies for Families
- The Hidden Tax Time Bomb in Your RSU Grants: California Edition – Mission Street Wealth (https://missionstreetwealth.com/california-rsu-taxation-the-hidden-tax-time-bomb)
- US state tax RSU optimization guide 2026 (https://vested.blog/posts/us-state-tax-optimization-rsu-holders-2026)
- RSU Tax Guide 2026: How Restricted Stock Units Are Taxed, the Withholding Gap, and What to Do About It (https://countrytaxcalc.com/tax-guides/rsu-tax-guide-2026)
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- How Restricted Stock Units (RSUs) Are Taxed | Lido Advisors (https://lidoadvisors.com/perspectives/tax-consulting-preparation/rsu-tax-guide-how-restricted-stock-units-are-taxed)
- Implement Effective Liquidity Strategies After RSU Vesting
- Managing RSUs and Stock Options: A Tax-Efficient Strategy for Executives and High-Income Professionals – True Wealth Design (https://truewealthdesign.com/managing-rsus-and-stock-options)
- Should I Sell or Hold My RSUs? Key Factors to Consider. (https://usecache.com/companion/when-to-sell-rsu-stock)
- Selling RSUs Is a Long-Term Wealth Strategy (https://brightonjones.com/blog/selling-rsus)
- Sell or Stay? Thinking Strategically About Vested RSUs (https://wealthspire.com/blog/sell-or-stay-thinking-strategically-about-vested-rsus)
- Align RSU Management with Long-Term Financial Goals
- Managing RSUs and Stock Options: A Tax-Efficient Strategy for Executives and High-Income Professionals – True Wealth Design (https://truewealthdesign.com/managing-rsus-and-stock-options)
- RSU Tax Planning: 5 Proven Strategies For 2026 (https://tdwealth.net/rsu-tax-planning-strategies-tech-executives)
- Restricted Stock Units and Building a Diversified Portfolio (https://brightonjones.com/blog/restricted-stock-units)
- Cashing Out RSUs: Dodging Tech Stock Disasters by Diversifying (https://savantwealth.com/savant-views-news/article/cashing-out-rsus-dodging-tech-stock-disasters-by-diversifying)
- How to Diversify Investments After Receiving Rsus (https://linkedin.com/top-content/finance/investment-diversification-techniques/how-to-diversify-investments-after-receiving-rsus)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading