

Key Highlights
- A liquidity event is when families convert assets into cash, such as selling a business or receiving an inheritance.
- Understanding liquidity events is crucial for managing tax liabilities and long-term financial planning.
- Families should engage financial experts, establish operational foundations, and implement strategic planning to prepare for liquidity events.
- Tax implications can arise from liquidity events, such as capital gains tax on business sales and ordinary income tax on stock options.
- Proactive tax strategies, like timing asset sales and making charitable contributions, can help families manage tax burdens.
- After a liquidity event, families should create a financial plan that includes investment strategies and funds for urgent needs.
- Aligning financial goals with family values fosters a supportive environment and enhances financial satisfaction.
- Engaging children in financial discussions prepares them for future financial responsibilities and strengthens family connexions.
- Past performance does not guarantee future results; securities investments are subject to risk.
Introduction
Have you ever felt a mix of excitement and worry when faced with a sudden financial windfall? Selling a business or receiving stock options can bring not just exciting opportunities but also challenges that may feel overwhelming, especially for young families. These moments can present complex questions about tax implications and long-term planning.
Let’s explore some essential strategies that can help your family navigate this journey together, ensuring you can optimize your financial outcomes while aligning your wealth with your core family values. With the right strategies, you can turn that uncertainty into a path toward a secure and fulfilling future for your family.
Define Liquidity Events and Their Importance for Families
Imagine facing a sudden financial windfall, only to feel anxious about the decisions that lie ahead. A liquidity event is a moment when families can turn their assets into cash, like selling a business or receiving an inheritance. Understanding these events is crucial, as they can lead to significant financial gains. However, they also come with unique challenges, particularly in relation to liquidity after vesting tax planning and long-term planning. Many families find themselves overwhelmed by the complex decisions surrounding taxes, asset protection, and future planning during these times. Keeping track of holding periods and documentation is essential to minimize tax liabilities and ensure everything aligns with broader investment strategies.
Take the story of Allison and Brian, for example. This couple in their late forties felt uncertain about their financial future. They reached out to Bright Advisers, hoping to uncover the financial opportunities they had been missing due to inadequate tax strategies. Through their collaboration, they optimized their tax situation, secured their children’s education funding, and even found a path to retire sooner. This planning helped them feel more in control, making it easier to navigate the challenges that came with their liquidity after vesting tax planning event.
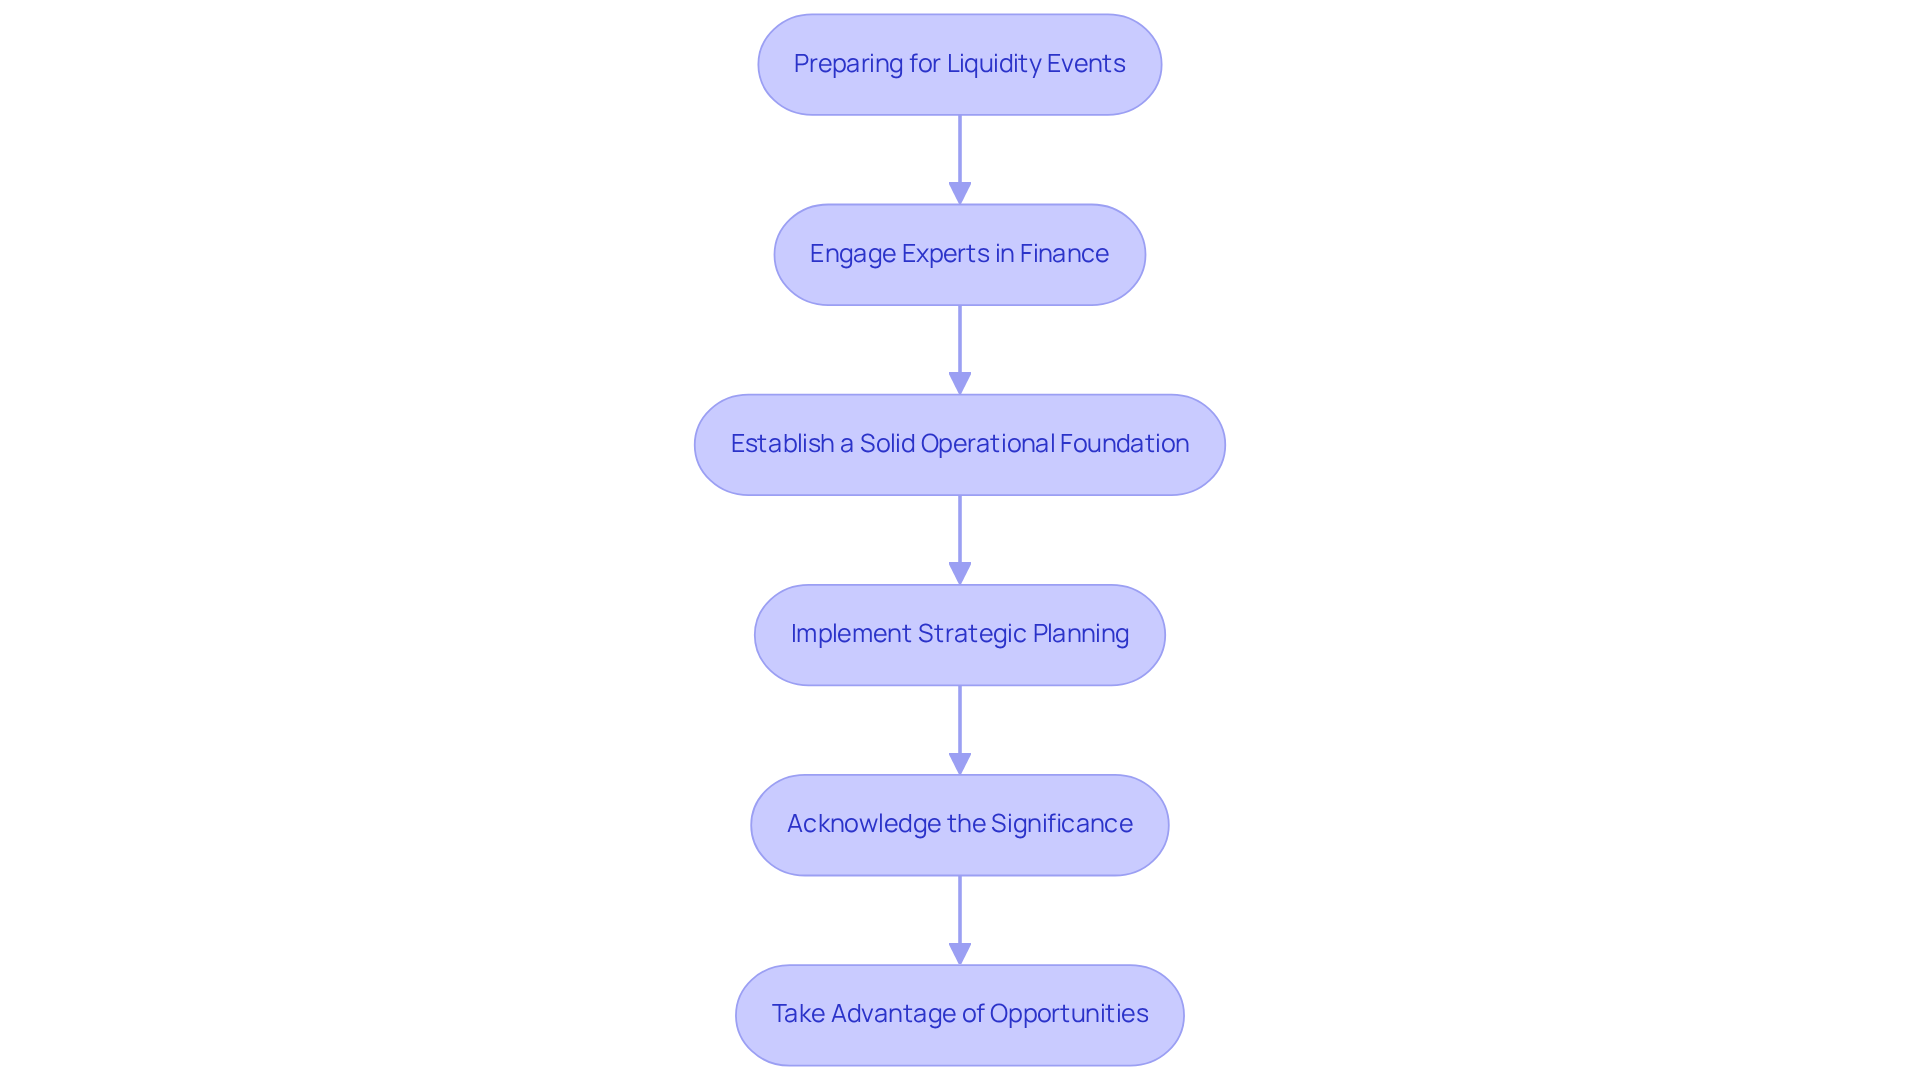
To prepare adequately for a liquidity event, families should consider these steps:
- Engage Experts in Finance: Consult with advisors, tax professionals, and legal specialists to navigate the complexities of liquidity events.
- Establish a Solid Operational Foundation: Organize documents and implement robust cash flow forecasting to manage monetary complexities.
- Implement Strategic Planning: Develop a comprehensive monetary plan that includes budgeting, cash flow projections, and tax preparation to leverage opportunities while mitigating risks.
Acknowledging the significance of liquidity occurrences enables households to prepare sufficiently, ensuring they can take advantage of opportunities while reducing potential risks. With the right support, families can turn potential stress into a stepping stone for a brighter future.
Explore Tax Implications of Liquidity Events for Effective Planning
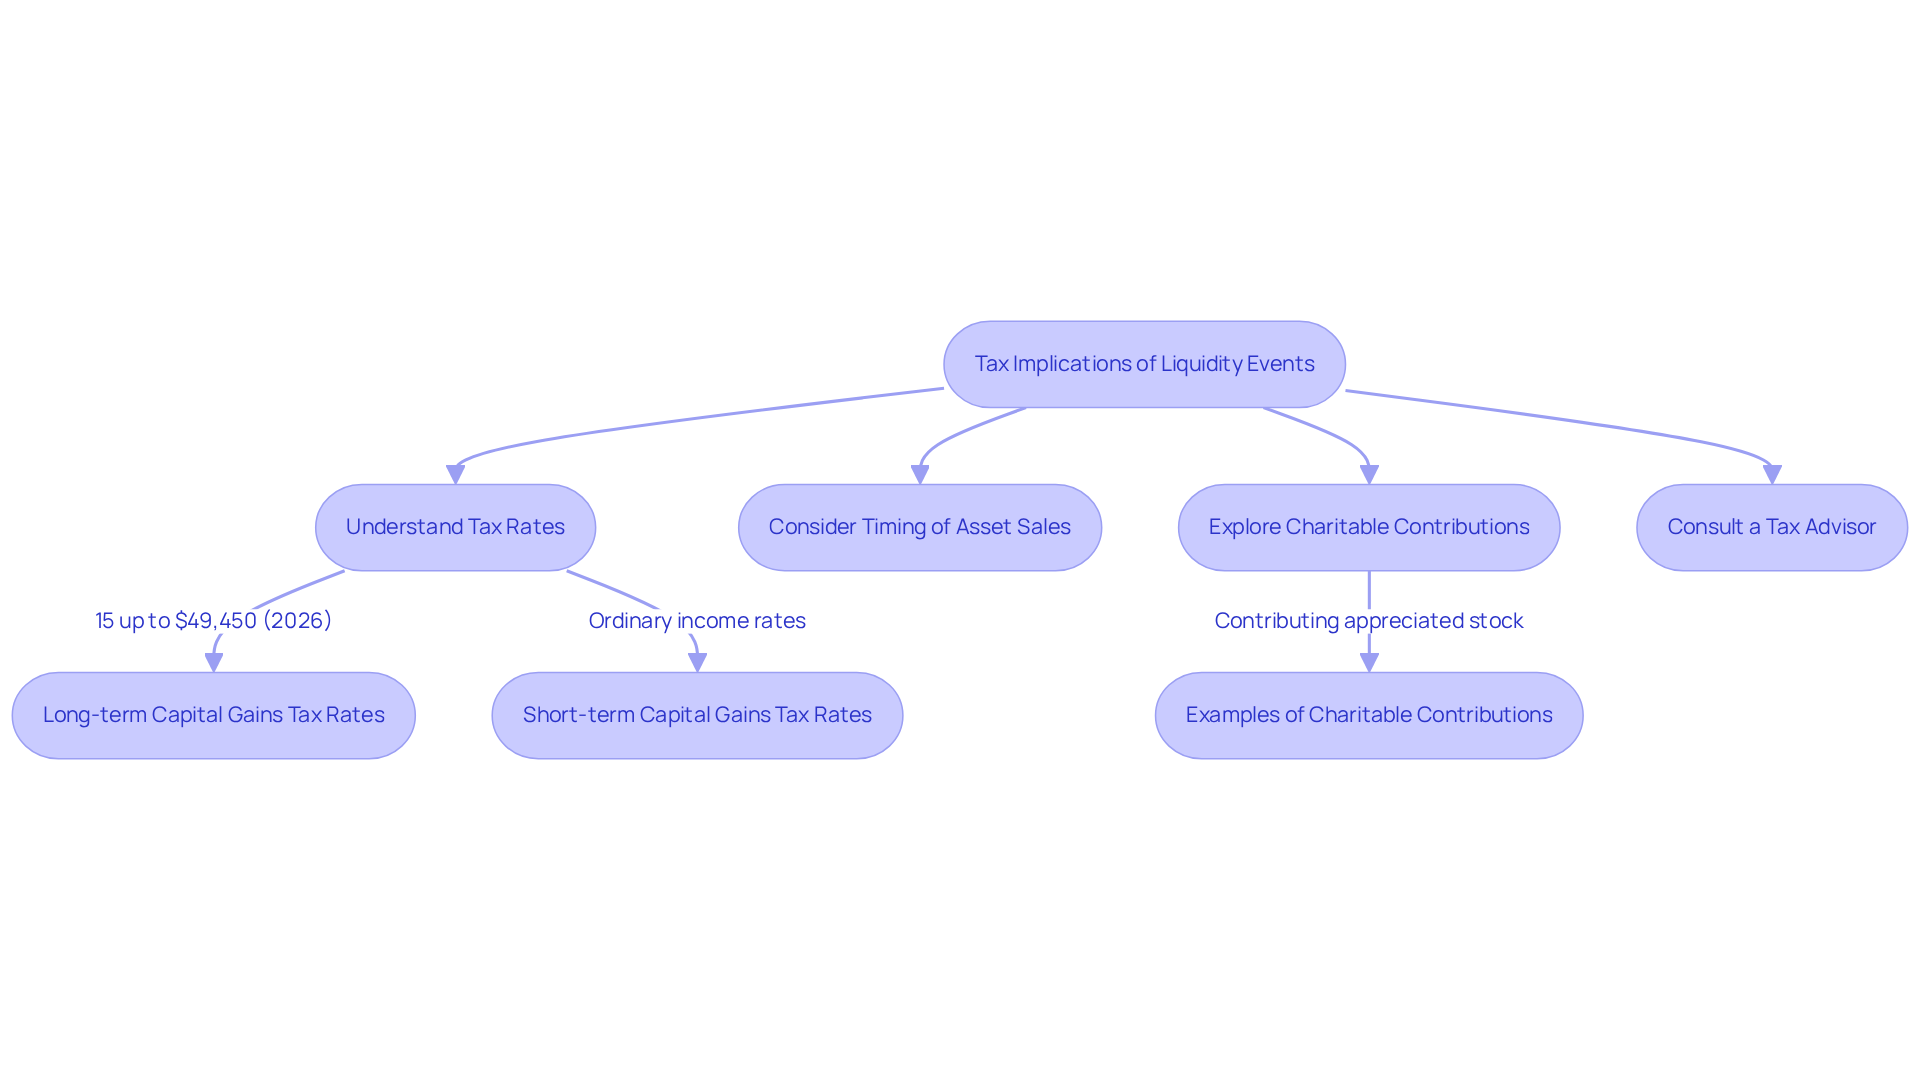
Navigating the world of taxes can feel overwhelming, especially when you’re focused on what truly matters – your family’s future. Imagine facing unexpected tax obligations when you sell a business or receive stock options – it’s a lot to handle, right? For instance, when you sell a business, you might face capital gains tax on the profits, and stock options can be taxed as ordinary income when they vest. It’s important to be prepared for these scenarios.
Working closely with a tax advisor can help your family understand your unique tax obligations and find ways to ease that burden together. You might consider:
- Timing the sale of assets
- Making charitable contributions to help offset taxable income
These strategies can make a difference!
By 2026, if you’re a single filer, long-term capital gains tax rates will be:
- 15% for income up to $49,450
- 20% for income over $545,500
Keeping these figures in mind can help you plan better. It’s also important to know that the tax rate on IPO stock can vary based on how you acquired the shares and how long you’ve held them. Understanding this can help you make informed decisions.
For example, if you hold Qualified Small Business Stock (QSBS), you could potentially exclude up to $10 million or 10 times your adjusted basis from federal capital gains taxes when you sell. That’s a significant benefit! Regularly checking in on your financial strategies is crucial, especially during events related to liquidity after vesting tax planning. It helps keep everything on track!
Understanding the timing of events like lock-up periods and vesting dates is key for families to plan effectively. It can make all the difference! By being proactive with your tax strategies, you can help your family keep more of your wealth and make the transition into your new financial reality smoother. Addressing tax consequences early allows your family to align your financial decisions with your long-term goals and values. It’s a step toward a secure future!
Implement Strategies for Post-Vesting Financial Optimization
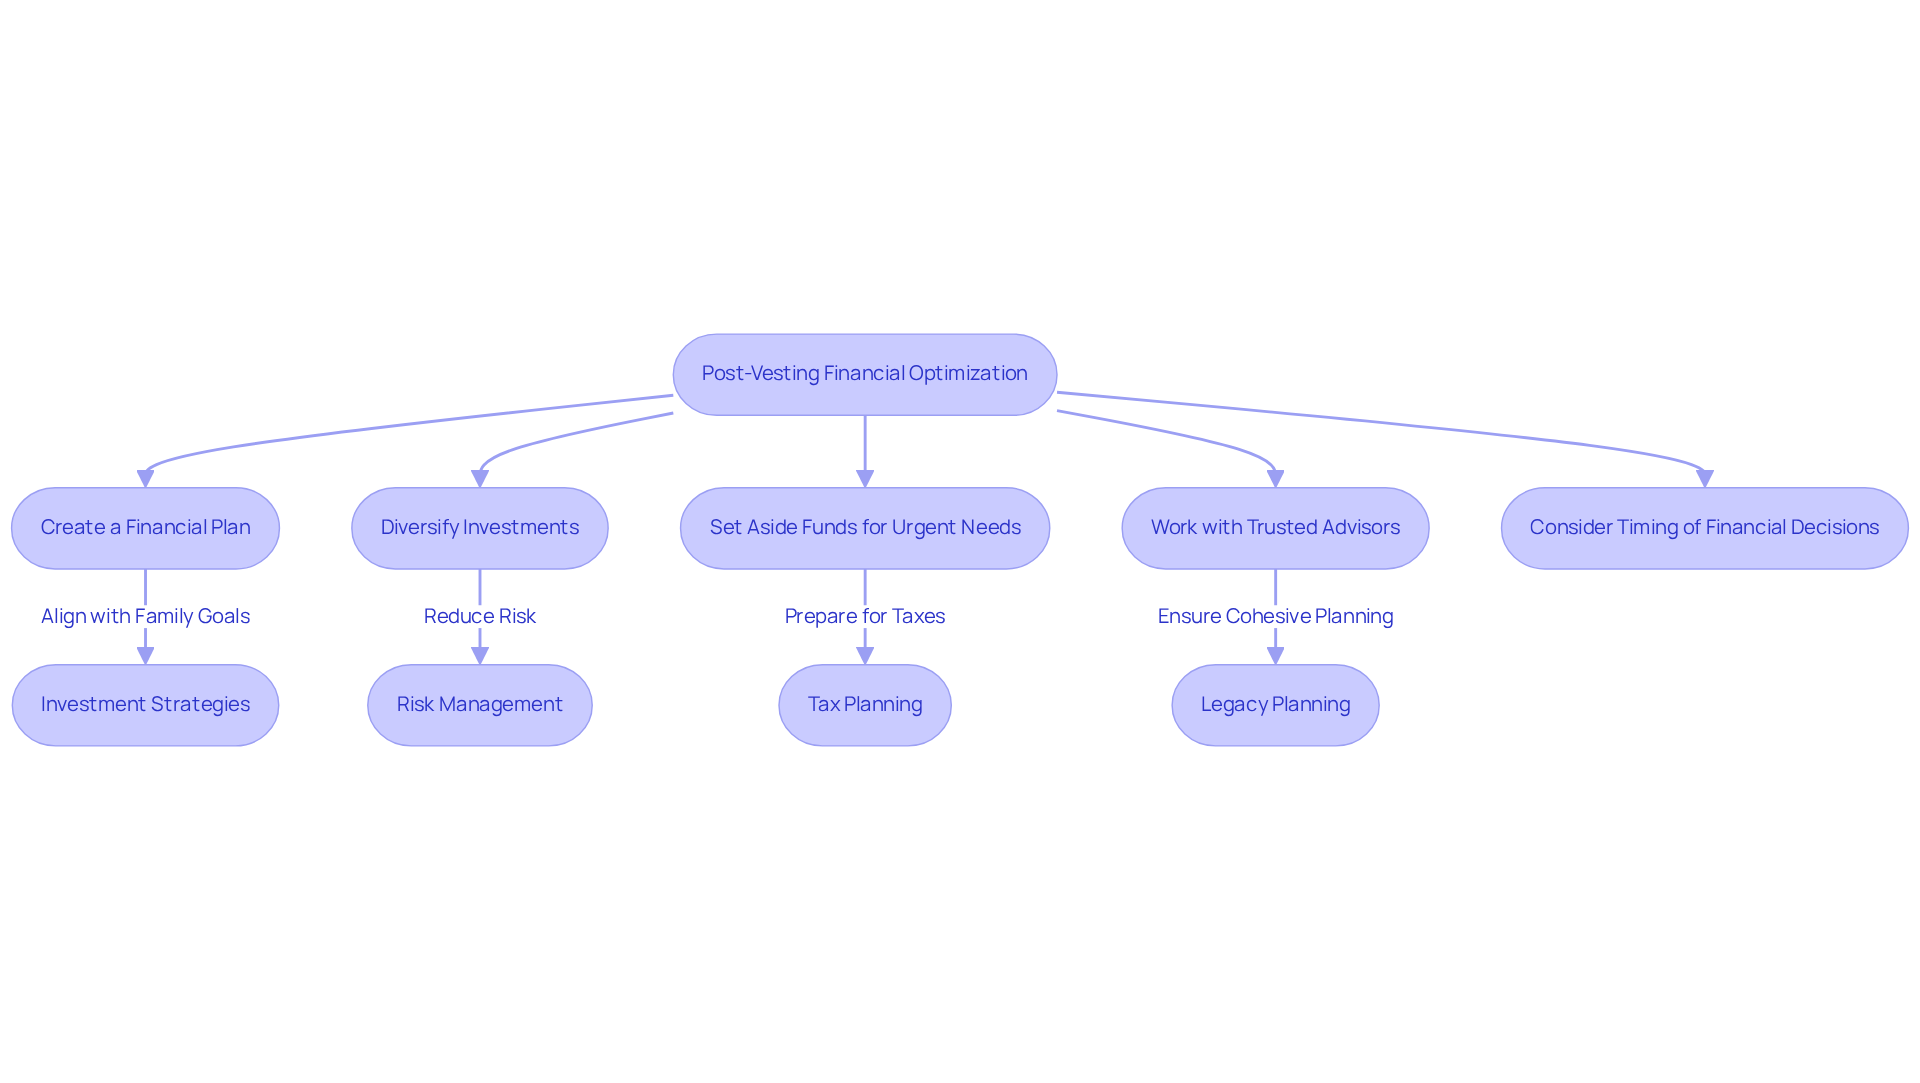
After a liquidity event, it’s so important to create a financial plan that embraces your new wealth and what it means for your family. Your plan should include investment strategies that match your comfort level and long-term family goals. Diversifying your investments is key, especially if you’ve previously held a lot in one asset. This can help reduce risk significantly.
Setting aside funds for urgent needs, like taxes or debt repayment, is essential for maintaining stability during this transition. Working with a trusted advisor like Bright Advisers can help you make these choices easier and create a plan that truly reflects your family’s values.
For instance, think about Allison and Brian, a couple who turned to Bright Advisers to enhance their financial potential through smart tax planning. Even with their significant incomes, they were missing out on opportunities due to a lack of effective tax strategies. By collaborating with their advisor, they optimized their tax situation, secured their children’s future through education funding, and even gained the ability to retire sooner. This shows how smart tax planning can really change a family’s financial future for the better.
It’s also important to consider the timing of your financial decisions. For example, if you’re planning to move from a high-tax state to one with no income tax, delaying the exercise of stock options can lead to significant tax savings. This kind of strategic timing can help families navigate the complexities of tax implications more effectively.
Bringing together a team of financial planners and tax advisors can make a big difference in ensuring a smooth transition after a sale. By addressing tax, investment, estate, and planning issues early, families can create a lasting legacy and avoid losing value due to taxes and poor investment decisions. Remember, Bright Advisers is here to support you in making wise wealth choices and protecting your family’s assets for generations to come.
Align Family Values with Financial Goals After a Liquidity Event
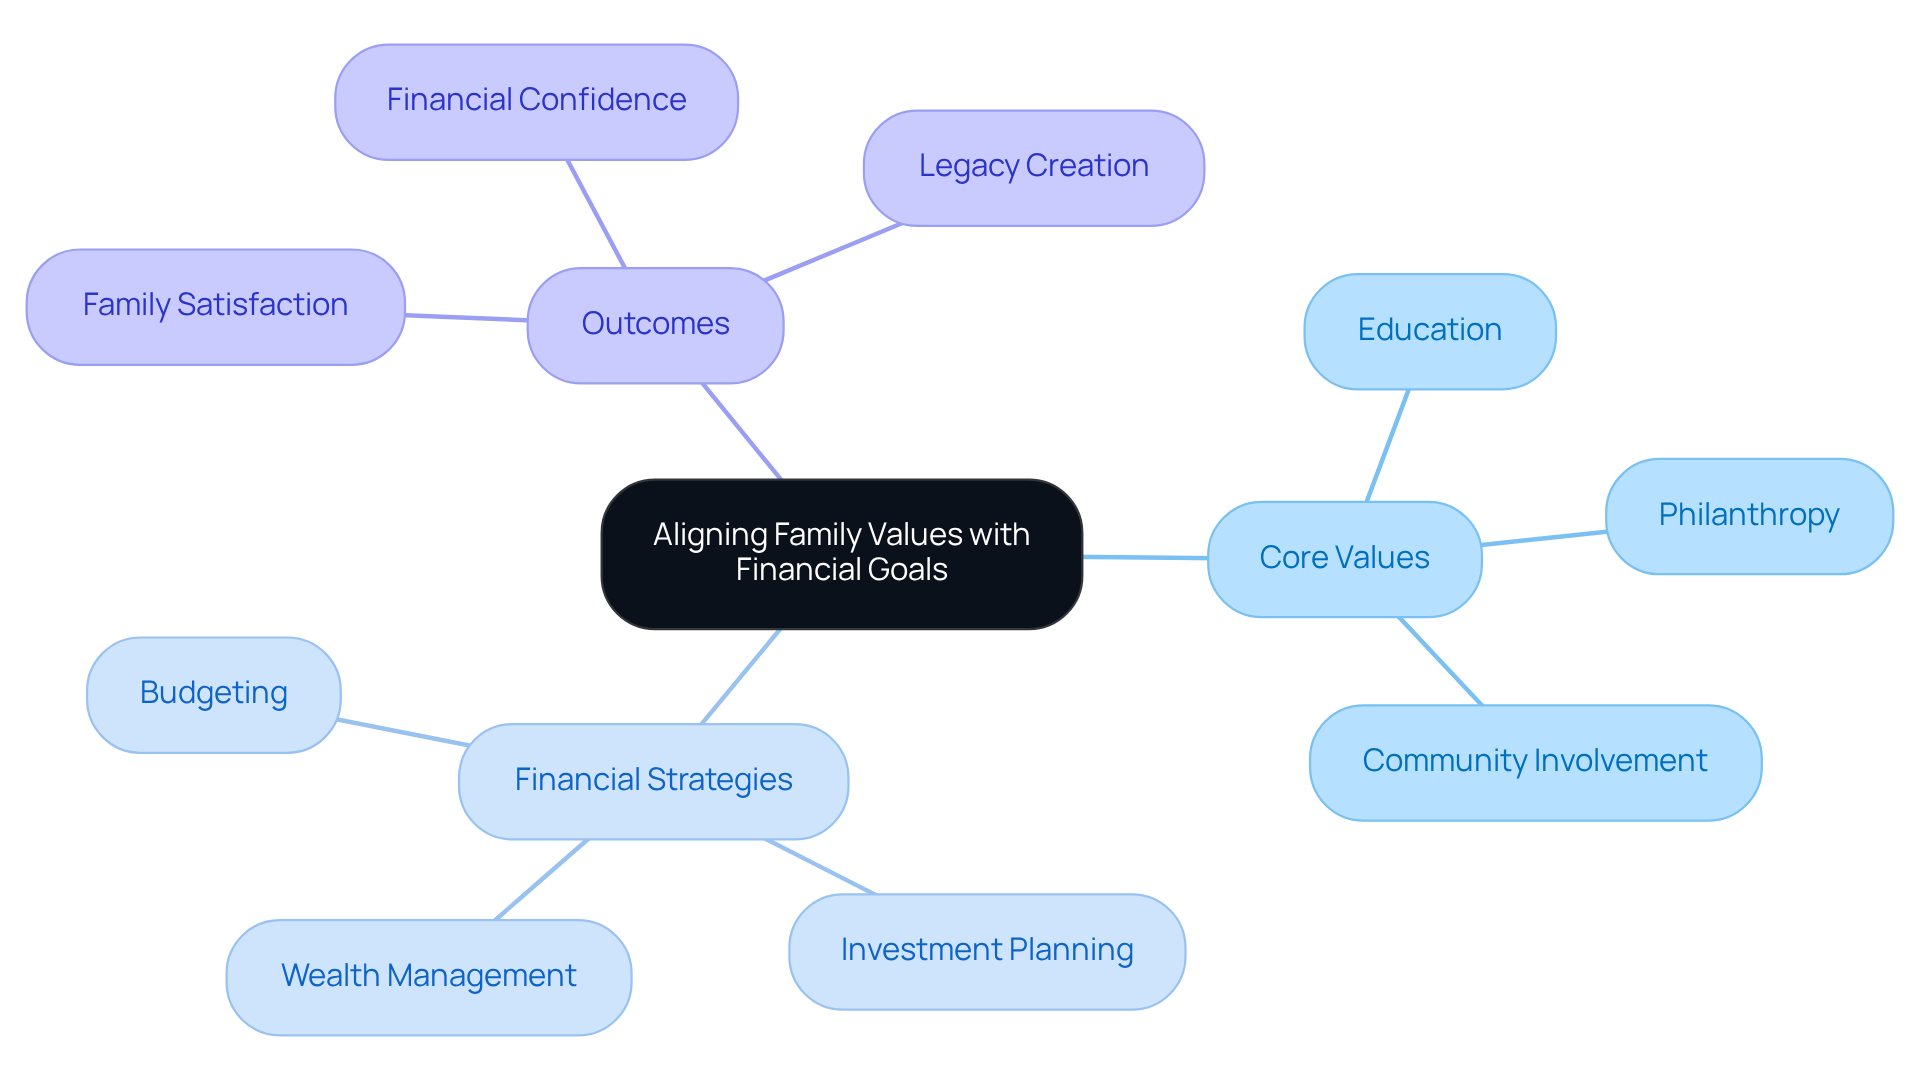
Have you ever felt overwhelmed by the financial decisions that shape your family’s future? After a big financial change, have you thought about what truly matters to your family? It’s essential to have open discussions about your core values, like education, philanthropy, or community involvement. Imagine the challenges of discussing finances with your loved ones, where differing priorities can create tension. By creating a financial plan that mirrors your family’s values, you’re ensuring that every dollar spent reflects your shared dreams. Engaging children in these discussions not only teaches them valuable lessons but also prepares them to handle their own finances with confidence. This alignment strengthens connections among relatives and creates a meaningful legacy for generations to come.
At Bright Advisers, we understand how important it is to connect your money with what you care about most. Families like Emily and Mark have gained access to a variety of services designed to meet their unique requirements, including strategies that emphasize low fund fees to improve wealth management accessibility. Through a thorough evaluation of their monetary situation, they devised a strategy that not only concentrated on enhancing their economic well-being but also granted them the liberty to decide whether or not to continue working. This approach shows that when your financial goals reflect your family’s values, you’re setting the stage for lasting success and happiness.
Expert insights emphasize that aligning monetary objectives with household values is essential for long-term achievement. For example, studies show that households who emphasize shared principles in their budgeting are more likely to reach their monetary goals. Statistics indicate that 63% of millennials feel assured in achieving their monetary objectives, highlighting the significance of a values-based strategy to managing finances.
Case studies further illustrate this concept. A recent survey indicated that households who participated in conversations about their monetary values reported greater satisfaction with their economic situations. Moreover, 70% of participants stated that having clear monetary goals enhances their sense of control and decreases unnecessary spending. By prioritizing family values in financial planning, families can navigate the complexities of wealth management while fostering a supportive environment for future generations.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Conclusion
Imagine the moment when a significant financial change could either bring relief or create worry for your family. Think about how selling a business or dealing with stock options can feel like a double-edged sword. It can be both exciting and daunting. But with the right guidance, you can turn that stress into a stepping stone for your family’s future.
Families like Allison and Brian show us that reaching out for help and planning together can make a world of difference. By timing your financial decisions wisely and considering the impact of taxes, you can keep more of what you earn and ensure your financial goals reflect your core values.
When your family’s values guide your financial goals, you create a nurturing space for your children to thrive. Open discussions about priorities not only strengthen family bonds but also empower your children to manage their finances confidently. Embracing these best practices can help your family navigate the complexities of wealth management, ensuring that every financial decision contributes to a meaningful legacy. Taking small steps today can lead to a future where your family’s dreams are not just possible, but within reach.
Frequently Asked Questions
What is a liquidity event?
A liquidity event is a moment when families can convert their assets into cash, such as selling a business or receiving an inheritance.
Why are liquidity events important for families?
Liquidity events can lead to significant financial gains, but they also present unique challenges related to tax planning, asset protection, and long-term financial strategies.
What challenges do families face during liquidity events?
Families often feel overwhelmed by complex decisions surrounding taxes, asset protection, and future planning, particularly regarding liquidity after vesting tax planning.
How can families prepare for a liquidity event?
Families should engage experts in finance, establish a solid operational foundation by organizing documents and implementing cash flow forecasting, and develop a comprehensive monetary plan that includes budgeting and tax preparation.
Can you provide an example of how a family benefited from planning around a liquidity event?
Allison and Brian, a couple in their late forties, worked with Bright Advisers to optimize their tax situation, secure their children’s education funding, and find a path to retire sooner, helping them feel more in control during their liquidity event.
What is the role of documentation in managing liquidity events?
Keeping track of holding periods and documentation is essential to minimize tax liabilities and ensure alignment with broader investment strategies.
What types of professionals should families consult during a liquidity event?
Families should consult with advisors, tax professionals, and legal specialists to navigate the complexities of liquidity events effectively.
List of Sources
- Define Liquidity Events and Their Importance for Families
- How to Plan a Family Office Liquidity Event (https://asora.com/blog/liquidity-event)
- A Guide to Preparing for Wealth Transfer – Merrill (https://ml.com/articles/prepare-for-wealth-transfer.html)
- Planning for Significant Liquidity Events Before They Happen – Galbraith Weatherbie Law (https://gwtrust.law/planning-for-significant-liquidity-events-before-they-happen)
- The advantages of proactive planning for liquidity events (https://crainscleveland.com/crains-content-studio/wealth-management-guide/2026/ccl-clearstead-wealth-management-planning-liquidity)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Explore Tax Implications of Liquidity Events for Effective Planning
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- Navigating Liquidity Events: Key Insights for IPOs, M&As and Buyouts (https://aspiriant.com/fathom/guide-to-major-financial-events)
- How to Plan a Family Office Liquidity Event (https://asora.com/blog/liquidity-event)
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- Implement Strategies for Post-Vesting Financial Optimization
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- 5 Expensive Mistakes to Avoid Before and After a Liquidity Event (https://aspiriant.com/fathom/liquidity-event-mistakes)
- Financial Planning After a Liquidity Event – Evercore Wealth Management (https://evercorewealthandtrust.com/liquidity-event-financial-planning)
- Navigating Stock Options: Strategic Timing for Founders & Employees Facing a Liquidity Event – BGM (https://bgm360.com/news-insights/navigating-stock-options-strategic-timing-for-founders-employees-facing-a-liquidity-event)
- Planning for Liquidity Events: Preparing Business Owners for a Transaction | Lawless, Edwards & Warren (https://lawlessedwardswarren.com/blog/planning-liquidity-events-preparing-business-owners-transaction)
- Align Family Values with Financial Goals After a Liquidity Event
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- CFP Board Research Reveals Millennials’ Top Life Goal: Financial Independence (https://cfp.net/news/2024/06/cfp-board-research-reveals-millennials-top-life-goal-financial-independence)
- 7 Steps to Align Your Money Values With Your Financial Goals in 2026 (https://amerisave.com/learn/steps-to-align-your-money-values-with-your-financial-goals-in)
- Setting New Financial Goals Feels Powerful; Sticking to Them Can Be Tough (https://newsroom.wf.com/news-releases/news-details/2026/Setting-New-Financial-Goals-Feels-Powerful-Sticking-to-Them-Can-Be-Tough/default.aspx)
- Gleaning Wisdom from Family Quotes | MONTAG Wealth Management (https://montagwealthmanagement.com/gleaning-wisdom-from-family-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading