

Key Highlights
- A Non-Qualified Personal Residence Trust (NQPRT) allows homeowners to transfer their property into a trust while retaining the right to live there, aiding in estate tax management.
- NQPRTs can provide stronger asset protection compared to Qualified Personal Residence Trusts (QPRTs), reducing the risk of fraudulent transfer claims.
- Key steps to create an NQPRT include selecting a trustee, drafting a trust agreement, transferring property, determining the trust term, filing tax documents, and regular reviews.
- Benefits of an NQPRT include avoiding probate, retaining property use, asset protection, simplified estate planning, and flexibility to meet family needs.
- Disadvantages include lack of tax benefits compared to QPRTs, irrevocability of the trust, potential increased costs, risk of property inclusion in taxable assets, and limited control over the property.
- Factors to assess suitability for an NQPRT include financial goals, property value, household dynamics, health and longevity, and consultation with experts.
- Families should be aware that establishing an NQPRT involves risks, and past performance does not guarantee future results; securities investments are subject to risk.
Introduction
Many families feel overwhelmed by the thought of planning for the future, especially when it comes to securing their legacy. A Non-Qualified Personal Residence Trust (NQPRT) can be a helpful tool, allowing families to transfer their homes into a trust while still enjoying the comfort of living there.
Let’s explore how you can set up an NQPRT and what it means for your family’s future. This guide will highlight the advantages and potential drawbacks, helping you make informed decisions that align with your long-term financial goals.
Could an NQPRT be the right choice for your family, or might it bring unexpected hurdles? Let’s find out together.
Define Non-Qualified Personal Residence Trust (NQPRT)
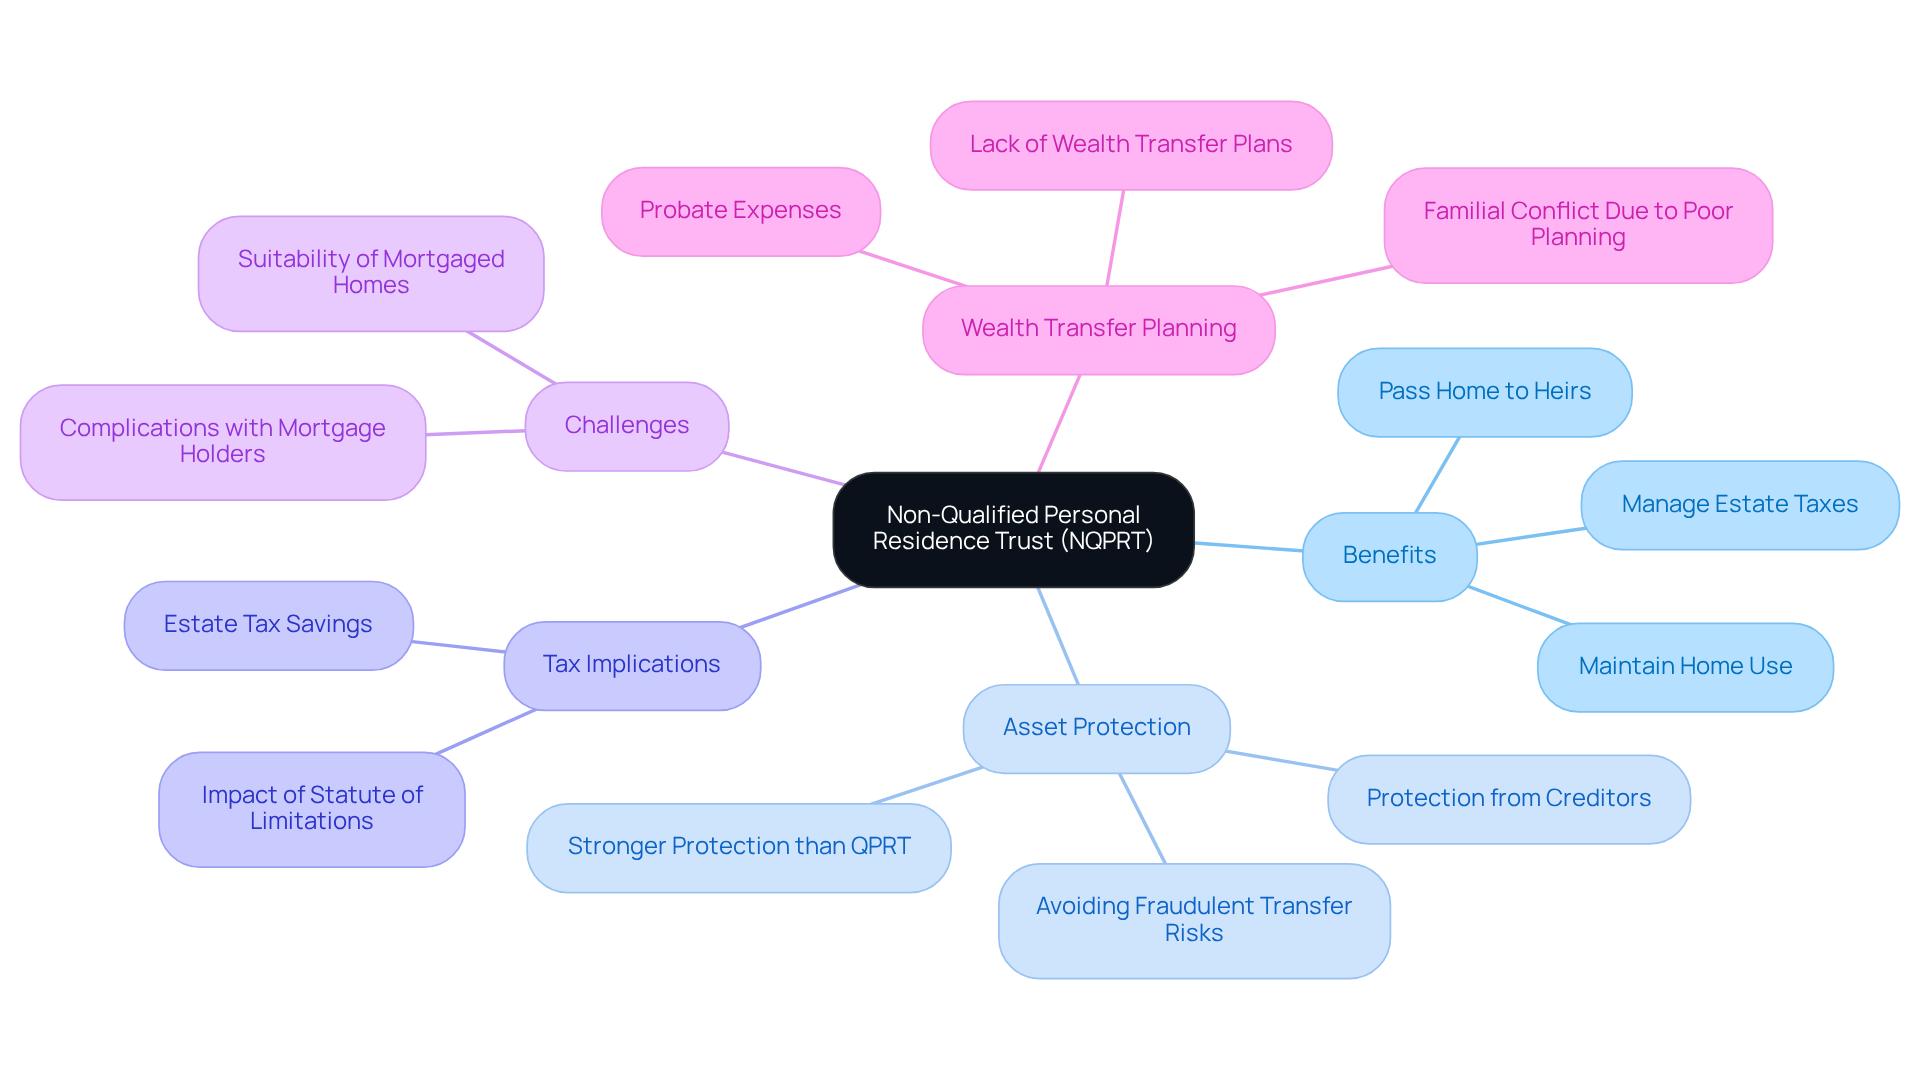
Imagine a way to protect your family’s home while planning for the future. A non qualified personal residence trust allows you to transfer your home into a trust while still being able to live there. While it doesn’t offer the same tax benefits as a non qualified personal residence trust, it provides a way to manage estate taxes and keep using your home, which can be a big relief for families.
If you’re thinking about a non qualified personal residence trust, it’s important to know it can help pass your home to your loved ones while making the process smoother. Plus, case studies show that a non qualified personal residence trust (NQPRT) can offer stronger asset protection than a qualified personal residence trust (QPRT), ensuring your home is transferred for equivalent value and reducing the risk of being seen as a fraudulent transfer.
However, be mindful of potential issues when transferring a mortgaged home to a non qualified personal residence trust, as this can complicate matters with your mortgage holder. With 28% of investors currently lacking a wealth transfer plan, understanding the non qualified personal residence trust (NQPRT) can be a key step in ensuring your family’s future is secure. Together, we can navigate this journey and make informed decisions for your family’s legacy.
Establish Steps for Creating an NQPRT
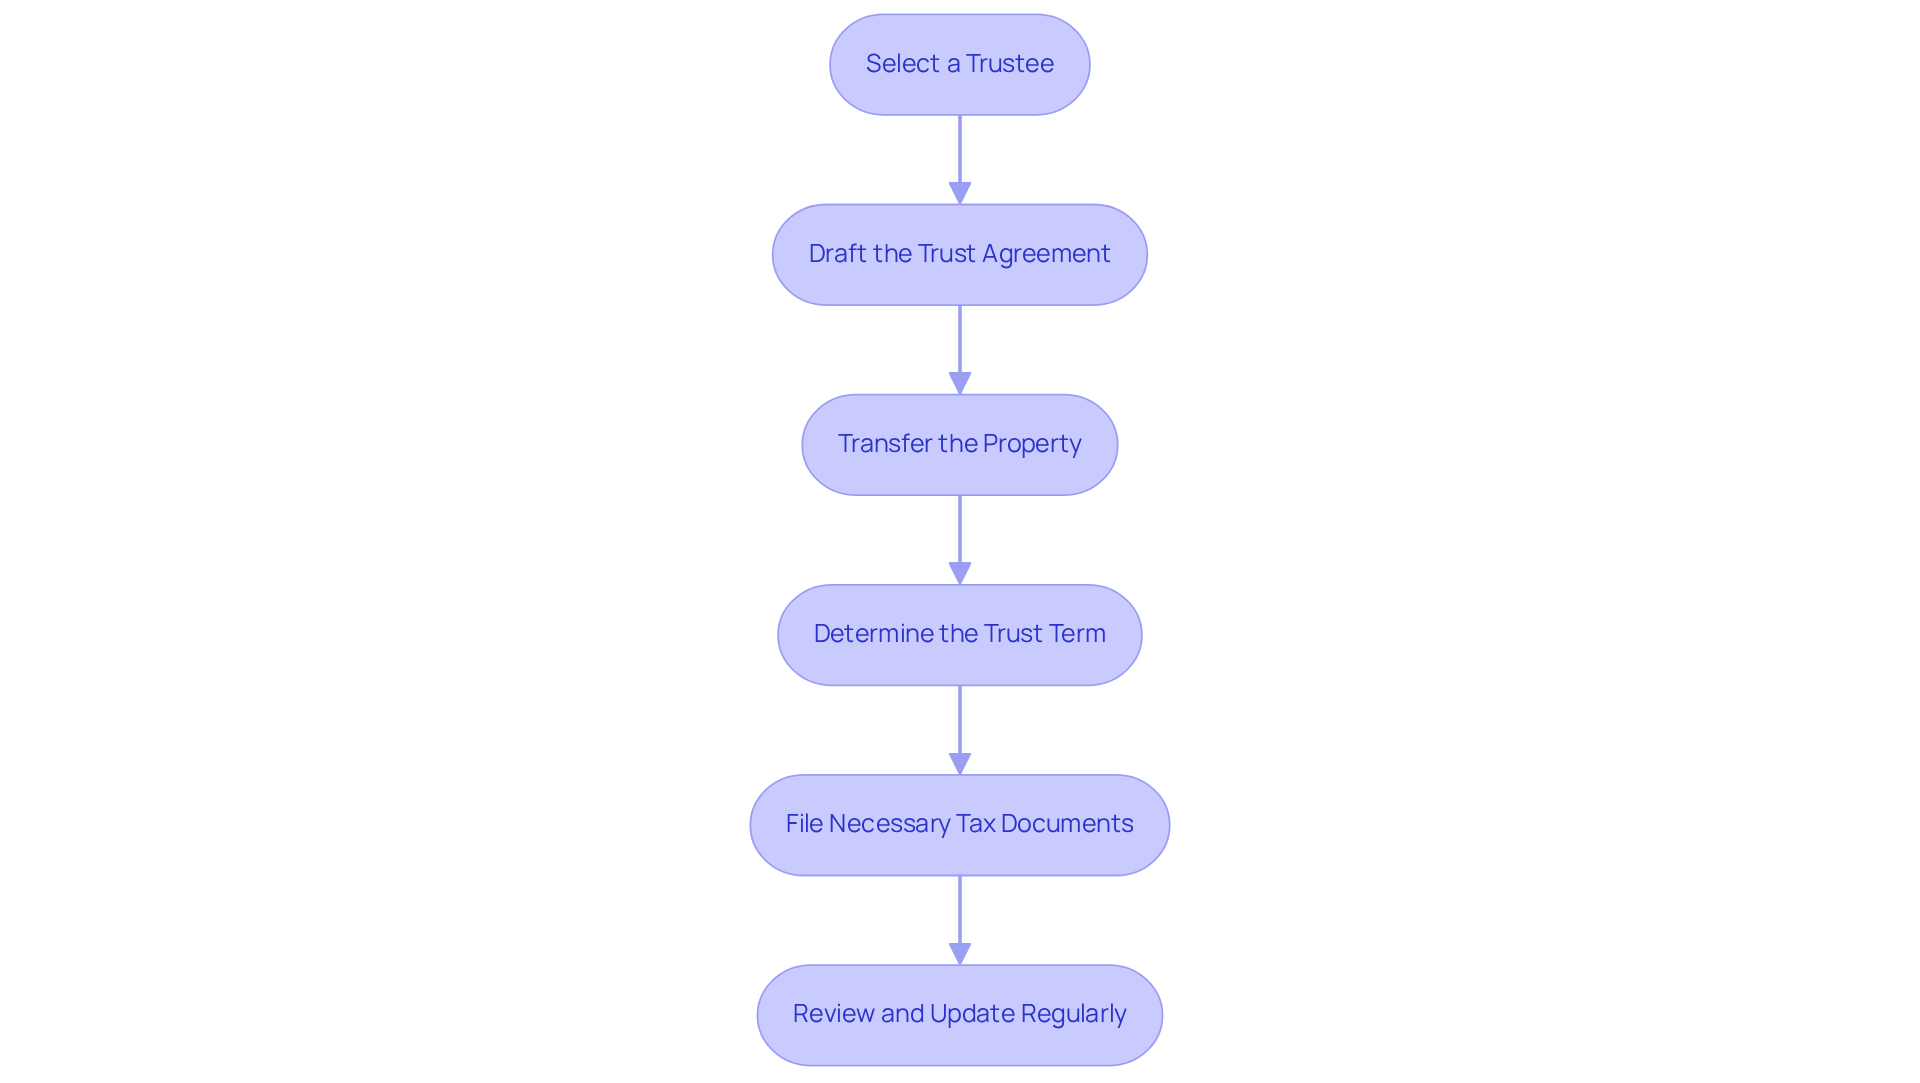
Imagine the peace of mind that comes from knowing your family’s future is secure, even in uncertain times. Creating a Non-Qualified Personal Residence Trust (NQPRT) involves several essential steps that can help families effectively manage their estate planning needs:
- Select a Trustee: Think about who in your life you trust the most to help manage your family’s future. This person will oversee the trust’s assets and ensure everything is in line with legal requirements.
- Draft the Trust Agreement: Collaborate with a planning lawyer to create a trust agreement that clearly defines the terms of the non-qualified personal residence trust, including the rights of both the grantor and the beneficiaries.
- Transfer the Property: Legally transfer the title of your home into the designated trust. This step is crucial because it helps reduce inheritance tax liability by removing the property from your holdings. Remember, under a non-qualified personal residence trust, the transferor does not live in the home without paying rent, which aids in reducing tax risks.
- Determine the Trust Term: Decide how long you want to retain the right to live in the property. This term can change depending on your family’s needs and planning goals. An NQPRT offers flexibility, as it doesn’t require the transferor to outlive a specific period to lessen tax liability.
- File Necessary Tax Documents: Complete any required tax filings, including reporting the transfer of the property as a gift, if applicable. This ensures compliance with tax regulations. It’s important to note that the estate and gift tax rate is 40% on amounts exceeding the exemption, highlighting the need for effective trust management.
- Review and Update Regularly: Periodically assess the trust to ensure it aligns with your family’s changing dynamics and financial situations, making adjustments as necessary to maintain its effectiveness.
At Bright Advisers, established by Kevin Luu and Kathleen Chou in 2010, we recognize that each household’s financial situation is unique. By following these steps, you can create an NQPRT that not only serves your current needs but also provides long-term benefits for future generations. Our customized wealth management services enable families to navigate financial complexities with assurance, ensuring that your planning aligns with your overall financial objectives. With our dedication to personalized planning and tax enhancement, including cohesive tax strategies and legacy planning services, we assist families in attaining financial stability and independence, enabling you to concentrate on what genuinely matters: your cherished ones. By taking these steps, you’re not just planning for today; you’re building a legacy of love and security for your family.
Highlight Benefits of an NQPRT
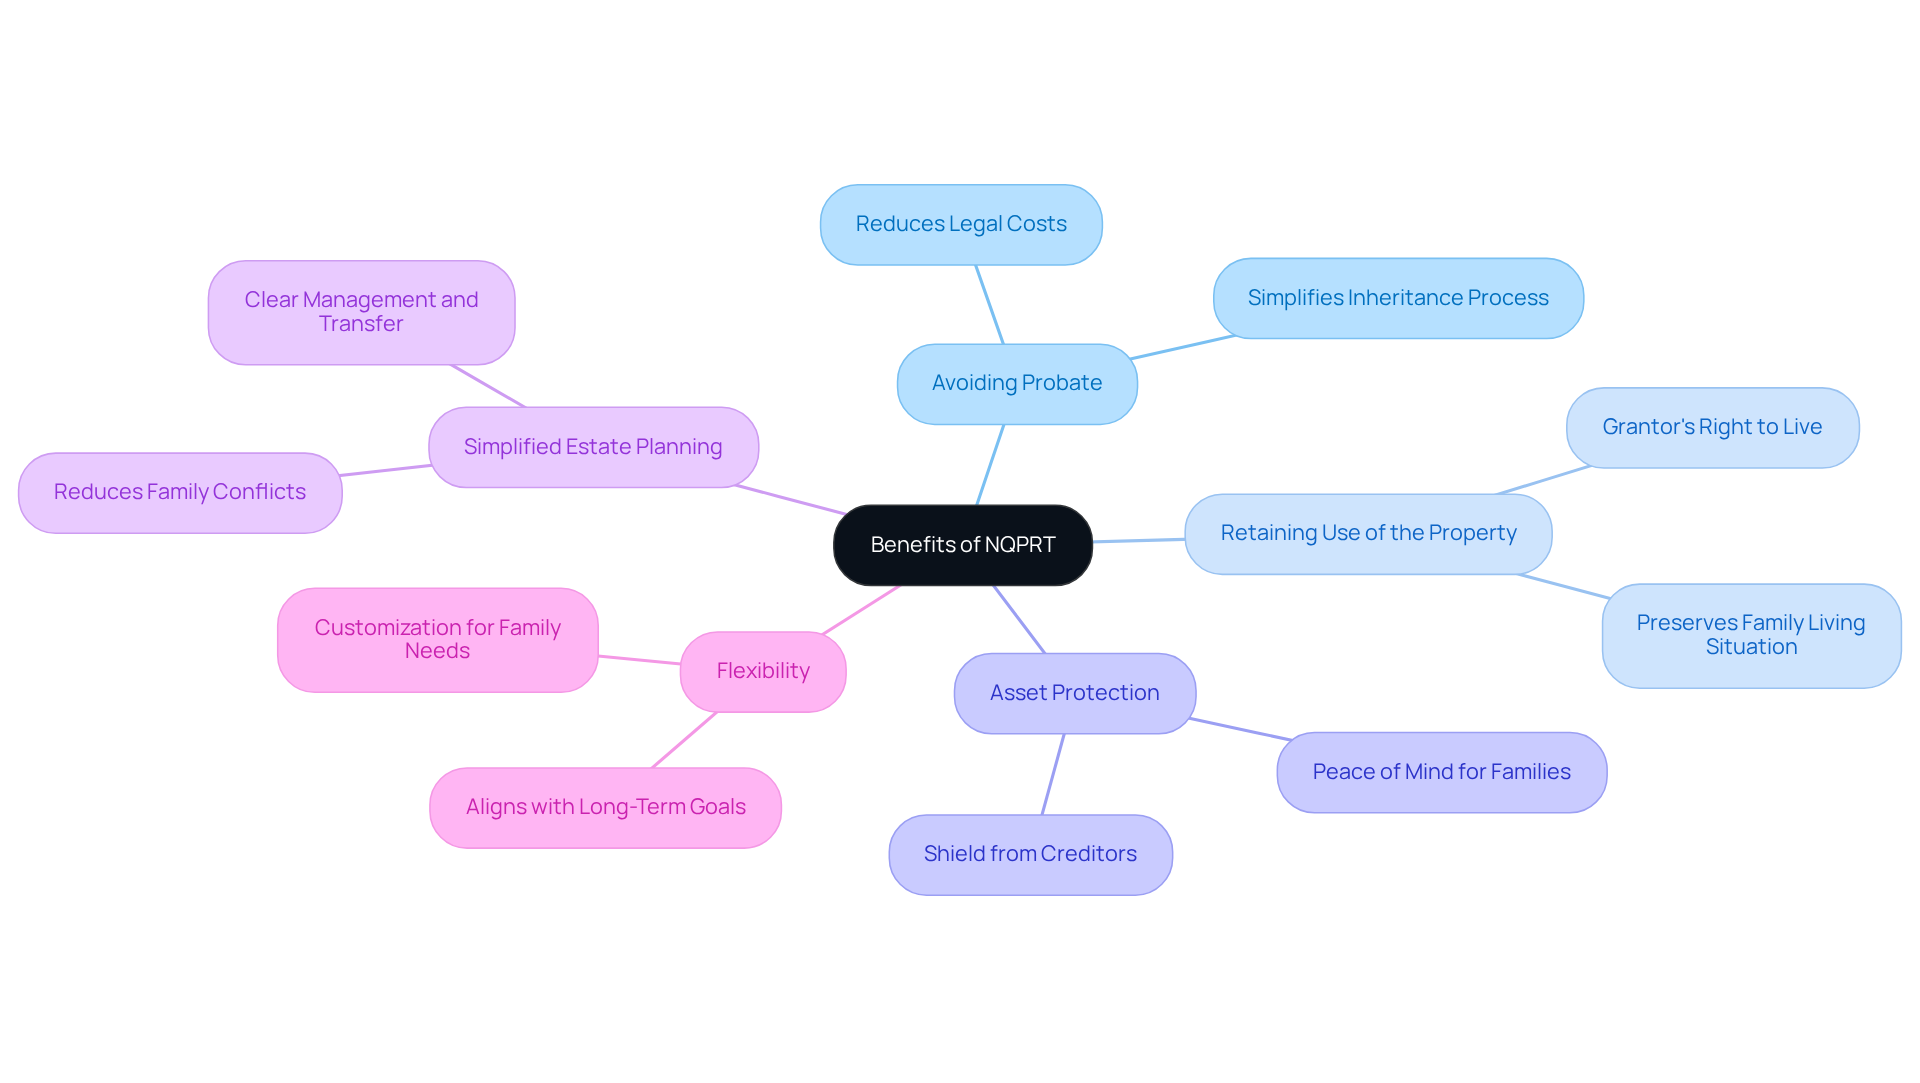
Imagine the peace of mind that comes from knowing your family’s future is secure, even in the face of life’s uncertainties. Establishing a Non-Qualified Personal Residence Trust (NQPRT) offers several significant benefits for families looking to secure their assets and simplify estate planning:
- Avoiding Probate: By placing your property in an NQPRT, you can avoid the long and expensive probate process, making it easier for your loved ones to inherit what you’ve worked so hard to build. Imagine the stress of losing a loved one and then facing unexpected costs that eat away at their legacy.
- Retaining Use of the Property: You can still enjoy your home while ensuring its future for your heirs. The grantor retains the right to live in the property for the duration specified in the trust, allowing families to preserve their living situation without interruption.
- Asset Protection: A non-qualified personal residence trust can help shield your home from creditors, giving you peace of mind knowing it’s safe for your family. This is particularly reassuring for those worried about possible financial obligations that could impact their assets.
- Simplified Estate Planning: By clearly defining how the property will be managed and transferred, families can reduce potential conflicts among heirs. Without a clear plan, families risk not only their assets but also their relationships, as over a third of U.S. adults report experiencing familial conflict due to a lack of estate planning.
- Flexibility: A non-qualified personal residence trust (NQPRT) can be tailored to meet the specific needs of households, allowing for customization based on individual circumstances and goals. This adaptability ensures that the trust aligns with your family’s long-term financial strategy.
Data suggest that households using NQPRTs are increasingly steering clear of probate, with many acknowledging the significance of proactive wealth planning. In fact, only 32% of Americans have established a will or living trust, highlighting a significant opportunity for families to enhance their estate planning efforts through tools like NQPRTs. By utilizing these trusts, you can ensure that your family’s legacy is protected and cherished for generations to come.
Examine Disadvantages of an NQPRT
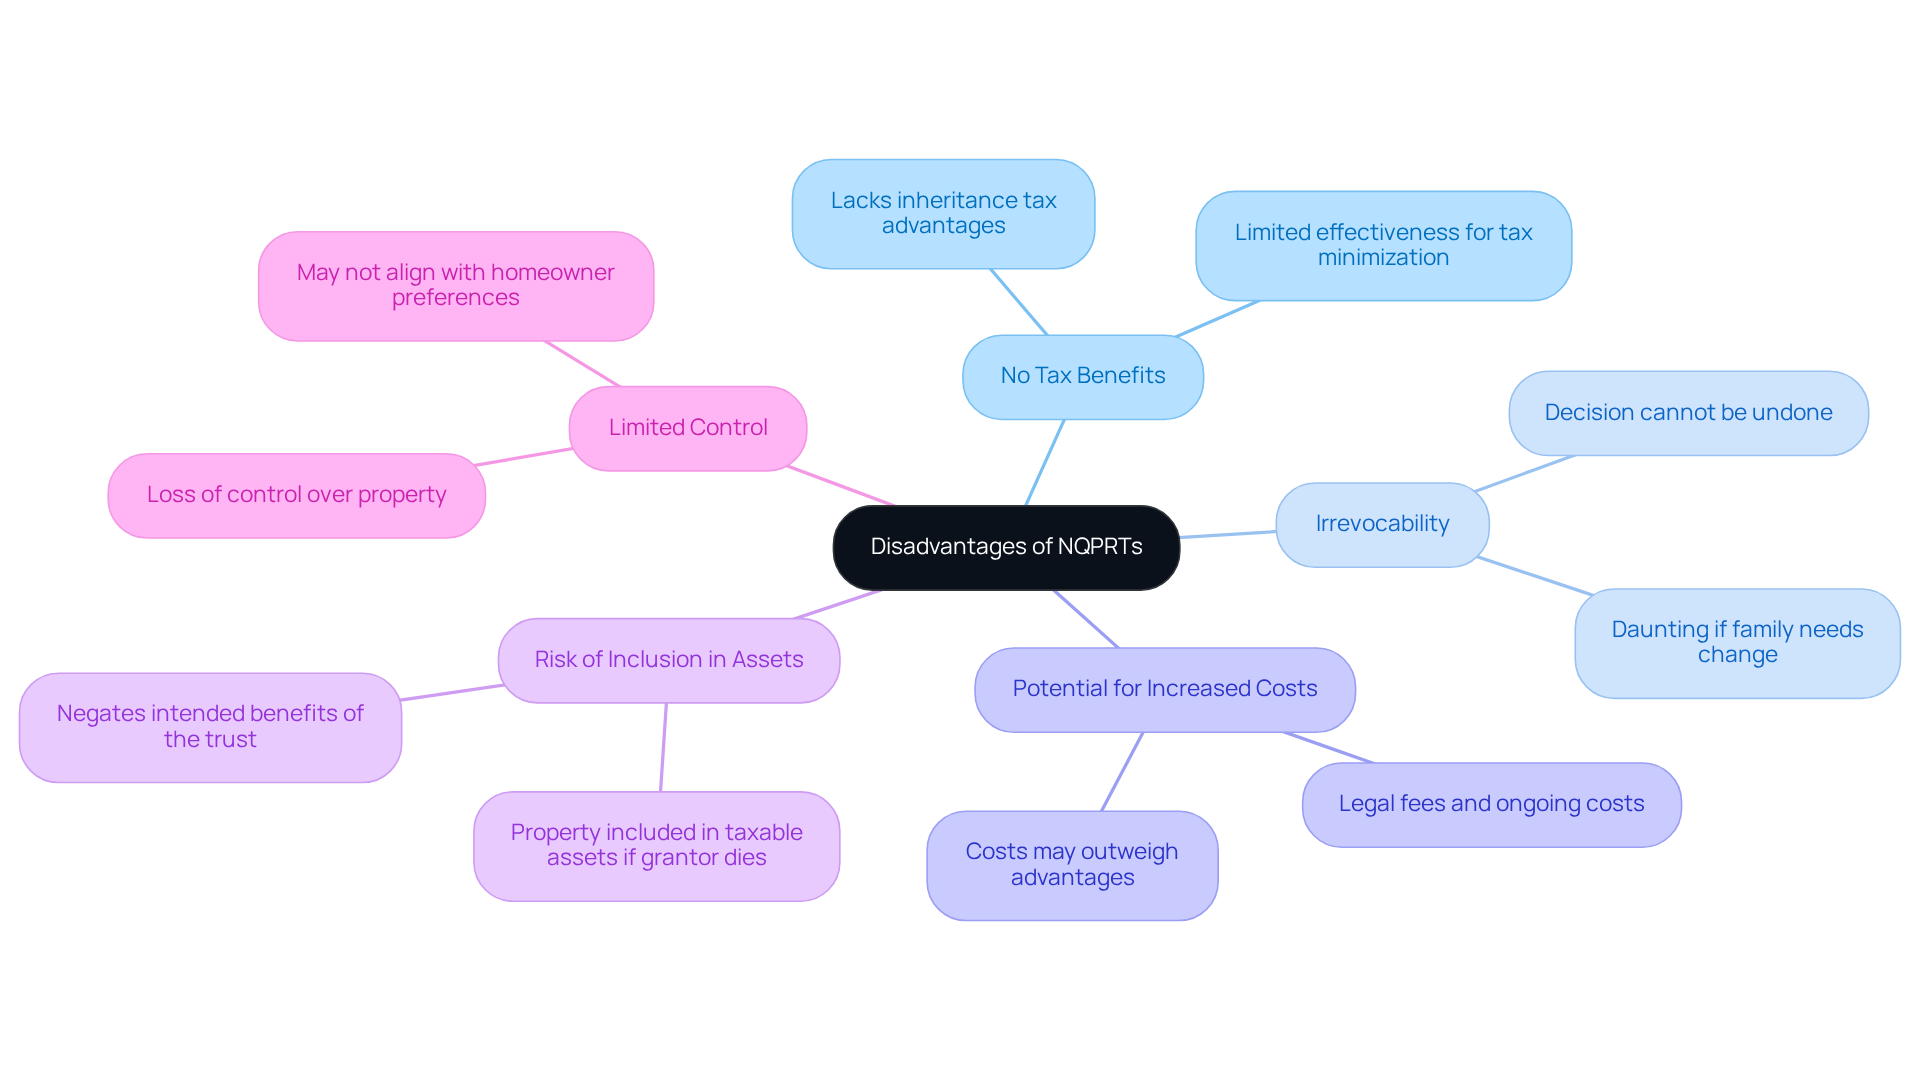
Imagine making a decision about your family’s future that you can’t take back-this is the reality with non-qualified personal residence trusts. While a non-qualified personal residence trust (NQPRT) can offer certain advantages, it also comes with notable disadvantages that families should carefully consider.
- No Tax Benefits: Unlike Qualified Personal Residence Trusts (QPRTs), NQPRTs lack the same inheritance tax advantages. This can limit their effectiveness for families looking to minimize tax liabilities. For instance, a primary residence worth $1 million can be removed from a taxable estate valued at $10 million by creating a QPRT, potentially saving significant estate taxes.
- Irrevocability: Once you place your property in a non-qualified personal residence trust, this decision cannot be easily undone, which may feel daunting if your family’s needs change. As Scott Filmore, Managing Director, notes, “The decision to use a QPRT requires careful consideration of its benefits and limitations.”
- Potential for Increased Costs: Setting up and maintaining a non-qualified personal residence trust can incur legal fees and ongoing costs, which might feel overwhelming for some families. For certain households, these costs may surpass the advantages, making it a less appealing choice.
- Risk of Inclusion in Assets: If the grantor passes away before the trust term concludes, the property may still be included in their taxable assets. This scenario can negate many of the intended benefits of establishing the trust in the first place. For instance, if a homeowner passes away with a QPRT established, their taxable property would be assessed at $9.5 million after excluding the residence’s value, resulting in considerable inheritance tax consequences.
- Limited Control: Once the property is placed in the trust, the grantor relinquishes control over it. This loss of control may not align with the preferences of all homeowners, particularly those who wish to retain flexibility in managing their assets. Cliff O’Conner, Founder and President, emphasizes, “They’re a powerful tool that’s able to reduce the value of your assets substantially, and assure you and your beneficiaries have a place to stay.”
Understanding these challenges is crucial, as it can shape the financial future you envision for your loved ones with a non-qualified personal residence trust. Consulting with a qualified estate planning professional can help navigate these complexities and ensure that the chosen approach aligns with your long-term financial goals. Furthermore, examining case studies on the drawbacks of NQPRTs can offer practical insights into the difficulties households may encounter.
Assess Suitability of an NQPRT for Your Family
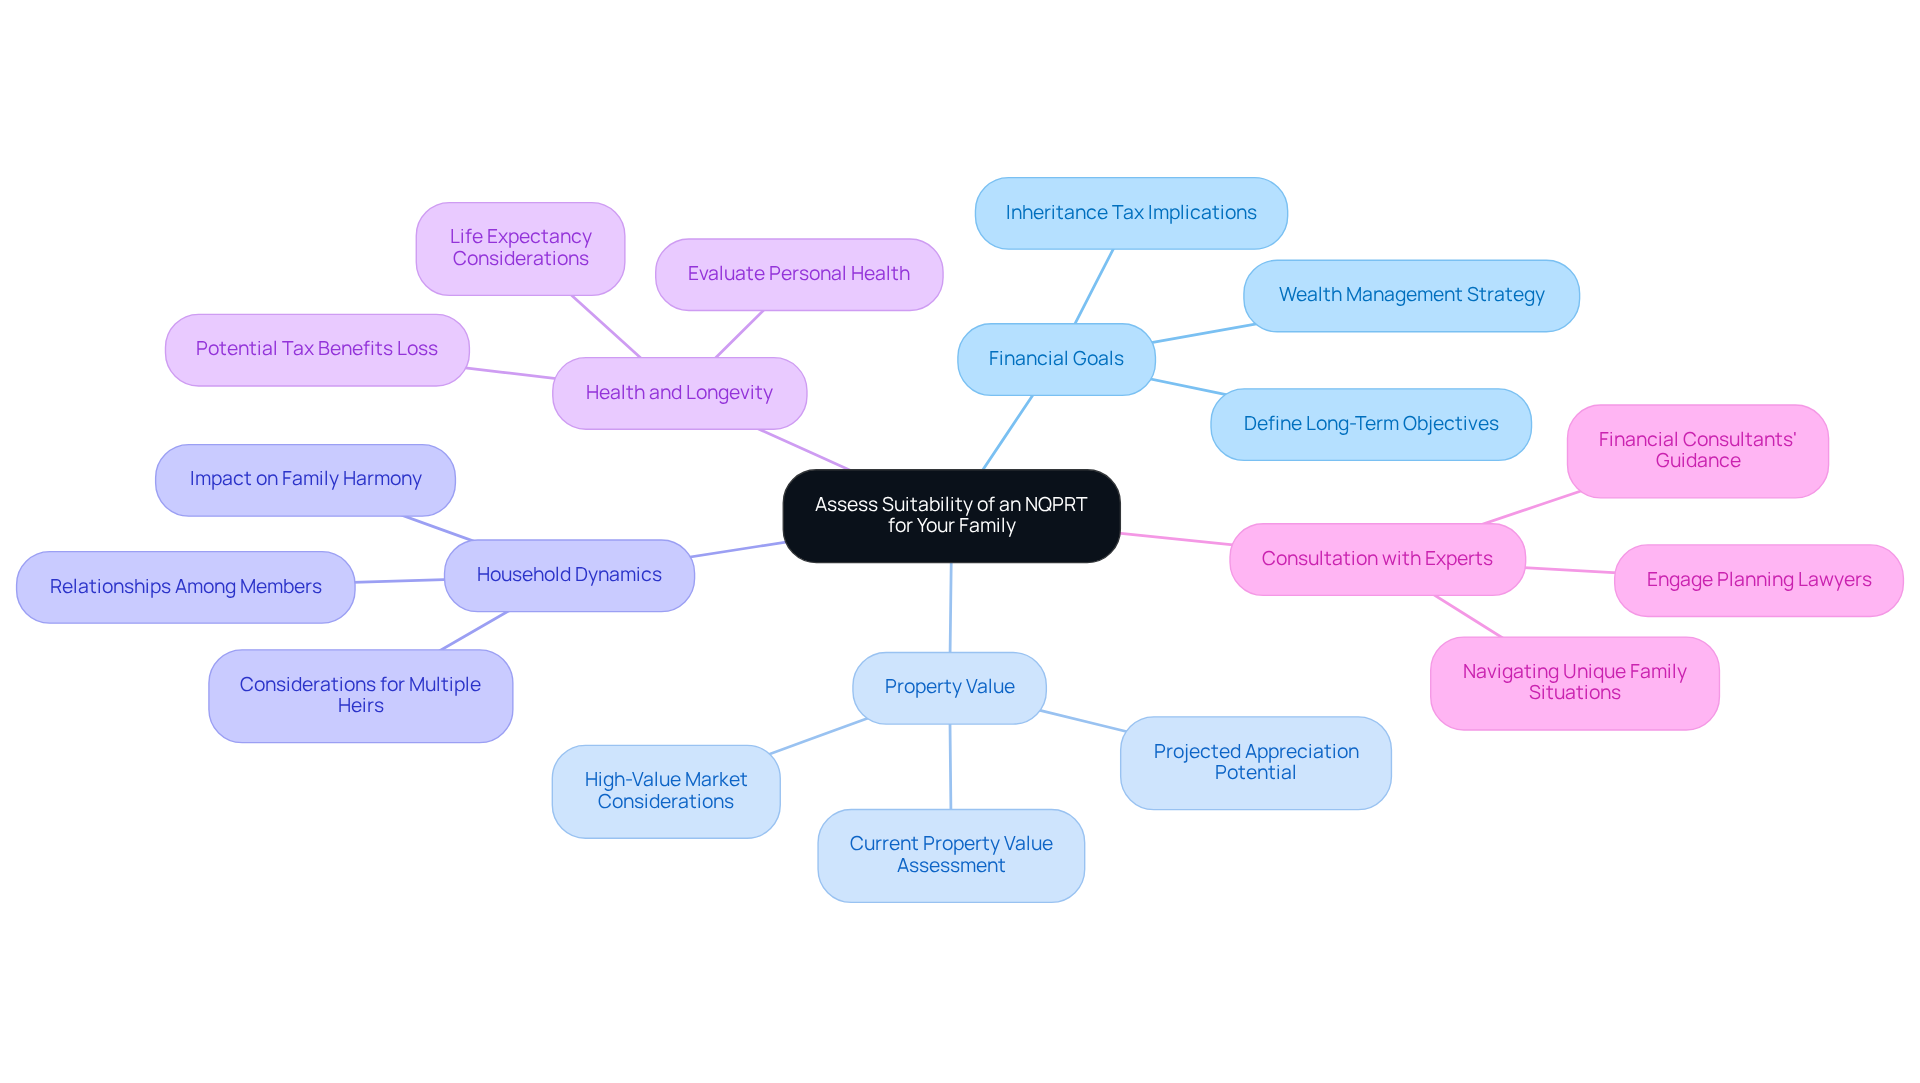
To determine if a Non-Qualified Personal Residence Trust (NQPRT) is suitable for your family, consider these important factors:
- Financial Goals: Clearly define your long-term financial objectives, including inheritance tax implications and your desire to pass property to your heirs. Understanding these goals can help you see if a non-qualified plan aligns with your family’s wealth management strategy.
- Property Value: Take a moment to assess the current and projected value of the property you want to place in the trust. A non-qualified personal residence trust can be advantageous if the property’s appreciation potential exceeds the associated costs, particularly in high-value markets where estate taxes may be a concern.
- Household Dynamics: Reflect on the relationships among your household members and how the trust might influence these dynamics. Considerations around property use and inheritance can significantly impact family harmony, particularly when multiple heirs are involved.
- Health and Longevity: Your health and life expectancy are crucial factors in how effective an NQPRT can be. Imagine the disappointment of losing potential tax benefits if the trust doesn’t work as planned. Evaluating your health can provide insights into the trust’s potential success.
- Consultation with Experts: Reach out to trusted planning lawyers and financial consultants who can help you navigate your unique family situation. Expert advice ensures that all elements of your property planning are considered, guiding you in making informed choices about establishing a non-qualified personal residence trust.
As we move toward 2026, families are increasingly recognizing the importance of strategic estate planning, especially as property values rise and tax implications become more complex. By taking the time to explore these factors, you can ensure your family’s legacy is protected and nurtured for generations to come.
Conclusion
Imagine securing your family’s future while navigating the complexities of estate planning. Establishing a Non-Qualified Personal Residence Trust (NQPRT) can be a pivotal step for families aiming to protect their home and manage their estate effectively. When families grasp how NQPRTs work, they can better manage their wealth and protect their legacy for the future. This trust not only allows families to retain the use of their property but also provides a structured approach to asset protection and simplified estate planning.
Throughout this article, we’ve gently outlined key steps for creating an NQPRT, including:
- Selecting a trustee
- Drafting the trust agreement
- Regularly reviewing the trust to adapt to changing family dynamics
Families may worry about missing out on tax advantages, but the benefits of an NQPRT, such as avoiding probate and protecting assets from creditors, have been emphasized. This careful consideration can lead to a more secure financial future.
Ultimately, setting up an NQPRT is more than just a financial step; it’s about ensuring a safe and loving future for your family. Families are encouraged to consult with trusted advisors, like those at Bright Advisers, to explore how an NQPRT can fit into their broader wealth management strategy. Taking these steps today can empower families to create a legacy filled with love and security for generations to come.
Frequently Asked Questions
What is a Non-Qualified Personal Residence Trust (NQPRT)?
A Non-Qualified Personal Residence Trust (NQPRT) allows you to transfer your home into a trust while still living there. It helps manage estate taxes and provides a way to pass your home to loved ones, offering stronger asset protection than a Qualified Personal Residence Trust (QPRT).
What are the benefits of creating an NQPRT?
An NQPRT can help reduce inheritance tax liability, protect your home from being seen as a fraudulent transfer, and allow you to continue living in your home while planning for the future.
What steps are involved in creating an NQPRT?
The steps include selecting a trustee, drafting the trust agreement with a planning lawyer, transferring the property into the trust, determining the trust term, filing necessary tax documents, and regularly reviewing and updating the trust.
Who should be selected as a trustee for the NQPRT?
You should select someone you trust to manage the trust’s assets and ensure compliance with legal requirements.
What is the importance of drafting a trust agreement?
The trust agreement clearly defines the terms of the NQPRT, including the rights of the grantor and beneficiaries, ensuring that all parties understand their roles and responsibilities.
How does transferring the property into the trust affect tax liability?
Transferring the property into the trust helps reduce inheritance tax liability by removing the property from your holdings, but the transferor must not live in the home without paying rent to minimize tax risks.
What should be considered when determining the trust term?
The trust term should reflect how long you wish to retain the right to live in the property, which can be adjusted based on your family’s needs and planning goals.
What tax documents need to be filed when creating an NQPRT?
You may need to report the transfer of the property as a gift and complete any required tax filings to ensure compliance with tax regulations.
Why is it important to review and update the NQPRT regularly?
Regular reviews ensure that the trust remains aligned with your family’s changing dynamics and financial situations, allowing for necessary adjustments to maintain its effectiveness.
Who provides advisory services related to NQPRTs?
Advisory services related to NQPRTs are provided through Lifeworks Advisors, a registered investment adviser, ensuring compliance and transparency in wealth management.
List of Sources
- Define Non-Qualified Personal Residence Trust (NQPRT)
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- Changing tax law may have made home trust unnecessary (https://latimes.com/business/story/2020-09-30/changing-tax-law-trusts)
- Qualified & Non Qualified Personal Residence Trust Strong Tool (https://assetprotectiontraining.com/non-qualified-personal-residence-trusts-non-qprt)
- Establish Steps for Creating an NQPRT
- Trusts: Income and Estate and Gift Tax Issues (https://congress.gov/crs-product/R48879)
- Qualified & Non Qualified Personal Residence Trust Strong Tool (https://assetprotectiontraining.com/non-qualified-personal-residence-trusts-non-qprt)
- SOI Tax Stats – Definitions of selected terms and concepts for income from trusts and estates | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-definitions-of-selected-terms-and-concepts-for-income-from-trusts-and-estates)
- Highlight Benefits of an NQPRT
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- Alarming Estate Planning Statistics (https://financialsense.com/blog/21022/alarming-estate-planning-statistics)
- 5 Eye-Opening Statistics About Estate Planning – Nickerson Law: A Professional Corporation (https://jeffreycnickersonlaw.com/blog/5-eye-opening-statistics-about-estate-planning)
- Position Your Family to Avoid Probate Court – The Living Trust Source | Reno Nevada (https://livingtrustsource.com/position-your-family-to-avoid-probate-court)
- Fact or Fiction? 43% of the Population Has No Estate Plan (https://info.wealthcounsel.com/blog/fact-or-fiction-43-of-the-population-has-no-estate-plan)
- Examine Disadvantages of an NQPRT
- Estate planning Q and A: Qualified Personal Residence Trusts Explained (https://rsmus.com/insights/tax-alerts/2024/estate-planning-qa-qualified-personal-residence-trusts-explained.html)
- Qualified Personal Residence Trust (QPRT): Pros and Cons | C.W. O’Conner (https://cwoconner.com/qualified-personal-residence-trust-qprt-pros-and-cons)
- What Is a Personal Residence Trust and Is It Right for You? (https://portebrown.com/newsblog-archive/what-is-a-personal-residence-trust-and-is-it-right-for-you)
- Crash Course: Qualified Personal Residence Trusts (QPRTs) (https://ssfpc.com/blog/a-crash-course-in-qualified-personal-residence-trusts-qprts)
- Assess Suitability of an NQPRT for Your Family
- Characteristics and consequences of families with low levels of financial wealth | Institute for Fiscal Studies (https://ifs.org.uk/publications/characteristics-and-consequences-families-low-levels-financial-wealth)
- Families’ job characteristics and economic self-sufficiency: Differences by income, race-ethnicity and nativity (https://diversitydatakids.org/research-library/journal-article/families-job-characteristics-and-economic-self-sufficiency)
- Lack of estate planning leads to family feuds, study shows (https://investmentnews.com/retirement-planning/lack-of-estate-planning-leads-to-family-feuds-study-shows/240734)
- How a QPRT Can Help Reduce Estate Tax (https://schwab.com/learn/story/how-qprt-can-help-reduce-estate-tax)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading