

Key Highlights
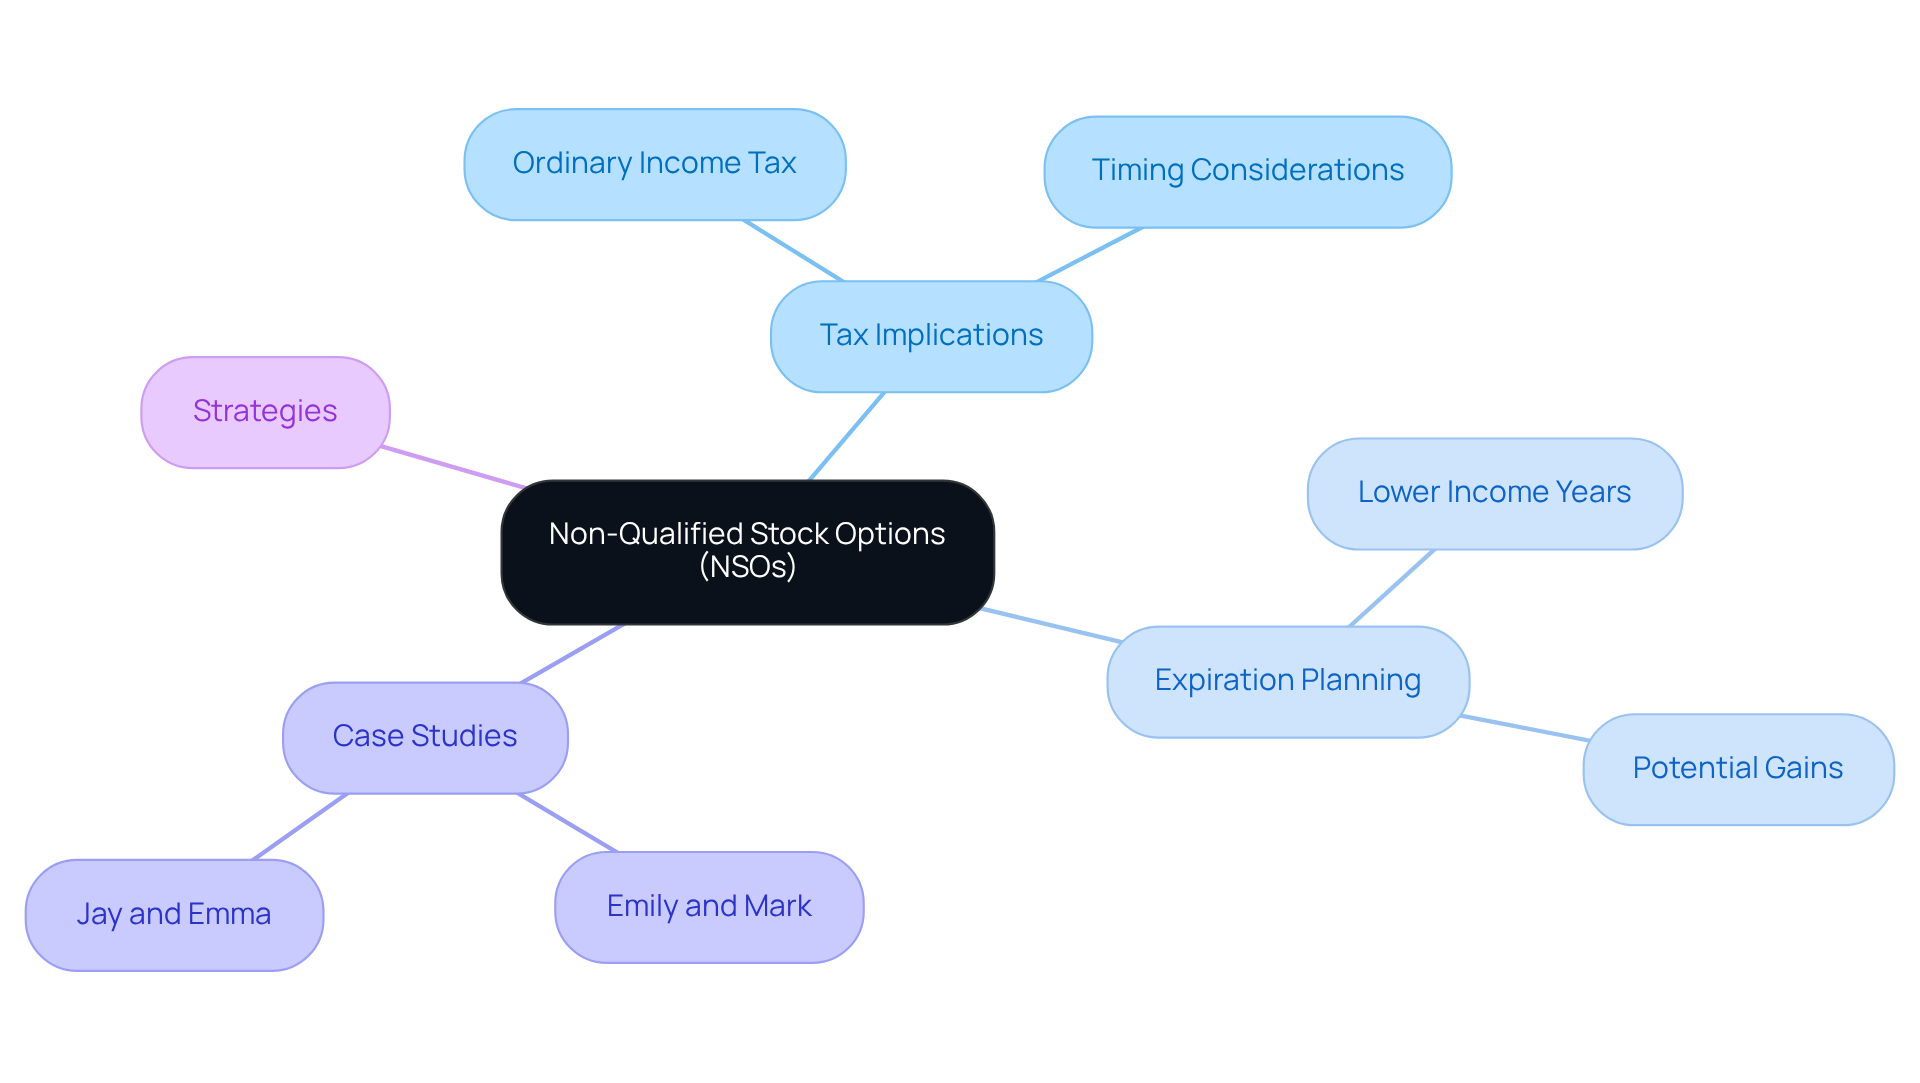
- Non-Qualified Stock Options (NSOs) allow employees to purchase company stock at a predetermined price but are taxed as ordinary income upon exercise.
- For example, exercising 500 shares at a $50 purchase price when the fair market value is $75 results in a taxable income of $12,500.
- Effective nso expiration planning can help families minimise tax liabilities by exercising options during lower income years.
- Families like Emily and Mark, and Jay and Emma, have successfully navigated NSOs with the help of Bright Advisers, balancing present financial responsibilities with future goals.
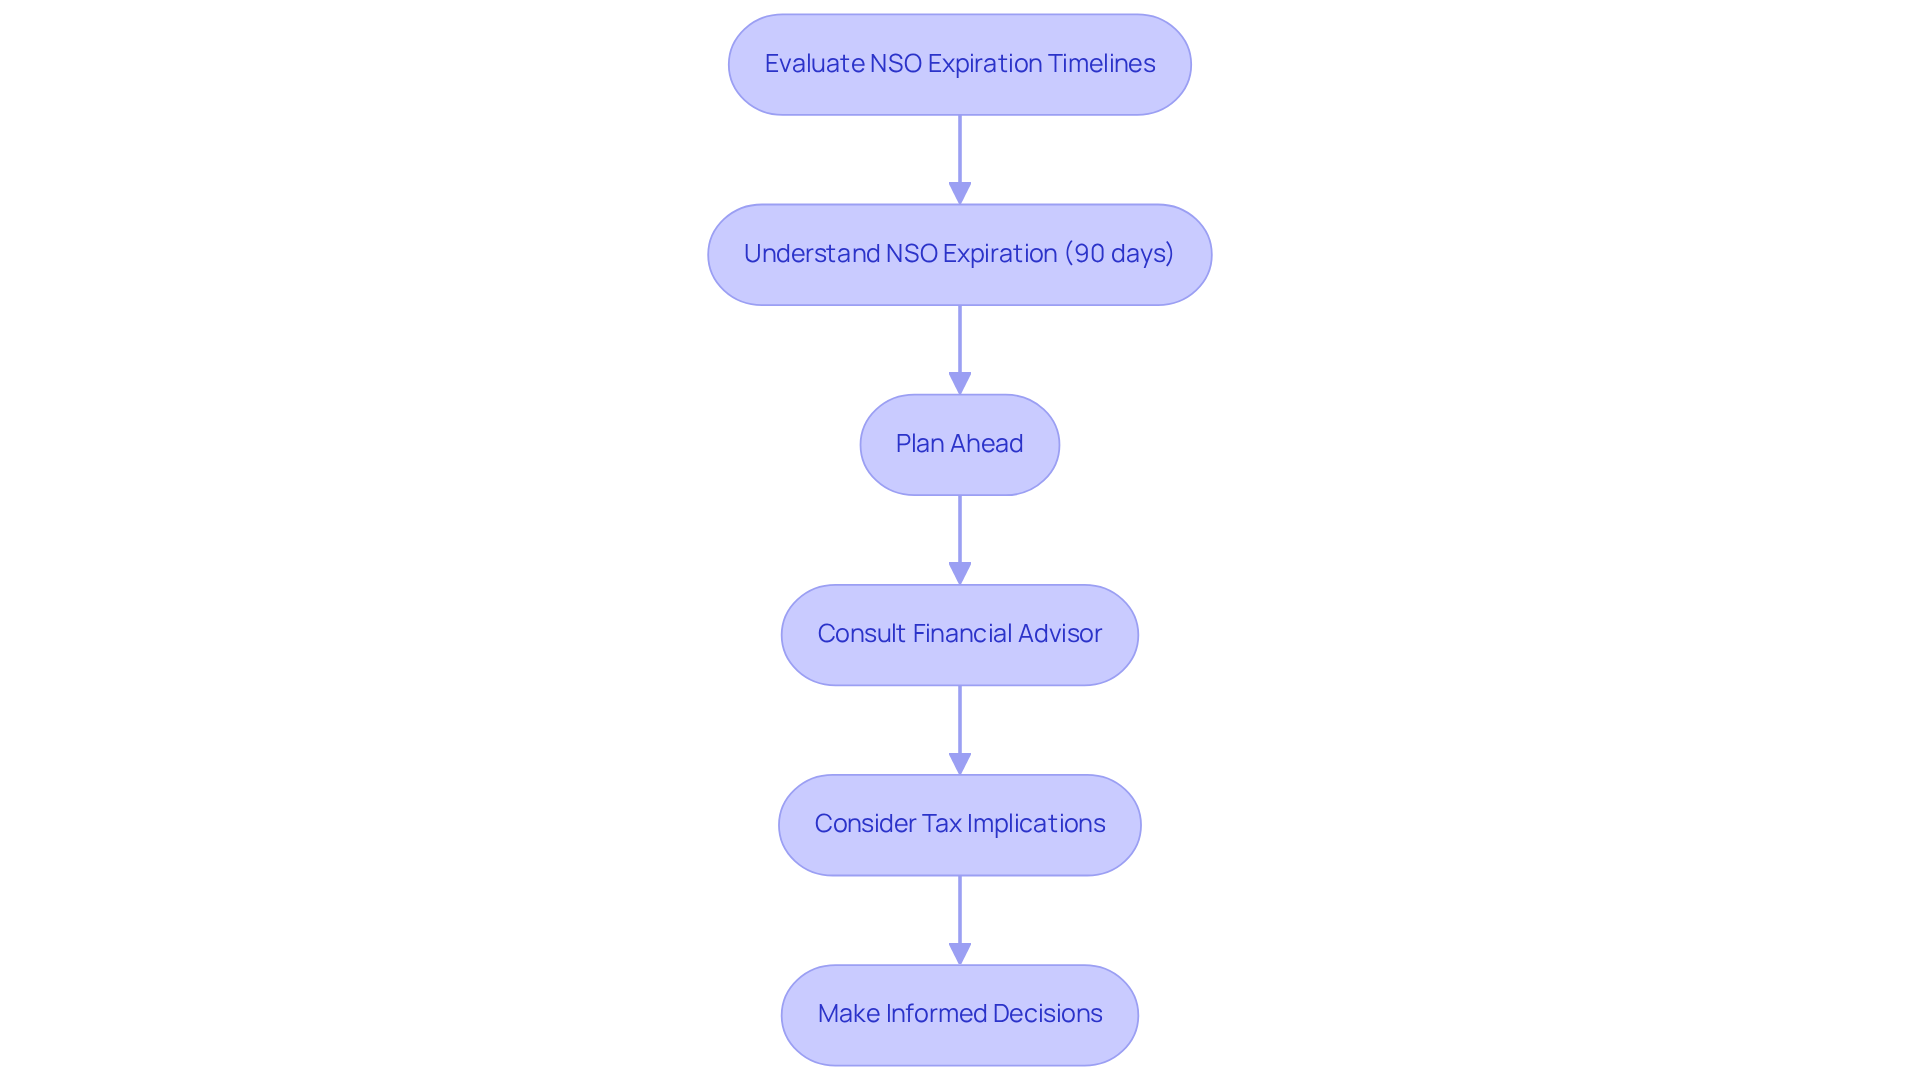
- NSOs typically have a 90-day exercise window after leaving a job, making timely planning crucial to avoid losing options.
- Tax implications include ordinary income tax rates of 22% for income under $1M and 37% for income over $1M when exercising NSOs.
- Strategies for exercising NSOs include ‘option and sell’ for immediate cash needs and ‘hold and utilise’ for long-term appreciation.
- Consulting with a financial advisor can provide tailored insights and help families make informed decisions regarding NSOs and their financial futures.
Introduction
Imagine feeling overwhelmed by the complexities of Non-Qualified Stock Options (NSOs) while trying to secure your family’s financial future. As these options become more common in corporate compensation packages, it’s essential to understand their implications for your family’s financial planning.
In this article, we’ll explore how you can make the most of NSOs, helping your family minimize tax burdens and unlock financial opportunities. But with so much on the line, how can you and your family feel confident in making the right choices before your options run out?
Understand Non-Qualified Stock Options (NSOs)
Imagine the worry of unexpected tax bills when you’re just trying to provide for your family. Non-Qualified Stock Options (NSOs) can be a valuable tool in nso expiration planning, enabling you to acquire company stock at a predetermined price. However, it’s important to understand how these options can impact your family’s finances. Unlike Incentive Stock Options (ISOs), NSOs don’t qualify for favorable tax treatment, which means that when you exercise them, the difference between the purchase price and the fair market value (FMV) is taxed as ordinary income.
For instance, if you acquire 500 shares at a purchase price of $50 when the FMV is $75, you’ll face a taxable income of $12,500. This amount is subject to ordinary income tax rates, which can vary based on your overall income. Understanding nso expiration planning can help you exercise these options during lower income years to minimize tax liabilities, potentially keeping you in a lower tax bracket.
Recent statistics show that NSOs are becoming more common in corporate compensation packages, offering employees a chance to invest in their companies. But timing is everything. Delaying the exercise until closer to the expiration date might seem tempting for better returns, yet it carries the risk of missing out on potential gains if the stock price continues to rise.
Consider Emily and Mark, a couple with ambitious career goals. They worked with Bright Advisers to navigate the complexities of their NSOs, developing a strategy that included nso expiration planning along with effective tax planning. This approach allowed them to manage their finances while keeping their options open for the future.
Similarly, Jay and Emma sought to alleviate their monetary stress. By collaborating with Bright Advisers, they crafted a solid strategy that included nso expiration planning, enabling them to balance present responsibilities with long-term aspirations, ensuring they could fund their children’s education while planning for retirement.
With the right guidance, you can transform financial challenges into stepping stones for your family’s future. By understanding the implications of NSOs and working with a skilled advisor, you can make informed choices that align with your financial goals. Bright Advisers is here to support families like Emily and Mark, and Jay and Emma, helping you navigate these complexities and achieve financial stability and independence through personalized planning and tax strategies.
Evaluate NSO Expiration Timelines
Managing Non-Qualified Stock Options (NSOs) can feel overwhelming, especially when time is ticking away. But if someone leaves their job, they often find themselves with just 90 days to make the most of their options. By planning ahead, families can ensure they don’t miss out on valuable opportunities that could slip away.
Take the story of Allison and Brian, for example. Like many families, they were initially unaware of the financial opportunities they could seize with better planning. Through their collaboration with Bright Advisers, they not only optimized their tax situation but also secured their children’s future through education funding and gained the ability to retire sooner. Their story shows how families who take the time to prepare can create a brighter financial future for themselves and their children.
Reaching out to a financial advisor can be a comforting step, offering guidance on the best times to exercise options based on your unique situation. It’s also important to be aware of the potential tax implications of exercising NSOs, including the statutory tax withholding rates of 22% for income under $1M and 37% for income over $1M. By staying organized and informed, families can ensure they make the most of their NSO expiration planning before their NSOs expire, just like Allison and Brian did with the guidance of Bright Advisers.
Implement Effective NSO Exercise Strategies
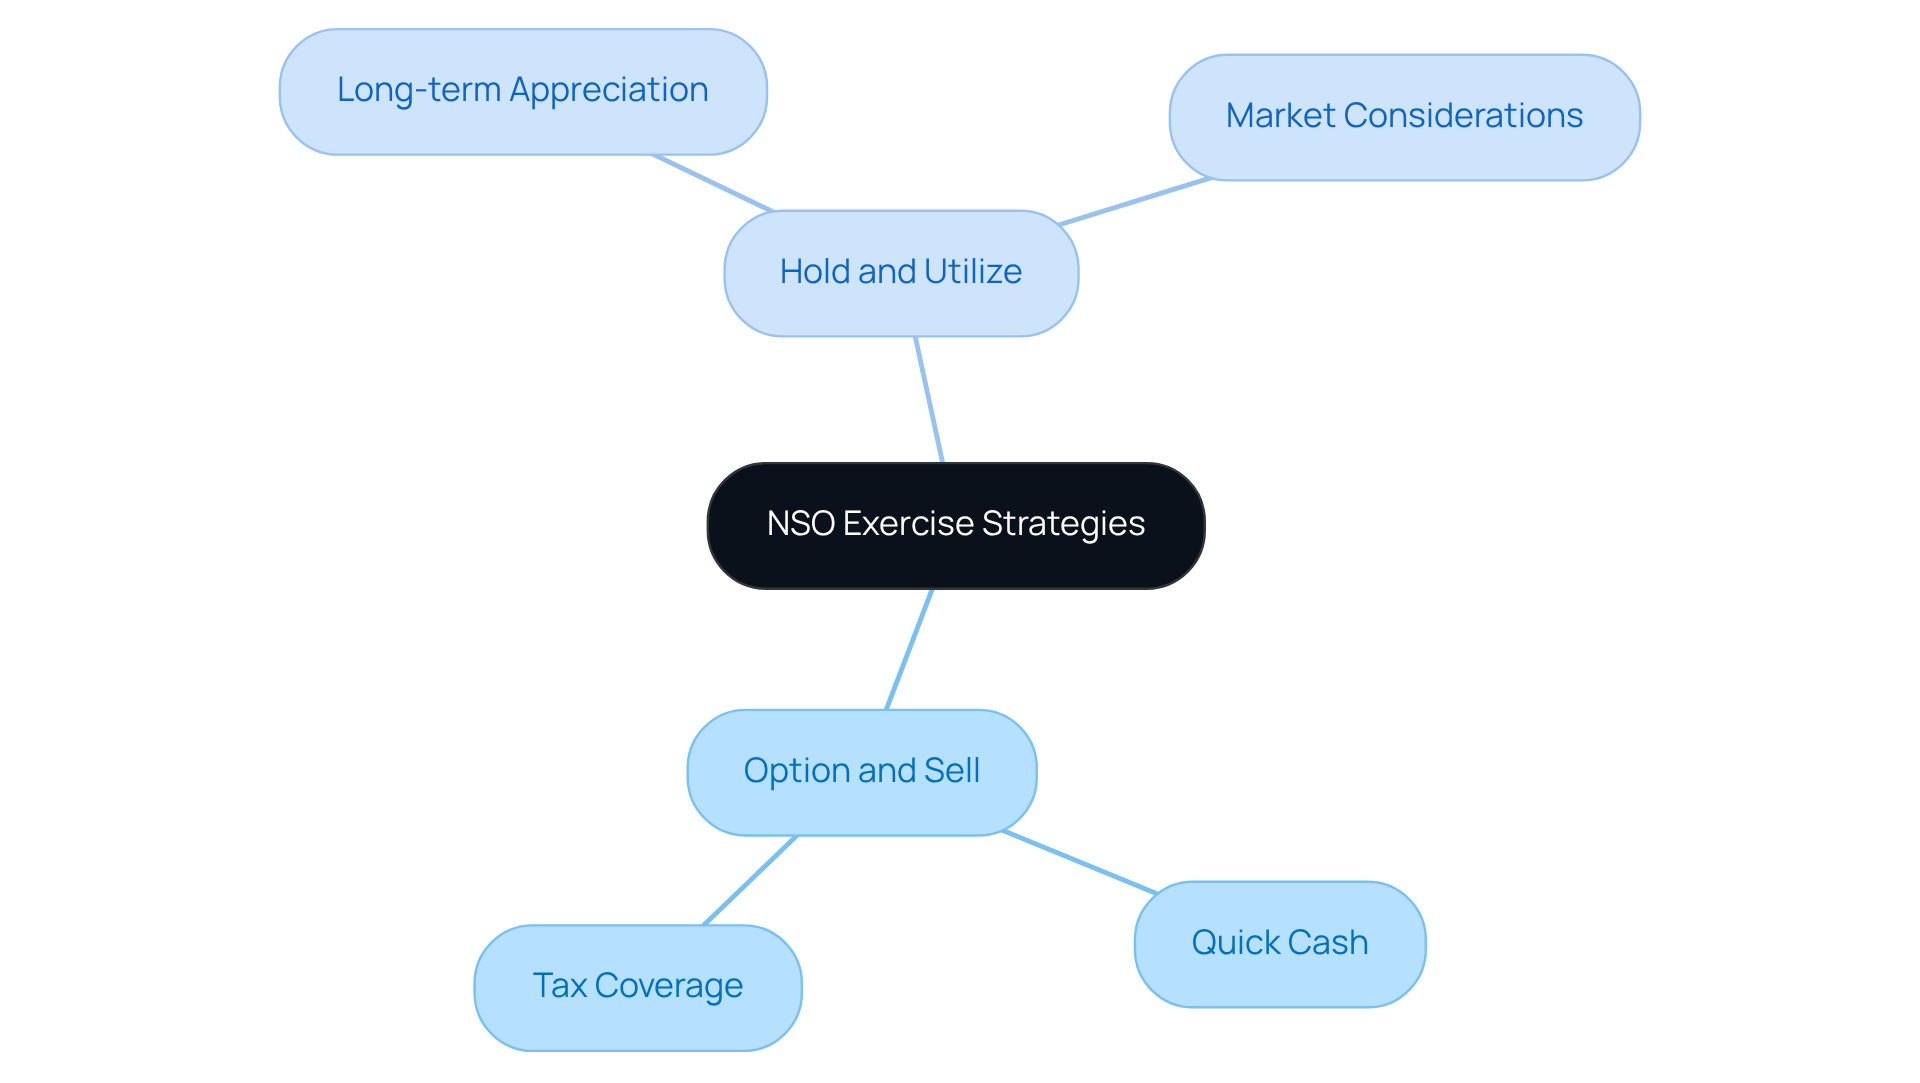
Imagine feeling uncertain about your financial future while juggling family responsibilities-this is where NSO expiration planning and effective strategies for exercising Non-Qualified Stock Options (NSOs) become essential. Families have several effective strategies that can significantly impact their financial future. One common approach is the ‘option and sell’ strategy, where employees utilize their options and promptly sell the shares to cover the acquisition cost and any related taxes. This strategy works well when families need quick cash or if they think the stock price might drop. For instance, this method allows families to convert stock option value into cash quickly, which can be redeployed into a diversified portfolio or used for immediate expenses. As Daniel Zajac, a CFP®, observes, ‘Delaying so long to act means putting yourself at risk of simply forgetting about the expiration date, or missing your window of opportunity if the trade doesn’t go through in time.’ This highlights the importance of timely decision-making in exercising options.
Another strategy is the ‘hold and utilize’ approach, where employees utilize their options but retain the shares for potential long-term appreciation. This method is beneficial for families who believe in the company’s growth potential and are willing to wait for the stock price to increase. But it’s important to think about taxes and how the market is doing before making a decision. As Zajac points out, ‘Deciding when to exercise employee stock options can be complicated and, for many people, is driven by fear and uncertainty; however, effective planning can alleviate this fear.’
For instance, Emily and Mark, a pair in their mid-30s, sought advice from Bright Advisers to manage their planning while balancing demanding careers. They implemented a comprehensive strategy that included exercising their NSOs wisely as part of their NSO expiration planning, which allowed them the freedom to choose whether or not to continue working. By improving their monetary situation and planning for retirement, they gained the flexibility to make career decisions based on their desired work-life balance.
Additionally, Jay and Emma, a couple with two children, worked with Bright Advisers to establish a sound financial strategy that incorporated NSO expiration planning along with exercising their NSOs. They focused on balancing growth potential and risk management, which helped them navigate funding their children’s education while planning for retirement.
A progressive approach to planning can also be effective, enabling households to utilize a portion of their options over several years. This method helps manage market volatility and spreads tax liabilities, reducing the emotional burden of decision-making. For example, by exercising a percentage of options each year, households can reduce concentration risk, which arises when a large portion of wealth is linked to one stock, and sustain a diversified investment portfolio. As Mellody Hobson highlights, there is a direct tradeoff between risk and returns in investing, making it essential for households to assess their economic situation, market conditions, and tax implications when determining an exercise strategy.
Ultimately, consulting with a financial advisor can offer customized insights and assist households in navigating the complexities of NSO expiration planning, ensuring they make informed decisions that align with their long-term financial goals. With the right guidance, families can confidently navigate their financial journey, ensuring a brighter future for their loved ones.
Navigate NSO Tax Implications
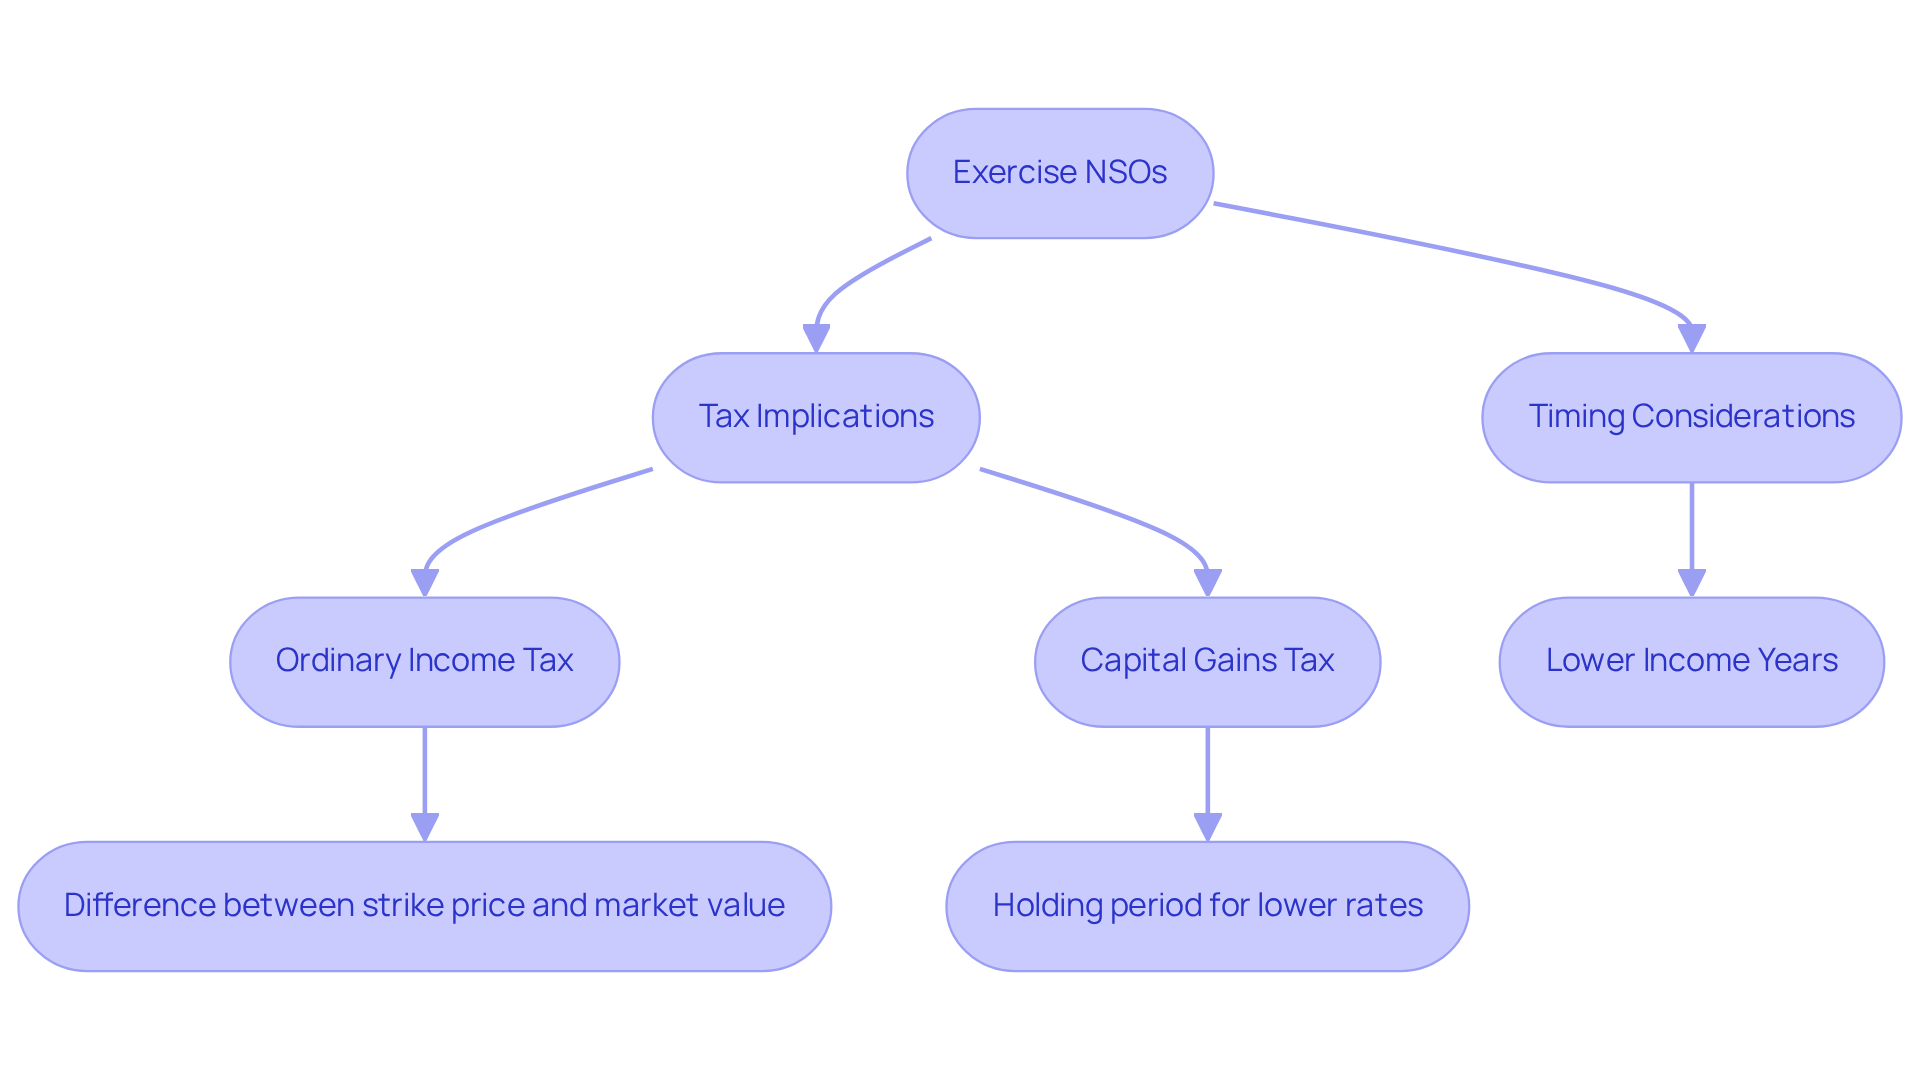
Imagine feeling confident about your family’s financial future, even when faced with the complexities of nso expiration planning related to Non-Qualified Stock Options (NSOs). Understanding how the difference between what you pay for your options and their market value can affect your family’s finances is crucial. When you exercise NSOs, the difference between the option price and the fair market value is taxed as ordinary income. This can significantly impact your family’s tax bracket, especially if the difference is substantial. For instance, if you exercise NSOs with a strike price of $1 and the fair market value is $5, that $4 difference is subject to ordinary income tax rates, which can be as high as 37% for higher income brackets in 2026.
Additionally, any appreciation beyond the strike price is subject to capital gains tax when you sell the shares. If you hold onto those shares for more than a year after exercising, you may qualify for long-term capital gains tax rates, which are generally lower than ordinary income tax rates. This distinction can lead to significant tax savings. Many families have successfully timed their NSO actions to align with lower income years, reducing their overall tax obligations.
It’s important for families to reflect on their total income and how nso expiration planning might influence their financial landscape. Timing the exercise of NSOs in a year when your household’s income is lower can be a smart move. By seeking guidance from a tax professional, you can turn confusion into clarity, ensuring you make informed decisions that benefit your loved ones. Together, we can navigate this journey and enhance your financial outcomes while managing your tax burdens.
Conclusion
Navigating the world of Non-Qualified Stock Options (NSOs) can feel overwhelming for families, but it doesn’t have to be that way. With thoughtful NSO expiration planning, families can feel more secure in their financial choices, making decisions that truly reflect their hopes for the future. When families understand how NSOs work and the tax implications of exercising them, they can approach this journey with greater confidence and peace of mind.
Throughout this article, we’ve shared key strategies for managing NSOs, like the importance of timely exercises and understanding expiration timelines. Real-life examples, such as Emily and Mark, and Jay and Emma, show how families can benefit from working with Bright Advisers to create tailored plans that fit their unique situations. By leveraging expert guidance, families can optimize their tax liabilities and make strategic decisions that support their dreams, whether it’s funding education or planning for retirement.
In the end, planning for NSO expiration isn’t just about the numbers; it’s about helping families feel empowered to shape their financial futures. Taking that first step towards financial clarity can make all the difference for your family’s future. If you’re ready to enhance your financial outcomes, reaching out to Bright Advisers could be a pivotal step in ensuring a brighter future for your loved ones.
Frequently Asked Questions
What are Non-Qualified Stock Options (NSOs)?
Non-Qualified Stock Options (NSOs) are a type of employee stock option that allows you to purchase company stock at a predetermined price. Unlike Incentive Stock Options (ISOs), NSOs do not qualify for favorable tax treatment.
How are NSOs taxed?
When you exercise NSOs, the difference between the purchase price and the fair market value (FMV) is taxed as ordinary income. For example, if you acquire shares at $50 when the FMV is $75, you will have a taxable income of $12,500, which is subject to ordinary income tax rates.
What is nso expiration planning?
Nso expiration planning involves strategizing the timing of exercising your NSOs to minimize tax liabilities. Exercising during lower income years can help keep you in a lower tax bracket.
Why is timing important when exercising NSOs?
Timing is crucial because delaying the exercise of NSOs until closer to the expiration date may seem appealing for better returns, but it also carries the risk of missing out on potential gains if the stock price continues to rise.
How can families benefit from working with Bright Advisers regarding NSOs?
Families can benefit from working with Bright Advisers by developing strategies for nso expiration planning and effective tax planning. This guidance helps manage finances while balancing present responsibilities and long-term aspirations, such as funding children’s education and planning for retirement.
Can you provide examples of families who successfully navigated NSOs?
Yes, Emily and Mark worked with Bright Advisers to create a strategy for their NSOs, allowing them to manage their finances effectively. Similarly, Jay and Emma collaborated with Bright Advisers to alleviate monetary stress and ensure they could fund their children’s education while planning for retirement.
What is the mission of Bright Advisers?
Bright Advisers aims to help families make wise wealth decisions and preserve wealth across generations through personalized planning and tax strategies.
List of Sources
- Understand Non-Qualified Stock Options (NSOs)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Non-Qualified Stock Options Taxation (https://wealthenhancement.com/blog/non-qualified-stock-options-taxation)
- The 11 Best Quotes about Investing (https://birchstreetadvisors.com/blog/the-11-best-quotes-about-investing)
- What are nonqualified stock options (NSOs)? | Fidelity (https://fidelity.com/viewpoints/wealth-management/insights/nonqualified-stock-options)
- Understanding Non-Qualified Stock Options: Tax Implications and Strategies (https://withum.com/resources/understanding-non-qualified-stock-options-tax-implications-and-strategies)
- Evaluate NSO Expiration Timelines
- 9 Things To Know about Non-Qualified Stock Options | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/9-things-non-qualified-stock)
- Stock Options: NQSOs and ISOs (https://schwab.com/learn/story/stock-options-nqsos-and-isos-guide)
- What to Do with Expiring Non-Qualified Stock Options (NSOs) — EquityFTW (https://equityftw.com/articles/what-to-do-with-expiring-non-qualified-stock-options-nsos)
- Unlocking the Power of Equity-Based Incentive Compensation: Basics of Nonqualified Stock Options and Stock-Settled Stock Appreciation Rights (https://foley.com/insights/publications/2024/07/equity-based-incentive-compensation-basics)
- Non-Qualified Stock Options (NSOs) Explained for Tech Employees | Equity Comp Academy (https://3040wealth.com/academy/nso-stock-option)
- Implement Effective NSO Exercise Strategies
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- 6 Strategies to Consider to Exercise Your Employee Stock Options (https://zajacgrp.com/insights/6-strategies-to-exercise-your-employee-stock-options)
- Rho | Non-Qualified Stock Options Explained (https://rho.co/blog/non-qualified-stock-options)
- Exercise and Sell or Exercise and Hold – Stock Options Case Study (https://kbfinancialadvisors.com/same-day-sale-vs-exercise-hold-case-study)
- Navigate NSO Tax Implications
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- Non-Qualified Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/non-qualified-stock-options/L8zsxRi7B)
- How to Maximize Your NSO Stock Options: Tax Strategies and Exercise Tips for Startup Employees — Secfi (https://secfi.com/learn/nso-non-qualified-stock-options-tax-treatment)
- ISO vs NSO: The Tax Implications (https://brightonjones.com/blog/iso-vs-nso)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading